营业利润增速连续快于营收,原因在毛利率:24.2%(2025年3月期)升到26.7%(2026年3月期),2027年3月期上半年再到27.1%,没有靠一次性收益。公司无银行借款和公司债,权益比率65.9%,资本开支仅54亿日元左右,约50%的分红比率连续兑现。2026年3月期经营现金流为负34.09亿日元,可以由上年证券收益的税款延后和50亿日元和解款解释,2027年3月期上半年已回升到正312.35亿日元。
2327
日鉄ソリューションズ株式会社(NS Solutions Corporation)
日鉄ソリューションズ株式会社(NS Solutions Corporation,简称NSSOL,东证Prime市场,代码2327)主营企业信息系统服务,覆盖管理与系统咨询,信息系统的规划、设计、开发、运维,以及相关软硬件销售。公司源自日本制铁集团的系统部门,对外客户占营收约八成,客户包括制造业、金融机构、流通企业和政府部门。管理上分两个领域:商业解决方案(Business Solutions)面向钢铁、制造、金融、流通等行业系统;咨询与数字服务(Consulting & Digital Services)做咨询、数字化和公共部门项目,其中包括防卫项目。会计上只有信息服务一个报告分部,合并员工10,276人。
最近亮点:2026年11月2日公布2027年3月期(FY27/3)上半年业绩:营收1,989.78亿日元,增长11.6%;营业利润232.09亿日元,增长27.0%;归母利润148.57亿日元,增长23.7%,均为中期历史新高。全年预测上调到营业利润490亿日元、归母利润324亿日元,年分红上调到89日元。市场没有买账,11月6日收盘下跌4.43%,报3,819日元。 估值简报:股价3,819日元(2026年11月6日收盘)/总市值6,988.85亿日元/预测PER(市盈率)21.6倍(按修订后2027年3月期预测每股收益177.06日元)。实绩PBR(市净率)2.50倍(2026年3月末每股净资产1,525.86日元)。IRBANK按9月末每股净资产1,563日元左右算为2.44倍。ROE 11.4%(2026年3月期实绩,无推算预测)/预测股息率2.33%(年分红预测89日元)/EV/EBITDA 9.8倍。EV 5,715.2亿日元=总市值减2026年9月末净现金1,273.68亿日元,公司无有息借款,租赁负债未计入。EBITDA 581.31亿日元=2026年3月期营业利润442.42亿日元加折旧摊销138.89亿日元。两个口径期间不同,且净现金大部分存放在母公司。
日本制铁同时是控股股东(表决权63.44%)、最大客户(占营收18.5%)和现金托管方(通过集中资金管理体系,下称资金池,保管约九成集团现金),这使治理折价缺少近期的解决路径;母公司对持股的最终意图和资金池的利率、提取条款都没有披露。计划层面,中期经营计划(2025–2027年度)要求2028年3月期营业利润600亿日元,比2027年3月期预测还多110亿日元。这要靠TAM型业务继续提升毛利率。TAM型业务指次世代系统集成、资产运用、平台提供三类,占营收比重2026年3月期为38%,计划2028年3月期约75%。Infocom等并购形成644.03亿日元商誉与无形资产,减值一旦发生会一次确认。
结论:Kabugami评分63.21/100(V3.2),评级B,操作为持有并跟踪、不追高。业务质量和盈利兑现支持持有,但价格处在两次受阻的高位箱体中段,估值已计入部分计划兑现,治理折价没有近期的解决路径。 关键依据:营业利润增长有产品组合上的原因,现金与分红扎实;约束来自母公司的控制结构,其最终意图、资金池条款和活跃投资者3D Investment Partners的诉求均未明。下半年隐含的利润下降是保守还是真实恶化,要等第三季度业绩;TAM口径未经审计。价格结构上旧状态的控制力在减弱,新状态尚未确认。 翻转条件:2027年1月下旬第三季度业绩显示TAM占比不低于50%左右、毛利率不低于27%,且全年指引能通向600亿日元,判断上修;TAM停滞、毛利率回到26%以下、Infocom商誉减值或母公司收紧控制,判断下修。 当前动作:持有并跟踪,不追高:业务质量和盈利兑现支持继续持有,但价格处于已两次受阻的区间中位,估值已计入部分计划兑现,治理折价缺乏近期解决路径。2027年1月下旬的第三季度业绩(检验下半年隐含的利润下降、TAM占比约50%、毛利率不低于27%)是下一个关键检查点;若毛利率和TAM占比同时达标,可考虑在价格回到下方支撑带附近时增加仓位;若TAM停滞、毛利率回落或母公司收紧控制,则应降低判断。
报告目录
01|投资问题与当前结论
01.1|计划兑现与治理事件,哪一个先改变这家公司的折价
NSSOL的经营质量在改善,股价能否再上一个台阶,取决于两件事谁先到:2028年3月期600亿日元营业利润的计划兑现,或者日本制铁在持股、资金池、流通股上出现治理动作。需求不构成约束。
先看经营这一半。2026年3月期营收3,813.40亿日元,增长12.7%;营业利润442.42亿日元,增长14.9%;ROE 11.4%。2027年3月期上半年营业利润再增27.0%。公司没有借款,分红比率稳定在50%。
再看控制这一半。日本制铁握着63.44%表决权,贡献705.50亿日元、占18.5%的营收,托管着九成左右的集团现金,有效流通股只有11.56%上下(二手估算)。需求稳、资产负债表稳是这套结构的好处,估值上修空间被压住是它的代价。两个故事用不同的证据检验:经营故事看TAM占比、毛利率和全年指引,治理故事看减持、资金池条款披露和派息比率。
最强的反证有两处。价格上,创纪录的业绩公布后被卖出,价格落在两年平均成本之下。指引上,按修订后全年预测倒推,下半年归母利润为175.43亿日元,比上年同期低6.8%(二次推算)。
什么会推翻这个判断:到2027年3月期全年业绩发布时,如果TAM占比不低于50%左右、毛利率不低于27%、2028年3月期指引能通向600亿日元,经营故事成立。如果TAM停滞在45%以下且毛利率回到26%以下,下半年下降被证实而2028年3月期指引低于520亿日元左右的营业利润,Infocom商誉减值,或母公司收紧控制(比如以偏低价格公开收购少数股权),判断下修。
反方向上,母公司减持、资金池按市场条款披露或派息比率上调,任一项都会推翻折价长期存在的看法。以上门槛由研究判断设定,并非公司承诺,母公司的行为事前无法预知。
01.2|计划算术:产品组合比需求更紧
中期经营计划对2028年3月期的目标是营收4,500亿日元、营业利润600亿日元、营业利润率13%、ROE 13%左右。2027年3月期营业利润指引为490亿日元,最后一年还要多做110亿日元。
先试试只靠规模。按现在11.6%至11.7%的营业利润率,营收做到4,500亿日元,营业利润只有520亿至527亿日元(本研究的简单推算),距目标仍差70多亿日元。需求即使全部达标,计划也到不了13%。
缺口只能由组合补上:TAM型业务占比升到75%上下,毛利率继续抬高。传导路径是TAM占比提升,毛利率上升,营业利润增速超过营收,目标缺口收窄。2026年3月期毛利率提高了2.5个百分点(24.2%到26.7%),但销售管理费从410.71亿日元升到580.57亿日元,营业利润率只守在11.6%附近。毛利率的改善有一部分被花在能力建设上。
TAM占比和毛利率共同押在一个由管理层自己定义的指标上,落空时会一起落空。因此600亿日元是进取情形,不是正常化盈利。缺口的拆解构成公司没有披露;防卫这类大项目在2028年3月期能否被替代,也会影响增长。
02|公司本质与商业模式
02.1|一家把工程师和可复用资产嵌进客户核心系统的轻资产服务商
NSSOL靠长期参与客户的核心系统赚钱:从咨询、设计、开发到运维,工程师和可复用资产留在客户系统里,换供应商的成本高,收入因此持续。公司1980年作为日本制铁的计算机系统部门成立,1988年并入母公司信息系统部门,2002年上市,2022年进入东证Prime市场。
对外客户占营收约八成,涵盖政府机构、制造、流通和金融。会计上只有信息服务一个报告分部,管理上按商业解决方案和咨询与数字服务两个领域看。2026年3月期商业解决方案营收2,865.06亿日元,按新分类重述后增长17.7%;咨询与数字服务948.33亿日元,基本持平。这两个领域的数字是管理会计口径,不是经审计的分部披露。
这个模式的资本负担轻:资本开支54亿日元左右,没有银行借款,权益比率66.9%。现金不受资本强度约束,利润杠杆落在工作内容的组合上,规模和价格不是主要变量。
护城河的证据主要来自业务结构和收入连续性的推断。合同期限、客户流失、经常性收入与项目收入的比例、在手订单都没有披露,所以黏性在这里是推断,没有实测。
02.2|TAM型业务:从按人月计费转向资产与平台,口径是公司自己的
公司正在把收入从按人月计价的人力服务,转向TAM型工作:T是次世代系统集成,A是资产运用,M是平台提供(TAM是公司的内部口径,下文即指这三类)。占营收比重2026年3月期为38%,同比增长33%,2027年3月期预期50%左右,2028年3月期目标75%上下。
交付手段包括Nestorium平台、NS Devia(AI工程套件)、Corepeak(2026年4月推出的AI代理品牌)、NSRelato(运营平台)和Alli Coworker(生成式AI服务)。2026年9月,公司还与Anthropic建立了战略合作。公司同时设定了开发生产率和内部运营效率各提高20%的目标。
这条路的好处是资产和平台收入不随人数线性增加,毛利率有抬升空间。风险在两处。其一,这一比例没有第三方审计,现有人力收入能否被重新归类为TAM而经济性不变,公司没有说明。其二,AI既提高交付效率,也可能替代按工时计费的工作量,与Anthropic合作的商业条款也没有披露。验证问题见第13章。
03|产品、客户与供应链
03.1|最大客户同时是控股股东:客户并不集中,但不完全独立
客户结构上,对外客户占营收约八成,最大单一客户是日本制铁:2026年3月期贡献705.50亿日元,占营收18.5%,比2022年3月期的20.4%逐步下降。母公司在钢铁领域的设备投资会直接传导到公司的钢铁业务,不过2027年3月期上半年钢铁领域收入已经下降。
关联交易的定价,以及董事会如何审议这笔交易,公司治理报告没有读到,属于未核实事项。控制关系本身放在第7章讨论。
03.2|上半年的加速看似全面,拆开是轮动:咨询与数字服务靠一个防卫大项目
咨询与数字服务上半年收入从433.02亿日元升到555.74亿日元,增长28.3%,主要来自一个大型防卫项目;此前2026年3月期该领域全年持平在948.33亿日元。商业解决方案从1,350.72亿日元升到1,434.04亿日元,由汽车、化工材料、食品、铁路等工业客户和Infocom并表带动,钢铁和流通平台领域收入下降。
防卫和公共部门的需求有政策支撑,但项目是大块的,大块项目没有替代,年化后增长会掉下来。防卫项目占咨询与数字服务的比重没有披露。2026年3月期的领域收入已按新分类重述,全年口径要等2027年3月期全年披露才能对照审计。2028年3月期能否续约或替换,是计划的前提,见第13章。
03.3|需求从制造业投资、防卫预算和金融IT进来,行业冲击先到股价、后到利润
需求的传导可以分三条看。制造业数字化投资(钢铁、汽车、化工、食品、铁路)是商业解决方案的基本盘,客户的资本开支直接转成公司的订单。防卫和公共部门是咨询与数字服务近期增长的最大来源。金融机构的IT投资偏选择性但在回升,领域内正由许可证转售转向公司自有平台与咨询,TAM占比的提升也靠这条线承载。
政策(数字政府、防卫预算)是顺风。宏观冲击通过客户资本开支滞后地进入利润,却会立刻进入股价,2025年4月关税冲击把股价压到3,259日元就是例子。公司把2026年3月期的环境描述为数字化投资稳健,劳动力短缺和旧系统更新支撑需求。关键依赖在工程师供给,原材料和设备不构成约束。客户资本开支的弹性、防卫业务的规模,都无法从现有资料测算。
04|竞争格局与产业关系
04.1|同业都是日本大型系统集成商,竞争靠信任、行业知识和交付能力
主要对手有NTT Data(规模最大)、野村综合研究所(利润率标杆,金融领域也是NSSOL的战场)、富士通(正在向服务转型)和伊藤忠Techno-Solutions(流通领域见长,同时也是一家合资公司的少数股东伙伴)。此外还有客户自己的IT团队,以及可以替代计费工时的AI原生交付。
竞争主要靠信任、行业知识和交付能力,价格不是唯一变量。AI替代有一层特殊性:公司正在采用的同一项技术,可能压缩按人月计费的收入。野村综研这类利润率可以当作TAM转型的参照。本研究没有建立细分领域的份额表,也没有正式的同业中位倍数,相对估值和份额的比较因此缺位。
04.2|资本关系:母公司、Infocom、合资公司与海外子公司
日本制铁是母公司、最大客户和现金托管方。Infocom(原帝人集团旗下上市系统集成商)2025年7月起成为全资子公司,是收购带动增长的主要检验。B-Prost(非寿险核心系统)2026年5月并入,规模小,显示收购仍在继续。Nitetsu Hitachi System Engineering是1988年成立的合资公司,NSSOL持51%,日立持49%,代表长期的联盟式交付。
另有2026年7月与台湾iAuto的资本与业务联盟、印尼ERP子公司PT. WCS Abyakta Nawesena,以及美国、英国、中国、新加坡、泰国的海外子公司。合并口径下,少数股东权益为96.70亿日元(2026年9月末),不属于普通股东。合资公司和合作伙伴的利润贡献没有披露。
05|护城河判断
护城河的判断是:成立,但证据停在「有迹象」,没到「已验证」。
正面证据有三层。工程师和可复用资产嵌在客户核心系统里,覆盖全生命周期,切换成本高、收入连续。对外客户占八成左右,不靠母公司单线。公司无借款、轻资产、自我造血,现金和分红在两年窗口内能兑现。
长期因素有五个:日本数字化需求与工程师稀缺;AI交付技术;母公司的治理引力;并购留下的644.03亿日元商誉与无形资产;公共和防卫预算。AI技术是双刃的,只有TAM占比真正上升时才对公司有利,否则它在压缩人月计费的收入。
反面证据同样清楚:没有合同期限、客户流失和独立份额数据;TAM口径未经审计,如果只是把原有人力收入重新归类,护城河并没有加深。
自我修复能力两头不同。偿债和现金上很强:无负债,销售管理费也可以调节。治理上弱,母公司的利益在结构上优先。减值上也弱,一旦发生会一次冲击净资产和权益比率。季度业绩是观察这些长期因素有没有移动的唯一窗口。
06|财务质量与现金流
06.1|利润增长来自产品组合,不靠一次性收益
这两年的记录业绩质量不差。2026年3月期营收3,813.40亿日元,增长12.7%;营业利润442.42亿日元,增长14.9%;归母利润308.32亿日元,增长14.0%;每股收益168.50日元。2027年3月期上半年营收1,989.78亿日元,营业利润232.09亿日元,归母利润148.57亿日元。
需要排除的是一次性因素。2025年3月期的综合收益曾被证券的公允价值收益136.82亿日元抬高,到2026年3月期综合收益从425.53亿日元降到335.65亿日元,下降21.1%。这类收益不属于经营能力,也已经退出。两个记录期的增长都来自经营。
指引的节奏也值得读。2027年3月期营业利润预测4月为475亿日元,第一季度已上调上半年指引,11月再上调到490亿日元;归母利润预测从316亿日元到324亿日元,分红从87日元到89日元。上半年营业利润232.09亿日元超过第一季度阶段的215亿日元指引,营收1,989.78亿日元则略低于2,000亿日元。这是「保守指引、年内逐步上调」的模式,但它是一个待检验的信号,不是已证实的事实。下半年隐含的利润下降见第11章。
06.2|毛利率是整套逻辑里信息量最大的数字
毛利率从24.2%(2025年3月期)升到26.7%(2026年3月期),2027年3月期上半年为27.1%,比上年同期的25.9%高1.2个百分点。同一时期销售管理费从410.71亿日元升到580.57亿日元,原因是Infocom并表和计划投入前置。因此营业利润率仍停在11.6%至11.7%,上半年为11.7%,上年同期10.2%。毛利率的收益有一部分被花在了能力建设上。
TAM占比、AI生产率、人才稀缺下的定价权,以及600亿日元的缺口,最后都要反映在毛利率这一条线上。销售管理费是管理层可以调节节奏的成本项。项目级盈利、损失准备以及销售管理费增加的具体归因,公司都没有披露。每半年的业绩,都应先看毛利率。
06.3|2026年3月期经营现金流为负,原因是税款错期和一笔和解款
2026年3月期税前利润452.86亿日元,经营现金流却是负34.09亿日元。解释有两项。其一,实际缴纳所得税492.46亿日元,当年税费只有131.18亿日元,差额是上一年出售证券(收入785.23亿日元)获得的收益在这一年才缴税。其二,经营现金流里含有50亿日元的和解款。扣除利息和税款之前,经营现金流为516.48亿日元。
和解款来自2020年Mizuho Toshiba Leasing提起的诉讼,索赔109.26亿日元,起因是NetOne前员工的虚假交易。NSSOL是被告,NetOne支付了40亿日元,NSSOL自己的现金流量表记录支付50亿日元,2025年5月在东京地方法院达成和解。2027年3月期上半年经营现金流转为正312.35亿日元(上年同期为负122.99亿日元),这些因素已经退出。
同年投资现金流为负593.80亿日元,其中收购子公司544.23亿日元;融资现金流负216.20亿日元,含分红141.80亿日元、租赁还款69.74亿日元。现金从1,929.31亿日元降到1,087.98亿日元。
我的判断是:这是时间错位和已识别的非经常项目,没有盈利恶化的证据,应当按两年滚动合计来读。税款中多少属于证券收益、多少属于普通负债,公司没有披露,这个归因由上半年现金流的反转和利润率推断而来,把握一般。2027年3月期全年经营现金流是确认这一判断的下一份数据。因为资本开支轻、没有负债,50%的分红可以直接由经营现金流支付。
06.4|合同资产在增长中占用现金,是判断周期的观察指标
增长会占用营运资金。合同资产(已确认收入、尚未向客户开票的部分)2026年3月期增加76.44亿日元到313.41亿日元,2027年3月期上半年再增90.27亿日元到403.69亿日元。同期应收账款从735.15亿日元降到659.33亿日元,因为年末账款被收回;合同负债从337.74亿日元降到317.15亿日元。
这种增加和项目量增长成比例,是系统集成行业常见的季节性。它在需求稳定时没有问题,需求转弱时会变成完工与回款风险。它也给经营现金流增加了一层时间错位:建设期压低现金,回款期释放现金。合同资产的账龄、滞留项目的集中度和在手订单公司都没有披露。合同资产的变化和各领域的评论可以一起作为周期的早期信号。
06.5|没有有息借款:风险从负债端移到商誉和被托管的现金
资产负债表上没有公司债或银行借款。2026年3月末负债1,287.75亿日元,包括应付账款391.13亿日元、合同负债337.74亿日元、租赁负债251.49亿日元、退休福利负债225.53亿日元和准备金12.82亿日元,权益比率66.9%(2026年9月末65.9%)。杠杆在这个股权故事里不起作用,再融资和契约风险都不存在,摊薄风险在证据中为零。
风险因此搬到了资产端:并购商誉能否被盈利支撑,以及资金池里的现金能否被少数股东真正使用。2026年9月末资金池存款1,144.51亿日元,占现金1,273.68亿日元的大头;2026年3月末为944.02亿日元,占现金1,087.98亿日元的86.8%。这笔现金是真的,却不是自由现金:它的价值取决于母公司的信用,存放利率、通知期和提取条件未披露。把它当作自由净现金,会高估少数股东能够动用的部分。
这笔现金也在压低ROE:权益比率在66%至67%,ROE为11.4%,计划目标是13%左右。资产负债表防得住破产,防不住股价20%到45%的账面回撤。退休金假设和租赁期限分布未读。
07|股东、董事与治理
07.1|日本制铁在需求、现金和控制权三个渠道同时用力
日本制铁的位置是理解这家公司股东回报的关键。它持有63.44%表决权,是最大客户(705.50亿日元,占营收18.5%),通过资金池托管九成左右的集团现金,有效流通股只有11.56%上下。四十多年里,公司几经更名与重组,母公司的控制没有变过,这是判断持股走向的基准情形。
同一个变量通过三个渠道起作用,并在第四个渠道上放大。需求上,母公司的订单支撑了收入的稳定;现金上,资金池带来了资产负债表的安静;控制权上,少数股东在治理议题上没有否决权;流通股上,市值的每一次跳动都来自很少的几个持股人。结果是业务稳、折价长。
两股力量在反方向:活跃投资者3D Investment Partners已经出现在大额持股申报里,东京证券交易所对上市公司的改革压力也在推动资本效率。母公司对持股的最终意图、关联交易定价和董事会的审议方式,公司治理报告尚未读到。现任社长是Kazuhiko Tamaki,董事会构成和薪酬安排同样未读。对治理走向的判断把握一般。
07.2|资金池:同一笔钱既是下行保护,也是折价的原因
资金池在经济上是向控股股东的关联方存款。公司披露了这笔安排,并把它描述为提高资本效率,另外还和母公司有透支额度。问题在于「净现金」的质量:它取决于母公司的信用,也取决于没有披露的利率和通知期。
这笔钱同时是两件事。作为下行保护,它让公司几乎没有财务风险;作为治理折价的来源,它说明少数股东对资金的用途没有发言权。资金池条款一旦被披露,两个判断会同时被重估。存放条款是否经过独立董事的公平交易审议,目前无法确认,见第13章。
07.3|流通股很薄,活跃投资者在场:治理事件可能突然来
有效流通股比例据二手估算只有11.56%左右,这是对一家东证Prime公司来说极薄的流通盘。信用交易余额不大:买方62,500股、卖方47,000股(参考日为2026年7月),占183,002,000股发行股数微乎其微,杠杆持仓不构成压力。
3D Investment Partners出现在大额持股申报的清单里,持股规模和诉求要看原始申报,目前未读。流通股薄加上活跃投资者,再加上控股股东,是治理事件突然发生的典型条件:投资者可以推动母公司关系和资本政策的讨论,从而带来估值上修;也可能引发公开对抗,母公司以收紧控制回应。一个持股人的订单对价格的影响,可能超过一个季度的业绩,这与财报后价格下跌4.43%的反应一致。升级的时间无法预知。
08|资本政策
08.1|约50%的分红比率兑现了,每股增长只靠盈利
股东回报政策清晰且真实兑现。2025年3月期分红74日元(分红比率50.1%,净资产分红率5.4%)。2026年3月期85日元(50.4%,净资产分红率5.8%,年末比预期上调5日元,分红总额155.53亿日元)。2027年3月期计划89日元,其中中期44.50日元。分红由董事会依据公司章程决定。
没有有意义的回购:库存股只有20,595股,发行股数固定在183,002,000股(2024年7月1拆2之后),因此每股增长只来自盈利增长和分红,没有回购带来的额外贡献,摊薄也不存在。分红可以由经营现金流直接支付,这一点见第6章。本研究没有取得公司披露的股东总回报数据。
未解的问题在资本效率:大量现金闲置并存放在母公司处,ROE 11.4%低于计划目标13%左右。2028年3月期营业利润如果落在490亿日元的年化水平与600亿日元的目标之间,派息比率是否提高、还是在较小的利润基数上守住50%,没有答案,见第13章。
08.2|收购把现金换成靠预测支撑的资产,成长腿与减值尾巴是同一个变量
2026年3月期,Infocom(2025年7月并表)和印尼的PT. WCS Abyakta Nawesena成为全资子公司,新并表公司共六家,收购子公司股份付出544.23亿日元。商誉从29.23亿日元升到318.23亿日元,无形资产从40.39亿日元升到325.80亿日元,合计644.03亿日元,占总权益2,888.08亿日元的22%左右,几乎全部发生在这一年。2026年5月并入的B-Prost表明收购仍在继续。
收购带来营收和稀缺的工程师,也把现金换成账面价值靠管理层预测支撑的资产。日本IFRS下同类减值往往不会逐步确认,而是一次到位,同时冲击资产负债表和收购带来的成长腿。成功与风险在这里是同一个变量。
购买价格分摊、可使用年限和减值测试假设尚未读到。一份二手资料的中期口径为575.10亿日元,和公司的644.03亿日元不一致,口径差异未能核实。这笔投入的资本回报要等2028年3月期之后才能判断。
09|估值与安全边际
09.1|估值快照:市盈率21.6倍,是质量复利型与母公司折价之间的折中
2026年11月6日收盘3,819日元(研究截止日11月9日)。总市值6,988.85亿日元,即3,819日元乘以183,002,000股发行股数。
按修订后2027年3月期预测每股收益177.06日元,市盈率(PER)21.6倍;按2026年3月末每股净资产1,525.86日元,市净率(PBR)2.50倍,IRBANK以9月末约1,563日元算为2.44倍;ROE 11.4%(2026年3月期实绩);预测股息率2.33%;EV/EBITDA 9.8倍。
EV 5,715.2亿日元是总市值减去2026年9月末净现金1,273.68亿日元,EBITDA 581.31亿日元是2026年3月期营业利润442.42亿日元加折旧摊销138.89亿日元。各项口径的期间并不一致:预测市盈率用预测每股收益,市净率用3月末净资产,EV用9月末现金,EBITDA是上一整年。净现金大部分在母公司的资金池里,不能按自由现金看。
这个倍数是质量复利型公司与母公司控制折价之间的折中。它已经包含2027年3月期的指引、对下半年隐含下降的怀疑,以及对600亿日元计划的部分信用,但没有计入任何治理事件。没有建立市场一致预期,也没有正式的同业中位倍数。
09.2|正常化盈利以2027年3月期预测的324亿日元为底
正常化的归母利润大致是2027年3月期预测的324亿日元(营收4,190亿日元,营业利润率11.7%左右),并按TAM组合允许的速度,从2026年3月期的308.32亿日元往上走。两个连续的记录年度和不断上升的毛利率,构成这个底座。
三类项目不进入正常化:2025年3月期综合收益里的证券收益、2026年3月期的税款错期和50亿日元和解款,它们都是非经营项目,不影响年化水平。盈利能力的增长遵循组合公式:营收以高个位数到低两位数增长,毛利率每年提高1个百分点上下。600亿日元是进取情形。2028年3月期之后取决于下一轮计划,现在无法判断。这个正常化是研究的构造,不是公司公布的数字。
09.3|折价从哪里来:母公司的控制结构,只有母公司或股东压力才能改变
为什么一家创纪录、无负债的复利型公司只拿21.6倍的折中倍数?解释是母公司的三重控制:需求、现金和表决权让业务稳,却让估值上修没有自动的路径。这个解释是研究的推断,并没有被市场直接确认。
撬动折价的杠杆只有三个:母公司持股、资金池条款、派息比率。它们都不由公司经营决定。即使计划如期兑现,折价也未必收窄;而一个治理事件可以在没有任何业绩变化的情况下改变倍数。
09.4|价格已经为计划的最后一步付了一部分
买入者为第一步的计划兑现付了全价,只用部分折价换到了治理期权。2027年3月期指引490亿日元与600亿日元目标之间还有110亿日元,缺口只能靠TAM占比和毛利率共同补上,而这两项都是管理层自己定义的指标。
11月2日的记录业绩公布后价格被卖出,表明市场更在意下半年隐含的利润下降和110亿日元的计划缺口,而不是记录的标题。这是一次单一的事件观察,没有一致预期数据可以验证。倍数既不便宜也不昂贵,估值上修主要靠盈利增长,不能依靠倍数修复。
09.5|安全边际:防得住破产,防不住股价回撤
基本面的下行保护来自不举债:没有偿债和再融资压力,现金转化在两年窗口内扎实,分红由经营现金流覆盖。这些保护防止的是本金永久损失,不等于现金可以自由分配,也不阻止账面回撤。
价格侧的下行风险可以直接量化:高位箱体下沿的3,075至3,259日元,比11月6日的3,819日元低550日元以上;若失守,下一个锚点在2,000日元附近的旧区间,60个月均线2,851日元是2023至2024年上移被否定的位置。2.33%的股息率只提供有限的缓冲。具体的价格结构见第10章。商誉减值和资金池条款没有披露,是安全边际里仍未量化的部分。
10|Kabugami 技术结构
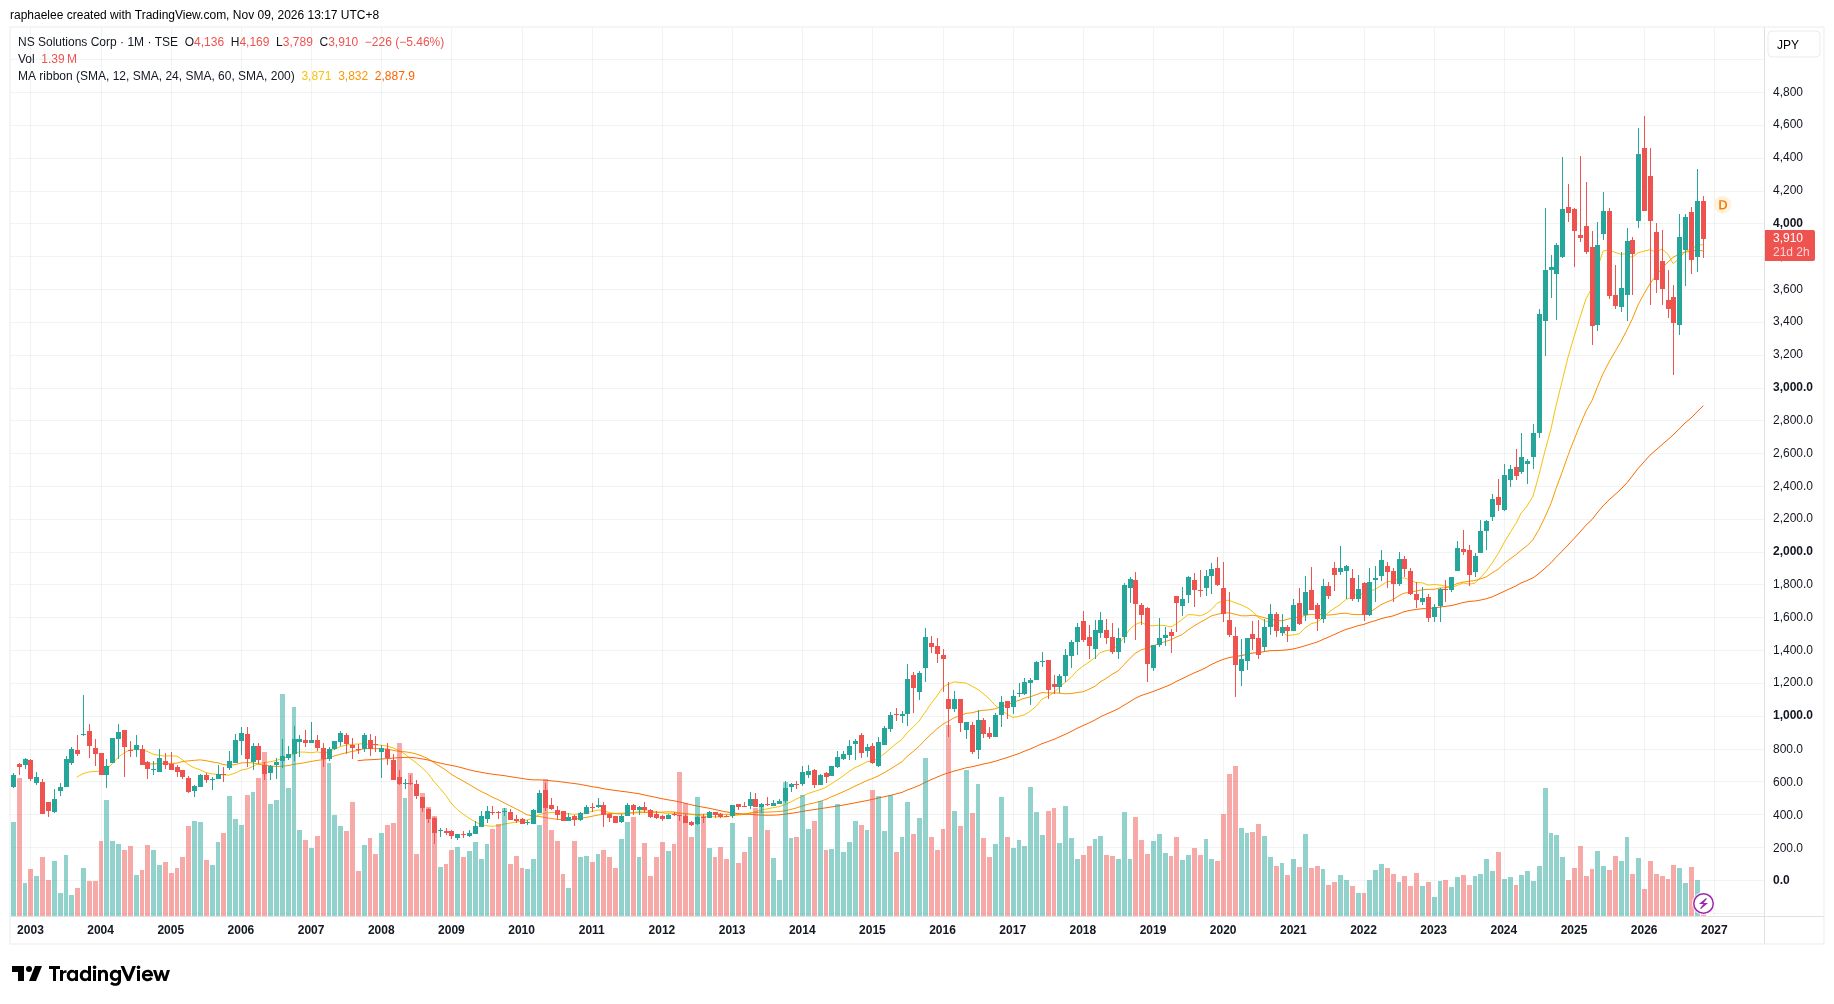
10.1|二十年低位之后,价格在2023至2024年上移到一个高位箱体
技术问题很具体:二十年里绝大多数月份收盘低于2,000日元,2023至2024年价格上移到3,075至4,655日元的区间,这个区间是在固化成新的价格重心,还是两次冲高失败预示价格回向旧区间?
先说数据。使用的是2002年10月至2026年10月共289根经拆股调整的月线,镜像数据截至2026年10月20日,最后一根10月月线并未走完,收盘4,118日元。
历史最高4,655日元出现在2026年1月,历史最低231日元出现在2008年10月。IRBANK的拆股调整年度区间给出2026年3月期高点4,655日元(2026年1月23日)和低点3,259日元(2025年4月30日),与镜像数据完全吻合。
11月6日收盘3,819日元来自IRBANK,比镜像更新,作为当前价格;均线以镜像数据算到10月。
价格行为是这样的:2002年上市时在640日元左右,2008年探到231日元。2009至2022年大致在440至2,440日元之间运行,87%的月线收盘低于2,000日元(22%在0至500日元,32%在500至1,000日元,15%在1,000至1,500日元,18%在1,500至2,000日元)。
2023年台阶式抬升,年末收盘2,288日元,上涨70%。2024年继续抬升,最高4,405日元,收盘4,072日元,上涨78%,其间7月实施1拆2。
下文把2025年4月以来价格反复运行的3,075至4,655日元区间称为高位箱体,把2023至2024年价格从旧区间整体抬到箱体的过程称为上移。
10.2|箱体内的价格行为:下探被快速买回,冲高两次在同一高度受阻
上移完成之后,价格在箱体内走出了清晰的形态。2025年4月低点3,259日元,2025年12月高点4,580日元,2026年1月创历史新高4,655日元,2026年6月低点3,075日元,10月(截至20日)收盘4,118日元。两次冲高在三个月内几乎被同一高度拦住,两次下探都被买回。
每一次偏离,向下的4月和6月,向上的1月,都在一到三个月内被拉回箱体中点3,850日元附近。向任何一个方向都没有形成突破,箱体把价格拉回的速度快于趋势形成的速度,回拉力量占主导。
箱体的中点约3,865日元,12个月均线(3,863日元)和24个月均线(3,838日元)都收敛在这个位置:两年期平均持仓成本与区间中点是同一个价格。60个月均线2,851日元仍在下方上行,标记着上移之前的世界在哪里结束。
恢复速度在加快:2025年4月的下探用了八个月才回到之前的收盘水平,2026年6月的低点在四个月内就回到4,118日元。但每一次恢复都停在4,580至4,655日元这个固定的上限,速度被花在一堵固定的墙上。下跌被买回得更快更彻底,上涨则追不上去:两次V型回收对两次失败的冲高。
收益形态也是台阶式,不是趋势式:2023年上涨70%,2024年上涨78%,完成了上移的全部工作;2025年只有8.6%;2026年到10月为下跌6.9%(数据到10月20日)。动量已经衰减成区间震荡。
没有压缩:箱体内的月度波动超过1,500日元,2023年之前通常只有几百日元。结构松散而活跃,是分歧区间,不是蓄势的底部。12月的4,580日元和1月的4,655日元两次失败的冲高留下了近期且具体的上限记忆。第三次受阻会让上限成为结构里最主要的事实,月线收盘站上4,655日元则会抹去它。
10.3|当前状态:箱体中段略偏弱,上移尚未被确认
11月6日收盘3,819日元,略低于12个月和24个月均线,位于箱体中段,价格形态中性偏弱,处在3,800至3,870日元这个关键位置:区间中点和平均成本在这里重合。下方的支撑带是3,075至3,259日元,上方的压力带是4,580至4,655日元。价格在五年区间(1,570至4,655日元)的82.6%、历史区间的87.9%,在整个区间里位置很高,但这个位置已经两次被拒绝在上沿。
停留历史很短是结构的弱点。289根月线里,261根(90%)收盘在2,440日元以下,2,000日元以上的月份只有34个月左右。高位的停留既年轻又单薄,统计上的支撑很浅。目前只能说旧状态的控制力在减弱,新状态还没有建立。
往后确认要看三件事:月线收盘站上4,655日元,抹去两次受阻并确认上移;月线收盘回到4,000日元之上且12个月均线拐头向上,说明11月的疲弱只是箱体内的噪音;回测3,075至3,259日元的支撑带并在月线收盘守住3,000日元。
推翻的条件有三个:月线收盘跌破3,000日元,箱体下沿失守,年轻的高位停留被放弃;月线收盘跌破60个月均线2,851日元,2023至2024年的上移被否定;连续两个月月线收盘低于3,800日元且12个月均线下行,价格重心从箱体回到旧区间。
本节没有成交量和月线以下周期的证据,相对强弱和价量配合也没有纳入,判断仅建立在价格结构、停留分布和响应形态上。技术判断把握一般。
10.4|事件响应与时序:业绩创纪录,价格没有留住好消息
价格结构形成之后,再看它对公开事件的反应。11月2日公布了创纪录的中期业绩并上调全年预测,11月6日收盘下跌4.43%,报3,819日元,略低于12个月均线3,863日元和24个月均线3,838日元:区间中点和两年平均成本恰好重合的位置。好消息没有留下更高的价格。
这只是一次单一的事件观察,没有一致预期数据可以验证。价格的反应与市场正在计价下半年隐含下降和110亿日元计划缺口的看法一致,但这个解读没有被直接证实。基本面不是技术状态的成因,这里只是价格对公开信息的响应。
时序上,价格先动:2023至2024年价格上移,当时公司的中期计划正在成形;基本面随后跟上,2026年3月期和2027年3月期出现记录业绩和预测上调。计划的最后一步(2028年3月期600亿日元)仍在被提前计价,所以时序风险现在是基本面在追一个已经停止上行的价格。
两个事实同时成立:财报描述的是一家创纪录、分红50%的复利型公司,图表描述的是一个年轻单薄的高位停留、两次受阻的上限和一个滑到两年成本之下的价格。箱体下沿比当前价格低550日元以上,两个事实之间的这道距离,就是这个仓位真正的风险度量。
11|风险与催化剂
11.1|三个已定日期的检验,加一组没有日期的治理事件
最近的检验是2027年1月下旬的2027年3月期第三季度业绩,日期按公司惯例日程推断,尚未公告。它要看三件事:下半年隐含的利润下降是否成真,TAM占比是否朝50%左右的中间目标走,以及是否再次上调。随后是2027年4月下旬的全年业绩,带来年末分红和2028年3月期的第一份指引;再后是2027年6月的股东大会,要看是否出现关于母公司关系、资金池或资本政策的提案。
没有日期的是治理事件:任何涉及母公司持股、资金池条款或流通股的披露,包括减持、资金池之外的回购、对活跃投资者的回应,都会直接作用在折价上。经营类事件检验经营故事,治理类事件检验折价故事。3D是否在股东大会前升级无法预知。
11.2|下半年隐含的利润下降:是保守,还是真实的组合恶化
从修订后的全年指引减去上半年实绩,下半年营收2,200.22亿日元、营业利润257.91亿日元(利润率11.7%左右)、归母利润175.43亿日元,比上年同期低6.8%(二次推算)。一份创纪录的全年预测里藏着一次利润下降。
我的判断是阶段性保守,而不是恶化:同一管理层已经两次上调,毛利率和领域广度同时改善。但这仍是假设,要到第三季度业绩才能验证。市场在11月2日之后的卖出,说明它拒绝提前给这种保守以信用。如果下降成真,价格会向箱体下沿靠拢;如果指引再被上调,会向箱体上沿靠拢。解决所需的证据见第13章。
11.3|Infocom商誉:减值一次到位,同时冲击资产和增长腿
644.03亿日元商誉与无形资产约占总权益的22%,其账面价值依赖管理层预测。如果Infocom的盈利或收购管线不及预期,减值会一次性冲击净资产和权益比率,同时让计划里由收购带动的增长部分被重新定价。这属于估值和权益比率的事件,不是融资事件。触发条件和购买价格分摊尚未读到,见第13章。
11.4|母公司收紧还是放松,决定哪个故事先落地
母公司对63.44%持股的最终意图未知。大阪制铁的先例是母公司减持到51%后停止,但母公司在公司上四十多年保持控制是更长的基准。如果母公司以偏低价格公开收购少数股权,收紧控制,折价看法就成立;如果减持、披露资金池的市场条款或提高派息比率,折价才会缩小。3D的出现既可能推动前一路径,也可能引发公开对抗。全部判断来自先例推断,没有找到公司或母公司对意图的任何表态。
其他风险散见各章:AI替代按人月计费的收入(第4章)、防卫大项目需要替换(第3章)、合同资产在需求转弱时转为回款风险(第6章)。
12|反常识发现
12.1|同一份创纪录业绩,市场选择了另一种解释
管理层的惯例是先给保守指引,再逐步上调;上半年利润超过第一季度阶段的指引,似乎在印证这个惯例。市场在11月2日的反应却相反:创纪录的业绩被卖出。
这里有一个预期落差。公司一侧的解释是阶段性保守,市场一侧的解释是下半年隐含的利润下降和110亿日元的计划缺口。两种解释目前都是假设,只有第三季度业绩能裁决。业绩若再次上调,管理层的惯例得到确认;若下半年真实走弱,市场的怀疑被证实。预期落差的方向决定价格会向箱体的哪一端靠拢。
12.2|一个变量四条渠道:为什么一条公告可以让价格跳空
日本制铁通过四条渠道作用于同一只股票:客户需求、现金托管、表决权和有效流通股。它同时稳住了需求和资产负债表,压住了估值上修,让分红支撑的价格下沿变硬。
50%的固定派息比率对应11.6%上下的流通股,意味着追求收益的买家在争抢很少的股份,这抬高了下沿;同样的薄流通盘,也让一条治理消息就能让价格穿过它跳空。已观察到的活跃投资者和东证改革压力,是唯一松动这个结构的力量。这是这次研究对结构的整合性判断:折价不是由经营决定的,它可能在计划兑现之后依然存在。母公司意图、资金池条款和3D的位置都还是未知。
13|下一次值得跟踪什么
13.1|最先要回答的三个问题:下半年、母公司意图、资金池条款
下半年隐含的利润下降是保守,还是被创纪录标题盖住的真实组合恶化?这个问题最重要,因为它裁决管理层惯例与市场怀疑谁对,答案相反时价格分别指向箱体上沿或下沿。2027年1月下旬的第三季度业绩,带着TAM占比、毛利率和是否再上调,是能回答它的证据。下半年归母利润175.43亿日元、低于上年同期6.8%,是二次推算。
日本制铁对63.44%持股的最终意图是什么?它决定折价走向放松还是收紧。如果母公司减持(大阪制铁先例是降到51%),流通股和折价会直接被重估;如果以偏低价格公开收购少数股权,折价看法被确认。能回答的证据是任何母公司对持股、公开收购、减持或对活跃投资者回应的披露,目前只有先例推断。
资金池里的1,144.51亿日元,利率、通知期和提取条件是什么,董事会谁按公平交易批准?它同时关系下行保护和治理折价,条款若按市场水平披露,两者会一起重估。能回答的证据是公司治理报告、有价证券报告书的关联方附注或公司披露。
13.2|第二层问题:3D的诉求、Infocom的分摊、TAM由谁验证
3D Investment Partners持股多少,向董事会提了什么?它决定治理事件会推动估值上修还是引发母公司收紧。答案在EDINET的大额持股报告书及变更报告里,目前未读到原文。
Infocom的购买价格分摊支持多少商誉,需要它交付多少盈利,什么会触发减值?它决定644.03亿日元资产的脆弱程度。答案在2026年3月期有价证券报告书的企业合并与商誉附注。
TAM占比由谁验证,现有人力收入能否被归类为TAM而经济性不变?它是计划的核心机制,答案相反时计划失去解释力。答案是经审计或披露的定义,以及2027年3月期全年实绩与50%左右中间目标的对照。每半年的毛利率则是最直接的间接检验。
13.3|第三层问题:防卫需求续约、领域披露口径、股东大会提案、派息路径
咨询与数字服务上半年的防卫需求,能否在2028年3月期以相近规模续约或替换?它决定增长质量,如果只是单一项目的脉冲,年化后增长会掉下来。防卫业务的规模未披露,答案在2027年3月期全年的领域披露。
公司何时披露新分类下全年的领域收入?2026年3月期已重述,只有这份披露才能把商业解决方案和咨询与数字服务的分拆与2026年3月期对照审计。
2027年6月的股东大会季是否会出现关于母公司关系、资金池或资本政策的提案?这一点关系治理事件的时间。
如果2028年3月期营业利润落在490亿日元的年化水平与600亿日元的目标之间,派息比率是否提高?它决定分红是在较小利润基数上守住50%,还是被主动提高。答案是2027年3月期年末分红决定和2028年3月期的指引。
13.4|每次业绩都要核对的门槛
判断是否上修,先看哪几个数?因为它们把叙事变成可核对的检验。到2027年3月期全年业绩:TAM占比是否在50%左右或以上,毛利率是否不低于27%,2028年3月期指引是否可信地通向600亿日元。下修信号:TAM低于45%左右且毛利率回到26%以下,2028年3月期指引开在520亿日元左右的推算线以下,Infocom减值,母公司收紧控制。门槛由研究设定,不是公司承诺。
合同资产的增减,与各领域的评论一起,是判断周期的早期信号,值得和毛利率同时看。
14|Kabugami 评分卡
14.1|总分63.21/100,评级B,持有并跟踪、不追高
Kabugami评分(V3.2)为63.21/100,评级B。操作:持有并跟踪,不追高。业务质量和盈利兑现支持继续持有,但价格处在已两次受阻的箱体中段,估值已计入部分计划兑现,治理折价没有近期的解决路径。
2027年1月下旬的第三季度业绩,检验下半年隐含的利润下降、TAM占比50%左右和毛利率不低于27%,是下一个关键检查点。若毛利率和TAM占比同时达标,可以考虑在价格回到下方支撑带附近时增加仓位;若TAM停滞、毛利率回落或母公司收紧控制,则应降低判断。
14.2|八个模块的得分与理由
财务韧性与下行防御:10.4/13分。无借款、权益比率65.9%、轻资产,偿债和再融资风险基本不存在;扣分来自九成现金存放在条款未披露的资金池,以及644.03亿日元商誉的减值风险。
竞争优势与结构耐久性:9.8/14分。核心系统嵌入带来高切换成本,但没有续约率、合同期限和独立份额数据,TAM口径也未经审计,护城河有迹象而未验证。
盈利质量、现金转化与资本效率:12.58/17分。毛利率从24.2%升到27.1%,两年创纪录,现金错期已得到解释;下半年隐含下降和TAM口径未审计限制了上限,ROE 11.4%低于计划目标13%左右。
商业结构、产品、客户与关键依赖:7.48/11分。客户分散,对外占八成左右,母公司占18.5%,但上半年的加速依赖一个防卫项目,替换要到2028年3月期才见分晓。
估值与安全边际:7.2/15分。市盈率21.6倍、市净率2.50倍已计入部分计划兑现,没有计入治理事件,安全边际有限,且各项计算混用了不同期间。
资本配置与股东回报:5.8/10分。50%派息持续兑现、没有摊薄,但没有回购,大量现金闲置在母公司处,并购回报未经验证。
治理、所有权与管理层:2.8/7分。母公司同时控制表决权、客户、现金和流通股,最终意图、资金池条款和3D的诉求均未明确。
Kabugami 技术结构:7.15/13分。2023至2024年上移后在高位箱体守了22个月左右,但两次冲高在4,580至4,655日元受阻,价格略低于两年均线,旧状态的控制力在减弱,新状态尚未确认。
14.3|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 10.4 | 公司没有银行借款和公司债,2026年9月末权益比率65.9%(2026年3月末66.9%),资本开支约54亿日元,属于轻资产、无杠杆、自有资金经营。偿债、再融资和契约风险基本不存在。但约九成集团现金(2026年9月末1144.51亿日元,占1273.68亿日元的大头)存放在控股股东日本制铁的集中资金管理体系里,存放利率、通知期和提取条件未披露。另外2026年3月期并购使商誉和无形资产合计升至644.03亿日元,约占总权益的22%,资产端的减值风险取代了负债端风险。 |
| 竞争优势与结构耐久性 | 14 | 9.8 | 公司是日本制铁集团出身的系统开发商,工程师和可复用资产深度嵌入客户核心系统,覆盖咨询、设计、开发、运维全周期,切换成本高、收入连续性好。对外客户约占八成,业务不只靠母公司。管理层正在把人月计价的人力服务转向次世代系统集成、资产运用和平台提供三类“TAM型”业务,占比从2026年3月期的38%提高到2027年3月期约50%,目标2028年3月期约75%。 |
| 盈利质量、现金转化与资本效率 | 17 | 12.58 | 2026年3月期营收3813.4亿日元(增12.7%),营业利润442.42亿日元(增14.9%),ROE 11.4%;2027年3月期上半年营收1989.78亿日元(增11.6%),营业利润232.09亿日元(增27.0%),归母利润148.57亿日元(增23.7%)。毛利率从24.2%升至26.7%,上半年27.1%,利润增速高于收入增速主要来自产品组合,不是一次性收益。公司在年内分阶段上调指引:营业利润490亿日元,归母利润324亿日元,分红89日元,常见保守指引后逐步上调的模式。 |
| 商业结构、产品、客户与关键依赖 | 11 | 7.48 | 客户覆盖制造业(钢铁、汽车、化工、食品、铁路)、金融机构和公共部门,对外部客户依赖约八成,业务相对分散。日本制铁是最大单一客户,2026年3月期贡献705.5亿日元,占营收18.5%,比2022年3月期的20.4%略降。关键依赖是工程师供给,而不是原材料或设备。 |
| 估值与安全边际 | 15 | 7.2 | 2026年11月6日收盘价3819日元,市值约6988.8亿日元,按2027年3月期预测每股收益177.06日元计市盈率约21.6倍,市净率约2.50倍,预测股息率2.33%,EV/EBITDA约9.8倍(扣除1273.68亿日元净现金,且该现金大部分在母公司集中管理体系中)。这个倍数是优质复利型公司与母公司控制折价之间的折中:已计入2027年3月期指引和部分计划兑现,但没有计入治理事件。 |
| 资本配置与股东回报 | 10 | 5.8 | 股东回报政策清晰并真实兑现:约50%合并派息率,2025年3月期74日元(派息率50.1%),2026年3月期85日元(50.4%,年末比预期上调5日元),2027年3月期计划89日元;发行股数固定在1.83002亿股,库存股仅20595股,没有稀释风险。 |
| 治理、所有权与管理层 | 7 | 2.8 | 日本制铁持有63.44%表决权,同时是最大客户(约18.5%营收),并通过集中资金管理保管约九成集团现金,有效流通股比例据估计只有约11.56%。同一个控股股东在需求、现金、控制权和流通股四个渠道同时发力,使得公司业务稳定,但少数股东在治理议题上没有话语权。活跃投资者3D Investment Partners已出现在大额持股申报中,东京证券交易所的改革压力是反方向的力量。 |
| Kabugami 技术结构 | 13 | 7.15 | 股价在2023至2024年从过去二十年主要低于2000日元的区域迁移到3075至4655日元的高位区间,已持有约22个月,但这个高位停留的历史很短(约34个月高于2000日元),且在2025年12月的4580日元和2026年1月的4655日元两次受阻。11月6日收盘3819日元,位于12个月和24个月均线(约3838至3863日元)附近稍下方,近期回落时跌破了两年的平均持仓成本,新状态还没有被确认。 |
总分: 63.21 / 100 评级: B 操作建议: 持有并跟踪,不追高:业务质量和盈利兑现支持继续持有,但价格处于已两次受阻的区间中位,估值已计入部分计划兑现,治理折价缺乏近期解决路径。2027年1月下旬的第三季度业绩(检验下半年隐含的利润下降、TAM占比约50%、毛利率不低于27%)是下一个关键检查点;若毛利率和TAM占比同时达标,可考虑在价格回到下方支撑带附近时增加仓位;若TAM停滞、毛利率回落或母公司收紧控制,则应降低判断。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|资料来源与日期:以公司披露为主,价格截至2026年11月6日
本报告的评审日期为2026年11月9日。价格取自2026年11月6日收盘(IRBANK)。月线价格结构使用Yahoo Finance月线数据的镜像,截至2026年10月20日,最后一根10月月线未走完;技术判断基于完整月份和该日数据,11月6日收盘作为当前价格。
公司一手资料:2026年3月期财报(東証TDnet,2026年4月27日披露)、2027年3月期第一季度财报(2026年7月30日)、2027年3月期上半年财报(2026年11月2日)、公司章程(2020年6月22日提交)。外部资料:NetOne Systems关于诉讼和解的公告(2025年5月19日)、时事通信社对2026年11月2日业绩的报道。
二手资料用于交叉核对:IRBANK(2026年11月6日)、企业研究ノート(编译2026年3月期有价证券报告书的整理,无发布日期)、日语维基百科(2026年8月30日)、Mynavi 2027公司概要(2026年11月9日)。公司正式名称为日鉄ソリューションズ株式会社(NS Solutions Corporation),英文名取自公司章程。
15.2|证据限制:哪些事实没有核实,对判断有什么影响
以下事实目前没有核实,不能当作已知。2027年3月期上半年的中期有价证券报告书原定2026年11月10日提交,晚于评审日,其中的商誉、关联方和合同资产附注尚未读到。公司治理报告尚未读到,所以母公司最终意图、资金池的利率和提取条件、关联交易定价和董事会审议方式没有核实,这限制了治理和资金池相关判断的强度。EDINET上3D Investment Partners大额持股报告的原文未读,持股规模和诉求未知。
有效流通股11.56%是二手估算;领域收入是管理会计口径,且2026年3月期已按新分类重述;TAM占比由公司定义,未经审计;与Anthropic合作的商业条款、防卫项目占比、合同资产账龄、在手订单、续约率均未披露。没有取得市场一致预期,也没有建立同业中位倍数。
估值倍数的计算混用了预测每股收益、3月末净资产、9月末现金和上一整年EBITDA,是本研究的推算,不是新的一手事实;各项精度不应超过输入数据。正常化盈利、门槛数值和下半年6.8%的下降都是本研究的构造或二次推算。
第三季度业绩日期来自公司惯例日程,并非公司公告。
本报告为研究用途,不构成投资建议,也不构成买卖要约。数据不完整不等于结果不好,缺失的数据在可得之后可能提高也可能降低相应判断;投资者应自行判断并承担风险。
主要资料来源
- FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation
- Management-field revenue, H1 FY3/27 短信 qualitative section
- Articles of Incorporation of NS Solutions Corporation (filed 2020-06-22)
- NS Solutions Corporation company outline and history (cross-check)
- Company outline: employees, capital, leadership, NSSOL company overview
- Positioning versus the major SIers, company-research note on NS Solutions
- What the TAM model change means, Jiji Press report of the results
- Q1 FY3/27 results 短信 (IFRS), NS Solutions Corporation
- Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327
- Settlement of litigation, notice by NetOne Systems (auxiliary participant)
- Recomputed moving-average structure, 2327 monthly series
研究发现索引
展开本次 Review 的 46 项研究发现
F001|02|一家把工程师和可复用资产嵌进客户核心系统的轻资产服务商
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|一家把工程师和可复用资产嵌进客户核心系统的轻资产服务商
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(10项,重复标签已合并)
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接证据;一手验证:15、22、28
Management-field revenue, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:03、05、12、13
Management-field revenue, FY3/26 短信 (with reclassification note)怎么使用:直接 / 支持;一手验证:02、03
Segment information note: single segment, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:02、10
NS Solutions Corporation company outline and history (cross-check)怎么使用:直接证据;一手验证:01、09;外部现实校验:23
Company outline: employees, capital, leadership, NSSOL company overview怎么使用:直接证据;一手验证:06、23;外部现实校验:01、09、20;专项深挖:01
History spine 1980–2025, NS Solutions Corporation overview怎么使用:直接证据;一手验证:33;外部现实校验:07;专项深挖:33;同业比较:01、02、08、09;其他用途:历史
Positioning versus the major SIers, company-research note on NS Solutions怎么使用:直接证据;外部现实校验:02、03、05、06、08、10;专项深挖:06、07、08、09
What the TAM model change means, Jiji Press report of the results怎么使用:直接证据;一手验证:02;外部现实校验:04;专项深挖:02、03、10
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域13)|Management-field revenue, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03)|Management-field revenue, FY3/26 短信 (with reclassification note);直接证据 / 一手证据(研究域01)|Articles of Incorporation of NS Solutions Corporation (filed 2020-06-22);直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域10)|Segment information note: single segment, H1 FY3/27 短信;直接证据 / 一手证据(研究域01) / 一手证据(研究域09) / 外部现实(研究域23)|NS Solutions Corporation company outline and history (cross-check);直接证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域20) / 定向深挖(研究域01)|Company outline: employees, capital, leadership, NSSOL company overview;直接证据 / 一手证据(研究域33) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 定向深挖(研究域33)|History spine 1980–2025, NS Solutions Corporation overview;直接证据 / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域10) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域08) / 定向深挖(研究域09)|Positioning versus the major SIers, company-research note on NS Solutions;直接证据 / 一手证据(研究域02) / 外部现实(研究域04) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域10)|What the TAM model change means, Jiji Press report of the results
完整研究记录(核对用)
研究原文:NS Solutions is the Nippon Steel group's former captive systems house, now a Prime-listed, single-reportable-segment information-services company (about 80% external customers, 10,276 employees). It earns money by embedding engineers and reusable assets in customers' core systems across the whole life cycle (consulting, design, build, operation, maintenance), so switching costs are high and revenue recurs. Management runs two fields: Business Solutions (FY3/26 ¥286,506m, +17.7% restated) and Consulting & Digital Services (¥94,833m, flat). The model is migrating from person-month labour resale toward TAM-type work (next-gen SI, asset utilisation, platform provision). The economic lever is mix, not volume or price spikes. The business is asset-light (capex about ¥5.4bn), unlevered and self-financed, so cash is not constrained by capital intensity.
内部研究类型:durable_business_portrait_core
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Shareholders own a high-retention, service-heavy franchise whose profitability lever is the mix of work, with no capex treadmill or financial leverage.
不确定性(原始记录):Moat is inferred from business structure and revenue continuity; no contract-tenure, churn or independent share data.
F002|06|利润增长来自产品组合,不靠一次性收益
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|利润增长来自产品组合,不靠一次性收益
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15、22、28
H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:28
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:直接证据;一手验证:16;专项深挖:16
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:直接证据;一手验证:30、31、35;专项深挖:30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域15)|H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 支持证据|Q1 FY3/27 results 短信 (IFRS), NS Solutions Corporation;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;直接证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:FY3/26 and H1 FY3/27 are both record periods and quality improved with quantity: FY3/26 revenue ¥381,340m (+12.7%), operating profit ¥44,242m (+14.9%), attributable profit ¥30,832m, ROE 11.4%; H1 FY3/27 revenue ¥198,978m (+11.6%), operating profit ¥23,209m (+27.0%), attributable profit ¥14,857m (+23.7%). Guidance was raised in stages (April ¥47,500m → Q1 raise → November ¥49,000m operating profit; attributable ¥31,600m → ¥32,400m; dividend ¥87 → ¥89), with H1 profit beating the Q1-stage H1 guide while revenue landed just under it. The pattern is conservative guidance raised through the year, and the gains are operating, not one-off.
内部研究类型:earnings_quality_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operating earnings are compounding with a visible mix cause; the guidance convention is a signal to be tested, not a fact.
不确定性(原始记录):Record headlines coexist with an implied H2 profit decline (see N_H2); revenue guide slightly missed at H1.
F003|06|毛利率是整套逻辑里信息量最大的数字
研究范围:35项覆盖检查+开放研究
写入正文:06|毛利率是整套逻辑里信息量最大的数字13|第二层问题:3D的诉求、Infocom的分摊、TAM由谁验证13|每次业绩都要核对的门槛
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Income statement detail FY3/26, FY3/26 短信 (IFRS P&L)怎么使用:直接 / 支持;一手验证:15、16;专项深挖:15、16
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:16;专项深挖:16
Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements怎么使用:直接证据;一手验证:32;外部现实校验:17、28;专项深挖:17、32
Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet怎么使用:直接证据;一手验证:19;外部现实校验:15;专项深挖:15、19
查看完整证据标签(核对用)
直接证据|Q1 FY3/27 results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 定向深挖(研究域15) / 定向深挖(研究域16)|Income statement detail FY3/26, FY3/26 短信 (IFRS P&L);直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;直接证据 / 一手证据(研究域32) / 外部现实(研究域17) / 外部现实(研究域28) / 定向深挖(研究域17) / 定向深挖(研究域32)|Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements;直接证据 / 一手证据(研究域19) / 外部现实(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet
完整研究记录(核对用)
研究原文:Gross margin is the plan's single highest-information observable: 24.2% (FY3/25) → 26.7% (FY3/26) → 27.1% (H1 FY3/27, +1.2pt), while SG&A jumped from ¥41,071m to ¥58,057m in FY3/26 on Infocom consolidation and front-loaded plan spending. Operating margin therefore held near 11.6–11.7% — the gross-margin gain was partly spent on capability. TAM share, AI productivity, pricing power under labour scarcity and the ¥60,000m bridge all collapse into this line each half; SG&A is a management-controlled cost lever that can be re-timed.
内部研究类型:single_observable_mechanism
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Every future print should be read through gross margin per head; it is where AI-productivity and TAM claims either show up or do not.
不确定性(原始记录):Project-level profitability, loss provisions and SG&A step-up attribution beyond narrative are not disclosed.
F004|02|TAM型业务:从按人月计费转向资产与平台,口径是公司自己的
研究范围:开放研究+35项覆盖检查
写入正文:02|TAM型业务:从按人月计费转向资产与平台,口径是公司自己的13|第二层问题:3D的诉求、Infocom的分摊、TAM由谁验证
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信怎么使用:直接 / 支持;一手验证:04、35
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:直接 / 支持;外部现实校验:11;专项深挖:09、11、22、28、35
What the TAM model change means, Jiji Press report of the results怎么使用:直接 / 支持;一手验证:02;外部现实校验:04;专项深挖:02、03、10
Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:03、04、07
NSSOL 2030 Vision and the four transformations, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:10、11;专项深挖:02、03、04、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域35)|Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信;直接证据 / 支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域04) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域10)|What the TAM model change means, Jiji Press report of the results;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域07)|Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域10) / 一手证据(研究域11) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|NSSOL 2030 Vision and the four transformations, FY3/26 短信 qualitative section
完整研究记录(核对用)
研究原文:The TAM-type revenue ratio (T next-gen SI, A asset utilisation, M platform provision) was 38% in FY3/26 after +33% growth, is expected near 50% in FY3/27 and targeted near 75% in FY3/28. It is the plan's central mix metric and is delivered through Nestorium, NS Devia, Corepeak, NSRelato, Alli Coworker and the September 2026 Anthropic partnership, with +20% development productivity and +20% internal efficiency targets. The metric is management-defined and not independently audited; it is unclear whether existing labour revenue can be reclassified into TAM without changing its economics.
内部研究类型:mix_transition_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):If TAM share climbs and gross margin follows, earnings quality and the multiple improve; if the metric is definitional drift, the plan loses its mechanism.
不确定性(原始记录):Definition, audit and economics of the TAM classification are undisclosed; AI productivity outturns unmeasured; commercial terms of the Anthropic tie-up undisclosed.
F005|03|最大客户同时是控股股东:客户并不集中,但不完全独立
研究范围:开放研究+35项覆盖检查
写入正文:03|最大客户同时是控股股东:客户并不集中,但不完全独立07|日本制铁在需求、现金和控制权三个渠道同时用力14|八个模块的得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:直接 / 支持;一手验证:08、09、24
Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:29;外部现实校验:19
CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:21;外部现实校验:25;专项深挖:18、21
CMS deposit at September 2026, H1 FY3/27 短信 qualitative section怎么使用:直接证据;一手验证:21;专项深挖:21、29
History spine 1980–2025, NS Solutions Corporation overview怎么使用:直接证据;一手验证:33;外部现实校验:07;专项深挖:33;同业比较:01、02、08、09;其他用途:历史
Management-field revenue, H1 FY3/27 短信 qualitative section怎么使用:直接证据;一手验证:03、05、12、13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域19)|Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信;直接证据 / 一手证据(研究域21) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域21)|CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|CMS deposit at September 2026, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域33) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 定向深挖(研究域33)|History spine 1980–2025, NS Solutions Corporation overview;直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域13)|Management-field revenue, H1 FY3/27 短信 qualitative section
完整研究记录(核对用)
研究原文:Nippon Steel holds 63.44% of voting rights, is the largest single customer (¥70,550m, 18.5% of FY3/26 revenue, down gradually from 20.4% in FY3/22) and, through its cash management system, custodies about 90% of group cash (¥114,451m of ¥127,368m at September 2026; ¥94,402m or 86.8% at March 2026). The same grip underwrites demand stability and balance-sheet calm while capping the governance re-rating. The parent has held control unchanged through four decades of renamings and restructurings, which is the base rate for the stake question; the parent's steel-sector capex also transmits directly into the steel field (which fell in H1 FY3/27).
内部研究类型:control_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Minority shareholders hold a compounding business whose controller they cannot outvote; the discount is the price of that structure and lifts only on parent action or governance pressure.
不确定性(原始记录):Parent's end-state intention for the stake, board's arm's-length process and related-party transfer pricing on ¥70,550m of parent revenue are unread (governance report not read).
F006|06|没有有息借款:风险从负债端移到商誉和被托管的现金
研究范围:35项覆盖检查+开放研究
写入正文:06|没有有息借款:风险从负债端移到商誉和被托管的现金07|资金池:同一笔钱既是下行保护,也是折价的原因13|最先要回答的三个问题:下半年、母公司意图、资金池条款
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;外部现实校验:25;专项深挖:18、21
CMS deposit at September 2026, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators怎么使用:直接证据;一手验证:22;专项深挖:22、28
Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet怎么使用:直接证据;一手验证:18、25、29;专项深挖:18、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域21)|CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|CMS deposit at September 2026, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域28)|Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet
完整研究记录(核对用)
研究原文:The cash-management-system arrangement is economically a related-party deposit of about 90% of group cash with the controlling shareholder, disclosed and framed as capital efficiency, alongside an overdraft facility with the parent. 'Net cash' quality therefore depends on the parent's credit and on undisclosed rate and notice terms. The same balance is simultaneously downside protection for the company and the cause of part of the governance discount, and it mechanically dilutes ROE (equity ratio 66–67%, ROE 11.4% vs plan target ~13%). Any terms disclosure reprices both downside protection and the discount.
内部研究类型:related_party_cash_custody
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):The cash is real but governance-encumbered; treating it as free net cash overstates minority access, while disclosed market-rate terms would reprice the discount.
不确定性(原始记录):Terms undisclosed; residual securities portfolio composition not itemised.
F007|11|母公司收紧还是放松,决定哪个故事先落地
研究范围:开放研究+35项覆盖检查
写入正文:11|母公司收紧还是放松,决定哪个故事先落地13|最先要回答的三个问题:下半年、母公司意图、资金池条款15|证据限制:哪些事实没有核实,对判断有什么影响
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:直接证据;一手验证:08、09、24
Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327怎么使用:直接证据;外部现实校验:24、30、35;专项深挖:24
History spine 1980–2025, NS Solutions Corporation overview怎么使用:直接证据;一手验证:33;外部现实校验:07;专项深挖:33;同业比较:01、02、08、09;其他用途:历史
查看完整证据标签(核对用)
直接证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;直接证据 / 外部现实(研究域24) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域24)|Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327;直接证据 / 一手证据(研究域33) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 定向深挖(研究域33)|History spine 1980–2025, NS Solutions Corporation overview
完整研究记录(核对用)
研究原文:Nippon Steel's end-state intention for its 63.44% stake is unknown. The Osaka Steel precedent, where the parent tendered down and stopped at 51%, is the live analogue, but the parent's 45-year pattern is retained control. The stake, CMS and payout ratio are the three levers that would unlock or fix the discount.
内部研究类型:research_debt_governance
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A stake sell-down or tender would reprice the float and discount directly; a tightening move (captive-price tender) would falsify the loosening reading.
不确定性(原始记录):Wholly inferential from precedent; no company or parent statement of intent was found.
F008|06|2026年3月期经营现金流为负,原因是税款错期和一笔和解款
研究范围:开放研究+35项覆盖检查
写入正文:06|2026年3月期经营现金流为负,原因是税款错期和一笔和解款
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement怎么使用:直接 / 支持;一手验证:17、20、25、32
Consolidated cash flow H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:17
Settlement of litigation, notice by NetOne Systems (auxiliary participant)怎么使用:直接 / 支持;一手验证:33
Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements怎么使用:直接证据;一手验证:32;外部现实校验:17、28;专项深挖:17、32
Working capital build in H1 FY3/27, H1 FY3/27 短信怎么使用:直接证据;一手验证:19;专项深挖:17、19
Other expenses normalising after the dispute years, FY3/26 短信 P&L怎么使用:直接证据;外部现实校验:28;专项深挖:32;同业比较:16、32;其他用途:历史
H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation怎么使用:支持证据;一手验证:15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 一手证据(研究域25) / 一手证据(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域17)|Consolidated cash flow H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域33)|Settlement of litigation, notice by NetOne Systems (auxiliary participant);直接证据 / 一手证据(研究域32) / 外部现实(研究域17) / 外部现实(研究域28) / 定向深挖(研究域17) / 定向深挖(研究域32)|Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements;直接证据 / 一手证据(研究域19) / 定向深挖(研究域17) / 定向深挖(研究域19)|Working capital build in H1 FY3/27, H1 FY3/27 短信;直接证据 / 外部现实(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Other expenses normalising after the dispute years, FY3/26 短信 P&L;支持证据 / 一手证据(研究域15)|H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation
完整研究记录(核对用)
研究原文:FY3/26 operating cash flow was −¥3,409m despite ¥45,286m of pre-tax profit (operating cash flow before interest and tax ¥51,648m). Income taxes paid were ¥49,246m against a ¥13,118m expense, because tax on FY3/25's securities-sale gains (¥78,523m proceeds, ¥13,682m FVOCI gains) fell due a year late, and a ¥5,000m settlement payment sat inside operating cash flow. H1 FY3/27 operating cash flow reversed to +¥31,235m (vs −¥12,299m a year earlier) as those items rolled off. The settled lawsuit was the 2020 Mizuho Toshiba Leasing claim (¥10,926m) arising from a former NetOne employee's fictitious transactions; NS Solutions was defendant, NetOne paid ¥4,000m, and NS Solutions' own statement records ¥5,000m. Judgment: timing and identified non-recurring items, not earnings deterioration — read cash on rolling two-year sums.
内部研究类型:cash_conversion_anomaly_explained
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Profit does convert to cash over a two-year window; single-year readings will stay noisy around tax and legal events.
不确定性(原始记录):Medium: causal attribution is inferential from reversal; full-year FY3/27 operating cash flow is the confirming print.
F009|06|合同资产在增长中占用现金,是判断周期的观察指标
研究范围:35项覆盖检查
写入正文:06|合同资产在增长中占用现金,是判断周期的观察指标
还不能确定:Aging, stale-project concentration and order backlog (受注残) not disclosed.
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet怎么使用:直接 / 支持;一手验证:19;外部现实校验:15;专项深挖:15、19
Working capital build in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:19;专项深挖:17、19
Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信怎么使用:直接证据;一手验证:29;外部现实校验:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet;直接证据 / 支持证据 / 一手证据(研究域19) / 定向深挖(研究域17) / 定向深挖(研究域19)|Working capital build in H1 FY3/27, H1 FY3/27 短信;直接证据 / 一手证据(研究域29) / 外部现实(研究域19)|Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:Growth absorbs working capital: contract assets rose ¥7,644m in FY3/26 to ¥31,341m and a further ¥9,027m in H1 FY3/27 to ¥40,369m as revenue on in-progress projects is recognised ahead of billing; receivables ¥73,515m fell to ¥65,933m on collections; contract liabilities ¥33,774m eased to ¥31,715m. The build is growth-proportionate seasonality, healthy while the cycle holds but a completion/collection risk if demand turns. Contract-asset aging and backlog are undisclosed.
内部研究类型:working_capital_mechanism
内部来源标记:COVERAGE35
普通股东含义(原始记录):Expect half-year cash swings of this shape; watch contract assets as the cycle gauge.
不确定性(原始记录):Aging, stale-project concentration and order backlog (受注残) not disclosed.
F010|01|计划算术:产品组合比需求更紧
研究范围:开放研究+35项覆盖检查
写入正文:01|计划算术:产品组合比需求更紧09|价格已经为计划的最后一步付了一部分
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release怎么使用:直接 / 支持
Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信怎么使用:直接 / 支持;一手验证:04、35
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:28
NSSOL 2030 Vision and the four transformations, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:10、11;专项深挖:02、03、04、10
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:直接 / 支持;外部现实校验:11;专项深挖:09、11、22、28、35
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:30、31、35;专项深挖:30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据|Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域35)|Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域11) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|NSSOL 2030 Vision and the four transformations, FY3/26 短信 qualitative section;直接证据 / 支持证据|Initial FY3/27 guidance given with FY3/26 results;直接证据 / 支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;直接证据 / 支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:Mid-term plan targets for FY3/28 are revenue ¥450,000m, operating profit ¥60,000m, margin 13%, ROE ~13%. FY3/27 guidance of ¥49,000m operating profit leaves about ¥11,000m to close in one year. Volume growth alone at the current 11.6–11.7% margin does not arithmetically reach 13%; the bridge requires TAM share near 75% and continued gross-margin expansion. Mix, not demand, is the binding constraint, and a TAM shortfall and a margin shortfall would arrive together because the TAM metric is management-defined. The ¥60,000m figure is the stretch case, not normalised earnings.
内部研究类型:plan_arithmetic_tension
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The market is paying in advance for the plan's final step; a slip is a de-rating event.
不确定性(原始记录):Bridge composition not disclosed; falsification tripwires (FY3/28 guidance below ~¥52,000m bridge, TAM below ~45%) are analyst-stated, not company commitments.
F011|11|下半年隐含的利润下降:是保守,还是真实的组合恶化
研究范围:35项覆盖检查+开放研究
写入正文:11|下半年隐含的利润下降:是保守,还是真实的组合恶化13|最先要回答的三个问题:下半年、母公司意图、资金池条款
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:30、31、35;专项深挖:30、31、35
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:16;专项深挖:16
H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation怎么使用:直接证据;一手验证:15
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接证据;一手验证:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信;直接证据 / 支持证据|Q1 FY3/27 results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;直接证据 / 一手证据(研究域15)|H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation;直接证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:Subtracting H1 actuals from revised full-year guidance implies H2 FY3/27 revenue ¥220,022m, operating profit ¥25,791m (margin about 11.7%) and attributable profit ¥17,543m, roughly 6.8% below the prior-year H2 on secondary calculation. The judgment is staged conservatism rather than deterioration, because management raised twice while gross margin and field breadth improved — but this stays an assumption until the Q3 print. The market sold the record results on 2 November (−4.43% by 6 November), refusing to credit conservatism.
内部研究类型:implied_guidance_signal
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Arbitrates between management's signalling convention and market scepticism; opposite answers move the price toward the shelf top or floor.
不确定性(原始记录):Q3 date inferred from the company's calendar; 6.8% decline is a secondary calculation.
F012|08|收购把现金换成靠预测支撑的资产,成长腿与减值尾巴是同一个变量
研究范围:开放研究+35项覆盖检查
写入正文:08|收购把现金换成靠预测支撑的资产,成长腿与减值尾巴是同一个变量11|Infocom商誉:减值一次到位,同时冲击资产和增长腿13|第二层问题:3D的诉求、Infocom的分摊、TAM由谁验证
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信怎么使用:直接 / 支持;外部现实校验:33
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:直接 / 支持;一手验证:18
Goodwill and intangibles step-up from FY3/26 acquisitions, FY3/26 短信 balance sheet怎么使用:直接 / 支持;外部现实校验:18、32;专项深挖:20、33
Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section怎么使用:直接证据;一手验证:03、04、07
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域33)|Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 支持证据 / 外部现实(研究域18) / 外部现实(研究域32) / 定向深挖(研究域20) / 定向深挖(研究域33)|Goodwill and intangibles step-up from FY3/26 acquisitions, FY3/26 短信 balance sheet;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域07)|Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section
完整研究记录(核对用)
研究原文:Infocom (consolidated July 2025) and PT. WCS Abyakta, with six newly consolidated companies and ¥54,423m paid for subsidiaries, lifted goodwill from ¥2,923m to ¥31,823m and intangibles from ¥4,039m to ¥32,580m — ¥64,403m combined, about 22% of total equity — almost entirely in FY3/26. B-Prost (May 2026) shows the programme continuing. The acquisition adds revenue and scarce engineers but converts cash into assets whose carrying value rests on management forecasts; Japanese IFRS impairments tend to arrive at once, hitting the balance sheet and the acquisition-led growth leg together. The Infocom deal powers the growth leg and creates the impairment tail — M&A success and balance-sheet risk are one variable.
内部研究类型:acquisition_balance_sheet_risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):If Infocom disappoints, impairment and growth repricing arrive together on a balance sheet that previously carried almost no goodwill.
不确定性(原始记录):PPA details, useful lives and impairment-test assumptions unread; one secondary source cites a different interim goodwill figure (~¥57,510m).
F013|03|上半年的加速看似全面,拆开是轮动:咨询与数字服务靠一个防卫大项目
研究范围:开放研究+35项覆盖检查
写入正文:03|上半年的加速看似全面,拆开是轮动:咨询与数字服务靠一个防卫大项目13|第三层问题:防卫需求续约、领域披露口径、股东大会提案、派息路径
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Management-field revenue, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:03、05、12、13
Management-field revenue, FY3/26 短信 (with reclassification note)怎么使用:直接 / 支持;一手验证:02、03
Defence-sector large project as C&DS growth driver, H1 FY3/27 短信怎么使用:直接 / 支持;外部现实校验:13;专项深挖:05、13
Distribution and platformer field declined in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;同业比较:12;其他用途:历史
Industrial field detail in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:14;同业比较:05;其他用途:历史
Demand environment as described by the company, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:05、11、12;专项深挖:05、11、12
Industrial and steel field in FY3/26, FY3/26 短信 field commentary怎么使用:直接证据;同业比较:05、12;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域13)|Management-field revenue, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03)|Management-field revenue, FY3/26 短信 (with reclassification note);直接证据 / 支持证据 / 外部现实(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域13)|Defence-sector large project as C&DS growth driver, H1 FY3/27 短信;直接证据 / 支持证据 / 历史/同业比较(研究域12)|Distribution and platformer field declined in H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域14) / 历史/同业比较(研究域05)|Industrial field detail in H1 FY3/27, H1 FY3/27 短信;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment as described by the company, FY3/26 短信 qualitative section;直接证据 / 历史/同业比较(研究域05) / 历史/同业比较(研究域12)|Industrial and steel field in FY3/26, FY3/26 短信 field commentary
完整研究记录(核对用)
研究原文:Field divergence is widening: H1 FY3/27 Consulting & Digital Services revenue rose to ¥55,574m from ¥43,302m (+28.3%), mainly on a large defence-sector project, after being flat at ¥94,833m in FY3/26; Business Solutions rose to ¥143,404m from ¥135,072m on industrial fields (automobiles, chemicals, food, railways) and Infocom. Steel-sector and distribution/platformer revenue declined. Public/defence demand is policy-durable but project-lumpy, and lumpy projects annualise badly if not replaced. Demand is rotating rather than uniformly expanding; the growth centre of gravity is shifting to consulting and digital.
内部研究类型:growth_concentration_risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Headline acceleration is more project-concentrated than it looks; replacement of the defence pulse is a FY3/28 plan dependency.
不确定性(原始记录):Defence share of C&DS undisclosed; FY3/26 field figures are restated on a new basis.
F014|07|流通股很薄,活跃投资者在场:治理事件可能突然来
研究范围:开放研究+35项覆盖检查
写入正文:07|流通股很薄,活跃投资者在场:治理事件可能突然来13|第二层问题:3D的诉求、Infocom的分摊、TAM由谁验证15|证据限制:哪些事实没有核实,对判断有什么影响
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Effective free float estimate, shareholder analysis compiled from securities reports怎么使用:直接 / 支持;一手验证:24
Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327怎么使用:直接 / 支持;外部现实校验:24、30、35;专项深挖:24
2327 market snapshot and disclosure index, IRBANK怎么使用:直接证据;一手验证:27、31
Margin-trading balances for 2327, IRBANK怎么使用:直接证据;外部现实校验:27;专项深挖:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24)|Effective free float estimate, shareholder analysis compiled from securities reports;直接证据 / 支持证据 / 外部现实(研究域24) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域24)|Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327;直接证据 / 一手证据(研究域27) / 一手证据(研究域31)|2327 market snapshot and disclosure index, IRBANK;直接证据 / 外部现实(研究域27) / 定向深挖(研究域27)|Margin-trading balances for 2327, IRBANK
完整研究记录(核对用)
研究原文:Effective free float is only about 11.56% (estimated after the parent's stake, employee shareholding association and stable holders), and the register includes large-shareholding filings by activist 3D Investment Partners (stake size and proposals unread). Margin balances are trivial (buy 62,500 vs sell 47,000 shares), so leveraged positioning is not an overhang. Thin float plus activist attention plus a controlling parent is the classic setup for an abrupt governance event; the activist can either force the parent-relationship and capital questions that unlock a re-rating or provoke a contest the parent answers by tightening control. Order flow from one holder moves price more than a quarter of earnings does — consistent with the −4.43% reaction to record results.
内部研究类型:float_activism_setup
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Minority exit prices are set by float dynamics as much as value; governance news can gap the price in either direction.
不确定性(原始记录):Float figure is a secondary estimate; activist stake and intent unknown; escalation timing unknowable.
F015|06|没有有息借款:风险从负债端移到商誉和被托管的现金
研究范围:35项覆盖检查
写入正文:06|没有有息借款:风险从负债端移到商誉和被托管的现金09|安全边际:防得住破产,防不住股价回撤14|八个模块的得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet怎么使用:直接 / 支持;一手验证:18、25、29;专项深挖:18、29
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:直接 / 支持;一手验证:18
Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信怎么使用:直接证据;一手验证:29;外部现实校验:19
Balance sheet at Q1 FY3/27, Q1 FY3/27 短信怎么使用:直接证据;同业比较:18;其他用途:历史
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement怎么使用:直接证据;一手验证:17、20、25、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet;直接证据 / 支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 一手证据(研究域29) / 外部现实(研究域19)|Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信;直接证据 / 历史/同业比较(研究域18)|Balance sheet at Q1 FY3/27, Q1 FY3/27 短信;直接证据 / 一手证据(研究域17) / 一手证据(研究域20) / 一手证据(研究域25) / 一手证据(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement
完整研究记录(核对用)
研究原文:The balance sheet carries no bonds or bank borrowings. Liabilities of ¥128,775m (March 2026) are payables ¥39,113m, contract liabilities ¥33,774m, leases ¥25,149m combined, retirement-benefit obligations ¥22,553m and provisions ¥1,282m, against a 66.9% equity ratio (65.9% at September 2026). Financial leverage plays no role in the equity story in either direction; refinancing and covenant risk are absent. Balance-sheet risk has migrated from the liability side to asset-side goodwill recoverability and the encumbered CMS cash. Dilution risk is nil in the evidence; the capital-policy question is the opposite — idle, parent-parked surplus cash.
内部研究类型:balance_sheet_structure
内部来源标记:COVERAGE35
普通股东含义(原始记录):Protection against ruin, not against a 20–45% mark-to-market drawdown.
不确定性(原始记录):Pension assumptions and lease maturity detail unread.
F016|08|约50%的分红比率兑现了,每股增长只靠盈利
研究范围:开放研究+35项覆盖检查
写入正文:08|约50%的分红比率兑现了,每股增长只靠盈利13|第三层问题:防卫需求续约、领域披露口径、股东大会提案、派息路径
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信怎么使用:直接证据;一手验证:26、30;专项深挖:30
Statement of changes in equity, H1 FY3/27 短信怎么使用:直接证据;专项深挖:23、26;同业比较:26;其他用途:历史
Share count, treasury shares and 2024 stock split, FY3/26 短信 share section怎么使用:直接 / 支持;专项深挖:01、24;同业比较:24;其他用途:历史
Dividend decision governance under the articles, FY3/26 短信 dividend section怎么使用:直接证据;一手验证:23;专项深挖:23、25、26
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:支持证据;一手验证:18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 一手证据(研究域26) / 一手证据(研究域30) / 定向深挖(研究域30)|Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信;直接证据 / 历史/同业比较(研究域26) / 定向深挖(研究域23) / 定向深挖(研究域26)|Statement of changes in equity, H1 FY3/27 短信;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域24)|Share count, treasury shares and 2024 stock split, FY3/26 短信 share section;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision governance under the articles, FY3/26 短信 dividend section;支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信
完整研究记录(核对用)
研究原文:Shareholder return is a stated ~50% consolidated payout actually delivered: FY3/25 ¥74 (50.1%, DOE 5.4%), FY3/26 ¥85 (50.4%, DOE 5.8%, year-end raised ¥5 above forecast, ¥15,553m), FY3/27 planned ¥89 after a ¥2 H1 raise (interim ¥44.50). There is no meaningful buyback, treasury shares are 20,595 and shares issued are static at 183,002,000 (after the July 2024 1:2 split), so per-share compounding comes only from earnings growth and the dividend. Dividends are decided by the board under the articles. Whether the payout ratio can rise, or whether the dividend is defended at 50% of a smaller number if FY3/28 lands between ¥49,000m and ¥60,000m, is unanswered.
内部研究类型:shareholder_return_policy
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A growing ~2.3% yield is the return floor; any capital-return expansion depends on the parent tolerating a higher payout or float-increasing action.
不确定性(原始记录):Total-return history is computed from dividend record and market data, not a company TSR disclosure.
F017|09|估值快照:市盈率21.6倍,是质量复利型与母公司折价之间的折中
研究范围:开放研究+35项覆盖检查
写入正文:09|估值快照:市盈率21.6倍,是质量复利型与母公司折价之间的折中14|八个模块的得分与理由15|资料来源与日期:以公司披露为主,价格截至2026年11月6日
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
2327 market snapshot and disclosure index, IRBANK怎么使用:直接 / 支持;一手验证:27、31
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15、22、28
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:28
Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:29;外部现实校验:19
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement怎么使用:直接 / 支持;一手验证:17、20、25、32
Share count, treasury shares and 2024 stock split, FY3/26 短信 share section怎么使用:直接 / 支持;专项深挖:01、24;同业比较:24;其他用途:历史
Dividend yield cross-check at the 6 November 2026 close, IRBANK怎么使用:直接 / 支持;一手验证:27;外部现实校验:22、26、31;专项深挖:27、31
Margin-trading balances for 2327, IRBANK怎么使用:直接 / 支持;外部现实校验:27;专项深挖:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|2327 market snapshot and disclosure index, IRBANK;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域19)|Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 一手证据(研究域25) / 一手证据(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域24)|Share count, treasury shares and 2024 stock split, FY3/26 短信 share section;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域31) / 定向深挖(研究域27) / 定向深挖(研究域31)|Dividend yield cross-check at the 6 November 2026 close, IRBANK;直接证据 / 支持证据 / 外部现实(研究域27) / 定向深挖(研究域27)|Margin-trading balances for 2327, IRBANK
完整研究记录(核对用)
研究原文:At the 6 November 2026 close of ¥3,819 (research cut-off 9 November): market capitalisation ¥698.88bn (¥3,819 × 183,002,000 issued shares), forecast PER 21.6x on revised FY3/27 EPS ¥177.06, PBR 2.50x on FY3/26-year-end BPS ¥1,525.86 (IRBANK shows 2.44x on September BPS about ¥1,563), ROE 11.4% (FY3/26 actual), forecast dividend yield 2.33% on ¥89, EV/EBITDA 9.8x (EV ¥571.52bn after ¥127.37bn net cash at 30 September 2026, with the CMS-encumbered caveat; EBITDA ¥58.13bn = FY3/26 operating profit ¥44,242m plus D&A ¥13,889m). The multiple is a compromise between a quality-compounder multiple and a parent-triple-grip discount; it embodies the FY3/27 guidance, scepticism about the implied H2 decline and partial credit for the ¥60,000m plan, but no governance event. Operands mix period bases: forward PER on forecast EPS, PBR on March BPS, EV on September cash with FY3/26 EBITDA.
内部研究类型:valuation_snapshot
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Buyers pay for first-half plan delivery and receive the governance option at a partial price; neither euphoric nor distressed.
不确定性(原始记录):No consensus data or formal peer-median multiple was built; PBR varies with BPS date.
F018|09|正常化盈利以2027年3月期预测的324亿日元为底
研究范围:35项覆盖检查
写入正文:09|正常化盈利以2027年3月期预测的324亿日元为底
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15、22、28
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:28
FY3/25 comparatives and comprehensive income, FY3/26 短信怎么使用:直接 / 支持;外部现实校验:16、21;同业比较:28;其他用途:历史
Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements怎么使用:直接 / 支持;一手验证:32;外部现实校验:17、28;专项深挖:17、32
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:直接证据;外部现实校验:11;专项深挖:09、11、22、28、35
Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators怎么使用:直接证据;一手验证:22;专项深挖:22、28
Other expenses normalising after the dispute years, FY3/26 短信 P&L怎么使用:直接证据;外部现实校验:28;专项深挖:32;同业比较:16、32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域21) / 历史/同业比较(研究域28)|FY3/25 comparatives and comprehensive income, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域17) / 外部现实(研究域28) / 定向深挖(研究域17) / 定向深挖(研究域32)|Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements;直接证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域28)|Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators;直接证据 / 外部现实(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Other expenses normalising after the dispute years, FY3/26 短信 P&L
完整研究记录(核对用)
研究原文:Normalised attributable profit is roughly the FY3/27 guided ¥32,400m (revenue ¥419,000m, ~11.7% operating margin), growing from ¥30,832m at the pace the TAM mix allows: two consecutive record years with a rising gross margin define the base. FY3/25 comprehensive-income gains from securities, FY3/26's tax lag and the settlement are non-operating items and do not touch the run-rate. Earnings power grows by the mix identity — revenue compounding high-single to low-double digits, gross margin rising about a point a year — and the plan's ¥60,000m is a stretch case. Post-FY3/28 power depends on the next plan and is unknowable now.
内部研究类型:normalised_earnings_judgment
内部来源标记:COVERAGE35
普通股东含义(原始记录):Capitalising roughly ¥32,000m growing toward plan defines the fundamental anchor under the price shelf.
不确定性(原始记录):Growth rate depends on TAM trajectory; post-FY3/28 unknown.
F019|01|计划兑现与治理事件,哪一个先改变这家公司的折价
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|计划兑现与治理事件,哪一个先改变这家公司的折价13|每次业绩都要核对的门槛14|总分63.21/100,评级B,持有并跟踪、不追高
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(10项,重复标签已合并)
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15、22、28
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:28
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:直接 / 支持;一手验证:08、09、24
Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release怎么使用:直接 / 支持
Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信怎么使用:直接 / 支持;一手验证:04、35
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:16;专项深挖:16
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:30、31、35;专项深挖:30、31、35
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:直接 / 支持;外部现实校验:11;专项深挖:09、11、22、28、35
Recomputed moving-average structure, 2327 monthly series怎么使用:直接 / 支持;一手验证:34;外部现实校验:29;专项深挖:34;同业比较:31、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;直接证据 / 支持证据|Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域35)|Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信;直接证据 / 支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;直接证据 / 支持证据 / 一手证据(研究域34) / 外部现实(研究域29) / 历史/同业比较(研究域31) / 历史/同业比较(研究域35) / 定向深挖(研究域34)|Recomputed moving-average structure, 2327 monthly series
完整研究记录(核对用)
研究原文:Thesis: a compounding, 50%-payout SIer whose earnings quality is improving through the TAM mix shift, but whose equity story is capped by the parent's triple grip; the question is not demand but whether plan delivery (¥60,000m by FY3/28) or a governance event (stake, CMS, float) reprices the captive discount first. Falsification — compounder reading holds if by the FY3/27 full-year release TAM is tracking ≥~50%, gross margin ≥27% and FY3/28 guidance credibly bridges toward ¥60,000m; it fails if TAM stalls below ~45% with gross margin back under 26%, the implied H2 decline proves real with FY3/28 guidance opening below a ~¥52,000m operating-profit bridge, Infocom goodwill is impaired, or the parent tightens control (e.g. a captive-price tender). The discount reading is falsified by a stake sell-down, market-rate CMS terms disclosure or a payout-ratio raise.
内部研究类型:thesis_and_falsification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A dated, checkable list rather than a narrative to re-litigate each quarter.
不确定性(原始记录):Tripwire thresholds are analyst-chosen against disclosed waypoints; outcomes depend on parent decisions that are unknowable in advance.
F020|11|三个已定日期的检验,加一组没有日期的治理事件
研究范围:35项覆盖检查+开放研究
写入正文:11|三个已定日期的检验,加一组没有日期的治理事件
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:30、31、35;专项深挖:30、31、35
Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:26、30;专项深挖:30
Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327怎么使用:直接 / 支持;外部现实校验:24、30、35;专项深挖:24
Effective free float estimate, shareholder analysis compiled from securities reports怎么使用:直接 / 支持;一手验证:24
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:支持证据;一手验证:28
Management-field revenue, H1 FY3/27 短信 qualitative section怎么使用:支持证据;一手验证:03、05、12、13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域26) / 一手证据(研究域30) / 定向深挖(研究域30)|Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信;直接证据 / 支持证据|Q1 FY3/27 results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 外部现实(研究域24) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域24)|Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327;直接证据 / 支持证据 / 一手证据(研究域24)|Effective free float estimate, shareholder analysis compiled from securities reports;支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;支持证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域13)|Management-field revenue, H1 FY3/27 短信 qualitative section
完整研究记录(核对用)
研究原文:Dated catalysts: Q3 FY3/27 results in late January 2027 (usual calendar; tests the implied H2 decline, TAM waypoint ~50% and any further raise); full-year release in late April 2027 with the year-end dividend and first FY3/28 bridge; June 2027 AGM for activist proposals. Undated: any disclosure touching the parent's stake, the CMS terms, or the float (sell-down, buyback funded outside the CMS, response to activists), which would act directly on the governance discount. Operating prints test story one; governance events test story two.
内部研究类型:catalyst_calendar
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):The calendar alternates between operating and governance questions at known dates.
不确定性(原始记录):Whether the activist escalates before the AGM is unknowable.
F021|04|同业都是日本大型系统集成商,竞争靠信任、行业知识和交付能力
研究范围:35项覆盖检查+开放研究
写入正文:04|同业都是日本大型系统集成商,竞争靠信任、行业知识和交付能力
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:直接证据;一手验证:08、09、24
Positioning versus the major SIers, company-research note on NS Solutions怎么使用:直接证据;外部现实校验:02、03、05、06、08、10;专项深挖:06、07、08、09
History spine 1980–2025, NS Solutions Corporation overview怎么使用:直接证据;一手验证:33;外部现实校验:07;专项深挖:33;同业比较:01、02、08、09;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;直接证据 / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域10) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域08) / 定向深挖(研究域09)|Positioning versus the major SIers, company-research note on NS Solutions;直接证据 / 一手证据(研究域33) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 定向深挖(研究域33)|History spine 1980–2025, NS Solutions Corporation overview
完整研究记录(核对用)
研究原文:Competitors are major Japanese SIers: NTT Data (scale leader), Nomura Research Institute (margin benchmark, strong in finance where NSSOL also competes), Fujitsu (mid-restructuring toward services) and Itochu Techno-Solutions (distribution-strong, also minority partner in the NCI joint venture), plus customers' in-house teams and AI-native delivery that substitutes for billed engineering hours. Competition is on trust, domain know-how and delivery capacity rather than price alone; the substitution threat is the same AI technology the company is adopting.
内部研究类型:competitive_set
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Peer prints each quarter frame whether NSSOL's mix gains are company-specific or sector-wide.
不确定性(原始记录):No niche-level market-share table and no formal peer multiple were built.
F022|04|资本关系:母公司、Infocom、合资公司与海外子公司
研究范围:35项覆盖检查+开放研究
写入正文:04|资本关系:母公司、Infocom、合资公司与海外子公司
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:直接证据;一手验证:08、09、24
Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信怎么使用:直接证据;外部现实校验:33
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:直接证据;一手验证:18
Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section怎么使用:直接证据;一手验证:03、04、07
Overseas footprint and group companies, NSSOL company outline怎么使用:直接证据;一手验证:07、14;专项深挖:07、14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;直接证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 外部现实(研究域33)|Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信;直接证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域07)|Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域07) / 一手证据(研究域14) / 定向深挖(研究域07) / 定向深挖(研究域14)|Overseas footprint and group companies, NSSOL company outline
完整研究记录(核对用)
研究原文:Capital relationships: Nippon Steel (INBOUND, parent, customer and cash custodian); Infocom (wholly owned since July 2025, the main acquisition and test of the acquisition-led growth leg); B-Prost (non-life insurance core systems, May 2026, small vertical-niche evidence of continuing M&A); and the Nitetsu Hitachi System Engineering joint venture (51% NSSOL, Hitachi 49%, founded 1988), an example of the long-standing alliance-based delivery fabric. Group perimeter items also include the Taiwan iAuto capital and business alliance (July 2026), Indonesian ERP subsidiary and overseas subsidiaries in the US, UK, China, Singapore and Thailand.
内部研究类型:capital_relationship_set
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Perimeter and partner economics determine which cash flows belong to ordinary shareholders; minority interests are ¥9,670m.
不确定性(原始记录):Contribution of JV and partnerships is undisclosed.
F023|03|需求从制造业投资、防卫预算和金融IT进来,行业冲击先到股价、后到利润
研究范围:35项覆盖检查+开放研究
写入正文:03|需求从制造业投资、防卫预算和金融IT进来,行业冲击先到股价、后到利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Management-field revenue, H1 FY3/27 短信 qualitative section怎么使用:直接证据;一手验证:03、05、12、13
Management-field revenue, FY3/26 短信 (with reclassification note)怎么使用:直接证据;一手验证:02、03
Positioning versus the major SIers, company-research note on NS Solutions怎么使用:直接证据;外部现实校验:02、03、05、06、08、10;专项深挖:06、07、08、09
Demand environment as described by the company, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:05、11、12;专项深挖:05、11、12
Defence-sector large project as C&DS growth driver, H1 FY3/27 短信怎么使用:直接证据;外部现实校验:13;专项深挖:05、13
Overseas footprint and group companies, NSSOL company outline怎么使用:直接证据;一手验证:07、14;专项深挖:07、14
Industrial field detail in H1 FY3/27, H1 FY3/27 短信怎么使用:直接证据;一手验证:14;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域13)|Management-field revenue, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域02) / 一手证据(研究域03)|Management-field revenue, FY3/26 短信 (with reclassification note);直接证据|Financial field in FY3/26, FY3/26 短信 field commentary;直接证据 / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域10) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域08) / 定向深挖(研究域09)|Positioning versus the major SIers, company-research note on NS Solutions;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment as described by the company, FY3/26 短信 qualitative section;直接证据 / 外部现实(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域13)|Defence-sector large project as C&DS growth driver, H1 FY3/27 短信;直接证据 / 一手证据(研究域07) / 一手证据(研究域14) / 定向深挖(研究域07) / 定向深挖(研究域14)|Overseas footprint and group companies, NSSOL company outline;直接证据 / 一手证据(研究域14) / 历史/同业比较(研究域05)|Industrial field detail in H1 FY3/27, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:End-market transmission: manufacturing DX investment (steel, automobiles, chemicals, food, railways) is the core Business Solutions demand base and transmits customers' capex cycle directly into the largest field; defence and public-sector demand was the single biggest driver of Consulting & Digital Services growth in H1 FY3/27; financial institutions' IT investment is a heritage strength where the field is shifting from licence resale toward the company's own platforms and consulting, carrying the TAM mix with it. Policy (digital government, defence build-up) is a demand tailwind; macro reaches P&L with a lag through customer capex but reaches the share price immediately, as the April 2025 tariff-shock drawdown to ¥3,259 showed.
内部研究类型:end_market_exposure
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Macro drawdowns are likely to hit the price without equivalent earnings damage; the defence tailwind is policy-durable but project-lumpy.
不确定性(原始记录):Customer-capex elasticity and defence exposure size are not measurable from sources.
F024|09|安全边际:防得住破产,防不住股价回撤
研究范围:开放研究
写入正文:09|安全边际:防得住破产,防不住股价回撤10|二十年低位之后,价格在2023至2024年上移到一个高位箱体10|箱体内的价格行为:下探被快速买回,冲高两次在同一高度受阻15|资料来源与日期:以公司披露为主,价格截至2026年11月6日
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Recomputed moving-average structure, 2327 monthly series怎么使用:直接 / 支持;一手验证:34;外部现实校验:29;专项深挖:34;同业比较:31、35;其他用途:历史
Recomputed life history and annual ranges, 2327 monthly series怎么使用:直接 / 支持;外部现实校验:29;专项深挖:34;同业比较:33、34;其他用途:历史
Recomputed residence distribution, 2327 monthly series怎么使用:直接 / 支持;专项深挖:34;同业比较:34;其他用途:历史
External cross-check of price levels, IRBANK 2327怎么使用:直接 / 支持;外部现实校验:14、34
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域34)|2327.T split-adjusted monthly OHLC series (mirror of Yahoo Finance chart data);直接证据 / 支持证据 / 一手证据(研究域34) / 外部现实(研究域29) / 历史/同业比较(研究域31) / 历史/同业比较(研究域35) / 定向深挖(研究域34)|Recomputed moving-average structure, 2327 monthly series;直接证据 / 支持证据 / 外部现实(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域34) / 定向深挖(研究域34)|Recomputed life history and annual ranges, 2327 monthly series;直接证据 / 支持证据 / 历史/同业比较(研究域34) / 定向深挖(研究域34)|Recomputed residence distribution, 2327 monthly series;直接证据 / 支持证据 / 外部现实(研究域14) / 外部现实(研究域34)|External cross-check of price levels, IRBANK 2327
完整研究记录(核对用)
研究原文:Reproduced from Research claims without altering the protected Technical state: monthly closes show a two-decade residence mostly below ¥2,000 (87% of 289 monthly closes), a 2023–24 migration to a ¥3,075–4,655 shelf, two rejections at ¥4,580 (December 2025) and the all-time high ¥4,655 (January 2026), and two buyers at ¥3,259 (April 2025) and ¥3,075 (June 2026). The high residence is young and thin (about 34 months above ¥2,000); the floor band is more than ¥550 below the 6 November mark and the old centre near ¥2,000 is the next anchor if it fails, with MA60 at ¥2,851 as the migration-voiding level. The authoritative non-confirming-or-otherwise Technical State resides in the protected structure, not here.
内部研究类型:technical_observation_reference
内部来源标记:TECHNICAL / OPEN_DISCOVERY
普通股东含义(原始记录):Fundamental protection does not protect the price; the shelf floor is the mark-to-market risk measure.
不确定性(原始记录):Mirror has GAP status through 20 October 2026; freshest mark from IRBANK; volume and sub-monthly structure not in evidence.
F025|09|价格已经为计划的最后一步付了一部分
研究范围:35项覆盖检查
写入正文:09|价格已经为计划的最后一步付了一部分10|事件响应与时序:业绩创纪录,价格没有留住好消息
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Recomputed moving-average structure, 2327 monthly series怎么使用:直接 / 支持;一手验证:34;外部现实校验:29;专项深挖:34;同业比较:31、35;其他用途:历史
External cross-check of price levels, IRBANK 2327怎么使用:直接 / 支持;外部现实校验:14、34
2327 market snapshot and disclosure index, IRBANK怎么使用:直接 / 支持;一手验证:27、31
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:直接证据;一手验证:30、31、35;专项深挖:30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域34) / 外部现实(研究域29) / 历史/同业比较(研究域31) / 历史/同业比较(研究域35) / 定向深挖(研究域34)|Recomputed moving-average structure, 2327 monthly series;直接证据 / 支持证据 / 外部现实(研究域14) / 外部现实(研究域34)|External cross-check of price levels, IRBANK 2327;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|2327 market snapshot and disclosure index, IRBANK;直接证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:Price at ¥3,819 on 6 November sits just below MA12 ¥3,863 and MA24 ¥3,838 — the shelf midpoint and two-year average participant cost coincide — and the 2 November record results and guidance raise were sold (−4.43% by 6 November). The market is pricing the implied H2 decline and the ¥11,000m plan gap rather than the record headline. This is cross-lane price-response evidence from public events; it does not make fundamentals a cause of the Technical State.
内部研究类型:event_response_cross_lane
内部来源标记:TECHNICAL / COVERAGE35
普通股东含义(原始记录):Record headlines did not produce acceptance; the undecided level is exactly where the migration's average participant breaks even.
不确定性(原始记录):Single event observation; consensus data not pulled.
F026|01|计划算术:产品组合比需求更紧
研究范围:开放研究+35项覆盖检查
写入正文:01|计划算术:产品组合比需求更紧06|毛利率是整套逻辑里信息量最大的数字09|价格已经为计划的最后一步付了一部分14|八个模块的得分与理由
归并到:F043
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信怎么使用:直接 / 支持;一手验证:04、35
Income statement detail FY3/26, FY3/26 短信 (IFRS P&L)怎么使用:直接 / 支持;一手验证:15、16;专项深挖:15、16
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:16;专项深挖:16
What the TAM model change means, Jiji Press report of the results怎么使用:直接 / 支持;一手验证:02;外部现实校验:04;专项深挖:02、03、10
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:支持证据;外部现实校验:11;专项深挖:09、11、22、28、35
Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section怎么使用:支持证据;一手验证:03、04、07
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域35)|Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 定向深挖(研究域15) / 定向深挖(研究域16)|Income statement detail FY3/26, FY3/26 短信 (IFRS P&L);直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域04) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域10)|What the TAM model change means, Jiji Press report of the results;支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域07)|Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section
完整研究记录(核对用)
研究原文:Rising TAM share (assets and platforms inside services revenue) lifts gross margin; the plan needs this to keep winning to reach 13% operating margin.
内部研究类型:drives
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F027|01|计划算术:产品组合比需求更紧
研究范围:开放研究+35项覆盖检查
写入正文:01|计划算术:产品组合比需求更紧06|毛利率是整套逻辑里信息量最大的数字09|价格已经为计划的最后一步付了一部分14|八个模块的得分与理由
归并到:F043
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15、22、28
H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15
Income statement detail FY3/26, FY3/26 短信 (IFRS P&L)怎么使用:直接 / 支持;一手验证:15、16;专项深挖:15、16
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:16;专项深挖:16
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:支持证据;一手验证:28
Dividend record and policy, FY3/26 短信 dividend section怎么使用:支持证据;一手验证:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域15)|H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 定向深挖(研究域15) / 定向深挖(研究域16)|Income statement detail FY3/26, FY3/26 短信 (IFRS P&L);直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section
完整研究记录(核对用)
研究原文:Gross-margin expansion, not one-off gains, explains why operating profit outgrew revenue in FY3/26 and H1 FY3/27, partly offset by SG&A investment.
内部研究类型:explains
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F028|01|计划算术:产品组合比需求更紧
研究范围:开放研究+35项覆盖检查
写入正文:01|计划算术:产品组合比需求更紧06|毛利率是整套逻辑里信息量最大的数字09|价格已经为计划的最后一步付了一部分14|八个模块的得分与理由
归并到:F043
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release怎么使用:直接 / 支持
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:直接 / 支持;外部现实校验:11;专项深挖:09、11、22、28、35
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:28
Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信怎么使用:支持证据;一手验证:04、35
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:支持证据;一手验证:30、31、35;专项深挖:30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据|Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release;直接证据 / 支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;直接证据 / 支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;支持证据 / 一手证据(研究域04) / 一手证据(研究域35)|Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信;支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:The ¥60,000m / 13% target cannot be reached by volume at the current margin; it depends on continued gross-margin expansion and TAM at about 75%.
内部研究类型:constrains
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F029|06|没有有息借款:风险从负债端移到商誉和被托管的现金
研究范围:35项覆盖检查
写入正文:06|没有有息借款:风险从负债端移到商誉和被托管的现金07|资金池:同一笔钱既是下行保护,也是折价的原因13|最先要回答的三个问题:下半年、母公司意图、资金池条款
归并到:F006
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;外部现实校验:25;专项深挖:18、21
CMS deposit at September 2026, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:支持证据;一手验证:08、09、24
Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信怎么使用:支持证据;一手验证:29;外部现实校验:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域21)|CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|CMS deposit at September 2026, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;支持证据 / 一手证据(研究域29) / 外部现实(研究域19)|Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:The CMS is where the balance sheet and governance story physically meet: ¥114,451m of cash is both downside protection and a cause of the discount, so CMS terms disclosure reprices both at once.
内部研究类型:balance_sheet_meets_governance
内部来源标记:COVERAGE35
F030|07|日本制铁在需求、现金和控制权三个渠道同时用力
研究范围:35项覆盖检查
写入正文:07|日本制铁在需求、现金和控制权三个渠道同时用力09|折价从哪里来:母公司的控制结构,只有母公司或股东压力才能改变12|一个变量四条渠道:为什么一条公告可以让价格跳空
归并到:F042
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Effective free float estimate, shareholder analysis compiled from securities reports怎么使用:直接 / 支持;一手验证:24
Share count, treasury shares and 2024 stock split, FY3/26 短信 share section怎么使用:直接证据;专项深挖:01、24;同业比较:24;其他用途:历史
Recomputed moving-average structure, 2327 monthly series怎么使用:直接证据;一手验证:34;外部现实校验:29;专项深挖:34;同业比较:31、35;其他用途:历史
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:支持证据;一手验证:18
Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327怎么使用:支持证据;外部现实校验:24、30、35;专项深挖:24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 支持证据 / 一手证据(研究域24)|Effective free float estimate, shareholder analysis compiled from securities reports;直接证据 / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域24)|Share count, treasury shares and 2024 stock split, FY3/26 短信 share section;直接证据 / 一手证据(研究域34) / 外部现实(研究域29) / 历史/同业比较(研究域31) / 历史/同业比较(研究域35) / 定向深挖(研究域34)|Recomputed moving-average structure, 2327 monthly series;支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;支持证据 / 外部现实(研究域24) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域24)|Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327
完整研究记录(核对用)
研究原文:A fixed 50% payout on an 11.6% float means income buyers compete for very few shares, stiffening the shelf floor, while the same thinness lets a single governance headline gap the price through it.
内部研究类型:interacts_with
内部来源标记:COVERAGE35 / TECHNICAL
F031|08|收购把现金换成靠预测支撑的资产,成长腿与减值尾巴是同一个变量
研究范围:开放研究
写入正文:08|收购把现金换成靠预测支撑的资产,成长腿与减值尾巴是同一个变量11|Infocom商誉:减值一次到位,同时冲击资产和增长腿13|第二层问题:3D的诉求、Infocom的分摊、TAM由谁验证
归并到:F012
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信怎么使用:直接 / 支持;外部现实校验:33
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:直接 / 支持;一手验证:18
Segment information note: single segment, H1 FY3/27 短信怎么使用:直接证据;一手验证:02、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域33)|Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 一手证据(研究域02) / 一手证据(研究域10)|Segment information note: single segment, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:The Infocom acquisition powers part of the revenue and capability growth behind the plan while creating the goodwill whose impairment would hit the same plan.
内部研究类型:growth_leg_and_impairment_tail
内部来源标记:OPEN_DISCOVERY
F032|12|同一份创纪录业绩,市场选择了另一种解释
研究范围:35项覆盖检查
写入正文:12|同一份创纪录业绩,市场选择了另一种解释13|最先要回答的三个问题:下半年、母公司意图、资金池条款
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:30、31、35;专项深挖:30、31、35
2327 market snapshot and disclosure index, IRBANK怎么使用:直接 / 支持;一手验证:27、31
Recomputed moving-average structure, 2327 monthly series怎么使用:直接 / 支持;一手验证:34;外部现实校验:29;专项深挖:34;同业比较:31、35;其他用途:历史
H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation怎么使用:支持证据;一手验证:15
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:支持证据;一手验证:28
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:支持证据;一手验证:16;专项深挖:16
External cross-check of price levels, IRBANK 2327怎么使用:支持证据;外部现实校验:14、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信;直接证据 / 支持证据|Q1 FY3/27 results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|2327 market snapshot and disclosure index, IRBANK;直接证据 / 支持证据 / 一手证据(研究域34) / 外部现实(研究域29) / 历史/同业比较(研究域31) / 历史/同业比较(研究域35) / 定向深挖(研究域34)|Recomputed moving-average structure, 2327 monthly series;支持证据 / 一手证据(研究域15)|H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation;支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;支持证据 / 外部现实(研究域14) / 外部现实(研究域34)|External cross-check of price levels, IRBANK 2327
完整研究记录(核对用)
研究原文:Management's staged-conservatism convention is precisely what the market refused to believe on 2 November; Q3 arbitrates between guidance convention and market scepticism.
内部研究类型:expectation_mismatch
内部来源标记:COVERAGE35 / TECHNICAL
F033|10|事件响应与时序:业绩创纪录,价格没有留住好消息
研究范围:35项覆盖检查
写入正文:10|事件响应与时序:业绩创纪录,价格没有留住好消息
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Recomputed moving-average structure, 2327 monthly series怎么使用:直接 / 支持;一手验证:34;外部现实校验:29;专项深挖:34;同业比较:31、35;其他用途:历史
Recomputed life history and annual ranges, 2327 monthly series怎么使用:直接 / 支持;外部现实校验:29;专项深挖:34;同业比较:33、34;其他用途:历史
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接证据;一手验证:15、22、28
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接证据;一手验证:28
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:直接证据;外部现实校验:11;专项深挖:09、11、22、28、35
External cross-check of price levels, IRBANK 2327怎么使用:支持证据;外部现实校验:14、34
2327 market snapshot and disclosure index, IRBANK怎么使用:支持证据;一手验证:27、31
Recomputed residence distribution, 2327 monthly series怎么使用:支持证据;专项深挖:34;同业比较:34;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域34) / 外部现实(研究域29) / 历史/同业比较(研究域31) / 历史/同业比较(研究域35) / 定向深挖(研究域34)|Recomputed moving-average structure, 2327 monthly series;直接证据 / 支持证据 / 外部现实(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域34) / 定向深挖(研究域34)|Recomputed life history and annual ranges, 2327 monthly series;直接证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;直接证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;支持证据 / 外部现实(研究域14) / 外部现实(研究域34)|External cross-check of price levels, IRBANK 2327;支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|2327 market snapshot and disclosure index, IRBANK;支持证据 / 历史/同业比较(研究域34) / 定向深挖(研究域34)|Recomputed residence distribution, 2327 monthly series
完整研究记录(核对用)
研究原文:Price migrated first (2023–24, on the plan story); fundamentals then caught up (FY3/26 records, FY3/27 raises); the final plan step is still being paid for in advance, so both clocks synchronise on the FY3/28 target. Delivery risk is fundamental chasing a price that has stopped rising. This is a cross-lane timing relation and does not alter the Technical State.
内部研究类型:price_fundamental_timing_synchronised
内部来源标记:COVERAGE35 / TECHNICAL
F034|06|2026年3月期经营现金流为负,原因是税款错期和一笔和解款
研究范围:开放研究
写入正文:06|2026年3月期经营现金流为负,原因是税款错期和一笔和解款08|约50%的分红比率兑现了,每股增长只靠盈利
归并到:F044
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement怎么使用:直接 / 支持;一手验证:17、20、25、32
Consolidated cash flow H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:17
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:支持证据;一手验证:18
H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation怎么使用:支持证据;一手验证:15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 一手证据(研究域25) / 一手证据(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域17)|Consolidated cash flow H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;支持证据 / 一手证据(研究域33)|Settlement of litigation, notice by NetOne Systems (auxiliary participant);支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;支持证据 / 一手证据(研究域15)|H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation
完整研究记录(核对用)
研究原文:Because cash conversion is sound over two years and capex is light, the 50% payout is fundable from operating cash without leverage; FY3/26's dip did not impair the dividend.
内部研究类型:funds
内部来源标记:OPEN_DISCOVERY
F035|06|2026年3月期经营现金流为负,原因是税款错期和一笔和解款
研究范围:35项覆盖检查
写入正文:06|2026年3月期经营现金流为负,原因是税款错期和一笔和解款08|约50%的分红比率兑现了,每股增长只靠盈利
归并到:F044
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet怎么使用:直接 / 支持;一手验证:19;外部现实校验:15;专项深挖:15、19
Working capital build in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:19;专项深挖:17、19
Consolidated cash flow H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:17
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement怎么使用:支持证据;一手验证:17、20、25、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet;直接证据 / 支持证据 / 一手证据(研究域19) / 定向深挖(研究域17) / 定向深挖(研究域19)|Working capital build in H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域17)|Consolidated cash flow H1 FY3/27, H1 FY3/27 短信;支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 一手证据(研究域25) / 一手证据(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement;支持证据 / 一手证据(研究域33)|Settlement of litigation, notice by NetOne Systems (auxiliary participant)
完整研究记录(核对用)
研究原文:Contract-asset build in the build half suppresses operating cash flow and releases it in the collection half, a second timing layer on top of the tax and settlement effects.
内部研究类型:modulates
内部来源标记:COVERAGE35
F036|03|上半年的加速看似全面,拆开是轮动:咨询与数字服务靠一个防卫大项目
研究范围:开放研究
写入正文:03|上半年的加速看似全面,拆开是轮动:咨询与数字服务靠一个防卫大项目13|第三层问题:防卫需求续约、领域披露口径、股东大会提案、派息路径
归并到:F013
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Defence-sector large project as C&DS growth driver, H1 FY3/27 短信怎么使用:直接 / 支持;外部现实校验:13;专项深挖:05、13
Distribution and platformer field declined in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;同业比较:12;其他用途:历史
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:直接 / 支持;外部现实校验:11;专项深挖:09、11、22、28、35
Industrial field detail in H1 FY3/27, H1 FY3/27 短信怎么使用:支持证据;一手验证:14;同业比较:05;其他用途:历史
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:支持证据;一手验证:30、31、35;专项深挖:30、31、35
Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release怎么使用:支持证据
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域13)|Defence-sector large project as C&DS growth driver, H1 FY3/27 短信;直接证据 / 支持证据 / 历史/同业比较(研究域12)|Distribution and platformer field declined in H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;支持证据 / 一手证据(研究域14) / 历史/同业比较(研究域05)|Industrial field detail in H1 FY3/27, H1 FY3/27 短信;支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信;支持证据|Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release
完整研究记录(核对用)
研究原文:Concentration of H1 growth in one defence project means FY3/28 growth requires replacement of a lumpy pulse in addition to TAM mix improvement.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY
F037|09|折价从哪里来:母公司的控制结构,只有母公司或股东压力才能改变
研究范围:35项覆盖检查
写入正文:09|折价从哪里来:母公司的控制结构,只有母公司或股东压力才能改变
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:直接 / 支持;一手验证:08、09、24
2327 market snapshot and disclosure index, IRBANK怎么使用:直接 / 支持;一手验证:27、31
Dividend yield cross-check at the 6 November 2026 close, IRBANK怎么使用:直接 / 支持;一手验证:27;外部现实校验:22、26、31;专项深挖:27、31
Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信怎么使用:支持证据;一手验证:29;外部现实校验:19
Margin-trading balances for 2327, IRBANK怎么使用:支持证据;外部现实校验:27;专项深挖:27
查看完整证据标签(核对用)
直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|2327 market snapshot and disclosure index, IRBANK;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域31) / 定向深挖(研究域27) / 定向深挖(研究域31)|Dividend yield cross-check at the 6 November 2026 close, IRBANK;支持证据 / 一手证据(研究域29) / 外部现实(研究域19)|Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信;支持证据 / 外部现实(研究域27) / 定向深挖(研究域27)|Margin-trading balances for 2327, IRBANK
完整研究记录(核对用)
研究原文:The parent's triple grip is why a record-earning, unlevered compounder trades on a compromise multiple of about 21.6x forward rather than a pure quality multiple.
内部研究类型:discounts
内部来源标记:COVERAGE35
F038|06|没有有息借款:风险从负债端移到商誉和被托管的现金
研究范围:35项覆盖检查
写入正文:06|没有有息借款:风险从负债端移到商誉和被托管的现金09|安全边际:防得住破产,防不住股价回撤14|八个模块的得分与理由
归并到:F015
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet怎么使用:直接 / 支持;一手验证:18、25、29;专项深挖:18、29
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:直接 / 支持;一手验证:18
Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信怎么使用:直接 / 支持;外部现实校验:33
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet;直接证据 / 支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 支持证据 / 外部现实(研究域33)|Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信
完整研究记录(核对用)
研究原文:With no debt, balance-sheet risk is not solvency but asset-side goodwill recoverability; impairment would be a valuation and equity-ratio event rather than a financing event.
内部研究类型:risk_relocation
内部来源标记:COVERAGE35
F039|01|计划兑现与治理事件,哪一个先改变这家公司的折价
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|计划兑现与治理事件,哪一个先改变这家公司的折价11|母公司收紧还是放松,决定哪个故事先落地13|每次业绩都要核对的门槛14|总分63.21/100,评级B,持有并跟踪、不追高
归并到:F045
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(11项,重复标签已合并)
Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327怎么使用:直接证据;外部现实校验:24、30、35;专项深挖:24
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:支持证据;一手验证:15、22、28
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:支持证据;一手验证:28
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:支持证据;一手验证:08、09、24
Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release怎么使用:支持证据
Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信怎么使用:支持证据;一手验证:04、35
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:支持证据;一手验证:16;专项深挖:16
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:支持证据;一手验证:30、31、35;专项深挖:30、31、35
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:支持证据;外部现实校验:11;专项深挖:09、11、22、28、35
Recomputed moving-average structure, 2327 monthly series怎么使用:支持证据;一手验证:34;外部现实校验:29;专项深挖:34;同业比较:31、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 外部现实(研究域24) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域24)|Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327;支持证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;支持证据|Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release;支持证据 / 一手证据(研究域04) / 一手证据(研究域35)|Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信;支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信;支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;支持证据 / 一手证据(研究域34) / 外部现实(研究域29) / 历史/同业比较(研究域31) / 历史/同业比较(研究域35) / 定向深挖(研究域34)|Recomputed moving-average structure, 2327 monthly series
完整研究记录(核对用)
研究原文:The parent's unknown intention on stake, CMS and payout decides whether the governance leg of the thesis resolves toward discount lift or toward tighter control.
内部研究类型:determines_resolution_path
内部来源标记:COVERAGE35
F040|10|二十年低位之后,价格在2023至2024年上移到一个高位箱体
写入正文:10|二十年低位之后,价格在2023至2024年上移到一个高位箱体10|箱体内的价格行为:下探被快速买回,冲高两次在同一高度受阻10|当前状态:箱体中段略偏弱,上移尚未被确认14|八个模块的得分与理由
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (RESEARCH_TRUTH.technical_state)
内部研究类型:protected_technical_synthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
F041|02|一家把工程师和可复用资产嵌进客户核心系统的轻资产服务商
研究范围:开放研究+35项覆盖检查
写入正文:02|一家把工程师和可复用资产嵌进客户核心系统的轻资产服务商05|护城河成立,但目前只有迹象,尚未验证
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(35项,重复标签已合并)
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接证据;一手验证:15、22、28
Management-field revenue, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:03、05、12、13
Management-field revenue, FY3/26 短信 (with reclassification note)怎么使用:直接 / 支持;一手验证:02、03
Segment information note: single segment, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:02、10
NS Solutions Corporation company outline and history (cross-check)怎么使用:直接证据;一手验证:01、09;外部现实校验:23
Company outline: employees, capital, leadership, NSSOL company overview怎么使用:直接证据;一手验证:06、23;外部现实校验:01、09、20;专项深挖:01
History spine 1980–2025, NS Solutions Corporation overview怎么使用:直接证据;一手验证:33;外部现实校验:07;专项深挖:33;同业比较:01、02、08、09;其他用途:历史
Positioning versus the major SIers, company-research note on NS Solutions怎么使用:直接证据;外部现实校验:02、03、05、06、08、10;专项深挖:06、07、08、09
What the TAM model change means, Jiji Press report of the results怎么使用:直接证据;一手验证:02;外部现实校验:04;专项深挖:02、03、10
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:直接 / 支持;一手验证:08、09、24
Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:29;外部现实校验:19
CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;外部现实校验:25;专项深挖:18、21
CMS deposit at September 2026, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators怎么使用:直接证据;一手验证:22;专项深挖:22、28
Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet怎么使用:直接 / 支持;一手验证:18、25、29;专项深挖:18、29
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:直接 / 支持;一手验证:18
Balance sheet at Q1 FY3/27, Q1 FY3/27 短信怎么使用:直接证据;同业比较:18;其他用途:历史
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement怎么使用:直接证据;一手验证:17、20、25、32
Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信怎么使用:直接 / 支持;外部现实校验:33
Goodwill and intangibles step-up from FY3/26 acquisitions, FY3/26 短信 balance sheet怎么使用:直接 / 支持;外部现实校验:18、32;专项深挖:20、33
Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section怎么使用:直接证据;一手验证:03、04、07
Demand environment as described by the company, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:05、11、12;专项深挖:05、11、12
Defence-sector large project as C&DS growth driver, H1 FY3/27 短信怎么使用:直接证据;外部现实校验:13;专项深挖:05、13
Overseas footprint and group companies, NSSOL company outline怎么使用:直接证据;一手验证:07、14;专项深挖:07、14
Industrial field detail in H1 FY3/27, H1 FY3/27 短信怎么使用:直接证据;一手验证:14;同业比较:05;其他用途:历史
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信怎么使用:直接证据;一手验证:26、30;专项深挖:30
Statement of changes in equity, H1 FY3/27 短信怎么使用:直接证据;专项深挖:23、26;同业比较:26;其他用途:历史
Share count, treasury shares and 2024 stock split, FY3/26 短信 share section怎么使用:直接 / 支持;专项深挖:01、24;同业比较:24;其他用途:历史
Dividend decision governance under the articles, FY3/26 短信 dividend section怎么使用:直接证据;一手验证:23;专项深挖:23、25、26
Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet怎么使用:直接 / 支持;一手验证:19;外部现实校验:15;专项深挖:15、19
Working capital build in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:19;专项深挖:17、19
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域13)|Management-field revenue, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03)|Management-field revenue, FY3/26 短信 (with reclassification note);直接证据 / 一手证据(研究域01)|Articles of Incorporation of NS Solutions Corporation (filed 2020-06-22);直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域10)|Segment information note: single segment, H1 FY3/27 短信;直接证据 / 一手证据(研究域01) / 一手证据(研究域09) / 外部现实(研究域23)|NS Solutions Corporation company outline and history (cross-check);直接证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域20) / 定向深挖(研究域01)|Company outline: employees, capital, leadership, NSSOL company overview;直接证据 / 一手证据(研究域33) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 定向深挖(研究域33)|History spine 1980–2025, NS Solutions Corporation overview;直接证据 / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域10) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域08) / 定向深挖(研究域09)|Positioning versus the major SIers, company-research note on NS Solutions;直接证据 / 一手证据(研究域02) / 外部现实(研究域04) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域10)|What the TAM model change means, Jiji Press report of the results;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域19)|Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域21)|CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|CMS deposit at September 2026, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域28)|Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet;直接证据 / 支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 历史/同业比较(研究域18)|Balance sheet at Q1 FY3/27, Q1 FY3/27 短信;直接证据 / 一手证据(研究域17) / 一手证据(研究域20) / 一手证据(研究域25) / 一手证据(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement;直接证据 / 支持证据 / 外部现实(研究域33)|Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信;直接证据 / 支持证据 / 外部现实(研究域18) / 外部现实(研究域32) / 定向深挖(研究域20) / 定向深挖(研究域33)|Goodwill and intangibles step-up from FY3/26 acquisitions, FY3/26 短信 balance sheet;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域07)|Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section;直接证据|Financial field in FY3/26, FY3/26 短信 field commentary;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment as described by the company, FY3/26 短信 qualitative section;直接证据 / 外部现实(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域13)|Defence-sector large project as C&DS growth driver, H1 FY3/27 短信;直接证据 / 一手证据(研究域07) / 一手证据(研究域14) / 定向深挖(研究域07) / 定向深挖(研究域14)|Overseas footprint and group companies, NSSOL company outline;直接证据 / 一手证据(研究域14) / 历史/同业比较(研究域05)|Industrial field detail in H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 一手证据(研究域26) / 一手证据(研究域30) / 定向深挖(研究域30)|Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信;直接证据 / 历史/同业比较(研究域26) / 定向深挖(研究域23) / 定向深挖(研究域26)|Statement of changes in equity, H1 FY3/27 短信;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域24)|Share count, treasury shares and 2024 stock split, FY3/26 短信 share section;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision governance under the articles, FY3/26 短信 dividend section;直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet;直接证据 / 支持证据 / 一手证据(研究域19) / 定向深挖(研究域17) / 定向深挖(研究域19)|Working capital build in H1 FY3/27, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:Durable Business Portrait and structural durability map|The foundation is a durable core-systems SIer: high switching costs, diversified enterprise and public demand, asset-light, unlevered, self-financing and cash-generative over a two-year window, with a delivered 50% payout. Five slow variables govern it: (1) Japanese DX demand and engineer scarcity; (2) AI delivery technology, which raises the productivity ceiling while threatening the labour-resale model, favourable only while TAM share actually climbs; (3) the parent's governance gravity — 63.44%, CMS pooling, 11.6% float — against a TSE reform ratchet pushing the other way; (4) the acquisition residue of ¥64,403m goodwill and intangibles making the equity story younger and more promise-based than the old NSSOL; (5) public and defence budgets, durable as policy but lumpy as projects. Self-repair capacity is strong on solvency and cash (no debt, flexible SG&A) and weak on governance (parent interest is structurally senior) and on impairment (arrives at once). Quarterly prints matter because they are the only windows through which these slow variables can be seen moving.
内部研究类型:durable_business_portrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Shareholders hold a durable, high-quality operating franchise whose equity ceiling is set by control structure and promise-based acquired assets rather than by operations.
不确定性(原始记录):Moat, labour economics (partner-staff ratios), churn and backlog not disclosed; governance report unread.
F042|07|日本制铁在需求、现金和控制权三个渠道同时用力
研究范围:开放研究+35项覆盖检查
写入正文:07|日本制铁在需求、现金和控制权三个渠道同时用力09|折价从哪里来:母公司的控制结构,只有母公司或股东压力才能改变12|一个变量四条渠道:为什么一条公告可以让价格跳空
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(29项,重复标签已合并)
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:直接 / 支持;一手验证:08、09、24
Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:29;外部现实校验:19
CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;外部现实校验:25;专项深挖:18、21
CMS deposit at September 2026, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
History spine 1980–2025, NS Solutions Corporation overview怎么使用:直接证据;一手验证:33;外部现实校验:07;专项深挖:33;同业比较:01、02、08、09;其他用途:历史
Management-field revenue, H1 FY3/27 短信 qualitative section怎么使用:直接证据;一手验证:03、05、12、13
Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators怎么使用:直接证据;一手验证:22;专项深挖:22、28
Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet怎么使用:直接证据;一手验证:18、25、29;专项深挖:18、29
Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327怎么使用:直接 / 支持;外部现实校验:24、30、35;专项深挖:24
Effective free float estimate, shareholder analysis compiled from securities reports怎么使用:直接 / 支持;一手验证:24
2327 market snapshot and disclosure index, IRBANK怎么使用:直接 / 支持;一手验证:27、31
Margin-trading balances for 2327, IRBANK怎么使用:直接 / 支持;外部现实校验:27;专项深挖:27
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信怎么使用:直接证据;一手验证:26、30;专项深挖:30
Statement of changes in equity, H1 FY3/27 短信怎么使用:直接证据;专项深挖:23、26;同业比较:26;其他用途:历史
Share count, treasury shares and 2024 stock split, FY3/26 短信 share section怎么使用:直接 / 支持;专项深挖:01、24;同业比较:24;其他用途:历史
Dividend decision governance under the articles, FY3/26 短信 dividend section怎么使用:直接证据;一手验证:23;专项深挖:23、25、26
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:支持证据;一手验证:18
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15、22、28
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:28
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement怎么使用:直接 / 支持;一手验证:17、20、25、32
Dividend yield cross-check at the 6 November 2026 close, IRBANK怎么使用:直接 / 支持;一手验证:27;外部现实校验:22、26、31;专项深挖:27、31
Recomputed moving-average structure, 2327 monthly series怎么使用:直接 / 支持;一手验证:34;外部现实校验:29;专项深挖:34;同业比较:31、35;其他用途:历史
Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release怎么使用:支持证据
Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信怎么使用:支持证据;一手验证:04、35
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:支持证据;一手验证:16;专项深挖:16
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:支持证据;一手验证:30、31、35;专项深挖:30、31、35
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:支持证据;外部现实校验:11;专项深挖:09、11、22、28、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域19)|Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域21)|CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|CMS deposit at September 2026, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域33) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 定向深挖(研究域33)|History spine 1980–2025, NS Solutions Corporation overview;直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域13)|Management-field revenue, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域28)|Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet;直接证据 / 支持证据 / 外部现实(研究域24) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域24)|Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327;直接证据 / 支持证据 / 一手证据(研究域24)|Effective free float estimate, shareholder analysis compiled from securities reports;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|2327 market snapshot and disclosure index, IRBANK;直接证据 / 支持证据 / 外部现实(研究域27) / 定向深挖(研究域27)|Margin-trading balances for 2327, IRBANK;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 一手证据(研究域26) / 一手证据(研究域30) / 定向深挖(研究域30)|Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信;直接证据 / 历史/同业比较(研究域26) / 定向深挖(研究域23) / 定向深挖(研究域26)|Statement of changes in equity, H1 FY3/27 短信;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域24)|Share count, treasury shares and 2024 stock split, FY3/26 短信 share section;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision governance under the articles, FY3/26 短信 dividend section;支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 一手证据(研究域25) / 一手证据(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域31) / 定向深挖(研究域27) / 定向深挖(研究域31)|Dividend yield cross-check at the 6 November 2026 close, IRBANK;直接证据 / 支持证据 / 一手证据(研究域34) / 外部现实(研究域29) / 历史/同业比较(研究域31) / 历史/同业比较(研究域35) / 定向深挖(研究域34)|Recomputed moving-average structure, 2327 monthly series;支持证据|Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release;支持证据 / 一手证据(研究域04) / 一手证据(研究域35)|Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信;支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信;支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press
完整研究记录(核对用)
研究原文:Parent triple-grip mechanism: demand, cash, control, float and valuation|One variable — Nippon Steel's position — acts through four channels at once: customer demand (18.5%), cash custody (about 90%), voting control (63.44%) and effective float (about 11.6%). It stabilises demand and balance-sheet calm, caps re-rating, stiffens the dividend-supported floor, and lets single governance headlines gap the price. Activist attention and TSE reform are the only observed forces loosening it.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Re-rating depends on a parent decision or governance pressure as much as on earnings; the discount may persist even if the plan is delivered.
不确定性(原始记录):Parent intent, CMS terms and 3D's position are unknown.
F043|01|计划算术:产品组合比需求更紧
研究范围:开放研究+35项覆盖检查
写入正文:01|计划算术:产品组合比需求更紧06|毛利率是整套逻辑里信息量最大的数字09|价格已经为计划的最后一步付了一部分14|八个模块的得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(31项,重复标签已合并)
Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信怎么使用:直接 / 支持;一手验证:04、35
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:直接 / 支持;外部现实校验:11;专项深挖:09、11、22、28、35
What the TAM model change means, Jiji Press report of the results怎么使用:直接 / 支持;一手验证:02;外部现实校验:04;专项深挖:02、03、10
Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:03、04、07
NSSOL 2030 Vision and the four transformations, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:10、11;专项深挖:02、03、04、10
Income statement detail FY3/26, FY3/26 短信 (IFRS P&L)怎么使用:直接 / 支持;一手验证:15、16;专项深挖:15、16
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:16;专项深挖:16
Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements怎么使用:直接 / 支持;一手验证:32;外部现实校验:17、28;专项深挖:17、32
Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet怎么使用:直接证据;一手验证:19;外部现实校验:15;专项深挖:15、19
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15、22、28
H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:28
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:30、31、35;专项深挖:30、31、35
Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release怎么使用:直接 / 支持
Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信怎么使用:直接 / 支持;外部现实校验:33
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:直接 / 支持;一手验证:18
Goodwill and intangibles step-up from FY3/26 acquisitions, FY3/26 短信 balance sheet怎么使用:直接 / 支持;外部现实校验:18、32;专项深挖:20、33
Management-field revenue, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:03、05、12、13
Management-field revenue, FY3/26 短信 (with reclassification note)怎么使用:直接 / 支持;一手验证:02、03
Defence-sector large project as C&DS growth driver, H1 FY3/27 短信怎么使用:直接 / 支持;外部现实校验:13;专项深挖:05、13
Distribution and platformer field declined in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;同业比较:12;其他用途:历史
Industrial field detail in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:14;同业比较:05;其他用途:历史
Demand environment as described by the company, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:05、11、12;专项深挖:05、11、12
Industrial and steel field in FY3/26, FY3/26 短信 field commentary怎么使用:直接证据;同业比较:05、12;其他用途:历史
FY3/25 comparatives and comprehensive income, FY3/26 短信怎么使用:直接 / 支持;外部现实校验:16、21;同业比较:28;其他用途:历史
Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators怎么使用:直接证据;一手验证:22;专项深挖:22、28
Other expenses normalising after the dispute years, FY3/26 短信 P&L怎么使用:直接证据;外部现实校验:28;专项深挖:32;同业比较:16、32;其他用途:历史
Segment information note: single segment, H1 FY3/27 短信怎么使用:直接证据;一手验证:02、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域35)|Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信;直接证据 / 支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域04) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域10)|What the TAM model change means, Jiji Press report of the results;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域07)|Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域11) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|NSSOL 2030 Vision and the four transformations, FY3/26 短信 qualitative section;直接证据 / 支持证据|Q1 FY3/27 results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 定向深挖(研究域15) / 定向深挖(研究域16)|Income statement detail FY3/26, FY3/26 短信 (IFRS P&L);直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域17) / 外部现实(研究域28) / 定向深挖(研究域17) / 定向深挖(研究域32)|Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements;直接证据 / 一手证据(研究域19) / 外部现实(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域15)|H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信;直接证据 / 支持证据|Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release;直接证据 / 支持证据|Initial FY3/27 guidance given with FY3/26 results;直接证据 / 支持证据 / 外部现实(研究域33)|Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 支持证据 / 外部现实(研究域18) / 外部现实(研究域32) / 定向深挖(研究域20) / 定向深挖(研究域33)|Goodwill and intangibles step-up from FY3/26 acquisitions, FY3/26 短信 balance sheet;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域13)|Management-field revenue, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03)|Management-field revenue, FY3/26 短信 (with reclassification note);直接证据 / 支持证据 / 外部现实(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域13)|Defence-sector large project as C&DS growth driver, H1 FY3/27 短信;直接证据 / 支持证据 / 历史/同业比较(研究域12)|Distribution and platformer field declined in H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域14) / 历史/同业比较(研究域05)|Industrial field detail in H1 FY3/27, H1 FY3/27 短信;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment as described by the company, FY3/26 短信 qualitative section;直接证据 / 历史/同业比较(研究域05) / 历史/同业比较(研究域12)|Industrial and steel field in FY3/26, FY3/26 短信 field commentary;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域21) / 历史/同业比较(研究域28)|FY3/25 comparatives and comprehensive income, FY3/26 短信;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域28)|Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators;直接证据 / 外部现实(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Other expenses normalising after the dispute years, FY3/26 短信 P&L;直接证据 / 一手证据(研究域02) / 一手证据(研究域10)|Segment information note: single segment, H1 FY3/27 短信
完整研究记录(核对用)
研究原文:Plan delivery chain: TAM mix → gross margin → operating profit → plan gap → expectations|Demand is not the constraint; mix is. TAM share lifts gross margin, gross margin (net of deliberate SG&A) lifts operating profit faster than revenue, and the FY3/28 ¥60,000m target needs a further ~¥11,000m from TAM near 75%. Acquisitions and a lumpy defence project supply part of the growth but add impairment and replacement risk. The implied H2 FY3/27 decline is the first dated test of whether management's conservatism or market scepticism is correct.
内部研究类型:main_causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Delivery of the plan's final step is what the price already partly pays for; shortfall in TAM and margin would arrive together.
不确定性(原始记录):TAM definition unaudited; bridge composition and defence renewal unknown.
F044|06|2026年3月期经营现金流为负,原因是税款错期和一笔和解款
研究范围:开放研究+35项覆盖检查
写入正文:06|2026年3月期经营现金流为负,原因是税款错期和一笔和解款08|约50%的分红比率兑现了,每股增长只靠盈利
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(17项,重复标签已合并)
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement怎么使用:直接 / 支持;一手验证:17、20、25、32
Consolidated cash flow H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:17
Settlement of litigation, notice by NetOne Systems (auxiliary participant)怎么使用:直接 / 支持;一手验证:33
Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements怎么使用:直接证据;一手验证:32;外部现实校验:17、28;专项深挖:17、32
Working capital build in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:19;专项深挖:17、19
Other expenses normalising after the dispute years, FY3/26 短信 P&L怎么使用:直接证据;外部现实校验:28;专项深挖:32;同业比较:16、32;其他用途:历史
H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation怎么使用:支持证据;一手验证:15
Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet怎么使用:直接 / 支持;一手验证:19;外部现实校验:15;专项深挖:15、19
Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信怎么使用:直接证据;一手验证:29;外部现实校验:19
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信怎么使用:直接证据;一手验证:26、30;专项深挖:30
Statement of changes in equity, H1 FY3/27 短信怎么使用:直接证据;专项深挖:23、26;同业比较:26;其他用途:历史
Share count, treasury shares and 2024 stock split, FY3/26 短信 share section怎么使用:直接 / 支持;专项深挖:01、24;同业比较:24;其他用途:历史
Dividend decision governance under the articles, FY3/26 短信 dividend section怎么使用:直接证据;一手验证:23;专项深挖:23、25、26
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:直接 / 支持;一手验证:18
Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet怎么使用:直接 / 支持;一手验证:18、25、29;专项深挖:18、29
Balance sheet at Q1 FY3/27, Q1 FY3/27 短信怎么使用:直接证据;同业比较:18;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 一手证据(研究域25) / 一手证据(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域17)|Consolidated cash flow H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域33)|Settlement of litigation, notice by NetOne Systems (auxiliary participant);直接证据 / 一手证据(研究域32) / 外部现实(研究域17) / 外部现实(研究域28) / 定向深挖(研究域17) / 定向深挖(研究域32)|Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements;直接证据 / 支持证据 / 一手证据(研究域19) / 定向深挖(研究域17) / 定向深挖(研究域19)|Working capital build in H1 FY3/27, H1 FY3/27 短信;直接证据 / 外部现实(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Other expenses normalising after the dispute years, FY3/26 短信 P&L;支持证据 / 一手证据(研究域15)|H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet;直接证据 / 一手证据(研究域29) / 外部现实(研究域19)|Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 一手证据(研究域26) / 一手证据(研究域30) / 定向深挖(研究域30)|Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信;直接证据 / 历史/同业比较(研究域26) / 定向深挖(研究域23) / 定向深挖(研究域26)|Statement of changes in equity, H1 FY3/27 短信;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域24)|Share count, treasury shares and 2024 stock split, FY3/26 短信 share section;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision governance under the articles, FY3/26 短信 dividend section;直接证据 / 支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet;直接证据 / 历史/同业比较(研究域18)|Balance sheet at Q1 FY3/27, Q1 FY3/27 短信
完整研究记录(核对用)
研究原文:Profit-to-cash transmission: tax lag, litigation, working capital and payout|Reported profit and operating cash flow diverge by timing: lagged tax on a prior-year securities gain, a settled lawsuit and a contract-asset build suppressed FY3/26 operating cash flow to −¥3,409m, then reversed to +¥31,235m in H1 FY3/27. Light capex and no debt let the 50% payout run on operating cash regardless; judgment is by rolling two-year sums.
内部研究类型:cash_transmission_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Cash quality is sound; apparent FY3/26 weakness is not an earnings-quality signal, but the cash itself is largely parent-custodied.
不确定性(原始记录):Medium: attribution inferential until FY3/27 full-year operating cash flow.
F045|01|计划兑现与治理事件,哪一个先改变这家公司的折价
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|计划兑现与治理事件,哪一个先改变这家公司的折价11|母公司收紧还是放松,决定哪个故事先落地13|每次业绩都要核对的门槛14|总分63.21/100,评级B,持有并跟踪、不追高
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(49项,重复标签已合并)
FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15、22、28
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:28
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:直接 / 支持;一手验证:08、09、24
Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release怎么使用:直接 / 支持
Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信怎么使用:直接 / 支持;一手验证:04、35
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:16;专项深挖:16
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:30、31、35;专项深挖:30、31、35
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:直接 / 支持;外部现实校验:11;专项深挖:09、11、22、28、35
Recomputed moving-average structure, 2327 monthly series怎么使用:直接 / 支持;一手验证:34;外部现实校验:29;专项深挖:34;同业比较:31、35;其他用途:历史
Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:26、30;专项深挖:30
Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327怎么使用:直接 / 支持;外部现实校验:24、30、35;专项深挖:24
Effective free float estimate, shareholder analysis compiled from securities reports怎么使用:直接 / 支持;一手验证:24
Management-field revenue, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:03、05、12、13
2327 market snapshot and disclosure index, IRBANK怎么使用:直接 / 支持;一手验证:27、31
Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:29;外部现实校验:19
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement怎么使用:直接 / 支持;一手验证:17、20、25、32
Share count, treasury shares and 2024 stock split, FY3/26 短信 share section怎么使用:直接 / 支持;专项深挖:01、24;同业比较:24;其他用途:历史
Dividend yield cross-check at the 6 November 2026 close, IRBANK怎么使用:直接 / 支持;一手验证:27;外部现实校验:22、26、31;专项深挖:27、31
Margin-trading balances for 2327, IRBANK怎么使用:直接 / 支持;外部现实校验:27;专项深挖:27
FY3/25 comparatives and comprehensive income, FY3/26 短信怎么使用:直接 / 支持;外部现实校验:16、21;同业比较:28;其他用途:历史
Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements怎么使用:直接 / 支持;一手验证:32;外部现实校验:17、28;专项深挖:17、32
Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators怎么使用:直接证据;一手验证:22;专项深挖:22、28
Other expenses normalising after the dispute years, FY3/26 短信 P&L怎么使用:直接证据;外部现实校验:28;专项深挖:32;同业比较:16、32;其他用途:历史
NSSOL 2030 Vision and the four transformations, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:10、11;专项深挖:02、03、04、10
What the TAM model change means, Jiji Press report of the results怎么使用:直接 / 支持;一手验证:02;外部现实校验:04;专项深挖:02、03、10
Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:03、04、07
Income statement detail FY3/26, FY3/26 短信 (IFRS P&L)怎么使用:直接 / 支持;一手验证:15、16;专项深挖:15、16
Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet怎么使用:直接证据;一手验证:19;外部现实校验:15;专项深挖:15、19
H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation怎么使用:直接 / 支持;一手验证:15
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信怎么使用:直接 / 支持;外部现实校验:33
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:直接 / 支持;一手验证:18
Goodwill and intangibles step-up from FY3/26 acquisitions, FY3/26 短信 balance sheet怎么使用:直接 / 支持;外部现实校验:18、32;专项深挖:20、33
Management-field revenue, FY3/26 短信 (with reclassification note)怎么使用:直接 / 支持;一手验证:02、03
Defence-sector large project as C&DS growth driver, H1 FY3/27 短信怎么使用:直接 / 支持;外部现实校验:13;专项深挖:05、13
Distribution and platformer field declined in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;同业比较:12;其他用途:历史
Industrial field detail in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:14;同业比较:05;其他用途:历史
Demand environment as described by the company, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:05、11、12;专项深挖:05、11、12
Industrial and steel field in FY3/26, FY3/26 短信 field commentary怎么使用:直接证据;同业比较:05、12;其他用途:历史
Segment information note: single segment, H1 FY3/27 短信怎么使用:直接证据;一手验证:02、10
CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;外部现实校验:25;专项深挖:18、21
CMS deposit at September 2026, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
History spine 1980–2025, NS Solutions Corporation overview怎么使用:直接证据;一手验证:33;外部现实校验:07;专项深挖:33;同业比较:01、02、08、09;其他用途:历史
Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet怎么使用:直接证据;一手验证:18、25、29;专项深挖:18、29
Statement of changes in equity, H1 FY3/27 短信怎么使用:直接证据;专项深挖:23、26;同业比较:26;其他用途:历史
Dividend decision governance under the articles, FY3/26 短信 dividend section怎么使用:直接证据;一手验证:23;专项深挖:23、25、26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域22) / 一手证据(研究域28)|FY3/26 consolidated results (Japanese GAAP-style 短信 under IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;直接证据 / 支持证据|Record interim profit and mid-term plan targets, Jiji Press report of the 2 Nov 2026 release;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域35)|Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信;直接证据 / 支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;直接证据 / 支持证据 / 一手证据(研究域34) / 外部现实(研究域29) / 历史/同业比较(研究域31) / 历史/同业比较(研究域35) / 定向深挖(研究域34)|Recomputed moving-average structure, 2327 monthly series;直接证据 / 支持证据 / 一手证据(研究域26) / 一手证据(研究域30) / 定向深挖(研究域30)|Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信;直接证据 / 支持证据|Q1 FY3/27 results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 外部现实(研究域24) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域24)|Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327;直接证据 / 支持证据 / 一手证据(研究域24)|Effective free float estimate, shareholder analysis compiled from securities reports;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域13)|Management-field revenue, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|2327 market snapshot and disclosure index, IRBANK;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域19)|Consolidated balance sheet at 2026-09-30, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 一手证据(研究域25) / 一手证据(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域24)|Share count, treasury shares and 2024 stock split, FY3/26 短信 share section;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域31) / 定向深挖(研究域27) / 定向深挖(研究域31)|Dividend yield cross-check at the 6 November 2026 close, IRBANK;直接证据 / 支持证据 / 外部现实(研究域27) / 定向深挖(研究域27)|Margin-trading balances for 2327, IRBANK;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域21) / 历史/同业比较(研究域28)|FY3/25 comparatives and comprehensive income, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域17) / 外部现实(研究域28) / 定向深挖(研究域17) / 定向深挖(研究域32)|Tax-payment lag and prior-year securities sales, FY3/26/FY3/25 cash-flow statements;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域28)|Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators;直接证据 / 外部现实(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Other expenses normalising after the dispute years, FY3/26 短信 P&L;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域11) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|NSSOL 2030 Vision and the four transformations, FY3/26 短信 qualitative section;直接证据 / 支持证据|Initial FY3/27 guidance given with FY3/26 results;直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域04) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域10)|What the TAM model change means, Jiji Press report of the results;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域07)|Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 定向深挖(研究域15) / 定向深挖(研究域16)|Income statement detail FY3/26, FY3/26 短信 (IFRS P&L);直接证据 / 一手证据(研究域19) / 外部现实(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Working capital build in FY3/26, FY3/26 短信 cash-flow and balance sheet;直接证据 / 支持证据 / 一手证据(研究域15)|H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 支持证据 / 外部现实(研究域33)|Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 支持证据 / 外部现实(研究域18) / 外部现实(研究域32) / 定向深挖(研究域20) / 定向深挖(研究域33)|Goodwill and intangibles step-up from FY3/26 acquisitions, FY3/26 短信 balance sheet;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03)|Management-field revenue, FY3/26 短信 (with reclassification note);直接证据 / 支持证据 / 外部现实(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域13)|Defence-sector large project as C&DS growth driver, H1 FY3/27 短信;直接证据 / 支持证据 / 历史/同业比较(研究域12)|Distribution and platformer field declined in H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域14) / 历史/同业比较(研究域05)|Industrial field detail in H1 FY3/27, H1 FY3/27 短信;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment as described by the company, FY3/26 短信 qualitative section;直接证据 / 历史/同业比较(研究域05) / 历史/同业比较(研究域12)|Industrial and steel field in FY3/26, FY3/26 短信 field commentary;直接证据 / 一手证据(研究域02) / 一手证据(研究域10)|Segment information note: single segment, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域21)|CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|CMS deposit at September 2026, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域33) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 定向深挖(研究域33)|History spine 1980–2025, NS Solutions Corporation overview;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet;直接证据 / 历史/同业比较(研究域26) / 定向深挖(研究域23) / 定向深挖(研究域26)|Statement of changes in equity, H1 FY3/27 短信;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision governance under the articles, FY3/26 短信 dividend section
完整研究记录(核对用)
研究原文:Thesis, falsification and catalyst calendar|Two stories compete: an operating compounder story tested by results prints and a captive-discount story tested by governance events. Either can resolve the shelf independently. The dated list of tripwires converts the narrative into checkable tests.
内部研究类型:thesis_falsification_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The position is an option on which story resolves first, with fundamental support for earnings but no protection for the price.
不确定性(原始记录):Tripwire levels are analyst-set; parent behaviour unknowable in advance.
F046|13|最先要回答的三个问题:下半年、母公司意图、资金池条款
研究范围:开放研究+35项覆盖检查
写入正文:13|最先要回答的三个问题:下半年、母公司意图、资金池条款13|第三层问题:防卫需求续约、领域披露口径、股东大会提案、派息路径15|证据限制:哪些事实没有核实,对判断有什么影响
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(36项,重复标签已合并)
Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:30、31、35;专项深挖:30、31、35
Income statement detail H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:16;专项深挖:16
H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation怎么使用:直接证据;一手验证:15
Full-year FY3/27 guidance revised upward, H1 FY3/27 短信怎么使用:直接证据;一手验证:28
Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report怎么使用:直接证据;一手验证:08、09、24
Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327怎么使用:直接 / 支持;外部现实校验:24、30、35;专项深挖:24
History spine 1980–2025, NS Solutions Corporation overview怎么使用:直接证据;一手验证:33;外部现实校验:07;专项深挖:33;同业比较:01、02、08、09;其他用途:历史
CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;外部现实校验:25;专项深挖:18、21
CMS deposit at September 2026, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators怎么使用:直接证据;一手验证:22;专项深挖:22、28
Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet怎么使用:直接证据;一手验证:18、25、29;专项深挖:18、29
Effective free float estimate, shareholder analysis compiled from securities reports怎么使用:直接 / 支持;一手验证:24
2327 market snapshot and disclosure index, IRBANK怎么使用:直接证据;一手验证:27、31
Margin-trading balances for 2327, IRBANK怎么使用:直接证据;外部现实校验:27;专项深挖:27
Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信怎么使用:直接 / 支持;外部现实校验:33
Consolidated balance sheet at 2026-03-31, FY3/26 短信怎么使用:直接 / 支持;一手验证:18
Goodwill and intangibles step-up from FY3/26 acquisitions, FY3/26 短信 balance sheet怎么使用:直接 / 支持;外部现实校验:18、32;专项深挖:20、33
Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:03、04、07
Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信怎么使用:直接 / 支持;一手验证:04、35
Mid-term plan targets and TAM trajectory restated, Jiji Press怎么使用:直接 / 支持;外部现实校验:11;专项深挖:09、11、22、28、35
What the TAM model change means, Jiji Press report of the results怎么使用:直接 / 支持;一手验证:02;外部现实校验:04;专项深挖:02、03、10
NSSOL 2030 Vision and the four transformations, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:10、11;专项深挖:02、03、04、10
Management-field revenue, H1 FY3/27 短信 qualitative section怎么使用:直接 / 支持;一手验证:03、05、12、13
Management-field revenue, FY3/26 短信 (with reclassification note)怎么使用:直接 / 支持;一手验证:02、03
Defence-sector large project as C&DS growth driver, H1 FY3/27 短信怎么使用:直接 / 支持;外部现实校验:13;专项深挖:05、13
Distribution and platformer field declined in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;同业比较:12;其他用途:历史
Industrial field detail in H1 FY3/27, H1 FY3/27 短信怎么使用:直接 / 支持;一手验证:14;同业比较:05;其他用途:历史
Demand environment as described by the company, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:05、11、12;专项深挖:05、11、12
Industrial and steel field in FY3/26, FY3/26 短信 field commentary怎么使用:直接证据;同业比较:05、12;其他用途:历史
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信怎么使用:直接证据;一手验证:26、30;专项深挖:30
Statement of changes in equity, H1 FY3/27 短信怎么使用:直接证据;专项深挖:23、26;同业比较:26;其他用途:历史
Share count, treasury shares and 2024 stock split, FY3/26 短信 share section怎么使用:直接 / 支持;专项深挖:01、24;同业比较:24;其他用途:历史
Dividend decision governance under the articles, FY3/26 短信 dividend section怎么使用:直接证据;一手验证:23;专项深挖:23、25、26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|Implied second-half FY3/27 figures inside revised guidance, H1 FY3/27 短信;直接证据 / 支持证据|Q1 FY3/27 results 短信 (IFRS), NS Solutions Corporation;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Income statement detail H1 FY3/27, H1 FY3/27 短信;直接证据 / 一手证据(研究域15)|H1 FY3/27 interim results 短信 (IFRS), NS Solutions Corporation;直接证据 / 一手证据(研究域28)|Full-year FY3/27 guidance revised upward, H1 FY3/27 短信;直接证据 / 支持证据|Capital policy and parent-group cash management, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域24)|Parent shareholding and parent-company sales, company-research note compiling the FY3/26 securities report;直接证据 / 支持证据 / 外部现实(研究域24) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域24)|Large-shareholding filings including 3D Investment Partners, IRBANK disclosure index for 2327;直接证据 / 一手证据(研究域33) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 定向深挖(研究域33)|History spine 1980–2025, NS Solutions Corporation overview;直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域21)|CMS deposit at FY3/26 year-end, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|CMS deposit at September 2026, H1 FY3/27 短信 qualitative section;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域28)|Profitability ratios FY3/26 vs FY3/25, FY3/26 短信 summary indicators;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Debt profile: no borrowings, leases only, FY3/26 短信 balance sheet;直接证据 / 支持证据 / 一手证据(研究域24)|Effective free float estimate, shareholder analysis compiled from securities reports;直接证据 / 一手证据(研究域27) / 一手证据(研究域31)|2327 market snapshot and disclosure index, IRBANK;直接证据 / 外部现实(研究域27) / 定向深挖(研究域27)|Margin-trading balances for 2327, IRBANK;直接证据 / 支持证据 / 外部现实(研究域33)|Infocom and PT. WCS Abyakta Nawesena made wholly owned, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域18)|Consolidated balance sheet at 2026-03-31, FY3/26 短信;直接证据 / 支持证据 / 外部现实(研究域18) / 外部现实(研究域32) / 定向深挖(研究域20) / 定向深挖(研究域33)|Goodwill and intangibles step-up from FY3/26 acquisitions, FY3/26 短信 balance sheet;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域07)|Strategic alliances and M&A in H1 FY3/27, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域35)|Mid-term plan progress: TAM-type revenue, Corepeak, AI delivery, FY3/26 短信;直接证据 / 支持证据 / 外部现实(研究域11) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域35)|Mid-term plan targets and TAM trajectory restated, Jiji Press;直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域04) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域10)|What the TAM model change means, Jiji Press report of the results;直接证据 / 一手证据(研究域10) / 一手证据(研究域11) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|NSSOL 2030 Vision and the four transformations, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域13)|Management-field revenue, H1 FY3/27 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03)|Management-field revenue, FY3/26 短信 (with reclassification note);直接证据 / 支持证据 / 外部现实(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域13)|Defence-sector large project as C&DS growth driver, H1 FY3/27 短信;直接证据 / 支持证据 / 历史/同业比较(研究域12)|Distribution and platformer field declined in H1 FY3/27, H1 FY3/27 短信;直接证据 / 支持证据 / 一手证据(研究域14) / 历史/同业比较(研究域05)|Industrial field detail in H1 FY3/27, H1 FY3/27 短信;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment as described by the company, FY3/26 短信 qualitative section;直接证据 / 历史/同业比较(研究域05) / 历史/同业比较(研究域12)|Industrial and steel field in FY3/26, FY3/26 短信 field commentary;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 一手证据(研究域26) / 一手证据(研究域30) / 定向深挖(研究域30)|Filing calendar: interim report and dividend payment dates, H1 FY3/27 短信;直接证据 / 历史/同业比较(研究域26) / 定向深挖(研究域23) / 定向深挖(研究域26)|Statement of changes in equity, H1 FY3/27 短信;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域24)|Share count, treasury shares and 2024 stock split, FY3/26 短信 share section;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision governance under the articles, FY3/26 短信 dividend section
完整研究记录(核对用)
研究原文:Prioritised Research Debt carried forward|Priority 1: implied H2 decline; parent's end-state stake; CMS terms. Priority 2: 3D's stake and proposals; Infocom PPA and impairment triggers; TAM verification. Priority 3: defence renewal; field-level disclosure under the new classification; June 2027 AGM proposals; payout path if FY3/28 lands between run-rate and target. Reasonable current public paths are exhausted for these; each names its resolving evidence. None requires reopening Research.
内部研究类型:research_debt_set
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):These unknowns condition confidence, valuation and the strength of the governance and plan judgments; none can be turned into certainty now.
不确定性(原始记录):Several resolve only through future disclosure (Q3 FY3/27, FY3/27 full-year, June 2027 AGM) or unread but public documents (governance report, securities report notes, EDINET filings).
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | 83913e70805428a175e9a1a023f4ea2d4c022ccb |
| Delivery Commit SHA | 83913e70805428a175e9a1a023f4ea2d4c022ccb |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | f2e5df8e-6c37-5143-919e-c1af283cfc65 |
| Canonical Revision | 1 |