北九州工厂的两组电池炉改造比计划提前约一个月完成。7–9月产量比4–6月增加20%以上,每吨加工成本大幅下降,焦炭板块当季转为盈利。另外,土地账面值333.99亿日元高于235.83亿日元的市值,银行和两大产业股东在两个亏损年度里没有逼出增资。
3315
日本コークス工業株式会社(Nippon Coke & Engineering Co., Ltd.)
日本コークス工業株式会社(Nippon Coke & Engineering Co., Ltd.,代码3315,东证 Prime 市场)主营焦炭及化工副产品的制造与销售。公司章程记载的英文名为 NIPPON COKE & ENGINEERING COMPANY, LIMITED。同时经营煤炭、石油焦等燃料销售与煤灰等资源回收,以及粉粒体机械与成套设备的综合工程业务。另有运输、不动产等其他业务。 估值简报:股价78日元(2026年11月6日收盘)。总市值235.83亿日元(按含库存股的已发行股数)。预测PER 45.4倍(按公司指引每股收益1.72日元,指引净利润仅5亿日元,倍数意义有限)。实绩PBR 0.65倍(2026年3月末每股净资产119.57日元)。 ROE -20.1%(2026年3月期实绩,亏损年度;不并列预测值)。预测股息率不适用(2027年3月期分红未定,2026年3月期分红为零)。EV/EBITDA 12.5倍。EV 828.3亿日元,等于总市值加净有息负债592.5亿日元(2026年9月30日:短期借款370.71亿加长期借款273.50亿减现金51.72亿)。EBITDA 66.2亿日元,等于2026年3月期营业利润6.07亿加折旧60.09亿。EBITDA取3月期、净负债取9月末,期间口径不一致。
最近亮点:2026年11月6日披露的2027年3月期(FY27/3)上半年(4–9月)业绩:营业利润11.03亿日元(同比增113.3%),高于公司自己的中期指引8亿日元;焦炭板块经营亏损缩到0.05亿日元(上年同期13.96亿日元)。全年计划原封不动,下半年仍须赚到营业利润24.97亿日元,当天股价下跌6.02%,收78日元。
短期借款370.71亿日元,现金只有51.72亿日元,净负债约592.5亿日元,全部排在股东之前。煤价若先于售价上涨,或2027年2月的第三季度财报显示下半年提升落空,公司要带着更薄的自有资本(27.2%)重回银行谈判。
结论:Kabugami 评分40.98/100(评分版本 V3.2),评级 C。暂不建立仓位,列入重点跟踪;结论取决于2027年2月和5月两次披露,之前不宜当作定论。 依据:成本和开工率的改善有实际数字,但债务排在股东前面,没有分红,股价仍在底部区间且没有抬高的低点,0.65倍市净率更像对生存风险的定价,不是安全边际。 翻转条件:2027年2月第三季度财报守住第二季度的水平、三年经营计划公布并写明恢复分红的条件、2027年5月全年业绩和分红决定兑现,再重新评估;毛利率或焦炭板块利润退回2026年3月期水平,或短期借款上升而现金下降,则按依赖银行的煤炭遗留业务处理。研究截止2026年11月9日,价格截至2026年11月6日收盘。 当前动作:暂不建立仓位,列入重点跟踪。公司的改善有实际证据,但债务排在股东之前、没有分红、价格结构也还没有走出底部,目前的低估值更多是对生存风险的定价,不是安全边际。接下来按时间验证:2027年2月的第三季度财报是否把第二季度的水平延续到下半年,三年计划是否发布并包含恢复分红的条件,2027年5月的全年业绩和分红决定。若这些都兑现,且短期借款没有重新上升、特别损失没有再出现大块,再重新评估;若第三季度毛利率或焦炭板块利润回到2026年3月期水平,或短期借款上升而现金下降,则把它归入依赖银行的煤炭遗留业务,不再考虑。
报告目录
01|投资问题与当前结论
01.1|两组焦炉改造完成后,股东能分到多少
判断:改善是真的,但这家公司的负债结构决定了只有一部分改善会走到普通股东手里。
核心问题因此变成:北九州焦炭工厂两组电池炉改造完成后,公司能否在整个周期里赚够债务利息,其中有多少最终属于没有分红、手持0.65倍市净率股票、排在约592亿日元净负债之后的股东。这件事要看交付证据:下半年的提升、2027年2月的第三季度财报、公司承诺的三年计划,不看叙事。
先看杠杆为什么重要。利息每年大致12亿日元(上半年付出6.17亿日元,按半年直线推算),处置损失和环境费用每期都会出现,净负债592亿日元对着235.83亿日元的市值。焦炭板块经营利润几十亿日元的摆动,就足以决定净利润是正还是负。对债权人这是小数字,对股东是全部。
反面一点:伴随闲置设备处理结束,表外之下的损失有可能收缩,这一项属于推断,还不能算数。
01.2|上半年超出指引,全年计划却一点没动
2027年3月期上半年,销售额481.07亿日元(同比降3.2%),营业利润11.03亿日元,经常利润4.38亿日元,归属母公司净亏损1.31亿日元(上年同期亏4.87亿日元)。公司5月给出的中期指引是营业利润8亿日元、经常利润为零、净亏损8亿日元,各项都被超过。
但全年计划保持不变:销售额1016亿日元,营业利润36亿日元,经常利润20亿日元,净利润5亿日元,每股收益1.72日元。倒推下半年需要销售额534.93亿日元、营业利润24.97亿日元、经常利润15.62亿日元。上半年经常利润只完成全年计划的21.9%。上半年超预期证明方向,没有证明幅度;公司也没有提供业绩说明资料或说明会。
支撑这个计划的机制,在一个干净的季度里已经看得到:工厂提前约一个月完成改造,2026年5月起用两组完好的电池炉运转,其中包括新建的2A电池炉。7–9月产量比4–6月增加20%以上,每吨加工成本(含修理与折旧)大幅下降,焦炉故障明显减少,焦炭板块当季转盈。
就整个上半年看,这个板块经营亏损从13.96亿日元缩到0.05亿日元,销售额还降了4.4%,所以改善来自成本和开工率,而不是售价或销量。证据限制也要写清:只有一个季度,每吨加工成本和价量拆分都没有披露。
01.3|当前结论:条件齐备才有上行,两次披露就能见分晓
如果两组电池炉守住第二季度的单位经济性,营业利润有望回到30亿至40亿日元的年化水平,2027年3月期计划得以兑现,股价可以从低于土地账面值的压力定价向资产价值靠拢。把握一般:这条判断依赖的开工率、毛利率、特别损失和银行耐心要同时再撑两个季度,而且指引只是承诺,上半年只完成经常利润计划的21.9%。
这条判断有时限,也有明确的推翻条件:2027年2月第三季度焦炭板块利润或集团毛利率退回2026年3月期水平;2027年3月期经常利润明显低于20亿日元,或再出现一大块特别损失;三年计划到2027年5月仍未公布,或公布后没有资本政策内容;短期借款从370.71亿日元明显上升而现金下降。任意两条成立,就推翻当前判断,公司会被归入长期规模不足、依赖银行的煤炭遗留业务。
再看估值。资产覆盖只能说明生存无忧,0.65倍市净率要上修,需要计划超预期或资本政策改变,不能只靠资产。所以动作是暂不建立仓位,列入重点跟踪,按时间验证。
02|公司本质与商业模式
02.1|两种性格不同的生意,共用一张资产负债表
这家公司在2004年3月10日重新上市,现为东证 Prime 市场3315,总部在东京丰洲,资本金70亿日元,已发行302,349,449股,其中库存股11,326,799股。集团由母公司加八家子公司组成,新日本制铁(Nippon Steel)和住友商事(Sumitomo Corporation)被披露为「其他关联公司」。
母公司持有焦炭工厂和大部分债务,所以只有合并报表才有意义。英文名按公司章程记载为 NIPPON COKE & ENGINEERING COMPANY, LIMITED,该信息来自转载章程的二手资料。
焦炭是一个商品加工价差生意:销量跟着钢铁需求,利润跟着煤价和焦炭价格谈判之间的时滞。2026年3月期该板块销售额561.34亿日元。燃料与资源回收(233.43亿日元)、综合工程(79.17亿日元)和其他(39.91亿日元)较小,但更稳。
2027年3月期上半年的结果主要由这几块撑起:燃料与资源回收加综合工程合计分部营业利润18.57亿日元,焦炭持平,集团不分摊的总部费用8.85亿日元(全年大致18亿日元)。非焦炭业务每年3.5亿到4.5亿日元量级的营业利润,能不能成为焦炭波动之下的底,决定盈利质量。限制是:各分部的资产和占用资本没有披露,分部回报无法计算。
02.2|最后一座煤矿关了,留下的是焦炉、港口和遗留负债
2027年3月期上半年,子公司 Sanmi Mining 退出煤矿业务,集团不再在任何地方开采煤炭,该公司的分部也从燃料与资源回收转入「其他」。三井矿山时代留下的东西,如今只剩焦炭工厂、围绕它的燃料物流、机械业务,以及遗留准备金。这次退出的财务影响没有单独披露。
这个变化去掉的是开采风险,没有去掉遗留环境负债,后者仍以债务般的形态留在资产负债表上。
02.3|资产撑过了每次冲击,每股价值却被亏损和时间稀释
公司的转折点连起来看:1889年三井接手三池煤矿;1950年金属部门分离;此后逐步退出煤炭开采;2003年因子公司土地重估导致资不抵债,进入产业再生机构(IRCJ)支持;2006年退出;2009年4月1日由三井矿山更名为现名并离开三井集团;2016至2020年股价长期处在压力区间;2025年11月做出设备优化决定,2026年5月完成两组电池炉改造。后者是第一次减少而不是重新排列生产资产的重置。
规律是:资产在每个阶段都活了下来,股东对资产的权益却在亏损和时间中被摊薄。问题从来不是能否生存,而是每股价值能否增长。
从这里可以得出耐久性判断。耐久的是物理和关系层面:配置好的两组电池炉加港口设施,供应到仍在运转的高炉的资质,两家股权多年未动的产业股东,以及在两个亏损年度里持续展期的银行。
脆弱的是流量:煤价与焦炭售价谈判之间的时滞,每期都出现的处置和环境费用,以及股权相对债务过于靠后,使小的经营失望变成大的股权失望。公司作为企业可以存续,作为投资仍未证明,这种不对称正是0.65倍市净率在表达的。
耐久性依赖一厂两炉格局下维护纪律能守住,银行与股东背后的合同条款则没有披露。
03|产品、客户与供应链
03.1|焦炉改造把利润变化压缩进了一个季度
2026年3月期,焦炭板块经营亏损从123.57亿日元缩到23.28亿日元,原因是修理费等固定成本下降,以及产量增加摊薄了每吨固定成本,即使2025年12月北九州工厂输煤带起火也没改变这一方向。当年焦炭产量99万吨(增7.3万吨),销量97.2万吨(增10万吨)。起火后工厂用起重机装煤的替代方式保持生产。
这个机制的起点是2025年11月11日的决定:把四组电池炉中两组老炉闲置,以新建的2A电池炉为中心。2026年5月完成后,管理层说要转向预防性维护,把原先浇在老炉上的资源转到整个工厂。
剩下的空白很具体:每吨加工成本和毛利,在满负荷下是多少,第二季度的改善有多少来自销量摊薄、多少来自价格。这决定了它是一次成本重置还是一个季度的销量效应;要等第三季度和全年分部披露才能回答。
03.2|煤价与焦炭售价之间的时滞,才是利润的真变量
主要原料是进口炼焦煤,用美元计价,在海运市场定价;焦炭以日元谈判,调整滞后。这个错配就是利润机制:宏观因素通过这一根管道进入利润表,日元走弱和煤价上涨实际上是同一件事。2025年3月期毛利率为负、销售成本高于销售额,是这种时滞最极端的一次。
同时有两个周期叠加:工厂可用性(公司能控制,现在正在改善)和商品价差(由外部决定)。改造完成后,可控周期的方差在下降,不可控的这一项主导了利润的波动。原料与资材库存160.52亿日元(2026年9月末),显示这条管线的规模;住友商事是煤炭采购联盟的伙伴。限制是:指引使用的煤价和汇率假设、采购条款和对冲安排都没有披露,下半年计划的煤价假设是最大的未知。
03.3|新日铁和住友商事同时是客户、供应商和股东
新日本制铁持股22.55%,是最大股东,也是焦炭主要买家,并是联盟伙伴;公司声明保有独立决策权。住友商事持股19.43%,是贸易商对手方,负责联盟中的煤炭采购与燃料销售。
三方联盟覆盖焦炭稳定供应、技术合作和煤炭采购与销售。这使公司的需求、原料来源和融资背景都有稳定的对手方,保证了数量;代价是价格谈判地位不完全独立。联盟的商业条款没有披露。
03.4|综合工程利润率最高,但订单能否持续还不清楚
综合工程是集团每单位销售利润最高的业务:2027年3月期上半年营业利润9.42亿日元,外部销售额41.54亿日元,利润率22.7%(按外部销售额)。机械业务利润比上年增70%以上,为公司成立以来最高,动力是抹茶用茶叶磨机(Tea Meister Mill)订单,以及AI相关带动的电子部件订单恢复。
分部利润2026年3月期14.77亿日元,2025年3月期推算约20.72亿日元,约占集团销售的8%。终端需求是抹茶热潮和电子材料厂商,与煤炭周期无关,子公司有明有电机工业(Ariake Kiden Kogyo)。
但它弥补不了焦炭的波动。订单余额和产品拆分都没有披露,这是一次订单高峰还是持久的小众业务,仍未解决,需要在订单与余额披露里找答案。
03.5|燃料业务销量在缩,港口物流能补多少没有数字
燃料与资源回收处在销量管理式下滑中:2026年3月期燃料销量降到82万吨(减4.5万吨),客户在改用其他能源;2027年3月期上半年分部利润减少6.41亿日元至9.15亿日元,因为一个客户的业务转换压低了销量,上年同期的现货交易也没有重演。2026年3月期该分部营业利润26.30亿日元。
管理层的对策是利用自有港口和呼叫中心,使用焦炭优化后空出的堆场,并考虑加强能源物流能力。这些设施在异常天气导致周边燃料配送中断时证明过价值。子公司三池港口物流(Miike Port Logistics)负责港口设施。物流转型实际带来多少销量,以及现货与长约比例,没有披露,这一块的稳定程度影响盈利底部。
04|竞争格局与产业关系
04.1|焦炭需求在缩小,公司靠开工率在缩小的池子里拿份额
焦炭需求是国内粗钢产量派生出来的,长期方向向下。2026年3月期销量仍增加10万吨到97.2万吨,是因为工厂终于能开工,是在持续缩小的池子里争得的份额和可用性,不是需求回升。氢还原炼铁和电炉等替代路线,以十年尺度逐步绕开焦炭。公司在中期层面按这个池子的方向承担风险,三年计划的需求假设尚未发布。
它的位置是少数几家独立的商业焦炭厂之一,日本大部分焦炭产能在新日本制铁和 JFE 集团内部自用。自用炉老化时稀缺性会增值,但前提是工厂能运转,2025年3月期停工那一年已经显示相反的结果。客户中新日铁集团与其他客户的比例、供货合同条款、对自用炉的交付成本比较,以及稀缺性本身的真实程度,都没有量化。
04.2|真正的竞争对手是钢厂自己的焦炉
公司争夺的是商业市场的余量,以及自用炉停产或重建时释放出来的销量。这个竞争对手同时是客户的集团,所以价格不由公司单独决定。交付成本相对自用炉处于什么水平,公开数据看不到。
05|护城河判断
判断:护城河存在但偏窄,只覆盖销量。公司的资质来自对特定高炉的供货认证和自有港口物流,而年度谈判仍然只是把煤价滞后地转嫁,没有出现独立定价权的证据。
反证很具体:2026年3月期销量增加主要来自工厂恢复运转,不是需求增加或议价提高;燃料板块销量下降说明部分客户在离开煤炭;合并毛利率2027年3月期上半年仅9.0%,不足以说明护城河带来定价权。
耐久性方面,物理与关系层面的结构(两组电池炉、港口、两家产业股东、银行的展期)能持续到高炉大规模关停之前,前提是工厂可用性。工程与燃料物流是非煤炭的收益来源,但合计只占集团销售的一成多。对股东而言,这撑住的是盈利和估值的下限,推不动估值倍数持续抬升,复苏的价值上限因此受限。
06|财务质量与现金流
06.1|毛利率分三步修复,修复来自成本不是售价
合并毛利率2025年3月期为负2.1%(销售成本高于销售额,毛亏21.15亿日元),2026年3月期回到7.9%(毛利72.16亿日元),2027年3月期上半年9.0%(毛利43.43亿日元)。每一步的驱动都是产量恢复、修理费下降和固定成本摊薄,而不是营业额增长;2026年3月期销售额还下降了7.7%。营业利润率从0.7%升到2.3%。
改善发生在毛利这一行,也就是工厂物理发生的地方,方向对。但相对利息和下面的漏损仍然很薄。
还要注意一个限制:焦炭每吨的实际售价没有披露,吨数有披露,所以毛利率改善中价格与成本各占多少,外部无法拆分,归因只在管理层手里。判断时应看吨数和分部利润,不能看合并销售额;吨数和产量比日元数字领先约一个季度,第二季度的销量比上半年销售额更能说明问题。
06.2|下半年的利润要靠第二季度的水平再撑六个月
第二季度单季经常利润10.70亿日元(同比降11.6%),营业利润率4.9%。公司要求的下半年经常利润15.62亿日元,大致等于把这个季度的水平再保持六个月,而不是进一步加速。但对比2026年3月期下半年:营业利润只有0.90亿日元,经常亏损推算约6.8亿至6.9亿日元(两个来源推算略有差异),销售额417.06亿日元,下半年计划销售额要增长约28%。
固定的利息是这条桥上最硬的一环。上半年利息6.17亿日元,超过经常利润4.38亿日元,全年约12亿日元的利息先要被覆盖,经常利润才存在。所以部分兑现只会让经常利润接近零,股权需要整个计划,不是一部分。
下半年计划的煤价、售价和销量假设没有披露,这是计划里最大的未知。第三季度分部披露、产品库存是否出货,是最早的外部检验。
06.3|经营现金流多半来自折旧和减值,自由现金流接近零
2026年3月期经营现金流85.11亿日元,主要由折旧60.09亿日元和不涉及现金的减值44.36亿日元构成,另有应收账款减少30.23亿日元,被库存增加14.86亿日元抵消。固定资产购买79.65亿日元(投资现金流−86.84亿日元),自由现金流接近零,期末现金63.88亿日元;2025年3月期经营现金流为负。
在建工程从2025年3月末的25.73亿日元降到2026年3月末16.81亿日元、2026年9月末11.83亿日元,说明设备投入从建设转向收获。折旧每年约60亿日元,建立在较老的资产基础上,会让现金转换看起来更好。如果利润兑现,同样的折旧可以转去还债或分红,不再用于建设,所以现金由负转正,而不是会计利润,决定任何分配。
2027年3月期上半年没有现金流量表,经营现金流看不到;保持两组电池炉所需的维持性资本开支也没有披露。
06.4|重启靠供应商的信用垫着,产品库存要在第三季度出货
2027年3月期上半年,应收账款增加23.87亿日元,产品库存增加20.93亿日元,与第二季度产量先于下半年发货一致。这笔垫付主要靠应付账款增加67.08亿日元来融资,现金减少12.19亿日元,长期借款还了20.40亿日元,总资产增加19.54亿日元。
也就是说,重启部分由供应商的信用垫着。供应商配合时这是高效的融资,条款收紧时就变脆弱,银行之外又多了一层依赖对手方善意的风险。应付款条款和是否有供应链融资没有披露,也没有中期现金流量表可确认现金影响。
产品库存的20.93亿日元能否在2026年12月季度末前作为下半年销量出货,还是留在第三季度的资产负债表上,是下半年需求侧是否真实的第一个实物检验,也是免费的先行信号;库存的成本计价与可变现性没有单独披露。
06.5|每次经营改善都被特别损失吃掉一块
2026年3月期营业利润6.07亿日元,但净亏损76.78亿日元,因为70.57亿日元的特别损失记在营业利润之下:闲置焦炭资产减值44.36亿日元、固定资产处置损失10.94亿日元、2025年12月输煤带起火的灾害损失5.80亿日元。
即使在复苏的2027年3月期上半年,仍有特别收入2.81亿日元(和解金2.15亿日元、资产出售收益0.61亿日元),对应特别损失8.45亿日元,其中处置损失7.25亿日元,税前亏损1.25亿日元,净亏损1.31亿日元。特别项目每期都有,没有会计政策变更或追溯重述。
环境费用是另一路慢性漏损:环境对策准备金在2026年3月和9月都是40.45亿日元,营业外每年计入711万日元的说法需要纠正为:2025年3月期7.11亿日元,2026年3月期3.32亿日元,来自旧煤矿和工业用地,与焦炭周期无关,近似债务。
在估算正常盈利时,这些漏损要放进区间宽度里,不能剔除;全部剔除会高估盈利能力。处置损失会随闲置资产处理完成而减少,但2027年3月期全年合计和留用设备的减值测试假设没有核查,递延所得税资产12.92亿日元的回收性也没有核查。这些都是目前无法证明、也无法排除的项目,要靠有价证券报告书的税务与减值附注来解决。
06.6|资产负债表是最紧的约束,银行条款一概未公开
2026年9月末总资产1284.99亿日元,净资产349.22亿日元,自有资本比率27.2%,2022年3月期还是44.5%,此后依次为38.7%、40.0%、31.8%、27.5%(2026年3月期)。短期借款370.71亿日元,长期借款273.50亿日元,合计644.21亿日元,对应现金51.72亿日元,净负债约592亿日元;另有环境准备金40.45亿日元和退休金负债25.46亿日元。
2026年3月期按经营现金流计的利息保障倍数9.7倍,有息负债相当于经营现金流7.9年。
融资靠展期:2026年3月期短期借款借入3175.57亿日元、偿还3097.13亿日元,约为年末短期借款余额的五倍,主要银行的理解在当年被公司公开记录。授信额度、担保(包括土地是否已设定抵押)和财务约束条款都没有披露,银行真实的容忍度只能从展期行为推断。
整条机制连起来:焦炭利润等于销量乘以(焦炭价格减煤价减加工成本)再扣固定成本;改造攻击的是加工成本和开工率,价格相对煤价滞后;利息是优先的固定索取,特别损失把改善漏出营业利润之下;非焦炭板块能缓冲但替代不了焦炭的摆动。股权的损失又反过来加重对银行的依赖。所以经营方差在股权上被放大,改善先还债,股东最后拿、波动最快。
06.7|资本回报低于同业,计划兑现也补不上缺口
2026年3月期净资产收益率−20.1%(2025年3月期−28.4%),营业利润率0.7%,自有资本比率27.5%,都低于石油煤炭行业的中位数(净资产收益率8.0%、营业利润率5.4%、自有资本比率37.1%)。第三方机械汇编的投入资本回报率为0.4%。
即使全年计划兑现,净利润5亿日元对应的净资产收益率也只有1.4%左右,离任何合理的股权资本成本都差得远。分母是完整的工业资产,分子是只配置了一半的工厂。限制:投入资本回报率是第三方机械汇编,公司自己的资本成本表述没有查阅;七家公司的同业组是能源加工企业,不是争夺焦炭销量的一体化钢厂。
07|股东、董事与治理
07.1|两大产业股东把股东名册固定住了
新日本制铁持股22.55%(65,628,595股),住友商事持股19.43%(56,558,095股)。日本 Master Trust 信托银行(信托账户)持股5.55%,前十大股东合计55.06%。自由流通部分不到一半,其中最大一块是信托银行托管户。两家产业股东的持股在至少四份有价证券报告书里没有变化。
两家都是关联公司、主要客户和采购对手方,处在三方联盟里,公司声明没有正式的控制权。2026年6月公司发布澄清:新日铁表决权22.6%,住友商事19.4%,公司保有独立决策并没有受到正式业务限制;该澄清我们是通过二手摘要看到的。
这个结构同时解释了两件事:公司为什么能挺过两个亏损年度,以及治理上的折价为什么存在,二者出自同一个原因。
07.2|稳定的另一面:市场化的重组也被一并挡住
锚定股东使无序崩塌或敌意收购不太可能,同样使市场主导的增资重组不太可能,所以少数股东的结果几乎全取决于经营兑现。自由流通股偏薄,投机性成交可以大幅推动价格,却不改变控制权。
未知的是:两家是否把合计42%的持股视为永久,以及复苏停滞时,是否支持或阻止增资、资产出售或合并。没有任何停止协议、支持函或联盟条款披露,只能在以后的持股申报或资本动作中观察到。
07.3|管理层集中而内部化,薪酬全部与业绩挂钩
董事会为四名内部董事,设监事会,社长 Hiroaki Matsuoka 经历了亏损年度和设备优化决定。董事报酬8200万日元全部是业绩挂钩的现金;两名内部监事1400万日元,三名外部人员合计1900万日元。业绩挂钩的薪酬使管理层与利润线一致,但向锚定股东的问责比向市场更直接,一个可信的计划加上恢复分配,是唯一会改变股东名册的治理信号。
同一管理层按期推进优化并提前约一个月完成改造,执行力不弱。董事会评价、技能矩阵和外部董事的独立性细节没有核查。
08|资本政策
08.1|两年亏损耗掉近一半留存收益,分红随盈利一起消失
留存收益从2024年4月的485.51亿日元,降到2025年3月末337.69亿日元、2026年3月末260.90亿日元,2026年9月末259.59亿日元。两个亏损年度消耗了约46%的缓冲,自有资本比率从40.0%降到27.5%。
最近一次实际支付的分红是2024年3月期的8.73亿日元,在2025年3月期支付;2025年3月期、2026年3月期分红为零,2027年3月期未定,中期也没有分红。库存股占3.7%一直未用,也没有回购。公司明确的优先事项是充实自有资本,不是分配,分红记录与盈利记录完全对应,所以2027年5月的分红决定是一个清晰的、有日期的管理层信号。
没有净资产股息率(DOE)或分红比例框架,分红是自主决定,时间也不确定。
08.2|资本政策是银行优先:现金先还债,亏损由股权承担
现金流先偿还并展期债务,股权吸收亏损,分配排在后面。没有增资,没有回购,没有正式的分配框架;公司表述的政策是在股东回报与重建盈利基础所需的投资和留存之间取平衡。在0.65倍市净率下没有发出稀释信号,这本身对股东有利。2024年3月期分红8.73亿日元,显示盈利恢复时分配的量级。
约束来自现金:2026年3月期自由现金流接近零,没有留给还债之外的任何用途,所以政策是银行优先,直到现金转正;折旧约60亿日元如果不再用于建设,才可能为分红打下基础。这里的关键是耐心,不是股数。
三年经营计划是否会设定分红框架、现金优先还债还是恢复分红,目前没有披露:公司2026年5月把资本政策答案推后,计划本身也没有公布日期。该计划的发布时间、有没有资本政策内容、对焦炭销量与利润的承诺,以及是否假设国内粗钢需求企稳,都还是问号;到2027年5月没有发布,本身就是推翻条件之一。
09|估值与安全边际
09.1|价格在为生存定价:资产说便宜,盈利说无物可估
2026年11月6日收盘78日元,市值235.83亿日元(按302,349,449股已发行股数)。市净率0.65倍,按2026年3月末每股净资产119.57日元,2026年9月末约120日元。预测市盈率45.4倍,在指引净利润5亿日元的舍入量级上算术正确,但没有经济意义。2026年3月期净资产收益率−20.1%,预测股息率不适用,EV/EBITDA 12.5倍。
口径要说明:EBITDA 66.2亿日元用的是2026年3月期,净负债592.5亿日元用的是2026年9月末,市净率用3月期账面。市值使用含1132.7万股库存股的已发行股数,扣除库存股后约2.910亿股,市值约227亿日元。另外没有分析师一致预期,没法推算市场隐含的兑现概率。
16年里市净率大致在0.3至1.6倍之间(2026年3月期高点对应1.28倍),现在偏中下。压力时期曾低到0.30至0.31倍。资产锚说期权便宜,盈利锚说目前没什么可资本化。
09.2|土地账面值高于市值,但它是生存缓冲,不是变现价值
土地账面值333.99亿日元,是净资产349.22亿日元的96%,所以公司市值低于仅土地的账面值。投资有价证券21.66亿日元,含10.65亿日元的未实现收益储备;少量处置(资产出售收益、和解金)起到筹资辅助作用。
但土地按取得成本计价,没有评估价,抵押、担保和整治义务是否附着都没有披露。旧矿山和工业用地的环境义务可能附着在土地上(这是推断),所以土地只能当作生存缓冲。环境准备金与脱碳期限一起,把土地从简单的资产锚变成了部分受限的锚。
因此估值是对持续经营和治理的判断,不是资产评估:市场为生存和兑现付钱,计划落地或资金模式破裂时,同一批资产会被很快重新定价。资产覆盖让期权得以持有,不是回报路径。
09.3|正常化后的盈利大致在0到30亿日元,净利润近乎于零
在改造完成的工厂格局下,合并经常利润的正常水平大致在0至30亿日元,中心接近计划的20亿日元。非焦炭板块贡献营业利润35亿至45亿日元,扣除约18亿日元的总部费用。焦炭板块围绕盈亏平衡上下摆动数十亿日元(近期证据看,约−20亿到+20亿日元)。锚点:2025年3月期经常亏损102.69亿日元,2026年3月期经常亏损2.76亿日元,2027年3月期计划经常利润20亿日元。
持续的处置与环境漏损已经放进区间宽度里,所以正常化的净利润很薄,近乎于零到15亿日元;在中心水平上,按市值计算股权的经常利润回报大致是8%至12%,漏损之前。恢复情景没有给持续漏损留余地。
限制:新配置下焦炭全周期每吨利润要几年之后才看得到;2022至2023年3月期的煤价飙升年度被刻意排除,没有重新核实。反方证据是2026年3月期的特别损失。
09.4|一个超预期的半年被卖掉,说明市场按部分兑现定价
2026年11月6日股价下跌6.02%至78日元,成交973.63万股,原因是上半年经常利润只完成全年计划的21.9%,而隐含的下半年摆动(从推算的2026年3月期下半年经常亏损约6.8亿日元,到+15.62亿日元)是整个计划里最大的假设。市场报道的概括是「上半年经常利润增6%、第二季度降12%」。
杠杆正是这个反应的原因:净负债近592亿日元,经常利润要在重复兑现之后,才会被相信到达股权,一次超预期不够。所以买入的前提是预留重复兑现的时间;好消息被卖掉,意味着兑现要重复才会被资本化。
这个预期是从一次公布的价格反应和二手报道推出来的,信托账户背后的机构仓位看不到;反方可能性是,卖出的原因是资金需要而不是不信。价格侧的镜像:2026年3月的冲高在改造完成之前先行,随后被完全吐回,详见技术结构一章。
09.5|下行是缓慢拖长,不是快速塌陷
下行有缓冲,没有底。保护:账面333.99亿日元的土地,以及吸收了两个亏损年度而没有稀释的银行与股东结构。非保护:约592亿日元的净负债排在股权之前,自有资本比率降到27.2%,市场在2020至2021年表现过的压力定价是0.30至0.31倍市净率(51至52日元),按目前每股账面值约120日元折算约36日元。
阻止塌陷的锚也阻止快速增资,所以现实的坏路径是在0.3至0.5倍市净率之间长期拖延,同时亏损吞噬缓冲,像2016至2020年那样,股价多年停在58日元到138日元之间。这是一次从78日元大致腰斩、缓慢实现的亏损情景。保护是行为上的,不是合同上的;土地和工厂上的担保和抵押没有披露,也没有估算清算价值。
09.6|脱碳是终值问题,不是未来两次财报的问题
高炉炼钢脱碳是焦炭板块经营资格的长期约束:政策成本已经以缓慢的环境费用进入报表(短期现金影响小),战略期限在需求侧以十年尺度运作(对终值影响大);氢基和电炉炼钢会完全绕开焦炭。这意味着焦炭板块的终值期限有限,现金回收宜早不宜晚。没有查阅明确点名焦炭的 GX 或碳成本定价,碳成本传导机制也没有披露。
09.7|杠杆放大了估值后果
债务排在前面,把几十亿日元的经营摆动变成股权的决定性摆动,所以0.65倍市净率不是低估的证明。对估值的含义是:资产支撑生存,薄的正常化盈利配上低于资本成本的回报,使上修需要计划超预期或资本政策改变;持续漏损若按2026年3月期的速度继续,复苏情景就没有空间。
10|Kabugami 技术结构
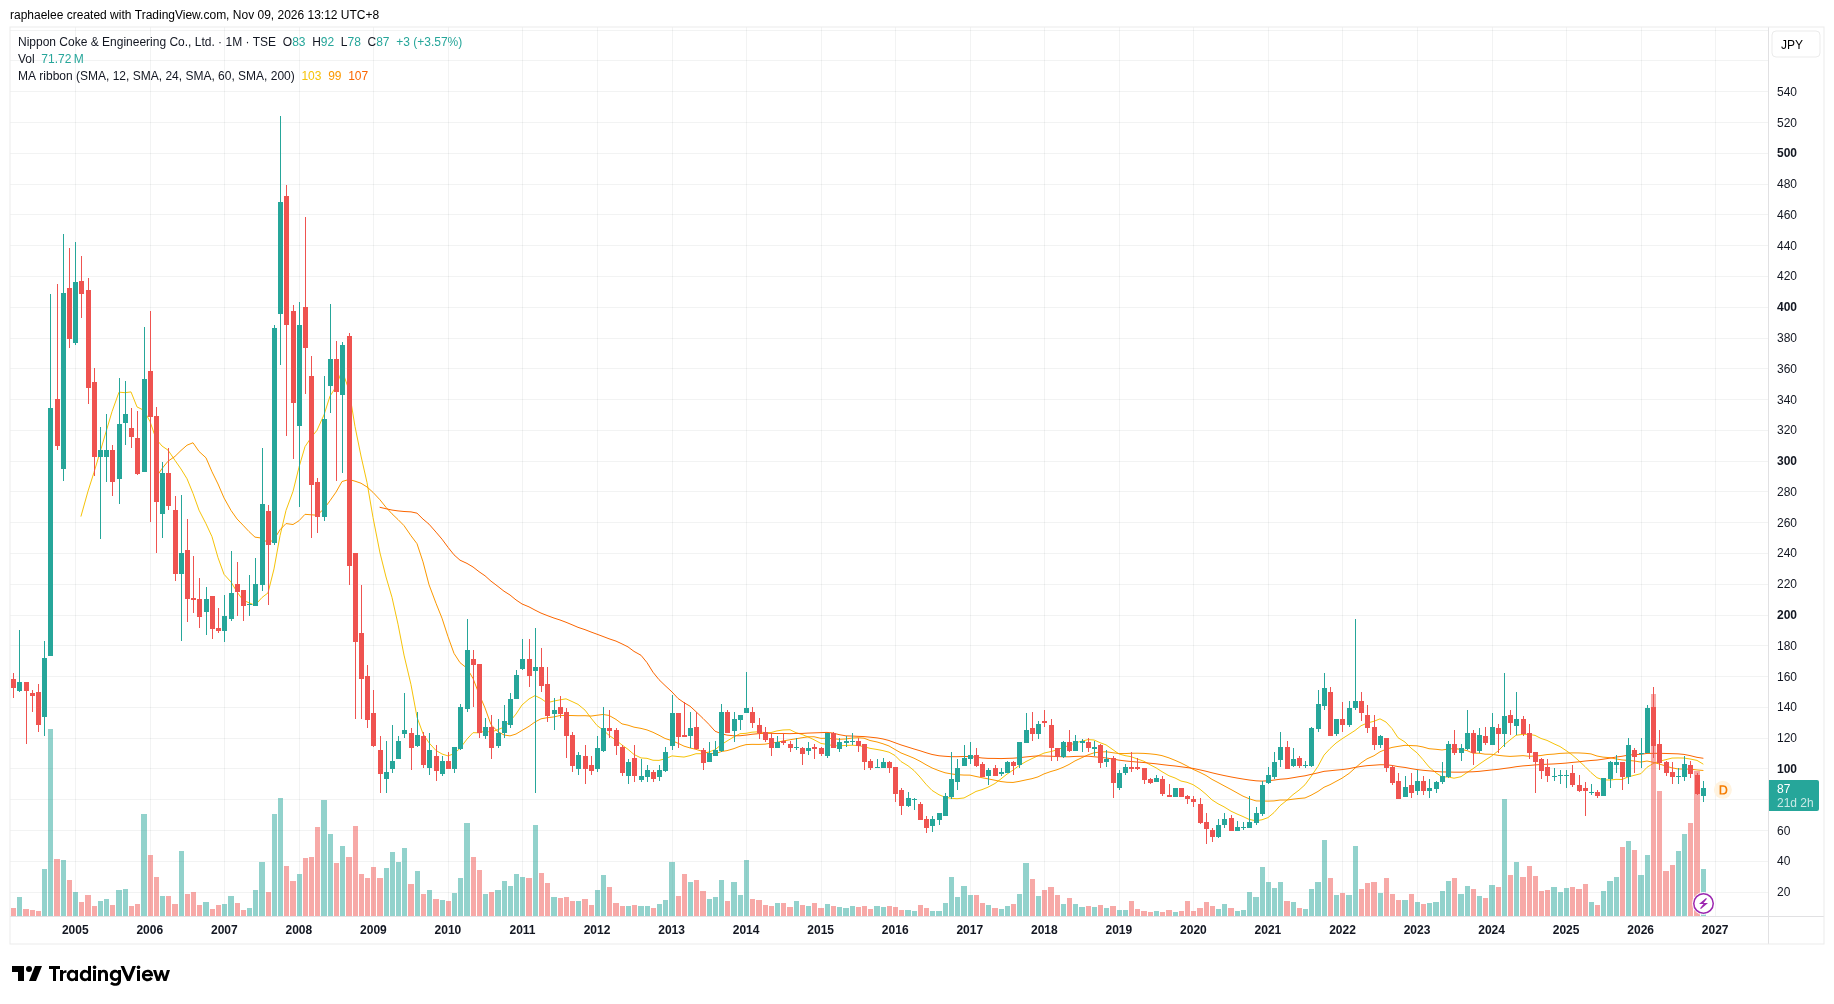
10.1|价格从2007年的497日元一路下来,十年只在51到200日元之间来回
这只股票的技术问题是:不看基本面,十年的箱体有没有走出下跌结束所需的三项证据——下跌回合逐渐变弱、低点抬高、站回长期均线;还是2026年3月那次冲高,只是未完成的底部里又一次失败的上冲。
数据是2004年3月重新上市至2026年10月共272根月线,10月为截至26日的未完成月线,数据未复权且缺少最后一段。价格在2007年10月见到上市以来最高的497日元,2020年3月见到最低的51日元。2026年10月收盘85日元,处在全部区间的7.6%;2026年11月6日收盘78日元,约6%,位于自身历史最低的一成。
年度低点依次是:2016年58日元、2017年89、2018年81、2019年77、2020年51、2021年90、2022年81、2023年81、2024年84、2025年69、2026年(截至10月)83日元。序列没有抬高:2025年的69日元跌破了2024年的84日元,2026年的83日元只比它略高,而且出现在3月冲高之后的10月。
2016至2025年每个年度高点都在120至200日元之间被压回。2021年3月期至2026年3月期的年度高点162、197、138、162、150、153日元,对应低点52、100、81、84、84、69日元,2022年3月期以来没有一个年度收在接近区间高位的位置。
10.2|价格比三条长期均线低15%到25%,下跌回合没有缩浅
以下把「在箱体里待了很久,却没有抬高低点、也没有站回均线」的状态简称为「未完成的底部」。
12个月、24个月、60个月均线分别是105.3日元、99.1日元、107.2日元,三条线挤在8日元之内,聚在99至107日元。78至85日元的价格比这个均线区低15%至25%。箱体的重心大致在100至130日元,和均线区基本重合,所以站回均线和离开箱体几乎是同一件事。
下沿的支撑是真实的:51至84日元这一带守了十年。但只有承接,没有进展:下跌回合没有缩短成一个抬高的序列,69日元的2025年低点就破了84日元。压力位有两层,99至107日元的均线区,以及2016至2025年压住每个年度高点的120至200日元。
没有出现压缩。2026年的行情把区间和成交量都推到了这只股票的极值,并向下收场;这只股票释放能量靠脉冲,不靠区间收窄后的蓄势。参与度的确变了:近十二个月月均成交约1.34亿股,是2019至2023年均值约2900万股的4.6倍。
10.3|2026年3月放量冲到153日元,七个月后涨幅全部吐回
2026年3月,当月成交3.467亿股,超过全部已发行股数3.0235亿股,盘中最高153日元,收盘115日元。之后七个月的月收盘依次是104、98、95、95、103、97、85日元,完全回到此前的底部区间,10月之后11月6日又到78日元。
这是箱体内典型的放量见顶式冲高,不是突破。它没有一项迁移质量的指标过关:顶部放量,之后任何一个月收盘都没有保住涨幅,并立刻跌回起点以下。
形态是区间而不是趋势:长时间窄幅停留,夹着短暂的垂直上冲,然后回落。过去十年里,120日元以上的上冲没有一次守过年底,而放量最大的这一次回落得最快。价格从2020年51日元的低点出来后,花了数年才重新碰到150至200日元,也没有守住;建设以年计,失败以月计。100至153日元之间堆积的套牢筹码,以后任何一次接近均线区时都可能碰上。
10.4|融资买入是融券的近十倍,破位时容易变成被动卖出
融资买入余额889.28万股,融券89.71万股,比值9.91倍(读数为2026年7月,11月可能不同)。融资买入约占自由流通股的3.1%。这意味着价格跌破69至83日元这一带时,先遇到的可能是被迫平仓,不是价值买盘。这是价格侧的风险;上述读数是7月的,不是11月截止日的。
10.5|纯价格状态定下之后,再看价格对公开事件的反应
以上状态完全由价格形成,下面才叠加公开事件,看价格的反应。
2026年3月的冲高跑在改造完成之前;5月改造完成和全年业绩公布,没有阻止回撤;2026年11月6日上半年业绩超过公司指引,开盘80日元、最高81、最低78、收盘78,下跌6.02%,成交973.63万股。上冲猛而短,下行是磨的(4至10月连续七个月回撤)。好消息被当作变现机会,没有成为持有的理由。
时间关系是:价格在3月顶部之前领先,随后跟着交付证据一路向下,现在位于均线下方,等待2027年2月第三季度财报第一次检验下半年的提升。下一个时序问题是价格会提前反应,还是等业绩公布。基本面的交付证据既不用来确认,也不用来改写这个技术状态。
10.6|什么会确认,什么会推翻这个技术判断
判断:这是一个有时长、没有进展的底部,既没有完成,也没有破位。资产覆盖能说明生存,价格结构还没有给出复苏的迹象。
确认需要看到:月线收盘站上99至107日元的均线区并经得起回踩;2026年的低点83日元不再被跌破,且2027年出现更高的低点,这是序列里第一次抬高;利好脉冲的涨幅在下一个月收盘时大部分保住,与2026年3月相反。
推翻(价格被降级)的条件:月线收盘跌破2026年3月期低点69日元,重新打开51至58日元的压力区;又一次放量冲高并被完全吐回;在99至107日元均线区遇到好消息仍被压回,说明上方供给压过了交付。
证据限制:只研究了月线,周线和日线结构没有研究,也没有计算技术指标序列;月线数据未复权且缺少尾段,技术判断把握一般。
11|风险与催化剂
11.1|最大的风险:展期依赖遇上经营落空
短期借款370.71亿日元,现金51.72亿日元。煤价先于售价传导而上涨,或重演2025年3月期那样销售成本高过销售额,会在自有资本被两年亏损削到349亿日元的基础上重新打开亏损。
资金模式的容忍度才是真正的约束条款:如果第三季度显示下半年提升失败,公司要带着更弱的故事、比2026年3月报告的27.5%更薄的自有资本比率回到银行面前。
反证:银行和锚定股东在两个亏损年度里吸收了亏损,没有稀释性融资,行为上的耐心已经被观察到。合同条款没有公开,所以这只是行为证据。
供应商信用是第二层依赖:这次重启部分靠应付账款垫着,条款收紧会直接冲击流动性,与银行的依赖叠加。
11.2|煤价和汇率走在售价前面,是不能对冲的变数
煤价上涨先于焦炭售价调整,会重新打开毛亏(如2025年3月期)并考验银行容忍度。日元走弱和煤价上涨是同一件事。指引使用的煤价和汇率假设以及对冲信息没有披露。
11.3|十年尺度的脱碳压力和短期的被动卖出风险
长期看,脱碳压缩焦炭的终值期限,对下两次财报影响很小。短期看,融资买入偏高使破位时下跌可能被放大,这个读数是2026年7月的,见技术结构一章。
11.4|催化剂都是有日期的交付检验
2027年2月的第三季度财报是第一次检验:下半年提升是否成立,产品库存是否出货。三年经营计划2026年5月承诺公布,至今没有公布,也没有承诺日期;是与第三季度同时公布,还是拖到2027年5月,不知道。2027年5月全年业绩连同2028年3月期分红决定,随后是2027年6月股东大会和有价证券报告书。
触发条件:第三季度焦炭板块利润或毛利率退回2026年3月期水平;经常利润明显低于20亿日元或再出现多十亿日元规模的特别损失;三年计划到5月仍未公布或不含资本政策;短期借款上升而现金下降。任意两条成立,就推翻当前判断;公司一旦兑现这几项,才会重新评估。
12|反常识发现
超出指引的半年被卖,看起来矛盾,拆开却能对上:全年经常利润计划的完成度只有21.9%,隐含的下半年摆动是整个计划里最大的单项假设,加上592亿日元净负债排在股东前面,市场只愿意为部分兑现付钱。这个差距具体且可度量,一个季度的分部数据就能把它向两个方向补上大半。
还有一层来自历史:这家公司的资产在每个阶段都活了下来,被稀释的一直是每股价值。所以复苏的检验不是生存,而是每股能否复利。这两点都是对已有证据的重新排列,不构成新事实;预期是从一次价格反应和二手报道推出的,投机性成交较多时,预期重置也容易过冲。
13|下一次值得跟踪什么
13.1|下半年计划里到底假设了什么煤价、售价和销量?
这是最大的未知:未调整的计划隐含下半年营业利润24.97亿日元、销售额534.93亿日元,上半年经常利润完成度21.9%。如果答案是保守的,计划只是延续;如果是靠煤价或售价上行,计划就是拉伸,答案会把判断拉向两头。目前没有披露,只能靠2027年2月第三季度分部说明,或公司公开的计划假设来解决。
13.2|三年计划什么时候发布,会写进恢复分红的条件吗?
这是第一份关于全周期经济性和分配条件的声明,所以重要。需要知道的包括:发布日期(没有承诺)、是否包含2026年5月推后的资本政策答案、对焦炭全周期销量与利润的承诺,以及是否假设国内粗钢需求企稳还是继续缩小。到2027年5月仍未公布,本身就是推翻条件。解决靠未来的披露。
13.3|两组电池炉满负荷时每吨成本和毛利是多少,第二季度的改善有多少来自销量?
它区分的是持久的成本重置和一个季度的销量效应,决定正常化盈利的关键未知。目前没有每吨数字,需要第三季度和全年的分部披露。
13.4|银行的授信条款、担保和展期立场是什么?
银行耐心决定股权期权的到期时间。需要的证据是有价证券报告书里的授信额度、担保和约定条款披露;370.71亿日元的短期借款对51.72亿日元现金,现在看不到这些,也没有任何来源披露承诺额度、担保或约定条款。结果越差,下行越深。
13.5|产品库存20.93亿日元会不会在第三季度出货?
这是下半年需求侧是否真实的最早物理检验,不需要等利润数字。库存若留在2027年2月的资产负债表上,计划需求就有疑问;库存的成本计价和可变现性也没有单独披露。
13.6|燃料利润下滑会不会稳住,港口物流能增加多少销量?
燃料板块是焦炭之下的盈利底部之一,上半年利润减少6.41亿日元。转型实际增加的销量和现货比例未披露,要看2027年3月期分部说明。
13.7|其余几项:环境费用、机械订单、股东意图、递延税、实际价格
环境准备金40.45亿日元背后的支出进度,以及年度费用还会持续多久,决定债务般的负担、正常化漏损和土地受限程度,要看有价证券报告书的环境附注。
抹茶磨机和机械利润高峰(上半年增70%以上、创成立以来最高)是持久的小众业务还是单周期订单高峰,要靠订单余额披露。
新日本制铁和住友商事是否把合计42%的持股视为永久,复苏停滞时是否支持或阻止增资、资产出售、合并,决定少数股东有哪些下行和上修路径;只能从未来的持股申报或资本动作观察。
递延所得税资产12.92亿日元的回收性,以及44.36亿日元减值是否足够、留用设备的减值测试假设,这一轮没有核查,既没有证据支持,也没有证据排除,要看有价证券报告书的税务和减值附注。
焦炭每吨实际售价没有披露,所以毛利率改善里价格与成本的拆分不能从外部判断。
14|Kabugami 评分卡
14.1|总分40.98/100,评级C,暂不建立仓位
评分版本 V3.2,Kabugami 评分40.98/100,评级 C(40至54.9分档)。八个模块得分合计:4.16+6.72+6.80+5.50+7.80+3.00+3.36+3.64=40.98。
动作:暂不建立仓位,列入重点跟踪。公司的改善有实际证据,但债务排在股东之前、没有分红、价格结构也还没有走出底部,目前的低估值更多是对生存风险的定价,不是安全边际。
接下来按时间验证:2027年2月的第三季度财报是否把第二季度的水平延续到下半年,三年计划是否发布并包含恢复分红的条件,2027年5月的全年业绩和分红决定。若这些都兑现,且短期借款没有重新上升、特别损失没有再出现大块,再重新评估;若第三季度毛利率或焦炭板块利润回到2026年3月期水平,或短期借款上升而现金下降,则把它归入依赖银行的煤炭遗留业务,不再考虑。
14.2|八个模块逐项得分与理由
财务韧性与下行防御 4.16/13:自有资本比率27.2%,短期借款370.71亿日元对现金51.72亿日元,净负债约592亿日元排在股东前面;银行和股东连续展期是行为上的缓冲,不是合同保障,授信与担保条款未公开。
竞争优势与结构耐久性 6.72/14:独立商业焦炭厂有稀缺性,资质和港口保护销量,但不保护价格,需求在缩小;客户结构与供货条款未披露。
盈利质量、现金转化与资本效率 6.80/17:焦炭亏损收窄来自成本和开工率,毛利率回到9.0%,但特别损失和利息吃掉改善,自由现金流接近零,计划兑现后净资产收益率也只有1.4%左右;下半年计划假设和每吨成本未知。
商业结构、产品、客户与关键依赖 5.50/11:客户、供应商同时是股东,保证数量但价格议价有限;工程业务利润率高但订单是否持久不清楚。
估值与安全边际 7.80/15:0.65倍市净率低于土地账面值,但土地是生存缓冲不是变现价值,计划兑现也补不上资本成本;评估价和担保情况未知。
资本配置与股东回报 3.00/10:2025年3月期、2026年3月期分红为零,2027年3月期未定,没有回购和分配框架,现金先还债。
治理、所有权与管理层 3.36/7:两大产业股东控制名册,内部董事为主,薪酬与业绩挂钩;独立性细节和股东真实立场未核查。
Kabugami 技术结构 3.64/13:价格在长期范围最低一成,低于三条均线,年度低点没有抬高,3月冲高被完全吐回;只看了月线,把握一般。
14.3|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 4.16 | 2026年9月末净资产349.22亿日元,自有资本比率27.2%,两年亏损后已明显变薄。短期借款370.71亿日元,现金只有51.72亿日元,净负债约592亿日元,排在股东之前。上半年支付利息6.17亿日元,超过同期经常利润4.38亿日元。主要银行和两大股东在两个亏损年度里持续展期,没有出现稀释性融资,这是实际存在的缓冲,但属于行为上的支持,不是合同上的保障。 |
| 竞争优势与结构耐久性 | 14 | 6.72 | 日本大部分焦炭产能在新日铁和JFE集团内部自用,公司是少数独立的商业焦炭生产商。随着自用炉老化,这种稀缺性会增加价值,但前提是工厂能稳定开工,2025年3月期停工那一年已经证明了这一点。护城河主要是对特定高炉的供货资质和自有港口物流,保护的是销量而不是价格,因为年度谈判仍然只是把煤价滞后地转嫁出去。 |
| 盈利质量、现金转化与资本效率 | 17 | 6.8 | 上半年焦炭板块经营亏损从13.96亿日元缩小到0.05亿日元,第二季度该板块已转为盈利,来自成本和可用性而不是价格或销量。合并毛利率从2025年3月期的-2.1%恢复到2026年3月期7.9%、上半年9.0%。但下面的漏损仍在:2026年3月期经营利润6.07亿日元,却因70.57亿日元的特别损失(含减值44.36亿日元)出现76.78亿日元净亏损;上半年即使恢复,仍有8.45亿日元特别损失,税前亏损1.25亿日元。2026年3月期经营现金流85.11亿日元主要来自折旧60.09亿日元和减值,扣除79.65亿日元固定资产购买后自由现金流约等于零。 |
| 商业结构、产品、客户与关键依赖 | 11 | 5.5 | 主要客户新日铁集团既是持股22.55%的最大股东,也是焦炭主要买家;住友商事持股19.43%,负责煤炭采购和燃料销售。三方联盟涵盖焦炭稳定供应、技术合作和煤炭采购,使公司的需求、原料来源和融资背景都有稳定的对手方。同时工程业务(抹茶磨机、电子部件)与煤炭周期无关,上半年利润9.42亿日元,利润率22.7%。 |
| 估值与安全边际 | 15 | 7.8 | 2026年11月6日收盘78日元,市值约235.83亿日元,市净率0.65倍,低于单看土地账面值333.99亿日元的水平,也低于净资产349.22亿日元。预期市盈率45.4倍没有意义,因为指引净利润只有5亿日元。市场对一个超过中期指引的上半年仍然卖出(当日下跌6.02%),说明价格已经反映的是部分兑现,而不是失败。16年来市净率大致在0.3至1.6倍之间,当前处于中间偏下,压力时期曾低到0.30至0.31倍,约对应36日元。 |
| 资本配置与股东回报 | 10 | 3 | 最近一次实际分红是2024年3月期的8.73亿日元;2025年3月期和2026年3月期都没有分红,2027年3月期未定、中期无分红。库存股占3.7%但没有回购,也没有增资和股东回报框架,公司明确把充实自有资本放在首位。资本配置是银行优先:现金流先偿还和展期债务,亏损由股权承担。 |
| 治理、所有权与管理层 | 7 | 3.36 | 董事会为四名内部董事,设监事会,同一位社长(松冈)经历了亏损年度和设备优化决定;董事报酬8200万日元全部与业绩挂钩,并与利润线保持一致。2026年6月公司澄清,虽然有两大股东,但仍独立决策,没有正式的业务限制。前十大股东合计持股55.06%,新日铁和住友商事的持股在至少四份有价证券报告中没有变化。 |
| Kabugami 技术结构 | 13 | 3.64 | 从2007年的497日元下跌后,股价已经在51至200日元的区间里停留了约十年。目前78至85日元,处在长期价格范围最低的一成附近,低于12个月、24个月和60个月均线,这三条均线聚集在约99至107日元。年度低点没有逐步抬高(2024年84、2025年69、2026年83),说明下跌的旧运动规律还没有被新的规律取代。2026年3月的脉冲冲到153日元,当月成交量超过全部发行股份,但涨幅在七个月内全部收回,属于失败的突破而不是迁移。 |
总分: 40.98 / 100 评级: C 操作建议: 暂不建立仓位,列入重点跟踪。公司的改善有实际证据,但债务排在股东之前、没有分红、价格结构也还没有走出底部,目前的低估值更多是对生存风险的定价,不是安全边际。接下来按时间验证:2027年2月的第三季度财报是否把第二季度的水平延续到下半年,三年计划是否发布并包含恢复分红的条件,2027年5月的全年业绩和分红决定。若这些都兑现,且短期借款没有重新上升、特别损失没有再出现大块,再重新评估;若第三季度毛利率或焦炭板块利润回到2026年3月期水平,或短期借款上升而现金下降,则把它归入依赖银行的煤炭遗留业务,不再考虑。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
研究日期为2026年11月9日;价格与估值数据截至2026年11月6日收盘。主要来源:公司通过 TDnet 披露的2026年3月期业绩(2026年5月15日)和2027年3月期上半年业绩(2026年11月6日);经产省 gBizINFO 转载的 EDINET 有价证券报告书(2026年6月25日提交);EDINET DB 整理的董事报酬与同业中位数;IRBANK 的行情、融资余额和披露索引(2026年11月6日);Kabutan(Minkabu)的上半年解读(2026年11月6日);J-LiC 的股东汇编;JINGI 的机械汇编(2026年11月9日);日文版 Wikipedia 的历史沿革(2026年10月23日);Yahoo Finance 月线镜像(未复权,缺少尾段,使用至2026年10月26日)。
限制:公司英文名依据转载公司章程的二手资料,没有从公司英文投资者资料中直接核对;2026年6月的股东影响澄清来自二手摘要;2027年3月期上半年没有现金流量表,也没有说明资料和说明会;没有分析师一致预期;融资余额读数是2026年7月的;投入资本回报率是第三方机械汇编;估值倍数的各项取值日期不同(见估值一章);2026年3月期下半年的经常亏损由两个来源推算,分别是约6.8亿和6.9亿日元,略有差异。
土地评估价、借款担保与约定条款、联盟商业条款、每吨加工成本、计划煤价假设和订单余额都没有公开,见下一次值得跟踪什么。技术部分只用月线,没有研究周线和日线。
本报告是研究资料,不构成任何投资建议;股价、业绩和信息会随时间变化,读者应自行判断并承担决策风险。
主要资料来源
- FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance
- FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan
- Valuation detail: book value, forecast earnings multiple and market value
- Nippon Coke & Engineering - corporate outline, history and legal English name (articles of incorporation)
- Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)
- Employee data and petroleum/coal-products sector medians from securities-report data
- Compiled securities-report analysis: returns on capital, leverage gap and sales trend
- Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress
- Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance
- Major-shareholder compilation: top-10 concentration and stake stability
- Monthly series for 3315.T, March 2004 to October 2026: span, averages and last close
研究发现索引
展开本次 Review 的 96 项研究发现
F001|01|两组焦炉改造完成后,股东能分到多少
研究范围:开放研究+35项覆盖检查
写入正文:01|两组焦炉改造完成后,股东能分到多少
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接证据;一手验证:35;反向验证:29
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、25、29
FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan怎么使用:直接证据;一手验证:30
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:直接证据;反向验证:31、35
Valuation detail: book value, forecast earnings multiple and market value怎么使用:直接证据;一手验证:27;外部现实校验:21;专项深挖:27
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域30)|FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan;直接证据 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up;直接证据 / 一手证据(研究域27) / 外部现实(研究域21) / 定向深挖(研究域27)|Valuation detail: book value, forecast earnings multiple and market value
完整研究记录(核对用)
研究原文:Does the completed two-battery reconfiguration of the Kitakyushu coke works turn Nippon Coke & Engineering from a loss-making, levered coal legacy into a company that can earn its cost of debt through the cycle, and how much of that normalisation reaches ordinary shareholders who receive no dividend, hold a stock at 0.65x a land-heavy book and rank behind about JPY 59 billion of net debt? The question resolves on delivery evidence (the implied second-half step-up, the February 2027 Q3 print, the promised three-year plan), not on narrative.
内部研究类型:InvestmentQuestion
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Frames the whole case: shareholder outcome is set by whether operating delivery clears interest, leakage and the debt stack, not by asset cover.
不确定性(原始记录):Answer depends on undisclosed plan assumptions and two to three dated disclosures not yet public.
F002|Legal English name per its articles is NIPPON COKE & ENGINEERING COMPANY, LIMITED (日本コークス工業). TSE Prime 3315, listed 10 March 2004 after the IRCJ restructuring; HQ Toyosu, Tokyo; capital JPY 7,000 million; 302,349,449 shares issued of which 11,326,799 are treasury; parent plus eight subsidiaries; Nippon Steel and Sumitomo Corporation are named 'other related companies'. Consolidated group accounts are the only meaningful lens because the parent carries the coke plant and most debt.
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|两种性格不同的生意,共用一张资产负债表15|资料来源、日期与限制
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Nippon Coke & Engineering - corporate outline, history and legal English name (articles of incorporation)怎么使用:直接证据;一手验证:01;同业比较:33;其他用途:历史
Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)怎么使用:直接证据;一手验证:24;外部现实校验:07
FY3/27 interim results release, segment-change note; FY3/26 release group structure怎么使用:直接证据;同业比较:13;其他用途:历史
Business outline from the securities report as republished by gBizINFO怎么使用:直接证据;一手验证:01;专项深挖:01
FY3/26 results release, group structure and segment assignment of group companies怎么使用:直接证据;一手验证:02;专项深挖:02
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 历史/同业比较(研究域33)|Nippon Coke & Engineering - corporate outline, history and legal English name (articles of incorporation);直接证据 / 一手证据(研究域24) / 外部现实(研究域07)|Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI);直接证据 / 历史/同业比较(研究域13)|FY3/27 interim results release, segment-change note; FY3/26 release group structure;直接证据 / 一手证据(研究域01) / 定向深挖(研究域01)|Business outline from the securities report as republished by gBizINFO;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, group structure and segment assignment of group companies
完整研究记录(核对用)
研究原文:Legal English name per its articles is NIPPON COKE & ENGINEERING COMPANY, LIMITED (日本コークス工業). TSE Prime 3315, listed 10 March 2004 after the IRCJ restructuring; HQ Toyosu, Tokyo; capital JPY 7,000 million; 302,349,449 shares issued of which 11,326,799 are treasury; parent plus eight subsidiaries; Nippon Steel and Sumitomo Corporation are named 'other related companies'. Consolidated group accounts are the only meaningful lens because the parent carries the coke plant and most debt.
内部研究类型:CompanyIdentityPerimeter
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Shareholders own a claim on the consolidated recovery, not on one segment; perimeter is now stable so delivery rather than restructuring is the variable.
不确定性(原始记录):English name rests on the articles-level name as republished; outside-director detail and governance-report fine print were not pulled.
F003|02|两种性格不同的生意,共用一张资产负债表
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接 / 支持;一手验证:02
FY3/26 results release, segment review and coke volumes怎么使用:直接证据;同业比较:03、05、15;其他用途:历史
FY3/26 results release, group structure and segment assignment of group companies怎么使用:直接证据;一手验证:02;专项深挖:02
FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders怎么使用:直接证据;一手验证:03;专项深挖:03
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15)|FY3/26 results release, segment review and coke volumes;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, group structure and segment assignment of group companies;直接证据 / 一手证据(研究域03) / 定向深挖(研究域03)|FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders
完整研究记录(核对用)
研究原文:Two different engines share one balance sheet: a commodity conversion spread in coke (FY3/26 sales JPY 56,134 million) whose volume follows steel demand and whose margin follows a price-negotiation lag, and steadier but smaller fuel/resource recycling (JPY 23,343 million), integrated engineering (JPY 7,917 million) and other (JPY 3,991 million) earners. In H1 FY3/27 fuel/recycling plus engineering earned JPY 1,857 million of segment operating profit while coke was at breakeven and unallocated corporate costs absorbed JPY 885 million (about JPY 1.8 billion a year).
内部研究类型:BusinessModelSegmentMix
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Whether the JPY 3.5-4.5 billion non-coke operating profit is a floor under the coke swing or merely a cushion decides earnings quality.
不确定性(原始记录):Segment assets and capital employed are not disclosed, so segment returns on capital cannot be computed.
F004|02|最后一座煤矿关了,留下的是焦炉、港口和遗留负债
研究范围:开放研究+35项覆盖检查
写入正文:02|最后一座煤矿关了,留下的是焦炉、港口和遗留负债
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim results release, segment-change note; FY3/26 release group structure怎么使用:直接 / 支持;同业比较:13;其他用途:历史
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:直接 / 支持;一手验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域13)|FY3/27 interim results release, segment-change note; FY3/26 release group structure;直接证据 / 支持证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed
完整研究记录(核对用)
研究原文:With Sanmi Mining's exit in H1 FY3/27 the group no longer mines coal anywhere. What remains of the Mitsui Mining inheritance is the coke plant, the fuel logistics built around it, the machinery business and the legacy provisions; Sanmi's segment was moved from fuel/recycling to 'other'.
内部研究类型:PerimeterChange
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Removes extraction risk but leaves the legacy environmental provision as a debt-like residue.
不确定性(原始记录):Financial effect of the exit is not separately disclosed.
F005|03|综合工程利润率最高,但订单能否持续还不清楚
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, qualitative review of integrated engineering怎么使用:直接 / 支持;一手验证:03
FY3/26 results release, group structure and segment assignment of group companies怎么使用:直接证据;一手验证:02;专项深挖:02
FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders怎么使用:直接 / 支持;一手验证:03;专项深挖:03
Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan怎么使用:直接证据;一手验证:28;专项深挖:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域03)|FY3/27 interim results release, qualitative review of integrated engineering;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, group structure and segment assignment of group companies;直接证据 / 支持证据 / 一手证据(研究域03) / 定向深挖(研究域03)|FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders;直接证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan
完整研究记录(核对用)
研究原文:Integrated engineering is the group's most profitable business per unit of sales: H1 FY3/27 operating profit JPY 942 million on external sales JPY 4,154 million (22.7% margin on external sales), with the machinery unit at a record profit since founding (up more than 70%), driven by Tea Meister Mill orders for matcha production and an AI-related recovery in electronic-component orders. Segment profit was JPY 1,477 million in FY3/26 and about JPY 2,072 million (derived) in FY3/25; the segment is about 8% of sales. End demand is the matcha boom and electronic-materials producers, unrelated to the coal cycle. Subsidiary Ariake Kiden Kogyo sits in this segment.
内部研究类型:SegmentNicheBusiness
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A genuine non-coal profit source, but too small to replace the coke swing.
不确定性(原始记录):No order backlog or product-level split is disclosed; durability of the niche versus a one-cycle order bulge is unresolved (see Research Debt).
F006|03|燃料业务销量在缩,港口物流能补多少没有数字
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim results release, qualitative review of fuel and resource recycling怎么使用:直接 / 支持;一手验证:15;反向验证:10
FY3/26 results release, group structure and segment assignment of group companies怎么使用:直接证据;一手验证:02;专项深挖:02
FY3/26 results release, coke demand: inquiries and sales-volume growth怎么使用:直接 / 支持;一手验证:05;专项深挖:05;同业比较:11;其他用途:历史
FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption怎么使用:直接证据;一手验证:10;专项深挖:10
FY3/27 interim release: revenue-quality colour in the fuel segment怎么使用:直接证据;一手验证:15;专项深挖:15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 反证(研究域10)|FY3/27 interim results release, qualitative review of fuel and resource recycling;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, group structure and segment assignment of group companies;直接证据 / 支持证据 / 一手证据(研究域05) / 历史/同业比较(研究域11) / 定向深挖(研究域05)|FY3/26 results release, coke demand: inquiries and sales-volume growth;直接证据 / 一手证据(研究域10) / 定向深挖(研究域10)|FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption;直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|FY3/27 interim release: revenue-quality colour in the fuel segment
完整研究记录(核对用)
研究原文:Fuel and resource recycling is in managed decline at the volume line: fuel sales volume fell to 820 thousand tonnes in FY3/26 (-45kt) as customers convert away from coal, and H1 FY3/27 segment profit fell JPY 641 million to JPY 915 million as a customer's business conversion cut volumes and prior-year spot deals lapsed (FY3/26 segment operating profit JPY 2,630 million). Management's response is to leverage the private port and call-centre operation, use yard space freed by the coke optimisation and consider strengthening energy-logistics capability; the port proved its value by covering regional fuel-distribution disruption. Subsidiary Miike Port Logistics supports the port infrastructure.
内部研究类型:SegmentManagedDecline
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A shrinking contributor to the floor under coke; its stabilisation affects normalised earnings.
不确定性(原始记录):Volume actually added by the logistics pivot, and the spot versus recurring split, are undisclosed.
F007|04|焦炭需求在缩小,公司靠开工率在缩小的池子里拿份额
研究范围:开放研究+35项覆盖检查
写入正文:04|焦炭需求在缩小,公司靠开工率在缩小的池子里拿份额05|护城河保护销量,不保护价格14|八个模块逐项得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
FY3/26 results release, segment review and coke volumes怎么使用:直接证据;同业比较:03、05、15;其他用途:历史
Employee data and petroleum/coal-products sector medians from securities-report data怎么使用:直接证据;外部现实校验:03、08
FY3/26 results release, coke demand: inquiries and sales-volume growth怎么使用:直接证据;一手验证:05;专项深挖:05;同业比较:11;其他用途:历史
Petroleum and coal products sector panel: seven-company medians versus the company怎么使用:直接证据;一手验证:08;外部现实校验:09、22;专项深挖:08
Compiled securities-report analysis: returns on capital, leverage gap and sales trend怎么使用:直接证据;一手验证:09、22;外部现实校验:02、18;专项深挖:09
FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption怎么使用:直接证据;一手验证:10;专项深挖:10
FY3/26 results release, outlook: risk framing for FY3/27怎么使用:直接证据;一手验证:11;外部现实校验:14;专项深挖:11
FY3/26 results release, group description: the customer and procurement counterparties怎么使用:直接证据;一手验证:05
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15)|FY3/26 results release, segment review and coke volumes;直接证据 / 外部现实(研究域03) / 外部现实(研究域08)|Employee data and petroleum/coal-products sector medians from securities-report data;直接证据 / 一手证据(研究域05) / 历史/同业比较(研究域11) / 定向深挖(研究域05)|FY3/26 results release, coke demand: inquiries and sales-volume growth;直接证据 / 一手证据(研究域08) / 外部现实(研究域09) / 外部现实(研究域22) / 定向深挖(研究域08)|Petroleum and coal products sector panel: seven-company medians versus the company;直接证据 / 一手证据(研究域09) / 一手证据(研究域22) / 外部现实(研究域02) / 外部现实(研究域18) / 定向深挖(研究域09)|Compiled securities-report analysis: returns on capital, leverage gap and sales trend;直接证据 / 一手证据(研究域10) / 定向深挖(研究域10)|FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption;直接证据 / 一手证据(研究域11) / 外部现实(研究域14) / 定向深挖(研究域11)|FY3/26 results release, outlook: risk framing for FY3/27;直接证据 / 一手证据(研究域05)|FY3/26 results release, group description: the customer and procurement counterparties
完整研究记录(核对用)
研究原文:Coke demand is a derived, shrinking flow tied to domestic crude-steel output; FY3/26 sales volume still rose 100kt to 972kt because the plant could finally run, i.e. share and availability inside a draining pond. The company is one of Japan's few independent merchant coke producers; most capacity is captive inside the Nippon Steel and JFE groups, and hydrogen/electric steelmaking substitutes on a decade clock. Its position is a scarcity rent that rises as captive ovens age but only for a plant that runs (the FY3/25 stoppage year shows the collapse when it does not); its moat is qualification into specific blast furnaces plus port logistics, which protects volume more than price because annual negotiations still pass coal costs through with a lag.
内部研究类型:IndustryPositionMoat
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Underwrite flat-to-declining volume; the equity is a share of a shrinking merchant pool with improving availability, which caps the multiple recovery can earn.
不确定性(原始记录):Customer split between Nippon Steel group and others, supply-contract terms, delivered-cost comparison with captive ovens and the scarcity claim itself are unquantified; the three-year plan's demand assumption is not published.
F008|01|上半年超出指引,全年计划却一点没动
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|上半年超出指引,全年计划却一点没动03|焦炉改造把利润变化压缩进了一个季度
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接 / 支持;一手验证:02
FY3/27 interim results release, qualitative review of the coke business怎么使用:直接 / 支持;一手验证:04
FY3/26 results release, management narrative on the November 2025 production-system optimisation decision怎么使用:直接证据;一手验证:12、20、33;同业比较:04;其他用途:历史
FY3/27 interim release, operating-technology change: preventive maintenance and resource reallocation怎么使用:直接证据;一手验证:04、10;专项深挖:04
FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution怎么使用:直接证据;一手验证:12
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 支持证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;直接证据 / 一手证据(研究域12) / 一手证据(研究域20) / 一手证据(研究域33) / 历史/同业比较(研究域04)|FY3/26 results release, management narrative on the November 2025 production-system optimisation decision;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04)|FY3/27 interim release, operating-technology change: preventive maintenance and resource reallocation;直接证据 / 一手证据(研究域12)|FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution
完整研究记录(核对用)
研究原文:The turnaround mechanism is visible in one clean quarter. The Kitakyushu optimisation completed about a month ahead of plan; since May 2026 the plant runs on two sound battery groups including the new 2A battery. In July-September 2026 production rose more than 20% versus April-June, per-tonne conversion cost including repair and depreciation fell sharply, oven operating troubles dropped substantially and the coke segment turned profitable in the quarter; the H1 coke operating loss narrowed to JPY 5 million from JPY 1,396 million on sales down 4.4%, so the half-level gain is a cost and availability effect, not price or volume. This extends the FY3/26 narrowing of the coke loss from JPY 12,357 million to JPY 2,328 million through repair-cost cuts and fixed-cost dilution. Management is shifting to preventive maintenance.
内部研究类型:TurnaroundMechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):If availability and unit cost hold, the technology question disappears into the cost line; if troubles return the whole recovery loses its mechanism.
不确定性(原始记录):Per-tonne conversion cost and volume-versus-price attribution are undisclosed; battery age profile and remaining life are unknown; only one quarter of evidence.
F009|06|毛利率分三步修复,修复来自成本不是售价
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:02
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接证据;一手验证:16;同业比较:06、12、16、28;其他用途:历史
FY3/26 results release, income statement: gross-profit repair怎么使用:直接 / 支持;一手验证:16;专项深挖:16
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/26 results release, income statement: gross-profit repair
完整研究记录(核对用)
研究原文:Gross margin has repaired in steps: -2.1% in FY3/25 (cost of sales exceeded sales), 7.9% in FY3/26 and 9.0% in H1 FY3/27, each step driven by volume recovery, repair-cost reduction and fixed-cost dilution rather than revenue growth. Operating margin was 0.7% in FY3/26 and 2.3% in H1 FY3/27.
内部研究类型:MarginRepair
内部来源标记:COVERAGE35
普通股东含义(原始记录):Improvement is in the right place (the gross line where plant physics live) but remains thin against interest and below-the-line leakage.
不确定性(原始记录):How much of the Q2 gross margin was price revision versus cost is undisclosed; margin persistence assumes availability holds.
F010|01|上半年超出指引,全年计划却一点没动
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|上半年超出指引,全年计划却一点没动06|下半年的利润要靠第二季度的水平再撑六个月11|催化剂都是有日期的交付检验
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接 / 支持;一手验证:35;反向验证:29
Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress怎么使用:直接 / 支持;一手验证:31;外部现实校验:05、15、30
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:直接 / 支持;反向验证:31、35
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接证据;一手验证:28、35;专项深挖:35
查看完整证据标签(核对用)
直接证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域05) / 外部现实(研究域15) / 外部现实(研究域30)|Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up;直接证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results
完整研究记录(核对用)
研究原文:The FY3/27 plan is a second-half promise. H1 operating profit of JPY 1,103 million beat the company's interim guidance of JPY 800 million (and every other guided line), yet the full-year plan was left unchanged at sales JPY 101,600 million, operating profit JPY 3,600 million, ordinary profit JPY 2,000 million, net income JPY 500 million (EPS JPY 1.72). It therefore needs JPY 2,497 million of operating profit, JPY 1,562 million of ordinary profit and JPY 53,493 million of sales in H2 (about 28% sales growth on H2 FY3/26, which delivered operating profit of only about JPY 90 million and an ordinary loss of roughly JPY 0.68-0.69 billion). H1 ordinary profit was a 21.9% progress rate. Q2 standalone ordinary profit was JPY 1,070 million (operating margin 4.9%), so the H2 target needs roughly Q2's run-rate held for six months rather than acceleration. The H1 beat proves direction, not magnitude; no results briefing or supplementary materials accompanied the releases.
内部研究类型:PlanBridgeContradiction
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The next two prints test whether one good quarter is a run-rate; the bulk of the planned profit is still unearned.
不确定性(原始记录):Embedded coal price, selling price and volume assumptions are undisclosed; the two sources differ slightly on the derived H2 FY3/26 ordinary loss (0.68 vs 0.69 billion).
F011|06|毛利率分三步修复,修复来自成本不是售价
研究范围:35项覆盖检查
写入正文:06|毛利率分三步修复,修复来自成本不是售价13|其余几项:环境费用、机械订单、股东意图、递延税、实际价格
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, qualitative review of fuel and resource recycling怎么使用:直接证据;一手验证:15;反向验证:10
FY3/26 results release, coke demand: inquiries and sales-volume growth怎么使用:直接证据;一手验证:05;专项深挖:05;同业比较:11;其他用途:历史
FY3/26 results release: production recovery through disruption怎么使用:直接证据;一手验证:12;专项深挖:12
FY3/27 interim release: revenue-quality colour in the fuel segment怎么使用:直接证据;一手验证:15;专项深挖:15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域15) / 反证(研究域10)|FY3/27 interim results release, qualitative review of fuel and resource recycling;直接证据 / 一手证据(研究域05) / 历史/同业比较(研究域11) / 定向深挖(研究域05)|FY3/26 results release, coke demand: inquiries and sales-volume growth;直接证据 / 一手证据(研究域12) / 定向深挖(研究域12)|FY3/26 results release: production recovery through disruption;直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|FY3/27 interim release: revenue-quality colour in the fuel segment
完整研究记录(核对用)
研究原文:Revenue is volume-honest but price-opaque: tonnes are disclosed for coke and fuel while realised coke price per tonne is not. Group H1 sales fell 3.2% despite the plant recovery because coke's first quarter was still transitional and fuel lost spot and converted volumes. Production and tonnes lead the yen figures by about a quarter, so the Q2 volume print matters more than the H1 sales line.
内部研究类型:RevenueQuality
内部来源标记:COVERAGE35
普通股东含义(原始记录):Judge recovery on tonnes and segment profit, not the consolidated sales line.
不确定性(原始记录):Realised price per tonne and the spot/recurring split in fuel are undisclosed.
F012|06|经营现金流多半来自折旧和减值,自由现金流接近零
研究范围:开放研究+35项覆盖检查
写入正文:06|经营现金流多半来自折旧和减值,自由现金流接近零
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接证据;一手验证:17;同业比较:17、25;其他用途:历史
FY3/26 results release, cash-flow detail: what the operating cash flow is made of怎么使用:直接 / 支持;一手验证:17;专项深挖:17
FY3/26 results release: investment scale behind the reconfiguration怎么使用:直接 / 支持;一手验证:20;专项深挖:20
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|FY3/26 results release, cash-flow detail: what the operating cash flow is made of;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|FY3/26 results release: investment scale behind the reconfiguration
完整研究记录(核对用)
研究原文:FY3/26 operating cash flow of JPY 8,511 million was mostly non-cash in origin - depreciation JPY 6,009 million and impairment JPY 4,436 million, helped by a JPY 3,023 million receivables decrease against a JPY 1,486 million inventory increase - and after JPY 7,965 million of fixed-asset purchases (investing outflow JPY 8,684 million) free cash flow was approximately zero; cash ended at JPY 6,388 million. Construction in progress fell JPY 2,573 million (Mar 2025) to JPY 1,681 million to JPY 1,183 million (Sep 2026), marking the passage from construction to harvest; depreciation of about JPY 6.0 billion a year on an old asset base flatters conversion. FY3/25 operating cash flow was negative.
内部研究类型:CashConversionCapex
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):With optimisation capex complete, the run-rate should tilt positive if operating profit delivers; that tilt decides whether depreciation funds debt reduction or dividends.
不确定性(原始记录):The interim release has no cash-flow statement, so H1 FY3/27 operating cash flow is unobservable; maintenance capex to sustain two batteries is undisclosed.
F013|06|重启靠供应商的信用垫着,产品库存要在第三季度出货
研究范围:35项覆盖检查
写入正文:06|重启靠供应商的信用垫着,产品库存要在第三季度出货
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/27 interim release, financial-position narrative: working-capital movements怎么使用:直接 / 支持;一手验证:19;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/27 interim release, financial-position narrative: working-capital movements
完整研究记录(核对用)
研究原文:In H1 FY3/27 receivables rose JPY 2,387 million and products inventory JPY 2,093 million (consistent with Q2 production ahead of H2 shipments), but the build was funded mainly by a JPY 6,708 million rise in payables; cash fell JPY 1,219 million and long-term borrowings were repaid JPY 2,040 million. The restart is being financed substantially by supplier credit, efficient while suppliers cooperate and fragile if terms tighten.
内部研究类型:WorkingCapitalFunding
内部来源标记:COVERAGE35
普通股东含义(原始记录):The Q3 inventory and payables lines are an early, free truth-teller about H2 delivery.
不确定性(原始记录):Payables terms and any supply-chain financing are undisclosed; no interim cash-flow statement confirms the cash effect.
F014|06|下半年的利润要靠第二季度的水平再撑六个月
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、25、29
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据|FY3/27 interim (H1) consolidated results release, headline results
完整研究记录(核对用)
研究原文:Interest consumes the recovery at its current scale: H1 interest paid of JPY 617 million exceeded H1 ordinary profit of JPY 438 million, so about JPY 1.2 billion a year of interest must be cleared before ordinary profit exists; the equity needs the full plan, not a partial one, before ordinary profit is meaningfully positive.
内部研究类型:FixedClaimBurden
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Interest is a senior fixed claim; operating shortfall translates into magnified ordinary-profit shortfall.
不确定性(原始记录):Interest rate and facility terms are undisclosed; annualisation is straight-line from one half.
F015|06|资产负债表是最紧的约束,银行条款一概未公开
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|资产负债表是最紧的约束,银行条款一概未公开14|八个模块逐项得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接证据;一手验证:17;同业比较:17、25;其他用途:历史
FY3/26 results release: stakeholder support obtained for the optimisation plan怎么使用:直接证据;一手验证:07;外部现实校验:25;专项深挖:07
FY3/27 interim balance sheet: asset composition怎么使用:直接证据;一手验证:18;专项深挖:18
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接 / 支持;一手验证:25;专项深挖:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 一手证据(研究域07) / 外部现实(研究域25) / 定向深挖(研究域07)|FY3/26 results release: stakeholder support obtained for the optimisation plan;直接证据 / 一手证据(研究域18) / 定向深挖(研究域18)|FY3/27 interim balance sheet: asset composition;直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn
完整研究记录(核对用)
研究原文:The balance sheet is the binding constraint. At 30 September 2026: total assets JPY 128,499 million, net assets JPY 34,922 million (equity ratio 27.2%, down from 44.5% in FY3/22), short-term borrowings JPY 37,071 million and long-term JPY 27,350 million (gross JPY 64,421 million) against cash JPY 5,172 million (net debt about JPY 59 billion), plus a JPY 4,045 million environmental provision and JPY 2,546 million of retirement liabilities; interim interest paid JPY 617 million exceeded ordinary profit JPY 438 million. Funding is a rollover model: FY3/26 short-term borrowing proceeds of JPY 317,557 million and repayments of JPY 309,713 million, roughly five times the year-end short-term balance, with lender banks whose understanding the company publicly recorded in FY3/26. Indicators: interest coverage 9.7x and debt/operating cash flow 7.9 years in FY3/26.
内部研究类型:BalanceSheetFundingModel
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operating variance is transformed into magnified equity variance; first claim on improvement is the debt stack, and equity moves last and fastest.
不确定性(原始记录):Facility terms, commitments, collateral (including whether borrowings are secured on land) and covenants are undisclosed.
F016|11|最大的风险:展期依赖遇上经营落空
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论11|最大的风险:展期依赖遇上经营落空
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接 / 支持;一手验证:16;同业比较:06、12、16、28;其他用途:历史
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接 / 支持;一手验证:17;同业比较:17、25;其他用途:历史
FY3/26 results release: stakeholder support obtained for the optimisation plan怎么使用:直接 / 支持;一手验证:07;外部现实校验:25;专项深挖:07
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接 / 支持;一手验证:25;专项深挖:25
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:一手验证:35;反向验证:29;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域25) / 定向深挖(研究域07)|FY3/26 results release: stakeholder support obtained for the optimisation plan;直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn;反证 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance
完整研究记录(核对用)
研究原文:Refinancing dependence is structural: JPY 37,071 million of short-term borrowings against JPY 5,172 million of cash. A coking-coal spike arriving before selling-price pass-through, or a repeat of the FY3/25 pattern with cost of sales above sales, would reopen losses against an equity base two loss years have already cut to JPY 34.9 billion. The funding model's tolerance is the true covenant: if the Q3 print shows the second-half step-up failing, the company returns to its lenders with a weaker story and a thinner equity ratio than the 27.5% reported in March 2026.
内部研究类型:RefinancingRisk
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):A disappointment can force a recapitalisation-type outcome against an already thin equity.
不确定性(原始记录):Lenders' actual stance is behavioural evidence only (rolled through two loss years); contractual terms are not public. Counter-evidence: lenders and anchors did absorb two loss years without a dilutive event.
F017|03|煤价与焦炭售价之间的时滞,才是利润的真变量
研究范围:开放研究+35项覆盖检查
写入正文:03|煤价与焦炭售价之间的时滞,才是利润的真变量11|煤价和汇率走在售价前面,是不能对冲的变数14|八个模块逐项得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接证据;一手验证:16;同业比较:06、12、16、28;其他用途:历史
Procurement dependence: imported coal at the centre of the business outline怎么使用:直接证据;一手验证:06;专项深挖:06
FY3/26 results release, outlook: risk framing for FY3/27怎么使用:直接证据;一手验证:11;外部现实校验:14;专项深挖:11
FY3/27 interim release, management's macro framing怎么使用:直接证据;一手验证:14;外部现实校验:06、11、12;专项深挖:14
FY3/26 results release, income statement: gross-profit repair怎么使用:直接证据;一手验证:16;专项深挖:16
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 一手证据(研究域06) / 定向深挖(研究域06)|Procurement dependence: imported coal at the centre of the business outline;直接证据 / 一手证据(研究域11) / 外部现实(研究域14) / 定向深挖(研究域11)|FY3/26 results release, outlook: risk framing for FY3/27;直接证据 / 一手证据(研究域14) / 外部现实(研究域06) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域14)|FY3/27 interim release, management's macro framing;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/26 results release, income statement: gross-profit repair
完整研究记录(核对用)
研究原文:Imported coking coal is the dominant input, priced in dollars in the seaborne market, while coke prices are negotiated in yen with a lag; this mismatch is the margin mechanism and macro reaches the P&L through this one pipe (a weak yen and a coal spike are the same event). Two cycles are superimposed: plant availability (company-controlled, now rising) and the commodity spread (externally set). The FY3/25 gross loss is the extreme print of the lag. Raw-material inventory of JPY 16,052 million shows the pipeline's scale; Sumitomo Corporation is an alliance procurement partner.
内部研究类型:CommoditySpreadMechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Unhedged commodity-spread risk in both directions: with the controllable cycle done, the uncontrollable one dominates the variance of earnings.
不确定性(原始记录):Coal and FX assumptions in guidance, procurement terms and any hedging are undisclosed; the coal price assumption in H2 guidance is the largest unknown in the plan.
F018|06|每次经营改善都被特别损失吃掉一块
研究范围:开放研究+35项覆盖检查
写入正文:06|每次经营改善都被特别损失吃掉一块14|八个模块逐项得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接 / 支持;一手验证:16;同业比较:06、12、16、28;其他用途:历史
FY3/26 results release, special losses and narrative on the optimisation and fire怎么使用:直接 / 支持;一手验证:32;同业比较:20;其他用途:历史
FY3/27 interim income statement: the special-items block inside a 'clean' half怎么使用:直接证据;一手验证:32;反向验证:16;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域20)|FY3/26 results release, special losses and narrative on the optimisation and fire;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 定向深挖(研究域32)|FY3/27 interim income statement: the special-items block inside a 'clean' half
完整研究记录(核对用)
研究原文:FY3/26 closed with a net loss of JPY 7,678 million despite operating profit of JPY 607 million because special losses of JPY 7,057 million (impairment JPY 4,436 million on idled coke assets, disposal losses JPY 1,094 million, disaster loss JPY 580 million from the December 2025 conveyor fire) were charged below the operating line. Even the H1 FY3/27 recovery half booked special income of JPY 281 million (settlement JPY 215 million, asset-sale gains JPY 61 million) against special losses of JPY 845 million, dominated by JPY 725 million of disposal losses, leaving a pre-tax loss of JPY 125 million and net loss of JPY 131 million. Special items recur every period; no accounting-policy change or restatement was reported.
内部研究类型:RecurringLeakage
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operating improvement is repeatedly converted into net losses; judge management on ordinary profit and cash flow, and treat net income here as lagging and noisy.
不确定性(原始记录):The disposal-loss stream should shrink as the idled-asset programme completes, but the full-year FY3/27 total and impairment-test assumptions for the retained plant were not reviewed.
F019|06|每次经营改善都被特别损失吃掉一块
研究范围:开放研究+35项覆盖检查
写入正文:06|每次经营改善都被特别损失吃掉一块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接 / 支持;一手验证:13;同业比较:32;其他用途:历史
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:直接 / 支持;一手验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;直接证据 / 支持证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed
完整研究记录(核对用)
研究原文:The environmental-countermeasure provision stood unchanged at JPY 4,045 million at March and September 2026, with annual non-operating charges of JPY 711 million (FY3/25) and JPY 332 million (FY3/26): a slow legacy bleed from former mining and industrial sites that is independent of the coke cycle and debt-like in nature.
内部研究类型:LegacyObligation
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Reduces normalised earnings power and partially encumbers the asset base.
不确定性(原始记录):Spending schedule by site and remaining charge run-rate are undisclosed.
F020|09|脱碳是终值问题,不是未来两次财报的问题
研究范围:35项覆盖检查
写入正文:09|脱碳是终值问题,不是未来两次财报的问题11|十年尺度的脱碳压力和短期的被动卖出风险
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接证据;一手验证:13;同业比较:32;其他用途:历史
Petroleum and coal products sector panel: seven-company medians versus the company怎么使用:直接证据;一手验证:08;外部现实校验:09、22;专项深挖:08
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:直接证据;一手验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;直接证据 / 一手证据(研究域08) / 外部现实(研究域09) / 外部现实(研究域22) / 定向深挖(研究域08)|Petroleum and coal products sector panel: seven-company medians versus the company;直接证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed
完整研究记录(核对用)
研究原文:Decarbonisation of blast-furnace steelmaking is the long-horizon constraint on the coke segment's licence to operate; policy cost already enters the numbers as a slow environmental bleed (near-term cash effect small) while the strategic deadline operates on the demand side over a decade (terminal-value effect large). Hydrogen-based and electric steelmaking substitute away from coke altogether.
内部研究类型:PolicyHorizon
内部来源标记:COVERAGE35
普通股东含义(原始记录):Argues for cash extraction sooner rather than later and a finite terminal horizon for the coke segment.
不确定性(原始记录):No GX/carbon-cost pricing that names coke was reviewed; carbon-cost pass-through mechanism undisclosed.
F021|08|两年亏损耗掉近一半留存收益,分红随盈利一起消失
研究范围:开放研究+35项覆盖检查
写入正文:08|两年亏损耗掉近一半留存收益,分红随盈利一起消失
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接证据;一手验证:17;同业比较:17、25;其他用途:历史
FY3/26 results release, dividend record and profit-distribution policy怎么使用:直接 / 支持;一手验证:26
FY3/26 results release, statement of changes in equity and retained-earnings path怎么使用:直接证据;同业比较:02、18、22、26;其他用途:历史
FY3/26 results release, statement of changes in equity: the last dividend actually paid怎么使用:直接 / 支持;一手验证:26;专项深挖:26
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 支持证据 / 一手证据(研究域26)|FY3/26 results release, dividend record and profit-distribution policy;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|FY3/26 results release, statement of changes in equity and retained-earnings path;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|FY3/26 results release, statement of changes in equity: the last dividend actually paid
完整研究记录(核对用)
研究原文:Retained earnings fell from JPY 48,551 million (April 2024) to JPY 33,769 million (March 2025), JPY 26,090 million (March 2026) and JPY 25,959 million (September 2026): two loss years consumed about 46% of the buffer and cut the equity ratio from 40.0% to 27.5%. The last dividend actually paid was JPY 873 million for FY3/24, paid in FY3/25; FY3/25 and FY3/26 dividends were zero, FY3/27 is undetermined with no interim dividend, treasury shares of 3.7% sit unused and no buyback exists. Equity repair, not distribution, is the stated priority; the dividend record tracks the earnings record exactly, so the May 2027 dividend decision is a clean dated management signal.
内部研究类型:EquityRepairNoReturn
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Shareholders currently receive nothing; the entire return path is price recovery on delivery evidence.
不确定性(原始记录):No DOE or payout framework exists; the dividend is discretionary and its timing unknown.
F022|01|两组焦炉改造完成后,股东能分到多少
研究范围:开放研究
写入正文:01|两组焦炉改造完成后,股东能分到多少09|杠杆放大了估值后果
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 results release, special losses and narrative on the optimisation and fire怎么使用:直接 / 支持;一手验证:32;同业比较:20;其他用途:历史
Market snapshot and margin-trading data for 3315怎么使用:直接证据;一手验证:27;外部现实校验:01、24、31
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接 / 支持;一手验证:13;同业比较:32;其他用途:历史
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:一手验证:16;同业比较:06、12、16、28;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域20)|FY3/26 results release, special losses and narrative on the optimisation and fire;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 支持证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;反证 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison
完整研究记录(核对用)
研究原文:The equity is a levered claim on coke-margin normalisation rather than on the asset base: interest runs at roughly JPY 1.2 billion a year, 'one-off' disposal and environmental charges recur, and net debt of about JPY 59 billion sits against a JPY 23.6 billion market value, so a coke operating swing of a few billion yen decides whether net results are positive at all.
内部研究类型:EquityStructureInference
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):A JPY 3 billion operating swing is minor for lenders and decisive for shareholders.
不确定性(原始记录):Inference; counter-evidence is that the below-the-line stream may shrink as the idled-asset programme completes.
F023|09|土地账面值高于市值,但它是生存缓冲,不是变现价值
研究范围:开放研究+35项覆盖检查
写入正文:09|土地账面值高于市值,但它是生存缓冲,不是变现价值14|八个模块逐项得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、25、29
FY3/27 interim balance sheet: asset composition怎么使用:直接证据;一手验证:18;专项深挖:18
FY3/27 interim balance sheet: land and securities relative to equity怎么使用:直接 / 支持;一手验证:21;专项深挖:21
Valuation detail: book value, forecast earnings multiple and market value怎么使用:直接 / 支持;一手验证:27;外部现实校验:21;专项深挖:27
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域18) / 定向深挖(研究域18)|FY3/27 interim balance sheet: asset composition;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21)|FY3/27 interim balance sheet: land and securities relative to equity;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域21) / 定向深挖(研究域27)|Valuation detail: book value, forecast earnings multiple and market value
完整研究记录(核对用)
研究原文:Land is carried at JPY 33,399 million, 96% of net assets of JPY 34,922 million, so the market value of the company (JPY 23,583 million) is below the book value of its land alone; investment securities are JPY 2,166 million with a JPY 1,065 million unrealised-gain reserve, and small disposals (asset-sale gains, a settlement receipt) act as a funding adjunct. The valuation is a going-concern and governance judgment rather than an asset appraisal: the market pays for survival and delivery and would reprice the same assets quickly if the plan lands or the funding model cracks.
内部研究类型:HiddenAssetGoingConcernDiscount
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Land is survival cover and downside context, not the upside thesis or a realisable-value claim.
不确定性(原始记录):Land is at historical cost; no appraisal, encumbrance, collateral or site-remediation attachment is disclosed, so book is not realisable value.
F024|09|下行是缓慢拖长,不是快速塌陷
研究范围:35项覆盖检查
写入正文:09|下行是缓慢拖长,不是快速塌陷
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、25、29
Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26怎么使用:直接证据;外部现实校验:27、29
Historical downside prints: PBR at the 2020-2021 lows怎么使用:直接证据;一手验证:29;专项深挖:29;同业比较:27;其他用途:历史
Corporate turning points: IRCJ restructuring, 2009 renaming, exit from the Mitsui group怎么使用:直接证据;一手验证:33;专项深挖:33;同业比较:01、09、29;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 外部现实(研究域27) / 外部现实(研究域29)|Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26;直接证据 / 一手证据(研究域29) / 历史/同业比较(研究域27) / 定向深挖(研究域29)|Historical downside prints: PBR at the 2020-2021 lows;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域29) / 定向深挖(研究域33)|Corporate turning points: IRCJ restructuring, 2009 renaming, exit from the Mitsui group
完整研究记录(核对用)
研究原文:Downside is cushioned but not floored. Protection: land at JPY 33,399 million book and a lender/anchor structure that absorbed two loss years without a dilutive event. Non-protection: net debt of about JPY 59 billion senior to equity, equity ratio down to 27.2%, and demonstrated stress pricing of 0.30-0.31x book (JPY 51-52 in 2020-2021), about JPY 36 on current book value per share of roughly JPY 120. The anchors that prevent collapse also prevent quick recapitalisation, so the realistic bad path is a long drift at 0.3-0.5x book while losses consume the buffer, as in 2016-2020 when the shares spent years between JPY 58 and JPY 138. Protection is behavioural, not contractual.
内部研究类型:DownsideProtection
内部来源标记:COVERAGE35
普通股东含义(原始记录):A loss case of roughly a halving from JPY 78, realised slowly; protection rests on counterparties continuing to behave as they have.
不确定性(原始记录):Collateral and security over land and plant are undisclosed; liquidation value was not estimated.
F025|09|价格在为生存定价:资产说便宜,盈利说无物可估
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|价格在为生存定价:资产说便宜,盈利说无物可估14|总分40.98/100,评级C,暂不建立仓位15|资料来源、日期与限制
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接 / 支持;一手验证:35;反向验证:29
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接 / 支持;一手验证:16;同业比较:06、12、16、28;其他用途:历史
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接 / 支持;一手验证:17;同业比较:17、25;其他用途:历史
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26怎么使用:直接证据;外部现实校验:27、29
Valuation detail: book value, forecast earnings multiple and market value怎么使用:直接 / 支持;一手验证:27;外部现实校验:21;专项深挖:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 外部现实(研究域27) / 外部现实(研究域29)|Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域21) / 定向深挖(研究域27)|Valuation detail: book value, forecast earnings multiple and market value
完整研究记录(核对用)
研究原文:Valuation snapshot (close 6 November 2026, research cut-off 9 November): price JPY 78; market capitalisation JPY 23.58 billion (JPY 78 x 302,349,449 issued shares); forecast PER 45.4x on FY3/27 company EPS JPY 1.72 (an arithmetically correct but economically empty multiple on rounding-level guided net income of JPY 500 million); actual PBR 0.65x on net assets per share JPY 119.57 at FY3/26 year-end (about JPY 120 at September 2026); FY3/26 ROE -20.1% (net-loss year); forecast dividend yield not applicable (FY3/27 dividend undetermined, FY3/26 dividend zero); EV/EBITDA 12.5x (EV JPY 82.83 billion = market cap plus net debt JPY 59.25 billion at 30 September 2026 (short-term 37,071 + long-term 27,350 - cash 5,172); EBITDA JPY 6.62 billion = FY3/26 operating profit 607 + depreciation 6,009). Sixteen-year PBR range at fiscal highs/lows is roughly 0.3x-1.6x (1.28x at the FY3/26 high print). Asset anchors say the option is cheap; earnings anchors say there is nothing to capitalise yet.
内部研究类型:ValuationSnapshot
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The market prices the equity as an option on delivery with lender patience setting the expiry; the 0.65x level is mid-range for this register, distress priced but catastrophe not.
不确定性(原始记录):Mixed operand dates: EBITDA is FY3/26 trailing at March while net debt is September 2026, PBR uses March 2026 book, and market cap uses issued shares including 11.3 million treasury shares (derived outstanding about 291.0 million shares, market value about JPY 22.7 billion); no analyst consensus to triangulate market-implied delivery probability.
F026|09|一个超预期的半年被卖掉,说明市场按部分兑现定价
研究范围:开放研究+35项覆盖检查
写入正文:09|一个超预期的半年被卖掉,说明市场按部分兑现定价12|一次超预期的半年为什么被卖:预期差有名有姓
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress怎么使用:直接 / 支持;一手验证:31;外部现实校验:05、15、30
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:直接 / 支持;反向验证:31、35
Market framing of the interim print: progress rate and implied second half怎么使用:直接证据;一手验证:31;外部现实校验:28、35;专项深挖:31
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域05) / 外部现实(研究域15) / 外部现实(研究域30)|Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up;直接证据 / 一手证据(研究域31) / 外部现实(研究域28) / 外部现实(研究域35) / 定向深挖(研究域31)|Market framing of the interim print: progress rate and implied second half
完整研究记录(核对用)
研究原文:The market is pricing partial delivery of the plan, not failure: on 6 November 2026 the shares fell 6.02% to JPY 78 (0.65x book) on 9,736,300 shares even though the half beat guidance, because progress against the full-year ordinary-profit plan was only 21.9% and the implied H2 swing, from a derived H2 FY3/26 ordinary loss of roughly JPY 0.68 billion to +JPY 1,562 million, is the largest single assumption. Market coverage framed it as 'ordinary profit up 6% for the half, second quarter down 12%'. The gap is specific and measurable, so one quarter of segment data can close most of it in either direction; good news being sold means delivery must be repeated before price capitalises it.
内部研究类型:MarketExpectationGap
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Budget time for repeated delivery; a speculative fringe means resets will overshoot.
不确定性(原始记录):Expectations are inferred from one print's price action and secondary market coverage; institutional positioning behind trust accounts is unobservable. Counter-evidence: guidance-beating half was sold, which could also reflect liquidity use rather than disbelief.
F027|09|正常化后的盈利大致在0到30亿日元,净利润近乎于零
研究范围:35项覆盖检查+开放研究
写入正文:09|正常化后的盈利大致在0到30亿日元,净利润近乎于零
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:02
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接证据;一手验证:16;同业比较:06、12、16、28;其他用途:反证、历史
Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan怎么使用:直接 / 支持;一手验证:28;专项深挖:28
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接 / 支持;一手验证:28、35;专项深挖:35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 反证 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan;直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results
完整研究记录(核对用)
研究原文:Normalised consolidated ordinary profit on the completed plant configuration is best framed as a band of roughly JPY 0-3 billion, centred near the plan's JPY 2 billion: non-coke segments contribute JPY 3.5-4.5 billion of operating profit before about JPY 1.8 billion of corporate costs, and the coke segment swings the total by several billion yen around breakeven (roughly -2 to +2 billion on recent evidence). Anchors: FY3/25 ordinary loss JPY 10,269 million, FY3/26 ordinary loss JPY 276 million, FY3/27 plan ordinary profit JPY 2,000 million. Recurring disposal and environmental leakage is carried inside the band's width, so normalised net income is thin, near zero to about JPY 1.5 billion; at the centre the equity earns roughly 8-12% on market value in ordinary-profit terms before leakage.
内部研究类型:NormalizedEarningsPower
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):The recovery case is real but leaves no room for leakage to continue at FY3/26 rates.
不确定性(原始记录):Coke through-cycle margin per tonne on the new configuration is unobservable until delivered years; FY3/22-FY3/23 coal-spike years were deliberately excluded and not re-verified. Opposing evidence: FY3/26 below-the-line losses.
F028|06|资本回报低于同业,计划兑现也补不上缺口
研究范围:35项覆盖检查
写入正文:06|资本回报低于同业,计划兑现也补不上缺口09|正常化后的盈利大致在0到30亿日元,净利润近乎于零
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Employee data and petroleum/coal-products sector medians from securities-report data怎么使用:直接证据;外部现实校验:03、08
Petroleum and coal products sector panel: seven-company medians versus the company怎么使用:直接 / 支持;一手验证:08;外部现实校验:09、22;专项深挖:08
Compiled securities-report analysis: returns on capital, leverage gap and sales trend怎么使用:直接证据;一手验证:09、22;外部现实校验:02、18;专项深挖:09
FY3/26 results release, headline ratios: ROE and margins怎么使用:直接 / 支持;一手验证:22;专项深挖:22
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域03) / 外部现实(研究域08)|Employee data and petroleum/coal-products sector medians from securities-report data;直接证据 / 支持证据 / 一手证据(研究域08) / 外部现实(研究域09) / 外部现实(研究域22) / 定向深挖(研究域08)|Petroleum and coal products sector panel: seven-company medians versus the company;直接证据 / 一手证据(研究域09) / 一手证据(研究域22) / 外部现实(研究域02) / 外部现实(研究域18) / 定向深挖(研究域09)|Compiled securities-report analysis: returns on capital, leverage gap and sales trend;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域22)|FY3/26 results release, headline ratios: ROE and margins
完整研究记录(核对用)
研究原文:FY3/26 ROE of -20.1% (FY3/25: -28.4%), operating margin of 0.7% and equity ratio of 27.5% sit below every petroleum/coal sector median (ROE 8.0%, margin 5.4%, equity ratio 37.1%); compiled ROIC is 0.4%. Even if delivered, the FY3/27 plan (net income JPY 500 million) implies ROE of only about 1.4%, so the gap to any plausible cost of equity remains the central economic fact: the denominator carries a full industrial asset base while the numerator carries a half-configured plant.
内部研究类型:CapitalEfficiency
内部来源标记:COVERAGE35
普通股东含义(原始记录):The re-rating case must include either plan outperformance or capital-policy change, because the plan itself does not cover the cost of equity.
不确定性(原始记录):ROIC is a third-party mechanical compilation; the company's own cost-of-capital framing was not pulled; the seven-company panel is an energy-processing peer set, not the integrated steelmakers that compete for coke volume.
F029|07|管理层集中而内部化,薪酬全部与业绩挂钩
研究范围:35项覆盖检查+开放研究
写入正文:07|管理层集中而内部化,薪酬全部与业绩挂钩14|八个模块逐项得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接证据;一手验证:07;外部现实校验:23
Board composition and director compensation from the FY3/26 securities report怎么使用:直接 / 支持;一手验证:23;专项深挖:23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance;直接证据 / 支持证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Board composition and director compensation from the FY3/26 securities report
完整研究记录(核对用)
研究原文:Governance is compact and insider-led: four internal directors whose JPY 82 million compensation is recorded entirely as performance-linked cash, a company-with-statutory-auditors structure, and the same president (Hiroaki Matsuoka) across the loss years and the optimisation decision. In June 2026 the company clarified that despite the two anchor holders it retains independent decision-making and faces no formal business restrictions.
内部研究类型:GovernanceStructure
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Performance-linked pay aligns management with the profit line, but accountability runs to the anchors as much as the market; a credible plan plus restored distributions is the only governance signal that will move the register.
不确定性(原始记录):Board evaluation, skills matrix and outside-director independence detail were not reviewed; June 2026 clarification is known through a secondary summary.
F030|03|新日铁和住友商事同时是客户、供应商和股东
研究范围:开放研究+35项覆盖检查
写入正文:03|新日铁和住友商事同时是客户、供应商和股东07|两大产业股东把股东名册固定住了
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)怎么使用:直接 / 支持;一手验证:24;外部现实校验:07
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
Major-shareholder compilation: top-10 concentration and stake stability怎么使用:直接 / 支持;一手验证:24;专项深挖:24
FY3/26 results release, group description: the customer and procurement counterparties怎么使用:直接证据;一手验证:05
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域07)|Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI);直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance;直接证据 / 支持证据 / 一手证据(研究域24) / 定向深挖(研究域24)|Major-shareholder compilation: top-10 concentration and stake stability;直接证据 / 一手证据(研究域05)|FY3/26 results release, group description: the customer and procurement counterparties
完整研究记录(核对用)
研究原文:The register is anchored and static. Nippon Steel holds 22.55% (65,628,595 shares) and Sumitomo Corporation 19.43% (56,558,095 shares), with the Master Trust Bank trust account at 5.55%; the top ten hold 55.06%, leaving a free float under half of which trust-bank custody is the largest component. The two industrial stakes have not changed across at least four securities reports. Both are named related companies, major customers and procurement counterparties in a tripartite alliance covering stable coke supply, technical cooperation and coal procurement and sales; the company states no formal control rights.
内部研究类型:OwnershipRegisterAnchor
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Protects against disorder while placing control outcomes outside minorities' reach; strategic counterparties are also shareholders, customers and suppliers.
不确定性(原始记录):Alliance commercial terms are undisclosed; large-holding filings after March 2026 were not separately reviewed; beneficial owners behind trust accounts are unidentified.
F031|07|稳定的另一面:市场化的重组也被一并挡住
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
Major-shareholder compilation: top-10 concentration and stake stability怎么使用:直接证据;一手验证:24;专项深挖:24
FY3/26 results release, group description: the customer and procurement counterparties怎么使用:直接 / 支持;一手验证:05
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance;直接证据 / 一手证据(研究域24) / 定向深挖(研究域24)|Major-shareholder compilation: top-10 concentration and stake stability;直接证据 / 支持证据 / 一手证据(研究域05)|FY3/26 results release, group description: the customer and procurement counterparties
完整研究记录(核对用)
研究原文:The anchor shareholdings cut both ways for minorities: they make a disorderly collapse or hostile outcome unlikely and, equally, make a market-driven recapitalisation unlikely, so the minority claim depends almost entirely on operating delivery. The thin float lets speculative volume move the price violently without changing control.
内部研究类型:OwnershipDoubleEdge
内部来源标记:COVERAGE35
普通股东含义(原始记录):Minorities own liquidity exposure to a controlled company; value realisation waits on anchors' and management's timetable.
不确定性(原始记录):Whether the anchors view the 42% combined holding as permanent, or would support or block a capital action if recovery stalls, is unknown.
F032|08|资本政策是银行优先:现金先还债,亏损由股权承担
研究范围:35项覆盖检查
写入正文:08|资本政策是银行优先:现金先还债,亏损由股权承担14|八个模块逐项得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、25、29
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接证据;一手验证:25;专项深挖:25
FY3/26 results release, statement of changes in equity: the last dividend actually paid怎么使用:直接证据;一手验证:26;专项深挖:26
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域26)|FY3/26 results release, dividend record and profit-distribution policy;直接证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn;直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|FY3/26 results release, statement of changes in equity: the last dividend actually paid
完整研究记录(核对用)
研究原文:Capital policy in practice is lender-first: cash flow services and rolls the debt, equity absorbs losses and distributions wait. There is no equity issuance, no buyback and no formal payout framework; the stated policy balances returns against reserves for rebuilding the earnings base, and dilution at 0.65x book is not signalled. The FY3/24 dividend of JPY 873 million shows the scale distribution takes when profits allow.
内部研究类型:CapitalPolicyInPractice
内部来源标记:COVERAGE35
普通股东含义(原始记录):Expect no capital return until delivery rebuilds retained earnings; the constraint is patience, not share count.
不确定性(原始记录):Whether a DOE or payout-ratio framework will be adopted in the three-year plan is unknown.
F033|01|当前结论:条件齐备才有上行,两次披露就能见分晓
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论01|当前结论:条件齐备才有上行,两次披露就能见分晓14|总分40.98/100,评级C,暂不建立仓位
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接 / 支持;一手验证:35;反向验证:29
FY3/27 interim results release, qualitative review of the coke business怎么使用:直接 / 支持;一手验证:04
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接证据;一手验证:28、35;专项深挖:35
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:反向验证:31、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results;反证 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up
完整研究记录(核对用)
研究原文:If the two-battery coke operation holds its Q2 unit economics through the second half, consolidated operating profit normalises toward a JPY 3-4 billion run-rate, the FY3/27 plan is delivered, and equity can re-rate from distress pricing (0.65x book, market value below land book) toward asset value. The thesis rests on delivery in the next two prints, not on the asset base; it needs availability, gross margin, below-the-line leakage and lender patience to hold simultaneously for two more quarters.
内部研究类型:Thesis
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Gives the conditional upside path and what it costs to wait without dividends.
不确定性(原始记录):Confidence moderate (about 0.6); opposing evidence is that guidance is a commitment device, not evidence, and H1 progress was only 21.9% of the ordinary-profit plan.
F034|01|当前结论:条件齐备才有上行,两次披露就能见分晓
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|当前结论:条件齐备才有上行,两次披露就能见分晓11|催化剂都是有日期的交付检验
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接证据;一手验证:35;反向验证:29
Timely-disclosure index for 3315, 2025-2026: the dated catalyst record怎么使用:直接 / 支持;一手验证:30;专项深挖:30
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接 / 支持;一手验证:28、35;专项深挖:35
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:反向验证:31、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Timely-disclosure index for 3315, 2025-2026: the dated catalyst record;直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results;反证 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up
完整研究记录(核对用)
研究原文:The thesis is time-boxed and falsifiable: (1) Q3 FY3/27 shows coke segment profit or group gross margin relapsing toward FY3/26 levels; (2) FY3/27 closes with ordinary profit materially below JPY 2,000 million or another multi-billion special-loss block; (3) the three-year plan is not published by the May 2027 print, or publishes without capital-policy content; (4) short-term borrowings rise materially from JPY 37,071 million while cash falls, signalling rollover funding losses again. Any two of four falsify the thesis as stated; failure reclassifies the company as a permanently sub-scale, lender-dependent coal legacy.
内部研究类型:FalsificationConditions
内部来源标记:COVERAGE35
普通股东含义(原始记录):Tells the shareholder what evidence within two quarters would end the position logic.
不确定性(原始记录):Falsifier (1) is judged on segment outcomes because plan coal and volume assumptions are undisclosed.
F035|11|催化剂都是有日期的交付检验
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论11|催化剂都是有日期的交付检验
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接 / 支持;一手验证:35;反向验证:29
FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan怎么使用:直接 / 支持;一手验证:30
Timely-disclosure index for 3315, 2025-2026: the dated catalyst record怎么使用:直接证据;一手验证:30;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域30)|FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Timely-disclosure index for 3315, 2025-2026: the dated catalyst record
完整研究记录(核对用)
研究原文:Dated catalysts are delivery tests rather than narrative events: the Q3 FY3/27 print in February 2027 (first test of the implied H2 step-up), publication of the three-year business plan promised in May 2026 but not yet published and uncommitted in date, and the May 2027 full-year print with the FY3/28 dividend decision, followed by the June 2027 AGM and securities report.
内部研究类型:CatalystCalendar
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):The position is auditable quarter by quarter; shareholders wait on scheduled disclosures rather than exogenous luck.
不确定性(原始记录):Whether the plan is published with Q3 or held to May 2027 is unknown.
F036|02|资产撑过了每次冲击,每股价值却被亏损和时间稀释
研究范围:35项覆盖检查
写入正文:02|资产撑过了每次冲击,每股价值却被亏损和时间稀释12|一次超预期的半年为什么被卖:预期差有名有姓
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Nippon Coke & Engineering - corporate outline, history and legal English name (articles of incorporation)怎么使用:直接证据;一手验证:01;同业比较:33;其他用途:历史
FY3/26 results release, management narrative on the November 2025 production-system optimisation decision怎么使用:直接证据;一手验证:12、20、33;同业比较:04;其他用途:历史
Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26怎么使用:直接证据;外部现实校验:27、29
Historical downside prints: PBR at the 2020-2021 lows怎么使用:直接证据;一手验证:29;专项深挖:29;同业比较:27;其他用途:历史
Corporate turning points: IRCJ restructuring, 2009 renaming, exit from the Mitsui group怎么使用:直接证据;一手验证:33;专项深挖:33;同业比较:01、09、29;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 历史/同业比较(研究域33)|Nippon Coke & Engineering - corporate outline, history and legal English name (articles of incorporation);直接证据 / 一手证据(研究域12) / 一手证据(研究域20) / 一手证据(研究域33) / 历史/同业比较(研究域04)|FY3/26 results release, management narrative on the November 2025 production-system optimisation decision;直接证据 / 外部现实(研究域27) / 外部现实(研究域29)|Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26;直接证据 / 一手证据(研究域29) / 历史/同业比较(研究域27) / 定向深挖(研究域29)|Historical downside prints: PBR at the 2020-2021 lows;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域29) / 定向深挖(研究域33)|Corporate turning points: IRCJ restructuring, 2009 renaming, exit from the Mitsui group
完整研究记录(核对用)
研究原文:Turning points: 1889 Miike origins; 1950 metals separation; progressive exit from coal mining; 2003 IRCJ support after a subsidiary's land revaluation caused insolvency; 2006 IRCJ exit; 1 April 2009 renaming from Mitsui Mining and departure from the Mitsui group; 2016-2020 distress price shelf; November 2025 optimisation decision; May 2026 two-battery completion; 2026 coal-mining exit. The 2025-26 optimisation is the first reset that reduces rather than rearranges the productive base. The pattern is that the asset base survives every regime while the equity's claim on it is diluted by losses and time: survival has never been the question, per-share compounding has.
内部研究类型:HistoricalTurningPoints
内部来源标记:COVERAGE35
普通股东含义(原始记录):Argues for respecting downside duration: this register spent most of two decades below 1x book and turns took years, not quarters.
不确定性(原始记录):Pre-2004 and Mitsui-era detail is context, not load-bearing; whether the three-year plan frames itself against this history is unknown.
F037|09|一个超预期的半年被卖掉,说明市场按部分兑现定价
研究范围:开放研究
写入正文:09|一个超预期的半年被卖掉,说明市场按部分兑现定价10|2026年3月放量冲到153日元,七个月后涨幅全部吐回
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26怎么使用:直接证据;外部现实校验:27、29
March 2026 monthly bar: climax volume and rejection怎么使用:直接 / 支持;反向验证:34
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域27) / 外部现实(研究域29)|Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26;直接证据|Monthly series for 3315.T, March 2004 to October 2026: span, averages and last close;直接证据 / 支持证据 / 反证(研究域34)|March 2026 monthly bar: climax volume and rejection
完整研究记录(核对用)
研究原文:The March 2026 price pulse failed completely: the stock printed JPY 153 intra-month (close JPY 115) on volume of 346.7 million shares, more than the entire 302.3 million issued, and the next seven monthly closes were 104, 98, 95, 95, 103, 97 and 85, a full retracement to JPY 78-85 by autumn. Trailing twelve-month average monthly volume is about 134 million shares against about 29 million in 2019-2023.
内部研究类型:FailedPricePulseFact
内部来源标记:OPEN_DISCOVERY / TECHNICAL
普通股东含义(原始记录):Shows how violently the register reprices ahead of delivery evidence and then gives it back.
不确定性(原始记录):Monthly mirror series is unadjusted with MISSING_TAIL status, accepted through 26 October 2026.
F038|10|价格从2007年的497日元一路下来,十年只在51到200日元之间来回
写入正文:10|价格从2007年的497日元一路下来,十年只在51到200日元之间来回10|价格比三条长期均线低15%到25%,下跌回合没有缩浅10|什么会确认,什么会推翻这个技术判断14|八个模块逐项得分与理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Fiscal-year highs, lows and PBR prints, FY3/10-FY3/26怎么使用:直接证据;外部现实校验:34
March 2026 monthly bar: climax volume and rejection怎么使用:直接 / 支持;反向验证:34
Yearly lows and highs, 2016-2026: no rising-lows sequence怎么使用:直接 / 支持;同业比较:34;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|Monthly series for 3315.T, March 2004 to October 2026: span, averages and last close;直接证据 / 外部现实(研究域34)|Fiscal-year highs, lows and PBR prints, FY3/10-FY3/26;直接证据 / 支持证据 / 反证(研究域34)|March 2026 monthly bar: climax volume and rejection;直接证据 / 支持证据 / 历史/同业比较(研究域34)|Yearly lows and highs, 2016-2026: no rising-lows sequence
完整研究记录(核对用)
研究原文:As recorded in the Research claims (without redefining the protected Technical state): the price sits below its 12-month (JPY 105.3), 24-month (JPY 99.1) and 60-month (JPY 107.2) averages at roughly 6-8% of its 2004-2026 life range; annual lows show no rising sequence (2024: 84, 2025: 69, 2026: 83); every advance of the past decade terminated inside a JPY 120-200 band. By the standard this research applies to price structure, the decline is not yet complete, and the one attempt at altitude in March 2026 was rejected on climax volume and fully retraced.
内部研究类型:PriceStateObservations
内部来源标记:TECHNICAL
普通股东含义(原始记录):Technically shareholders are early; position logic must rest on the fundamental falsifiers, not the chart.
不确定性(原始记录):Weekly and daily structure were not examined; monthly register used. The authoritative Technical judgment remains the protected structure.
F039|10|融资买入是融券的近十倍,破位时容易变成被动卖出
研究范围:开放研究
写入正文:10|融资买入是融券的近十倍,破位时容易变成被动卖出11|十年尺度的脱碳压力和短期的被动卖出风险
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
6 November 2026 session and margin positioning怎么使用:直接 / 支持
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 支持证据|6 November 2026 session and margin positioning
完整研究记录(核对用)
研究原文:Margin positioning amplifies the downside path: margin longs of 8,892,800 shares against 897,100 shares short (9.91x, July 2026 reading) mean a break of the JPY 69-83 shelf can feed on forced selling rather than meet value buying first; the longs are about 3.1% of the free float.
内部研究类型:PositioningDownsideRisk
内部来源标记:OPEN_DISCOVERY / TECHNICAL
普通股东含义(原始记录):Speculative fringe raises the odds that an expectations reset overshoots.
不确定性(原始记录):The margin reading is dated July 2026 and may differ at the November cut-off.
F040|03|新日铁和住友商事同时是客户、供应商和股东
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)怎么使用:直接证据;一手验证:24;外部现实校验:07
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接证据;一手验证:07;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域24) / 外部现实(研究域07)|Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI);直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance
完整研究记录(核对用)
研究原文:Nippon Steel Corporation: 22.55% shareholder, principal coke customer and alliance partner; the company asserts independent decision-making.
内部研究类型:CounterpartyEntity
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Anchors demand and stability while constraining outcomes available to minorities.
不确定性(原始记录):Alliance terms and intentions undisclosed.
F041|03|新日铁和住友商事同时是客户、供应商和股东
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)怎么使用:直接证据;一手验证:24;外部现实校验:07
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接证据;一手验证:07;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域24) / 外部现实(研究域07)|Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI);直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance
完整研究记录(核对用)
研究原文:Sumitomo Corporation: 19.43% shareholder and trading-house counterparty for coal procurement and fuel sales inside the tripartite alliance.
内部研究类型:CounterpartyEntity
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Underpins coal procurement and sales capability and register stability.
不确定性(原始记录):Procurement terms and pricing mechanism undisclosed.
F042|04|真正的竞争对手是钢厂自己的焦炉
研究范围:开放研究
写入正文:04|真正的竞争对手是钢厂自己的焦炉
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 results release, segment review and coke volumes怎么使用:直接证据;同业比较:03、05、15;其他用途:历史
Employee data and petroleum/coal-products sector medians from securities-report data怎么使用:直接证据;外部现实校验:03、08
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15)|FY3/26 results release, segment review and coke volumes;直接证据 / 外部现实(研究域03) / 外部现实(研究域08)|Employee data and petroleum/coal-products sector medians from securities-report data
完整研究记录(核对用)
研究原文:Integrated steelmakers' captive coke ovens: most Japanese coke is made inside steel groups; Nippon Coke competes for the merchant balance and for volume when captive ovens are idled or rebuilt.
内部研究类型:CompetitorEntity
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Sets the merchant pool the company can address and the scarcity rent as captive ovens age.
不确定性(原始记录):Delivered-cost comparison against captive ovens is not observable from public data.
F043|06|下半年的利润要靠第二季度的水平再撑六个月
研究范围:开放研究
写入正文:06|下半年的利润要靠第二季度的水平再撑六个月13|下半年计划里到底假设了什么煤价、售价和销量?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接证据;一手验证:35;反向验证:29
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:直接证据;反向验证:31、35
Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress怎么使用:直接证据;一手验证:31;外部现实校验:05、15、30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up;直接证据 / 一手证据(研究域31) / 外部现实(研究域05) / 外部现实(研究域15) / 外部现实(研究域30)|Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress
完整研究记录(核对用)
研究原文:What coking-coal price, coke selling price and sales volume are embedded in the unchanged FY3/27 plan's implied second half (operating profit JPY 2,497 million on sales JPY 53,493 million), given a 21.9% H1 progress rate against the ordinary-profit plan? Material because it decides whether the plan is a run-rate extension or a stretch; opposite answers would swing the thesis either way. Resolved by the Q3 FY3/27 print segment commentary or any disclosed plan assumptions.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Largest single unknown in the plan; priority 1.
不确定性(原始记录):Unresolved because assumptions are undisclosed and no reasonable current public path exists; future disclosure only.
F044|08|资本政策是银行优先:现金先还债,亏损由股权承担
研究范围:开放研究+35项覆盖检查
写入正文:08|资本政策是银行优先:现金先还债,亏损由股权承担13|三年计划什么时候发布,会写进恢复分红的条件吗?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan怎么使用:直接证据;一手验证:30
Timely-disclosure index for 3315, 2025-2026: the dated catalyst record怎么使用:直接证据;一手验证:30;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域30)|FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Timely-disclosure index for 3315, 2025-2026: the dated catalyst record
完整研究记录(核对用)
研究原文:When will the promised three-year business plan be published, will it contain the capital-policy answer (conditions and sequencing for restoring the dividend) deferred in May 2026, and what will it commit to for the coke plant's through-cycle volume and margin - and does it assume domestic crude-steel demand stabilises or keeps shrinking? Material because it is the first statement of through-cycle economics and distribution conditions; non-publication by May 2027 is itself a falsifier.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Decides whether recovered cash flow has a stated shareholder purpose; priority 1.
不确定性(原始记录):Publication date uncommitted; resolved only by a future disclosure.
F045|03|焦炉改造把利润变化压缩进了一个季度
研究范围:开放研究+35项覆盖检查
写入正文:03|焦炉改造把利润变化压缩进了一个季度13|两组电池炉满负荷时每吨成本和毛利是多少,第二季度的改善有多少来自销量?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:02
FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution怎么使用:直接证据;一手验证:12
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;直接证据 / 一手证据(研究域12)|FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution
完整研究记录(核对用)
研究原文:What is the coke segment's per-tonne conversion cost and gross margin on the two-battery configuration at full utilisation, and how much of the Q2 improvement was volume (fixed-cost dilution) versus price? Material because it separates a durable cost reset from a one-quarter volume effect; resolved by Q3 and full-year segment disclosure.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Determines the through-cycle margin per tonne, the key unobservable in normalised earnings; priority 2.
不确定性(原始记录):Not disclosed; only delivered years reveal it.
F046|06|资产负债表是最紧的约束,银行条款一概未公开
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表是最紧的约束,银行条款一概未公开13|银行的授信条款、担保和展期立场是什么?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、25、29
FY3/26 results release: stakeholder support obtained for the optimisation plan怎么使用:直接证据;一手验证:07;外部现实校验:25;专项深挖:07
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接证据;一手验证:25;专项深挖:25
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域07) / 外部现实(研究域25) / 定向深挖(研究域07)|FY3/26 results release: stakeholder support obtained for the optimisation plan;直接证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn
完整研究记录(核对用)
研究原文:What are the terms of the short-term borrowing base - committed lines, collateral and the lender group's stance if FY3/27 delivery slips - given JPY 37,071 million of short-term borrowings against JPY 5,172 million of cash? Material because lender patience sets the expiry of the equity option; resolved by securities-report facility and collateral disclosures.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Defines downside severity if delivery slips; priority 2.
不确定性(原始记录):No commitment-line, collateral or covenant disclosure in any source used.
F047|03|燃料业务销量在缩,港口物流能补多少没有数字
研究范围:开放研究+35项覆盖检查
写入正文:03|燃料业务销量在缩,港口物流能补多少没有数字13|燃料利润下滑会不会稳住,港口物流能增加多少销量?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, qualitative review of fuel and resource recycling怎么使用:直接证据;一手验证:15;反向验证:10
FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption怎么使用:直接证据;一手验证:10;专项深挖:10
FY3/27 interim release: revenue-quality colour in the fuel segment怎么使用:直接证据;一手验证:15;专项深挖:15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域15) / 反证(研究域10)|FY3/27 interim results release, qualitative review of fuel and resource recycling;直接证据 / 一手证据(研究域10) / 定向深挖(研究域10)|FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption;直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|FY3/27 interim release: revenue-quality colour in the fuel segment
完整研究记录(核对用)
研究原文:Will the fuel and resource recycling segment's profit decline (H1 operating profit down JPY 641 million on customer fuel-switching and lapsed spot deals) stabilise, and what volume does the logistics/port pivot actually add? Material because the segment is part of the earnings floor under coke.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Floor stability affects normalised earnings; priority 2.
不确定性(原始记录):Pivot volumes and spot split undisclosed; resolved by FY3/27 segment commentary.
F048|06|每次经营改善都被特别损失吃掉一块
研究范围:开放研究+35项覆盖检查
写入正文:06|每次经营改善都被特别损失吃掉一块13|其余几项:环境费用、机械订单、股东意图、递延税、实际价格
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接证据;一手验证:13;同业比较:32;其他用途:历史
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:直接证据;一手验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;直接证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed
完整研究记录(核对用)
研究原文:What is the remaining schedule of environmental and site-restoration spending behind the JPY 4,045 million provision, and how much further will the recurring annual charges run? Material because it sets debt-like burden, normalised leakage and land encumbrance; resolved by securities-report environmental notes.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Priority 3; affects land realisability and recurring charges.
不确定性(原始记录):Site-level composition undisclosed.
F049|03|综合工程利润率最高,但订单能否持续还不清楚
研究范围:开放研究+35项覆盖检查
写入正文:03|综合工程利润率最高,但订单能否持续还不清楚13|其余几项:环境费用、机械订单、股东意图、递延税、实际价格
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders怎么使用:直接证据;一手验证:03;专项深挖:03
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域03)|FY3/27 interim results release, qualitative review of integrated engineering;直接证据 / 一手证据(研究域03) / 定向深挖(研究域03)|FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders
完整研究记录(核对用)
研究原文:Is the Tea Meister Mill / machinery profit spike (segment profit up more than 70% in H1, a record since founding) a durable niche business or a single-cycle order bulge, and what is its order backlog? Material because engineering is the most profitable segment per unit of sales; resolved by backlog and order disclosure.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Priority 3; affects durability of the non-coke floor.
不确定性(原始记录):No backlog or product-level split disclosed.
F050|07|稳定的另一面:市场化的重组也被一并挡住
研究范围:开放研究+35项覆盖检查
写入正文:07|稳定的另一面:市场化的重组也被一并挡住13|其余几项:环境费用、机械订单、股东意图、递延税、实际价格
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)怎么使用:直接证据;一手验证:24;外部现实校验:07
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接证据;一手验证:07;外部现实校验:23
FY3/26 results release, group description: the customer and procurement counterparties怎么使用:直接证据;一手验证:05
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域24) / 外部现实(研究域07)|Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI);直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance;直接证据 / 一手证据(研究域05)|FY3/26 results release, group description: the customer and procurement counterparties
完整研究记录(核对用)
研究原文:Do Nippon Steel and Sumitomo Corporation intend their combined 42% holding as a permanent structure, and would either support or block a future capital action (equity raise, asset sale, merger) if the recovery stalls? Material because it determines which downside and re-rating routes exist for minorities.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Priority 3.
不确定性(原始记录):No standstill, support letter or alliance term sheet disclosure; observable only through future stake filings or capital actions.
F051|06|重启靠供应商的信用垫着,产品库存要在第三季度出货
研究范围:开放研究+35项覆盖检查
写入正文:06|重启靠供应商的信用垫着,产品库存要在第三季度出货13|产品库存20.93亿日元会不会在第三季度出货?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/27 interim release, financial-position narrative: working-capital movements怎么使用:直接证据;一手验证:19;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/27 interim release, financial-position narrative: working-capital movements
完整研究记录(核对用)
研究原文:Did the H1 FY3/27 products-inventory build of JPY 2,093 million ship as second-half volume by the December 2026 quarter-end, or does it remain on the balance sheet at Q3? Material because it is the earliest physical test of whether the H2 demand side is real; the inventory costing basis and realisability were not separately disclosed.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Early free signal before any profit figure; if unshipped, plan demand is in question.
不确定性(原始记录):Resolved by the February 2027 balance sheet.
F052|06|每次经营改善都被特别损失吃掉一块
研究范围:35项覆盖检查
写入正文:06|每次经营改善都被特别损失吃掉一块13|其余几项:环境费用、机械订单、股东意图、递延税、实际价格
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim balance sheet: asset composition怎么使用:直接证据;一手验证:18;专项深挖:18
FY3/27 interim income statement: the special-items block inside a 'clean' half怎么使用:直接证据;一手验证:32;反向验证:16;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 定向深挖(研究域18)|FY3/27 interim balance sheet: asset composition;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 定向深挖(研究域32)|FY3/27 interim income statement: the special-items block inside a 'clean' half
完整研究记录(核对用)
研究原文:Deferred-tax recoverability (deferred tax assets of JPY 1,292 million against two loss years) and the impairment-test assumptions for the retained plant were not reviewed in this pass. Material because they bear on earnings quality, equity book value and whether the JPY 4,436 million impairment was sufficient; resolved by securities-report tax and impairment notes.
内部研究类型:ResearchDebt
内部来源标记:COVERAGE35
普通股东含义(原始记录):Could change book value and normalised earnings if recoverability is weaker than recognised.
不确定性(原始记录):Not reviewed; no evidence either way.
F053|03|新日铁和住友商事同时是客户、供应商和股东
研究范围:开放研究
写入正文:03|新日铁和住友商事同时是客户、供应商和股东07|两大产业股东把股东名册固定住了
归并到:F030
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)怎么使用:直接 / 支持;一手验证:24;外部现实校验:07
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域07)|Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI);直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance
完整研究记录(核对用)
研究原文:Nippon Steel is the largest shareholder (22.55%) and a principal coke customer; the alliance formalises supply and technical ties while the company asserts independent decision-making.
内部研究类型:CAPITAL
内部来源标记:OPEN_DISCOVERY
F054|03|新日铁和住友商事同时是客户、供应商和股东
研究范围:开放研究
写入正文:03|新日铁和住友商事同时是客户、供应商和股东07|两大产业股东把股东名册固定住了
归并到:F030
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)怎么使用:直接 / 支持;一手验证:24;外部现实校验:07
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域07)|Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI);直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance
完整研究记录(核对用)
研究原文:Sumitomo Corporation is the second shareholder (19.43%) and trading-house counterparty for coal procurement and fuel sales inside the tripartite alliance.
内部研究类型:CAPITAL
内部来源标记:OPEN_DISCOVERY
F055|04|真正的竞争对手是钢厂自己的焦炉
研究范围:开放研究
写入正文:04|真正的竞争对手是钢厂自己的焦炉
归并到:F042
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 results release, segment review and coke volumes怎么使用:直接证据;同业比较:03、05、15;其他用途:历史
Employee data and petroleum/coal-products sector medians from securities-report data怎么使用:直接证据;外部现实校验:03、08
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15)|FY3/26 results release, segment review and coke volumes;直接证据 / 外部现实(研究域03) / 外部现实(研究域08)|Employee data and petroleum/coal-products sector medians from securities-report data
完整研究记录(核对用)
研究原文:The company competes with integrated steelmakers' captive coke ovens for the merchant balance and for volume when captive ovens are idled or rebuilt (relation confidence 0.7).
内部研究类型:COMPETITOR
内部来源标记:OPEN_DISCOVERY
F056|04|焦炭需求在缩小,公司靠开工率在缩小的池子里拿份额
研究范围:开放研究
写入正文:04|焦炭需求在缩小,公司靠开工率在缩小的池子里拿份额05|护城河保护销量,不保护价格14|八个模块逐项得分与理由
归并到:F007
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/26 results release, segment review and coke volumes怎么使用:直接证据;同业比较:03、05、15;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15)|FY3/26 results release, segment review and coke volumes
完整研究记录(核对用)
研究原文:Coke volumes ultimately follow Japanese blast-furnace and crude-steel demand, which is in long-run decline; FY3/26 sales volume still rose 100kt on the new battery's availability.
内部研究类型:END_MARKET
内部来源标记:OPEN_DISCOVERY
F057|03|煤价与焦炭售价之间的时滞,才是利润的真变量
研究范围:开放研究
写入正文:03|煤价与焦炭售价之间的时滞,才是利润的真变量11|煤价和汇率走在售价前面,是不能对冲的变数14|八个模块逐项得分与理由
归并到:F017
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Nippon Coke & Engineering - corporate outline, history and legal English name (articles of incorporation)怎么使用:直接证据;一手验证:01;同业比较:33;其他用途:历史
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接证据;一手验证:16;同业比较:06、12、16、28;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 历史/同业比较(研究域33)|Nippon Coke & Engineering - corporate outline, history and legal English name (articles of incorporation);直接证据 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison
完整研究记录(核对用)
研究原文:The seaborne coking-coal market sets the offshore cost side; the lag between coal-price moves and coke selling-price revisions is the core margin mechanism.
内部研究类型:SUPPLIER
内部来源标记:OPEN_DISCOVERY
F058|09|土地账面值高于市值,但它是生存缓冲,不是变现价值
研究范围:开放研究
写入正文:09|土地账面值高于市值,但它是生存缓冲,不是变现价值
归并到:F091
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim results release, segment-change note; FY3/26 release group structure怎么使用:直接证据;同业比较:13;其他用途:历史
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接证据;一手验证:13;同业比较:32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域13)|FY3/27 interim results release, segment-change note; FY3/26 release group structure;直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision
完整研究记录(核对用)
研究原文:Carbon-neutrality policy and coal-phase-out pressure shorten the coke industry's horizon and raise the value of the non-coke legs; legacy-site obligations are already provided at JPY 4,045 million.
内部研究类型:POLICY
内部来源标记:OPEN_DISCOVERY
F059|02|最后一座煤矿关了,留下的是焦炉、港口和遗留负债
研究范围:开放研究
写入正文:02|最后一座煤矿关了,留下的是焦炉、港口和遗留负债
归并到:F004
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim results release, segment-change note; FY3/26 release group structure怎么使用:直接 / 支持;同业比较:13;其他用途:历史
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:支持证据;一手验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域13)|FY3/27 interim results release, segment-change note; FY3/26 release group structure;支持证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed
完整研究记录(核对用)
研究原文:Wholly-owned subsidiary Sanmi Mining withdrew from coal mining in H1 FY3/27, closing the group's last coal-extraction activity.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F060|03|综合工程利润率最高,但订单能否持续还不清楚
研究范围:开放研究
归并到:F005
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/26 results release, group structure and segment assignment of group companies怎么使用:直接证据;一手验证:02;专项深挖:02
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, group structure and segment assignment of group companies
完整研究记录(核对用)
研究原文:Wholly-owned Ariake Kiden Kogyo is an engineering subsidiary inside the group's most profitable segment.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F061|03|燃料业务销量在缩,港口物流能补多少没有数字
研究范围:开放研究
归并到:F006
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/26 results release, group structure and segment assignment of group companies怎么使用:直接证据;一手验证:02;专项深挖:02
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, group structure and segment assignment of group companies
完整研究记录(核对用)
研究原文:Wholly-owned Miike Port Logistics operates around the Miike port infrastructure that supports the fuel and recycling business (the group chart places it in 'other').
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F062|06|资产负债表是最紧的约束,银行条款一概未公开
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论06|资产负债表是最紧的约束,银行条款一概未公开14|八个模块逐项得分与理由
归并到:F015
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 results release: stakeholder support obtained for the optimisation plan怎么使用:直接证据;一手验证:07;外部现实校验:25;专项深挖:07
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接证据;一手验证:25;专项深挖:25
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 外部现实(研究域25) / 定向深挖(研究域07)|FY3/26 results release: stakeholder support obtained for the optimisation plan;直接证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn
完整研究记录(核对用)
研究原文:The main lender bank group provides the rolled short-term credit the funding model depends on; the company publicly recorded its understanding and support for the optimisation plan in FY3/26.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F063|03|综合工程利润率最高,但订单能否持续还不清楚
研究范围:开放研究
归并到:F005
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders怎么使用:直接证据;一手验证:03;专项深挖:03
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域03) / 定向深挖(研究域03)|FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders
完整研究记录(核对用)
研究原文:Tea and food-processing machinery demand (matcha production) is the end demand behind the Tea Meister Mill's record orders: a small but growing niche unrelated to the coal cycle.
内部研究类型:END_MARKET
内部来源标记:OPEN_DISCOVERY
F064|01|两组焦炉改造完成后,股东能分到多少
研究范围:开放研究+35项覆盖检查
写入正文:01|两组焦炉改造完成后,股东能分到多少06|资产负债表是最紧的约束,银行条款一概未公开
归并到:F087
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接 / 支持;一手验证:02
FY3/27 interim results release, qualitative review of the coke business怎么使用:直接 / 支持;一手验证:04
FY3/26 results release, income statement: gross-profit repair怎么使用:直接 / 支持;一手验证:16;专项深挖:16
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 支持证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/26 results release, income statement: gross-profit repair
完整研究记录(核对用)
研究原文:Lower conversion cost, fewer operating troubles and higher availability drive the repair in consolidated gross margin through fixed-cost dilution and lower repair spend.
内部研究类型:DRIVES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F065|01|当前结论:条件齐备才有上行,两次披露就能见分晓
研究范围:开放研究
写入正文:01|当前结论:条件齐备才有上行,两次披露就能见分晓11|催化剂都是有日期的交付检验
归并到:F093
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim results release, qualitative review of the coke business怎么使用:直接 / 支持;一手验证:04
Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress怎么使用:直接 / 支持;一手验证:31;外部现实校验:05、15、30
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:直接 / 支持;反向验证:31、35
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:支持证据;一手验证:35;反向验证:29
FY3/27 interim results release, segment information怎么使用:支持证据;一手验证:02
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域05) / 外部现实(研究域15) / 外部现实(研究域30)|Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up;支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;支持证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information
完整研究记录(核对用)
研究原文:The second-half plan holds only if the Q2 coke run-rate (volume, unit cost, availability) persists for six months.
内部研究类型:CONDITIONALLY_UNDERPINS
内部来源标记:OPEN_DISCOVERY
F066|06|下半年的利润要靠第二季度的水平再撑六个月
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接证据;一手验证:35;反向验证:29
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
查看完整证据标签(核对用)
直接证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026
完整研究记录(核对用)
研究原文:Because interest of about JPY 1.2 billion a year exceeds current ordinary profit, partial delivery of the plan leaves ordinary profit near zero.
内部研究类型:RAISES_REQUIRED_DELIVERY
内部来源标记:OPEN_DISCOVERY
F067|09|一个超预期的半年被卖掉,说明市场按部分兑现定价
研究范围:开放研究
写入正文:09|一个超预期的半年被卖掉,说明市场按部分兑现定价
归并到:F089
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress怎么使用:直接 / 支持;一手验证:31;外部现实校验:05、15、30
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:直接 / 支持;反向验证:31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域05) / 外部现实(研究域15) / 外部现实(研究域30)|Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up
完整研究记录(核对用)
研究原文:The large implied H2 step-up explains why a guidance-beating half was sold and the shares fell 6.02% to 0.65x book.
内部研究类型:EXPLAINS
内部来源标记:OPEN_DISCOVERY
F068|06|每次经营改善都被特别损失吃掉一块
研究范围:开放研究+35项覆盖检查
写入正文:06|每次经营改善都被特别损失吃掉一块09|正常化后的盈利大致在0到30亿日元,净利润近乎于零
归并到:F092
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 results release, special losses and narrative on the optimisation and fire怎么使用:直接 / 支持;一手验证:32;同业比较:20;其他用途:历史
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接 / 支持;一手验证:13;同业比较:32;其他用途:历史
FY3/27 interim income statement: the special-items block inside a 'clean' half怎么使用:直接证据;一手验证:32;反向验证:16;专项深挖:32
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:支持证据;一手验证:16;同业比较:06、12、16、28;其他用途:反证、历史
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:支持证据;一手验证:18、25、29
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:支持证据;一手验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域20)|FY3/26 results release, special losses and narrative on the optimisation and fire;直接证据 / 支持证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 定向深挖(研究域32)|FY3/27 interim income statement: the special-items block inside a 'clean' half;支持证据 / 反证 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;支持证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed
完整研究记录(核对用)
研究原文:Recurring special losses and environmental charges convert operating improvement into net losses, so net income stays thin even in recovery.
内部研究类型:LEAKS_OPERATING_GAIN
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F069|01|两组焦炉改造完成后,股东能分到多少
研究范围:开放研究
写入正文:01|两组焦炉改造完成后,股东能分到多少06|资产负债表是最紧的约束,银行条款一概未公开
归并到:F087
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
Market snapshot and margin-trading data for 3315怎么使用:直接证据;一手验证:27;外部现实校验:01、24、31
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:支持证据;一手验证:13;同业比较:32;其他用途:历史
FY3/26 results release, special losses and narrative on the optimisation and fire怎么使用:支持证据;一手验证:32;同业比较:20;其他用途:历史
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:一手验证:16;同业比较:06、12、16、28;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;支持证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域20)|FY3/26 results release, special losses and narrative on the optimisation and fire;反证 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison
完整研究记录(核对用)
研究原文:Net debt senior to equity turns a few billion yen of operating variance into decisive equity variance.
内部研究类型:AMPLIFIES
内部来源标记:OPEN_DISCOVERY
F070|01|当前结论:条件齐备才有上行,两次披露就能见分晓
研究范围:开放研究+35项覆盖检查
写入正文:01|当前结论:条件齐备才有上行,两次披露就能见分晓09|价格在为生存定价:资产说便宜,盈利说无物可估14|总分40.98/100,评级C,暂不建立仓位
归并到:F094
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY3/27 interim balance sheet: land and securities relative to equity怎么使用:直接 / 支持;一手验证:21;专项深挖:21
Valuation detail: book value, forecast earnings multiple and market value怎么使用:直接 / 支持;一手验证:27;外部现实校验:21;专项深挖:27
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:支持证据;一手验证:35;反向验证:29
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:支持证据;一手验证:16;同业比较:06、12、16、28;其他用途:历史
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:支持证据;一手验证:18、25、29
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:支持证据;一手验证:17;同业比较:17、25;其他用途:历史
Market snapshot and margin-trading data for 3315怎么使用:支持证据;一手验证:27;外部现实校验:01、24、31
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21)|FY3/27 interim balance sheet: land and securities relative to equity;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域21) / 定向深挖(研究域27)|Valuation detail: book value, forecast earnings multiple and market value;支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315
完整研究记录(核对用)
研究原文:Land book value above market capitalisation says the equity is cheap on assets, while earnings anchors (empty PER, negative ROE) say nothing is yet capitalisable; both are true and the gap is a going-concern discount.
内部研究类型:ANCHORS_WITH_TENSION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F071|09|土地账面值高于市值,但它是生存缓冲,不是变现价值
研究范围:35项覆盖检查
写入正文:09|土地账面值高于市值,但它是生存缓冲,不是变现价值
归并到:F091
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接 / 支持;一手验证:13;同业比较:32;其他用途:历史
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:直接 / 支持;一手验证:13;专项深挖:13
FY3/27 interim balance sheet: land and securities relative to equity怎么使用:直接证据;一手验证:21;专项深挖:21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;直接证据 / 支持证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|FY3/27 interim balance sheet: land and securities relative to equity
完整研究记录(核对用)
研究原文:Legacy environmental obligations at former mining and industrial sites may attach to the land bank, so land is treated as survival cover rather than realisable value (inference; attachments undisclosed).
内部研究类型:POSSIBLY_ENCUMBERS
内部来源标记:COVERAGE35
F072|01|两组焦炉改造完成后,股东能分到多少
研究范围:开放研究+35项覆盖检查
写入正文:01|两组焦炉改造完成后,股东能分到多少06|资产负债表是最紧的约束,银行条款一概未公开
归并到:F087
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接 / 支持;一手验证:16;同业比较:06、12、16、28;其他用途:历史
Procurement dependence: imported coal at the centre of the business outline怎么使用:直接证据;一手验证:06;专项深挖:06
FY3/26 results release, income statement: gross-profit repair怎么使用:直接证据;一手验证:16;专项深挖:16
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:支持证据;一手验证:18、25、29
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:支持证据;一手验证:17;同业比较:17、25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 一手证据(研究域06) / 定向深挖(研究域06)|Procurement dependence: imported coal at the centre of the business outline;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/26 results release, income statement: gross-profit repair;支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators
完整研究记录(核对用)
研究原文:A coking-coal spike arriving before selling-price pass-through would reopen gross losses (as in FY3/25) and test lender tolerance.
内部研究类型:THREATENS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F073|07|两大产业股东把股东名册固定住了
研究范围:35项覆盖检查
写入正文:07|两大产业股东把股东名册固定住了
归并到:F090
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
FY3/26 results release, group description: the customer and procurement counterparties怎么使用:直接 / 支持;一手验证:05
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance;直接证据 / 支持证据 / 一手证据(研究域05)|FY3/26 results release, group description: the customer and procurement counterparties
完整研究记录(核对用)
研究原文:Anchor stability prevents disorder but blocks market-driven recapitalisation, leaving minority outcomes dependent on operating delivery.
内部研究类型:QUALIFIES
内部来源标记:COVERAGE35
F074|11|最大的风险:展期依赖遇上经营落空
研究范围:35项覆盖检查
写入正文:11|最大的风险:展期依赖遇上经营落空
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/27 interim release, financial-position narrative: working-capital movements怎么使用:直接 / 支持;一手验证:19;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/27 interim release, financial-position narrative: working-capital movements
完整研究记录(核对用)
研究原文:Supplier credit funding the restart adds a second goodwill dependence alongside lenders; tightening terms would hit liquidity.
内部研究类型:ADDS_COUNTERPARTY_DEPENDENCE
内部来源标记:COVERAGE35
F075|01|当前结论:条件齐备才有上行,两次披露就能见分晓
研究范围:35项覆盖检查
写入正文:01|当前结论:条件齐备才有上行,两次披露就能见分晓11|催化剂都是有日期的交付检验
归并到:F093
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Timely-disclosure index for 3315, 2025-2026: the dated catalyst record怎么使用:直接 / 支持;一手验证:30;专项深挖:30
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接 / 支持;一手验证:28、35;专项深挖:35
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:支持证据;一手验证:35;反向验证:29
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:支持证据;一手验证:18、25、29
Market snapshot and margin-trading data for 3315怎么使用:支持证据;一手验证:27;外部现实校验:01、24、31
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:反向验证:31、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Timely-disclosure index for 3315, 2025-2026: the dated catalyst record;直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results;支持证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;反证 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up
完整研究记录(核对用)
研究原文:Any two of the four dated falsifiers invalidate the thesis as stated.
内部研究类型:FALSIFIES_IF_TRIGGERED
内部来源标记:COVERAGE35
F076|01|当前结论:条件齐备才有上行,两次披露就能见分晓
研究范围:35项覆盖检查
写入正文:01|当前结论:条件齐备才有上行,两次披露就能见分晓11|催化剂都是有日期的交付检验
归并到:F093
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan怎么使用:直接 / 支持;一手验证:30
Timely-disclosure index for 3315, 2025-2026: the dated catalyst record怎么使用:直接证据;一手验证:30;专项深挖:30
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:支持证据;一手验证:35;反向验证:29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Timely-disclosure index for 3315, 2025-2026: the dated catalyst record;支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance
完整研究记录(核对用)
研究原文:The February 2027 Q3 print is the first test of the implied second-half bridge, followed by the plan and May 2027 results.
内部研究类型:TESTS
内部来源标记:COVERAGE35
F077|01|当前结论:条件齐备才有上行,两次披露就能见分晓
研究范围:35项覆盖检查
写入正文:01|当前结论:条件齐备才有上行,两次披露就能见分晓09|价格在为生存定价:资产说便宜,盈利说无物可估14|总分40.98/100,评级C,暂不建立仓位
归并到:F094
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan怎么使用:直接 / 支持;一手验证:28;专项深挖:28
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接 / 支持;一手验证:28、35;专项深挖:35
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:一手验证:16;同业比较:06、12、16、28;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan;直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results;反证 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison
完整研究记录(核对用)
研究原文:The normalised JPY 0-3 billion ordinary-profit band, with leakage built in, is the earnings anchor against which the 0.65x book price is judged.
内部研究类型:INFORMS
内部来源标记:COVERAGE35
F078|10|融资买入是融券的近十倍,破位时容易变成被动卖出
研究范围:开放研究
写入正文:10|融资买入是融券的近十倍,破位时容易变成被动卖出11|十年尺度的脱碳压力和短期的被动卖出风险
归并到:F039
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
6 November 2026 session and margin positioning怎么使用:直接 / 支持
Market snapshot and margin-trading data for 3315怎么使用:支持证据;一手验证:27;外部现实校验:01、24、31
查看完整证据标签(核对用)
直接证据 / 支持证据|6 November 2026 session and margin positioning;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315
完整研究记录(核对用)
研究原文:Margin long dominance means a break of the JPY 69-83 shelf can feed forced selling.
内部研究类型:AMPLIFIES_DOWNSIDE_PATH
内部来源标记:TECHNICAL / OPEN_DISCOVERY
F079|09|一个超预期的半年被卖掉,说明市场按部分兑现定价
研究范围:开放研究
写入正文:09|一个超预期的半年被卖掉,说明市场按部分兑现定价10|纯价格状态定下之后,再看价格对公开事件的反应
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
March 2026 monthly bar: climax volume and rejection怎么使用:直接 / 支持;反向验证:34
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress怎么使用:支持证据;一手验证:31;外部现实校验:05、15、30
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:支持证据;反向验证:31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域34)|March 2026 monthly bar: climax volume and rejection;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;支持证据 / 一手证据(研究域31) / 外部现实(研究域05) / 外部现实(研究域15) / 外部现实(研究域30)|Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress;支持证据 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up
完整研究记录(核对用)
研究原文:The March 2026 climax pulse anticipated the completion news ahead of evidence and was fully retraced, the price-side mirror of the expectations gap.
内部研究类型:PRICE_SIDE_MIRROR
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F080|01|两组焦炉改造完成后,股东能分到多少
研究范围:35项覆盖检查
写入正文:01|两组焦炉改造完成后,股东能分到多少06|资产负债表是最紧的约束,银行条款一概未公开
归并到:F087
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, qualitative review of integrated engineering怎么使用:直接 / 支持;一手验证:03
Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan怎么使用:直接证据;一手验证:28;专项深挖:28
FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders怎么使用:支持证据;一手验证:03;专项深挖:03
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域03)|FY3/27 interim results release, qualitative review of integrated engineering;直接证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan;支持证据 / 一手证据(研究域03) / 定向深挖(研究域03)|FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders
完整研究记录(核对用)
研究原文:Engineering contributes a growing, niche earnings floor to normalised profit.
内部研究类型:CONTRIBUTES_FLOOR
内部来源标记:COVERAGE35
F081|01|两组焦炉改造完成后,股东能分到多少
研究范围:35项覆盖检查
写入正文:01|两组焦炉改造完成后,股东能分到多少06|资产负债表是最紧的约束,银行条款一概未公开
归并到:F087
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, qualitative review of fuel and resource recycling怎么使用:直接 / 支持;一手验证:15;反向验证:10
Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan怎么使用:直接证据;一手验证:28;专项深挖:28
FY3/26 results release, coke demand: inquiries and sales-volume growth怎么使用:支持证据;一手验证:05;专项深挖:05;同业比较:11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 反证(研究域10)|FY3/27 interim results release, qualitative review of fuel and resource recycling;直接证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan;支持证据 / 一手证据(研究域05) / 历史/同业比较(研究域11) / 定向深挖(研究域05)|FY3/26 results release, coke demand: inquiries and sales-volume growth
完整研究记录(核对用)
研究原文:Fuel's managed volume decline erodes the non-coke floor that damps but cannot replace the coke swing.
内部研究类型:ERODES_FLOOR
内部来源标记:COVERAGE35
F082|01|两组焦炉改造完成后,股东能分到多少
研究范围:开放研究
写入正文:01|两组焦炉改造完成后,股东能分到多少06|资产负债表是最紧的约束,银行条款一概未公开
归并到:F087
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接证据;一手验证:17;同业比较:17、25;其他用途:历史
FY3/26 results release, statement of changes in equity and retained-earnings path怎么使用:直接证据;同业比较:02、18、22、26;其他用途:历史
FY3/26 results release: stakeholder support obtained for the optimisation plan怎么使用:直接 / 支持;一手验证:07;外部现实校验:25;专项深挖:07
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:支持证据;一手验证:25;专项深挖:25
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:一手验证:35;反向验证:29;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|FY3/26 results release, statement of changes in equity and retained-earnings path;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域25) / 定向深挖(研究域07)|FY3/26 results release: stakeholder support obtained for the optimisation plan;支持证据 / 一手证据(研究域26)|FY3/26 results release, dividend record and profit-distribution policy;支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn;反证 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance
完整研究记录(核对用)
研究原文:Loss-driven equity erosion thins the equity ratio and raises the importance of lender goodwill.
内部研究类型:RAISES_LENDER_DEPENDENCE
内部来源标记:OPEN_DISCOVERY
F083|06|毛利率分三步修复,修复来自成本不是售价
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim release: revenue-quality colour in the fuel segment怎么使用:直接证据;一手验证:15;专项深挖:15
FY3/26 results release, income statement: gross-profit repair怎么使用:直接 / 支持;一手验证:16;专项深挖:16
FY3/27 interim results release, segment information怎么使用:支持证据;一手验证:02
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|FY3/27 interim release: revenue-quality colour in the fuel segment;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/26 results release, income statement: gross-profit repair;支持证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information
完整研究记录(核对用)
研究原文:Because realised price per tonne is undisclosed, the gross-margin repair cannot be split between price and cost from outside; attribution is management's.
内部研究类型:QUALIFIES
内部来源标记:COVERAGE35
F084|06|经营现金流多半来自折旧和减值,自由现金流接近零
研究范围:35项覆盖检查
写入正文:06|经营现金流多半来自折旧和减值,自由现金流接近零08|资本政策是银行优先:现金先还债,亏损由股权承担
归并到:F088
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 results release, cash-flow detail: what the operating cash flow is made of怎么使用:直接 / 支持;一手验证:17;专项深挖:17
FY3/26 results release: investment scale behind the reconfiguration怎么使用:直接 / 支持;一手验证:20;专项深挖:20
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接证据;一手验证:25;专项深挖:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|FY3/26 results release, cash-flow detail: what the operating cash flow is made of;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|FY3/26 results release: investment scale behind the reconfiguration;直接证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn
完整研究记录(核对用)
研究原文:Free cash flow near zero in FY3/26 left nothing for debt reduction or dividends, which is why capital policy is lender-first until cash tilts positive.
内部研究类型:CONSTRAINS
内部来源标记:COVERAGE35
F085|10|纯价格状态定下之后,再看价格对公开事件的反应
研究范围:开放研究
写入正文:10|纯价格状态定下之后,再看价格对公开事件的反应
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Market snapshot and margin-trading data for 3315怎么使用:直接证据;一手验证:27;外部现实校验:01、24、31
March 2026 monthly bar: climax volume and rejection怎么使用:支持证据;反向验证:34
Yearly lows and highs, 2016-2026: no rising-lows sequence怎么使用:支持证据;同业比较:34;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 支持证据|Monthly series for 3315.T, March 2004 to October 2026: span, averages and last close;支持证据 / 反证(研究域34)|March 2026 monthly bar: climax volume and rejection;支持证据 / 历史/同业比较(研究域34)|Yearly lows and highs, 2016-2026: no rising-lows sequence
完整研究记录(核对用)
研究原文:The fundamental-side price-versus-delivery reading references the protected Technical Synthesis as a whole for its authoritative price-structure judgment; it neither restates nor modifies it, and fundamental delivery evidence is not used to alter the Technical State.
内部研究类型:CROSS_LANE_REFERENCE_ONLY
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F086|02|资产撑过了每次冲击,每股价值却被亏损和时间稀释
研究范围:开放研究+35项覆盖检查
写入正文:02|资产撑过了每次冲击,每股价值却被亏损和时间稀释05|护城河保护销量,不保护价格
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(44项,重复标签已合并)
Nippon Coke & Engineering - corporate outline, history and legal English name (articles of incorporation)怎么使用:直接证据;一手验证:01;同业比较:33;其他用途:历史
Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)怎么使用:直接 / 支持;一手验证:24;外部现实校验:07
FY3/27 interim results release, segment-change note; FY3/26 release group structure怎么使用:直接证据;同业比较:13;其他用途:历史
Business outline from the securities report as republished by gBizINFO怎么使用:直接证据;一手验证:01;专项深挖:01
FY3/26 results release, group structure and segment assignment of group companies怎么使用:直接证据;一手验证:02;专项深挖:02
FY3/27 interim results release, segment information怎么使用:直接 / 支持;一手验证:02
FY3/26 results release, segment review and coke volumes怎么使用:直接证据;同业比较:03、05、15;其他用途:历史
FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders怎么使用:直接证据;一手验证:03;专项深挖:03
Employee data and petroleum/coal-products sector medians from securities-report data怎么使用:直接证据;外部现实校验:03、08
FY3/26 results release, coke demand: inquiries and sales-volume growth怎么使用:直接证据;一手验证:05;专项深挖:05;同业比较:11;其他用途:历史
Petroleum and coal products sector panel: seven-company medians versus the company怎么使用:直接证据;一手验证:08;外部现实校验:09、22;专项深挖:08
Compiled securities-report analysis: returns on capital, leverage gap and sales trend怎么使用:直接证据;一手验证:09、22;外部现实校验:02、18;专项深挖:09
FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption怎么使用:直接证据;一手验证:10;专项深挖:10
FY3/26 results release, outlook: risk framing for FY3/27怎么使用:直接证据;一手验证:11;外部现实校验:14;专项深挖:11
FY3/26 results release, group description: the customer and procurement counterparties怎么使用:直接证据;一手验证:05
FY3/27 interim results release, qualitative review of the coke business怎么使用:直接 / 支持;一手验证:04
FY3/26 results release, management narrative on the November 2025 production-system optimisation decision怎么使用:直接证据;一手验证:12、20、33;同业比较:04;其他用途:历史
FY3/27 interim release, operating-technology change: preventive maintenance and resource reallocation怎么使用:直接证据;一手验证:04、10;专项深挖:04
FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution怎么使用:直接证据;一手验证:12
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接 / 支持;一手验证:16;同业比较:06、12、16、28;其他用途:反证、历史
Procurement dependence: imported coal at the centre of the business outline怎么使用:直接证据;一手验证:06;专项深挖:06
FY3/27 interim release, management's macro framing怎么使用:直接证据;一手验证:14;外部现实校验:06、11、12;专项深挖:14
FY3/26 results release, income statement: gross-profit repair怎么使用:直接证据;一手验证:16;专项深挖:16
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接证据;一手验证:17;同业比较:17、25;其他用途:历史
FY3/26 results release: stakeholder support obtained for the optimisation plan怎么使用:直接证据;一手验证:07;外部现实校验:25;专项深挖:07
FY3/27 interim balance sheet: asset composition怎么使用:直接证据;一手验证:18;专项深挖:18
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接 / 支持;一手验证:25;专项深挖:25
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
Major-shareholder compilation: top-10 concentration and stake stability怎么使用:直接 / 支持;一手验证:24;专项深挖:24
FY3/26 results release, special losses and narrative on the optimisation and fire怎么使用:直接 / 支持;一手验证:32;同业比较:20;其他用途:历史
FY3/27 interim income statement: the special-items block inside a 'clean' half怎么使用:直接证据;一手验证:32;反向验证:16;专项深挖:32
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接 / 支持;一手验证:13;同业比较:32;其他用途:历史
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:直接 / 支持;一手验证:13;专项深挖:13
FY3/27 interim balance sheet: land and securities relative to equity怎么使用:直接 / 支持;一手验证:21;专项深挖:21
Valuation detail: book value, forecast earnings multiple and market value怎么使用:直接 / 支持;一手验证:27;外部现实校验:21;专项深挖:27
Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26怎么使用:直接证据;外部现实校验:27、29
Historical downside prints: PBR at the 2020-2021 lows怎么使用:直接证据;一手验证:29;专项深挖:29;同业比较:27;其他用途:历史
Corporate turning points: IRCJ restructuring, 2009 renaming, exit from the Mitsui group怎么使用:直接证据;一手验证:33;专项深挖:33;同业比较:01、09、29;其他用途:历史
Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan怎么使用:直接 / 支持;一手验证:28;专项深挖:28
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接 / 支持;一手验证:28、35;专项深挖:35
FY3/26 results release, statement of changes in equity: the last dividend actually paid怎么使用:直接证据;一手验证:26;专项深挖:26
Board composition and director compensation from the FY3/26 securities report怎么使用:直接 / 支持;一手验证:23;专项深挖:23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 历史/同业比较(研究域33)|Nippon Coke & Engineering - corporate outline, history and legal English name (articles of incorporation);直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域07)|Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI);直接证据 / 历史/同业比较(研究域13)|FY3/27 interim results release, segment-change note; FY3/26 release group structure;直接证据 / 一手证据(研究域01) / 定向深挖(研究域01)|Business outline from the securities report as republished by gBizINFO;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, group structure and segment assignment of group companies;直接证据 / 支持证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15)|FY3/26 results release, segment review and coke volumes;直接证据 / 一手证据(研究域03) / 定向深挖(研究域03)|FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders;直接证据 / 外部现实(研究域03) / 外部现实(研究域08)|Employee data and petroleum/coal-products sector medians from securities-report data;直接证据 / 一手证据(研究域05) / 历史/同业比较(研究域11) / 定向深挖(研究域05)|FY3/26 results release, coke demand: inquiries and sales-volume growth;直接证据 / 一手证据(研究域08) / 外部现实(研究域09) / 外部现实(研究域22) / 定向深挖(研究域08)|Petroleum and coal products sector panel: seven-company medians versus the company;直接证据 / 一手证据(研究域09) / 一手证据(研究域22) / 外部现实(研究域02) / 外部现实(研究域18) / 定向深挖(研究域09)|Compiled securities-report analysis: returns on capital, leverage gap and sales trend;直接证据 / 一手证据(研究域10) / 定向深挖(研究域10)|FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption;直接证据 / 一手证据(研究域11) / 外部现实(研究域14) / 定向深挖(研究域11)|FY3/26 results release, outlook: risk framing for FY3/27;直接证据 / 一手证据(研究域05)|FY3/26 results release, group description: the customer and procurement counterparties;直接证据 / 支持证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;直接证据 / 一手证据(研究域12) / 一手证据(研究域20) / 一手证据(研究域33) / 历史/同业比较(研究域04)|FY3/26 results release, management narrative on the November 2025 production-system optimisation decision;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04)|FY3/27 interim release, operating-technology change: preventive maintenance and resource reallocation;直接证据 / 一手证据(研究域12)|FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution;直接证据 / 支持证据 / 反证 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 一手证据(研究域06) / 定向深挖(研究域06)|Procurement dependence: imported coal at the centre of the business outline;直接证据 / 一手证据(研究域14) / 外部现实(研究域06) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域14)|FY3/27 interim release, management's macro framing;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/26 results release, income statement: gross-profit repair;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 一手证据(研究域07) / 外部现实(研究域25) / 定向深挖(研究域07)|FY3/26 results release: stakeholder support obtained for the optimisation plan;直接证据 / 一手证据(研究域18) / 定向深挖(研究域18)|FY3/27 interim balance sheet: asset composition;直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance;直接证据 / 支持证据 / 一手证据(研究域24) / 定向深挖(研究域24)|Major-shareholder compilation: top-10 concentration and stake stability;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域20)|FY3/26 results release, special losses and narrative on the optimisation and fire;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 定向深挖(研究域32)|FY3/27 interim income statement: the special-items block inside a 'clean' half;直接证据 / 支持证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;直接证据 / 支持证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21)|FY3/27 interim balance sheet: land and securities relative to equity;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域21) / 定向深挖(研究域27)|Valuation detail: book value, forecast earnings multiple and market value;直接证据 / 外部现实(研究域27) / 外部现实(研究域29)|Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26;直接证据 / 一手证据(研究域29) / 历史/同业比较(研究域27) / 定向深挖(研究域29)|Historical downside prints: PBR at the 2020-2021 lows;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域29) / 定向深挖(研究域33)|Corporate turning points: IRCJ restructuring, 2009 renaming, exit from the Mitsui group;直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan;直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results;直接证据 / 一手证据(研究域26)|FY3/26 results release, dividend record and profit-distribution policy;直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|FY3/26 results release, statement of changes in equity: the last dividend actually paid;直接证据 / 支持证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Board composition and director compensation from the FY3/26 securities report
完整研究记录(核对用)
研究原文:Durable business portrait: a durable physical and relational structure carrying fragile flows|The durable elements are physical and relational: a configured two-battery coke plant with port infrastructure, qualified supply into blast furnaces that still run, two industrial anchors whose stakes have not moved in years, and lenders who rolled credit through two loss years. The fragile elements are all in the flow: a price-negotiation lag against a dollar commodity, a below-the-line habit of disposal and environmental charges, and an equity claim so far behind the debt stack that small operating disappointments become large equity disappointments. The structure endures as a company while remaining unproven as an investment; that asymmetry is what 0.65x book is expressing, and delivery in FY3/27 and FY3/28 is the only mechanism by which the flow can catch up with the structure.
内部研究类型:DurableBusinessPortrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Survival is not in question, per-share compounding is; shareholders hold a levered option on delivery with no income while waiting.
不确定性(原始记录):Durability depends on maintenance discipline holding on a one-plant, two-battery configuration; contract and facility terms behind the relational durability are undisclosed.
F087|01|两组焦炉改造完成后,股东能分到多少
研究范围:开放研究+35项覆盖检查
写入正文:01|两组焦炉改造完成后,股东能分到多少06|资产负债表是最紧的约束,银行条款一概未公开
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(37项,重复标签已合并)
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接 / 支持;一手验证:16;同业比较:06、12、16、28;其他用途:反证、历史
Procurement dependence: imported coal at the centre of the business outline怎么使用:直接证据;一手验证:06;专项深挖:06
FY3/26 results release, outlook: risk framing for FY3/27怎么使用:直接证据;一手验证:11;外部现实校验:14;专项深挖:11
FY3/27 interim release, management's macro framing怎么使用:直接证据;一手验证:14;外部现实校验:06、11、12;专项深挖:14
FY3/26 results release, income statement: gross-profit repair怎么使用:直接 / 支持;一手验证:16;专项深挖:16
FY3/27 interim results release, segment information怎么使用:直接 / 支持;一手验证:02
FY3/27 interim results release, qualitative review of the coke business怎么使用:直接 / 支持;一手验证:04
FY3/26 results release, management narrative on the November 2025 production-system optimisation decision怎么使用:直接证据;一手验证:12、20、33;同业比较:04;其他用途:历史
FY3/27 interim release, operating-technology change: preventive maintenance and resource reallocation怎么使用:直接证据;一手验证:04、10;专项深挖:04
FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution怎么使用:直接证据;一手验证:12
FY3/27 interim results release, qualitative review of fuel and resource recycling怎么使用:直接 / 支持;一手验证:15;反向验证:10
FY3/26 results release, group structure and segment assignment of group companies怎么使用:直接证据;一手验证:02;专项深挖:02
FY3/26 results release, coke demand: inquiries and sales-volume growth怎么使用:直接 / 支持;一手验证:05;专项深挖:05;同业比较:11;其他用途:历史
FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption怎么使用:直接证据;一手验证:10;专项深挖:10
FY3/27 interim release: revenue-quality colour in the fuel segment怎么使用:直接证据;一手验证:15;专项深挖:15
FY3/27 interim results release, qualitative review of integrated engineering怎么使用:直接 / 支持;一手验证:03
FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders怎么使用:直接 / 支持;一手验证:03;专项深挖:03
Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan怎么使用:直接证据;一手验证:28;专项深挖:28
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 results release, special losses and narrative on the optimisation and fire怎么使用:直接 / 支持;一手验证:32;同业比较:20;其他用途:历史
FY3/27 interim income statement: the special-items block inside a 'clean' half怎么使用:直接证据;一手验证:32;反向验证:16;专项深挖:32
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接 / 支持;一手验证:17;同业比较:17、25;其他用途:历史
FY3/26 results release, dividend record and profit-distribution policy怎么使用:直接 / 支持;一手验证:26
FY3/26 results release, statement of changes in equity and retained-earnings path怎么使用:直接证据;同业比较:02、18、22、26;其他用途:历史
FY3/26 results release, statement of changes in equity: the last dividend actually paid怎么使用:直接 / 支持;一手验证:26;专项深挖:26
FY3/26 results release: stakeholder support obtained for the optimisation plan怎么使用:直接 / 支持;一手验证:07;外部现实校验:25;专项深挖:07
FY3/27 interim balance sheet: asset composition怎么使用:直接证据;一手验证:18;专项深挖:18
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接 / 支持;一手验证:25;专项深挖:25
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:一手验证:35;反向验证:29;其他用途:反证
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接 / 支持;一手验证:13;同业比较:32;其他用途:历史
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
Major-shareholder compilation: top-10 concentration and stake stability怎么使用:直接证据;一手验证:24;专项深挖:24
FY3/26 results release, group description: the customer and procurement counterparties怎么使用:直接 / 支持;一手验证:05
6 November 2026 session and margin positioning怎么使用:直接 / 支持
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:支持证据;一手验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 一手证据(研究域06) / 定向深挖(研究域06)|Procurement dependence: imported coal at the centre of the business outline;直接证据 / 一手证据(研究域11) / 外部现实(研究域14) / 定向深挖(研究域11)|FY3/26 results release, outlook: risk framing for FY3/27;直接证据 / 一手证据(研究域14) / 外部现实(研究域06) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域14)|FY3/27 interim release, management's macro framing;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/26 results release, income statement: gross-profit repair;直接证据 / 支持证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 支持证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;直接证据 / 一手证据(研究域12) / 一手证据(研究域20) / 一手证据(研究域33) / 历史/同业比较(研究域04)|FY3/26 results release, management narrative on the November 2025 production-system optimisation decision;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04)|FY3/27 interim release, operating-technology change: preventive maintenance and resource reallocation;直接证据 / 一手证据(研究域12)|FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution;直接证据 / 支持证据 / 一手证据(研究域15) / 反证(研究域10)|FY3/27 interim results release, qualitative review of fuel and resource recycling;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, group structure and segment assignment of group companies;直接证据 / 支持证据 / 一手证据(研究域05) / 历史/同业比较(研究域11) / 定向深挖(研究域05)|FY3/26 results release, coke demand: inquiries and sales-volume growth;直接证据 / 一手证据(研究域10) / 定向深挖(研究域10)|FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption;直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|FY3/27 interim release: revenue-quality colour in the fuel segment;直接证据 / 支持证据 / 一手证据(研究域03)|FY3/27 interim results release, qualitative review of integrated engineering;直接证据 / 支持证据 / 一手证据(研究域03) / 定向深挖(研究域03)|FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders;直接证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域20)|FY3/26 results release, special losses and narrative on the optimisation and fire;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 定向深挖(研究域32)|FY3/27 interim income statement: the special-items block inside a 'clean' half;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 支持证据 / 一手证据(研究域26)|FY3/26 results release, dividend record and profit-distribution policy;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|FY3/26 results release, statement of changes in equity and retained-earnings path;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|FY3/26 results release, statement of changes in equity: the last dividend actually paid;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域25) / 定向深挖(研究域07)|FY3/26 results release: stakeholder support obtained for the optimisation plan;直接证据 / 一手证据(研究域18) / 定向深挖(研究域18)|FY3/27 interim balance sheet: asset composition;直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn;反证 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 支持证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance;直接证据 / 一手证据(研究域24) / 定向深挖(研究域24)|Major-shareholder compilation: top-10 concentration and stake stability;直接证据 / 支持证据 / 一手证据(研究域05)|FY3/26 results release, group description: the customer and procurement counterparties;直接证据 / 支持证据|6 November 2026 session and margin positioning;支持证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed
完整研究记录(核对用)
研究原文:Coke economics to equity: availability, spread lag, interest, leakage and lender patience|Coke operating profit is volume times (coke price minus coal cost minus conversion cost) minus fixed costs; the two-battery change attacks conversion cost and availability while the price term lags coal. Interest is a senior fixed claim and recurring special items leak the improvement below the operating line. Non-coke segments damp but cannot replace the coke swing. Equity erosion feeds back into lender dependence; anchors stabilise but block recapitalisation; speculative positioning makes price discovery detached from delivery.
内部研究类型:MainCausalArchitecture
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Equity variance is far larger than operating variance; a coke swing of a few billion yen decides whether net results are positive at all.
不确定性(原始记录):Price-versus-cost split and plan coal assumptions undisclosed.
F088|06|经营现金流多半来自折旧和减值,自由现金流接近零
研究范围:开放研究+35项覆盖检查
写入正文:06|经营现金流多半来自折旧和减值,自由现金流接近零08|资本政策是银行优先:现金先还债,亏损由股权承担
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(12项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接 / 支持;一手验证:02
FY3/27 interim results release, qualitative review of the coke business怎么使用:直接 / 支持;一手验证:04
FY3/26 results release, management narrative on the November 2025 production-system optimisation decision怎么使用:直接证据;一手验证:12、20、33;同业比较:04;其他用途:历史
FY3/27 interim release, operating-technology change: preventive maintenance and resource reallocation怎么使用:直接证据;一手验证:04、10;专项深挖:04
FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution怎么使用:直接证据;一手验证:12
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接证据;一手验证:17;同业比较:17、25;其他用途:历史
FY3/26 results release, cash-flow detail: what the operating cash flow is made of怎么使用:直接 / 支持;一手验证:17;专项深挖:17
FY3/26 results release: investment scale behind the reconfiguration怎么使用:直接 / 支持;一手验证:20;专项深挖:20
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、25、29
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接证据;一手验证:25;专项深挖:25
FY3/26 results release, statement of changes in equity: the last dividend actually paid怎么使用:直接证据;一手验证:26;专项深挖:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 支持证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;直接证据 / 一手证据(研究域12) / 一手证据(研究域20) / 一手证据(研究域33) / 历史/同业比较(研究域04)|FY3/26 results release, management narrative on the November 2025 production-system optimisation decision;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04)|FY3/27 interim release, operating-technology change: preventive maintenance and resource reallocation;直接证据 / 一手证据(研究域12)|FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution;直接证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|FY3/26 results release, cash-flow detail: what the operating cash flow is made of;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|FY3/26 results release: investment scale behind the reconfiguration;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域26)|FY3/26 results release, dividend record and profit-distribution policy;直接证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn;直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|FY3/26 results release, statement of changes in equity: the last dividend actually paid
完整研究记录(核对用)
研究原文:Operations to cash: depreciation-funded cash flow now freed from construction|The plant reconfiguration is visible in cash registers: depreciation of about JPY 6 billion a year funded an operating cash flow that exactly matched the JPY 8.7 billion rebuilding outflow in FY3/26. From FY3/27 the question is whether the same depreciation funds debt reduction or dividends instead of construction.
内部研究类型:CrossDomainMechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Cash tilt, not accounting profit, gates any distribution.
不确定性(原始记录):H1 FY3/27 operating cash flow unobservable until the full-year statement.
F089|09|一个超预期的半年被卖掉,说明市场按部分兑现定价
研究范围:开放研究+35项覆盖检查
写入正文:09|一个超预期的半年被卖掉,说明市场按部分兑现定价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(17项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接 / 支持;一手验证:17;同业比较:17、25;其他用途:历史
FY3/26 results release: stakeholder support obtained for the optimisation plan怎么使用:直接证据;一手验证:07;外部现实校验:25;专项深挖:07
FY3/27 interim balance sheet: asset composition怎么使用:直接证据;一手验证:18;专项深挖:18
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接 / 支持;一手验证:25;专项深挖:25
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress怎么使用:直接 / 支持;一手验证:31;外部现实校验:05、15、30
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:直接 / 支持;反向验证:31、35
Market framing of the interim print: progress rate and implied second half怎么使用:直接证据;一手验证:31;外部现实校验:28、35;专项深挖:31
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接 / 支持;一手验证:35;反向验证:29
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接 / 支持;一手验证:16;同业比较:06、12、16、28;其他用途:反证、历史
Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26怎么使用:直接证据;外部现实校验:27、29
Valuation detail: book value, forecast earnings multiple and market value怎么使用:直接 / 支持;一手验证:27;外部现实校验:21;专项深挖:27
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接证据;一手验证:28、35;专项深挖:35
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:支持证据;一手验证:13;同业比较:32;其他用途:历史
FY3/26 results release, special losses and narrative on the optimisation and fire怎么使用:支持证据;一手验证:32;同业比较:20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 一手证据(研究域07) / 外部现实(研究域25) / 定向深挖(研究域07)|FY3/26 results release: stakeholder support obtained for the optimisation plan;直接证据 / 一手证据(研究域18) / 定向深挖(研究域18)|FY3/27 interim balance sheet: asset composition;直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域05) / 外部现实(研究域15) / 外部现实(研究域30)|Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up;直接证据 / 一手证据(研究域31) / 外部现实(研究域28) / 外部现实(研究域35) / 定向深挖(研究域31)|Market framing of the interim print: progress rate and implied second half;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 反证 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 外部现实(研究域27) / 外部现实(研究域29)|Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域21) / 定向深挖(研究域27)|Valuation detail: book value, forecast earnings multiple and market value;直接证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results;支持证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域20)|FY3/26 results release, special losses and narrative on the optimisation and fire
完整研究记录(核对用)
研究原文:Balance sheet to expectations: why a beat is not capitalised|With net debt near JPY 59 billion, leverage is why the market refuses to capitalise a guidance-beating half: ordinary-profit delivery must be repeated before any of it is believed to reach the equity, which shows up in the valuation.
内部研究类型:CrossDomainMechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Budget for repeated delivery before re-rating.
不确定性(原始记录):No consensus series to calibrate implied delivery probability.
F090|07|两大产业股东把股东名册固定住了
研究范围:开放研究+35项覆盖检查
写入正文:07|两大产业股东把股东名册固定住了
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(10项,重复标签已合并)
Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)怎么使用:直接 / 支持;一手验证:24;外部现实校验:07
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
Major-shareholder compilation: top-10 concentration and stake stability怎么使用:直接 / 支持;一手验证:24;专项深挖:24
FY3/26 results release, group description: the customer and procurement counterparties怎么使用:直接 / 支持;一手验证:05
Board composition and director compensation from the FY3/26 securities report怎么使用:直接 / 支持;一手验证:23;专项深挖:23
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接证据;一手验证:17;同业比较:17、25;其他用途:历史
FY3/26 results release: stakeholder support obtained for the optimisation plan怎么使用:直接证据;一手验证:07;外部现实校验:25;专项深挖:07
FY3/27 interim balance sheet: asset composition怎么使用:直接证据;一手验证:18;专项深挖:18
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接 / 支持;一手验证:25;专项深挖:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域07)|Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI);直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance;直接证据 / 支持证据 / 一手证据(研究域24) / 定向深挖(研究域24)|Major-shareholder compilation: top-10 concentration and stake stability;直接证据 / 支持证据 / 一手证据(研究域05)|FY3/26 results release, group description: the customer and procurement counterparties;直接证据 / 支持证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Board composition and director compensation from the FY3/26 securities report;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 一手证据(研究域07) / 外部现实(研究域25) / 定向深挖(研究域07)|FY3/26 results release: stakeholder support obtained for the optimisation plan;直接证据 / 一手证据(研究域18) / 定向深挖(研究域18)|FY3/27 interim balance sheet: asset composition;直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn
完整研究记录(核对用)
研究原文:Ownership to governance: survival through two loss years and a governance discount from one cause|The frozen anchor register explains both the survival through two loss years and the governance discount; the June 2026 clarification is the company's own recognition that the two cannot be separated.
内部研究类型:CrossDomainMechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Minorities' return must come from dividends and price, not corporate action.
不确定性(原始记录):Anchor intentions undisclosed.
F091|09|土地账面值高于市值,但它是生存缓冲,不是变现价值
研究范围:35项覆盖检查+开放研究
写入正文:09|土地账面值高于市值,但它是生存缓冲,不是变现价值
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(13项,重复标签已合并)
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接 / 支持;一手验证:13;同业比较:32;其他用途:历史
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:直接 / 支持;一手验证:13;专项深挖:13
Petroleum and coal products sector panel: seven-company medians versus the company怎么使用:直接证据;一手验证:08;外部现实校验:09、22;专项深挖:08
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/27 interim balance sheet: asset composition怎么使用:直接证据;一手验证:18;专项深挖:18
FY3/27 interim balance sheet: land and securities relative to equity怎么使用:直接 / 支持;一手验证:21;专项深挖:21
Valuation detail: book value, forecast earnings multiple and market value怎么使用:直接 / 支持;一手验证:27;外部现实校验:21;专项深挖:27
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接 / 支持;一手验证:35;反向验证:29
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接 / 支持;一手验证:16;同业比较:06、12、16、28;其他用途:历史
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接 / 支持;一手验证:17;同业比较:17、25;其他用途:历史
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26怎么使用:直接证据;外部现实校验:27、29
FY3/27 interim results release, segment-change note; FY3/26 release group structure怎么使用:直接证据;同业比较:13;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;直接证据 / 支持证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed;直接证据 / 一手证据(研究域08) / 外部现实(研究域09) / 外部现实(研究域22) / 定向深挖(研究域08)|Petroleum and coal products sector panel: seven-company medians versus the company;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域18) / 定向深挖(研究域18)|FY3/27 interim balance sheet: asset composition;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21)|FY3/27 interim balance sheet: land and securities relative to equity;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域21) / 定向深挖(研究域27)|Valuation detail: book value, forecast earnings multiple and market value;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 外部现实(研究域27) / 外部现实(研究域29)|Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26;直接证据 / 历史/同业比较(研究域13)|FY3/27 interim results release, segment-change note; FY3/26 release group structure
完整研究记录(核对用)
研究原文:Policy to terminal value: land as survival cover, not realisable value|Environmental provisions and the decarbonisation deadline convert the land bank from a simple asset anchor into a partially encumbered one, which is why valuation treats land as survival cover rather than realisable value.
内部研究类型:CrossDomainMechanism
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Asset cover supports survival, which allows the delivery option to be exercised, but is not the return path.
不确定性(原始记录):Remediation attachments and appraisal undisclosed.
F092|06|每次经营改善都被特别损失吃掉一块
研究范围:35项覆盖检查+开放研究
写入正文:06|每次经营改善都被特别损失吃掉一块09|正常化后的盈利大致在0到30亿日元,净利润近乎于零
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(14项,重复标签已合并)
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接 / 支持;一手验证:16;同业比较:06、12、16、28;其他用途:反证、历史
FY3/26 results release, special losses and narrative on the optimisation and fire怎么使用:直接 / 支持;一手验证:32;同业比较:20;其他用途:历史
FY3/27 interim income statement: the special-items block inside a 'clean' half怎么使用:直接证据;一手验证:32;反向验证:16;专项深挖:32
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接 / 支持;一手验证:13;同业比较:32;其他用途:历史
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:直接 / 支持;一手验证:13;专项深挖:13
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:02
Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan怎么使用:直接 / 支持;一手验证:28;专项深挖:28
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接 / 支持;一手验证:28、35;专项深挖:35
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接 / 支持;一手验证:35;反向验证:29
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接 / 支持;一手验证:17;同业比较:17、25;其他用途:历史
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26怎么使用:直接证据;外部现实校验:27、29
Valuation detail: book value, forecast earnings multiple and market value怎么使用:直接 / 支持;一手验证:27;外部现实校验:21;专项深挖:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域20)|FY3/26 results release, special losses and narrative on the optimisation and fire;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 定向深挖(研究域32)|FY3/27 interim income statement: the special-items block inside a 'clean' half;直接证据 / 支持证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;直接证据 / 支持证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed;直接证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan;直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 外部现实(研究域27) / 外部现实(研究域29)|Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域21) / 定向深挖(研究域27)|Valuation detail: book value, forecast earnings multiple and market value
完整研究记录(核对用)
研究原文:Leakage to normalisation: below-the-line drag priced inside the band's width|The recurring below-the-line items are built into the normalised band rather than stripped out, which is why the band's centre sits at the plan's ordinary profit while its net-income translation stays thin; stripping leakage entirely would overstate earning power.
内部研究类型:CrossDomainMechanism
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):The recovery case leaves no room for leakage to continue at FY3/26 rates.
不确定性(原始记录):Full-year special-items total unknown.
F093|01|当前结论:条件齐备才有上行,两次披露就能见分晓
研究范围:开放研究+35项覆盖检查
写入正文:01|当前结论:条件齐备才有上行,两次披露就能见分晓11|催化剂都是有日期的交付检验
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(13项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接 / 支持;一手验证:35;反向验证:29
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan怎么使用:直接 / 支持;一手验证:30
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:直接 / 支持;反向验证:31、35;其他用途:反证
Valuation detail: book value, forecast earnings multiple and market value怎么使用:直接证据;一手验证:27;外部现实校验:21;专项深挖:27
FY3/27 interim results release, qualitative review of the coke business怎么使用:直接 / 支持;一手验证:04
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接 / 支持;一手验证:28、35;专项深挖:35
Timely-disclosure index for 3315, 2025-2026: the dated catalyst record怎么使用:直接 / 支持;一手验证:30;专项深挖:30
Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress怎么使用:直接 / 支持;一手验证:31;外部现实校验:05、15、30
Market framing of the interim print: progress rate and implied second half怎么使用:直接证据;一手验证:31;外部现实校验:28、35;专项深挖:31
FY3/27 interim results release, segment information怎么使用:支持证据;一手验证:02
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域30)|FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan;直接证据 / 支持证据 / 反证 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up;直接证据 / 一手证据(研究域27) / 外部现实(研究域21) / 定向深挖(研究域27)|Valuation detail: book value, forecast earnings multiple and market value;直接证据 / 支持证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results;直接证据 / 支持证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Timely-disclosure index for 3315, 2025-2026: the dated catalyst record;直接证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域05) / 外部现实(研究域15) / 外部现实(研究域30)|Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress;直接证据 / 一手证据(研究域31) / 外部现实(研究域28) / 外部现实(研究域35) / 定向深挖(研究域31)|Market framing of the interim print: progress rate and implied second half;支持证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information
完整研究记录(核对用)
研究原文:Thesis, falsifiers and dated catalysts|The thesis is a four-link chain (availability, gross margin, below-the-line leakage, lender patience) that must hold together for two more quarters; it is time-boxed to the February and May 2027 prints and the plan publication.
内部研究类型:ThesisFalsification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Within two disclosures the thesis will have materially more or less evidence than it has today.
不确定性(原始记录):Guidance is a commitment device; delivery prints are the evidence.
F094|01|当前结论:条件齐备才有上行,两次披露就能见分晓
研究范围:开放研究+35项覆盖检查
写入正文:01|当前结论:条件齐备才有上行,两次披露就能见分晓09|价格在为生存定价:资产说便宜,盈利说无物可估14|总分40.98/100,评级C,暂不建立仓位
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(24项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接 / 支持;一手验证:35;反向验证:29
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、25、29
FY3/26 consolidated results release, headline results and prior-year comparison怎么使用:直接 / 支持;一手验证:16;同业比较:06、12、16、28;其他用途:反证、历史
FY3/26 results release, consolidated cash-flow statement and indicators怎么使用:直接 / 支持;一手验证:17;同业比较:17、25;其他用途:历史
Market snapshot and margin-trading data for 3315怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26怎么使用:直接证据;外部现实校验:27、29
Valuation detail: book value, forecast earnings multiple and market value怎么使用:直接 / 支持;一手验证:27;外部现实校验:21;专项深挖:27
FY3/27 interim balance sheet: asset composition怎么使用:直接证据;一手验证:18;专项深挖:18
FY3/27 interim balance sheet: land and securities relative to equity怎么使用:直接 / 支持;一手验证:21;专项深挖:21
Historical downside prints: PBR at the 2020-2021 lows怎么使用:直接证据;一手验证:29;专项深挖:29;同业比较:27;其他用途:历史
Corporate turning points: IRCJ restructuring, 2009 renaming, exit from the Mitsui group怎么使用:直接证据;一手验证:33;专项深挖:33;同业比较:01、09、29;其他用途:历史
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:02
Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan怎么使用:直接 / 支持;一手验证:28;专项深挖:28
FY3/27 guidance table as published with the FY3/26 results怎么使用:直接 / 支持;一手验证:28、35;专项深挖:35
Employee data and petroleum/coal-products sector medians from securities-report data怎么使用:直接证据;外部现实校验:03、08
Petroleum and coal products sector panel: seven-company medians versus the company怎么使用:直接 / 支持;一手验证:08;外部现实校验:09、22;专项深挖:08
Compiled securities-report analysis: returns on capital, leverage gap and sales trend怎么使用:直接证据;一手验证:09、22;外部现实校验:02、18;专项深挖:09
FY3/26 results release, headline ratios: ROE and margins怎么使用:直接 / 支持;一手验证:22;专项深挖:22
Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress怎么使用:直接 / 支持;一手验证:31;外部现实校验:05、15、30
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:直接 / 支持;反向验证:31、35
Market framing of the interim print: progress rate and implied second half怎么使用:直接证据;一手验证:31;外部现实校验:28、35;专项深挖:31
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接证据;一手验证:25;专项深挖:25
FY3/26 results release, statement of changes in equity: the last dividend actually paid怎么使用:直接证据;一手验证:26;专项深挖:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 反证 / 一手证据(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域12) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28)|FY3/26 consolidated results release, headline results and prior-year comparison;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域17) / 历史/同业比较(研究域25)|FY3/26 results release, consolidated cash-flow statement and indicators;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|Market snapshot and margin-trading data for 3315;直接证据 / 外部现实(研究域27) / 外部现实(研究域29)|Fiscal-year price ranges, PBR at highs and lows, FY3/10-FY3/26;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域21) / 定向深挖(研究域27)|Valuation detail: book value, forecast earnings multiple and market value;直接证据 / 一手证据(研究域18) / 定向深挖(研究域18)|FY3/27 interim balance sheet: asset composition;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21)|FY3/27 interim balance sheet: land and securities relative to equity;直接证据 / 一手证据(研究域29) / 历史/同业比较(研究域27) / 定向深挖(研究域29)|Historical downside prints: PBR at the 2020-2021 lows;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域29) / 定向深挖(研究域33)|Corporate turning points: IRCJ restructuring, 2009 renaming, exit from the Mitsui group;直接证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Earnings anchors across the cycle: FY3/25 trough, FY3/26 repair, FY3/27 plan;直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 定向深挖(研究域35)|FY3/27 guidance table as published with the FY3/26 results;直接证据 / 外部现实(研究域03) / 外部现实(研究域08)|Employee data and petroleum/coal-products sector medians from securities-report data;直接证据 / 支持证据 / 一手证据(研究域08) / 外部现实(研究域09) / 外部现实(研究域22) / 定向深挖(研究域08)|Petroleum and coal products sector panel: seven-company medians versus the company;直接证据 / 一手证据(研究域09) / 一手证据(研究域22) / 外部现实(研究域02) / 外部现实(研究域18) / 定向深挖(研究域09)|Compiled securities-report analysis: returns on capital, leverage gap and sales trend;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域22)|FY3/26 results release, headline ratios: ROE and margins;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域05) / 外部现实(研究域15) / 外部现实(研究域30)|Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up;直接证据 / 一手证据(研究域31) / 外部现实(研究域28) / 外部现实(研究域35) / 定向深挖(研究域31)|Market framing of the interim print: progress rate and implied second half;直接证据 / 一手证据(研究域26)|FY3/26 results release, dividend record and profit-distribution policy;直接证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn;直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|FY3/26 results release, statement of changes in equity: the last dividend actually paid
完整研究记录(核对用)
研究原文:Valuation bridge: asset cover, thin normalised earnings, sub-cost-of-equity returns and lender-set expiry|Assets (land above market value) support survival; normalised earnings of roughly JPY 0-3 billion ordinary profit leave thin net income; even full plan delivery implies ROE of about 1.4%, below any plausible cost of equity; downside is a long drift rather than a floor. Re-rating therefore needs plan outperformance or capital-policy change, not asset cover alone.
内部研究类型:ValuationDownsideBridge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Asset cover is consolation; the return path is delivery converting the option into earnings.
不确定性(原始记录):No analyst consensus; land at book, not appraisal.
F095|13|下半年计划里到底假设了什么煤价、售价和销量?
研究范围:开放研究+35项覆盖检查
写入正文:13|下半年计划里到底假设了什么煤价、售价和销量?15|资料来源、日期与限制
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(26项,重复标签已合并)
FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance怎么使用:直接证据;一手验证:35;反向验证:29
FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up怎么使用:直接证据;反向验证:31、35
Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress怎么使用:直接证据;一手验证:31;外部现实校验:05、15、30
FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan怎么使用:直接证据;一手验证:30
Timely-disclosure index for 3315, 2025-2026: the dated catalyst record怎么使用:直接证据;一手验证:30;专项深挖:30
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:02
FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution怎么使用:直接证据;一手验证:12
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、25、29
FY3/26 results release: stakeholder support obtained for the optimisation plan怎么使用:直接证据;一手验证:07;外部现实校验:25;专项深挖:07
FY3/26 results release, financing cash-flow detail: short-term borrowing churn怎么使用:直接证据;一手验证:25;专项深挖:25
FY3/27 interim results release, qualitative review of fuel and resource recycling怎么使用:直接证据;一手验证:15;反向验证:10
FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption怎么使用:直接证据;一手验证:10;专项深挖:10
FY3/27 interim release: revenue-quality colour in the fuel segment怎么使用:直接证据;一手验证:15;专项深挖:15
FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision怎么使用:直接证据;一手验证:13;同业比较:32;其他用途:历史
FY3/27 interim release: environmental provision carried flat; coal-mining exit completed怎么使用:直接证据;一手验证:13;专项深挖:13
FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders怎么使用:直接证据;一手验证:03;专项深挖:03
Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI)怎么使用:直接证据;一手验证:24;外部现实校验:07
Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance怎么使用:直接证据;一手验证:07;外部现实校验:23
FY3/26 results release, group description: the customer and procurement counterparties怎么使用:直接证据;一手验证:05
FY3/27 interim release, financial-position narrative: working-capital movements怎么使用:直接证据;一手验证:19;专项深挖:19
FY3/27 interim balance sheet: asset composition怎么使用:直接证据;一手验证:18;专项深挖:18
FY3/27 interim income statement: the special-items block inside a 'clean' half怎么使用:直接证据;一手验证:32;反向验证:16;专项深挖:32
FY3/26 results release, coke demand: inquiries and sales-volume growth怎么使用:直接证据;一手验证:05;专项深挖:05;同业比较:11;其他用途:历史
FY3/26 results release: production recovery through disruption怎么使用:直接证据;一手验证:12;专项深挖:12
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域29)|FY3/27 interim results release, full-year forecast (unchanged) and comparison with the May interim guidance;直接证据 / 反证(研究域31) / 反证(研究域35)|FY3/27 interim release forecast table and FY3/26 release: implied second-half step-up;直接证据 / 一手证据(研究域31) / 外部现实(研究域05) / 外部现实(研究域15) / 外部现实(研究域30)|Kabutan news summary of the FY3/27 interim print: second-quarter standalone ordinary profit and plan progress;直接证据 / 一手证据(研究域30)|FY3/26 results release, outlook section: commitment to formulate and publish a three-year business plan;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Timely-disclosure index for 3315, 2025-2026: the dated catalyst record;直接证据 / 一手证据(研究域02)|FY3/27 interim results release, segment information;直接证据 / 一手证据(研究域04)|FY3/27 interim results release, qualitative review of the coke business;直接证据 / 一手证据(研究域12)|FY3/26 results release: how the coke loss narrowed - volume and fixed-cost dilution;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 一手证据(研究域29)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域07) / 外部现实(研究域25) / 定向深挖(研究域07)|FY3/26 results release: stakeholder support obtained for the optimisation plan;直接证据 / 一手证据(研究域25) / 定向深挖(研究域25)|FY3/26 results release, financing cash-flow detail: short-term borrowing churn;直接证据 / 一手证据(研究域15) / 反证(研究域10)|FY3/27 interim results release, qualitative review of fuel and resource recycling;直接证据 / 一手证据(研究域10) / 定向深挖(研究域10)|FY3/26 results release: the fuel segment's private-port and call-centre advantage in a disruption;直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|FY3/27 interim release: revenue-quality colour in the fuel segment;直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域32)|FY3/26 results release, income statement and balance sheet: environmental-countermeasure provision;直接证据 / 一手证据(研究域13) / 定向深挖(研究域13)|FY3/27 interim release: environmental provision carried flat; coal-mining exit completed;直接证据 / 一手证据(研究域03)|FY3/27 interim results release, qualitative review of integrated engineering;直接证据 / 一手证据(研究域03) / 定向深挖(研究域03)|FY3/27 interim release, product-level colour: Tea Meister Mill and machinery orders;直接证据 / 一手证据(研究域24) / 外部现实(研究域07)|Major shareholders from the FY3/26 securities report (EDINET data republished by gBizINFO, METI);直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|Report of the company's June 2026 clarification on major-shareholder influence and the tripartite alliance;直接证据 / 一手证据(研究域05)|FY3/26 results release, group description: the customer and procurement counterparties;直接证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/27 interim release, financial-position narrative: working-capital movements;直接证据 / 一手证据(研究域18) / 定向深挖(研究域18)|FY3/27 interim balance sheet: asset composition;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 定向深挖(研究域32)|FY3/27 interim income statement: the special-items block inside a 'clean' half;直接证据 / 一手证据(研究域05) / 历史/同业比较(研究域11) / 定向深挖(研究域05)|FY3/26 results release, coke demand: inquiries and sales-volume growth;直接证据 / 一手证据(研究域12) / 定向深挖(研究域12)|FY3/26 results release: production recovery through disruption
完整研究记录(核对用)
研究原文:Research Debt carried forward|Unresolved questions that no reasonable current public path closes, each tied to a dated future disclosure; highest-priority are the plan's embedded assumptions and the three-year plan's capital-policy content.
内部研究类型:ResearchDebtCluster
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):These unknowns qualify thesis confidence and normalised earnings but do not by themselves change the current falsifiable judgment.
不确定性(原始记录):All are future-disclosure dependent; none authorises further current search.
F096|10|价格从2007年的497日元一路下来,十年只在51到200日元之间来回
写入正文:10|价格从2007年的497日元一路下来,十年只在51到200日元之间来回10|价格比三条长期均线低15%到25%,下跌回合没有缩浅10|2026年3月放量冲到153日元,七个月后涨幅全部吐回10|纯价格状态定下之后,再看价格对公开事件的反应10|什么会确认,什么会推翻这个技术判断15|资料来源、日期与限制
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (dereference only)
内部研究类型:ProtectedTechnicalSynthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | a8a061955c98f0b058e7d272e6d194ee47beef46 |
| Delivery Commit SHA | a8a061955c98f0b058e7d272e6d194ee47beef46 |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | 925bb723-94e2-5ac2-bf2a-30798a9ce00b |
| Canonical Revision | 1 |