没有有息借款,自有资本比率67.3%,现金及存款276.00亿日元,约相当于市值的46%。销售下滑时毛利率仍在上升,分红比例已提高到约50%。
4832
JFEシステムズ株式会社(JFE Systems, Inc.)
JFEシステムズ株式会社(JFE Systems, Inc.,东证 Standard 市场,代码 4832)主营系统集成。公司为控股股东JFE钢铁及集团公司开发、运行和维护生产管理等核心系统。同时面向制造业客户提供供应链与数据平台、SAP/Microsoft ERP 构建、自有软件包和行业系统,以及云、网络和安全的搭建与运维。公司只报告一个信息服务分部,员工合并口径1,960人。
最近亮点:2026年10月28日公布的2027年3月期上半年财报:销售额264.66亿日元(下降9.5%),毛利率由22.8%升至26.0%,营业利润22.95亿日元(下降13.9%)。全年指引原样不变,订单下降8.3%,订单余额下降9.9%至225.40亿日元。
订单余额在下降,而2028年3月期计划要求合计销售再增加74亿日元。外部业务若补不上集团业务的缺口,销售管理费已经提前投入,利润会先受压。最大客户同时是持股65.16%的控股股东,需求、定价和治理由同一方决定。
结论:B 级,Kabugami 评分 61.22/100(Score V3.2),观察为主,不追高,研究把握一般。依据:下行有现金和50%分红比例托底,上行取决于外部业务补上集团业务下滑;预测倍数全部基于公司指引,没有分析师一致预期可对照,各业务单元的订单和毛利率也未披露。翻转:2027年1月下旬的第三季度财报若迫使下调指引、订单余额连续两个半期下降,或分红比例被削弱,判断下调;下半年约43亿日元营业利润得到确认且订单余额止跌,判断上调。 当前动作:观察为主,不追高。当前价格下方有现金和50%分红比例的支撑,但上行取决于外部业务能否补上集团业务的下滑。2027年1月下旬的第3季度决算是第一次检验:下半年需要约43亿日元营业利润,订单余额必须停止下降,指引不能下调。指引下调、订单余额连续两个半期下降或分红比例被削弱,就应降低判断。已有持仓可以继续持有,新增仓位宜等决算后的证据;仓位应偏小,因为流通股少,坏消息当天的下跌会很快。
报告目录
01|投资问题与当前结论
01.1|核心问题是外部业务补上集团缺口的速度,两个季度内就有第一个答案
判断先说在前面:这家公司现在的投资价值,取决于一道可以按日期检验的算术题。集团内最大的项目已经退场,外部客户业务要在多快的时间里把缺口补上。
JFE Systems 为JFE钢铁及集团运行钢铁厂的核心系统。2026年3月期销售额574.11亿日元,其中集团业务单元219.93亿日元,占38%。控股股东JFE钢铁持股65.16%,同时又是最大客户,所以需求、定价和治理出自同一方。市场眼下给出的价格是13.3倍预测市盈率(基于公司指引),1.64倍市净率。这个价格要为外部成长付多少钱,要看下面这条链条能不能走通。
我们的判断是:转型的方向有证据,转型的速度还没有证据。研究把握一般,原因在后面逐项交代。
01.2|2026年3月期的下滑来自一个项目收尾,外部业务全部在增长
2026年3月期销售额574.11亿日元,下降10.3%;营业利润63.46亿日元,下降16.4%。原因是JFE钢铁钢铁厂系统更新项目的主要开发阶段完成。这个项目曾把2025年3月期销售额推到639.72亿日元的纪录高位。JFE集团业务单元销售额由约303亿日元降到219.93亿日元,而所有面向外部客户的业务单元都在增长。
拉长到十年看,销售额从2020年3月期的465亿日元一路上升到2025年3月期的639.72亿日元,中间只有这一次中断,就是更新项目的上升与完成。同期集团业务单元占销售的比例从约三分之二降到38%。所以2026年3月期的下滑应当和此前的高峰放在同一个项目故事里读:这样看,近期利润既不代表外部业务在恶化,也不代表可以永久维持在高位。
这条因果链有一个自己无法控制的变数。下一个大型JFE钢铁项目何时启动、规模多大,没有披露,是母公司的决定。管理层只说正在加强争取未来大型项目的订单。
01.3|2027年3月期的指引是外部增长的主张,下半年要交出约43亿日元营业利润
全年指引自2026年4月起没有改变:销售额600亿日元(增长4.5%),营业利润66亿日元(增长4.0%),归属母公司利润43.8亿日元。其中集团业务单元再降17.7%至181.10亿日元,缺口要由外部业务填上:子公司及其他增长55.3%至85.65亿日元,ERP增长21.1%,行业解决方案增长17.6%,数字制造增长12.5%,基础设施增长7.3%,智能解决方案增长3.2%。
管理层自己的营业利润增减拆解说得很直接:更新项目退场拿走16亿日元左右,外部业务要增加27亿日元左右,有意提高的销售管理费又抵掉9亿日元左右,净增约2.5亿日元。这是一份外部增长的计划,不是成本压缩的计划。上半年营业利润只有22.95亿日元,按指引不变推算,下半年营业利润约43.05亿日元,比上年下半年的36.79亿日元高约17%。
这里有一处无法核实:各业务单元的订单没有披露,所以外部增长中有多少是真正的新需求,目前无法确认。
01.4|指引原样不变,管理层把可信度押在第三季度
上半年经常利润只达到全年计划的35.2%,公司引用的五年平均进度是45.8%,而这个五年窗口主要由更新项目年份构成,季节规律本来不同。管理层在这样的进度下不下调指引,等于把可信度押在下半年集中交付和外部订单上。
同一天公司还把中间分红从22日元调到24日元,把期末分红从48日元调到46日元,全年仍是70日元。分红的总额没有变,只是提前。这可以读作对下半年的信心,如果第三季度失望,也会反过来损害管理层的可信度,不过动机属于推断。
所以第三季度财报是双向信息:下调指引既说明利润比预期差,也说明管理层的判断错了;确认则支持“计划内空档”的看法。现在无法区分指引不变是因为看得见订单,还是自设的陷阱,要等2027年1月下旬。
01.5|反面证据:订单和订单余额都在下降,计划最难的一年还在后面
2027年3月期上半年订单259.52亿日元,下降8.3%;订单余额225.40亿日元,比上年同期的250.30亿日元下降9.9%,约相当于600亿日元销售指引的4.5个月。对一家下半年集中交付的系统集成商来说这个覆盖月数并不异常,但它是财报里唯一向坏方向移动的先行指标。公司在同一份材料里把市场需求描述为稳固,说明缺口很可能出在公司自己,也就是集团项目周期,但这一点没有被证实。
后果在2028年3月期:中期计划要求合计销售从602亿日元增加到674亿日元,一年多出74亿日元,集团业务单元只回升到约200亿日元,所以全部净增长再加约100亿日元的替代都要来自外部业务和子公司。这个目标现在建立在尚未接到的订单上,而已接订单在减少。
如果订单余额连续第二个半期下降,计划的算术在最后一年开始之前就已被打破,而销售管理费此时早已为招聘预先花出。上一期计划的目标被超额完成(销售额639.72亿日元对570亿日元,经常利润77亿日元对66亿日元),但那是靠已经结束的更新项目。
还有一层质量问题。最大的计划增长线是JFE ComService带动的子公司及其他,增长55.3%。其中有一部分可能只是集团工作从母公司业务单元转到子公司名下,并非新需求,财报没有拆分,所以真实的外部补缺速度很可能比表面慢。这只是推断,尚未检验。
02|公司本质与商业模式
02.1|公司按工时和软件包收费,一个分部之下有七个管理单元
JFE Systems 的收入是工程师的工时变成的项目费和服务费,没有存货,也没有靠授权收费的大宗业务。公司成立于1983年,前身是川崎制铁系统开发公司,在东证 Standard 市场上市;合并员工1,960人,其中母公司1,600人。
公司只报告一个信息服务分部,财报中的七个单元是管理用的划分。
2026年3月期销售额分别是:JFE集团219.93亿日元(为JFE钢铁及集团开发、运行、维护生产管理和关键业务系统);基础设施99.04亿日元(云、网络、虚拟化和安全的搭建与运维);行业解决方案78.95亿日元(面向大型制造业的业务系统);智能解决方案59.07亿日元(自有软件包,如电子表单、食品质量信息、成本管理、采购,以及合作方方案);子公司及其他55.15亿日元;ERP解决方案39.77亿日元(集成SAP和Microsoft ERP与公司自有模板,加BI和数据仓库);数字制造22.19亿日元(供应链管理方案与工业数据、AI平台)。
各单元加总与合并销售有会计调整差异。
公司的经济逻辑是把长期运行客户系统积累的知识,转成毛利率更高的软件包和服务收入。但开发、运维与软件包在收入中各占多少没有披露,单位毛利率也没有披露,所以“软件包拉高毛利率”只能从合并毛利率推断,无法逐项验证。
02.2|合并范围里没有第二台引擎,上市主体基本就是母公司
母公司单体2026年3月期销售额514.57亿日元,占合并574.11亿日元的九成;营业利润54.34亿日元,经常利润57.37亿日元,净利润40.12亿日元。合并报表比母公司单体多出约60亿日元销售和约9亿日元营业利润,主要来自JFE ComService和IAF Consulting(提供BI和管理指标可视化咨询,是数据平台战略的咨询入口)。
子公司这一条增长线是真实的,但规模小,且略有外流:少数股东权益12.31亿日元,约占合并净利润的3.7%。商誉只有2.69亿日元。合并报表仍是看这家公司的正确口径,子公司价值不应另外再算一次。子公司内部是否藏有休眠或非核心资产,研究没有单独核查。
02.3|长期因素是更新周期、软件包和轻资产,短期变数是订单与母公司态度
把当下的变化放在基本面貌之上看:这是一家靠人员和软件、几乎不占用重资产的系统集成商。客户的核心系统由它运行,替换成本来自业务知识和停机风险;软件包嵌在合规与结算流程里;有形固定资产投资一年只有1.89亿日元,软件投资11.49亿日元;资产负债表无借款。
变化得快的部分是半年一次的订单、2028年3月期的增减拆解,以及JFE控股对上市子公司的态度。项目完成、毛利率结构变化和销售管理费提前投入,是叠加在这个基础之上的增量,并不改写这个基础。对普通股东来说,下行由现金托底,每股收益的长期增长受资本配置和长期存在的控股折价限制,除非母公司采取行动,或外部增长超过集团业务的下滑。这个面貌的护城河和续约证据只有间接证据,单位经济和客户流失数据没有披露。
03|产品、客户与供应链
03.1|最大客户同时是持股65.16%的母公司
JFEスチール(JFE钢铁)持有65.16%股份,也是JFE集团业务单元(2026年3月期219.93亿日元,占销售的38%)背后的主客户。它的钢铁厂系统更新项目,既带动了2022至2025年3月期的上行,也在完成时造成了现在的下行。
母公司对钢铁厂系统的持续运维需求给这块业务提供一个不会归零的底部,但规模没有量化。向JFE钢铁本身的销售额以及集团内部价格的确定方式,在已查阅材料中都没有披露,需要等2027年3月期的有价证券报告。
03.2|其他JFE集团公司既是客户,也是小股东
JFE Plant Engineering(1.27%)、JFE Advantech(0.64%)和JFE Logistics(0.64%)既在集团业务单元里是客户,也出现在前十大股东中。它们的工作对钢铁周期有一定对冲作用,但定价和行为仍按关联方工作看待。集团业务单元内各类客户的拆分没有披露,所以这一对冲的大小无法估计。
03.3|外部需求被公司描述为稳固,公司自己的订单却没有跟上
公司把核心系统更新、云迁移、安全和数据利用描述为钢铁、汽车、化工等制造业的稳固需求,这也是补上集团缺口的主要动力。但2027年3月期上半年订单下降8.3%,落后于这一描述,说明缺口更可能出在公司自身的集团项目周期,而不是市场整体下滑。
这段需求判断全部来自公司自己的叙述,没有查阅第三方市场规模数据。市场增长是缓慢的顺风,计划需要的是每年夺得份额,靠市场增长本身不够。
03.4|ERP业务靠SAP和Microsoft两家平台,增长一部分押在它们的客户基础上
ERP解决方案以SAP和Microsoft的ERP平台为基础,加上公司自有模板和BI、数据仓库建设,计划增长21.1%至48.18亿日元。平台方为这条业务提供实施订单,公司不必自己去开发客户,代价是依赖它们的产品路线。如果平台方转向自己直接实施或以AI主导实施,这条增长线会受影响。联盟收入的拆分和平台方一侧的确认,都没有公开资料。
04|竞争格局与产业关系
04.1|在钢铁和制造业里有深度,规模上比不过NTT DATA
公司的位置是细分领域的深度,不是规模:它是日本第二大钢铁集团的在位系统公司,有获奖的旗舰迁移项目和有份额领先记录的软件包;离开钢铁,它只是制造业系统集成中的一家,对面有大规模的NTT DATA、直接可比的NS Solutions,以及客户自研、软件厂商直接实施和AI辅助开发这些替代选项。
切换成本来自运行客户核心系统的运营依赖,以及软件包嵌入合规流程,不来自合同。护城河一旦变弱,会先反映在订单和订单余额上,这正是现在向坏方向移动的指标。上一期计划里服务型业务销售达到64.9亿日元,高于50亿日元的目标。公司没有披露与竞争对手的胜率、客户流失或份额数据。
NTT DATA是日本最大的系统集成商,为企业和制造业数字化需求设定了交付能力和价格的参照。JFE Systems 的防线是钢铁和制造业运营深度,不是广度;一旦失去这个细分聚焦,失去的是护城河而不只是份额。双方在公开资料中没有胜率可比。
04.2|NS Solutions是直接可比公司,也是估值和治理的参照
NS Solutions(2327)是新日铁的附属系统公司,母公司持股63.44%,是上市钢铁集团系统公司中最直接的可比对象。两家公司估值倍数的差距,反映市场更信任哪一家母公司的意图。这里只做结构性对照,所用的数据来自研究此前对2327的工作,没有在本次重新核对倍数,因此不据此给出具体估值结论。
04.3|钢铁厂的投资周期决定集团业务的下一次大订单
钢铁企业周期性重建核心系统,会产生多年的系统集成项目,刚完成的更新项目就是例子。管理层表示正在加强争取下一批大型项目的订单,但下一个JFE钢铁项目的时间和规模没有披露。这是最大的变数之一:它既可以让2028年3月期的增长变得容易,也可以让它几乎不可能。买在低谷,有一部分是在买母公司的日历。
04.4|生成式AI可能改变按工时计费的基础,现有披露无法衡量
管理层把生成式AI用在自有产品、服务和交付流程里,并在建立子公司和AI用例的实施体制。但没有披露任何生产率或定价数据。如果AI压缩可计费工时的速度快于软件包和平台收入的增长,1,960人的人员基础会变成固定成本负担;反之则是经营杠杆。
这条因果链放在整份研究里看:销售管理费提前投入招聘(母公司人数由1,554人增至1,600人),把今天的利润压低,同时也是明天能交付的前提;AI交付效率决定按工时计费的经济是否持续,订单余额是检验提前投入是否转化的测试。目前哪些业务线暴露于AI、被什么替代,都没有数据。
04.5|监管和宏观是顺风或二阶影响,没有发现重大依赖
电子账簿保存法和电子发票制度,对公司的软件包业务是需求支撑,不是风险;没有发现牌照、关税或补贴上的重要依赖。宏观传导渠道狭窄且在国内:企业信息化预算、工程师工资上涨,以及存款利息收入对应的短期利率。日元和商品价格只通过客户间接影响,属于二阶。2026年春季工资协商的结果尚未体现在材料中。
05|护城河判断
05.1|优势在长期因素里,弱点在半年一变的订单里
支撑护城河的长期因素有五项:日本制造业核心系统的更新周期;钢铁行业的投资节奏(集团业务的底部是周期,不是悬崖,但时点由母公司决定);嵌在合规与结算流程里的软件包;约2亿步旧系统代码迁移所积累的钢铁运营知识,这类隐性知识很难靠外部招聘复制;以及67%自有资本比率的资产负债表。
变化得快的因素是每半年的订单、2028年3月期的增减拆解和JFE控股对上市子公司的立场。结构上的判断是:它在长期因素上耐久,在短期变数上脆弱,权益投资的理由是长期因素能比短期变数活得更久。但护城河的证据是旁证:没有客户流失率或续约率披露,也没有对比数据。
05.2|更新项目既是失去的收入,也是对外销售的凭证
约2亿步旧的钢铁厂代码被迁移到开放云环境,JFE钢铁因此在2026年7月24日获得IT Japan Award 2026大奖,公司的贡献被明确写入。这和数字制造、ERP业务向其他制造业客户推销的是同一种能力。软件包也有证据:FiBridge连续19年占国内同类产品份额第一(富士Chimera研究所的调查),DataDelivery取得电子账簿保存要求的全范围JIIMA认证,J-CCOREs增加了与SAP的联动功能。
奖项是凭证,不是利润。这些份额数据是公司引用的第三方调查,没有独立的生产率基准,凭证转化为外部订单的情况尚未观察到,也没有披露。
06|财务质量与现金流
06.1|销售下滑时毛利率反而上升,来自收入结构变化,与涨价无关
毛利率从2025年3月期的23.6%升至2026年3月期的25.1%,2027年3月期上半年再升至26.0%(上年同期22.8%)。2026年3月期销售成本减少59.01亿日元,销售额只减少65.61亿日元:更新项目附带的转包和项目人工几乎与收入同步退出,留下的软件包、ERP和基础设施业务毛利率更高。上半年毛利润增长3.1%,销售额却下降9.5%。
这是结构变化,不是价格变化,只有外部业务占比继续上升时才成立。下一轮收入回升时,同样销售额带来的利润应当更高,这是正常化盈利范围偏高的依据。这个判断没有单位毛利率可验证,季度走势(第一季度营业利润下降51.5%,随后7至9月单季上升约47%、营业利润率10.9%)也是推断。
06.2|上半年毛利润增长3.1%,营业利润仍下降13.9%,原因是销售管理费提前增加
2027年3月期上半年:销售额264.66亿日元(下降9.5%),毛利润68.82亿日元。销售管理费增加14.5%至45.87亿日元,营业利润22.95亿日元(下降13.9%),经常利润下降11.5%,归属母公司利润15.28亿日元(下降13.4%)。
公司的增减拆解中,更新项目退场的影响0.30亿日元左右,被集团业务内项目构成改善带来的0.42亿日元左右抵掉。外部业务增加约0.66亿日元。
销售管理费增加拿走约0.56亿日元和0.33亿日元,营业利润从26.7亿日元降到23.0亿日元左右。
销售管理费是管理层选择的成本曲线:2025年3月期74.95亿日元,2026年3月期80.78亿日元(销售额下降10.3%的年份里增加7.8%),计划2027年3月期89.60亿日元(增加10.9%)。两年内每年增加约15亿日元,用在研发、内部信息系统、为增长业务招聘和培训、战略销售费用上。营业利润率压缩到11%左右,是政策选择,不是价格或工资冲击。
提前投入造成了经营杠杆:订单回补,它会放大利润;订单不回,它就变成固定成本问题。2027年度工资谈判和人员利用率,目前看不到。
06.3|2026年3月期现金流最好,是项目收尾放出来的现金
2026年3月期营业现金流84.48亿日元,净利润只有44.29亿日元。差距的主要来源是更新项目收尾:应收账款回收(现金流量表29.56亿日元,资产负债表约减少25亿日元),加上折旧27.70亿日元。有形固定资产投资仅1.89亿日元,软件投资11.49亿日元,所以业务是轻资产的。
这个现金流和利润下降来自同一个项目周期:项目量下降时,系统集成商的资产负债表会把现金释放出来。随着新订单以早期阶段的外部工作填满订单簿,现金转化会机械地变差。此前研究曾得出“按正常化自由现金流,分红约有三倍覆盖”的粗略结论,但这个口径包含了应收款回收,又没有计入11.36亿日元租赁还款,保守口径下覆盖更薄。2027年3月期上半年的现金流量表还没有打开,应收账款账龄和客户集中度也没有披露;正常化自由现金流是研究计算,租赁处理口径不统一。
06.4|没有借款,现金占市值46%,但大半已转成定期存款
2026年3月期末自有资本比率67.3%(2026年9月为67.4%),现金及存款276.00亿日元(9月末269.97亿日元),负债合计160.27亿日元,没有借款。类似债务的项目只有租赁负债28.82亿日元和退休给付负债38.06亿日元。按9月末口径,这些现金约相当于581亿日元市值的46%。
2026年3月期投资现金流出158.49亿日元,并不是资本开支:141.50亿日元是现金净转入三个月以上的定期存款,所以现金及现金等价物从240.53亿日元降到134.50亿日元,而资产负债表现金反而上升。利息收入从0.47亿日元升至1.07亿日元。
这条链的后果是:现金让利润波动变成时间问题,而不是偿债问题,也让经常利润略高于营业利润;同时同一笔现金拉低净资产收益率,并让机械的现金流指标失真。定期存款的期限和收益率没有披露;估值里的企业价值把存款全部抵掉,没有扣除租赁和退休给付,上市主体能否随时调用子公司现金,也没有单独核查。
06.5|三处会计表述会误导机械筛选,修正后的图像更平常
账目总体简单干净:采用日本会计准则,研发费用化,没有稀释性证券,商誉2.69亿日元,没有持续经营附注。但有三处会让不细看的筛选出错:一是2.81亿日元的未上市股票减值;二是定期存款调整使投资现金流(负158.49亿日元)失真;三是2026年3月期营业现金流被应收款回收抬高。
三项都不激进,修正之后得到的图像更平常,不会更差。有价证券报告里的关联方、税务和主要客户附注尚未打开。
06.6|未上市股票减值2.81亿日元,是账目里唯一不透明的项目
有价证券账面只有17.35亿日元(占总资产3.3%),含未实现收益储备10.16亿日元,不构成隐含资产故事;净资产的资产支撑是定期存款和307.73亿日元留存收益。但2026年3月期计提的2.81亿日元未上市股票减值说明,一个材料里从未讨论的未上市投资组合,仍然可能带来损失。剩下的未上市持仓是什么、成本多少、对类似风险投资的治理如何,没有披露。规模不大,但是账目里唯一真正不透明的一项,也没有披露的闲置地产。
07|股东、董事与治理
07.1|控制权绝对,流通股很薄,没有外部力量能推动资本政策
JFE钢铁持股65.16%,员工持股会6.65%,JFE Plant Engineering 1.27%,JFE Advantech和JFE Logistics各0.64%,集团系持股合计约占股东名册的四分之三。最大的外部股东是一个名义持有人(1.17%),光通信相关的投资合伙企业0.93%,没有外部股东达到1.2%。所以没有机构力量能够就资本政策或母子关系向董事会施压,也没有浮动持股带来的治理压力。
好处是没有稀释:注册资本五年来都是13.91亿日元,上市以来没有股权融资,股份数只因2021年和2025年的两次1拆2而变化,也没有稀释性证券。2026年3月之后的大额持股报告没有核查,独立董事构成也没有取得。
07.2|客户和控股股东是同一方,需求风险和治理风险合在一起
钢铁企业下行会削减集团信息系统预算(这部分占销售的38%),同时压低股价情绪,而公司没有披露集团工作的合同下限。最大客户又是控股股东,所以价格、订单量和上市子公司安排由同一方决定;少数股东只能接受结果。
JFEホールディングス(JFE控股)是JFE钢铁的最终母公司,上市子公司结构保留、收紧还是解除,是在这一层决定,不是JFE Systems 董事会能决定的。目前没有任何表态。最大的潜在催化因素,母公司减持或增加流通股,完全由它们选择。
07.3|约四分之一的流通股,使价格在财报日前后分步调整
股东名册上实际流通的股份约占四分之一,日常成交量只有几万股。价格发现因此集中在公布日前后;预期在财报当天打开,之后缓慢收敛。这一层是股东名册方面对价格如何重估的解释,只作为背景提供,不是技术证据,价格结构本身的判断见技术结构一章。
这个因果链的股东后果是:折价在没有母公司动作时具有结构上的持续性,也没有任何市场机制迫使公司增加流通、回购或处理资产。这只是推断,没有分析师一致预期和资金流向数据可对照。
08|资本政策
08.1|分红已写成政策,约50%的比例没有下限,也没有回购
分红比例从2025年3月期的35.2%提高到2026年3月期的50.1%(每股68日元,中间28日元、期末40日元),2027年3月期计划50.2%(每股70日元)。2026年3月期每股分红增加11.5%,每股收益却下降21.6%:分红已由剩余变成与利润挂钩的固定份额。以1,851日元计算,预测股息率约3.8%。
政策本身有限制:没有净资产分红率下限,没有逐年提高的承诺,也没有回购框架;约50%是中期计划期内的目标。库存股只有2,325股,2026年3月期的购买只花了10.8万日元。2028年3月期之后的政策,要看2027年的新计划:50%能否成为长期规则,是否出现下限或逐年提高,还是回到与利润完全挂钩。有人可能期待回购,但没有任何回购框架。
08.2|中间分红上调、期末下调,全年不变,是时间安排上的信号
2026年10月28日,中间分红由22日元提高到24日元,期末由48日元降到46日元,全年仍是70日元。这是在上半年利润下降时对下半年交付信心的表态,没有增加股东价值,只是一种信息上的承诺;若第三季度失望,会损伤管理层可信度。动机属于推断。
08.3|净资产收益率下降一半来自分母,50%分红只是下限
净资产收益率从17.5%降到12.5%,预测11.9%。一部分原因是分母:2026年3月期净资产增加24.61亿日元,因为即使分红50%,仍留存一半利润;留存的现金按存款利率计入回报。所以分红提高在一定程度上是在守住净资产收益率,50%是最低可信的设定,不算慷慨,这是推断。
每个闲置的年份,存款大约增加22亿日元。公司在已查阅材料里没有设净资产收益率目标,董事会是否正式评估过回购、若否决依据是什么,也不清楚。市净率在1.6倍附近,流通股约四分之一的条件下,这个问题没有答案。每股价值的复利,因此受资本配置限制,而不是受经营限制。
09|估值与安全边际
09.1|估值简报:13.3倍预测市盈率,1.64倍市净率,现金约占市值46%
估值简报(价格截至2026年11月6日收盘): 股价:1,851日元;总市值:581.44亿日元(发行股份31,412,000股,库存股可忽略)。 预测市盈率(PER):13.3倍,基于公司2027年3月期指引每股收益139.45日元,不是一致预期。 实绩市净率(PBR):1.64倍,基于2026年3月期末每股净资产1,129.19日元;第三方数据显示1.62倍,可能是账面价值日期不同,未核实。 净资产收益率(ROE):12.5%(2026年3月期实绩);公司预测11.9%。 预测股息率:3.78%,基于公司预计年度分红70日元。 EV/EBITDA:3.4倍。EV 311.5亿日元=总市值减去2026年9月30日净现金270.0亿日元;EBITDA 91.2亿日元=2026年3月期营业利润加折旧(含租赁和软件摊销)。三个口径时点不同。
把存款全部扣掉后,上市主体的经营业务约值311亿日元,相当于预测营业利润的4.7倍。企业价值没有扣除租赁和退休给付负债,也没有加上少数股东权益;EBITDA用的是低谷年的营业利润;预测倍数全部依赖公司指引,没有查阅分析师一致预期。2026年3月期的市净率区间为1.14倍到2.19倍,说明市场在最近一年内给过更高的估值。
09.2|下行由资产托底,上行靠计划兑现,两端都可以按日期检验
以1,851日元计算,市场为一家无借款、存款覆盖约46%价格的公司付13.3倍预测盈利、约1.6倍账面。下行是资产锚定的:时间可能很长,但资产没有受损;上行是执行算术:交付674亿日元销售并保持约12%的净资产收益率,或出现治理事件。两端都不需要相信一个故事,都能用1月的第三季度财报和4月的全年财报检验。
风险是时间:计划兑现得慢,估值就可能回到扣除现金后的盈利倍数。现金也不等于母公司可调用的价值,没有政策要求分配。过去一年的高估值(2026年1月高点2,469日元)说明当前价格不算明显便宜。估值不能依据低谷每股收益去看,也不能依据高峰每股收益去看;比较诚实的锚是一个范围,每个季度检验一次。
09.3|正常化营业利润65亿至75亿日元,每股收益140至160日元(研究估算)
以更新周期的各年为参照:高峰2025年3月期营业利润75.89亿日元,退场年63.46亿日元,2027年3月期预测66亿日元,毛利率结构性升至25.1%至26.0%(此前23.6%)。研究估算当前范围内的周期中段营业利润为65亿至75亿日元,按现有股份数每股收益约140至160日元;外部业务交付后,向计划最后一年的水平上升。这是研究估算,不是公司指引,成立前提是外部业务贡献销量,而各业务单元毛利率没有披露。
09.4|下行有四层保护,最坏情形是多年的估值倍数压缩
第一层是资产负债表:自有资本比率67%,无借款,存款约占市值46%。第二层是约3.8%的股息率,50%的分红比例在利润下降的年份没有削减。第三层是母公司持续运行钢铁厂系统所带来的需求底部,但没有合同。第四层是2023年以后形成的价格平台。
对应的反面是:流通股薄,对好坏两个方向都放大;计划落空时盈利倍数会向扣除现金后的资产价值压缩;分红没有下限,合同下限也没有;价格平台可能被打破。现实的最坏情形是多年的倍数压缩,向存款价值靠拢,幅度有限,可以持续监测。
10|Kabugami 技术结构
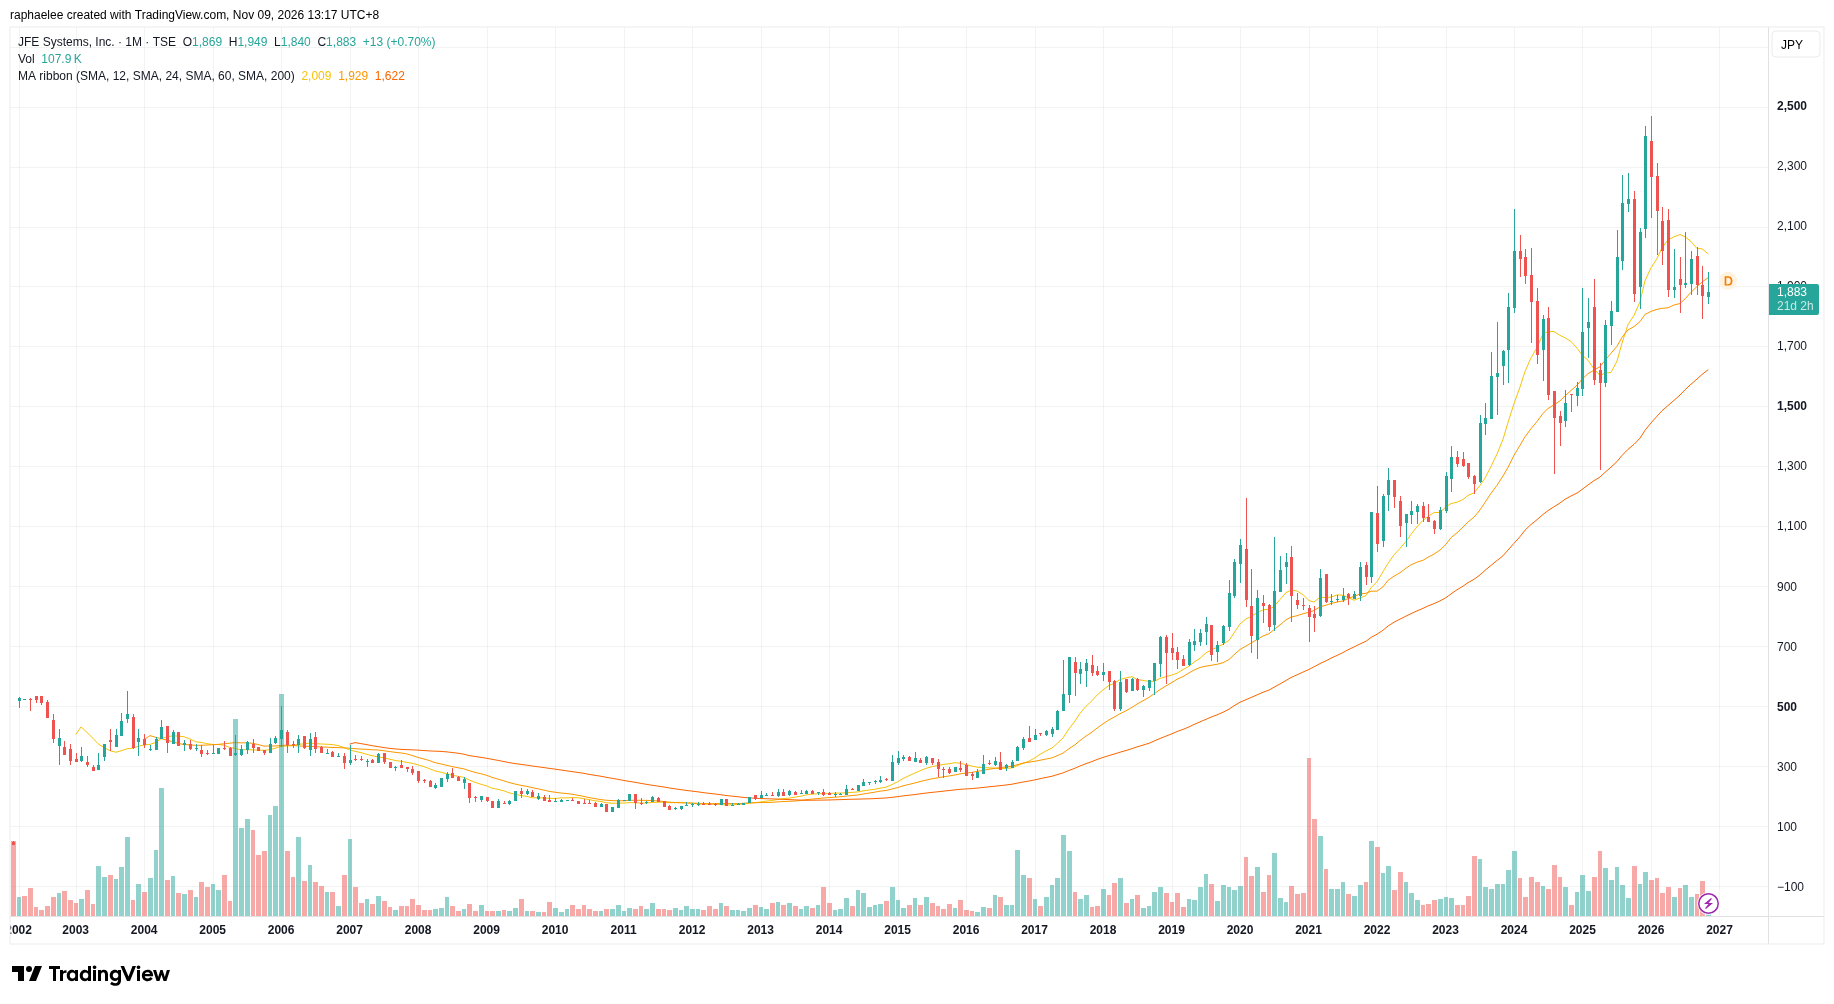
10.1|月线有两段人生:2001至2022年长期低价,2023年起才抬到1,000日元以上
这一章只依据价格本身。数据是308根月线,2001年3月至2026年10月,已按2021年4月和2025年4月两次1拆2调整;11月的读数用2026年11月6日的收盘价1,851日元,11月月线尚未走完,不作为已确认依据。
2001年12月有一个3,450日元的开盘期标价,成交只有2,500股,不是有效交易价位,不计入判断。此后股价一路走低,2010年11月见到史上最低的146日元,2011至2019年在250至900日元之间长期休眠。2021年3月冲到1,731日元,到2022年12月已完全回落到584日元,这是一次完整回吐的失败冲高。全部月收盘价里,61%低于500日元,80%低于1,000日元。
所以现在这个价位只有三年历史,对面是二十多年的低价。当前价格在全部历史收盘价区间里处在约第54百分位,在2015年以来的区间里处在约第76百分位:以近年的窗口看,股价已经站在自身历史的上段,“便宜”是相对历史说的,不是相对近年。
10.2|2023至2025年台阶式上行带量,2026年1月的新高只高出一点
2023年起股价放量上行:月成交量从15万至25万股升到50万至70万股,约增加两倍,依次站上1,000日元(2023年)、1,500日元(2024年)和2,000日元(2025年),每一级都整理了数个季度才走下一级。最深的一次回撤在2025年10月:开盘2,192日元,最低1,848日元,收盘1,878日元,12月已收复到收盘2,401日元,两个月收复。
与2021年那次冲高比,这一轮上行有成交量跟着放大,回撤也浅。但2026年1月的高点2,469日元只比前高略高,之后全年在1,792至2,313日元之间运行,下跌过程成交量缩小而不是放大(2026年10月约28万股)。缩量下跌更像是在消化,不像出货,但这个判断还没有被一次坏消息落在平台上的考验证实。2026年的回落已经持续九个月,尚未收复。
过去的失败冲高留下了位置记忆:146至252日元(2010至2015年的底部),584至900日元(2020至2022年的失败区),以及2,469日元(2026年1月高点)。1,790至1,850日元一带正在形成第四个记忆位置。
10.3|现在是平台整理,状态中性,价格围着24个月均线转
这里把“平台整理”定义为:价格在一个区间内反复整理、跌到下沿有买盘接住,但上沿尚未突破,也尚未跌破下沿。全章只用这个说法。
2026年11月6日收盘1,851日元,比2026年1月高点低21%左右至25%。24个月均线1,918日元左右,价格围着它来回;12个月均线约2,032日元,在价格上方;60个月均线约1,608日元,仍在上升。月线波动幅度在收窄:1至2月在1,985至2,469日元,10至11月收缩到1,851至1,940日元。
平台下沿在1,790至1,850日元:2026年10月盘中最低1,792日元,11月6日在单日下跌3.89%、成交4.2万股之后收在1,851日元,两次都守住了。上方压力在2,469日元(1月高点)和12个月均线;下方若破位,依次是1,287至1,300日元(2025年4月低点),其后是584至900日元。
冲击被较快吸收:10月29日单日下跌6.97%,随后在1,851至1,884日元企稳;2025年10月的空档两个月收复。但上涨很慢,2023至2025年用三年涨约150%,下跌则常在单日跳空完成。内在矛盾是:平台已有三年和带量上行,但从未经过一次指引下调或大盘冲击的检验,而2021年那次从1,731日元完全回落的先例仍在。平台收窄在下沿守住时偏中性,价格一旦破位,方向会很快出来。
10.4|价格结构的变化早于后来被公开确认的基本面变化,第三季度财报是两条线共同的检验点
在纯价格状态确定之后再看公开事件:2026年10月28日公布上半年财报,第二季度单季营业利润同比增长约47%、营业利润率10.9%,但次日股价单日下跌6.97%,之后只是企稳在1,851至1,884日元,没有走高。市场对这次业绩的反应是收住下跌,没有留下更高的价格区域。
时序上,价格在2026年1月见顶,随后回落九个月,早于公司以公开财报确认外部业务补缺的时点。这只描述价格与公开信息的先后关系,不表示市场提前知道未公开信息。如果2027年1月下旬的第三季度财报确认下半年的计划,价格与基本面可能从较低位置重新同步;如果迫使下调指引,平台下沿1,790日元的检验会和财报同时到来。
这个检验点对两条线是共同的,但互不改写:基本面的确认不能改写一个尚未确认的价格状态,价格状态也证明不了基本面判断。另外,股东名册里约四分之一的流通股和只有几万股的日成交量,只能解释价格为什么在财报日前后分步调整,作为背景,不构成技术证据。
10.5|站稳还是破位:三个确认信号和三个失效信号
本章的核心问题是:1,790至1,850日元的平台,是2023至2025年上行后新形成的站稳位置,还是一次失败冲高的下沿、价格将回到旧区间。目前的技术状态偏中性,两种可能都还没有被价格证实。
确认信号有三个:月线收盘重新站上12个月均线(约2,032日元)且月成交量超过约50万股;平台下沿1,790至1,850日元在第三季度财报(2027年1月下旬)中第三次守住,尤其是财报只是符合预期时;月线收盘站上2,200日元,这是重新夺回1月高点的第一步。
失效信号有三个:月线收盘跌破1,790日元(2026年低点),平台第一次真实考验失败;月线收盘跌破仍在上升的60个月均线(约1,608日元),2023年后的整体形态被放弃;价格回到1,287至1,300日元(2025年4月低点),上行最后一段被完全回吐,2021年的形态重现。
由于股票成交薄,对这个状态更合适的应对是靠仓位,不是靠择时。观察指标没有额外的判断。
11|风险与催化剂
11.1|最大的风险来自母公司的周期,最大的变数是下一个大项目何时到来
风险排序如下。第一,母公司周期:JFE钢铁的下行会直接削减集团信息系统预算,这部分占销售的38%,没有披露合同下限;母公司对运维的持续需求提供底部,规模没有量化;向JFE钢铁的销售额和集团内部定价基准也没有披露。第二,钢铁厂系统投资的节奏:下一个大型项目的时间和规模是母公司决定,既可以让2028年3月期的增长变得容易,也可以让它几乎不可能。第三,订单和订单余额连续下降。
监管和宏观只是次要影响:电子账簿保存法和电子发票是需求支撑;国内信息化预算、工程师工资上涨和存款利率是主要的宏观传导,日元和商品价格是二阶影响。
11.2|催化剂是日历上的三个检验,加上两件没有日期的事
确定会发生、内容未知的催化剂有三个:2027年1月下旬第三季度财报,检验九个月进度是否支撑下半年约43亿日元营业利润,第三季度是否呈现季节性回升,或者指引被下调;2027年4月的全年财报,决定最后一年计划的讨论和期末分红;2027年发布的新中期计划,决定资本政策。第三季度财报是否披露业务单元订单拆分,目前不清楚。
没有日期的事件:母公司减持或增加流通股,或公布下一个JFE钢铁大型项目。前者是最大的治理催化剂,完全由JFE控股决定,尚无任何表态。
12|反常识发现
2026年3月期是利润最差的一年,却同时出现了三个看上去矛盾的数字:营业现金流84.48亿日元,比净利润44.29亿日元高出近一倍;毛利率25.1%,高于上一年的23.6%;每股分红增加11.5%,每股收益却下降21.6%。
三者来自同一个原因。项目收尾,转包随收入退出,毛利率因构成变化上升;应收账款收回,现金流被抬高;分红比例固定在50%,分红就脱离了每股收益的下降。而净资产收益率从17.5%降到12.5%,一半来自利润,一半来自留存现金的堆积。
机械的筛选会在两个方向误读:按低谷每股收益算,估值显得贵;按2026年3月期现金流算,分红覆盖显得厚。两种读法都需要修正,研究的处理是用一个正常化范围去看,并逐季检验。
13|下一次值得跟踪什么
13.1|第三季度财报:九个月进度是否支撑下半年约43亿日元营业利润
为什么重要:这是指引可信度和“计划内空档”判断的第一次硬检验。上半年经常利润进度只有35.2%,下半年要交出约43亿日元营业利润,比上年下半年高约17%。
要回答的问题:2027年1月下旬的第三季度财报,九个月进度能否确认这个下半年集中的预测,第三季度是否呈现季节性回升,还是指引被下调。反向答案会同时伤害利润预期和管理层的可信度。需要的证据是第三季度财报本身,以及是否有业务单元订单披露。
13.2|2028年3月期的674亿日元由哪些业务单元组成,是否假设有一个已命名的大项目
为什么重要:这是未解问题里优先级最高的一项。计划要求合计销售从602亿日元增加到674亿日元,目前建立在尚未接到的订单上。
问题是:增长由哪些单元构成,已看得见的订单有多少,集团业务单元回到约200亿日元,是否假设了JFE钢铁一个有名字的下一个大项目。若答案是没有已知订单且假设大项目,计划的可行性和估值都要重估;若答案是外部订单已覆盖大部分,则判断上调。解决问题的证据是第三季度和全年财报的订单披露,以及2027年的新中期计划。
13.3|订单余额减少的2,490万日元……实际是24.90亿日元,集中在哪个单元
为什么重要:订单余额由250.30亿日元降到225.40亿日元,减少24.90亿日元,是财报里唯一向坏方向变动的先行指标,且已经和计划最难的一年并行。
问题是:这笔减少集中在JFE集团单元(预期之内),还是扩散到了外部单元(需求警告)。目前没有业务单元的订单和余额披露,也没有证据区分。解决它需要业务单元的订单披露;若第二个半期余额继续下降,则同时削弱计划和护城河的判断。
13.4|JFE ComService自己赚多少,增长55.3%里有多少是母公司转来的工作
为什么重要:这是计划中最大的单条增长线,如果其中一部分是集团工作换了名义,外部补缺就比表面慢,2028年3月期的增减拆解更难,同时少数股东会拿走这条增长线约3.7%的利润。
要回答的问题:ComService独立盈利多少,多少增长来自母公司业务单元转来的工作。这是推断,尚未检验,也没有独立披露。解决它需要子公司单独披露或母公司对转移工作的说明。
13.5|向JFE钢铁的销售额是多少,集团内部价格怎样确定
为什么重要:最大的单一客户同时是控股股东,价格条件可能在母公司与少数股东之间转移价值,且没有披露合同下限。
问题是:2027年3月期有价证券报告的关联方和主要客户附注中,向JFE钢铁本身的销售额是多少,集团内部合同价格怎样确定和参照。证据在2027年6月的有价证券报告。
13.6|276亿日元存款的期限和收益是多少,董事会是否评估过回购,50%分红能否延续
为什么重要:每股价值的复利受资本配置限制,闲置的年份存款大约增加22亿日元,净资产收益率被拉低。
三个问题:存款的期限结构和收益率是什么;董事会是否正式评估过回购,若否决依据是什么(市净率约1.6倍、流通股约四分之一);2027年新计划之后,50%分红是否成为长期政策,是否加入净资产分红率下限或逐年提高,还是回到与利润完全挂钩。证据是2027年的新中期计划和有价证券报告。
13.7|剩余未上市证券是什么,AI会怎样改变计费基础,价格平台能否守住第三季度
未上市证券:为什么重要:2.81亿日元减值说明这是一块材料里从不讨论的风险,规模小但治理上不透明。问题是减值之后剩余组合的持仓、成本,以及对类似风险投资的治理。
生成式AI:为什么重要:这是按工时计费模型面对的新竞争变量,现有披露无法量化。问题是AI压缩可计费工时时,哪些业务线暴露,由什么替代。
价格一侧:为什么重要:这是基本面和价格的共同检验点。问题是价格能否在第三季度财报中守住1,790至1,850日元,还是向60个月均线(约1,608日元)破位,后者意味着市场不再相信计划的增减拆解。股东名册只解释价格如何分步调整,不是技术证据,技术状态以第10章为准。
13.8|什么会推翻这个判断
判断建立在四条可观察的条件上,任何一条出现都会改变结论:第三季度财报迫使下调指引,说明“计划内空档”判断有误;订单余额连续第二个半期下降,说明外部订单补缺没有发生,2028年3月期的增减拆解成为虚构;分红规则在下一期计划或2027年3月期期末分红决定中被稀释,说明回报合同被打破;价格月线收盘跌破2026年低点,随后又跌破60个月均线(约1,610日元),这是价格一侧的推翻条件。
基本面和价格任何一侧单独失守,只会削弱判断,不会单独推翻它。价格一侧的条件依赖于一个流通很薄的价格记录。
14|Kabugami 评分卡
14.1|总分61.22/100,B级,观察为主、不追高
Kabugami 评分(Score V3.2)61.22/100,评级B。操作结论:观察为主,不追高。
当前价格下方有现金和50%分红比例的支撑,但上行取决于外部业务能否补上集团业务的下滑。2027年1月下旬的第三季度财报是第一次检验:下半年需要约43亿日元营业利润,订单余额必须止跌,指引不能下调。
指引下调、订单余额连续两个半期下降或分红比例被削弱,就应降低判断。已有持仓可以继续持有,新增仓位宜等财报后的证据;仓位应偏小,因为流通股少,坏消息当天的下跌来得快。
评分把没有分析师一致预期、各业务单元订单和毛利率、集团内部定价和下一个母公司项目时间这些未知,都放在判断强度里,没有按固定比例扣分;订单和余额的单元数据出来后,评分可以上调也可以下调。
14.2|财务、盈利和商业结构四个模块
财务韧性与下行防御 11.05/13:无借款,自有资本比率67.3%,现金及存款276.00亿日元,偿债和再融资风险基本不存在;现金能否被上市主体自由调用没有政策保证。
竞争优势与结构耐久性 8.68/14:钢铁运营知识、约2亿步迁移经验和软件包份额领先提供旁证,但上半年订单下降8.3%,客户流失和胜率没有披露。
盈利质量、现金转化与资本效率 11.05/17:毛利率在销售下滑中升至25.1%和26.0%,但销售管理费提前增加,2026年3月期现金流被应收款回收抬高,闲置现金拉低净资产收益率至12.5%。
商业结构、产品、客户与关键依赖 6.05/11:外部业务全部增长,但集团业务占38%,最大客户即控股股东,最大计划增长线可能含有转移的集团工作,订单数据缺位。
14.3|估值、资本政策、治理和技术四个模块
估值与安全边际 9.3/15:13.3倍预测市盈率、1.64倍市净率,现金约占市值46%,下行由资产托底;没有一致预期,过去一年有过更高估值,不算明显低估。
资本配置与股东回报 5.0/10:分红比例50.1%,2027年3月期计划50.2%,但没有回购、没有下限,现金每年约增加22亿日元闲置。
治理、所有权与管理层 2.94/7:JFE钢铁持股65.16%,集团系约四分之三,没有外部力量,没有稀释;优点是账目简单,缺点是少数股东是控股股东耐心的价格接受者。
Kabugami 技术结构 7.15/13:价格处于平台整理,状态中性:2023至2025年带量上行已削弱旧的低位状态,但平台尚未经过指引下调或大盘冲击的检验,不能算作确立。
14.4|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 11.05 | 公司没有有息借款,2026年3月期末自有资本比率67.3%,现金及存款276亿日元,负债合计约160亿日元。有息债务之外只有约29亿日元租赁负债和约38亿日元退休给付负债。业务轻资产,有形固定资产投资仅1.89亿日元,软件投资约11.5亿日元。偿债和再融资风险基本不存在,下行风险主要在利润和治理上。 |
| 竞争优势与结构耐久性 | 14 | 8.68 | 公司是JFE集团的系统部门出身,长期为钢铁厂运营核心系统,客户切换靠的是运营依赖和知识积累,而不是合同。约2亿步旧系统代码迁移到开放云环境,这件事在2026年7月获得IT Japan Award大奖,是行业内少有的案例。自有软件FiBridge连续19年位居国内份额第一(公司引用的第三方调查),部分软件进入合规和结算流程。离开钢铁和制造业,公司只是众多系统集成商之一,面对NTT Data的规模和NS Solutions这样的同类上市子公司。 |
| 盈利质量、现金转化与资本效率 | 17 | 11.05 | 2026年3月期销售额574亿日元(同比下降10.3%),营业利润63.5亿日元(下降16.4%),但毛利率从23.6%升至25.1%,2027年3月期上半年进一步升至26.0%。毛利率上升来自转包比例高的更新项目退出、软件和ERP占比提高,属于业务构成变化,不是涨价。上半年毛利润增长3.1%,销售额却下降9.5%。盈利的正常水平大致是营业利润65亿至75亿日元,每股收益约140至160日元(这是研究估算,不是公司指引)。净资产收益率12.5%,预测11.9%。 |
| 商业结构、产品、客户与关键依赖 | 11 | 6.05 | JFE集团业务约占2026年3月期销售的38%,上半年再下降34.0%,而所有外部业务单元都在增长(数字制造+13.2%,ERP+8.5%,智能+7.4%,行业+4.1%,基础设施+3.4%)。2027年3月期指引要求子公司及其他板块增长55.3%到约85.7亿日元,主要是JFE ComService。业务依赖SAP和Microsoft两个平台,以及2,000人左右的工程师团队。 |
| 估值与安全边际 | 15 | 9.3 | 2026年11月6日收盘价1,851日元,市值约581亿日元,按2027年3月期公司指引每股收益139.45日元,预测市盈率约13.3倍;市净率约1.64倍;预测股息收益率约3.8%。扣除约270亿日元的净现金,企业价值约312亿日元,约相当于预测营业利润的4.7倍,EV/EBITDA约3.4倍(EBITDA用的是低谷年的营业利润)。2026年3月期的市净率区间为1.14倍到2.19倍。 |
| 资本配置与股东回报 | 10 | 5 | 2026年3月期分红比例50.1%(每股68日元),2027年3月期计划50.2%(每股70日元),2026年3月期每股分红增长11.5%,而每股收益下降21.6%。资本政策只有分红,没有回购,库存股只有2,325股,也没有下限分红政策。现金276亿日元闲置,每年约增加22亿日元。2027年3月期把中期分红从22日元提高到24日元、期末从48日元降到46日元,全年不变。 |
| 治理、所有权与管理层 | 7 | 2.94 | JFE Steel持股65.16%,员工持股会6.65%,集团公司合计约四分之三,最大的外部股东仅1.17%,没有外部股东能够推动资本政策或母子关系调整。好处是没有稀释,注册资本5年保持13.91亿日元,上市以来没有股权融资,也没有稀释性证券。会计采用日本会计准则,研发费用化,账目简单清晰。 |
| Kabugami 技术结构 | 13 | 7.15 | 价格在2026年11月6日收于1,851日元,比2026年1月高点2,469日元低约21%至25%,处在24个月均线(约1,918日元)附近、12个月均线(约2,032日元)下方,60个月均线(约1,608日元)仍在上升。2023至2025年伴随成交量放大的阶梯式上行,说明旧的低位长期状态已明显削弱;2026年1月的新高幅度很小,随后进入下跌消化,成交量变薄而非放大,1,790至1,850日元一带今年秋天两次守住。新的较高运行区间尚未经受过一次真正的业绩冲击,还不能算作确立。 |
总分: 61.22 / 100 评级: B 操作建议: 观察为主,不追高。当前价格下方有现金和50%分红比例的支撑,但上行取决于外部业务能否补上集团业务的下滑。2027年1月下旬的第3季度决算是第一次检验:下半年需要约43亿日元营业利润,订单余额必须停止下降,指引不能下调。指引下调、订单余额连续两个半期下降或分红比例被削弱,就应降低判断。已有持仓可以继续持有,新增仓位宜等决算后的证据;仓位应偏小,因为流通股少,坏消息当天的下跌会很快。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|数据截至2026年11月6日收盘,评审日期为2026年11月9日
本报告的评审日期是2026年11月9日。价格和估值数据截至2026年11月6日收盘(1,851日元);技术判断使用2001年3月至2026年10月的月线,加11月6日的日线收盘,11月月线尚未走完,不作为已确认依据。
主要来源:公司2026年3月期财报(业绩快报,2026年4月24日披露);2027年3月期上半年财报概览(英文,2026年10月28日披露)及同日的分红公告摘要;中期经营计划2025–2027(2025年4月25日披露)及对上一期计划的回顾;公司概况(2026年6月);经济产业省gBizINFO提供的有价证券报告摘录(股东、母公司单体数据);IRBANK的行情和估值快照;株探新闻(Kabutan)对上半年财报的速报,以及Quartr对第一季度财报的摘要。所有金额以公司披露的日元为准,按万、亿换算。
15.2|证据的限制:这些是公开资料里查不到的信息,不代表公司有问题
没有分析师一致预期,预测倍数依据公司指引;业务单元的订单、订单余额和毛利率没有披露,转包比例、人员利用率,以及开发、运维和软件包的收入拆分也没有披露;独立董事构成和少数股东保护措施(公司治理报告)没有取得;2026年3月之后的大额持股报告没有核查;有价证券报告中的关联方、税务和主要客户附注,以及2027年3月期上半年的现金流量表没有打开;没有客户流失数据。
其他需要说明的口径:1.64倍和1.62倍两种市净率的差异未核实;五年平均进度45.8%来自Kabutan,其窗口主要由更新项目年份构成;NS Solutions对照用的是研究此前的工作,只做结构参照;正常化盈利范围是研究估算,不是公司指引。接下来最能补上这些空白的是2027年1月的第三季度财报、4月的全年财报、6月的有价证券报告和2027年的新中期计划。
本报告用于研究目的,不构成投资建议;所涉价格、估值和预测均为特定日期的快照,投资决定请自行判断并考虑自身风险承受能力。
主要资料来源
- Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.
- Segment information note, FY3/26 短信 notes
- Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract)
- Reporting-unit definitions, Q2 FY3/27 overview (English)
- Q1 FY3/27 results summary (from the company's Q1 短信 of 29 July 2026)
- H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance
- H1 FY3/27 短信 summary: dividend revision (interim ¥24 decided, year-end ¥46), Japan IR summary of TDnet filing
- Valuation snapshot and extremes, IRBANK 4832
- Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)
研究发现索引
展开本次 Review 的 78 项研究发现
F001|02|公司按工时和软件包收费,一个分部之下有七个管理单元
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|公司按工时和软件包收费,一个分部之下有七个管理单元
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.怎么使用:直接证据;一手验证:01、24
Segment information note, FY3/26 短信 notes怎么使用:直接 / 支持;一手验证:02、08、13
Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract)怎么使用:直接证据;同业比较:06;其他用途:历史
Reporting-unit definitions, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:02、03、07;专项深挖:02、03
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接证据;一手验证:02、05、15
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:支持证据;一手验证:23、30、31、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域24)|Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域08) / 一手证据(研究域13)|Segment information note, FY3/26 短信 notes;直接证据 / 历史/同业比较(研究域06)|Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域03)|Reporting-unit definitions, Q2 FY3/27 overview (English);直接证据|Parent-only results vs consolidated, FY3/26 短信 reference section;直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)
完整研究记录(核对用)
研究原文:JFE Systems is a TSE Standard-listed systems integrator (4832) reporting one information-services segment; the seven units in earnings materials are management units. It sells engineering hours as project and service fees (bespoke development, operation and maintenance for JFE Steel and group companies, plus SCM/data platforms, SAP/Microsoft ERP builds, own packages, industry systems, infrastructure build-and-run) and converts accumulated know-how into higher-gross-margin package and service revenue. The listed perimeter is largely the parent company (parent-only sales ¥51,457m of ¥57,411m; 1,600 of 1,960 staff) with a small, profitable subsidiary layer. There are no inventories or licences of consequence.
内部研究类型:EconomicIdentity
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Defines what the ordinary shareholder owns: a simple, fully visible, people-and-software earnings stream whose margin depends on mix.
不确定性(原始记录):Contract-level pricing and unit margins are undisclosed; mix claims are inferred from consolidated gross margin only.
F002|01|2026年3月期的下滑来自一个项目收尾,外部业务全部在增长
研究范围:开放研究+35项覆盖检查
写入正文:01|2026年3月期的下滑来自一个项目收尾,外部业务全部在增长
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
2026年3月期 決算短信〔日本基準〕(連結)怎么使用:直接 / 支持;一手验证:22、28;同业比较:16、17、35;其他用途:历史
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:04、12、14
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
Reference: history of net sales by reporting unit (consolidated totals), Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:28、33;专项深挖:33;同业比较:02、09、11、14、28;其他用途:历史
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域35)|2026年3月期 決算短信〔日本基準〕(連結);直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域14) / 历史/同业比较(研究域28) / 定向深挖(研究域33)|Reference: history of net sales by reporting unit (consolidated totals), Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)
完整研究记录(核对用)
研究原文:FY3/26 was a planned down year, not a demand collapse: sales ¥57,411m (−10.3%) and operating income ¥6,346m (−16.4%) fell because the JFE Steel Steelworks System Refresh Project, which had lifted FY3/25 sales to a record ¥63,972m, completed its major development phase. JFE Group unit sales fell from about ¥30.3bn to ¥21,993m while every external-facing unit grew. Over a decade (¥46.5bn FY3/20 to ¥64.0bn FY3/25) the sales arc has exactly one interruption, the refresh cycle, and the JFE Group share fell from about two thirds to 38%.
内部研究类型:CausalDriver
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The FY3/26 decline should be read as the second half of one project story, so trailing earnings understate the external business and overstate how permanent the dip is.
不确定性(原始记录):The date and size of the next large JFE Steel programme are undisclosed and are the parent's decision.
F003|01|2027年3月期的指引是外部增长的主张,下半年要交出约43亿日元营业利润
研究范围:开放研究+35项覆盖检查
写入正文:01|2027年3月期的指引是外部增长的主张,下半年要交出约43亿日元营业利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接证据;一手验证:02、05、15
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接 / 支持;一手验证:23、30、31、35
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:35;专项深挖:15、35
Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:28;专项深挖:28
Segment information note, FY3/26 短信 notes怎么使用:直接 / 支持;一手验证:02、08、13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域08) / 一手证据(研究域13)|Segment information note, FY3/26 短信 notes
完整研究记录(核对用)
研究原文:The air pocket is planned. FY3/27 guidance, unchanged since April, holds sales at ¥60,000m (+4.5%), operating income ¥6,600m (+4.0%), profit attributable ¥4,380m, with JFE Group falling a further 17.7% to ¥18,110m. External growth must fill it: subsidiaries/JFE ComService +55.3% to ¥8,565m, ERP +21.1%, Industry Solutions +17.6%, Digital Manufacturing +12.5%, Infrastructure +7.3%, Smart Solutions +3.2%. Management's operating-income bridge: refresh removes about ¥1.6bn, external businesses add about ¥2.7bn, deliberate SG&A growth takes back about ¥0.9bn, netting +¥0.25bn. The plan is an external-growth claim, not a cost claim, and requires H2 operating income of about ¥4,305m, roughly 17% above the prior-year second half.
内部研究类型:ForwardBridge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The earnings recovery is an arithmetic statement about external-unit delivery that can be tested at dated checkpoints.
不确定性(原始记录):Order intake by unit is not disclosed, so the share of external growth that is genuinely new demand is unverified.
F004|06|销售下滑时毛利率反而上升,来自收入结构变化,与涨价无关
研究范围:开放研究+35项覆盖检查
写入正文:06|销售下滑时毛利率反而上升,来自收入结构变化,与涨价无关12|三个反直觉的细节:最差的利润年有最好的现金流,也有最高的毛利率14|财务、盈利和商业结构四个模块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:05、15
Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信怎么使用:直接 / 支持;一手验证:06、16;专项深挖:16
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接 / 支持;一手验证:14、16、32
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接 / 支持;一手验证:12、31;外部现实校验:12、30
查看完整证据标签(核对用)
直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 定向深挖(研究域16)|Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信;直接证据 / 支持证据|Q1 FY3/27 results summary (from the company's Q1 短信 of 29 July 2026);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance
完整研究记录(核对用)
研究原文:Gross margin rose through the revenue decline: 23.6% (FY3/25) to 25.1% (FY3/26) to 26.0% in H1 FY3/27 (from 22.8% a year earlier). In FY3/26 cost of sales fell ¥5,901m against a ¥6,561m sales decline because subcontractor-heavy refresh content rolled off with its revenue while the retained package, ERP and infrastructure mix carries higher margin; H1 gross profit rose 3.1% on 9.5% lower sales. It is a mix identity, not a pricing claim, and persists only while the external mix keeps rising. The trough is a mix trough rather than a franchise trough: Q1 operating income fell 51.5%, then the July–September quarter rose about 47% at a 10.9% margin.
内部研究类型:MechanismMixIdentity
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operating earnings quality is better than the headline decline implies, and the next revenue peak should print more profit per yen of sales if volume returns.
不确定性(原始记录):Unit-level margins are undisclosed so the mix claim cannot be verified unit by unit; the quarterly pattern is inference.
F005|06|上半年毛利润增长3.1%,营业利润仍下降13.9%,原因是销售管理费提前增加
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|上半年毛利润增长3.1%,营业利润仍下降13.9%,原因是销售管理费提前增加
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:05、15
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接证据;一手验证:12、31;外部现实校验:12、30
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接证据;一手验证:23、30、31、35
Progress rates and the Q2-only quarter, Kabutan flash of 28 October 2026怎么使用:直接 / 支持;外部现实校验:15、16、28;专项深挖:31
查看完整证据标签(核对用)
直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance;直接证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据|H1 FY3/27 短信 summary: dividend revision (interim ¥24 decided, year-end ¥46), Japan IR summary of TDnet filing;直接证据 / 支持证据|Q1 FY3/27 results summary (from the company's Q1 短信 of 29 July 2026);直接证据 / 支持证据 / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域28) / 定向深挖(研究域31)|Progress rates and the Q2-only quarter, Kabutan flash of 28 October 2026
完整研究记录(核对用)
研究原文:H1 FY3/27 (published 28 October 2026): sales ¥26,466m (−9.5%), gross profit +3.1%, SG&A +14.5% to ¥4,587m, operating income ¥2,295m (−13.9%), ordinary income −11.5%, profit attributable ¥1,528m (−13.4%). Guidance was left unchanged, so ordinary-income progress is 35.2% against a company-cited five-year average of 45.8% (a window dominated by refresh years), implying a deliberately H2-loaded forecast. Every external unit grew (Digital Manufacturing +13.2%, ERP +8.5%, Smart +7.4%, Industry +4.1%, Infrastructure +3.4%) while the JFE Group unit fell 34.0%; subsidiaries −1.8%. Delivery seasonality is reasserting itself, so the 35.2% progress ratio is a profile artefact until the Q3 print proves otherwise.
内部研究类型:CurrentChange
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Headline weakness is real but concentrated in a known cause; the progress-ratio concern is the market's specific doubt.
不确定性(原始记录):Interpretation of seasonality rests on Kabutan's five-year window and quarter arithmetic, not on unit-level disclosures.
F006|01|指引原样不变,管理层把可信度押在第三季度
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接 / 支持;一手验证:12、31;外部现实校验:12、30
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接 / 支持;一手验证:23、30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance;直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)
完整研究记录(核对用)
研究原文:Holding full-year guidance while H1 progress is only 35.2% stakes management credibility on the second-half-weighted delivery pattern and the external order book. A Q3 downgrade would therefore be doubly informative, while confirmation would validate the planned-air-pocket reading.
内部研究类型:ManagementSignal
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Makes the narrative cheap to check on a dated calendar; a miss damages both earnings and credibility.
不确定性(原始记录):Whether the unchanged guidance reflects visibility or a self-imposed trap cannot be distinguished before Q3.
F007|06|上半年毛利润增长3.1%,营业利润仍下降13.9%,原因是销售管理费提前增加
研究范围:开放研究+35项覆盖检查
写入正文:06|上半年毛利润增长3.1%,营业利润仍下降13.9%,原因是销售管理费提前增加
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
SG&A movement and its stated drivers, FY3/26 短信 and Q2 FY3/27 overview怎么使用:直接 / 支持;一手验证:06、16;反向验证:28;专项深挖:16
Factors affecting operating income changes in Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;专项深挖:28
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接证据;一手验证:14、16、32
People indicators: certifications, diversity certification and headcount, Q2 FY3/27 overview and company data怎么使用:直接证据;一手验证:06;专项深挖:06
Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract)怎么使用:直接证据;同业比较:06;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 反证(研究域28) / 定向深挖(研究域16)|SG&A movement and its stated drivers, FY3/26 短信 and Q2 FY3/27 overview;直接证据 / 定向深挖(研究域28)|Factors affecting operating income changes in Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信;直接证据 / 一手证据(研究域06) / 定向深挖(研究域06)|People indicators: certifications, diversity certification and headcount, Q2 FY3/27 overview and company data;直接证据 / 历史/同业比较(研究域06)|Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract)
完整研究记录(核对用)
研究原文:SG&A is a management-chosen curve: ¥7,495m (FY3/25) to ¥8,078m (FY3/26, +7.8% in a −10.3% sales year) to a planned ¥8,960m (FY3/27, +10.9%), with H1 +14.5%, driven by R&D, internal IT, hiring and training for growth businesses and strategic sales expenses. Parent headcount rose from 1,554 to 1,600 into the revenue decline. About ¥1.5bn of annual SG&A has been added over two years against a shrinking group-revenue base; operating margin compression to about 11% is policy, not price or wage shock.
内部研究类型:ManagementChosenCostCurve
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Pre-spent capacity creates operating leverage if orders refill and a fixed-cost problem if they do not.
不确定性(原始记录):Wage settlements for FY3/27 hiring and utilisation rates are not visible.
F008|06|2026年3月期现金流最好,是项目收尾放出来的现金
研究范围:开放研究+35项覆盖检查
写入正文:06|2026年3月期现金流最好,是项目收尾放出来的现金12|三个反直觉的细节:最差的利润年有最好的现金流,也有最高的毛利率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Working-capital detail, FY3/26 consolidated balance sheet and cash-flow statement怎么使用:直接 / 支持;一手验证:17、19;专项深挖:19
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review怎么使用:直接 / 支持;一手验证:17、19、20;同业比较:32;其他用途:历史
Interim balance-sheet movements, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 定向深挖(研究域19)|Working-capital detail, FY3/26 consolidated balance sheet and cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 历史/同业比较(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review;直接证据 / 一手证据(研究域19)|Interim balance-sheet movements, Q2 FY3/27 overview (English);直接证据|Q1 FY3/27 balance-sheet summary (from the Q1 短信 of 29 July 2026)
完整研究记录(核对用)
研究原文:FY3/26 operating cash flow of ¥8,448m (against net income ¥4,429m) was flattered by the same project cycle that depressed earnings: trade receivables released about ¥2.5bn (¥2,956m in the cash-flow statement) as refresh billings were collected, with depreciation ¥2,770m. Tangible capex was only ¥189m and software ¥1,149m, so the model is capital-light. Cash conversion will mechanically worsen as the book refills with earlier-stage external work; the research's ‘~3x dividend cover by normalised FCF’ rests on a basis that includes the receivables release and excludes ¥1,136m of lease repayments, so conservative cover is thinner.
内部研究类型:CashMechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Trailing cash metrics overstate forward cash generation; the constraint on returns is policy rather than cash.
不确定性(原始记录):H1 FY3/27 cash-flow detail was not opened; receivable ageing and customer concentration are undisclosed. Normalised FCF figure is a Research calculation with mixed lease treatment.
F009|06|没有借款,现金占市值46%,但大半已转成定期存款
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|没有借款,现金占市值46%,但大半已转成定期存款14|财务、盈利和商业结构四个模块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review怎么使用:直接 / 支持;一手验证:17、19、20;同业比较:32;其他用途:历史
Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement怎么使用:直接 / 支持;一手验证:17、18、29、32;外部现实校验:32;专项深挖:17、18、29
Lease and retirement-benefit liabilities, FY3/26 consolidated balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、29
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接 / 支持;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
Interim balance-sheet movements, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 历史/同业比较(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域18) / 一手证据(研究域29) / 一手证据(研究域32) / 外部现实(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域18) / 定向深挖(研究域29)|Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Lease and retirement-benefit liabilities, FY3/26 consolidated balance sheet;直接证据|Balance sheet as of Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832;直接证据 / 一手证据(研究域19)|Interim balance-sheet movements, Q2 FY3/27 overview (English)
完整研究记录(核对用)
研究原文:The balance sheet carries no borrowings: equity ratio 67.3% (67.4% at September 2026), cash and deposits ¥27,600m (¥26,997m at September) against total liabilities of ¥16,027m. Debt-like claims are only lease liabilities of ¥2,882m and a retirement benefit liability of ¥3,806m. The pile equals about 46% of the ¥58.1bn market capitalisation (September basis). FY3/26's ¥15,849m investing outflow was a ¥14,150m net shift into time deposits over three months, not capex, so cash equivalents fell to ¥13,450m while balance-sheet cash rose. Interest income rose to ¥107m from ¥47m.
内部研究类型:BalanceSheetStructure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):All risk is P&L and governance risk, not solvency; but the asset is static and also dilutes ROE.
不确定性(原始记录):The time-deposit ladder and yield are undisclosed; deposits are not netted for leases and pension in headline EV figures, and the parent-available character of subsidiary cash is not separately examined.
F010|08|净资产收益率下降一半来自分母,50%分红只是下限
研究范围:开放研究+35项覆盖检查
写入正文:08|净资产收益率下降一半来自分母,50%分红只是下限12|三个反直觉的细节:最差的利润年有最好的现金流,也有最高的毛利率13|276亿日元存款的期限和收益是多少,董事会是否评估过回购,50%分红能否延续
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
ROE, EPS and BPS path, FY3/26 短信 headline indicators怎么使用:直接 / 支持;一手验证:22;外部现实校验:17、20;专项深挖:22;同业比较:27;其他用途:历史
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:26;专项深挖:26;同业比较:25;其他用途:历史
Shareholder-return policy statement, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:25;专项深挖:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域17) / 外部现实(研究域20) / 历史/同业比较(研究域27) / 定向深挖(研究域22)|ROE, EPS and BPS path, FY3/26 短信 headline indicators;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域25) / 定向深挖(研究域26)|Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|Shareholder-return policy statement, Q2 FY3/27 overview (English);直接证据|Share count, treasury stock and per-share notes, FY3/26 短信
完整研究记录(核对用)
研究原文:ROE fell 17.5% to 12.5% to 11.9% forecast, partly denominator-driven: equity rose ¥2,461m in FY3/26 because a 50% payout retains half of a positive year, and retained cash earns deposit rates inside the return calculation. The payout raise therefore functions partly as ROE defence; 50% is the minimum credible setting. Open question carried: what is the ladder and yield on the ¥27.6bn pile, and has the board ever formally evaluated a buyback (rejected on what grounds) given a 1.6x book multiple and a ~25% float? Treasury stock is 2,325 shares and no buyback framework exists.
内部研究类型:CapitalEfficiencyMechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Per-share compounding is bounded by capital allocation rather than operations; each idle year adds about ¥2.2bn to the pile.
不确定性(原始记录):Management has set no ROE target in the opened materials; the board's buyback evaluation is unknown.
F011|07|控制权绝对,流通股很薄,没有外部力量能推动资本政策
研究范围:开放研究+35项覆盖检查
写入正文:07|控制权绝对,流通股很薄,没有外部力量能推动资本政策14|估值、资本政策、治理和技术四个模块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.怎么使用:直接 / 支持;一手验证:01、24
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:01、23、24
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
Capital and share-count history from securities reports, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:01、25;专项深挖:01、25;同业比较:18、24;其他用途:历史
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:支持证据;一手验证:02、05、15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域24)|Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域25) / 历史/同业比较(研究域18) / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域25)|Capital and share-count history from securities reports, gBizINFO (EDINET extract);直接证据|Share count, treasury stock and per-share notes, FY3/26 短信;支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)
完整研究记录(核对用)
研究原文:Control is absolute and the float thin: JFE Steel 65.16%, employee association 6.65%, JFE Plant Engineering 1.27%, JFE Advantech 0.64%, JFE Logistics 0.64% (group-aligned about three quarters of the register); the largest outside holder is a nominee at 1.17%, a Hikari Tsushin partnership 0.93%. No outside holder reaches 1.2%, so no institutional constituency can press the board on capital policy or the parent relationship. Stated capital has been ¥1,391m for five years with no equity issuance since listing; share count changed only by the 2021 and 2025 two-for-one splits. There are no dilutive securities.
内部研究类型:OwnershipGovernanceStructure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):No dilution or refinancing risk; minorities are price-takers of the parent's patience and the 50% payout rule is the whole return contract.
不确定性(原始记录):Large-holding filings after March 2026 were not swept and independent-director composition was not captured.
F012|08|分红已写成政策,约50%的比例没有下限,也没有回购
研究范围:开放研究+35项覆盖检查
写入正文:08|分红已写成政策,约50%的比例没有下限,也没有回购12|三个反直觉的细节:最差的利润年有最好的现金流,也有最高的毛利率13|276亿日元存款的期限和收益是多少,董事会是否评估过回购,50%分红能否延续14|估值、资本政策、治理和技术四个模块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:26;专项深挖:26;同业比较:25;其他用途:历史
Shareholder-return policy statement, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:25;专项深挖:25
Interim dividend decision and year-end revision notice summary, Japan IR (TDnet)怎么使用:直接证据;一手验证:26;专项深挖:26;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 支持证据|H1 FY3/27 短信 summary: dividend revision (interim ¥24 decided, year-end ¥46), Japan IR summary of TDnet filing;直接证据 / 支持证据|Share count, treasury stock and per-share notes, FY3/26 短信;直接证据 / 一手证据(研究域26) / 历史/同业比较(研究域25) / 定向深挖(研究域26)|Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域25) / 定向深挖(研究域25)|Shareholder-return policy statement, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域26) / 历史/同业比较(研究域30) / 定向深挖(研究域26)|Interim dividend decision and year-end revision notice summary, Japan IR (TDnet)
完整研究记录(核对用)
研究原文:Shareholder return is dividend-only and was hardened into policy under the 2025–2027 plan: payout 35.2% (FY3/25) to 50.1% (FY3/26, ¥68, interim ¥28 + year-end ¥40) with a planned 50.2% (FY3/27, ¥70). FY3/26 DPS rose 11.5% while EPS fell 21.6%. Yield at ¥1,851 is about 3.8%. The policy has no DOE floor, no progressive commitment and no buyback; the 50% is a plan-period target. Open question: does the ~50% payout survive into the post-2027 plan as standing policy, or does a DOE floor or progressive commitment appear, or does the dividend revert to full earnings linkage?
内部研究类型:ShareholderReturnPolicy
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Dividend is a contracted share of earnings, a leveraged read on plan delivery rather than an annuity; total-return holders get no buyback kicker.
不确定性(原始记录):Post-FY3/28 policy is undisclosed; next plan expected in 2027.
F013|08|中间分红上调、期末下调,全年不变,是时间安排上的信号
研究范围:开放研究+35项覆盖检查
写入正文:08|中间分红上调、期末下调,全年不变,是时间安排上的信号
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Interim dividend decision and year-end revision notice summary, Japan IR (TDnet)怎么使用:直接 / 支持;一手验证:26;专项深挖:26;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域30) / 定向深挖(研究域26)|Interim dividend decision and year-end revision notice summary, Japan IR (TDnet);直接证据 / 支持证据|H1 FY3/27 短信 summary: dividend revision (interim ¥24 decided, year-end ¥46), Japan IR summary of TDnet filing
完整研究记录(核对用)
研究原文:Raising the interim dividend from ¥22 to ¥24 while trimming the year-end from ¥48 to ¥46 keeps the ¥70 total unchanged: a distribution-timing decision that signals confidence in second-half delivery at the moment of maximum headline weakness, and costs management credibility if Q3 disappoints.
内部研究类型:ManagementSignal
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Not an increase in shareholder value; an informational commitment.
不确定性(原始记录):Motive is inferred.
F014|01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面
研究范围:开放研究+35项覆盖检查
写入正文:01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面13|2028年3月期的674亿日元由哪些业务单元组成,是否假设有一个已命名的大项目
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接 / 支持;一手验证:11
Review of the previous Mid-Term Management Plan FY2022-2024, plan document of 25 April 2025怎么使用:直接 / 支持;同业比较:10、12、22、26;其他用途:历史
Orders received and order backlog, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:05、15;外部现实校验:19;反向验证:05、15、35;专项深挖:05、15、35
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接证据;一手验证:23、30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025);直接证据 / 支持证据 / 历史/同业比较(研究域10) / 历史/同业比较(研究域12) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Review of the previous Mid-Term Management Plan FY2022-2024, plan document of 25 April 2025;直接证据 / 支持证据|Mid-term plan sales path by unit (plan document charts), 25 April 2025;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15) / 外部现实(研究域19) / 反证(研究域05) / 反证(研究域15) / 反证(研究域35) / 定向深挖(研究域05) / 定向深挖(研究域15) / 定向深挖(研究域35)|Orders received and order backlog, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)
完整研究记录(核对用)
研究原文:The 2025–2027 plan targets FY3/28 unit-sum sales of ¥67.4bn (from ¥60.2bn FY3/27 target; +¥7.4bn in a single year) with JFE Group down to about ¥20.0bn, on the way to a 2030 vision above ¥85bn sales and ¥12bn ordinary income; so all net growth plus about ¥10bn of replacement must come from external units. The prior plan's targets were beaten (sales ¥64.0bn vs ¥57.0bn; ordinary income ¥7.7bn vs ¥6.6bn) on the same refresh demand that has ended. H1 orders fell 8.3% to ¥25,952m, so the FY3/28 target rests on orders not yet booked; a second consecutive half of falling backlog would break the arithmetic before the final year begins. Open question: which units, what visible order intake, and does the JFE Group return to ~¥20.0bn assume a named next large JFE Steel project?
内部研究类型:PlanFeasibility
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Delivery of the final year is what re-rates the shares from a captive multiple toward an independent compounder's.
不确定性(原始记录):Bridge composition and unit-level orders undisclosed; part of external growth may be re-channelled group work.
F015|01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面13|订单余额减少的2,490万日元……实际是24.90亿日元,集中在哪个单元
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Orders received and order backlog, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:05、15;外部现实校验:19;反向验证:05、15、35;专项深挖:05、15、35
Industry environment as described in the FY3/26 短信 management review怎么使用:直接证据;一手验证:11、14;外部现实校验:02、05、06;专项深挖:11、14
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:支持证据;一手验证:23、30、31、35
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:支持证据;一手验证:11
查看完整证据标签(核对用)
直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15) / 外部现实(研究域19) / 反证(研究域05) / 反证(研究域15) / 反证(研究域35) / 定向深挖(研究域05) / 定向深挖(研究域15) / 定向深挖(研究域35)|Orders received and order backlog, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域11) / 一手证据(研究域14) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域14)|Industry environment as described in the FY3/26 短信 management review;支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);支持证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)
完整研究记录(核对用)
研究原文:The order backlog fell 9.9% in H1 FY3/27 to ¥22,540m (from ¥25,030m), about 4.5 months of the ¥60,000m sales forecast, while orders fell 8.3%. It is the one forward indicator in the release moving the wrong way, even though the filing describes solid market demand; the gap is probably company-specific (group project cycle) but this is not proven. Open question: is the ¥2,490m backlog decline concentrated in the JFE Group unit (expected) or spread into external units (a demand warning)?
内部研究类型:ForwardIndicatorWarning
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Backlog is the earliest gauge of whether the refill engine or the moat is working, and the plan's hardest year follows while SG&A is already pre-spent.
不确定性(原始记录):No unit-level backlog or order disclosure; the ~4.5-month cover is arithmetic on a full-year forecast and is normal for a second-half-weighted SIer.
F016|05|更新项目既是失去的收入,也是对外销售的凭证
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English)怎么使用:直接 / 支持;一手验证:04、10;专项深挖:04、10
Major news and press releases, first half FY Ending March 2027 (appendix), Q2 results overview (English)怎么使用:直接证据;一手验证:03、07、09、10;外部现实校验:07
Product franchise evidence, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:03、09、10、13;外部现实校验:03、04;专项深挖:03、09、10
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:04、12、14
Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025怎么使用:直接证据;一手验证:04;专项深挖:04;同业比较:03、04;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域03) / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域10) / 外部现实(研究域07)|Major news and press releases, first half FY Ending March 2027 (appendix), Q2 results overview (English);直接证据 / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 定向深挖(研究域03) / 定向深挖(研究域09) / 定向深挖(研究域10)|Product franchise evidence, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 定向深挖(研究域04)|Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025
完整研究记录(核对用)
研究原文:The refresh is also the company's flagship credential: roughly 200 million steps of legacy steelworks code were migrated to an open cloud environment, and JFE Steel won the IT Japan Award 2026 Grand Prix on 24 July 2026 with JFE Systems' contribution on the record; the same capability is what the Digital Manufacturing and ERP pitch sells to other manufacturers. Package franchises add proof points (FiBridge No. 1 domestic share for 19 consecutive years per a Fuji Chimera survey; DataDelivery full-scope JIIMA certification; J-CCOREs SAP linkage). Whether external wins from the credential exist at scale is not yet disclosed.
内部研究类型:CapabilityEvidence
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Supports the margin path and gives a sales asset for external legacy migrations; award is a credential, not profit.
不确定性(原始记录):Share claims are company-quoted third-party surveys; no independent productivity benchmark; credential-to-order conversion unobserved.
F017|01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面
研究范围:开放研究+35项覆盖检查
写入正文:01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面13|JFE ComService自己赚多少,增长55.3%里有多少是母公司转来的工作
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:07;专项深挖:02、07
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:35;专项深挖:15、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域07)|Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English);直接证据|Non-controlling interests, FY3/26 consolidated statements
完整研究记录(核对用)
研究原文:The largest planned growth line is subsidiaries and others at +55.3% (¥5,515m to ¥8,565m) on JFE ComService, which provides infrastructure and SI for the JFE Group. Part of it may be group work re-channelled from the JFE Group unit into the subsidiary rather than new demand; the filings do not split it, so the true external refill rate is probably slower than the headline and the FY3/28 bridge harder. Non-controlling interests (¥1,231m of net assets) take about 3.7% of consolidated net income. Open question: what does ComService earn standalone, and how much of its growth is transferred parent work?
内部研究类型:GrowthQualityDoubt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Distinguishes genuine external compounding from relabelled group demand and shows a small minority leakage on the fastest line.
不确定性(原始记录):The inference (confidence ~0.6) is untested; no standalone ComService disclosure.
F018|02|合并范围里没有第二台引擎,上市主体基本就是母公司
研究范围:35项覆盖检查
写入正文:02|合并范围里没有第二台引擎,上市主体基本就是母公司
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract)怎么使用:直接证据;同业比较:06;其他用途:历史
Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:07;专项深挖:02、07
查看完整证据标签(核对用)
直接证据 / 支持证据|Parent-only results vs consolidated, FY3/26 短信 reference section;直接证据 / 支持证据|Non-controlling interests, FY3/26 consolidated statements;直接证据 / 历史/同业比较(研究域06)|Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域07)|Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English)
完整研究记录(核对用)
研究原文:Subsidiaries add about ¥6.0bn of sales and ¥0.9bn of operating income over the parent-only accounts (parent-only FY3/26: sales ¥51,457m, operating income ¥5,434m, net income ¥4,012m), contributed mainly by JFE ComService and IAF Consulting (BI/management-indicator consulting feeding the data-platform strategy). The subsidiary growth line is real but small and slightly leaky; there is no hidden second engine inside the perimeter.
内部研究类型:PerimeterFinding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Group accounts remain the right lens; subsidiary value should not be counted separately.
不确定性(原始记录):Whether dormant or non-core assets sit inside subsidiaries was not separately audited.
F019|06|未上市股票减值2.81亿日元,是账目里唯一不透明的项目
研究范围:开放研究+35项覆盖检查
写入正文:06|未上市股票减值2.81亿日元,是账目里唯一不透明的项目13|剩余未上市证券是什么,AI会怎样改变计费基础,价格平台能否守住第三季度
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Investment securities and valuation reserves, FY3/26 consolidated balance sheet and income statement怎么使用:直接 / 支持;一手验证:20、21;专项深挖:20、21
Extraordinary and non-operating items, FY3/26 consolidated income statement怎么使用:直接 / 支持;一手验证:21、32;专项深挖:32;同业比较:21;其他用途:历史
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接证据;一手验证:18、21、22、29;同业比较:19;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20) / 一手证据(研究域21) / 定向深挖(研究域20) / 定向深挖(研究域21)|Investment securities and valuation reserves, FY3/26 consolidated balance sheet and income statement;直接证据 / 支持证据 / 一手证据(研究域21) / 一手证据(研究域32) / 历史/同业比较(研究域21) / 定向深挖(研究域32)|Extraordinary and non-operating items, FY3/26 consolidated income statement;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信
完整研究记录(核对用)
研究原文:The securities portfolio is small (¥1,735m, 3.3% of assets, with a ¥1,016m unrealised-gain reserve) and not a hidden-asset story; the equity's asset backing is the deposit pile and ¥30,773m of retained earnings. But a ¥281m FY3/26 extraordinary write-down of unlisted shares shows an undisclosed unlisted portfolio can still produce losses the materials never discuss. Open question: what is the remaining unlisted-securities portfolio (holdings, cost, governance over further venture-style investments)? Goodwill is ¥269m and there is no disclosed surplus real estate.
内部研究类型:AssetOpacityRisk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):No hidden-asset upside; small residual loss risk and a governance question on non-core investing.
不确定性(原始记录):Composition of the remaining unlisted portfolio is unknown.
F020|11|最大的风险来自母公司的周期,最大的变数是下一个大项目何时到来
研究范围:开放研究+35项覆盖检查
写入正文:11|最大的风险来自母公司的周期,最大的变数是下一个大项目何时到来13|向JFE钢铁的销售额是多少,集团内部价格怎样确定
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:04、12、14
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)
完整研究记录(核对用)
研究原文:A steel downturn at JFE Steel would cut group IT budgets (the anchor 38% of sales) at the same moment it pressures the shares' sentiment, and no contractual minimum for group work is disclosed. The parent's operation-and-maintenance need for its works systems gives a demand floor that does not go to zero, but its size is unquantified. Open question: what were sales to JFE Steel itself in the securities report's related-party and major-customer notes, and how are intra-group prices set and benchmarked?
内部研究类型:ConcentrationRisk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The largest single demand risk is also the controlling shareholder's budget cycle; pricing terms may transfer value between parent and minorities.
不确定性(原始记录):JFE Steel standalone transaction amount and pricing terms are not captured in opened materials.
F021|09|估值简报:13.3倍预测市盈率,1.64倍市净率,现金约占市值46%
研究范围:开放研究+35项覆盖检查
写入正文:09|估值简报:13.3倍预测市盈率,1.64倍市净率,现金约占市值46%
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
4832 market snapshot, IRBANK怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、08、14、23、26、31
2026年3月期 決算短信〔日本基準〕(連結)怎么使用:直接 / 支持;一手验证:22、28;同业比较:16、17、35;其他用途:历史
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review怎么使用:直接 / 支持;一手验证:17、19、20;同业比较:32;其他用途:历史
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接证据;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
Annual price ranges and valuation at extremes, IRBANK 4832怎么使用:直接证据;外部现实校验:24、27、33;同业比较:08、29、31;其他用途:历史
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接证据;一手验证:18、21、22、29;同业比较:19;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域08) / 外部现实(研究域14) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域31)|4832 market snapshot, IRBANK;直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域35)|2026年3月期 決算短信〔日本基準〕(連結);直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 历史/同业比较(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review;直接证据 / 支持证据|Balance sheet as of Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据|H1 FY3/27 短信 summary: dividend revision (interim ¥24 decided, year-end ¥46), Japan IR summary of TDnet filing;直接证据 / 支持证据|Share count, treasury stock and per-share notes, FY3/26 短信;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832;直接证据 / 外部现实(研究域24) / 外部现实(研究域27) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域29) / 历史/同业比较(研究域31)|Annual price ranges and valuation at extremes, IRBANK 4832;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信
完整研究记录(核对用)
研究原文:At the 6 November 2026 close: price ¥1,851; market cap ¥58.14bn (31,412,000 shares issued); forecast PER 13.3x on FY3/27 EPS ¥139.45; PBR 1.64x on FY3/26-end BPS ¥1,129.19 (IRBANK shows 1.62x, plausibly a different book-value date, not verified); FY3/26 ROE 12.5%; forecast yield 3.78% on ¥70; EV ¥31.15bn after net cash ¥27.00bn at 30 September 2026; EV/EBITDA 3.4x on EBITDA ¥9.12bn (FY3/26 operating income + depreciation including lease and software amortisation). Netting the deposit pile prices the operating business at roughly 4.7x forecast operating income. The FY3/26 price range spanned PBR 1.14x–2.19x. Share-count basis is issued shares; treasury is negligible. No analyst consensus was opened.
内部研究类型:ValuationSnapshot
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Valuation is anchored by visible cash; the multiple is a referendum on the FY3/28 bridge and payout durability.
不确定性(原始记录):EV nets all deposits without deducting lease or pension claims or adding minorities; the EBITDA includes FY3/26 trough operating income; forecast multiples use company guidance, not consensus; PBR basis difference between 1.64x and 1.62x unverified.
F022|09|下行由资产托底,上行靠计划兑现,两端都可以按日期检验
研究范围:开放研究+35项覆盖检查
写入正文:09|下行由资产托底,上行靠计划兑现,两端都可以按日期检验14|估值、资本政策、治理和技术四个模块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接 / 支持;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接 / 支持;一手验证:11
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
Disclosure calendar pattern, IRBANK 4832 disclosure index怎么使用:直接 / 支持;一手验证:30;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832;直接证据 / 支持证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025);直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Disclosure calendar pattern, IRBANK 4832 disclosure index
完整研究记录(核对用)
研究原文:At ¥1,851 the market pays 13.3x forecast earnings and 1.62x book for a debt-free company whose deposit pile covers about 46% of the price: the downside is asset-anchored, the upside is execution arithmetic (deliver ¥67.4bn and about 12% ROE, or surface a governance event), and neither leg requires believing a narrative; both are checkable against the January Q3 print and April full-year release.
内部研究类型:ThesisBridge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Risk is time (a slow bridge) rather than impairment of the asset base, unless the plan fails and the earnings multiple compresses toward ex-cash value.
不确定性(原始记录):No consensus; cash is not equal to parent-controlled releasable value because no policy compels distribution.
F023|01|核心问题是外部业务补上集团缺口的速度,两个季度内就有第一个答案
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|核心问题是外部业务补上集团缺口的速度,两个季度内就有第一个答案14|总分61.22/100,B级,观察为主、不追高
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接 / 支持;一手验证:23、30、31、35
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接 / 支持;一手验证:11
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025);直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信
完整研究记录(核对用)
研究原文:JFE Systems is a captive SIer in mid-metamorphosis: the completed refresh removes its largest parent-supplied project and exposes a smaller, higher-gross-margin external business, on a debt-free balance sheet that now pays out half its earnings. The question is whether external growth refills the group hole quickly enough to deliver ¥67.4bn and hold ROE near 12%, repricing the shares from a captive's ~13x toward an independent compounder's multiple, before the market instead prices the permanent 65.16% parent discount and thin float.
内部研究类型:InvestmentThesis
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Defines the position as an arithmetic claim with dated checkpoints rather than a narrative about IT demand.
不确定性(原始记录):Medium confidence (~0.7); resolves over two quarters.
F024|11|催化剂是日历上的三个检验,加上两件没有日期的事
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|催化剂是日历上的三个检验,加上两件没有日期的事13|第三季度财报:九个月进度是否支撑下半年约43亿日元营业利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接 / 支持;一手验证:23、30、31、35
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接 / 支持;一手验证:12、31;外部现实校验:12、30
Disclosure calendar pattern, IRBANK 4832 disclosure index怎么使用:直接证据;一手验证:30;专项深挖:30
Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English)怎么使用:直接证据;一手验证:11、30、35;专项深挖:30、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Disclosure calendar pattern, IRBANK 4832 disclosure index;直接证据 / 一手证据(研究域11) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English)
完整研究记录(核对用)
研究原文:The next hard evidence is the Q3 FY3/27 release expected in late January 2027: nine-month progress against the second-half-weighted forecast will confirm the plan's delivery pattern or expose the unchanged guidance as optimism; the FY3/27 results in April 2027 then set the final-year plan debate and the year-end dividend; the next mid-term plan (2027) resets capital policy. Open question: does nine-month progress confirm roughly ¥4,305m of H2 operating income, with Q3 showing seasonal build, or is guidance revised? Undated decisive events: a parent sell-down or float measure, a named next large JFE Steel programme.
内部研究类型:CatalystAndResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Calendar catalysts are certain to occur; their content is the variable.
不确定性(原始记录):Whether Q3 discloses any unit-level order split is unknown; governance catalysts are calendar-free.
F025|07|约四分之一的流通股,使价格在财报日前后分步调整
研究范围:35项覆盖检查
写入正文:07|约四分之一的流通股,使价格在财报日前后分步调整13|剩余未上市证券是什么,AI会怎样改变计费基础,价格平台能否守住第三季度
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check怎么使用:直接 / 支持;外部现实校验:34、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 外部现实(研究域34) / 外部现实(研究域35)|Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check
完整研究记录(核对用)
研究原文:With roughly a quarter of shares effectively floating and ordinary daily volume in the tens of thousands, price discovery in this name happens in steps around disclosures; expectations open at results and close slowly. This is a fundamental-register explanation for how the market reprices, offered as context and not as Technical evidence. Open question carried across lanes: whether price holds its recent lower region through the Q3 print or breaks toward the 60-month average, which would signal the market has stopped believing the plan bridge; the Technical State itself remains the protected source and is not restated here.
内部研究类型:CrossLaneContext
内部来源标记:COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Thin float magnifies disclosure-day moves and makes the captive discount persistent without a parent action.
不确定性(原始记录):Inference (~0.7); no analyst consensus or flow data opened.
F026|04|生成式AI可能改变按工时计费的基础,现有披露无法衡量
研究范围:35项覆盖检查
写入正文:04|生成式AI可能改变按工时计费的基础,现有披露无法衡量13|剩余未上市证券是什么,AI会怎样改变计费基础,价格平台能否守住第三季度
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:04、10;专项深挖:04、10
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:04、12、14
Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025怎么使用:直接证据;一手验证:04;专项深挖:04;同业比较:03、04;其他用途:历史
Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English)怎么使用:直接证据;一手验证:11、30、35;专项深挖:30、35
People indicators: certifications, diversity certification and headcount, Q2 FY3/27 overview and company data怎么使用:直接证据;一手验证:06;专项深挖:06
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 定向深挖(研究域04)|Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025;直接证据 / 一手证据(研究域11) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English);直接证据 / 一手证据(研究域06) / 定向深挖(研究域06)|People indicators: certifications, diversity certification and headcount, Q2 FY3/27 overview and company data
完整研究记录(核对用)
研究原文:No disclosure quantifies how the generative-AI delivery model changes the billing base. Management applies generative AI to its own products, services and delivery processes; if AI compresses billed engineering hours faster than package and platform revenue scales, the 1,960-person labour base becomes a fixed-cost problem, otherwise it is operating leverage. Open question: which unit revenue lines are exposed and what replaces them?
内部研究类型:ResearchDebt
内部来源标记:COVERAGE35
普通股东含义(原始记录):The one genuinely new competitive vector for an hours-based SI model; unquantifiable from current disclosure.
不确定性(原始记录):No productivity or pricing data exists publicly in opened materials.
F027|09|正常化营业利润65亿至75亿日元,每股收益140至160日元(研究估算)
研究范围:35项覆盖检查
写入正文:09|正常化营业利润65亿至75亿日元,每股收益140至160日元(研究估算)
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English)怎么使用:直接证据;一手验证:28;专项深挖:28
2026年3月期 決算短信〔日本基準〕(連結)怎么使用:直接证据;一手验证:22、28;同业比较:16、17、35;其他用途:历史
Reference: history of net sales by reporting unit (consolidated totals), Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:28、33;专项深挖:33;同业比较:02、09、11、14、28;其他用途:历史
Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信怎么使用:直接证据;一手验证:06、16;专项深挖:16
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English);直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域35)|2026年3月期 決算短信〔日本基準〕(連結);直接证据 / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域14) / 历史/同业比较(研究域28) / 定向深挖(研究域33)|Reference: history of net sales by reporting unit (consolidated totals), Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域06) / 一手证据(研究域16) / 定向深挖(研究域16)|Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信
完整研究记录(核对用)
研究原文:Research-constructed (not company guidance) normalisation across the refresh cycle: operating income ¥7,589m at the peak (FY3/25), ¥6,346m in the roll-off year, ¥6,600m forecast, with structurally higher gross margin (25.1–26.0% vs 23.6%). A defensible mid-cycle operating range on the current perimeter is ¥6.5–7.5bn and EPS about ¥140–160 on the current share count, rising toward the plan's final-year level if external units deliver. Trough-EPS anchoring overstates expensiveness; peak-EPS anchoring understates the mix improvement.
内部研究类型:NormalizedEconomicsEstimate
内部来源标记:COVERAGE35
普通股东含义(原始记录):Honest valuation anchor is a range tested quarterly.
不确定性(原始记录):Unit margins undisclosed; range depends on external units delivering volume.
F028|13|什么会推翻这个判断
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论13|什么会推翻这个判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:35;专项深挖:15、35
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接证据;一手验证:23、30、31、35
Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English)怎么使用:直接证据;一手验证:11、30、35;专项深挖:30、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据 / 一手证据(研究域11) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English)
完整研究记录(核对用)
研究原文:Thesis falsifiers: (1) Q3 FY3/27 forces a guidance cut, so the planned-air-pocket reading is wrong; (2) backlog falls for a second consecutive half, so the refill engine is not working and the FY3/28 bridge is fiction; (3) the payout rule is diluted in the next plan or the FY3/27 year-end decision, so the return contract breaks; (4) price closes below the 2026 low and then below the 60-month average (~¥1,610), the cited price-side falsifier. Either fundamental or price leg failing alone weakens but does not kill the thesis.
内部研究类型:FalsificationConditions
内部来源标记:COVERAGE35
普通股东含义(原始记录):A holder knows within two quarters whether the position is working.
不确定性(原始记录):Falsifier (4) depends on a thin-float tape.
F029|09|下行有四层保护,最坏情形是多年的估值倍数压缩
研究范围:35项覆盖检查
写入正文:09|下行有四层保护,最坏情形是多年的估值倍数压缩
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接证据;一手验证:18、21、22、29;同业比较:19;其他用途:历史
Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement怎么使用:直接证据;一手验证:17、18、29、32;外部现实校验:32;专项深挖:17、18、29
Lease and retirement-benefit liabilities, FY3/26 consolidated balance sheet怎么使用:直接证据;一手验证:18、29;专项深挖:18、29
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接证据;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 一手证据(研究域17) / 一手证据(研究域18) / 一手证据(研究域29) / 一手证据(研究域32) / 外部现实(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域18) / 定向深挖(研究域29)|Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement;直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Lease and retirement-benefit liabilities, FY3/26 consolidated balance sheet;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832
完整研究记录(核对用)
研究原文:Downside layers: (1) the balance sheet (67% equity, no debt, deposits ≈46% of market cap); (2) a ~3.8% yield on a 50% payout that survived a down year; (3) a structural demand floor from the parent's ongoing operation of its works systems, though uncontracted; (4) the post-2023 price shelf. Against these, the thin float cuts both ways and plan failure would compress the earnings multiple toward ex-cash asset value. Realistic worst case is years of multiple compression toward deposit value, bounded and monitorable.
内部研究类型:DownsideStructure
内部来源标记:COVERAGE35
普通股东含义(原始记录):Downside is a valuation grind rather than a solvency event.
不确定性(原始记录):No contractual minimum for group work; price-shelf layer can break; the payout has no floor.
F030|05|优势在长期因素里,弱点在半年一变的订单里
研究范围:开放研究+35项覆盖检查
写入正文:05|优势在长期因素里,弱点在半年一变的订单里14|财务、盈利和商业结构四个模块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:04、10;专项深挖:04、10
Product franchise evidence, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:03、09、10、13;外部现实校验:03、04;专项深挖:03、09、10
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接证据;一手验证:18、21、22、29;同业比较:19;其他用途:历史
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
Industry environment as described in the FY3/26 短信 management review怎么使用:直接证据;一手验证:11、14;外部现实校验:02、05、06;专项深挖:11、14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 定向深挖(研究域03) / 定向深挖(研究域09) / 定向深挖(研究域10)|Product franchise evidence, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域11) / 一手证据(研究域14) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域14)|Industry environment as described in the FY3/26 短信 management review
完整研究记录(核对用)
研究原文:Slow variables: Japanese manufacturers' core-system renewal cycle; the steel industry's investment rhythm (the group unit's floor is a cycle not a cliff, though timing is the parent's choice); package franchises that sit inside compliance and closing processes; steel-operations knowledge (about 200 million migrated steps, tacit and hard to re-hire); the 67% equity-ratio balance sheet. Fast variables: half-by-half order intake, the FY3/28 bridge arithmetic, and JFE Holdings' evolving stance on listed subsidiaries. The structure is durable where slow and fragile where fast; the equity case is that the slow variables outlast the fast ones.
内部研究类型:StructuralDurabilityMap
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Tells the holder which variables to underwrite and which to treat as weather.
不确定性(原始记录):Moat evidence is circumstantial; no churn or renewal-rate disclosure.
F031|研究发现
研究范围:35项覆盖检查
写入正文:15|数据截至2026年11月6日收盘,评审日期为2026年11月9日15|证据的限制:这些是公开资料里查不到的信息,不代表公司有问题
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接证据;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
Reporting-unit definitions, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:02、03、07;专项深挖:02、03
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
Accounting-policy stance and disclosure omissions, FY3/26 短信怎么使用:直接证据;一手验证:13、25;专项深挖:13、32
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接证据;一手验证:14、16、32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域03)|Reporting-unit definitions, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域13) / 一手证据(研究域25) / 定向深挖(研究域13) / 定向深挖(研究域32)|Accounting-policy stance and disclosure omissions, FY3/26 短信;直接证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信
完整研究记录(核对用)
研究原文:Material evidence limits carried forward: no analyst consensus (forecast multiples rest on company guidance); no unit-level orders, backlog or margins; subcontractor ratios and utilisation undisclosed; revenue split between development, operation/maintenance and packages undisclosed; independent-director composition and minority-protection measures (CG report) not captured; large-holding filings after March 2026 not swept; securities-report related-party, tax and major-customer notes not opened; H1 cash-flow statement not opened; no churn data. These are absences of public information in the opened materials, not evidence of weakness.
内部研究类型:ResearchDebtCluster
内部来源标记:COVERAGE35
普通股东含义(原始记录):Confidence is medium; each gap would sharpen margin, concentration or governance judgments.
不确定性(原始记录):Next evidence: FY3/27 securities report (June 2027) and Q3/full-year releases.
F032|04|在钢铁和制造业里有深度,规模上比不过NTT DATA
研究范围:35项覆盖检查
写入正文:04|在钢铁和制造业里有深度,规模上比不过NTT DATA
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Product franchise evidence, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:03、09、10、13;外部现实校验:03、04;专项深挖:03、09、10
Major news and press releases, first half FY Ending March 2027 (appendix), Q2 results overview (English)怎么使用:直接证据;一手验证:03、07、09、10;外部现实校验:07
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接证据;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:04、10;专项深挖:04、10
Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025怎么使用:直接证据;一手验证:04;专项深挖:04;同业比较:03、04;其他用途:历史
Segment information note, FY3/26 短信 notes怎么使用:直接证据;一手验证:02、08、13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 定向深挖(研究域03) / 定向深挖(研究域09) / 定向深挖(研究域10)|Product franchise evidence, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域03) / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域10) / 外部现实(研究域07)|Major news and press releases, first half FY Ending March 2027 (appendix), Q2 results overview (English);直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 定向深挖(研究域04)|Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025;直接证据 / 一手证据(研究域02) / 一手证据(研究域08) / 一手证据(研究域13)|Segment information note, FY3/26 短信 notes
完整研究记录(核对用)
研究原文:Position is a niche rather than scale: the incumbent systems house of Japan's second steel group with an award-winning flagship migration and package franchises with documented share leadership; outside steel it is one credible manufacturing-SI name among NTT Data at scale, NS Solutions as the directly comparable captive, and the broader SIer set, with customers' in-house IT, vendor-direct implementation and AI-assisted development as substitutes. Switching costs are operational rather than contractual (running the customer's core systems; packages inside compliance workflows). Moat weakening would appear first in backlog and orders. Previous-plan service business reached ¥6.49bn vs ¥5.0bn target.
内部研究类型:MoatAndCompetition
内部来源标记:COVERAGE35
普通股东含义(原始记录):Moat protects the margin path the thesis depends on and sustains incumbency pricing at renewal.
不确定性(原始记录):No head-to-head win/loss, churn or share data; competitor framing is structural.
F033|03|外部需求被公司描述为稳固,公司自己的订单却没有跟上
研究范围:开放研究+35项覆盖检查
写入正文:03|外部需求被公司描述为稳固,公司自己的订单却没有跟上
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:05、15
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接证据;一手验证:11
Industry environment as described in the FY3/26 短信 management review怎么使用:直接证据;一手验证:11、14;外部现实校验:02、05、06;专项深挖:11、14
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:35;专项深挖:15、35
Orders received and order backlog, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:05、15;外部现实校验:19;反向验证:05、15、35;专项深挖:05、15、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025);直接证据 / 一手证据(研究域11) / 一手证据(研究域14) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域14)|Industry environment as described in the FY3/26 短信 management review;直接证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域05) / 一手证据(研究域15) / 外部现实(研究域19) / 反证(研究域05) / 反证(研究域15) / 反证(研究域35) / 定向深挖(研究域05) / 定向深挖(研究域15) / 定向深挖(研究域35)|Orders received and order backlog, Q2 FY3/27 overview (English)
完整研究记录(核对用)
研究原文:External demand (core-systems renewal, cloud migration, security and data utilisation across steel, automotive, chemicals and other manufacturing; manufacturing DX budgets) is described as solid and is the refill engine for the group hole. The company's order intake (−8.3% in H1) lags that description, so the gap appears company-specific. Market growth is a durable but slow tailwind; the plan requires share gains every year, not market beta.
内部研究类型:EndMarketDemand
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The single external variable deciding whether the FY3/28 bridge is arithmetic or aspiration.
不确定性(原始记录):No third-party market-size series opened; market read is the company's own.
F034|03|最大客户同时是持股65.16%的母公司
研究范围:开放研究
写入正文:03|最大客户同时是持股65.16%的母公司14|财务、盈利和商业结构四个模块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:01、23、24
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接证据;一手验证:02、05、15
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:04、12、14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section
完整研究记录(核对用)
研究原文:JFEスチール (JFE Steel Corporation) is the 65.16% parent, the anchor customer behind the JFE Group unit (¥21,993m, about 38% of FY3/26 sales) and the owner of the steelworks whose refresh drove the FY3/22–25 up-cycle and whose completion drives the current down-cycle.
内部研究类型:RelatedParty
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Guarantees a demand floor and strategic patience, but its capex rhythm sets the largest revenue line and no sell-down is stated.
不确定性(原始记录):Standalone transaction amount and pricing terms undisclosed in opened materials.
F035|07|客户和控股股东是同一方,需求风险和治理风险合在一起
研究范围:开放研究
写入正文:07|客户和控股股东是同一方,需求风险和治理风险合在一起11|催化剂是日历上的三个检验,加上两件没有日期的事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)
完整研究记录(核对用)
研究原文:JFEホールディングス (JFE Holdings, Inc.) is the ultimate parent that controls JFE Steel; any end-state for the listed-subsidiary structure (maintained, tightened or unwound) is decided at this level, not by JFE Systems' board.
内部研究类型:RelatedParty
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The governance re-rating or parent sell-down catalyst is entirely this group's choice.
不确定性(原始记录):No stated intention.
F036|04|在钢铁和制造业里有深度,规模上比不过NTT DATA
研究范围:开放研究+35项覆盖检查
写入正文:04|在钢铁和制造业里有深度,规模上比不过NTT DATA
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Segment information note, FY3/26 短信 notes怎么使用:直接证据;一手验证:02、08、13
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接证据;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域08) / 一手证据(研究域13)|Segment information note, FY3/26 短信 notes;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832
完整研究记录(核对用)
研究原文:NTT DATA Group is Japan's largest systems integrator and competes for enterprise and manufacturing DX demand, setting scale benchmarks for delivery capacity and pricing; JFE Systems' defence is depth in steel and manufacturing operations rather than breadth.
内部研究类型:Competitor
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Losing niche focus would remove the moat, not just share.
不确定性(原始记录):No public win-rate data.
F037|04|NS Solutions是直接可比公司,也是估值和治理的参照
研究范围:开放研究+35项覆盖检查
写入正文:04|NS Solutions是直接可比公司,也是估值和治理的参照
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:01、23、24
4832 market snapshot, IRBANK怎么使用:直接证据;一手验证:27、31;外部现实校验:01、08、14、23、26、31
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接证据;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域08) / 外部现实(研究域14) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域31)|4832 market snapshot, IRBANK;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832
完整研究记录(核对用)
研究原文:NS Solutions (2327), Nippon Steel's captive SIer (63.44% parent-held), is the directly comparable listed steel-group SIer and the natural valuation and governance comp; divergence between the two multiples reads which parent's intentions the market trusts more.
内部研究类型:Competitor
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Shows both the ceiling and the template of a captive trading on plan delivery and payout.
不确定性(原始记录):Comp figures come from the research's own prior work on 2327, used structurally only.
F038|03|其他JFE集团公司既是客户,也是小股东
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接证据;一手验证:02、05、15
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)
完整研究记录(核对用)
研究原文:Other JFE group companies are both customers inside the JFE Group business unit and small shareholders (JFE Plant Engineering 1.27%, JFE Advantech 0.64%, JFE Logistics 0.64%); their work is a partial hedge against the steel cycle but prices and behaves as related-party work.
内部研究类型:RelatedParty
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Its growth inside ComService is the number to watch for genuine versus re-channelled expansion.
不确定性(原始记录):Split not disclosed.
F039|03|ERP业务靠SAP和Microsoft两家平台,增长一部分押在它们的客户基础上
研究范围:开放研究+35项覆盖检查
写入正文:03|ERP业务靠SAP和Microsoft两家平台,增长一部分押在它们的客户基础上
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Reporting-unit definitions, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:02、03、07;专项深挖:02、03
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:05、15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域03)|Reporting-unit definitions, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)
完整研究记录(核对用)
研究原文:SAP and Microsoft ERP platforms are the load-bearing platforms of the ERP Solutions unit (core systems integrating them with the company's own templates, plus BI/DWH); the +21.1% planned ERP growth is partly a bet on two vendors' installed bases and upgrade cycles, exposed if vendors move toward direct or AI-led implementation.
内部研究类型:PlatformPartner
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Supplies implementation pipeline without origination cost, at the price of roadmap dependence.
不确定性(原始记录):No alliance revenue split disclosed; no partner-side confirmation.
F040|04|钢铁厂的投资周期决定集团业务的下一次大订单
研究范围:开放研究+35项覆盖检查
写入正文:04|钢铁厂的投资周期决定集团业务的下一次大订单11|最大的风险来自母公司的周期,最大的变数是下一个大项目何时到来
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:35;专项深挖:15、35
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)
完整研究记录(核对用)
研究原文:Steelmakers' periodic core-system rebuilds create multi-year SI programmes (the refresh is the completed example). Management says it is stepping up efforts to secure future orders for large projects after the refresh; the timing and size of the next JFE Steel programme is the swing factor that can make the FY3/28 bridge trivial or impossible.
内部研究类型:IndustryCycle
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Buying the trough is partly buying the parent's calendar.
不确定性(原始记录):Next programme undisclosed.
F041|06|三处会计表述会误导机械筛选,修正后的图像更平常
研究范围:35项覆盖检查
写入正文:06|三处会计表述会误导机械筛选,修正后的图像更平常
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接证据;一手验证:14、16、32
Extraordinary and non-operating items, FY3/26 consolidated income statement怎么使用:直接证据;一手验证:21、32;专项深挖:32;同业比较:21;其他用途:历史
Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement怎么使用:直接证据;一手验证:17、18、29、32;外部现实校验:32;专项深挖:17、18、29
Accounting-policy stance and disclosure omissions, FY3/26 短信怎么使用:直接证据;一手验证:13、25;专项深挖:13、32
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review怎么使用:直接证据;一手验证:17、19、20;同业比较:32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信;直接证据 / 一手证据(研究域21) / 一手证据(研究域32) / 历史/同业比较(研究域21) / 定向深挖(研究域32)|Extraordinary and non-operating items, FY3/26 consolidated income statement;直接证据 / 一手证据(研究域17) / 一手证据(研究域18) / 一手证据(研究域29) / 一手证据(研究域32) / 外部现实(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域18) / 定向深挖(研究域29)|Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement;直接证据 / 一手证据(研究域13) / 一手证据(研究域25) / 定向深挖(研究域13) / 定向深挖(研究域32)|Accounting-policy stance and disclosure omissions, FY3/26 短信;直接证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 历史/同业比较(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review
完整研究记录(核对用)
研究原文:The accounts are simple and largely clean (Japanese GAAP by explicit choice, expensed R&D, no dilutive securities, goodwill ¥269m, no going-concern note), but three items distort naive screens: the ¥281m unlisted-securities write-down, the time-deposit reshuffle making investing cash flow (−¥15,849m) misleading, and FY3/26 operating cash flow flattered by receivables release. None is aggressive; corrections make the picture more ordinary, not worse.
内部研究类型:AccountingPresentation
内部来源标记:COVERAGE35
普通股东含义(原始记录):Screen-driven holders may misread the name in both directions.
不确定性(原始记录):Full securities-report notes (tax, related parties) were not opened.
F042|04|监管和宏观是顺风或二阶影响,没有发现重大依赖
研究范围:35项覆盖检查
写入正文:04|监管和宏观是顺风或二阶影响,没有发现重大依赖11|最大的风险来自母公司的周期,最大的变数是下一个大项目何时到来
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Accounting-policy stance and disclosure omissions, FY3/26 短信怎么使用:直接证据;一手验证:13、25;专项深挖:13、32
Product franchise evidence, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:03、09、10、13;外部现实校验:03、04;专项深挖:03、09、10
Industry environment as described in the FY3/26 短信 management review怎么使用:直接证据;一手验证:11、14;外部现实校验:02、05、06;专项深挖:11、14
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:04、12、14
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接证据;一手验证:14、16、32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 一手证据(研究域25) / 定向深挖(研究域13) / 定向深挖(研究域32)|Accounting-policy stance and disclosure omissions, FY3/26 短信;直接证据 / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 定向深挖(研究域03) / 定向深挖(研究域09) / 定向深挖(研究域10)|Product franchise evidence, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域11) / 一手证据(研究域14) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域14)|Industry environment as described in the FY3/26 短信 management review;直接证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信
完整研究记录(核对用)
研究原文:Regulation is a demand tailwind rather than a risk (electronic-books preservation law and e-invoice regimes support the package franchises); no licence, tariff or subsidy dependence of consequence was found. Macro transmission is narrow and domestic: corporate IT budgets, engineer wage inflation and short rates on deposit income; yen and commodity effects arrive second-order via customers.
内部研究类型:ExposureProfile
内部来源标记:COVERAGE35
普通股东含义(原始记录):Low-beta domestic compounder by construction; no macro hedges or windfalls.
不确定性(原始记录):Spring wage outcomes not yet visible.
F043|03|最大客户同时是持股65.16%的母公司
研究范围:开放研究
写入正文:03|最大客户同时是持股65.16%的母公司14|财务、盈利和商业结构四个模块
归并到:F034
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:01、23、24
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接证据;一手验证:02、05、15
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:04、12、14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section
完整研究记录(核对用)
研究原文:Parent holds 65.16% and supplies the anchor JFE Group demand block; the parent's grip guarantees a floor but caps the governance re-rating available to minorities.
内部研究类型:CAPITAL_AND_ANCHOR_CUSTOMER
内部来源标记:OPEN_DISCOVERY
F044|07|客户和控股股东是同一方,需求风险和治理风险合在一起
研究范围:开放研究
写入正文:07|客户和控股股东是同一方,需求风险和治理风险合在一起11|催化剂是日历上的三个检验,加上两件没有日期的事
归并到:F035
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)
完整研究记录(核对用)
研究原文:JFE Holdings controls JFE Steel, the direct 65.16% holder; the listed-subsidiary end-state cannot be delivered by JFE Systems' own board alone.
内部研究类型:ULTIMATE_PARENT_CONTROL
内部来源标记:OPEN_DISCOVERY
F045|01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面
研究范围:开放研究
写入正文:01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面13|JFE ComService自己赚多少,增长55.3%里有多少是母公司转来的工作
归并到:F017
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接证据;一手验证:02、05、15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据|Share count, treasury stock and per-share notes, FY3/26 短信;直接证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English)
完整研究记录(核对用)
研究原文:JFE ComService is a partly owned consolidated subsidiary (non-controlling interests ¥1,231m) providing infrastructure and SI to the JFE Group and behind the +55.3% planned subsidiary jump; it is where part of post-refresh group work may be re-homed, an early indicator of whether group demand is shrinking or re-channelled.
内部研究类型:CAPITAL_PARTLY_OWNED_SUBSIDIARY
内部来源标记:OPEN_DISCOVERY
F046|02|合并范围里没有第二台引擎,上市主体基本就是母公司
研究范围:开放研究
写入正文:02|合并范围里没有第二台引擎,上市主体基本就是母公司
归并到:F018
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Major news and press releases, first half FY Ending March 2027 (appendix), Q2 results overview (English)怎么使用:直接证据;一手验证:03、07、09、10;外部现实校验:07
Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:07;专项深挖:02、07
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域03) / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域10) / 外部现实(研究域07)|Major news and press releases, first half FY Ending March 2027 (appendix), Q2 results overview (English);直接证据 / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域07)|Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English)
完整研究记录(核对用)
研究原文:IAF Consulting is a consolidated subsidiary providing BI and management-visualisation consulting; small, but the consulting tip of the data-platform strategy on which ERP and Digital Manufacturing growth claims rest.
内部研究类型:CAPITAL_SUBSIDIARY
内部来源标记:OPEN_DISCOVERY
F047|04|在钢铁和制造业里有深度,规模上比不过NTT DATA
研究范围:开放研究
写入正文:04|在钢铁和制造业里有深度,规模上比不过NTT DATA
归并到:F036
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Segment information note, FY3/26 短信 notes怎么使用:直接证据;一手验证:02、08、13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域08) / 一手证据(研究域13)|Segment information note, FY3/26 短信 notes
完整研究记录(核对用)
研究原文:Bidirectional competition for enterprise and manufacturing DX demand against the scale leader; JFE Systems' defence is niche depth.
内部研究类型:COMPETITOR
内部来源标记:OPEN_DISCOVERY
F048|04|NS Solutions是直接可比公司,也是估值和治理的参照
研究范围:开放研究
写入正文:04|NS Solutions是直接可比公司,也是估值和治理的参照
归并到:F037
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:01、23、24
4832 market snapshot, IRBANK怎么使用:直接证据;一手验证:27、31;外部现实校验:01、08、14、23、26、31
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域08) / 外部现实(研究域14) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域31)|4832 market snapshot, IRBANK
完整研究记录(核对用)
研究原文:NS Solutions is the directly comparable captive steel-group SIer and the natural valuation/governance comp; divergence in multiples reads which parent the market trusts more.
内部研究类型:COMPETITOR_AND_VALUATION_COMP
内部来源标记:OPEN_DISCOVERY
F049|03|外部需求被公司描述为稳固,公司自己的订单却没有跟上
研究范围:开放研究
写入正文:03|外部需求被公司描述为稳固,公司自己的订单却没有跟上
归并到:F033
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:05、15
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接证据;一手验证:11
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)
完整研究记录(核对用)
研究原文:Manufacturers' DX budgets feed the Digital Manufacturing, ERP and Industry units and are the refill engine for the group hole.
内部研究类型:END_MARKET_DEMAND
内部来源标记:OPEN_DISCOVERY
F050|03|其他JFE集团公司既是客户,也是小股东
研究范围:开放研究
归并到:F038
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接证据;一手验证:02、05、15
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)
完整研究记录(核对用)
研究原文:Other JFE group companies are customers inside the JFE Group unit and small shareholders; a partial hedge against the steel cycle priced as related-party work.
内部研究类型:CUSTOMER_AND_MINOR_SHAREHOLDER
内部来源标记:OPEN_DISCOVERY
F051|03|ERP业务靠SAP和Microsoft两家平台,增长一部分押在它们的客户基础上
研究范围:开放研究
写入正文:03|ERP业务靠SAP和Microsoft两家平台,增长一部分押在它们的客户基础上
归并到:F039
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Reporting-unit definitions, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:02、03、07;专项深挖:02、03
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:05、15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域03)|Reporting-unit definitions, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)
完整研究记录(核对用)
研究原文:The ERP unit builds core systems on SAP and Microsoft platforms; growth is levered to the vendors' installed bases and delivery-model choices.
内部研究类型:PLATFORM_PARTNER
内部来源标记:OPEN_DISCOVERY
F052|07|控制权绝对,流通股很薄,没有外部力量能推动资本政策
研究范围:开放研究+35项覆盖检查
写入正文:07|控制权绝对,流通股很薄,没有外部力量能推动资本政策14|估值、资本政策、治理和技术四个模块
归并到:F011
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)
完整研究记录(核对用)
研究原文:The employee shareholding association (6.65%) is a stable management-aligned block; with the parent and group companies it takes allied holdings to about three quarters, so float-driven governance pressure is structurally unavailable and disclosure-day price discovery dominates.
内部研究类型:FLOAT_COMPRESSION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F053|04|钢铁厂的投资周期决定集团业务的下一次大订单
研究范围:开放研究+35项覆盖检查
写入正文:04|钢铁厂的投资周期决定集团业务的下一次大订单11|最大的风险来自母公司的周期,最大的变数是下一个大项目何时到来
归并到:F040
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:35;专项深挖:15、35
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)
完整研究记录(核对用)
研究原文:The next JFE Steel large-project cycle is the group unit's largest future revenue event and decides whether the FY3/28 bridge is easy or impossible.
内部研究类型:INBOUND_CYCLE_SWING_FACTOR
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F054|01|2026年3月期的下滑来自一个项目收尾,外部业务全部在增长
研究范围:开放研究+35项覆盖检查
写入正文:01|2026年3月期的下滑来自一个项目收尾,外部业务全部在增长
归并到:F070
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
2026年3月期 決算短信〔日本基準〕(連結)怎么使用:直接 / 支持;一手验证:22、28;同业比较:16、17、35;其他用途:历史
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:04、12、14
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:28;专项深挖:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域35)|2026年3月期 決算短信〔日本基準〕(連結);直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English)
完整研究记录(核对用)
研究原文:Completion of the refresh removes the largest group project and creates the planned FY3/26–27 air pocket that external growth must bridge.
内部研究类型:CAUSES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F055|06|销售下滑时毛利率反而上升,来自收入结构变化,与涨价无关
研究范围:开放研究+35项覆盖检查
写入正文:06|销售下滑时毛利率反而上升,来自收入结构变化,与涨价无关12|三个反直觉的细节:最差的利润年有最好的现金流,也有最高的毛利率14|财务、盈利和商业结构四个模块
归并到:F004
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信怎么使用:直接 / 支持;一手验证:06、16;专项深挖:16
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接 / 支持;一手验证:14、16、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 定向深挖(研究域16)|Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信;直接证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English)
完整研究记录(核对用)
研究原文:Roll-off of subcontractor-heavy refresh work mechanically lifted consolidated gross margin even as revenue shrank.
内部研究类型:CAUSES_MIX_SHIFT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F056|06|上半年毛利润增长3.1%,营业利润仍下降13.9%,原因是销售管理费提前增加
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|上半年毛利润增长3.1%,营业利润仍下降13.9%,原因是销售管理费提前增加
归并到:F005
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Factors affecting operating income changes in Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;专项深挖:28
SG&A movement and its stated drivers, FY3/26 短信 and Q2 FY3/27 overview怎么使用:直接 / 支持;一手验证:06、16;反向验证:28;专项深挖:16
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:支持证据;一手验证:05、15
查看完整证据标签(核对用)
直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 定向深挖(研究域28)|Factors affecting operating income changes in Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 反证(研究域28) / 定向深挖(研究域16)|SG&A movement and its stated drivers, FY3/26 短信 and Q2 FY3/27 overview;支持证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)
完整研究记录(核对用)
研究原文:Deliberate SG&A growth absorbed the gross-profit gain, so operating income fell despite rising gross profit in H1.
内部研究类型:OFFSETS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F057|08|净资产收益率下降一半来自分母,50%分红只是下限
研究范围:开放研究+35项覆盖检查
写入正文:08|净资产收益率下降一半来自分母,50%分红只是下限12|三个反直觉的细节:最差的利润年有最好的现金流,也有最高的毛利率13|276亿日元存款的期限和收益是多少,董事会是否评估过回购,50%分红能否延续
归并到:F010
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
ROE, EPS and BPS path, FY3/26 短信 headline indicators怎么使用:直接 / 支持;一手验证:22;外部现实校验:17、20;专项深挖:22;同业比较:27;其他用途:历史
Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement怎么使用:直接证据;一手验证:17、18、29、32;外部现实校验:32;专项深挖:17、18、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域17) / 外部现实(研究域20) / 历史/同业比较(研究域27) / 定向深挖(研究域22)|ROE, EPS and BPS path, FY3/26 短信 headline indicators;直接证据 / 一手证据(研究域17) / 一手证据(研究域18) / 一手证据(研究域29) / 一手证据(研究域32) / 外部现实(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域18) / 定向深挖(研究域29)|Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement
完整研究记录(核对用)
研究原文:Retention at a 50% payout builds the deposit pile that earns deposit rates, diluting ROE unless earnings refill, payout rises or cash is deployed.
内部研究类型:DILUTES_RETURN
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F058|08|净资产收益率下降一半来自分母,50%分红只是下限
研究范围:开放研究+35项覆盖检查
写入正文:08|净资产收益率下降一半来自分母,50%分红只是下限12|三个反直觉的细节:最差的利润年有最好的现金流,也有最高的毛利率13|276亿日元存款的期限和收益是多少,董事会是否评估过回购,50%分红能否延续
归并到:F010
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
ROE, EPS and BPS path, FY3/26 短信 headline indicators怎么使用:直接 / 支持;一手验证:22;外部现实校验:17、20;专项深挖:22;同业比较:27;其他用途:历史
Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:26;专项深挖:26;同业比较:25;其他用途:历史
Shareholder-return policy statement, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:25;专项深挖:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域17) / 外部现实(研究域20) / 历史/同业比较(研究域27) / 定向深挖(研究域22)|ROE, EPS and BPS path, FY3/26 短信 headline indicators;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域25) / 定向深挖(研究域26)|Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|Shareholder-return policy statement, Q2 FY3/27 overview (English)
完整研究记录(核对用)
研究原文:ROE defence is a plausible motive for hardening the payout to 50%.
内部研究类型:MOTIVATES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F059|01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面
研究范围:开放研究+35项覆盖检查
写入正文:01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面13|订单余额减少的2,490万日元……实际是24.90亿日元,集中在哪个单元
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Orders received and order backlog, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:05、15;外部现实校验:19;反向验证:05、15、35;专项深挖:05、15、35
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接 / 支持;一手验证:11
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:支持证据;一手验证:23、30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15) / 外部现实(研究域19) / 反证(研究域05) / 反证(研究域15) / 反证(研究域35) / 定向深挖(研究域05) / 定向深挖(研究域15) / 定向深挖(研究域35)|Orders received and order backlog, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025);直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);支持证据|Mid-term plan sales path by unit (plan document charts), 25 April 2025
完整研究记录(核对用)
研究原文:Falling orders and backlog are the counter-evidence to the plan's external-growth bridge and are not yet explained by unit.
内部研究类型:COUNTER_EVIDENCE_TO
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F060|01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面
研究范围:开放研究+35项覆盖检查
写入正文:01|反面证据:订单和订单余额都在下降,计划最难的一年还在后面13|JFE ComService自己赚多少,增长55.3%里有多少是母公司转来的工作
归并到:F017
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:07;专项深挖:02、07
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:35;专项深挖:15、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域07)|Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)
完整研究记录(核对用)
研究原文:The largest planned growth line may be partly group work moved into a subsidiary, so the headline external refill rate may be overstated.
内部研究类型:QUALIFIES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F061|05|更新项目既是失去的收入,也是对外销售的凭证
研究范围:开放研究+35项覆盖检查
归并到:F016
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English)怎么使用:直接 / 支持;一手验证:04、10;专项深挖:04、10
Major news and press releases, first half FY Ending March 2027 (appendix), Q2 results overview (English)怎么使用:直接证据;一手验证:03、07、09、10;外部现实校验:07
Product franchise evidence, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:03、09、10、13;外部现实校验:03、04;专项深挖:03、09、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域03) / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域10) / 外部现实(研究域07)|Major news and press releases, first half FY Ending March 2027 (appendix), Q2 results overview (English);直接证据 / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 定向深挖(研究域03) / 定向深挖(研究域09) / 定向深挖(研究域10)|Product franchise evidence, Q2 FY3/27 overview appendix (English)
完整研究记录(核对用)
研究原文:The refresh credential supports external wins in legacy migration, but conversion into orders has not yet been disclosed.
内部研究类型:SUPPORTS_CONDITIONALLY
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F062|11|催化剂是日历上的三个检验,加上两件没有日期的事
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论11|催化剂是日历上的三个检验,加上两件没有日期的事13|第三季度财报:九个月进度是否支撑下半年约43亿日元营业利润
归并到:F024
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接 / 支持;一手验证:12、31;外部现实校验:12、30
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接 / 支持;一手验证:23、30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance;直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)
完整研究记录(核对用)
研究原文:The Q3 print tests unchanged guidance against 35.2% H1 progress.
内部研究类型:TESTS
内部来源标记:OPEN_DISCOVERY
F063|09|正常化营业利润65亿至75亿日元,每股收益140至160日元(研究估算)
研究范围:35项覆盖检查
写入正文:09|正常化营业利润65亿至75亿日元,每股收益140至160日元(研究估算)
归并到:F027
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English)怎么使用:直接证据;一手验证:28;专项深挖:28
Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信怎么使用:直接 / 支持;一手验证:06、16;专项深挖:16
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:支持证据;一手验证:14、16、32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 定向深挖(研究域16)|Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信;支持证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信
完整研究记录(核对用)
研究原文:Higher structural gross margin is why the next revenue peak should print higher profit, anchoring the normalised range.
内部研究类型:SUPPORTS
内部来源标记:COVERAGE35
F064|06|三处会计表述会误导机械筛选,修正后的图像更平常
研究范围:35项覆盖检查
写入正文:06|三处会计表述会误导机械筛选,修正后的图像更平常
归并到:F041
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review怎么使用:直接 / 支持;一手验证:17、19、20;同业比较:32;其他用途:历史
Working-capital detail, FY3/26 consolidated balance sheet and cash-flow statement怎么使用:直接 / 支持;一手验证:17、19;专项深挖:19
Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement怎么使用:直接证据;一手验证:17、18、29、32;外部现实校验:32;专项深挖:17、18、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 历史/同业比较(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 定向深挖(研究域19)|Working-capital detail, FY3/26 consolidated balance sheet and cash-flow statement;直接证据 / 一手证据(研究域17) / 一手证据(研究域18) / 一手证据(研究域29) / 一手证据(研究域32) / 外部现实(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域18) / 定向深挖(研究域29)|Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement
完整研究记录(核对用)
研究原文:Presentation effects (time-deposit reshuffle, receivables unwind) qualify naive reads of FY3/26 cash flow.
内部研究类型:QUALIFIES
内部来源标记:COVERAGE35
F065|07|客户和控股股东是同一方,需求风险和治理风险合在一起
研究范围:开放研究+35项覆盖检查
写入正文:07|客户和控股股东是同一方,需求风险和治理风险合在一起
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:01、23、24
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接证据;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.怎么使用:支持证据;一手验证:01、24
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:支持证据;一手验证:02、05、15
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:支持证据;一手验证:04、12、14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract);支持证据 / 一手证据(研究域01) / 一手证据(研究域24)|Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.;支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);支持证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section
完整研究记录(核对用)
研究原文:The anchor customer is also the controlling shareholder, so demand risk and governance risk are one party's decisions.
内部研究类型:SAME_COUNTERPARTY_DUAL_ROLE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F066|07|约四分之一的流通股,使价格在财报日前后分步调整
研究范围:35项覆盖检查
写入正文:07|约四分之一的流通股,使价格在财报日前后分步调整13|剩余未上市证券是什么,AI会怎样改变计费基础,价格平台能否守住第三季度
归并到:F025
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check怎么使用:直接 / 支持;外部现实校验:34、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 外部现实(研究域34) / 外部现实(研究域35)|Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check
完整研究记录(核对用)
研究原文:Register structure is a fundamental-side context for how price reprices around disclosures. The relation references the protected Technical Synthesis as a whole; it does not redefine or rewrite it.
内部研究类型:CROSS_LANE_CONTEXT
内部来源标记:COVERAGE35 / TECHNICAL
F067|10|价格结构的变化早于后来被公开确认的基本面变化,第三季度财报是两条线共同的检验点
研究范围:35项覆盖检查
写入正文:10|价格结构的变化早于后来被公开确认的基本面变化,第三季度财报是两条线共同的检验点13|剩余未上市证券是什么,AI会怎样改变计费基础,价格平台能否守住第三季度
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接 / 支持;一手验证:23、30、31、35
Disclosure calendar pattern, IRBANK 4832 disclosure index怎么使用:直接证据;一手验证:30;专项深挖:30
Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check怎么使用:直接证据;外部现实校验:34、35
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:支持证据;一手验证:12、31;外部现实校验:12、30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Disclosure calendar pattern, IRBANK 4832 disclosure index;直接证据 / 外部现实(研究域34) / 外部现实(研究域35)|Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check;支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance
完整研究记录(核对用)
研究原文:The Q3 FY3/27 print is the shared dated checkpoint for the fundamental thesis and the Technical question. Fundamental positivity or confirmation cannot rewrite a non-confirming Technical State, and the Technical State does not prove the fundamental thesis.
内部研究类型:SHARED_CHECKPOINT
内部来源标记:COVERAGE35 / TECHNICAL
F068|10|月线有两段人生:2001至2022年长期低价,2023年起才抬到1,000日元以上
写入正文:10|月线有两段人生:2001至2022年长期低价,2023年起才抬到1,000日元以上10|2023至2025年台阶式上行带量,2026年1月的新高只高出一点10|现在是平台整理,状态中性,价格围着24个月均线转10|价格结构的变化早于后来被公开确认的基本面变化,第三季度财报是两条线共同的检验点10|站稳还是破位:三个确认信号和三个失效信号14|估值、资本政策、治理和技术四个模块
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (dereference only)
内部研究类型:ProtectedTechnicalSynthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
F069|02|长期因素是更新周期、软件包和轻资产,短期变数是订单与母公司态度
研究范围:开放研究+35项覆盖检查
写入正文:02|长期因素是更新周期、软件包和轻资产,短期变数是订单与母公司态度
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(42项,重复标签已合并)
Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.怎么使用:直接 / 支持;一手验证:01、24
Segment information note, FY3/26 短信 notes怎么使用:直接 / 支持;一手验证:02、08、13
Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract)怎么使用:直接证据;同业比较:06;其他用途:历史
Reporting-unit definitions, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:02、03、07;专项深挖:02、03
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:支持证据;一手验证:23、30、31、35
Product franchise evidence, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:03、09、10、13;外部现实校验:03、04;专项深挖:03、09、10
Major news and press releases, first half FY Ending March 2027 (appendix), Q2 results overview (English)怎么使用:直接证据;一手验证:03、07、09、10;外部现实校验:07
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接 / 支持;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English)怎么使用:直接 / 支持;一手验证:04、10;专项深挖:04、10
Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025怎么使用:直接证据;一手验证:04;专项深挖:04;同业比较:03、04;其他用途:历史
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:05、15
Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信怎么使用:直接 / 支持;一手验证:06、16;专项深挖:16
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接 / 支持;一手验证:14、16、32
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接 / 支持;一手验证:12、31;外部现实校验:12、30
Working-capital detail, FY3/26 consolidated balance sheet and cash-flow statement怎么使用:直接 / 支持;一手验证:17、19;专项深挖:19
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review怎么使用:直接 / 支持;一手验证:17、19、20;同业比较:32;其他用途:历史
Interim balance-sheet movements, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:19
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement怎么使用:直接 / 支持;一手验证:17、18、29、32;外部现实校验:32;专项深挖:17、18、29
Lease and retirement-benefit liabilities, FY3/26 consolidated balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、29
ROE, EPS and BPS path, FY3/26 短信 headline indicators怎么使用:直接 / 支持;一手验证:22;外部现实校验:17、20;专项深挖:22;同业比较:27;其他用途:历史
Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:26;专项深挖:26;同业比较:25;其他用途:历史
Shareholder-return policy statement, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:25;专项深挖:25
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:01、23、24
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
Capital and share-count history from securities reports, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:01、25;专项深挖:01、25;同业比较:18、24;其他用途:历史
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:04、12、14
Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English)怎么使用:直接证据;一手验证:28;专项深挖:28
2026年3月期 決算短信〔日本基準〕(連結)怎么使用:直接证据;一手验证:22、28;同业比较:16、17、35;其他用途:历史
Reference: history of net sales by reporting unit (consolidated totals), Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:28、33;专项深挖:33;同业比较:02、09、11、14、28;其他用途:历史
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
Industry environment as described in the FY3/26 短信 management review怎么使用:直接证据;一手验证:11、14;外部现实校验:02、05、06;专项深挖:11、14
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接证据;一手验证:11
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:35;专项深挖:15、35
Orders received and order backlog, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:05、15;外部现实校验:19;反向验证:05、15、35;专项深挖:05、15、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域24)|Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域08) / 一手证据(研究域13)|Segment information note, FY3/26 短信 notes;直接证据 / 历史/同业比较(研究域06)|Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域03)|Reporting-unit definitions, Q2 FY3/27 overview (English);直接证据|Parent-only results vs consolidated, FY3/26 短信 reference section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据 / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 定向深挖(研究域03) / 定向深挖(研究域09) / 定向深挖(研究域10)|Product franchise evidence, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域03) / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域10) / 外部现实(研究域07)|Major news and press releases, first half FY Ending March 2027 (appendix), Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 定向深挖(研究域04)|Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025;直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 定向深挖(研究域16)|Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信;直接证据 / 支持证据|Q1 FY3/27 results summary (from the company's Q1 短信 of 29 July 2026);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 定向深挖(研究域19)|Working-capital detail, FY3/26 consolidated balance sheet and cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 历史/同业比较(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review;直接证据 / 一手证据(研究域19)|Interim balance-sheet movements, Q2 FY3/27 overview (English);直接证据|Q1 FY3/27 balance-sheet summary (from the Q1 短信 of 29 July 2026);直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域18) / 一手证据(研究域29) / 一手证据(研究域32) / 外部现实(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域18) / 定向深挖(研究域29)|Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Lease and retirement-benefit liabilities, FY3/26 consolidated balance sheet;直接证据|Balance sheet as of Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域17) / 外部现实(研究域20) / 历史/同业比较(研究域27) / 定向深挖(研究域22)|ROE, EPS and BPS path, FY3/26 短信 headline indicators;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域25) / 定向深挖(研究域26)|Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|Shareholder-return policy statement, Q2 FY3/27 overview (English);直接证据|Share count, treasury stock and per-share notes, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域25) / 历史/同业比较(研究域18) / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域25)|Capital and share-count history from securities reports, gBizINFO (EDINET extract);直接证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English);直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域35)|2026年3月期 決算短信〔日本基準〕(連結);直接证据 / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域14) / 历史/同业比较(研究域28) / 定向深挖(研究域33)|Reference: history of net sales by reporting unit (consolidated totals), Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域11) / 一手证据(研究域14) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域14)|Industry environment as described in the FY3/26 短信 management review;直接证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025);直接证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域05) / 一手证据(研究域15) / 外部现实(研究域19) / 反证(研究域05) / 反证(研究域15) / 反证(研究域35) / 定向深挖(研究域05) / 定向深挖(研究域15) / 定向深挖(研究域35)|Orders received and order backlog, Q2 FY3/27 overview (English)
完整研究记录(核对用)
研究原文:Durable business portrait: a captive SIer with a capital-light, debt-free core|A people-and-software SI franchise with incumbent switching costs in steel and manufacturing, package annuities inside compliance workflows, tiny capital needs, strong cash conversion, no debt, and a parent-controlled register. Durable where variables are slow (franchises, knowledge, balance sheet, renewal cycle) and fragile where fast (orders, parent intentions). Current change (project completion, mix shift, SG&A pre-spend) is an increment to this foundation, not a replacement.
内部研究类型:DurableBusinessPortrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Downside is asset-anchored and cash-backed; per-share compounding is limited by capital allocation and a persistent captive discount unless the parent acts or external growth outruns the group decline.
不确定性(原始记录):Moat and recurrence are evidenced circumstantially; unit-level economics and churn undisclosed.
F070|01|2026年3月期的下滑来自一个项目收尾,外部业务全部在增长
研究范围:开放研究+35项覆盖检查
写入正文:01|2026年3月期的下滑来自一个项目收尾,外部业务全部在增长
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(23项,重复标签已合并)
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:35;专项深挖:15、35
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
2026年3月期 決算短信〔日本基準〕(連結)怎么使用:直接 / 支持;一手验证:22、28;同业比较:16、17、35;其他用途:历史
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:04、12、14
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
Reference: history of net sales by reporting unit (consolidated totals), Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:28、33;专项深挖:33;同业比较:02、09、11、14、28;其他用途:历史
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接 / 支持;一手验证:23、30、31、35
Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:28;专项深挖:28
Segment information note, FY3/26 短信 notes怎么使用:直接 / 支持;一手验证:02、08、13
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:05、15
Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信怎么使用:直接 / 支持;一手验证:06、16;专项深挖:16
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接 / 支持;一手验证:14、16、32
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接 / 支持;一手验证:12、31;外部现实校验:12、30
SG&A movement and its stated drivers, FY3/26 短信 and Q2 FY3/27 overview怎么使用:直接 / 支持;一手验证:06、16;反向验证:28;专项深挖:16
Factors affecting operating income changes in Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;专项深挖:28
People indicators: certifications, diversity certification and headcount, Q2 FY3/27 overview and company data怎么使用:直接证据;一手验证:06;专项深挖:06
Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract)怎么使用:直接证据;同业比较:06;其他用途:历史
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接 / 支持;一手验证:11
Review of the previous Mid-Term Management Plan FY2022-2024, plan document of 25 April 2025怎么使用:直接 / 支持;同业比较:10、12、22、26;其他用途:历史
Orders received and order backlog, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:05、15;外部现实校验:19;反向验证:05、15、35;专项深挖:05、15、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域35)|2026年3月期 決算短信〔日本基準〕(連結);直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域14) / 历史/同业比较(研究域28) / 定向深挖(研究域33)|Reference: history of net sales by reporting unit (consolidated totals), Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域08) / 一手证据(研究域13)|Segment information note, FY3/26 短信 notes;直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 定向深挖(研究域16)|Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信;直接证据 / 支持证据|Q1 FY3/27 results summary (from the company's Q1 短信 of 29 July 2026);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 反证(研究域28) / 定向深挖(研究域16)|SG&A movement and its stated drivers, FY3/26 短信 and Q2 FY3/27 overview;直接证据 / 定向深挖(研究域28)|Factors affecting operating income changes in Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域06) / 定向深挖(研究域06)|People indicators: certifications, diversity certification and headcount, Q2 FY3/27 overview and company data;直接证据 / 历史/同业比较(研究域06)|Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025);直接证据 / 支持证据 / 历史/同业比较(研究域10) / 历史/同业比较(研究域12) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Review of the previous Mid-Term Management Plan FY2022-2024, plan document of 25 April 2025;直接证据 / 支持证据|Mid-term plan sales path by unit (plan document charts), 25 April 2025;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15) / 外部现实(研究域19) / 反证(研究域05) / 反证(研究域15) / 反证(研究域35) / 定向深挖(研究域05) / 定向深挖(研究域15) / 定向深挖(研究域35)|Orders received and order backlog, Q2 FY3/27 overview (English)
完整研究记录(核对用)
研究原文:Project chain: steelmaker capex office to this P&L's gross margin|JFE Steel's investment calendar created the refresh, the refresh created the revenue peak, its completion creates the air pocket, and the air pocket forces the mix shift; one causal chain runs from a steelmaker's capex office to gross margin, and the next programme's timing decides whether the final-year bridge is easy.
内部研究类型:CausalChain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Earnings are a levered read on the spread between the group cycle and the external cycle.
不确定性(原始记录):Next group programme and unit-level orders undisclosed.
F071|06|没有借款,现金占市值46%,但大半已转成定期存款
研究范围:开放研究+35项覆盖检查
写入正文:06|没有借款,现金占市值46%,但大半已转成定期存款
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(16项,重复标签已合并)
Working-capital detail, FY3/26 consolidated balance sheet and cash-flow statement怎么使用:直接 / 支持;一手验证:17、19;专项深挖:19
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review怎么使用:直接 / 支持;一手验证:17、19、20;同业比较:32;其他用途:历史
Interim balance-sheet movements, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:19
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement怎么使用:直接 / 支持;一手验证:17、18、29、32;外部现实校验:32;专项深挖:17、18、29
Lease and retirement-benefit liabilities, FY3/26 consolidated balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、29
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接 / 支持;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
ROE, EPS and BPS path, FY3/26 短信 headline indicators怎么使用:直接 / 支持;一手验证:22;外部现实校验:17、20;专项深挖:22;同业比较:27;其他用途:历史
Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:26;专项深挖:26;同业比较:25;其他用途:历史
Shareholder-return policy statement, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:25;专项深挖:25
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接证据;一手验证:14、16、32
Extraordinary and non-operating items, FY3/26 consolidated income statement怎么使用:直接证据;一手验证:21、32;专项深挖:32;同业比较:21;其他用途:历史
Accounting-policy stance and disclosure omissions, FY3/26 短信怎么使用:直接证据;一手验证:13、25;专项深挖:13、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 定向深挖(研究域19)|Working-capital detail, FY3/26 consolidated balance sheet and cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 历史/同业比较(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review;直接证据 / 一手证据(研究域19)|Interim balance-sheet movements, Q2 FY3/27 overview (English);直接证据|Q1 FY3/27 balance-sheet summary (from the Q1 短信 of 29 July 2026);直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域18) / 一手证据(研究域29) / 一手证据(研究域32) / 外部现实(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域18) / 定向深挖(研究域29)|Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Lease and retirement-benefit liabilities, FY3/26 consolidated balance sheet;直接证据|Balance sheet as of Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832;直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域17) / 外部现实(研究域20) / 历史/同业比较(研究域27) / 定向深挖(研究域22)|ROE, EPS and BPS path, FY3/26 短信 headline indicators;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域25) / 定向深挖(研究域26)|Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|Shareholder-return policy statement, Q2 FY3/27 overview (English);直接证据|Share count, treasury stock and per-share notes, FY3/26 短信;直接证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信;直接证据 / 一手证据(研究域21) / 一手证据(研究域32) / 历史/同业比较(研究域21) / 定向深挖(研究域32)|Extraordinary and non-operating items, FY3/26 consolidated income statement;直接证据 / 一手证据(研究域13) / 一手证据(研究域25) / 定向深挖(研究域13) / 定向深挖(研究域32)|Accounting-policy stance and disclosure omissions, FY3/26 短信
完整研究记录(核对用)
研究原文:Treasury chain: a debt-free balance sheet turns volatility into timing|Operating cash flow of ¥8,448m in the worst earnings year, a ¥27.6bn deposit pile and rising interest income (¥107m) cushion ordinary income above operating income, converting earnings volatility into mere timing, while the same pile dilutes ROE and distorts naive cash-flow screens.
内部研究类型:CausalChain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Solvency is not the issue; allocation of retained cash is.
不确定性(原始记录):Deposit ladder and yield undisclosed; FY3/26 cash flow includes one-offs.
F072|08|分红已写成政策,约50%的比例没有下限,也没有回购
研究范围:开放研究+35项覆盖检查
写入正文:08|分红已写成政策,约50%的比例没有下限,也没有回购
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(10项,重复标签已合并)
ROE, EPS and BPS path, FY3/26 短信 headline indicators怎么使用:直接 / 支持;一手验证:22;外部现实校验:17、20;专项深挖:22;同业比较:27;其他用途:历史
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:26;专项深挖:26;同业比较:25;其他用途:历史
Shareholder-return policy statement, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:25;专项深挖:25
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Interim dividend decision and year-end revision notice summary, Japan IR (TDnet)怎么使用:直接 / 支持;一手验证:26;专项深挖:26;同业比较:30;其他用途:历史
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check怎么使用:直接 / 支持;外部现实校验:34、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域17) / 外部现实(研究域20) / 历史/同业比较(研究域27) / 定向深挖(研究域22)|ROE, EPS and BPS path, FY3/26 短信 headline indicators;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域25) / 定向深挖(研究域26)|Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|Shareholder-return policy statement, Q2 FY3/27 overview (English);直接证据 / 支持证据|Share count, treasury stock and per-share notes, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 支持证据|H1 FY3/27 短信 summary: dividend revision (interim ¥24 decided, year-end ¥46), Japan IR summary of TDnet filing;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域30) / 定向深挖(研究域26)|Interim dividend decision and year-end revision notice summary, Japan IR (TDnet);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 外部现实(研究域34) / 外部现实(研究域35)|Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check
完整研究记录(核对用)
研究原文:Return chain: payout rule, ROE defence and the yield under the price|The 50% payout converted the dividend from a residual into a contracted share of earnings, which is why DPS rose 11.5% in a year EPS fell 21.6%; the yield of about 3.8% is part of the valuation floor.
内部研究类型:CausalChain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Income holders get a growing but cyclical stream with no buyback kicker; a diluted payout would break the return contract.
不确定性(原始记录):Post-FY3/28 policy and the board's buyback stance unknown; the price-floor role of the yield is an inference.
F073|07|约四分之一的流通股,使价格在财报日前后分步调整
研究范围:开放研究+35项覆盖检查
写入正文:07|约四分之一的流通股,使价格在财报日前后分步调整
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.怎么使用:直接 / 支持;一手验证:01、24
Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:01、23、24
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
Capital and share-count history from securities reports, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:01、25;专项深挖:01、25;同业比较:18、24;其他用途:历史
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:04、12、14
Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check怎么使用:直接 / 支持;外部现实校验:34、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域24)|Company Factsheet (COMPANY DATA 2026.6), JFE Systems, Inc.;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Major shareholders and parent-only indicators from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域25) / 历史/同业比较(研究域18) / 历史/同业比较(研究域24) / 定向深挖(研究域01) / 定向深挖(研究域25)|Capital and share-count history from securities reports, gBizINFO (EDINET extract);直接证据|Share count, treasury stock and per-share notes, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 外部现实(研究域34) / 外部现实(研究域35)|Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check
完整研究记录(核对用)
研究原文:Float chain: parent control, thin float and disclosure-day repricing|65.16% parent ownership plus allied holders compress the float to about a quarter, so no market mechanism forces float expansion, buybacks or asset deployment and valuation debates are settled at the four disclosure dates.
内部研究类型:CausalChain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The captive discount is structurally persistent unless the parent acts; a sell-down or float measure would be the largest catalyst and is entirely the parent's choice.
不确定性(原始记录):No stated parent intention; post-March holdings not swept.
F074|04|生成式AI可能改变按工时计费的基础,现有披露无法衡量
研究范围:开放研究+35项覆盖检查
写入正文:04|生成式AI可能改变按工时计费的基础,现有披露无法衡量
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(18项,重复标签已合并)
SG&A movement and its stated drivers, FY3/26 短信 and Q2 FY3/27 overview怎么使用:直接 / 支持;一手验证:06、16;反向验证:28;专项深挖:16
Factors affecting operating income changes in Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;专项深挖:28
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接 / 支持;一手验证:14、16、32
People indicators: certifications, diversity certification and headcount, Q2 FY3/27 overview and company data怎么使用:直接证据;一手验证:06;专项深挖:06
Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract)怎么使用:直接证据;同业比较:06;其他用途:历史
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:05、15
Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信怎么使用:直接 / 支持;一手验证:06、16;专项深挖:16
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接 / 支持;一手验证:12、31;外部现实校验:12、30
Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:04、10;专项深挖:04、10
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接证据;一手验证:04、12、14
Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025怎么使用:直接证据;一手验证:04;专项深挖:04;同业比较:03、04;其他用途:历史
Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English)怎么使用:直接证据;一手验证:11、30、35;专项深挖:30、35
Orders received and order backlog, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:05、15;外部现实校验:19;反向验证:05、15、35;专项深挖:05、15、35
Industry environment as described in the FY3/26 短信 management review怎么使用:直接证据;一手验证:11、14;外部现实校验:02、05、06;专项深挖:11、14
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:支持证据;一手验证:23、30、31、35
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:支持证据;一手验证:11
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 反证(研究域28) / 定向深挖(研究域16)|SG&A movement and its stated drivers, FY3/26 短信 and Q2 FY3/27 overview;直接证据 / 定向深挖(研究域28)|Factors affecting operating income changes in Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信;直接证据 / 一手证据(研究域06) / 定向深挖(研究域06)|People indicators: certifications, diversity certification and headcount, Q2 FY3/27 overview and company data;直接证据 / 历史/同业比较(研究域06)|Parent-only five-year indicators from the securities report, gBizINFO (EDINET extract);直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 定向深挖(研究域16)|Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信;直接证据 / 支持证据|Q1 FY3/27 results summary (from the company's Q1 短信 of 29 July 2026);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 定向深挖(研究域04)|Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025;直接证据 / 一手证据(研究域11) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15) / 外部现实(研究域19) / 反证(研究域05) / 反证(研究域15) / 反证(研究域35) / 定向深挖(研究域05) / 定向深挖(研究域15) / 定向深挖(研究域35)|Orders received and order backlog, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域11) / 一手证据(研究域14) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域14)|Industry environment as described in the FY3/26 短信 management review;支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);支持证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)
完整研究记录(核对用)
研究原文:Labour chain: workforce as product, cost pre-spend and constraint|Hiring ahead of the refill depresses today's margin and is the same action that makes tomorrow's delivery possible; SG&A is where the strategy is actually happening, and AI delivery productivity decides whether billed-hour economics survive. Backlog is the test of whether the pre-spend converts.
内部研究类型:CausalChain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operating leverage in either direction on a pre-spent cost base; wage-cycle risk with no asset hedge.
不确定性(原始记录):No data on AI effect on billed hours, utilisation or subcontractor ratios.
F075|01|指引原样不变,管理层把可信度押在第三季度
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(11项,重复标签已合并)
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:05、15
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接 / 支持;一手验证:12、31;外部现实校验:12、30
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接 / 支持;一手验证:23、30、31、35
Progress rates and the Q2-only quarter, Kabutan flash of 28 October 2026怎么使用:直接 / 支持;外部现实校验:15、16、28;专项深挖:31
Interim dividend decision and year-end revision notice summary, Japan IR (TDnet)怎么使用:直接 / 支持;一手验证:26;专项深挖:26;同业比较:30;其他用途:历史
Disclosure calendar pattern, IRBANK 4832 disclosure index怎么使用:直接证据;一手验证:30;专项深挖:30
Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English)怎么使用:直接证据;一手验证:11、30、35;专项深挖:30、35
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接证据;一手验证:35;专项深挖:15、35
查看完整证据标签(核对用)
直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance;直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据 / 支持证据|H1 FY3/27 短信 summary: dividend revision (interim ¥24 decided, year-end ¥46), Japan IR summary of TDnet filing;直接证据 / 支持证据|Q1 FY3/27 results summary (from the company's Q1 短信 of 29 July 2026);直接证据 / 支持证据 / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域28) / 定向深挖(研究域31)|Progress rates and the Q2-only quarter, Kabutan flash of 28 October 2026;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域30) / 定向深挖(研究域26)|Interim dividend decision and year-end revision notice summary, Japan IR (TDnet);直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Disclosure calendar pattern, IRBANK 4832 disclosure index;直接证据 / 一手证据(研究域11) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English);直接证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)
完整研究记录(核对用)
研究原文:Credibility chain: unchanged guidance against 35.2% progress with a dated test|Management has made its own narrative cheap to check: unchanged guidance, an interim dividend raised and year-end trimmed, and a second-half-weighted forecast converge on the Q3 print as a falsifiable promise, which is either confidence or a self-made trap.
内部研究类型:CausalChain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Each confirmed checkpoint should compress the doubt discount; a miss damages earnings and credibility together.
不确定性(原始记录):Cannot be resolved before late January 2027.
F076|01|核心问题是外部业务补上集团缺口的速度,两个季度内就有第一个答案
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|核心问题是外部业务补上集团缺口的速度,两个季度内就有第一个答案14|总分61.22/100,B级,观察为主、不追高
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(23项,重复标签已合并)
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接 / 支持;一手验证:23、30、31、35
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接 / 支持;一手验证:11
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接 / 支持;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
Disclosure calendar pattern, IRBANK 4832 disclosure index怎么使用:直接 / 支持;一手验证:30;专项深挖:30
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:35;专项深挖:15、35
Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English)怎么使用:直接证据;一手验证:11、30、35;专项深挖:30、35
Review of the previous Mid-Term Management Plan FY2022-2024, plan document of 25 April 2025怎么使用:直接 / 支持;同业比较:10、12、22、26;其他用途:历史
Orders received and order backlog, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:05、15;外部现实校验:19;反向验证:05、15、35;专项深挖:05、15、35
Industry environment as described in the FY3/26 短信 management review怎么使用:直接证据;一手验证:11、14;外部现实校验:02、05、06;专项深挖:11、14
Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:07;专项深挖:02、07
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:04、12、14
Sales by business for Q2 FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:05、15
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接 / 支持;一手验证:12、31;外部现实校验:12、30
Progress rates and the Q2-only quarter, Kabutan flash of 28 October 2026怎么使用:直接 / 支持;外部现实校验:15、16、28;专项深挖:31
Interim dividend decision and year-end revision notice summary, Japan IR (TDnet)怎么使用:直接 / 支持;一手验证:26;专项深挖:26;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025);直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832;直接证据 / 支持证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Disclosure calendar pattern, IRBANK 4832 disclosure index;直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域11) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English);直接证据 / 支持证据 / 历史/同业比较(研究域10) / 历史/同业比较(研究域12) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Review of the previous Mid-Term Management Plan FY2022-2024, plan document of 25 April 2025;直接证据 / 支持证据|Mid-term plan sales path by unit (plan document charts), 25 April 2025;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15) / 外部现实(研究域19) / 反证(研究域05) / 反证(研究域15) / 反证(研究域35) / 定向深挖(研究域05) / 定向深挖(研究域15) / 定向深挖(研究域35)|Orders received and order backlog, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域11) / 一手证据(研究域14) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域14)|Industry environment as described in the FY3/26 短信 management review;直接证据 / 支持证据 / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域07)|Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English);直接证据|Non-controlling interests, FY3/26 consolidated statements;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15)|Sales by business for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance;直接证据 / 支持证据|H1 FY3/27 短信 summary: dividend revision (interim ¥24 decided, year-end ¥46), Japan IR summary of TDnet filing;直接证据 / 支持证据|Q1 FY3/27 results summary (from the company's Q1 短信 of 29 July 2026);直接证据 / 支持证据 / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域28) / 定向深挖(研究域31)|Progress rates and the Q2-only quarter, Kabutan flash of 28 October 2026;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域30) / 定向深挖(研究域26)|Interim dividend decision and year-end revision notice summary, Japan IR (TDnet)
完整研究记录(核对用)
研究原文:Thesis: captive SIer in metamorphosis, asset-anchored with execution upside|The thesis is an arithmetic claim (mix + external bridge + payout + asset floor versus price) with dated falsifiers. Strongest counter-evidence is falling orders and backlog, possible re-channelled group growth, and parent-cycle dependence, which temper confidence.
内部研究类型:ThesisAndFalsification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Position resolves within two quarters on the Q3 and full-year prints; downside is bounded by cash, upside conditional on delivery or a governance event.
不确定性(原始记录):Medium confidence; many drivers are unit-level and undisclosed.
F077|09|下行由资产托底,上行靠计划兑现,两端都可以按日期检验
研究范围:开放研究+35项覆盖检查
写入正文:09|下行由资产托底,上行靠计划兑现,两端都可以按日期检验
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(22项,重复标签已合并)
4832 market snapshot, IRBANK怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、08、14、23、26、31
2026年3月期 決算短信〔日本基準〕(連結)怎么使用:直接 / 支持;一手验证:22、28;同业比较:16、17、35;其他用途:历史
Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review怎么使用:直接 / 支持;一手验证:17、19、20;同业比较:32;其他用途:历史
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接 / 支持;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
Annual price ranges and valuation at extremes, IRBANK 4832怎么使用:直接证据;外部现实校验:24、27、33;同业比较:08、29、31;其他用途:历史
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接 / 支持;一手验证:11
Disclosure calendar pattern, IRBANK 4832 disclosure index怎么使用:直接 / 支持;一手验证:30;专项深挖:30
Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English)怎么使用:直接证据;一手验证:28;专项深挖:28
Reference: history of net sales by reporting unit (consolidated totals), Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:28、33;专项深挖:33;同业比较:02、09、11、14、28;其他用途:历史
Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信怎么使用:直接 / 支持;一手验证:06、16;专项深挖:16
Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement怎么使用:直接 / 支持;一手验证:17、18、29、32;外部现实校验:32;专项深挖:17、18、29
Lease and retirement-benefit liabilities, FY3/26 consolidated balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、29
Interim balance-sheet movements, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:19
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:26;专项深挖:26;同业比较:25;其他用途:历史
Shareholder-return policy statement, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:25;专项深挖:25
Interim dividend decision and year-end revision notice summary, Japan IR (TDnet)怎么使用:直接证据;一手验证:26;专项深挖:26;同业比较:30;其他用途:历史
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:支持证据;一手验证:14、16、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域08) / 外部现实(研究域14) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域31)|4832 market snapshot, IRBANK;直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域35)|2026年3月期 決算短信〔日本基準〕(連結);直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 历史/同业比较(研究域32)|Consolidated cash flow FY3/26, FY3/26 短信 cash-flow statement and review;直接证据 / 支持证据|Balance sheet as of Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 支持证据|H1 FY3/27 短信 summary: dividend revision (interim ¥24 decided, year-end ¥46), Japan IR summary of TDnet filing;直接证据 / 支持证据|Share count, treasury stock and per-share notes, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832;直接证据 / 外部现实(研究域24) / 外部现实(研究域27) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域29) / 历史/同业比较(研究域31)|Annual price ranges and valuation at extremes, IRBANK 4832;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025);直接证据 / 支持证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Disclosure calendar pattern, IRBANK 4832 disclosure index;直接证据 / 一手证据(研究域28) / 定向深挖(研究域28)|Factors affecting operating income changes in the FY3/27 forecast, Q2 results overview (English);直接证据 / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域14) / 历史/同业比较(研究域28) / 定向深挖(研究域33)|Reference: history of net sales by reporting unit (consolidated totals), Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域16) / 定向深挖(研究域16)|Gross profit and cost of sales, FY3/25–FY3/26 consolidated income statements, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域18) / 一手证据(研究域29) / 一手证据(研究域32) / 外部现实(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域18) / 定向深挖(研究域29)|Time-deposit flows and the cash-equivalents reconciliation, FY3/26 cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|Lease and retirement-benefit liabilities, FY3/26 consolidated balance sheet;直接证据 / 一手证据(研究域19)|Interim balance-sheet movements, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 一手证据(研究域26) / 历史/同业比较(研究域25) / 定向深挖(研究域26)|Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域25) / 定向深挖(研究域25)|Shareholder-return policy statement, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域26) / 历史/同业比较(研究域30) / 定向深挖(研究域26)|Interim dividend decision and year-end revision notice summary, Japan IR (TDnet);支持证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信
完整研究记录(核对用)
研究原文:Valuation bridge: cash floor, normalised earnings and expectation test|Visible cash is not in dispute, so the debate is about the earnings multiple on a ¥6.5–7.5bn normalised range and payout durability; the market already paid a compounder's multiple within the last year.
内部研究类型:ValuationBridge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Valuation anchored on trough EPS overstates expense; the honest anchor is a range tested quarterly.
不确定性(原始记录):No consensus; EV treatment of leases, pension and minorities simplified; normalised range is a Research estimate.
F078|13|第三季度财报:九个月进度是否支撑下半年约43亿日元营业利润
研究范围:开放研究+35项覆盖检查
写入正文:13|第三季度财报:九个月进度是否支撑下半年约43亿日元营业利润13|什么会推翻这个判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(35项,重复标签已合并)
Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English)怎么使用:直接 / 支持;一手验证:23、30、31、35
H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance怎么使用:直接 / 支持;一手验证:12、31;外部现实校验:12、30
Disclosure calendar pattern, IRBANK 4832 disclosure index怎么使用:直接证据;一手验证:30;专项深挖:30
Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English)怎么使用:直接证据;一手验证:11、30、35;专项深挖:30、35
Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025)怎么使用:直接 / 支持;一手验证:11
Review of the previous Mid-Term Management Plan FY2022-2024, plan document of 25 April 2025怎么使用:直接 / 支持;同业比较:10、12、22、26;其他用途:历史
Orders received and order backlog, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:05、15;外部现实校验:19;反向验证:05、15、35;专项深挖:05、15、35
JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:12、33;专项深挖:12、33;同业比较:05、15;其他用途:历史
FY3/26 management review of operations, FY3/26 短信 qualitative section怎么使用:直接 / 支持;一手验证:04、12、14
Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English)怎么使用:直接 / 支持;一手验证:02、05、15
Industry environment as described in the FY3/26 短信 management review怎么使用:直接证据;一手验证:11、14;外部现实校验:02、05、06;专项深挖:11、14
Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:07;专项深挖:02、07
Net sales forecast by business for FY Ending March 2027, Q2 results overview (English)怎么使用:直接 / 支持;一手验证:35;专项深挖:15、35
ROE, EPS and BPS path, FY3/26 短信 headline indicators怎么使用:直接 / 支持;一手验证:22;外部现实校验:17、20;专项深挖:22;同业比较:27;其他用途:历史
Consolidated balance sheet at 31 March 2026, FY3/26 短信怎么使用:直接 / 支持;一手验证:18、21、22、29;同业比较:19;其他用途:历史
Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:26;专项深挖:26;同业比较:25;其他用途:历史
Shareholder-return policy statement, Q2 FY3/27 overview (English)怎么使用:直接 / 支持;一手验证:25;专项深挖:25
Dividend record and policy, FY3/26 短信 dividend section怎么使用:直接 / 支持;一手验证:26
Interim dividend decision and year-end revision notice summary, Japan IR (TDnet)怎么使用:直接证据;一手验证:26;专项深挖:26;同业比较:30;其他用途:历史
Investment securities and valuation reserves, FY3/26 consolidated balance sheet and income statement怎么使用:直接 / 支持;一手验证:20、21;专项深挖:20、21
Extraordinary and non-operating items, FY3/26 consolidated income statement怎么使用:直接 / 支持;一手验证:21、32;专项深挖:32;同业比较:21;其他用途:历史
Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English)怎么使用:直接证据;一手验证:04、10;专项深挖:04、10
Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025怎么使用:直接证据;一手验证:04;专项深挖:04;同业比较:03、04;其他用途:历史
People indicators: certifications, diversity certification and headcount, Q2 FY3/27 overview and company data怎么使用:直接证据;一手验证:06;专项深挖:06
Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract)怎么使用:直接 / 支持;一手验证:23、24;外部现实校验:13;专项深挖:01、23、24
Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check怎么使用:直接 / 支持;外部现实校验:34、35
Valuation snapshot and extremes, IRBANK 4832怎么使用:直接证据;一手验证:08、09、27;外部现实校验:09、10、11、18、21、22、25、29;专项深挖:08、27、31
Reporting-unit definitions, Q2 FY3/27 overview (English)怎么使用:直接证据;一手验证:02、03、07;专项深挖:02、03
Accounting-policy stance and disclosure omissions, FY3/26 短信怎么使用:直接证据;一手验证:13、25;专项深挖:13、32
Consolidated income statement detail FY3/26, FY3/26 短信怎么使用:直接证据;一手验证:14、16、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30) / 一手证据(研究域31) / 一手证据(研究域35)|Financial forecast for FY Ending March 2027 (unchanged from 24 April 2026), Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域31) / 外部现实(研究域12) / 外部现实(研究域30)|H1 results flash: ordinary income −11.5%, interim dividend raised ¥2, Kabutan news via Yahoo Finance;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Disclosure calendar pattern, IRBANK 4832 disclosure index;直接证据 / 一手证据(研究域11) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Progress against the Mid-term Management Plan at H1 FY3/27, Q2 results overview (English);直接证据 / 支持证据 / 一手证据(研究域11)|Notice Regarding the Formulation of the Mid-Term Management Plan 2025-2027 (25 April 2025);直接证据 / 支持证据 / 历史/同业比较(研究域10) / 历史/同业比较(研究域12) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Review of the previous Mid-Term Management Plan FY2022-2024, plan document of 25 April 2025;直接证据 / 支持证据|Mid-term plan sales path by unit (plan document charts), 25 April 2025;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域15) / 外部现实(研究域19) / 反证(研究域05) / 反证(研究域15) / 反证(研究域35) / 定向深挖(研究域05) / 定向深挖(研究域15) / 定向深挖(研究域35)|Orders received and order backlog, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 定向深挖(研究域12) / 定向深挖(研究域33)|JFE Group unit sales history within the reference chart, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域12) / 一手证据(研究域14)|FY3/26 management review of operations, FY3/26 短信 qualitative section;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域15)|Net sales by reporting unit, FY3/26 results and FY3/27 forecasts, Q2 FY3/27 results overview (English);直接证据 / 支持证据|Financial summary for Q2 FY Ending March 2027, Q2 results overview (English);直接证据 / 一手证据(研究域11) / 一手证据(研究域14) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域14)|Industry environment as described in the FY3/26 短信 management review;直接证据 / 支持证据 / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域07)|Subsidiaries: JFE ComService and IAF Consulting, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域15) / 定向深挖(研究域35)|Net sales forecast by business for FY Ending March 2027, Q2 results overview (English);直接证据|Non-controlling interests, FY3/26 consolidated statements;直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域17) / 外部现实(研究域20) / 历史/同业比较(研究域27) / 定向深挖(研究域22)|ROE, EPS and BPS path, FY3/26 短信 headline indicators;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域22) / 一手证据(研究域29) / 历史/同业比较(研究域19)|Consolidated balance sheet at 31 March 2026, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域25) / 定向深挖(研究域26)|Shareholder returns: dividend history and payout ratios, Q2 FY3/27 overview (English);直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域25)|Shareholder-return policy statement, Q2 FY3/27 overview (English);直接证据 / 支持证据|Share count, treasury stock and per-share notes, FY3/26 短信;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and policy, FY3/26 短信 dividend section;直接证据 / 支持证据|H1 FY3/27 短信 summary: dividend revision (interim ¥24 decided, year-end ¥46), Japan IR summary of TDnet filing;直接证据 / 一手证据(研究域26) / 历史/同业比较(研究域30) / 定向深挖(研究域26)|Interim dividend decision and year-end revision notice summary, Japan IR (TDnet);直接证据 / 支持证据 / 一手证据(研究域20) / 一手证据(研究域21) / 定向深挖(研究域20) / 定向深挖(研究域21)|Investment securities and valuation reserves, FY3/26 consolidated balance sheet and income statement;直接证据 / 支持证据 / 一手证据(研究域21) / 一手证据(研究域32) / 历史/同业比较(研究域21) / 定向深挖(研究域32)|Extraordinary and non-operating items, FY3/26 consolidated income statement;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Steelworks System Refresh Project and the IT Japan Award 2026, Q2 FY3/27 overview appendix (English);直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 定向深挖(研究域04)|Product-development and service-business investment record, Mid-Term Plan document of 25 April 2025;直接证据 / 一手证据(研究域06) / 定向深挖(研究域06)|People indicators: certifications, diversity certification and headcount, Q2 FY3/27 overview and company data;直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域13) / 定向深挖(研究域01) / 定向深挖(研究域23) / 定向深挖(研究域24)|Top-ten shareholders from the FY3/26 securities report, gBizINFO (EDINET extract);直接证据 / 支持证据 / 外部现实(研究域34) / 外部现实(研究域35)|Recent daily tape and the October 2025 air pocket, IRBANK 4832 cross-check;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域27) / 外部现实(研究域09) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域25) / 外部现实(研究域29) / 定向深挖(研究域08) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation snapshot and extremes, IRBANK 4832;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域07) / 定向深挖(研究域02) / 定向深挖(研究域03)|Reporting-unit definitions, Q2 FY3/27 overview (English);直接证据 / 一手证据(研究域13) / 一手证据(研究域25) / 定向深挖(研究域13) / 定向深挖(研究域32)|Accounting-policy stance and disclosure omissions, FY3/26 短信;直接证据 / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域32)|Consolidated income statement detail FY3/26, FY3/26 短信
完整研究记录(核对用)
研究原文:Research Debt carried forward|Ten open questions plus evidence limits remain after reasonable public paths were exhausted; none requires reopening public research now, because the resolving evidence is future disclosure (Q3 release, FY3/27 securities report, next plan).
内部研究类型:ResearchDebtCluster
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Highest-VOI items are the Q3 progress test, FY3/28 bridge composition and JFE Steel related-party concentration; the opposite answers would change guidance credibility, plan feasibility and valuation.
不确定性(原始记录):Resolution depends on disclosures the company has not yet made.
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | 72d701a94752b0acccea244ad652eb85a4830a17 |
| Delivery Commit SHA | 72d701a94752b0acccea244ad652eb85a4830a17 |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | f9d61f9e-65b1-5b3f-abc8-1bec253bdecc |
| Canonical Revision | 1 |