资产负债表是证据最扎实的一环:2025年12月期末权益比率63.5%,现金及存款151.80亿日元,借款103.31亿日元,净现金约47亿日元,五年窗口内每年都是净现金。第二层是碳化硅纤维:利润率35.8%,满负荷生产,认证锁定在航空发动机部件上。第三层是2026年的股东回报上调:分红加回购合计约47亿日元,相当于预测净利润27亿日元的1.7倍。
5302
日本カーボン株式会社(Nippon Carbon Co., Ltd.)
日本カーボン株式会社(Nippon Carbon Co., Ltd.,东证 Prime 市场 5302)主营人造石墨电极(电炉炼钢耗材)和精细碳素(半导体、太阳能生产用特种石墨);同时生产碳化硅连续纤维 NICALON(用于航空发动机陶瓷基复合材料)、碳纤维隔热材料和锂电负极材料,并经营工业机械。公司成立于1915年,12月结账。2025年12月期(FY12/25)销售额377.35亿日元,碳素产品、碳化硅产品和其他业务的占比分别为86%、11%和3%左右。
最近亮点:2026年上半年(1–6月)营业利润24.75亿日元,同比下降5.1%,但比2月公布的中期计划(16亿日元)高出54.7%,全年指引没有上调。二季度(4–6月)单季营业利润14.18亿日元,比上年同期高约7%。2026年3月至8月,公司回购52.16万股,金额24.9968亿日元,用满金额上限的99.99%。 估值简报(价格截至2026年11月6日收盘):股价4,610日元(11月9日收盘4,660日元),总市值545.5亿日元(按已发行11,832,504股计,其中约11.0%为库存股)。预测 PER 18.9倍(按2026年12月期公司预测每股收益244.19日元;数据服务商印出18.49倍,差异原因未披露)。实绩 PBR 0.94倍(按2025年12月期末每股净资产4,919.46日元;按2026年6月30日的5,041.20日元算为0.91倍)。ROE 实绩9.1%(2025年12月期,含证券出售收益);预测4.95%为数据服务商按公司指引的推算值。预测股息率4.34%。EV/EBITDA 5.8倍。EV 486.1亿日元=总市值545.5亿日元-净现金59.4亿日元(2026年6月30日现金及存款163.05亿日元减借款103.65亿日元)。EBITDA 83.4亿日元=2025年12月期营业利润48.09亿日元+折旧35.34亿日元。
最大的风险是电极周期的振幅。经常利润从2018年12月期的165.08亿日元降到2020年12月期的35.87亿日元,两年下降约76%;目前51亿日元左右的水平只是周期中段,还没有被证明是新的底部。碳化硅利润又有一半归GE和Safran所有,而全年指引拒绝外推中期的超预期。
结论:Kabugami 评分 V3.2 为60.92/100分,评级 B,行动以观察为主,持有或小仓位跟踪,不追高。 关键依据:这是资产负债表加半个归属的航空纤维专营权的逻辑,不是盈利动能的逻辑。净现金、股价低于账面和4.34%的预测股息率补偿等待时间,但仓位应按电极下行的低谷情景来定,而不是按目前的平台期。三季度财报、2027年2月年报和几份尚未读到的公告会逐项检验这个判断,在读到之前,结论都带条件。 翻转条件:2026年12月期三季度(7–9月)财报下调指引或碳素板块利润率没有继续修复;2027年2月年报没有给出回购到期后的接续回报方案;碳化硅满产下销量下降;电极再度下行使集团营业利润跌破30亿日元左右。数据截至2026年11月9日。 当前动作:观察为主,持有或小仓位跟踪,不追高。理由是投资逻辑建立在资产负债表和半个归属的航空纤维专营权上,而不是盈利动能:净现金、接近账面价、4.3%左右的预测股息率提供等待的补偿,但电极周期的振幅(三年内超过四倍)、碳化硅利润被少数股东分走一半、指引拒绝外推中期超预期,使得按低谷情景定仓位比按平台期更合理。第三季度财报预计在11月10日前后发布,晚于本次研究截止日,应在读到碳素板块利润率是否继续修复、指引是否下调之后再决定加仓或减仓;2027年2月年报是否给出后继回报方案是第二个检验点。若碳素利润率持续未修复、指引下调、碳化硅在满产下销量下降,或电极下行使集团营业利润跌到约30亿日元以下,应降低判断。
报告目录
01|投资问题与当前结论
01.1|净现金加低于账面的价格,买的是等待转换
这只股票要回答的问题是:一家净现金约47亿日元、股价低于每股净资产的材料公司,市场到底在折价什么。研究的答案是折价的对象是利润的波动,不是资产。2025年12月期末权益比率63.5%,现金及存款151.80亿日元,借款103.31亿日元;市值545.5亿日元,市净率0.94倍。而同一家公司的经常利润,三年内可以从165.08亿日元掉到35.87亿日元。
投资逻辑因此落在三条腿上。第一条是资产负债表,证据最扎实,经历过2020年的低谷、2025年8月的富山工厂火灾和一轮扩产。第二条是碳化硅纤维:公司只持有一半,但产能满负荷、利润率35.8%。第三条是资本政策:2026年的分红加回购约47亿日元,相当于预测净利润27亿日元的1.7倍,资金来自资产负债表,而不是当年的自由现金流(2025年12月期约8亿日元)。
持有人拿到的回报机制,是金融资产和留存利润经低于账面价的回购和被守住的分红,变成逐年上升的每股权益,同时利润结构慢慢向高质量产品移动。等待期间由4.34%的预测股息率补偿。估值起点应是2026年12月期预测每股收益244.19日元,而不是含证券出售收益的436.91日元;底部参照研究自己估算的正常化经常利润46亿—71亿日元。把握一般:后两条腿各自只有一次回购、一个季度的修复作证据,几份公开文件也尚未读到(见第13章与第15章)。
01.2|三项反证决定仓位大小
电极周期是最强的反证。经常利润从2018年12月期的165.08亿日元(销售额474.69亿日元)降到2020年12月期的35.87亿日元,约两年跌去76%,此后只回升到2025年12月期的51.03亿日元,销售额再没回到2018年的水平。
2023年至2025年的71.15亿、66.92亿、51.03亿日元,只是周期中段的一个停靠点;再来一轮电极下行,集团利润可能再度减半。精细碳素还有一个与半导体挂钩、节奏不同的周期。
三年内集团利润振幅超过四倍,所以仓位应按低谷情景来定,不能按平台期来定。外部的电极价格序列没有取得,平台能撑多久,无法从财报回答。
第二项反证来自归属。碳化硅增长最快,却放在NGS Advanced Fibers里(公司50%、GE 25%、Safran 25%)。合并口径下少数股东权益92.13亿日元,占净资产14.5%,2025年12月期吸走5.57亿日元净利润(上年7.23亿日元)。增长要按归母利润来读。“一半”只是近似:这笔少数股东权益主要而非全部与NGS有关,碳化硅层面的精确拆分没有披露。
第三项来自指引。2026年上半年营业利润比2月的中期计划高出54.7%,全年指引却原封不动,隐含下半年营业利润18.25亿日元,比上半年实际低26%。这使指引更像地板,而不是对盈利的中间估计,压住了盈利动能的叙事;但下半年为何下降,公司没有说明,所以“地板”是判断,不是已披露的事实。
01.3|什么会推翻这个判断
推翻条件都有日期、可以观察:
一,2026年12月期三季度财报(预计在2026年11月10日前后,日期由往年发布日推断,非公司公告)下调指引,或碳素板块利润率没有继续修复,“一季度事件、不是趋势性下滑”的看法就不成立。
二,2027年2月年报在回购到期后没有给出接续的回报方案,“回报已成政策”的看法不成立。
三,碳化硅在产能未满时销量下降,航空需求稳定的看法不成立。
四,电极再度下行,使集团营业利润跌破30亿日元左右,周期平台的看法不成立。
另外,几处空白条件着所有判断:3月25日关于资本成本与股价的公告内容尚未读到,库存结构互换原因未明,权益法关联公司没有具名,公司没有披露数值化的中期目标。
02|公司本质与商业模式
02.1|公司卖的是客户高温工艺中被消耗掉的材料
日本カーボン株式会社(法定名 Nippon Carbon Kabushiki Kaisha,英文名 Nippon Carbon Co., Ltd.)在东证 Prime 市场上市,代码5302,EDINET 代码 E01140。公司披露文件与同业SEC Carbon的英文官网均使用这一英文形式。
公司1915年成立,资本金74.02亿日元,12月结账。有价证券报告书(2026年3月25日提交)和股东大会(2026年3月27日)的时间框架已经由一手文件确认。
产品都是客户高温工艺里被消耗或埋进部件的材料:电弧炉里消耗的石墨电极、半导体和太阳能生产中消耗的精细碳素、嵌入航空发动机复合材料的碳化硅纤维,外加工业机械。因此收入取决于客户的产量(钢产量、晶圆投片、发动机交付),而不是装机量合同,财报里也没有披露经常性收入或在手订单指标。
2025年12月期销售额377.35亿日元(同比下降0.6%),营业利润48.09亿日元(下降23.9%),归母净利润48.30亿日元(增长18.4%)。有价证券报告书的全文是通过整理后的数据库而不是原始PDF读取的。
02.2|利润重心已经移到最小的业务,销售重心没有
按分部拆开,2025年12月期(公司调整前)碳素产品销售额323.97亿日元,分部营业利润29.90亿日元(下降42.5%),利润率9.2%左右;碳化硅产品41.28亿日元,14.79亿日元(增长72.9%),35.8%左右;其他业务12.09亿日元,3.30亿日元(增长35.6%),27.3%左右。2026年上半年碳化硅利润率进一步升到39.5%左右,碳素压缩到8.1%左右。
上半年的子产品销售更直观:精细碳素100.24亿日元(约占集团53%),电极60.03亿日元(约32%),碳化硅24.14亿日元(约13%)。碳化硅分部的利润9.53亿日元,是碳素分部12.95亿日元的74%,销售额却只有七分之一。
利润重心已经落在最小的分部,销售重心还留在碳素。因此跟踪这家公司,看分部利润比看销售额更诚实:向碳化硅多偏移一个百分点的结构,价值大致相当于电极多长四个百分点。
分部利润在公司调整之前,火灾相关费用在分部与公司项目之间如何分摊,财报没有写明。
02.3|碳化硅是利润引擎,但一半经济利益在伙伴手里
2025年12月期碳化硅销售额41.28亿日元(增长52.9%),分部营业利润14.79亿日元(增长72.9%),占各分部利润合计(47.99亿日元)的31%左右,销售占比只有11%左右。生产已是满负荷。
这条利润线由NGS Advanced Fibers承载,公司只持有50%,GE和Safran各25%。合并增长数字因此高估了母公司股东的所得,高估的幅度大致就是少数股东的份额;估值要按母公司每股收益做,不能按分部利润做。碳化硅利润中母公司拥有多少,没有披露。
增长的天花板在产能。现有产能已满,要跟上LEAP系列陶瓷基复合材料需求,是否又要一轮多年的资本开支,如何在50/25/25的股东之间出资和分配,公开资料里没有产能数字,也没有NGS的扩产协议。答案会决定增长有多少归到母公司股东,也决定自由现金流的改善会不会被逆转。
02.4|整体面貌:周期性底盘上的半个专营权,由净现金托底
把这些拼在一起:这家企业靠卖消耗品,直接面对钢铁、半导体、航空三个生产周期,唯一深度锁定的位置(认证纤维)与客户的母公司对半持有。利润重心已移到最小的分部,销售重心没有;一份大而无杠杆的资产负债表让企业能承受周期,弱点是资本效率,不是偿债能力。2025年的火灾、扩产完工和2026年的回报上调,是叠加在这个基础上的新变化,没有改变这个基础。
对普通股东,这意味着应按正常化经常利润46亿—71亿日元和母公司每股收益来承保,结构改善是通过产品组合缓慢发生的。仍未解决的事项包括:精细碳素吸收新产能的进度、电极周期的方向、纤维产能路径,以及缺少外部份额数据。
03|产品、客户与供应链
03.1|产品越往上走,差异化越强,利润率也越高
产品线沿着一条梯子往上走:人造石墨电极(电炉炼钢)拼价格和成本;精细碳素(半导体、太阳能生产用特种石墨)拼规格;NICALON碳化硅连续纤维(1983年量产,1995年推出Hi-NICALON)拼认证。纤维耐高温、耐氧化,碳纤维在这种条件下会烧掉,所以能增强航空发动机热端的陶瓷基复合材料。除此之外还有碳纤维隔热材料、锂电负极材料和工业机械。梯子越往上,利润率和耐久性越高,销售占比却越低。
2025年12月期研发费用5.25亿日元,占销售额约1.4%,金额不大,和技术地位主要靠工艺经验、认证历史与合资公司积累的生产经验、而不是研发规模相符。财报还点名功率半导体相关产品和碳中和业务为开发方向,但没有披露目标、时间表和投入,所以这里只算期权,不计入增长估值。精细碳素按用途的销售拆分也没有披露。
03.2|三条需求线2025年朝三个方向走
2025年12月期,钢铁挂钩的电极因向北美出口增加而增长,半导体挂钩的精细碳素因功率半导体放缓而下降,航空挂钩的碳化硅满负荷。2026年上半年精细碳素销售保持稳健,利润却因新产能的成本而下降。收入是产量型收入,随钢产量、晶圆投片和发动机交付变化,在全球衰退中三个方向会同时受压:方向分散,但并非互相独立。
客户名称、合同数量、国内外电极占比都没有披露。供应端同样披露很少:财报只点名原材料、燃料价格和美国关税是持续的不确定因素,没有供应商名单和采购结构;生产集中在富山,2025年8月的火灾已经暴露了这一单点。股东无法在这只股票里分散需求风险,持有的是三个周期的组合,外加一份能等待的资产负债表。
03.3|碳化硅需求来自CFM LEAP发动机的放量
碳化硅纤维的需求,实质上是CFM LEAP系列发动机(空客A320neo、波音737 MAX、中国商飞C919)陶瓷基复合材料热端部件的需求。2026年上半年,飞机发动机用纤维销量超过计划,是营业利润超预期的原因之一,与此同时电极和精细碳素销量低于计划。
航空需求按生产计划走,认证锁定,在集团里最耐久;代价是最高的利润率集中押在一个发动机系列的增产节奏上,属于单一来源风险。当前LEAP的生产节奏,在已读材料之外,无法判断。
04|竞争格局与产业关系
04.1|三条产品线面对三种竞争,电极周期决定利润范围
碳化硅纤维的竞争被认证提前挡住:纤维已设计进获证的发动机部件,合资公司的股东就是客户的母公司。精细碳素比的是半导体工艺所需的规格和纯度,公司正在投资扩大份额。电极比的是成本与出口渠道,公司自己的计划用语是“彻底降本、重新审视销售渠道”,按研究判断,在电极上它是周期中的价格接受者,而不是定价者。国内同业包括联盟伙伴SEC Carbon。
电极周期的幅度,公司自己的历史写得清楚:经常利润2018年12月期165.08亿日元,2020年12月期35.87亿日元,下降约76%;2023年至2025年的71.15亿、66.92亿、51.03亿日元居于两者之间,约为峰值的三分之一、谷底的一倍半。三年内集团利润振幅超过四倍。没有取得外部电极价格序列和市场份额数据,这里的判断只能建立在公司披露之上。
04.2|NGS Advanced Fibers:用经济利益换认证与需求
2012年,公司与GE、Safran设立NGS Advanced Fibers,资本金约10亿日元,持股50%、25%、25%,公司的NICALON业务转入合资公司,作为合并子公司承载纤维业务。设立时合作方预期NICALON需求在十年内增长十倍以上。
共同股东是纤维最终客户(发动机)的母公司,这种结构用一半的经济利益,换来了认证、需求可见度和客户承诺:锁定与外流来自同一份持股结构。合作方之间除持股比例和合并少数股东权益外的经济安排没有披露,NGS的扩产协议也未公开。
04.3|与同业SEC Carbon的相互持股
SEC Carbon(5304)是国内同业,自2022年10月起与公司建立资本与业务联盟。SEC Carbon持有公司444,200股(4.08%)。公司持有SEC Carbon 81.3万股,2026年3月31日占4.06%,数据来自SEC Carbon英文官网。相互持股表明同业合作,也让双方各有一部分股权成为战略性、不参与套利的持股。联盟在持股之外的业务内容,披露只有笼统描述。
05|护城河判断
05.1|护城河真实但很窄,只落在碳化硅纤维一处
NICALON是少数通过商业认证、用于航空发动机陶瓷基复合材料的碳化硅纤维,已经设计进获证部件,发动机厂商的母公司又是供应商的共同股东,这种认证加持股的锁定以十年计,技术领先约四十年。电极的成本、质量和供货可靠性没有可比的锁定,大宗精细碳素也没有,只有部分规格有地位。所以护城河完整保护的利润大约是三分之一(碳化硅占分部利润合计31%),部分保护精细碳素,电极则完全没有。
外在表现是可观察的:2026年上半年,电极和精细碳素销量低于计划,碳化硅却超计划,利润率还从35.8%扩大到约39.5%,这正是切换成本在起作用的签名。代价也来自同一处:护城河靠把一半经济利益让给GE和Safran换来。
这些判断依据的是认证结构,不是实测的客户流失、定价或外部份额序列;竞争对手纤维的认证进度、精细碳素规格地位在变宽还是变窄,也无从观察。电极价格战会在一年内传导到集团利润。
05.2|耐久性:哪些成立,哪些故意不下结论
耐久性靠结构续命,而不是靠合同:碳素耗材在每个生产周期都要重新采购,背后是1915年起积累的技术;纤维锁定在获证的发动机部件上,认证周期以年计,客户母公司共同持股,商业耐久性最强,但是用分享经济利益买来的;再加上权益比率63.5%、净现金、可按市价计量的证券,这份资产负债表足以让两项业务扛过电极周期的四倍振幅,不必被迫卖资产、增发或削减分红,2020年12月期的低谷、2025年的火灾和一轮资本开支周期里都是这样。
没有被证明的是:电极价格由全球大宗周期决定、精细碳素扩产的经济性有待新产能被吸收、资本政策只走过一轮。企业本身和股东收入的耐久性高,两条增长故事则有意保持未经证实,这正是市场折价的形状。还有一点要留意:纤维地位如果受损,不会提前公告。
06|财务质量与现金流
06.1|净利润上升来自卖证券,经营利润其实下降了
2025年12月期的头条数字和经营实际是反的。归母净利润增长18.4%至48.30亿日元,原因是35.30亿日元的投资证券出售收益,超过了8.03亿日元的火灾损失;而营业利润下降23.9%至48.09亿日元,毛利率从30.3%降到27.2%(毛利102.57亿日元,上年114.85亿日元),下降发生在碳素产品内部的成本与产品组合上,不在管理费用。
2026年12月期预测净利润下降44.1%至27亿日元(每股收益244.19日元),这是收益消失的算术,公司说明不含非经常项目,并非新指引的经营恶化。指引的营业利润率约10.5%,对应销售额增长8.7%。
因此,含证券收益的每股收益436.91日元不能当估值起点,9.1%的ROE也被这笔收益抬高。2026年3月25日还提交过一份财报数字更正,内容没有读到,性质未分类。
06.2|碳素板块:新产能的成本先到,销量还没到
碳素产品是销售基本盘,也是大部分周期性所在。2025年12月期分部利润下降42.5%,销售额只下降5.7%;2026年上半年销售额增长2.1%,利润下降23.1%,原因是已完工扩产的制造成本先于销量进入成本。按分部数字推算,碳素利润率从一季度的约7.0%回升到二季度的约9.0%,但这只是一个季度的修复,而且仍低于未变更的全年计划在下半年所需的水平。
资产端印证了这一点:在建工程从21.83亿日元降到4.32亿日元,机械设备净值从88.11亿日元升到108.15亿日元,2025年12月期资本开支55.01亿日元(上年46.67亿日元),高于折旧35.34亿日元;2026年上半年资本开支降到13.86亿日元。扩产阶段已经结束,问题变成利用率:108亿日元的机械设备底盘带来的是固定成本拖累,靠销量吸收,不靠再花钱。能否改善,取决于销量,设计产能和开工率没有披露。
06.3|上半年的下滑被累计数字夸大了,但指引没有跟着上调
2026年上半年营业利润24.75亿日元,下降5.1%。拆开看,一季度营业利润下降17.9%(碳素分部下降34.6%),二季度单季14.18亿日元,比上年同期的13.21亿日元高约7%。非经营项目放大了下滑:闲置设备费用累计3.24亿日元,权益法投资收益从2025年12月期的盈利1.00亿日元变成累计亏损0.38亿日元,所以经常利润下降14.0%、净利润下降40.5%,比营业利润的趋势更难看。这是修复,不是下滑;但只有一个季度的证据。
与此同时,上半年营业利润比2月中期计划(16亿日元)高出54.7%,经常利润高出30.08%,净利润高出24.17%,销售额只高出0.12%。公司给出的原因是日元贬值(计划汇率145日元兑美元)和航空发动机用纤维超计划,电极与精细碳素销量低于计划。
全年指引没有调整(营业利润43亿日元,净利润27亿日元),隐含下半年营业利润18.25亿日元,比上半年低26%,销售额却高约16%(219.77亿日元)。这更像是地板,下半年下降的原因(汇率回吐、销量走软、火灾残余费用或刻意保守)公司没有披露,所以把指引读作地板,是判断,不是事实。
06.4|火灾、库存换位和成本抬升,出在同一个生产系统里
2025年8月富山工厂的火灾,还在2025年和2026年的账里流动:2025年12月期特别损失8.03亿日元,火灾拨备7.68亿日元,2026年6月末仍有7.65亿日元;闲置设备费用2025年12月期2.70亿日元,2026年上半年累计3.24亿日元;上半年经营现金流里含5.13亿日元保险赔款,属于非常态。最后一份报告在2026年3月31日提交,其中的恢复细节没有读到。
剩余拨备还要冲销多少、各产品线是否已完全恢复,都不清楚。火灾也暴露了富山的单点集中。
同一段时间还有一个没解释的数字:2025年12月期成品库存减少78.50亿日元(113.01亿降到34.51亿日元),在制品增加76.90亿日元(45.43亿升到122.33亿日元),总库存几乎不变,约196亿日元,财报没有给出任何桥接。火灾后的重新排产、扩产备货、重新分类,都和数字相容,没有一个有证据;如果有未售成品被重新归类,等于推迟了减值。2026年上半年又从应收款里释放了21.31亿日元现金。
火灾、库存换位和精细碳素的成本抬升在十八个月内挤在同一条生产线上,三者之间的因果归属没有证据。在三季度财报和年度库存附注把它们分开之前,分部利润里混着一次性中断、不明库存换位和结构性成本抬升,正常化的碳素利润率和库存的下行价值都要打信息折扣。库存账面值不能当作可变现的下行保护,那约78亿日元结构互换的部分尤其如此。
06.5|利润能变成现金,卡住自由现金流的是投资
2025年12月期营业现金流63.19亿日元,高于合并净利润53.88亿日元,折旧35.34亿日元是最大的非现金加回项,利息保障倍数55.7倍。五年里每年营业现金流都为正(75.51亿、57.98亿、31.89亿、52.34亿、63.19亿日元)。问题在于构成:扣除55.01亿日元资本开支后,自由现金流只有约8亿日元。
2026年上半年营业现金流46.74亿日元,含5.13亿日元保险赔款和21.31亿日元应收款释放,都不是常态。资本开支减半以后,同样的营业利润每年大约多出30亿日元自由现金流。维护与增长资本开支的拆分没有披露;一旦决定扩产碳化硅,这一改善就会被逆转。
06.6|资产负债表:净现金、63.5%权益比率,证据最扎实
2025年12月期末:总资产856.07亿日元,负债220.00亿日元,净资产636.07亿日元(母公司权益543.93亿日元,少数股东权益92.13亿日元),权益比率63.5%(2026年6月末64.2%)。现金及存款151.80亿日元,借款103.31亿日元,净现金约47亿日元,窗口内每年都是净现金;利息支付仅1.13亿日元。
每股净资产4,919.46日元,2026年6月末升到5,041.20日元。借款98%是短期(101.51亿日元),但现金约为借款的1.5倍,这是现金充裕的借款人滚动续借的习惯,不是再融资压力。
投资证券101.97亿日元(6月末116.23亿日元),土地按历史成本35.82亿日元,这是一块有限、部分带战略性的储备,包括SEC Carbon 4.06%的股权,也是回购和分红的资金来源。
把握较高:这是整个逻辑里证据最扎实的一项,让持有的权益从有杠杆的周期筹码,变成基本无杠杆的筹码;低谷伤害的是股价,不是权益本身。限制有几条:证券里战略持股与财务持股的比例、未使用授信额度和抵押资产没有披露;市值会改变证券价值;合并现金里包含与少数股东共享的子公司,母公司可自由支配的现金没有单列。
06.7|五年是有利润的平台,ROE一直没到两位数
2025年12月期之前的五年,既不是下滑也不是增长,而是有利润的平台:销售额315.78亿、357.99亿、378.67亿、379.56亿、377.35亿日元;营业利润37.06亿、47.91亿、65.73亿、63.19亿、48.09亿日元,营业利润率从11.7%升到17.4%再回到12.7%;ROE依次为6.1%、7.1%、8.5%、8.0%、9.1%,最后一个数字被证券收益抬高,2026年12月期预测ROE只有4.95%;权益比率61.4%至63.5%,总资产和净资产逐年增厚。
现在仍然管着今天经济状态的历史转折有:2012年NGS合资、2018至2020年的电极崩盘、2022年SEC联盟、2023年的利润率峰值、2025年的火灾与扩产完工、2026年的回报重置。2026年会成为转折点还是一年期事件,由2027年2月的年报决定。资本效率才是这份资产负债表一贯的软肋:现金与证券合计约250亿日元,回报接近存款,压在543.93亿日元的母公司权益里。ROIC公司没有披露,研究也没有自行计算。
07|股东、董事与治理
07.1|没有控股股东,个人股东占55.41%
股东名册没有控制人:个人55.41%,金融机构27.15%,外资9.28%,其他法人6.53%,共16,137名股东(2025年12月期末)。信托银行账户合计约14.1%(Master Trust 11.28%,Custody Bank 2.77%),瑞穗银行5.01%,SEC Carbon 4.08%,日本生命3.92%,其余大股东基本是个人。2026年2月10日续期了收购应对方针,尽管并无锚定股东。
零售占多数、又有关系型持股的名册,机构对折价的套利压力小,价格容易受事件和零售资金驱动,压力下反而稳定。所以折价更可能通过每股价值增长和股东回报来收窄,而不是通过控制权交易;收购应对方针则保护了董事会免受市场约束。信托账户背后的实际机构持有人看不见,收购应对方针是否有日落条款或股东批准机制,已读材料里没有写。
公司与SEC Carbon的相互持股(4.08%对4.06%)稳定了名册,也释放了同业合作信号,同时让双方各有一部分股权成为不参与套利的战略持股,它守住的是现状,并不创造增长。研究中有一个推断:零售占比高、收益型股东耐心,或许是价格底部的回落一再收窄的微观原因,这只是对名册行为的推断,没有证实因果。
07.2|少数股东权益:增长的一半被分走
合并口径下,少数股东权益92.13亿日元,占净资产14.5%,主要是GE与Safran持有的NGS股份;2025年12月期吸走5.57亿日元的集团净利润(2024年12月期7.23亿日元),并收到1.78亿日元分红。碳化硅利润每增长一元,母公司股东就大约少拿一半。这里的“一半”是近似,因为少数股东权益主要而非全部与NGS有关;碳化硅层面的精确拆分没有披露。这也是估值必须按母公司每股收益做的原因(见第9章)。
07.3|中期计划只有方向,没有数值目标
“GO BEYOND 2030”(2025年12月期是第一年)列的是方向:改善盈利能力、可持续经营管理、加强股东回报;精细碳素扩大份额并优化生产结构,电极彻底降本、重审渠道,碳化硅确保人员与安全运行,新业务是功率半导体产品和碳中和。2026年的动作与计划一致,但财报没有披露数值目标,指引隐含的营业利润率约10.5%、销售额增长8.7%。
所以计划暂时无法打分,也无法被推翻;可信度靠2026年的一连串行动,以及2027年2月前能否出现接续框架来支撑。
07.4|2026年的治理动作异常密集,纪律只有一年历史
2026年的公告簇相当密:2月10日回购决议与收购应对方针续期;3月25日资本成本与股价公告及财报数字更正;3月30日公司治理报告更新;3月31日火灾最终报告;8月25日股东优待制度;9月7日回购完成。董事会还有一份股权信托,使董事利益与股价挂钩。信息披露及时(业绩差异通知当日发布,有英文摘要)。整体看,这像一年内执行的名册和估值方案,但其中资本纪律的一半只有一年历史。
8月25日的股东优待制度,条款没有读到,所以不对其内容作任何断言。它与回购、收购应对方针放在一起,是不是对一份55.41%为个人股东的名册的有意识安排,目前只能留作待查。董事会构成、独立性和薪酬同样没有读到;少数股东的保护目前靠的是董事会当下的选择,而不是制度,在回报行为重复出现之前,应保持中性看待。
08|资本政策
08.1|2026年回报上调:回购用满上限,分红守住200日元
2026年2月10日董事会决议的回购,在3月2日至8月31日实施:买入521,600股,金额24.9968亿日元,用满金额上限的99.99%(股数上限的83.5%)。库存股增至1,297,716股左右,占11,832,504股已发行股份的11.0%左右。
分红每年200日元,已连续五年,2026年12月期预测不变,按干净每股收益244.19日元算支付率81.9%;金额固定,没有写明政策公式,每年约22亿日元。2026年12月期合计回报约47亿日元,是预测净利润27亿日元的1.7倍,也远高于2025年12月期约8亿日元的自由现金流;同时上半年资本开支减半至13.86亿日元,因为扩产已经结束。
这是一次可观察的偏好排序:估值修复排在继续扩产之前。但回购只被证明了一次,回购框架已到期;没有任何总回报或支付框架约束未来的董事会,上面的合计回报也把中期分红按预测计入。
08.2|回报资金来自卖证券:每股价值在增长,但这条回路有尽头
2025年12月期出售证券的37.16亿日元,实质上是2026年回购的一部分资金来源:金融资产在低于账面价的价格下被转化成每股价值。回报超过自由现金流,意味着这条回路经由资产负债表运转,剩下的约100亿—120亿日元可按市价计量的证券是一个看得见的跑道,不是无限的。
扩产结束使自由现金流回升,按目前水平,2027年12月期起运行利润保持住的话,收支大致可以闭合;如果碳化硅又要扩产,这个改善就会逆转。证券里战略持股与财务持股的比例没有披露。
每股层面的结果已经显现:在净利润下降40.5%的上半年,每股净资产仍从4,919.46日元升到5,041.20日元;五年里从4,073.6日元一路增长,期间没有增发。低于账面的每一元回购,都是把金融资产储备的价值转给继续持股的人。每年2%—3%的每股地板抬升,只在股价低于账面、储备没有用完的条件下自我强化。
08.3|回报会不会成为政策:两份文件决定
资本效率是这家公司的软肋:ROE五年没到过两位数,2026年12月期预测4.95%(详见第6章)。2026年3月25日公司提交了关于资本成本与股价的公告,其内容没有读到,所以研究不对ROE目标、市净率改善措施或回报政策作任何断言,这是最大的一份文档缺口。它是否把2026年的回报上调(回购用满、预测支付率81.9%)变成回购框架到期后的常设政策,尚不能确认。
第二个检验是2027年2月的年报:是否出现接续回报方案(新的回购框架、分红政策公式,或注销约11.0%库存股的一部分),以及2027年12月期指引是否把2026年的上调写成政策。这是未来披露,目前没有公开途径可查。
09|估值与安全边际
09.1|资产说便宜,干净盈利说不便宜,收益说有支撑
2026年11月6日收盘价4,610日元(研究截止日为11月9日,当日收盘4,660日元),总市值545.5亿日元(按已发行11,832,504股)。预测PER 18.9倍(按2026年12月期预测每股收益244.19日元,数据服务商印出18.49倍);按含证券收益的2025年12月期每股收益436.91日元只有10.6倍,不能据此判断;PBR 0.94倍(按2025年12月期末每股净资产4,919.46日元,按中期5,041.20日元为0.91倍);2025年12月期ROE 9.1%,预测4.95%;预测股息率4.34%(200日元);EV/EBITDA 5.8倍(EV 486.1亿日元,EBITDA 83.4亿日元=2025年12月期营业利润加折旧)。
三种框架给出三种读数:资产价值框架偏便宜,干净盈利框架偏满,收益框架有支撑。关键机制是:这个接近账面的价格,不是对资产负债表的判断(资产负债表是净现金),而是对利润波动的判断,该利润在三年内印出过35.87亿日元和165.08亿日元的经常利润。
所以重估只能靠方差下降,也就是让碳化硅和精细碳素在利润中占更大比例,没有通过发现资产价值的捷径。等待由股息率和每股净资产的复利来补偿。
倍数都是数据服务商按公司指引计算的,没有同行倍数;EV把含少数股东共享价值的市值,与合并净现金放在一起,并不严格可比。
09.2|这些倍数口径不同,不能混着比
PBR 0.91倍用的是2026年6月30日的每股净资产5,041.20日元,0.94倍用的是2025年12月期末的4,919.46日元;预测PER 18.9倍是股价除以公司预测每股收益244.19日元,数据服务商印出的是18.49倍,差异来源没有披露,两个数都照实记录;按报告每股收益算的10.6倍分母含一次性收益;ROE 9.1%是含证券收益的2025年12月期实绩,4.95%是预测;EV用2026年6月30日的净现金,EBITDA用2025年12月期。
市值用的是已发行股数,尽管其中约11.0%是库存股,这会影响每股和市值的读数。倍数之间几个百分点的差异,往往只来自分母选择。
09.3|正常化盈利:46亿—71亿日元,区间本身就是发现
2025年12月期经常利润51.03亿日元,已经剔除证券收益和火灾损失这对特别项目;加回2.70亿日元闲置设备费用,底层水平54亿日元左右。结合2023年至2025年的实际(71.15亿、66.92亿、51.03亿日元)和2026年12月期计划(46亿日元),研究自己估算正常化经常利润区间约为46亿—71亿日元,中心约52亿日元。
这是碳化硅满负荷、碳素处于低位、碳化硅利润来源五五分摊的中周期状态。这是研究自己的算术,公司没有披露底层利润指标。
按中心值和545.5亿日元市值算,约10.5倍;市场按这个区间的8至12倍定价,同时给出低于账面的价格,这才是介于两个PER之间的诚实倍数。完整周期的真实谷底无法从五年窗口算出,2018至2020年的记录是谷底参照,区间之宽本身就是发现。含证券收益的每股收益436.91日元,不应成为估值锚。
09.4|价格怀疑的是盈利,不是资产
11月6日收盘4,610日元(当日下跌3.35%),11月9日4,660日元,都低于中期每股净资产,比9月和10月的高点(5,440日元、5,410日元)低14%—15%,52周区间为4,275—5,440日元,公司指引没有变。这说明市场怀疑的是盈利,不是资产。
如果三季度之后指引保持不变,会打败低于账面价格里隐含的怀疑;如果下调,则会印证它。账面价附近、4.34%股息率的位置上,向好的意外比向坏的意外定价更便宜,前提是资产负债表的地板真实存在。
这里的“市场判断”其实就是公司没有修改的预测被定了价,没有分析师一致预期可参考。个人股东占55.41%,短窗口价格信号更嘈杂;预期要用月来读,不能用日。
09.5|按母公司每股价值估值,增长要打折
碳化硅利润由NGS承载,少数股东权益占净资产14.5%,吸走2025年12月期5.57亿日元净利润,所以合并口径的增长高估了母公司股东的所得。估值应以母公司每股收益为准,不应以分部利润为准;碳化硅层面精确归属母公司的比例没有披露。如果碳化硅在NGS内部扩产,出资和回报也要与伙伴分摊。
另一条长期因素是每股净资产:低于账面的回购加留存利润,使它每年上升约2%—3%,所以实际入场倍数会随时间下降,与股价无关。这个机制只有在价格低于账面、证券储备未耗尽时自我强化。
09.6|下行保护是结构性的,真实损失是漫长的谷底
保护按硬度排序:净现金与约100亿—120亿日元可按市价计量的证券,对照220.00亿日元负债;63.5%的权益比率;按历史成本计价的土地;五年不间断的固定200日元分红;由生产计划决定的航空需求。现实的亏损情景不是权益受损,而是漫长的谷底:电极下行使集团营业利润滑向30亿日元左右(经常利润滑向2020年12月期的35.87亿日元,约36亿日元),股价更低,等待多年,由股息率缓冲。
净现金、权益比率和证券,把谷底变成等待的问题,而不是权益减值的问题。软肋同样具体:滚动的短期借款、没有解释的库存换位、没有收尾的火灾,以及已经证明过的两年下降76%的经常利润。清算价值没有估算,库存价值目前也无法确认为保护。
10|Kabugami 技术结构
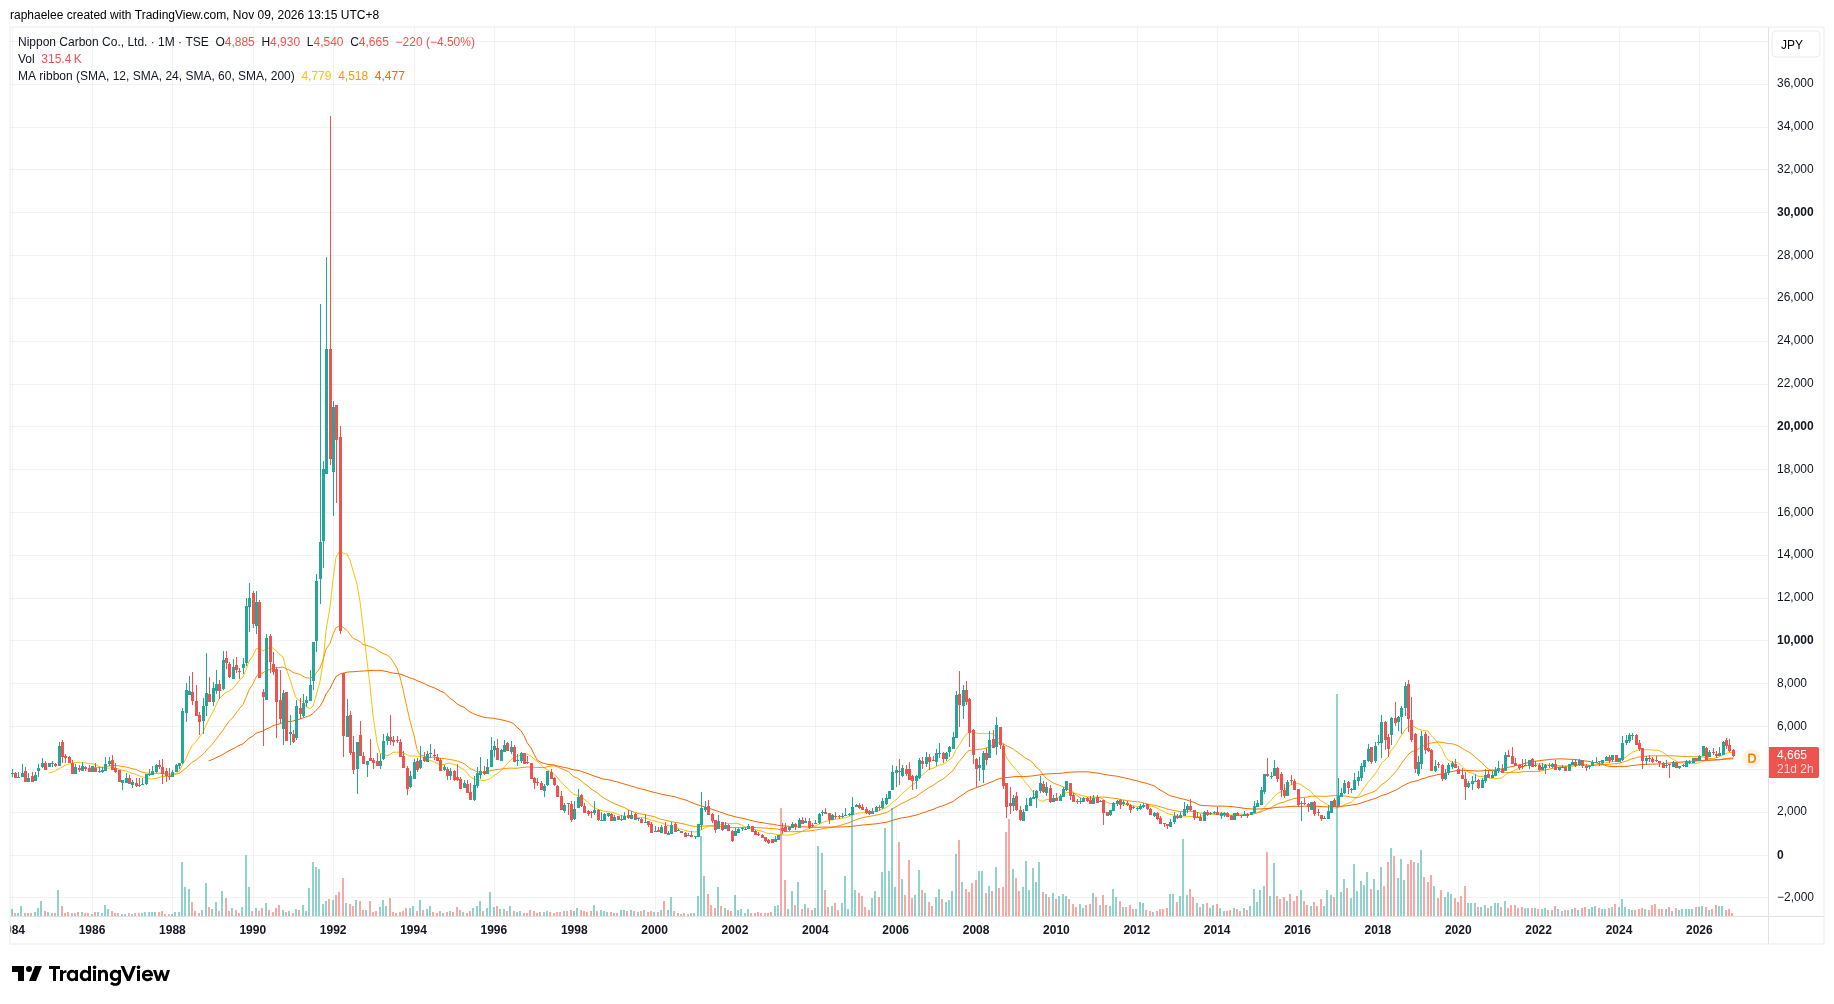
10.1|长期下跌已经走完,上行是否启动还没有答案
技术上只有一个问题:六年箱体收敛之后,价格是继续停在衰竭完成的位置,还是走到启动。
先定义两个状态名,全章只用这两个。“衰竭完成”指长期下跌的力量已耗尽:回落一轮比一轮浅、一轮比一轮快被修复,均线聚拢,成交量枯竭。“启动”指价格以月线收盘站上六年箱体上沿(约5,800日元),并伴随明显放量,随后回踩守住原来的上沿。眼下价格处在衰竭完成、尚未启动的位置。
观察日为2026年11月9日。月线覆盖2001年1月至2026年10月共310根(按2017年10月的10合1并股调整),另有11月6日收盘4,610日元和11月9日收盘4,660日元的日线。10月月线收盘4,920日元。
10.2|价格生命史:两次冲高都回落过半,随后是六年箱体
价格走过五个阶段。2001年至2002年的崩落把价格带到500日元(2002年11月)。
2003年至2007年的恢复把价格带到历史最高的8,460日元(2007年8月)。2008年至2017年的长平台是价格真正待过的地方:全部月线收盘中有30.3%落在1,500至2,500日元。
电极超级周期带来第二次纯周期性冲高,2018年10月8,170日元,到12月收盘4,025日元已回吐约一半,随后是2019年低点3,445日元和2020年3月疫情低点2,536日元。第五阶段从2020年开始,是箱体:六个年度收盘在3,945至4,415日元之间,年度振幅逐年收窄。
到达今天的路径是这样的。价格从500日元(2002年11月)涨到8,460日元(2007年8月),随后在1,500—2,500日元的长平台停留(2008年至2017年)。
2018年10月出现8,170日元的电极尖峰,12月收盘4,025日元。之后是3,445日元(2019年)和2,536日元(2020年3月),进入六年箱体,年度收盘在3,945至4,415日元之间。
2025年4月关税冲击下当月急跌到3,560日元,收于4,185日元。2026年9月、10月两次试探5,440日元和5,410日元,10月收盘4,920日元。
年度收盘六年只上涨12%,且伴随成交量下降,按这个框架,这是低能量、方向对但证据偏薄的迁移。
10.3|回落一轮比一轮浅,修复一轮比一轮快,收敛已到三重
回落的幅度和时长在逐轮缩小。2018年10月高点8,170日元到12月收盘4,025日元,跌51%左右,约两年才修复;2025年4月的急跌到3,560日元,当月就收在4,185日元,一个月内修复;2026年3月,5,020日元的高点被压回,收盘4,470日元,当月盘中回落约11%,4月、5月收盘回到4,790日元和4,740日元。
修复所需时间从两年缩到一个月左右,这是同一种衰竭在时间轴上的表现;而回复的力量随箱体成熟变强,更像卖盘耗尽,而不像有买盘在承接分发。
收敛可以用三个互相独立的尺度同时量到。年度振幅从2019年的67%降到2022年的19%、2023年的20%、2025年的27%、2026年至今的24%(2024年的冲高年除外);60个月与12个月均线之间的差距只有6.7%;成交量2023年至2026年月均约116万股,2018年至2019年是637万股,2026年10月只有75万股。
三重收敛到这个程度不会长久,它会走向某个方向,但框架的纪律是等方向出现,而不是预判。2026年9月、10月的两次试探,正是一个尚未解开的收敛从内部看到的样子。
10.4|三条长期均线聚成一团,上方有两段历史压力
当前的价格重心就是那团均线本身:12个月均线4,769日元,24个月4,508日元,60个月4,469日元,短、中、长三个结构已经不再相互分歧。10月收盘4,920日元,高于12个月均线3.2%,高于60个月均线10.1%:价格从一个完全平衡的重心略向上倾斜,这个幅度一个普通的下跌月份就能抹掉。
下方反复停留的价格带是:4,469至4,769日元的均线聚集区、年度收盘重心约4,400日元、箱体下沿约3,900日元,2025年4月的急跌低点3,560日元是向下假突破的参照。上方是:2026年试探的5,400至5,440日元,再往上是5,700至5,800日元,2024年4月高点5,700日元与箱体上沿在此重合,再向上是2018年的8,170日元和历史高点8,460日元,那里只在周期狂热时到访过。
5,800日元到8,170日元之间没有任何有意义的价格停留带:这段空间两次在几周内、在狂热中被穿过,什么也没留下。
市场的记忆分层很清楚。最深的一层是平台:十年里收盘都在1,500至2,500日元,教会持有人这只股票不动。其上有两段惩罚性记忆,2007年与2018年,高于5,800日元之后都出现过半的回吐,全部收盘里只有3.9%在这条线之上。最新的一层是箱体本身:六年里每轮回落都比前一轮浅,每个年度收盘都比上一年高。4,920日元的价格,是平台的耐心与尖峰警告之间的一场谈判。
形态上,这是长平台、周期性急涨急跌、再到六年收敛箱体;它不像阶梯式上行,而是把能量存在收敛里(区间、均线、成交量),释放时的幅度往往与收敛成比例,方向可上可下。
10.5|公开事件之后,好消息被相信,但没有被外推
2026年的几次公开事件,价格反应有各自的特点。2月业绩与回购公告之后,价格收在5,050日元,是当时当年最好的月收盘,成交量正常而非高潮放量。
随后3月的回落在两个月内被消化。8月中期业绩超出计划(营业利润比计划高54.7%,指引不变),把价格推到试探区:8月收盘5,240日元,9月最高5,440日元,却没能制造出一次站上箱体上沿的收盘。
临近预计在11月10日前后发布的三季度财报,11月6日出现一次3.35%的单日下跌,仍被限制在箱体之内,11月9日回升1.08%。这些反应是不对称的:对好消息,价格相信但不外推;对坏消息,影响在缩小,近期最大的一次下跌被限制在箱体内并部分收回。
高位怀疑、低位平静,这是收敛底下一份价值型名册的特征。
价格与公开基本面的时序关系是:价格提前一个公告把问题问了出来。9月、10月对箱体上沿的试探,发生在需要为它们辩护的三季度财报之前,就像2月的收盘早于一股都还没回购的回购年故事。
价格图形和财报等待的是同一批有日期的证据,即分部季度利润,尤其是精细碳素的吸收进度。因此技术状态格外依赖接下来的两份基本面报告,在它们之后也格外容易重新评估。
两条线索是同一笔对执行的押注,用两种方式表达了一次,而不是两个互相独立的观点。基本面信息不会改变这里独立形成的技术状态,基本面的正面也不用来确认它。
10.6|两种冲高失败不是一回事,价格已在高位区待了九个月
有两次失败的冲高管着上方。2018年的冲高(8,170日元,伴随周期高潮的放量)是惩罚性的原型:高度即狂热。2026年的两次试探(9月5,440日元、10月5,410日元,成交量枯竭,从箱体内部发起)是另一个物种:是尝试,不是狂热。判断下一次尝试的关键区别是:如果第三次试探在下跌放量中失败,2026年的两次就要重新归类为分发;在成交量这样说之前,它们读起来像是收敛在试探自己的盖子。
价格重心落在箱体上三分之一:4,500至5,800日元这一带,只占生命史收盘的13.9%,所以在这里停留在历史上并不寻常。2026年2月至10月,收盘在4,470至5,240日元之间,期间经历火灾披露、指引发布和中期业绩超预期,价格仍留在这个区域九个月。在这个高度停留,已经不是到访,但还不是离开,因为上沿没有被拿下。
箱体内的迁移很慢:从旧平台的迁出已在2018至2020年的重置中完成,目前是箱体内部的缓慢上移。质量不会由更多的漂移来证明,只能由启动本身来证明:月线收盘站上箱体上沿,成交量从枯竭区放大,随后的回踩把旧天花板守成地板。
10.7|当前状态、内部矛盾,以及确认与失效条件
当前状态:衰竭完成但尚未启动。六年收窄的箱体、完全缠绕的长期均线、枯竭的成交量、逐轮缩小的回落,加上一个两个月里被试探两次、还没有被月线收盘拿下的盖子。把握一般。
内部矛盾是高度对历史:箱体的几何结构(收敛、阻尼、成交量衰竭、在箱体上三分之一停留九个月)指向下一段持续的行情会向上走出收敛;生命史则说,每一次到访箱体上沿之上都是狂热,并以回吐收场。两者出自同一条序列。框架的处理方式是不提前解决矛盾:衰竭完成已经成立,启动需要它自己的那一根月线,由观察指标而不是叙事来说明哪段记忆是对的。
四个月线观察指标:箱体上沿5,800日元左右,站上并伴随成交量从116万股月均的枯竭区放大,才算启动;4,469至4,769日元的均线聚集区代表平衡,收盘跌破60个月均线,价格向上的倾斜就破了;箱体下沿约3,900日元代表失效,收盘跌破即结束衰竭完成的判断(2025年4月3,560日元的低点只是向下假突破的参照,不是这条线本身);成交量本身,在穿过聚集区的下跌月份放量,将是箱体生命史上第一次分发的特征。截至2026年10月收盘,没有一个指标被触发。
什么会进一步确认:月线收盘站上约5,800日元,同时成交量明显脱离2023至2026年的枯竭区;启动后的回踩守住5,000至5,800日元一带,不再回到箱体里;2026年的年度收盘高于9月、10月试探的收盘(5,130日元和4,920日元),2027年的年内低点高于2026年的4,390日元,把箱体逐年抬高的地板延续进上行。
什么会推翻:月线收盘跌破约3,900日元;月线收盘持续低于60个月均线(4,469日元),且聚集的均线本身开始向下,即平衡被破坏,而不只是被测试;在穿过聚集区的下跌月份,成交量明显高于枯竭区均值,把2026年的试探重新归类为顶部。
11|风险与催化剂
11.1|最近的催化剂是三季度财报,几天内就到
2026年12月期三季度(7–9月)财报预计在2026年11月10日前后发布,日期由2023年11月10日、2024年11月11日、2025年11月10日的往年发布日推断,并非公司公告。它是对未变更指引和碳素利润率修复的第一次检验:二季度单季营业利润的同比恢复能否延续,精细碳素的新产能吸收是否体现在碳素分部利润率上,碳化硅能否把超计划的销量带进下半年。本次研究截止于2026年11月9日,该财报属于截止之后的信息。
如果财报下调指引或碳素利润率仍未修复,“一季度事件”的看法就被推翻;2027年2月年报是否给出接续回报方案,是第二个检验。另外两个触发条件是:碳化硅在产能未满时销量下降,电极再度下行使集团营业利润跌破30亿日元左右。
11.2|指引是保守还是有预见,下半年才知道
公司消化了54.7%的中期营业利润超预期,却没有上调全年,把日元相对计划汇率145日元的贬值视为暂时的(2025年12月期平均汇率148.7日元)。下半年会揭示这到底是保守还是预见,答案会同时重估预测的可信度和股价对汇率的敏感度。
下半年营业利润18.25亿日元的隐含降幅有四种可能:汇率回吐、电极或精细碳素销量走软、残余火灾费用、刻意保守。公司披露了算术,没有披露归因,所以三季度财报要么证实“地板”的看法,要么迫使公司首次修订。
11.3|宏观风险通过汇率、关税和原料三条管道进入利润表
汇率:计划汇率145日元,2025年12月期平均148.7日元,2026年上半年的超预期有一部分来自日元贬值。美国关税政策:财报点名为不确定因素,直接关系到北美电极出口,2025年4月的关税冲击当月曾印出3,560日元的价格低点。原料与燃料价格:2025年12月期毛利率压缩了3.1个百分点。此外还有一层货币敞口叠加在两个产品周期之上。公司没有披露套期保值或敏感度表,销售与成本的币种拆分也未披露。
日元反转,是对下半年最近、最直接的机械性风险,且已被管理层未变更的指引部分计入。
12|反常识发现
12.1|净利润上升,其实是证券收益盖住了经营下滑
最容易被头条数字误导的一点:2025年12月期净利润上升18.4%,营业利润却下降23.9%,毛利率少了3.1个百分点。把两条线拆开才看得清,净利润的上升来自35.30亿日元的证券出售收益,经营线本身是向下的;2026年12月期预测净利润下降44.1%,是同一笔收益消失,不是新的经营恶化。看懂这一点,才不会把436.91日元的每股收益当起点。
同样的拆分还揭示了结构:碳化硅分部利润是碳素分部的74%,销售额只有七分之一,而且它还有一半归伙伴。利润重心和销售重心不在一个地方,合并增长又高估了母公司股东的所得。这些发现来自对公开财报的拆分和对照,没有外部独立数据的验证。
12.2|卖证券的钱,实质上变成了2026年的每股价值
2025年12月期证券出售的37.16亿日元,一边抬高了当年的净利润,一边变成了2026年低于账面价回购的资金。于是一条回路连了起来:金融资产变为每股净资产的增长,回报超出自由现金流的部分由资产负债表垫付,约100亿—120亿日元的证券是看得见的跑道。
这使“低PBR”的含义变了:它既不是资产的发现,也不只是廉价,而是一笔正在被消耗的储备正在向继续持股的人转移价值。回路有尽头,所以2027年2月年报是否给出接续方案,就是这个发现能不能成为政策的检验。
13|下一次值得跟踪什么
13.1|三季度财报会不会延续二季度的修复?
这是最近的一个检验,因为它决定“一季度事件”与“趋势性下滑”哪个读法成立。要看三件事:二季度单季营业利润的同比恢复(14.18亿日元,比上年同期高约7%)是否延续;精细碳素新产能的吸收是否体现在碳素分部利润率上,向未变更全年计划所需的水平靠近;碳化硅能否把超计划的销量带进季节性决定性的下半年。
修复保持,“一季度事件”的看法成立;指引下调或利润率未修复,这个读法被推翻。该财报预计在2026年11月10日前后发布,属于本次研究截止日之后的信息,应放入下一次更新;目前没有可查的公开路径。
价格与基本面在同一份财报上等待验证,技术状态与基本面论点是同一笔对执行的押注,用两种方式表达,不构成两个独立的论据。
13.2|下半年隐含的降幅到底来自什么?
这决定指引是不是地板。2026年中期超预期54.7%后全年指引不变,隐含下半年营业利润18.25亿日元,可能的原因有四种:从145日元计划汇率回吐的汇率因素、电极或精细碳素销量走软、火灾相关费用残余确认、刻意保守。公司只披露了算术,没有披露归因,三季度财报是否迫使首次修订,会同时重估指引可信度和汇率敏感度。
13.3|库存78亿日元的换位和火灾尾部,什么时候说清?
这两项之所以重要,是因为它们决定碳素真实利润率和库存的下行价值。2025年12月期成品库存减少78.50亿日元、在制品增加76.90亿日元,原因可能是火灾后的重新排产、为扩产备货,或重新分类,没有一个有证据;如果是未售成品被重分类,等于推迟了减值。
火灾方面:2026年6月末还有7.65亿日元拨备,还要冲销多少,2026年3月31日的最终报告是否确认全面恢复生产、哪些产品线恢复,都不清楚。三者很可能同属一个生产系统,因果归属目前没有证据。
库存换位有望在2027年3月的2026年12月期有价证券报告库存附注中说清。
13.4|资本成本公告写了什么,回购到期后会不会有接续?
这两项决定2026年的回报是政策还是一年期事件。2026年3月25日关于资本成本与股价的公告,是否承诺ROE目标、市净率改善措施或回报政策,没有读到,研究不对其内容作断言,这是最大的一份文档缺口,该文件在截止日前已公开,是已知而未读的缺口,并不表示它不存在或没有内容。2027年2月年报是否给出接续回报方案(新的回购框架、分红公式,或注销约11.0%库存股的一部分),属于未来披露,目前没有公开路径。
13.5|碳化硅纤维能否扩产,谁出钱、怎么分?
这决定增长有多少归到母公司股东,也决定自由现金流的改善是否被逆转。碳化硅已满产,能否在不再来一轮多年资本开支的情况下满足LEAP系列需求增长,NGS内部的扩产如何在50/25/25股东之间出资和分享,公开资料里没有NGS的扩产协议,也没有产能数字。
13.6|权益法关联公司和股东优待制度,两个小项为什么还要查?
权益法投资收益从2025年12月期的盈利1.00亿日元(2024年12月期1.66亿日元),变成2026年一季度亏损0.44亿日元、上半年累计亏损0.38亿日元,这拉大了经常利润与营业利润的降幅差。是哪家关联公司、拖累是结构性还是暂时的,财报没有写明,只能在有价证券报告书附注中查到。
2025年8月25日引入的股东优待制度,条款没有读到,所以不作断言。它与回购、收购应对方针放在一起,是不是对一份个人股东占55.41%的名册的有意识策略,影响折价如何收窄,目前待查。
13.7|还有哪些限制贯穿所有判断?
待查事项按优先级排序:第一档是三季度财报、下半年指引的归因、2027年2月的接续回报方案;第二档是资本成本公告内容、库存换位、火灾尾部、碳化硅扩产;第三档是权益法关联公司、股东优待条款。每一项都有明确的解决文件,相反的答案会移动论点或信心。面向未来的事项应放入下一次更新,已公开但未读的文件,则是已知的缺口。更完整的证据边界见第15章。
14|Kabugami 评分卡
14.1|Kabugami 评分 V3.2:60.92/100分,评级 B
Kabugami 评分 V3.2 为60.92/100分,评级 B,行动以观察为主:持有或小仓位跟踪,不追高。理由是投资逻辑建立在资产负债表和半个归属的航空纤维专营权上,而不是盈利动能。净现金、接近账面价、4.3%左右的预测股息率提供等待的补偿;但电极周期的振幅(三年内超过四倍)、碳化硅利润被少数股东分走一半、指引拒绝外推中期超预期,使得按低谷情景定仓位比按平台期更合理。
三季度财报预计在11月10日前后发布,晚于本次研究截止日,应在读到碳素板块利润率是否继续修复、指引是否下调之后,再决定加仓或减仓;2027年2月年报是否给出后继回报方案,是第二个检验点。若碳素利润率持续未修复、指引下调、碳化硅在满产下销量下降,或电极下行使集团营业利润跌到30亿日元左右以下,应降低判断。
14.2|八项得分:资产负债表最高,治理最低
财务韧性与下行防御 10.14/13:净现金47亿日元左右、权益比率63.5%,证据最扎实;库存约78亿日元结构互换原因未明、母公司可用现金没有单列,限制了进一步上调。
竞争优势与结构耐久性 9.10/14:认证锁定集中在碳化硅纤维一处,且利润一半归伙伴;缺少外部份额和价格数据,扩产如何出资未知。
盈利质量、现金转化与资本效率 8.84/17:现金转化良好,但净利润增长来自证券收益,ROE从未到两位数,自由现金流只有约8亿日元,正常化经常利润区间46亿—71亿日元很宽,三季度修复情况未明。
商业结构、产品、客户与关键依赖 6.38/11:三条需求线方向分散,但没有订单可见度指标,高利润押在单一发动机系列,生产集中在富山。
估值与安全边际 8.70/15:低于账面、预测股息率4.34%有支撑,但干净盈利并不便宜,没有同行倍数和一致预期,各倍数口径不一。
资本配置与股东回报 6.20/10:2026年回报约47亿日元,是预测净利润的1.7倍,但回购只证明了一次,接续方案和3月公告内容未读。
治理、所有权与管理层 3.50/7:没有控股股东,披露及时,但保护目前靠董事会的选择,董事会构成、薪酬和收购应对方针条款未读。
Kabugami 技术结构 8.06/13:旧的下跌状态明显失去控制,新的上行结构尚未经过检验,对三季度财报依赖高。
八项合计60.92/100分。
14.3|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 10.14 | 2025年12月期末总资产856.07亿日元,净资产636.07亿日元,权益比率63.5%,2026年中期升至64.2%。现金及存款151.8亿日元,借款103.31亿日元,净现金约47亿日元,五年窗口内每年都是净现金。利息支出仅约1.13亿日元。投资有价证券约102亿日元(中期约116亿日元),土地按历史成本计价,是一块有限但真实的缓冲。这一项是整个投资逻辑里证据最扎实的一环,经历过2020年低谷、2025年火灾和一轮扩产。 |
| 竞争优势与结构耐久性 | 14 | 9.1 | 护城河真实但很窄,集中在一处。NICALON碳化硅连续纤维是少数通过认证、用于航空发动机陶瓷基复合材料热端部件的商品化纤维,认证周期以年计,且GE与赛峰作为发动机厂商的母公司持有合资公司NGS Advanced Fibers各25%。碳化硅板块2025年12月期利润14.79亿日元,利润率约35.8%,2026年中期约39.5%,在电极和精细碳素销量低于计划的半年里仍然超计划,这是切换成本起作用的外在表现。电极几乎没有锁定,精细碳素只在部分规格上有地位。 |
| 盈利质量、现金转化与资本效率 | 17 | 8.84 | 利润质量与资本效率混合偏中性。正面:营业现金流连续五年为正,2025年12月期63.19亿日元,高于合并净利润53.88亿日元;资本开支在扩产结束后减半(2026年上半年13.86亿日元)。负面:2025年12月期净利润增长18.4%至48.3亿日元,来自35.3亿日元证券出售收益,而营业利润下降23.9%至48.09亿日元,毛利率下降3.1个百分点至27.2%;自由现金流只有约8亿日元;ROE从未到过两位数,2026年预测约4.95%;少数股东权益吃掉5.57亿日元净利润,碳化硅增长不能全部算给母公司股东。经研究者自己测算,正常化经常利润区间约46亿—71亿日元,中心约52亿日元,区间本身很宽。 |
| 商业结构、产品、客户与关键依赖 | 11 | 6.38 | 商业结构分散于三个方向,但需求没有订单或合同积压之类的可见度指标。2025年12月期碳素产品约占销售的86%(电极、精细碳素),碳化硅约11%,其他约3%。三条需求线同年走势不同:电极因对北美出口增长,精细碳素因功率半导体放缓下降,碳化硅满负荷。2026年上半年精细碳素约占53%,电极约32%,碳化硅约13%。关键依赖包括:碳化硅高度依赖LEAP系列发动机放量;生产集中在富山工厂,2025年8月火灾已暴露单点风险;客户名称、合同数量、国内外电极占比均未披露。 |
| 估值与安全边际 | 15 | 8.7 | 2026年11月6日收盘价4,610日元(9日4,660日元),市值约545.5亿日元。预测市盈率约18.9倍(按2026年12月期预测每股收益244.19日元),按含证券收益的2025年每股收益436.91日元只有约10.6倍,不应据此判断;市净率约0.94倍(按中期每股净资产5,041.20日元约0.91倍);预测股息率4.34%;EV/EBITDA约5.8倍。资产看起来便宜,干净盈利看起来不便宜,收益率有支撑。市场用约8—12倍的正常化经常利润区间定价,同时给出低于账面的价格。 |
| 资本配置与股东回报 | 10 | 6.2 | 2026年的股东回报明显上调:2月10日决议、3月2日至8月31日执行的回购共52.16万股,金额约25亿日元,用满金额上限的99.99%;库存股约11.0%;分红每年200日元,连续第五年、2026年12月期预测不变。2026年12月期合计回报约47亿日元,相当于预测净利润27亿日元的约1.7倍,也远超2025年约8亿日元的自由现金流;资本开支已由55亿日元降至上半年约14亿日元。这表明管理层在估值修复与继续扩产之间选择了前者。 |
| 治理、所有权与管理层 | 7 | 3.5 | 公司没有控股股东:个人股东55.41%,金融机构27.15%,外资9.28%,其他法人6.53%,共16,137名股东;信托银行账户合计约14.1%,瑞穗银行5.01%,与同业SEC Carbon(5304)的相互持股约4%,日本生命3.92%。2026年2月续期了收购应对方针。披露及时(当日发布业绩差异通知,有英文摘要),2026年的回购、资本成本公告、股东优待制度集中出现,表现出对登记簿与估值的有意识安排。 |
| Kabugami 技术结构 | 13 | 8.06 | 价格走势处于一个完成了衰竭阶段、尚未出现启动的结构。2020年以来六年底部区间内,各次下跌依次变短变浅、修复变快:2018年高点后的回落约两年才恢复,2025年4月的急跌一个月内修复,2026年3月的回落两个月内被消化;12、24、60个月均线聚集在约4,470—4,770日元的狭窄区域;成交量降到该股有记录以来的最低水平。2026年9月、10月两次试探约5,400—5,440日元,均未收在六年区间上沿(约5,800日元)之上。旧的持续下跌状态正在明显失去控制,但新的上行结构尚未经过检验。把握一般。 |
总分: 60.92 / 100 评级: B 操作建议: 观察为主,持有或小仓位跟踪,不追高。理由是投资逻辑建立在资产负债表和半个归属的航空纤维专营权上,而不是盈利动能:净现金、接近账面价、4.3%左右的预测股息率提供等待的补偿,但电极周期的振幅(三年内超过四倍)、碳化硅利润被少数股东分走一半、指引拒绝外推中期超预期,使得按低谷情景定仓位比按平台期更合理。第三季度财报预计在11月10日前后发布,晚于本次研究截止日,应在读到碳素板块利润率是否继续修复、指引是否下调之后再决定加仓或减仓;2027年2月年报是否给出后继回报方案是第二个检验点。若碳素利润率持续未修复、指引下调、碳化硅在满产下销量下降,或电极下行使集团营业利润跌到约30亿日元以下,应降低判断。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|主要来源与日期
公司一手披露包括:2025年12月期财报(业绩快报,2026年2月10日)和2026年一季度财报(2026年5月8日)。还有2026年中期财报与资产负债表、现金流(2026年8月10日),以及中期业绩差异通知(2026年8月10日,经JPX披露)。
回购完成公告的日期是2026年9月7日。有价证券报告书的数据经整理后的数据库(JINGI,2026年3月25日)读取,股东名册来自EDINET DB(2026年6月30日口径)。
同业SEC Carbon英文官网(2026年3月31日)提供相互持股和公司英文名的第二来源;GE于2012年2月27日的新闻稿提供NGS Advanced Fibers的股权结构和NICALON技术背景。行情与披露索引来自IRBANK(2026年11月6日行情快照,披露索引2026年11月9日抓取)。
价格与估值截至2026年11月6日收盘,11月9日收盘作为后续参照。技术分析使用的月线来自本地整理的价格历史(Yahoo Finance 图表口径,已按2017年10月的10合1并股调整,年度高低点与IRBANK逐年核对),月线数据采用至2026年10月27日,其后只有11月6日和9日的日收盘快照。
15.2|证据边界:哪些没读到,不等于经营不好
几处限制贯穿所有判断:2026年3月25日关于资本成本与股价的公告、2026年8月25日股东优待制度的公告,已在披露索引中确认存在,但没有读到内容,因此不断言ROE目标和优待条款;2025年12月期有价证券报告书通过财报和整理后的数据库读取,没有逐页阅读,分部资产、联盟之外的关联方细节、火灾最终报告的恢复细节仍未读;3月25日的财报数字更正未分类;没有取得独立的市场份额、同行倍数、电极价格、一致预期和库存桥接证据;公司没有披露数值化的中期目标;2026年12月期三季度财报在2026年11月9日截止日时尚未发布。
数据没有披露,不等于经营差,也不等于风险不存在。上述若干项是可以公开取得的文件,下一次更新可能降低其不确定性;晚于截止日发布的信息属于后续更新。
15.3|研究目的与风险提示
本报告是对公司的研究记录,目的是解释公司与证据,不构成买卖建议。结论依赖上述日期的公开资料和第9章所列倍数口径,价格会随市场变动,正常化利润区间是研究自己的估算,不是公司披露的指标。主要风险包括电极周期的下行、碳化硅利润被少数股东分走一半、指引变化、日元汇率反转和美国关税,详见第11章。
主要资料来源
- FY12/2025 consolidated results (tanshin): issuer identity and headline earnings
- GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%
- Filing frame: EDINET code E01140, securities report 25 March 2026, AGM 27 March 2026, governance report 30 March 2026
- SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon
- Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million
- Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear
- Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised
- FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million
- Shareholder register (EDINET database over securities-report filings): top holders and ownership mix
- Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%
- IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91
研究发现索引
展开本次 Review 的 83 项研究发现
F001|Nippon Carbon Co., Ltd. (日本カーボン株式会社; legal name Nippon Carbon Kabushiki Kaisha), TSE Prime 5302, EDINET E01140, founded 1915, capital JPY 7,402 million, December year-end, is a carbon-materials maker with three reported segments: carbon products (about 86% of FY12/25 sales; electrodes and fine carbon), silicon-carbide products (about 11%) and other/industrial machinery (about 3%). FY12/25: sales JPY 37,735 million (-0.6%), operating profit JPY 4,809 million (-23.9%), net income JPY 4,830 million (+18.4%). Filing frame (securities report 25 Mar 2026, AGM 27 Mar 2026) and the English form are confirmed by primary sources and the alliance partner's official English page.
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|公司卖的是客户高温工艺中被消耗掉的材料
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/2025 consolidated results (tanshin): issuer identity and headline earnings怎么使用:直接 / 支持;一手验证:01
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接 / 支持;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Filing frame: EDINET code E01140, securities report 25 March 2026, AGM 27 March 2026, governance report 30 March 2026怎么使用:直接 / 支持;一手验证:01;专项深挖:01
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:直接证据;外部现实校验:01、07、24
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:支持证据;一手验证:02、03、16
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 支持证据 / 一手证据(研究域01) / 定向深挖(研究域01)|Filing frame: EDINET code E01140, securities report 25 March 2026, AGM 27 March 2026, governance report 30 March 2026;直接证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other
完整研究记录(核对用)
研究原文:Nippon Carbon Co., Ltd. (日本カーボン株式会社; legal name Nippon Carbon Kabushiki Kaisha), TSE Prime 5302, EDINET E01140, founded 1915, capital JPY 7,402 million, December year-end, is a carbon-materials maker with three reported segments: carbon products (about 86% of FY12/25 sales; electrodes and fine carbon), silicon-carbide products (about 11%) and other/industrial machinery (about 3%). FY12/25: sales JPY 37,735 million (-0.6%), operating profit JPY 4,809 million (-23.9%), net income JPY 4,830 million (+18.4%). Filing frame (securities report 25 Mar 2026, AGM 27 Mar 2026) and the English form are confirmed by primary sources and the alliance partner's official English page.
内部研究类型:EconomicIdentity
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Fixes the investable perimeter: a 110-year-old materials maker with no controlling shareholder whose best business is a joint venture.
不确定性(原始记录):Full securities-report register was used via compiled database, not read in the original PDF.
F002|03|产品越往上走,差异化越强,利润率也越高
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Product map from the 2012 joint-venture release and the filings: electrodes, special carbon, NICALON fibre, anode materials怎么使用:直接 / 支持;一手验证:03、04、08;专项深挖:03
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:直接 / 支持;一手验证:04、10;专项深挖:04、10
Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing怎么使用:直接 / 支持;外部现实校验:13、23
Business model constitution: three segments, one consumables-and-materials model怎么使用:直接证据;一手验证:02、15;专项深挖:02、15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 定向深挖(研究域03)|Product map from the 2012 joint-venture release and the filings: electrodes, special carbon, NICALON fibre, anode materials;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域23)|Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing;直接证据|Sustainability and new-business directions named in the plan: power-semiconductor products and carbon-neutrality businesses;直接证据 / 一手证据(研究域02) / 一手证据(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域15)|Business model constitution: three segments, one consumables-and-materials model
完整研究记录(核对用)
研究原文:Products: artificial graphite electrodes (electric-arc-furnace steel), fine carbon (special graphite for semiconductor/solar production), NICALON silicon-carbide continuous fibre (mass production 1983, Hi-NICALON 1995) for ceramic-matrix composites in aircraft-engine hot sections, carbon-fibre insulation, lithium-ion anode materials and industrial machinery; power-semiconductor-related products and carbon-neutrality businesses are named only as development directions with no disclosed targets, timetable or investment. Differentiation rises along electrodes (price/cost) → fine carbon (specification) → fibre (qualification), which is also the order of margin and durability.
内部研究类型:ProductProfitPoolMap
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Shareholders carry commodity spread exposure on most revenue today, with the qualified fibre layer (half-owned) carrying margin and growth.
不确定性(原始记录):No revenue split of fine carbon by application; new-business directions are options, not valued growth.
F003|02|利润重心已经移到最小的业务,销售重心没有
研究范围:开放研究
写入正文:02|利润重心已经移到最小的业务,销售重心没有12|净利润上升,其实是证券收益盖住了经营下滑
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:直接 / 支持;一手验证:15
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;直接证据 / 支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year
完整研究记录(核对用)
研究原文:FY12/25 segment economics before corporate adjustments: carbon products sales JPY 32,397 million, operating profit JPY 2,990 million (-42.5%), margin about 9.2%; silicon carbide JPY 4,128 million, JPY 1,479 million (+72.9%), about 35.8%; other JPY 1,209 million, JPY 330 million (+35.6%), about 27.3%. In H1 FY12/26 the SiC margin widened to about 39.5% while carbon compressed to about 8.1%; H1 sub-product sales were fine carbon JPY 10,024 million (about 53% of group), electrodes JPY 6,003 million (about 32%), SiC JPY 2,414 million (about 13%). SiC profit was 74% of carbon's on about one-seventh of its sales: profit centre of gravity has moved to the smallest segment, sales centre of gravity has not.
内部研究类型:SegmentEconomics
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Segment profit, not sales, is the honest tracking variable; one point of mix toward fibre is worth roughly four points of electrode growth.
不确定性(原始记录):Segment figures are before corporate adjustments; allocation of fire costs between segment and corporate lines is not shown.
F004|02|碳化硅是利润引擎,但一半经济利益在伙伴手里
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:直接 / 支持;一手验证:15
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接证据;一手验证:20
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;直接证据 / 支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;直接证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%
完整研究记录(核对用)
研究原文:Silicon-carbide products are the profit engine: FY12/25 sales JPY 4,128 million (+52.9%) and operating profit JPY 1,479 million (+72.9%) — about 31% of segment operating profit from about 11% of sales at about 35.8% margin, rising to about 39.5% in H1 FY12/26 — produced by a business the parent owns only 50% of and that runs at full production capacity.
内部研究类型:ProfitEngine
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The scarce, durable, high-margin earnings stream — but headline growth overstates what accrues to parent shareholders.
不确定性(原始记录):Capacity ceiling means further growth depends on an undisclosed expansion path (see SiC capacity debt).
F005|06|碳素板块:新产能的成本先到,销量还没到
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:直接 / 支持;一手验证:15
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million怎么使用:直接证据;一手验证:20;专项深挖:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;直接证据 / 支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 一手证据(研究域20) / 定向深挖(研究域20)|Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million;直接证据 / 支持证据|Interim trajectory: Q1 shock, Q2 repair - the half-year path inside FY12/26;支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear
完整研究记录(核对用)
研究原文:Carbon products (electrodes plus fine carbon) are the sales base and most of the cyclicality: FY12/25 profit fell 42.5% on a 5.7% sales decline (fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports); H1 FY12/26 sales +2.1% but profit -23.1% because the completed capacity expansion's manufacturing costs arrived ahead of volume absorption. Implied carbon margin recovered from about 7.0% in Q1 to about 9.0% in Q2 FY12/26.
内部研究类型:SegmentMechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Largest single swing factor in group operating profit; the repair is a volume-absorption question, not a spending question.
不确定性(原始记录):Only one quarter of margin repair printed; electrode price direction and fine-carbon application split not disclosed.
F006|04|NGS Advanced Fibers:用经济利益换认证与需求
研究范围:开放研究+35项覆盖检查
写入正文:04|NGS Advanced Fibers:用经济利益换认证与需求05|护城河真实但很窄,只落在碳化硅纤维一处
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:直接 / 支持;一手验证:07;外部现实校验:06;专项深挖:07
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:支持证据;外部现实校验:01、07、24
Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012怎么使用:支持证据;一手验证:09、10;专项深挖:09
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:支持证据;一手验证:04、10;专项深挖:04、10
Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes怎么使用:支持证据;一手验证:08;专项深挖:08
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;支持证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon;支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 定向深挖(研究域09)|Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012;支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;支持证据 / 一手证据(研究域08) / 定向深挖(研究域08)|Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes
完整研究记录(核对用)
研究原文:NGS Advanced Fibers (2012; Nippon Carbon 50%, GE 25%, Safran 25%; NICALON business transferred in) carries the fibre franchise as a consolidated subsidiary; the co-owners are the parents of the fibre's engine customers. The structure trades economics for qualification, demand visibility and customer commitment, and was formed against an expected tenfold demand increase over ten years.
内部研究类型:StrategicGeometry
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Half of the best asset's economics are permanently shared; both lock-in and leakage come from the same ownership structure.
不确定性(原始记录):Partner economics beyond ownership split and consolidated minority interest are undisclosed; any NGS expansion agreement is not public.
F007|03|碳化硅需求来自CFM LEAP发动机的放量
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
Demand engines as disclosed: steel (electrodes), semiconductors (fine carbon), aerospace (SiC fibre), machinery怎么使用:直接证据;一手验证:05、11;专项深挖:05、11
Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012怎么使用:支持证据;一手验证:09、10;专项深挖:09
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:支持证据;一手验证:04、10;专项深挖:04、10
Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes怎么使用:支持证据;一手验证:08;专项深挖:08
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Demand engines as disclosed: steel (electrodes), semiconductors (fine carbon), aerospace (SiC fibre), machinery;支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 定向深挖(研究域09)|Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012;支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;支持证据 / 一手证据(研究域08) / 定向深挖(研究域08)|Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes
完整研究记录(核对用)
研究原文:Silicon-carbide fibre demand is the ceramic-matrix-composite hot-section demand of CFM LEAP engines (A320neo, 737 MAX, C919); aircraft-engine fibre volumes above plan were a named driver of the H1 FY12/26 operating beat. Aerospace demand is schedule-driven and qualification-locked, the most durable in the group, but concentrates the highest margin on one engine family's ramp.
内部研究类型:EndMarketDemand
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Durable volume for the franchise leg; programme-rate risk is a single-source risk.
不确定性(原始记录):Current LEAP production-rate trajectory is outside the sources read.
F008|03|三条需求线2025年朝三个方向走
研究范围:35项覆盖检查+开放研究
写入正文:03|三条需求线2025年朝三个方向走14|八项得分:资产负债表最高,治理最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(10项,重复标签已合并)
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:直接证据;一手验证:05;外部现实校验:02、09、11、12、14、15
Demand engines as disclosed: steel (electrodes), semiconductors (fine carbon), aerospace (SiC fibre), machinery怎么使用:直接证据;一手验证:05、11;专项深挖:05、11
Business model constitution: three segments, one consumables-and-materials model怎么使用:直接证据;一手验证:02、15;专项深挖:02、15
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:直接证据;一手验证:15
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:支持证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:支持证据;一手验证:02、03、16
Product map from the 2012 joint-venture release and the filings: electrodes, special carbon, NICALON fibre, anode materials怎么使用:支持证据;一手验证:03、04、08;专项深挖:03
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:支持证据;一手验证:04、10;专项深挖:04、10
Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing怎么使用:支持证据;外部现实校验:13、23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Demand engines as disclosed: steel (electrodes), semiconductors (fine carbon), aerospace (SiC fibre), machinery;直接证据 / 一手证据(研究域02) / 一手证据(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域15)|Business model constitution: three segments, one consumables-and-materials model;直接证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 定向深挖(研究域03)|Product map from the 2012 joint-venture release and the filings: electrodes, special carbon, NICALON fibre, anode materials;支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;支持证据 / 外部现实(研究域13) / 外部现实(研究域23)|Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing
完整研究记录(核对用)
研究原文:Three demand engines moved in three directions in FY12/25: steel-linked electrodes up on North American exports, semiconductor-linked fine carbon down in the power-semiconductor slowdown, aerospace-linked SiC at full capacity. Revenue is production-volume revenue (steel output, wafer starts, engine deliveries) with no recurring-revenue or backlog measure disclosed; diversified in direction, correlated in a global downturn.
内部研究类型:DemandStructure
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Volume risk cannot be diversified inside the stock; holders own a spread of three cycles plus a balance sheet that waits them out.
不确定性(原始记录):Customer names, contract volumes and domestic/export electrode split undisclosed.
F009|07|少数股东权益:增长的一半被分走
研究范围:开放研究+35项覆盖检查
写入正文:07|少数股东权益:增长的一半被分走09|按母公司每股价值估值,增长要打折
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接 / 支持;一手验证:07、09、11、33;外部现实校验:03、04、08、10
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:直接证据;一手验证:07;外部现实校验:06;专项深挖:07
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries
完整研究记录(核对用)
研究原文:Non-controlling interests of JPY 9,213 million (14.5% of consolidated net assets, principally the GE and Safran stakes in NGS) absorbed JPY 557 million of FY12/25 group net income (JPY 723 million in FY12/24) and received JPY 178 million of dividends. Headline SiC growth overstates the parent shareholders' claim by roughly the minority share; valuation must be done on parent earnings (EPS), not segment profit.
内部研究类型:ValueLeakage
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Every yen of SiC growth is shared; the 'about 50%' leakage is an approximation, since the minority interest relates principally, not exclusively, to NGS.
不确定性(原始记录):The JPY 557 million is a group-level minority figure, not an NGS-only attribution; precise SiC-level split not disclosed.
F010|04|与同业SEC Carbon的相互持股
研究范围:开放研究+35项覆盖检查
写入正文:04|与同业SEC Carbon的相互持股07|没有控股股东,个人股东占55.41%
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Shareholder register (EDINET database over securities-report filings): top holders and ownership mix怎么使用:直接 / 支持;一手验证:24
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:直接 / 支持;外部现实校验:01、07、24
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:直接 / 支持;一手验证:07;外部现实校验:06;专项深挖:07
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:支持证据;一手验证:19、21、29;反向验证:19、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24)|Shareholder register (EDINET database over securities-report filings): top holders and ownership mix;直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries;支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror
完整研究记录(核对用)
研究原文:SEC Carbon (5304), the domestic carbon peer, is capital and business alliance partner since October 2022: SEC Carbon holds 444,200 Nippon Carbon shares (4.08%) and Nippon Carbon holds 813 thousand SEC Carbon shares (4.06% at 31 March 2026, per SEC Carbon's official English page). The reciprocal holding stabilises the register and signals industry cooperation but is a strategic, non-arbitrage holding.
内部研究类型:StrategicGeometry
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Part of the register will not arbitrage the discount; it steadies the present rather than creating growth.
不确定性(原始记录):Alliance business content beyond the holdings is described only generally.
F011|06|净利润上升来自卖证券,经营利润其实下降了
研究范围:开放研究+35项覆盖检查
写入正文:06|净利润上升来自卖证券,经营利润其实下降了09|正常化盈利:46亿—71亿日元,区间本身就是发现14|八项得分:资产负债表最高,治理最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/2025 consolidated results (tanshin): issuer identity and headline earnings怎么使用:直接 / 支持;一手验证:01
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges怎么使用:直接证据;一手验证:16、28、32;专项深挖:16、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 一手证据(研究域16) / 一手证据(研究域28) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges
完整研究记录(核对用)
研究原文:The FY12/25 headline inverts the year's economics: net income rose 18.4% to JPY 4,830 million because a JPY 3,530 million securities-sale gain exceeded the JPY 803 million fire loss, while operating profit fell 23.9% to JPY 4,809 million and gross margin compressed 3.1 points to 27.2% (cost and mix inside carbon products, not overhead). The FY12/26 forecast net decline of 44.1% (JPY 2,700 million, EPS JPY 244.19, no extraordinary items assumed) is the lapse of the gain, not newly guided operating deterioration; guided operating margin falls to about 10.5% on +8.7% sales. Printed EPS of JPY 436.91 must not anchor valuation.
内部研究类型:EarningsQualityInversion
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Reported ROE of 9.1% and net income growth are flattered by non-operating gain; clean EPS basis is the FY12/26 forecast.
不确定性(原始记录):The numerical correction to the earnings release filed 25 March 2026 was not read and is unclassified.
F012|09|正常化盈利:46亿—71亿日元,区间本身就是发现
研究范围:35项覆盖检查+开放研究
写入正文:09|正常化盈利:46亿—71亿日元,区间本身就是发现
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges怎么使用:直接 / 支持;一手验证:16、28、32;专项深挖:16、32
Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement怎么使用:直接证据;一手验证:28;外部现实校验:27;专项深挖:28
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域28) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges;直接证据 / 一手证据(研究域28) / 外部现实(研究域27) / 定向深挖(研究域28)|Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed
完整研究记录(核对用)
研究原文:FY12/25 ordinary profit of JPY 5,103 million already excludes the extraordinary gain/loss pair; adding back the JPY 270 million idle-equipment charge gives an underlying level of about JPY 5.4 billion. With the FY12/23-25 actuals (7,115 / 6,692 / 5,103) and the FY12/26 plan (4,600), the research's normalised ordinary-profit band is about JPY 4.6-7.1 billion (centre about JPY 5.2 billion), mid-cycle, with SiC at capacity, carbon at a low ebb and the SiC pool shared 50/50. This band is the research's own arithmetic; the company publishes no underlying-profit measure.
内部研究类型:NormalizedEarningsPower
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Capitalising the centre at the market value gives roughly 10.5 times — the honest multiple between the two headline PERs.
不确定性(原始记录):A genuine full-cycle trough year cannot be computed from the five-year window; the FY12/18-20 record is the trough reference; width of band is itself the finding.
F013|06|上半年的下滑被累计数字夸大了,但指引没有跟着上调
研究范围:开放研究+35项覆盖检查
写入正文:06|上半年的下滑被累计数字夸大了,但指引没有跟着上调
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear怎么使用:直接 / 支持
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed怎么使用:直接 / 支持
查看完整证据标签(核对用)
直接证据 / 支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 支持证据|Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed;直接证据 / 支持证据|Interim trajectory: Q1 shock, Q2 repair - the half-year path inside FY12/26
完整研究记录(核对用)
研究原文:The H1 FY12/26 decline is narrower than its headline: operating profit -5.1% (JPY 2,475 million), but Q2 alone was JPY 1,418 million, about 7% above the prior-year quarter. The half's weakness is a Q1 event (operating profit -17.9%, carbon segment -34.6%) plus non-operating drag: cumulative idle-equipment costs JPY 324 million and an equity-method swing from +JPY 100 million (FY12/25) to -JPY 38 million; ordinary profit -14.0% and net income -40.5% exaggerate the operating trend. Repair, not slide — but the Q2 carbon margin (about 9.0%) is still below what second-half arithmetic requires.
内部研究类型:TrajectoryReading
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Cumulative headlines overstate deterioration; the Q3 print tests whether the repair extends.
不确定性(原始记录):Single quarter of repair; fire provision schedule by line and equity-method affiliate undisclosed.
F014|06|上半年的下滑被累计数字夸大了,但指引没有跟着上调
研究范围:开放研究+35项覆盖检查
写入正文:06|上半年的下滑被累计数字夸大了,但指引没有跟着上调11|指引是保守还是有预见,下半年才知道
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:直接 / 支持;反向验证:31、35
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接证据;反向验证:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;直接证据 / 支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;直接证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed
完整研究记录(核对用)
研究原文:H1 FY12/26 beat the February interim plan by 54.7% at operating profit (JPY 2,475 million vs JPY 1,600 million; ordinary +30.08%, net +24.17%, sales +0.12%) on yen depreciation against the JPY 145 plan rate and above-plan aircraft-engine SiC volumes, despite below-plan electrode and fine-carbon volumes. Full-year guidance (operating profit JPY 4,300 million, net income JPY 2,700 million) was left unchanged; the implied second half is operating profit about JPY 1,825 million (26% below the first half's actual) on about 16% higher sales. Guidance functions as a floor with conservative second-half assumptions rather than a central estimate; which of FX give-back, softer volumes, residual fire costs or conservatism dominates is not disclosed.
内部研究类型:GuidanceBehaviour
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Risk to the forecast is skewed to caution in profit and two-sided in sales; a Q3 cut would validate the market's scepticism, holding guidance would beat it.
不确定性(原始记录):Attribution of the second-half step-down is undisclosed.
F015|06|火灾、库存换位和成本抬升,出在同一个生产系统里
研究范围:开放研究+35项覆盖检查
写入正文:06|火灾、库存换位和成本抬升,出在同一个生产系统里13|库存78亿日元的换位和火灾尾部,什么时候说清?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Toyama plant fire (29 August 2025): the accounting footprint across FY12/25 and H1 FY12/26怎么使用:直接 / 支持;一手验证:06;反向验证:06、16
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure怎么使用:直接证据;一手验证:06、14;专项深挖:06、14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域06) / 反证(研究域16)|Toyama plant fire (29 August 2025): the accounting footprint across FY12/25 and H1 FY12/26;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 一手证据(研究域06) / 一手证据(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure
完整研究记录(核对用)
研究原文:The August 2025 Toyama plant fire runs through FY12/25-FY12/26 accounts: FY12/25 extraordinary loss JPY 803 million, provision JPY 768 million (JPY 765 million at H1 FY12/26), idle-equipment costs JPY 270 million in FY12/25 rising to a cumulative JPY 324 million by H1 FY12/26, and JPY 513 million of insurance proceeds received inside H1 operating cash flow; disclosure chain closed with a final report on 31 March 2026 whose restoration detail was not read. Open: what remains to be charged against the provision and whether full production restoration was confirmed, and at which product lines. The fire also demonstrated Toyama single-site concentration.
内部研究类型:OneOffTail
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Clouds the segment-margin read until charges stop; insurance receipt inflates H1 operating cash flow as non-run-rate.
不确定性(原始记录):Remaining charge schedule, restoration scope and site rebalancing unknown.
F016|06|火灾、库存换位和成本抬升,出在同一个生产系统里
研究范围:开放研究+35项覆盖检查
写入正文:06|火灾、库存换位和成本抬升,出在同一个生产系统里13|库存78亿日元的换位和火灾尾部,什么时候说清?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
Working capital: the FY12/25 inventory mirror and a receivables position that recovered in H1 FY12/26怎么使用:直接 / 支持;一手验证:19、32;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域32) / 定向深挖(研究域19)|Working capital: the FY12/25 inventory mirror and a receivables position that recovered in H1 FY12/26
完整研究记录(核对用)
研究原文:FY12/25 inventories were flat in total at about JPY 19.6 billion but rotated internally: finished goods fell JPY 7,850 million (11,301 to 3,451) while work in process rose JPY 7,690 million (4,543 to 12,233), in the same year as the Toyama fire and fine-carbon capacity completion; the tanshin offers no bridge. Candidate causes — fire-related restaging, expansion staging, reclassification — are all consistent with the numbers and none is evidenced; if unsold finished product was reclassified it defers a write-down. H1 FY12/26 then released JPY 2,131 million from receivables. Until a bridge appears, inventory quality is an open item and about JPY 7.8 billion of composition carries an information discount, including for any liquidation-style downside value.
内部研究类型:AccountingAnomalyOpenItem
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A clean bridge would remove the discount in either direction; inventory-heavy ratios must not be treated as liquid downside value.
不确定性(原始记录):Cause of the rotation unresolved; resolves with the FY12/26 securities report inventory notes (March 2027).
F017|08|2026年回报上调:回购用满上限,分红守住200日元
研究范围:开放研究+35项覆盖检查
写入正文:08|2026年回报上调:回购用满上限,分红守住200日元14|八项得分:资产负债表最高,治理最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接 / 支持;外部现实校验:26
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:直接 / 支持;一手验证:26
Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
Dividend framework as practised: a fixed JPY 200 through a full earnings cycle, payout ratio as the residual怎么使用:直接 / 支持
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接证据;外部现实校验:17、18、19、20、21、25;反向验证:17
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million怎么使用:支持证据;一手验证:20;专项深挖:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return;直接证据 / 支持证据|Dividend framework as practised: a fixed JPY 200 through a full earnings cycle, payout ratio as the residual;直接证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million
完整研究记录(核对用)
研究原文:The 2026 return step-up is complete: buyback resolved 10 Feb 2026 and executed 2 Mar–31 Aug at 521,600 shares for JPY 2,499,678,000 (99.99% of the money cap; 83.5% of the share cap), treasury shares to about 1,297,716 (about 11.0% of 11,832,504 issued); JPY 200 dividend for a fifth consecutive year, forecast again for FY12/26 (81.9% payout on clean EPS; fixed-yen, no stated policy formula; total about JPY 2.2 billion a year). Combined FY12/26 returns about JPY 4.7 billion versus forecast net income JPY 2,700 million (about 1.7 times) and FY12/25 free cash flow of about JPY 0.8 billion; capex halved to JPY 1,386 million in H1 as the expansion ended. Revealed preference ranks valuation repair above further capacity; the buyback is proven for exactly one programme.
内部研究类型:CapitalReturnProgramme
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Income holders get 4.34% forecast yield; total-return holders get below-book buyback accretion; durability rests on follow-through at the February 2027 print.
不确定性(原始记录):No stated total-return or payout framework binds future boards; combined return figure counts the interim dividend on forecast terms.
F018|06|资产负债表:净现金、63.5%权益比率,证据最扎实
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表:净现金、63.5%权益比率,证据最扎实14|八项得分:资产负债表最高,治理最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million怎么使用:直接 / 支持;一手验证:18;专项深挖:18
Debt profile: borrowings are almost entirely short-term - and covered 1.5 times by cash怎么使用:直接 / 支持;一手验证:18、25;专项深挖:25
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:22;反向验证:27
Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book怎么使用:直接证据;一手验证:21;外部现实校验:29;专项深挖:21
Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend怎么使用:支持证据;外部现实校验:28;同业比较:01、04、06、07、12、13、16、17、18、19、20、21、22、23、24、25、26、27、29、30、32、33;其他用途:历史
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:支持证据;一手验证:17、25;反向验证:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 支持证据 / 一手证据(研究域18) / 定向深挖(研究域18)|Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 定向深挖(研究域25)|Debt profile: borrowings are almost entirely short-term - and covered 1.5 times by cash;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;直接证据 / 一手证据(研究域21) / 外部现实(研究域29) / 定向深挖(研究域21)|Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book;支持证据 / 外部现实(研究域28) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域27) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域33)|Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend;支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds
完整研究记录(核对用)
研究原文:FY12/25 balance sheet: total assets JPY 85,607 million, liabilities JPY 22,000 million, net assets JPY 63,607 million (parent equity JPY 54,393 million, NCI JPY 9,213 million), equity ratio 63.5% (64.2% at H1 FY12/26), cash and deposits JPY 15,180 million against borrowings JPY 10,331 million (98% short-term; covered about 1.5 times by cash; interest paid JPY 113 million) — net cash about JPY 4.7 billion, positive every year of the window; BPS JPY 4,919.46 rising to JPY 5,041.20 at H1. Priced at JPY 4,610 (6 Nov 2026), PBR is below one: the discount is applied to earnings variance, not the asset base. Investment securities JPY 10,197 million (JPY 11,623 million at H1) and land at JPY 3,582 million historical cost form a finite, partly strategic reservoir (including the 4.06% SEC Carbon stake) that funds the return programme.
内部研究类型:FinancialResilience
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Converts the equity from a leveraged cycle claim into an unlevered one; trough earnings hurt the price, not the claim.
不确定性(原始记录):Securities composition (strategic vs financial), undrawn facilities and pledged assets not disclosed; marks move with markets; consolidated cash includes minority-shared entities, so parent-available cash is not separately shown.
F019|08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头
研究范围:35项覆盖检查+开放研究
写入正文:08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头09|按母公司每股价值估值,增长要打折
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接 / 支持;外部现实校验:26
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend怎么使用:直接 / 支持;外部现实校验:28;同业比较:01、04、06、07、12、13、16、17、18、19、20、21、22、23、24、25、26、27、29、30、32、33;其他用途:历史
Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book怎么使用:直接证据;一手验证:21;外部现实校验:29;专项深挖:21
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:支持证据;一手验证:26
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:支持证据;反向验证:28
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:支持证据;一手验证:19、21、29;反向验证:19、32
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:支持证据;一手验证:27、31;外部现实校验:22;反向验证:27
Financial history FY12/21-FY12/25: a sales plateau at JPY 37-38 billion and an operating-margin round-trip怎么使用:支持证据;一手验证:33;专项深挖:33;同业比较:02、03、09、15、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 支持证据 / 外部现实(研究域28) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域27) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域33)|Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend;直接证据 / 一手证据(研究域21) / 外部现实(研究域29) / 定向深挖(研究域21)|Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book;支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%;支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域33)|Financial history FY12/21-FY12/25: a sales plateau at JPY 37-38 billion and an operating-margin round-trip
完整研究记录(核对用)
研究原文:Buybacks below book plus retained earnings lifted BPS from JPY 4,919.46 (FY12/25) to JPY 5,041.20 (H1 FY12/26) in a half when net income fell 40.5%; BPS compounded from JPY 4,073.6 in five years without any increase in shares issued. Every buyback yen spent below book transfers value from the financial-asset reservoir to continuing holders.
内部研究类型:PerShareCompounding
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):The floor per share rises roughly 2-3% a year on current behaviour; the effective entry multiple falls with time independent of price.
不确定性(原始记录):Mechanism is self-reinforcing only while price stays below book and the reservoir lasts (runway of years, not indefinite).
F020|01|三项反证决定仓位大小
研究范围:开放研究+35项覆盖检查
写入正文:01|三项反证决定仓位大小04|三条产品线面对三种竞争,电极周期决定利润范围
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:直接 / 支持;一手验证:05;外部现实校验:02、09、11、12、14、15
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:直接 / 支持;一手验证:12;专项深挖:12
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;直接证据 / 支持证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)
完整研究记录(核对用)
研究原文:Electrode cyclicality dominates the long record: ordinary profit JPY 16,508 million (FY12/18, sales JPY 47,469 million) fell about 76% to JPY 3,587 million (FY12/20) and recovered only to JPY 5,103 million by FY12/25; sales never regained the FY12/18 level. The FY12/23-25 plateau (7,115 / 6,692 / 5,103) is a mid-cycle resting point that a renewed electrode downturn could halve again; fine carbon adds a second, semiconductor-linked cycle on a different clock; group amplitude has exceeded a factor of four within three years.
内部研究类型:CycleAmplitude
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Sets the range inside which the thesis must be underwritten; position size should follow the trough scenario, not the plateau.
不确定性(原始记录):No external electrode price series obtained; whether the plateau lasts is not answerable from filings.
F021|06|五年是有利润的平台,ROE一直没到两位数
研究范围:35项覆盖检查+开放研究
写入正文:06|五年是有利润的平台,ROE一直没到两位数08|回报会不会成为政策:两份文件决定
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Financial history FY12/21-FY12/25: a sales plateau at JPY 37-38 billion and an operating-margin round-trip怎么使用:直接 / 支持;一手验证:33;专项深挖:33;同业比较:02、03、09、15、35;其他用途:历史
Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend怎么使用:直接 / 支持;外部现实校验:28;同业比较:01、04、06、07、12、13、16、17、18、19、20、21、22、23、24、25、26、27、29、30、32、33;其他用途:历史
Profitability quality: ROE 9.1% in FY12/25 is flattered by the securities gain; the operating return on assets is mid-single-digit怎么使用:直接证据;一手验证:22;专项深挖:22
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:支持证据;一手验证:12;专项深挖:12
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域33)|Financial history FY12/21-FY12/25: a sales plateau at JPY 37-38 billion and an operating-margin round-trip;直接证据 / 支持证据 / 外部现实(研究域28) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域27) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域33)|Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Profitability quality: ROE 9.1% in FY12/25 is flattered by the securities gain; the operating return on assets is mid-single-digit;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;支持证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)
完整研究记录(核对用)
研究原文:FY12/21-25 is a profitable plateau, not decline or growth: sales JPY 31,578 / 35,799 / 37,867 / 37,956 / 37,735 million; operating profit 3,706 / 4,791 / 6,573 / 6,319 / 4,809 million; operating margin round-tripping 11.7% → 17.4% → 12.7%; ROE 6.1% / 7.1% / 8.5% / 8.0% / 9.1% (never double digits, last flattered by the securities gain; FY12/26 forecast ROE 4.95%); equity ratio 61.4-63.5%; total assets and net assets thickening every year. Historical turning points that still govern today: 2012 NGS venture, FY12/18-20 electrode collapse, 2022 SEC alliance, FY12/23 margin peak, 2025 fire plus expansion completion, 2026 return reset.
内部研究类型:HistoricalPath
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Capital efficiency, not solvency, is the standing criticism; roughly JPY 25 billion of cash and securities earn deposit-like returns inside a JPY 54 billion equity base.
不确定性(原始记录):Whether 2026 joins the list as a turning point or a one-year episode is decided by the February 2027 print; ROIC is not disclosed and not computed.
F022|06|利润能变成现金,卡住自由现金流的是投资
研究范围:35项覆盖检查+开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Cash-flow quality: operating cash flow exceeded net income in FY12/25 and across the five-year window怎么使用:直接 / 支持;一手验证:17;专项深挖:17
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:直接 / 支持;一手验证:17、25;反向验证:26
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接证据;外部现实校验:17、18、19、20、21、25;反向验证:17
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|Cash-flow quality: operating cash flow exceeded net income in FY12/25 and across the five-year window;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds;直接证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received
完整研究记录(核对用)
研究原文:FY12/25 operating cash flow JPY 6,319 million exceeded group net income JPY 5,388 million (depreciation JPY 3,534 million; interest coverage 55.7 times); operating cash flow positive in each of five years (7,551 / 5,798 / 3,189 / 5,234 / 6,319). Free cash flow was only about JPY 0.8 billion after JPY 5,501 million of capex at the investment peak. H1 FY12/26 operating cash flow JPY 4,674 million includes JPY 513 million insurance proceeds and a JPY 2,131 million receivables release (both non-run-rate); with capex halved, the same operating profit yields roughly JPY 3 billion more annual free cash flow.
内部研究类型:CashConversion
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):FY12/26 returns exceed even the inflected free cash flow and are part-funded from the balance sheet; the run-rate arithmetic approximately closes from FY12/27 if profit holds.
不确定性(原始记录):Maintenance-vs-growth capex split not disclosed; an SiC expansion decision would reverse the inflection.
F023|06|碳素板块:新产能的成本先到,销量还没到
研究范围:35项覆盖检查+开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million怎么使用:直接 / 支持;一手验证:20;专项深挖:20
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year
完整研究记录(核对用)
研究原文:The asset base has finished its expansion phase: construction in progress fell from JPY 2,183 million to JPY 432 million in FY12/25, net machinery rose from JPY 8,811 million to JPY 10,815 million, capex was JPY 5,501 million (JPY 4,667 million in FY12/24) against depreciation of JPY 3,534 million, then JPY 1,386 million in H1 FY12/26. The interim filing states the new capacity's manufacturing costs compress fine-carbon profitability until volumes absorb them: the margin question is utilisation (a fixed-cost drag with a JPY 10.8 billion machinery base) rather than spending.
内部研究类型:CapitalAssetCycle
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):If volumes come, incremental fine-carbon volume drops through at high margin; if not, the same mechanism runs in reverse.
不确定性(原始记录):Nameplate capacity, utilisation and project detail not disclosed.
F024|05|护城河真实但很窄,只落在碳化硅纤维一处
研究范围:35项覆盖检查+开放研究
写入正文:05|护城河真实但很窄,只落在碳化硅纤维一处14|八项得分:资产负债表最高,治理最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012怎么使用:直接 / 支持;一手验证:09、10;专项深挖:09
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:直接 / 支持;一手验证:04、10;专项深挖:04、10
Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes怎么使用:直接 / 支持;一手验证:08;专项深挖:08
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 定向深挖(研究域09)|Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;直接证据 / 支持证据 / 一手证据(研究域08) / 定向深挖(研究域08)|Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes;直接证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%
完整研究记录(核对用)
研究原文:The moat is real but narrow and located in one place: NICALON is among the very few commercially qualified SiC fibres for CMC, designed into certified engine parts, with the engine makers' parents as co-owners of the supplier — a qualification-and-ownership lock-in measured in decades, with a forty-year technology lead. Electrodes (cost, quality, supply reliability) and commodity fine carbon carry no comparable lock-in; fine carbon has specification positions. The blended moat protects about a third of the profit pool completely, part of fine carbon partially and the electrode pool not at all.
内部研究类型:MoatAssessment
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Margin defence depends on holding fine-carbon specification positions while fibre matures the mix; an electrode price war reaches group profit within a year.
不确定性(原始记录):Inferred from qualification structure, not measured churn or pricing; no external share series; whether fine-carbon positions widen or narrow is unobservable; rival fibre qualification milestones outside sources.
F025|07|没有控股股东,个人股东占55.41%
研究范围:开放研究+35项覆盖检查
写入正文:07|没有控股股东,个人股东占55.41%14|八项得分:资产负债表最高,治理最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Shareholder register (EDINET database over securities-report filings): top holders and ownership mix怎么使用:直接 / 支持;一手验证:24
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:直接 / 支持;外部现实校验:01、07、24
Ownership detail: trust banks, relationship holders and a 55.41% retail base across 16,137 shareholders怎么使用:直接 / 支持;一手验证:24;专项深挖:24
Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place怎么使用:直接证据;一手验证:13、22、23;专项深挖:13、23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24)|Shareholder register (EDINET database over securities-report filings): top holders and ownership mix;直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon;直接证据 / 支持证据 / 一手证据(研究域24) / 定向深挖(研究域24)|Ownership detail: trust banks, relationship holders and a 55.41% retail base across 16,137 shareholders;直接证据 / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place
完整研究记录(核对用)
研究原文:The register has no controller: individuals 55.41%, financial institutions 27.15%, foreign holders 9.28%, other corporations 6.53% across 16,137 shareholders (FY12/25); trust-bank accounts about 14.1% (Master Trust 11.28%, Custody Bank 2.77%), Mizuho Bank 5.01%, SEC Carbon 4.08%, Nippon Life 3.92%; remaining top holders are individuals. A takeover-response policy was renewed on 10 Feb 2026 despite the absence of an anchor holder. Retail-majority registers with relationship anchors give low institutional arbitrage of the discount, event-driven retail flows and stability in stress.
内部研究类型:OwnershipStructure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The discount is more likely to close through per-share compounding and returns than through a control event; the defence policy insulates the board from market discipline.
不确定性(原始记录):Beneficial institutional ownership behind trust accounts not visible; whether the defence policy has a sunset or ratification mechanism is not in the materials read.
F026|07|中期计划只有方向,没有数值目标
研究范围:开放研究+35项覆盖检查
写入正文:07|中期计划只有方向,没有数值目标
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing怎么使用:直接 / 支持;外部现实校验:13、23
'GO BEYOND 2030' in operation: what the interim filing shows of the plan's product directions怎么使用:直接 / 支持
Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:支持证据;反向验证:28
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:支持证据;一手验证:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域23)|Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing;直接证据 / 支持证据|'GO BEYOND 2030' in operation: what the interim filing shows of the plan's product directions;直接证据|Sustainability and new-business directions named in the plan: power-semiconductor products and carbon-neutrality businesses;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return;支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year
完整研究记录(核对用)
研究原文:'GO BEYOND 2030' (FY12/25 first year) states directions — profitability improvement, sustainability management, stronger shareholder returns; fine carbon: expand share and optimal production structure; electrodes: thorough cost reduction and channel review; SiC: secure people and safe operations; new businesses: power-semiconductor products, carbon-neutrality. The 2026 actions are consistent with it, but the tanshin discloses no numeric targets, and guidance implies about 10.5% operating margin on +8.7% sales. The plan cannot yet be scored or falsified from primary filings; credibility rests on the 2026 action sequence and on a successor framework appearing by February 2027.
内部研究类型:StrategicPlanCredibility
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Near-term proof must come from fine-carbon cost absorption and SiC volume, not plan language.
不确定性(原始记录):No numeric mid-term targets read; the capital-cost notice contents are unread.
F027|07|2026年的治理动作异常密集,纪律只有一年历史
研究范围:35项覆盖检查+开放研究
写入正文:07|2026年的治理动作异常密集,纪律只有一年历史
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place怎么使用:直接 / 支持;一手验证:13、22、23;专项深挖:13、23
IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026怎么使用:直接 / 支持;一手验证:13、23、30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域30)|IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026;直接证据|Disclosure quality: timely difference notices and English summaries; the gaps are the unread capital-cost notice and the unexplained inventory rotation
完整研究记录(核对用)
研究原文:The 2026 governance and register cluster is unusually dense: buyback resolution and defence-policy renewal (10 Feb), capital-cost notice and an earnings-release numerical correction (25 Mar), fire final report (31 Mar), corporate-governance report update (30 Mar), shareholder benefit programme (25 Aug), buyback completion (7 Sep); a board benefit trust aligns directors with the share price. Disclosure practice is timely (same-day forecast-difference notices, English summaries). It reads as a coordinated register-and-valuation programme executed inside one year, but its capital-discipline half is one year old.
内部研究类型:GovernanceBehaviour
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Minority protection is behavioural (a board currently choosing returns) rather than structural, and deserves the discount until the behaviour repeats.
不确定性(原始记录):Board composition, independence and compensation not read; durability unproven past the buyback's expiry.
F028|09|资产说便宜,干净盈利说不便宜,收益说有支撑
研究范围:开放研究+35项覆盖检查
写入正文:09|资产说便宜,干净盈利说不便宜,收益说有支撑14|八项得分:资产负债表最高,治理最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:22;反向验证:27
Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield怎么使用:直接 / 支持;一手验证:27;外部现实校验:31、35;专项深挖:27
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
FY12/2025 consolidated results (tanshin): issuer identity and headline earnings怎么使用:直接 / 支持;一手验证:01
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:直接 / 支持;一手验证:17、25;反向验证:26
Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement怎么使用:直接 / 支持;一手验证:28;外部现实校验:27;专项深挖:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域31) / 外部现实(研究域35) / 定向深挖(研究域27)|Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域27) / 定向深挖(研究域28)|Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement
完整研究记录(核对用)
研究原文:At the 6 Nov 2026 close of JPY 4,610 (research cut-off 9 Nov 2026; JPY 4,660 on 9 Nov): market capitalisation JPY 54.55 billion (11,832,504 shares issued); forecast PER 18.9x on FY12/26 forecast EPS JPY 244.19 (aggregator print 18.49x), about 10.6x on gain-inflated FY12/25 EPS JPY 436.91; PBR 0.94x on FY12/25-end BPS JPY 4,919.46 (0.91x on interim BPS JPY 5,041.20); FY12/25 ROE 9.1% (forecast 4.95%); forecast dividend yield 4.34% on JPY 200; EV/EBITDA 5.8x (EV JPY 48.61 billion after net cash of JPY 5.94 billion at 30 Jun 2026 — borrowings JPY 10,365 million vs cash and deposits JPY 16,305 million; EBITDA JPY 8.34 billion = FY12/25 operating profit plus depreciation). Asset value says cheap, clean earnings say full, income says supported; the market pays about 8-12 times the normalised ordinary band while paying below book.
内部研究类型:ValuationSnapshot
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A buyer at about book is short the electrode cycle's next leg down and long everything else; sizing should follow the trough scenario.
不确定性(原始记录):Multiples are aggregator-computed on company guidance; no peer multiple set compiled; EV mixes a market capitalisation including minority-shared value with consolidated net cash.
F029|09|这些倍数口径不同,不能混着比
研究范围:35项覆盖检查+开放研究
写入正文:09|这些倍数口径不同,不能混着比
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:22;反向验证:27
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接证据;一手验证:19、21、29;反向验证:19、32
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
FY12/2025 consolidated results (tanshin): issuer identity and headline earnings怎么使用:直接 / 支持;一手验证:01
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接证据;外部现实校验:26
Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield怎么使用:支持证据;一手验证:27;外部现实校验:31、35;专项深挖:27
Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement怎么使用:支持证据;一手验证:28;外部现实校验:27;专项深挖:28
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:支持证据;一手验证:17、25;反向验证:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;直接证据 / 支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;直接证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;支持证据 / 一手证据(研究域27) / 外部现实(研究域31) / 外部现实(研究域35) / 定向深挖(研究域27)|Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield;支持证据 / 一手证据(研究域28) / 外部现实(研究域27) / 定向深挖(研究域28)|Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement;支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds
完整研究记录(核对用)
研究原文:Valuation operands differ in basis and date and must not be mixed: PBR 0.91x uses interim BPS JPY 5,041.20 (30 Jun 2026) while 0.94x uses FY12/25-end BPS JPY 4,919.46; forecast PER 18.9x is price over the FY12/26 company forecast EPS of JPY 244.19 while the aggregator prints 18.49x; reported-EPS PER of about 10.6x uses a gain-inflated EPS; ROE 9.1% is FY12/25 actual including the securities gain while 4.95% is a forecast; EV uses net cash as of 30 Jun 2026 and EBITDA of FY12/25. Share-count denominator is 11,832,504 issued shares (market capitalisation) although about 11.0% are treasury shares, which affects per-share and market-cap readings.
内部研究类型:CalculationBasisIdentity
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Prevents false precision: headline multiples differ by several percent purely from denominator choice.
不确定性(原始记录):The source of the 18.49x versus 18.9x difference is not disclosed; treat both as the research recorded them.
F030|09|价格怀疑的是盈利,不是资产
研究范围:35项覆盖检查+开放研究
写入正文:09|价格怀疑的是盈利,不是资产
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Market expectations as priced on 6-9 November 2026: scepticism at the top of the year's range, calm at the print's approach怎么使用:直接证据;一手验证:31;专项深挖:31
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:22;反向验证:27
Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield怎么使用:直接 / 支持;一手验证:27;外部现实校验:31、35;专项深挖:27
Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement怎么使用:支持证据;一手验证:28;外部现实校验:27;专项深挖:28
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Downside structure: what protects the equity if both cycles turn down together怎么使用:支持证据;一手验证:29;专项深挖:29
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:支持证据;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|Market expectations as priced on 6-9 November 2026: scepticism at the top of the year's range, calm at the print's approach;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域31) / 外部现实(研究域35) / 定向深挖(研究域27)|Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield;支持证据 / 一手证据(研究域28) / 外部现实(研究域27) / 定向深挖(研究域28)|Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank
完整研究记录(核对用)
研究原文:Priced expectations: JPY 4,610 on 6 Nov (-3.35% on the day) and JPY 4,660 on 9 Nov sit below interim book and about 14-15% under the September-October highs (JPY 5,440 / 5,410), on unchanged company guidance; the 52-week range is JPY 4,275-5,440. The market doubts the earnings stream, not the assets: holding guidance after Q3 would beat the scepticism embedded in a sub-book price, a cut would validate it. Retail dominance (55.41% individuals) makes short-window price signals noisier; no analyst consensus series was available.
内部研究类型:MarketExpectationReading
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Positive surprises are under-priced relative to negative ones at about book with a 4.34% yield, provided the balance-sheet floor is real.
不确定性(原始记录):The 'market view' is the company's unrevised forecast as priced; expectations read over months, not days.
F031|09|下行保护是结构性的,真实损失是漫长的谷底
研究范围:35项覆盖检查+开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Downside structure: what protects the equity if both cycles turn down together怎么使用:直接 / 支持;一手验证:29;专项深挖:29
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:直接 / 支持;一手验证:12;专项深挖:12
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:支持证据;外部现实校验:17、18、19、20、21、25;反向验证:17
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:支持证据;一手验证:27、31;外部现实校验:22;反向验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 支持证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors);直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91
完整研究记录(核对用)
研究原文:Protection stack in order of hardness: net cash and a JPY 10-12 billion marked securities portfolio against JPY 22.0 billion of liabilities; 63.5% equity ratio; land at historical cost; fixed-yen dividend with a five-year unbroken record; schedule-driven aerospace demand. The realistic loss scenario is not impairment of the claim but a long trough: electrode downcycle taking group operating profit toward JPY 3 billion (ordinary profit toward JPY 3.6 billion as in FY12/20), a lower price, and years of waiting, cushioned by the yield. Soft spots: short-book rolling, the unexplained inventory rotation, the unfinished fire tail and a demonstrated 76% ordinary-profit fall in two years.
内部研究类型:DownsideMechanism
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Loss risk is opportunity cost and price drawdown rather than capital impairment; protection is structural, not dependent on management goodwill.
不确定性(原始记录):Liquidation values not estimated; protection value of inventory cannot currently be certified.
F032|11|宏观风险通过汇率、关税和原料三条管道进入利润表
研究范围:35项覆盖检查+开放研究
写入正文:11|宏观风险通过汇率、关税和原料三条管道进入利润表
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure怎么使用:直接证据;一手验证:06、14;专项深挖:06、14
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:直接证据;一手验证:12;专项深挖:12
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:支持证据;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:支持证据;一手验证:05;外部现实校验:02、09、11、12、14、15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 一手证据(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure;直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;直接证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors);支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity
完整研究记录(核对用)
研究原文:Macro reaches the P&L through three pipes: yen (plan rate JPY 145 vs FY12/25 average JPY 148.7; part of the H1 beat was yen depreciation), US tariff policy (named uncertainty bearing on North American electrode exports; April 2025 tariff shock printed the price's low), and raw-material/fuel prices (FY12/25 gross-margin compression of 3.1 points). A third, currency layer sits over both product cycles. No hedging or sensitivity table is disclosed.
内部研究类型:ExposureMap
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):A yen reversal is the nearest-term mechanical risk to the second half and is partly assumed by management's unchanged guidance.
不确定性(原始记录):Currency split of sales and costs undisclosed.
F033|01|净现金加低于账面的价格,买的是等待转换
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|净现金加低于账面的价格,买的是等待转换14|Kabugami 评分 V3.2:60.92/100分,评级 B
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:直接 / 支持;一手验证:35
Downside structure: what protects the equity if both cycles turn down together怎么使用:直接 / 支持;一手验证:29;专项深挖:29
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield怎么使用:直接证据;一手验证:27;外部现实校验:31、35;专项深挖:27
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;直接证据 / 支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 一手证据(研究域27) / 外部现实(研究域31) / 外部现实(研究域35) / 定向深挖(研究域27)|Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield;反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank
完整研究记录(核对用)
研究原文:The equity case is a balance-sheet-and-franchise case, not an earnings-momentum case: net cash, about book value, a half-owned but genuinely scarce aerospace fibre franchise at capacity, and demonstrated willingness to return about 1.7 times a clean year's earnings — underwritten on normalised ordinary profit of JPY 4.6-7.1 billion, held against electrode amplitude that halved group profit in two years before, the minority leakage of the best business's economics, and guidance that refuses to extrapolate the interim beat. Mechanism that pays the holder is conversion of financial assets and retained earnings via below-book buybacks and a defended dividend into a rising per-share claim on a slowly improving profit mix.
内部研究类型:InvestmentThesis
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Holder is paid 4.34% to wait for conversion; true cost is the trough scenario's opportunity cost. Durability is highest in the balance-sheet leg, high in the fibre leg, lowest in the capital-policy leg.
不确定性(原始记录):Conditioned by the standing evidence gaps and by guidance that the market treats as unrevised.
F034|01|什么会推翻这个判断
研究范围:开放研究+35项覆盖检查
写入正文:01|什么会推翻这个判断11|最近的催化剂是三季度财报,几天内就到
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Falsification anchors: the dated prints against which this research can be proven wrong怎么使用:直接 / 支持;一手验证:35;专项深挖:35
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:直接 / 支持
Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print怎么使用:直接证据;一手验证:30;专项深挖:30、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域35)|Falsification anchors: the dated prints against which this research can be proven wrong;直接证据 / 支持证据|Limitations anchor: what this research did not read, stated once and carried through every domain;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30) / 定向深挖(研究域34)|Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print
完整研究记录(核对用)
研究原文:The thesis falsifies on dated, observable evidence: (1) a Q3 FY12/26 print (expected on or about 10 Nov 2026) that cuts guidance or shows carbon margin still unrepaired; (2) a February 2027 annual print with no successor return framework after the expired buyback; (3) SiC volumes falling while running below capacity; (4) a renewed electrode downcycle taking group operating profit below about JPY 3 billion. Standing gaps condition every judgement: the unread capital-cost notice, the unexplained inventory rotation, the unnamed equity-method affiliate and the absence of numeric mid-term targets.
内部研究类型:FalsificationConditions
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Falsifiers should be pre-committed before the Q3 print, which arrives within days of the review date.
不确定性(原始记录):Q3 date is inferred from three years of prints, not company-announced; whether a pre-announced difference notice appears is unknowable.
F035|11|最近的催化剂是三季度财报,几天内就到
研究范围:开放研究+35项覆盖检查
写入正文:11|最近的催化剂是三季度财报,几天内就到13|三季度财报会不会延续二季度的修复?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print怎么使用:直接证据;一手验证:30;专项深挖:30、34
Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear怎么使用:直接 / 支持
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026怎么使用:直接证据;一手验证:13、23、30
Falsification anchors: the dated prints against which this research can be proven wrong怎么使用:支持证据;一手验证:35;专项深挖:35
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:支持证据
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域30) / 定向深挖(研究域30) / 定向深挖(研究域34)|Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print;直接证据 / 支持证据|Interim trajectory: Q1 shock, Q2 repair - the half-year path inside FY12/26;直接证据 / 支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域30)|IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026;支持证据|Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed;支持证据 / 一手证据(研究域35) / 定向深挖(研究域35)|Falsification anchors: the dated prints against which this research can be proven wrong;支持证据|Limitations anchor: what this research did not read, stated once and carried through every domain
完整研究记录(核对用)
研究原文:Open: what the Q3 FY12/26 tanshin (not published at freeze; expected on or about 10 Nov 2026 per prints on 10 Nov 2023, 11 Nov 2024, 10 Nov 2025) will show — whether Q2's year-on-year operating-profit recovery extends, whether fine-carbon absorption becomes visible in carbon segment margin toward the level the unchanged plan requires, and whether SiC holds its above-plan run-rate into the second half. Opposite answers move the thesis: repair keeps the 'Q1 event' reading, a cut or unrepaired margin falsifies it.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):First scored test of the thesis, post-dating the review date; any post-cutoff print belongs to a later Review.
不确定性(原始记录):Information first public after the 9 Nov 2026 cutoff; no current public path exists.
F036|13|下半年隐含的降幅到底来自什么?
研究范围:开放研究+35项覆盖检查
写入正文:13|下半年隐含的降幅到底来自什么?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:直接 / 支持;反向验证:31、35
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接证据;反向验证:28
查看完整证据标签(核对用)
直接证据 / 支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;直接证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed
完整研究记录(核对用)
研究原文:Open: which second-half assumptions keep full-year guidance unchanged after a +54.7% interim operating beat — expected exchange-rate give-back from the JPY 145 plan rate, softer electrode or fine-carbon volumes, residual fire-related cost recognition, or deliberate conservatism — and whether the Q3 print forces the first revision.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The answer reprices guidance credibility and FX sensitivity at once.
不确定性(原始记录):Company discloses the arithmetic but not the attribution.
F037|08|回报会不会成为政策:两份文件决定
研究范围:35项覆盖检查+开放研究
写入正文:08|回报会不会成为政策:两份文件决定13|资本成本公告写了什么,回购到期后会不会有接续?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place怎么使用:直接证据;一手验证:13、22、23;专项深挖:13、23
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:直接证据
IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026怎么使用:直接证据;一手验证:13、23、30
Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing怎么使用:直接 / 支持;外部现实校验:13、23
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:支持证据;反向验证:28
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:支持证据;一手验证:20
'GO BEYOND 2030' in operation: what the interim filing shows of the plan's product directions怎么使用:支持证据
Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return怎么使用:支持证据;一手验证:26;反向验证:22;专项深挖:26
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place;直接证据|Limitations anchor: what this research did not read, stated once and carried through every domain;直接证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域30)|IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域23)|Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing;支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;支持证据|'GO BEYOND 2030' in operation: what the interim filing shows of the plan's product directions;支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return
完整研究记录(核对用)
研究原文:Open: what the 25 March 2026 notice on management conscious of capital cost and share price commits to — an ROE target, a PBR remedy, a stated return policy — and whether it converts the 2026 return step-up (buyback to the cap, 81.9% forecast payout) into standing policy after the buyback frame expired. The notice's existence and date are established; its contents were not read line by line, so no ROE target or terms are asserted anywhere in this research. This is the single largest documentary gap.
内部研究类型:ResearchDebt
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Provides the missing scorecard for management on ROE trajectory under the capital-cost framework.
不确定性(原始记录):Contents unread; public document existed by the cutoff, so it is a gap carried by the frozen research, not evidence of absence.
F038|08|回报会不会成为政策:两份文件决定
研究范围:开放研究+35项覆盖检查
写入正文:08|回报会不会成为政策:两份文件决定13|资本成本公告写了什么,回购到期后会不会有接续?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接 / 支持;外部现实校验:26
Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print怎么使用:直接证据;一手验证:30;专项深挖:30、34
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:直接 / 支持;一手验证:26
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:支持证据;反向验证:28
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million怎么使用:支持证据;一手验证:20;专项深挖:20
Falsification anchors: the dated prints against which this research can be proven wrong怎么使用:支持证据;一手验证:35;专项深挖:35
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:支持证据
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30) / 定向深挖(研究域34)|Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%;支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million;支持证据 / 一手证据(研究域35) / 定向深挖(研究域35)|Falsification anchors: the dated prints against which this research can be proven wrong;支持证据|Limitations anchor: what this research did not read, stated once and carried through every domain
完整研究记录(核对用)
研究原文:Open: at the February 2027 annual print, whether a successor return framework replaces the expired buyback (a new frame, a dividend-policy formula, or cancellation of part of the roughly 11.0% treasury holding), and whether FY12/27 guidance turns the 2026 return step-up into stated policy under the capital-cost framework.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Decides whether returns are policy or a one-year episode; failure is a falsifier.
不确定性(原始记录):Future disclosure; no current public path.
F039|02|碳化硅是利润引擎,但一半经济利益在伙伴手里
研究范围:35项覆盖检查+开放研究
写入正文:02|碳化硅是利润引擎,但一半经济利益在伙伴手里13|碳化硅纤维能否扩产,谁出钱、怎么分?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接 / 支持;一手验证:07、09、11、33;外部现实校验:03、04、08、10
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:直接证据;一手验证:05;外部现实校验:02、09、11、12、14、15
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:直接 / 支持;一手验证:07;外部现实校验:06;专项深挖:07
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接证据;外部现实校验:17、18、19、20、21、25;反向验证:17
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:支持证据;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:支持证据;一手验证:15
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:支持证据;一手验证:19、21、29;反向验证:19、32
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:支持证据;外部现实校验:16、32
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:支持证据;外部现实校验:01、07、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries;直接证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;支持证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon
完整研究记录(核对用)
研究原文:Open: whether SiC fibre capacity, already at full production, can expand to meet LEAP-family CMC demand growth without another multi-year capex bulge, and how expansion inside NGS Advanced Fibers would be funded and shared among the 50/25/25 partners.
内部研究类型:ResearchDebt
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Growth in the best business is capacity-bound; funding and sharing terms decide how much accrues to parent holders and whether free-cash-flow inflection reverses.
不确定性(原始记录):No NGS expansion agreement or capacity figures public in materials read.
F040|13|权益法关联公司和股东优待制度,两个小项为什么还要查?
研究范围:开放研究+35项覆盖检查
写入正文:13|权益法关联公司和股东优待制度,两个小项为什么还要查?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed怎么使用:直接 / 支持
Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear怎么使用:直接 / 支持
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges怎么使用:直接证据;一手验证:16、28、32;专项深挖:16、32
查看完整证据标签(核对用)
直接证据 / 支持证据|Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed;直接证据 / 支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 一手证据(研究域16) / 一手证据(研究域28) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges
完整研究记录(核对用)
研究原文:Open: which equity-method affiliate swung from a JPY 100 million profit (FY12/25; JPY 166 million in FY12/24) to a JPY 44 million loss in Q1 FY12/26 (JPY 38 million cumulative at H1), and whether the drag is structural or temporary; the tanshin does not name the affiliate.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Small but it widened ordinary-profit decline versus operating profit in H1.
不确定性(原始记录):Resolvable only via securities-report notes.
F041|07|2026年的治理动作异常密集,纪律只有一年历史
研究范围:开放研究+35项覆盖检查
写入正文:07|2026年的治理动作异常密集,纪律只有一年历史13|权益法关联公司和股东优待制度,两个小项为什么还要查?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place怎么使用:直接 / 支持;一手验证:13、22、23;专项深挖:13、23
IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026怎么使用:直接 / 支持;一手验证:13、23、30
Ownership detail: trust banks, relationship holders and a 55.41% retail base across 16,137 shareholders怎么使用:直接证据;一手验证:24;专项深挖:24
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:直接证据
Shareholder register (EDINET database over securities-report filings): top holders and ownership mix怎么使用:支持证据;一手验证:24
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:支持证据;外部现实校验:01、07、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域30)|IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026;直接证据 / 一手证据(研究域24) / 定向深挖(研究域24)|Ownership detail: trust banks, relationship holders and a 55.41% retail base across 16,137 shareholders;直接证据|Limitations anchor: what this research did not read, stated once and carried through every domain;支持证据 / 一手证据(研究域24)|Shareholder register (EDINET database over securities-report filings): top holders and ownership mix;支持证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon
完整研究记录(核对用)
研究原文:Open: the terms of the shareholder benefit programme introduced 25 Aug 2026, and whether it — with the buyback and the renewed takeover-response policy of 10 Feb 2026 — marks a deliberate retail-register strategy for a company whose holders are 55.41% individuals. The notice was identified in the disclosure index but not read, so no benefit terms are asserted.
内部研究类型:ResearchDebt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Bears on how the discount closes for a retail-majority register.
不确定性(原始记录):Terms unread.
F042|13|还有哪些限制贯穿所有判断?
研究范围:35项覆盖检查+开放研究
写入正文:13|还有哪些限制贯穿所有判断?15|主要来源与日期15|证据边界:哪些没读到,不等于经营不好15|研究目的与风险提示
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:直接 / 支持
Falsification anchors: the dated prints against which this research can be proven wrong怎么使用:支持证据;一手验证:35;专项深挖:35
查看完整证据标签(核对用)
直接证据 / 支持证据|Limitations anchor: what this research did not read, stated once and carried through every domain;直接证据|Disclosure quality: timely difference notices and English summaries; the gaps are the unread capital-cost notice and the unexplained inventory rotation;支持证据 / 一手证据(研究域35) / 定向深挖(研究域35)|Falsification anchors: the dated prints against which this research can be proven wrong
完整研究记录(核对用)
研究原文:Stated limits of the evidence base carried through every judgement: the 25 March and 25 August 2026 notices were not read; the FY12/25 securities report was used via the tanshin and compiled statement data, so segment assets, related-party detail beyond the alliance and the fire final report's restoration specifics remain unread; the 25 March earnings-release correction is unclassified; no independent market-share, peer-multiple, electrode-price, consensus or inventory-bridge evidence was obtained; no numeric mid-term targets are disclosed; Q3 FY12/26 had not been published at the 9 Nov 2026 cutoff.
内部研究类型:EvidenceBoundary
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Conclusions are conditional on these gaps; absence of data is not evidence of poor operations.
不确定性(原始记录):Several gaps are retrievable public documents that may reduce uncertainty in a later Review.
F043|05|耐久性:哪些成立,哪些故意不下结论
研究范围:35项覆盖检查+开放研究
写入正文:05|耐久性:哪些成立,哪些故意不下结论
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(12项,重复标签已合并)
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接证据;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Downside structure: what protects the equity if both cycles turn down together怎么使用:直接证据;一手验证:29;专项深挖:29
Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012怎么使用:支持证据;一手验证:09、10;专项深挖:09
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:支持证据;一手验证:04、10;专项深挖:04、10
Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes怎么使用:支持证据;一手验证:08;专项深挖:08
Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million怎么使用:支持证据;一手验证:18;专项深挖:18
Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend怎么使用:支持证据;外部现实校验:28;同业比较:01、04、06、07、12、13、16、17、18、19、20、21、22、23、24、25、26、27、29、30、32、33;其他用途:历史
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:支持证据;外部现实校验:17、18、19、20、21、25;反向验证:17
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:支持证据;一手验证:27、31;外部现实校验:22;反向验证:27
查看完整证据标签(核对用)
直接证据|Durability composite: qualification lock-in in fibre, consumables in carbon, a balance sheet built to wait out cycles;直接证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 定向深挖(研究域09)|Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012;支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;支持证据 / 一手证据(研究域08) / 定向深挖(研究域08)|Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes;支持证据 / 一手证据(研究域18) / 定向深挖(研究域18)|Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million;支持证据 / 外部现实(研究域28) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域27) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域33)|Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend;支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91
完整研究记录(核对用)
研究原文:Durability renews structurally rather than contractually: carbon consumables re-bought each production campaign from a technology base accumulated since 1915; fibre locked into certified aircraft-engine parts on qualification cycles measured in years with customers' parents co-owning the venture (strongest commercial durability, purchased by sharing the economics); and a 63.5%-equity-ratio, net-cash, marked-securities balance sheet built to hold both through the electrode cycle's fourfold swings without forced selling, dilution or a dividend cut, as it did through FY12/20, the 2025 fire and a capex cycle. Not durable or not yet proven: electrode pricing set by a global commodity cycle, fine-carbon expansion economics awaiting absorption, and a one-programme-old capital-policy turn. High durability for the enterprise and holder income; deliberately unproven for the two growth claims — the shape of the market's discount.
内部研究类型:StructuralDurabilityUnderstanding
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Explains why the equity is underwritable on normalised earnings rather than on survival.
不确定性(原始记录):Durability of the fibre position would not be announced early if impaired.
F044|02|整体面貌:周期性底盘上的半个专营权,由净现金托底
研究范围:开放研究
写入正文:02|整体面貌:周期性底盘上的半个专营权,由净现金托底05|耐久性:哪些成立,哪些故意不下结论
归并到:F076
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:直接 / 支持;一手验证:15
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:支持证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:支持证据;一手验证:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;直接证据 / 支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year
完整研究记录(核对用)
研究原文:Carbon products are the group's core segment (about 86% of FY12/25 sales; segment profit JPY 2,990 million, -42.5%), split into fine carbon and electrodes. Thesis impact: carries the sales base and most cyclicality; its margin path after the completed expansion is the largest swing in group operating profit.
内部研究类型:CORE_SEGMENT_OF
内部来源标记:OPEN_DISCOVERY
F045|02|碳化硅是利润引擎,但一半经济利益在伙伴手里
研究范围:开放研究+35项覆盖检查
写入正文:02|碳化硅是利润引擎,但一半经济利益在伙伴手里09|按母公司每股价值估值,增长要打折12|净利润上升,其实是证券收益盖住了经营下滑
归并到:F079
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:支持证据;一手验证:15
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:支持证据;一手验证:07;外部现实校验:06;专项深挖:07
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:支持证据;外部现实校验:01、07、24
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:支持证据;一手验证:19、21、29;反向验证:19、32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;支持证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries;支持证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon;支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror
完整研究记录(核对用)
研究原文:NGS Advanced Fibers (50/25/25) is the consolidated venture on which the SiC segment is built (FY12/25 sales JPY 4,128 million, profit JPY 1,479 million at full capacity). Thesis impact: the best business is half-owned by its customers' parents — scarce growth, but about half the economics accrue to partners.
内部研究类型:UNDERLIES_SEGMENT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F046|02|整体面貌:周期性底盘上的半个专营权,由净现金托底
研究范围:开放研究+35项覆盖检查
写入正文:02|整体面貌:周期性底盘上的半个专营权,由净现金托底05|耐久性:哪些成立,哪些故意不下结论
归并到:F076
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012怎么使用:支持证据;一手验证:09、10;专项深挖:09
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:支持证据;一手验证:04、10;专项深挖:04、10
Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes怎么使用:支持证据;一手验证:08;专项深挖:08
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 定向深挖(研究域09)|Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012;支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;支持证据 / 一手证据(研究域08) / 定向深挖(研究域08)|Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes
完整研究记录(核对用)
研究原文:CFM LEAP CMC hot-section demand is the end market for NICALON; above-plan aircraft-engine fibre volumes drove part of the H1 FY12/26 beat. Thesis impact: long qualification cycles and slow switching make it the most durable demand, tying the highest margin to one engine family's ramp.
内部研究类型:DEMAND_POOL_FOR
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F047|02|整体面貌:周期性底盘上的半个专营权,由净现金托底
研究范围:开放研究+35项覆盖检查
写入正文:02|整体面貌:周期性底盘上的半个专营权,由净现金托底05|耐久性:哪些成立,哪些故意不下结论
归并到:F076
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:直接 / 支持;一手验证:05;外部现实校验:02、09、11、12、14、15
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:支持证据;一手验证:12;专项深挖:12
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;支持证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)
完整研究记录(核对用)
研究原文:The electrode price cycle (FY12/18 ordinary profit JPY 16,508 million → FY12/20 JPY 3,587 million; FY12/25 electrode revenue up on North American exports inside a segment whose profit fell 42.5%) governs the carbon segment's profit range. Thesis impact: can multiply or divide group profit by four within three years and sets the range for underwriting.
内部研究类型:PRICE_CYCLE_DRIVES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F048|06|火灾、库存换位和成本抬升,出在同一个生产系统里
研究范围:开放研究
写入正文:06|火灾、库存换位和成本抬升,出在同一个生产系统里13|库存78亿日元的换位和火灾尾部,什么时候说清?
归并到:F080
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Toyama plant fire (29 August 2025): the accounting footprint across FY12/25 and H1 FY12/26怎么使用:直接 / 支持;一手验证:06;反向验证:06、16
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:支持证据;外部现实校验:17、18、19、20、21、25;反向验证:17
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域06) / 反证(研究域16)|Toyama plant fire (29 August 2025): the accounting footprint across FY12/25 and H1 FY12/26;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear;支持证据|Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed
完整研究记录(核对用)
研究原文:The Toyama fire's accounting footprint (idle-equipment costs, provision, insurance receipt) depresses FY12/26 ordinary profit and clouds the segment-margin read until the provision is exhausted and the charges stop.
内部研究类型:DISTORTS
内部来源标记:OPEN_DISCOVERY
F049|08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头
研究范围:开放研究
写入正文:08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头12|卖证券的钱,实质上变成了2026年的每股价值
归并到:F077
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接 / 支持;外部现实校验:26
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:直接 / 支持;一手验证:26
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:直接证据;一手验证:17、25;反向验证:26
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:支持证据;反向验证:28
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:支持证据;一手验证:19、21、29;反向验证:19、32
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:支持证据;外部现实校验:17、18、19、20、21、25;反向验证:17
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:支持证据;一手验证:27、31;外部现实校验:22;反向验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%;直接证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds;支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91
完整研究记录(核对用)
研究原文:The dividend plus the 2026 buyback (about JPY 4.7 billion in FY12/26, roughly 1.7 times forecast net income) are funded from the balance sheet rather than the year's free cash flow of about JPY 0.8 billion. Thesis impact: returns are the clearest management signal and their continuation after the buyback's expiry is a dated test of 'GO BEYOND 2030'.
内部研究类型:FUNDED_FROM
内部来源标记:OPEN_DISCOVERY
F050|07|没有控股股东,个人股东占55.41%
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Shareholder register (EDINET database over securities-report filings): top holders and ownership mix怎么使用:直接 / 支持;一手验证:24
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:直接 / 支持;外部现实校验:01、07、24
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:支持证据;一手验证:07;外部现实校验:06;专项深挖:07
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:支持证据;一手验证:19、21、29;反向验证:19、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24)|Shareholder register (EDINET database over securities-report filings): top holders and ownership mix;直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon;支持证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries;支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror
完整研究记录(核对用)
研究原文:The reciprocal holdings (SEC Carbon 4.08% of Nippon Carbon; Nippon Carbon 4.06% of SEC Carbon) under the October 2022 alliance stabilise the register and signal cooperation between the two domestic carbon makers, while making part of each register a non-arbitrage strategic holding.
内部研究类型:STABILISES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F051|06|火灾、库存换位和成本抬升,出在同一个生产系统里
研究范围:开放研究+35项覆盖检查
写入正文:06|火灾、库存换位和成本抬升,出在同一个生产系统里13|库存78亿日元的换位和火灾尾部,什么时候说清?
归并到:F080
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million怎么使用:直接 / 支持;一手验证:20;专项深挖:20
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:支持证据;一手验证:19、21、29;反向验证:19、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;支持证据|Interim trajectory: Q1 shock, Q2 repair - the half-year path inside FY12/26;支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear
完整研究记录(核对用)
研究原文:The completed fine-carbon expansion (construction in progress JPY 2,183 → 432 million; machinery net JPY 10,815 million) turns a demand problem into an absorption problem: segment margin repairs with volume, not further spending. Thesis impact: Q3 and Q4 volume prints directly test the investment's logic.
内部研究类型:ABSORPTION_CONDITION_FOR
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F052|02|碳化硅是利润引擎,但一半经济利益在伙伴手里
研究范围:开放研究+35项覆盖检查
写入正文:02|碳化硅是利润引擎,但一半经济利益在伙伴手里09|按母公司每股价值估值,增长要打折12|净利润上升,其实是证券收益盖住了经营下滑
归并到:F079
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:直接证据;一手验证:07;外部现实校验:06;专项深挖:07
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:支持证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries;支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%
完整研究记录(核对用)
研究原文:Non-controlling interests of JPY 9,213 million (14.5% of net assets), absorbing JPY 557 million of FY12/25 net income and receiving JPY 178 million of dividends, share each yen of SiC growth with GE and Safran. Thesis impact: consolidated growth overstates the parent's claim; value on parent EPS.
内部研究类型:LEAKS_VALUE_FROM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F053|08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头
研究范围:开放研究+35项覆盖检查
写入正文:08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头12|卖证券的钱,实质上变成了2026年的每股价值
归并到:F077
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接 / 支持;外部现实校验:26
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend怎么使用:直接 / 支持;外部现实校验:28;同业比较:01、04、06、07、12、13、16、17、18、19、20、21、22、23、24、25、26、27、29、30、32、33;其他用途:历史
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:支持证据;一手验证:26
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:支持证据;反向验证:28
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:支持证据;一手验证:19、21、29;反向验证:19、32
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:支持证据;一手验证:27、31;外部现实校验:22;反向验证:27
Financial history FY12/21-FY12/25: a sales plateau at JPY 37-38 billion and an operating-margin round-trip怎么使用:支持证据;一手验证:33;专项深挖:33;同业比较:02、03、09、15、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 支持证据 / 外部现实(研究域28) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域27) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域33)|Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend;支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%;支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域33)|Financial history FY12/21-FY12/25: a sales plateau at JPY 37-38 billion and an operating-margin round-trip
完整研究记录(核对用)
研究原文:The completed buyback (treasury to about 11.0%) plus retained earnings lifted BPS from JPY 4,919.46 to JPY 5,041.20 even in a half with net income -40.5%; BPS has compounded from JPY 4,073.6 over five years. Thesis impact: the per-share floor rises about 2-3% a year on current behaviour.
内部研究类型:COMPOUNDS_PER_SHARE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F054|09|资产说便宜,干净盈利说不便宜,收益说有支撑
研究范围:开放研究+35项覆盖检查
归并到:F078
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield怎么使用:直接 / 支持;一手验证:27;外部现实校验:31、35;专项深挖:27
Profitability quality: ROE 9.1% in FY12/25 is flattered by the securities gain; the operating return on assets is mid-single-digit怎么使用:直接证据;一手验证:22;专项深挖:22
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:支持证据;一手验证:05;外部现实校验:02、09、11、12、14、15
Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement怎么使用:支持证据;一手验证:28;外部现实校验:27;专项深挖:28
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:支持证据;一手验证:27、31;外部现实校验:22;反向验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域31) / 外部现实(研究域35) / 定向深挖(研究域27)|Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Profitability quality: ROE 9.1% in FY12/25 is flattered by the securities gain; the operating return on assets is mid-single-digit;支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;支持证据 / 一手证据(研究域28) / 外部现实(研究域27) / 定向深挖(研究域28)|Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91
完整研究记录(核对用)
研究原文:Demonstrated ordinary-profit amplitude is why a net-cash, asset-rich company trades near or below book at a 4.95% forecast ROE: the market capitalises the variance of earnings, not doubts about marked assets. Thesis impact: re-rating runs through variance reduction (a larger SiC and fine-carbon share of profit), not asset discovery.
内部研究类型:CAPS_VALUATION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F055|08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头
研究范围:35项覆盖检查+开放研究
写入正文:08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头12|卖证券的钱,实质上变成了2026年的每股价值
归并到:F077
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges怎么使用:直接 / 支持;一手验证:16、28、32;专项深挖:16、32
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域28) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings
完整研究记录(核对用)
研究原文:The gain-inflated FY12/25 net line forces valuation onto ordinary profit and the clean FY12/26 forecast; the normalised band is derived by separating the securities gain, fire loss and idle-equipment charge at their own lines.
内部研究类型:REQUIRES_NORMALISATION
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F056|08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头
研究范围:35项覆盖检查+开放研究
写入正文:08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头12|卖证券的钱,实质上变成了2026年的每股价值
归并到:F077
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:直接证据;一手验证:17、25;反向验证:26
Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book怎么使用:直接证据;一手验证:21;外部现实校验:29;专项深挖:21
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接 / 支持;外部现实校验:26
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:支持证据;反向验证:28
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:支持证据;外部现实校验:16、32
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:支持证据;一手验证:26
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds;直接证据 / 一手证据(研究域21) / 外部现实(研究域29) / 定向深挖(研究域21)|Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book;直接证据 / 支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%
完整研究记录(核对用)
研究原文:The JPY 3,716 million of securities-sale proceeds that produced the FY12/25 gain are, in substance, part of what funded the FY12/26 buyback: financial assets are converted into per-share value at a discount-to-book price.
内部研究类型:FINANCIAL_ASSET_CONVERSION
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F057|05|护城河真实但很窄,只落在碳化硅纤维一处
研究范围:35项覆盖检查+开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接证据;一手验证:20
Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012怎么使用:直接 / 支持;一手验证:09、10;专项深挖:09
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:支持证据;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:支持证据;一手验证:15
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:支持证据;一手验证:04、10;专项深挖:04、10
Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes怎么使用:支持证据;一手验证:08;专项深挖:08
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;直接证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 定向深挖(研究域09)|Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;支持证据 / 一手证据(研究域08) / 定向深挖(研究域08)|Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes;支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half
完整研究记录(核对用)
研究原文:Schedule-driven SiC volumes beating plan in a half when electrode and fine-carbon volumes missed, at a widening margin, are the observable signature of qualification switching costs.
内部研究类型:EVIDENCES
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F058|09|资产说便宜,干净盈利说不便宜,收益说有支撑
研究范围:35项覆盖检查+开放研究
归并到:F078
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:22;反向验证:27
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接证据;一手验证:19、21、29;反向验证:19、32
Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield怎么使用:支持证据;一手验证:27;外部现实校验:31、35;专项深挖:27
Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement怎么使用:支持证据;一手验证:28;外部现实校验:27;专项深挖:28
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:支持证据;反向验证:28
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:支持证据;一手验证:17、25;反向验证:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;支持证据 / 一手证据(研究域27) / 外部现实(研究域31) / 外部现实(研究域35) / 定向深挖(研究域27)|Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield;支持证据 / 一手证据(研究域28) / 外部现实(研究域27) / 定向深挖(研究域28)|Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement;支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds
完整研究记录(核对用)
研究原文:The denominator and as-of differences recorded in the basis note qualify every multiple in the valuation snapshot.
内部研究类型:QUALIFIES
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F059|09|资产说便宜,干净盈利说不便宜,收益说有支撑
研究范围:35项覆盖检查
归并到:F078
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Market expectations as priced on 6-9 November 2026: scepticism at the top of the year's range, calm at the print's approach怎么使用:直接证据;一手验证:31;专项深挖:31
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:22;反向验证:27
Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield怎么使用:支持证据;一手验证:27;外部现实校验:31、35;专项深挖:27
Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement怎么使用:支持证据;一手验证:28;外部现实校验:27;专项深挖:28
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|Market expectations as priced on 6-9 November 2026: scepticism at the top of the year's range, calm at the print's approach;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;支持证据 / 一手证据(研究域27) / 外部现实(研究域31) / 外部现实(研究域35) / 定向深挖(研究域27)|Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield;支持证据 / 一手证据(研究域28) / 外部现实(研究域27) / 定向深挖(研究域28)|Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement
完整研究记录(核对用)
研究原文:The discount to book on unrevised guidance is read as scepticism about the earnings stream, giving an asymmetric reaction function around the Q3 print.
内部研究类型:INTERPRETS
内部来源标记:COVERAGE35
F060|11|指引是保守还是有预见,下半年才知道
研究范围:开放研究+35项覆盖检查
写入正文:11|指引是保守还是有预见,下半年才知道13|下半年隐含的降幅到底来自什么?
归并到:F081
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:直接 / 支持;反向验证:31、35
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:支持证据;一手验证:14;外部现实校验:05、30;反向验证:14
查看完整证据标签(核对用)
直接证据 / 支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised
完整研究记录(核对用)
研究原文:Undisclosed attribution of the 26% second-half step-down means the floor reading of guidance is a judgement, not a disclosed fact.
内部研究类型:QUALIFIES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F061|11|指引是保守还是有预见,下半年才知道
研究范围:35项覆盖检查+开放研究
写入正文:11|指引是保守还是有预见,下半年才知道13|下半年隐含的降幅到底来自什么?
归并到:F081
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure怎么使用:直接证据;一手验证:06、14;专项深挖:06、14
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:支持证据;反向验证:31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;直接证据 / 一手证据(研究域06) / 一手证据(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure;支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;支持证据 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank
完整研究记录(核对用)
研究原文:Yen weakness versus the JPY 145 plan rate flattered the H1 beat; management's refusal to raise guidance treats it as transitory, tying forecast credibility to FX.
内部研究类型:DRIVES_ASSUMPTION
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F062|06|火灾、库存换位和成本抬升,出在同一个生产系统里
研究范围:35项覆盖检查+开放研究
写入正文:06|火灾、库存换位和成本抬升,出在同一个生产系统里13|库存78亿日元的换位和火灾尾部,什么时候说清?
归并到:F080
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Toyama plant fire (29 August 2025): the accounting footprint across FY12/25 and H1 FY12/26怎么使用:直接 / 支持;一手验证:06;反向验证:06、16
Working capital: the FY12/25 inventory mirror and a receivables position that recovered in H1 FY12/26怎么使用:直接 / 支持;一手验证:19、32;专项深挖:19
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:支持证据;一手验证:20
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:支持证据;外部现实校验:17、18、19、20、21、25;反向验证:17
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:支持证据;一手验证:19、21、29;反向验证:19、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域06) / 反证(研究域16)|Toyama plant fire (29 August 2025): the accounting footprint across FY12/25 and H1 FY12/26;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域32) / 定向深挖(研究域19)|Working capital: the FY12/25 inventory mirror and a receivables position that recovered in H1 FY12/26;支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror
完整研究记录(核对用)
研究原文:The fire is one of three candidate explanations for the inventory rotation, alongside expansion staging and reclassification; no evidence distinguishes them.
内部研究类型:POSSIBLE_CAUSE_UNRESOLVED
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F063|06|火灾、库存换位和成本抬升,出在同一个生产系统里
研究范围:35项覆盖检查
写入正文:06|火灾、库存换位和成本抬升,出在同一个生产系统里
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
Working capital: the FY12/25 inventory mirror and a receivables position that recovered in H1 FY12/26怎么使用:直接 / 支持;一手验证:19、32;专项深挖:19
Downside structure: what protects the equity if both cycles turn down together怎么使用:直接证据;一手验证:29;专项深挖:29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域32) / 定向深挖(研究域19)|Working capital: the FY12/25 inventory mirror and a receivables position that recovered in H1 FY12/26;直接证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together
完整研究记录(核对用)
研究原文:About JPY 19.6 billion of inventories of undetermined composition prevents counting inventory book value as liquid downside protection.
内部研究类型:QUALIFIES_DOWNSIDE_VALUE
内部来源标记:COVERAGE35
F064|13|还有哪些限制贯穿所有判断?
研究范围:35项覆盖检查+开放研究
写入正文:13|还有哪些限制贯穿所有判断?
归并到:F083
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place怎么使用:直接证据;一手验证:13、22、23;专项深挖:13、23
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:直接证据
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:支持证据;外部现实校验:26
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:支持证据;一手验证:26
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:支持证据;反向验证:28
Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing怎么使用:支持证据;外部现实校验:13、23
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:支持证据;一手验证:20
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place;直接证据|Limitations anchor: what this research did not read, stated once and carried through every domain;支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%;支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 外部现实(研究域13) / 外部现实(研究域23)|Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing;支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year
完整研究记录(核对用)
研究原文:Whether the return step-up is standing policy or a one-year episode depends on the unread notice and the February 2027 successor framework.
内部研究类型:QUALIFIES_DURABILITY
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F065|01|净现金加低于账面的价格,买的是等待转换
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|净现金加低于账面的价格,买的是等待转换14|Kabugami 评分 V3.2:60.92/100分,评级 B
归并到:F082
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:直接 / 支持;一手验证:12;专项深挖:12
Downside structure: what protects the equity if both cycles turn down together怎么使用:直接证据;一手验证:29;专项深挖:29
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:支持证据;一手验证:05;外部现实校验:02、09、11、12、14、15
Falsification anchors: the dated prints against which this research can be proven wrong怎么使用:支持证据;一手验证:35;专项深挖:35
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:支持证据
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 支持证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors);直接证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;支持证据 / 一手证据(研究域35) / 定向深挖(研究域35)|Falsification anchors: the dated prints against which this research can be proven wrong;支持证据|Limitations anchor: what this research did not read, stated once and carried through every domain
完整研究记录(核对用)
研究原文:A renewed electrode downcycle is the realistic trigger of the long-trough scenario (operating profit toward JPY 3 billion).
内部研究类型:TRIGGERS
内部来源标记:COVERAGE35
F066|09|下行保护是结构性的,真实损失是漫长的谷底
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
Downside structure: what protects the equity if both cycles turn down together怎么使用:直接证据;一手验证:29;专项深挖:29
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:支持证据;一手验证:27、31;外部现实校验:22;反向验证:27
Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million怎么使用:支持证据;一手验证:18;专项深挖:18
Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend怎么使用:支持证据;外部现实校验:28;同业比较:01、04、06、07、12、13、16、17、18、19、20、21、22、23、24、25、26、27、29、30、32、33;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;支持证据 / 一手证据(研究域18) / 定向深挖(研究域18)|Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million;支持证据 / 外部现实(研究域28) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域27) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域33)|Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend
完整研究记录(核对用)
研究原文:Net cash, equity ratio and marked securities turn a trough into a waiting problem rather than a claim impairment.
内部研究类型:MITIGATES
内部来源标记:COVERAGE35
F067|01|净现金加低于账面的价格,买的是等待转换
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论01|净现金加低于账面的价格,买的是等待转换14|Kabugami 评分 V3.2:60.92/100分,评级 B
归并到:F082
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
Downside structure: what protects the equity if both cycles turn down together怎么使用:直接 / 支持;一手验证:29;专项深挖:29
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:支持证据;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:支持证据;外部现实校验:17、18、19、20、21、25;反向验证:17
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:支持证据;一手验证:27、31;外部现实校验:22;反向验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91
完整研究记录(核对用)
研究原文:The balance-sheet leg is the thesis's best-evidenced and most durable support.
内部研究类型:SUPPORTS
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F068|01|净现金加低于账面的价格,买的是等待转换
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论01|净现金加低于账面的价格,买的是等待转换14|Kabugami 评分 V3.2:60.92/100分,评级 B
归并到:F082
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:直接 / 支持;一手验证:35
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接 / 支持;外部现实校验:26
Downside structure: what protects the equity if both cycles turn down together怎么使用:支持证据;一手验证:29;专项深挖:29
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:支持证据;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:支持证据;一手验证:26
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:支持证据;反向验证:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;直接证据 / 支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%;支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed
完整研究记录(核对用)
研究原文:Revealed preference for returns and valuation repair over further capacity supports the conversion mechanism of the thesis.
内部研究类型:SUPPORTS
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F069|01|净现金加低于账面的价格,买的是等待转换
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论01|净现金加低于账面的价格,买的是等待转换14|Kabugami 评分 V3.2:60.92/100分,评级 B
归并到:F082
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Downside structure: what protects the equity if both cycles turn down together怎么使用:支持证据;一手验证:29;专项深挖:29
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:支持证据;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:支持证据;一手验证:15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;直接证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million
完整研究记录(核对用)
研究原文:The scarce, capacity-bound fibre franchise is the thesis's franchise leg.
内部研究类型:SUPPORTS
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F070|01|三项反证决定仓位大小
研究范围:35项覆盖检查+开放研究
写入正文:01|三项反证决定仓位大小
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:直接证据;一手验证:12;专项深挖:12
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Downside structure: what protects the equity if both cycles turn down together怎么使用:支持证据;一手验证:29;专项深挖:29
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:支持证据;一手验证:05;外部现实校验:02、09、11、12、14、15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors);支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity
完整研究记录(核对用)
研究原文:Electrode amplitude that halved group profit in two years before is the strongest counter-evidence to a mix-improvement thesis and must condition sizing and confidence.
内部研究类型:COUNTER_EVIDENCE
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F071|01|三项反证决定仓位大小
研究范围:35项覆盖检查
写入正文:01|三项反证决定仓位大小
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接 / 支持;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Downside structure: what protects the equity if both cycles turn down together怎么使用:支持证据;一手验证:29;专项深挖:29
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:支持证据;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank
完整研究记录(核对用)
研究原文:Minority leakage caps how much of the franchise's growth reaches ordinary shareholders.
内部研究类型:COUNTER_EVIDENCE
内部来源标记:COVERAGE35
F072|01|三项反证决定仓位大小
研究范围:35项覆盖检查+开放研究
写入正文:01|三项反证决定仓位大小
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:直接 / 支持;反向验证:31、35;其他用途:反证
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Downside structure: what protects the equity if both cycles turn down together怎么使用:支持证据;一手验证:29;专项深挖:29
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:支持证据;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:支持证据;一手验证:14;外部现实校验:05、30;反向验证:14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;直接证据 / 支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised
完整研究记录(核对用)
研究原文:Guidance that refuses to extrapolate a 54.7% interim beat tempers the earnings-momentum reading and is retained as counter-evidence, not as Principal Risk alone.
内部研究类型:COUNTER_EVIDENCE
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F073|01|净现金加低于账面的价格,买的是等待转换
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论01|净现金加低于账面的价格,买的是等待转换14|Kabugami 评分 V3.2:60.92/100分,评级 B
归并到:F082
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Falsification anchors: the dated prints against which this research can be proven wrong怎么使用:直接 / 支持;一手验证:35;专项深挖:35
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:支持证据
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Downside structure: what protects the equity if both cycles turn down together怎么使用:支持证据;一手验证:29;专项深挖:29
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:支持证据;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域35)|Falsification anchors: the dated prints against which this research can be proven wrong;支持证据|Limitations anchor: what this research did not read, stated once and carried through every domain;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank
完整研究记录(核对用)
研究原文:Four dated, observable falsifiers test the thesis legs one by one.
内部研究类型:TESTS
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F074|10|公开事件之后,好消息被相信,但没有被外推
研究范围:35项覆盖检查
写入正文:10|公开事件之后,好消息被相信,但没有被外推13|三季度财报会不会延续二季度的修复?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print怎么使用:直接证据;一手验证:30;专项深挖:30、34
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接证据;一手验证:27、31;外部现实校验:22;反向验证:27
Falsification anchors: the dated prints against which this research can be proven wrong怎么使用:支持证据;一手验证:35;专项深挖:35
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:支持证据
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:支持证据;一手验证:20
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域30) / 定向深挖(研究域30) / 定向深挖(研究域34)|Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print;直接证据 / 支持证据|Interim trajectory: Q1 shock, Q2 repair - the half-year path inside FY12/26;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;支持证据 / 一手证据(研究域35) / 定向深挖(研究域35)|Falsification anchors: the dated prints against which this research can be proven wrong;支持证据|Limitations anchor: what this research did not read, stated once and carried through every domain;支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear;支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year
完整研究记录(核对用)
研究原文:Cross-lane timing note, outside the protected Technical source: the independently formed Technical State and the fundamental thesis wait on the same dated evidence — quarterly segment profit, above all fine-carbon absorption — so the two readings are one execution bet expressed twice rather than diversified views. Fundamental information does not alter the protected Technical State, which remains as dereferenced from its source, and Fundamental positivity is not used to confirm it.
内部研究类型:SHARED_DEPENDENCY_CROSS_LANE
内部来源标记:COVERAGE35 / TECHNICAL
F075|10|长期下跌已经走完,上行是否启动还没有答案
写入正文:10|长期下跌已经走完,上行是否启动还没有答案10|价格生命史:两次冲高都回落过半,随后是六年箱体10|回落一轮比一轮浅,修复一轮比一轮快,收敛已到三重10|三条长期均线聚成一团,上方有两段历史压力10|公开事件之后,好消息被相信,但没有被外推10|两种冲高失败不是一回事,价格已在高位区待了九个月10|当前状态、内部矛盾,以及确认与失效条件14|八项得分:资产负债表最高,治理最低
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (dereference-only)
内部研究类型:ProtectedTechnicalSynthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
F076|02|整体面貌:周期性底盘上的半个专营权,由净现金托底
研究范围:开放研究+35项覆盖检查
写入正文:02|整体面貌:周期性底盘上的半个专营权,由净现金托底05|耐久性:哪些成立,哪些故意不下结论
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(46项,重复标签已合并)
FY12/2025 consolidated results (tanshin): issuer identity and headline earnings怎么使用:直接 / 支持;一手验证:01
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接 / 支持;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Filing frame: EDINET code E01140, securities report 25 March 2026, AGM 27 March 2026, governance report 30 March 2026怎么使用:直接 / 支持;一手验证:01;专项深挖:01
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:直接 / 支持;外部现实校验:01、07、24
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
Product map from the 2012 joint-venture release and the filings: electrodes, special carbon, NICALON fibre, anode materials怎么使用:直接 / 支持;一手验证:03、04、08;专项深挖:03
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:直接 / 支持;一手验证:04、10;专项深挖:04、10
Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing怎么使用:直接 / 支持;外部现实校验:13、23
Business model constitution: three segments, one consumables-and-materials model怎么使用:直接证据;一手验证:02、15;专项深挖:02、15
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:直接 / 支持;一手验证:15
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million怎么使用:直接 / 支持;一手验证:20;专项深挖:20
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:直接 / 支持;一手验证:07;外部现实校验:06;专项深挖:07
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012怎么使用:直接 / 支持;一手验证:09、10;专项深挖:09
Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes怎么使用:直接 / 支持;一手验证:08;专项深挖:08
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
Demand engines as disclosed: steel (electrodes), semiconductors (fine carbon), aerospace (SiC fibre), machinery怎么使用:直接证据;一手验证:05、11;专项深挖:05、11
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:直接 / 支持;一手验证:05;外部现实校验:02、09、11、12、14、15
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:直接 / 支持;一手验证:12;专项深挖:12
Financial history FY12/21-FY12/25: a sales plateau at JPY 37-38 billion and an operating-margin round-trip怎么使用:直接 / 支持;一手验证:33;专项深挖:33;同业比较:02、03、09、15、35;其他用途:历史
Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend怎么使用:直接 / 支持;外部现实校验:28;同业比较:01、04、06、07、12、13、16、17、18、19、20、21、22、23、24、25、26、27、29、30、32、33;其他用途:历史
Profitability quality: ROE 9.1% in FY12/25 is flattered by the securities gain; the operating return on assets is mid-single-digit怎么使用:直接证据;一手验证:22;专项深挖:22
Cash-flow quality: operating cash flow exceeded net income in FY12/25 and across the five-year window怎么使用:直接 / 支持;一手验证:17;专项深挖:17
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:直接 / 支持;一手验证:17、25;反向验证:26
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million怎么使用:直接 / 支持;一手验证:18;专项深挖:18
Debt profile: borrowings are almost entirely short-term - and covered 1.5 times by cash怎么使用:直接 / 支持;一手验证:18、25;专项深挖:25
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:22;反向验证:27
Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book怎么使用:直接证据;一手验证:21;外部现实校验:29;专项深挖:21
Shareholder register (EDINET database over securities-report filings): top holders and ownership mix怎么使用:直接 / 支持;一手验证:24
Ownership detail: trust banks, relationship holders and a 55.41% retail base across 16,137 shareholders怎么使用:直接 / 支持;一手验证:24;专项深挖:24
Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place怎么使用:直接证据;一手验证:13、22、23;专项深挖:13、23
Downside structure: what protects the equity if both cycles turn down together怎么使用:直接 / 支持;一手验证:29;专项深挖:29
Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges怎么使用:直接 / 支持;一手验证:16、28、32;专项深挖:16、32
Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement怎么使用:直接证据;一手验证:28;外部现实校验:27;专项深挖:28
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 支持证据 / 一手证据(研究域01) / 定向深挖(研究域01)|Filing frame: EDINET code E01140, securities report 25 March 2026, AGM 27 March 2026, governance report 30 March 2026;直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 定向深挖(研究域03)|Product map from the 2012 joint-venture release and the filings: electrodes, special carbon, NICALON fibre, anode materials;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域23)|Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing;直接证据|Sustainability and new-business directions named in the plan: power-semiconductor products and carbon-neutrality businesses;直接证据 / 一手证据(研究域02) / 一手证据(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域15)|Business model constitution: three segments, one consumables-and-materials model;直接证据 / 支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million;直接证据 / 支持证据|Interim trajectory: Q1 shock, Q2 repair - the half-year path inside FY12/26;支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 定向深挖(研究域09)|Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012;直接证据 / 支持证据 / 一手证据(研究域08) / 定向深挖(研究域08)|Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes;直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Demand engines as disclosed: steel (electrodes), semiconductors (fine carbon), aerospace (SiC fibre), machinery;支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;直接证据 / 支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 支持证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors);直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域33)|Financial history FY12/21-FY12/25: a sales plateau at JPY 37-38 billion and an operating-margin round-trip;直接证据 / 支持证据 / 外部现实(研究域28) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域27) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域33)|Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Profitability quality: ROE 9.1% in FY12/25 is flattered by the securities gain; the operating return on assets is mid-single-digit;直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|Cash-flow quality: operating cash flow exceeded net income in FY12/25 and across the five-year window;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 支持证据 / 一手证据(研究域18) / 定向深挖(研究域18)|Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 定向深挖(研究域25)|Debt profile: borrowings are almost entirely short-term - and covered 1.5 times by cash;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;直接证据 / 一手证据(研究域21) / 外部现实(研究域29) / 定向深挖(研究域21)|Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book;直接证据 / 支持证据 / 一手证据(研究域24)|Shareholder register (EDINET database over securities-report filings): top holders and ownership mix;直接证据 / 支持证据 / 一手证据(研究域24) / 定向深挖(研究域24)|Ownership detail: trust banks, relationship holders and a 55.41% retail base across 16,137 shareholders;直接证据 / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place;直接证据|Durability composite: qualification lock-in in fibre, consumables in carbon, a balance sheet built to wait out cycles;直接证据 / 支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域28) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges;直接证据 / 一手证据(研究域28) / 外部现实(研究域27) / 定向深挖(研究域28)|Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank
完整研究记录(核对用)
研究原文:Durable Business Portrait: a half-shared scarce franchise on a cyclical base, held by a net-cash balance sheet|The enterprise earns through consumables sold into three production cycles, with the only deeply locked-in position (qualified fibre) held 50/50 with customers' parents. Profit centre of gravity has moved to the smallest segment while sales centre of gravity has not. A large unlevered balance sheet lets the enterprise absorb cycles; capital efficiency, not solvency, is the weak point. Foundation formed before overlaying the 2025-26 changes (fire, expansion completion, return step-up).
内部研究类型:DurableBusinessPortrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Underwrite on normalised ordinary profit (JPY 4.6-7.1 billion) and parent EPS; improvement comes mechanically through mix, slowly.
不确定性(原始记录):Fine-carbon absorption, electrode cycle direction and fibre capacity path are unresolved; no external share data.
F077|08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头
研究范围:35项覆盖检查+开放研究
写入正文:08|回报资金来自卖证券:每股价值在增长,但这条回路有尽头12|卖证券的钱,实质上变成了2026年的每股价值
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(20项,重复标签已合并)
FY12/2025 consolidated results (tanshin): issuer identity and headline earnings怎么使用:直接 / 支持;一手验证:01
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges怎么使用:直接 / 支持;一手验证:16、28、32;专项深挖:16、32
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接 / 支持;外部现实校验:26
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:直接 / 支持;一手验证:26
Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
Dividend framework as practised: a fixed JPY 200 through a full earnings cycle, payout ratio as the residual怎么使用:直接 / 支持
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million怎么使用:支持证据;一手验证:20;专项深挖:20
Cash-flow quality: operating cash flow exceeded net income in FY12/25 and across the five-year window怎么使用:直接 / 支持;一手验证:17;专项深挖:17
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:直接 / 支持;一手验证:17、25;反向验证:26
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million怎么使用:直接 / 支持;一手验证:18;专项深挖:18
Debt profile: borrowings are almost entirely short-term - and covered 1.5 times by cash怎么使用:直接 / 支持;一手验证:18、25;专项深挖:25
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:22;反向验证:27
Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book怎么使用:直接证据;一手验证:21;外部现实校验:29;专项深挖:21
Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend怎么使用:直接 / 支持;外部现实校验:28;同业比较:01、04、06、07、12、13、16、17、18、19、20、21、22、23、24、25、26、27、29、30、32、33;其他用途:历史
Financial history FY12/21-FY12/25: a sales plateau at JPY 37-38 billion and an operating-margin round-trip怎么使用:支持证据;一手验证:33;专项深挖:33;同业比较:02、03、09、15、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域28) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges;直接证据 / 支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return;直接证据 / 支持证据|Dividend framework as practised: a fixed JPY 200 through a full earnings cycle, payout ratio as the residual;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million;直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|Cash-flow quality: operating cash flow exceeded net income in FY12/25 and across the five-year window;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 一手证据(研究域18) / 定向深挖(研究域18)|Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 定向深挖(研究域25)|Debt profile: borrowings are almost entirely short-term - and covered 1.5 times by cash;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;直接证据 / 一手证据(研究域21) / 外部现实(研究域29) / 定向深挖(研究域21)|Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book;直接证据 / 支持证据 / 外部现实(研究域28) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域27) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域33)|Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend;支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域33)|Financial history FY12/21-FY12/25: a sales plateau at JPY 37-38 billion and an operating-margin round-trip
完整研究记录(核对用)
研究原文:Earnings quality and capital returns as one circuit|The securities portfolio whose sale flattered FY12/25 net income (JPY 3,716 million of proceeds) is in substance part of what funded the FY12/26 return step-up (JPY 2.5 billion buyback completed). FY12/26 returns of about JPY 4.7 billion exceed FY12/25 free cash flow of about JPY 0.8 billion, so the circuit runs through the balance sheet, with a visible runway (about JPY 10-12 billion of marked securities remain) rather than an indefinite one.
内部研究类型:CrossDomainCausalCircuit
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Per-share compounding is real but finite and funded by a reservoir; run-rate free cash flow approximately closes from FY12/27 only if profit holds.
不确定性(原始记录):Securities strategic/financial split undisclosed.
F078|09|资产说便宜,干净盈利说不便宜,收益说有支撑
研究范围:35项覆盖检查+开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(22项,重复标签已合并)
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:直接 / 支持;一手验证:05;外部现实校验:02、09、11、12、14、15
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:直接 / 支持;一手验证:12;专项深挖:12
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:22;反向验证:27
Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield怎么使用:直接 / 支持;一手验证:27;外部现实校验:31、35;专项深挖:27
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
FY12/2025 consolidated results (tanshin): issuer identity and headline earnings怎么使用:直接 / 支持;一手验证:01
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:直接 / 支持;一手验证:17、25;反向验证:26
Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement怎么使用:直接 / 支持;一手验证:28;外部现实校验:27;专项深挖:28
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接证据;一手验证:19、21、29;反向验证:19、32
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接证据;外部现实校验:26
Market expectations as priced on 6-9 November 2026: scepticism at the top of the year's range, calm at the print's approach怎么使用:直接证据;一手验证:31;专项深挖:31
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Downside structure: what protects the equity if both cycles turn down together怎么使用:支持证据;一手验证:29;专项深挖:29
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:反向验证:31、35;其他用途:反证
Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges怎么使用:直接 / 支持;一手验证:16、28、32;专项深挖:16、32
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:直接 / 支持;一手验证:15
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
Profitability quality: ROE 9.1% in FY12/25 is flattered by the securities gain; the operating return on assets is mid-single-digit怎么使用:直接证据;一手验证:22;专项深挖:22
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;直接证据 / 支持证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors);直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域31) / 外部现实(研究域35) / 定向深挖(研究域27)|Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 支持证据 / 一手证据(研究域01)|FY12/2025 consolidated results (tanshin): issuer identity and headline earnings;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域27) / 定向深挖(研究域28)|Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement;直接证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|Market expectations as priced on 6-9 November 2026: scepticism at the top of the year's range, calm at the print's approach;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域28) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;直接证据 / 支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Profitability quality: ROE 9.1% in FY12/25 is flattered by the securities gain; the operating return on assets is mid-single-digit
完整研究记录(核对用)
研究原文:Cycle variance and the sub-book valuation|The near-book PBR is not a balance-sheet judgement (the balance sheet is net cash) but a variance judgement on an earnings stream that has printed JPY 3.6 billion and JPY 16.5 billion of ordinary profit within three years. The only durable re-rating mechanism is mix — a larger share of profit from the qualified fibre line — which links valuation to segment economics with no shortcut through asset discovery.
内部研究类型:CrossDomainCausalCircuit
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Re-rating requires variance reduction; waiting is paid by yield and per-share compounding.
不确定性(原始记录):No peer multiples compiled; multiples are on company guidance and differ by denominator basis.
F079|02|碳化硅是利润引擎,但一半经济利益在伙伴手里
研究范围:35项覆盖检查+开放研究
写入正文:02|碳化硅是利润引擎,但一半经济利益在伙伴手里09|按母公司每股价值估值,增长要打折12|净利润上升,其实是证券收益盖住了经营下滑
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(16项,重复标签已合并)
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:直接 / 支持;一手验证:15
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接证据;一手验证:20
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接 / 支持;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:直接 / 支持;一手验证:07;外部现实校验:06;专项深挖:07
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:直接 / 支持;外部现实校验:01、07、24
Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012怎么使用:支持证据;一手验证:09、10;专项深挖:09
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:支持证据;一手验证:04、10;专项深挖:04、10
Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes怎么使用:支持证据;一手验证:08;专项深挖:08
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:直接证据;一手验证:05;外部现实校验:02、09、11、12、14、15
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接证据;外部现实校验:17、18、19、20、21、25;反向验证:17
Shareholder register (EDINET database over securities-report filings): top holders and ownership mix怎么使用:直接 / 支持;一手验证:24
Ownership detail: trust banks, relationship holders and a 55.41% retail base across 16,137 shareholders怎么使用:直接 / 支持;一手验证:24;专项深挖:24
Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place怎么使用:直接证据;一手验证:13、22、23;专项深挖:13、23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;直接证据 / 支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;直接证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon;支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 定向深挖(研究域09)|Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012;支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;支持证据 / 一手证据(研究域08) / 定向深挖(研究域08)|Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;直接证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 支持证据 / 一手证据(研究域24)|Shareholder register (EDINET database over securities-report filings): top holders and ownership mix;直接证据 / 支持证据 / 一手证据(研究域24) / 定向深挖(研究域24)|Ownership detail: trust banks, relationship holders and a 55.41% retail base across 16,137 shareholders;直接证据 / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place
完整研究记录(核对用)
研究原文:Joint-venture structure caps translation of growth into parent economics|The fastest-growing, highest-margin business is the one the parent owns half of, so consolidated growth overstates parent economics by the minority share (JPY 557 million of FY12/25 net income; JPY 9,213 million of net assets). Segment and ownership domains must be read together or both are misread.
内部研究类型:CrossDomainCausalCircuit
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Value the franchise on parent earnings; any capacity expansion inside NGS shares funding and returns.
不确定性(原始记录):Precise parent share of SiC profit is not disclosed.
F080|06|火灾、库存换位和成本抬升,出在同一个生产系统里
研究范围:35项覆盖检查+开放研究
写入正文:06|火灾、库存换位和成本抬升,出在同一个生产系统里13|库存78亿日元的换位和火灾尾部,什么时候说清?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(14项,重复标签已合并)
Toyama plant fire (29 August 2025): the accounting footprint across FY12/25 and H1 FY12/26怎么使用:直接 / 支持;一手验证:06;反向验证:06、16
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure怎么使用:直接证据;一手验证:06、14;专项深挖:06、14
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
Working capital: the FY12/25 inventory mirror and a receivables position that recovered in H1 FY12/26怎么使用:直接 / 支持;一手验证:19、32;专项深挖:19
Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million怎么使用:直接 / 支持;一手验证:20;专项深挖:20
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:直接 / 支持;一手验证:15
Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear怎么使用:直接 / 支持
Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed怎么使用:直接 / 支持
Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges怎么使用:直接证据;一手验证:16、28、32;专项深挖:16、32
Downside structure: what protects the equity if both cycles turn down together怎么使用:直接证据;一手验证:29;专项深挖:29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域06) / 反证(研究域16)|Toyama plant fire (29 August 2025): the accounting footprint across FY12/25 and H1 FY12/26;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 一手证据(研究域06) / 一手证据(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域32) / 定向深挖(研究域19)|Working capital: the FY12/25 inventory mirror and a receivables position that recovered in H1 FY12/26;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;直接证据 / 支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;直接证据 / 支持证据|Interim trajectory: Q1 shock, Q2 repair - the half-year path inside FY12/26;直接证据 / 支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear;直接证据 / 支持证据|Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed;直接证据 / 一手证据(研究域16) / 一手证据(研究域28) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges;直接证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together
完整研究记录(核对用)
研究原文:Fire, inventory rotation and fine-carbon cost bulge in one production system|The Toyama fire, the JPY 7.8 billion inventory rotation and the fine-carbon cost bulge all sit inside the same production system within eighteen months. Until the Q3 print and the annual inventory note separate them, reported segment margins mix a one-off disruption, an unexplained stock rotation and a structural cost step-up: the accounting, working-capital and margin domains share one unresolved variable.
内部研究类型:SharedUnresolvedVariable
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Normalised carbon margin and the downside value of inventory carry an information discount until separated.
不确定性(原始记录):Causal attribution among the three is unevidenced.
F081|11|指引是保守还是有预见,下半年才知道
研究范围:35项覆盖检查+开放研究
写入正文:11|指引是保守还是有预见,下半年才知道13|下半年隐含的降幅到底来自什么?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(21项,重复标签已合并)
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:直接 / 支持;反向验证:31、35
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接证据;反向验证:28
Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure怎么使用:直接证据;一手验证:06、14;专项深挖:06、14
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:直接证据;一手验证:12;专项深挖:12
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:支持证据;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:支持证据;一手验证:05;外部现实校验:02、09、11、12、14、15
Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print怎么使用:直接证据;一手验证:30;专项深挖:30、34
Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear怎么使用:直接 / 支持
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026怎么使用:直接证据;一手验证:13、23、30
Falsification anchors: the dated prints against which this research can be proven wrong怎么使用:支持证据;一手验证:35;专项深挖:35
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:支持证据
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接证据;一手验证:07、09、11、33;外部现实校验:03、04、08、10
Demand engines as disclosed: steel (electrodes), semiconductors (fine carbon), aerospace (SiC fibre), machinery怎么使用:直接证据;一手验证:05、11;专项深挖:05、11
Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012怎么使用:支持证据;一手验证:09、10;专项深挖:09
Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base怎么使用:支持证据;一手验证:04、10;专项深挖:04、10
Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes怎么使用:支持证据;一手验证:08;专项深挖:08
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;直接证据 / 支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;直接证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;直接证据 / 一手证据(研究域06) / 一手证据(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure;直接证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors);支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30) / 定向深挖(研究域34)|Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print;直接证据 / 支持证据|Interim trajectory: Q1 shock, Q2 repair - the half-year path inside FY12/26;直接证据 / 支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域30)|IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026;支持证据|Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed;支持证据 / 一手证据(研究域35) / 定向深挖(研究域35)|Falsification anchors: the dated prints against which this research can be proven wrong;支持证据|Limitations anchor: what this research did not read, stated once and carried through every domain;直接证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Demand engines as disclosed: steel (electrodes), semiconductors (fine carbon), aerospace (SiC fibre), machinery;支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 定向深挖(研究域09)|Market position: a 1915-vintage carbon pioneer; in SiC fibre, a qualified supplier inside the LEAP supply chain since 2012;支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域10)|Technology base: NICALON (mass production 1983) and Hi-NICALON (1995) - a forty-year fibre lead inside a 110-year carbon base;支持证据 / 一手证据(研究域08) / 定向深挖(研究域08)|Competitive frame: specification and qualification in fibre and fine carbon; price and cost in electrodes
完整研究记录(核对用)
研究原文:Guidance conservatism and yen exposure|Management absorbed a +54.7% interim operating beat without raising the year, treating yen weakness against the JPY 145 plan rate as transitory. The second half will reveal whether that was conservatism or foresight, and the answer reprices both the forecast's credibility and the stock's FX sensitivity at once.
内部研究类型:CrossDomainCausalCircuit
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Q3 either confirms the floor reading or forces the first revision.
不确定性(原始记录):Attribution of the second-half step-down is undisclosed; Q3 print post-dates the review cutoff.
F082|01|净现金加低于账面的价格,买的是等待转换
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|净现金加低于账面的价格,买的是等待转换14|Kabugami 评分 V3.2:60.92/100分,评级 B
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(40项,重复标签已合并)
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:直接 / 支持;一手验证:35
Downside structure: what protects the equity if both cycles turn down together怎么使用:直接 / 支持;一手验证:29;专项深挖:29
IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough)怎么使用:直接 / 支持;一手验证:12;外部现实校验:33;反向验证:12、29、35;同业比较:05、08、10、11、28;其他用途:历史
Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield怎么使用:直接 / 支持;一手验证:27;外部现实校验:31、35;专项深挖:27
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:直接 / 支持;反向验证:31、35;其他用途:反证
Falsification anchors: the dated prints against which this research can be proven wrong怎么使用:直接 / 支持;一手验证:35;专项深挖:35
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:直接 / 支持
Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print怎么使用:直接证据;一手验证:30;专项深挖:30、34
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:直接 / 支持;一手验证:05;外部现实校验:02、09、11、12、14、15
Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors)怎么使用:直接 / 支持;一手验证:12;专项深挖:12
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接 / 支持;一手验证:07、09、11、33;外部现实校验:03、04、08、10
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:直接 / 支持;外部现实校验:16、32
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:直接证据;一手验证:07;外部现实校验:06;专项深挖:07
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million怎么使用:直接 / 支持;一手验证:18;专项深挖:18
Debt profile: borrowings are almost entirely short-term - and covered 1.5 times by cash怎么使用:直接 / 支持;一手验证:18、25;专项深挖:25
IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:22;反向验证:27
Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book怎么使用:直接证据;一手验证:21;外部现实校验:29;专项深挖:21
Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend怎么使用:支持证据;外部现实校验:28;同业比较:01、04、06、07、12、13、16、17、18、19、20、21、22、23、24、25、26、27、29、30、32、33;其他用途:历史
FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds怎么使用:支持证据;一手验证:17、25;反向验证:26
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接 / 支持;外部现实校验:26
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:直接 / 支持;一手验证:26
Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
Dividend framework as practised: a fixed JPY 200 through a full earnings cycle, payout ratio as the residual怎么使用:直接 / 支持
Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million怎么使用:支持证据;一手验证:20;专项深挖:20
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:直接 / 支持;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:直接 / 支持;一手验证:15
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
Market expectations as priced on 6-9 November 2026: scepticism at the top of the year's range, calm at the print's approach怎么使用:直接证据;一手验证:31;专项深挖:31
Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement怎么使用:支持证据;一手验证:28;外部现实校验:27;专项深挖:28
Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing怎么使用:直接 / 支持;外部现实校验:13、23
'GO BEYOND 2030' in operation: what the interim filing shows of the plan's product directions怎么使用:直接 / 支持
Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place怎么使用:直接 / 支持;一手验证:13、22、23;专项深挖:13、23
IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026怎么使用:直接 / 支持;一手验证:13、23、30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;直接证据 / 支持证据 / 一手证据(研究域29) / 定向深挖(研究域29)|Downside structure: what protects the equity if both cycles turn down together;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域33) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域28) / 反证(研究域12) / 反证(研究域29) / 反证(研究域35)|IRBANK annual results table: the electrode super-cycle in the company's own history (FY12/18 peak, FY12/20 trough);直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域31) / 外部现实(研究域35) / 定向深挖(研究域27)|Valuation frame at 6 November 2026: 0.91 times book, 18.5 times clean forecast earnings, 4.34% forecast yield;直接证据 / 支持证据 / 反证 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域35)|Falsification anchors: the dated prints against which this research can be proven wrong;直接证据 / 支持证据|Limitations anchor: what this research did not read, stated once and carried through every domain;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30) / 定向深挖(研究域34)|Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print;直接证据 / 支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;直接证据 / 支持证据 / 一手证据(研究域12) / 定向深挖(研究域12)|Cycle exposure quantified: two cycles, different clocks - electrodes (steel) and fine carbon (semiconductors);直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;直接证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries;直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;直接证据 / 支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;直接证据 / 支持证据 / 一手证据(研究域18) / 定向深挖(研究域18)|Balance-sheet structure at FY12/25: assets JPY 85,607 million, liabilities only JPY 22,000 million;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 定向深挖(研究域25)|Debt profile: borrowings are almost entirely short-term - and covered 1.5 times by cash;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域22) / 反证(研究域27)|IRBANK market snapshot, 6 November 2026: close JPY 4,610, market capitalisation JPY 54.5 billion, PBR 0.91;直接证据 / 一手证据(研究域21) / 外部现实(研究域29) / 定向深挖(研究域21)|Non-operating and financial assets: a JPY 10,197 million securities portfolio (after JPY 3,716 million of sales) and land at JPY 3,582 million book;支持证据 / 外部现实(研究域28) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域27) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域33)|Five-year record from the securities reports (FY12/21-FY12/25): plateau sales, margin round-trip, flat dividend;支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 反证(研究域26)|FY12/2025 results (tanshin): cash flow - operating cash covers the profit, capex peak, securities proceeds;直接证据 / 支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return;直接证据 / 支持证据|Dividend framework as practised: a fixed JPY 200 through a full earnings cycle, payout ratio as the residual;支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;直接证据 / 支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|Market expectations as priced on 6-9 November 2026: scepticism at the top of the year's range, calm at the print's approach;支持证据 / 一手证据(研究域28) / 外部现实(研究域27) / 定向深挖(研究域28)|Normalised earnings power: ordinary profit of about JPY 5.1-5.4 billion on the current structure, before cycle movement;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域23)|Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing;直接证据 / 支持证据|'GO BEYOND 2030' in operation: what the interim filing shows of the plan's product directions;直接证据|Sustainability and new-business directions named in the plan: power-semiconductor products and carbon-neutrality businesses;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域30)|IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026;直接证据|Disclosure quality: timely difference notices and English summaries; the gaps are the unread capital-cost notice and the unexplained inventory rotation
完整研究记录(核对用)
研究原文:Thesis, strongest counter-evidence and falsifiers|Three legs — balance sheet (most durable), fibre franchise (high, half-owned), capital policy (least proven, one programme old) — are weighed against electrode amplitude, minority leakage and non-extrapolating guidance. The thesis is as durable as its weakest leg's next print.
内部研究类型:ThesisAdjudication
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Paid 4.34% to wait for conversion; cost is trough-scenario opportunity cost.
不确定性(原始记录):Conditioned by standing evidence gaps.
F083|13|还有哪些限制贯穿所有判断?
研究范围:开放研究+35项覆盖检查
写入正文:13|还有哪些限制贯穿所有判断?
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(36项,重复标签已合并)
Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print怎么使用:直接证据;一手验证:30;专项深挖:30、34
Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear怎么使用:直接 / 支持
Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year怎么使用:直接 / 支持;一手验证:20
IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026怎么使用:直接 / 支持;一手验证:13、23、30
Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed怎么使用:直接 / 支持
Falsification anchors: the dated prints against which this research can be proven wrong怎么使用:支持证据;一手验证:35;专项深挖:35
Limitations anchor: what this research did not read, stated once and carried through every domain怎么使用:直接 / 支持
Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised怎么使用:直接 / 支持;一手验证:14;外部现实校验:05、30;反向验证:14
Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank怎么使用:直接 / 支持;反向验证:31、35
FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed怎么使用:直接 / 支持;反向验证:28
Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place怎么使用:直接 / 支持;一手验证:13、22、23;专项深挖:13、23
Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing怎么使用:直接 / 支持;外部现实校验:13、23
'GO BEYOND 2030' in operation: what the interim filing shows of the plan's product directions怎么使用:支持证据
Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%怎么使用:直接 / 支持;外部现实校验:26
Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%怎么使用:直接 / 支持;一手验证:26
Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference怎么使用:支持证据;一手验证:35
Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million怎么使用:支持证据;一手验证:20;专项深挖:20
GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%怎么使用:直接 / 支持;一手验证:07、09、11、33;外部现实校验:03、04、08、10
FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity怎么使用:直接证据;一手验证:05;外部现实校验:02、09、11、12、14、15
Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries怎么使用:直接 / 支持;一手验证:07;外部现实校验:06;专项深挖:07
Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received怎么使用:直接 / 支持;外部现实校验:17、18、19、20、21、25;反向验证:17
FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other怎么使用:支持证据;一手验证:02、03、16
Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million怎么使用:支持证据;一手验证:15
FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror怎么使用:直接 / 支持;一手验证:19、21、29;反向验证:19、32
FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million怎么使用:支持证据;外部现实校验:16、32
SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon怎么使用:支持证据;外部现实校验:01、07、24
Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges怎么使用:直接证据;一手验证:16、28、32;专项深挖:16、32
Ownership detail: trust banks, relationship holders and a 55.41% retail base across 16,137 shareholders怎么使用:直接证据;一手验证:24;专项深挖:24
Shareholder register (EDINET database over securities-report filings): top holders and ownership mix怎么使用:支持证据;一手验证:24
Working capital: the FY12/25 inventory mirror and a receivables position that recovered in H1 FY12/26怎么使用:直接 / 支持;一手验证:19、32;专项深挖:19
Toyama plant fire (29 August 2025): the accounting footprint across FY12/25 and H1 FY12/26怎么使用:直接 / 支持;一手验证:06;反向验证:06、16
Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure怎么使用:直接证据;一手验证:06、14;专项深挖:06、14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域30) / 定向深挖(研究域30) / 定向深挖(研究域34)|Catalyst calendar as of the review date: Q3 print on or about 10 November 2026, then the February 2027 annual print;直接证据 / 支持证据|Interim trajectory: Q1 shock, Q2 repair - the half-year path inside FY12/26;直接证据 / 支持证据|Q1 FY12/2026 results (tanshin): sales up 11.3%, operating profit down 17.9%, idle-equipment costs appear;直接证据 / 支持证据 / 一手证据(研究域20)|Interim (H1) FY12/2026 results (tanshin): the decline narrows - Q2 alone turns operating profit positive year on year;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域30)|IRBANK timely-disclosure index for 5302 (crawled 2026-11-09): the Q3 print is not yet out; dated governance and returns filings of 2026;直接证据 / 支持证据|Q1 FY12/2026 detail: equity-method result swings to a loss; first buyback tranche executed;支持证据 / 一手证据(研究域35) / 定向深挖(研究域35)|Falsification anchors: the dated prints against which this research can be proven wrong;直接证据 / 支持证据|Limitations anchor: what this research did not read, stated once and carried through every domain;直接证据 / 支持证据|The February 2026 interim plan against H1 actuals: what unchanged full-year guidance implies for the second half;直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域05) / 外部现实(研究域30) / 反证(研究域14)|Notice of differences between the H1 FY12/2026 forecast and actual results (10 August 2026): a 54.7% operating beat, guidance not raised;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域35)|Guidance credibility: a February plan beaten by 54.7% at the half and still not raised - a pattern to price, not a promise to bank;直接证据 / 支持证据 / 反证(研究域28)|FY12/2026 guidance (set in the FY12/25 tanshin, 10 February 2026): sales up, profit down, no special items assumed;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|Governance record of 2026: capital-cost notice, defence-policy renewal, benefit programme, board benefit trust in place;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域23)|Management policy in the FY12/25 tanshin: mid-term management policy 'GO BEYOND 2030' - qualitative themes, no numeric targets in the filing;支持证据|'GO BEYOND 2030' in operation: what the interim filing shows of the plan's product directions;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|Capital allocation in 2026: buyback to the cap, dividend defended, capex falling - a deliberate shift from investment to return;直接证据 / 支持证据 / 外部现实(研究域26)|Share buyback completion notice (7 September 2026): JPY 2.5 billion frame used to 99.99%;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 200 per share held for five consecutive years; FY12/25 payout 45.8%, dividend-on-equity 4.2%;支持证据 / 一手证据(研究域35)|Thesis support composite: the 2026 actions - buyback to the cap, defended dividend, capital-cost notice - as revealed preference;支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|Capex and the productive base: the expansion completed in FY12/25; H1 FY12/26 capex fell to JPY 1,386 million;直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域33) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域08) / 外部现实(研究域10)|GE press release (27 February 2012): NGS Advanced Fibers established - Nippon Carbon 50%, GE 25%, Safran 25%;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域14) / 外部现实(研究域15)|FY12/25 tanshin business narrative: fine carbon down on the power-semiconductor slowdown, electrodes up on North American exports, SiC fibre at full capacity;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域06) / 定向深挖(研究域07)|Group structure: the 50/25/25 NGS venture and the SEC Carbon alliance define the group's two strategic geometries;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域25) / 反证(研究域17)|Interim FY12/2026 balance sheet and cash flow: equity ratio 64.2%, capex phase over, insurance received;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域16)|FY12/2025 results (tanshin): segment sales and profit - carbon products, silicon-carbide products, other;支持证据 / 一手证据(研究域15)|Interim FY12/2026 sub-product split inside carbon products: fine carbon JPY 10,024 million, electrodes JPY 6,003 million;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域19) / 反证(研究域32)|FY12/2025 results (tanshin): balance sheet - net cash, 63.5% equity ratio, the inventory mirror;支持证据 / 外部现实(研究域16) / 外部现实(研究域32)|FY12/25 profit-and-loss detail from the securities report: gross margin fell 3.1 points; R&D JPY 525 million;支持证据 / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域24)|SEC Carbon official English stock-information page: 'NIPPON CARBON CO., LTD.' holds 4.06% of SEC Carbon;直接证据 / 一手证据(研究域16) / 一手证据(研究域28) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|Accounting separation: FY12/25's three one-off families - securities gain, fire loss and provision, idle-equipment charges;直接证据 / 一手证据(研究域24) / 定向深挖(研究域24)|Ownership detail: trust banks, relationship holders and a 55.41% retail base across 16,137 shareholders;支持证据 / 一手证据(研究域24)|Shareholder register (EDINET database over securities-report filings): top holders and ownership mix;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域32) / 定向深挖(研究域19)|Working capital: the FY12/25 inventory mirror and a receivables position that recovered in H1 FY12/26;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域06) / 反证(研究域16)|Toyama plant fire (29 August 2025): the accounting footprint across FY12/25 and H1 FY12/26;直接证据 / 一手证据(研究域06) / 一手证据(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Risk register as the filings themselves frame it: raw-material and fuel prices, US tariff policy, the yen, single-programme aerospace exposure;直接证据|Disclosure quality: timely difference notices and English summaries; the gaps are the unread capital-cost notice and the unexplained inventory rotation
完整研究记录(核对用)
研究原文:Research Debt carried to the next Review|Priority-1: Q3 FY12/26 print, second-half guidance assumptions, February 2027 successor return framework. Priority-2: capital-cost notice contents, inventory rotation, fire tail, SiC capacity. Priority-3: equity-method affiliate, benefit programme terms. Future-dated items belong to a later MATERIAL_UPDATE; unread public documents are carried gaps.
内部研究类型:ResearchDebtRegister
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Each item has an identified resolving document; opposite answers move the thesis or confidence.
不确定性(原始记录):No reopen of public research is required for this synthesis.
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | 784a0cbd603333f95a7a596470c939cd61aaed43 |
| Delivery Commit SHA | 784a0cbd603333f95a7a596470c939cd61aaed43 |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | 36e0a491-c112-5fb0-974f-d25786fad7c0 |
| Canonical Revision | 1 |