公司能稳定做出的营业利润在130亿至140亿日元这一档:2026年3月期营业利润136.09亿日元,剔除22.16亿日元汇兑收益后的经常利润也在同一水平。自有资本比率47.1%,扩张期间没有增发股票。2027年3月期起股息改为以净资产股息率(DOE)4%以上为下限,预测每股95日元,按收盘价算股息率5.14%,市净率0.77倍(按2026年6月底净资产)。
5351
品川リフラ株式会社(Shinagawa Refra Co., Ltd.)
品川リフラ株式会社(SHINAGAWA REFRA CO., LTD.,东证 Prime 市场及札幌证券交易所上市,代码5351;原名 Shinagawa Refractories,2025年10月1日更名)1875年创业,社长为 Hiroyuki Fujiwara,资本金33亿日元。公司主营耐火材料,同时经营隔热材料、先进材料和工程(炉体施工)业务,客户主要是钢铁及其他高温工业。JFE Steel 持有34.9%的表决权。 估值简报:股价1,847日元(2026年11月6日收盘)。总市值870.8亿日元(按含库存股的发行股数47,146,830股)。预测PER 8.03倍(按公司2027年3月期预测每股利润230.10日元,该预测含Kwinana征收收益)。实绩PBR 0.79倍(2026年3月期末每股净资产2,343.45日元;按2026年6月底2,414.18日元为0.77倍)。ROE 26.6%(2026年3月期实绩,含不动产出售收益;预测9.53%为IRBANK口径推算)。预测股息率5.14%(2027年3月期95日元)。EV/EBITDA 5.7倍(EV 1,172.8亿日元=总市值870.8亿+净有息负债302.0亿〔2026年6月30日〕;EBITDA 207.4亿日元=2026年3月期营业利润136.09亿+折旧71.31亿;两项期间不同)。
最近亮点:2027年3月期(FY27/3)一季度(4–6月)销售465.90亿日元,上涨21.8%;营业利润17.36亿日元,下跌39.9%;毛利率20.1%,上年同期25.2%。8月10日公司把全年销售预测从1,890亿日元上调到1,980亿日元,营业利润预测仍维持130亿日元。上半年(4–9月)的中期财报在评审日2026年11月9日尚未公布,按前两年的发布节奏预计近日披露。
规模扩大没有变成利润:营业利润率从2025年3月期的9.2%左右降到2026年3月期的7.7%,公司预测2027年3月期为6.6%。预测要求下半年营业利润85亿日元,一季度只有17.36亿日元,依赖原料涨价转嫁、海外设备故障排除和巴西 Reframax 项目确认三项尚未兑现的假设。商誉和无形资产合计490.65亿日元,占净资产四成上下,若再减值会同时压低账面净资产。
结论:评分59.25/100,评级B。暂不追高;已持有者可继续持有并以中期决算作检验点,空仓者等决算公布后,看上半年营业利润是否达到45亿日元、Reframax是否回到盈利、毛利率是否回升,再决定是否分批建仓,并按耐心资金对待折价可能长期存在的情形。 依据:经常性营业利润130亿至140亿日元、47.1%的自有资本比率和5%左右的股息给出较厚的底,但规模扩张尚未转化为利润。价格上,二十年平台已被突破,2026年3月触及历史高点2,507日元后被压回,目前在1,824至2,158日元的高位区间等待第一个完整业绩季的检验。中期决算和第七次中期经营计划都在评审日之后才公布,对这一结论把握一般。 翻转条件:上半年营业利润明显低于45亿日元并下调全年预测、Reframax再度亏损,或Ako工厂等资产再次减值,判断转弱。 当前动作:暂不追高。基本面上,约130亿至140亿日元的经常性营业利润、47.1%的自有资本比率和以净资产为基准的约5%股息提供了较厚的底,但规模扩大尚未转化为利润,中期决算(预计近日公布)是第一个实质检验。已持有者可继续持有并以中期决算为检验点;尚未持有者宜等决算公布后,看上半期营业利润是否达到45亿日元、Reframax是否回到盈利、毛利率是否回升,再决定是否分批建仓,并按耐心资金对待折价可能长期存在的情形。若上半期利润明显低于预测并下调全年预测,或再次出现减值,应重新评估。
报告目录
01|投资问题与当前结论
01.1|规模已经买到手,利润还没有跟上
当前判断是:规模买到了,利润还没有跟上,所以评分59.25分(满分100),评级B,暂不追高。
一组数字说明问题所在。营业利润2025年3月期为133亿日元左右,2026年3月期136.09亿日元,2027年3月期公司预测130亿日元;同期销售从1,440亿日元上下升到1,777.38亿日元,再到预测的1,980亿日元。营业利润率因此从9.2%左右降到7.7%,预测为6.6%。按预测,销售比2025年3月期多出540亿日元,营业利润反而略低。
这把投资问题收窄成一句话:扩大后的全球平台,能不能在摩擦吃掉成果之前,把规模变成营业利润?摩擦有四项:每年18亿日元左右的商誉摊销,Reframax的项目波动,Ako工厂的减值,以及不断缩小的国内钢铁需求。
如果转化发生,一家每年稳定赚130亿至140亿日元、按DOE方针分红、市净率只有0.77倍的公司就是被低估的,隔热材料和先进材料这两个增长期权也几乎白送。如果不发生,折价就是合理价格。
转化现在没有证明;即使经常性利润区间守得住,折价也可能延续数年。
正反两面的证据都很具体。正面是经常性利润区间、47.1%的自有资本比率、没有增发、以净资产为基准的5%左右股息,以及0.77倍的净资产价格。反面是销售创纪录而利润率下滑,被计划列为增长引擎的隔热和先进材料反而落后于计划,减值来得很早,下半年恢复由几项假设叠在一起,治理上外部压力基本不存在。检验这些的日期都在评审日之后:2027年3月期中期决算、第三季度财报,以及随2027年3月期决算公布的第七次中期经营计划。
01.2|七条因果链都落在同一个检验上:每单位收购来的规模换回多少营业利润
七条因果链最后落到同一个问题:收购来的规模,每一单位能变成多少营业利润。
前三条解释公司怎样走到今天。国内钢铁产量下降,耐火材料的利润只能靠价格、产品结构和海外贡献;海外收购一步步同时抬高销售、管理费用和商誉;Reframax的项目节奏让工程部门,进而让集团营业利润出现大起大落。第二、第三条依赖尚未观察到的上半年和第三季度表现,现在只能按公司预测理解。
后四条讲钱和约束。出售不动产修复了资产负债表,却带来一张税单,把短期借款重新推高。减值冲击的是重组和收购资产本身,使490亿日元左右无形资产的举证责任更重。DOE方针把股息变成资产负债表上的承诺。JFE Steel同时是客户和股东,把需求稳定和治理独立性绑在钢铁集团的走势上。七条链条的终点相同,都是营业利润能否追上规模。
01.3|什么会推翻这个判断
判断在第一批检查点就可能被推翻。下面四种情形,任何一种出现都算数。
第一,上半年累计营业利润明显低于45亿日元的预测,并下调全年预测。第二,Reframax再出现亏损的半年。第三,Ako工厂、被收购的海外资产在2027年3月期内再次减值。第四,第七次中期经营计划放弃利润率目标,又没有资本政策补偿。
四者之一出现,低于净资产的价格就只是一个“边际利润被摊薄的整合者”的合理价格,而不是错杀。
这些检查依据公司自己的定期披露,而评审日时它们都还没有公开,所以判断本身带有这一未知。
02|公司本质与商业模式
02.1|耐火材料每烧一炉磨损一次,工程业务把销量和波动一起带来
公司的赚钱方式很朴素:耐火材料每烧一炉就磨损一次,钢厂必须不断补货;公司再承接炉体施工,并越来越多地把两者作为全球打包业务卖给客户。材料部分的利润像一笔年金,是基本盘;工程是销量和波动的来源,如今占集团销售的四分之一左右(2027年3月期一季度外部销售114.31亿日元,集团465.90亿日元)。
2026年3月期分部数据(亿日元):
| 分部 | 销售 | 分部利润 |
|---|---|---|
| 耐火材料 | 1,109.01 | 85.75 |
| 隔热材料 | 177.08 | 24.80 |
| 先进材料 | 41.01 | -1.15 |
| 工程 | 458.56 | 27.14 |
四个分部相加略高于合并销售,因为尚未扣除内部抵销。
现在的利润来源是耐火材料加工程两块,而工程主要由巴西Reframax构成。盈利质量因此不再只取决于国内价格修正,还取决于巴西项目的执行:基数更宽,也更难预测。分部之间的内部转移价格、通用品与差异化产品的比例、产品层面的定价,公司都没有披露。
02.2|耐久的是消耗品基本盘,尚未证明的是海外扩张
整体面貌可以概括为:一个耐久的消耗品基本盘,在为一次尚未证明的全球扩张出钱。
耐久的部分有清楚的依据。耐火材料每炉都要消耗,公司自1875年起供货,JFE Steel这样的客户关系(持股34.9%,占销售30%左右)每次炉衬更换都会续约。
这块基本盘通过出售不动产,换来了三年内买下一个全球第二引擎的机会,赶在国内钢铁需求进一步缩小之前。扩张买到的资产是真实的:欧洲、巴西、美国、意大利的平台,重建后的国内工厂,增长业务的产能。
它的代价也是真实的,部分已经确认:97.16亿日元减值、490亿日元无形资产、利润率从9.2%到预测的6.6%。
所以耐久性对企业整体较高,对扩张本身尚未证明。DOE股息让股东在扩张接受检验期间,靠耐久的资产负债表拿到回报;而基本盘的自我修复,依赖耗材需求和资产出售的灵活性,后者无法以同样规模重复。最坏情形是长期折价加减值,而不是破产。
扩张的回报、护城河强度、工程在手订单质量和国内工厂开工率都没有量化;这一面貌来自财报和结构判断,没有独立的市场份额数据印证。普通股东持有的,是一个以0.77倍净资产交易、有JFE Steel作靠山的耐久特许经营,回报取决于买来的规模能否在未来四个财报期内赚回它占用的资本。
02.3|一个世纪的国内龙头,三年里决定用不动产买一个全球化未来
这家公司先是国内一个世纪的在位者,近三年才决定用国内不动产去买全球化。关键节点依次是:1875年创业,是日本第一家民营耐火材料企业;2009年与JFE Refractories重组,把集团绑进JFE的轨道;2022年通过要约收购把Isolite Industries纳入合并;2023年10月进行1拆5股票拆分,同年有Saint-Gobain业务转入;2024年收购Gouda;2025年创业150周年之际更名;2026年3月期并入Reframax,并完成不动产出售的资金循环。
以往几轮整合最终体现为稳定的盈利,而这一轮的兑现期,按判断在两到三年之后。2023年之前的收购细节,现有材料读得有限。
03|产品、客户与供应链
03.1|国内需求池在缩小,增长只能靠海外买来
国内需求的基准是日本钢铁,而这个池子正在缩小:2026年3月期粗钢产量8,033万吨,下降3.2%;2027年3月期一季度2,035万吨,上升1.0%。耐火材料的消耗跟着产量和炉衬更换周期走。一季度出口和建筑相关需求仍弱,汽车和工业机械需求在改善。国内核心因此面对持续缩小的销量,只有价格修正和产品结构改善在抵消。
对投资者的含义是把国内销量预期放在零:集团的全部增长,都来自份额、并购范围或产品结构。这也解释了公司为什么去海外买平台:销量池缩小,是增长被买来的原因。相对而言,行业周期的振幅小于集团自己制造的业绩波动。
2027年3月期下半年的钢铁环境在评审日无法观察,全球耐火材料的独立市场规模也没有取得。
03.2|JFE Steel既是最大客户也是最大股东,需求保险和独立性上限是同一件事
需求稳定和股权关系,在这家公司是同一条线。JFE Steel直接持有34.9%的表决权,也是最大客户:2026年3月期交易额530.59亿日元,占合并销售30%左右,年末应收款130.92亿日元。价格逐个谈判,按市场条件成交,公司声明保持独立。
对需求来说,这是在缩小的市场里买的一份保险:只要JFE的炉子在运转,这部分收入就会续存。对股东来说,它同时是独立性的硬上限:一个对象,同时决定需求、控制权格局和重估的空间。JFE集团内其他公司的销售没有单独披露,大股东的长期意图也未知。
03.3|被计划当作增长引擎的两个板块,反而落在计划后面
计划的重点板块,落后于计划;超额的是计划里原本没有的部分。2026年3月期各板块销售与计划对比(亿日元):
| 板块 | 2026年3月期实绩 | 计划 |
|---|---|---|
| 耐火材料 | 1,109 | 1,034 |
| 隔热材料 | 177 | 220 |
| 先进材料 | 41 | 54 |
| 工程 | 459 | 249 |
工程大幅超额,是因为并入了计划没有包含的Reframax。这一反证削弱了增长期权的说法:转向高附加值的上行空间没有证明,眼下的盈利靠钢铁相关和收购来的业务。
隔热材料和先进材料(半导体、电池、精细陶瓷相关需求;Isolite Industries,东证5358,2022年被要约收购,是隔热业务的主体)只占2026年3月期销售的12%左右,而且都缩了:隔热材料利润下降24.1%,先进材料亏损1.15亿日元。2027年3月期一季度销售回升(隔热材料上涨6.9%,先进材料上涨21.0%),但先进材料因Setouchi工厂折旧仍亏损,隔热材料利润因产品结构下降18.7%。这只是一个季度。
所以它们更像对2028年3月期产品结构的期权,而不是当下的盈利。增长业务的规模和投资回报没有披露。
04|竞争格局与产业关系
04.1|按规模和收购记录看,公司是分散行业里的整合者,全球份额没有量到
从规模、生产网点和收购记录看,品川リフラ是在分散的全球行业里买区域平台的整合者,在全球层面是挑战者,不是在位龙头。这是推断:没有竞争对手数据,也没有独立的全球市场份额序列,全球份额和竞标胜率都没有量到。收购来的位置能否转化为分部利润,是尚未证明的部分。
04.2|收购方向从区域耐火材料厂转向紧贴钢铁生产的产品线
收购的重心已经变了:从买区域耐火材料厂(Gouda、Reframax),转向买与炼钢相邻的产品线位置。2026年1月22日取得股权的美国Dynamix Casting Fluxes生产连铸保护渣,这是与铸造量直接挂钩的耗材;意大利Danieli合资公司(Shinagawa Danieli Advanced Materials)把先进材料和工程业务接入欧洲钢厂的渠道,由钢厂工程集团Danieli带路,现有披露没有给出其财务贡献。
期权价值和执行风险同时到来:同一个范围,既延伸了触达,也带进了巴西和欧洲的成本结构。收购价格、合资持股比例和后续对价都没有披露。
04.3|脱碳对需求既是产品结构上的顺风,也是销量上的逆风
脱碳对这个行业是双刃的。Vision 2030承诺2030年把范围1、2的二氧化碳排放从13.9万吨减半,把再生原料使用比例从8.0%提高到15.0%;低导热系数砖、隔热材料这类节能产品受益。但客户转向电炉和氢冶金,会改变耐火材料的需求结构:产品结构上顺风,销量上逆风。目前对估值是二阶因素,方向长期且在收紧;真正已经在影响股价的是东证对资本成本的要求。各工厂的碳排放暴露和所在地细节没有披露。
05|护城河判断
护城河的核心是认证资质和在位关系。钢厂在炉役中途更换耐火材料供应商,要承担停炉风险,其代价远大于材料节省,所以老供应商每次炉衬更换都能续约。叠加对客户设备(包括JFE Steel的工厂)的工程了解、靠收购拼成的全球工厂网络,以及连铸保护渣等指定产品,形成了价格和份额的缓冲。
它保护的是耐火材料的利润(2026年3月期分部利润85.75亿日元),保护不了集团自己的收购定价。同时它保护的是单位利润而不是销量:国内粗钢产量仍在缩小。股东应把它当作防守性的优势,而不是增长溢价的理由。
这一判断来自行业结构推断:客户流失事件和投标胜率没有披露,公司也没有量化自己的护城河。
06|财务质量与现金流
06.1|销售上涨23.4%,是合并范围变了,不是国内销量涨了
2026年3月期销售上涨23.4%,到1,777.38亿日元,主要因为合并范围变了:Gouda(2024年10月收购)贡献了第一个整年,巴西Reframax从2025年5月并入,意大利Danieli合资公司和Dynamix也进入范围。国内量没有增长:粗钢产量下降3.2%,耐火材料销量下降。耐火材料部门销售上涨15.7%,增量来自Gouda,加上价格修正和产品结构,而销量在下降。
因此并购带来的销售不能当作需求证据,增长要拆成范围、价格和销量三块看,三者贡献差别很大。2024至2026年三项收购的价格和或有对价,在已读材料中没有。
06.2|毛利率守住了,费用吃掉了规模
三年营业利润持平,原因出在毛利率之下。2026年3月期毛利率维持在24.2%,毛利429.90亿日元;销售和管理费用却从218.65亿日元升到293.80亿日元,增加75亿日元左右,对应Gouda和Reframax并入后的费用以及商誉摊销。毛利率没有变,说明每一元销售的毛利仍完整;扩大后的范围,成本都落在费用和摊销这两行。
每年18亿日元左右的商誉摊销,是这个固定费用里最硬的一块,占2027年3月期营业利润预测的14%左右,未来数年都会存在。
销售分部表现、计划兑现程度(目标营业利润率11%,预测6.6%)与0.77倍净资产的估值,其实是同一个问题从三个角度看。2027年3月期中期决算,会同时给出这三个问题的第一期答案:转化体现为营业利润高于130亿至140亿日元区间,没有出现就说明折价合理。这要等上半年和第三季度的数字才能观察。
06.3|260亿日元净利润是一次资本运作,不是常态盈利
2026年3月期净利润260.71亿日元(上涨166.6%,每股571.45日元)不是常态盈利:里面有372.45亿日元固定资产出售收益,被97.16亿日元减值部分抵消;营业利润只增长2.5%,到136.09亿日元。可持续的盈利中心在130亿至140亿日元:营业利润在这一档,经常利润159.86亿日元剔除22.16亿日元汇兑收益后,也在138亿日元左右。
公司没有公布基础利润指标,这个区间是按披露项目拆出来的研究推算。按账面每股利润估值,会把盈利力高估一倍左右;该资本化的是经营区间,不是净利润线。
汇兑收益已经成为经常利润里一个结构性、波动大的因素:2026年3月期22.16亿日元,2027年3月期一季度就有11.75亿日元(上年同期0.62亿日元)。正是这笔差额,使一季度经常利润只下降2.8%,而营业利润下降39.9%。剔除汇兑后,经常利润和营业利润讲的是同一个持平的故事。这是波动,不是偿债风险;公司的套期保值政策和敏感度没有披露。
另一笔一次性收益是Kwinana(澳大利亚)土地被征收,在2027年3月期一季度记入37.65亿日元特别收益,是当季净利润46.79亿日元的最大贡献。迁厂的剩余费用和时间表没有披露,它是一个未量化的尾巴,也抬高了预测每股利润。
06.4|只有合并口径有意义,母公司数字混了资产出售
母公司单体2026年3月期销售869.57亿日元,不到合并销售1,777.38亿日元的一半,而母公司净利润313.23亿日元(上涨318.0%),因为固定资产出售收益主要记在母公司。收入的重心已转到子公司和海外,而为转型出钱的收益留在母公司账上。所以只能用合并口径分析:母公司数字把一次资产循环和一个不断缩小的经营份额混在一起。少数股东权益88.31亿日元和内部抵销没有逐项披露,普通股东应占部分无法精确归属。
06.5|一季度毛利率从25.2%掉到20.1%,问题出在毛利这一行
2027年3月期一季度销售465.90亿日元,上涨21.8%,毛利却从96.55亿日元降到93.71亿日元;销售和管理费用从67.64亿日元升到76.35亿日元。毛利率从25.2%降到20.1%,说明问题在毛利线,不在集团费用控制。
披露的原因有四项:Reframax在工程部门的亏损季度,耐火材料的原料和燃料涨价,海外关联公司的设备故障,隔热材料的产品结构变化。这一季度,工程分部亏损9.88亿日元(上年同期亏损0.15亿日元),因为一位主要客户的工程进度推迟,加上巴西通胀推高成本。耐火材料分部利润22.92亿日元,仅增长1.5%。
工程由此成了集团的大起大落部分:Reframax2026年3月期使工程销售上涨78.2%、利润增长68.1%到27.14亿日元,一个季度的项目时点问题,就能让集团营业利润变动一成左右。巴西项目账本是下半年最大的单项变数;工程在手订单和项目毛利的差异没有披露。
这也影响对增长的折价:重复性按耐火材料最高(运转中炉子的合格供货),隔热材料其次,工程最低(按完工确认,时点易变);而并购以来的增长排序几乎相反,增长落在最难重复的业务上,且越来越多来自海外和收购。公司没有按合同类型披露收入,也没有披露工程在手订单。
三个原因各自占多少,没有披露:原料成本中价格修正能够追回的部分,与Reframax产品结构和海外设备故障的部分,要等到上半年和第三季度财报才有依据。
06.6|下半年要赚85亿日元:预测的算术
8月10日修订后的2027年3月期预测:销售1,980亿日元(原1,890亿日元),营业利润仍是130亿日元,经常利润140亿日元(原130亿日元),净利润105亿日元(原100亿日元),每股利润230.10日元;上半年预测营业利润45亿日元。
倒推下来:第二季度需做出营业利润27.64亿日元(第一季度17.36亿日元),销售484.10亿日元;下半年需做出营业利润85亿日元,销售1,030亿日元,利润率8.3%左右,而一季度只有3.7%。这不是不可能,2026年3月期工程完工也偏下半年,但很陡。
修订本身已经把利润率下滑写了进去:销售预测上调90亿日元,营业利润一分未动。收入预期上升而利润预期没有,实际是管理层对持续的利润率摊薄做了定价。这是公司预测,上半年数字在评审日尚未公布。
06.7|经营现金流匹配利润,但一半以上的自由现金流是资产出售
2026年3月期经营现金流138.61亿日元,对营业利润136.09亿日元,转化良好。但投资现金流为正107.85亿日元,只是因为出售不动产的400.89亿日元超过了收购支出192.15亿日元和有形资产购置95.80亿日元;账面自由现金流246亿日元左右,属于资产循环,不是经营所得。
真正的自由现金流是经营现金流减去维持性资本开支,为正,但不大;维持性与增长性资本开支的划分没有披露。融资现金流为负260.50亿日元(短期借款净减124.09亿日元,长期借款偿还103.63亿日元)。
营运资金随增长而增长。2026年3月期应收账款和合同资产增加27%左右,从392亿日元上下到497.81亿日元,因为工程完工开票晚;2026年6月降到448.24亿日元,存货336亿日元左右。下半年若按预测的假设出现完工集中,即使利润达标,也会占用现金。一季度现金流量表没有公布,应收账龄和被收购单位的纠纷情况未知。
一个上半年现金偏弱、而利润预测达标的结果,本身不足以推翻判断;现金转化要在全年里看。
06.8|资产负债表修复了一半:没有增发,但税单把借款推回去了
资产负债表是这个案子最扎实的部分,也只修复了一半。
扎实的一面:2026年6月底自有资本比率47.1%,归属母公司净资产1,101.66亿日元,每股净资产2,414.18日元,发行股数47,146,830股没有变,没有增发;收购借款大部分用出售不动产的收入还清,2026年3月期短期借款从248.54亿日元降到166.22亿日元。一季度综合收益57.95亿日元,净资产大致以股息的速度增长。
没修好的一面:出售收益带来171.43亿日元税款,占税前利润433.68亿日元的40%左右。年底还有149.37亿日元未缴,到2026年6月已缴到只剩5.51亿日元。
资金来自短期借款,从166.22亿日元升到260.41亿日元。借款总额503亿日元左右,基本回到2025年3月期的水平。
利息支出一年内从4.77亿日元升到13.42亿日元,现金流利息覆盖倍数从26.2倍降到10.6倍,有息负债相当于3.2年经营现金流:仍然舒适,但对130亿日元营业利润来说不再可以忽略。
结论是资产负债表和利润表一样处在转换中途:出售不动产的资金循环——不动产卖出、收购买入、负债偿还、税单回来——其可再卖的不动产已基本用完。授信额度余量、约束条款和短期借款的续借条件没有披露。
06.9|商誉490亿日元占着资本,资本回报只在计划里达标
商誉在2026年6月30日为287.59亿日元(2026年3月期末281.39亿日元,上年149.57亿日元),其他无形资产209.26亿日元,二者合计490.65亿日元,占净资产四成上下。摊销每季度4.48亿日元,一年18亿日元左右,集中在Reframax(商誉91.31亿日元)和欧洲收购,恰恰是这个投资判断依赖其兑现的单位。
资本回报方面,消耗品基本盘高于资本成本,收购项目从利润率角度看到目前为止低于资本成本。2026年3月期ROE 26.6%是一次性假象,预测ROE 9.53%左右;计划要求ROIC 10%,资本成本基准为6.5%,在商誉计入资本基数后,按简单计算实际ROIC明显低于目标。ROIC是近似计算,管理层当前的资本成本数字和实际ROIC没有重新披露。
资本成本意识体现在DOE方针和对PBR的讨论上,收购定价的纪律性则体现得少。商誉的可回收性取决于被收购单位的现金流,而这些现金流没有单独披露。
07|股东、董事与治理
07.1|业务上整合,董事会上不整合:JFE的影响通过人员和客户关系传导
治理的真实形状是:业务整合,董事会不整合。JFE Steel派来15名人员,但没有董事互相兼任;防御收购政策在2026年5月15日获得续期;董事绩效股份奖励规模很小(2026年7月24日处分33,588股库存股,每股1,873日元,对5名董事)。
影响通过业务里的人和客户关系传导,而不是通过董事会,所以文件可以如实声明独立,而依赖在结构上仍然存在。JFE Steel持有34.9%表决权又是占销售30%左右的最大客户,少数股东在实际上是JFE系耐火材料供应链里的次要合伙人,钢铁集团层面的决策会传导到这个股东名册。防御政策还去掉了可能给这种依赖定价的外部纪律:重估只能来自兑现和资本政策,不能指望控制权溢价;收购定价也没有外部约束。
董事会构成与独立性细节、继任安排没有深入核查,绩效股份金额在财务上不重要。
07.2|除了JFE,股东名册上还有谁,目前不清楚
除大股东外,股东名册没有查清:库存股1,513,710股,占发行股数的3.2%;扣除JFE的34.9%和库存股,流通部分最多在62%左右,还要再扣除全名册里可能存在的稳定持股法人。第二大及以下股东的身份和持股规模未知,2026年3月期有价证券报告的前十大股东没有重新读取。定价因此取决于国内边际持有者,面对的是固定的大股东背景;名册一旦变化,会是重估事件。
07.3|计划与兑现:规模超额完成,利润率没有
第六次中期计划(2024至2026年度)里,规模超过了目标,利润率没有达到。2027年3月期销售预测1,980亿日元,高于计划最后一年1,800亿日元的目标;但预测营业利润130亿日元,只有计划11% ROS目标所对应的198亿日元左右的三分之二(2026年3月期ROS 7.7%,预测6.6%)。
ROIC目标10%对比6.5%的资本成本基准,同样没有达成。Vision 2030把线拉到销售2,400亿日元、ROS 12%、ROIC 10%、海外销售比例50%。
抵消高炉停产等逆风的办法是海外扩张和降本,交付的是收入而不是利润率。年度财报没有把计划目标拿新预测重新对照。这套兑现模式(规模靠收购、利润率未交付)是判断Vision 2030该资本化多少的先验。第七次计划的目标和对Vision 2030的处理尚未公布。
计划最醒目的指标,海外销售比例45%(基数29.8%),无法从财报核实:财报没有披露这一比例,只能从母公司销售不到合并的一半看出方向是对的,精确分数要由管理层来公布。
08|资本政策
08.1|股息改成净资产基准,让股东在检验期间有一份稳定的索取权
股息政策从2027年3月期起换了锚。40%派息率目标被取消,改为以DOE 4%以上为下限的渐进式派息;2027年3月期定为每股95日元(中期47日元、期末48日元),现金43亿日元左右,相当于净资产的3.9%上下。2026年3月期派息90日元,派息率只有15.7%,因为出售不动产的资金被用于还债和增长投资。
历史显示董事会愿意为资本配置牺牲已公布的政策,然后围绕资产负债表重新设计政策。每股利润被资产出售、减值和汇兑扭曲,以资产负债表为基准的股息,让股东在经营转化接受检验期间有稳定的权利;净资产以大致等于股息的速度增长,约占经营现金流的三分之一,所以可负担。
DOE的净资产口径是公司自定的;在新方针下价格低于净资产时是否回购,尚未说明。
08.2|Ako工厂减值是资本配置最大的未解问题
2026年3月期减值97.16亿日元,落在Ako工厂和两家海外子公司上。Ako是国内单体耐火材料整合的旗舰,2024年6月才投产,减值与创纪录的销售发生在同一年,市场在2026年4月16日,也就是决算前一个月得知。
这有两种读法:一是在受到最大关注的时点保守地做账,一是收购和重组过价的证据。文件无法区分,所以不能断言是多付了钱。受影响的生产线、被改变的开工率或需求假设、两家海外子公司的名称,在已读摘要中都没有。
国内生产基地正在重建:Ako集中了单体耐火材料产能(Teiyo关闭,Hinae转为保护渣专用厂),东部从四个工厂向两个整合已经开始,Setouchi精细陶瓷基地通过先进材料分部折旧。2026年3月期有形资产购置95.80亿日元,对比年化折旧7亿日元上下。
投资阶段使自由现金流低于潜力,回报要体现为耐火材料利润率的防守和增长业务的规模;Ako和Setouchi开工率、东部整合的剩余成本和完工日期没有披露。减值提高了对剩余收购和新建资产的举证要求。
08.3|商誉是收购决策留在资产负债表上的残余
490亿日元的无形资产,是收购决策在资产负债表上的形态。它的摊销是利润率问题里的固定费用,减值名单(Ako和两家海外单位)是这些决策如何老化的第一份证据。含这些无形资产在内,每股净资产2,414日元左右的账面价值里,有一部分价值是预测,不是事实。商誉的可回收性要等被收购单位的现金流披露后才能观察。
08.4|不动产换收购的资金循环,之后的扩张要自己承担
从资本配置角度看,这一圈很清楚:卖出国内不动产,买入海外经营资产,还掉收购债务,再被一笔税单推回借款。资产负债表因此处在转换中途,不能简单读成已经修复。将来的收购要由经营现金流和借款承担,战略节奏变成自筹,也就更慢。剩余不动产和证券的可变现价值,以及授信条件,均未披露。
09|估值与安全边际
09.1|市场按0.77倍净资产定价:没给转化溢价,也没按利润区间崩塌定价
2026年11月6日收盘价1,847日元,当日下跌4.94%,总市值870.8亿日元,约为2026年6月底净资产1,101.66亿日元的79%。
| 指标 | 数值 | 口径 |
|---|---|---|
| 预测PER | 8.03倍 | 2027年3月期预测每股利润230.10日元,含Kwinana收益 |
| 实绩PBR | 0.79倍/0.77倍 | 2026年3月期末每股净资产2,343.45日元/2026年6月底2,414.18日元 |
| 预测股息率 | 5.14% | 95日元 |
| ROE | 26.6% | 2026年3月期,受不动产收益扭曲;IRBANK预测口径9.53% |
| EV/EBITDA | 5.7倍 | EV 1,172.8亿日元,净负债302.0亿日元(2026年6月30日);EBITDA 207.4亿日元=营业利润136.09亿+折旧71.31亿;公司含商誉摊销的EBITDA为221.34亿日元 |
这些数字口径不一:EBITDA取2026年3月期,净负债取2026年6月;市值按发行股数而非流通股数;PBR取决于净资产日期;没有找到分析师一致预期。按130亿日元左右经常性营业利润扣税后计算,有效市盈率在10至11倍,是研究推算而非公司披露。报价对转化持怀疑态度,但没有给利润区间的崩塌定价。
股价对应的估值,能否重估,取决于转化而不是资产价值。
09.2|估值要从净利润换到经常性盈利:8.03倍看起来比实际便宜
账面倍数被扭曲:PER 8.03倍、ROE 26.6%都受资产出售收益、Kwinana收益、汇兑收益影响,EV/EBITDA又混了日期。把盈利基础换成130亿至140亿日元的经营区间,有效市盈率为10至11倍,加上5%的股息率。这个折价的合理性,必须由转化来证明,不是资产价值。
同一个盈利区间也连着利润率问题:转化体现为营业利润高于该区间,没有出现就说明折价合理。JFE的持股加上防御政策,使控制权市场基本不存在,所以重估的渠道只剩兑现和资本政策,折价的一部分是结构性的。
09.3|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧
安全边际建立在账面和股息上,不是变现价值。不动产这个明显的储备大部分已经实现:土地从94.49亿日元降到87.81亿日元,租赁性质的“其他”分部从2027年3月期取消,一季度剩余租金收入0.21亿日元记入营业外;剩下投资有价证券129.83亿日元(2026年6月为145亿日元左右,估值储备71.56亿日元)和按历史成本入账的经营用土地。有价证券中交叉持股与财务投资的构成、土地评估价均未披露。
权益约为市值的127%,资产负债表较厚;但490亿日元的商誉和无形资产是无保护的一侧,压力下出售的实际价值,尤其是专用工厂和商誉,会不同。再次减值会同时压低账面净资产和0.77倍的参照;或有负债没有量化,Kwinana迁厂费用也没有披露。持仓规模应假设折价可能延续数年,防守的逻辑更适合耐心资金。
09.4|预期从股价和预测算术读出,交付只要达到预测就已好于定价
市场预期是从报价和预测算术读出来的,不是一致预期:价格资本化的是经常性区间,没有给转化溢价;管理层维持不变的营业利润预测,暗示内部预期同样克制;按修订预测交付,在经常性盈利上已经好于被定价的预期。差距靠财报收敛,不靠叙事。这对耐心持有者有利,是不对称的。没有找到分析师一致预期,上述看法是从价格走势和预测算术推断的。
10|Kabugami 技术结构
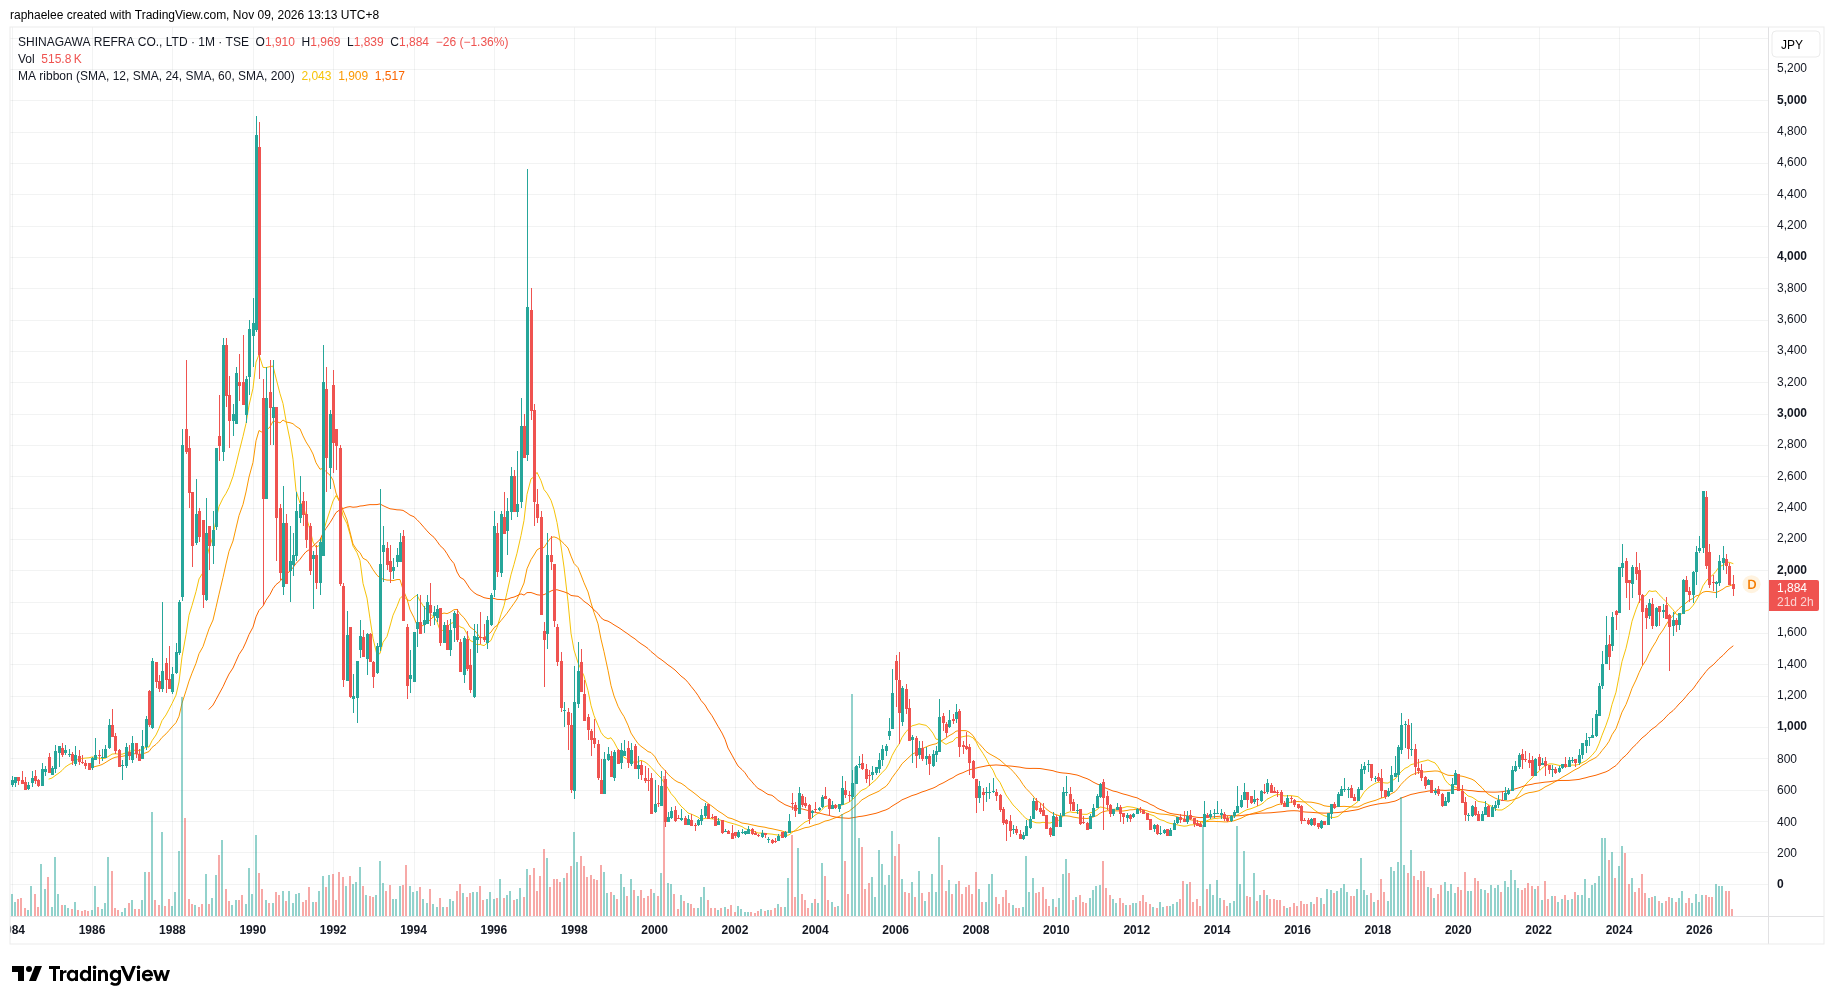
10.1|二十年平台已经突破,但历史高点只被测试一次就被压回
价格结构当前的状态是:历史高点被压回之后,在高位区间等待第一个完整业绩季的检验。
这只股票的技术问题由它的完整上市历史决定。价格在2006至2022年的十几年里,大部分年份在280日元到1,092日元之间运行,成交清淡;2023年向上突破(当年高点1,749日元,收盘1,719日元,成交量大致翻倍),随后逐级抬高,2024年高点2,167日元,2025年高点2,155日元(收盘2,115日元);2026年2至3月冲到历史高点2,507日元,3月当月就被压回,收盘2,036日元,比高点低19%。
此后4至10月,价格在1,824日元到2,158日元之间运行,10月收盘1,951日元。
问题因此是:这一段运行,是三年台阶式上涨的落脚点,可以在上面给业绩定价;还是一次被拒绝的上涨之后的暂停,下一步要回到刚离开三年的平台?
10.2|从254日元跌到平台,再用二十年待在平台里
本章使用2001年1月至2026年10月共310根月线,价格来路分四段。2001至2002年下跌,在2002年12月见到上市以来低点254日元;2003至2005年回升到1,370日元左右;2006至2022年进入平台,大部分年份在280日元到1,092日元之间,成交清淡,这是同类股票里很长的一段横盘,与公司作为国内供应商、面对缩小的钢铁行业的停滞相对应;2023年突破平台,之后随着并购推进上行,到2026年3月触及2,507日元。
三年上涨的质量并不一致。2023至2025年的上行是渐进的、有成交量配合的,质量较好;最后一段冲向2026年3月是尖峰式的。此后的运行是一种协商,不是离开。判断它质量的标准是:运行区间能否经受业绩季,之后再在业绩成交量配合下突破上沿。
10.3|运行区间站了七个月,价格在两年均线附近找平衡
为叙述方便,本章把2026年4月至10月价格在1,824日元到2,158日元之间的运行,称为“运行区间”,下文只用这个名字。
当前价格的重心是24个月均线(1,901日元),10月收盘1,951日元刚好在它之上。12个月均线2,055日元窗口里还含着3月的尖峰,压在短期结构上方;60个月均线1,498日元距离太远,组织不了当前的交易。价格就平衡在两年的重心上。
下方的参照依次是:1,824至1,901日元这一带(运行区间下沿与24个月均线),然后是60个月均线1,498日元,再往下是平台顶部1,370日元左右(2005年高点)。上方是运行区间上沿2,158日元,然后是3月拒绝区2,503至2,507日元,再往上没有任何历史价格。1,370日元到1,498日元之间没有有意义的停留价格带,2023年的上涨穿过这段太快,没有建起一层。
4月至10月的月线幅度收窄,区间宽度17%左右,成交量从6月的调整峰值回到一般水平:高位的轻度压缩,更像是公允价上的犹豫,不像吸筹。3月那次冲击使价格丢了一个月高度就停住,没有像2002年那样连续下跌;之后可见的承接,就是运行区间本身:买盘在1,824至1,951日元带出现,成交量正常。
10.4|高点的失败脉冲留下记忆:卖出过一次的故事,值多少
这只股票的价格记忆分四层:二十年的平台,教会两代持有者这只股票不动;2023年的突破,把它重估为一只并购故事;2026年3月的被拒绝,说明故事在价格最高处,一个月内就值得少19%;此后安静的运行区间,是股价在等业绩而不是等叙事。最深的记忆是平台,一旦运行区间守不住,它就是引力井。
2026年3月的这根线(高点2,507日元,收盘2,036日元)是主导的失败脉冲:只要没有一个月线收盘在业绩兑现支持下超过2,507日元,这个价位就代表“故事被完全相信时”的价格。它的失败有序,进入了七个月的运行区间,而不是退回平台,说明它不是纯投机的见顶。
恢复半衰期在这里不是主要概念,因为价格接近上市高点,不是在从下跌中恢复;更重要的是这次拒绝的衰减:七个月后价格仍保有高点高度的78%(1,951日元对2,507日元),比失败的投机尖峰通常的衰减慢,符合持有者买的是并购故事而不是尖峰。
价格对好消息和坏消息的响应不对称,方向有信息量:3月的冲高吸收了全年最好的消息(创纪录销售、资产出售收益),仍比高点低19%收盘,好消息在高处被卖掉;8月一季度不及预期(营业利润下降39.9%)和11月6日财报前的下跌(下降4.94%)都只带来有序、有限的回落,没有恐慌。这个名册在高位怀疑,在低位相对平静,像是价值型持有者垫在投机外壳之下。
返回形态是平台突破型:很长的平整底部、三年陡峭上涨、顶部尖峰被拒绝、再横向运行。不像台阶式上涨,中间的支撑层很少;上涨速度本身是结构弱点,因为信心完全丧失时,在60个月均线(比10月收盘低23%)之前没有落脚点。
10.5|价格结构的变化早于后来被公开确认的基本面变化,现在两者指向同一个日期
在上面的纯价格状态形成之后,再把价格和公开的基本面事件对照,只看价格怎样响应,事件本身不构成技术证据。
价格结构的变化早于后来被公开确认的基本面变化。2023年的突破先于账目确认并购带来的规模;2026年3月的被拒绝先于2027年3月期一季度利润率不及预期被公开确认。
2026年内几次事件的价格响应,也勾出这个名册的性格:3月在创纪录业绩的消息月里冲高回落;4月减值预告之后,5月业绩公布时价格有序消化;8月一季度不及预期,运行区间内能够承受;11月6日在没有披露的情况下下跌4.94%,与中期决算前的仓位调整相符,收盘1,847日元,仍在1,824日元之上,但低于两年均线1,901日元。
图表和账目现在汇合到同一个问题:下半年的恢复是不是真的。价格在两年重心上,恰好站在两种回答之间。数日内公布的中期决算是下一个公开的基本面事件,也是价格响应的下一次观察点;它是运行区间第一次完整的检验,使这个技术状态异常依赖一个有日期的基本面输入。后续价格的响应,只能作为技术上的证据,不改变上述纯价格状态。成交稀薄、融资买盘偏单边,可能放大这次响应。
10.6|高度与证据之间的矛盾:确认条件和失效条件
结构上的内在矛盾是高度与证据:价格处在25年上市历史的上四分之一,靠的是账目确认了的规模和账目否定了的利润率;最近的结构性支撑离10月收盘价只有5%,有意义的支撑(60个月均线)则在23%之外。高度在倍数上不高(0.77倍净资产),在结构上又很高(脚下是几十年的平台)。
三个月线参照是观察指标:运行区间下沿与24个月均线(1,824至1,901日元)衡量高度能否保住,60个月均线(1,498日元)衡量上涨是否完整,2026年3月高点(2,507日元)衡量能否延续。目前没有一个触发结构性判断,下沿这个观察指标是最接近的一个,在10月收盘价下方5%左右。
什么会确认: - 月线收盘在2026年11月中期决算和2027年2月第三季度财报期间守住1,824至1,901日元,使运行区间下沿变成被捍卫的价位。 - 月线收盘在业绩成交量配合下站上运行区间上沿2,158日元,从底部而不是从尖峰重新打开拒绝区。 - 2026年全年最低价不低于1,824日元,2027年的低点又高于它,使运行区间成为这一结构新的平台。
什么会推翻: - 月线收盘跌破1,824日元,运行区间下沿失守,高度保持的判断失效。 - 月线收盘跌破60个月均线(1,498日元左右),说明2023至2026年的上涨被交还。 - 放量重回平台顶部1,370日元左右,两个十年的平台重新成为有效结构。
对技术判断本身把握一般:中期决算发布后的价格响应不在已有数据之内;融资买盘(7月数据买入19.38万股、卖出800股)此后是否已经释放,也不清楚。
11|风险与催化剂
11.1|下半年恢复要靠三项还没有兑现的假设
公司预测的下半年恢复,叠了三项假设:一是耐火材料里原料涨价转嫁到价格上,一季度毛利率20.1%(上年25.2%)还看不到转嫁;二是海外关联公司设备故障已排除、在手订单恢复;三是Reframax把一季度推迟的项目确认入账,并把通胀成本转嫁出去。每一项都是管理层对未来的陈述,不是已观察到的结果。
单看都合理,合起来要求很高:任何一项落空,都会下调预测,并削弱转化的叙事。客户价格谈判和Reframax与主要客户的转嫁约定都没有披露。上半年和第三季度的数字,是这三项假设的验证点。
11.2|再次减值是还没有关上的风险
490.65亿日元的商誉和无形资产,占净资产四成上下,依附于同一批被收购的现金流,这批现金流在2026年3月期已经带来减值,2027年3月期一季度又让Reframax亏损9.88亿日元。日本会计准则下的摊销并不排除再次减值,若项目经济性再度落空,会冲击账面净资产和0.77倍的参照,折价能否持续也成为空头的论据。可回收性取决于没有单独披露的被收购单位现金流。
11.3|成交稀薄,加上融资买盘偏单边,会放大财报前后的价格反应
11月6日成交15.54万股,金额2.87亿日元左右,相对870.8亿日元的市值很薄。2026年7月中旬的融资余额显示,买入19.38万股,卖出800股(差242倍),说明夏天偏向单边杠杆做多,而此后股价下跌。如果中期决算令人失望,这类仓位会放大跌幅。融资余额的日期是7月,之后可能已变化。
11.4|中期决算是最近的验证事件,要看第二季度做出27.64亿日元营业利润
上半年中期财报是最近的验证事件。前两年分别在2024年11月7日和2025年11月11日发布,到2026年11月9日还没有公布,预计数日内披露;日期是按公司自己的发布节奏推断,内容在公布前无法知道。它要回答:第二季度是否做出倒推所需的27.64亿日元营业利润(一季度17.36亿日元),以及Reframax是否回到盈利。这是一个有日期的答案,而不是无限期的等待。
11.5|第七次中期经营计划会显示利润率目标是否诚实重设,以及价格低于净资产时是否回购
第七次中期经营计划预计2027年5月随2027年3月期决算公布,是治理意义上的催化剂:它会显示Vision 2030的各项目标,在第六次计划利润不及预期之后是否还留着;资本政策是否在DOE股息之外增加回购(先例:2024年3月期回购1,220,800股,22.4亿日元)。具体时间和内容尚未公布。
11.6|2026年10月的小额投资,是增长业务从叙述变成产能的第一步
2026年10月22日公布的投资金额8.5亿日元左右,用于精细陶瓷烧成和精密加工产能,以及Isolite的高功能隔热材料产能。金额不大,但投产后,隔热和先进材料这个期权会在2028年3月期里从叙述变成产能。公告只读了金额层面的摘要,回报没有披露。
12|反常识发现
这家公司没有一个隐藏的单一机制,值得并排看的是几处表面数字和实质方向相反的地方。
其一,“债务还清”只说对一半。出售不动产的收益带来一张171.43亿日元的税单,结算后短期借款从166.22亿日元回升到260.41亿日元,借款总额503亿日元左右,又回到2025年3月期的水平:资产出售修复的资产负债表,被它自己的税款部分拿了回去。
其二,增长的指定引擎是落后者。计划围绕的隔热和先进材料低于计划,超额的是耐火材料和计划里没有的Reframax工程,而工程是收入最难重复的一块。
其三,JFE Steel是同一条线上的客户、股东和治理约束。需求的稳定,就是独立性的上限,二者无法分开买到。
13|下一次值得跟踪什么
13.1|最重要的三个问题都等同一份中期财报
最优先的三个问题,答案都在即将公布的中期财报里,它们决定转化论点是否成立。
第一,上半年累计营业利润相对45亿日元的预测是多少,130亿日元的全年预测是否撑得住?这直接决定判断是继续被检验,还是被推翻;该财报在冻结时尚未公布,到时看2027年3月期中期短信即可。
第二,Reframax在第二季度是否回到盈利,8月修订所假设的通胀成本转嫁,是否真的与主要客户谈成?它是下半年预测里最大的单项变数;项目层面披露有限,可能只看到分部利润。
第三,一季度毛利率下降(20.1%对25.2%)中,有多少是价格修正在下半年能够追回的原料成本,有多少是Reframax产品结构和海外设备故障?它决定利润率压缩是周期性滞后还是结构性摊薄;证据来自上半年和第三季度的毛利率。
这三项目前没有合理的公开路径可以提前取得,都是评审日之后才公布的披露。
13.2|Ako减值、第七次计划和海外销售比例,决定资本配置判断的来龙去脉
Ako工厂到底减了什么,为什么重要:它是国内重组的旗舰,投产两年内就减值,答案能区分保守做账和收购过价,也影响东部整合。具体是哪些生产线、什么开工率或需求假设变了?2026年3月期有价证券报告的减值附注可以回答。
第七次中期计划会设什么销售、ROS和ROIC目标,会不会原样保留Vision 2030(销售2,400亿日元、ROS 12%、ROIC 10%、海外比例50%)?在第六次计划利润落空之后,用一个有时间表的ROS路径来替代,还是悄悄改口径,是对管理层诚信的治理检验,也是更长周期估值的锚;这是未来的披露,目前没有公开路径。
2026年3月期实际海外销售比例是多少,2027年3月期隐含多少,对比计划45%?这是计划最显眼的指标,财报没有披露,可能出现在有价证券报告或统合报告书里,这两份没有读取。同一个缺口见于计划兑现一节。
13.3|回购、股东名册和Kwinana迁厂,是优先级较低但有重估意义的问题
在DOE 4%以上的渐进式股息下,股价低于净资产时,董事会对回购持什么态度(先例2024年3月期22.4亿日元,库存股已占3.2%)?2027年3月期有价证券报告的完整股东名册,会不会显示JFE Steel 34.9%的锚定结构有变化,或出现机构投资者?它们是价格低于净资产时的潜在重估杠杆,董事会的标准和名册尚未披露。
Kwinana迁厂的完成时间表和预期补偿是多少,2027年3月期到2028年3月期还会不会有进一步的收益或费用?这是已记入利润之下的一个未量化的尾巴,优先级较低,一季度财报没有量化。
13.4|竞争位置和下行保护里还有没量化的缺口
全球份额和竞标胜率没有量到,所以收购来的位置能否转成利润,下次要看有没有独立的份额序列和竞争对手数据。或有负债、土地评估价、Kwinana迁厂成本没有量化,所以下行保护只能建立在账面上,压力下的实际变现价值需要更多披露。价格方面的确认和失效条件,见第10章。
14|Kabugami 评分卡
14.1|总分59.25/100,评级B:资产负债表和估值撑着,利润转化和治理拖着
Kabugami评分V3.2的总分是59.25/100(八个模块的得分之和,满分100),对应评级B(B档为55至64.9分)。
判断上,资产负债表和估值是加分项:47.1%的自有资本比率、没有增发、0.77倍净资产和5%左右的股息,给出了较厚的底。拖分的是盈利转化和治理:规模扩张没有换来利润,JFE Steel使需求稳定和独立性绑在一起。
行动结论与第00章一致:暂不追高。已持有者可继续持有并以中期决算为检验点,尚未持有者等决算公布后看上半年营业利润是否达到45亿日元、Reframax是否回到盈利、毛利率是否回升,再决定是否分批建仓,并按耐心资金对待折价可能长期存在的情形;若上半年利润明显低于预测并下调全年预测,或再次出现减值,应重新评估。对结论把握一般,因为中期决算和第七次中期经营计划都在评审日之后才公布。
14.2|八个模块的得分和一句理由
| 模块 | 得分/满分 | 一句理由 |
|---|---|---|
| 财务韧性与下行防御 | 8.84/13 | 自有资本比率47.1%、没有增发;但税款使短期借款回升,商誉和无形资产占净资产四成上下 |
| 竞争优势与结构耐久性 | 8.68/14 | 耗材续约和现场关系保护耐火材料利润;海外平台仍在证明自己,没有份额和客户流失数据 |
| 盈利质量、现金转化与资本效率 | 8.50/17 | 经常性营业利润130亿至140亿日元、现金转化良好;利润率下滑,ROIC低于目标 |
| 商业结构、产品、客户与关键依赖 | 5.72/11 | JFE Steel约占销售30%、稳定需求;增长来自最难重复的工程和海外项目 |
| 估值与安全边际 | 10.50/15 | 0.77倍净资产、5%左右股息,价格不为转化付溢价;折价可能持续多年 |
| 资本配置与股东回报 | 5.80/10 | DOE股息、没有增发;收购定价纪律和低于净资产时是否回购尚无答案 |
| 治理、所有权与管理层 | 3.15/7 | 业务整合而董事会不整合,防御政策去掉了外部纪律 |
| Kabugami 技术结构 | 8.06/13 | 旧平台已失去约束,但高位运行区间只有七个月,尚未经历完整业绩季 |
| 合计 | 59.25/100 | 评级B |
14.3|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 8.84 | 资产负债表是这个案子里最扎实的部分。截至2026年6月底自有资本比率47.1%,净资产1,101.66亿日元,没有增发股份,收购借款大部分用出售不动产的收入还清。但这份修复只完成了一半:出售收益带来的税款约171.43亿日元,年底还有149.37亿日元未缴,6月前付清,短期借款又从166.22亿日元升到260.41亿日元,借款总额约503亿日元,基本回到2025年3月期水平。另有商誉和无形资产约490.65亿日元,占净资产约四成,这是下行时最没有保护的一块。 |
| 竞争优势与结构耐久性 | 14 | 8.68 | 耐火材料是每炉都要消耗的耗材,中途更换供应商会带来炉况和停产风险,这种资质和现场关系让品川リフラ在日本钢铁客户中享有长期、可续的利润。2026年3月期耐火材料部门销售1,109.01亿日元、利润85.75亿日元,是全集团的利润基本盘。但这个优势主要在国内成立,海外收购来的平台仍在证明自己;公司没有量化自己的护城河,也没有可核对的全球份额,竞争位置主要是从规模、网点和收购记录推断。 |
| 盈利质量、现金转化与资本效率 | 17 | 8.5 | 2026年3月期净利润260.71亿日元(同比增166.6%,每股571.45日元)不是常态盈利:其中包含372.45亿日元固定资产出售收益,被97.16亿日元减值部分抵消;营业利润仅增2.5%至136.09亿日元。可持续的盈利水平大约在130亿至140亿日元的营业利润区间。销售从约1,440亿日元升到1,777亿日元,营业利润却基本持平,利润率从约9.2%降到7.7%,公司预测2027年3月期降到6.6%。经营现金流138.61亿日元与营业利润匹配,现金转化本身没有问题;汇兑收益(2026年3月期22.16亿日元)和Kwinana征收收益(37.65亿日元,2027年3月期第一季度)则抬高了账面利润。资本回报方面,计划目标是ROIC 10%,但在商誉进入资本基数后,实际明显偏低。 |
| 商业结构、产品、客户与关键依赖 | 11 | 5.72 | 需求结构有稳定的一面,也有集中和波动的一面。JFE Steel既是持有34.9%表决权的最大股东,又是最大客户:2026年3月期交易额530.59亿日元,约占合并销售30%,年末应收130.92亿日元。这既是需求保险,也是独立性的上限。国内需求取决于钢铁产量,2026年3月期下降3.2%;增长因此来自海外并购。工程部门因Reframax(巴西)合并,销售增78.2%,但2027年3月期第一季度部门亏损9.88亿日元,成为波动来源。绝缘材料和先进材料约占销售12%,计划中的重点板块反而低于计划目标,2026年3月期绝缘材料销售177.08亿日元(计划220亿)、先进材料41.01亿日元(计划54亿)。 |
| 估值与安全边际 | 15 | 10.5 | 2026年11月6日收盘1,847日元,市值约870.8亿日元,市净率0.79倍(按2026年3月期末每股净资产)或0.77倍(按2026年6月底每股净资产2,414.18日元),预测股息收益率约5.1%(95日元),预测市盈率8.03倍。但预测每股利润230.10日元包含Kwinana收益,若以约130亿日元的经常性营业利润按税后计算,实际倍数约10至11倍。EV/EBITDA约5.7倍。价格已经不为利润率恢复付溢价,也没有按崩塌定价;折价的合理性取决于转化能否发生。 |
| 资本配置与股东回报 | 10 | 5.8 | 从2027年3月期起,派息方针由40%派息率改为以净资产股息率(DOE)4%以上为下限的渐进式派息,2027年3月期预计95日元(中期47日元、期末48日元),约43亿日元,约占经营现金流三分之一。2026年3月期派息90日元、派息率仅15.7%,因为出售不动产的资金被用来还债和收购。没有增发,库存股3.2%,2024年3月期曾回购122.08万股、约22.4亿日元。这套新方针让股息与被资产出售、减值和汇兑扭曲的每股利润脱钩,对等待期间的股东是实实在在的回报。 |
| 治理、所有权与管理层 | 7 | 3.15 | 治理的结构是业务上整合、董事会层面不整合:JFE Steel派来15名人员,但没有董事互相兼任;有效的防御收购政策在2026年5月15日获得续期;对董事的绩效股份奖励规模很小(2026年7月处分33,588股库存股,每股1,873日元)。公司在文件中声明独立,但实际依赖是结构性的,防御政策又去掉了可能给这种依赖定价的外部纪律。收购定价缺少外部约束,计划目标(销售超额、利润率未达)说明管理层对规模的兑现好于对利润率的兑现。 |
| Kabugami 技术结构 | 13 | 8.06 | 股价在2006年至2022年的二十年区间(约280至1,092日元)之后,于2023年向上突破,经2024年、2025年逐级走高,在2026年3月触及历史高点2,507日元后当月被压回,收盘2,036日元;此后4月至10月在约1,824至2,158日元的区间内运行,10月收盘1,951日元,位于两年均线(约1,901日元)上方。旧的长期平台已明显失去对价格的约束,但新的高位运行区间只经历了七个月,尚未经历一次完整的业绩季检验,因此属于旧状态弱化可信、新状态尚未确立。11月6日在没有披露的情况下下跌4.94%,收盘1,847日元,已低于该区间下沿,需要关注是否带来区间被突破的确认。 |
总分: 59.25 / 100 评级: B 操作建议: 暂不追高。基本面上,约130亿至140亿日元的经常性营业利润、47.1%的自有资本比率和以净资产为基准的约5%股息提供了较厚的底,但规模扩大尚未转化为利润,中期决算(预计近日公布)是第一个实质检验。已持有者可继续持有并以中期决算为检验点;尚未持有者宜等决算公布后,看上半期营业利润是否达到45亿日元、Reframax是否回到盈利、毛利率是否回升,再决定是否分批建仓,并按耐心资金对待折价可能长期存在的情形。若上半期利润明显低于预测并下调全年预测,或再次出现减值,应重新评估。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|主要来源和日期:公司披露为主,行情与数据汇总站辅助
本报告的评审日为2026年11月9日。基本面主要依据公司自己的披露:2025年3月27日的商号变更公告;2024年5月13日公布的Vision 2030和第六次中期经营计划;2026年3月期财报(业绩快报,2026年5月15日);2026年6月25日的控股股东事项公告;2027年3月期一季度财报与预测修订公告(均为2026年8月10日);2026年10月22日的资本投资公告;以及公司英文官网和统合报告书。
这些披露多经IRBANK(行情与适时披露索引)取得,股价与估值数据取自IRBANK 2026年11月6日页面;公司官方英文名称SHINAGAWA REFRA CO., LTD.经官网、统合报告书与章程变更公告相互印证。
价格结构依据2001年1月至2026年10月的月线价格历史(以Yahoo Finance图表口径整理的本地序列,与IRBANK按拆股调整的年度价格区间一致,含2026年3月高点2,507日元),以及2026年11月6日的日线收盘价。月线序列的数据截至2026年10月27日,10月这根月线可能不含当月最后几个交易日。
15.2|证据的限制和未能确认的事项
以下事项在评审日无法确认,相关判断因此带有限定:
- 2027年3月期上半年中期财报在评审日尚未公布(日期按前两年节奏推断),第七次中期经营计划尚无内容;所有推翻条件都依赖这些之后才公开的数字。
- 没有找到分析师一致预期,市场预期是从价格和预测算术推断的;10至11倍的有效市盈率和130亿至140亿日元的经常性区间,是依据披露项目的研究推算,公司没有公布基础利润。
- 估值口径混用:EBITDA取2026年3月期,净负债取2026年6月,市值按发行股数含库存股,PBR随净资产日期而异。
- 2026年3月期有价证券报告的前十大股东没有重新读取,大股东以外的名册不明;2026年10月22日投资公告只读了金额层面的摘要。
- 融资买盘余额为2026年7月数据,此后可能已变化。
- 没有独立的全球耐火材料市场规模、份额和竞争对手数据;收购价格、授信条件、或有负债、土地评估价、Kwinana迁厂成本均未披露。
本报告基于公开资料,用于研究目的,不构成买卖建议;投资者需自行判断并承担风险。提供给本报告的材料中,没有需要披露的利益冲突事项。
主要资料来源
- Trade-name change notice (27 March 2025): new legal name and registered English name, effective 1 October 2025
- Official English website and Integrated Report 2025: English name, headquarters and founding
- FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering
- Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment
- Gouda Refractories Group acquisition notices (24 October 2024) on the disclosure index
- Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit
- Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale
- Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets
- IRBANK stock page snapshot for 5351 (6 November 2026)
研究发现索引
展开本次 Review 的 93 项研究发现
F001|研究发现
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论15|主要来源和日期:公司披露为主,行情与数据汇总站辅助
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Trade-name change notice (27 March 2025): new legal name and registered English name, effective 1 October 2025怎么使用:直接 / 支持;一手验证:01、33
Official English website and Integrated Report 2025: English name, headquarters and founding怎么使用:直接 / 支持;一手验证:01
Company profile: headquarters, capital, leadership and listing怎么使用:直接证据;一手验证:27;专项深挖:01、27;同业比较:01;其他用途:历史
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接 / 支持;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域33)|Trade-name change notice (27 March 2025): new legal name and registered English name, effective 1 October 2025;直接证据 / 支持证据 / 一手证据(研究域01)|Official English website and Integrated Report 2025: English name, headquarters and founding;直接证据 / 一手证据(研究域27) / 历史/同业比较(研究域01) / 定向深挖(研究域01) / 定向深挖(研究域27)|Company profile: headquarters, capital, leadership and listing;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering
完整研究记录(核对用)
研究原文:Shinagawa Refra Co., Ltd. (formerly Shinagawa Refractories; renamed 1 Oct 2025; official English name SHINAGAWA REFRA CO., LTD.; TSE Prime and Sapporo, code 5351, founded 1875, capital JPY 3,300m, president Hiroyuki Fujiwara) is a refractories-centred group in four segments (refractories, insulation materials, advanced materials, engineering) selling heat-management products and furnace construction mainly to steel and other high-temperature industries. JFE Steel is the 34.9% anchor holder.
内部研究类型:company_identity_perimeter
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Defines the investable perimeter: a JFE-affiliated minority claim inside a 150-year-old consumables franchise mid-globalisation; the name change means vendors still mix old and new names.
不确定性(原始记录):Full top-ten register beyond the anchor was not re-read; legal identity otherwise well supported by agreeing primary filings.
F002|02|耐火材料每烧一炉磨损一次,工程业务把销量和波动一起带来
研究范围:开放研究+35项覆盖检查
写入正文:02|耐火材料每烧一炉磨损一次,工程业务把销量和波动一起带来
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment怎么使用:直接证据;一手验证:02;专项深挖:02、15
FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope怎么使用:直接证据;一手验证:16;同业比较:29;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment;直接证据 / 一手证据(研究域16) / 历史/同业比较(研究域29)|FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope
完整研究记录(核对用)
研究原文:The model sells a consumable (refractories wear out with every heat) plus the engineering to install it, increasingly as a global package. FY3/26 segment sales/profit (JPY m): refractories 110,901/8,575; insulation 17,708/2,480; advanced materials 4,101/-115; engineering 45,856/2,714. Materials margin is the annuity; engineering is the volume and variance engine and is now about a quarter of group sales (Q1 FY3/27 external sales 11,431 of 46,590).
内部研究类型:business_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Earnings quality now depends on Brazilian project execution as well as domestic price correction: a wider, less predictable base than the old domestic model.
不确定性(原始记录):Inter-segment transfer pricing, commodity-versus-differentiated product split and product-level pricing are not disclosed.
F003|06|260亿日元净利润是一次资本运作,不是常态盈利
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|260亿日元净利润是一次资本运作,不是常态盈利09|估值要从净利润换到经常性盈利:8.03倍看起来比实际便宜14|总分59.25/100,评级B:资产负债表和估值撑着,利润转化和治理拖着
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:直接 / 支持;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base怎么使用:直接证据;一手验证:28;专项深挖:28;同业比较:02、09、12、15、17、27、33、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost;直接证据 / 一手证据(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 历史/同业比较(研究域27) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35) / 定向深挖(研究域28)|FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base
完整研究记录(核对用)
研究原文:FY3/26 net income of JPY 26,071m (+166.6%, EPS JPY 571.45) is a capital-recycling event, not recurring earnings: it contains a JPY 37,245m gain on fixed-asset sales offset by JPY 9,716m impairment, while operating profit grew only 2.5% to JPY 13,609m. The recurring centre is a JPY 13-14bn band at both the operating line and ordinary profit excluding JPY 2,216m of exchange gains.
内部研究类型:normalized_earnings_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Valuation on printed FY3/26 EPS would overstate earnings power by roughly half; capitalise the operating band, not the net line.
不确定性(原始记录):No company-published underlying-profit measure; the band is this research's construction from disclosed items.
F004|06|260亿日元净利润是一次资本运作,不是常态盈利
研究范围:开放研究+35项覆盖检查
写入正文:06|260亿日元净利润是一次资本运作,不是常态盈利
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Foreign-exchange gains inside ordinary profit: FY3/2026 and Q1 FY3/2027怎么使用:直接 / 支持;一手验证:06、14、32;外部现实校验:10;反向验证:28;专项深挖:06、14
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:直接 / 支持;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域32) / 外部现实(研究域10) / 反证(研究域28) / 定向深挖(研究域06) / 定向深挖(研究域14)|Foreign-exchange gains inside ordinary profit: FY3/2026 and Q1 FY3/2027;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost
完整研究记录(核对用)
研究原文:Foreign-exchange gains are now a structural, volatile flatterer of ordinary profit (JPY 2,216m in FY3/26; JPY 1,175m in Q1 FY3/27 alone versus JPY 62m a year earlier, the difference between ordinary profit -2.8% and a fall in line with operating profit -39.9%). Read ex-exchange gain, the ordinary and operating lines tell the same flat story.
内部研究类型:profit_quality_component
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Translation noise inflates trend readings on the ordinary line; it is variance, not solvency risk.
不确定性(原始记录):Hedging policy and sensitivity are not disclosed.
F005|06|销售上涨23.4%,是合并范围变了,不是国内销量涨了
研究范围:开放研究+35项覆盖检查
写入正文:06|销售上涨23.4%,是合并范围变了,不是国内销量涨了
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接 / 支持;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接 / 支持;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop怎么使用:直接 / 支持;一手验证:05、11、12;外部现实校验:02、15、19
Gouda Refractories Group acquisition notices (24 October 2024) on the disclosure index怎么使用:直接证据;反向验证:09;专项深挖:09、25;同业比较:07、25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 外部现实(研究域02) / 外部现实(研究域15) / 外部现实(研究域19)|FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop;直接证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域25) / 反证(研究域09) / 定向深挖(研究域09) / 定向深挖(研究域25)|Gouda Refractories Group acquisition notices (24 October 2024) on the disclosure index
完整研究记录(核对用)
研究原文:FY3/26 sales rose 23.4% to JPY 177,738m because the consolidation perimeter changed (full year of Gouda from the October 2024 acquisition; Reframax from May 2025; Danieli JV and Dynamix added), not because the domestic volume pool grew: domestic crude steel fell 3.2% to 80.33 Mt and refractories volume declined. Gouda carried refractories sales +15.7% on falling volumes, together with price correction and mix.
内部研究类型:growth_quality_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Headline growth must be decomposed: scope, price and volume contributed very differently, and acquired sales are not evidence of organic demand.
不确定性(原始记录):Purchase prices and contingent consideration for the 2024-2026 acquisitions are not in the materials read.
F006|01|规模已经买到手,利润还没有跟上
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|规模已经买到手,利润还没有跟上06|毛利率守住了,费用吃掉了规模14|八个模块的得分和一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base怎么使用:直接 / 支持;一手验证:28;专项深挖:28;同业比较:02、09、12、15、17、27、33、35;其他用途:历史
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope怎么使用:直接 / 支持;一手验证:16;同业比较:29;其他用途:历史
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接 / 支持;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 历史/同业比较(研究域27) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35) / 定向深挖(研究域28)|FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域29)|FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix
完整研究记录(核对用)
研究原文:Operating profit has been flat on rising sales: about JPY 13.3bn (FY3/25), 13,609m (FY3/26), 13.0bn forecast (FY3/27) against sales of about 144.0, 177.7 and 198.0bn; operating margin compresses from about 9.2% to 7.7% to a forecast 6.6%. Gross margin held at 24.2% in FY3/26 while SG&A rose about JPY 7.5bn to JPY 29,380m with the Gouda and Reframax consolidations and goodwill amortisation: gross economics were intact and overhead absorbed the expansion.
内部研究类型:margin_trajectory_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The expansion has so far been bought at the margin line; acquisitions have replaced domestic decline rather than added profit.
不确定性(原始记录):Whether the FY3/27 recovery assumptions (pass-through, equipment, Reframax) deliver is unobservable before the H1/Q3 prints.
F007|06|只有合并口径有意义,母公司数字混了资产出售
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 results (tanshin): parent-only results against consolidated
完整研究记录(核对用)
研究原文:Parent-only FY3/26 sales were JPY 86,957m, less than half of consolidated JPY 177,738m, while parent net income was JPY 31,323m (+318.0%) because the fixed-asset sale gains were booked mainly at the parent: revenue's centre of gravity has moved to subsidiaries and overseas, while the funding gains sit in the parent's books.
内部研究类型:perimeter_shift_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Only consolidated analysis is meaningful; parent figures mix an asset-recycling event with a shrinking share of operations.
不确定性(原始记录):Minority interests (JPY 8,831m of net assets) and intercompany eliminations are not itemised for ordinary-shareholder attribution.
F008|03|国内需求池在缩小,增长只能靠海外买来
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop怎么使用:直接证据;一手验证:05、11、12;外部现实校验:02、15、19
Q1 FY3/2027 narrative: demand conditions by end-market怎么使用:直接证据;一手验证:12;外部现实校验:05、11;专项深挖:05、12
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 外部现实(研究域02) / 外部现实(研究域15) / 外部现实(研究域19)|FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop;直接证据 / 一手证据(研究域12) / 外部现实(研究域05) / 外部现实(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域12)|Q1 FY3/2027 narrative: demand conditions by end-market
完整研究记录(核对用)
研究原文:The domestic demand pool is Japanese steel: crude steel output 80.33 Mt in FY3/26 (-3.2%) and 20.35 Mt in Q1 FY3/27 (+1.0%); refractory consumption follows output and relining schedules, with export and construction demand weak and automotive and industrial-machinery demand improving. The domestic core faces a structurally shrinking volume pool offset only by price correction and mix.
内部研究类型:end_market_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Set domestic volume expectations to zero; all growth in the case is share, scope or mix. Industry cycle amplitude is small relative to the group's self-made variance.
不确定性(原始记录):The H2 FY3/27 steel environment is unobservable at freeze; no independent global refractories market sizing was obtained.
F009|06|下半年要赚85亿日元:预测的算术
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|下半年要赚85亿日元:预测的算术
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged怎么使用:直接 / 支持;一手验证:31;专项深挖:31
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接 / 支持;一手验证:35;反向验证:30;专项深挖:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 支持证据 / 一手证据(研究域31) / 定向深挖(研究域31)|Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%
完整研究记录(核对用)
研究原文:The revised FY3/27 forecast (10 Aug 2026) raised sales from JPY 189bn to 198bn while holding operating profit at JPY 13,000m (ordinary 13,000 to 14,000, net 10,000 to 10,500, EPS JPY 230.10; H1 forecast operating profit 4,500m). Arithmetic requires Q2 operating profit of JPY 2,764m (versus Q1 1,736m) and H2 operating profit of JPY 8,500m on sales of JPY 103,000m (about 8.3% margin versus Q1's 3.7%). The revision itself capitalises continued margin dilution: revenue expectations rose, profit expectations did not.
内部研究类型:forecast_arithmetic_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The year's verdict is concentrated in an unprinted second half; an H1-stage cut would reopen the conversion question.
不确定性(原始记录):The H1 print was not public at freeze; whether H2 assumptions are met is unknown.
F010|11|下半年恢复要靠三项还没有兑现的假设
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|下半年恢复要靠三项还没有兑现的假设
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%怎么使用:直接 / 支持
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据|Revision notice (August 2026): the stated second-half recovery mechanics in engineering
完整研究记录(核对用)
研究原文:The forecast's second-half recovery stacks three assumptions: raw-material price pass-through in refractories (not yet evidenced, Q1 gross margin 20.1% versus 25.2%), resolution of an overseas affiliate's equipment trouble and backlog recovery, and Reframax booking projects deferred from Q1 with inflation passed through. Each element is a management assertion about the future, not an observed result.
内部研究类型:risk_assumption_stack
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Individually plausible, jointly demanding: shortfall in any one cuts the forecast and the conversion narrative.
不确定性(原始记录):Customer price negotiations and Reframax's customer agreement on pass-through are not disclosed.
F011|06|一季度毛利率从25.2%掉到20.1%,问题出在毛利这一行
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|一季度毛利率从25.2%掉到20.1%,问题出在毛利这一行
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%怎么使用:直接 / 支持;一手验证:16;反向验证:19;专项深挖:16
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
查看完整证据标签(核对用)
直接证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%;直接证据 / 支持证据 / 一手证据(研究域16) / 反证(研究域19) / 定向深挖(研究域16)|Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering
完整研究记录(核对用)
研究原文:Q1 FY3/27: sales JPY 46,590m (+21.8%) but operating profit JPY 1,736m (-39.9%) and gross margin 20.1% (from 25.2%); gross profit fell in absolute terms (9,371m from 9,655m) while SG&A rose to JPY 7,635m from 6,764m. The event is at the gross line, locating the problem in Reframax project economics, raw-material and fuel inflation, the overseas equipment trouble and insulation mix, not in group overhead. Net income (+166.2%) was rescued by a JPY 3,765m Kwinana expropriation gain and exchange gains.
内部研究类型:profit_quality_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Variance is manufactured in project execution and cost pass-through, which are management-execution variables rather than market givens.
不确定性(原始记录):How much is cost that price correction recovers versus Reframax mix and equipment trouble is not decomposed (Research Debt).
F012|06|一季度毛利率从25.2%掉到20.1%,问题出在毛利这一行
研究范围:开放研究+35项覆盖检查
写入正文:06|一季度毛利率从25.2%掉到20.1%,问题出在毛利这一行
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接 / 支持;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接证据;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment怎么使用:直接证据;一手验证:02;专项深挖:02、15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment
完整研究记录(核对用)
研究原文:Engineering has become the swing segment: Reframax Engenharia (Brazil, consolidated from May 2025, goodwill JPY 9,131m) lifted FY3/26 engineering sales +78.2% and profit +68.1% to JPY 2,714m, then Q1 FY3/27 produced a JPY 988m segment loss (versus -15m) on a major customer's schedule slippage and Brazilian cost inflation. A project-timing exposure of this size can move group operating profit by about a tenth in a quarter.
内部研究类型:segment_volatility_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Reframax is the growth engine and the volatility engine at once; its Brazilian steel project book is the largest single swing in the FY3/27 second half.
不确定性(原始记录):Engineering backlog and project-level margin dispersion are not disclosed.
F013|06|一季度毛利率从25.2%掉到20.1%,问题出在毛利这一行
研究范围:35项覆盖检查
写入正文:06|一季度毛利率从25.2%掉到20.1%,问题出在毛利这一行
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接证据;一手验证:06、14、15;反向验证:16、35
Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment怎么使用:直接证据;一手验证:02;专项深挖:02、15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment
完整研究记录(核对用)
研究原文:Revenue repeatability ranks refractories highest (qualified consumable supply into running furnaces), insulation next, engineering lowest (completion-based, timing-prone) - while growth since the acquisitions ranks almost inversely, so the group's growth is arriving in its least repeatable line and a rising share is overseas and acquisition-borne.
内部研究类型:revenue_quality_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Growth should be discounted for repeatability until Reframax backlog quality is evidenced.
不确定性(原始记录):No revenue disaggregation by contract type or engineering backlog disclosure in the materials read.
F014|03|JFE Steel既是最大客户也是最大股东,需求保险和独立性上限是同一件事
研究范围:开放研究
写入正文:03|JFE Steel既是最大客户也是最大股东,需求保险和独立性上限是同一件事07|业务上整合,董事会上不整合:JFE的影响通过人员和客户关系传导12|几处表面数字与实质方向相反14|八个模块的得分和一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接 / 支持;一手验证:05、07、10、23、24
IRBANK timely-disclosure index for 5351: takeover response policy and performance share units怎么使用:支持证据;同业比较:23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;支持证据 / 历史/同业比较(研究域23)|IRBANK timely-disclosure index for 5351: takeover response policy and performance share units
完整研究记录(核对用)
研究原文:JFE Steel holds 34.9% of voting rights directly (JFE Holdings 34.9% indirectly; the company is JFE Steel's equity-method affiliate) and is the largest customer: FY3/26 transactions of JPY 53,059m, about 30% of consolidated sales, with JPY 13,092m of receivables outstanding at year-end. Prices are negotiated individually on market terms and independence is asserted. The equity link and the demand link are the same link: demand insurance in a shrinking market and a hard ceiling on independence.
内部研究类型:customer_shareholder_dependency
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Minority holders are in substance junior partners of the JFE group's refractory supply chain; steel-group decisions at JFE Holdings transmit into this register.
不确定性(原始记录):Sales to JFE group companies beyond JFE Steel itself are not separately disclosed; the anchor's long-term intentions are unknown.
F015|07|业务上整合,董事会上不整合:JFE的影响通过人员和客户关系传导
研究范围:开放研究+35项覆盖检查
写入正文:07|业务上整合,董事会上不整合:JFE的影响通过人员和客户关系传导14|八个模块的得分和一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接 / 支持;一手验证:05、07、10、23、24
IRBANK timely-disclosure index for 5351: takeover response policy and performance share units怎么使用:直接 / 支持;同业比较:23;其他用途:历史
Q1 FY3/2027 subsequent event: performance share unit disposal of treasury shares怎么使用:直接证据;一手验证:23;专项深挖:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;直接证据 / 支持证据 / 历史/同业比较(研究域23)|IRBANK timely-disclosure index for 5351: takeover response policy and performance share units;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Q1 FY3/2027 subsequent event: performance share unit disposal of treasury shares
完整研究记录(核对用)
研究原文:Governance geometry is operational integration without board integration: 15 JFE Steel secondees, zero officer interlocks, a large-scale purchase response policy (takeover defence) continued on 15 May 2026, and director performance-share compensation (33,588 treasury shares disposed 24 July 2026 at JPY 1,873). Influence runs through people in the business and through the customer relationship; the filings can honestly assert independence while dependence remains structural, and the maintained defence removes the external discipline that might price that dependence.
内部研究类型:governance_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Any re-rating must come from delivery and capital policy, not from contestability; acquisition pricing faces no external check.
不确定性(原始记录):Board composition and independence detail and succession planning were not pursued; PSU amounts are financially immaterial.
F016|07|除了JFE,股东名册上还有谁,目前不清楚
研究范围:35项覆盖检查
写入正文:07|除了JFE,股东名册上还有谁,目前不清楚13|回购、股东名册和Kwinana迁厂,是优先级较低但有重估意义的问题15|证据的限制和未能确认的事项
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Ownership beyond the anchor: what the controlling-shareholder filing does and does not show怎么使用:直接证据;一手验证:24;反向验证:01、23;专项深挖:24
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接证据;一手验证:05、07、10、23、24
Q1 FY3/2027 results (tanshin): share counts and capital怎么使用:直接证据;一手验证:25;同业比较:01、24;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域23) / 定向深挖(研究域24)|Ownership beyond the anchor: what the controlling-shareholder filing does and does not show;直接证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域01) / 历史/同业比较(研究域24)|Q1 FY3/2027 results (tanshin): share counts and capital
完整研究记录(核对用)
研究原文:Beyond the anchor, the ownership register is not established in this research: treasury shares are 1,513,710 (3.2% of 47,146,830 issued); float is at most about 62% before any stable corporate holders; the identity and size of holders ranked second and below are unknown.
内部研究类型:research_boundary_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Pricing is set by the marginal domestic holder against a fixed anchor backdrop; a register change would be a re-rating event.
不确定性(原始记录):Top-ten register of the FY3/26 securities report not re-read; carried as stated gap.
F017|07|计划与兑现:规模超额完成,利润率没有
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接 / 支持;一手验证:08、09、11、13;同业比较:30;其他用途:历史
FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets怎么使用:直接 / 支持;反向验证:22
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines怎么使用:直接证据;一手验证:22;专项深挖:22
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets;直接证据 / 支持证据 / 反证(研究域22)|FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines;直接证据|FY3/2026 tanshin: management's framing of the final plan year
完整研究记录(核对用)
研究原文:Scale beat the 6th plan and margin missed it: FY3/27 forecast sales of JPY 198bn exceed the plan's final-year target of JPY 180bn, but forecast operating profit of JPY 13.0bn is roughly two-thirds of the about JPY 19.8bn implied by the 11% ROS target (FY3/26 ROS 7.7%, forecast 6.6%); ROIC 10% against a 6.5% capital-cost benchmark is similarly unmet on simple computation. Vision 2030 extends sales JPY 240bn, ROS 12%, ROIC 10%, overseas ratio 50%. The offsets delivered revenue, not margin; the annual filing does not restate the plan targets against the new forecast.
内部研究类型:strategy_delivery_divergence
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The plan is the measuring rod for the conversion thesis; its pattern (scale by acquisition, margin undelivered) is the prior for how much of Vision 2030 to capitalise.
不确定性(原始记录):The 7th plan's targets and treatment of Vision 2030 are not yet published.
F018|03|被计划当作增长引擎的两个板块,反而落在计划后面
研究范围:35项覆盖检查
写入正文:03|被计划当作增长引擎的两个板块,反而落在计划后面12|几处表面数字与实质方向相反
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
6th plan sector targets for FY2026 against FY3/2026 actual segment results怎么使用:直接 / 支持;反向验证:02、03;专项深挖:08、33;同业比较:08;其他用途:历史
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接 / 支持;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域08) / 反证(研究域02) / 反证(研究域03) / 定向深挖(研究域08) / 定向深挖(研究域33)|6th plan sector targets for FY2026 against FY3/2026 actual segment results;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering
完整研究记录(核对用)
研究原文:Delivery against the plan's sector lines is inverted: FY3/26 refractories (JPY 110.9bn versus plan 103.4bn) and engineering (45.9bn versus 24.9bn, on an acquisition the plan did not contain) beat plan, while insulation (17.7bn versus 22.0bn) and advanced materials (4.1bn versus 5.4bn) - the sectors the plan was centred on - undershot. The growth story's designated engines are its laggards.
内部研究类型:counter_evidence_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Mix-shift upside is unproven; present economics rest on steel-adjacent and acquired lines.
不确定性(原始记录):Recovery in Q1 FY3/27 (insulation +6.9%, advanced materials +21.0%) is one quarter.
F019|03|被计划当作增长引擎的两个板块,反而落在计划后面
研究范围:开放研究+35项覆盖检查
写入正文:03|被计划当作增长引擎的两个板块,反而落在计划后面
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/2026 and Q1 FY3/2027 segment record: the growth sectors are still small怎么使用:直接证据;一手验证:03;反向验证:08、11
Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases怎么使用:直接证据;一手验证:04、20;外部现实校验:03
Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment怎么使用:直接证据;反向验证:07
Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment怎么使用:直接证据;专项深挖:04、20;同业比较:04;其他用途:历史
Q1 FY3/2027 narrative: demand conditions by end-market怎么使用:直接证据;一手验证:12;外部现实校验:05、11;专项深挖:05、12
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域03) / 反证(研究域08) / 反证(研究域11)|FY3/2026 and Q1 FY3/2027 segment record: the growth sectors are still small;直接证据 / 一手证据(研究域04) / 一手证据(研究域20) / 外部现实(研究域03)|Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases;直接证据 / 反证(研究域07)|Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment;直接证据 / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment;直接证据 / 一手证据(研究域12) / 外部现实(研究域05) / 外部现实(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域12)|Q1 FY3/2027 narrative: demand conditions by end-market;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering
完整研究记录(核对用)
研究原文:Insulation and advanced materials (semiconductor, battery and fine-ceramics demand; Isolite Industries, TSE 5358, taken over by tender offer in 2022, anchors insulation) are about 12% of FY3/26 sales and both shrank (insulation profit -24.1%, advanced materials a JPY 115m loss); Q1 FY3/27 showed recovery in sales but advanced materials stayed in loss on Setouchi plant depreciation and insulation profit fell 18.7% on mix. They are an option on the FY3/28 mix rather than current earnings.
内部研究类型:growth_option
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Carried for little in the price; its returns sit beyond the forecast year and the parent-subsidiary listing of Isolite is a standing governance feature.
不确定性(原始记录):Scale of growth lines and returns on the capex are not disclosed.
F020|08|Ako工厂减值是资本配置最大的未解问题
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation怎么使用:直接 / 支持;一手验证:04、20;反向验证:10
Impairment and forecast-revision notice (16 April 2026) on the disclosure index怎么使用:直接证据;反向验证:32;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 反证(研究域10)|6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation;直接证据 / 反证(研究域32) / 定向深挖(研究域32)|Impairment and forecast-revision notice (16 April 2026) on the disclosure index
完整研究记录(核对用)
研究原文:FY3/26 impairment of JPY 9,716m hit the Ako plant (flagship of the domestic monolithic consolidation, operating since June 2024) and two overseas subsidiaries in the same year as record sales; the market learned of it on 16 April 2026, a month before results. The restructuring and acquisition programme is being marked to reality early: either conservative housekeeping at peak scrutiny or evidence of overpayment. The filings do not distinguish the two.
内部研究类型:capital_allocation_signal
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The central capital-allocation question the next plan must answer; it raises the burden of proof on remaining acquired and new assets.
不确定性(原始记录):Affected lines, changed utilisation or demand assumption and identity of the two overseas subsidiaries are not named in the summary lines read.
F021|09|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧11|再次减值是还没有关上的风险
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Goodwill balance and amortisation run-rate at Q1 FY3/2027怎么使用:直接 / 支持;反向验证:06、18、29、35
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域18) / 反证(研究域29) / 反证(研究域35)|Goodwill balance and amortisation run-rate at Q1 FY3/2027;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering
完整研究记录(核对用)
研究原文:Further impairment is a live risk: JPY 49,065m of goodwill and intangibles (about 42% of net assets) rests on the same acquired cash flows that produced the JPY 988m Reframax quarterly loss and the FY3/26 write-downs; Japanese GAAP amortisation does not preclude additional impairment if project economics disappoint again.
内部研究类型:risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Impairment would hit book value and the 0.77x-book anchor of the valuation case; the discount's durability is the bear case.
不确定性(原始记录):Recoverability rests on acquired cash flows not separately reported.
F022|06|商誉490亿日元占着资本,资本回报只在计划里达标
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|商誉490亿日元占着资本,资本回报只在计划里达标
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Goodwill balance and amortisation run-rate at Q1 FY3/2027怎么使用:直接 / 支持;反向验证:06、18、29、35
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接证据;一手验证:18、21、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域18) / 反证(研究域29) / 反证(研究域35)|Goodwill balance and amortisation run-rate at Q1 FY3/2027;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%
完整研究记录(核对用)
研究原文:Goodwill was JPY 28,759m at 30 June 2026 (JPY 28,139m at FY3/26 from 14,957m), other intangibles JPY 20,926m at FY3/26; quarterly amortisation JPY 448m is about JPY 1.8bn a year, roughly 14% of forecast operating profit, recurring for years, and concentrated in Reframax (JPY 9,131m) and the European acquisitions - the units whose delivery the thesis depends on.
内部研究类型:balance_sheet_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Fixed charge inside the margin question and the first place a disappointment would surface as impairment.
不确定性(原始记录):Goodwill recoverability and the acquired units' separate cash flows are not disclosed.
F023|06|资产负债表修复了一半:没有增发,但税单把借款推回去了
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表修复了一半:没有增发,但税单把借款推回去了14|八个模块的得分和一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接 / 支持;一手验证:18、21、29
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接 / 支持;一手验证:17、25;同业比较:19、20;其他用途:历史
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
Q1 FY3/2027 results (tanshin): share counts and capital怎么使用:直接证据;一手验证:25;同业比较:01、24;其他用途:历史
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域01) / 历史/同业比较(研究域24)|Q1 FY3/2027 results (tanshin): share counts and capital;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves
完整研究记录(核对用)
研究原文:The balance sheet absorbed the transformation without equity dilution: equity ratio 47.1% (equity JPY 110,166m at 30 June 2026; BPS JPY 2,414.18; no equity issued, 47,146,830 shares unchanged), acquisition debt largely repaid from property proceeds, interest-bearing debt cut sharply in FY3/26 (short-term borrowings from JPY 24,854m to 16,622m), and equity growing at roughly the dividend rate (Q1 comprehensive income JPY 5,795m). It is the strongest part of the case.
内部研究类型:financial_resilience_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Downside is a long discount and impairment risk, not insolvency; strategy pace is now self-funded.
不确定性(原始记录):Undrawn facility headroom, covenants and facility terms are not disclosed.
F024|06|资产负债表修复了一半:没有增发,但税单把借款推回去了
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表修复了一半:没有增发,但税单把借款推回去了12|几处表面数字与实质方向相反
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Q1 FY3/2027 balance sheet: settlement of the FY3/2026 tax charge怎么使用:直接 / 支持;反向验证:17、25;专项深挖:18;同业比较:18;其他用途:历史
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域18) / 反证(研究域17) / 反证(研究域25) / 定向深挖(研究域18)|Q1 FY3/2027 balance sheet: settlement of the FY3/2026 tax charge;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing
完整研究记录(核对用)
研究原文:The 'debt repaid' headline is incomplete: the FY3/26 tax charge of JPY 17,143m (about 40% effective on pre-tax JPY 43,368m) left unpaid taxes of JPY 14,937m, settled by June 2026 (JPY 551m left), funded by short-term borrowings rising from JPY 16,622m to 26,041m; total borrowings of about JPY 50.3bn at quarter-end were roughly back to the FY3/25 level.
内部研究类型:balance_sheet_qualification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The asset-recycling gain had a cash tax cost; the repair is mid-conversion, like the P&L.
不确定性(原始记录):Refinancing terms of the short-term borrowing are not disclosed.
F025|06|资产负债表修复了一半:没有增发,但税单把借款推回去了
研究范围:35项覆盖检查
写入正文:06|资产负债表修复了一半:没有增发,但税单把借款推回去了
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/2026 results: interest expense nearly tripled on acquisition debt怎么使用:直接 / 支持;外部现实校验:06、25;反向验证:14
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接 / 支持;一手验证:17、25;同业比较:19、20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域06) / 外部现实(研究域25) / 反证(研究域14)|FY3/2026 results: interest expense nearly tripled on acquisition debt;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year
完整研究记录(核对用)
研究原文:Interest expense rose from JPY 477m to JPY 1,342m in FY3/26 on acquisition debt; cash-flow interest coverage fell to about 10.6x from 26.2x and interest-bearing debt to operating cash flow was 3.2 years: comfortable but no longer negligible against JPY 13bn operating profit.
内部研究类型:financing_cost_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):A recurring charge against the acquisition model's returns that grows if overseas balances grow.
不确定性(原始记录):Rates and covenants undisclosed.
F026|06|经营现金流匹配利润,但一半以上的自由现金流是资产出售
研究范围:开放研究+35项覆盖检查
写入正文:06|经营现金流匹配利润,但一半以上的自由现金流是资产出售
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Working capital: receivables build in FY3/2026, partial collection in Q1 FY3/2027怎么使用:直接 / 支持;一手验证:17、19;外部现实校验:32;反向验证:15;专项深挖:17、19
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接 / 支持;一手验证:35;反向验证:30;专项深挖:35
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接证据;一手验证:18、19、29;反向验证:21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 外部现实(研究域32) / 反证(研究域15) / 定向深挖(研究域17) / 定向深挖(研究域19)|Working capital: receivables build in FY3/2026, partial collection in Q1 FY3/2027;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing
完整研究记录(核对用)
研究原文:Receivables and contract assets rose about 27% in FY3/26 (from about JPY 39.2bn to 49,781m) because engineering completions bill late, then fell to JPY 44,824m by June 2026; inventories about JPY 33.6bn. A second-half completion surge on the forecast's own assumptions would absorb cash even if profit lands.
内部研究类型:cash_conversion_risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A weak H1 cash print alongside a met profit forecast would not alone break the thesis; cash conversion must be read across the year.
不确定性(原始记录):Receivable ageing, disputes at acquired units and Q1 cash flow (not published) are unknown.
F027|06|经营现金流匹配利润,但一半以上的自由现金流是资产出售
研究范围:开放研究+35项覆盖检查
写入正文:06|经营现金流匹配利润,但一半以上的自由现金流是资产出售
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接证据;一手验证:17、25;同业比较:19、20;其他用途:历史
FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment怎么使用:直接证据;反向验证:33;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year;直接证据 / 历史/同业比较(研究域21) / 反证(研究域33)|FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment
完整研究记录(核对用)
研究原文:FY3/26 operating cash flow JPY 13,861m versus operating profit JPY 13,609m shows sound conversion, but investing cash flow was +JPY 10,785m only because property sales (JPY 40,089m) exceeded acquisitions (JPY 19,215m) and tangible capex (JPY 9,580m); reported free cash flow of about JPY 24.6bn is therefore asset-recycling, while underlying free cash flow is the operating line less maintenance capex - positive but not large. Financing cash flow was -JPY 26,050m (short-term net -12,409m, long-term repayments -10,363m).
内部研究类型:cash_flow_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operations fund the dividend comfortably; acquisitions must justify themselves against the property they consumed.
不确定性(原始记录):Maintenance versus growth capex split not disclosed; Q1 cash flow statement unpublished.
F028|09|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧
研究范围:35项覆盖检查
写入正文:09|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接证据;一手验证:18、21、29
FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment怎么使用:直接证据;反向验证:33;同业比较:21;其他用途:历史
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21、29
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 历史/同业比较(研究域21) / 反证(研究域33)|FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves
完整研究记录(核对用)
研究原文:The obvious property reservoir has largely been realised: land fell to JPY 8,781m from 9,449m, the leasing 'other' segment was abolished from FY3/27 (residual rental income JPY 21m in Q1 booked non-operating), leaving investment securities of JPY 12,983m (about JPY 14.5bn at June 2026, valuation reserve JPY 7,156m) and operating land at historical cost.
内部研究类型:non_operating_assets_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Asset value supports the below-book entry only modestly now; the discount must be justified by earnings conversion, not another property cycle.
不确定性(原始记录):Composition of investment securities (cross-holdings versus financial) and any land appraisal are not disclosed.
F029|08|股息改成净资产基准,让股东在检验期间有一份稳定的索取权
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论08|股息改成净资产基准,让股东在检验期间有一份稳定的索取权14|八个模块的得分和一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive怎么使用:直接 / 支持;一手验证:26;同业比较:31;其他用途:历史
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
Dividend policy history: from the 40% payout target to the DOE progressive regime怎么使用:直接 / 支持;同业比较:13、22、26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域31)|FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves;直接证据 / 支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Dividend policy history: from the 40% payout target to the DOE progressive regime
完整研究记录(核对用)
研究原文:The dividend regime changes from FY3/27: the 40% payout target is replaced by a progressive dividend anchored on DOE of at least 4%, with FY3/27 at JPY 95 (47 interim, 48 year-end), about JPY 4.3bn or roughly 3.9% of equity; FY3/26 paid JPY 90 at a 15.7% payout because asset-sale proceeds were directed to debt and growth. With EPS swung by asset sales, impairments and exchange gains, the balance-sheet-anchored dividend gives holders a stable claim while operating conversion is tested, and equity growth at about the dividend rate keeps it affordable (about a third of operating cash flow).
内部研究类型:capital_policy_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Yield of about 5.1% on the forecast dividend is a real part of the return while conversion is proven; the board has shown it will subordinate stated policy to capital allocation, then redesign the policy around the balance sheet.
不确定性(原始记录):DOE base definition is the company's own; buyback criteria under the new regime are unstated.
F030|06|260亿日元净利润是一次资本运作,不是常态盈利
研究范围:35项覆盖检查
写入正文:06|260亿日元净利润是一次资本运作,不是常态盈利
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation怎么使用:直接 / 支持;反向验证:27
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域27)|Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment
完整研究记录(核对用)
研究原文:The Kwinana (Australia) land expropriation produced a JPY 3,765m special gain in Q1 FY3/27, the largest contributor to quarterly net income JPY 4,679m, but the relocation's remaining costs and timetable are not disclosed, and Australian operations may already appear in the impairment population.
内部研究类型:unquantified_tail
内部来源标记:COVERAGE35
普通股东含义(原始记录):The gain flatters forecast EPS; relocation costs are an open tail.
不确定性(原始记录):Timetable, cost and compensation are unquantified.
F031|07|计划与兑现:规模超额完成,利润率没有
研究范围:35项覆盖检查
写入正文:07|计划与兑现:规模超额完成,利润率没有13|Ako减值、第七次计划和海外销售比例,决定资本配置判断的来龙去脉15|证据的限制和未能确认的事项
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results: overseas scale is visible in segments but the overseas sales ratio is not disclosed怎么使用:直接 / 支持;反向验证:05;专项深挖:11;同业比较:11;其他用途:历史
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接证据;一手验证:08、09、11、13;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域11) / 反证(研究域05) / 定向深挖(研究域11)|FY3/2026 results: overseas scale is visible in segments but the overseas sales ratio is not disclosed;直接证据 / 支持证据|FY3/2026 results (tanshin): parent-only results against consolidated;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets
完整研究记录(核对用)
研究原文:The plan's headline KPI, an overseas sales ratio of 45% by FY2026 (29.8% base), cannot be verified from the tanshin; parent sales below half of consolidated says direction is right, but the precise score is management's to publish.
内部研究类型:disclosure_gap
内部来源标记:COVERAGE35
普通股东含义(原始记录):The most publicised plan number cannot be audited from the annual filing.
不确定性(原始记录):Where and when the ratio will be reported is unknown.
F032|11|中期决算是最近的验证事件,要看第二季度做出27.64亿日元营业利润
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|中期决算是最近的验证事件,要看第二季度做出27.64亿日元营业利润15|证据的限制和未能确认的事项
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print怎么使用:直接 / 支持;一手验证:30
IRBANK disclosure index: interim publication dates 2024-2026怎么使用:直接证据;一手验证:30;专项深挖:30
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index: interim publication dates 2024-2026;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit
完整研究记录(核对用)
研究原文:The H1 FY3/27 tanshin is the nearest verification event: published 11 Nov 2025 and 7 Nov 2024 in prior years, and not yet published at 9 Nov 2026, it is expected within days. It shows whether Q2 delivered the implied JPY 2,764m of operating profit and whether Reframax returned to profit.
内部研究类型:catalyst
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Gives a dated answer on forecast credibility rather than an open-ended wait.
不确定性(原始记录):Date inferred from the company's own cadence; content unknowable before publication.
F033|11|第七次中期经营计划会显示利润率目标是否诚实重设,以及价格低于净资产时是否回购
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|第七次中期经营计划会显示利润率目标是否诚实重设,以及价格低于净资产时是否回购
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Share buyback precedent recorded in the 6th plan document (FY3/2024)怎么使用:直接 / 支持;同业比较:26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 tanshin: management's framing of the final plan year;直接证据 / 支持证据 / 历史/同业比较(研究域26)|Share buyback precedent recorded in the 6th plan document (FY3/2024)
完整研究记录(核对用)
研究原文:The 7th medium-term plan, expected with the FY3/27 results in May 2027, is the governance catalyst: it will show whether Vision 2030's lines survive the 6th plan's profit shortfall and whether capital policy adds buybacks to the DOE dividend while the price is below book (buyback precedent: 1,220,800 shares for JPY 2.24bn in FY3/24).
内部研究类型:catalyst
内部来源标记:COVERAGE35
普通股东含义(原始记录):Reveals honest re-basing of margin targets and any buyback response to the book discount.
不确定性(原始记录):Timing and content unannounced.
F034|11|2026年10月的小额投资,是增长业务从叙述变成产能的第一步
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|2026年10月的小额投资,是增长业务从叙述变成产能的第一步15|主要来源和日期:公司披露为主,行情与数据汇总站辅助
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases怎么使用:直接 / 支持;一手验证:04、20;外部现实校验:03
Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment怎么使用:直接 / 支持;反向验证:07
Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment怎么使用:直接 / 支持;专项深挖:04、20;同业比较:04;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 外部现实(研究域03)|Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases;直接证据 / 支持证据 / 反证(研究域07)|Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment;直接证据 / 支持证据 / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment
完整研究记录(核对用)
研究原文:The 22 Oct 2026 capital investment of about JPY 850m (fine-ceramics firing and precision processing, and high-function insulation capacity at Isolite) is a dated physical catalyst; its commissioning would convert the insulation and advanced-materials option from narrative into capacity during FY3/28.
内部研究类型:catalyst
内部来源标记:COVERAGE35
普通股东含义(原始记录):Small in amount; relevant to growth-segment scale.
不确定性(原始记录):Notice read in abstract at amount level; returns not disclosed.
F035|09|市场按0.77倍净资产定价:没给转化溢价,也没按利润区间崩塌定价
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|市场按0.77倍净资产定价:没给转化溢价,也没按利润区间崩塌定价14|总分59.25/100,评级B:资产负债表和估值撑着,利润转化和治理拖着14|八个模块的得分和一句理由15|主要来源和日期:公司披露为主,行情与数据汇总站辅助
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接 / 支持;一手验证:17、25;同业比较:19、20;其他用途:历史
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:直接 / 支持;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation怎么使用:直接 / 支持;反向验证:27
Q1 FY3/2027 results (tanshin): share counts and capital怎么使用:直接证据;一手验证:25;同业比较:01、24;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost;直接证据 / 支持证据 / 反证(研究域27)|Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域01) / 历史/同业比较(研究域24)|Q1 FY3/2027 results (tanshin): share counts and capital
完整研究记录(核对用)
研究原文:At the 6 Nov 2026 close of JPY 1,847 (-4.94% on the day): market cap JPY 87.08bn (on 47,146,830 issued shares including treasury); forecast PER 8.03x on revised FY3/27 EPS JPY 230.10 (which includes the Kwinana gain); PBR 0.79x on FY3/26-end BPS JPY 2,343.45 and 0.77x on 30 June 2026 BPS JPY 2,414.18; forecast dividend yield 5.14% (JPY 95); FY3/26 ROE 26.6% as reported (distorted by the property gain; IRBANK forecast ROE 9.53%); EV/EBITDA 5.7x (EV JPY 117.28bn after net debt JPY 30.20bn at 30 June 2026; EBITDA JPY 20.74bn = FY3/26 operating profit 13,609m plus depreciation 7,131m; company EBITDA incl. goodwill amortisation JPY 22,134m). On recurring operating profit of about JPY 13bn the effective earnings multiple is nearer 10-11x after tax. The quote is sceptical about conversion but not pricing collapse of the band.
内部研究类型:valuation_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Entry pays for asset cover and a 5% yield while waiting; risk is time and another impairment more than forgone multiple expansion.
不确定性(原始记录):Mixed bases: FY3/26 EBITDA against June 2026 net debt; market cap on issued rather than outstanding shares; PBR depends on book date; the recurring-earnings multiple is this research's construction; no analyst consensus was found.
F036|06|商誉490亿日元占着资本,资本回报只在计划里达标
研究范围:35项覆盖检查
写入正文:06|商誉490亿日元占着资本,资本回报只在计划里达标
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接证据;一手验证:22;同业比较:28、32;其他用途:历史
Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines怎么使用:直接证据;一手验证:22;专项深挖:22
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接证据;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接证据;一手验证:18、21、29
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%
完整研究记录(核对用)
研究原文:Returns oscillate around the cost of capital: the consumables core earns above it, the acquisition programme has so far earned below it in margin terms. Reported ROE 26.6% is a one-off artefact; forecast ROE is about 9.5%; plan ROIC target 10% versus a stated capital-cost benchmark of 6.5% with JPY 49,065m of goodwill and intangibles in the capital base puts delivered ROIC visibly below target. Capital-cost awareness is evidenced by the DOE redesign and the PBR debate, less so by acquisition pricing discipline so far.
内部研究类型:capital_efficiency_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):At 0.77x book, mid-band returns suffice for the price to work; the burden of proof sits with delivery.
不确定性(原始记录):ROIC is computed approximately; management's current cost-of-capital figure and ROIC outturn were not restated in the materials read.
F037|01|规模已经买到手,利润还没有跟上
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|规模已经买到手,利润还没有跟上
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接 / 支持;一手验证:08、09、11、13;同业比较:30;其他用途:历史
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
FY3/2026 and Q1 FY3/2027 segment record: the growth sectors are still small怎么使用:直接 / 支持;一手验证:03;反向验证:08、11
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);直接证据 / 支持证据 / 一手证据(研究域03) / 反证(研究域08) / 反证(研究域11)|FY3/2026 and Q1 FY3/2027 segment record: the growth sectors are still small
完整研究记录(核对用)
研究原文:Can the enlarged global platform convert scale into operating profit before its frictions - goodwill amortisation of about JPY 1.8bn a year, Reframax's project volatility, the Ako write-down and a shrinking domestic steel pool - consume the gain? If conversion comes, a group earning a recurring JPY 13-14bn, paying a DOE-anchored progressive dividend at 0.77x book is mispriced and the insulation and advanced-materials options are carried for little.
内部研究类型:investment_question_thesis
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Frames the position as a verification-schedule case rather than a hope list.
不确定性(原始记录):Conversion is unproven; the discount may persist for years even if the band holds.
F038|01|什么会推翻这个判断
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|什么会推翻这个判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接 / 支持;一手验证:35;反向验证:30;专项深挖:35
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment
完整研究记录(核对用)
研究原文:The thesis fails observably if the H1 FY3/27 print shows cumulative operating profit materially below the JPY 4,500m half-year forecast with a full-year cut, or Reframax records another loss half, or further impairment touches Ako or the acquired overseas assets in FY3/27, or the 7th plan abandons margin lines without a capital-policy offset; then the below-book price is a fair price for a structurally margin-dilutive consolidator.
内部研究类型:falsification_conditions
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):If falsified, exit into ordinary liquidity; a below-book affiliate of a steel group can stay below book indefinitely.
不确定性(原始记录):Falsifiers rest on the company's own dated prints, which were not yet available at freeze.
F039|05|护城河是资质和现场关系,保护的是耐火材料的单位利润,保护不了并购定价
研究范围:开放研究
写入正文:05|护城河是资质和现场关系,保护的是耐火材料的单位利润,保护不了并购定价14|八个模块的得分和一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接证据;一手验证:05、07、10、23、24
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation怎么使用:直接证据;一手验证:04、20;反向验证:10
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 一手证据(研究域04) / 一手证据(研究域20) / 反证(研究域10)|6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation
完整研究记录(核对用)
研究原文:The protective layer is qualification and installed relationship: switching a refractory supplier mid-campaign risks furnace downtime whose cost dwarfs materials savings, so incumbency earns margin renewed at every reline; supported by engineering knowledge of customer plants (including JFE Steel's), a global plant network assembled by acquisition and specified positions such as mold flux. It protects the refractories margin pool (JPY 8,575m in FY3/26) but not the group from its own acquisition pricing.
内部研究类型:moat_mechanism
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Underwrites durability of the consumables core; strongest domestically, still being earned in acquired markets; weaker in contestable engineering projects.
不确定性(原始记录):Inferred from industry structure; customer retention or loss events and bid win rates are not disclosed; the company does not quantify its moat.
F040|04|按规模和收购记录看,公司是分散行业里的整合者,全球份额没有量到
研究范围:开放研究
写入正文:04|按规模和收购记录看,公司是分散行业里的整合者,全球份额没有量到13|竞争位置和下行保护里还有没量化的缺口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接证据;一手验证:08、09、11、13;同业比较:30;其他用途:历史
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接证据;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets;直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix
完整研究记录(核对用)
研究原文:Industry position is assessed from scale, footprint and the acquisition record (consolidator buying regional platforms in a fragmented global industry, challenger rather than incumbent at global scale); no competitor data or independent global market-share series was obtained, so global share and competitive win rates remain unmeasured.
内部研究类型:research_boundary_finding
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The conversion of acquired position into segment profit is the unproven part.
不确定性(原始记录):Global share not measurable from sources read.
F041|04|脱碳对需求既是产品结构上的顺风,也是销量上的逆风
研究范围:35项覆盖检查
写入正文:04|脱碳对需求既是产品结构上的顺风,也是销量上的逆风
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Vision 2030 sustainability targets: CO2 halving and recycled raw materials怎么使用:直接证据;一手验证:13;外部现实校验:04;反向验证:26;专项深挖:13
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接证据;一手验证:08、09、11、13;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 反证(研究域26) / 定向深挖(研究域13)|Vision 2030 sustainability targets: CO2 halving and recycled raw materials;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets
完整研究记录(核对用)
研究原文:Decarbonisation is double-edged: Vision 2030 commits to halving Scope 1-2 CO2 from 139 thousand tonnes by 2030 and lifting recycled raw materials from 8.0% to 15.0%; efficiency products (low-conductivity bricks, insulation) gain while customers' shift to electric-furnace and hydrogen steelmaking changes refractory demand profiles - a mix tailwind against a volume headwind. TSE capital-cost policy is the channel already acting on the share price.
内部研究类型:policy_transmission
内部来源标记:COVERAGE35
普通股东含义(原始记录):Second-order for valuation today; direction durable and tightening.
不确定性(原始记录):Plant-level carbon exposure and jurisdiction detail not disclosed.
F042|04|收购方向从区域耐火材料厂转向紧贴钢铁生产的产品线
研究范围:35项覆盖检查
写入正文:04|收购方向从区域耐火材料厂转向紧贴钢铁生产的产品线
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Dynamix Casting Fluxes stake acquisition (22 January 2026 notice; consolidated in FY3/2026)怎么使用:直接证据;专项深挖:03、10;同业比较:03、07、10;其他用途:历史
FY3/2026 consolidation: Shinagawa Danieli Advanced Materials S.p.A. (Italy)怎么使用:直接证据;一手验证:07;反向验证:04;专项深挖:07
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接证据;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域07) / 历史/同业比较(研究域10) / 定向深挖(研究域03) / 定向深挖(研究域10)|Dynamix Casting Fluxes stake acquisition (22 January 2026 notice; consolidated in FY3/2026);直接证据 / 一手证据(研究域07) / 反证(研究域04) / 定向深挖(研究域07)|FY3/2026 consolidation: Shinagawa Danieli Advanced Materials S.p.A. (Italy);直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix
完整研究记录(核对用)
研究原文:The acquisition programme shifted from buying regional refractories makers (Gouda, Reframax) to buying product-line positions adjacent to steel production: Dynamix Casting Fluxes (US mold fluxes, consumable tied to casting volumes, stake acquired 22 Jan 2026) and the Danieli joint venture in Italy (advanced materials and engineering channel into European steel plants; no financial contribution disclosed).
内部研究类型:acquisition_strategy_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Option value and execution risk arrive together; the same perimeter extends reach and imports Brazilian and European cost bases.
不确定性(原始记录):Purchase prices, JV shares and earn-outs undisclosed.
F043|08|Ako工厂减值是资本配置最大的未解问题
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation怎么使用:直接证据;一手验证:04、20;反向验证:10
Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment怎么使用:直接证据;专项深挖:04、20;同业比较:04;其他用途:历史
Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases怎么使用:直接证据;一手验证:04、20;外部现实校验:03
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域20) / 反证(研究域10)|6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation;直接证据 / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment;直接证据 / 一手证据(研究域04) / 一手证据(研究域20) / 外部现实(研究域03)|Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases
完整研究记录(核对用)
研究原文:The domestic production base is being rebuilt: monolithic refractory output concentrated at the Ako plant (western Japan; Teiyo closed, Hinae converted to mold-powder), eastern consolidation from four sites toward two started, Setouchi fine-ceramics base depreciating through advanced materials; FY3/26 tangible capex JPY 9,580m against annualised depreciation of roughly JPY 7bn.
内部研究类型:capex_restructuring_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Investment stage holds free cash flow below potential; returns must appear as refractories margin defence and growth-segment scale.
不确定性(原始记录):Utilisation at Ako and Setouchi, remaining cost and completion dates for eastern consolidation are not disclosed.
F044|11|成交稀薄,加上融资买盘偏单边,会放大财报前后的价格反应
研究范围:35项覆盖检查
写入正文:11|成交稀薄,加上融资买盘偏单边,会放大财报前后的价格反应15|证据的限制和未能确认的事项
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
IRBANK stock page for 5351: trading scale and margin balance怎么使用:直接证据;反向验证:34
查看完整证据标签(核对用)
直接证据 / 反证(研究域34)|IRBANK stock page for 5351: trading scale and margin balance
完整研究记录(核对用)
研究原文:Trading is thin relative to size (155,400 shares, about JPY 287m on 6 Nov 2026 against JPY 87.08bn capitalisation); a dated mid-July 2026 margin long balance of 193,800 shares against 800 short (about 242x) suggests one-sided leveraged long positioning that has since met a falling price and can amplify a disappointing print.
内部研究类型:market_microstructure_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Raises price-reaction variance around the interim print.
不确定性(原始记录):Margin balance is dated July 2026 and may have changed.
F045|09|预期从股价和预测算术读出,交付只要达到预测就已好于定价
研究范围:35项覆盖检查
写入正文:09|预期从股价和预测算术读出,交付只要达到预测就已好于定价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged怎么使用:直接证据;一手验证:31;专项深挖:31
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接证据;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026)
完整研究记录(核对用)
研究原文:Expectations are read from the quote and forecast arithmetic, not consensus: the price capitalises the band with no conversion premium, management's unchanged operating-profit forecast suggests similarly restrained internal expectations, and delivery at the revised forecast already beats the priced prior on recurring earnings; the gap closes on prints, not narrative.
内部研究类型:market_expectations_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Asymmetry favours the patient holder if delivery merely meets forecast.
不确定性(原始记录):No analyst consensus data was found; inferred from price behaviour and forecast arithmetic.
F046|09|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧
研究范围:35项覆盖检查
写入正文:09|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧13|竞争位置和下行保护里还有没量化的缺口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接证据;一手验证:18、21、29
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接证据;一手验证:18、19、29;反向验证:21
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21、29
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves
完整研究记录(核对用)
研究原文:Downside protection rests on book values (equity ratio 47.1%, equity about 127% of market capitalisation, securities, DOE dividend) while asset quality (JPY 49-50bn goodwill and intangibles) is the unprotected flank; contingent liabilities are not quantified, land is at historical cost without appraisal, and realisable values in a stress sale would differ, particularly for specialised plant and goodwill.
内部研究类型:downside_boundary_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Position sizing should assume the discount can persist for years; protection argues for patience capital.
不确定性(原始记录):Contingent liabilities and relocation costs are a genuine gap for a group with overseas plants.
F047|02|一个世纪的国内龙头,三年里决定用不动产买一个全球化未来
研究范围:35项覆盖检查
写入正文:02|一个世纪的国内龙头,三年里决定用不动产买一个全球化未来
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Trade-name change notice (27 March 2025): new legal name and registered English name, effective 1 October 2025怎么使用:直接证据;一手验证:01、33
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接证据;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
Q1 FY3/2027 results (tanshin): share counts and capital怎么使用:直接证据;一手验证:25;同业比较:01、24;其他用途:历史
Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment怎么使用:直接证据;反向验证:07
Gouda Refractories Group acquisition notices (24 October 2024) on the disclosure index怎么使用:直接证据;反向验证:09;专项深挖:09、25;同业比较:07、25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域33)|Trade-name change notice (27 March 2025): new legal name and registered English name, effective 1 October 2025;直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域01) / 历史/同业比较(研究域24)|Q1 FY3/2027 results (tanshin): share counts and capital;直接证据 / 反证(研究域07)|Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment;直接证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域25) / 反证(研究域09) / 定向深挖(研究域09) / 定向深挖(研究域25)|Gouda Refractories Group acquisition notices (24 October 2024) on the disclosure index
完整研究记录(核对用)
研究原文:Defining moments: 1875 founding as Japan's first private refractory maker; 2009 reorganisation with JFE Refractories binding the group to the JFE orbit; Isolite consolidation (2022); 5-for-1 split (October 2023); Saint-Gobain business transfer (2023); Gouda (2024); name change at the 150th anniversary (2025); Reframax and the property-sale circuit (FY3/26). The pattern is a century of domestic incumbency followed by a three-year decision to buy a global future with domestic property.
内部研究类型:historical_path
内部来源标记:COVERAGE35
普通股东含义(原始记录):Prior consolidations eventually showed in stable earnings; the payoff window for this wave is argued as two to three years out.
不确定性(原始记录):Pre-2023 acquisition detail is limited in the sources read.
F048|13|最重要的三个问题都等同一份中期财报
研究范围:开放研究
写入正文:13|最重要的三个问题都等同一份中期财报
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print怎么使用:直接 / 支持;一手验证:30
IRBANK disclosure index: interim publication dates 2024-2026怎么使用:直接证据;一手验证:30;专项深挖:30
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接证据;一手验证:35;反向验证:30;专项深挖:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index: interim publication dates 2024-2026;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%
完整研究记录(核对用)
研究原文:What will the H1 FY3/27 tanshin (not yet published at freeze; expected within days on the 11 Nov 2025 and 7 Nov 2024 pattern) show for cumulative operating profit against the JPY 4,500m H1 forecast, and does the full-year JPY 13,000m forecast survive it?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Opposite answers separate a delivering conversion story from a re-opened margin-dilution story.
不确定性(原始记录):Resolved only by evidence first public after the review date; no current public path exists.
F049|13|最重要的三个问题都等同一份中期财报
研究范围:开放研究
写入正文:13|最重要的三个问题都等同一份中期财报
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:支持证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据|Revision notice (August 2026): the stated second-half recovery mechanics in engineering;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%
完整研究记录(核对用)
研究原文:Did Reframax return to profit in Q2 FY3/27 as deferred projects were booked, and has the inflation cost pass-through assumed in the August revision actually been agreed with its major customer?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Reframax is the largest single swing in the H2 forecast.
不确定性(原始记录):Project-level disclosure is not given; H1 print may reveal segment profit only.
F050|13|最重要的三个问题都等同一份中期财报
研究范围:开放研究
写入正文:13|最重要的三个问题都等同一份中期财报
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%怎么使用:直接 / 支持;一手验证:16;反向验证:19;专项深挖:16
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 反证(研究域19) / 定向深挖(研究域16)|Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%;直接证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering
完整研究记录(核对用)
研究原文:How much of the Q1 gross-margin compression (20.1% against 25.2%) is raw-material cost that price correction will recover in H2, and how much is Reframax mix and the overseas equipment trouble?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Determines whether margin compression is cyclical lag or structural dilution.
不确定性(原始记录):No decomposition disclosed; evidence is gross margin at H1 and Q3 prints.
F051|13|Ako减值、第七次计划和海外销售比例,决定资本配置判断的来龙去脉
研究范围:开放研究
写入正文:13|Ako减值、第七次计划和海外销售比例,决定资本配置判断的来龙去脉
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation怎么使用:直接 / 支持;一手验证:04、20;反向验证:10
Impairment and forecast-revision notice (16 April 2026) on the disclosure index怎么使用:直接证据;反向验证:32;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 反证(研究域10)|6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation;直接证据 / 反证(研究域32) / 定向深挖(研究域32)|Impairment and forecast-revision notice (16 April 2026) on the disclosure index
完整研究记录(核对用)
研究原文:What exactly was impaired at the Ako plant (which lines; what utilisation or demand assumption changed within two years of its June 2024 start), and what does it imply for the eastern consolidation still under way?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Distinguishes conservative marking from overpayment in the restructuring programme.
不确定性(原始记录):Resolution needs annual securities-report impairment notes.
F052|13|Ako减值、第七次计划和海外销售比例,决定资本配置判断的来龙去脉
研究范围:开放研究
写入正文:13|Ako减值、第七次计划和海外销售比例,决定资本配置判断的来龙去脉
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接 / 支持;一手验证:08、09、11、13;同业比较:30;其他用途:历史
Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines怎么使用:直接证据;一手验证:22;专项深挖:22
Share buyback precedent recorded in the 6th plan document (FY3/2024)怎么使用:支持证据;同业比较:26;其他用途:历史
FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets怎么使用:支持证据;反向验证:22
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:支持证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets;直接证据 / 支持证据|FY3/2026 tanshin: management's framing of the final plan year;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines;支持证据 / 历史/同业比较(研究域26)|Share buyback precedent recorded in the 6th plan document (FY3/2024);支持证据 / 反证(研究域22)|FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets;支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit
完整研究记录(核对用)
研究原文:What sales, ROS and ROIC targets will the 7th medium-term plan (expected with FY3/27 results, May 2027) set, does it carry Vision 2030 (sales JPY 240bn, ROS 12%, ROIC 10%, overseas ratio 50%) forward unchanged after the 6th plan's profit shortfall, and what does it substitute for the missed margin targets - a dated ROS path or a quieter redefinition?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Governance test of honest re-basing and the longer-horizon valuation anchor.
不确定性(原始记录):Future disclosure; no current public path.
F053|13|Ako减值、第七次计划和海外销售比例,决定资本配置判断的来龙去脉
研究范围:开放研究
写入正文:13|Ako减值、第七次计划和海外销售比例,决定资本配置判断的来龙去脉
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results: overseas scale is visible in segments but the overseas sales ratio is not disclosed怎么使用:直接 / 支持;反向验证:05;专项深挖:11;同业比较:11;其他用途:历史
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接证据;一手验证:08、09、11、13;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域11) / 反证(研究域05) / 定向深挖(研究域11)|FY3/2026 results: overseas scale is visible in segments but the overseas sales ratio is not disclosed;直接证据 / 支持证据|FY3/2026 results (tanshin): parent-only results against consolidated;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets
完整研究记录(核对用)
研究原文:What overseas sales ratio was actually achieved in FY3/26 and is implied for FY3/27 against the plan's 45% target, given the tanshin does not disclose it, and where will it be reported?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Needed to audit the plan's headline KPI.
不确定性(原始记录):May appear in the securities report or integrated report not retrieved.
F054|13|回购、股东名册和Kwinana迁厂,是优先级较低但有重估意义的问题
研究范围:开放研究
写入正文:13|回购、股东名册和Kwinana迁厂,是优先级较低但有重估意义的问题
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Share buyback precedent recorded in the 6th plan document (FY3/2024)怎么使用:直接证据;同业比较:26;其他用途:历史
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
Ownership beyond the anchor: what the controlling-shareholder filing does and does not show怎么使用:直接证据;一手验证:24;反向验证:01、23;专项深挖:24
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接证据;一手验证:05、07、10、23、24
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:支持证据;一手验证:21;专项深挖:21、29
Dividend policy history: from the 40% payout target to the DOE progressive regime怎么使用:支持证据;同业比较:13、22、26;其他用途:历史
FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive怎么使用:支持证据;一手验证:26;同业比较:31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域26)|Share buyback precedent recorded in the 6th plan document (FY3/2024);直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;直接证据 / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域23) / 定向深挖(研究域24)|Ownership beyond the anchor: what the controlling-shareholder filing does and does not show;直接证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves;支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Dividend policy history: from the 40% payout target to the DOE progressive regime;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域31)|FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive
完整研究记录(核对用)
研究原文:Under the DOE 4% progressive policy, what is the board's stance on buybacks while shares trade below book (precedent JPY 2.24bn in FY3/24; treasury 3.2%), and will the FY3/27 securities report's full register show any change in the JFE Steel 34.9% anchor structure or the appearance of institutional holders?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Buybacks below book and register changes are potential re-rating levers.
不确定性(原始记录):Board criteria and register unstated in materials read.
F055|13|回购、股东名册和Kwinana迁厂,是优先级较低但有重估意义的问题
研究范围:开放研究
写入正文:13|回购、股东名册和Kwinana迁厂,是优先级较低但有重估意义的问题
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation怎么使用:直接 / 支持;反向验证:27
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:支持证据;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域27)|Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation;支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment
完整研究记录(核对用)
研究原文:What is the completion timetable and expected compensation for the Kwinana plant relocation after the land expropriation, and will further gains or costs arise in FY3/27-FY3/28?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Unquantified tail beneath a booked gain that flatters forecast EPS.
不确定性(原始记录):Not quantified in the Q1 filing.
F056|01|规模已经买到手,利润还没有跟上
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|规模已经买到手,利润还没有跟上06|毛利率守住了,费用吃掉了规模14|八个模块的得分和一句理由
归并到:F006
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接 / 支持;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope怎么使用:直接 / 支持;一手验证:16;同业比较:29;其他用途:历史
FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base怎么使用:直接 / 支持;一手验证:28;专项深挖:28;同业比较:02、09、12、15、17、27、33、35;其他用途:历史
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:支持证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop怎么使用:支持证据;一手验证:05、11、12;外部现实校验:02、15、19
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:支持证据;一手验证:22;同业比较:28、32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域29)|FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 历史/同业比较(研究域27) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35) / 定向深挖(研究域28)|FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 外部现实(研究域02) / 外部现实(研究域15) / 外部现实(研究域19)|FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop;支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes
完整研究记录(核对用)
研究原文:Scope-driven sales growth arrived with an overhead and amortisation step that left operating profit flat: scale delivered, margin diluted.
内部研究类型:scale_absorbed_by_overhead
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F057|06|商誉490亿日元占着资本,资本回报只在计划里达标
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|商誉490亿日元占着资本,资本回报只在计划里达标
归并到:F022
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Goodwill balance and amortisation run-rate at Q1 FY3/2027怎么使用:直接 / 支持;反向验证:06、18、29、35
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:支持证据;一手验证:18、19、29;反向验证:21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域18) / 反证(研究域29) / 反证(研究域35)|Goodwill balance and amortisation run-rate at Q1 FY3/2027;支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing
完整研究记录(核对用)
研究原文:Goodwill amortisation of about JPY 1.8bn a year is a structural charge inside the margin question.
内部研究类型:fixed_charge_inside
内部来源标记:COVERAGE35
F058|06|一季度毛利率从25.2%掉到20.1%,问题出在毛利这一行
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|一季度毛利率从25.2%掉到20.1%,问题出在毛利这一行
归并到:F011
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%怎么使用:直接 / 支持;一手验证:16;反向验证:19;专项深挖:16
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:支持证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据 / 支持证据 / 一手证据(研究域16) / 反证(研究域19) / 定向深挖(研究域16)|Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering
完整研究记录(核对用)
研究原文:Reframax's loss quarter is a principal driver of the Q1 gross-margin event, with raw-material inflation and the equipment trouble as co-drivers.
内部研究类型:drives
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F059|11|下半年恢复要靠三项还没有兑现的假设
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|下半年恢复要靠三项还没有兑现的假设
归并到:F010
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:支持证据;一手验证:06、14、15;反向验证:16、35
查看完整证据标签(核对用)
直接证据|Revision notice (August 2026): the stated second-half recovery mechanics in engineering;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%;支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering
完整研究记录(核对用)
研究原文:The H2 operating-profit requirement depends on Reframax booking deferred projects with inflation pass-through.
内部研究类型:conditions
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F060|11|下半年恢复要靠三项还没有兑现的假设
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|下半年恢复要靠三项还没有兑现的假设
归并到:F010
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接 / 支持;一手验证:35;反向验证:30;专项深挖:35
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:支持证据;一手验证:06、14、15;反向验证:16、35
Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged怎么使用:支持证据;一手验证:31;专项深挖:31
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据|Revision notice (August 2026): the stated second-half recovery mechanics in engineering;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%;支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;支持证据 / 一手证据(研究域31) / 定向深挖(研究域31)|Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged
完整研究记录(核对用)
研究原文:The forecast's second-half arithmetic is only as strong as the stacked, unevidenced assumptions beneath it.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F061|11|下半年恢复要靠三项还没有兑现的假设
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|下半年恢复要靠三项还没有兑现的假设
归并到:F010
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%怎么使用:直接 / 支持
Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%怎么使用:直接 / 支持;一手验证:16;反向验证:19;专项深挖:16
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:支持证据;一手验证:06、14、15;反向验证:16、35
查看完整证据标签(核对用)
直接证据 / 支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%;直接证据 / 支持证据 / 一手证据(研究域16) / 反证(研究域19) / 定向深挖(研究域16)|Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering
完整研究记录(核对用)
研究原文:Q1 gross margin shows no pass-through yet, so the forecast's recovery rests on a mechanism not yet observed.
内部研究类型:unevidenced_precondition
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F062|06|经营现金流匹配利润,但一半以上的自由现金流是资产出售
研究范围:35项覆盖检查
写入正文:06|经营现金流匹配利润,但一半以上的自由现金流是资产出售
归并到:F026
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Working capital: receivables build in FY3/2026, partial collection in Q1 FY3/2027怎么使用:直接 / 支持;一手验证:17、19;外部现实校验:32;反向验证:15;专项深挖:17、19
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接 / 支持;一手验证:35;反向验证:30;专项深挖:35
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:支持证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 外部现实(研究域32) / 反证(研究域15) / 定向深挖(研究域17) / 定向深挖(研究域19)|Working capital: receivables build in FY3/2026, partial collection in Q1 FY3/2027;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%
完整研究记录(核对用)
研究原文:Delivering the H2 completion surge would absorb working capital even if profit lands.
内部研究类型:cash_cost_of_delivery
内部来源标记:COVERAGE35
F063|06|资产负债表修复了一半:没有增发,但税单把借款推回去了
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表修复了一半:没有增发,但税单把借款推回去了12|几处表面数字与实质方向相反
归并到:F024
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY3/2027 balance sheet: settlement of the FY3/2026 tax charge怎么使用:直接 / 支持;反向验证:17、25;专项深挖:18;同业比较:18;其他用途:历史
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:支持证据;一手验证:18、21、29
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:支持证据;一手验证:17、25;同业比较:19、20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域18) / 反证(研究域17) / 反证(研究域25) / 定向深挖(研究域18)|Q1 FY3/2027 balance sheet: settlement of the FY3/2026 tax charge;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year
完整研究记录(核对用)
研究原文:The tax settlement on the property gain rebuilt short-term borrowing, so the balance-sheet repair is partial and mid-conversion.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F064|06|资产负债表修复了一半:没有增发,但税单把借款推回去了
研究范围:35项覆盖检查
写入正文:06|资产负债表修复了一半:没有增发,但税单把借款推回去了
归并到:F025
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/2026 results: interest expense nearly tripled on acquisition debt怎么使用:直接 / 支持;外部现实校验:06、25;反向验证:14
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接 / 支持;一手验证:17、25;同业比较:19、20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域06) / 外部现实(研究域25) / 反证(研究域14)|FY3/2026 results: interest expense nearly tripled on acquisition debt;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year
完整研究记录(核对用)
研究原文:Higher interest cost is a recurring charge against acquisition returns relative to cost of capital.
内部研究类型:cost_of_acquisition_model
内部来源标记:COVERAGE35
F065|08|股息改成净资产基准,让股东在检验期间有一份稳定的索取权
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论08|股息改成净资产基准,让股东在检验期间有一份稳定的索取权14|八个模块的得分和一句理由
归并到:F029
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive怎么使用:直接 / 支持;一手验证:26;同业比较:31;其他用途:历史
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:支持证据;一手验证:21;专项深挖:21、29
Dividend policy history: from the 40% payout target to the DOE progressive regime怎么使用:支持证据;同业比较:13、22、26;其他用途:历史
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:支持证据;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:支持证据;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域31)|FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves;支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Dividend policy history: from the 40% payout target to the DOE progressive regime;支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost
完整研究记录(核对用)
研究原文:The DOE-anchored dividend detaches distributions from EPS swung by asset sales, impairments and exchange gains and ties them to the balance sheet.
内部研究类型:decouples_from_distorted_eps
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F066|09|市场按0.77倍净资产定价:没给转化溢价,也没按利润区间崩塌定价
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|市场按0.77倍净资产定价:没给转化溢价,也没按利润区间崩塌定价14|总分59.25/100,评级B:资产负债表和估值撑着,利润转化和治理拖着14|八个模块的得分和一句理由15|主要来源和日期:公司披露为主,行情与数据汇总站辅助
归并到:F035
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:支持证据;一手验证:21;专项深挖:21、29
Dividend policy history: from the 40% payout target to the DOE progressive regime怎么使用:支持证据;同业比较:13、22、26;其他用途:历史
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:支持证据;一手验证:35
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:支持证据;一手验证:22;同业比较:28、32;其他用途:历史
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:支持证据;一手验证:18、19、29;反向验证:21
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:支持证据;一手验证:17、25;同业比较:19、20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves;支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Dividend policy history: from the 40% payout target to the DOE progressive regime;支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year
完整研究记录(核对用)
研究原文:A forecast yield of about 5.1% gives holders income while conversion is proven.
内部研究类型:supports_income_case
内部来源标记:COVERAGE35
F067|03|JFE Steel既是最大客户也是最大股东,需求保险和独立性上限是同一件事
研究范围:开放研究
写入正文:03|JFE Steel既是最大客户也是最大股东,需求保险和独立性上限是同一件事07|业务上整合,董事会上不整合:JFE的影响通过人员和客户关系传导12|几处表面数字与实质方向相反14|八个模块的得分和一句理由
归并到:F014
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接 / 支持;一手验证:05、07、10、23、24
IRBANK timely-disclosure index for 5351: takeover response policy and performance share units怎么使用:直接 / 支持;同业比较:23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;直接证据 / 支持证据 / 历史/同业比较(研究域23)|IRBANK timely-disclosure index for 5351: takeover response policy and performance share units
完整研究记录(核对用)
研究原文:The demand link and the equity link are one counterparty; governance independence is asserted while dependence is structural.
内部研究类型:same_link_as
内部来源标记:OPEN_DISCOVERY
F068|07|业务上整合,董事会上不整合:JFE的影响通过人员和客户关系传导
研究范围:开放研究+35项覆盖检查
写入正文:07|业务上整合,董事会上不整合:JFE的影响通过人员和客户关系传导14|八个模块的得分和一句理由
归并到:F015
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接 / 支持;一手验证:05、07、10、23、24
IRBANK timely-disclosure index for 5351: takeover response policy and performance share units怎么使用:直接 / 支持;同业比较:23;其他用途:历史
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:支持证据;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation怎么使用:支持证据;反向验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;直接证据 / 支持证据 / 历史/同业比较(研究域23)|IRBANK timely-disclosure index for 5351: takeover response policy and performance share units;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost;支持证据 / 反证(研究域27)|Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation
完整研究记录(核对用)
研究原文:Anchor plus defence policy forecloses a control market, so re-rating channels are delivery and capital policy; the discount for affiliation is treated as structural.
内部研究类型:removes_external_discipline
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F069|03|国内需求池在缩小,增长只能靠海外买来
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop怎么使用:直接 / 支持;一手验证:05、11、12;外部现实校验:02、15、19
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接 / 支持;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:支持证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 外部现实(研究域02) / 外部现实(研究域15) / 外部现实(研究域19)|FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering
完整研究记录(核对用)
研究原文:A structurally shrinking domestic pool is why growth is being bought overseas.
内部研究类型:motivates
内部来源标记:OPEN_DISCOVERY
F070|09|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧11|再次减值是还没有关上的风险
归并到:F021
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
Goodwill balance and amortisation run-rate at Q1 FY3/2027怎么使用:直接 / 支持;反向验证:06、18、29、35
6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation怎么使用:支持证据;一手验证:04、20;反向验证:10
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:支持证据;一手验证:06、14、15;反向验证:16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域18) / 反证(研究域29) / 反证(研究域35)|Goodwill balance and amortisation run-rate at Q1 FY3/2027;支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 反证(研究域10)|6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation;支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering
完整研究记录(核对用)
研究原文:The FY3/26 write-downs are the observed precedent for further impairment on the acquired and rebuilt asset base.
内部研究类型:precedent_for
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F071|09|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|资产托底只剩一部分:不动产已卖完,无形资产是没有保护的一侧11|再次减值是还没有关上的风险
归并到:F021
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Goodwill balance and amortisation run-rate at Q1 FY3/2027怎么使用:直接 / 支持;反向验证:06、18、29、35
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:支持证据;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:支持证据;一手验证:18、19、29;反向验证:21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域18) / 反证(研究域29) / 反证(研究域35)|Goodwill balance and amortisation run-rate at Q1 FY3/2027;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing
完整研究记录(核对用)
研究原文:The goodwill and intangibles block (about 42% of net assets) is the exposure that further impairment would hit.
内部研究类型:exposure_base
内部来源标记:COVERAGE35
F072|03|被计划当作增长引擎的两个板块,反而落在计划后面
研究范围:35项覆盖检查
写入正文:03|被计划当作增长引擎的两个板块,反而落在计划后面12|几处表面数字与实质方向相反
归并到:F018
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
6th plan sector targets for FY2026 against FY3/2026 actual segment results怎么使用:直接 / 支持;反向验证:02、03;专项深挖:08、33;同业比较:08;其他用途:历史
FY3/2026 and Q1 FY3/2027 segment record: the growth sectors are still small怎么使用:直接证据;一手验证:03;反向验证:08、11
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:支持证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域08) / 反证(研究域02) / 反证(研究域03) / 定向深挖(研究域08) / 定向深挖(研究域33)|6th plan sector targets for FY2026 against FY3/2026 actual segment results;直接证据 / 一手证据(研究域03) / 反证(研究域08) / 反证(研究域11)|FY3/2026 and Q1 FY3/2027 segment record: the growth sectors are still small;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering
完整研究记录(核对用)
研究原文:Growth sectors undershot their plan lines, qualifying the option narrative.
内部研究类型:counter_evidence_to
内部来源标记:COVERAGE35
F073|11|2026年10月的小额投资,是增长业务从叙述变成产能的第一步
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|2026年10月的小额投资,是增长业务从叙述变成产能的第一步15|主要来源和日期:公司披露为主,行情与数据汇总站辅助
归并到:F034
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases怎么使用:直接 / 支持;一手验证:04、20;外部现实校验:03
Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment怎么使用:直接 / 支持;反向验证:07
Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment怎么使用:直接 / 支持;专项深挖:04、20;同业比较:04;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 外部现实(研究域03)|Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases;直接证据 / 支持证据 / 反证(研究域07)|Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment;直接证据 / 支持证据 / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment
完整研究记录(核对用)
研究原文:The October 2026 capex converts the option into physical capacity during FY3/28.
内部研究类型:converts_to_capacity
内部来源标记:COVERAGE35
F074|11|中期决算是最近的验证事件,要看第二季度做出27.64亿日元营业利润
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|中期决算是最近的验证事件,要看第二季度做出27.64亿日元营业利润15|证据的限制和未能确认的事项
归并到:F032
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print怎么使用:直接 / 支持;一手验证:30
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接证据;一手验证:35;反向验证:30;专项深挖:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%
完整研究记录(核对用)
研究原文:The H1 print is the first test of the implied Q2 and H2 path.
内部研究类型:tests
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F075|11|第七次中期经营计划会显示利润率目标是否诚实重设,以及价格低于净资产时是否回购
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|第七次中期经营计划会显示利润率目标是否诚实重设,以及价格低于净资产时是否回购
归并到:F033
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接 / 支持;一手验证:08、09、11、13;同业比较:30;其他用途:历史
Share buyback precedent recorded in the 6th plan document (FY3/2024)怎么使用:支持证据;同业比较:26;其他用途:历史
FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets怎么使用:支持证据;反向验证:22
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:支持证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 tanshin: management's framing of the final plan year;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets;支持证据 / 历史/同业比较(研究域26)|Share buyback precedent recorded in the 6th plan document (FY3/2024);支持证据 / 反证(研究域22)|FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets;支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit
完整研究记录(核对用)
研究原文:The 7th plan shows whether management re-bases the margin lines honestly.
内部研究类型:tests
内部来源标记:COVERAGE35
F076|07|计划与兑现:规模超额完成,利润率没有
研究范围:35项覆盖检查
写入正文:07|计划与兑现:规模超额完成,利润率没有13|Ako减值、第七次计划和海外销售比例,决定资本配置判断的来龙去脉15|证据的限制和未能确认的事项
归并到:F031
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 results: overseas scale is visible in segments but the overseas sales ratio is not disclosed怎么使用:直接 / 支持;反向验证:05;专项深挖:11;同业比较:11;其他用途:历史
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接 / 支持;一手验证:08、09、11、13;同业比较:30;其他用途:历史
FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets怎么使用:支持证据;反向验证:22
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:支持证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域11) / 反证(研究域05) / 定向深挖(研究域11)|FY3/2026 results: overseas scale is visible in segments but the overseas sales ratio is not disclosed;直接证据 / 支持证据|FY3/2026 results (tanshin): parent-only results against consolidated;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets;支持证据 / 反证(研究域22)|FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets;支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit
完整研究记录(核对用)
研究原文:The plan's headline overseas KPI cannot be audited from the annual filing.
内部研究类型:unverifiable_kpi_of
内部来源标记:COVERAGE35
F077|01|什么会推翻这个判断
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|什么会推翻这个判断
归并到:F038
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接 / 支持;一手验证:35;反向验证:30;专项深挖:35
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:支持证据;一手验证:08、09、11、13;同业比较:30;其他用途:历史
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:支持证据;一手验证:35
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:支持证据;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
FY3/2026 and Q1 FY3/2027 segment record: the growth sectors are still small怎么使用:支持证据;一手验证:03;反向验证:08、11
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets;支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);支持证据 / 一手证据(研究域03) / 反证(研究域08) / 反证(研究域11)|FY3/2026 and Q1 FY3/2027 segment record: the growth sectors are still small
完整研究记录(核对用)
研究原文:The stated dated observations would disprove the conversion thesis at its first checkpoints.
内部研究类型:falsifies_if
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F078|09|市场按0.77倍净资产定价:没给转化溢价,也没按利润区间崩塌定价
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|市场按0.77倍净资产定价:没给转化溢价,也没按利润区间崩塌定价14|总分59.25/100,评级B:资产负债表和估值撑着,利润转化和治理拖着14|八个模块的得分和一句理由15|主要来源和日期:公司披露为主,行情与数据汇总站辅助
归并到:F035
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:直接 / 支持;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:支持证据;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation怎么使用:支持证据;反向验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;支持证据 / 反证(研究域27)|Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation
完整研究记录(核对用)
研究原文:The JPY 13-14bn recurring band, not printed net income, is the earnings base for the valuation, giving a 10-11x effective multiple versus a printed 8.03x.
内部研究类型:normalization_basis
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F079|06|260亿日元净利润是一次资本运作,不是常态盈利
研究范围:开放研究+35项覆盖检查
写入正文:06|260亿日元净利润是一次资本运作,不是常态盈利
归并到:F004
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Foreign-exchange gains inside ordinary profit: FY3/2026 and Q1 FY3/2027怎么使用:直接 / 支持;一手验证:06、14、32;外部现实校验:10;反向验证:28;专项深挖:06、14
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:直接 / 支持;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:支持证据;一手验证:22;同业比较:28、32;其他用途:历史
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:支持证据;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域32) / 外部现实(研究域10) / 反证(研究域28) / 定向深挖(研究域06) / 定向深挖(研究域14)|Foreign-exchange gains inside ordinary profit: FY3/2026 and Q1 FY3/2027;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost;支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment
完整研究记录(核对用)
研究原文:Exchange gains must be removed to see that ordinary and operating lines show the same flat band.
内部研究类型:qualifies_ordinary_line
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F080|09|市场按0.77倍净资产定价:没给转化溢价,也没按利润区间崩塌定价
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|市场按0.77倍净资产定价:没给转化溢价,也没按利润区间崩塌定价14|总分59.25/100,评级B:资产负债表和估值撑着,利润转化和治理拖着14|八个模块的得分和一句理由15|主要来源和日期:公司披露为主,行情与数据汇总站辅助
归并到:F035
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation怎么使用:直接 / 支持;反向验证:27
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:支持证据;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:支持证据;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域27)|Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost
完整研究记录(核对用)
研究原文:The Kwinana gain sits inside the revised forecast EPS behind the 8.03x forecast PER.
内部研究类型:inflates_forecast_eps
内部来源标记:COVERAGE35
F081|06|只有合并口径有意义,母公司数字混了资产出售
研究范围:35项覆盖检查
归并到:F007
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 results (tanshin): parent-only results against consolidated
完整研究记录(核对用)
研究原文:Gains funding the transformation sit at the parent while operating revenue sits in subsidiaries, which is why consolidated recurring earnings, not parent results, are the frame.
内部研究类型:perimeter_context
内部来源标记:COVERAGE35
F082|10|价格结构的变化早于后来被公开确认的基本面变化,现在两者指向同一个日期
写入正文:10|价格结构的变化早于后来被公开确认的基本面变化,现在两者指向同一个日期
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print怎么使用:直接 / 支持;一手验证:30
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit
完整研究记录(核对用)
研究原文:Cross-lane reference only: the interim print is the next dated public fundamental event against which the protected Technical State will show a price response. This relation does not alter or reinterpret the protected Technical truth and fundamental evidence is not used as technical proof.
内部研究类型:cross_lane_next_dated_fundamental_input
内部来源标记:TECHNICAL
F083|10|价格结构的变化早于后来被公开确认的基本面变化,现在两者指向同一个日期
研究范围:开放研究+35项覆盖检查
写入正文:10|价格结构的变化早于后来被公开确认的基本面变化,现在两者指向同一个日期
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接证据;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print怎么使用:直接 / 支持;一手验证:30
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接证据;一手验证:35;反向验证:30;专项深挖:35
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:支持证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print;直接证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%
完整研究记录(核对用)
研究原文:The cross-lane timing structure references the protected Technical Synthesis as a whole without flattening or redefining it.
内部研究类型:references_whole
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
F084|10|二十年平台已经突破,但历史高点只被测试一次就被压回
写入正文:00|报告身份、评分与核心结论10|二十年平台已经突破,但历史高点只被测试一次就被压回10|从254日元跌到平台,再用二十年待在平台里10|运行区间站了七个月,价格在两年均线附近找平衡10|高点的失败脉冲留下记忆:卖出过一次的故事,值多少10|价格结构的变化早于后来被公开确认的基本面变化,现在两者指向同一个日期10|高度与证据之间的矛盾:确认条件和失效条件14|八个模块的得分和一句理由
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (RESEARCH_TRUTH.technical_state)
内部研究类型:protected_technical_synthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
F085|02|耐久的是消耗品基本盘,尚未证明的是海外扩张
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(31项,重复标签已合并)
Trade-name change notice (27 March 2025): new legal name and registered English name, effective 1 October 2025怎么使用:直接 / 支持;一手验证:01、33
Official English website and Integrated Report 2025: English name, headquarters and founding怎么使用:直接 / 支持;一手验证:01
Company profile: headquarters, capital, leadership and listing怎么使用:直接证据;一手验证:27;专项深挖:01、27;同业比较:01;其他用途:历史
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接 / 支持;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment怎么使用:直接证据;一手验证:02;专项深挖:02、15
FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope怎么使用:直接 / 支持;一手验证:16;同业比较:29;其他用途:历史
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接 / 支持;一手验证:05、07、10、23、24
6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation怎么使用:直接 / 支持;一手验证:04、20;反向验证:10
FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop怎么使用:直接 / 支持;一手验证:05、11、12;外部现实校验:02、15、19
Q1 FY3/2027 narrative: demand conditions by end-market怎么使用:直接证据;一手验证:12;外部现实校验:05、11;专项深挖:05、12
IRBANK timely-disclosure index for 5351: takeover response policy and performance share units怎么使用:直接 / 支持;同业比较:23;其他用途:历史
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接 / 支持;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
Gouda Refractories Group acquisition notices (24 October 2024) on the disclosure index怎么使用:直接证据;反向验证:09;专项深挖:09、25;同业比较:07、25;其他用途:历史
FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base怎么使用:直接 / 支持;一手验证:28;专项深挖:28;同业比较:02、09、12、15、17、27、33、35;其他用途:历史
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接 / 支持;一手验证:17、25;同业比较:19、20;其他用途:历史
FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment怎么使用:直接证据;反向验证:33;同业比较:21;其他用途:历史
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接 / 支持;一手验证:18、21、29
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
Q1 FY3/2027 results (tanshin): share counts and capital怎么使用:直接证据;一手验证:25;同业比较:01、24;其他用途:历史
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive怎么使用:直接 / 支持;一手验证:26;同业比较:31;其他用途:历史
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
Dividend policy history: from the 40% payout target to the DOE progressive regime怎么使用:直接 / 支持;同业比较:13、22、26;其他用途:历史
Goodwill balance and amortisation run-rate at Q1 FY3/2027怎么使用:直接 / 支持;反向验证:06、18、29、35
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
Impairment and forecast-revision notice (16 April 2026) on the disclosure index怎么使用:直接证据;反向验证:32;专项深挖:32
Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment怎么使用:直接证据;专项深挖:04、20;同业比较:04;其他用途:历史
Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases怎么使用:直接证据;一手验证:04、20;外部现实校验:03
Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment怎么使用:直接证据;反向验证:07
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接证据;一手验证:06、14、15;反向验证:16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域33)|Trade-name change notice (27 March 2025): new legal name and registered English name, effective 1 October 2025;直接证据 / 支持证据 / 一手证据(研究域01)|Official English website and Integrated Report 2025: English name, headquarters and founding;直接证据 / 一手证据(研究域27) / 历史/同业比较(研究域01) / 定向深挖(研究域01) / 定向深挖(研究域27)|Company profile: headquarters, capital, leadership and listing;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域29)|FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 反证(研究域10)|6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 外部现实(研究域02) / 外部现实(研究域15) / 外部现实(研究域19)|FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop;直接证据 / 一手证据(研究域12) / 外部现实(研究域05) / 外部现实(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域12)|Q1 FY3/2027 narrative: demand conditions by end-market;直接证据 / 支持证据 / 历史/同业比较(研究域23)|IRBANK timely-disclosure index for 5351: takeover response policy and performance share units;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix;直接证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域25) / 反证(研究域09) / 定向深挖(研究域09) / 定向深挖(研究域25)|Gouda Refractories Group acquisition notices (24 October 2024) on the disclosure index;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 历史/同业比较(研究域27) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35) / 定向深挖(研究域28)|FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year;直接证据 / 历史/同业比较(研究域21) / 反证(研究域33)|FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域01) / 历史/同业比较(研究域24)|Q1 FY3/2027 results (tanshin): share counts and capital;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域31)|FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;直接证据 / 支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Dividend policy history: from the 40% payout target to the DOE progressive regime;直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域18) / 反证(研究域29) / 反证(研究域35)|Goodwill balance and amortisation run-rate at Q1 FY3/2027;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 反证(研究域32) / 定向深挖(研究域32)|Impairment and forecast-revision notice (16 April 2026) on the disclosure index;直接证据 / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment;直接证据 / 一手证据(研究域04) / 一手证据(研究域20) / 外部现实(研究域03)|Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases;直接证据 / 反证(研究域07)|Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment;直接证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering
完整研究记录(核对用)
研究原文:Durable Business Portrait: a durable consumables franchise funding an unproven global expansion|The durable core is the consumable franchise: refractories wear out with every heat, the group has supplied them since 1875, and relationships such as JFE Steel (34.9% holder, about 30% of sales) renew structurally. That core funded, via property sales, a three-year attempt to buy a global second engine before the domestic steel pool shrinks further. The expansion's assets are real (European, Brazilian, American, Italian platforms, rebuilt domestic plants, growth-segment capacity) and its costs are real and partly recognised (JPY 9.7bn impairment, JPY 49bn intangibles, margin from 9.2% to a forecast 6.6%). Durability is high for the enterprise and unproven for the expansion; the DOE dividend pays shareholders from the durable balance sheet while the expansion is tested; the franchise's self-repair rests on consumable demand and asset-recycling flexibility, which cannot repeat at the same scale. Irreversible-failure risk is low; the failure mode is a long discount and impairment, not insolvency.
内部研究类型:durable_business_portrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Ordinary shareholders hold a durable, affiliate-anchored franchise at 0.77x book whose return depends on whether acquired scale earns its capital over the next four reporting periods.
不确定性(原始记录):Expansion returns, moat strength, backlog quality and domestic utilisation are unmeasured; foundation judged from filings and structure, with no independent market-share data.
F086|06|毛利率守住了,费用吃掉了规模
研究范围:开放研究+35项覆盖检查
写入正文:06|毛利率守住了,费用吃掉了规模
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(30项,重复标签已合并)
FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base怎么使用:直接 / 支持;一手验证:28;专项深挖:28;同业比较:02、09、12、15、17、27、33、35;其他用途:历史
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope怎么使用:直接 / 支持;一手验证:16;同业比较:29;其他用途:历史
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接 / 支持;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接 / 支持;一手验证:08、09、11、13;同业比较:30;其他用途:历史
FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets怎么使用:直接 / 支持;反向验证:22
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines怎么使用:直接证据;一手验证:22;专项深挖:22
Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%怎么使用:直接 / 支持
Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%怎么使用:直接 / 支持;一手验证:16;反向验证:19;专项深挖:16
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接 / 支持;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment怎么使用:直接证据;一手验证:02;专项深挖:02、15
Goodwill balance and amortisation run-rate at Q1 FY3/2027怎么使用:直接 / 支持;反向验证:06、18、29、35
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接证据;一手验证:18、21、29
Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged怎么使用:直接 / 支持;一手验证:31;专项深挖:31
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接 / 支持;一手验证:35;反向验证:30;专项深挖:35
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接 / 支持;一手验证:17、25;同业比较:19、20;其他用途:历史
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:直接 / 支持;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation怎么使用:直接 / 支持;反向验证:27
Q1 FY3/2027 results (tanshin): share counts and capital怎么使用:直接证据;一手验证:25;同业比较:01、24;其他用途:历史
IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print怎么使用:直接 / 支持;一手验证:30
IRBANK disclosure index: interim publication dates 2024-2026怎么使用:直接证据;一手验证:30;专项深挖:30
FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop怎么使用:支持证据;一手验证:05、11、12;外部现实校验:02、15、19
Share buyback precedent recorded in the 6th plan document (FY3/2024)怎么使用:支持证据;同业比较:26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 历史/同业比较(研究域27) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35) / 定向深挖(研究域28)|FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域29)|FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets;直接证据 / 支持证据 / 反证(研究域22)|FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines;直接证据 / 支持证据|FY3/2026 tanshin: management's framing of the final plan year;直接证据 / 支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%;直接证据 / 支持证据 / 一手证据(研究域16) / 反证(研究域19) / 定向深挖(研究域16)|Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment;直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域18) / 反证(研究域29) / 反证(研究域35)|Goodwill balance and amortisation run-rate at Q1 FY3/2027;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 支持证据 / 一手证据(研究域31) / 定向深挖(研究域31)|Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost;直接证据 / 支持证据 / 反证(研究域27)|Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域01) / 历史/同业比较(研究域24)|Q1 FY3/2027 results (tanshin): share counts and capital;直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index: interim publication dates 2024-2026;支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 外部现实(研究域02) / 外部现实(研究域15) / 外部现实(研究域19)|FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop;直接证据|Revision notice (August 2026): the stated second-half recovery mechanics in engineering;支持证据 / 历史/同业比较(研究域26)|Share buyback precedent recorded in the 6th plan document (FY3/2024)
完整研究记录(核对用)
研究原文:Margin conversion as the single variable linking operations, plan and valuation|Segment delivery, plan delivery (ROS 11% targeted, 6.6% forecast) and the 0.77x-book valuation are the same question seen from three domains; the H1 FY3/27 print answers the first instalment of all three at once.
内部研究类型:cross_domain_causal_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Conversion shows up as operating profit above the JPY 13-14bn band; absence leaves the discount fair.
不确定性(原始记录):Unobservable until H1 and Q3 prints and the 7th plan.
F087|03|JFE Steel既是最大客户也是最大股东,需求保险和独立性上限是同一件事
研究范围:开放研究+35项覆盖检查
写入正文:03|JFE Steel既是最大客户也是最大股东,需求保险和独立性上限是同一件事07|业务上整合,董事会上不整合:JFE的影响通过人员和客户关系传导
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(17项,重复标签已合并)
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接 / 支持;一手验证:05、07、10、23、24
IRBANK timely-disclosure index for 5351: takeover response policy and performance share units怎么使用:直接 / 支持;同业比较:23;其他用途:历史
Q1 FY3/2027 subsequent event: performance share unit disposal of treasury shares怎么使用:直接证据;一手验证:23;专项深挖:23
FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop怎么使用:直接证据;一手验证:05、11、12;外部现实校验:02、15、19
Q1 FY3/2027 narrative: demand conditions by end-market怎么使用:直接证据;一手验证:12;外部现实校验:05、11;专项深挖:05、12
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation怎么使用:直接证据;一手验证:04、20;反向验证:10
Ownership beyond the anchor: what the controlling-shareholder filing does and does not show怎么使用:直接证据;一手验证:24;反向验证:01、23;专项深挖:24
Q1 FY3/2027 results (tanshin): share counts and capital怎么使用:直接证据;一手验证:25;同业比较:01、24;其他用途:历史
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接 / 支持;一手验证:17、25;同业比较:19、20;其他用途:历史
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:直接 / 支持;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation怎么使用:直接 / 支持;反向验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;直接证据 / 支持证据 / 历史/同业比较(研究域23)|IRBANK timely-disclosure index for 5351: takeover response policy and performance share units;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Q1 FY3/2027 subsequent event: performance share unit disposal of treasury shares;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 外部现实(研究域02) / 外部现实(研究域15) / 外部现实(研究域19)|FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop;直接证据 / 一手证据(研究域12) / 外部现实(研究域05) / 外部现实(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域12)|Q1 FY3/2027 narrative: demand conditions by end-market;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 一手证据(研究域04) / 一手证据(研究域20) / 反证(研究域10)|6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation;直接证据 / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域23) / 定向深挖(研究域24)|Ownership beyond the anchor: what the controlling-shareholder filing does and does not show;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域01) / 历史/同业比较(研究域24)|Q1 FY3/2027 results (tanshin): share counts and capital;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost;直接证据 / 支持证据 / 反证(研究域27)|Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation
完整研究记录(核对用)
研究原文:One counterparty, three domains: JFE Steel as demand, control and re-rating cap|JFE Steel stabilises the demand the refractories moat monetises, fixes the register's control geometry and caps available re-rating channels: one counterparty, three domains, the same dependence.
内部研究类型:cross_domain_dependency_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Stability and insulation come with a structurally priced discount; a change in JFE's holding would be a re-rating event either way.
不确定性(原始记录):Anchor's long-term intentions and the rest of the register are unknown.
F088|06|资产负债表修复了一半:没有增发,但税单把借款推回去了
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表修复了一半:没有增发,但税单把借款推回去了08|不动产换收购的资金循环,之后的扩张要自己承担
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(13项,重复标签已合并)
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:直接 / 支持;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base怎么使用:直接证据;一手验证:28;专项深挖:28;同业比较:02、09、12、15、17、27、33、35;其他用途:历史
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接 / 支持;一手验证:17、25;同业比较:19、20;其他用途:历史
FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment怎么使用:直接证据;反向验证:33;同业比较:21;其他用途:历史
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接 / 支持;一手验证:18、21、29
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
Q1 FY3/2027 balance sheet: settlement of the FY3/2026 tax charge怎么使用:直接 / 支持;反向验证:17、25;专项深挖:18;同业比较:18;其他用途:历史
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
Q1 FY3/2027 results (tanshin): share counts and capital怎么使用:直接证据;一手验证:25;同业比较:01、24;其他用途:历史
FY3/2026 results: interest expense nearly tripled on acquisition debt怎么使用:直接 / 支持;外部现实校验:06、25;反向验证:14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost;直接证据 / 一手证据(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 历史/同业比较(研究域27) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35) / 定向深挖(研究域28)|FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year;直接证据 / 历史/同业比较(研究域21) / 反证(研究域33)|FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves;直接证据 / 支持证据 / 历史/同业比较(研究域18) / 反证(研究域17) / 反证(研究域25) / 定向深挖(研究域18)|Q1 FY3/2027 balance sheet: settlement of the FY3/2026 tax charge;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域01) / 历史/同业比较(研究域24)|Q1 FY3/2027 results (tanshin): share counts and capital;直接证据 / 支持证据 / 外部现实(研究域06) / 外部现实(研究域25) / 反证(研究域14)|FY3/2026 results: interest expense nearly tripled on acquisition debt;直接证据 / 支持证据|FY3/2026 results (tanshin): parent-only results against consolidated
完整研究记录(核对用)
研究原文:The asset-recycling circuit: property out, acquisitions in, debt repaid, tax bill back|Property sales funded acquisitions and deleveraging, but the same circuit's tax bill rebuilt short-term debt, and the reservoir is largely spent; the balance sheet is mid-conversion, like the P&L, and cannot be read as simply repaired.
内部研究类型:capital_recycling_circuit
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Future acquisitions must be carried by operations and debt; strategy pace is self-funded and slower.
不确定性(原始记录):Remaining property and securities realisable values and facility terms are undisclosed.
F089|08|商誉是收购决策留在资产负债表上的残余
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(13项,重复标签已合并)
Goodwill balance and amortisation run-rate at Q1 FY3/2027怎么使用:直接 / 支持;反向验证:06、18、29、35
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接证据;一手验证:18、21、29
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation怎么使用:直接 / 支持;一手验证:04、20;反向验证:10
Impairment and forecast-revision notice (16 April 2026) on the disclosure index怎么使用:直接证据;反向验证:32;专项深挖:32
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines怎么使用:直接证据;一手验证:22;专项深挖:22
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接证据;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base怎么使用:直接 / 支持;一手验证:28;专项深挖:28;同业比较:02、09、12、15、17、27、33、35;其他用途:历史
FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope怎么使用:直接 / 支持;一手验证:16;同业比较:29;其他用途:历史
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接 / 支持;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域18) / 反证(研究域29) / 反证(研究域35)|Goodwill balance and amortisation run-rate at Q1 FY3/2027;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 反证(研究域10)|6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation;直接证据 / 反证(研究域32) / 定向深挖(研究域32)|Impairment and forecast-revision notice (16 April 2026) on the disclosure index;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 历史/同业比较(研究域27) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35) / 定向深挖(研究域28)|FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域29)|FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix
完整研究记录(核对用)
研究原文:Goodwill as the balance-sheet residue of the acquisition decisions|The JPY 49bn intangibles block is the balance-sheet form of the acquisition decisions; its amortisation is a fixed charge inside the margin question and the impairment population (Ako, two overseas units) is first evidence of how those decisions are ageing.
内部研究类型:cross_domain_accounting_strategy_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Book value of about JPY 2,414 per share includes acquisition intangibles whose value is a forecast, not a fact.
不确定性(原始记录):Recoverability unobservable until acquired cash flows are reported.
F090|01|规模已经买到手,利润还没有跟上
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|规模已经买到手,利润还没有跟上14|总分59.25/100,评级B:资产负债表和估值撑着,利润转化和治理拖着
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(24项,重复标签已合并)
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接 / 支持;一手验证:08、09、11、13;同业比较:30;其他用途:历史
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
FY3/2026 and Q1 FY3/2027 segment record: the growth sectors are still small怎么使用:直接 / 支持;一手验证:03;反向验证:08、11
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接 / 支持;一手验证:35;反向验证:30;专项深挖:35
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print怎么使用:直接 / 支持;一手验证:30
IRBANK disclosure index: interim publication dates 2024-2026怎么使用:直接证据;一手验证:30;专项深挖:30
Share buyback precedent recorded in the 6th plan document (FY3/2024)怎么使用:直接 / 支持;同业比较:26;其他用途:历史
Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases怎么使用:直接 / 支持;一手验证:04、20;外部现实校验:03
Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment怎么使用:直接 / 支持;反向验证:07
Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment怎么使用:直接 / 支持;专项深挖:04、20;同业比较:04;其他用途:历史
Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%怎么使用:直接 / 支持
6th plan sector targets for FY2026 against FY3/2026 actual segment results怎么使用:直接 / 支持;反向验证:02、03;专项深挖:08、33;同业比较:08;其他用途:历史
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接 / 支持;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
Goodwill balance and amortisation run-rate at Q1 FY3/2027怎么使用:直接 / 支持;反向验证:06、18、29、35
Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged怎么使用:直接证据;一手验证:31;专项深挖:31
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接证据;一手验证:18、21、29
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接证据;一手验证:18、19、29;反向验证:21
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21、29
FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets怎么使用:支持证据;反向验证:22
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);直接证据 / 支持证据 / 一手证据(研究域03) / 反证(研究域08) / 反证(研究域11)|FY3/2026 and Q1 FY3/2027 segment record: the growth sectors are still small;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index: interim publication dates 2024-2026;直接证据 / 支持证据|FY3/2026 tanshin: management's framing of the final plan year;直接证据 / 支持证据 / 历史/同业比较(研究域26)|Share buyback precedent recorded in the 6th plan document (FY3/2024);直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 外部现实(研究域03)|Capital investment notice (22 October 2026): semiconductor-related capacity expansion at domestic bases;直接证据 / 支持证据 / 反证(研究域07)|Isolite Industries: tender-offer record on the disclosure index and role in the insulation segment;直接证据 / 支持证据 / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|Shinagawa Fine Ceramics merger notice (22 January 2025) and the Setouchi plant in the advanced segment;直接证据 / 支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%;直接证据|Revision notice (August 2026): the stated second-half recovery mechanics in engineering;直接证据 / 支持证据 / 历史/同业比较(研究域08) / 反证(研究域02) / 反证(研究域03) / 定向深挖(研究域08) / 定向深挖(研究域33)|6th plan sector targets for FY2026 against FY3/2026 actual segment results;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域18) / 反证(研究域29) / 反证(研究域35)|Goodwill balance and amortisation run-rate at Q1 FY3/2027;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves;支持证据 / 反证(研究域22)|FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets
完整研究记录(核对用)
研究原文:Conversion thesis, counter-evidence and dated falsifiers|Positive case: recurring JPY 13-14bn band, 47.1% equity ratio, no dilution, DOE-anchored 5% yield, 0.77x book, growth options carried for little. Strongest counter-evidence: margin dilution from 9.2% to 6.6% despite record sales, inverted sector delivery, early impairment, assumption-stacked H2 and structural governance insulation. Falsifiers are dated prints (H1 FY3/27, Q3, FY3/27 annual with 7th plan).
内部研究类型:thesis_falsification_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A verification-schedule case: re-underwrite at each print; patience capital only since the discount can persist.
不确定性(原始记录):All falsifiers depend on prints first public after the review date.
F091|09|估值要从净利润换到经常性盈利:8.03倍看起来比实际便宜
研究范围:开放研究+35项覆盖检查
写入正文:09|估值要从净利润换到经常性盈利:8.03倍看起来比实际便宜
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(19项,重复标签已合并)
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:直接 / 支持;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base怎么使用:直接证据;一手验证:28;专项深挖:28;同业比较:02、09、12、15、17、27、33、35;其他用途:历史
Foreign-exchange gains inside ordinary profit: FY3/2026 and Q1 FY3/2027怎么使用:直接 / 支持;一手验证:06、14、32;外部现实校验:10;反向验证:28;专项深挖:06、14
Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation怎么使用:直接 / 支持;反向验证:27
IRBANK stock page snapshot for 5351 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、08、09、12、13、14、16、17、18、21、22、23、26、28、29、35;反向验证:24
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接 / 支持;一手验证:17、25;同业比较:19、20;其他用途:历史
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
Q1 FY3/2027 results (tanshin): share counts and capital怎么使用:直接证据;一手验证:25;同业比较:01、24;其他用途:历史
FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive怎么使用:直接 / 支持;一手验证:26;同业比较:31;其他用途:历史
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
Dividend policy history: from the 40% payout target to the DOE progressive regime怎么使用:直接 / 支持;同业比较:13、22、26;其他用途:历史
Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines怎么使用:直接证据;一手验证:22;专项深挖:22
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接证据;一手验证:18、21、29
Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged怎么使用:直接证据;一手验证:31;专项深挖:31
FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment怎么使用:直接证据;反向验证:33;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost;直接证据 / 一手证据(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 历史/同业比较(研究域27) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35) / 定向深挖(研究域28)|FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域32) / 外部现实(研究域10) / 反证(研究域28) / 定向深挖(研究域06) / 定向深挖(研究域14)|Foreign-exchange gains inside ordinary profit: FY3/2026 and Q1 FY3/2027;直接证据 / 支持证据 / 反证(研究域27)|Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域23) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5351 (6 November 2026);直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域01) / 历史/同业比较(研究域24)|Q1 FY3/2027 results (tanshin): share counts and capital;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域31)|FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves;直接证据 / 支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Dividend policy history: from the 40% payout target to the DOE progressive regime;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|Forecast bridge, May to August 2026: sales up JPY 9 billion, operating profit unchanged;直接证据 / 历史/同业比较(研究域21) / 反证(研究域33)|FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment
完整研究记录(核对用)
研究原文:From printed multiples to the recurring-earnings valuation|Printed multiples (PER 8.03x, ROE 26.6%, PBR 0.77-0.79x by book date, EV/EBITDA 5.7x) are distorted by asset-sale gains, Kwinana, exchange gains and a mixed-date EV; the recurring band implies 10-11x after tax with a 5% yield, and the discount's justification must come from conversion, not asset value.
内部研究类型:valuation_bridge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Margin of safety lives in band stability and the balance sheet; upside requires margin conversion.
不确定性(原始记录):Recurring multiple is a research construction; no consensus; denominators mix dates and share counts.
F092|13|最重要的三个问题都等同一份中期财报
研究范围:开放研究+35项覆盖检查
写入正文:13|最重要的三个问题都等同一份中期财报
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(30项,重复标签已合并)
IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print怎么使用:直接 / 支持;一手验证:30
IRBANK disclosure index: interim publication dates 2024-2026怎么使用:直接证据;一手验证:30;专项深挖:30
Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit怎么使用:直接 / 支持;一手验证:35
Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast怎么使用:直接证据;一手验证:35;反向验证:30;专项深挖:35
Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%怎么使用:直接 / 支持
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:支持证据;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%怎么使用:直接 / 支持;一手验证:16;反向验证:19;专项深挖:16
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation怎么使用:直接 / 支持;一手验证:04、20;反向验证:10
Impairment and forecast-revision notice (16 April 2026) on the disclosure index怎么使用:直接证据;反向验证:32;专项深挖:32
Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets怎么使用:直接 / 支持;一手验证:08、09、11、13;同业比较:30;其他用途:历史
Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines怎么使用:直接证据;一手验证:22;专项深挖:22
Share buyback precedent recorded in the 6th plan document (FY3/2024)怎么使用:直接 / 支持;同业比较:26;其他用途:历史
FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets怎么使用:支持证据;反向验证:22
FY3/2026 results: overseas scale is visible in segments but the overseas sales ratio is not disclosed怎么使用:直接 / 支持;反向验证:05;专项深挖:11;同业比较:11;其他用途:历史
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
Ownership beyond the anchor: what the controlling-shareholder filing does and does not show怎么使用:直接证据;一手验证:24;反向验证:01、23;专项深挖:24
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接证据;一手验证:05、07、10、23、24
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
Dividend policy history: from the 40% payout target to the DOE progressive regime怎么使用:支持证据;同业比较:13、22、26;其他用途:历史
FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive怎么使用:支持证据;一手验证:26;同业比较:31;其他用途:历史
Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation怎么使用:直接 / 支持;反向验证:27
Q1 FY3/2027 results (tanshin): share counts and capital怎么使用:直接证据;一手验证:25;同业比较:01、24;其他用途:历史
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接证据;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:直接证据;一手验证:18、21、29
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接证据;一手验证:18、19、29;反向验证:21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for 5351: interim-results cadence and the pending H1 FY3/27 print;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index: interim publication dates 2024-2026;直接证据 / 支持证据 / 一手证据(研究域35)|Forecast revision notice (10 August 2026): FY3/2027 forecast raised on sales, held on operating profit;直接证据 / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域35)|Forecast arithmetic: the implied Q2 and H2 inside the revised FY3/2027 forecast;直接证据 / 支持证据|Q1 FY3/2027 results (tanshin): first-quarter earnings - operating profit down 39.9%, net income up 166.2%;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据|Revision notice (August 2026): the stated second-half recovery mechanics in engineering;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 支持证据 / 一手证据(研究域16) / 反证(研究域19) / 定向深挖(研究域16)|Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 反证(研究域10)|6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation;直接证据 / 反证(研究域32) / 定向深挖(研究域32)|Impairment and forecast-revision notice (16 April 2026) on the disclosure index;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13) / 历史/同业比较(研究域30)|Vision 2030 and the 6th medium-term plan (13 May 2024): final-year and 2030 targets;直接证据 / 支持证据|FY3/2026 tanshin: management's framing of the final plan year;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Plan versus delivery: ROS and ROIC against the 6th plan's final-year lines;直接证据 / 支持证据 / 历史/同业比较(研究域26)|Share buyback precedent recorded in the 6th plan document (FY3/2024);支持证据 / 反证(研究域22)|FY3/2027 initial forecast (15 May 2026) against the medium-term plan's final-year targets;直接证据 / 支持证据 / 历史/同业比较(研究域11) / 反证(研究域05) / 定向深挖(研究域11)|FY3/2026 results: overseas scale is visible in segments but the overseas sales ratio is not disclosed;直接证据 / 支持证据|FY3/2026 results (tanshin): parent-only results against consolidated;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;直接证据 / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域23) / 定向深挖(研究域24)|Ownership beyond the anchor: what the controlling-shareholder filing does and does not show;直接证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves;支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Dividend policy history: from the 40% payout target to the DOE progressive regime;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域31)|FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive;直接证据 / 支持证据 / 反证(研究域27)|Q1 FY3/2027 results: the Kwinana land expropriation gain and the Australian relocation;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域01) / 历史/同业比较(研究域24)|Q1 FY3/2027 results (tanshin): share counts and capital;直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing
完整研究记录(核对用)
研究原文:Open Research Debt carried to the next Review|Priority-1 debt clusters on the unprinted H1 print, Reframax's recovery and the nature of the Q1 gross-margin compression; priority 2-3 covers the Ako impairment detail, overseas ratio, buyback stance, register and Kwinana relocation, plus gaps in ownership, competitive share and contingent liabilities. Each resolves only through disclosures first public after this review date or from retrievable annual notes.
内部研究类型:research_debt_set
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Opposite answers on priority-1 items decide whether the conversion thesis survives.
不确定性(原始记录):No reasonable current public path remains for priority-1 items; they are future-dated disclosures.
F093|01|七条因果链都落在同一个检验上:每单位收购来的规模换回多少营业利润
研究范围:开放研究+35项覆盖检查
写入正文:01|七条因果链都落在同一个检验上:每单位收购来的规模换回多少营业利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(28项,重复标签已合并)
FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop怎么使用:直接 / 支持;一手验证:05、11、12;外部现实校验:02、15、19
Q1 FY3/2027 narrative: demand conditions by end-market怎么使用:直接证据;一手验证:12;外部现实校验:05、11;专项深挖:05、12
FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering怎么使用:直接 / 支持;一手验证:02、03、08、10、15;同业比较:05;其他用途:历史
FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix怎么使用:直接 / 支持;一手验证:09、33;反向验证:12;同业比较:06;其他用途:历史
Gouda Refractories Group acquisition notices (24 October 2024) on the disclosure index怎么使用:直接证据;反向验证:09;专项深挖:09、25;同业比较:07、25;其他用途:历史
Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering怎么使用:直接 / 支持;一手验证:06、14、15;反向验证:16、35
Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment怎么使用:直接证据;一手验证:02;专项深挖:02、15
FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year怎么使用:直接 / 支持;一手验证:17、25;同业比较:19、20;其他用途:历史
FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment怎么使用:直接证据;反向验证:33;同业比较:21;其他用途:历史
Q1 FY3/2027 balance sheet: settlement of the FY3/2026 tax charge怎么使用:直接 / 支持;反向验证:17、25;专项深挖:18;同业比较:18;其他用途:历史
Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing怎么使用:直接 / 支持;一手验证:18、19、29;反向验证:21
FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment怎么使用:直接 / 支持;一手验证:32;反向验证:20、31;同业比较:16、28、35;其他用途:历史
6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation怎么使用:直接 / 支持;一手验证:04、20;反向验证:10
Impairment and forecast-revision notice (16 April 2026) on the disclosure index怎么使用:直接证据;反向验证:32;专项深挖:32
FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive怎么使用:直接 / 支持;一手验证:26;同业比较:31;其他用途:历史
Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy怎么使用:直接 / 支持;一手验证:26;专项深挖:26
Q1 FY3/2027 equity walk: retained earnings and valuation reserves怎么使用:直接 / 支持;一手验证:21;专项深挖:21、29
Dividend policy history: from the 40% payout target to the DOE progressive regime怎么使用:直接 / 支持;同业比较:13、22、26;其他用途:历史
Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale怎么使用:直接 / 支持;一手验证:05、07、10、23、24
IRBANK timely-disclosure index for 5351: takeover response policy and performance share units怎么使用:直接 / 支持;同业比较:23;其他用途:历史
Q1 FY3/2027 subsequent event: performance share unit disposal of treasury shares怎么使用:直接证据;一手验证:23;专项深挖:23
FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base怎么使用:直接 / 支持;一手验证:28;专项深挖:28;同业比较:02、09、12、15、17、27、33、35;其他用途:历史
FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:28、32;其他用途:历史
FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope怎么使用:直接 / 支持;一手验证:16;同业比较:29;其他用途:历史
Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%怎么使用:直接 / 支持;一手验证:16;反向验证:19;专项深挖:16
FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%怎么使用:支持证据;一手验证:18、21、29
Goodwill balance and amortisation run-rate at Q1 FY3/2027怎么使用:直接 / 支持;反向验证:06、18、29、35
FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost怎么使用:支持证据;一手验证:28;反向验证:13;同业比较:14、16;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 外部现实(研究域02) / 外部现实(研究域15) / 外部现实(研究域19)|FY3/2026 and Q1 FY3/2027 results: the domestic crude steel backdrop;直接证据 / 一手证据(研究域12) / 外部现实(研究域05) / 外部现实(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域12)|Q1 FY3/2027 narrative: demand conditions by end-market;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域10) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): segment sales and profit - refractories, insulation, advanced materials, engineering;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 历史/同业比较(研究域06) / 反证(研究域12)|FY3/2026 results (tanshin): consolidation scope changes - Reframax, the Danieli joint venture, Dynamix;直接证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域25) / 反证(研究域09) / 定向深挖(研究域09) / 定向深挖(研究域25)|Gouda Refractories Group acquisition notices (24 October 2024) on the disclosure index;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 反证(研究域16) / 反证(研究域35)|Q1 FY3/2027 results (tanshin): segment review - Reframax loss inside engineering;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 segment note: external sales by segment and the abolition of the 'other' segment;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域25) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20)|FY3/2026 cash flow: asset sales funded acquisitions and debt repayment in the same year;直接证据 / 历史/同业比较(研究域21) / 反证(研究域33)|FY3/2026 asset-sale programme: proceeds, use and the abolition of the leasing segment;直接证据 / 支持证据 / 历史/同业比较(研究域18) / 反证(研究域17) / 反证(研究域25) / 定向深挖(研究域18)|Q1 FY3/2027 balance sheet: settlement of the FY3/2026 tax charge;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域29) / 反证(研究域21)|Q1 FY3/2027 balance sheet at 30 June 2026: tax payment funded by short-term borrowing;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35) / 反证(研究域20) / 反证(研究域31)|FY3/2026 results (tanshin): special profits and losses - asset-sale gain against impairment;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 反证(研究域10)|6th medium-term plan: production-base restructuring - Ako as the western hub, eastern consolidation;直接证据 / 反证(研究域32) / 定向深挖(研究域32)|Impairment and forecast-revision notice (16 April 2026) on the disclosure index;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域31)|FY3/2026 results and FY3/2027 notices: dividend policy change from payout ratio to DOE progressive;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Dividend notices: FY3/2027 split of JPY 47 interim and JPY 48 year-end under the DOE policy;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域29)|Q1 FY3/2027 equity walk: retained earnings and valuation reserves;直接证据 / 支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 历史/同业比较(研究域26)|Dividend policy history: from the 40% payout target to the DOE progressive regime;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域10) / 一手证据(研究域23) / 一手证据(研究域24)|Controlling-shareholder matters notice (25 June 2026): JFE Steel's 34.9% holding and transaction scale;直接证据 / 支持证据 / 历史/同业比较(研究域23)|IRBANK timely-disclosure index for 5351: takeover response policy and performance share units;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Q1 FY3/2027 subsequent event: performance share unit disposal of treasury shares;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 历史/同业比较(研究域27) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35) / 定向深挖(研究域28)|FY3/2026 results (tanshin): prior-year comparatives - FY3/2025 as the pre-expansion base;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域32)|FY3/2026 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域29)|FY3/2026 profit-and-loss detail: gross margin held, SG&A stepped with the consolidation scope;直接证据 / 支持证据 / 一手证据(研究域16) / 反证(研究域19) / 定向深挖(研究域16)|Q1 FY3/2027 margin bridge: gross margin 20.1% against 25.2%;支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: goodwill doubling, debt reduction, equity ratio 46.1%;直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域18) / 反证(研究域29) / 反证(研究域35)|Goodwill balance and amortisation run-rate at Q1 FY3/2027;支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16) / 反证(研究域13)|FY3/2026 results (tanshin): what sits inside ordinary profit - foreign-exchange gains and interest cost
完整研究记录(核对用)
研究原文:Main causal chains of the enlarged group|Chains: (1) shrinking steel output means refractories profit must come from price, mix and overseas contribution; (2) the overseas acquisition sequence steps sales, SG&A and goodwill together; (3) Reframax project timing swings engineering and hence group operating profit; (4) property sales repaired the balance sheet but produced the tax bill that rebuilt short-term debt; (5) the impairment charges the restructuring and acquisition assets themselves and raises the burden of proof on the JPY 49bn intangibles; (6) the DOE regime makes the dividend a balance-sheet commitment; (7) JFE Steel's dual role plus defence ties demand stability and governance insulation to the steel group's path.
内部研究类型:main_causal_architecture
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Each chain ends in the same shareholder test: operating profit conversion per unit of acquired scale.
不确定性(原始记录):Chains 2-3 depend on unobserved H1/Q3 delivery.
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | 5c99403a1fd5e4313c9b50e9240acc5ed833418a |
| Delivery Commit SHA | 5c99403a1fd5e4313c9b50e9240acc5ed833418a |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | fcbac4f4-489f-5b8c-8c5f-bc434c1af074 |
| Canonical Revision | 1 |