公司自己口径的基础利润(剔除库存估值影响和一次性项目的经常利润)前九个月为51亿日元,上年同期32亿日元;第三季度单季经常利润16.67亿日元,没有新的一次性项目。焚烧灰渣再利用九个月经常利润25.89亿日元,利润率30.3%,已超过去年全年。分红按基础净利润的40%计算,2026年12月期预测股息17日元,股息率4.53%,总市值470.4亿日元低于账面净资产701.19亿日元。
5563
新日本電工株式会社(Nippon Denko Co., Ltd.)
新日本電工株式会社(Nippon Denko Co., Ltd.,东证 Prime 市场,代码5563)主营锰系铁合金,占销售额的62%,产品按国际基准价定价,供钢铁企业冶炼使用;同时经营功能材料(储氢合金、电池与电子材料)、焚烧灰渣再利用、水处理设备(aqua solutions)和水力发电。公司1925年10月创立,最大股东是日本制铁(Nippon Steel,持股24.29%)。
最近亮点:2026年11月6日披露的2026年12月期(FY12/26)前三季度财报(业绩快报)显示,营业利润73.15亿日元,增长131.6%,但经常损益亏损12.46亿日元,原因是马来西亚联营公司Pertama Ferroalloys被全额减值。当天收盘价375日元,下跌5.3%。 估值简报:股价375日元(2026年11月6日收盘)。总市值470.4亿日元。预测PER 93.5倍,联营公司减值压低了预测每股收益,倍数失真。实绩PBR 0.66倍。ROE 2.0%(2025年12月期实绩)。预测股息率4.53%。EV/EBITDA 5.9倍:EV=总市值+2026年9月30日净有息负债46.9亿日元;EBITDA=2025年12月期营业利润51.61亿日元+折旧摊销36.65亿日元,合计88.26亿日元。
本轮利润抬升靠的是欧洲保障措施带来的价格溢价、日元偏弱和库存估值,这三项都有期限或可逆。2026年12月期预测在第三季度没有下调,第四季度要兑现27.46亿日元经常利润,折成基础利润是24亿日元上下,而第三季度基础利润只有6亿日元左右。保障措施2026年之后的设计尚未公布。
Kabugami Score V3.2:60.97/100,评级B。操作以持有和耐心观察为主,2027年2月年报之前不追高。报表上的窟窿叠在一条正在改善的基础利润线上,但改善里有多少是自己挣来的、多少是政策溢价,要等第四季度业绩和第十次中期计划才能确认,目前对这一点的把握一般。 当前动作:以持有和耐心观察为主,不在2027年2月年报之前追高;若已持有,可以拿着4.5%上下的预测股息等待验证,新增仓位宜小、分批,等第四季度经常利润和第十次中期计划两个节点落地后再决定是否加码。若第四季度经常利润明显低于约27.46亿日元而价格并无暴跌、计划下调2027年12月期100亿日元目标、Pertama出现新的现金支持,或月收盘跌破约334日元,应回到0.3至0.5倍账面净资产的低谷框架重新定价,不靠摊平。
报告目录
01|投资问题与当前结论
01.1|2026年的报表窟窿,是周期反复上演的最后一幕吗
这只股票眼下要回答的问题很具体:2026年12月期前九个月经常损益亏损12.46亿日元,是不是锰价周期里同一出戏的尾声。同一时期营业利润是73.15亿日元。两个数字相差近86亿日元,出自同一份财报。
研究走到最后,这个问题被改写成两条时间线的赛跑。一条是2026年12月期预测和2027年12月期中期计划,能否在新社长手里兑现;另一条是欧洲保障措施带来的价格溢价还能维持多久。前者在2026年内公布的第十次中期计划和2027年2月年报上见分晓,后者在2026年之后怎么设计,至今没有公开。
前者赢,一家以0.67倍账面净资产交易、自有资本比率74.3%、分红按公式逐年抬升的公司,就有条件向2027年12月期计划靠拢。后者先到,这个折价就是市场对这套结构的合理定价。两种结果目前都没有被财报证实。
01.2|三条腿都在两个季度内接受检验
我们的判断是:报表窟窿是一次会计事件,下面的基础利润在改善,折价(0.67倍账面净资产,按75亿日元基础利润预测计为6.3倍)对它定价过重。这个判断站在三条腿上:第四季度兑现被推迟到年底的基础利润,新社长任内计划不被下调,Pertama清零后不再有新的现金支出。每一条都有日期明确的检验。
检验最集中的是第四季度。公司在第三季度保持全年预测不变,减去前九个月实绩,第四季度要交出27.46亿日元经常利润和36.85亿日元营业利润。交得出来,说明基础利润复苏的解释成立;交不出来,市场现在定价的「窟窿叙事」就被重新证实。
三条腿目前都没有结论:第四季度未发布,第十次中期计划未公布,Pertama的担保和出资承诺要等年度有价证券报告书。
01.3|反证有八条,但不是八个独立风险
这八条反证共同指向三件事:政策溢价会到期,报表利润的周期形状反复出现,全年预测的兑现压在最后一个季度。
具体是:一,欧洲保障措施带来的毛利率抬升,有可审查的有限期限;二,报表利润起伏很大,2022年12月期103.67亿日元的高点次年下降76%,2019年12月期的亏损与今年是同一种结构;三,预测后置,第四季度要有24亿日元上下的基础利润,第三季度只有6亿日元左右;四,上半年自由现金流为负,营运资金吸收了上行期的现金;五,功能材料在锂电正极材料代工合同终止后收缩;六,反收购方案在母公司轴线收紧的同时被废止;七,基础利润是管理层自己的口径;八,2027年12月期计划要求销售额增长17%,而国内钢铁需求平缓。
抵消这些的有三点:第三季度单季经常利润是干净的,Pertama这条利润表渠道已经关闭,资产负债表已经吸收过两次谷底冲击。
八条之间并不独立,政策、周期和预测形状三个驱动共享其中好几条,不能当作八个单独的负面来数。真正的风险在于它们同时发生,一起拖垮三条腿。
01.4|能被承接的是地位,不是某一年的利润
这家公司可以被持有的东西有五样:国内整合后的锰系合金地位,许可制灰渣回收带来的30%上下经常利润率,自有水力发电,74%自有资本比率加有价证券缓冲,以及在报表亏损年份仍然付出的分红公式。
靠不住的是报表利润的水平本身。同一套资产,七年里报表经常利润从亏损64.26亿日元,到103.67亿日元,再到2026年预测的15亿日元,因为锰价、库存估值和权益法联营公司都砸在同一条利润线上。
价格侧的三个观察位(559日元、400日元、334日元)属于第10章的技术结构,只作为已有日期的参照,不用基本面叙事去改写它。
01.5|操作思路:持有观察,等两个节点落地再决定加码
以持有和耐心观察为主,2027年2月年报之前不追高。已经持有的,可以拿着4.5%上下的预测股息等待验证;新增仓位宜小、分批,等第四季度经常利润和第十次中期计划两个节点落地后再决定是否加码。
出现以下任何一种情况,就应回到低谷定价框架(研究设定的0.3至0.5倍账面净资产,是研究框架,不是披露事实)重新定价,不靠摊平:第四季度经常利润明显低于27.46亿日元而价格并无暴跌;计划下调2027年12月期100亿日元目标;Pertama出现新的现金支持;月收盘价跌破334日元上下。
02|公司本质与商业模式
02.1|五台引擎共用一个屋顶,其中最大的一台跟着锰价走
新日本電工(Nippon Denko,法定日文名新日本電工株式会社)是日本制铁集团内的铁合金整合者,靠五条业务线赚钱:锰系铁合金占销售额的62%,按国际基准价定价;功能材料、焚烧灰渣再利用、水处理设备(aqua solutions)和水力发电,加上规模很小的「其他」。公司1925年创立,2025年10月迎来创业百年。
分部利润按经常利润层面计量,五个分部加调整项等于合并经常利润。这意味着铁合金分部里装着马来西亚权益法联营公司的损益。公司没有披露产品级的收入拆分。
02.2|同一家公司说两种利润语言,读分部必须看拆分
公司同时公布两套数字:报表经常利润,受锰价周期、库存估值和一次性损益影响;管理层的基础利润,剔除库存估值影响和一次性项目。两者经常相差几十亿日元。
只看分部销售占比,或只看报表每股收益,都会在周期两端误判这家公司。具体数字和背后的会计原因放在第6章展开。基础利润由管理层自己构造,历年口径一致,但没有作为系列经过审计。
02.3|可以持有的是国内合金地位加回收年金,不是任何一年的盈利
这家公司的长期地位由几块组成:国内合并后的锰系合金生产、许可制灰渣回收、自有水力、74%自有资本比率加有价证券缓冲,以及一个在报表亏损年份也执行了的分红公式。当前的价格上行、联营公司减值和中期计划,都是叠在这个地基上的增量,替代不了地基。
自我修复已经被检验过:资产负债表、灰渣和水力利润以及分红底线,吸收了2019年12月期和2026年两次谷底冲击。最坏情形是保障措施到期与价格暴跌同时发生,公司历史上没有这样的先例。
对股东来说,持有的是一块以账面净资产以下价格交易、回报有公式支撑的耐久地位,代价是接受周期性、政策依赖的报表利润,以及接近股权成本的资本效率。合金护城河只是成本曲线位置,回收业务的护城河证据停留在结构层面,没有合同层面的证据,大额投资的回报也还没有被证明。
03|产品、客户与供应链
03.1|国内合金真正赚钱,但被联营公司的亏损盖住了
国内铁合金是这家公司的变数最大的盈利来源。基础利润上半年14亿日元(报表24亿日元),第三季度单季7亿日元(报表15亿日元)。可铁合金分部九个月报表却亏损53.56亿日元,销售额366.21亿日元,因为马来西亚联营公司Pertama被记在了同一个分部里。
2026年12月期的分部基础利润计划是:国内20亿日元,海外亏损4亿日元。2025年12月期剔除权益法损失和库存影响后,铁合金分部基础利润也是正的。
这些分部基础利润来自管理层说明会数字,不是经过审计的分部披露。
03.2|矿石、电力和日元共同决定合金价差
所有铁合金产品都依赖进口锰矿,按每Mn%美元计价(2025年4.5美元,2026年第二季度5.4美元,第三季度4.8美元),还依赖炉用电力和日元汇率(上半年157至160日元兑1美元,下半年公司假设155日元,第三季度实际159日元左右)。
矿石和电力成本滞后进入销售成本,合金价格却是浮动的,这个时间差就是利润周期。日元走弱同时抬高合金的日元售价和矿石的日元成本,保障措施有效时价格端占上风。矿石价格急升同时日元转强,是典型的价差被挤压。
矿石价格与保障措施支撑的合金价格之间的价差,是铁合金利润的核心。公司没有披露供应商身份、合同条款、套期保值和汇率敏感度,这些只能从市场价格表推断。
03.3|合金需求来自粗钢产量和贸易流向,国内不增长
铁合金需求是派生需求,跟着粗钢产量和受保障措施影响的欧美贸易流向走,国内钢铁需求平缓偏降。增长因此只能靠整合、产能和产品结构,不能指望市场本身。管理层的说明把上半年和第三季度的利润构成更多归因于价格和估值,而不是销量。
灰渣需求跟废弃物量走,稳定得多;水处理设备的交付按项目排期;水力发电量稳定。客户名称和销量均未披露,2027年12月期的钢铁需求展望要等第十次中期计划。
03.4|焚烧灰渣回收:九个月经常利润已超过去年全年
集团里被低估的第二台引擎是焚烧灰渣再利用。前九个月销售额85.32亿日元,经常利润25.89亿日元,利润率30.3%(上半年15.21亿日元;2025年12月期全年20.74亿日元,利润率23.3%),九个月已经超过去年全年。2026年12月期基础利润计划为29亿日元。
它是集团里利润率最高、对合金价格最不敏感的利润来源。客户是自治体和产业废弃物排出方,按废弃物法律把灰渣交给公司处理并回收熔融金属,处理需求不跟金属价格走。这也是为什么铁合金分部报表亏损时,灰渣分部仍赚了25.89亿日元。
利润率能否保持,取决于熔融金属价格的回落幅度;鹿岛扩建增加的产能和回报没有量化,许可续期和新进入者也没有证据。
03.5|功能材料:被寄予厚望的第二增长业务在收缩
功能材料前九个月经常利润9.66亿日元,利润率9.7%,2025年12月期全年是19.23亿日元,利润率13.0%。原因是2025年11月锂离子电池正极材料代工合同被部分终止,储氢合金需求也走弱,电子零部件材料只抵消了一部分。2026年12月期基础利润计划为12亿日元,电池材料的投资仍在继续。
这家公司对代工客户的敞口只能从终止通知里看到,替代产品或替代销量没有披露。
04|竞争格局与产业关系
04.1|整合让它成为国内参照级供应商,但没有份额数据来印证
这家百年老厂靠整合活到今天:2014年通过换股拿下同业中央电气工业,2024年7月1日吸收合并;2021至2022年停掉鹿岛的高碳锰铁炉,把产能集中;现在锰系合金集中在高冈和鹿岛,原中央电气的妙高和和歌山工厂以及德岛、郡山也在生产体系内。
整合给了它两样东西:低谷里的价格韧性,和上行期完整落到这家公司身上的经营杠杆。这也是2026年上行落在这张利润表上力度很大的原因。
研究没有取得同业对标或独立的市场份额数据,国内参照级供应商的判断来自整合历史;对手是否新增产能或退出,也未知。
04.2|保障措施是眼下最大的单一利润变量,也是有期限的
欧洲对铁合金进口的保障措施,是集团目前最大的单一利润变量,比任何管理层能控制的经营杠杆都大。管理层把价格上涨主要归因于这项措施:它拉动了日本出口需求和国内价格,欧洲高碳锰铁从2025年均价每吨1,175美元涨到2026年第三季度的1,335美元,美国基准价为1,345至1,361美元。
传导链是:保障措施抬高进口价格上限,国内合金价格跟着抬高,2026年12月期毛利率随之跳升。保障措施失效时,国内溢价会向进口平价压缩。这项措施有可审查的有限期限,2026年之后的设计还没有公开。
与之相对,废弃物法律支撑灰渣处理量,等于给第二台引擎垫了一层政策底。
05|护城河判断
结构性的那一半是:冶炼技术、废弃物处理许可、自有水力发电,以及整合后的国内地位。灰渣回收业务靠许可和废弃物量托底,是真正耐久的部分。
铁合金本身的优势只是成本曲线位置,不是定价权。2026年毛利率从14.8%升到22.3%,相当一部分来自保障措施带来的政策溢价,这不属于护城河,期限有限。
反面证据有两条:没有同业对比或独立份额数据来印证国内地位;功能材料作为第二增长业务,九个月经常利润9.66亿日元,对比去年全年19.23亿日元,并不稳固。股东持有的是一个下行时仍有利润来源的基本盘,而不是可以定价的合金垄断;周期上行时放大收益,但保障措施带来的溢价不应当成长期因素。
06|财务质量与现金流
06.1|同一家公司公布两套利润,差距可以达到一倍
看这家公司的利润,先要知道它同时公布两套数字。一套是报表经常利润,受锰价周期、库存估值和一次性损益影响;另一套是公司自己的基础利润,剔除库存估值影响和一次性项目。2025年12月期两者相差一倍:报表经常利润27.03亿日元,基础利润53亿日元。
差距的来源在分部口径里。分部利润按经常利润层面计量,五个分部加调整项等于合并经常利润,所以马来西亚权益法联营公司的损益直接记在铁合金分部里。
基础利润是管理层自己的构造,历年口径一致,但没有作为系列经过审计,季度之间也没有完整的拆分表。
06.2|利润抬升来自价格,不来自销量
2026年12月期前九个月销售额只增长1.8%,营业利润却增长131.6%,达到73.15亿日元。毛利润131.32亿日元,上年同期85.74亿日元,毛利率从14.8%升到22.3%。
驱动链有三环。欧洲对铁合金进口的保障措施,把欧洲高碳锰铁价格从2025年均价每吨1,175美元推到2026年第三季度的1,335美元;日元停在159日元兑1美元左右,抬高了合金的日元售价;锰矿价格从第二季度每Mn% 5.4美元回落到第三季度4.8美元,价差进一步拉宽。库存估值同时有利,把毛利放得更大。
营业端的拐点出现得更早:第一季度营业利润已增长99.6%,比联营公司减值冲击经常损益早一个季度。价格型利润在持续期间转化率高,回落时同样快,比销量型利润更容易逆转。价格、汇率和库存估值各自的贡献,公司只披露合计数,无法再拆。
06.3|Pertama全额减值,把一份财报拆成两层
Pertama是马来西亚的权益法联营公司,记在铁合金分部里。2026年12月期第二季度,母公司单体计入特别损失78.77亿日元;合并后变成权益法投资损失,上半年合计77.33亿日元,其中71.80亿日元是超出联营公司日常亏损份额的减值部分。
结果是上半年经常损益亏损29.13亿日元,前九个月亏损12.46亿日元,上半年净亏损26.89亿日元(每股收益亏损21.55日元)。权益法亏损大多不能抵税,所以亏损年份税负依然偏重。
营业端同期完全相反:基础利润前九个月51亿日元,上年同期32亿日元。营业温度和报表温度之间,只差这一次减值。基础利润是管理层口径,减值在母公司和合并口径之间的分拆是清楚的,现金影响却不清楚。
06.4|这条利润表渠道已经关闭,现金渠道还没有核对
作为利润表项目,Pertama已经结束。第三季度只新增0.1亿日元左右,累计77.43亿日元;账面价值为零;2026年12月期基础利润预测里,海外部分只按亏损4亿日元左右计入,海外业务预计2027年12月期才回到基础利润盈利。
剩下的问题在现金端。已审阅的中期和第三季度文件,没有披露对Pertama的新增贷款、担保或出资。文件没披露,不等于不存在,年度有价证券报告书可能披露担保或出资承诺。这是「联营公司已清零」这个判断目前没有闭合的缺口,要到2027年3月才能核对。
06.5|减值、库存评估损和联营公司损失,不是第一次一起出现
2019年12月期经常亏损64.26亿日元,减值损失、库存评估损和联营公司股份评估损三项同时出现(2020年1月30日披露),与2026年结构一致,相隔七年。2025年12月期联营公司的权益法损失已有13.92亿日元,Pertama的拖累在减值之前就存在。
把整条时间线放在一起:2020年12月期经常利润34.92亿日元,2021年68.70亿日元,2022年103.67亿日元见顶。此后2023年降到24.65亿日元(下降76.2%),2024年48.59亿日元,2025年27.03亿日元(下降44.4%)。同一套资产,报表经常利润在亏损64亿和盈利104亿日元之间起伏;基础利润在2023至2025年12月期始终落在52至55亿日元之间。
所以减值、库存评估损和联营公司损失,应当看成这套商业模式在周期转折点会反复付出的成本,2026年这一笔又是清理步骤里最大的一笔。这种结构叠在价格周期上,放大了报表利润的起伏。Pertama退出能否关掉这条渠道,取决于上面说的现金敞口,也取决于未来是否出现新的联营公司或库存转折。
06.6|上行期利润和现金反向走,谷底反而释放现金
2026年上半年营业利润增长164.5%,营业现金流却从92.24亿日元降到24.94亿日元:价格上涨时,库存和应收款先吃掉现金。投资活动现金流出36.07亿日元,自由现金流为负。鹿岛灰渣熔融炉扩建的在建工程,从2025年12月末的6.91亿日元升到6月末的30.67亿日元、9月末的34.47亿日元。
2025年12月期是同一台机器的反面。营业现金流145.69亿日元,是净利润14.18亿日元的十倍以上,来自折旧、不涉及现金的权益法亏损和营运资金释放。它覆盖了48.28亿日元左右的资本开支、40.31亿日元的回购和分红,自有资本比率仍有76.0%。
传导链在库存上。库存263.97亿日元(成品133.33亿日元,原材料及物料130.64亿日元;6月末分别为175.44亿日元和100.93亿日元),相当于年销售额的三分之一。价格转折先通过库存估值进入报表利润,之后才进入现金,库存既放大利润,也是下行时第一个吸收损失的资产。
账面库存不能当作可随时变现的下行价值:库存按产品的构成、所有权、计价基础和变现折价,公司都只披露合计数,第四季度库存方向也未知。半年现金流有季节性,2026年12月期年度现金流量表是否与110亿日元营业利润预测匹配,才是干净的检验。对分红和回购来说,报表最难看的年份反而最安全,因为谷底会释放现金;上行期考验的是现金覆盖,不是利润。
06.7|资产负债表比利润表结实,但不是净现金
2026年9月30日总资产944.04亿日元,净资产701.19亿日元,自有资本比率74.3%(2025年12月末为76.0%)。有息负债142.05亿日元,高于现金57.47亿日元;投资证券145.26亿日元(2025年12月末为191.54亿日元,减值在2026年传入);土地53.48亿日元按成本入账,现有材料中没有评估价值。
关键的缓冲在权益层面。前九个月净亏损13.80亿日元,综合收益却是盈利6.15亿日元,因为有价证券的未实现收益计入净资产而不经过利润表。每股净资产因此只从2025年12月末的569.17日元降到9月末的562日元左右。
因此,0.67倍账面净资产并不等于0.67倍清算价值。但有价证券收益不是现金,不能直接支付分红;土地的隐含增值可能存在,没有量化;证券按市价计,会随股市波动,年末的债务和证券余额也还没出来。偿债不是眼下的问题,资金怎么分配才是。
06.8|五处会计呈现需要对照着读,否则会低估这家公司
2026年有五处会计呈现,各自把报表利润压到经营实况以下(2022年的高点则相反):母公司单体特别损失78.77亿日元,与合并口径的权益法损失增加额71.80亿日元(上半年合计77.33亿日元)不是同一个数;库存估值放在毛利润里;权益法亏损大多不能抵税,税前亏损时税负依然偏重;其他综合收益吸收了净资产层面的证券收益,前九个月综合收益盈利6.15亿日元,净亏损13.80亿日元;分部经常利润把联营公司藏在铁合金分部里。
这是一份证据质量的对照表,不是对造假的推定。内容来自财报附注本身,没有做独立审计;2027年3月的有价证券报告书可能增加新的一次性项目类别。依赖报表每股收益筛股的人,在周期两端都会误判这只股票。
06.9|资本效率低于目标,最好的口径下也只接近股权成本
2025年12月期ROE为2.0%,2024年12月期为4.5%(每股收益10.70日元对24.35日元,营业利润率6.7%对8.8%,经常利润对总资产3.0%)。盈利基础一年里减半,资产负债表没有受到冲击。
按基础利润折算,年化水平的ROE在7%至8%之间,这是研究的推算,低于10%的目标,接近股权成本。公司没有公布自己的资本成本估计和ROIC,ROIC只能用ROE近似。2026年12月期ROE和第十次中期计划里的资本效率表述都还没出来。
07|股东、董事与治理
07.1|日本制铁握着控制权框架,少数股东的条件取决于对方的善意
日本制铁持股24.29%(2025年12月期有价证券报告书的股东名册,剔除库存股)。其后是Master Trust Bank of Japan信托账户11.41%、Japan Custody Bank信托账户2.79%、交易伙伴持股会2.00%、日铁矿业1.68%、员工持股会1.50%。
这一持股比例触发每年3月东证的「控股股东等相关事项」披露(2024年3月28日、2025年3月28日、2026年3月27日),控股股东框架是实际存在的。2026年1月29日公司废止了反收购方案,少了一层少数股东保护,母公司轴线却在收紧。公司采用监察等委员会设置公司的治理结构。母公司很可能提供治理、原料和客户渠道,商业条款没有披露。
信托账户持股属于托管,日本制铁的持股变化只能在EDINET大量持股报告里看到。「轴线在收紧」是解读,日本制铁没有明确表态。在估值上,这是0.67倍账面净资产里的结构性成分:少数股东要问的是共处的条件,多年的股东名册并没有把倍数推高,这一联系带解读性质,没有哪份文件直接证明。
对股东并非全是负面:分红公式在报表亏损年仍然执行,回购和注销也有实际动作。
07.2|社长换成日本制铁原料部门出身者,执行可信度和集团影响一起上升
2027年1月1日起,现任社长Aoki Yasushi转任无代表权的董事兼顾问。接任代表董事社长的是小林次郎,1965年生,1988年进入日本制铁,2013年任其欧洲办事处负责人,2017至2023年主管原料部门。他2024年3月起任新日本電工董事,持有25,900股。
这次更替与第十次中期计划同步,公司表示该计划将在2026年内公布。一位熟悉原料市场的社长,对管理铁合金价差有实际价值,也会加深母公司的影响;同一事件还将交出确认或重设2027年12月期目标的文件,少数股东正是按这些目标定价。
计划的具体内容、治理框架是否变化、社长的激励机制和董事会讨论细节,目前都没有公开。
08|资本政策
08.1|分红按基础利润算,所以报表亏损年份也照付
股东回报政策有三部分:基础净利润(基础经常利润乘0.7)的40%左右作为派息;年度最低分红从10日元提高到11日元(2026年12月期起,因为股数减少);回购作为灵活的补充。
2025年12月期分红12日元(中期6.00日元,期末6.00日元,含1日元百年纪念分红),按报表每股收益10.70日元算派息率112.1%;按政策使用的基础口径看并不突出,14.8亿日元上下,大致就是1.25亿股左右付12日元的成本。2026年12月期预测股息从最初的13.00日元提高到17.00日元(中期5.50日元已决议,期末11.50日元),对比预测每股收益4.01日元,派息率超过400%,这是联营公司减值造成的假象,不是政策失灵。
用基础利润核对:75亿日元乘0.7再乘40%是21亿日元,17日元乘1.254亿股是21.3亿日元,两者吻合。预测股息率4.53%(股价375日元)。这是公式把基础口径变成现金的地方:报表亏损年份付出17日元,股数还被削减了8.69%,基础故事先于报表故事送到股东手里。
期末11.50日元在2027年2月决议前仍是预测,没有正式的股息率上限或下限承诺,第十次中期计划可能固化或改动这个公式。
08.2|回购加注销,让同一笔分红资金落到更高的每股金额
2025年8月至10月,公司通过ToSTNeT-3回购约40.31亿日元股票,10月28日完成;2025年12月末持有库存股12,597,919股,占已发行137,386,472股的9.17%。2026年8月21日注销11,948,808股(占已发行8.69%),已发行股数降到125,437,664股;资本公积从174.84亿日元降到138.29亿日元,用来吸收注销。9月末财报显示库存股为零。
回购和11日元分红底线是同一个每股政策的两半:注销8.69%股份,同一笔分红资金对应的每股金额就更高。回购的资金来自2025年12月期145.69亿日元的营业现金流,同时覆盖了资本开支和分红。融资是借款支撑营运资金,没有增发股票;每股指标靠注销大约一成的股数反复抬升。
日本制铁和稳定持股者支撑着股东名册,少数股东拿到公式分红,也是2025年回购的对手方;浮动股的回报取决于公式和回购节奏能否延续,这两者在报表亏损年份都保住了。回购价格相对正常化价值是否合理,除对账面的折价外没有评估,未来回购节奏由公司自行决定。
08.3|到2030年计划投入450至500亿日元,回报要看灰渣扩建能否守住30%利润率
战略投资计划到2030年共450至500亿日元,节奏是上一期计划的三倍左右,对比年度营业利润50亿至110亿日元并不轻;另有第九期计划内的研发32亿日元和数字化投资40亿日元,主要投向铁合金竞争力、灰渣回收产能和功能材料。
执行首先体现在在建工程:鹿岛灰渣熔融炉扩建(2025年11月公布),在建工程从2025年12月的6.91亿日元升到2026年9月的34.47亿日元。如果扩建能按灰渣分部现在30%的经常利润率赚钱,谷底盈利就会结构性抬升;利润率回落,投资案和下行保护会一起变弱。
作为电炉冶炼企业,公司承诺2030年度二氧化碳排放(范围1+2,对比2015年度)至少减少45%,德岛燃气发动机发电装置(2025年12月)是其中一步。项目级回报和总投入都没有披露,在建工程转固的时间和二氧化碳成本也无法量化。
09|估值与安全边际
09.1|估值简报:几个倍数各用不同的期间和利润口径
价格为2026年11月6日收盘: 股价375日元;总市值470.4亿日元(按8月注销后的已发行125,437,664股计)。 预测PER 93.5倍(2026年12月期预测每股收益4.01日元;数据商显示93.66倍;被联营公司减值压低的每股收益扭曲了这个倍数)。 实绩PBR 0.66倍(2025年12月末每股净资产569.17日元;按2026年9月末562日元左右算为0.67倍;数据商显示0.67倍,2009年以来区间0.28至1.9倍)。 ROE 2.0%(2025年12月期实绩)。 预测股息率4.53%(2026年12月期预测股息17日元)。 EV/EBITDA 5.9倍:EV 517.3亿日元,等于总市值加2026年9月30日净有息负债46.9亿日元(短期借款50.00亿日元、一年内到期长期借款15.50亿日元、长期借款38.87亿日元,减现金57.47亿日元);EBITDA 88.26亿日元,等于2025年12月期营业利润51.61亿日元加折旧摊销36.65亿日元。
口径上有三点要对着看:多个倍数混用了2025年12月期实绩和2026年12月期预测的分母;EBITDA用的是2025年12月期实绩,而2026年12月期营业利润预测已接近110亿日元;这里的净有息负债只计借款项,与前文资产负债表上142.05亿日元的有息负债合计口径不同,材料中没有拆分两者的差额。
09.2|同一个股价,三种利润口径,三个倍数
对这只股票,倍数取决于用哪种利润语言。375日元对应470.4亿日元市值,低于2026年9月末701.19亿日元的账面净资产;按75亿日元基础经常利润预测计是6.3倍,按15亿日元报表经常利润预测计是31倍,按4.01日元预测每股收益计是94倍。
市场定价的是报表窟窿和母公司轴线,没有给基础利润或计划定价。折价已经存在多年,市净率2009年以来在0.28至1.9倍之间,0.67倍处于区间偏下;2025年12月末账面口径自有资本比率76.0%,按市值计算只有47.8%,这个落差就是常驻折价的一个数字。
账面也有缓冲:证券收益让每股净资产在三个报表亏损的季度里仍保持在562日元左右,所以0.67倍账面净资产不等于0.67倍清算价值,当然证券收益也不是现金。控制关系是折价里的结构性成分。重估靠兑现,不靠论证。
基础口径的倍数用的是管理层的非公认会计准则数字,账面净资产也含证券缓冲,没有取得分析师一致预期,因此对估值的把握一般。
09.3|正常化盈利是50亿至75亿日元的区间,上半部分靠政策溢价
基础经常利润历年是:2023年12月期55亿日元,2024年52亿日元,2025年53亿日元,2026年预测75亿日元(最初约60亿日元;上半年45亿日元对22亿日元,前九个月51亿日元对32亿日元)。对比报表经常利润从亏损64亿到盈利104亿日元,正常化区间大致是50亿至75亿日元。
2026年的预测已经包含上行期的价格,所以区间上沿不是谷底数字:下半部分经过谷底检验,上半部分靠保障措施的价格。按区间上沿算是6.3倍,市场付的是区间的兑现,没付计划的钱。
基础利润是管理层的非公认会计准则构造,公司没有公布完整的季度拆分,第十次计划之后是否继续披露也没有保证。
09.4|2027年12月期100亿日元目标,需要的不是价格,是三件还没发生的事
第九期中期计划(2024至2027年度)的2027年12月期目标是销售额950亿日元、经常利润100亿日元、ROE 10%;2030年构想是销售额不低于1100亿日元、经常利润不低于130亿日元、ROE不低于10%。基数是2023年度销售额764亿日元、经常利润25亿日元(基础利润55亿日元)、ROE 6%。
对比2025年12月期实绩(销售额772.77亿日元、经常利润27.03亿日元、ROE 2.0%)和2026年12月期预测(销售额811亿日元、基础利润75亿日元),2027年12月期这一步需要销售额增长17%,经常利润再增25亿日元。
这一步大部分要来自海外扭亏(基础亏损4亿日元回到盈利)、功能材料恢复和灰渣扩建,不是价格。功能材料如果继续收缩,需要由其他两项承担的份额更大;Pertama扭亏是计划的前提之一。计划还隐含保障措施的溢价大体延续,这使保障措施的后续设计成为计划层面的事件。第十次中期计划将确认或重设目标,目前尚未公布。
09.5|ROE接近股权成本时,低于账面价值有其算术上的合理性
在ROE(2025年12月期2.0%,基础利润口径7%至8%,均为研究推算)达到资本成本以前,以账面净资产以下交易是说得通的。10%的目标需要100亿日元经常利润,并且不再有新的权益拖累。
研究没有找到公司自己的资本成本估计,ROIC只能用ROE近似,所以这条判断的精度受限,要等2026年12月期ROE实绩和第十次中期计划里的资本效率表述。
09.6|下行靠资产和年金托底,不靠盈利
下行保护的来源是:自有资本比率74.3%、145亿日元证券、按成本入账的土地、11日元分红底线,以及不跟合金价格走的灰渣和水力利润。灰渣的处理需求来自废弃物量,所以报表最差的2026年,这块仍有25.89亿日元利润。2019年12月期的谷底结构,资产负债表也已吸收过。
保护在十年里被检验过两次,都守住了。现实的下行情形是回到225至300日元的旧底部区间;研究用0.3至0.5倍账面净资产作低谷定价框架,这是研究框架,不是披露事实,不是财务困境。
反方向的分量是:保障措施失效和价格暴跌同时发生,公司的历史上没有先例。保护是用公司自己的谷底历史构造出来的。
10|Kabugami 技术结构
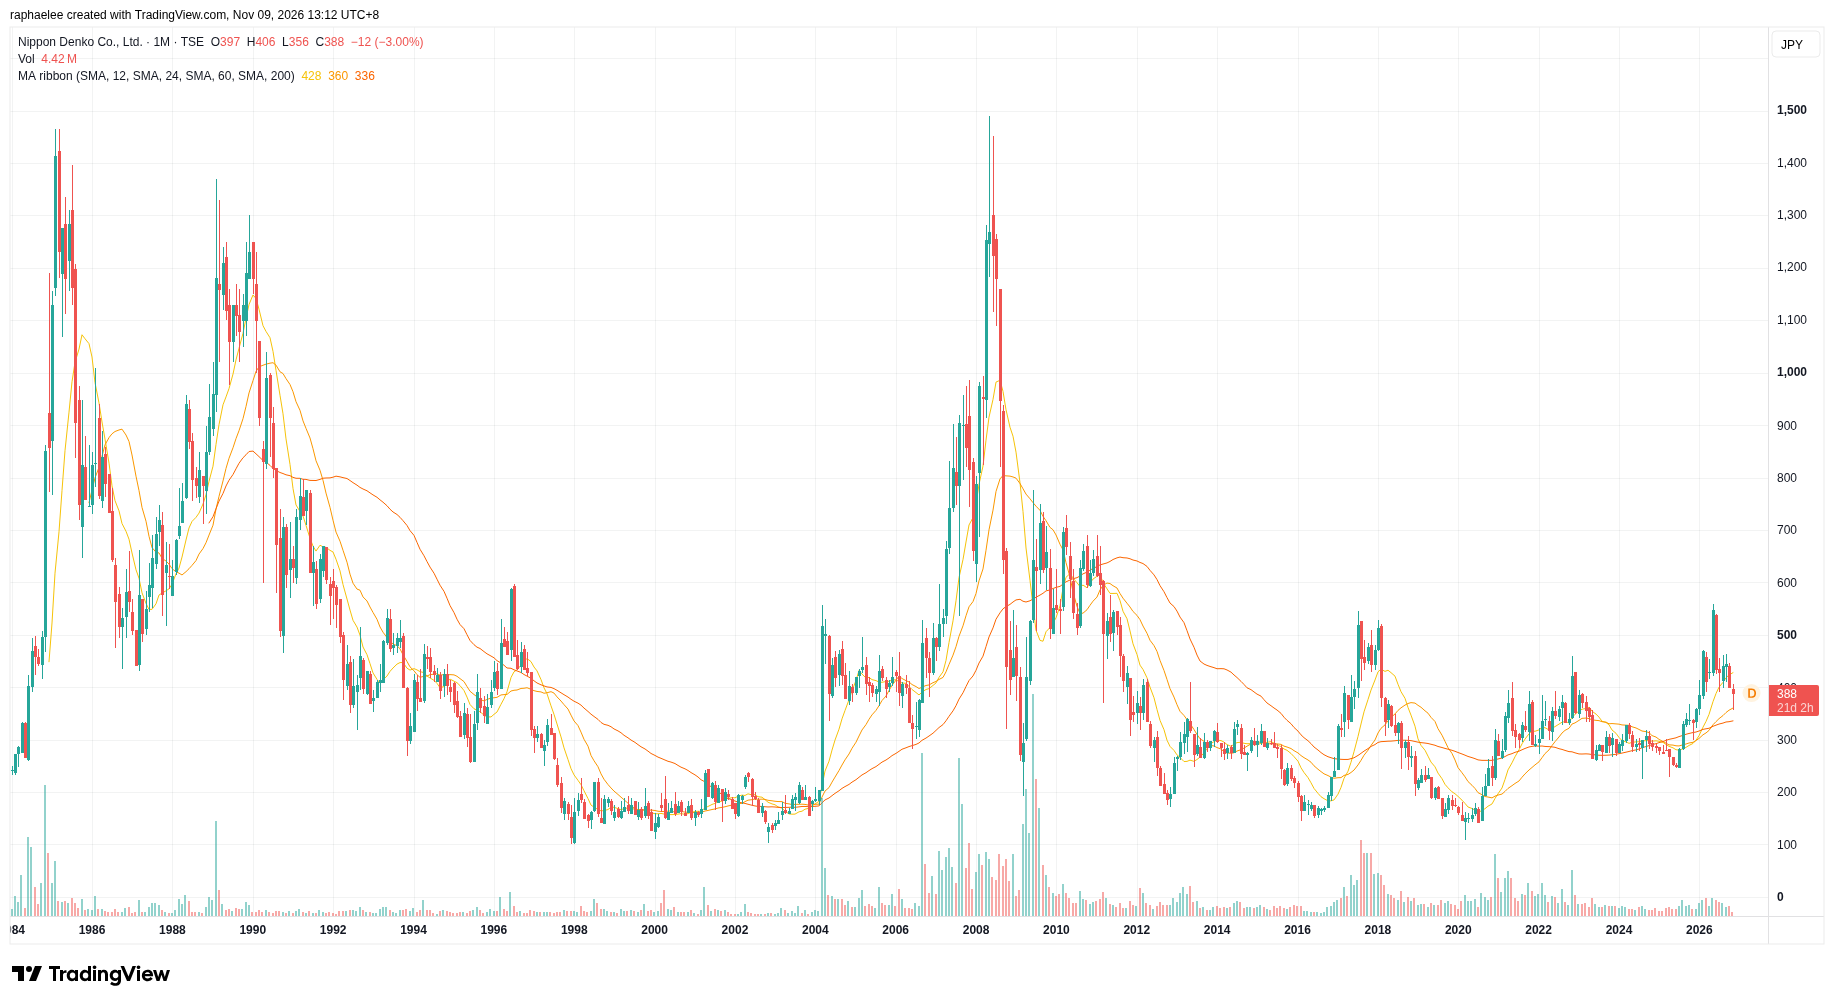
10.1|这轮上涨,是脱离二十五年底部,还是又一次冲高回落
这一章要回答的问题是:2025至2026年的上涨,把价格带出了持续二十五年的100至400日元底部,这是2008年以来第一次;2026年5月冲到559日元之后,价格回落到390至463日元的整理区。这是一次世代级的脱离,暂停在第一轮脉冲之后,还是会像2017年冲高那样,又回到这个底部?
分析依据2001年1月至2026年10月共310根月线,价格为未复权的原始价格,数据末端有缺失,已确认可用至2026年10月27日;2026年11月只有11月6日的日线收盘价375日元可用,未完成的11月月线不作确认。观察日为2026年11月9日。
10.2|二十五年价格史分五段,每次冲高都没有守住
第一段是锰价大周期:价格从2002年11月的低点102日元涨到2008年5月的历史高点1,476日元,同年崩到321日元,2009年反弹到750日元后失败。第二段是十年衰退,2016年2月跌到145日元,中间只有2017年冲到545日元,当年内回落。
第三段是最后一次洗盘:2019年低点148日元,2020年3月108日元,距离历史低点102日元只有一步之遥;2021至2022年反弹到459日元也失败,价格回到225至394日元的底部,度过2023至2024年。
第四段从2025年开始。4月低点228日元,8月放量突破(成交2,165万股,约为2024年月均水平的2.3倍),收盘330日元;2025年12月收盘358日元,2026年2月收盘469日元。第五段是2026年5月冲到559日元(收盘547日元,成交2,330万股),6月反转收盘434日元,6月到10月在390至463日元之间整理,10月收盘412日元,成交量降到944万股;11月6日日线收盘375日元。
10.3|价格长期活在100到400日元,500日元上方筹码稀薄
310个月收盘价里,大约45%低于300日元,100到400日元之间的四个价格带合计占213个月,高于500日元的只有9%上下。2026年的交易区间390至559日元,上一次停留较久是2007至2010年,2017至2018年只是短暂停留,所以500日元上方的承接历史上很薄,涨跌两个方向的行情都很快(2008年崩盘,2017年冲高回落)。
10月收盘价412日元,在2001至2026年全部价格区间(低102日元,高1,476日元)中只处于22.6%的高度。这只股票在自己年轻的新结构里站在中间,在自己一生的价格范围里却还在下四分之一。
对应地,价格在400日元上方只停留过寥寥数月:2007至2010年,2017至2018年的短暂几个月,和2026年初以来。能不能在这个高度站得住,本身就是后续几个月要验证的事实。
10.4|底部在逐代抬高,但向上只被验证过一次
每一轮下跌的终点比较:2020年3月的108日元已接近2002年的102日元,之后2024至2025年的低点抬到225至228日元。每一次洗盘都比上一次在更高处停下,这是一个在缓慢修复的结构的特征。向上的修复力只被验证到559日元,也就是2026年5月那一轮脉冲。
支撑位从下往上看:2026年6至10月整理区的底部390日元附近,其下是2025年高点368日元和60个月均线334日元,再往下是2024至2025年低位区225至249日元。压力位是2026年5月脉冲区547至559日元,再上是2009年反弹高点750日元,750日元以上唯一的参照是2008年1,476日元的历史高点。
价格重心方面,当前结构的重心靠近12个月均线424日元,略高于10月收盘价412日元。历史上的主要运行区间则低得多:100到300日元的长期反复停留价格带,才是价格如果完全失守时的深层落脚区。
10.5|第一轮脉冲已用完,回踩停在底部上沿而不是里面
2026年5月冲高559日元,6月收盘434日元,这一轮脉冲是目前的失败脉冲:只要没有月收盘超过559日元,这个高点就是买盘已被验证的上限。
它的失败到目前为止是有序的:五个月的390至463日元整理,没有向旧底部崩落。这与2017年和2021至2022年不同——那两次的脉冲在数月内就重新回到了底部。这次的区别在于,回踩停在了底部的上沿,没有回到底部里面。
放量脱离是真实的:2025至2026年月成交量是2024年月均水平的2到2.5倍。但按这只股票自己的历史,高质量的脱离(2009年、2021至2022年)恰好在这个阶段失败过两次。形态上,二十五年的水平底部加一次正在进行的脱离尝试,中间没有阶梯式的台阶,所以一旦解决,历史上两个方向都很快(2008年、2017年、2020年)。
10.6|均线、压缩与量能:站稳尚未确认,也没有触发结构重置
2026年10月收盘412日元,12个月均线424日元,24个月均线357日元,60个月均线334日元:长期均线仍在上行,价格处在12个月均线之下、24个月均线之上。11月6日日线收盘375日元,位于12个月与24个月均线之间,靠近24个月均线一带,是警戒位置,不是重置。
6至10月月线振幅收窄,成交量从5月的2,330万股降到10月的944万股,属于年轻底部里的温和压缩。它支持耐心,不支持择时判断:这只股票的底部,历史上在长期安静之后往往解决得很猛烈。
从2008年1,476日元的高点算起,十八年后价格只回到过它的38%,这个旧下跌的影响半衰期很长;高点是遥远的参照和心理上限,不是近期目标。三条均线与基准位构成观察指标:12个月均线看短期结构保持,390日元底部加24个月均线看底部完整,559日元高点看延续。目前三者还没有一个触发结构重置。
10.7|当前状态是试探性脱离,内部矛盾是高度和证明不匹配
这里把当前纯价格状态叫作「试探性脱离」:价格放量离开长期底部,只有一轮脉冲,尚未被后续走势确认。全章只用这个名字。
旧的下跌状态在一代人以前就结束了,长期底部已经被放量离开过一次,第一轮脉冲已经用完,底部仍在建。内部矛盾是高度和证明之间的落差:价格站在二十五年里只有几个月停留过的区间,成交热度又从5月的峰值回落;结构说底部被突破了,价格行为却还没有交出第二轮证明。
决定性的区域是390至400日元一带和24个月均线能否在2027年2月业绩前后守住。技术把握一般。
10.8|业绩日的价格反应:先对放量定价,后对利润表语言打折
纯价格状态形成之后,再看价格对公开信息的反应。2026年11月6日第三季度财报披露,营业利润增长131.6%、全年预测不变,价格却下跌5.3%到375日元,收在12个月均线下方、24个月均线附近。同一份文件里,还有前九个月经常亏损这一行,下跌与它的时间重合;把下跌归因于亏损标题,是解读,价格本身无法证明。
作为对照,2025年8月的放量突破,是在业绩确认之前就被买盘接下的。这只股票最近的价格反应是不对称的:对价格和成交量事实付钱,对利润表语言打折。
价格与基本面的时序关系是价格领先:2025年8月的放量脱离,领先于后来公开确认的营业利润大幅增长两个报告期。安全的说法是,价格结构的变化早于后来被公开确认的基本面变化。现在两者在等同一份证据:第四季度财报和第十次中期计划。这些事件不是技术成因,只是价格响应的证据。
10.9|价格上什么会确认,什么会推翻
会确认的价格行为:月收盘价超过559日元,把一次失败脉冲变成延续;2027年2月业绩季里月收盘持续守在400日元上方,使整理区仍然站在旧平台之上;2027年全年最低价高于2024至2025年的低位区(225至249日元),延续逐代抬高的低点。
会让这个状态降级或被推翻的价格行为:月收盘跌破60个月均线(334日元上下),价格重新落入旧平台的引力范围;月收盘跌破249日元,等于否定这次脱离,重新打开长期底部;放量回测225至228日元,意味着是派发而不是筑底。
本章全部结论只来自价格证据,基本面事件只在上面作为价格响应出现。
11|风险与催化剂
11.1|第四季度必须交出27.46亿日元经常利润
2026年12月期全年预测在第三季度保持不变:销售额811亿日元(增长5.0%)、营业利润110亿日元(增长113.1%)、经常利润15亿日元(下降44.5%)、净利润5亿日元(每股收益4.01日元)。减去前九个月实绩,第四季度要交出经常利润27.46亿日元,约为上年同期的2.1倍;营业利润36.85亿日元,上年同期是20.02亿日元左右。
第三季度单季经常利润16.67亿日元,没有新的一次性项目,是目前对年化水平最干净的读数。另一条推算:基础利润预测75亿日元减去前九个月51亿日元,第四季度要有24亿日元,对比第三季度的6亿日元,而第三季度是季节上最弱的一个季度,所以不能只靠年化水平,价格和库存效应也得出力。
推算用的是四舍五入的整数和管理层的非公认会计准则口径,这个季度还没有发布。兑现了,基础利润复苏的解释成立;落空了,市场现在定价的窟窿叙事被重新证实。
11.2|保障措施一旦到期,影响的是计划,不只是毛利率
2027年12月期100亿日元的计划目标,隐含保障措施带来的国内溢价大体延续。这项措施的下一版设计目前未公开,所以它的审查结果是计划层面的事件:溢价被压向进口平价,2026年毛利率从14.8%跳到22.3%的那部分就会回吐。
成本侧另有一条典型的挤压路径:矿石价格急升同时日元转强。灰渣和水力的利润不受影响,可以缓冲,但无法覆盖合金价差的收窄。
11.3|接下来两个季度的节点,各解开一层「两种利润语言」
催化剂在未来两个季度密集出现,之后回到看周期。每一个节点各回答一个问题:计划回答目标,年报回答兑现,分红回答公式。
具体顺序:第十次中期计划(2026年内公布,具体日期未定);2027年1月1日社长更替;2027年2月的年报,检验第四季度推算值;期末分红决议(预测11.50日元);2027年3月的控股股东事项披露。
仓位大小宜尊重2027年2月这个二选一的节点;这些事件各自的影响幅度,事前无法估算,第四季度的推算数字定义的是惊喜的方向。
11.4|什么会推翻这个判断
三条腿各有一个推翻条件:
第四季度经常利润远低于27.46亿日元,而锰铁价格没有崩跌,基础利润复苏的解释被推翻;第十次中期计划下调2027年12月期100亿日元的经常利润目标,靠计划兑现的重估逻辑随之被推翻;Pertama出现新的现金支持,关于联营公司已清零的判断被推翻;价格方面,月收盘价跌回2025年的低位区间(225至249日元),说明脱离没有被接受,月收盘跌破60个月均线(334日元上下)则让第10章的技术结构降级。
任何一条腿断了,就回到低谷定价框架重新定价(研究框架0.3至0.5倍账面净资产),不靠叙事摊平。价格条件属于技术结构,不由基本面叙事回答。
12|反常识发现
12.1|同一份财报,营业利润大增,市场却盯着亏损那一行
11月6日的第三季度财报,同时载着营业利润增长131.6%、全年预测不变和前九个月经常亏损,市场的第一反应是下跌5.3%到375日元。被定价的是亏损。
仓位数据显示散户在秋天之前明显一边倒:融资买入1,750,300股,融券卖出26,600股,比例65.8倍。这个数据是7月中旬的,到11月已经陈旧。由此推断,散户相信得早,机构似乎在等第四季度;这是从价格和融资余额反推出的预期,没有取得分析师一致预期。
如果这个推断成立,不对称的结果是:第四季度兑现,会被晚相信、快定价;落空,则会坐实窟窿叙事。
12.2|灰渣扩建把利润率、资本开支和下行保护绑在了一起
灰渣再利用分部同时承担三个论点:它是利润率最高的利润来源(30.3%),是在建工程里可见的增长资本去向,也是2023至2025年12月期保护谷底利润的年金。鹿岛扩建是账面里信息量最大的一项资本决定。
如果扩建的盈利接近当前的利润率,谷底盈利就会结构性抬升;如果熔融金属价格回落,年金和投资案会一起走弱。产能增量和回报都没有披露,这是这条结论目前最大的缺口。
13|下一次值得跟踪什么
13.1|第四季度会不会交出27.46亿日元经常利润
以下几项欠账里,前三项对估值的影响最大。多数要等2027年2月年报、第十次中期计划和2027年3月有价证券报告书才能解开,目前没有更早的公开路径。
第四季度是头号问题,因为它决定窟窿是否被证实为会计噪音。公司需要交出27.46亿日元经常利润(库存影响和锰铁价格允许的情况下),否则会在年报时下调全年预测。反过来:没有价格崩跌而落空,就推翻基础利润复苏的解释。解开它的证据是2027年2月年报、第四季度库存余额和市场价格表。
13.2|Pertama清零之后,还会不会消耗现金
这是已经写掉的最大价值毁灭源头的残余现金风险。问题是:股权账面价值为零,敞口是否真的关闭,还是联营公司仍可能通过贷款、担保或追加出资消耗现金。
如果出现新的现金支持,「联营公司已清零」这条腿就被推翻。已审阅的文件没有披露这些事项,但文件没披露不等于没有。解开它的证据是2027年3月的2026年12月期有价证券报告书附注(担保与承诺),以及任何新的TDnet公告。
13.3|保障措施到期或重新设计后,国内溢价和那段毛利率还剩多少
这是对计划和正常化利润最大的外部风险,研究中两次上调了它的优先级。问题是:欧洲保障措施在2026年后到期或改版,国内铁合金溢价以及2026年12月期毛利率从14.8%到22.3%的跳升,还有多少留得住。
如果到期,毛利率会向进口平价压缩,削弱2027年12月期计划。后续设计未公开,仅凭公司披露无法估算幅度。解开它的证据是欧盟保障措施审查公告、公司风险披露和进口价格数据。
13.4|第十次中期计划会设定什么目标,会不会保留100亿日元和分红公式
这是从基础利润走向更高估值的桥。问题是:2026年内公布的第十次中期计划,对2027至2029年12月期设定什么,是否保留100亿日元经常利润目标和现行分红公式。
下调目标,会拿走靠计划兑现的重估逻辑;公式变动,则会改变股东回报的锚。解开它的证据就是计划文本本身,公布日期只说了「2026年内」。
13.5|灰渣利润率能否保持,功能材料是复苏还是继续缩小
这两项决定集团有没有第二台增长引擎。灰渣方面:熔融金属价格正常化后,30%上下的经常利润率能否保持,鹿岛熔融炉扩建增加多少产能和利润。利润率回落,会拿走谷底年金,削弱投资案。解开它的证据是到2027年12月期的分部业绩和炉子产能披露;项目回报和产能增量目前未披露。
功能材料方面:在锂电正极材料代工合同终止和储氢合金需求走弱之后,是复苏,还是缩向电子材料的核心。继续缩小,会让计划那一步更多压在灰渣和海外扭亏上。解开它的证据是2027年2月年报的分部注释和第十次计划里的分部战略;替代产品或销量没有披露。
13.6|母公司轴线和价格高度这两件,优先级较低但要继续看
治理方面:日本制铁24.29%的持股、已废止的反收购方案、以及出自其原料部门的新社长,是否会改变资本政策或公司在集团里的最终定位。这是解读性问题,现有材料里没有日本制铁的表态。持股或定位变化会向两个方向重估治理折价。解开它的证据是2027年3月的控股股东事项披露、EDINET大量持股报告和第十次计划中的定位表述。
价格方面:突破400日元之后,能否守过2027年2月年报,还是像2017年那样退回长期底部。这个问题只能由未来的月线行为和业绩日的价格反应回答,不能用基本面叙事回答。
13.7|还有哪些证据缺口会限制几项判断的精度
几项判断目前只能做结构性描述:没有取得同业对标或独立市场份额数据;矿石供应商身份与合同条款、客户名称与销量、产品级收入和研发管线没有披露;ROIC和公司自己的资本成本没有公布;没有分析师一致预期;土地按成本入账,没有评估。
这些缺口会影响护城河、竞争地位和资本回报的判断强度。解开它们要等有价证券报告书里的披露,或者本次没有取得的第三方数据;在那之前,不能把公司不披露当成风险不存在,也不能当成优势存在。
14|Kabugami 评分卡
14.1|总分60.97/100,评级B,操作以持有观察为主
评分版本V3.2,满分100分,评级B(55至64.9分档)。八个模块的得分/满分合计60.97/100。
一句话理由:地基扎实(自有资本、灰渣年金、分红公式),但利润是价格型、现金滞后、第四季度未兑现,保障措施和第十次中期计划两个外部变数没有解开,所以盈利质量、估值和护城河都没有给高分。操作以持有和耐心观察为主,2027年2月年报前不追高。
14.2|基本面七个模块:各自得分与一句理由
财务韧性与下行防御 9.75/13:自有资本比率74.3%,净资产701.19亿日元,两次谷底都扛住了;但有息负债142.05亿日元高于现金57.47亿日元,不是净现金,2026年上半年自由现金流为负。
竞争优势与结构耐久性 8.4/14:整合地位、许可业务和自有水力是结构优势;合金价格优势来自政策溢价,没有同业数据印证,功能材料在收缩。
盈利质量、现金转化与资本效率 8.5/17:营业利润73.15亿日元与经常亏损12.46亿日元并存,利润是价格型且现金滞后,基础利润口径ROE为7%至8%(研究推算),第四季度未兑现。
商业结构、产品、客户与关键依赖 5.72/11:锰系铁合金占销售额六成,客户、矿石合同和汇率敏感度均未披露,2027年12月期计划的利润台阶,证据最少。
估值与安全边际 10.5/15:0.67倍账面净资产、4.53%股息率和6.3倍基础利润倍数给下行托底;多个倍数口径不同,94倍市盈率是减值的结果,要等兑现。
资本配置与股东回报 6.8/10:公式分红在报表亏损年仍然支付,注销8.69%股份、没有增发;但新投资的回报率与资本成本没有披露。
治理、所有权与管理层 3.5/7:日本制铁持股24.29%,反收购方案被取消,新社长出自其原料部门,少数股东的条件没有合同保证。
14.3|技术结构 7.8/13:脱离了长期底部,但只有一轮脉冲
Kabugami 技术结构 7.8/13:价格2025年8月放量脱离长期低位平台,旧的下跌状态已明显失去控制,新结构只有一轮脉冲,没有被确认;500日元上方历史承接很薄。结论只来自价格证据,详见第10章。
14.4|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 9.75 | 2026年9月底自有资本比率74.3%,净资产701.19亿日元,投资证券约145亿日元,土地按成本入账。有息负债约142亿日元,高于现金约57亿日元,所以不是净现金公司,但偿债没有压力。2019年12月期的亏损和2026年的联营公司减值,资产负债表都扛住了,账面净资产每股约562日元,基本没动。 |
| 竞争优势与结构耐久性 | 14 | 8.4 | 公司创立已满百年,通过合并中央电气工业等同业,把国内锰系铁合金集中到高冈、鹿岛等工厂,是国内参照级供应商。冶炼技术、废弃物处理许可和自有水力发电构成结构性优势;铁合金本身的优势只是成本曲线位置,不是定价权。灰渣再利用业务九个月经常利润25.89亿日元,利润率30.3%,有许可和废弃物量托底,是真正耐久的部分。 |
| 盈利质量、现金转化与资本效率 | 17 | 8.5 | 账面与实际经营差异很大。2026年12月期前九个月营业利润73.15亿日元(增长131.6%),经常损益却是亏损12.46亿日元,原因是Pertama联营公司减值,上半年权益法损失77.33亿日元。公司自己口径的基础经常利润前九个月约51亿日元,上年同期约32亿日元。基础利润过去三年在52至55亿日元区间,2026年指引约75亿日元;2025年12月期ROE仅2.0%,基础利润口径下约7%至8%,接近股权成本。 |
| 商业结构、产品、客户与关键依赖 | 11 | 5.72 | 锰系铁合金约占销售额六成,价格按国际基准定,需求来自粗钢产量与保障措施下的贸易流向,国内需求偏弱。进口锰矿按每Mn%美元计价(2025年4.5美元,2026年第二季度5.4,第三季度4.8),电力与日元同样影响成本。灰渣、水力发电和水处理需求相对稳定,功能材料受锂电代工合同终止与储氢合金需求疲弱拖累。 |
| 估值与安全边际 | 15 | 10.5 | 11月6日收盘价375日元,市值约470.4亿日元,低于2026年9月底的净资产701.19亿日元,市净率约0.67倍;按基础经常利润指引75亿日元计约6.3倍,按报表经常利润指引15亿日元约31倍,按预测每股收益4.01日元约94倍。预测股息17日元,股息率4.53%,EV/EBITDA约5.9倍(EBITDA取2025年12月期实绩)。多个倍数的利润口径和期间不同,94倍市盈率是减值压低每股收益的结果,不能直接比较。 |
| 资本配置与股东回报 | 10 | 6.8 | 股东回报按基础净利润约40%的公式执行,年度最低分红从10日元提高到11日元,回购作为补充。2025年8月至10月回购约40.31亿日元,2026年8月注销11,948,808股(占已发行8.69%),已发行股数降至125,437,664股;没有增发。2026年12月期预测股息17日元,按约1.254亿股计约21.3亿日元,与基础利润75亿日元乘0.7再乘40%的约21亿日元吻合,所以在报表亏损年仍付出分红,不是政策失灵。 |
| 治理、所有权与管理层 | 7 | 3.5 | 新日铁持股24.29%,是控股股东框架下的第一大股东,每年发布控股股东事项报告(2024年、2025年、2026年3月)。反收购方案已于2026年1月29日取消,同时2027年1月1日起由新日铁原原料部门出身的小林次郎接任社长,2024年3月起已是公司董事。这种组合提升执行可信度,也提高集团对公司的影响,少数股东的条件没有合同保证。公司实行监察等委员会设置。 |
| Kabugami 技术结构 | 13 | 7.8 | 月线数据覆盖2001年1月至2026年10月。价格25年间主要在100至400日元之间运行,2008年5月高点1,476日元后一直没有接近。2025年8月放量离开长期低位平台,2026年5月高点559日元,6月收盘434日元;此后到10月在390至463日元之间整理,10月收盘412日元,11月6日收盘375日元,位于12个月与24个月均线之间。旧的下跌状态已明显失去控制,新的结构还只有一轮脉冲,没有确认。 |
总分: 60.97 / 100 评级: B 操作建议: 以持有和耐心观察为主,不在2027年2月年报之前追高;若已持有,可以拿着4.5%上下的预测股息等待验证,新增仓位宜小、分批,等第四季度经常利润和第十次中期计划两个节点落地后再决定是否加码。若第四季度经常利润明显低于约27.46亿日元而价格并无暴跌、计划下调2027年12月期100亿日元目标、Pertama出现新的现金支持,或月收盘跌破约334日元,应回到0.3至0.5倍账面净资产的低谷框架重新定价,不靠摊平。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|主要来源与日期:公司披露为主,市场数据和说明会记录为辅
本报告的基本面事实主要来自公司在东京证券交易所披露的财报和公告(TDnet)。其中有2025年12月期全年财报(2026年2月12日)、2026年第一季度财报(2026年5月12日)、中期财报及联营公司减值公告(2026年8月5日)、第三季度财报(2026年11月6日)和社长更替公告(2026年10月29日)。
持股结构来自经产省G-Biz Info转载的2025年12月期有价证券报告书数据(2026年3月31日);中期计划来自公司官网英文摘要(2023年11月29日)。公司正式英文名为Nippon Denko Co., Ltd.,来自上述公开资料。
市场数据来自数据商IRBANK(价格、估值倍数、信用余额,截至2026年11月6日);价格历史来自Yahoo Finance图表数据的本地组装月线,确认可用至2026年10月27日。2026年8月24日的中期说明会记录来自转录服务Logmi Finance,不是公司原始披露文件。
15.2|数据截止与证据局限
评审日为2026年11月9日,价格截止2026年11月6日收盘,月线数据完整到2026年10月;2026年12月期第四季度业绩、第十次中期计划和2027年3月有价证券报告书都发布在这个截止日之后,不在本报告之内。
以下局限限定了相关判断的强度:没有取得同业对标和独立市场份额数据;矿石供应商和合同条款、客户名称与销量、产品级收入和研发管线均未披露;ROIC和公司自己的资本成本未公布;没有分析师一致预期;土地按成本入账,没有评估;基础利润和分部基础利润是管理层构造,没有经过审计;价格和融资余额来自数据商,其中融资余额是7月中旬的,已经陈旧;价格历史是未复权的原始价格,末端有缺失;中期说明会内容来自转录服务。这些缺口里,多数要等有价证券报告书里的披露或第三方数据才能解开。
本报告是研究性分析,不构成投资建议。公司披露中的预测、基础利润和计划目标均为公司或研究的估计,实际结果可能不同,读者应结合自身情况独立判断。
主要资料来源
- FY December 2026 third-quarter earnings report (tanshin), consolidated
- FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions
- Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary
- Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile
- FY12/25 tanshin: segment sales and ordinary profit for the full year
- IRBANK results headline history for 5563, FY12/2019 to FY12/2025
- FY12/26 Q1 tanshin: headline results and the margin turn
- Notice on the valuation loss on affiliate shares and the equity-method investment loss
- Interim briefing record: overseas ferroalloy path and functional-materials headwinds
- Notice on the change of representative director (president)
- Notice on the publication of the 100th anniversary history (founding October 1925)
- Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026
研究发现索引
展开本次 Review 的 85 项研究发现
F001|01|2026年的报表窟窿,是周期反复上演的最后一幕吗
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|2026年的报表窟窿,是周期反复上演的最后一幕吗
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接证据;一手验证:06、12、14、16
Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary怎么使用:直接证据;一手验证:04、11、30
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接证据;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
查看完整证据标签(核对用)
直接证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter;直接证据 / 一手证据(研究域04) / 一手证据(研究域11) / 一手证据(研究域30)|Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary;直接证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table
完整研究记录(核对用)
研究原文:Reconciled core question after Research: is the FY12/26 reported-earnings hole (nine-month ordinary loss of JPY 1,246 million beside operating profit of JPY 7,315 million) the last act of a recurring manganese-cycle pattern, after which a safeguard-fed ferroalloy upcycle, a roughly 30%-margin ash-recycling engine and a formulaic rising shareholder return on a 74%-equity balance sheet at about 0.67x book re-rate the stock toward the FY12/27 plan? Or do policy-dependent prices, a back-loaded forecast and a strengthening Nippon Steel axis make the discount the correct price for the structure? Research resolves this into a race between two dated processes: delivery of the Q4 FY12/26 forecast and the FY12/27 plan under a new president, versus the finite life of the safeguard premium that created the current margin.
内部研究类型:investment_question
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Frames every other node: the shareholder outcome depends on whether the underlying run-rate is earned and policy-durable or borrowed from a reviewable trade measure.
不确定性(原始记录):The answer is open until the February 2027 annual print and the 10th medium-term plan; both are unprinted at the 2026-11-09 cutoff.
F002|02|五台引擎共用一个屋顶,其中最大的一台跟着锰价走
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|五台引擎共用一个屋顶,其中最大的一台跟着锰价走02|同一家公司说两种利润语言,读分部必须看拆分06|同一家公司公布两套利润,差距可以达到一倍
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、07、24
FY12/25 tanshin: segment sales and ordinary profit for the full year怎么使用:直接 / 支持;一手验证:02;同业比较:02、09、15;其他用途:历史
FY12/25 tanshin: shareholder-return policy statement怎么使用:直接 / 支持;一手验证:25、26
FY12/26 interim tanshin: segment information note (sales, segment profit)怎么使用:直接 / 支持;外部现实校验:02;专项深挖:02
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接 / 支持;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24)|Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15)|FY12/25 tanshin: segment sales and ordinary profit for the full year;直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|FY12/25 tanshin: shareholder-return policy statement;直接证据 / 支持证据 / 外部现实(研究域02) / 定向深挖(研究域02)|FY12/26 interim tanshin: segment information note (sales, segment profit);直接证据 / 支持证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months
完整研究记录(核对用)
研究原文:Nippon Denko (legal name Shin Nippon Denko), a Nippon Steel-group ferroalloy consolidator, earns through five engines under one roof: manganese ferroalloys (about 62% of sales, priced off international benchmarks), functional materials, incineration-ash recycling, aqua solutions and hydroelectric power, plus a small 'other'. Segment profit is measured at the ordinary-profit level and the segments plus adjustments sum to the consolidated ordinary result, so the ferroalloy segment carries the Malaysian equity-method affiliate inside it. The company therefore speaks in two profit languages that routinely differ by billions of yen: statutory ordinary profit (cycle, inventory valuation and one-offs) and management's 'underlying' ordinary profit (ex inventory effects and one-offs). Segment reads must use the underlying/reported split, never sales shares alone.
内部研究类型:business_model_and_profit_languages
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Reading reported EPS alone mispriced this stock in both directions across the cycle; the segment/underlying split decides what profit actually belongs to the ordinary shareholder.
不确定性(原始记录):Underlying is management's own construction, consistent across years but unaudited as a series; no product-level revenue split is disclosed.
F003|06|减值、库存评估损和联营公司损失,不是第一次一起出现
研究范围:开放研究+35项覆盖检查
写入正文:06|减值、库存评估损和联营公司损失,不是第一次一起出现
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY December 2025 full-year earnings report (tanshin), consolidated怎么使用:直接 / 支持;一手验证:22;同业比较:12、14;其他用途:历史
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接 / 支持;一手验证:12、29、33;同业比较:28、35;其他用途:历史
IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:29、33;反向验证:35;专项深挖:29、33;同业比较:08、10、11;其他用途:历史
FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure怎么使用:直接证据;一手验证:28;外部现实校验:12、16、28;专项深挖:12、16、28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14)|FY December 2025 full-year earnings report (tanshin), consolidated;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域29) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 反证(研究域35) / 定向深挖(研究域29) / 定向深挖(研究域33)|IRBANK disclosure index: the FY12/19 loss notices (30 January 2020);直接证据 / 一手证据(研究域28) / 外部现实(研究域12) / 外部现实(研究域16) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure
完整研究记录(核对用)
研究原文:The ordinary-profit record shows a manganese sawtooth: FY12/19 loss of JPY 6,426 million, FY12/20 JPY 3,492 million, FY12/21 JPY 6,870 million, FY12/22 peak of JPY 10,367 million, FY12/23 JPY 2,465 million (-76.2%), FY12/24 JPY 4,859 million, FY12/25 JPY 2,703 million (-44.4%), while underlying ordinary profit stayed in a band of about JPY 5.2-5.5 billion across FY12/23-25. History warns against extrapolating the top of the cycle: the reported series swings from -6.4 to +10.4 billion yen on the same asset base, with a smoother underlying band beneath it.
内部研究类型:cycle_history
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The market's discount partly reflects a long record of whipsaw in reported profit; only the underlying band has been stable.
不确定性(原始记录):Cycle dating rests on the company's own price tables and profit record; no external cycle index was pulled.
F004|06|减值、库存评估损和联营公司损失,不是第一次一起出现
研究范围:开放研究+35项覆盖检查
写入正文:06|减值、库存评估损和联营公司损失,不是第一次一起出现
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接 / 支持;一手验证:12、29、33;同业比较:28、35;其他用途:历史
IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)怎么使用:直接证据;一手验证:09、33;外部现实校验:29、33;反向验证:35;专项深挖:29、33;同业比较:08、10、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据|FY12/25 tanshin: segment note and non-operating items;直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域29) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 反证(研究域35) / 定向深挖(研究域29) / 定向深挖(研究域33)|IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)
完整研究记录(核对用)
研究原文:The FY12/26 affiliate write-down is the second time impairment, inventory write-down and affiliate-share valuation losses have blown a hole in reported profit: FY12/19 (ordinary loss JPY 6,426 million, notices of 30 January 2020) carried the same three-part anatomy seven years earlier, and the Pertama equity-method drag already existed in FY12/25 at JPY 1,392 million. The pattern is a recurring feature of the business model, not a one-off accident.
内部研究类型:recurring_pattern
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):If affiliate and inventory write-downs recur at cycle turns, the clean-up thesis must be priced as a recurring cost of the model; the 2026 charge is also described as the largest clean-up step.
不确定性(原始记录):Whether the Pertama exit closes the recurrence channel depends on undisclosed cash exposure (see research debt) and on future affiliates or inventory turns.
F005|06|利润抬升来自价格,不来自销量
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|利润抬升来自价格,不来自销量14|基本面七个模块:各自得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接 / 支持;一手验证:06、12、14、16
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接 / 支持;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter;直接证据|FY12/26 Q1 tanshin: headline results and the margin turn;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary
完整研究记录(核对用)
研究原文:The FY12/26 operating surge is a price-and-valuation event, not a volume event. Nine-month operating profit rose 131.6% to JPY 7,315 million and gross margin jumped from 14.8% to 22.3% (gross profit JPY 13,132 million against JPY 8,574 million) while sales rose only 1.8%, because European high-carbon ferromanganese rose from a 2025 average of USD 1,175/t to USD 1,335/t in Q3 2026 under safeguard protection, the yen stayed near 159 per dollar, and inventory valuation was favourable. Q1 already showed the operating turn (operating profit +99.6%) a quarter before the affiliate charge hit below the line; ore eased from USD 5.4 to 4.8 per Mn% in Q3, widening the spread.
内部研究类型:causal_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Price-led profit converts at high incremental margin while it lasts and reverses the same way; it is more reversible than volume-led profit.
不确定性(原始记录):Persistence depends on safeguard design and the yen; the split between price, FX and inventory valuation within quarters is disclosed only in aggregate.
F006|06|Pertama全额减值,把一份财报拆成两层
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|Pertama全额减值,把一份财报拆成两层
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Notice on the valuation loss on affiliate shares and the equity-method investment loss怎么使用:直接 / 支持;一手验证:32
FY12/25 tanshin: income-statement bridge and non-operating items怎么使用:直接证据;同业比较:16、32;其他用途:历史
FY12/26 interim tanshin: interim income statement detail怎么使用:直接证据;一手验证:16;反向验证:32
Affiliate write-down notice: impairment mechanics and P&L routing怎么使用:直接证据;一手验证:32;外部现实校验:32;反向验证:16、21、29、33;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 支持证据|FY December 2026 interim earnings report (tanshin), consolidated, Japanese GAAP;直接证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;直接证据 / 支持证据 / 一手证据(研究域32)|Notice on the valuation loss on affiliate shares and the equity-method investment loss;直接证据 / 历史/同业比较(研究域16) / 历史/同业比较(研究域32)|FY12/25 tanshin: income-statement bridge and non-operating items;直接证据 / 一手证据(研究域16) / 反证(研究域32)|FY12/26 interim tanshin: interim income statement detail;直接证据 / 一手证据(研究域32) / 外部现实(研究域32) / 反证(研究域16) / 反证(研究域21) / 反证(研究域29) / 反证(研究域33) / 定向深挖(研究域32)|Affiliate write-down notice: impairment mechanics and P&L routing;直接证据|FY12/26 Q3 tanshin: nine-month underlying ordinary profit (JPY 5.1 billion)
完整研究记录(核对用)
研究原文:Pertama Ferroalloys (Malaysian equity-method affiliate inside the ferroalloy segment) was impaired in full in Q2 FY12/26: a parent-level special loss of JPY 7,877 million became, on consolidation, an equity-method loss of JPY 7,733 million in H1 (JPY 7,180 million of it the write-down beyond the running loss share). This turned reported ordinary profit to -JPY 2,913 million at H1 and -JPY 1,246 million at nine months and net profit negative (EPS -JPY 21.55 at H1), because taxes stay booked as equity-method losses are largely non-deductible. Underlying ordinary profit was about JPY 5.1 billion over nine months against JPY 3.2 billion a year earlier: the operating temperature and the reported temperature differ by one impairment.
内部研究类型:impairment_event
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Reported EPS collapsed by an accounting event that does not reflect the operating business; valuation on the statutory print overstates the multiple (about 94x forecast EPS) against about 6.3x on underlying.
不确定性(原始记录):The underlying figure is management's own series; the split of the charge between parent and consolidated routing is clear but the cash consequence is not.
F007|06|这条利润表渠道已经关闭,现金渠道还没有核对
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Affiliate write-down notice: impairment mechanics and P&L routing怎么使用:直接 / 支持;一手验证:32;外部现实校验:32;反向验证:16、21、29、33;专项深挖:32
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
FY12/26 interim tanshin: subsequent events note怎么使用:直接 / 支持
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
查看完整证据标签(核对用)
直接证据|FY12/26 Q3 tanshin: third-quarter standalone dynamics implied by cumulative figures;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域32) / 反证(研究域16) / 反证(研究域21) / 反证(研究域29) / 反证(研究域33) / 定向深挖(研究域32)|Affiliate write-down notice: impairment mechanics and P&L routing;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;直接证据 / 支持证据|FY12/26 interim tanshin: subsequent events note;直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans
完整研究记录(核对用)
研究原文:The Pertama impairment is finished as a P&L item: Q3 added only about JPY 10 million (cumulative JPY 7,743 million), the carrying value is zero, the FY12/26 underlying forecast carries the overseas loss at only about JPY 0.4 billion, and the overseas operation is expected to return to underlying profit only in FY12/27. The interim and Q3 documents reviewed disclose no new loans, guarantees or capital injections for Pertama, so any further exposure would have to arrive through guarantees or new funding, which are not disclosed in the filings reviewed.
内部研究类型:exposure_closure_judgement
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The P&L channel through which the affiliate destroyed value is closed; whether a cash channel remains is the residual risk.
不确定性(原始记录):Non-disclosure in reviewed filings is not proof of absence; the annual securities report may disclose guarantees or funding commitments.
F008|11|第四季度必须交出27.46亿日元经常利润
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|第四季度必须交出27.46亿日元经常利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接证据;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
查看完整证据标签(核对用)
直接证据 / 支持证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 支持证据|FY12/26 Q3 tanshin: third-quarter standalone dynamics implied by cumulative figures;直接证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table;直接证据|FY12/26 Q3 tanshin: nine-month underlying ordinary profit (JPY 5.1 billion)
完整研究记录(核对用)
研究原文:The FY12/26 forecast was left unchanged at Q3: sales JPY 81,100 million (+5.0%), operating profit JPY 11,000 million (+113.1%), ordinary profit JPY 1,500 million (-44.5%), net profit JPY 500 million (EPS JPY 4.01). Subtracting nine-month actuals, Q4 must deliver ordinary profit of about JPY 2,746 million (about 2.1x the prior-year quarter) and operating profit of about JPY 3,685 million (against about JPY 2,002 million in Q4 FY12/25). Q3 standalone ordinary profit was about +JPY 1,667 million with no new one-offs, the cleanest read of run-rate. Derived cross-check (synthesis arithmetic on frozen figures): the underlying forecast of about JPY 7.5 billion less nine-month underlying of about JPY 5.1 billion implies roughly JPY 2.4 billion of underlying profit in Q4, against about JPY 0.6 billion in Q3, the seasonally softest quarter - so price and inventory effects, not run-rate alone, must carry Q4.
内部研究类型:forecast_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The year's verdict is concentrated in one unprinted quarter: delivery validates the underlying-recovery framing; a cut revalidates the reported-hole narrative the market currently prices.
不确定性(原始记录):Derived underlying Q4 arithmetic uses rounded 'about' figures and management's non-GAAP series; the quarter has not printed.
F009|03|国内合金真正赚钱,但被联营公司的亏损盖住了
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY12/26 interim tanshin: segment sales and ordinary profit for H1怎么使用:直接证据;一手验证:02
FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months怎么使用:直接证据;一手验证:02、15
FY12/25 tanshin: segment sales and ordinary profit for the full year怎么使用:直接证据;一手验证:02;同业比较:02、09、15;其他用途:历史
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
FY12/26 interim tanshin: segment information note (sales, segment profit)怎么使用:直接 / 支持;外部现实校验:02;专项深挖:02
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion)怎么使用:直接 / 支持;外部现实校验:06;专项深挖:06
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02)|FY12/26 interim tanshin: segment sales and ordinary profit for H1;直接证据 / 一手证据(研究域02) / 一手证据(研究域15)|FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months;直接证据 / 一手证据(研究域02) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15)|FY12/25 tanshin: segment sales and ordinary profit for the full year;直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 支持证据 / 外部现实(研究域02) / 定向深挖(研究域02)|FY12/26 interim tanshin: segment information note (sales, segment profit);直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;直接证据 / 支持证据 / 外部现实(研究域06) / 定向深挖(研究域06)|FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion)
完整研究记录(核对用)
研究原文:Domestic ferroalloys is the swing earner: underlying profit of about JPY 1.4 billion in H1 (about JPY 2.4 billion reported) and about JPY 0.7 billion underlying in Q3 alone (about JPY 1.5 billion reported), against a reported segment loss (nine months -JPY 5,356 million on sales of JPY 36,621 million) created entirely by booking the Malaysian affiliate in the same segment. FY12/26 segment underlying plan: domestic about +JPY 2.0 billion, overseas about -JPY 0.4 billion; FY12/25 underlying ferroalloy profit was also positive once the equity-method charge and inventory effects are excluded.
内部研究类型:profit_pool
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The segment carrying most of the cycle also carries the affiliate noise; the domestic underlying earning power is what the market is not capitalising.
不确定性(原始记录):Segment underlying splits are management briefing figures, not audited segment disclosures.
F010|03|焚烧灰渣回收:九个月经常利润已超过去年全年
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论03|焚烧灰渣回收:九个月经常利润已超过去年全年14|基本面七个模块:各自得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months怎么使用:直接 / 支持;一手验证:02、15
FY12/25 tanshin: segment sales and ordinary profit for the full year怎么使用:直接 / 支持;一手验证:02;同业比较:02、09、15;其他用途:历史
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接 / 支持;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
FY12/26 interim tanshin: demand commentary by segment怎么使用:直接证据;一手验证:03、05、08;外部现实校验:03、05、08;反向验证:09、11、15;专项深挖:03、05、08;同业比较:06;其他用途:历史
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接 / 支持;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域15)|FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15)|FY12/25 tanshin: segment sales and ordinary profit for the full year;直接证据 / 支持证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months;直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域08) / 历史/同业比较(研究域06) / 反证(研究域09) / 反证(研究域11) / 反证(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05) / 定向深挖(研究域08)|FY12/26 interim tanshin: demand commentary by segment;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary
完整研究记录(核对用)
研究原文:Incineration-ash recycling is the under-rated second engine: nine-month sales of JPY 8,532 million and ordinary profit of JPY 2,589 million (30.3% margin; H1 JPY 1,521 million; FY12/25 JPY 2,074 million at 23.3%), already above the whole of FY12/25, driven by waste-treatment volumes and molten-metal prices. It is the highest-margin and least price-cyclical profit pool, underwritten by permits and waste volumes rather than alloy prices alone; FY12/26 underlying plan is about JPY 2.9 billion.
内部研究类型:profit_pool
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):This is the trough-earnings annuity: it earned through the alloy downturn and is the destination of growth capital; roughly matches the swing factor of the entire reported result.
不确定性(原始记录):Molten-metal price normalisation could compress the margin; permit renewals and new entrants are not evidenced; capacity added by the Kashima expansion is not quantified.
F011|03|功能材料:被寄予厚望的第二增长业务在收缩
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months怎么使用:直接证据;一手验证:02、15
FY12/25 tanshin: segment sales and ordinary profit for the full year怎么使用:直接证据;一手验证:02;同业比较:02、09、15;其他用途:历史
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接 / 支持;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接 / 支持;反向验证:03、04、05、10
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域15)|FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months;直接证据 / 一手证据(研究域02) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15)|FY12/25 tanshin: segment sales and ordinary profit for the full year;直接证据 / 支持证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months;直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds
完整研究记录(核对用)
研究原文:Functional materials is the soft spot: nine-month ordinary profit of JPY 966 million (margin 9.7%) against JPY 1,923 million for all of FY12/25 (margin 13.0%), after the November 2025 partial termination of a lithium-ion cathode OEM contract and weaker hydrogen-storage alloy demand, partly offset by electronic-component materials; FY12/26 underlying plan about +JPY 1.2 billion. Battery-materials investment continues in the plan despite the termination.
内部研究类型:profit_pool_weakness
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The segment meant to be the second growth engine is shrinking; the plan's step to JPY 10 billion needs it to recover or be replaced.
不确定性(原始记录):The OEM exposure is known only through the termination notice; replacement products or volumes are not disclosed.
F012|06|资产负债表比利润表结实,但不是净现金
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表比利润表结实,但不是净现金14|基本面七个模块:各自得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、19、20、21、29
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、20
FY12/26 interim tanshin: interim balance-sheet detail怎么使用:直接证据;一手验证:19、21;外部现实校验:19;反向验证:17;专项深挖:19
FY12/26 Q3 tanshin: September balance sheet and comprehensive income怎么使用:直接证据;外部现实校验:20;专项深挖:20;同业比较:18;其他用途:历史
FY12/25 tanshin: year-end balance sheet detail怎么使用:直接证据;外部现实校验:18;专项深挖:18;同业比较:19、20、21、29;其他用途:历史
FY12/25 tanshin: comprehensive income and the securities cushion怎么使用:直接证据;外部现实校验:21;专项深挖:21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 一手证据(研究域19) / 一手证据(研究域21) / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|FY12/26 interim tanshin: interim balance-sheet detail;直接证据 / 外部现实(研究域20) / 历史/同业比较(研究域18) / 定向深挖(研究域20)|FY12/26 Q3 tanshin: September balance sheet and comprehensive income;直接证据 / 外部现实(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/25 tanshin: year-end balance sheet detail;直接证据 / 外部现实(研究域21) / 定向深挖(研究域21)|FY12/25 tanshin: comprehensive income and the securities cushion
完整研究记录(核对用)
研究原文:At 30 September 2026 total assets were JPY 94,404 million and net assets JPY 70,119 million (equity ratio 74.3%; 76.0% at FY12/25). The balance sheet is conservative but not net cash: interest-bearing debt of about JPY 14.2 billion exceeds cash of JPY 5.7 billion; investment securities JPY 14.5 billion (JPY 19.2 billion at FY12/25 before the write-off flowed through), land JPY 5.3 billion at cost without appraisal in the evidence set, inventories about JPY 26.4 billion. Nine-month comprehensive income was +JPY 615 million against a net loss of JPY 1,380 million because unrealised securities gains cushioned equity, so BPS (about JPY 562) sits barely below FY12/25's JPY 569.17; market-value equity ratio was 47.8% against 76.0% book at FY12/25. Solvency is not the question in this register; allocation is.
内部研究类型:balance_sheet_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Book value is sturdier than the P&L suggests; part of why 0.67x book is not 0.67x liquidation value. Securities gains are not cash and do not fund the dividend directly.
不确定性(原始记录):Land hidden reserves are plausible but unquantified; securities are marked to market and will move with equities; year-end debt and securities balances not yet known.
F013|06|上行期利润和现金反向走,谷底反而释放现金
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、20
FY12/25 tanshin: cash flows, buyback and treasury position怎么使用:直接 / 支持;一手验证:17;同业比较:25;其他用途:历史
FY12/26 interim tanshin: interim cash-flow statement怎么使用:直接 / 支持;一手验证:17;反向验证:19
FY12/25 tanshin: cash-flow statement quality check怎么使用:直接 / 支持;外部现实校验:17;专项深挖:17;同业比较:17;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域25)|FY12/25 tanshin: cash flows, buyback and treasury position;直接证据 / 支持证据 / 一手证据(研究域17) / 反证(研究域19)|FY12/26 interim tanshin: interim cash-flow statement;直接证据 / 支持证据 / 外部现实(研究域17) / 历史/同业比较(研究域17) / 定向深挖(研究域17)|FY12/25 tanshin: cash-flow statement quality check
完整研究记录(核对用)
研究原文:Cash conversion runs counter-cyclical to profit quality. In the upcycle, H1 FY12/26 operating cash flow fell to JPY 2,494 million from JPY 9,224 million even as operating profit rose 164.5%, because inventories and receivables absorbed cash as prices rose; investing outflow of JPY 3,607 million made free cash flow negative; construction in progress tripled to JPY 3,067 million by June and JPY 3,447 million by September on the Kashima ash-furnace expansion. In the trough, FY12/25 operating cash flow of JPY 14,569 million (more than ten times net profit of JPY 1,418 million, helped by depreciation, the non-cash equity-method loss and working-capital release) covered capex of about JPY 4,828 million, the JPY 4,031 million buyback and the dividend, with the equity ratio at 76.0%. Across a full cycle the machine is cash-positive; within a year it can be either.
内部研究类型:cash_conversion_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Dividends and buybacks are safest exactly when reported profit looks worst (trough cash release); the upcycle tests cash cover, not profit.
不确定性(原始记录):Half-year cash flows are seasonally loaded; the FY12/26 annual cash-flow statement against the JPY 11,000 million operating-profit forecast is the clean test.
F014|06|上行期利润和现金反向走,谷底反而释放现金
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、19、20、21、29
FY12/26 interim tanshin: interim cash-flow statement怎么使用:直接证据;一手验证:17;反向验证:19
FY12/26 interim tanshin: interim balance-sheet detail怎么使用:直接 / 支持;一手验证:19、21;外部现实校验:19;反向验证:17;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 一手证据(研究域17) / 反证(研究域19)|FY12/26 interim tanshin: interim cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|FY12/26 interim tanshin: interim balance-sheet detail
完整研究记录(核对用)
研究原文:Working capital is structurally long: inventories of about JPY 26.4 billion (finished products JPY 13.3 billion, raw materials JPY 13.1 billion at September 2026; JPY 17.5 billion and JPY 10.1 billion at June) equal roughly a third of annual sales, which is why price turns reach reported profit through inventory valuation before they reach cash. Inventory is both the profit amplifier and the first loss absorber at a downturn.
内部研究类型:working_capital_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A price reversal hits inventory valuation and margin before it hurts cash; inventory book value is not liquid downside value without evidence of saleability.
不确定性(原始记录):Inventory composition by product, ownership, costing basis and realizability haircut are not disclosed beyond aggregates; Q4 inventory direction unknown.
F015|08|到2030年计划投入450至500亿日元,回报要看灰渣扩建能否守住30%利润率
研究范围:开放研究+35项覆盖检查
写入正文:08|到2030年计划投入450至500亿日元,回报要看灰渣扩建能否守住30%利润率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、19、20、21、29
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、20
Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary怎么使用:直接证据;一手验证:04、11、30
IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings怎么使用:直接证据;反向验证:01、07;同业比较:30;其他用途:历史
Medium- and Long-Term Management Plan 2030: 2030 vision and investment plan (official English)怎么使用:直接 / 支持;一手验证:04;外部现实校验:04、11;反向验证:20;专项深挖:04、11
Medium- and Long-Term Management Plan 2030: environmental targets (official English)怎么使用:直接证据;一手验证:13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 一手证据(研究域04) / 一手证据(研究域11) / 一手证据(研究域30)|Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary;直接证据 / 历史/同业比较(研究域30) / 反证(研究域01) / 反证(研究域07)|IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings;直接证据 / 支持证据 / 一手证据(研究域04) / 外部现实(研究域04) / 外部现实(研究域11) / 反证(研究域20) / 定向深挖(研究域04) / 定向深挖(研究域11)|Medium- and Long-Term Management Plan 2030: 2030 vision and investment plan (official English);直接证据 / 一手证据(研究域13)|Medium- and Long-Term Management Plan 2030: environmental targets (official English)
完整研究记录(核对用)
研究原文:Strategic investment is large relative to the P&L: JPY 45-50 billion planned through 2030 (roughly triple the previous plan's pace) against annual operating profit of JPY 5-11 billion, plus R&D of JPY 3.2 billion in the 9th plan and DX spend of about JPY 4 billion, concentrated on ferroalloy competitiveness, ash-recycling capacity and functional materials. Execution shows first in construction in progress (JPY 691 million at Dec 2025 to JPY 3,447 million at Sep 2026 on the Kashima ash-melting expansion announced November 2025) and a CO2 target of at least 45% reduction by FY2030 (Scope 1+2 vs FY2015) for an electric-furnace producer; the Tokushima gas-engine installation (December 2025) is one practical step.
内部研究类型:capital_investment
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):If recycling returns hold near the current 30% margin, today's CIP is tomorrow's trough protection; if not, the investment envelope strains cash and ROIC.
不确定性(原始记录):Project-level returns and total programme cost are not disclosed; CIP conversion timing and CO2 cost are unquantified.
F016|08|分红按基础利润算,所以报表亏损年份也照付
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论08|分红按基础利润算,所以报表亏损年份也照付14|基本面七个模块:各自得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/25 tanshin: shareholder-return policy statement怎么使用:直接 / 支持;一手验证:25、26
FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation怎么使用:直接 / 支持;一手验证:25
FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50)怎么使用:直接 / 支持;一手验证:26;反向验证:25
FY12/25 tanshin: dividend record (interim 6.00 / year-end 6.00)怎么使用:直接证据;外部现实校验:26;专项深挖:26
FY12/26 interim tanshin: interim dividend resolution (JPY 5.50)怎么使用:直接 / 支持;同业比较:26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|FY12/25 tanshin: shareholder-return policy statement;直接证据 / 支持证据 / 一手证据(研究域25)|FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域25)|FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50);直接证据 / 外部现实(研究域26) / 定向深挖(研究域26)|FY12/25 tanshin: dividend record (interim 6.00 / year-end 6.00);直接证据 / 支持证据 / 历史/同业比较(研究域26)|FY12/26 interim tanshin: interim dividend resolution (JPY 5.50)
完整研究记录(核对用)
研究原文:Shareholder returns are formulaic: about 40% of 'underlying net profit' (underlying ordinary profit x 0.7), a minimum annual dividend of JPY 11 from FY12/26 (raised from JPY 10 because the share count shrank), and buybacks as a flexible complement. FY12/25 paid JPY 12 (6.00 + 6.00 including a JPY 1 centenary dividend), a 112.1% payout on reported EPS of JPY 10.70 but unremarkable on the underlying basis (about JPY 1.48 billion, broadly what JPY 12 costs on about 125 million shares). The FY12/26 forecast was raised to JPY 17.00 (interim 5.50 resolved, year-end 11.50 from an initial JPY 13.00) against forecast reported EPS of JPY 4.01, a payout above 400%, which is an artefact of the affiliate write-down, not a policy break. Cross-check (synthesis arithmetic): 40% of about JPY 5.25 billion (JPY 7.5 billion x 0.7) is about JPY 2.1 billion, close to JPY 17 x about 125.4 million shares (about JPY 2.13 billion). Forecast yield 4.53% at JPY 375.
内部研究类型:shareholder_return_policy
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Holders are paid to wait through the Q4 verification window; the underlying story reaches holders before the reported story catches up. The floor makes the minimum return durable while the variable part rides the cycle.
不确定性(原始记录):The year-end JPY 11.50 remains a forecast until the February 2027 resolution; no formal DOE or payout ceiling is stated; the 10th plan may formalise or change the formula.
F017|08|回购加注销,让同一笔分红资金落到更高的每股金额
研究范围:开放研究+35项覆盖检查
写入正文:08|回购加注销,让同一笔分红资金落到更高的每股金额
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation怎么使用:直接 / 支持;一手验证:25
FY12/25 tanshin: cash flows, buyback and treasury position怎么使用:直接 / 支持;一手验证:17;同业比较:25;其他用途:历史
FY12/26 Q3 tanshin: September balance sheet and comprehensive income怎么使用:直接证据;外部现实校验:20;专项深挖:20;同业比较:18;其他用途:历史
IRBANK disclosure index: FY12/25 buyback and cancellation notices怎么使用:直接证据;外部现实校验:25;专项深挖:25;同业比较:24;其他用途:历史
FY12/26 interim tanshin: interim dividend resolution (JPY 5.50)怎么使用:直接证据;同业比较:26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25)|FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域25)|FY12/25 tanshin: cash flows, buyback and treasury position;直接证据 / 外部现实(研究域20) / 历史/同业比较(研究域18) / 定向深挖(研究域20)|FY12/26 Q3 tanshin: September balance sheet and comprehensive income;直接证据 / 外部现实(研究域25) / 历史/同业比较(研究域24) / 定向深挖(研究域25)|IRBANK disclosure index: FY12/25 buyback and cancellation notices;直接证据 / 历史/同业比较(研究域26)|FY12/26 interim tanshin: interim dividend resolution (JPY 5.50)
完整研究记录(核对用)
研究原文:Capital actions are material: the company bought back about JPY 4,031 million of stock between August and October 2025 (ToSTNeT-3, completed 28 October 2025), held 12,597,919 treasury shares (9.17% of 137,386,472 issued) at the FY12/25 year-end, and cancelled 11,948,808 shares (8.69% of issued) on 21 August 2026, leaving 125,437,664 shares issued; capital surplus fell from JPY 17,484 million to JPY 13,829 million as the cancellation was absorbed. Financing is debt-funded working capital with no equity issuance; per-share metrics have been repeatedly lifted by retiring roughly a tenth of the share count.
内部研究类型:capital_action
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The same dividend pool buys a higher per-share amount after cancellation; per-share outcomes compound even when the cycle does not cooperate, and the float is shrunk.
不确定性(原始记录):Buyback price versus normalised value is not evaluated beyond the discount to book; future buyback cadence is discretionary.
F018|07|日本制铁握着控制权框架,少数股东的条件取决于对方的善意
研究范围:开放研究+35项覆盖检查
写入正文:07|日本制铁握着控制权框架,少数股东的条件取决于对方的善意14|基本面七个模块:各自得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、07、24
Notice on the change of representative director (president)怎么使用:直接 / 支持;一手验证:23、30
IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings怎么使用:直接 / 支持;反向验证:01、07;同业比较:30;其他用途:历史
FY12/25 securities report: major shareholders table怎么使用:直接 / 支持;一手验证:07、24;外部现实校验:01、24;专项深挖:01、24;同业比较:23;其他用途:历史
IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)怎么使用:直接 / 支持;外部现实校验:23;反向验证:23;专项深挖:23;同业比较:07、13;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24)|Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile;直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30)|Notice on the change of representative director (president);直接证据 / 支持证据 / 历史/同业比较(研究域30) / 反证(研究域01) / 反证(研究域07)|IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings;直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域01) / 外部现实(研究域24) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域24)|FY12/25 securities report: major shareholders table;直接证据 / 支持证据 / 外部现实(研究域23) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 反证(研究域23) / 定向深挖(研究域23)|IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)
完整研究记录(核对用)
研究原文:Nippon Steel is the largest shareholder at 24.29% (FY12/25 register ex-treasury; Master Trust Bank 11.41%, Japan Custody Bank 2.79%, business-partner association 2.00%, Nittetsu Mining 1.68%, employee association 1.50%). The stake triggers the annual TSE 'matters concerning controlling shareholders' notice (28 March 2024, 28 March 2025, 27 March 2026) and the controlling-shareholder framework is live, not theoretical. The takeover-defence plan was abolished on 29 January 2026, removing a minority-protection layer just as the parent axis strengthens; governance runs under an audit-and-supervisory-committee structure. The axis supplies governance and likely raw-material and customer channels, but commercial terms are not disclosed.
内部研究类型:control_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Minorities ride on the parent axis's terms; alignment is assumed, not contracted; float scarcity cuts both ways (thin sponsorship up, thin bids down).
不确定性(原始记录):Trust-account holdings are custodial; any change in Nippon Steel's stake is visible only through EDINET large-holder filings; the inference that the axis is strengthening is interpretive.
F019|07|社长换成日本制铁原料部门出身者,执行可信度和集团影响一起上升
研究范围:开放研究+35项覆盖检查
写入正文:07|社长换成日本制铁原料部门出身者,执行可信度和集团影响一起上升
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Notice on the change of representative director (president)怎么使用:直接 / 支持;一手验证:23、30
President-change notice: successor profile and 10th plan timing怎么使用:直接 / 支持;一手验证:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30)|Notice on the change of representative director (president);直接证据 / 支持证据 / 一手证据(研究域23)|President-change notice: successor profile and 10th plan timing
完整研究记录(核对用)
研究原文:Governance and leadership change together at the 2026 year-end: President Aoki Yasushi becomes director and advisor without representative rights on 1 January 2027; Kobayashi Jiro (born 1965, Nippon Steel since 1988, head of its European office in 2013 and of its raw-materials divisions 2017-2023, Nippon Denko director since March 2024, holds 25,900 shares) becomes representative director and president, timed to the 10th medium-term plan to be published within 2026. Group alignment and execution risk rise together.
内部研究类型:governance_event
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Succession is the plan-launch mechanism: execution credibility rises with a raw-materials specialist, but the governance discount may not fall with it.
不确定性(原始记录):The 10th plan's content and any governance-framework changes are not yet public; the president's incentives and board deliberation detail are not disclosed.
F020|09|2027年12月期100亿日元目标,需要的不是价格,是三件还没发生的事
研究范围:开放研究+35项覆盖检查
写入正文:09|2027年12月期100亿日元目标,需要的不是价格,是三件还没发生的事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY December 2025 full-year earnings report (tanshin), consolidated怎么使用:直接 / 支持;一手验证:22;同业比较:12、14;其他用途:历史
Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary怎么使用:直接 / 支持;一手验证:04、11、30
Medium- and Long-Term Management Plan 2030: 2030 vision and investment plan (official English)怎么使用:直接证据;一手验证:04;外部现实校验:04、11;反向验证:20;专项深挖:04、11
9th medium-term plan: FY2027 target table and FY2023 base (official English)怎么使用:直接 / 支持;一手验证:11;同业比较:22;其他用途:历史
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:直接 / 支持;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14)|FY December 2025 full-year earnings report (tanshin), consolidated;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域11) / 一手证据(研究域30)|Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary;直接证据 / 一手证据(研究域04) / 外部现实(研究域04) / 外部现实(研究域11) / 反证(研究域20) / 定向深挖(研究域04) / 定向深挖(研究域11)|Medium- and Long-Term Management Plan 2030: 2030 vision and investment plan (official English);直接证据 / 支持证据 / 一手证据(研究域11) / 历史/同业比较(研究域22)|9th medium-term plan: FY2027 target table and FY2023 base (official English);直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:The 9th medium-term plan (FY2024-27) targets FY12/27 sales of JPY 95.0 billion, ordinary profit of JPY 10.0 billion and ROE 10% (2030 vision: sales of at least JPY 110 billion, ordinary profit at least JPY 13 billion, ROE at least 10%), from an FY2023 base of sales JPY 76.4 billion, ordinary profit JPY 2.5 billion (underlying JPY 5.5 billion) and ROE 6%. Against FY12/25 actuals (JPY 77.3 billion, JPY 2.7 billion, ROE 2.0%) and the FY12/26 forecast (sales JPY 81.1 billion, underlying ordinary profit about JPY 7.5 billion), the FY12/27 step requires sales +17% and about JPY 2.5 billion more ordinary profit; most of that step must come from the overseas turnaround, functional-materials recovery and ash-recycling expansion rather than price, and it implicitly assumes the safeguard premium largely survives. The 10th plan, due within 2026, will confirm or reset it.
内部研究类型:plan_target_gap
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The re-rating case built on plan delivery stands or falls with this target set; a cut would remove the main bridge from 6.3x underlying to a higher multiple.
不确定性(原始记录):The 10th plan text is unpublished; the sales step of +17% is large against a flat-to-declining domestic steel pond.
F021|06|资本效率低于目标,最好的口径下也只接近股权成本
研究范围:开放研究+35项覆盖检查
写入正文:06|资本效率低于目标,最好的口径下也只接近股权成本09|ROE接近股权成本时,低于账面价值有其算术上的合理性
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY December 2025 full-year earnings report (tanshin), consolidated怎么使用:直接证据;一手验证:22;同业比较:12、14;其他用途:历史
FY12/25 tanshin: per-share and ratio indicators怎么使用:直接证据;一手验证:22;外部现实校验:22;专项深挖:22
9th medium-term plan: FY2027 target table and FY2023 base (official English)怎么使用:直接证据;一手验证:11;同业比较:22;其他用途:历史
FY12/25 tanshin: year-end balance sheet detail怎么使用:直接证据;外部现实校验:18;专项深挖:18;同业比较:19、20、21、29;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域22) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14)|FY December 2025 full-year earnings report (tanshin), consolidated;直接证据 / 一手证据(研究域22) / 外部现实(研究域22) / 定向深挖(研究域22)|FY12/25 tanshin: per-share and ratio indicators;直接证据 / 一手证据(研究域11) / 历史/同业比较(研究域22)|9th medium-term plan: FY2027 target table and FY2023 base (official English);直接证据 / 外部现实(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/25 tanshin: year-end balance sheet detail
完整研究记录(核对用)
研究原文:Capital efficiency is below target and near cost of equity on the best measure: ROE was 2.0% in FY12/25 and 4.5% in FY12/24 (EPS JPY 10.70 vs JPY 24.35; operating margin 6.7% vs 8.8%; ordinary profit to assets 3.0%), against the plan target of 10% (FY12/27 and 2030). On underlying profit the run-rate ROE is roughly 7-8%, below target and near the cost of equity. The earnings base halved in a year without balance-sheet stress. The company's own cost-of-capital estimate and ROIC are not disclosed (ROIC approximated through ROE).
内部研究类型:capital_efficiency_judgement
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Until ROE clears the cost of capital, trading below book is defensible; the 10% target requires the JPY 10.0 billion ordinary profit and no new equity drag.
不确定性(原始记录):The underlying-profit ROE of 7-8% is a Research approximation; FY12/26 ROE print and the 10th plan's capital-efficiency language are pending.
F022|09|估值简报:几个倍数各用不同的期间和利润口径
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|估值简报:几个倍数各用不同的期间和利润口径
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY December 2025 full-year earnings report (tanshin), consolidated怎么使用:直接 / 支持;一手验证:22;同业比较:12、14;其他用途:历史
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、19、20、21、29
FY12/25 tanshin: cash flows, buyback and treasury position怎么使用:直接 / 支持;一手验证:17;同业比较:25;其他用途:历史
FY12/25 tanshin: per-share and ratio indicators怎么使用:直接 / 支持;一手验证:22;外部现实校验:22;专项深挖:22
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接 / 支持;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
IRBANK stock page for 5563: latest daily close, 6 November 2026怎么使用:直接 / 支持;反向验证:31、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14)|FY December 2025 full-year earnings report (tanshin), consolidated;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域25)|FY12/25 tanshin: cash flows, buyback and treasury position;直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域22) / 定向深挖(研究域22)|FY12/25 tanshin: per-share and ratio indicators;直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域34)|IRBANK stock page for 5563: latest daily close, 6 November 2026
完整研究记录(核对用)
研究原文:Valuation snapshot at the research cut-off (price at the 6 November 2026 close): share price JPY 375; market capitalisation JPY 47.04 billion (x 125,437,664 shares issued after the August 2026 cancellation); forecast PER 93.5x on FY12/26 forecast EPS of JPY 4.01 (aggregator shows 93.66x); actual PBR 0.66x on FY12/25 net assets per share of JPY 569.17 (0.67x on about JPY 562 at September 2026; aggregator PBR 0.67 with a 0.28-1.9x range since 2009); ROE 2.0% (FY12/25 actual); forecast dividend yield 4.53% on JPY 17.00; EV/EBITDA 5.9x (EV JPY 51.73 billion = market cap plus net interest-bearing debt of JPY 4.69 billion at 30 September 2026, being short-term borrowings JPY 5,000 million + current portion JPY 1,550 million + long-term JPY 3,887 million less cash JPY 5,747 million; EBITDA JPY 8.83 billion = FY12/25 operating profit JPY 5,161 million + depreciation JPY 3,665 million). Basis note: multiples mix FY12/25 actual denominators and FY12/26 forecast denominators; PER is distorted by the affiliate-loss-depressed EPS.
内部研究类型:valuation_snapshot
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The headline multiples are mutually inconsistent by construction (94x PER beside 0.66x PBR and 5.9x EV/EBITDA); each reflects a different period and profit basis.
不确定性(原始记录):Point-in-time snapshot at the 6 November close; EBITDA uses FY12/25 actuals while FY12/26 operating profit is forecast near JPY 11,000 million; per-share denominators differ across multiples.
F023|09|同一个股价,三种利润口径,三个倍数
研究范围:开放研究+35项覆盖检查
写入正文:09|同一个股价,三种利润口径,三个倍数14|基本面七个模块:各自得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY December 2025 full-year earnings report (tanshin), consolidated怎么使用:直接 / 支持;一手验证:22;同业比较:12、14;其他用途:历史
IRBANK stock page for 5563: price, valuation and credit-balance snapshot怎么使用:直接 / 支持;一手验证:27、31
IRBANK stock page for 5563: market capitalisation, yield and margin data怎么使用:直接 / 支持;一手验证:27;外部现实校验:27;反向验证:18、24、26;专项深挖:27;同业比较:31;其他用途:历史
IRBANK stock page for 5563: 6 November 2026 close and day move怎么使用:直接证据;一手验证:31;外部现实校验:31;反向验证:27、30;专项深挖:31
FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50)怎么使用:支持证据;一手验证:26;反向验证:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14)|FY December 2025 full-year earnings report (tanshin), consolidated;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|IRBANK stock page for 5563: price, valuation and credit-balance snapshot;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域27) / 历史/同业比较(研究域31) / 反证(研究域18) / 反证(研究域24) / 反证(研究域26) / 定向深挖(研究域27)|IRBANK stock page for 5563: market capitalisation, yield and margin data;直接证据 / 一手证据(研究域31) / 外部现实(研究域31) / 反证(研究域27) / 反证(研究域30) / 定向深挖(研究域31)|IRBANK stock page for 5563: 6 November 2026 close and day move;支持证据 / 一手证据(研究域26) / 反证(研究域25)|FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50)
完整研究记录(核对用)
研究原文:Valuation depends on which profit language is used. At JPY 375 the market capitalisation of about JPY 47.0 billion is smaller than book equity (JPY 70.1 billion at September 2026), about 6.3x the JPY 7.5 billion underlying ordinary-profit forecast, about 31x the JPY 1.5 billion reported ordinary-profit forecast and about 94x forecast reported EPS; yield 4.53%. The market prices the reported-earnings hole and the governance axis, not the underlying run-rate or the plan. The discount has persisted for years (PBR range 0.28-1.9x since 2009; the 0.67x sits in the lower half), so re-rating needs delivery, not argument; the gap between market-value equity ratio (47.8%) and book (76.0%) is the standing discount in one number.
内部研究类型:valuation_assumption_set
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Downside is cushioned by book and yield; upside requires the February print and the 10th plan.
不确定性(原始记录):Underlying-based multiples use management's non-GAAP series; the PBR anchor includes the securities cushion; no analyst consensus series was pulled.
F024|12|同一份财报,营业利润大增,市场却盯着亏损那一行
研究范围:开放研究+35项覆盖检查
写入正文:12|同一份财报,营业利润大增,市场却盯着亏损那一行
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK stock page for 5563: price, valuation and credit-balance snapshot怎么使用:直接证据;一手验证:27、31
IRBANK stock page for 5563: market capitalisation, yield and margin data怎么使用:直接证据;一手验证:27;外部现实校验:27;反向验证:18、24、26;专项深挖:27;同业比较:31;其他用途:历史
IRBANK stock page for 5563: 6 November 2026 close and day move怎么使用:直接证据;一手验证:31;外部现实校验:31;反向验证:27、30;专项深挖:31
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域27) / 一手证据(研究域31)|IRBANK stock page for 5563: price, valuation and credit-balance snapshot;直接证据 / 一手证据(研究域27) / 外部现实(研究域27) / 历史/同业比较(研究域31) / 反证(研究域18) / 反证(研究域24) / 反证(研究域26) / 定向深挖(研究域27)|IRBANK stock page for 5563: market capitalisation, yield and margin data;直接证据 / 一手证据(研究域31) / 外部现实(研究域31) / 反证(研究域27) / 反证(研究域30) / 定向深挖(研究域31)|IRBANK stock page for 5563: 6 November 2026 close and day move
完整研究记录(核对用)
研究原文:The market's first verdict on the Q3 print (6 November 2026) was a 5.3% fall to JPY 375: the document that carried an operating-profit beat (+131.6%) and an unchanged forecast also carried a nine-month ordinary loss, and the loss was what was priced. Credit data show retail positioning heavily one-sided into the autumn: margin longs of 1,750,300 shares against 26,600 short (65.8x, mid-July 2026). Retail believed early; institutions appear to be waiting for Q4. A Q4 beat is likely to be believed late and priced fast; a miss confirms the hole narrative.
内部研究类型:market_expectation_state
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Expectation asymmetry favours the patient holder if delivery comes; one clean Q4 print re-prices the underlying language.
不确定性(原始记录):Expectations are inferred from price action and the margin balance (mid-July, stale by November); no analyst consensus was pulled.
F025|09|正常化盈利是50亿至75亿日元的区间,上半部分靠政策溢价
研究范围:开放研究+35项覆盖检查
写入正文:09|正常化盈利是50亿至75亿日元的区间,上半部分靠政策溢价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure怎么使用:直接证据;一手验证:28;外部现实校验:12、16、28;专项深挖:12、16、28
FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion)怎么使用:直接证据;外部现实校验:06;专项深挖:06
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 一手证据(研究域28) / 外部现实(研究域12) / 外部现实(研究域16) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure;直接证据 / 外部现实(研究域06) / 定向深挖(研究域06)|FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion);直接证据|FY12/26 Q3 tanshin: nine-month underlying ordinary profit (JPY 5.1 billion)
完整研究记录(核对用)
研究原文:Normalised earnings power is best read on the underlying ordinary-profit series: about JPY 5.5 billion (FY12/23), 5.2 (FY12/24), 5.3 (FY12/25) and about 7.5 billion forecast for FY12/26 (initially about 6.0 billion; H1 about 4.5 billion vs 2.2 billion; nine months about 5.1 billion vs 3.2 billion) - a normalised band of roughly JPY 5-7.5 billion before plan delivery, against reported prints from -6.4 to +10.4 billion. The FY12/26 forecast already includes upcycle pricing, so the top of the band is not a trough number. At about 6.3x the top of the band the market pays for delivery of the band, not the plan.
内部研究类型:normalized_earnings_judgement
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Separates structural earning power from price-rent: the lower half of the band is the trough-tested part, the upper half rests on safeguard pricing.
不确定性(原始记录):Underlying is management's non-GAAP construction (ex inventory effects and one-offs); the company does not publish a full quarterly bridge; continuation of underlying disclosure under the 10th plan is not assured.
F026|09|下行靠资产和年金托底,不靠盈利
研究范围:开放研究+35项覆盖检查
写入正文:09|下行靠资产和年金托底,不靠盈利
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、19、20、21、29
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接证据;一手验证:12、29、33;同业比较:28、35;其他用途:历史
IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)怎么使用:直接证据;一手验证:09、33;外部现实校验:29、33;反向验证:35;专项深挖:29、33;同业比较:08、10、11;其他用途:历史
FY12/25 tanshin: year-end balance sheet detail怎么使用:直接证据;外部现实校验:18;专项深挖:18;同业比较:19、20、21、29;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域29) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 反证(研究域35) / 定向深挖(研究域29) / 定向深挖(研究域33)|IRBANK disclosure index: the FY12/19 loss notices (30 January 2020);直接证据 / 外部现实(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/25 tanshin: year-end balance sheet detail
完整研究记录(核对用)
研究原文:Downside protection is asset- and annuity-based, not earnings-based: equity ratio 74.3%, JPY 14.5 billion of securities, land at cost, the JPY 11 dividend floor, ash-recycling and hydro profits that persist through alloy troughs, and a demonstrated trough anatomy (FY12/19) that the balance sheet absorbed. Protection has been tested twice in a decade and held; the realistic downside is a return to the JPY 225-300 base zone (0.3-0.5x book trough framework), not distress. Counter-weight: a safeguard lapse combined with a price collapse has no exact precedent in the company's record.
内部研究类型:downside_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):If any thesis leg fails, the correct action is to re-price to the trough framework rather than to average down on narrative.
不确定性(原始记录):Protection is constructed from the company's own trough history; the 0.3-0.5x book trough range is a Research framing, not a disclosed fact.
F027|06|五处会计呈现需要对照着读,否则会低估这家公司
研究范围:35项覆盖检查
写入正文:06|五处会计呈现需要对照着读,否则会低估这家公司
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Notice on the valuation loss on affiliate shares and the equity-method investment loss怎么使用:直接证据;一手验证:32
FY12/25 tanshin: income-statement bridge and non-operating items怎么使用:直接证据;同业比较:16、32;其他用途:历史
FY12/26 interim tanshin: interim income statement detail怎么使用:直接证据;一手验证:16;反向验证:32
FY12/26 Q3 tanshin: September balance sheet and comprehensive income怎么使用:直接证据;外部现实校验:20;专项深挖:20;同业比较:18;其他用途:历史
Affiliate write-down notice: impairment mechanics and P&L routing怎么使用:直接证据;一手验证:32;外部现实校验:32;反向验证:16、21、29、33;专项深挖:32
FY12/25 tanshin: comprehensive income and the securities cushion怎么使用:直接证据;外部现实校验:21;专项深挖:21
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32)|Notice on the valuation loss on affiliate shares and the equity-method investment loss;直接证据 / 历史/同业比较(研究域16) / 历史/同业比较(研究域32)|FY12/25 tanshin: income-statement bridge and non-operating items;直接证据 / 一手证据(研究域16) / 反证(研究域32)|FY12/26 interim tanshin: interim income statement detail;直接证据 / 外部现实(研究域20) / 历史/同业比较(研究域18) / 定向深挖(研究域20)|FY12/26 Q3 tanshin: September balance sheet and comprehensive income;直接证据 / 一手证据(研究域32) / 外部现实(研究域32) / 反证(研究域16) / 反证(研究域21) / 反证(研究域29) / 反证(研究域33) / 定向深挖(研究域32)|Affiliate write-down notice: impairment mechanics and P&L routing;直接证据 / 外部现实(研究域21) / 定向深挖(研究域21)|FY12/25 tanshin: comprehensive income and the securities cushion
完整研究记录(核对用)
研究原文:Where the accounts mislead (each anomaly pushes reported profit below the operating business in 2026; the reverse held at the FY12/22 peak): the parent special loss (JPY 7,877 million) differs from the consolidated equity-method addition (JPY 7,180 million, beyond the running loss share, JPY 7,733 million in total at H1); inventory valuation sits inside gross profit; non-deductible equity-method losses leave the tax line heavy against a pre-tax loss; other comprehensive income absorbs equity-level securities gains (nine-month comprehensive income +JPY 615 million vs net loss -JPY 1,380 million); and ordinary-level segment profit hides the affiliate inside ferroalloys. This is a quality-of-evidence catalogue, not a fraud presumption.
内部研究类型:accounting_translation_map
内部来源标记:COVERAGE35
普通股东含义(原始记录):Readers who screen on reported EPS misprice this stock in both directions across the cycle.
不确定性(原始记录):Catalogued from the filings' own notes; no forensic re-audit; the FY12/26 securities report (March 2027) may add new one-off categories.
F028|04|保障措施是眼下最大的单一利润变量,也是有期限的
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论04|保障措施是眼下最大的单一利润变量,也是有期限的11|保障措施一旦到期,影响的是计划,不只是毛利率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接证据;一手验证:06、12、14、16
FY12/26 interim tanshin: demand commentary by segment怎么使用:直接证据;一手验证:03、05、08;外部现实校验:03、05、08;反向验证:09、11、15;专项深挖:03、05、08;同业比较:06;其他用途:历史
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接证据;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter;直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域08) / 历史/同业比较(研究域06) / 反证(研究域09) / 反证(研究域11) / 反证(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05) / 定向深挖(研究域08)|FY12/26 interim tanshin: demand commentary by segment;直接证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary
完整研究记录(核对用)
研究原文:European safeguard measures on ferroalloy imports are currently the group's largest single profit variable, larger than any operating lever management controls: management attributes the price rise mainly to safeguards, which lifted Japanese export demand and domestic prices (European HC-FeMn USD 1,175/t in 2025 to USD 1,335/t in Q3 2026; US benchmark USD 1,345-1,361/t). Safeguards raise the import price ceiling; when they lapse the domestic premium compresses toward import parity. The measures have a reviewable, finite life and their post-2026 design is not yet public. Waste law supports ash-recycling volumes, a policy floor under the second engine.
内部研究类型:policy_rent
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Part of the cycle's premium is a policy rent, and policy rents expire; it is a plan-level exposure, not a market footnote.
不确定性(原始记录):EU safeguard review outcomes and import-price data are not available; no named-peer benchmarking or import-price series was pulled.
F029|03|合金需求来自粗钢产量和贸易流向,国内不增长
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 interim tanshin: segment sales and ordinary profit for H1怎么使用:直接证据;一手验证:02
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 interim tanshin: demand commentary by segment怎么使用:直接证据;一手验证:03、05、08;外部现实校验:03、05、08;反向验证:09、11、15;专项深挖:03、05、08;同业比较:06;其他用途:历史
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接证据;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02)|FY12/26 interim tanshin: segment sales and ordinary profit for H1;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域08) / 历史/同业比较(研究域06) / 反证(研究域09) / 反证(研究域11) / 反证(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05) / 定向深挖(研究域08)|FY12/26 interim tanshin: demand commentary by segment;直接证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary
完整研究记录(核对用)
研究原文:Alloy demand is derived from crude-steel output and safeguard-shaped trade flows into Europe and the US, not from final consumption; domestic steel demand is structurally flat-to-declining, so growth must come from consolidation, capacity and mix rather than market beta. Management's commentary attributes the H1 and Q3 profit mix more to price and valuation than to volume. Ash demand follows waste volumes, far steadier than steel; aqua solutions deliveries are project-timed; hydropower generation is stable.
内部研究类型:end_market_dependency
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The same steel tonnage produces alloy profit only while safeguard premiums hold domestic prices above import parity; the blend with waste demand is the stabiliser.
不确定性(原始记录):Customer names and volumes are not disclosed; FY12/27 steel-demand outlook awaits the 10th plan.
F030|03|矿石、电力和日元共同决定合金价差
研究范围:开放研究+35项覆盖检查
写入正文:03|矿石、电力和日元共同决定合金价差14|基本面七个模块:各自得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接证据;一手验证:06、12、14、16
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接证据;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter;直接证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary
完整研究记录(核对用)
研究原文:All ferroalloy production depends on imported manganese ore priced off the USD per Mn% benchmark (USD 4.5 in 2025, 5.4 in Q2 2026, 4.8 in Q3), on furnace electricity and on the yen (157-160 realised in H1; H2 assumption 155 per dollar; about 159 in Q3). Ore and power costs enter COGS with a lag while alloy prices float; the lag is the margin cycle. A weak yen inflates both alloy yen-prices and ore yen-costs, with the price side winning while safeguards hold. A simultaneous ore spike and yen strength is the classic margin squeeze; FX reversal compresses the same margin it expanded.
内部研究类型:input_dependency
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The spread between the ore price and the safeguard-supported alloy price is the group's core alloy margin; hedging and supplier terms are not disclosed.
不确定性(原始记录):Supplier identities, contract terms and FX sensitivities are not disclosed; sensitivity is inferred from market tables.
F031|04|整合让它成为国内参照级供应商,但没有份额数据来印证
研究范围:开放研究+35项覆盖检查
写入正文:04|整合让它成为国内参照级供应商,但没有份额数据来印证05|护城河只有一半经得起检验
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Notice on the publication of the 100th anniversary history (founding October 1925)怎么使用:直接证据;一手验证:01、03、10
IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:29、33;反向验证:35;专项深挖:29、33;同业比较:08、10、11;其他用途:历史
Centenary notice: founding in October 1925 and company history outline怎么使用:直接 / 支持;一手验证:09、10;外部现实校验:07、10;专项深挖:07、10;同业比较:01、03、04、33;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域03) / 一手证据(研究域10)|Notice on the publication of the 100th anniversary history (founding October 1925);直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域29) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 反证(研究域35) / 定向深挖(研究域29) / 定向深挖(研究域33)|IRBANK disclosure index: the FY12/19 loss notices (30 January 2020);直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 外部现实(研究域07) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域10)|Centenary notice: founding in October 1925 and company history outline
完整研究记录(核对用)
研究原文:The century-old franchise (founded October 1925, centenary marked October 2025) has survived by consolidation: it absorbed listed peer Chuo Denki Kogyo (share exchange 2014, merged 1 July 2024), stopped the Kashima high-carbon ferromanganese furnace in 2021-22 to concentrate capacity, and now concentrates manganese alloys at Takaoka and Kashima with the ex-Chuo works at Myoko and Wakayama (plus Tokushima and Koriyama). It is the domestic reference ferroalloy supplier; smelting know-how, waste-treatment permits and in-house hydro assets are the structural moat, while the alloy moat is cost-curve position only.
内部研究类型:industry_position
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Consolidation gives pricing resilience in troughs and operating leverage in upcycles, which is why the upcycle lands on this P&L with full force.
不确定性(原始记录):No independent market-share series was pulled; position is inferred from consolidation history; any new capacity or exit moves by remaining rivals are unknown.
F032|11|接下来两个季度的节点,各解开一层「两种利润语言」
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|接下来两个季度的节点,各解开一层「两种利润语言」
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Notice on the change of representative director (president)怎么使用:直接证据;一手验证:23、30
Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary怎么使用:直接证据;一手验证:04、11、30
IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)怎么使用:直接证据;外部现实校验:23;反向验证:23;专项深挖:23;同业比较:07、13;其他用途:历史
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:直接证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域23) / 一手证据(研究域30)|Notice on the change of representative director (president);直接证据 / 一手证据(研究域04) / 一手证据(研究域11) / 一手证据(研究域30)|Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary;直接证据 / 外部现实(研究域23) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 反证(研究域23) / 定向深挖(研究域23)|IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026);直接证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:The dated catalyst path is dense for two quarters, then reverts to cycle-watching: the 10th medium-term plan (within 2026); the presidency change (1 January 2027); the FY12/26 annual print with the implied-Q4 verdict (February 2027); the year-end dividend resolution (JPY 11.50 forecast); the March 2027 controlling-shareholder disclosure. Each catalyst resolves one layer of the two-language problem: plan (targets), print (delivery), dividend (formula).
内部研究类型:dated_catalyst_path
内部来源标记:COVERAGE35
普通股东含义(原始记录):Position sizing should respect the February binary; catalyst sizes are not estimable in advance and the Q4 implied numbers define the surprise axis.
不确定性(原始记录):The 10th plan publication date is not announced beyond 'within 2026'.
F033|01|三条腿都在两个季度内接受检验
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|三条腿都在两个季度内接受检验01|操作思路:持有观察,等两个节点落地再决定加码11|什么会推翻这个判断14|总分60.97/100,评级B,操作以持有观察为主
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接证据;一手验证:12、29、33;同业比较:28、35;其他用途:历史
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接 / 支持;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:直接 / 支持;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table;直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:Thesis: the FY12/26 reported hole is a one-layer accounting event over an improving underlying business, and the discount (about 0.67x book, about 6.3x underlying ordinary profit) overprices it; the thesis stands on three legs - underlying delivery of the back-loaded year, plan continuity under the new president, and a zeroed affiliate - each with its own dated test. Falsifiers: Q4 ordinary profit far below the implied JPY 2,746 million without a ferromanganese price collapse (the 'underlying recovery' framing fails); the 10th plan cutting the FY12/27 JPY 10.0 billion ambition (the plan-delivery re-rating case fails); new cash support to Pertama; a monthly close back below the 2025 low band. If any leg fails, re-price to the trough framework (0.3-0.5x book) rather than average down on narrative.
内部研究类型:thesis_and_falsification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Gives the shareholder a short evidence fuse: all three legs are tested within two quarters.
不确定性(原始记录):Confidence about 0.75 as stated by Research; Q4 print, 10th plan text and FY12/27 Q1 underlying disclosure are all pending.
F034|01|反证有八条,但不是八个独立风险
研究范围:开放研究+35项覆盖检查
写入正文:01|反证有八条,但不是八个独立风险
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 interim tanshin: interim cash-flow statement怎么使用:直接证据;一手验证:17;反向验证:19
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接 / 支持;一手验证:12、29、33;同业比较:28、35;其他用途:历史
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:29、33;反向验证:35;专项深挖:29、33;同业比较:08、10、11;其他用途:历史
IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)怎么使用:直接证据;外部现实校验:23;反向验证:23;专项深挖:23;同业比较:07、13;其他用途:历史
查看完整证据标签(核对用)
直接证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域17) / 反证(研究域19)|FY12/26 interim tanshin: interim cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据|FY12/26 Q3 tanshin: third-quarter standalone dynamics implied by cumulative figures;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域29) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 反证(研究域35) / 定向深挖(研究域29) / 定向深挖(研究域33)|IRBANK disclosure index: the FY12/19 loss notices (30 January 2020);直接证据 / 外部现实(研究域23) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 反证(研究域23) / 定向深挖(研究域23)|IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026);直接证据|FY12/26 Q3 tanshin: nine-month underlying ordinary profit (JPY 5.1 billion)
完整研究记录(核对用)
研究原文:Strongest counter-evidence to the 'underlying recovery' framing, retained distinct from principal risk: (1) the FY12/26 margin is partly policy rent from European safeguards with a finite, reviewable life; (2) the reported series whipsaws and the FY12/19 anatomy has recurred, and FY12/22's JPY 10,367 million peak fell 76% the next year; (3) the forecast is back-loaded, requiring about JPY 2.4 billion of underlying profit in Q4 against about JPY 0.6 billion in Q3; (4) H1 free cash flow was negative as working capital absorbed the upcycle; (5) functional materials is shrinking after the cathode OEM termination; (6) the takeover-defence plan was abolished as the parent axis tightens; (7) the underlying series is management's own construction; (8) the plan's FY12/27 step needs +17% sales in a flat pond. Offsetting: Q3 standalone profit was clean, the affiliate P&L channel is closed and the balance sheet absorbed two trough events.
内部研究类型:counter_evidence_stack
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The discount is partly the correct price for structure if these items cluster; they are why the stock is not simply 'cheap on underlying'.
不确定性(原始记录):Items are not independent (several share the safeguard and price-cycle driver), so they should not be counted as eight separate negatives.
F035|01|能被承接的是地位,不是某一年的利润
研究范围:开放研究+35项覆盖检查
写入正文:01|能被承接的是地位,不是某一年的利润05|护城河只有一半经得起检验14|总分60.97/100,评级B,操作以持有观察为主
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY December 2025 full-year earnings report (tanshin), consolidated怎么使用:直接证据;一手验证:22;同业比较:12、14;其他用途:历史
FY12/25 tanshin: segment sales and ordinary profit for the full year怎么使用:直接证据;一手验证:02;同业比较:02、09、15;其他用途:历史
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、19、20、21、29
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接证据;一手验证:12、29、33;同业比较:28、35;其他用途:历史
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接证据;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:直接证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域22) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14)|FY December 2025 full-year earnings report (tanshin), consolidated;直接证据 / 一手证据(研究域02) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15)|FY12/25 tanshin: segment sales and ordinary profit for the full year;直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table;直接证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:What is durable here is not any year's profit but the position: the consolidated domestic manganese-alloy franchise built over a century, a permit-based recycling annuity earning near 30% ordinary margins, hydro assets, a 74%-equity balance sheet with a listed-securities cushion, and a shareholder-return formula that pays on underlying profit and has already survived a reported-loss year. What is not durable is the reported profit level itself: the statutory series has printed -6.4, +10.4 and +1.5 billion yen (forecast) within seven years on the same asset base, because manganese prices, inventory valuation and equity-method affiliates all strike the same line. The investment question resolves into a race between two dated processes: delivery of the back-loaded FY12/26 forecast and the FY12/27 plan (JPY 10.0 billion) under a new president, against the finite life of the safeguard premium that created the current margin. Both resolve within two quarters; the falsifiers are dated (the February 2027 print, the 10th plan within 2026, and the monthly price sensors at JPY 559, JPY 400 and JPY 334).
内部研究类型:structural_durability_judgement
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Tells the shareholder what can be underwritten (position, annuity, balance sheet, formula) and what cannot (reported profit level, safeguard premium).
不确定性(原始记录):Race outcome unknown; the price sensors named belong to the protected Technical structure and are cited here only as dated falsifier references.
F036|10|这轮上涨,是脱离二十五年底部,还是又一次冲高回落
写入正文:10|这轮上涨,是脱离二十五年底部,还是又一次冲高回落10|二十五年价格史分五段,每次冲高都没有守住10|价格长期活在100到400日元,500日元上方筹码稀薄10|底部在逐代抬高,但向上只被验证过一次10|第一轮脉冲已用完,回踩停在底部上沿而不是里面10|均线、压缩与量能:站稳尚未确认,也没有触发结构重置10|当前状态是试探性脱离,内部矛盾是高度和证明不匹配10|价格上什么会确认,什么会推翻14|技术结构 7.8/13:脱离了长期底部,但只有一轮脉冲
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
IRBANK stock page for 5563: price, valuation and credit-balance snapshot怎么使用:直接 / 支持;一手验证:27、31
IRBANK stock page for 5563: fiscal-year high/low price table FY12/2019-FY12/2026怎么使用:直接证据;外部现实校验:09;专项深挖:09、34;同业比较:27;其他用途:历史
Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026怎么使用:直接 / 支持;一手验证:34
Locally recomputed monthly close distribution from the assembled price history, 2001-2026怎么使用:直接 / 支持;同业比较:34;其他用途:历史
IRBANK stock page for 5563: fiscal-year high and low prices怎么使用:直接 / 支持;外部现实校验:34
IRBANK stock page for 5563: latest daily close, 6 November 2026怎么使用:直接 / 支持;反向验证:31、34
Locally recomputed monthly bars for 2025-2026 from the assembled price history怎么使用:直接 / 支持;一手验证:34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|IRBANK stock page for 5563: price, valuation and credit-balance snapshot;直接证据 / 外部现实(研究域09) / 历史/同业比较(研究域27) / 定向深挖(研究域09) / 定向深挖(研究域34)|IRBANK stock page for 5563: fiscal-year high/low price table FY12/2019-FY12/2026;直接证据 / 支持证据 / 一手证据(研究域34)|Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026;直接证据 / 支持证据 / 历史/同业比较(研究域34)|Locally recomputed monthly close distribution from the assembled price history, 2001-2026;直接证据 / 支持证据 / 外部现实(研究域34)|IRBANK stock page for 5563: fiscal-year high and low prices;直接证据 / 支持证据 / 反证(研究域31) / 反证(研究域34)|IRBANK stock page for 5563: latest daily close, 6 November 2026;直接证据 / 支持证据 / 一手证据(研究域34)|Locally recomputed monthly bars for 2025-2026 from the assembled price history
完整研究记录(核对用)
研究原文:Claim-level price-record observations retained as Research Truth (the protected Technical structure remains the authoritative Technical source; this node does not interpret or restate Technical State): on the monthly record the stock lived mostly between JPY 100 and 400, and the 2025-26 advance to a May 2026 high of JPY 559 is the first sustained trade above the JPY 400 shelf since 2008; the retracement since June 2026 has so far held above the rising 24- and 60-month averages. The May 2026 spike and June reversal (close JPY 434 from JPY 547) on volume of 23.3 million shares (about 2.4x the 2024 monthly norm) over a June-October base (closes JPY 390-463). At October 2026: close JPY 412 against MA12 JPY 424, MA24 JPY 357, MA60 JPY 334, with the 6 November daily close of JPY 375 testing the MA24 zone. About 45% of monthly closes since 2001 are below JPY 300 and about 9% above JPY 500.
内部研究类型:price_record_claim_observations
内部来源标记:TECHNICAL
普通股东含义(原始记录):Gives the price context within which the fundamental delivery race will be read; sponsorship above JPY 500 is historically thin.
不确定性(原始记录):Prices are raw unadjusted prints from a mirror with MISSING_TAIL status accepted through 27 October 2026; November is covered only by the 6 November daily close.
F037|13|第四季度会不会交出27.46亿日元经常利润
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接证据;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
查看完整证据标签(核对用)
直接证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;直接证据|FY12/26 Q3 tanshin: third-quarter standalone dynamics implied by cumulative figures;直接证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table
完整研究记录(核对用)
研究原文:Will Q4 FY12/26 deliver the implied ordinary profit of about JPY 2,746 million (inventory effects and ferromanganese prices permitting), or will the full-year forecast be cut at the annual print? Priority 1. Opposite answer: a miss without a price collapse falsifies the underlying-recovery framing. Resolving evidence: the FY12/26 annual release (February 2027), Q4 inventory balance and Q4 market-table prints.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Decides whether the reported hole is verified as accounting noise.
不确定性(原始记录):Resolves only with the unprinted February 2027 annual release; no current public path exists.
F038|13|Pertama清零之后,还会不会消耗现金
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Affiliate write-down notice: impairment mechanics and P&L routing怎么使用:直接证据;一手验证:32;外部现实校验:32;反向验证:16、21、29、33;专项深挖:32
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 外部现实(研究域32) / 反证(研究域16) / 反证(研究域21) / 反证(研究域29) / 反证(研究域33) / 定向深挖(研究域32)|Affiliate write-down notice: impairment mechanics and P&L routing;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;直接证据|FY12/26 interim tanshin: subsequent events note
完整研究记录(核对用)
研究原文:With the Pertama stake written down to zero, is the exposure truly closed, or can the affiliate still consume cash through loans, guarantees or further funding? Priority 1. Opposite answer: new cash support would reopen the channel and falsify the 'zeroed affiliate' leg. Resolving evidence: FY12/26 securities report notes (March 2027) on guarantees and commitments; any new TDnet notice.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The residual cash risk of the largest value destroyer in the reported P&L.
不确定性(原始记录):Not disclosed in filings reviewed; the annual report is not yet public.
F039|13|保障措施到期或重新设计后,国内溢价和那段毛利率还剩多少
研究范围:开放研究+35项覆盖检查
写入正文:13|保障措施到期或重新设计后,国内溢价和那段毛利率还剩多少
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接证据;一手验证:06、12、14、16
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接证据;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter;直接证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary
完整研究记录(核对用)
研究原文:If European safeguard measures lapse or are redesigned after 2026, how much of the domestic ferroalloy price premium, and of the FY12/26 gross-margin jump from 14.8% to 22.3%, survives? Priority 1 (raised twice in Research). Opposite answer: a lapse compresses margin toward import parity and undercuts the FY12/27 plan. Resolving evidence: EU safeguard review announcements, company risk disclosures and import-price data.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The single largest external risk to the plan and to normalised margin.
不确定性(原始记录):The post-2026 design is not public; magnitude cannot be estimated from company disclosure alone.
F040|13|第十次中期计划会设定什么目标,会不会保留100亿日元和分红公式
研究范围:开放研究+35项覆盖检查
写入正文:13|第十次中期计划会设定什么目标,会不会保留100亿日元和分红公式
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary怎么使用:直接证据;一手验证:04、11、30
9th medium-term plan: FY2027 target table and FY2023 base (official English)怎么使用:直接证据;一手验证:11;同业比较:22;其他用途:历史
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:直接证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域11) / 一手证据(研究域30)|Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary;直接证据 / 一手证据(研究域11) / 历史/同业比较(研究域22)|9th medium-term plan: FY2027 target table and FY2023 base (official English);直接证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:What will the 10th medium-term plan (due within 2026) set for FY12/27-29, and does it keep the JPY 10.0 billion ordinary-profit ambition and the current dividend formula? Priority 1-2 (stated twice in Research). Opposite answer: a cut removes the plan-delivery re-rating case; a formula change alters the shareholder-return anchor. Resolving evidence: the plan publication.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The bridge from underlying run-rate to a higher valuation.
不确定性(原始记录):Unpublished at cutoff; publication date only 'within 2026'.
F041|13|灰渣利润率能否保持,功能材料是复苏还是继续缩小
研究范围:开放研究+35项覆盖检查
写入正文:13|灰渣利润率能否保持,功能材料是复苏还是继续缩小
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months怎么使用:直接证据;一手验证:02、15
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、19、20、21、29
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接证据;一手验证:18、20
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接证据;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域15)|FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months;直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months
完整研究记录(核对用)
研究原文:Can the ash-recycling segment's roughly 30% ordinary margin persist as molten-metal prices normalise, and what does the Kashima melting-furnace expansion add to capacity and profit? Priority 2. Opposite answer: margin normalisation would remove the trough annuity and weaken the capex case. Resolving evidence: segment results through FY12/27 and disclosure on furnace capacity.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The highest-margin pool and the destination of growth capital.
不确定性(原始记录):Project returns and capacity increment are not disclosed.
F042|13|灰渣利润率能否保持,功能材料是复苏还是继续缩小
研究范围:开放研究+35项覆盖检查
写入正文:13|灰渣利润率能否保持,功能材料是复苏还是继续缩小
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接证据;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds
完整研究记录(核对用)
研究原文:Will functional materials recover from the lithium-cathode OEM contract termination and weak hydrogen-storage alloy demand, or does the segment shrink toward its electronic-materials core? Priority 2. Opposite answer: shrinkage would raise the share of the plan step that must come from ash recycling and the overseas turnaround. Resolving evidence: FY12/26 annual segment note (February 2027) and 10th plan segment strategies.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Determines whether a second growth engine exists besides recycling.
不确定性(原始记录):Replacement product or volume disclosure absent.
F043|13|母公司轴线和价格高度这两件,优先级较低但要继续看
研究范围:开放研究+35项覆盖检查
写入正文:13|母公司轴线和价格高度这两件,优先级较低但要继续看
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Notice on the change of representative director (president)怎么使用:直接证据;一手验证:23、30
IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings怎么使用:直接证据;反向验证:01、07;同业比较:30;其他用途:历史
FY12/25 securities report: major shareholders table怎么使用:直接证据;一手验证:07、24;外部现实校验:01、24;专项深挖:01、24;同业比较:23;其他用途:历史
IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)怎么使用:直接证据;外部现实校验:23;反向验证:23;专项深挖:23;同业比较:07、13;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域23) / 一手证据(研究域30)|Notice on the change of representative director (president);直接证据 / 历史/同业比较(研究域30) / 反证(研究域01) / 反证(研究域07)|IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings;直接证据 / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域01) / 外部现实(研究域24) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域24)|FY12/25 securities report: major shareholders table;直接证据 / 外部现实(研究域23) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 反证(研究域23) / 定向深挖(研究域23)|IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)
完整研究记录(核对用)
研究原文:Does Nippon Steel's 24.29% stake, the abolished takeover-defence plan and the incoming president from its raw-materials division change capital policy or the company's eventual group positioning? Priority 3. Opposite answer: a stake or positioning change would reprice the governance discount in either direction. Resolving evidence: March 2027 controlling-shareholder disclosure, EDINET large-holder filings and the 10th plan's positioning language.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Governance is part of why the multiple stays below book.
不确定性(原始记录):Interpretive; no stated intention by Nippon Steel in the evidence set.
F044|13|母公司轴线和价格高度这两件,优先级较低但要继续看
研究范围:开放研究
写入正文:13|母公司轴线和价格高度这两件,优先级较低但要继续看
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026怎么使用:直接证据;一手验证:34
IRBANK stock page for 5563: latest daily close, 6 November 2026怎么使用:直接证据;反向验证:31、34
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域34)|Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026;直接证据 / 反证(研究域31) / 反证(研究域34)|IRBANK stock page for 5563: latest daily close, 6 November 2026;直接证据 / 一手证据(研究域34)|Locally recomputed monthly bars for 2025-2026 from the assembled price history
完整研究记录(核对用)
研究原文:Will the break above the JPY 400 shelf hold through the February 2027 annual print, or fade like the 2017 spike back into the lifelong base? Priority 3. This is the price-side question posed by the protected Technical Question and is answered only by future monthly price behavior and the results-day reaction; it must not be answered by fundamental narrative.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / TECHNICAL
普通股东含义(原始记录):Determines whether the altitude is accepted by the market.
不确定性(原始记录):No fundamental evidence can resolve it; only subsequent price behavior.
F045|13|还有哪些证据缺口会限制几项判断的精度
研究范围:35项覆盖检查
写入正文:13|还有哪些证据缺口会限制几项判断的精度15|主要来源与日期:公司披露为主,市场数据和说明会记录为辅15|数据截止与证据局限
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
IRBANK stock page for 5563: price, valuation and credit-balance snapshot怎么使用:直接证据;一手验证:27、31
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026怎么使用:直接证据;一手验证:34
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 一手证据(研究域27) / 一手证据(研究域31)|IRBANK stock page for 5563: price, valuation and credit-balance snapshot;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;直接证据 / 一手证据(研究域34)|Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026
完整研究记录(核对用)
研究原文:Evidence-role limits that qualify judgments: no named-peer benchmarking or independent market-share series was pulled; ore supplier identities and contract terms, customer names and volumes, and product-level revenue and R&D pipeline are not disclosed; ROIC and the company's own cost-of-capital estimate are not published; no analyst consensus series was pulled; land is carried at cost without appraisal; the underlying-profit series and segment underlying splits are management constructions; the market-data snapshot comes from an aggregator (price, margin balance) while price history is a mirror with MISSING_TAIL status; part of the interim-briefing evidence comes from a transcript service rather than primary filings.
内部研究类型:evidence_boundaries
内部来源标记:COVERAGE35
普通股东含义(原始记录):Prevents non-disclosure from being read as absence of risk or strength; several judgments (moat, competitive position, ROIC) are structural characterisations only.
不确定性(原始记录):Each limit becomes resolvable only with annual securities report disclosures or third-party data not obtained.
F046|04|保障措施是眼下最大的单一利润变量,也是有期限的
研究范围:开放研究+35项覆盖检查
写入正文:04|保障措施是眼下最大的单一利润变量,也是有期限的06|利润抬升来自价格,不来自销量
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接 / 支持;一手验证:06、12、14、16
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接 / 支持;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary;支持证据|FY December 2026 third-quarter earnings report (tanshin), consolidated
完整研究记录(核对用)
研究原文:Policy to producer: safeguards lifted European high-carbon ferromanganese and pulled Japanese exports, raising domestic prices and the FY12/26 gross margin; trade policy is currently the largest single profit variable and has a reviewable, finite life.
内部研究类型:causes
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F047|03|矿石、电力和日元共同决定合金价差
研究范围:开放研究
写入正文:03|矿石、电力和日元共同决定合金价差14|基本面七个模块:各自得分与一句理由
归并到:F030
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接证据;一手验证:06、12、14、16
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter
完整研究记录(核对用)
研究原文:Input dependence: ore priced off the USD/Mn% benchmark (USD 5.4 in Q2 2026, 4.8 in Q3) feeds all production and, with the yen, sets the cost floor under every alloy tonne; the spread between ore cost and safeguard-supported alloy price is the core margin.
内部研究类型:conditions_margin_spread
内部来源标记:OPEN_DISCOVERY
F048|03|合金需求来自粗钢产量和贸易流向,国内不增长
研究范围:开放研究+35项覆盖检查
归并到:F029
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/26 interim tanshin: segment sales and ordinary profit for H1怎么使用:直接证据;一手验证:02
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 interim tanshin: demand commentary by segment怎么使用:直接证据;一手验证:03、05、08;外部现实校验:03、05、08;反向验证:09、11、15;专项深挖:03、05、08;同业比较:06;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02)|FY12/26 interim tanshin: segment sales and ordinary profit for H1;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域08) / 历史/同业比较(研究域06) / 反证(研究域09) / 反证(研究域11) / 反证(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05) / 定向深挖(研究域08)|FY12/26 interim tanshin: demand commentary by segment
完整研究记录(核对用)
研究原文:End-market relation: ferroalloy volumes and prices follow crude-steel production and safeguard-shaped trade flows; derived demand turns into alloy profit only while the premium holds domestic prices above import parity.
内部研究类型:derived_demand_conditions
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F049|06|上行期利润和现金反向走,谷底反而释放现金
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、19、20、21、29
FY12/26 interim tanshin: interim cash-flow statement怎么使用:直接 / 支持;一手验证:17;反向验证:19
FY12/26 interim tanshin: interim balance-sheet detail怎么使用:直接 / 支持;一手验证:19、21;外部现实校验:19;反向验证:17;专项深挖:19
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:支持证据;一手验证:18、20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 反证(研究域19)|FY12/26 interim tanshin: interim cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|FY12/26 interim tanshin: interim balance-sheet detail;支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026
完整研究记录(核对用)
研究原文:Price rises reach reported profit through inventory valuation before they reach cash; rising prices make inventories and receivables absorb cash.
内部研究类型:transmits_through_inventory
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F050|06|上行期利润和现金反向走,谷底反而释放现金
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、20
FY12/26 interim tanshin: interim cash-flow statement怎么使用:直接 / 支持;一手验证:17;反向验证:19
FY12/25 tanshin: cash-flow statement quality check怎么使用:直接 / 支持;外部现实校验:17;专项深挖:17;同业比较:17;其他用途:历史
FY12/25 tanshin: cash flows, buyback and treasury position怎么使用:支持证据;一手验证:17;同业比较:25;其他用途:历史
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:支持证据;一手验证:18、19、20、21、29
FY12/26 interim tanshin: interim balance-sheet detail怎么使用:支持证据;一手验证:19、21;外部现实校验:19;反向验证:17;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 反证(研究域19)|FY12/26 interim tanshin: interim cash-flow statement;直接证据 / 支持证据 / 外部现实(研究域17) / 历史/同业比较(研究域17) / 定向深挖(研究域17)|FY12/25 tanshin: cash-flow statement quality check;支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域25)|FY12/25 tanshin: cash flows, buyback and treasury position;支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|FY12/26 interim tanshin: interim balance-sheet detail
完整研究记录(核对用)
研究原文:Long working capital converts price falls into cash release (FY12/25) and price rises into cash absorption (H1 FY12/26), making cash quality counter-cyclical to profit quality.
内部研究类型:causes_cash_divergence
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F051|02|五台引擎共用一个屋顶,其中最大的一台跟着锰价走
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|五台引擎共用一个屋顶,其中最大的一台跟着锰价走02|同一家公司说两种利润语言,读分部必须看拆分06|同一家公司公布两套利润,差距可以达到一倍
归并到:F002
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Notice on the valuation loss on affiliate shares and the equity-method investment loss怎么使用:直接 / 支持;一手验证:32
FY12/26 interim tanshin: segment information note (sales, segment profit)怎么使用:直接证据;外部现实校验:02;专项深挖:02
Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile怎么使用:支持证据;一手验证:01、07、24
FY12/25 tanshin: segment sales and ordinary profit for the full year怎么使用:支持证据;一手验证:02;同业比较:02、09、15;其他用途:历史
FY12/25 tanshin: shareholder-return policy statement怎么使用:支持证据;一手验证:25、26
查看完整证据标签(核对用)
直接证据 / 支持证据|FY December 2026 interim earnings report (tanshin), consolidated, Japanese GAAP;直接证据 / 支持证据 / 一手证据(研究域32)|Notice on the valuation loss on affiliate shares and the equity-method investment loss;直接证据 / 外部现实(研究域02) / 定向深挖(研究域02)|FY12/26 interim tanshin: segment information note (sales, segment profit);支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24)|Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile;支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15)|FY12/25 tanshin: segment sales and ordinary profit for the full year;支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|FY12/25 tanshin: shareholder-return policy statement
完整研究记录(核对用)
研究原文:Booking the affiliate inside the ferroalloy segment makes the segment and consolidated ordinary result diverge from the underlying business: the two-layer result of operating surge over a reported loss.
内部研究类型:creates_profit_language_divergence
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F052|06|这条利润表渠道已经关闭,现金渠道还没有核对
研究范围:开放研究+35项覆盖检查
归并到:F007
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Notice on the valuation loss on affiliate shares and the equity-method investment loss怎么使用:直接 / 支持;一手验证:32
Affiliate write-down notice: impairment mechanics and P&L routing怎么使用:直接 / 支持;一手验证:32;外部现实校验:32;反向验证:16、21、29、33;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 支持证据|FY December 2026 interim earnings report (tanshin), consolidated, Japanese GAAP;直接证据 / 支持证据 / 一手证据(研究域32)|Notice on the valuation loss on affiliate shares and the equity-method investment loss;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域32) / 反证(研究域16) / 反证(研究域21) / 反证(研究域29) / 反证(研究域33) / 定向深挖(研究域32)|Affiliate write-down notice: impairment mechanics and P&L routing;支持证据|FY12/26 interim tanshin: subsequent events note
完整研究记录(核对用)
研究原文:Equity-method affiliate relation: the stake written down in full in Q2 FY12/26 (equity-method loss JPY 7,733 million in H1) leaves a zero carrying value; the P&L channel is closed and only undisclosed cash channels (loans, guarantees) could reopen it.
内部研究类型:closes_pnl_channel
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F053|07|日本制铁握着控制权框架,少数股东的条件取决于对方的善意
研究范围:开放研究+35项覆盖检查
写入正文:07|日本制铁握着控制权框架,少数股东的条件取决于对方的善意09|同一个股价,三种利润口径,三个倍数
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、07、24
IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings怎么使用:直接 / 支持;反向验证:01、07;同业比较:30;其他用途:历史
Notice on the change of representative director (president)怎么使用:支持证据;一手验证:23、30
IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)怎么使用:支持证据;外部现实校验:23;反向验证:23;专项深挖:23;同业比较:07、13;其他用途:历史
FY12/25 securities report: major shareholders table怎么使用:支持证据;一手验证:07、24;外部现实校验:01、24;专项深挖:01、24;同业比较:23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24)|Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile;直接证据 / 支持证据 / 历史/同业比较(研究域30) / 反证(研究域01) / 反证(研究域07)|IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings;支持证据 / 一手证据(研究域23) / 一手证据(研究域30)|Notice on the change of representative director (president);支持证据 / 外部现实(研究域23) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 反证(研究域23) / 定向深挖(研究域23)|IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026);支持证据 / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域01) / 外部现实(研究域24) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域24)|FY12/25 securities report: major shareholders table
完整研究记录(核对用)
研究原文:Control sits with the Nippon Steel axis (24.29%, annual controlling-shareholder disclosures) and is tightening; strategy, succession and capital policy operate inside the group frame, and the minority question is the terms of coexistence - a structural component of the 0.67x book valuation.
内部研究类型:contributes_to_discount
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F054|08|回购加注销,让同一笔分红资金落到更高的每股金额
研究范围:开放研究
写入正文:08|回购加注销,让同一笔分红资金落到更高的每股金额
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY12/25 tanshin: shareholder-return policy statement怎么使用:直接 / 支持;一手验证:25、26
FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation怎么使用:直接 / 支持;一手验证:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|FY12/25 tanshin: shareholder-return policy statement;直接证据 / 支持证据 / 一手证据(研究域25)|FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation
完整研究记录(核对用)
研究原文:Capital relationship: Nippon Steel and stable association holders anchor the register; minorities receive the formula dividend (JPY 17 forecast) and were counterparties to the 2025 buyback of about JPY 4,031 million; the float's return depends on the formula's survival and buyback cadence, both of which held through a reported-loss year.
内部研究类型:anchors_register_for
内部来源标记:OPEN_DISCOVERY
F055|03|焚烧灰渣回收:九个月经常利润已超过去年全年
研究范围:开放研究+35项覆盖检查
写入正文:03|焚烧灰渣回收:九个月经常利润已超过去年全年09|下行靠资产和年金托底,不靠盈利
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months怎么使用:直接 / 支持;一手验证:02、15
FY12/25 tanshin: segment sales and ordinary profit for the full year怎么使用:直接 / 支持;一手验证:02;同业比较:02、09、15;其他用途:历史
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:支持证据;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:支持证据;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域15)|FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15)|FY12/25 tanshin: segment sales and ordinary profit for the full year;支持证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months;支持证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary
完整研究记录(核对用)
研究原文:Customer relationship: municipalities and industrial waste generators supply incineration-ash treatment volumes under waste law with molten-metal recovery; treatment demand does not follow metal prices, which is why the segment earned JPY 2,589 million in nine months while the alloy segment reported a loss.
内部研究类型:underwrites
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F056|01|三条腿都在两个季度内接受检验
研究范围:开放研究+35项覆盖检查
写入正文:01|三条腿都在两个季度内接受检验11|第四季度必须交出27.46亿日元经常利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接 / 支持;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:支持证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 支持证据|FY12/26 Q3 tanshin: third-quarter standalone dynamics implied by cumulative figures;直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table;支持证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;支持证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:Forecast concentration: about JPY 2,746 million of ordinary profit and JPY 3,685 million of operating profit must land in Q4 FY12/26; delivery validates the underlying-recovery framing, a miss revalidates the reported-loss narrative the market prices.
内部研究类型:concentrates_verdict
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F057|08|到2030年计划投入450至500亿日元,回报要看灰渣扩建能否守住30%利润率
研究范围:开放研究+35项覆盖检查
写入正文:08|到2030年计划投入450至500亿日元,回报要看灰渣扩建能否守住30%利润率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、19、20、21、29
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、20
Medium- and Long-Term Management Plan 2030: 2030 vision and investment plan (official English)怎么使用:支持证据;一手验证:04;外部现实校验:04、11;反向验证:20;专项深挖:04、11
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;支持证据 / 一手证据(研究域04) / 外部现实(研究域04) / 外部现实(研究域11) / 反证(研究域20) / 定向深挖(研究域04) / 定向深挖(研究域11)|Medium- and Long-Term Management Plan 2030: 2030 vision and investment plan (official English)
完整研究记录(核对用)
研究原文:Capacity investment: construction in progress rose from JPY 691 million (Dec 2025) to JPY 3,447 million (Sep 2026) on the Kashima ash-melting expansion; if it earns at the segment's current 30% ordinary margin, trough earnings rise structurally.
内部研究类型:expands_capacity_of
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F058|09|2027年12月期100亿日元目标,需要的不是价格,是三件还没发生的事
研究范围:开放研究+35项覆盖检查
写入正文:09|2027年12月期100亿日元目标,需要的不是价格,是三件还没发生的事11|保障措施一旦到期,影响的是计划,不只是毛利率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接证据;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
9th medium-term plan: FY2027 target table and FY2023 base (official English)怎么使用:支持证据;一手验证:11;同业比较:22;其他用途:历史
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:支持证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary;支持证据 / 一手证据(研究域11) / 历史/同业比较(研究域22)|9th medium-term plan: FY2027 target table and FY2023 base (official English);支持证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:Policy horizon: the domestic ferroalloy premium underpinning the FY12/26 margin jump depends on measures whose next design is not yet public; the FY12/27 plan's JPY 10.0 billion ambition implicitly assumes the premium largely survives, making the safeguard review a plan-level event.
内部研究类型:implicit_assumption_of
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F059|07|社长换成日本制铁原料部门出身者,执行可信度和集团影响一起上升
研究范围:开放研究+35项覆盖检查
写入正文:07|社长换成日本制铁原料部门出身者,执行可信度和集团影响一起上升
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Notice on the change of representative director (president)怎么使用:直接 / 支持;一手验证:23、30
President-change notice: successor profile and 10th plan timing怎么使用:直接 / 支持;一手验证:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30)|Notice on the change of representative director (president);直接证据 / 支持证据 / 一手证据(研究域23)|President-change notice: successor profile and 10th plan timing
完整研究记录(核对用)
研究原文:Succession: a Nippon Steel raw-materials executive (Nippon Denko board since March 2024) becomes president on 1 January 2027, launching the 10th medium-term plan; the same event deepens parent alignment and delivers the document that confirms or resets the FY12/27 targets minorities are pricing.
内部研究类型:launches_and_owns
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F060|08|分红按基础利润算,所以报表亏损年份也照付
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/25 tanshin: shareholder-return policy statement怎么使用:直接 / 支持;一手验证:25、26
FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50)怎么使用:直接 / 支持;一手验证:26;反向验证:25
FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure怎么使用:直接证据;一手验证:28;外部现实校验:12、16、28;专项深挖:12、16、28
FY12/26 interim tanshin: interim dividend resolution (JPY 5.50)怎么使用:支持证据;同业比较:26;其他用途:历史
FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation怎么使用:支持证据;一手验证:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|FY12/25 tanshin: shareholder-return policy statement;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域25)|FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50);直接证据 / 一手证据(研究域28) / 外部现实(研究域12) / 外部现实(研究域16) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure;支持证据 / 历史/同业比较(研究域26)|FY12/26 interim tanshin: interim dividend resolution (JPY 5.50);支持证据 / 一手证据(研究域25)|FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation
完整研究记录(核对用)
研究原文:The dividend is anchored to the underlying-profit formula, so the JPY 17.00 forecast coexists with reported EPS of JPY 4.01; the apparent payout above 400% is an artefact of the write-down.
内部研究类型:anchors
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F061|08|回购加注销,让同一笔分红资金落到更高的每股金额
研究范围:开放研究+35项覆盖检查
写入正文:08|回购加注销,让同一笔分红资金落到更高的每股金额
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation怎么使用:直接 / 支持;一手验证:25
IRBANK disclosure index: FY12/25 buyback and cancellation notices怎么使用:直接证据;外部现实校验:25;专项深挖:25;同业比较:24;其他用途:历史
FY12/26 interim tanshin: interim dividend resolution (JPY 5.50)怎么使用:直接证据;同业比较:26;其他用途:历史
FY12/25 tanshin: cash flows, buyback and treasury position怎么使用:支持证据;一手验证:17;同业比较:25;其他用途:历史
FY12/25 tanshin: shareholder-return policy statement怎么使用:支持证据;一手验证:25、26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25)|FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation;直接证据 / 外部现实(研究域25) / 历史/同业比较(研究域24) / 定向深挖(研究域25)|IRBANK disclosure index: FY12/25 buyback and cancellation notices;直接证据 / 历史/同业比较(研究域26)|FY12/26 interim tanshin: interim dividend resolution (JPY 5.50);支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域25)|FY12/25 tanshin: cash flows, buyback and treasury position;支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|FY12/25 tanshin: shareholder-return policy statement
完整研究记录(核对用)
研究原文:Buyback-and-cancel and the JPY 11 dividend floor are two halves of one per-share policy: cancelling 8.69% of shares raises the per-share payout from the same dividend pool.
内部研究类型:reinforces_per_share
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F062|06|上行期利润和现金反向走,谷底反而释放现金
研究范围:开放研究+35项覆盖检查
归并到:F013
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/25 tanshin: cash flows, buyback and treasury position怎么使用:直接 / 支持;一手验证:17;同业比较:25;其他用途:历史
FY12/25 tanshin: cash-flow statement quality check怎么使用:直接 / 支持;外部现实校验:17;专项深挖:17;同业比较:17;其他用途:历史
FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation怎么使用:支持证据;一手验证:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域25)|FY12/25 tanshin: cash flows, buyback and treasury position;直接证据 / 支持证据 / 外部现实(研究域17) / 历史/同业比较(研究域17) / 定向深挖(研究域17)|FY12/25 tanshin: cash-flow statement quality check;支持证据 / 一手证据(研究域25)|FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation
完整研究记录(核对用)
研究原文:FY12/25 trough operating cash flow of JPY 14,569 million funded the JPY 4,031 million buyback and the dividend while capex was about JPY 4,828 million and the equity ratio stayed at 76.0%.
内部研究类型:funds
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F063|06|资产负债表比利润表结实,但不是净现金
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表比利润表结实,但不是净现金09|同一个股价,三种利润口径,三个倍数
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、19、20、21、29
FY12/26 Q3 tanshin: September balance sheet and comprehensive income怎么使用:直接证据;外部现实校验:20;专项深挖:20;同业比较:18;其他用途:历史
FY12/25 tanshin: comprehensive income and the securities cushion怎么使用:直接证据;外部现实校验:21;专项深挖:21
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:支持证据;一手验证:18、20
IRBANK stock page for 5563: price, valuation and credit-balance snapshot怎么使用:支持证据;一手验证:27、31
FY December 2025 full-year earnings report (tanshin), consolidated怎么使用:支持证据;一手验证:22;同业比较:12、14;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 外部现实(研究域20) / 历史/同业比较(研究域18) / 定向深挖(研究域20)|FY12/26 Q3 tanshin: September balance sheet and comprehensive income;直接证据 / 外部现实(研究域21) / 定向深挖(研究域21)|FY12/25 tanshin: comprehensive income and the securities cushion;支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|IRBANK stock page for 5563: price, valuation and credit-balance snapshot;支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14)|FY December 2025 full-year earnings report (tanshin), consolidated
完整研究记录(核对用)
研究原文:The securities cushion kept book value near JPY 562 per share through three loss-making reported quarters, so a 0.67x book multiple is not 0.67x liquidation value; securities gains are not cash.
内部研究类型:cushions_book_value_behind
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F064|09|2027年12月期100亿日元目标,需要的不是价格,是三件还没发生的事
研究范围:开放研究+35项覆盖检查
写入正文:09|2027年12月期100亿日元目标,需要的不是价格,是三件还没发生的事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接 / 支持;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接 / 支持;反向验证:03、04、05、10
9th medium-term plan: FY2027 target table and FY2023 base (official English)怎么使用:支持证据;一手验证:11;同业比较:22;其他用途:历史
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:支持证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months;直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;支持证据 / 一手证据(研究域11) / 历史/同业比较(研究域22)|9th medium-term plan: FY2027 target table and FY2023 base (official English);支持证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:A shrinking functional-materials segment raises the share of the FY12/27 profit step that must come from the overseas turnaround and ash-recycling expansion.
内部研究类型:weakens_delivery_path
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F065|09|2027年12月期100亿日元目标,需要的不是价格,是三件还没发生的事
研究范围:开放研究+35项覆盖检查
写入正文:09|2027年12月期100亿日元目标,需要的不是价格,是三件还没发生的事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
Affiliate write-down notice: impairment mechanics and P&L routing怎么使用:支持证据;一手验证:32;外部现实校验:32;反向验证:16、21、29、33;专项深挖:32
9th medium-term plan: FY2027 target table and FY2023 base (official English)怎么使用:支持证据;一手验证:11;同业比较:22;其他用途:历史
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:支持证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;支持证据 / 一手证据(研究域32) / 外部现实(研究域32) / 反证(研究域16) / 反证(研究域21) / 反证(研究域29) / 反证(研究域33) / 定向深挖(研究域32)|Affiliate write-down notice: impairment mechanics and P&L routing;支持证据|FY12/26 interim tanshin: subsequent events note;支持证据 / 一手证据(研究域11) / 历史/同业比较(研究域22)|9th medium-term plan: FY2027 target table and FY2023 base (official English);支持证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:The overseas operation returning to underlying profit in FY12/27 (from about -JPY 0.4 billion in FY12/26) is one of the steps the JPY 10.0 billion ordinary-profit target needs.
内部研究类型:is_precondition_for
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F066|01|反证有八条,但不是八个独立风险
研究范围:开放研究+35项覆盖检查
写入正文:01|反证有八条,但不是八个独立风险
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接 / 支持;一手验证:12、29、33;同业比较:28、35;其他用途:历史
IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:29、33;反向验证:35;专项深挖:29、33;同业比较:08、10、11;其他用途:历史
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:支持证据;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:支持证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域29) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 反证(研究域35) / 定向深挖(研究域29) / 定向深挖(研究域33)|IRBANK disclosure index: the FY12/19 loss notices (30 January 2020);支持证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table;支持证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:The counter-evidence stack conditions the thesis: confidence rests on three dated legs, and clustering of policy, cycle and forecast-shape items could jointly break them.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F067|06|减值、库存评估损和联营公司损失,不是第一次一起出现
研究范围:开放研究+35项覆盖检查
写入正文:06|减值、库存评估损和联营公司损失,不是第一次一起出现
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接 / 支持;一手验证:12、29、33;同业比较:28、35;其他用途:历史
IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:29、33;反向验证:35;专项深挖:29、33;同业比较:08、10、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域29) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 反证(研究域35) / 定向深挖(研究域29) / 定向深挖(研究域33)|IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)
完整研究记录(核对用)
研究原文:The repeated impairment/inventory/affiliate anatomy (FY12/19 and FY12/26) sits on top of the price cycle and amplifies its reported-profit swings.
内部研究类型:reinforces_pattern
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F068|13|第四季度会不会交出27.46亿日元经常利润
研究范围:开放研究
归并到:F037
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接证据;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
查看完整证据标签(核对用)
直接证据|FY12/26 Q3 tanshin: third-quarter standalone dynamics implied by cumulative figures;直接证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table
完整研究记录(核对用)
研究原文:The Q4 delivery question is the open uncertainty on the forecast shape.
内部研究类型:resolves_when_printed
内部来源标记:OPEN_DISCOVERY
F069|13|Pertama清零之后,还会不会消耗现金
研究范围:开放研究
归并到:F038
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
查看完整证据标签(核对用)
完整研究记录(核对用)
研究原文:Undisclosed guarantees or funding qualify the closure judgment.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY
F070|13|保障措施到期或重新设计后,国内溢价和那段毛利率还剩多少
研究范围:开放研究
写入正文:13|保障措施到期或重新设计后,国内溢价和那段毛利率还剩多少
归并到:F039
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接证据;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary
完整研究记录(核对用)
研究原文:The unknown post-2026 safeguard design qualifies the durability of the premium.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY
F071|13|第十次中期计划会设定什么目标,会不会保留100亿日元和分红公式
研究范围:开放研究
写入正文:13|第十次中期计划会设定什么目标,会不会保留100亿日元和分红公式
归并到:F040
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary怎么使用:直接证据;一手验证:04、11、30
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:直接证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域11) / 一手证据(研究域30)|Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary;直接证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business
完整研究记录(核对用)
研究原文:The unpublished 10th plan is the open reset of the plan targets and formula.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY
F072|13|灰渣利润率能否保持,功能材料是复苏还是继续缩小
研究范围:开放研究
写入正文:13|灰渣利润率能否保持,功能材料是复苏还是继续缩小
归并到:F041
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months怎么使用:直接证据;一手验证:02、15
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、19、20、21、29
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域15)|FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months;直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026
完整研究记录(核对用)
研究原文:Margin persistence and furnace capacity are unresolved for the second engine.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY
F073|13|灰渣利润率能否保持,功能材料是复苏还是继续缩小
研究范围:开放研究
写入正文:13|灰渣利润率能否保持,功能材料是复苏还是继续缩小
归并到:F042
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接证据;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds
完整研究记录(核对用)
研究原文:Recovery or shrinkage of functional materials is unresolved.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY
F074|13|母公司轴线和价格高度这两件,优先级较低但要继续看
研究范围:开放研究
写入正文:13|母公司轴线和价格高度这两件,优先级较低但要继续看
归并到:F043
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings怎么使用:直接证据;反向验证:01、07;同业比较:30;其他用途:历史
IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)怎么使用:直接证据;外部现实校验:23;反向验证:23;专项深挖:23;同业比较:07、13;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域30) / 反证(研究域01) / 反证(研究域07)|IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings;直接证据 / 外部现实(研究域23) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 反证(研究域23) / 定向深挖(研究域23)|IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)
完整研究记录(核对用)
研究原文:Whether the group axis changes capital policy or positioning is unresolved.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY
F075|13|母公司轴线和价格高度这两件,优先级较低但要继续看
研究范围:开放研究
写入正文:13|母公司轴线和价格高度这两件,优先级较低但要继续看
归并到:F044
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026怎么使用:直接证据;一手验证:34
IRBANK stock page for 5563: latest daily close, 6 November 2026怎么使用:直接证据;反向验证:31、34
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域34)|Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026;直接证据 / 反证(研究域31) / 反证(研究域34)|IRBANK stock page for 5563: latest daily close, 6 November 2026
完整研究记录(核对用)
研究原文:The base-hold question corresponds to the Technical Question held in the protected Technical structure; it is referenced as a whole and not answered or redefined here.
内部研究类型:poses_question_to_whole
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F076|10|业绩日的价格反应:先对放量定价,后对利润表语言打折
研究范围:开放研究
写入正文:10|业绩日的价格反应:先对放量定价,后对利润表语言打折
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
IRBANK stock page for 5563: 6 November 2026 close and day move怎么使用:直接证据;一手验证:31;外部现实校验:31;反向验证:27、30;专项深挖:31
IRBANK stock page for 5563: latest daily close, 6 November 2026怎么使用:直接证据;反向验证:31、34
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域31) / 外部现实(研究域31) / 反证(研究域27) / 反证(研究域30) / 定向深挖(研究域31)|IRBANK stock page for 5563: 6 November 2026 close and day move;直接证据 / 反证(研究域31) / 反证(研究域34)|IRBANK stock page for 5563: latest daily close, 6 November 2026
完整研究记录(核对用)
研究原文:The fundamental expectation finding (operating beat and unchanged forecast sold 5.3% on the reported loss) is available as event context for the price-response and timing study; it reuses existing evidence identities and does not enter or alter the Pure Technical State, which a non-confirming or confirming fundamental reading may never rewrite.
内部研究类型:event_context_for_response_study
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F077|10|这轮上涨,是脱离二十五年底部,还是又一次冲高回落
写入正文:10|这轮上涨,是脱离二十五年底部,还是又一次冲高回落10|二十五年价格史分五段,每次冲高都没有守住10|价格长期活在100到400日元,500日元上方筹码稀薄10|底部在逐代抬高,但向上只被验证过一次10|第一轮脉冲已用完,回踩停在底部上沿而不是里面10|均线、压缩与量能:站稳尚未确认,也没有触发结构重置10|当前状态是试探性脱离,内部矛盾是高度和证明不匹配10|价格上什么会确认,什么会推翻14|技术结构 7.8/13:脱离了长期底部,但只有一轮脉冲
归并到:F036
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026怎么使用:直接 / 支持;一手验证:34
Locally recomputed monthly close distribution from the assembled price history, 2001-2026怎么使用:直接 / 支持;同业比较:34;其他用途:历史
Locally recomputed monthly bars for 2025-2026 from the assembled price history怎么使用:直接 / 支持;一手验证:34
IRBANK stock page for 5563: price, valuation and credit-balance snapshot怎么使用:支持证据;一手验证:27、31
IRBANK stock page for 5563: fiscal-year high and low prices怎么使用:支持证据;外部现实校验:34
IRBANK stock page for 5563: latest daily close, 6 November 2026怎么使用:支持证据;反向验证:31、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域34)|Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026;直接证据 / 支持证据 / 历史/同业比较(研究域34)|Locally recomputed monthly close distribution from the assembled price history, 2001-2026;直接证据 / 支持证据 / 一手证据(研究域34)|Locally recomputed monthly bars for 2025-2026 from the assembled price history;支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|IRBANK stock page for 5563: price, valuation and credit-balance snapshot;支持证据 / 外部现实(研究域34)|IRBANK stock page for 5563: fiscal-year high and low prices;支持证据 / 反证(研究域31) / 反证(研究域34)|IRBANK stock page for 5563: latest daily close, 6 November 2026
完整研究记录(核对用)
研究原文:The price-record claim observations defer in interpretation and completeness to the protected Technical structure as a whole.
内部研究类型:claim_identity_defers_to
内部来源标记:TECHNICAL
F078|10|这轮上涨,是脱离二十五年底部,还是又一次冲高回落
写入正文:10|这轮上涨,是脱离二十五年底部,还是又一次冲高回落10|二十五年价格史分五段,每次冲高都没有守住10|价格长期活在100到400日元,500日元上方筹码稀薄10|底部在逐代抬高,但向上只被验证过一次10|第一轮脉冲已用完,回踩停在底部上沿而不是里面10|均线、压缩与量能:站稳尚未确认,也没有触发结构重置10|当前状态是试探性脱离,内部矛盾是高度和证明不匹配10|业绩日的价格反应:先对放量定价,后对利润表语言打折10|价格上什么会确认,什么会推翻14|技术结构 7.8/13:脱离了长期底部,但只有一轮脉冲
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical State (RESEARCH_TRUTH.technical_state, dereference only)
内部研究类型:protected_technical_synthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
F079|02|可以持有的是国内合金地位加回收年金,不是任何一年的盈利
研究范围:开放研究+35项覆盖检查
写入正文:02|可以持有的是国内合金地位加回收年金,不是任何一年的盈利
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(42项,重复标签已合并)
Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、07、24
FY12/25 tanshin: segment sales and ordinary profit for the full year怎么使用:直接 / 支持;一手验证:02;同业比较:02、09、15;其他用途:历史
FY12/25 tanshin: shareholder-return policy statement怎么使用:直接 / 支持;一手验证:25、26
FY12/26 interim tanshin: segment information note (sales, segment profit)怎么使用:直接 / 支持;外部现实校验:02;专项深挖:02
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接 / 支持;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
Notice on the publication of the 100th anniversary history (founding October 1925)怎么使用:直接证据;一手验证:01、03、10
IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:29、33;反向验证:35;专项深挖:29、33;同业比较:08、10、11;其他用途:历史
Centenary notice: founding in October 1925 and company history outline怎么使用:直接 / 支持;一手验证:09、10;外部现实校验:07、10;专项深挖:07、10;同业比较:01、03、04、33;其他用途:历史
FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months怎么使用:直接 / 支持;一手验证:02、15
FY12/26 interim tanshin: demand commentary by segment怎么使用:直接证据;一手验证:03、05、08;外部现实校验:03、05、08;反向验证:09、11、15;专项深挖:03、05、08;同业比较:06;其他用途:历史
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接 / 支持;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
FY12/26 interim tanshin: segment sales and ordinary profit for H1怎么使用:直接证据;一手验证:02
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion)怎么使用:直接 / 支持;外部现实校验:06;专项深挖:06
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、19、20、21、29
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、20
FY12/26 interim tanshin: interim balance-sheet detail怎么使用:直接 / 支持;一手验证:19、21;外部现实校验:19;反向验证:17;专项深挖:19
FY12/26 Q3 tanshin: September balance sheet and comprehensive income怎么使用:直接证据;外部现实校验:20;专项深挖:20;同业比较:18;其他用途:历史
FY12/25 tanshin: year-end balance sheet detail怎么使用:直接证据;外部现实校验:18;专项深挖:18;同业比较:19、20、21、29;其他用途:历史
FY12/25 tanshin: comprehensive income and the securities cushion怎么使用:直接证据;外部现实校验:21;专项深挖:21
FY12/25 tanshin: cash flows, buyback and treasury position怎么使用:直接 / 支持;一手验证:17;同业比较:25;其他用途:历史
FY12/26 interim tanshin: interim cash-flow statement怎么使用:直接 / 支持;一手验证:17;反向验证:19
FY12/25 tanshin: cash-flow statement quality check怎么使用:直接 / 支持;外部现实校验:17;专项深挖:17;同业比较:17;其他用途:历史
FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation怎么使用:直接 / 支持;一手验证:25
FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50)怎么使用:直接 / 支持;一手验证:26;反向验证:25
FY12/25 tanshin: dividend record (interim 6.00 / year-end 6.00)怎么使用:直接证据;外部现实校验:26;专项深挖:26
FY12/26 interim tanshin: interim dividend resolution (JPY 5.50)怎么使用:直接 / 支持;同业比较:26;其他用途:历史
IRBANK disclosure index: FY12/25 buyback and cancellation notices怎么使用:直接证据;外部现实校验:25;专项深挖:25;同业比较:24;其他用途:历史
Notice on the change of representative director (president)怎么使用:直接 / 支持;一手验证:23、30
IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings怎么使用:直接 / 支持;反向验证:01、07;同业比较:30;其他用途:历史
FY12/25 securities report: major shareholders table怎么使用:直接 / 支持;一手验证:07、24;外部现实校验:01、24;专项深挖:01、24;同业比较:23;其他用途:历史
IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)怎么使用:直接 / 支持;外部现实校验:23;反向验证:23;专项深挖:23;同业比较:07、13;其他用途:历史
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接 / 支持;一手验证:12、29、33;同业比较:28、35;其他用途:历史
FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure怎么使用:直接证据;一手验证:28;外部现实校验:12、16、28;专项深挖:12、16、28
FY December 2025 full-year earnings report (tanshin), consolidated怎么使用:直接 / 支持;一手验证:22;同业比较:12、14;其他用途:历史
FY12/25 tanshin: per-share and ratio indicators怎么使用:直接证据;一手验证:22;外部现实校验:22;专项深挖:22
9th medium-term plan: FY2027 target table and FY2023 base (official English)怎么使用:直接证据;一手验证:11;同业比较:22;其他用途:历史
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接证据;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:直接证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
IRBANK stock page for 5563: price, valuation and credit-balance snapshot怎么使用:支持证据;一手验证:27、31
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24)|Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15)|FY12/25 tanshin: segment sales and ordinary profit for the full year;直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|FY12/25 tanshin: shareholder-return policy statement;直接证据 / 支持证据 / 外部现实(研究域02) / 定向深挖(研究域02)|FY12/26 interim tanshin: segment information note (sales, segment profit);直接证据 / 支持证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months;直接证据 / 一手证据(研究域01) / 一手证据(研究域03) / 一手证据(研究域10)|Notice on the publication of the 100th anniversary history (founding October 1925);直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域29) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 反证(研究域35) / 定向深挖(研究域29) / 定向深挖(研究域33)|IRBANK disclosure index: the FY12/19 loss notices (30 January 2020);直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域10) / 外部现实(研究域07) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域10)|Centenary notice: founding in October 1925 and company history outline;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域15)|FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months;直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域08) / 历史/同业比较(研究域06) / 反证(研究域09) / 反证(研究域11) / 反证(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05) / 定向深挖(研究域08)|FY12/26 interim tanshin: demand commentary by segment;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary;直接证据 / 一手证据(研究域02)|FY12/26 interim tanshin: segment sales and ordinary profit for H1;直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;直接证据 / 支持证据 / 外部现实(研究域06) / 定向深挖(研究域06)|FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion);直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|FY12/26 interim tanshin: interim balance-sheet detail;直接证据 / 外部现实(研究域20) / 历史/同业比较(研究域18) / 定向深挖(研究域20)|FY12/26 Q3 tanshin: September balance sheet and comprehensive income;直接证据 / 外部现实(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/25 tanshin: year-end balance sheet detail;直接证据 / 外部现实(研究域21) / 定向深挖(研究域21)|FY12/25 tanshin: comprehensive income and the securities cushion;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域25)|FY12/25 tanshin: cash flows, buyback and treasury position;直接证据 / 支持证据 / 一手证据(研究域17) / 反证(研究域19)|FY12/26 interim tanshin: interim cash-flow statement;直接证据 / 支持证据 / 外部现实(研究域17) / 历史/同业比较(研究域17) / 定向深挖(研究域17)|FY12/25 tanshin: cash-flow statement quality check;直接证据 / 支持证据 / 一手证据(研究域25)|FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域25)|FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50);直接证据 / 外部现实(研究域26) / 定向深挖(研究域26)|FY12/25 tanshin: dividend record (interim 6.00 / year-end 6.00);直接证据 / 支持证据 / 历史/同业比较(研究域26)|FY12/26 interim tanshin: interim dividend resolution (JPY 5.50);直接证据 / 外部现实(研究域25) / 历史/同业比较(研究域24) / 定向深挖(研究域25)|IRBANK disclosure index: FY12/25 buyback and cancellation notices;直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30)|Notice on the change of representative director (president);直接证据 / 支持证据 / 历史/同业比较(研究域30) / 反证(研究域01) / 反证(研究域07)|IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings;直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域01) / 外部现实(研究域24) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域24)|FY12/25 securities report: major shareholders table;直接证据 / 支持证据 / 外部现实(研究域23) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 反证(研究域23) / 定向深挖(研究域23)|IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据 / 一手证据(研究域28) / 外部现实(研究域12) / 外部现实(研究域16) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure;直接证据|FY12/26 Q3 tanshin: nine-month underlying ordinary profit (JPY 5.1 billion);直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14)|FY December 2025 full-year earnings report (tanshin), consolidated;直接证据 / 一手证据(研究域22) / 外部现实(研究域22) / 定向深挖(研究域22)|FY12/25 tanshin: per-share and ratio indicators;直接证据 / 一手证据(研究域11) / 历史/同业比较(研究域22)|9th medium-term plan: FY2027 target table and FY2023 base (official English);直接证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table;直接证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business;支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|IRBANK stock page for 5563: price, valuation and credit-balance snapshot
完整研究记录(核对用)
研究原文:Durable Business Portrait: a consolidated manganese franchise with a recycling annuity, a strong balance sheet and a formula that pays on underlying profit|Foundation before change: the position (domestic alloy consolidation, recycling permits, hydro, a 74%-equity balance sheet and securities cushion, a return formula tested through a reported-loss year) is durable; the reported profit level is not. The current upturn, the affiliate write-down and the plan are increments overlaid on this base, not substitutes for it. Self-repair has been demonstrated twice (FY12/19, FY12/26) by balance-sheet absorption, annuity profits and the dividend floor; irreversible-break risk would come from a safeguard lapse coinciding with a price collapse, which has no precedent in the record. Structural durability: what is durable is the position, not any year's profit; the investment question is a race between delivery and the finite safeguard premium.
内部研究类型:durable_business_portrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Holders own a durable position at below-book pricing with a formula-backed return, but must accept cyclical, policy-dependent reported earnings and capital efficiency near the cost of equity.
不确定性(原始记录):The durability of the alloy moat is cost-position only; the recycling moat evidence is structural rather than contract-level; return on the investment envelope is unproven.
F080|06|利润抬升来自价格,不来自销量
研究范围:开放研究+35项覆盖检查
写入正文:06|利润抬升来自价格,不来自销量09|同一个股价,三种利润口径,三个倍数
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(33项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接 / 支持;一手验证:06、12、14、16
FY12/26 interim tanshin: demand commentary by segment怎么使用:直接证据;一手验证:03、05、08;外部现实校验:03、05、08;反向验证:09、11、15;专项深挖:03、05、08;同业比较:06;其他用途:历史
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接 / 支持;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
FY12/26 interim tanshin: segment sales and ordinary profit for H1怎么使用:直接证据;一手验证:02
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、19、20、21、29
FY12/26 interim tanshin: interim cash-flow statement怎么使用:直接 / 支持;一手验证:17;反向验证:19
FY12/26 interim tanshin: interim balance-sheet detail怎么使用:直接 / 支持;一手验证:19、21;外部现实校验:19;反向验证:17;专项深挖:19
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、20
FY12/25 tanshin: cash flows, buyback and treasury position怎么使用:直接 / 支持;一手验证:17;同业比较:25;其他用途:历史
FY12/25 tanshin: cash-flow statement quality check怎么使用:直接 / 支持;外部现实校验:17;专项深挖:17;同业比较:17;其他用途:历史
Notice on the valuation loss on affiliate shares and the equity-method investment loss怎么使用:直接 / 支持;一手验证:32
FY12/25 tanshin: income-statement bridge and non-operating items怎么使用:直接证据;同业比较:16、32;其他用途:历史
FY12/26 interim tanshin: interim income statement detail怎么使用:直接证据;一手验证:16;反向验证:32
Affiliate write-down notice: impairment mechanics and P&L routing怎么使用:直接 / 支持;一手验证:32;外部现实校验:32;反向验证:16、21、29、33;专项深挖:32
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
FY12/26 interim tanshin: subsequent events note怎么使用:直接 / 支持
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、07、24
FY12/25 tanshin: segment sales and ordinary profit for the full year怎么使用:直接 / 支持;一手验证:02;同业比较:02、09、15;其他用途:历史
FY12/25 tanshin: shareholder-return policy statement怎么使用:直接 / 支持;一手验证:25、26
FY12/26 interim tanshin: segment information note (sales, segment profit)怎么使用:直接 / 支持;外部现实校验:02;专项深挖:02
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接 / 支持;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
FY12/26 Q3 tanshin: September balance sheet and comprehensive income怎么使用:直接证据;外部现实校验:20;专项深挖:20;同业比较:18;其他用途:历史
FY12/25 tanshin: comprehensive income and the securities cushion怎么使用:直接证据;外部现实校验:21;专项深挖:21
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接证据;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure怎么使用:直接证据;一手验证:28;外部现实校验:12、16、28;专项深挖:12、16、28
FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion)怎么使用:直接证据;外部现实校验:06;专项深挖:06
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter;直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域08) / 历史/同业比较(研究域06) / 反证(研究域09) / 反证(研究域11) / 反证(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05) / 定向深挖(研究域08)|FY12/26 interim tanshin: demand commentary by segment;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary;直接证据 / 一手证据(研究域02)|FY12/26 interim tanshin: segment sales and ordinary profit for H1;直接证据 / 支持证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;直接证据|FY12/26 Q1 tanshin: headline results and the margin turn;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 反证(研究域19)|FY12/26 interim tanshin: interim cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|FY12/26 interim tanshin: interim balance-sheet detail;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域25)|FY12/25 tanshin: cash flows, buyback and treasury position;直接证据 / 支持证据 / 外部现实(研究域17) / 历史/同业比较(研究域17) / 定向深挖(研究域17)|FY12/25 tanshin: cash-flow statement quality check;直接证据 / 支持证据|FY December 2026 interim earnings report (tanshin), consolidated, Japanese GAAP;直接证据 / 支持证据 / 一手证据(研究域32)|Notice on the valuation loss on affiliate shares and the equity-method investment loss;直接证据 / 历史/同业比较(研究域16) / 历史/同业比较(研究域32)|FY12/25 tanshin: income-statement bridge and non-operating items;直接证据 / 一手证据(研究域16) / 反证(研究域32)|FY12/26 interim tanshin: interim income statement detail;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域32) / 反证(研究域16) / 反证(研究域21) / 反证(研究域29) / 反证(研究域33) / 定向深挖(研究域32)|Affiliate write-down notice: impairment mechanics and P&L routing;直接证据|FY12/26 Q3 tanshin: nine-month underlying ordinary profit (JPY 5.1 billion);直接证据 / 支持证据|FY12/26 Q3 tanshin: third-quarter standalone dynamics implied by cumulative figures;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;直接证据 / 支持证据|FY12/26 interim tanshin: subsequent events note;直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24)|Securities report data for Nippon Denko (FY12/2025): major shareholders and company profile;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15)|FY12/25 tanshin: segment sales and ordinary profit for the full year;直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|FY12/25 tanshin: shareholder-return policy statement;直接证据 / 支持证据 / 外部现实(研究域02) / 定向深挖(研究域02)|FY12/26 interim tanshin: segment information note (sales, segment profit);直接证据 / 支持证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months;直接证据 / 外部现实(研究域20) / 历史/同业比较(研究域18) / 定向深挖(研究域20)|FY12/26 Q3 tanshin: September balance sheet and comprehensive income;直接证据 / 外部现实(研究域21) / 定向深挖(研究域21)|FY12/25 tanshin: comprehensive income and the securities cushion;直接证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table;直接证据 / 一手证据(研究域28) / 外部现实(研究域12) / 外部现实(研究域16) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure;直接证据 / 外部现实(研究域06) / 定向深挖(研究域06)|FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion)
完整研究记录(核对用)
研究原文:Two-layer profit chain: policy-fed price rise to operating surge, inventory amplification, affiliate charge below the line|European safeguards lift ferromanganese prices; a weak yen and easing ore widen the spread; inventory valuation gains amplify gross margin (14.8% to 22.3%) and operating profit (+131.6%); the same price rise absorbs cash into inventories and receivables, so operating cash flow falls while profit rises; below the operating line the full Pertama write-down turns reported ordinary profit negative while underlying profit roughly doubles. The unchanged forecast then back-loads the year into Q4.
内部研究类型:main_causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Valuation must be run on the underlying language (about 6.3x) rather than the statutory print (about 94x EPS), but the underlying profit rests on a policy rent and valuation effects and is verified only when Q4 prints.
不确定性(原始记录):Split of the profit rise among price, FX and inventory valuation is not disclosed by quarter; underlying series is non-GAAP.
F081|06|资产负债表比利润表结实,但不是净现金
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(18项,重复标签已合并)
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18、19、20、21、29
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、20
FY12/26 interim tanshin: interim balance-sheet detail怎么使用:直接 / 支持;一手验证:19、21;外部现实校验:19;反向验证:17;专项深挖:19
FY12/26 Q3 tanshin: September balance sheet and comprehensive income怎么使用:直接证据;外部现实校验:20;专项深挖:20;同业比较:18;其他用途:历史
FY12/25 tanshin: year-end balance sheet detail怎么使用:直接证据;外部现实校验:18;专项深挖:18;同业比较:19、20、21、29;其他用途:历史
FY12/25 tanshin: comprehensive income and the securities cushion怎么使用:直接证据;外部现实校验:21;专项深挖:21
FY12/26 interim tanshin: interim cash-flow statement怎么使用:直接 / 支持;一手验证:17;反向验证:19
FY12/25 tanshin: cash flows, buyback and treasury position怎么使用:直接 / 支持;一手验证:17;同业比较:25;其他用途:历史
FY12/25 tanshin: cash-flow statement quality check怎么使用:直接 / 支持;外部现实校验:17;专项深挖:17;同业比较:17;其他用途:历史
FY December 2025 full-year earnings report (tanshin), consolidated怎么使用:直接 / 支持;一手验证:22;同业比较:12、14;其他用途:历史
IRBANK stock page for 5563: price, valuation and credit-balance snapshot怎么使用:直接 / 支持;一手验证:27、31
IRBANK stock page for 5563: market capitalisation, yield and margin data怎么使用:直接 / 支持;一手验证:27;外部现实校验:27;反向验证:18、24、26;专项深挖:27;同业比较:31;其他用途:历史
IRBANK stock page for 5563: 6 November 2026 close and day move怎么使用:直接证据;一手验证:31;外部现实校验:31;反向验证:27、30;专项深挖:31
FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50)怎么使用:支持证据;一手验证:26;反向验证:25
Notice on the valuation loss on affiliate shares and the equity-method investment loss怎么使用:直接证据;一手验证:32
FY12/25 tanshin: income-statement bridge and non-operating items怎么使用:直接证据;同业比较:16、32;其他用途:历史
FY12/26 interim tanshin: interim income statement detail怎么使用:直接证据;一手验证:16;反向验证:32
Affiliate write-down notice: impairment mechanics and P&L routing怎么使用:直接证据;一手验证:32;外部现实校验:32;反向验证:16、21、29、33;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域19) / 一手证据(研究域21) / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|FY12/26 interim tanshin: interim balance-sheet detail;直接证据 / 外部现实(研究域20) / 历史/同业比较(研究域18) / 定向深挖(研究域20)|FY12/26 Q3 tanshin: September balance sheet and comprehensive income;直接证据 / 外部现实(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/25 tanshin: year-end balance sheet detail;直接证据 / 外部现实(研究域21) / 定向深挖(研究域21)|FY12/25 tanshin: comprehensive income and the securities cushion;直接证据 / 支持证据 / 一手证据(研究域17) / 反证(研究域19)|FY12/26 interim tanshin: interim cash-flow statement;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域25)|FY12/25 tanshin: cash flows, buyback and treasury position;直接证据 / 支持证据 / 外部现实(研究域17) / 历史/同业比较(研究域17) / 定向深挖(研究域17)|FY12/25 tanshin: cash-flow statement quality check;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14)|FY December 2025 full-year earnings report (tanshin), consolidated;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|IRBANK stock page for 5563: price, valuation and credit-balance snapshot;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域27) / 历史/同业比较(研究域31) / 反证(研究域18) / 反证(研究域24) / 反证(研究域26) / 定向深挖(研究域27)|IRBANK stock page for 5563: market capitalisation, yield and margin data;直接证据 / 一手证据(研究域31) / 外部现实(研究域31) / 反证(研究域27) / 反证(研究域30) / 定向深挖(研究域31)|IRBANK stock page for 5563: 6 November 2026 close and day move;支持证据 / 一手证据(研究域26) / 反证(研究域25)|FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50);直接证据 / 一手证据(研究域32)|Notice on the valuation loss on affiliate shares and the equity-method investment loss;直接证据 / 历史/同业比较(研究域16) / 历史/同业比较(研究域32)|FY12/25 tanshin: income-statement bridge and non-operating items;直接证据 / 一手证据(研究域16) / 反证(研究域32)|FY12/26 interim tanshin: interim income statement detail;直接证据 / 一手证据(研究域32) / 外部现实(研究域32) / 反证(研究域16) / 反证(研究域21) / 反证(研究域29) / 反证(研究域33) / 定向深挖(研究域32)|Affiliate write-down notice: impairment mechanics and P&L routing
完整研究记录(核对用)
研究原文:The balance sheet bridges the two profit languages|The balance sheet is the bridge between the two profit languages: a 74% equity ratio, a JPY 14.5 billion securities portfolio whose unrealised gains kept book value near JPY 562 a share through three loss-making reported quarters, and inventories of about JPY 26.4 billion that translate price turns into reported profit before they translate into cash.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Book value and the dividend floor protect holders while reported profit is distorted; cash, not profit, is the test in the upcycle.
不确定性(原始记录):Securities values are market-sensitive; year-end balances unknown.
F082|12|灰渣扩建把利润率、资本开支和下行保护绑在了一起
研究范围:开放研究+35项覆盖检查
写入正文:12|灰渣扩建把利润率、资本开支和下行保护绑在了一起
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(20项,重复标签已合并)
FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months怎么使用:直接 / 支持;一手验证:02、15
FY12/25 tanshin: segment sales and ordinary profit for the full year怎么使用:直接 / 支持;一手验证:02;同业比较:02、09、15;其他用途:历史
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接 / 支持;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
FY12/26 interim tanshin: demand commentary by segment怎么使用:直接证据;一手验证:03、05、08;外部现实校验:03、05、08;反向验证:09、11、15;专项深挖:03、05、08;同业比较:06;其他用途:历史
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接 / 支持;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、19、20、21、29
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、20
Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary怎么使用:直接证据;一手验证:04、11、30
IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings怎么使用:直接证据;反向验证:01、07;同业比较:30;其他用途:历史
Medium- and Long-Term Management Plan 2030: 2030 vision and investment plan (official English)怎么使用:直接 / 支持;一手验证:04;外部现实校验:04、11;反向验证:20;专项深挖:04、11
Medium- and Long-Term Management Plan 2030: environmental targets (official English)怎么使用:直接证据;一手验证:13
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接证据;一手验证:12、29、33;同业比较:28、35;其他用途:历史
IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)怎么使用:直接证据;一手验证:09、33;外部现实校验:29、33;反向验证:35;专项深挖:29、33;同业比较:08、10、11;其他用途:历史
FY12/25 tanshin: year-end balance sheet detail怎么使用:直接证据;外部现实校验:18;专项深挖:18;同业比较:19、20、21、29;其他用途:历史
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure怎么使用:直接证据;一手验证:28;外部现实校验:12、16、28;专项深挖:12、16、28
FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion)怎么使用:直接证据;外部现实校验:06;专项深挖:06
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接证据;一手验证:06、12、14、16
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域15)|FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域15)|FY12/25 tanshin: segment sales and ordinary profit for the full year;直接证据 / 支持证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months;直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域08) / 历史/同业比较(研究域06) / 反证(研究域09) / 反证(研究域11) / 反证(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05) / 定向深挖(研究域08)|FY12/26 interim tanshin: demand commentary by segment;直接证据 / 支持证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary;直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 一手证据(研究域04) / 一手证据(研究域11) / 一手证据(研究域30)|Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary;直接证据 / 历史/同业比较(研究域30) / 反证(研究域01) / 反证(研究域07)|IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings;直接证据 / 支持证据 / 一手证据(研究域04) / 外部现实(研究域04) / 外部现实(研究域11) / 反证(研究域20) / 定向深挖(研究域04) / 定向深挖(研究域11)|Medium- and Long-Term Management Plan 2030: 2030 vision and investment plan (official English);直接证据 / 一手证据(研究域13)|Medium- and Long-Term Management Plan 2030: environmental targets (official English);直接证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域29) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 反证(研究域35) / 定向深挖(研究域29) / 定向深挖(研究域33)|IRBANK disclosure index: the FY12/19 loss notices (30 January 2020);直接证据 / 外部现实(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/25 tanshin: year-end balance sheet detail;直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 一手证据(研究域28) / 外部现实(研究域12) / 外部现实(研究域16) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure;直接证据 / 外部现实(研究域06) / 定向深挖(研究域06)|FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion);直接证据|FY12/26 Q3 tanshin: nine-month underlying ordinary profit (JPY 5.1 billion);直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter
完整研究记录(核对用)
研究原文:Ash recycling fuses the margin, capex and downside theses|The ash-recycling segment fuses the margin thesis, the capex thesis and the downside thesis: it is the highest-margin profit pool (30.3%), the destination of the growth capex now visible in construction in progress, and the annuity that protected trough earnings in FY12/23-25 - its Kashima expansion is the single most informative capital decision in the register.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):If the expansion earns near the current margin, trough earnings rise structurally; if molten-metal prices normalise, the annuity and the capex case weaken together.
不确定性(原始记录):Capacity and return of the expansion are undisclosed.
F083|08|分红按基础利润算,所以报表亏损年份也照付
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(21项,重复标签已合并)
FY12/25 tanshin: shareholder-return policy statement怎么使用:直接 / 支持;一手验证:25、26
FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation怎么使用:直接 / 支持;一手验证:25
FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50)怎么使用:直接 / 支持;一手验证:26;反向验证:25
FY12/25 tanshin: dividend record (interim 6.00 / year-end 6.00)怎么使用:直接证据;外部现实校验:26;专项深挖:26
FY12/26 interim tanshin: interim dividend resolution (JPY 5.50)怎么使用:直接 / 支持;同业比较:26;其他用途:历史
FY12/25 tanshin: cash flows, buyback and treasury position怎么使用:直接 / 支持;一手验证:17;同业比较:25;其他用途:历史
FY12/26 Q3 tanshin: September balance sheet and comprehensive income怎么使用:直接证据;外部现实校验:20;专项深挖:20;同业比较:18;其他用途:历史
IRBANK disclosure index: FY12/25 buyback and cancellation notices怎么使用:直接证据;外部现实校验:25;专项深挖:25;同业比较:24;其他用途:历史
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure怎么使用:直接证据;一手验证:28;外部现实校验:12、16、28;专项深挖:12、16、28
FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion)怎么使用:直接证据;外部现实校验:06;专项深挖:06
Notice on the valuation loss on affiliate shares and the equity-method investment loss怎么使用:直接 / 支持;一手验证:32
FY12/25 tanshin: income-statement bridge and non-operating items怎么使用:直接证据;同业比较:16、32;其他用途:历史
FY12/26 interim tanshin: interim income statement detail怎么使用:直接证据;一手验证:16;反向验证:32
Affiliate write-down notice: impairment mechanics and P&L routing怎么使用:直接证据;一手验证:32;外部现实校验:32;反向验证:16、21、29、33;专项深挖:32
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、20
FY12/26 interim tanshin: interim cash-flow statement怎么使用:直接 / 支持;一手验证:17;反向验证:19
FY12/25 tanshin: cash-flow statement quality check怎么使用:直接 / 支持;外部现实校验:17;专项深挖:17;同业比较:17;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|FY12/25 tanshin: shareholder-return policy statement;直接证据 / 支持证据 / 一手证据(研究域25)|FY12/26 interim tanshin: revised full-year forecast, dividend raise and treasury-share cancellation;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域25)|FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50);直接证据 / 外部现实(研究域26) / 定向深挖(研究域26)|FY12/25 tanshin: dividend record (interim 6.00 / year-end 6.00);直接证据 / 支持证据 / 历史/同业比较(研究域26)|FY12/26 interim tanshin: interim dividend resolution (JPY 5.50);直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域25)|FY12/25 tanshin: cash flows, buyback and treasury position;直接证据 / 外部现实(研究域20) / 历史/同业比较(研究域18) / 定向深挖(研究域20)|FY12/26 Q3 tanshin: September balance sheet and comprehensive income;直接证据 / 外部现实(研究域25) / 历史/同业比较(研究域24) / 定向深挖(研究域25)|IRBANK disclosure index: FY12/25 buyback and cancellation notices;直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 一手证据(研究域28) / 外部现实(研究域12) / 外部现实(研究域16) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|FY12/25 tanshin: underlying (jitsuryoku) ordinary-profit disclosure;直接证据 / 外部现实(研究域06) / 定向深挖(研究域06)|FY12/26 interim tanshin: underlying ordinary profit for H1 (JPY 4.5 billion);直接证据|FY12/26 Q3 tanshin: nine-month underlying ordinary profit (JPY 5.1 billion);直接证据 / 支持证据|FY December 2026 interim earnings report (tanshin), consolidated, Japanese GAAP;直接证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;直接证据 / 支持证据 / 一手证据(研究域32)|Notice on the valuation loss on affiliate shares and the equity-method investment loss;直接证据 / 历史/同业比较(研究域16) / 历史/同业比较(研究域32)|FY12/25 tanshin: income-statement bridge and non-operating items;直接证据 / 一手证据(研究域16) / 反证(研究域32)|FY12/26 interim tanshin: interim income statement detail;直接证据 / 一手证据(研究域32) / 外部现实(研究域32) / 反证(研究域16) / 反证(研究域21) / 反证(研究域29) / 反证(研究域33) / 定向深挖(研究域32)|Affiliate write-down notice: impairment mechanics and P&L routing;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 反证(研究域19)|FY12/26 interim tanshin: interim cash-flow statement;直接证据 / 支持证据 / 外部现实(研究域17) / 历史/同业比较(研究域17) / 定向深挖(研究域17)|FY12/25 tanshin: cash-flow statement quality check
完整研究记录(核对用)
研究原文:The dividend formula is where the underlying language binds cash|The dividend formula is the one place the underlying language is legally binding on cash: a JPY 17 forecast paid inside a reported-loss year, on a share count cut by 8.69%, is the mechanism by which the underlying story reaches holders before the reported story catches up.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Holders receive formula returns (4.53% forecast yield) while waiting; the return survives only if underlying profit and cash cover hold.
不确定性(原始记录):Year-end dividend resolution and any 10th-plan formula change are pending.
F084|01|三条腿都在两个季度内接受检验
研究范围:开放研究+35项覆盖检查
写入正文:01|三条腿都在两个季度内接受检验01|操作思路:持有观察,等两个节点落地再决定加码11|接下来两个季度的节点,各解开一层「两种利润语言」11|什么会推翻这个判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(27项,重复标签已合并)
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接证据;一手验证:06、12、14、16
Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary怎么使用:直接 / 支持;一手验证:04、11、30
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接 / 支持;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
FY December 2025 full-year earnings report (tanshin), consolidated怎么使用:直接 / 支持;一手验证:22;同业比较:12、14;其他用途:历史
Medium- and Long-Term Management Plan 2030: 2030 vision and investment plan (official English)怎么使用:直接证据;一手验证:04;外部现实校验:04、11;反向验证:20;专项深挖:04、11
9th medium-term plan: FY2027 target table and FY2023 base (official English)怎么使用:直接 / 支持;一手验证:11;同业比较:22;其他用途:历史
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:直接 / 支持;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
FY12/26 interim tanshin: demand commentary by segment怎么使用:直接证据;一手验证:03、05、08;外部现实校验:03、05、08;反向验证:09、11、15;专项深挖:03、05、08;同业比较:06;其他用途:历史
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接证据;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
IRBANK results headline history for 5563, FY12/2019 to FY12/2025怎么使用:直接 / 支持;一手验证:12、29、33;同业比较:28、35;其他用途:历史
FY12/26 interim tanshin: interim cash-flow statement怎么使用:直接证据;一手验证:17;反向验证:19
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
IRBANK disclosure index: the FY12/19 loss notices (30 January 2020)怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:29、33;反向验证:35;专项深挖:29、33;同业比较:08、10、11;其他用途:历史
IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)怎么使用:直接证据;外部现实校验:23;反向验证:23;专项深挖:23;同业比较:07、13;其他用途:历史
Notice on the change of representative director (president)怎么使用:直接 / 支持;一手验证:23、30
IRBANK stock page for 5563: price, valuation and credit-balance snapshot怎么使用:直接 / 支持;一手验证:27、31
IRBANK stock page for 5563: market capitalisation, yield and margin data怎么使用:直接 / 支持;一手验证:27;外部现实校验:27;反向验证:18、24、26;专项深挖:27;同业比较:31;其他用途:历史
IRBANK stock page for 5563: 6 November 2026 close and day move怎么使用:直接证据;一手验证:31;外部现实校验:31;反向验证:27、30;专项深挖:31
FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50)怎么使用:支持证据;一手验证:26;反向验证:25
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、19、20、21、29
FY12/25 tanshin: year-end balance sheet detail怎么使用:直接证据;外部现实校验:18;专项深挖:18;同业比较:19、20、21、29;其他用途:历史
President-change notice: successor profile and 10th plan timing怎么使用:直接 / 支持;一手验证:23
查看完整证据标签(核对用)
直接证据 / 支持证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域11) / 一手证据(研究域30)|Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary;直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table;直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 支持证据|FY12/26 Q3 tanshin: third-quarter standalone dynamics implied by cumulative figures;直接证据|FY12/26 Q3 tanshin: nine-month underlying ordinary profit (JPY 5.1 billion);直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14)|FY December 2025 full-year earnings report (tanshin), consolidated;直接证据 / 一手证据(研究域04) / 外部现实(研究域04) / 外部现实(研究域11) / 反证(研究域20) / 定向深挖(研究域04) / 定向深挖(研究域11)|Medium- and Long-Term Management Plan 2030: 2030 vision and investment plan (official English);直接证据 / 支持证据 / 一手证据(研究域11) / 历史/同业比较(研究域22)|9th medium-term plan: FY2027 target table and FY2023 base (official English);直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business;直接证据 / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域08) / 历史/同业比较(研究域06) / 反证(研究域09) / 反证(研究域11) / 反证(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05) / 定向深挖(研究域08)|FY12/26 interim tanshin: demand commentary by segment;直接证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域29) / 一手证据(研究域33) / 历史/同业比较(研究域28) / 历史/同业比较(研究域35)|IRBANK results headline history for 5563, FY12/2019 to FY12/2025;直接证据 / 一手证据(研究域17) / 反证(研究域19)|FY12/26 interim tanshin: interim cash-flow statement;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域29) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 反证(研究域35) / 定向深挖(研究域29) / 定向深挖(研究域33)|IRBANK disclosure index: the FY12/19 loss notices (30 January 2020);直接证据 / 外部现实(研究域23) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 反证(研究域23) / 定向深挖(研究域23)|IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域30)|Notice on the change of representative director (president);直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31)|IRBANK stock page for 5563: price, valuation and credit-balance snapshot;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域27) / 历史/同业比较(研究域31) / 反证(研究域18) / 反证(研究域24) / 反证(研究域26) / 定向深挖(研究域27)|IRBANK stock page for 5563: market capitalisation, yield and margin data;直接证据 / 一手证据(研究域31) / 外部现实(研究域31) / 反证(研究域27) / 反证(研究域30) / 定向深挖(研究域31)|IRBANK stock page for 5563: 6 November 2026 close and day move;支持证据 / 一手证据(研究域26) / 反证(研究域25)|FY12/26 interim tanshin: dividend forecast detail (interim 5.50 / year-end 11.50);直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 外部现实(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/25 tanshin: year-end balance sheet detail;直接证据 / 支持证据 / 一手证据(研究域23)|President-change notice: successor profile and 10th plan timing
完整研究记录(核对用)
研究原文:The race: dated delivery legs versus the finite safeguard premium|Three delivery legs (Q4 underlying delivery, plan continuity under the new president, zeroed affiliate) are tested within two quarters against a policy premium that has no disclosed design beyond 2026. Counter-evidence is retained as a contradiction rather than generic risk; valuation at about 0.67x book and 6.3x underlying prices the reported hole, so delivery re-rates it while failure re-prices toward the trough framework.
内部研究类型:thesis_architecture
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Binary-leaning payoff around the February 2027 print with book, yield and annuity cushioning the downside.
不确定性(原始记录):All three legs are unresolved at the cutoff.
F085|13|第四季度会不会交出27.46亿日元经常利润
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(25项,重复标签已合并)
FY12/26 Q3 tanshin: unchanged full-year forecast table怎么使用:直接证据;一手验证:35;外部现实校验:35;反向验证:14、28;专项深挖:35
Affiliate write-down notice: impairment mechanics and P&L routing怎么使用:直接证据;一手验证:32;外部现实校验:32;反向验证:16、21、29、33;专项深挖:32
Interim briefing record: overseas ferroalloy path and functional-materials headwinds怎么使用:直接证据;反向验证:03、04、05、10
FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions怎么使用:直接证据;一手验证:05、06、08、13、14
FY12/26 Q3 tanshin: market reference prices for the third quarter怎么使用:直接证据;一手验证:06、12、14、16
FY12/26 Q3 tanshin: third-quarter business commentary怎么使用:直接证据;外部现实校验:13、14;反向验证:06、08、12;专项深挖:13、14;同业比较:05;其他用途:历史
Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary怎么使用:直接证据;一手验证:04、11、30
9th medium-term plan: FY2027 target table and FY2023 base (official English)怎么使用:直接证据;一手验证:11;同业比较:22;其他用途:历史
Interim briefing record: FY12/27 expectations for the overseas business怎么使用:直接证据;一手验证:35;外部现实校验:30;反向验证:13、22;专项深挖:30
FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months怎么使用:直接证据;一手验证:02、15
FY12/26 Q3 tanshin: balance sheet at 30 September 2026怎么使用:直接证据;一手验证:18、19、20、21、29
FY12/26 interim tanshin: balance sheet at 30 June 2026怎么使用:直接证据;一手验证:18、20
FY12/26 Q3 tanshin: segment information note for the nine months怎么使用:直接证据;一手验证:15;外部现实校验:15;反向验证:02;专项深挖:15
Notice on the change of representative director (president)怎么使用:直接证据;一手验证:23、30
IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings怎么使用:直接证据;反向验证:01、07;同业比较:30;其他用途:历史
FY12/25 securities report: major shareholders table怎么使用:直接证据;一手验证:07、24;外部现实校验:01、24;专项深挖:01、24;同业比较:23;其他用途:历史
IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026)怎么使用:直接证据;外部现实校验:23;反向验证:23;专项深挖:23;同业比较:07、13;其他用途:历史
Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026怎么使用:直接证据;一手验证:34
IRBANK stock page for 5563: latest daily close, 6 November 2026怎么使用:直接证据;反向验证:31、34
FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans怎么使用:直接证据;一手验证:28
IRBANK stock page for 5563: price, valuation and credit-balance snapshot怎么使用:直接证据;一手验证:27、31
查看完整证据标签(核对用)
直接证据|FY December 2026 third-quarter earnings report (tanshin), consolidated;直接证据|FY12/26 Q3 tanshin: third-quarter standalone dynamics implied by cumulative figures;直接证据 / 一手证据(研究域35) / 外部现实(研究域35) / 反证(研究域14) / 反证(研究域28) / 定向深挖(研究域35)|FY12/26 Q3 tanshin: unchanged full-year forecast table;直接证据 / 一手证据(研究域32) / 外部现实(研究域32) / 反证(研究域16) / 反证(研究域21) / 反证(研究域29) / 反证(研究域33) / 定向深挖(研究域32)|Affiliate write-down notice: impairment mechanics and P&L routing;直接证据 / 反证(研究域03) / 反证(研究域04) / 反证(研究域05) / 反证(研究域10)|Interim briefing record: overseas ferroalloy path and functional-materials headwinds;直接证据|FY12/26 interim tanshin: subsequent events note;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域08) / 一手证据(研究域13) / 一手证据(研究域14)|FY12/26 interim tanshin: ferroalloy market reference prices and FX assumptions;直接证据 / 一手证据(研究域06) / 一手证据(研究域12) / 一手证据(研究域14) / 一手证据(研究域16)|FY12/26 Q3 tanshin: market reference prices for the third quarter;直接证据 / 外部现实(研究域13) / 外部现实(研究域14) / 历史/同业比较(研究域05) / 反证(研究域06) / 反证(研究域08) / 反证(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域14)|FY12/26 Q3 tanshin: third-quarter business commentary;直接证据 / 一手证据(研究域04) / 一手证据(研究域11) / 一手证据(研究域30)|Medium- and Long-Term Management Plan 2030 (9th plan, FY2024-2027): official English summary;直接证据 / 一手证据(研究域11) / 历史/同业比较(研究域22)|9th medium-term plan: FY2027 target table and FY2023 base (official English);直接证据 / 一手证据(研究域35) / 外部现实(研究域30) / 反证(研究域13) / 反证(研究域22) / 定向深挖(研究域30)|Interim briefing record: FY12/27 expectations for the overseas business;直接证据 / 一手证据(研究域02) / 一手证据(研究域15)|FY12/26 Q3 tanshin: segment sales and ordinary profit for the nine months;直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY12/26 Q3 tanshin: balance sheet at 30 September 2026;直接证据 / 一手证据(研究域18) / 一手证据(研究域20)|FY12/26 interim tanshin: balance sheet at 30 June 2026;直接证据 / 一手证据(研究域15) / 外部现实(研究域15) / 反证(研究域02) / 定向深挖(研究域15)|FY12/26 Q3 tanshin: segment information note for the nine months;直接证据 / 一手证据(研究域23) / 一手证据(研究域30)|Notice on the change of representative director (president);直接证据 / 历史/同业比较(研究域30) / 反证(研究域01) / 反证(研究域07)|IRBANK disclosure index for 5563: controlling-shareholder notices and governance filings;直接证据 / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域01) / 外部现实(研究域24) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域24)|FY12/25 securities report: major shareholders table;直接证据 / 外部现实(研究域23) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 反证(研究域23) / 定向深挖(研究域23)|IRBANK disclosure index: controlling-shareholder notices (March 2024/2025/2026);直接证据 / 一手证据(研究域34)|Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), January 2001 to October 2026;直接证据 / 反证(研究域31) / 反证(研究域34)|IRBANK stock page for 5563: latest daily close, 6 November 2026;直接证据 / 一手证据(研究域34)|Locally recomputed monthly bars for 2025-2026 from the assembled price history;直接证据 / 一手证据(研究域28)|FY12/26 interim results briefing transcript (Logmi Finance): underlying-profit bridge and segment plans;直接证据 / 一手证据(研究域27) / 一手证据(研究域31)|IRBANK stock page for 5563: price, valuation and credit-balance snapshot
完整研究记录(核对用)
研究原文:Research Debt carried into the next Review|Open questions each with materiality, opposite-answer consequence and resolving evidence; duplicated Research statements (10th plan, safeguard premium) are merged without losing either wording. Most resolve with the February 2027 annual release, the 10th plan and the March 2027 securities report; no reasonable current public path exists to resolve them earlier.
内部研究类型:research_debt_register
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):These determine whether the thesis legs hold; the first three carry the largest valuation consequences.
不确定性(原始记录):No reopen of Research is warranted: remaining questions depend on future disclosures after the cutoff.
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | 98a701479f050a09bbe8ec73a6e4ab2d805f4a1e |
| Delivery Commit SHA | 98a701479f050a09bbe8ec73a6e4ab2d805f4a1e |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | b6d3878a-72d3-5ff4-b4ae-3ebd424bd6fa |
| Canonical Revision | 1 |