资产下限比盈利更扎实:股价只有每股净资产的0.42倍,2020至2025年六个年度低点都守在900至1,004日元。合资的反垄断审批已经完成,时间表已定,执行风险缩窄到“合资之后能不能赚钱”。
5612
日本鋳鉄管株式会社(Nippon Chutetsukan K.K.)
日本鋳鉄管株式会社(NIPPON CHUTETSUKAN K.K.,东证 Standard 市场,代码 5612)主营水道、下水道和燃气用球墨铸铁管及管件,同时生产井盖和聚乙烯燃气管,销售阀门,承接管道工程并提供管网老化诊断服务。球墨铸铁相关业务占外部销售的87%左右,客户主要是各地的自来水、下水道和燃气公用事业。
最近亮点:2027年3月期(FY27/3)上半年(4–9月)扭亏:销售额83.64亿日元,增长5.6%;营业利润4.12亿日元,去年同期亏损1.10亿日元。公司却把全年指引原样保留,隐含下半年净利润只有0.17亿日元;11月6日股价下跌7.21%,收1,312日元。与最大对手科宝(Kubota)的制造合资计划于2027年1月4日生效,须先经12月17日的临时股东大会通过。
合资之后,占销售额70%左右的直管制造移入合资子公司日铸科技(Nichu Tech),它向两家母公司收取的代工价格、成本节约有多少归上市公司股东,目前没有披露,盈利提升无法定量。同时借款已升到103.99亿日元,下半年隐含利润极薄,利息和每股25日元分红都压在薄利润上。
结论:Kabugami 评分45.91(V3.2),评级 C。暂不主动加仓,列为重点跟踪;合资之后的成本节约尚无法定量,这是一份把握一般的判断。成交清淡,仓位按流动性控制。 依据:上半年扭亏来自调价和产品结构,公用事业订单仍然低迷;2026年3月期净资产收益率只有0.9%;估值已按低回报定价,资产下限比成长证据更可靠。 翻转条件:2028年3月期营业利润超过8.60亿日元、核心分部转盈且借款不再增加,则上调判断;分部继续亏损或借款继续攀升,则下调判断。 当前动作:暂不主动加仓,列为重点跟踪。公司不是资产出问题,而是用0.42倍净资产的价格在等合资后的成本节约兑现,兑现与否要到2027年4月的年度决算和2028年3月期指引才能看清。需要核对的节点:2026年12月17日的临时股东大会,2027年1月4日的分割生效,2027年1月底的第三季度公告,以及日铸科技对两家母公司的代工定价、分部披露、借款和分红政策。若2028年3月期营业利润超过8.6亿日元且分部转盈、借款不再增加,应上调判断;若仍在亏损或借款继续攀升,则应下调。成交量很小,仓位需按流动性控制。
报告目录
01|投资问题与当前结论
01.1|现价买的是合资之后的成本节约,这部分利润有多大目前无法测算
现价买的是合资之后的成本节约,而这部分利润的大小目前无法测算。2027年1月起,日本最小的球墨铸铁管厂要把占销售额70%左右的制造业务放进与最大对手科宝共用的工厂,股价只有每股净资产的0.42倍。问题在于,这次重组能不能把一个长期产能过剩的行业,变成这家公司自己的成本利润。
先看根基。需求二十年减了一半,行业产能过剩,2025年3月期(FY25/3)和2026年3月期(FY26/3)的营业利润率都低于2%。资产负债表却很厚:净资产99.56亿日元,其中留存收益64.84亿日元。净资产这么厚,净资产收益率只有0.9%,所以估值问题落在资本效率上,增长反在其次。
当前判断是一项有条件的主张。若日铸科技把开工率提高、单位成本降下来,而母公司保留的管件、井盖、树脂与燃气、服务业务利润率较稳,集团营业利润有机会持续高于2024年3月期(FY24/3)的8.60亿日元峰值,净资产收益率从0.9%向中个位数回升。市场此时才有理由把同一份净资产的倍数往上修:先是回报回升,然后才是估值修复。
失败的结局同样清楚。公司会是一家资产有支撑、杠杆偏高、回报偏低的小型股,在0.4倍净资产附近停留很久,而不是归零。这个判断受制于一个管理层掌握的未知:合资之后日铸科技向两家母公司收取的代工价格,以及成本节约有多少归上市公司股东,要到28/3 期的报告才可能披露。
01.2|上半年的扭亏靠价格和产品结构,销量没有回升
上半年的利润回升是真的,但它只在管理层能控制的维度上发生,在管理层不能控制的维度上没有发生。毛利率从15.0%升到20.3%,来自调价和产品结构;两期公告都说公用事业的订单仍然低迷。
这条主张因此带着一个具体的限定:只要需求疲软时已上调的价格守不住,利润就会重演25/3 期至26/3 期的回落,当时正是调价跟不上成本。成本侧的反面证据和更细的拆解见财务一章。
01.3|什么会推翻这个判断:28/3 期是第一个完整的验证年
验证点都设在可观察的产出上,并且有日期。若28/3 期合并营业利润超过8.60亿日元,核心的球墨铸铁分部转为盈利,借款也不再上升,说明合资把过剩产能转成了真正的成本利润,0.42倍市净率的定价就算错了。
反过来,若28/3 期指引重复今年的形态,即全年指引原样保留而隐含利润极薄,或者分割之后分部仍然亏损,合资就只是把行业的问题分摊给了两家,没有解决这家公司的问题,股票仍是押在土地、留存收益和每股25日元分红上的杠杆型资产股。其他推翻条件是:营业利润停在或低于合资前的正常化水平4亿至6亿日元;投资计划结束后借款仍高于104亿日元;月线收盘跌破1,001日元。最后一条只是价格上的观察点,不改变技术结构自身的判断。
时间顺序也要分清。2026年12月的股东大会和2027年1月4日的分割生效,只回答合资合不合法、结构成不成立;2027年4月下旬的年度决算和28/3 期指引,才是对上述条件的第一次实质检验。
02|公司本质与商业模式
02.1|日本最小的球墨铸铁管厂:东证 Standard 上市,工厂在埼玉县久喜
公司是日本三家球墨铸铁管厂中最小的一家,不是综合性的钢铁企业。日本鋳鉄管株式会社(NIPPON CHUTETSUKAN K.K.)创立于1937年10月15日,总部在东京筑地,工厂和注册地在埼玉县久喜市,股本18.55亿日元,已发行3,293,074股,总裁为石毛敏明(Toshiaki Ishige)。
股票于1962年7月上市,目前在东证 Standard 市场。2019年10月做过十合一并股,此后没有增发、拆股或回购计划的记录;库存股80,064股,占已发行股数的2.43%,上半年没有潜在稀释工具。
02.2|利润是价格与成本之间的时滞价差,直管和配套业务的经济性不同
公司的利润来自铁、能源、人工的成本和调价之间的时间差,而不是来自产品壁垒。业务包括水道、下水道和燃气用的球墨铸铁管及管件、FEM 铁盖和井盖、聚乙烯燃气管、阀门、管道工程和管网诊断,分两个分部报告:球墨铸铁相关分部占外部销售的87%左右,树脂管与燃气相关分部占其余部分。
分部内部的差别更重要。直管占销售额70%左右,是标准品,利润靠开工率和成本;管件、井盖、树脂与燃气、工程和诊断这一层相对有差异化。产品层面的收入和利润没有披露,上述判断来自分部数据的推断。
看公司要先看根基,再看变化。根基是:销量持平、价格可变的收入,应收和产成品占去大量资金、经营现金流很薄,资本配置上维持固定分红、用借款投资、不动用股本,修复能力来自资产和留存收益,回报却接近零。电炉、合资和上半年的利润回升,都是叠加在这个根基上的变化,替代不了它。
02.3|分割把直管制造移入合资子公司,合并范围不变,利润归属变了
2027年1月4日起,直管制造业务通过吸收分割转入日铸科技(Nichu Tech Co., Ltd.,日鋳テック株式会社),该业务占公司销售额的70%左右。日铸科技成立于2026年6月10日,位于久喜工厂内,设立时资本金0.30亿日元,计划2026年12月增至3亿日元。
分割属于共同控制下的交易,不产生转让损益。分割后公司持股80.1%,科宝持股19.9%,日铸科技仍是合并子公司,科宝的份额计入少数股东权益,该科目在2026年9月末为3.85亿日元。披露报道称董事会由母公司四人、科宝一人组成。
日铸科技将为母公司生产全部直管,并以代工方式为科宝生产小口径管的成品和半成品,两家集团各自保留销售团队、分开销售。所以经济上的变化出在经营和报表层面:上市公司自己的业务线赚多少,越来越取决于日铸科技的代工价格和开工率,而这两个变量尚未披露,日铸科技自身的业绩是否单独披露也没有承诺。
02.4|时间表已定,只比原计划晚一个月左右
2023年8月7日双方签基本协议,2025年3月27日签正式协议,当时设想的生效日是2026年12月1日前后。此后日铸科技在2026年6月10日成立,董事会在2026年10月5日通过分割协议和与科宝的股份转让备忘录,临时股东大会定于2026年12月17日,分割生效和科宝取得19.9%股权定于2027年1月4日,比原目标晚一个月左右。
以上均为计划日期,以股东大会通过为前提。剩下的步骤是程序性的、有日期的,执行风险已经从“合资会不会成”收窄到“合资能不能赚钱”。
02.5|分割之后,上市公司会变成另一种分析对象
合资生效后,上市公司自己的运营收缩到管件、井盖、树脂与燃气和服务这一层,这一层历史上是更稳的利润来源;占销售额70%的制造在一家与最大对手共有的子公司里。这是一项推断,但它意味着分部口径可能不再连续,今天的球墨铸铁分部和明年的同名分部未必可比。
最关键的未知也在这里:日铸科技会按什么盈利模式运行,包括对两家母公司的代工定价、利润率和分红政策;合资的成本节约有多少、从哪个财年起体现在上市公司的合并利润里;公司会不会在2027年1月之后披露日铸科技单独业绩,或者重述分部口径。这些现在都由管理层掌握。能解答它的证据是代工条款、关联交易附注和合资后的分部披露,最早要到2028年3月期的报告。在此之前,合资的利润贡献无法定量,信心上限也被它压住。
02.6|中期经营计划把业务延伸到管网维护的全周期,却没有数值目标
2025年7月公布的中期经营计划,目标是参与管网维护的全周期,而不只是造管和卖管。具体做法有四项。一是扩大减轻推进工法施工负担的“Ose-ru”部件销售。二是把预置式接合工具“Rakuchaku”推向新口径。三是推广在手机和平板上收集整理井盖数据的 DX 软件“Daisakukun”。四是通过与 Fracta 的合作推广 AI 管网诊断。
在已读到的材料中,这份计划没有销售额、营业利润、净资产收益率或资本政策的数值目标,所以它可衡量的内容只有27/3 期指引和合资时间表。目标可能存在于未读到的材料里,这一点在后文的待解问题中列出;若确实没有,这本身也是一条信息:资本效率这一问题,目前只能由市场的净资产折价来回答。
03|产品、客户与供应链
03.1|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
客户是各地自来水、下水道和燃气公用事业,需求稳定,但总量在收缩。水道普及率已超过98%,球墨铸铁管需求二十年间减了一半,在已读到的各期公告里,公用事业订单都被描述为全国低迷;2026年3月期前九个月销售额下降7.2%,全年下降5.9%,这是多年的市场状态,不是某一季的偶然。
新增需求不再来自铺设新管网,只剩老化管网的更新改造。公司的管网诊断、配套部件和软件,就是为了附着在更新周期上,但更新的节奏由各地财政预算决定,行业无法控制,更新潮的年度和地区节奏没有公布,客户名单和在手订单也没有披露。更新来得早,合并之后的产能才会被消化;来得晚,只是把过剩分摊得更便宜。
03.2|成本先涨、价格后调,电炉化把熔炼成本从焦炭转向电价
公司在输入成本上是结构性的空头:零部件、材料、能源和人工成本在26/3 期和27/3 期持续上涨,成本立刻进入销货成本,调价却分步、滞后,这段时滞就是利润率周期。管理层的应对是向售价转嫁和降本。
电炉改变了熔炼的能源结构,成本敏感度从焦炭和废钢市场部分转向电价,而这一变化的净影响,一个完整年度的业绩里还看不出来。大股东 JFE 钢铁处在铁源上游,但没有披露供货合同,供应商集中度也没有披露;另有104亿日元借款带来利率敞口。所以宏观因素对公司是利润率和利息的风险,需求崩塌不在其中。
04|竞争格局与产业关系
04.1|小口径直管份额只有15%,公司是三家里最小的一家
在小口径球墨铸铁管上,公司排第三。日本公正交易委员会(JFTC)披露的2023年份额是:科宝55%左右,另一家未具名的厂商30%左右,公司15%左右,约为全国市场的七分之一;公司收入规模最小,近年利润率最弱。
这里的问题在成本,不在份额流失:产能过剩的市场里,规模最小的制造商成本最高。其他材质的管道替代也压住了提价空间。竞争对手的成本地位和那家未具名的厂商,在已读到的材料中查不到。公司的位置资产有两项:稳定的股东结构,以及久喜工厂将成为共用平台、公司持有合资子公司80.1%。这比单独做第三名好,因为股东持有了行业重组的选择权。
04.2|需求腰斩和产能过剩是同一件事的两面,合资是对准两者的唯一手段
需求减半而行业产能没有减,造成长期的产能过剩和定价压力,这就是核心的球墨铸铁分部在2026年3月期前九个月、106.15亿日元的销售额上仍然略亏的原因。分部的亏损由市场结构决定,不能只归咎于执行。
合资是同时面向需求侧和供给侧的唯一工具:把70%左右的制造集中到一家工厂,与最大对手共摊固定成本,再靠更新需求吸收产能。成功意味着开工率提高带来真正的成本利润,失败意味着两家共用产能、把行业问题分摊开。检验它们的是合资后第一份分部业绩。科宝是否同步关闭自家工厂,与这次整合相匹配,目前没有记录。
需求侧的约束是结构性的:普及率超过98%,产能过剩,更新需求在已读到的任何一期都没有抬高公用事业订单,增长假设只能放在价格和份额上,销量增长是需要证据的主张。
04.3|最大对手成为制造伙伴:成本收益与反垄断脆弱性来自同一个安排
科宝控制小口径管市场55%左右,2027年1月4日起它将持有日铸科技19.9%的股份,同时是日铸科技的代工客户,销售上仍与公司竞争。这个安排把三家竞争的过剩市场变成了共同制造、分开销售,预期的成本节约和反垄断上的脆弱性都出自这里。
分工是明确的:日铸科技为公司生产全部口径、全部工序的直管;为科宝生产口径75至250毫米的小口径管成品和半成品,仅限特定工序,来自科宝京叶工厂的生产。两家各有销售部门、分开销售。JFTC 正是基于这一事实,认可两家之间仍有一定程度的竞争。这种分开销售只有在防火墙让竞争保持真实时才成立。合资协议的期限、退出和定价条款没有公开。
04.4|反垄断审批已经完成,但附带的条件是长期义务
2025年3月27日,公司与科宝签下正式协议,JFTC 同日结束审查,结论是在落实双方提出的补救措施前提下,交易不会实质性限制竞争。由于法定申报门槛未达到,审查是以咨询方式进行的。
补救措施不是一次性的:信息防火墙(限制接触和人员流动,防止竞争敏感信息经合资共享),以及经 JFTC 认可、在交易执行前选定的独立监督受托人。这些义务在合资存续期内持续,形成了共用工厂与分开销售之间的常设合规界面,受托人的身份没有公开。这既降低了协调漂移,也限制了定价协同的上行空间,应当当作永久条件来定价。JFTC 还依据绿色指南,认可了电炉改造带来的二氧化碳减排效率。
05|护城河判断
球墨铸铁管是标准品,产品层面的护城河很薄,这一点有公司自己的业绩作证:两年营业利润率低于2%。较厚的部分在系统层面:水道、下水道和燃气管网的规格资格,存量管网的更新需求,井盖、管件和管网诊断等配套业务,以及从2027年起对共用工厂的80.1%控股。
利润的真正来源也因此分布不均。树脂管与燃气分部九个月的分部利润率为8%左右,是相对有定价余地的一块;合资后的制造成本则取决于日铸科技的开工率。公司没有披露任何定价能力指标,代工条款又会重新划分合资的收益,所以判断只能到此为止。
把这一判断放进耐久性框架:耐久的是自1937年以来的公用事业供应商地位、规格资格、存量管网需要更新的事实,以及99.56亿日元净资产和64.84亿日元留存收益,它们在亏损年份撑住了固定分红,也没有稀释股权。不耐久的是在减半的市场里单独做直管的经济性。合资的目的,就是不再让耐久的这一层去补贴不耐久的那一层。每一环都能在有日期的节点观察:分部利润、借款和价格底部是验证点。
06|财务质量与现金流
06.1|五年的利润是一个利润率周期,销售额几乎没动
近五年的利润由利润率决定,销量没起作用。FY22/3至FY26/3的销售额分别为151.85亿、172.88亿、168.59亿、169.33亿和159.42亿日元。营业利润分别为3.83亿、5.21亿、8.60亿、2.60亿和2.58亿日元。每股收益分别为73.5、112.8、147.9、-71.7和28.4日元。FY25/3净亏损2.3亿日元左右,当年仍派息25日元。
26/3 期销售额下降5.9%,营业利润2.58亿日元,经常利润2.15亿日元,净利润0.91亿日元,净资产收益率0.9%,连续第二年营业利润率低于2%。成本持续上涨、售价分步上调、折旧随每轮投资上台阶,利润质量在一轮调价刚结束时最高,27/3 期上半年恰好处在这个位置。销量不变,经营杠杆会同时放大回升和下滑。
每提高1个百分点营业利润率,在160亿日元左右的销售额上,对应1.6亿日元营业利润,所以利润对价格时滞极敏感。8.60亿日元的峰值和谷底年都不该被年化:这个成本结构的正常化利润率更靠中间,而合资的增量暂时无法定量。
06.2|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
27/3 期上半年各项利润全部转正:销售额83.64亿日元(增长5.6%),营业利润4.12亿日元(上年同期亏损1.10亿日元),经常利润3.47亿日元,净利润1.93亿日元。销售额只增5.6%,利润却整体翻转,这是经营杠杆在起作用,不是需求回升。
干净的比较是毛利率。毛利润从11.86亿日元升到16.94亿日元,毛利率从15.0%升到20.3%:销售额多了4.46亿日元,毛利润多了5.08亿日元,说明调价和产品结构跑赢了成本上涨,同时上年同期的电炉试运行成本没有再出现。公司的公告也在说,材料、能源和人工成本仍在上升,这是反面证据。价格、结构与基数效应各占多少,没有量化。
上年上半年的基数既被抬高又被压低:它含有1.65亿日元的合资筹备和解金收益,却仍然亏损,因为同期有电炉试运行的一次性成本。这两项在本期都不再出现,所以表面的扭亏摆幅放大了经营的真实变化。
26/3 期前九个月,税前利润2.47亿日元就靠1.65亿日元的和解金收益和0.22亿日元的和解款项支撑,当期营业利润只有1.20亿日元;折旧由3.56亿日元升到5.77亿日元,新资产在合资规模到来之前已开始计入成本。本期上半年则有0.18亿日元的合资设备处置损失,列在经常利润线以下。
这些属于口径调整,不是诚信问题。
06.3|盈利质量在价格和结构上改善了,在销量上没有
盈利质量在管理层能控制的维度上改善了,在管理层不能控制的维度上没有。两期公告都说,公用事业的球墨铸铁管订单在全国范围内低迷,27/3 期上半年5.6%的销售增长来自调价、高附加值产品和集团企业订单的增加。
所以回升的持续性取决于:需求疲软时,已上调的价格能不能守住。25/3 期至26/3 期利润率的塌陷,正是调价跟不上成本时发生的,这是这家公司自己的前车之鉴。成本涨幅的压力至今没有解除,管理层的应对仍是转嫁和降本。收入应按“销量持平、价格可变”来估,改善是赚到的,但还没有证明持久。
06.4|二季度的营业利润是一季度的3.6倍,利润集中在一个季度
27/3 期一季度(4–6月)销售额37.58亿日元,营业利润0.90亿日元,净亏损0.32亿日元;二季度(7–9月)销售额46.06亿日元,营业利润3.22亿日元,营业利润率7.0%,净利润2.25亿日元。销售额多23%,营业利润是一季度的3.6倍左右。
这是固定成本型制造商在调价生效之后的经营杠杆,利润集中在二季度的公告里,没有平摊。在手订单没有披露,周期位置无法衡量,所以单季数字只是围绕结构性问题的时间噪音。
06.5|规模最大的分部亏损,规模小得多的分部在赚钱
分部经济和规模正好相反。26/3 期前九个月,占外部销售87%左右的球墨铸铁分部销售额106.15亿日元,分部亏损0.06亿日元;树脂管与燃气分部销售额15.49亿日元,分部利润1.23亿日元,利润率8%左右。
与上年同期比,球墨铸铁分部销售额减少8.11亿日元,业绩由盈利0.62亿日元转为亏损,摆幅0.68亿日元;树脂管与燃气分部则从1.65亿日元的分部利润小幅下降,仍是更稳的利润贡献者。小业务在补贴大业务。全年分部业绩只取得了九个月数据,全年和合资后的分部口径都没有拿到;分割把70%销售额移出以后,球墨铸铁分部报告的内容可能改变,前后可比性会断裂。
06.6|全年指引原样保留,隐含的下半年利润极薄
27/3 期全年指引在中期公告时原样保留:销售额167.00亿日元,营业利润6.20亿日元,经常利润4.80亿日元,净利润2.10亿日元,每股分红25日元。上半年已完成全年经常利润的72.3%和净利润的91.9%,扣除后,隐含的下半年是:销售额83.36亿日元,营业利润2.08亿日元,经常利润1.33亿日元(同比下降57.6%),净利润只有0.17亿日元。
这要么是与26/3 期利润记录一致的保守,要么是真实预期的走弱,两种解读的含义相反,要等第三季度公告才能区分。指引的信息含量现在几乎完全落在下半年能否不亏。
指引的历史也要放进来读。26/3 期的初始指引(2025年7月28日)一直保留到2026年1月30日,隐含销售额18.0亿日元以上、营业利润2.30亿日元、净利润为零;实际销售额159.42亿日元,低了11%左右,而营业利润2.58亿日元、净利润0.91亿日元反而超出。这是收入乐观、利润保守的记录,所以读指引要不对称:销售额要打折,利润要看底。销售额为何落空,没有查清。
06.7|26/3 期的投资花掉了经营现金流的十倍
26/3 期经营现金流约为+3.0亿日元,投资现金流-31.9亿日元,自由现金流约-29.8亿日元,靠+38.6亿日元的融资流入补上。电炉和合资投资年消耗的现金,是经营产生现金的十倍左右,分红也是靠资产负债表而不是自由现金流支付的。
27/3 期上半年的现金流量没有披露:中期公告没有现金流量表,所以半年内借款的增加无法与现金创造对上。这是披露形式上的缺口,不是不利证据,要到27/3 期年报的现金流量表才能查清;在这之前,利润回升是否转成现金,只能存疑。
06.8|应收和存货占去了资产的四成,产成品是要盯的指标
2026年9月末,应收票据及账款30.37亿日元,加上电子记录债权30.45亿日元,合计61亿日元,相当于上半年销售额的133天;存货46.57亿日元,其中产成品32.04亿日元,在制品7.53亿日元,原材料7.00亿日元。应收与存货合计107亿日元左右,占总资产267.43亿日元的四成。
对一家按库存生产、订单低迷的基础设施供应商来说,产成品偏重,是需求环境在资产负债表上的对应。需求回暖时这里是隐藏的现金来源,复苏落空时,产成品增加是第一个症状。应付款和完整的现金转换周期没有补齐,存货的所有权和变现能力也只看到账面价值,这些是这一判断的限度。
06.9|杠杆是盈利能力的问题,不是再融资的问题
2026年9月末,总资产267.43亿日元,归属母公司净资产99.56亿日元,自有资本比率37.2%(上年度末为38.6%)。借款103.99亿日元,现金36.24亿日元,净借款68亿日元左右,是净资产的0.68倍。这笔债务是为电炉和合资投资借的。
借款总额从26/3 期末的96.49亿日元增至103.99亿日元,结构却改变了。一年内到期的长期借款从21.69亿日元降到3.69亿日元,长期借款从26.30亿日元升到54.30亿日元。短期借款从48.50亿日元降到46.00亿日元,现金从38.81亿日元降到36.24亿日元。到期的压力在合资之前被拉长了,近期的偿债墙因此没有了。
但利息没有被拉长:26/3 期前九个月利息支出从0.28亿日元升到0.61亿日元,借款的举债成本变成了固定支出。借款契约和固定、浮动利率结构没有披露。此外,26/3 期自由现金流为负、靠借款弥补,这就是现在的借款的来源,下一步的偿债取决于合资后营业利润能否覆盖利息和分红。
06.10|电炉既是成本事件,也是监管资产,又是合资的共用平台
久喜工厂已完成从冲天炉到电炉的熔炼改造:2025年7月开始生产,2025年10月起实现100%电炉熔炼,目标是到2027年将产品二氧化碳排放比2013年度减半,并为合资投入27亿日元左右的久喜产能投资。
同一台电炉有三层含义。它是成本事件:试运行成本压低了26/3 期上半年的基数,折旧台阶式上升,能源基础也从焦炭转向电力;它是监管资产:JFTC 在审查中认可了它带来的减排效率;它是合资的共用生产平台。任何一层解读变化,另外两层都跟着变。
回报因此是二选一的:合资提高开工率,电炉成为被摊薄的资产;开工率上不去,它就是单一用途的闲置成本,加上被抬高的折旧。电炉的总成本和久喜投资中电炉、厂房、机械的划分没有披露。
07|股东、董事与治理
07.1|两家产业股东合计持有40%以上,个人投资者占近一半,机构几乎缺席
股东名册是两家产业股东加上一个以个人为主的流通盘。2026年3月末,JFE 钢铁持有29.88%、东京燃气(Tokyo Gas)持有10.37%(均为扣除库存股后的比例),合计40.25%。按持有者类别(FY25/3 数据),个人及其他占47.93%,金融机构只占1.86%,外国持股1.22%。
名册里没有活跃股东或大型机构持仓。交易也极薄:2026年10月(截至27日)月成交量只有9.4万股。控制权问题由两家产业股东的意图决定,而这些意图没有披露,二者的持股是否互持、名义持有人背后的实际持有者是谁,也都看不到。
07.2|JFE 钢铁处在上游,东京燃气处在下游,各自带来一种稳定性
JFE 钢铁是上游钢铁制造商,处在公司铁源的供应链里。它持股接近30%,对特别决议有实际的否决力,却不并表。双方没有披露供货合同,它的意图同样没有披露。
东京燃气是燃气公用事业,属于采购公司燃气产品的那一类客户,它的持股让一个下游客户的利益与股东名册对齐。商业条款没有披露。两家加起来,给股权结构带来的是稳定和产业视角,而不是资本政策上的压力。
07.3|没有机构约束资本政策:变化只可能由大股东和董事会发起
两家产业股东合计超过40%,机构只有1.86%,所以没有机构来约束资本政策。这是一项推断:固定分红和借款投资的合资计划,都是由大股东和董事会判断推进的,少数股东只能接受,并已把这一点折进0.42倍市净率。亏损年度仍派息、同时借款投资,正是这种治理结构允许的组合。
治理结构紧凑、传统:26/3 期三名内部董事的报酬合计4,500万日元左右,一名内部监事约1,500万日元,四名外部人员合计约900万日元,采用监事会结构,记录中没有股票报酬。外部董事的构成、政策持股情况,以及合资是否伴随资本政策检讨,在已读到的材料里没有。
07.4|股东结构、交易清淡与价格走势互相印证,但因果只是推断
两家产业股东(40%左右)加上近一半的个人持股,让公司能在没有市场压力的情况下推进以十年计的重组,同时让股票呈现“冲高”和“空洞下跌”的形态:2025年9月和2026年11月6日都是例子,因为流通盘薄、缺少机构。这是对股东结构和价格行为的一种联合推断,价格证据本身见技术结构一章。
对股东而言,控制权不可争夺、流动性偏薄是长期不变的输入,它们影响仓位大小,也影响估值倍数。股东结构与价格形态之间的因果关系,目前只能推断,不能证实。
08|资本政策
08.1|每股25日元是一条固定的现金线,不是和利润挂钩的公式
每股25日元合计8,000万日元,是一条固定的现金线。FY25/3净亏损仍派息25日元;26/3 期净利润0.91亿日元,派息率88.1%;27/3 期继续预计25日元,只在年末派,派息率38%左右(按指引每股收益65.36日元)。库存股80,064股(2.43%),记录中没有回购,也没有增发。
公司说明的基本方针是维持稳定分红,因为业务服务于水道、下水道和燃气等公共基础设施,并且在2026年4月27日的公告里表示,26/3 期净利润超出预期但仍然偏低,分红是出于中长期事业发展而保持。所以分红传递的是董事会的意图,而不是盈利。股息率1.91%,像一张债券票息,资金来自留存收益(64.84亿日元)的缓冲,它自己撑不起回报。
08.2|借款投资和固定分红是同一套资本政策,利息与分红要放在一起压力测试
董事会选择了同时做两件事:用借款把转型垫起来,同时把分红稳住。借款103.99亿日元撑起电炉和合资,26/3 期自由现金流约为负29.8亿日元,利息翻倍,而每股25日元在亏损年份仍从留存收益中支付。
结果是利息支出和8,000万日元的分红,要一起压在隐含下半年利润极薄的盈利上。这里没有回购也没有增发这类缓冲,每股价值只随盈利和估值倍数变化,调整只能通过利息覆盖,而不是发行股票。借款契约、利率结构,以及合资时代的分红政策,目前没有披露。
08.3|合资时代的分红和去杠杆政策还没有答案,第一个信号是2027年4月的分红决定
28/3 期起的分红与去杠杆政策尚未披露:借款在104亿日元左右的情况下,每股25日元会不会继续保持,是否在考虑派息率或净资产股息率之类的框架,都没有信息。
第一个信号是2027年4月年度决算时的分红决定。回升的利润最终去还债、去分红,还是两者都不去,是判断资本配置的关键,也直接影响股东回报是否有余地。
09|估值与安全边际
09.1|0.42倍市净率对应的是0.9%的净资产收益率,不是资产出了问题
2026年11月6日收盘价1,312日元,当日下跌102日元(7.21%),市值42.15亿日元左右。对照2026年9月末每股净资产3,098.84日元,市净率(PBR)为0.42倍;按27/3 期指引每股收益65.36日元,市盈率(PER)20.1倍,按26/3 期实际每股收益28.4日元则为46倍;股息率1.91%。这是在给低回报、有杠杆的小型股定价。
远期市盈率沿用了一份可信度打折的指引,没有分析师一致预期可对照。11月9日行情显示价格反弹到1,344日元(上涨2.44%),本文以11月6日收盘为准,不把它当作已确认的收盘价。
09.2|要清掉资本成本,合资必须跑过历史峰值,而不只是回到峰值
按净资产99.56亿日元计算,即使营业利润回到2024年3月期的峰值8.60亿日元,扣除借款利息之前,税前净资产收益率也低于9%。所以合资要超过历史峰值,才可能跨过合理的股权成本,回到峰值还不够。
这是推算出来的数字,不是披露的数字,投入资本回报率(ROIC)没有重建,公司也没有公布资本效率目标。折价由此有了清晰的修复路径:净资产收益率先回到中个位数,同一份净资产才有资格获得更高的倍数,这在盈利增长之前就会发生。
09.3|按正常化利润算,现价并不便宜,买的是合资的增量
合理的合资前正常化水平,是营业利润4亿至6亿日元、销售额160亿日元上下,对应营业利润率2.5%至3.5%;合资的成本节约是一项未量化的增量,要到28/3 期的报告才能估算。这是一项基于五年记录的研究估计。
粗算一下:市值42.15亿日元加上净借款68亿日元,合计110亿日元左右,对应4亿至6亿日元的营业利润,是18倍至27倍。账面净资产99.56亿日元,市价只有它的四成多,但净借款68亿日元要先扣除。因此现价的折扣并不意味着便宜,被定价的部分正是合资的增量。
09.4|资产下限能防住最坏情形,防不住长期平庸
土地账面值31.63亿日元(在有形固定资产94.41亿日元之内,按历史成本、没有评估),留存收益64.84亿日元,计入净资产的累计退休金调整13.54亿日元,规模大于近年任何一年的利润。它们构成了杠杆型低回报业务下面的资产下限,也降低了重组的紧迫性。
这里没有主张任何重估盈余。政策持股和土地评估值在已读到的材料中没有,退休金的精算余额还会随折现率变动。因此下行更像是一个十年左右停在0.4倍净资产的状态,而不是归零;防住灾难比防住平庸容易。
09.5|市场为“交付”付钱,不为“宣布”付钱
指引原样保留、隐含下半年利润极薄,是价格与倍数反推出的预期,只是推断。26/3 期的记录教会市场对销售额打折、对利润核底,因此一份进度72.3%的指引被卖出,而不是被追捧。远期市盈率20.1倍背后,是这份指引的可信度问题,下半年能否不亏决定了这个倍数是否站得住。
流动性是估值的一部分:个人为主的流通盘、两家产业股东占40%以上、成交极薄,让倍数里包含了持续的流动性折价,这是常设输入,不会因为一次业绩改善而消失。
合资的成败决定折价会修复还是长期保留:成功,则成本利润让0.42倍的定价被算错;失败,则公司仍是押在土地、留存收益和25日元分红上的杠杆资产股。两条路中,现价还没有给合资成功支付溢价,也没有给出足够的盈利安全垫。
10|Kabugami 技术结构
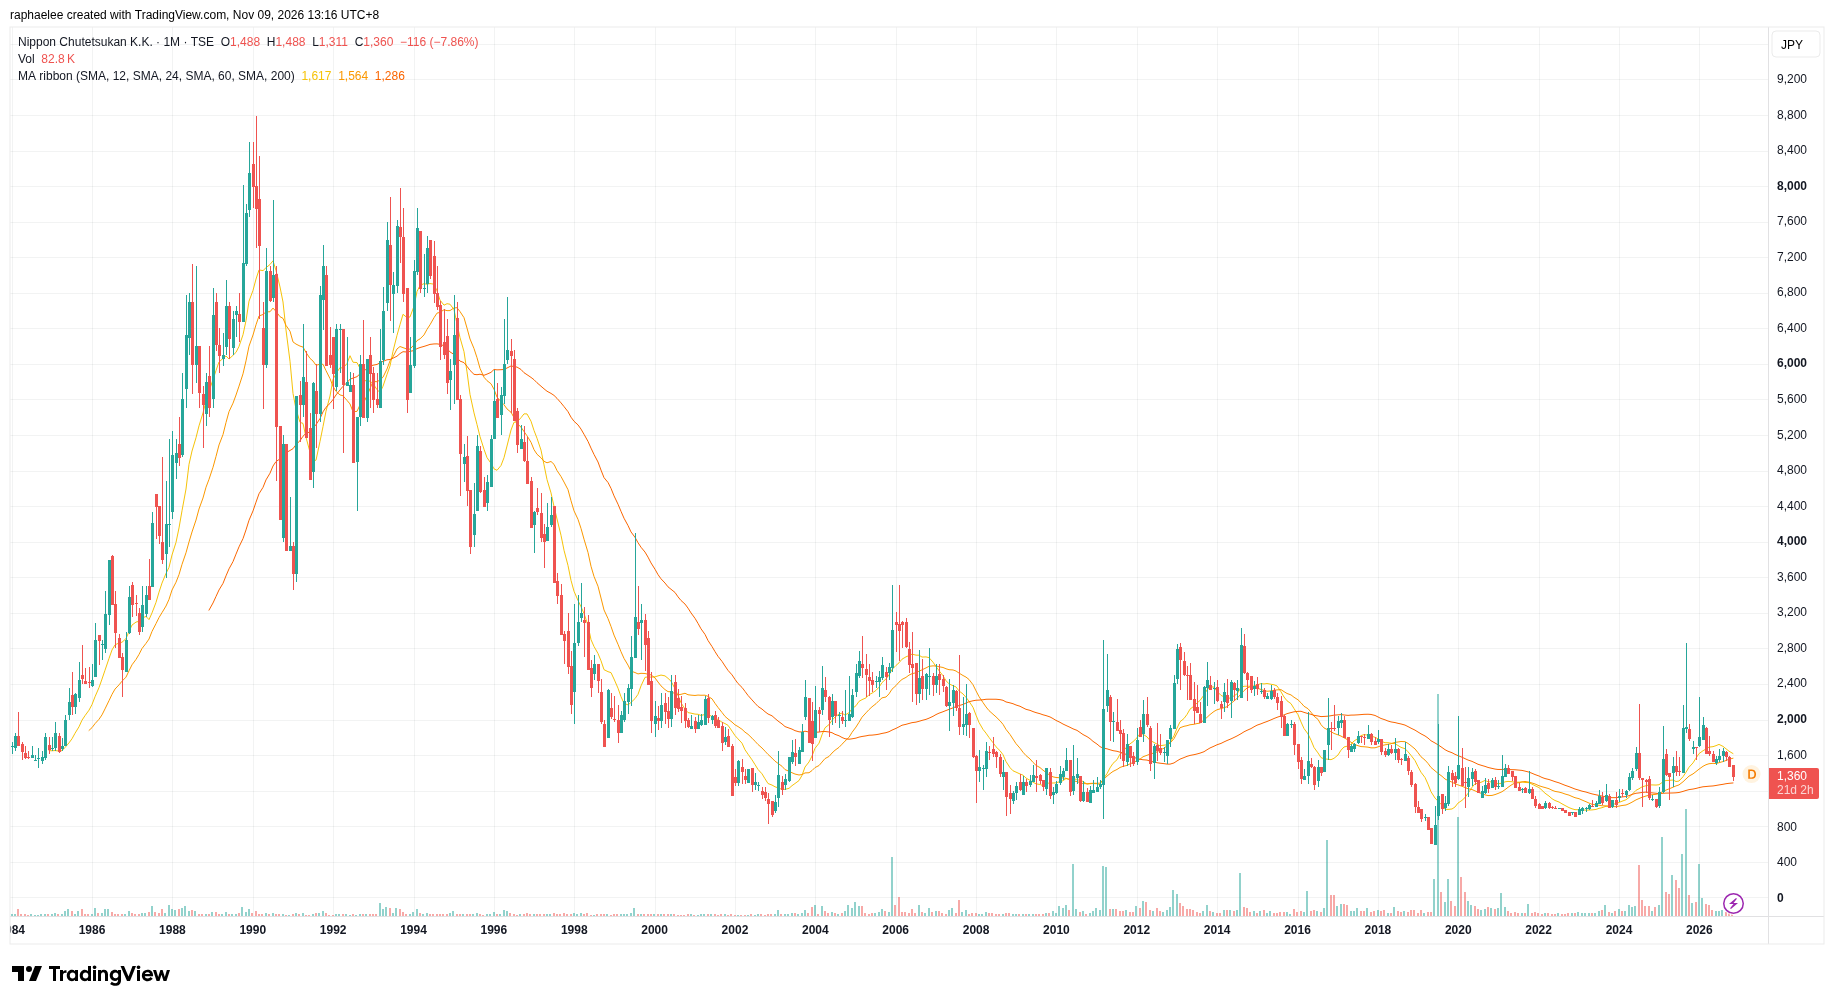
10.1|长期来看,价格大半时间停在1,000至2,000日元,2005年高点之后跌了十三年
这一章要回答的技术问题是:2020至2025年六年的底部,是否就是吸收2025年冲高的真实结构,还是2025年只是一次失败的冲高,会重新通向2019年的低点。
价格历史先给出一个主要运行区间。2001年1月至2026年10月共310根月线(6,430根日线,日线数据至2026年10月27日;2019年10月的十合一并股在序列中没有断档,长周期价位均为现行股本口径),收盘价有69.0%落在1,000至2,000日元,低于1,000日元的月收盘只有13根。
分布是:700日元以下1根,700至1,000日元12根,1,000至1,500日元123根,1,500至2,000日元91根,2,000至2,500日元64根,2,500至3,000日元15根,3,000日元及以上4根。两端都是短暂偏离。
路径分五段。2001至2005年一路上行,2005年12月月线最高3,510日元(2006年2月再次触及),是整个样本的最高点。2006至2019年连续十三年下跌,2019年6月月线最低601日元见底。2019至2023年筑底,2019年的低点此后没有被再次触及。2024年至2025年9月,底部抬到1,001日元之上,随后出现冲高。2025年10月至今,是冲高被打回、价格回落到底部上方的阶段。
10.2|六年筑底:2020至2025年的年度低点始终守在900至1,004日元
2019年之后的年度数据(最高/最低/年末收盘,单位日元):2019年1,950/601/1,292;2020年2,037/1,004/1,254;2021年1,606/1,001/1,039;2022年1,083/900/920;2023年1,274/933/1,048;2024年2,177/1,001/1,028;2025年2,858/1,001/1,678;2026年至10月2,249/1,470/1,489。2020至2025年六个年度低点依次是1,004、1,001、900、933、1,001、1,001,其中2024年12月和2025年1月两根月线的最低价都正好是1,001日元。
连续六年,价格每次跌到900至1,004日元一带就被重新买回,底部从2019年的601日元抬到了这个区间。这轮行情真正保留下来的部分是这条底部,不是冲到2,858日元的那一次。长期形态是一条下降通道被六年的水平底部截断,上升的只有底部延续的时间,不是趋势:年度收盘价自2025年的1,678日元之后没有再抬高,2026年10月收盘1,489日元,举证责任落在修复一侧。
价格记住了两个价位带:900至1,004日元的底部,以及2025年9月冲高形成的2,249至2,858日元,那里是被打回的冲高留下的上方筹码。
10.3|2025年9月放量冲高,当月即被打回,一月回踩失败后缩量下滑
2025年9月月线最高2,858日元,成交量4,428,000股,约为2023年月均成交量143,000股的三十倍,当月却收在1,915日元,留下很长的上影线,从最高价到收盘回落943日元,相当于高点的三分之一。此后没有一根月线收盘站稳2,000日元。
2026年1月再次向上回抽,最高2,249日元,成交量2,106,200股,收盘1,800日元,回抽失败。2月收盘1,939日元,之后在1,470至1,680日元的箱体内一路下滑,到10月收盘1,489日元;成交量逐月收缩,10月(截至27日)只有9.4万股,是整段里最薄的一个月。
回吐是两种速度:冲高当月快速吐出涨幅,之后十三个月从1,915日元缓慢滑向箱体下沿,价格的上涨短促,下跌漫长,这与十三年下跌、一个月冲高的历史是同一种不对称。缩量属于流动性衰退,在极低的成交量下,价格信号的可靠性本来就有限;不能把它读成有蓄势的压缩,也不主张出现了压缩形态。此外,没有计算均线以外的辅助指标和时间窗口结构,这里不作主张。
10.4|目前处在守底检验:价格贴着箱体下沿,三条均线给出上下两头的参照
这里把“冲高被打回之后,价格能否守住长期底部区间、不回到旧的下跌状态”的检验,简称守底检验。当前状态就是守底检验。
10月月线收盘1,489日元,低于12个月均线(1,645.17日元)和24个月均线(1,554.04日元),仍高于仍在上行的60个月均线(1,282.38日元,较六个月前上升2.6%)。10月收盘位于2001年以来价格范围(601至3,510日元)的30.5%处,处在2026年箱体的下沿。
11月6日日线收盘1,312日元,下跌102日元(7.21%),已低于箱体下沿1,470日元,位于价格范围的24.4%,比2005年的窗口高点低62.6%,比2025年9月的高点2,858日元低54.1%。按10月末的均线值算,它只高出60个月均线2.3%。11月月线尚未走完,不作为已确认的月收盘使用;最近一个完整交易日是11月6日。
参照位分布在上下两头。上方的压力位是12个月均线1,645日元和箱体上沿1,680日元,再往上是1月回抽高点2,249日元;下方的支撑位是60个月均线1,282日元一带和1,001日元的底部台阶。有两件事同时成立:六年的底部是实证,冲高被打回以及此后十三个月没能站稳更高价位也是实证。所以结构上的矛盾是:底部守住了,更高的状态没站住。
旧的下跌状态已经被六年底部明显削弱,但新的、更高的状态没有建立。当前价格状态是:冲高之后的守底检验,位于低于12个月和24个月均线、高于上行60个月均线、贴着2026年箱体下沿、仍在1,000至2,000日元这一长期主要运行区间之内。
10.5|守底检验靠什么确认,什么会让它失败
确认需要三种价格行为。其一,月线收盘重新站上12个月均线(1,645.17日元)和箱体上沿1,680日元,说明检验在这个长期区间内通过。其二,2026年的年度低点不低于2025年的1,001日元,第七年守住底部。其三,月线收盘守在60个月均线(1,282.38日元)之上,穿过2026年12月的股东大会和2027年1月的分割生效,表明价格反映的是结构而不是公告。
失败的条件同样是价格行为。月线收盘跌破60个月均线一带(1,282日元左右),检验失败,底部台阶成为下一道考验;月线收盘跌破1,001日元,六年的筑底作废,结构向2024年之前的区间重新打开;月线收盘跌破900日元,即底部时代最低的年度低点(2022年),同时合资后的首份分部业绩仍然亏损,则2024至2026年这一段会被重新归类为在继续下跌之上的一次失败冲高。
2025年9月的冲高暂时被归为失败,因为它一个月都没有守住2,000日元;但这个失败尚未传导到底部结构,那需要月线收盘跌破60个月均线再跌破1,001日元,两者都没有发生。2025年9月高点背后的催化因素没有核实,成交极薄意味着单一价位的信号可信度有限。技术判断的把握一般。
10.6|价格领先于业绩:两次大波动都早于基本面确认
价格结构先成形,之后才对照公开的基本面。2025年9月的冲高发生在2025年3月正式协议签署的六个月之后,当时分割所需的文件还不存在;2026年的合约节点(公司成立、分割协议)都没有带来可比的价格反应;2026年10月的业绩则带来下跌。市场在宣布时一度为故事付了钱,之后只为交付付钱。
具体到数字:2025年9月的冲高,比扭亏的确认早了一年左右(2026年10月的中报);11月6日业绩公布后的第一个交易日下跌7.21%,收1,312日元,尽管上半年已经扭亏,原因更可能是原样保留的指引所隐含的薄下半年,要求市场为尚未发生的交付定价。这是一项推断,把握在研究范围内仅作推断使用,它描述的是公开基本面与价格反应的时间关系,不改写上面已经形成的纯价格状态。11月9日行情显示反弹到1,344日元,未作为已确认收盘使用。
下一个时序问题是:2027年1月和4月的公告,会不会把价格与交付记录重新对齐,还是价格先滑到底部台阶。
10.7|股东结构与价格形态的联合推断
在纯价格结构之外,还有一项跨领域的推断:两家产业股东加上以个人为主的流通盘,让价格呈现出冲高和空洞下跌的形态,2025年9月和2026年11月6日都是例子。这只是联合推断,因果无法证实,也不改写技术状态。
11|风险与催化剂
11.1|下半年的风险由算术集中起来:隐含净利润只有0.17亿日元
下半年的风险被算术集中了。指引隐含下半年净利润0.17亿日元,业务订单又季节性偏重下半年,而26/3 期的记录里,管理层把销售额高估了11%左右,还把指引原样带进了1月。下半年只要略为偏软,就足以打破全年的数字。
同一份记录也有相反的一面:利润侧一直偏保守,26/3 期的营业利润和净利润都超出了指引。所以这一风险是双向的,要等第三季度公告区分,也是下一轮重新定价最直接的驱动。
11.2|转型成本已经成为固定支出:利息翻倍,分红还要一起支付
26/3 期前九个月,利息支出从0.28亿日元增加到0.61亿日元,借款逼近104亿日元,而净资产99.6亿日元左右。借款103.99亿日元对现金36.24亿日元,加上26/3 期自由现金流约-29.8亿日元,意味着合资必须产生节约,因为债务已经在资产负债表上了。
若节约来得慢,仅利息这一项就会吃掉合资想创造的营业利润的相当大一部分,同时8,000万日元的分红也要从同一份薄利润里出。应当把利息和分红放在一起,对隐含的薄下半年做压力测试。利率结构没有披露。
11.3|反垄断条件是永久的经营约束,违规会动摇合资的合法性
防火墙和监督受托人存在的原因,是两家集团共用一个工厂却在销售上竞争。这些义务贯穿合资存续期,任何合规失误,或者监管者将来重新评估一个合计占小口径管市场70%的结构,打击的都是合资的合法性,而不只是它的经济性。同时,常设监督也限制了协同定价的上行空间。
概率判断是中低水平,受托人的身份和报告方式没有公开。
11.4|需求风险是结构性的:市场二十年减半,更新潮的节奏不由行业决定
需求风险缓慢而结构性:市场二十年减半,普及率超过98%,行业产能过剩,更新需求在已读到的任何一期都没有抬高公用事业订单。唯一的增长来源是老化管网的更新,节奏由市政预算决定,行业控制不了。增长假设因此只能放在价格和份额上,销量增长是需要证据的主张。
11.5|催化剂是有日期的程序性事件,前后顺序要分清
接下来的催化剂都有日期:2026年12月17日临时股东大会表决分割;2026年12月日铸科技增资到3亿日元;2027年1月4日分割生效和科宝取得19.9%股权。各步骤在数周内都能在披露中看到,各自解决一个不同的未知:合法性与结构。这些都以股东大会通过为前提。
真正的重新定价点在后面。27/3 期第三季度公告预计在2027年1月下旬,是分割生效后的首份;年度决算预计在2027年4月下旬,两个日期都按惯例日历推算,并非公司已公布。年度决算会显示隐含的薄下半年是保守还是预警,其中的28/3 期展望是合资后结构的首份指引,市场第一次可以为日铸科技的实际贡献定价,而不是为承诺定价。合资后会不会披露目标,也不确定。
在观察顺序上,12月和1月的事件只回答合法与结构,4月的指引与决算才是对推翻条件的第一次检验。
12|反常识发现
这份中报里有一个反直觉的数字:上半年每股收益60.25日元,已经完成全年指引每股收益65.36日元的九成以上,而指引原样不变,隐含下半年每股收益只有5.3日元左右。上半年完成了经常利润的72.3%、净利润的91.9%,11月6日股价却下跌7.21%。
市场看起来读的是下半年,不是上半年。在价格已经先行的情况下,这份中报没有带来上调,等于告诉市场:还没发生的交付要由买方自己承担。同一个模式在上行时也出现过,价格比业绩的确认早了一年。这是一项推断,只依据价格反应和公开数据,没有分析师预期可以对照;价格形态本身见技术结构一章。
另一面是,这家公司在利润上一直偏保守,所以下半年是不是真的薄,要等第三季度公告给出答案。结论是:现在的股价在为合资的证明定价,不在为合资的宣布定价;对持有者而言,合资成功时的收益不对称,合资延迟时没有容错。
13|下一次值得跟踪什么
13.1|最优先要查清的三件事:合资的利润怎么分、有没有数值目标、半年现金流是多少
这三项直接决定判断能不能定量,所以放在最前。
日铸科技会按什么盈利模式运行,合资的节约有多少会进入上市公司的合并利润?这是最大的变数:它要看对两家母公司的代工价格、利润率和分红政策,答案不同,判断的方向也不同,节约大部分留在上市公司,则合资的收益成立,大部分留在代工价格里分摊给科宝,则上市公司的股东只得到有限的好处。
能回答它的证据是代工条款、关联交易附注,以及2027年1月之后是否披露日铸科技的单独业绩或重述的分部口径;下一次研究应从28/3 期的报告开始。这件事同时压住了对盈利质量、竞争优势和估值的信心上限。
2025年7月的中期经营计划有没有数值目标(销售额、营业利润、净资产收益率、资本政策)?如果有,它们会成为检验净资产收益率和重估的锚;如果确实没有,这本身也是信息。证据在计划文件或综合报告里。
27/3 期上半年的经营、投资和融资现金流是多少?它检验利润回升是否转成了现金,以及借款是否仍在支付投资。中期公告没有现金流量表,这是披露形式上的缺口,不是不利证据;27/3 期年度现金流量表可以解决。
13.2|第二层问题:全年分部、电炉成本、指引失准的原因、合资时代的分红
26/3 期全年的分部业绩(球墨铸铁与树脂管及燃气)是多少?这已经取得九个月的数据(球墨铸铁亏损0.06亿日元,树脂管及燃气盈利1.23亿日元),但没有全年。它能确认分部经济倒挂在年末是否仍然成立,解答来自26/3 期有价证券报告的分部附注。
电炉工程的总成本是多少,久喜27亿日元左右的合资产能投资,在电炉、厂房和机械之间怎么划分,折旧曲线怎样?它决定合资必须摊薄的固定费用有多大,证据在27/3 期有价证券报告的固定资产明细。
26/3 期销售额为什么比还保留到第三季度公告的全年指引低了11%左右(隐含18.0亿日元以上),是哪项需求假设落空了,预测流程在27/3 期有没有变化?它决定对原样保留的27/3 期指引及其薄下半年能给多少信用,答案可能来自管理层说明或27/3 期年度公告。
合资时代的分红和去杠杆政策是什么:借款104亿日元左右时每股25日元是否保持,是否在考虑派息率或净资产股息率框架?第一个信号是2027年4月的年度分红决定。
13.3|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口
公司的治理全貌是什么:外部董事构成、政策持股,包括 JFE 钢铁和东京燃气的持股是否互持,以及合资是否伴随资本政策的检讨?它关系到有利于少数股东的资本政策能否从董事会内部产生,答案在公司治理报告和有价证券报告。
2025年8至9月的价格冲高由什么驱动(月线最高2,858日元,成交量约为正常水平的三十倍)?已读到的披露没有解释时间点,催化因素未核实,也可能无法从公开资料得知,买方身份无法恢复。它能区分故事脉冲与信息事件,不改变纯价格的技术判断。
另有一组次要的披露缺口,各自只限制一个具体判断的信心,不是负面证据。在手订单没有披露,周期位置无法衡量。借款契约与固定浮动利率结构没有披露,压力测试的精度受限。合资协议的详细条款和监督受托人身份没有公开,合资的长期性无法判断。研发投入与管网诊断业务收入、供应商集中度、更新潮的节奏、与 Fracta 的合作条款也没有披露,技术经济性只能存疑。不披露不等于不存在,解决路径是有价证券报告的附注和未来的公告。
这些问题合在一起,每一项都限制着一个具体判断的信心,直到有日期的披露出现;最先到来的是2027年4月下旬的年度决算与28/3 期指引,它同时是观察推翻条件的第一个节点。
14|Kabugami 评分卡
14.1|评分45.91,评级C:资产下限可靠,成长与回报的证据尚未出现
Kabugami 评分 V3.2 给出45.91分(满分100),评级 C。八个模块的得分合计与总分一致。这是一份把握一般的判断:资产的下限比较可靠,成长与回报的证据尚未出现。
建议:暂不主动加仓,列为重点跟踪。公司的问题不在资产,而在于用0.42倍净资产的价格等待合资后的成本节约兑现,兑现与否要到2027年4月的年度决算和28/3 期指引才能看清。
需要核对的节点包括:2026年12月17日的临时股东大会、2027年1月4日的分割生效、2027年1月下旬的第三季度公告,以及日铸科技对两家母公司的代工定价、分部披露、借款和分红政策。若28/3 期营业利润超过8.60亿日元且分部转盈、借款不再增加,应上调判断;若分部仍亏损或借款继续攀升,应下调。
成交量很小,仓位需按流动性控制。
最大的变数是合资之后日铸科技的代工价格和节约归属,这件事直接限制了盈利质量、竞争优势和估值三个模块的高分可信度。其余未知,如上半年现金流、借款契约、中期计划目标、全年分部业绩、分红政策,各自只限制对应的判断,属于信息缺口,不是负面证据。
14.2|八个模块:估值和盈利质量给分最多,治理和资本配置最低
财务韧性与下行防御,6.50/13:资产负债表不脆弱,但回旋余地被投资吃掉了一部分。净资产99.56亿日元,自有资本比率37.2%,借款103.99亿日元对现金36.24亿日元;一年内到期的长期借款降到3.69亿日元,偿债墙已拉长,可是26/3 期自由现金流约为-29.8亿日元,利息翻倍。
竞争优势与结构耐久性,5.88/14:产品层面没有定价能力,系统层面有规格资格、更新需求和配套业务。小口径管份额15%左右,排第三,利润率连续两年低于2%,护城河靠合资后的成本地位,而不是壁垒。
盈利质量、现金转化与资本效率,6.80/17:上半年毛利率升到20.3%,但来自价格和结构,订单未回升;净资产收益率0.9%,应收与存货占用大量资金,现金转化偏弱。
商业结构、产品、客户与关键依赖,5.28/11:客户可靠,需求长期偏弱;市场二十年减半,核心分部在九个月的106.15亿日元销售额上亏损,成本被动、调价滞后。
估值与安全边际,8.25/15:市净率0.42倍与0.9%的净资产收益率基本相称,土地和留存收益提供下限;按4亿至6亿日元的正常化营业利润,现价并不便宜,买的是合资的增量。
资本配置与股东回报,4.20/10:每股25日元的固定分红在借款投资的年份仍由留存收益支付,没有回购,没有框架;它像票息,不能独自承担回报。
治理、所有权与管理层,3.15/7:两家产业股东占40.25%,机构占1.86%,成交极薄;控制权不可争夺,少数股东是被动的接受者。
Kabugami 技术结构,5.85/13:2020至2025年六个年度低点守在900至1,004日元,旧下跌状态被明显削弱,但2025年9月的冲高被打回、价格贴着箱体下沿,更高的状态没有建立;检验仍在进行中。
14.3|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 6.5 | 2026年9月末总资产267.43亿日元,净资产99.56亿日元,自有资本比率37.2%;借款103.99亿日元,现金36.24亿日元,净借款约68亿日元,约为净资产的0.68倍。一年内到期的长期借款从21.69亿日元降到3.69亿日元,长期借款升至54.30亿日元,短期还款压力已经拉长。但这笔债务是为电炉和合资计划借的,2026年3月期自由现金流约为负29.8亿日元,靠融资流入约38.6亿日元补上;九个月利息支出由2800万日元升到6100万日元。土地账面31.63亿日元、留存收益64.84亿日元,足以防住最坏情形,却不能抵消盈利偏薄的问题。整体是资产负债表不脆弱、但回旋余地被投资吃掉了一部分。 |
| 竞争优势与结构耐久性 | 14 | 5.88 | 公司是日本三家球墨铸铁管厂中最小的一家,小口径管份额约15%,科宝(Kubota)约55%,另一家约30%;产品本身是标准品,近五年营业利润率多数年份不到3%,2025年和2026年3月期都在2%以下,说明产品层面没有明显的定价能力。更扎实的部分在系统层面:水道、下水道和燃气管网的规格资格、存量管网更新、井盖与管件及管网诊断等配套业务,以及2027年1月起对共用的久喜工厂拥有80.1%控股权。树脂管与燃气业务九个月分部利润率约8%,是相对有利润的一块。总体上是处在衰退行业里的弱势第三名,靠结构重组而不是靠壁垒保护利润。 |
| 盈利质量、现金转化与资本效率 | 17 | 6.8 | 2026年3月期销售额159.42亿日元,营业利润2.58亿日元,净利润0.91亿日元,每股收益28.4日元,净资产收益率仅0.9%。2027年3月期上半年转为盈利:销售额83.64亿日元(增5.6%),营业利润4.12亿日元,毛利率由15.0%升到20.3%,主要靠售价调整、产品结构和上年电炉试运行成本不再重现。但销量并未回升,两期公告都称自来水和下水道订单低迷,所以改善来自价格和结构,而不是需求。上年同期含1.65亿日元合资筹备和解金收益,折旧也由3.56亿日元升到5.77亿日元,增速数字容易失真。现金转化偏弱:2026年3月期经营现金流约3亿日元,应收约61亿日元,库存46.57亿日元,其中产成品32.04亿日元。 |
| 商业结构、产品、客户与关键依赖 | 11 | 5.28 | 业务是水道、下水道和燃气用的球墨铸铁管及管件,另有井盖、聚乙烯燃气管、阀门、管道工程和管网诊断,球墨铸铁相关约占外部销售的87%,其中直管约占销售额70%。客户是自治体和公用事业,需求稳定但规模收缩:市场二十年减半,普及率已超过98%,行业产能过剩,各期公告都说订单低迷。更新改造是唯一的增长来源,节奏由市政预算决定,不受行业控制。成本侧,原料、能源和人工持续上涨,调价滞后;电炉化把熔炼成本从焦炭和废钢转向电价。大股东JFE钢铁位于铁源上游,东京燃气属于燃气产品买方,两者的商业条款均未披露。整体是需求长期偏弱、客户可靠、成本被动的结构。 |
| 估值与安全边际 | 15 | 8.25 | 2026年11月6日收盘1,312日元,市值约42.15亿日元,约为每股净资产3,098.84日元的0.42倍;按2027年3月期公司指引每股收益65.36日元计约20.1倍,按2026年3月期实际约46倍;股息率约1.91%。0.42倍市净率与0.9%的净资产收益率基本匹配,说明市场定价的是低回报、有杠杆的小型股,而不是资产出了问题。账面有土地31.63亿日元和64.84亿日元留存收益作支撑,但土地为历史成本、没有评估,净借款约68亿日元也要先扣除。按4亿至6亿日元营业利润的正常化水平,现价并不便宜,买的主要是合资之后的增量。 |
| 资本配置与股东回报 | 10 | 4.2 | 2025年3月期净亏损约2.3亿日元仍派息每股25日元,2026年3月期派息率约88.1%,2027年3月期继续预计25日元(约8000万日元,派息率约38%),股息率约1.9%。库存股80,064股(约2.43%),记录中没有回购,也没有增发。公司同时借入约104亿日元用于电炉和合资计划,等于在借钱投资的年份仍用留存收益维持分红。这是对公共基础设施行业“稳定分红”的承诺,信息含量主要是董事会意图而不是盈利,也无法替代回报。 |
| 治理、所有权与管理层 | 7 | 3.15 | JFE钢铁持有29.88%、东京燃气持有10.37%(扣除库存股后的比例,2026年3月期末),合计约40.25%;金融机构仅占1.86%,个人及其他占47.93%(2025年3月期口径),2026年10月月成交仅约9.4万股。治理结构紧凑传统:三名内部董事报酬约4500万日元,采用监事体系,没有股票报酬。两家产业股东使控制权不可争夺,同时缺少机构投资者对资本政策的约束,资本政策的变化只可能由大股东和董事会发起。 |
| Kabugami 技术结构 | 13 | 5.85 | 截至2026年11月6日,价格结构处于高位冲击被拒绝之后的保留检验:2020至2025年六个年度低点都落在900至1,004日元,2025年9月单月最高2,858日元、收在1,915日元,成交量约为正常水平的三十倍,2026年1月反抽2,249日元失败,之后在1,470至1,680日元区间内缩量下行;10月收盘1,489日元,低于12个月和24个月均线,仍高于上行的60个月均线(约1,282日元);11月6日日线收盘1,312日元,已跌破区间下沿。2001年以来310个月线收盘中69.0%位于1,000至2,000日元。旧的下行状态已被六年底部明显削弱,但新的更高状态并没有建立,只能算旧状态减弱、新状态尚未确认。 |
总分: 45.91 / 100 评级: C 操作建议: 暂不主动加仓,列为重点跟踪。公司不是资产出问题,而是用0.42倍净资产的价格在等合资后的成本节约兑现,兑现与否要到2027年4月的年度决算和2028年3月期指引才能看清。需要核对的节点:2026年12月17日的临时股东大会,2027年1月4日的分割生效,2027年1月底的第三季度公告,以及日铸科技对两家母公司的代工定价、分部披露、借款和分红政策。若2028年3月期营业利润超过8.6亿日元且分部转盈、借款不再增加,应上调判断;若仍在亏损或借款继续攀升,则应下调。成交量很小,仓位需按流动性控制。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|来源以公司披露、监管文件和登记资料为主,数据截至2026年11月6日收盘
本报告的评审日期为2026年11月9日;价格判断截至2026年11月6日的日线收盘,月线结构的数据至2026年10月,日线数据至2026年10月27日,11月月线尚未走完。11月9日行情显示的1,344日元不作为已确认的收盘价使用。
主要来源首先是公司通过东证披露系统发布的资料。包括2027年3月期中期决算(2026年10月30日)和2026年3月期第三季度决算(2026年1月30日)。还有2026年3月期中期决算(2025年10月31日)、2025年3月27日的正式协议公告和2026年4月27日的分红决议公告。
其次是日本公正交易委员会2025年3月27日的审查结论、审查概要和审查图表。
再次是政府法人登记信息(gBizINFO,来源于 EDINET 的数据)。公司法定英文名 NIPPON CHUTETSUKAN K.K. 取自登记信息和公司股东通讯中的公司概况栏。公司官网的业务介绍也在来源之列。
辅助来源有:JINGI 汇编的有价证券报告数据(2026年11月7日取得,用于26/3 期全年业绩、五年记录和现金流);Kabutan 的业绩快报报道;EDINET DB 的董事、员工资料;Minkabu 和 Finnhub 的行情数据;以及雅虎财经图表数据经 Kabugami 镜像本地合成的月线与均线。
15.2|证据的限度:几项关键数字来自二手汇编,若干判断受未披露信息限制
26/3 期全年业绩、五年记录和全年现金流来自第三方对有价证券报告的汇编,没有逐项回到原报告核对;26/3 期的分部数据只有前九个月;27/3 期中期公告没有现金流量表。合资协议的详细条款、监督受托人身份、借款契约、利率结构、在手订单、研发投入、供应商集中度、政策持股和土地评估,在已读到的材料中均没有。没有找到分析师一致预期,预期是从价格和倍数反推的。
以上均是信息缺口,不是对公司不利的证据。技术部分的数据为日线合成的月线,成交量极薄,2025年9月高点背后的原因没有核实。
本报告仅供研究参考,不构成买卖建议。公司处在重组期,借款偏高、利润偏薄,股价波动和流动性风险较大;全部依据为公开资料。
主要资料来源
- Corporate registry profile - identity and legal English name
- FY3/27 interim earnings release - listing and share count
- Company web profile - business description
- FY3/26 third-quarter release - reportable segments
- Officers and employees - EDINET-compiled data
- Definitive agreement - company split and manufacturing joint venture with Kubota
- JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary
- JFTC review summary - market definition, shares and remedies
- JFTC review chart - OEM scope of the joint venture
- FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion
- FY3/26 full-year results compiled from the securities report
- Quarterly path of FY3/27 - Q1 and Q2 standalone results
- Monthly price history - span and extremes (local assembly from mirror data)
- Dividend decision arithmetic - JPY 25 at an 88.1% payout
- Market snapshot - price, 6 November 2026 close and derived multiples
研究发现索引
展开本次 Review 的 96 项研究发现
F001|Nippon Chutetsukan Co., Ltd. (日本鋳鉄管株式会社; company's own English form 'NIPPON CHUTETSUKAN K.K.') is a TSE Standard-listed ductile iron pipe maker founded 15 October 1937, with head office in Tsukiji, Tokyo, works in Kuki City, Saitama, stated capital JPY 1,855 million, 3,293,074 shares issued, Toshiaki Ishige as president. It is the smallest of Japan's three ductile pipe makers, not a diversified steel company.
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论02|日本最小的球墨铸铁管厂:东证 Standard 上市,工厂在埼玉县久喜15|来源以公司披露、监管文件和登记资料为主,数据截至2026年11月6日收盘
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Corporate registry profile - identity and legal English name怎么使用:直接 / 支持;一手验证:01、23、33
FY3/27 interim earnings release - listing and share count怎么使用:直接 / 支持;一手验证:01、25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域33)|Corporate registry profile - identity and legal English name;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域25)|FY3/27 interim earnings release - listing and share count
完整研究记录(核对用)
研究原文:Nippon Chutetsukan Co., Ltd. (日本鋳鉄管株式会社; company's own English form 'NIPPON CHUTETSUKAN K.K.') is a TSE Standard-listed ductile iron pipe maker founded 15 October 1937, with head office in Tsukiji, Tokyo, works in Kuki City, Saitama, stated capital JPY 1,855 million, 3,293,074 shares issued, Toshiaki Ishige as president. It is the smallest of Japan's three ductile pipe makers, not a diversified steel company.
内部研究类型:company_identity
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Fixes the investable perimeter: a sub-scale, single-country infrastructure manufacturer whose register is anchored by two industrial holders.
不确定性(原始记录):Low; identity fully documented in registry and filings.
F002|02|利润是价格与成本之间的时滞价差,直管和配套业务的经济性不同
研究范围:开放研究
写入正文:02|利润是价格与成本之间的时滞价差,直管和配套业务的经济性不同03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Company web profile - business description怎么使用:直接 / 支持;一手验证:02、03、10
FY3/26 third-quarter release - reportable segments怎么使用:直接 / 支持;一手验证:03、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域10)|Company web profile - business description;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域10)|FY3/26 third-quarter release - reportable segments
完整研究记录(核对用)
研究原文:The business is ductile iron pipe and fittings for water, sewerage and gas, FEM and manhole covers, polyethylene gas pipe, valves, piping works and pipeline diagnosis, reported in two segments: ductile cast-iron-related (~87% of external sales) and resin pipe and gas-related.
内部研究类型:business_model_scope
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Profit is a manufacturing spread over iron, energy and labour recovered through lagged price revisions; commodity straight pipe (~70% of sales) differs sharply in economics from the attached fittings/covers/services layer.
不确定性(原始记录):Product-level revenue and profit are not disclosed; inferred from segment data.
F003|07|两家产业股东合计持有40%以上,个人投资者占近一半,机构几乎缺席
研究范围:开放研究+35项覆盖检查
写入正文:07|两家产业股东合计持有40%以上,个人投资者占近一半,机构几乎缺席09|市场为“交付”付钱,不为“宣布”付钱14|八个模块:估值和盈利质量给分最多,治理和资本配置最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Securities report data - major shareholders at FY3/26 year-end怎么使用:直接 / 支持;一手验证:09、24;反向验证:01
Securities report data - ownership by holder category怎么使用:直接 / 支持;一手验证:24
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接证据;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域24) / 反证(研究域01)|Securities report data - major shareholders at FY3/26 year-end;直接证据 / 支持证据 / 一手证据(研究域24)|Securities report data - ownership by holder category;直接证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas
完整研究记录(核对用)
研究原文:JFE Steel (29.88%) and Tokyo Gas (10.37%) of shares excluding treasury anchor the register at FY3/26 year-end (together ~40.25%), while individuals and others hold 47.93% of units and financial institutions only 1.86% (FY3/25 category data): a predominantly retail free float with almost no institutional middle, and thin trading (94,000 shares in October 2026).
内部研究类型:ownership_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Control is not contestable and liquidity is structurally thin - permanent inputs to sizing and to the multiple.
不确定性(原始记录):Whether the anchors' stakes are reciprocal/policy holdings and their intentions are undisclosed; nominee beneficial ownership not visible.
F004|07|没有机构约束资本政策:变化只可能由大股东和董事会发起
研究范围:开放研究+35项覆盖检查
写入正文:07|没有机构约束资本政策:变化只可能由大股东和董事会发起08|每股25日元是一条固定的现金线,不是和利润挂钩的公式
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接 / 支持;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
Securities report data - ownership by holder category怎么使用:直接 / 支持;一手验证:24
Officers and employees - EDINET-compiled data怎么使用:直接证据;一手验证:23;外部现实校验:23;专项深挖:23、24;同业比较:23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas;直接证据 / 支持证据 / 一手证据(研究域24)|Securities report data - ownership by holder category;直接证据 / 一手证据(研究域23) / 外部现实(研究域23) / 历史/同业比较(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域24)|Officers and employees - EDINET-compiled data
完整研究记录(核对用)
研究原文:Because the two anchors exceed 40% and institutions are almost absent, no institutional constituency disciplines capital policy: the flat dividend and the debt-funded venture proceed on anchor-and-board judgement, and minorities price that into the ~0.42x book multiple. Governance is compact and traditional (three internal directors ~JPY 45 million, statutory-auditor structure, no stock-based pay).
内部研究类型:governance_inference
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Capital-policy change (payout, buyback, deleveraging targets) would have to originate with the anchors; minorities are governance price-takers.
不确定性(原始记录):Inference; outside-director roster and policy shareholdings not in admitted sources.
F005|04|反垄断审批已经完成,但附带的条件是长期义务
研究范围:开放研究+35项覆盖检查
写入正文:04|反垄断审批已经完成,但附带的条件是长期义务15|来源以公司披露、监管文件和登记资料为主,数据截至2026年11月6日收盘
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Definitive agreement - company split and manufacturing joint venture with Kubota怎么使用:直接 / 支持;一手验证:07
JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary怎么使用:直接 / 支持;一手验证:13、33;反向验证:35;同业比较:04、07;其他用途:历史
JFTC review summary - market definition, shares and remedies怎么使用:直接 / 支持;一手验证:08、09、11、13
Definitive agreement - venture structure and original schedule怎么使用:直接证据;外部现实校验:07;反向验证:33;专项深挖:07、08;同业比较:13、30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07)|Definitive agreement - company split and manufacturing joint venture with Kubota;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域07) / 反证(研究域35)|JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13)|JFTC review summary - market definition, shares and remedies;直接证据 / 外部现实(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域08)|Definitive agreement - venture structure and original schedule
完整研究记录(核对用)
研究原文:On 27 March 2025 the company and Kubota signed the definitive agreement for a manufacturing JV (straight-pipe business split into a wholly-owned subsidiary, 19.9% then sold to Kubota) and the JFTC closed its review the same day, clearing it subject to an information firewall and a monitoring trustee; the plan originated in the 7 August 2023 basic agreement.
内部研究类型:transaction_fact
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Clearance de-risked legality but attached permanent operating conditions.
不确定性(原始记录):JV agreement detailed terms (term, exit, pricing) not public.
F006|02|时间表已定,只比原计划晚一个月左右
研究范围:开放研究+35项覆盖检查
写入正文:02|时间表已定,只比原计划晚一个月左右
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim release - subsequent events: Nichu Tech split agreement怎么使用:直接 / 支持;一手验证:07
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接 / 支持;一手验证:30
Definitive agreement - venture structure and original schedule怎么使用:直接证据;外部现实校验:07;反向验证:33;专项深挖:07、08;同业比较:13、30;其他用途:历史
Split agreement approved - EGM and January 2027 effectiveness怎么使用:直接证据;一手验证:35;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07)|FY3/27 interim release - subsequent events: Nichu Tech split agreement;直接证据 / 支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 外部现实(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域08)|Definitive agreement - venture structure and original schedule;直接证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness
完整研究记录(核对用)
研究原文:The venture timetable is fixed and near: Nichu Tech established 10 June 2026, split agreement approved 5 October 2026, EGM scheduled 17 December 2026, split effectiveness and Kubota's 19.9% acquisition on 4 January 2027 - about a month behind the original December 2026 target. Execution risk has narrowed from 'will it happen' to 'will it earn'.
内部研究类型:execution_status
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Remaining steps are procedural and dated; the slip of about a month is a small but visible delay the price already charges for.
不确定性(原始记录):Dates are planned and subject to EGM approval.
F007|02|分割把直管制造移入合资子公司,合并范围不变,利润归属变了
研究范围:开放研究+35项覆盖检查
写入正文:02|分割把直管制造移入合资子公司,合并范围不变,利润归属变了
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接 / 支持;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:直接 / 支持;一手验证:08
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;直接证据|Accounting consequence - common-control split and continued consolidation
完整研究记录(核对用)
研究原文:The split moves the straight-pipe manufacturing business (~70% of sales) into Nichu Tech as a common-control transaction with no transfer gain or loss; Nichu Tech will manufacture the parent's entire straight-pipe volume and Kubota's small-diameter finished and semi-finished products on an OEM basis while both groups sell separately. The parent holds 80.1% afterwards.
内部研究类型:transaction_mechanics
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Economic change is operational and presentational: OEM pricing and plant utilisation determine where the spread sits inside the group.
不确定性(原始记录):OEM pricing and post-split segment presentation undisclosed.
F008|06|电炉既是成本事件,也是监管资产,又是合资的共用平台
研究范围:开放研究+35项覆盖检查
写入正文:06|电炉既是成本事件,也是监管资产,又是合资的共用平台
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 third-quarter release - electric furnace conversion completed怎么使用:直接 / 支持;一手验证:04、06、20
FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion怎么使用:直接 / 支持;一手验证:20
Capacity investment of about JPY 2.7 billion at Kuki怎么使用:直接证据;外部现实校验:20;专项深挖:20
Electric furnace - timeline and CO2 target怎么使用:直接证据;外部现实校验:04、10;反向验证:06;专项深挖:04、06、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域06) / 一手证据(研究域20)|FY3/26 third-quarter release - electric furnace conversion completed;直接证据 / 支持证据 / 一手证据(研究域20)|FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion;直接证据 / 外部现实(研究域20) / 定向深挖(研究域20)|Capacity investment of about JPY 2.7 billion at Kuki;直接证据 / 外部现实(研究域04) / 外部现实(研究域10) / 反证(研究域06) / 定向深挖(研究域04) / 定向深挖(研究域06) / 定向深挖(研究域10)|Electric furnace - timeline and CO2 target
完整研究记录(核对用)
研究原文:Kuki completed cupola-to-electric-furnace conversion (production July 2025, 100% electric melting October 2025), targets halving product CO2 by FY2027 vs FY2013, and about JPY 2.7 billion of capacity investment at Kuki supports the venture. The furnace is simultaneously a cost event, a regulatory asset credited by the JFTC, and the shared production platform.
内部研究类型:capex_and_platform
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Return on the programme is binary: venture utilisation, or stranded single-purpose cost with stepped-up depreciation.
不确定性(原始记录):Total furnace cost and capex split undisclosed.
F009|02|中期经营计划把业务延伸到管网维护的全周期,却没有数值目标
研究范围:开放研究+35项覆盖检查
写入正文:02|中期经营计划把业务延伸到管网维护的全周期,却没有数值目标
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 interim release - mid-term management plan and lifecycle strategy怎么使用:直接 / 支持;一手验证:04;同业比较:03;其他用途:历史
Mid-term plan - lifecycle initiatives without published numerical targets怎么使用:直接证据;反向验证:04;专项深挖:04
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 历史/同业比较(研究域03)|FY3/26 interim release - mid-term management plan and lifecycle strategy;直接证据 / 反证(研究域04) / 定向深挖(研究域04)|Mid-term plan - lifecycle initiatives without published numerical targets
完整研究记录(核对用)
研究原文:The July 2025 mid-term plan aims at a business model spanning the whole pipeline-maintenance cycle (Ose-ru parts, Rakuchaku jointing tools, Daisakukun DX software, Fracta-AI diagnosis); no numerical targets appear in the materials read, so the plan's measurable content is the FY3/27 forecast and the venture timetable.
内部研究类型:strategy_without_targets
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Without ROE/profit targets the capital-efficiency question is answered only by the market's book discount.
不确定性(原始记录):Targets may exist in materials not read; carried as Research Debt.
F010|06|五年的利润是一个利润率周期,销售额几乎没动
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 full-year results compiled from the securities report怎么使用:直接 / 支持;一手验证:17、22;同业比较:18;其他用途:历史
Five-year consolidated record from securities reports怎么使用:直接 / 支持;一手验证:22、28;同业比较:09、10、27、34;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域22) / 历史/同业比较(研究域18)|FY3/26 full-year results compiled from the securities report;直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域27) / 历史/同业比较(研究域34)|Five-year consolidated record from securities reports
完整研究记录(核对用)
研究原文:FY3/26 closed weak: sales JPY 15,942 million (-5.9%), operating profit JPY 258 million, ordinary profit JPY 215 million, net profit JPY 91 million, EPS JPY 28.4, ROE 0.9% - the second consecutive year of sub-2% operating margin after FY3/24's JPY 860 million peak and FY3/25's net loss.
内部研究类型:financial_result
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The recovery is measured against a low, recently loss-making base.
不确定性(原始记录):Full-year FY3/26 segment split not obtained.
F011|06|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
研究范围:开放研究
写入正文:06|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim earnings release - headline results怎么使用:直接 / 支持;一手验证:15
Quarterly path of FY3/27 - Q1 and Q2 standalone results怎么使用:直接 / 支持;一手验证:12
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15)|FY3/27 interim earnings release - headline results;直接证据 / 支持证据 / 一手证据(研究域12)|Quarterly path of FY3/27 - Q1 and Q2 standalone results
完整研究记录(核对用)
研究原文:H1 FY3/27 swung to profit at every line: sales JPY 8,364 million (+5.6%), operating profit JPY 412 million (vs loss of JPY 110 million), ordinary profit JPY 347 million, net profit JPY 193 million; Q2 (operating profit JPY 322 million, 7.0% margin) was much stronger than Q1.
内部研究类型:financial_result
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):A genuine turn, but a profit swing on only 5.6% sales growth reveals operating leverage rather than demand recovery.
不确定性(原始记录):Interim release carries no cash-flow statement.
F012|06|杠杆是盈利能力的问题,不是再融资的问题
研究范围:开放研究+35项覆盖检查
写入正文:06|杠杆是盈利能力的问题,不是再融资的问题14|八个模块:估值和盈利质量给分最多,治理和资本配置最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:14、18、19、21、27、29
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接证据;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping
完整研究记录(核对用)
研究原文:At 30 September 2026 total assets were JPY 26,743 million, equity JPY 9,956 million (37.2% ratio), borrowings JPY 10,399 million against cash JPY 3,624 million - net borrowings about JPY 6.8 billion, ~0.68x equity - debt taken on for the furnace and venture programme.
内部研究类型:balance_sheet_state
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Leverage is a profitability question, not a refinancing question; equity holders are geared to the venture's success.
不确定性(原始记录):Covenants and rate structure (fixed vs floating) not disclosed.
F013|06|全年指引原样保留,隐含的下半年利润极薄
研究范围:开放研究+35项覆盖检查
写入正文:06|全年指引原样保留,隐含的下半年利润极薄09|市场为“交付”付钱,不为“宣布”付钱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim release - full-year forecast left unchanged怎么使用:直接 / 支持;一手验证:26
Implied second half under the unchanged FY3/27 forecast怎么使用:直接 / 支持;反向验证:22、26、28、30;专项深挖:28、31
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged;直接证据 / 支持证据|H1 FY3/27 results - progress against the unchanged full-year plan;直接证据 / 支持证据 / 反证(研究域22) / 反证(研究域26) / 反证(研究域28) / 反证(研究域30) / 定向深挖(研究域28) / 定向深挖(研究域31)|Implied second half under the unchanged FY3/27 forecast;直接证据|FY3/27 first-quarter release and the initial full-year forecast
完整研究记录(核对用)
研究原文:The FY3/27 forecast (sales JPY 16,700 million, operating profit JPY 620 million, ordinary profit JPY 480 million, net profit JPY 210 million, dividend JPY 25) was left unchanged despite H1 delivering 72.3% of ordinary profit and 91.9% of net profit, implying second-half sales JPY 8,336 million, operating profit JPY 208 million, ordinary profit JPY 133 million (-57.6% yoy) and net profit only JPY 17 million. Either conservatism consistent with the FY3/26 profit record or genuine expected weakness - the Q3 print separates the readings.
内部研究类型:guidance_arithmetic
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The forecast's information content now sits almost entirely in whether H2 avoids loss.
不确定性(原始记录):Management intent unknown; two readings have opposite implications.
F014|06|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
研究范围:开放研究+35项覆盖检查
写入正文:06|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim release - profit and loss detail怎么使用:直接 / 支持;一手验证:16;外部现实校验:15;反向验证:14;专项深挖:14、15、16
Prior-year one-offs - settlement gain and furnace trial costs怎么使用:直接 / 支持;一手验证:32;专项深挖:32;同业比较:16、32;其他用途:历史
FY3/27 interim release - qualitative drivers of the recovery怎么使用:直接证据;一手验证:05、06、14、15
Cost exposure - materials, energy and labour inflation怎么使用:外部现实校验:06、14;反向验证:10、16、35;专项深挖:06、10、14;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域15) / 反证(研究域14) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域16)|FY3/27 interim release - profit and loss detail;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Prior-year one-offs - settlement gain and furnace trial costs;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15)|FY3/27 interim release - qualitative drivers of the recovery;反证 / 外部现实(研究域06) / 外部现实(研究域14) / 反证(研究域10) / 反证(研究域16) / 反证(研究域35) / 定向深挖(研究域06) / 定向深挖(研究域10) / 定向深挖(研究域14)|Cost exposure - materials, energy and labour inflation
完整研究记录(核对用)
研究原文:H1 FY3/27 gross profit rose to JPY 1,694 million (20.3%) from JPY 1,186 million (15.0%), about JPY 508 million more gross profit on JPY 446 million more sales, because selling-price revisions and richer mix outran cost inflation and because the prior-year half's electric-furnace trial costs did not recur. The prior-year half also carried a JPY 165 million JV-preparation settlement gain yet still posted a loss.
内部研究类型:margin_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Gross margin is the clean series; headline growth rates around the transition are distorted by one-offs in both directions.
不确定性(原始记录):Counter-evidence on cost exposure (evidence 52): cost inflation persists; split between price, mix and base effect not quantified.
F015|01|上半年的扭亏靠价格和产品结构,销量没有回升
研究范围:开放研究+35项覆盖检查
写入正文:01|上半年的扭亏靠价格和产品结构,销量没有回升06|盈利质量在价格和结构上改善了,在销量上没有14|八个模块:估值和盈利质量给分最多,治理和资本配置最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim release - qualitative drivers of the recovery怎么使用:直接 / 支持;一手验证:05、06、14、15
FY3/27 interim earnings release - headline results怎么使用:直接 / 支持;一手验证:15
FY3/27 interim release - profit and loss detail怎么使用:直接 / 支持;一手验证:16;外部现实校验:15;反向验证:14;专项深挖:14、15、16
Demand environment - utility orders subdued nationwide怎么使用:直接 / 支持;外部现实校验:05;反向验证:11、12、19;专项深挖:05、11、12
Prior-year one-offs - settlement gain and furnace trial costs怎么使用:一手验证:32;专项深挖:32;同业比较:16、32;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15)|FY3/27 interim release - qualitative drivers of the recovery;直接证据 / 支持证据 / 一手证据(研究域15)|FY3/27 interim earnings release - headline results;直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域15) / 反证(研究域14) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域16)|FY3/27 interim release - profit and loss detail;直接证据 / 支持证据 / 外部现实(研究域05) / 反证(研究域11) / 反证(研究域12) / 反证(研究域19) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment - utility orders subdued nationwide;反证 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Prior-year one-offs - settlement gain and furnace trial costs
完整研究记录(核对用)
研究原文:Earnings quality improved along price and mix (controlled by management) but not along utility order volume (uncontrolled): both FY3/27 releases call orders subdued. Durability depends on holding revised prices in weak demand - the condition under which FY3/25-FY3/26 margins collapsed when revisions lagged costs.
内部研究类型:earnings_quality_judgement
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Revenue should be underwritten as flat-volume, price-variable; the recovery is earned, not yet proven durable.
不确定性(原始记录):Inference with confidence ~0.8; opposing evidence on cost inflation noted.
F016|01|现价买的是合资之后的成本节约,这部分利润有多大目前无法测算
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|现价买的是合资之后的成本节约,这部分利润有多大目前无法测算14|评分45.91,评级C:资产下限可靠,成长与回报的证据尚未出现
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接 / 支持;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:直接 / 支持;一手验证:08
FY3/27 interim release - full-year forecast left unchanged怎么使用:直接 / 支持;一手验证:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;直接证据 / 支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged
完整研究记录(核对用)
研究原文:The equity case is a restructuring claim with a dated proof point: if Nichu Tech lifts utilisation and cuts unit costs on ~70% of sales from January 2027 while the parent's retained layer keeps steadier margins, group operating profit can durably exceed the FY3/24 peak of JPY 860 million and ROE can rise from 0.9% toward mid-single digits, supporting a re-rating from ~0.42x book.
内部研究类型:investment_thesis
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Upside is a two-step: ROE recovery, then multiple repair on the same book; downside is a decade of discounted book, not a zero.
不确定性(原始记录):Confidence ~0.7; the venture's OEM pricing and savings rate are management-held unknowns until FY3/28 reporting.
F017|01|什么会推翻这个判断:28/3 期是第一个完整的验证年
研究范围:开放研究+35项覆盖检查
写入正文:01|什么会推翻这个判断:28/3 期是第一个完整的验证年13|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:直接 / 支持;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
Split agreement approved - EGM and January 2027 effectiveness怎么使用:直接 / 支持;一手验证:35;专项深挖:30
Catalyst calendar - EGM, split effectiveness and reporting dates怎么使用:直接 / 支持;一手验证:30;外部现实校验:30、35;专项深挖:30、35
Monthly price history - span and extremes (local assembly from mirror data)怎么使用:直接 / 支持;一手验证:34;同业比较:33;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness;直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Catalyst calendar - EGM, split effectiveness and reporting dates;直接证据 / 支持证据 / 一手证据(研究域34) / 历史/同业比较(研究域33)|Monthly price history - span and extremes (local assembly from mirror data)
完整研究记录(核对用)
研究原文:If in FY3/28 consolidated operating profit exceeds JPY 860 million with the ductile segment back in profit and borrowings no longer rising, the venture converted overcapacity into genuine cost earnings and the 0.42x-book pricing is wrong; if FY3/28 guidance repeats a thin implied-profit pattern under an unchanged forecast, or the segment stays loss-making after the split, the venture only socialised the industry's problem and the shares remain a leveraged asset play on land, retained earnings and a JPY 25 dividend. Further falsifiers: operating profit at or below the pre-venture normalised JPY 400-600 million, borrowings above JPY 10.4 billion after the programme ends, or a monthly close below JPY 1,001.
内部研究类型:falsification_conditions
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Falsifiers are set on observable outputs (segment profit, borrowings, guidance) with dates, not sentiment.
不确定性(原始记录):Technical falsifier references the price lane as an observable only; the pure Technical State is not altered by it.
F018|06|规模最大的分部亏损,规模小得多的分部在赚钱
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Segment results - nine months to December 2025怎么使用:直接 / 支持;一手验证:02;反向验证:03、15;专项深挖:02、03
FY3/26 third-quarter release - reportable segments怎么使用:直接证据;一手验证:03、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025;直接证据 / 支持证据|Segment comparatives - nine months to December 2024;直接证据 / 一手证据(研究域03) / 一手证据(研究域10)|FY3/26 third-quarter release - reportable segments
完整研究记录(核对用)
研究原文:Segment economics invert size: across 9M FY3/26 the ductile segment (~87% of external sales, JPY 10,615 million) lost JPY 6 million while resin pipe and gas earned JPY 123 million on JPY 1,549 million (~8% margin); the ductile result swung JPY 68 million into loss yoy on sales down about JPY 811 million. The small business subsidises the big one.
内部研究类型:segment_economics
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The restructured layer is currently loss-making; the retained layer is the steadier earner.
不确定性(原始记录):Only nine-month segment data obtained; full-year print and post-split presentation unknown.
F019|06|二季度的营业利润是一季度的3.6倍,利润集中在一个季度
研究范围:开放研究+35项覆盖检查
写入正文:06|二季度的营业利润是一季度的3.6倍,利润集中在一个季度
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Quarterly path arithmetic - Q1 loss to Q2 profit in FY3/27怎么使用:直接 / 支持;专项深挖:15
Quarterly path of FY3/27 - Q1 and Q2 standalone results怎么使用:直接 / 支持;一手验证:12
查看完整证据标签(核对用)
直接证据 / 支持证据 / 定向深挖(研究域15)|Quarterly path arithmetic - Q1 loss to Q2 profit in FY3/27;直接证据 / 支持证据 / 一手证据(研究域12)|Quarterly path of FY3/27 - Q1 and Q2 standalone results
完整研究记录(核对用)
研究原文:Q2 FY3/27 operating profit of JPY 322 million was about 3.6x Q1's JPY 90 million, and the quarterly net result swung from a JPY 32 million loss to a JPY 225 million profit on 23% more sales: delivery is concentrated in Q2, not spread evenly.
内部研究类型:earnings_path
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operating leverage on a fixed-cost base once price revisions take hold cuts both ways; quarterly prints are timing noise around the structural question.
不确定性(原始记录):Order backlog undisclosed, so cycle position cannot be measured.
F020|06|杠杆是盈利能力的问题,不是再融资的问题
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接 / 支持;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
FY3/26 cash flow compiled from the securities report怎么使用:直接 / 支持;一手验证:17;外部现实校验:17;反向验证:20、32;专项深挖:17、20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping;直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域17) / 反证(研究域20) / 反证(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域20)|FY3/26 cash flow compiled from the securities report
完整研究记录(核对用)
研究原文:Borrowings rose from JPY 9,649 million (FY3/26 year-end) to JPY 10,399 million at September 2026 while the current portion of long-term loans fell from JPY 2,169 million to JPY 369 million and long-term loans rose from JPY 2,630 million to JPY 5,430 million: maturities were termed out ahead of the split.
内部研究类型:leverage_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Removes the near-term maturity wall; leaves a profitability test.
不确定性(原始记录):Covenants and rate structure undisclosed.
F021|06|26/3 期的投资花掉了经营现金流的十倍
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/26 cash flow compiled from the securities report怎么使用:直接 / 支持;一手验证:17;外部现实校验:17;反向验证:20、32;专项深挖:17、20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域17) / 反证(研究域20) / 反证(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域20)|FY3/26 cash flow compiled from the securities report
完整研究记录(核对用)
研究原文:FY3/26 free cash flow was about -JPY 2,980 million (operating +JPY 300 million, investing -JPY 3,190 million), funded by financing inflows of +JPY 3,860 million: the furnace-and-venture year consumed roughly ten times the cash operations generated.
内部研究类型:cash_flow_fact
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The dividend is paid from the balance sheet, not free cash flow, in the investment trough.
不确定性(原始记录):H1 FY3/27 cash flows not disclosed in the interim release.
F022|06|五年的利润是一个利润率周期,销售额几乎没动
研究范围:开放研究+35项覆盖检查
写入正文:06|五年的利润是一个利润率周期,销售额几乎没动15|证据的限度:几项关键数字来自二手汇编,若干判断受未披露信息限制
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Five-year record - sales, operating profit and EPS怎么使用:直接 / 支持;一手验证:28;外部现实校验:22、28;专项深挖:22、28、33;同业比较:02、12、15、35;其他用途:历史
The FY3/24 peak and the two-year decline怎么使用:直接 / 支持;外部现实校验:33;专项深挖:22、33;同业比较:22、28、29;其他用途:历史
Five-year consolidated record from securities reports怎么使用:直接证据;一手验证:22、28;同业比较:09、10、27、34;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域22) / 外部现实(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域33)|Five-year record - sales, operating profit and EPS;直接证据 / 支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 定向深挖(研究域22) / 定向深挖(研究域33)|The FY3/24 peak and the two-year decline;直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域27) / 历史/同业比较(研究域34)|Five-year consolidated record from securities reports
完整研究记录(核对用)
研究原文:The five-year record is a margin cycle on flat sales (JPY 15.2-17.3 billion across FY3/22-FY3/26): operating profit 383/521/860/260/258 million, EPS 73.5/112.8/147.9/-71.7/28.4, a net loss of ~JPY 230 million in FY3/25. The demonstrated range is wide and its recent centre low.
内部研究类型:earnings_cycle
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The FY3/24 peak and the trough should not be annualised; mid-cycle margin is nearer 2-3.5%.
不确定性(原始记录):Venture increment to normalised power is unquantified.
F023|08|每股25日元是一条固定的现金线,不是和利润挂钩的公式
研究范围:开放研究+35项覆盖检查
写入正文:08|每股25日元是一条固定的现金线,不是和利润挂钩的公式14|八个模块:估值和盈利质量给分最多,治理和资本配置最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Dividend decision arithmetic - JPY 25 at an 88.1% payout怎么使用:直接 / 支持;外部现实校验:26;反向验证:25;专项深挖:25、26
Share history - the FY3/20 ten-for-one consolidation怎么使用:直接 / 支持;专项深挖:01;同业比较:01、21、24、25、26;其他用途:历史
Dividend decision for FY3/26 - stable-dividend policy怎么使用:直接证据;一手验证:26、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域26) / 反证(研究域25) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision arithmetic - JPY 25 at an 88.1% payout;直接证据 / 支持证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 定向深挖(研究域01)|Share history - the FY3/20 ten-for-one consolidation;直接证据 / 一手证据(研究域26) / 一手证据(研究域29)|Dividend decision for FY3/26 - stable-dividend policy
完整研究记录(核对用)
研究原文:JPY 25 per share (~JPY 80 million) was paid for FY3/25 through a net loss and for FY3/26 at an 88.1% payout, and is forecast again for FY3/27 (year-end only, ~38% payout); treasury shares stand at 80,064 (2.43%) with no buyback in the record. It is a fixed cash commitment under a stability policy for public-infrastructure businesses, whose information content is board intent, not earnings.
内部研究类型:shareholder_return_policy
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Yield ~1.9% is a bond-like coupon funded from retained earnings in thin years; cannot carry the return case alone.
不确定性(原始记录):Venture-era dividend policy from FY3/28 undisclosed.
F024|09|0.42倍市净率对应的是0.9%的净资产收益率,不是资产出了问题
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|0.42倍市净率对应的是0.9%的净资产收益率,不是资产出了问题14|评分45.91,评级C:资产下限可靠,成长与回报的证据尚未出现15|证据的限度:几项关键数字来自二手汇编,若干判断受未披露信息限制
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Market snapshot - price, 6 November 2026 close and derived multiples怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:27;反向验证:24;专项深挖:21、26、27、34
Book-value anchor - equity per share against the market price怎么使用:直接 / 支持;外部现实校验:21、29;反向验证:27;专项深挖:21、27、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域27) / 反证(研究域24) / 定向深挖(研究域21) / 定向深挖(研究域26) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market snapshot - price, 6 November 2026 close and derived multiples;直接证据 / 支持证据 / 外部现实(研究域21) / 外部现实(研究域29) / 反证(研究域27) / 定向深挖(研究域21) / 定向深挖(研究域27) / 定向深挖(研究域29)|Book-value anchor - equity per share against the market price
完整研究记录(核对用)
研究原文:At the 6 November 2026 close of JPY 1,312 the market value was about JPY 4,215 million: ~0.42x book value per share of JPY 3,098.84, ~20.1x FY3/27 forecast EPS of JPY 65.36 (~46x FY3/26 actual EPS), dividend yield ~1.91% - pricing of a low-return, leveraged micro-cap, not asset distress.
内部研究类型:valuation_state
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The discount prices ROE of 0.9%; re-rating requires mid-single-digit venture-era ROE.
不确定性(原始记录):Forecast PER inherits the forecast's credibility problem; no analyst consensus available.
F025|02|分割之后,上市公司会变成另一种分析对象
研究范围:开放研究+35项覆盖检查
写入正文:02|分割之后,上市公司会变成另一种分析对象06|规模最大的分部亏损,规模小得多的分部在赚钱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Split agreement approved - EGM and January 2027 effectiveness怎么使用:直接 / 支持;一手验证:35;专项深挖:30
Production base - the Kuki works and what stays with the parent怎么使用:直接 / 支持;外部现实校验:02、03;专项深挖:02、03
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness;直接证据 / 支持证据|Accounting consequence - common-control split and continued consolidation;直接证据 / 支持证据 / 外部现实(研究域02) / 外部现实(研究域03) / 定向深挖(研究域02) / 定向深挖(研究域03)|Production base - the Kuki works and what stays with the parent
完整研究记录(核对用)
研究原文:From January 2027 manufacturing of ~70% of sales sits in an 80.1%-owned subsidiary that also produces for the largest competitor, so consolidated profit increasingly depends on Nichu Tech's OEM pricing and utilisation - variables not yet disclosed - while the parent's own operations shrink to the fittings, covers, resin-and-gas and services layer, historically the steadier earner.
内部研究类型:structural_change_inference
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The listed company becomes a different business to analyse; comparability of segment reporting may break.
不确定性(原始记录):Inference; OEM pricing and presentation unspecified.
F026|11|下半年的风险由算术集中起来:隐含净利润只有0.17亿日元
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|下半年的风险由算术集中起来:隐含净利润只有0.17亿日元
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Implied second half under the unchanged FY3/27 forecast怎么使用:直接 / 支持;反向验证:22、26、28、30;专项深挖:28、31
Forecast-carry record - the FY3/26 initial forecast versus the outcome怎么使用:直接 / 支持;外部现实校验:32;反向验证:31;专项深挖:32、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域22) / 反证(研究域26) / 反证(研究域28) / 反证(研究域30) / 定向深挖(研究域28) / 定向深挖(研究域31)|Implied second half under the unchanged FY3/27 forecast;直接证据 / 支持证据 / 外部现实(研究域32) / 反证(研究域31) / 定向深挖(研究域32) / 定向深挖(研究域35)|Forecast-carry record - the FY3/26 initial forecast versus the outcome
完整研究记录(核对用)
研究原文:Second-half delivery risk is concentrated by arithmetic: implied H2 net profit is JPY 17 million, orders are seasonally second-half weighted, and FY3/26 shows revenue over-forecast by about 11% while the forecast was carried unchanged into January - a modest soft H2 would break the full-year print.
内部研究类型:risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Near-term print risk drives the next repricing step.
不确定性(原始记录):Profit conservatism in the same record cuts the other way.
F027|11|转型成本已经成为固定支出:利息翻倍,分红还要一起支付
研究范围:开放研究+35项覆盖检查
写入正文:11|转型成本已经成为固定支出:利息翻倍,分红还要一起支付
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Non-operating items - interest and fees rising with debt怎么使用:直接 / 支持;一手验证:32;反向验证:18、29;同业比较:14;其他用途:历史
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接 / 支持;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
FY3/26 cash flow compiled from the securities report怎么使用:直接证据;一手验证:17;外部现实校验:17;反向验证:20、32;专项深挖:17、20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域14) / 反证(研究域18) / 反证(研究域29)|Non-operating items - interest and fees rising with debt;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping;直接证据 / 一手证据(研究域17) / 外部现实(研究域17) / 反证(研究域20) / 反证(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域20)|FY3/26 cash flow compiled from the securities report
完整研究记录(核对用)
研究原文:The transition cost is now a fixed charge: interest expense rose from JPY 28 million to JPY 61 million in the nine-month comparison as borrowings climbed toward JPY 10.4 billion against equity of about JPY 10.0 billion; slow venture savings let the interest line absorb a meaningful share of the operating profit meant to be created. Borrowings of JPY 10,399 million versus cash JPY 3,624 million and FY3/26 FCF of about -JPY 2,980 million mean the venture must produce savings because its debt is already on the balance sheet.
内部研究类型:risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Interest and the JPY 80 million dividend must be stress-tested together against thin implied H2 earnings.
不确定性(原始记录):Rate structure unknown.
F028|04|反垄断审批已经完成,但附带的条件是长期义务
研究范围:开放研究+35项覆盖检查
写入正文:04|反垄断审批已经完成,但附带的条件是长期义务11|反垄断条件是永久的经营约束,违规会动摇合资的合法性
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
JFTC - remedies and their ongoing obligations怎么使用:直接 / 支持;外部现实校验:13;反向验证:08;专项深挖:13
Split agreement approved - EGM and January 2027 effectiveness怎么使用:直接 / 支持;一手验证:35;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域13) / 反证(研究域08) / 定向深挖(研究域13)|JFTC - remedies and their ongoing obligations;直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness
完整研究记录(核对用)
研究原文:The venture's antitrust conditions are a permanent operating constraint: the information firewall and monitoring trustee exist because two groups share a factory while competing in sales, and a compliance failure or future reassessment of a structure combining ~70% of the small-diameter market would strike the venture's legality, not merely its economics.
内部研究类型:risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Compliance failure is existential for the venture; the conditions also cap pricing-coordination upside.
不确定性(原始记录):Trustee identity and reporting not public; probability low-to-moderate, confidence ~0.7.
F029|04|需求腰斩和产能过剩是同一件事的两面,合资是对准两者的唯一手段
研究范围:开放研究+35项覆盖检查
写入正文:04|需求腰斩和产能过剩是同一件事的两面,合资是对准两者的唯一手段11|需求风险是结构性的:市场二十年减半,更新潮的节奏不由行业决定14|八个模块:估值和盈利质量给分最多,治理和资本配置最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:直接 / 支持;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
FY3/26 order environment - a full year of weak utility demand怎么使用:直接 / 支持;外部现实校验:12;反向验证:02;专项深挖:12;同业比较:05、11;其他用途:历史
JFTC review summary - demand structure of the ductile pipe market怎么使用:直接证据;一手验证:05、11、12;同业比较:08;其他用途:历史
Demand environment - utility orders subdued nationwide怎么使用:直接证据;外部现实校验:05;反向验证:11、12、19;专项深挖:05、11、12
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;直接证据 / 支持证据 / 外部现实(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域11) / 反证(研究域02) / 定向深挖(研究域12)|FY3/26 order environment - a full year of weak utility demand;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 历史/同业比较(研究域08)|JFTC review summary - demand structure of the ductile pipe market;直接证据 / 外部现实(研究域05) / 反证(研究域11) / 反证(研究域12) / 反证(研究域19) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment - utility orders subdued nationwide
完整研究记录(核对用)
研究原文:Demand risk is structural and slow: the market has halved in twenty years, penetration exceeds 98%, industry capacity is in surplus, and renewal demand had still not lifted utility orders in any period in the record; ageing-network renewal, the only growth source, is paced by municipal budgets outside industry control.
内部研究类型:risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Growth assumptions should be price-and-share only; volume growth is a claim requiring evidence.
不确定性(原始记录):Renewal timing by utility and prefecture not published.
F030|11|催化剂是有日期的程序性事件,前后顺序要分清
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Catalyst calendar - EGM, split effectiveness and reporting dates怎么使用:直接 / 支持;一手验证:30;外部现实校验:30、35;专项深挖:30、35
Split agreement approved - EGM and January 2027 effectiveness怎么使用:直接 / 支持;一手验证:35;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Catalyst calendar - EGM, split effectiveness and reporting dates;直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness
完整研究记录(核对用)
研究原文:Dated procedural catalysts: EGM on 17 December 2026; Nichu Tech capital increase to JPY 300 million in December 2026; split effectiveness and Kubota's 19.9% acquisition on 4 January 2027. Each resolves a different unknown (legality, structure) and is observable within weeks.
内部研究类型:catalyst_calendar
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Event risk is front-loaded into the next two quarters.
不确定性(原始记录):Planned dates subject to EGM approval.
F031|11|催化剂是有日期的程序性事件,前后顺序要分清
研究范围:开放研究+35项覆盖检查
写入正文:11|催化剂是有日期的程序性事件,前后顺序要分清13|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Catalyst calendar - EGM, split effectiveness and reporting dates怎么使用:直接 / 支持;一手验证:30;外部现实校验:30、35;专项深挖:30、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Catalyst calendar - EGM, split effectiveness and reporting dates;直接证据 / 支持证据|Accounting consequence - common-control split and continued consolidation
完整研究记录(核对用)
研究原文:The FY3/27 year-end release (expected late April 2027) is the first venture-era print and will show whether the thin implied H2 was conservatism or warning; its FY3/28 outlook is the first guidance for the post-split structure, when the market can first price Nichu Tech's actual contribution; Q3 FY3/27 (late January 2027) is the first print after effectiveness.
内部研究类型:catalyst_calendar
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):April guidance is the single largest repricing point.
不确定性(原始记录):Release dates are customary calendar, labelled expected; whether venture-era targets will be published is unknown.
F032|10|长期来看,价格大半时间停在1,000至2,000日元,2005年高点之后跌了十三年
研究范围:开放研究
写入正文:10|长期来看,价格大半时间停在1,000至2,000日元,2005年高点之后跌了十三年10|六年筑底:2020至2025年的年度低点始终守在900至1,004日元10|2025年9月放量冲高,当月即被打回,一月回踩失败后缩量下滑10|目前处在守底检验:价格贴着箱体下沿,三条均线给出上下两头的参照14|八个模块:估值和盈利质量给分最多,治理和资本配置最低15|来源以公司披露、监管文件和登记资料为主,数据截至2026年11月6日收盘
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Monthly price history - span and extremes (local assembly from mirror data)怎么使用:直接 / 支持;一手验证:34;同业比较:33;其他用途:历史
Monthly moving averages at October 2026 (local computation)怎么使用:直接 / 支持;一手验证:34;反向验证:34
Residence distribution of monthly closes, 2001-2026 (local computation)怎么使用:直接 / 支持;外部现实校验:34
Annual high, low and close, 2019-2026 (local computation)怎么使用:直接 / 支持;外部现实校验:34
Recent monthly path and volume, September 2025 to October 2026 (local computation)怎么使用:直接 / 支持;同业比较:31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域34) / 历史/同业比较(研究域33)|Monthly price history - span and extremes (local assembly from mirror data);直接证据 / 支持证据 / 一手证据(研究域34) / 反证(研究域34)|Monthly moving averages at October 2026 (local computation);直接证据 / 支持证据 / 外部现实(研究域34)|Residence distribution of monthly closes, 2001-2026 (local computation);直接证据 / 支持证据 / 外部现实(研究域34)|Annual high, low and close, 2019-2026 (local computation);直接证据 / 支持证据 / 历史/同业比较(研究域31)|Recent monthly path and volume, September 2025 to October 2026 (local computation)
完整研究记录(核对用)
研究原文:Research Claim 32 records the price record as a defended floor with a rejected spike: six annual lows at JPY 900-1,004 (2020-2025), a September 2025 high of JPY 2,858 closing at JPY 1,915 on ~30x normal volume, a failed January 2026 retest at JPY 2,249, a 2026 band JPY 1,470-1,680 with October close JPY 1,489 below MA12 (1,645.17) and MA24 (1,554.04) but above the rising MA60 (1,282.38); 69.0% of monthly closes since 2001 lie between JPY 1,000 and 2,000. This node references that claim as retained Research Truth; the authoritative pure-price interpretation is the protected Technical structure and is not redefined here.
内部研究类型:price_structure_claim_reference
内部来源标记:TECHNICAL / OPEN_DISCOVERY
普通股东含义(原始记录):The market pays for asset backing and the dividend while withholding credit for the venture until it prints.
不确定性(原始记录):Liquidity minimal (94,000 shares October 2026); November 2026 is an incomplete month; catalyst of the 2025 climax unverified.
F033|10|价格领先于业绩:两次大波动都早于基本面确认
研究范围:35项覆盖检查
写入正文:10|价格领先于业绩:两次大波动都早于基本面确认12|一份扭亏的中报被卖掉:市场付钱的对象是交付,不是公告
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Recent monthly path and volume, September 2025 to October 2026 (local computation)怎么使用:直接 / 支持;同业比较:31;其他用途:历史
Post-results market reaction - the 6 November 2026 session怎么使用:直接 / 支持;一手验证:31;外部现实校验:31;专项深挖:31、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域31)|Recent monthly path and volume, September 2025 to October 2026 (local computation);直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|Post-results market reaction - the 6 November 2026 session
完整研究记录(核对用)
研究原文:Price led fundamentals in both directions: the September 2025 climax preceded the earnings recovery's confirmation by about a year, and the market sold the October 2026 print (-7.21% on 6 November) despite the swing to profit because the unchanged forecast's implied H2 asked it to capitalise delivery not yet occurred - the shares price the venture's proof, not its announcement. This is a cross-lane relation of public fundamentals to price response; it does not rewrite the pure Technical State.
内部研究类型:cross_lane_timing_inference
内部来源标记:COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Positioning is asymmetric in the holder's favour if the venture works but unforgiving of delay.
不确定性(原始记录):Inference confidence ~0.75; buyers of the 2025 climax unknowable.
F034|07|JFE 钢铁处在上游,东京燃气处在下游,各自带来一种稳定性
研究范围:开放研究
写入正文:07|JFE 钢铁处在上游,东京燃气处在下游,各自带来一种稳定性
归并到:F060
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Securities report data - major shareholders at FY3/26 year-end怎么使用:直接证据;一手验证:09、24;反向验证:01
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域09) / 一手证据(研究域24) / 反证(研究域01)|Securities report data - major shareholders at FY3/26 year-end
完整研究记录(核对用)
研究原文:JFE Steel Corporation: largest shareholder (29.88%), an upstream steelmaker in the iron-unit chain; at just under 30% it holds effective negative control over special resolutions without consolidating.
内部研究类型:related_company
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Register stability and an industrial horizon; intentions undisclosed.
不确定性(原始记录):No supply contract disclosed.
F035|07|JFE 钢铁处在上游,东京燃气处在下游,各自带来一种稳定性
研究范围:开放研究
写入正文:07|JFE 钢铁处在上游,东京燃气处在下游,各自带来一种稳定性
归并到:F061
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Securities report data - major shareholders at FY3/26 year-end怎么使用:直接证据;一手验证:09、24;反向验证:01
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域09) / 一手证据(研究域24) / 反证(研究域01)|Securities report data - major shareholders at FY3/26 year-end
完整研究记录(核对用)
研究原文:Tokyo Gas Co., Ltd.: second-largest shareholder (10.37%), a gas utility of the class that buys the company's gas-related products.
内部研究类型:related_company
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):A customer-side anchor reinforces register stability and the gas-product franchise.
不确定性(原始记录):Commercial relationship terms not disclosed.
F036|04|最大对手成为制造伙伴:成本收益与反垄断脆弱性来自同一个安排
研究范围:开放研究
写入正文:04|最大对手成为制造伙伴:成本收益与反垄断脆弱性来自同一个安排
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
JFTC review chart - OEM scope of the joint venture怎么使用:直接证据;一手验证:08
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07)|Definitive agreement - company split and manufacturing joint venture with Kubota;直接证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture
完整研究记录(核对用)
研究原文:Kubota Corporation: dominant competitor (~55% of small-diameter ductile pipe) turned manufacturing partner - 19.9% owner of Nichu Tech from 4 January 2027 and OEM customer of the venture, while continuing to compete in sales.
内部研究类型:related_company
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Central relationship of the equity case: source of expected cost gains and of antitrust fragility.
不确定性(原始记录):JV agreement terms undisclosed; Kubota plant-closure matching not yet of record.
F037|Nichu Tech Co., Ltd. (日鋳テック): wholly-owned subsidiary established 10 June 2026 and from 4 January 2027 the group's straight-pipe manufacturer, 80.1%/19.9% with Kubota, remaining consolidated with Kubota's stake as non-controlling interests (board planned as four parent directors, one from Kubota).
研究范围:开放研究+35项覆盖检查
写入正文:02|分割把直管制造移入合资子公司,合并范围不变,利润归属变了
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接证据;一手验证:30
Nichu Tech - the successor company怎么使用:直接证据;专项深挖:07
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07)|FY3/27 interim release - subsequent events: Nichu Tech split agreement;直接证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 定向深挖(研究域07)|Nichu Tech - the successor company
完整研究记录(核对用)
研究原文:Nichu Tech Co., Ltd. (日鋳テック): wholly-owned subsidiary established 10 June 2026 and from 4 January 2027 the group's straight-pipe manufacturer, 80.1%/19.9% with Kubota, remaining consolidated with Kubota's stake as non-controlling interests (board planned as four parent directors, one from Kubota).
内部研究类型:related_company
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Its OEM pricing and cost performance decide how much of the venture's benefit reaches the listed parent's shareholders.
不确定性(原始记录):Standalone disclosure not committed.
F038|03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
研究范围:开放研究
写入正文:03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
归并到:F064
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim release - qualitative drivers of the recovery怎么使用:直接证据;一手验证:05、06、14、15
JFTC review summary - demand structure of the ductile pipe market怎么使用:直接证据;一手验证:05、11、12;同业比较:08;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15)|FY3/27 interim release - qualitative drivers of the recovery;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 历史/同业比较(研究域08)|JFTC review summary - demand structure of the ductile pipe market
完整研究记录(核对用)
研究原文:Japanese waterworks and sewerage utilities: the customer base whose ductile pipe order volumes are described as subdued nationwide in every period in the record.
内部研究类型:end_market
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Utility budgets and renewal cycles set the volume ceiling for the industry.
不确定性(原始记录):Customer names and order books not disclosed.
F039|04|反垄断审批已经完成,但附带的条件是长期义务
研究范围:开放研究+35项覆盖检查
归并到:F065
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary怎么使用:直接证据;一手验证:13、33;反向验证:35;同业比较:04、07;其他用途:历史
JFTC review summary - market definition, shares and remedies怎么使用:直接证据;一手验证:08、09、11、13
JFTC - remedies and their ongoing obligations怎么使用:直接证据;外部现实校验:13;反向验证:08;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域07) / 反证(研究域35)|JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13)|JFTC review summary - market definition, shares and remedies;直接证据 / 外部现实(研究域13) / 反证(研究域08) / 定向深挖(研究域13)|JFTC - remedies and their ongoing obligations
完整研究记录(核对用)
研究原文:Japan Fair Trade Commission: cleared Kubota's acquisition on 27 March 2025 subject to remedies and credited the venture's CO2 efficiency under its Green Guidelines; its published analysis is the most authoritative map of market shares and structure.
内部研究类型:regulator
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Conditional clearance with standing obligations.
不确定性(原始记录):Monitoring trustee identity not public.
F040|03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
研究范围:开放研究+35项覆盖检查
写入正文:03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
归并到:F069
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
JFTC review summary - demand structure of the ductile pipe market怎么使用:直接证据;一手验证:05、11、12;同业比较:08;其他用途:历史
FY3/26 interim release - mid-term management plan and lifecycle strategy怎么使用:直接证据;一手验证:04;同业比较:03;其他用途:历史
Demand environment - utility orders subdued nationwide怎么使用:直接证据;外部现实校验:05;反向验证:11、12、19;专项深挖:05、11、12
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:直接证据;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 历史/同业比较(研究域08)|JFTC review summary - demand structure of the ductile pipe market;直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03)|FY3/26 interim release - mid-term management plan and lifecycle strategy;直接证据 / 外部现实(研究域05) / 反证(研究域11) / 反证(研究域12) / 反证(研究域19) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment - utility orders subdued nationwide;直接证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe
完整研究记录(核对用)
研究原文:Ageing water and sewerage infrastructure renewal: with penetration above 98% replacement and renewal - including diagnosis services the company is building - replace network expansion as the only prospective volume growth source.
内部研究类型:end_market
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Pace set by municipal budgets decides whether consolidated capacity earns scarcity value or merely shares a shrinking pie more cheaply.
不确定性(原始记录):Renewal wave timing not published.
F041|04|小口径直管份额只有15%,公司是三家里最小的一家
研究主题:竞争格局 · 研究范围:35项覆盖检查
写入正文:04|小口径直管份额只有15%,公司是三家里最小的一家
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:直接证据;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
JFTC review summary - market definition, shares and remedies怎么使用:直接证据;一手验证:08、09、11、13
JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary怎么使用:直接证据;一手验证:13、33;反向验证:35;同业比较:04、07;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13)|JFTC review summary - market definition, shares and remedies;直接证据 / 一手证据(研究域13) / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域07) / 反证(研究域35)|JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary
完整研究记录(核对用)
研究原文:The company is third of three in small-diameter ductile pipe with about 15% share (Kubota ~55%, one anonymised maker ~30%), the smallest revenue base and weakest recent margins; positional assets are the anchor register and Kuki being the shared platform with the parent holding 80.1% of the venture. The competitive problem was cost in a surplus-capacity market, not share loss; substitution from other pipe materials caps pricing upside.
内部研究类型:competitive_position
内部来源标记:COVERAGE35
普通股东含义(原始记录):Shareholders hold the industry's restructuring option via majority ownership of the vehicle, better than the standalone third-place position.
不确定性(原始记录):Competitor cost positions and the anonymised maker are not in admitted sources.
F042|05|护城河在系统层面,产品层面很薄
研究范围:35项覆盖检查
写入正文:05|护城河在系统层面,产品层面很薄14|八个模块:估值和盈利质量给分最多,治理和资本配置最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Company web profile - business description怎么使用:直接证据;一手验证:02、03、10
FY3/26 third-quarter release - reportable segments怎么使用:直接证据;一手验证:03、10
Production base - the Kuki works and what stays with the parent怎么使用:直接证据;外部现实校验:02、03;专项深挖:02、03
Segment results - nine months to December 2025怎么使用:直接证据;一手验证:02;反向验证:03、15;专项深挖:02、03
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域10)|Company web profile - business description;直接证据 / 一手证据(研究域03) / 一手证据(研究域10)|FY3/26 third-quarter release - reportable segments;直接证据 / 外部现实(研究域02) / 外部现实(研究域03) / 定向深挖(研究域02) / 定向深挖(研究域03)|Production base - the Kuki works and what stays with the parent;直接证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025
完整研究记录(核对用)
研究原文:The moat is thin at product level (ductile pipe is a standards product) and thicker at system level: specification qualification, installed-base renewal, covers/fittings/diagnosis attachments, and from 2027 ownership of the consolidated plant. Evidence of thinness is the record itself: two years of sub-2% margins; rent sits in the attached layer (resin/gas ~8% segment margin) and post-consolidation manufacturing cost.
内部研究类型:moat_assessment
内部来源标记:COVERAGE35
普通股东含义(原始记录):Through-cycle margin should be set by the attached layer plus venture savings, not by a pipe franchise.
不确定性(原始记录):No pricing-power metric disclosed; OEM terms will divide the venture's economics.
F043|03|成本先涨、价格后调,电炉化把熔炼成本从焦炭转向电价
研究范围:35项覆盖检查
写入正文:03|成本先涨、价格后调,电炉化把熔炼成本从焦炭转向电价06|盈利质量在价格和结构上改善了,在销量上没有
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Cost exposure - materials, energy and labour inflation怎么使用:直接证据;外部现实校验:06、14;反向验证:10、16、35;专项深挖:06、10、14
FY3/27 interim release - qualitative drivers of the recovery怎么使用:直接证据;一手验证:05、06、14、15
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接证据;一手验证:14、18、19、21、27、29
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域06) / 外部现实(研究域14) / 反证(研究域10) / 反证(研究域16) / 反证(研究域35) / 定向深挖(研究域06) / 定向深挖(研究域10) / 定向深挖(研究域14)|Cost exposure - materials, energy and labour inflation;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15)|FY3/27 interim release - qualitative drivers of the recovery;直接证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026
完整研究记录(核对用)
研究原文:Parts, materials, energy and labour costs rose continuously through FY3/26 and FY3/27; input inflation enters cost of sales immediately while price revisions enter with a lag - the lag is the margin cycle. The electric furnace shifts melting exposure from coke/scrap toward electricity tariffs; interest on JPY 10.4 billion of debt adds a rate exposure. Macro risk is margin-and-interest risk, not demand collapse.
内部研究类型:input_cost_mechanism
内部来源标记:COVERAGE35
普通股东含义(原始记录):Shareholders are structurally short input prices, hedged only by lagged price revisions.
不确定性(原始记录):Supplier concentration, JFE-group supply terms and contract terms undisclosed.
F044|06|应收和存货占去了资产的四成,产成品是要盯的指标
研究范围:35项覆盖检查
写入正文:06|应收和存货占去了资产的四成,产成品是要盯的指标
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Working capital at the interim date怎么使用:直接证据;外部现实校验:19;反向验证:17;专项深挖:19
FY3/27 interim release - balance sheet detail怎么使用:直接证据;一手验证:19、21;反向验证:07;专项深挖:18、19
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接证据;一手验证:14、18、19、21、27、29
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|Working capital at the interim date;直接证据 / 一手证据(研究域19) / 一手证据(研究域21) / 反证(研究域07) / 定向深挖(研究域18) / 定向深挖(研究域19)|FY3/27 interim release - balance sheet detail;直接证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026
完整研究记录(核对用)
研究原文:At September 2026 receivables were about JPY 6.1 billion (notes and accounts JPY 3,037 million plus electronically recorded claims JPY 3,045 million, roughly 133 days of the half's sales) and inventories JPY 4,657 million, of which finished products JPY 3,204 million - heavy finished-goods stock for a make-to-stock supplier facing subdued orders, absorbing roughly a third of the balance sheet.
内部研究类型:working_capital_state
内部来源标记:COVERAGE35
普通股东含义(原始记录):Release is a hidden cash source in a demand recovery; a build is the first balance-sheet symptom of a failed one. Finished-goods level is the variable to watch.
不确定性(原始记录):Payables and full cash conversion cycle not completed; inventory ownership/realizability beyond book value not assessed.
F045|09|资产下限能防住最坏情形,防不住长期平庸
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim release - balance sheet detail怎么使用:直接证据;一手验证:19、21;反向验证:07;专项深挖:18、19
Book-value anchor - equity per share against the market price怎么使用:直接证据;外部现实校验:21、29;反向验证:27;专项深挖:21、27、29
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接证据;一手验证:14、18、19、21、27、29
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域19) / 一手证据(研究域21) / 反证(研究域07) / 定向深挖(研究域18) / 定向深挖(研究域19)|FY3/27 interim release - balance sheet detail;直接证据 / 外部现实(研究域21) / 外部现实(研究域29) / 反证(研究域27) / 定向深挖(研究域21) / 定向深挖(研究域27) / 定向深挖(研究域29)|Book-value anchor - equity per share against the market price;直接证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026
完整研究记录(核对用)
研究原文:Non-operating and downside-relevant balances: land carried at JPY 3,163 million within tangible fixed assets of JPY 9,441 million (historical cost, no appraisal), retained earnings JPY 6,484 million (funding reserve behind the flat dividend), and accumulated retirement-benefit adjustments of JPY 1,354 million within equity - larger than any recent year's profit. They define the asset floor under a leveraged, low-return business and cap restructuring urgency.
内部研究类型:asset_floor
内部来源标记:COVERAGE35
普通股东含义(原始记录):Downside is protected against catastrophe better than against mediocrity: a realistic outcome is a decade of ~0.4x book, not zero.
不确定性(原始记录):No revaluation surplus asserted; policy shareholdings and land appraisal not in admitted sources; actuarial balance moves with discount rates.
F046|06|全年指引原样保留,隐含的下半年利润极薄
研究范围:35项覆盖检查
写入正文:06|全年指引原样保留,隐含的下半年利润极薄09|市场为“交付”付钱,不为“宣布”付钱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Forecast-carry record - the FY3/26 initial forecast versus the outcome怎么使用:直接证据;外部现实校验:32;反向验证:31;专项深挖:32、35
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域32) / 反证(研究域31) / 定向深挖(研究域32) / 定向深挖(研究域35)|Forecast-carry record - the FY3/26 initial forecast versus the outcome;直接证据|FY3/27 first-quarter release and the initial full-year forecast
完整研究记录(核对用)
研究原文:The FY3/26 initial forecast (28 July 2025), still carried unchanged at 30 January 2026, implied sales of about JPY 18.0 billion, operating profit JPY 230 million and nil net profit; actuals were sales JPY 15,942 million (~11% below) but operating profit JPY 258 million and net profit JPY 91 million beat it. The record is revenue optimism with profit conservatism, so guidance must be read asymmetrically.
内部研究类型:forecast_reliability
内部来源标记:COVERAGE35
普通股东含义(原始记录):Teaches the market to distrust the top line and test the bottom line.
不确定性(原始记录):Cause of the sales shortfall not established (see Research Debt).
F047|06|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
研究范围:35项覆盖检查
写入正文:06|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Non-operating items - interest and fees rising with debt怎么使用:直接证据;一手验证:32;反向验证:18、29;同业比较:14;其他用途:历史
Prior-year one-offs - settlement gain and furnace trial costs怎么使用:直接证据;一手验证:32;专项深挖:32;同业比较:16、32;其他用途:历史
FY3/27 interim release - profit and loss detail怎么使用:直接证据;一手验证:16;外部现实校验:15;反向验证:14;专项深挖:14、15、16
Nine-month FY3/26 income statement and depreciation step-up怎么使用:直接证据;一手验证:16;外部现实校验:16;专项深挖:16、17;同业比较:06、17、19、20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域14) / 反证(研究域18) / 反证(研究域29)|Non-operating items - interest and fees rising with debt;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Prior-year one-offs - settlement gain and furnace trial costs;直接证据 / 一手证据(研究域16) / 外部现实(研究域15) / 反证(研究域14) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域16)|FY3/27 interim release - profit and loss detail;直接证据 / 一手证据(研究域16) / 外部现实(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 定向深挖(研究域16) / 定向深挖(研究域17)|Nine-month FY3/26 income statement and depreciation step-up;直接证据|Accounting consequence - common-control split and continued consolidation
完整研究记录(核对用)
研究原文:One-off items swing small profits: 9M FY3/26 pre-tax profit of JPY 247 million rested on a JPY 165 million JV-preparation settlement gain and JPY 22 million of settlement receipts against operating profit of JPY 120 million; furnace trial costs burdened the same base; depreciation stepped up to JPY 577 million from JPY 356 million; H1 FY3/27 carries a JPY 18 million JV-equipment disposal loss below the ordinary line. The interim release has no cash-flow statement.
内部研究类型:profit_comparability_adjustment
内部来源标记:COVERAGE35
普通股东含义(原始记录):With profits this small, one-offs of JPY 100-200 million separate a profit year from a loss year; headline growth rates around the transition mislead in both directions.
不确定性(原始记录):These are reading adjustments, not integrity findings; post-split segment presentation unspecified.
F048|09|要清掉资本成本,合资必须跑过历史峰值,而不只是回到峰值
研究范围:开放研究
写入正文:09|要清掉资本成本,合资必须跑过历史峰值,而不只是回到峰值
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 full-year results compiled from the securities report怎么使用:直接证据;一手验证:17、22;同业比较:18;其他用途:历史
Five-year consolidated record from securities reports怎么使用:直接证据;一手验证:22、28;同业比较:09、10、27、34;其他用途:历史
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接证据;一手验证:14、18、19、21、27、29
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域17) / 一手证据(研究域22) / 历史/同业比较(研究域18)|FY3/26 full-year results compiled from the securities report;直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域27) / 历史/同业比较(研究域34)|Five-year consolidated record from securities reports;直接证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026
完整研究记录(核对用)
研究原文:ROE was 0.9% in FY3/26; on equity of about JPY 10.0 billion even a return to the FY3/24 operating peak of JPY 860 million yields a pre-tax return on equity below ~9% before interest on JPY 10.4 billion of debt, so the venture must beat the historical peak, not regain it, to clear a plausible cost of equity. No ROIC or capital-efficiency target is published.
内部研究类型:capital_efficiency_arithmetic
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Capital efficiency, not growth, is the valuation question; each ROE point toward mid-single digits is worth a visible fraction of the book multiple.
不确定性(原始记录):Derived arithmetic, not a disclosed figure; ROIC not reconstructed.
F049|09|按正常化利润算,现价并不便宜,买的是合资的增量
研究范围:35项覆盖检查
写入正文:09|按正常化利润算,现价并不便宜,买的是合资的增量14|八个模块:估值和盈利质量给分最多,治理和资本配置最低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Five-year consolidated record from securities reports怎么使用:直接证据;一手验证:22、28;同业比较:09、10、27、34;其他用途:历史
Five-year record - sales, operating profit and EPS怎么使用:直接证据;一手验证:28;外部现实校验:22、28;专项深挖:22、28、33;同业比较:02、12、15、35;其他用途:历史
The FY3/24 peak and the two-year decline怎么使用:直接证据;外部现实校验:33;专项深挖:22、33;同业比较:22、28、29;其他用途:历史
Segment results - nine months to December 2025怎么使用:直接证据;一手验证:02;反向验证:03、15;专项深挖:02、03
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域27) / 历史/同业比较(研究域34)|Five-year consolidated record from securities reports;直接证据 / 一手证据(研究域28) / 外部现实(研究域22) / 外部现实(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域33)|Five-year record - sales, operating profit and EPS;直接证据 / 外部现实(研究域33) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 定向深挖(研究域22) / 定向深挖(研究域33)|The FY3/24 peak and the two-year decline;直接证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025
完整研究记录(核对用)
研究原文:A defensible pre-venture normalisation is operating profit of JPY 400-600 million on sales of about JPY 16 billion (2.5-3.5% margin), with venture utilisation savings as an unquantified addition only FY3/28 reporting can size. On this basis the current price (about JPY 4.2 billion market value against JPY 10.0 billion equity and ~JPY 6.8 billion net debt) is not cheap - the venture increment is what is being bought.
内部研究类型:normalized_earnings
内部来源标记:COVERAGE35
普通股东含义(原始记录):Sets the pre-venture base against which the thesis and falsifiers are measured.
不确定性(原始记录):Research estimate from a five-year record; venture savings rate undisclosed.
F050|02|分割之后,上市公司会变成另一种分析对象
研究范围:开放研究+35项覆盖检查
写入正文:02|分割之后,上市公司会变成另一种分析对象13|最优先要查清的三件事:合资的利润怎么分、有没有数值目标、半年现金流是多少14|评分45.91,评级C:资产下限可靠,成长与回报的证据尚未出现
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接证据;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:直接证据;一手验证:08
Split agreement approved - EGM and January 2027 effectiveness怎么使用:直接证据;一手验证:35;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;直接证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness;直接证据|Accounting consequence - common-control split and continued consolidation
完整研究记录(核对用)
研究原文:What earnings model will Nichu Tech run on (OEM pricing to the two parents, margin, dividend policy), how much of the venture's cost saving reaches the listed parent's consolidated profit and from which fiscal year; and will the company disclose Nichu Tech standalone results or a restated segment presentation after January 2027 once ~70% of sales moves into the subsidiary.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The decisive unknown: location of the spread inside the group and the visibility of it to minorities.
不确定性(原始记录):Management-held until FY3/28 reporting; evidence that resolves it is OEM terms, related-party notes and venture-era segment disclosure.
F051|13|最优先要查清的三件事:合资的利润怎么分、有没有数值目标、半年现金流是多少
研究范围:开放研究+35项覆盖检查
写入正文:13|最优先要查清的三件事:合资的利润怎么分、有没有数值目标、半年现金流是多少
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 interim release - mid-term management plan and lifecycle strategy怎么使用:直接证据;一手验证:04;同业比较:03;其他用途:历史
Mid-term plan - lifecycle initiatives without published numerical targets怎么使用:直接证据;反向验证:04;专项深挖:04
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03)|FY3/26 interim release - mid-term management plan and lifecycle strategy;直接证据 / 反证(研究域04) / 定向深挖(研究域04)|Mid-term plan - lifecycle initiatives without published numerical targets
完整研究记录(核对用)
研究原文:Does the July 2025 mid-term plan carry numerical targets (sales, operating profit, ROE, capital policy) anywhere in published materials, and if so what are they?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Targets, if they exist, would anchor the ROE/re-rating test.
不确定性(原始记录):Resolved by plan documents or integrated report; absence would itself be informative.
F052|06|26/3 期的投资花掉了经营现金流的十倍
研究范围:开放研究+35项覆盖检查
写入正文:06|26/3 期的投资花掉了经营现金流的十倍13|最优先要查清的三件事:合资的利润怎么分、有没有数值目标、半年现金流是多少
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接证据;一手验证:14、18、19、21、27、29
FY3/26 cash flow compiled from the securities report怎么使用:直接证据;一手验证:17;外部现实校验:17;反向验证:20、32;专项深挖:17、20
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026;直接证据 / 一手证据(研究域17) / 外部现实(研究域17) / 反证(研究域20) / 反证(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域20)|FY3/26 cash flow compiled from the securities report
完整研究记录(核对用)
研究原文:What were the H1 FY3/27 cash flows (operating, investing, financing)? The interim release has no cash-flow statement, so the debt trajectory within the half cannot be tied to cash generation.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Tests whether the profit swing converts to cash and whether borrowings are still funding capex.
不确定性(原始记录):A disclosure-form gap, not adverse evidence; resolved by FY3/27 annual cash-flow statement.
F053|13|第二层问题:全年分部、电炉成本、指引失准的原因、合资时代的分红
研究范围:开放研究+35项覆盖检查
写入正文:13|第二层问题:全年分部、电炉成本、指引失准的原因、合资时代的分红
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Segment results - nine months to December 2025怎么使用:直接证据;一手验证:02;反向验证:03、15;专项深挖:02、03
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025;直接证据|Segment comparatives - nine months to December 2024
完整研究记录(核对用)
研究原文:What were the full-year FY3/26 segment results (ductile versus resin and gas)? Only the nine-month split was obtained.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Confirms whether the inverted segment economics persisted through year-end.
不确定性(原始记录):Resolved by the FY3/26 securities report segment note.
F054|13|第二层问题:全年分部、电炉成本、指引失准的原因、合资时代的分红
研究范围:开放研究+35项覆盖检查
写入正文:13|第二层问题:全年分部、电炉成本、指引失准的原因、合资时代的分红
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion怎么使用:直接证据;一手验证:20
Capacity investment of about JPY 2.7 billion at Kuki怎么使用:直接证据;外部现实校验:20;专项深挖:20
Nine-month FY3/26 income statement and depreciation step-up怎么使用:直接证据;一手验证:16;外部现实校验:16;专项深挖:16、17;同业比较:06、17、19、20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域20)|FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion;直接证据 / 外部现实(研究域20) / 定向深挖(研究域20)|Capacity investment of about JPY 2.7 billion at Kuki;直接证据 / 一手证据(研究域16) / 外部现实(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 定向深挖(研究域16) / 定向深挖(研究域17)|Nine-month FY3/26 income statement and depreciation step-up
完整研究记录(核对用)
研究原文:What was the total cost of the electric furnace programme, how was the ~JPY 2.7 billion of venture capacity investment at Kuki divided between furnace, buildings and machinery, and what depreciation profile follows?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Sizes the stepped-up fixed charge the venture must absorb.
不确定性(原始记录):Resolved by fixed-asset schedules in the FY3/27 securities report.
F055|13|第二层问题:全年分部、电炉成本、指引失准的原因、合资时代的分红
研究范围:开放研究+35项覆盖检查
写入正文:13|第二层问题:全年分部、电炉成本、指引失准的原因、合资时代的分红
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Forecast-carry record - the FY3/26 initial forecast versus the outcome怎么使用:直接证据;外部现实校验:32;反向验证:31;专项深挖:32、35
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域32) / 反证(研究域31) / 定向深挖(研究域32) / 定向深挖(研究域35)|Forecast-carry record - the FY3/26 initial forecast versus the outcome;直接证据|FY3/27 first-quarter release and the initial full-year forecast
完整研究记录(核对用)
研究原文:Why did FY3/26 sales close about 11% below the forecast still carried unchanged at the Q3 release (implied ~JPY 18.0 billion), which demand assumption failed, and has the forecasting process changed for FY3/27?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Determines how much credibility to give the FY3/27 unchanged forecast and its thin H2.
不确定性(原始记录):Resolved by management commentary or FY3/27 year-end release.
F056|13|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口
研究范围:开放研究+35项覆盖检查
写入正文:13|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接证据;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
Officers and employees - EDINET-compiled data怎么使用:直接证据;一手验证:23;外部现实校验:23;专项深挖:23、24;同业比较:23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas;直接证据 / 一手证据(研究域23) / 外部现实(研究域23) / 历史/同业比较(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域24)|Officers and employees - EDINET-compiled data
完整研究记录(核对用)
研究原文:What is the full governance picture - outside director composition, policy shareholdings (including whether the JFE Steel and Tokyo Gas stakes are reciprocal), and any capital-policy review attached to the venture?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Bears on whether minority-friendly capital policy can ever originate inside the board.
不确定性(原始记录):Resolved by corporate governance report and securities report.
F057|13|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口
研究范围:开放研究
写入正文:13|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Recent monthly path and volume, September 2025 to October 2026 (local computation)怎么使用:直接证据;同业比较:31;其他用途:历史
Monthly price history - span and extremes (local assembly from mirror data)怎么使用:直接证据;一手验证:34;同业比较:33;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域31)|Recent monthly path and volume, September 2025 to October 2026 (local computation);直接证据 / 一手证据(研究域34) / 历史/同业比较(研究域33)|Monthly price history - span and extremes (local assembly from mirror data)
完整研究记录(核对用)
研究原文:What drove the August-September 2025 price climax (monthly high JPY 2,858 on about thirty times normal volume)? No disclosure read explains the timing; the catalyst is unverified.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / TECHNICAL
普通股东含义(原始记录):Distinguishes a story pulse from an information event, relevant to how much of the 2025 repricing was fundamental.
不确定性(原始记录):May be unknowable from public sources; buyers' identity not recoverable. Does not alter the pure Technical State.
F058|08|合资时代的分红和去杠杆政策还没有答案,第一个信号是2027年4月的分红决定
研究范围:开放研究+35项覆盖检查
写入正文:08|合资时代的分红和去杠杆政策还没有答案,第一个信号是2027年4月的分红决定13|第二层问题:全年分部、电炉成本、指引失准的原因、合资时代的分红
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Dividend decision arithmetic - JPY 25 at an 88.1% payout怎么使用:直接证据;外部现实校验:26;反向验证:25;专项深挖:25、26
Dividend decision for FY3/26 - stable-dividend policy怎么使用:直接证据;一手验证:26、29
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接证据;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域26) / 反证(研究域25) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision arithmetic - JPY 25 at an 88.1% payout;直接证据 / 一手证据(研究域26) / 一手证据(研究域29)|Dividend decision for FY3/26 - stable-dividend policy;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping
完整研究记录(核对用)
研究原文:What dividend and deleveraging policy applies in the venture era from FY3/28: is the flat JPY 25 held while borrowings stand at about JPY 10.4 billion, and is any payout-ratio or DOE framework under consideration?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Determines whether recovery profits go to deleveraging, dividends or neither.
不确定性(原始记录):First signal is the April 2027 year-end dividend decision.
F059|13|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口
研究范围:35项覆盖检查
写入正文:13|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口15|证据的限度:几项关键数字来自二手汇编,若干判断受未披露信息限制
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接证据;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
Definitive agreement - venture structure and original schedule怎么使用:直接证据;外部现实校验:07;反向验证:33;专项深挖:07、08;同业比较:13、30;其他用途:历史
JFTC - remedies and their ongoing obligations怎么使用:直接证据;外部现实校验:13;反向验证:08;专项深挖:13
Mid-term plan - lifecycle initiatives without published numerical targets怎么使用:直接证据;反向验证:04;专项深挖:04
Working capital at the interim date怎么使用:直接证据;外部现实校验:19;反向验证:17;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping;直接证据 / 外部现实(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域08)|Definitive agreement - venture structure and original schedule;直接证据 / 外部现实(研究域13) / 反证(研究域08) / 定向深挖(研究域13)|JFTC - remedies and their ongoing obligations;直接证据 / 反证(研究域04) / 定向深挖(研究域04)|Mid-term plan - lifecycle initiatives without published numerical targets;直接证据 / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|Working capital at the interim date
完整研究记录(核对用)
研究原文:Secondary disclosure gaps carried from Coverage: order backlog (cycle position unmeasurable), debt covenants and fixed/floating structure, detailed JV agreement terms, monitoring-trustee identity, R&D spend and diagnosis-business revenue, supplier concentration, renewal-wave timing, and the Fracta partnership terms.
内部研究类型:research_debt
内部来源标记:COVERAGE35
普通股东含义(原始记录):Each limits the confidence of a specific judgment (cycle, solvency stress, venture permanence, technology economics) without being negative evidence.
不确定性(原始记录):Non-disclosure is not evidence of absence; resolution paths are securities report notes and future disclosures.
F060|07|JFE 钢铁处在上游,东京燃气处在下游,各自带来一种稳定性
研究范围:开放研究
写入正文:07|JFE 钢铁处在上游,东京燃气处在下游,各自带来一种稳定性
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Securities report data - major shareholders at FY3/26 year-end怎么使用:直接证据;一手验证:09、24;反向验证:01
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域09) / 一手证据(研究域24) / 反证(研究域01)|Securities report data - major shareholders at FY3/26 year-end
完整研究记录(核对用)
研究原文:JFE Steel is the largest shareholder (29.88%) and upstream steelmaker; it provides register stability and holds effective negative control over special resolutions, with undisclosed intentions.
内部研究类型:CAPITAL
内部来源标记:OPEN_DISCOVERY
F061|07|JFE 钢铁处在上游,东京燃气处在下游,各自带来一种稳定性
研究范围:开放研究
写入正文:07|JFE 钢铁处在上游,东京燃气处在下游,各自带来一种稳定性
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Securities report data - major shareholders at FY3/26 year-end怎么使用:直接证据;一手验证:09、24;反向验证:01
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域09) / 一手证据(研究域24) / 反证(研究域01)|Securities report data - major shareholders at FY3/26 year-end
完整研究记录(核对用)
研究原文:Tokyo Gas holds 10.37% and, as a gas utility of the class that purchases the company's gas-related products, aligns a downstream customer interest with the register.
内部研究类型:CAPITAL
内部来源标记:OPEN_DISCOVERY
F062|04|最大对手成为制造伙伴:成本收益与反垄断脆弱性来自同一个安排
研究范围:开放研究
写入正文:04|最大对手成为制造伙伴:成本收益与反垄断脆弱性来自同一个安排
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Definitive agreement - company split and manufacturing joint venture with Kubota怎么使用:直接 / 支持;一手验证:07
JFTC review chart - OEM scope of the joint venture怎么使用:直接证据;一手验证:08
JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary怎么使用:支持证据;一手验证:13、33;反向验证:35;同业比较:04、07;其他用途:历史
JFTC review summary - market definition, shares and remedies怎么使用:支持证据;一手验证:08、09、11、13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07)|Definitive agreement - company split and manufacturing joint venture with Kubota;直接证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;支持证据 / 一手证据(研究域13) / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域07) / 反证(研究域35)|JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary;支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13)|JFTC review summary - market definition, shares and remedies
完整研究记录(核对用)
研究原文:Kubota, the ~55% share leader, becomes 19.9% owner of Nichu Tech and OEM customer of the venture for small-diameter products while still competing in sales: it converts a three-player overcapacity market into shared manufacturing with separated sales, the source of expected cost gains and of antitrust fragility.
内部研究类型:COMPETITOR_TURNED_PARTNER
内部来源标记:OPEN_DISCOVERY
F063|02|分割把直管制造移入合资子公司,合并范围不变,利润归属变了
研究范围:开放研究+35项覆盖检查
写入正文:02|分割把直管制造移入合资子公司,合并范围不变,利润归属变了
归并到:F037
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接 / 支持;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:支持证据;一手验证:08
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07)|FY3/27 interim release - subsequent events: Nichu Tech split agreement;直接证据 / 支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据|Accounting consequence - common-control split and continued consolidation;支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture
完整研究记录(核对用)
研究原文:The company owns 80.1% of Nichu Tech after the split; the subsidiary remains consolidated and Kubota's stake appears as non-controlling interests, so ~70% of group sales will be manufactured inside a jointly owned subsidiary whose OEM pricing and cost performance decide how much reaches the parent's shareholders.
内部研究类型:OWNERSHIP_AND_CONSOLIDATION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F064|03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
研究范围:开放研究+35项覆盖检查
写入正文:03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim release - qualitative drivers of the recovery怎么使用:直接证据;一手验证:05、06、14、15
JFTC review summary - demand structure of the ductile pipe market怎么使用:直接证据;一手验证:05、11、12;同业比较:08;其他用途:历史
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:支持证据;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
FY3/26 order environment - a full year of weak utility demand怎么使用:支持证据;外部现实校验:12;反向验证:02;专项深挖:12;同业比较:05、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15)|FY3/27 interim release - qualitative drivers of the recovery;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 历史/同业比较(研究域08)|JFTC review summary - demand structure of the ductile pipe market;支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;支持证据 / 外部现实(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域11) / 反证(研究域02) / 定向深挖(研究域12)|FY3/26 order environment - a full year of weak utility demand
完整研究记录(核对用)
研究原文:Municipal and regional water utilities are the customer base for ductile pipe and fittings; their subdued order volumes and budgets set the volume ceiling that the venture's cost consolidation is designed to survive.
内部研究类型:END_MARKET
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F065|04|反垄断审批已经完成,但附带的条件是长期义务
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary怎么使用:直接 / 支持;一手验证:13、33;反向验证:35;同业比较:04、07;其他用途:历史
JFTC review summary - market definition, shares and remedies怎么使用:直接 / 支持;一手验证:08、09、11、13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域07) / 反证(研究域35)|JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13)|JFTC review summary - market definition, shares and remedies;支持证据 / 一手证据(研究域07)|Definitive agreement - company split and manufacturing joint venture with Kubota
完整研究记录(核对用)
研究原文:The JFTC cleared Kubota's 19.9% acquisition on 27 March 2025 subject to an information firewall and independent monitoring trustee, and credited the venture's CO2-reduction efficiency under its Green Guidelines; the clearance is conditional and its conditions are standing obligations that protect legality while capping coordination upside.
内部研究类型:POLICY_CLEARANCE
内部来源标记:OPEN_DISCOVERY
F066|03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
研究范围:开放研究+35项覆盖检查
写入正文:03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
归并到:F069
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
JFTC review summary - demand structure of the ductile pipe market怎么使用:直接证据;一手验证:05、11、12;同业比较:08;其他用途:历史
FY3/26 interim release - mid-term management plan and lifecycle strategy怎么使用:直接 / 支持;一手验证:04;同业比较:03;其他用途:历史
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:支持证据;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
FY3/26 order environment - a full year of weak utility demand怎么使用:支持证据;外部现实校验:12;反向验证:02;专项深挖:12;同业比较:05、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 历史/同业比较(研究域08)|JFTC review summary - demand structure of the ductile pipe market;直接证据 / 支持证据 / 一手证据(研究域04) / 历史/同业比较(研究域03)|FY3/26 interim release - mid-term management plan and lifecycle strategy;支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;支持证据 / 外部现实(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域11) / 反证(研究域02) / 定向深挖(研究域12)|FY3/26 order environment - a full year of weak utility demand
完整研究记录(核对用)
研究原文:Renewal of the ageing network, including diagnosis services the company is building, replaces network expansion as the only available volume growth story; its municipal-budget pace decides whether the consolidated capacity earns scarcity value.
内部研究类型:END_MARKET
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F067|07|没有机构约束资本政策:变化只可能由大股东和董事会发起
研究范围:开放研究+35项覆盖检查
写入正文:07|没有机构约束资本政策:变化只可能由大股东和董事会发起08|每股25日元是一条固定的现金线,不是和利润挂钩的公式
归并到:F004
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接 / 支持;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
Securities report data - major shareholders at FY3/26 year-end怎么使用:支持证据;一手验证:09、24;反向验证:01
Securities report data - ownership by holder category怎么使用:支持证据;一手验证:24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas;支持证据 / 一手证据(研究域09) / 一手证据(研究域24) / 反证(研究域01)|Securities report data - major shareholders at FY3/26 year-end;支持证据 / 一手证据(研究域24)|Securities report data - ownership by holder category
完整研究记录(核对用)
研究原文:The anchor block (JFE Steel plus Tokyo Gas, ~40.25%) inside a ~48% retail unit base settles control and stability in advance; with no external governance pressure, capital-policy change would have to originate with the anchors.
内部研究类型:SETTLES_CONTROL
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F068|04|最大对手成为制造伙伴:成本收益与反垄断脆弱性来自同一个安排
研究范围:开放研究+35项覆盖检查
写入正文:04|最大对手成为制造伙伴:成本收益与反垄断脆弱性来自同一个安排
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Definitive agreement - venture structure and original schedule怎么使用:直接证据;外部现实校验:07;反向验证:33;专项深挖:07、08;同业比较:13、30;其他用途:历史
JFTC review chart - OEM scope of the joint venture怎么使用:直接 / 支持;一手验证:08
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:支持证据;一手验证:30
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域08)|Definitive agreement - venture structure and original schedule;直接证据 / 支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting
完整研究记录(核对用)
研究原文:From January 2027 Nichu Tech manufactures all of the parent's straight pipe (all diameters, all processes) and Kubota's small-diameter finished and semi-finished products (specific processes) on an OEM basis while each group sells through its own sales organisation under firewall conditions: shared fixed costs and utilisation on the factory side, continued rivalry on the sales side, real only to the extent the firewall keeps rivalry real.
内部研究类型:OEM_SUPPLY_WITH_SEPARATED_SALES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F069|03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
研究范围:开放研究+35项覆盖检查
写入正文:03|客户是各地公用事业,需求稳定但在收缩,增长只剩管网更新
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Demand environment - utility orders subdued nationwide怎么使用:直接证据;外部现实校验:05;反向验证:11、12、19;专项深挖:05、11、12
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:直接 / 支持;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
FY3/26 order environment - a full year of weak utility demand怎么使用:支持证据;外部现实校验:12;反向验证:02;专项深挖:12;同业比较:05、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域05) / 反证(研究域11) / 反证(研究域12) / 反证(研究域19) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment - utility orders subdued nationwide;直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;支持证据 / 外部现实(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域11) / 反证(研究域02) / 定向深挖(研究域12)|FY3/26 order environment - a full year of weak utility demand
完整研究记录(核对用)
研究原文:The renewal cycle is the demand regime that succeeds network expansion, paced by municipal finances and national infrastructure policy; the mid-term plan's diagnosis, parts, tools and software are built to attach services to it. Its timing decides whether consolidated Kuki capacity becomes scarce and profitable or remains surplus and merely cheaper.
内部研究类型:PACES_DEMAND
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F070|04|反垄断审批已经完成,但附带的条件是长期义务
研究范围:开放研究+35项覆盖检查
写入正文:04|反垄断审批已经完成,但附带的条件是长期义务11|反垄断条件是永久的经营约束,违规会动摇合资的合法性
归并到:F028
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
JFTC - remedies and their ongoing obligations怎么使用:直接 / 支持;外部现实校验:13;反向验证:08;专项深挖:13
Split agreement approved - EGM and January 2027 effectiveness怎么使用:支持证据;一手验证:35;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域13) / 反证(研究域08) / 定向深挖(研究域13)|JFTC - remedies and their ongoing obligations;支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness
完整研究记录(核对用)
研究原文:The firewall (access and personnel-transfer restrictions) and a JFTC-approved independent monitoring trustee, appointed before execution, form a continuing regulatory interface for the life of the venture; standing supervision lowers coordination drift but caps pricing synergy and should be priced as permanence.
内部研究类型:STANDING_CONDITIONS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F071|04|需求腰斩和产能过剩是同一件事的两面,合资是对准两者的唯一手段
研究范围:开放研究+35项覆盖检查
写入正文:04|需求腰斩和产能过剩是同一件事的两面,合资是对准两者的唯一手段
归并到:F088
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
JFTC review summary - demand structure of the ductile pipe market怎么使用:直接证据;一手验证:05、11、12;同业比较:08;其他用途:历史
Segment results - nine months to December 2025怎么使用:直接 / 支持;一手验证:02;反向验证:03、15;专项深挖:02、03
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:直接 / 支持;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
FY3/26 order environment - a full year of weak utility demand怎么使用:支持证据;外部现实校验:12;反向验证:02;专项深挖:12;同业比较:05、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 历史/同业比较(研究域08)|JFTC review summary - demand structure of the ductile pipe market;直接证据 / 支持证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025;直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;支持证据|Segment comparatives - nine months to December 2024;支持证据 / 外部现实(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域11) / 反证(研究域02) / 定向深挖(研究域12)|FY3/26 order environment - a full year of weak utility demand
完整研究记录(核对用)
研究原文:Halved demand with unchanged industry capacity produced chronic overcapacity and weak pricing power, which is why the core ductile segment was loss-making on JPY 10.6 billion of 9M FY3/26 sales: the demand structure, not execution alone, sets the margin ceiling the venture must break.
内部研究类型:CAUSES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F072|02|分割之后,上市公司会变成另一种分析对象
研究范围:开放研究+35项覆盖检查
写入正文:02|分割之后,上市公司会变成另一种分析对象06|规模最大的分部亏损,规模小得多的分部在赚钱
归并到:F025
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接 / 支持;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:直接 / 支持;一手验证:08
Split agreement approved - EGM and January 2027 effectiveness怎么使用:支持证据;一手验证:35;专项深挖:30
Production base - the Kuki works and what stays with the parent怎么使用:支持证据;外部现实校验:02、03;专项深挖:02、03
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;直接证据 / 支持证据|Accounting consequence - common-control split and continued consolidation;支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness;支持证据 / 外部现实(研究域02) / 外部现实(研究域03) / 定向深挖(研究域02) / 定向深挖(研究域03)|Production base - the Kuki works and what stays with the parent
完整研究记录(核对用)
研究原文:The split concentrates ~70% of manufacturing into a jointly owned OEM plant, so consolidated profit shifts from the parent's own lines to Nichu Tech's pricing and utilisation.
内部研究类型:CHANGES_STRUCTURE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F073|06|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
研究范围:开放研究+35项覆盖检查
写入正文:06|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Electric furnace - timeline and CO2 target怎么使用:直接证据;外部现实校验:04、10;反向验证:06;专项深挖:04、06、10
Prior-year one-offs - settlement gain and furnace trial costs怎么使用:直接 / 支持;一手验证:32;专项深挖:32;同业比较:16、32;其他用途:历史
Nine-month FY3/26 income statement and depreciation step-up怎么使用:直接证据;一手验证:16;外部现实校验:16;专项深挖:16、17;同业比较:06、17、19、20;其他用途:历史
FY3/26 third-quarter release - electric furnace conversion completed怎么使用:支持证据;一手验证:04、06、20
FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion怎么使用:支持证据;一手验证:20
FY3/27 interim release - profit and loss detail怎么使用:支持证据;一手验证:16;外部现实校验:15;反向验证:14;专项深挖:14、15、16
Cost exposure - materials, energy and labour inflation怎么使用:外部现实校验:06、14;反向验证:10、16、35;专项深挖:06、10、14;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域04) / 外部现实(研究域10) / 反证(研究域06) / 定向深挖(研究域04) / 定向深挖(研究域06) / 定向深挖(研究域10)|Electric furnace - timeline and CO2 target;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Prior-year one-offs - settlement gain and furnace trial costs;直接证据 / 一手证据(研究域16) / 外部现实(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 定向深挖(研究域16) / 定向深挖(研究域17)|Nine-month FY3/26 income statement and depreciation step-up;支持证据 / 一手证据(研究域04) / 一手证据(研究域06) / 一手证据(研究域20)|FY3/26 third-quarter release - electric furnace conversion completed;支持证据 / 一手证据(研究域20)|FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion;支持证据 / 一手证据(研究域16) / 外部现实(研究域15) / 反证(研究域14) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域16)|FY3/27 interim release - profit and loss detail;反证 / 外部现实(研究域06) / 外部现实(研究域14) / 反证(研究域10) / 反证(研究域16) / 反证(研究域35) / 定向深挖(研究域06) / 定向深挖(研究域10) / 定向深挖(研究域14)|Cost exposure - materials, energy and labour inflation
完整研究记录(核对用)
研究原文:The furnace's prior-year trial costs depressed the H1 FY3/26 base so their absence flatters the H1 FY3/27 swing, while its depreciation step-up (JPY 577 million vs 356 million over nine months) is a standing charge ahead of venture volume.
内部研究类型:BASE_EFFECT_AND_COST_STEP
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F074|01|上半年的扭亏靠价格和产品结构,销量没有回升
研究范围:开放研究+35项覆盖检查
写入正文:01|上半年的扭亏靠价格和产品结构,销量没有回升06|盈利质量在价格和结构上改善了,在销量上没有14|八个模块:估值和盈利质量给分最多,治理和资本配置最低
归并到:F015
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
FY3/27 interim release - qualitative drivers of the recovery怎么使用:直接 / 支持;一手验证:05、06、14、15
FY3/27 interim release - profit and loss detail怎么使用:直接 / 支持;一手验证:16;外部现实校验:15;反向验证:14;专项深挖:14、15、16
Demand environment - utility orders subdued nationwide怎么使用:直接 / 支持;外部现实校验:05;反向验证:11、12、19;专项深挖:05、11、12
FY3/27 interim earnings release - headline results怎么使用:支持证据;一手验证:15
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:支持证据;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:支持证据;一手验证:08
FY3/27 interim release - full-year forecast left unchanged怎么使用:支持证据;一手验证:26
Prior-year one-offs - settlement gain and furnace trial costs怎么使用:一手验证:32;专项深挖:32;同业比较:16、32;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15)|FY3/27 interim release - qualitative drivers of the recovery;直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域15) / 反证(研究域14) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域16)|FY3/27 interim release - profit and loss detail;直接证据 / 支持证据 / 外部现实(研究域05) / 反证(研究域11) / 反证(研究域12) / 反证(研究域19) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment - utility orders subdued nationwide;支持证据 / 一手证据(研究域15)|FY3/27 interim earnings release - headline results;支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged;反证 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Prior-year one-offs - settlement gain and furnace trial costs
完整研究记录(核对用)
研究原文:Price-and-mix-only recovery under subdued volume qualifies the thesis: the improvement is real but its durability is untested against the condition under which margins previously collapsed.
内部研究类型:QUALIFIES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F075|11|转型成本已经成为固定支出:利息翻倍,分红还要一起支付
研究范围:开放研究+35项覆盖检查
写入正文:11|转型成本已经成为固定支出:利息翻倍,分红还要一起支付
归并到:F027
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接 / 支持;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
Non-operating items - interest and fees rising with debt怎么使用:直接 / 支持;一手验证:32;反向验证:18、29;同业比较:14;其他用途:历史
FY3/26 cash flow compiled from the securities report怎么使用:支持证据;一手验证:17;外部现实校验:17;反向验证:20、32;专项深挖:17、20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域14) / 反证(研究域18) / 反证(研究域29)|Non-operating items - interest and fees rising with debt;支持证据 / 一手证据(研究域17) / 外部现实(研究域17) / 反证(研究域20) / 反证(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域20)|FY3/26 cash flow compiled from the securities report
完整研究记录(核对用)
研究原文:Rising borrowings raised interest expense from JPY 28 million to JPY 61 million in the nine-month comparison; the term-out solved refinancing risk but not the carrying cost.
内部研究类型:CREATES_FIXED_CHARGE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F076|06|杠杆是盈利能力的问题,不是再融资的问题
研究范围:开放研究+35项覆盖检查
写入正文:06|杠杆是盈利能力的问题,不是再融资的问题08|借款投资和固定分红是同一套资本政策,利息与分红要放在一起压力测试
归并到:F090
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 cash flow compiled from the securities report怎么使用:直接 / 支持;一手验证:17;外部现实校验:17;反向验证:20、32;专项深挖:17、20
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接 / 支持;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域17) / 反证(研究域20) / 反证(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域20)|FY3/26 cash flow compiled from the securities report;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping
完整研究记录(核对用)
研究原文:FY3/26 free cash flow of about -JPY 2,980 million was financed by +JPY 3,860 million of financing inflows, which is the origin of the borrowings now on the balance sheet.
内部研究类型:FUNDED_BY_DEBT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F077|11|下半年的风险由算术集中起来:隐含净利润只有0.17亿日元
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|下半年的风险由算术集中起来:隐含净利润只有0.17亿日元
归并到:F026
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Implied second half under the unchanged FY3/27 forecast怎么使用:直接 / 支持;反向验证:22、26、28、30;专项深挖:28、31
Forecast-carry record - the FY3/26 initial forecast versus the outcome怎么使用:直接 / 支持;外部现实校验:32;反向验证:31;专项深挖:32、35
FY3/27 interim release - full-year forecast left unchanged怎么使用:支持证据;一手验证:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域22) / 反证(研究域26) / 反证(研究域28) / 反证(研究域30) / 定向深挖(研究域28) / 定向深挖(研究域31)|Implied second half under the unchanged FY3/27 forecast;直接证据 / 支持证据 / 外部现实(研究域32) / 反证(研究域31) / 定向深挖(研究域32) / 定向深挖(研究域35)|Forecast-carry record - the FY3/26 initial forecast versus the outcome;支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged;支持证据|H1 FY3/27 results - progress against the unchanged full-year plan
完整研究记录(核对用)
研究原文:The implied H2 net profit of JPY 17 million makes the full-year print fragile to a modest stumble; the FY3/26 forecast record (revenue optimism, profit conservatism) cuts both ways.
内部研究类型:ARITHMETIC_IMPLIES_RISK
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F078|10|价格领先于业绩:两次大波动都早于基本面确认
研究范围:35项覆盖检查
写入正文:10|价格领先于业绩:两次大波动都早于基本面确认12|一份扭亏的中报被卖掉:市场付钱的对象是交付,不是公告
归并到:F033
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Post-results market reaction - the 6 November 2026 session怎么使用:直接 / 支持;一手验证:31;外部现实校验:31;专项深挖:31、34
Implied second half under the unchanged FY3/27 forecast怎么使用:直接证据;反向验证:22、26、28、30;专项深挖:28、31
FY3/27 interim release - full-year forecast left unchanged怎么使用:支持证据;一手验证:26
Recent monthly path and volume, September 2025 to October 2026 (local computation)怎么使用:支持证据;同业比较:31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|Post-results market reaction - the 6 November 2026 session;直接证据 / 反证(研究域22) / 反证(研究域26) / 反证(研究域28) / 反证(研究域30) / 定向深挖(研究域28) / 定向深挖(研究域31)|Implied second half under the unchanged FY3/27 forecast;支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged;支持证据|H1 FY3/27 results - progress against the unchanged full-year plan;支持证据 / 历史/同业比较(研究域31)|Recent monthly path and volume, September 2025 to October 2026 (local computation)
完整研究记录(核对用)
研究原文:The unchanged forecast with thin implied H2, rather than the H1 swing, is the most plausible reading of the -7.21% post-results session on 6 November 2026.
内部研究类型:EXPLAINS_MARKET_REACTION
内部来源标记:COVERAGE35 / TECHNICAL
F079|10|价格领先于业绩:两次大波动都早于基本面确认
研究范围:35项覆盖检查
写入正文:10|价格领先于业绩:两次大波动都早于基本面确认12|一份扭亏的中报被卖掉:市场付钱的对象是交付,不是公告
归并到:F033
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Recent monthly path and volume, September 2025 to October 2026 (local computation)怎么使用:直接 / 支持;同业比较:31;其他用途:历史
Post-results market reaction - the 6 November 2026 session怎么使用:直接 / 支持;一手验证:31;外部现实校验:31;专项深挖:31、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域31)|Recent monthly path and volume, September 2025 to October 2026 (local computation);直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|Post-results market reaction - the 6 November 2026 session
完整研究记录(核对用)
研究原文:The cross-lane timing inference relates public fundamentals to price response and points to the protected Technical structure as a whole; it neither flattens nor rewrites it, and the non-confirming or confirming status of that state stands independent of fundamental positivity or negativity.
内部研究类型:REFERENCES_PROTECTED_STATE_AS_WHOLE
内部来源标记:COVERAGE35 / TECHNICAL
F080|10|长期来看,价格大半时间停在1,000至2,000日元,2005年高点之后跌了十三年
写入正文:10|长期来看,价格大半时间停在1,000至2,000日元,2005年高点之后跌了十三年10|六年筑底:2020至2025年的年度低点始终守在900至1,004日元10|2025年9月放量冲高,当月即被打回,一月回踩失败后缩量下滑10|目前处在守底检验:价格贴着箱体下沿,三条均线给出上下两头的参照14|八个模块:估值和盈利质量给分最多,治理和资本配置最低15|来源以公司披露、监管文件和登记资料为主,数据截至2026年11月6日收盘
归并到:F032
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Monthly price history - span and extremes (local assembly from mirror data)怎么使用:直接 / 支持;一手验证:34;同业比较:33;其他用途:历史
Monthly moving averages at October 2026 (local computation)怎么使用:直接 / 支持;一手验证:34;反向验证:34
Residence distribution of monthly closes, 2001-2026 (local computation)怎么使用:直接 / 支持;外部现实校验:34
Annual high, low and close, 2019-2026 (local computation)怎么使用:直接 / 支持;外部现实校验:34
Recent monthly path and volume, September 2025 to October 2026 (local computation)怎么使用:直接 / 支持;同业比较:31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域34) / 历史/同业比较(研究域33)|Monthly price history - span and extremes (local assembly from mirror data);直接证据 / 支持证据 / 一手证据(研究域34) / 反证(研究域34)|Monthly moving averages at October 2026 (local computation);直接证据 / 支持证据 / 外部现实(研究域34)|Residence distribution of monthly closes, 2001-2026 (local computation);直接证据 / 支持证据 / 外部现实(研究域34)|Annual high, low and close, 2019-2026 (local computation);直接证据 / 支持证据 / 历史/同业比较(研究域31)|Recent monthly path and volume, September 2025 to October 2026 (local computation)
完整研究记录(核对用)
研究原文:The retained price-structure claim is a reference to Research Truth; the authoritative Technical interpretation is dereferenced from the protected structure.
内部研究类型:RETAINED_CLAIM_POINTS_TO_AUTHORITY
内部来源标记:TECHNICAL
F081|01|什么会推翻这个判断:28/3 期是第一个完整的验证年
研究范围:开放研究+35项覆盖检查
写入正文:01|什么会推翻这个判断:28/3 期是第一个完整的验证年11|催化剂是有日期的程序性事件,前后顺序要分清
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Catalyst calendar - EGM, split effectiveness and reporting dates怎么使用:直接 / 支持;一手验证:30;外部现实校验:30、35;专项深挖:30、35
Split agreement approved - EGM and January 2027 effectiveness怎么使用:直接 / 支持;一手验证:35;专项深挖:30
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:支持证据;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
Monthly price history - span and extremes (local assembly from mirror data)怎么使用:支持证据;一手验证:34;同业比较:33;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Catalyst calendar - EGM, split effectiveness and reporting dates;直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness;支持证据|Accounting consequence - common-control split and continued consolidation;支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;支持证据 / 一手证据(研究域34) / 历史/同业比较(研究域33)|Monthly price history - span and extremes (local assembly from mirror data)
完整研究记录(核对用)
研究原文:The April 2027 year-end release and FY3/28 guidance are the first observable tests of the falsification conditions; the December/January procedural catalysts resolve legality and structure only.
内部研究类型:TESTS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F082|09|0.42倍市净率对应的是0.9%的净资产收益率,不是资产出了问题
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|0.42倍市净率对应的是0.9%的净资产收益率,不是资产出了问题14|评分45.91,评级C:资产下限可靠,成长与回报的证据尚未出现15|证据的限度:几项关键数字来自二手汇编,若干判断受未披露信息限制
归并到:F024
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Market snapshot - price, 6 November 2026 close and derived multiples怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:27;反向验证:24;专项深挖:21、26、27、34
Book-value anchor - equity per share against the market price怎么使用:直接 / 支持;外部现实校验:21、29;反向验证:27;专项深挖:21、27、29
FY3/26 full-year results compiled from the securities report怎么使用:直接证据;一手验证:17、22;同业比较:18;其他用途:历史
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:支持证据;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:支持证据;一手验证:08
FY3/27 interim release - full-year forecast left unchanged怎么使用:支持证据;一手验证:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域27) / 反证(研究域24) / 定向深挖(研究域21) / 定向深挖(研究域26) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market snapshot - price, 6 November 2026 close and derived multiples;直接证据 / 支持证据 / 外部现实(研究域21) / 外部现实(研究域29) / 反证(研究域27) / 定向深挖(研究域21) / 定向深挖(研究域27) / 定向深挖(研究域29)|Book-value anchor - equity per share against the market price;直接证据 / 一手证据(研究域17) / 一手证据(研究域22) / 历史/同业比较(研究域18)|FY3/26 full-year results compiled from the securities report;支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged
完整研究记录(核对用)
研究原文:The 0.42x-book price is consistent with 0.9% ROE; the thesis needs venture-era ROE in mid-single digits for the same book to support a higher multiple before any earnings growth.
内部研究类型:DEFINES_REPRICING_ROOM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F083|07|没有机构约束资本政策:变化只可能由大股东和董事会发起
研究范围:开放研究+35项覆盖检查
写入正文:07|没有机构约束资本政策:变化只可能由大股东和董事会发起08|每股25日元是一条固定的现金线,不是和利润挂钩的公式
归并到:F004
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接 / 支持;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
Dividend decision arithmetic - JPY 25 at an 88.1% payout怎么使用:直接 / 支持;外部现实校验:26;反向验证:25;专项深挖:25、26
Securities report data - ownership by holder category怎么使用:支持证据;一手验证:24
Share history - the FY3/20 ten-for-one consolidation怎么使用:支持证据;专项深挖:01;同业比较:01、21、24、25、26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas;直接证据 / 支持证据 / 外部现实(研究域26) / 反证(研究域25) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision arithmetic - JPY 25 at an 88.1% payout;支持证据 / 一手证据(研究域24)|Securities report data - ownership by holder category;支持证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 定向深挖(研究域01)|Share history - the FY3/20 ten-for-one consolidation
完整研究记录(核对用)
研究原文:Anchor-and-board judgement, without institutional pressure, permits the flat JPY 25 dividend through a loss year alongside a debt-funded venture.
内部研究类型:PERMITS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F084|06|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
研究范围:35项覆盖检查
写入正文:06|上半年扭亏是真的,但比较基数里的一次性项目放大了摆幅
归并到:F047
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Prior-year one-offs - settlement gain and furnace trial costs怎么使用:直接 / 支持;一手验证:32;专项深挖:32;同业比较:16、32;其他用途:历史
Non-operating items - interest and fees rising with debt怎么使用:直接证据;一手验证:32;反向验证:18、29;同业比较:14;其他用途:历史
FY3/27 interim release - profit and loss detail怎么使用:直接 / 支持;一手验证:16;外部现实校验:15;反向验证:14;专项深挖:14、15、16
Cost exposure - materials, energy and labour inflation怎么使用:外部现实校验:06、14;反向验证:10、16、35;专项深挖:06、10、14;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Prior-year one-offs - settlement gain and furnace trial costs;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域14) / 反证(研究域18) / 反证(研究域29)|Non-operating items - interest and fees rising with debt;直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域15) / 反证(研究域14) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域16)|FY3/27 interim release - profit and loss detail;反证 / 外部现实(研究域06) / 外部现实(研究域14) / 反证(研究域10) / 反证(研究域16) / 反证(研究域35) / 定向深挖(研究域06) / 定向深挖(研究域10) / 定向深挖(研究域14)|Cost exposure - materials, energy and labour inflation
完整研究记录(核对用)
研究原文:One-off gains and costs in the comparative base mean headline swing exaggerates the operating change; the clean comparison is gross margin.
内部研究类型:DISTORTS_COMPARISON
内部来源标记:COVERAGE35
F085|02|分割之后,上市公司会变成另一种分析对象
研究范围:开放研究+35项覆盖检查
写入正文:02|分割之后,上市公司会变成另一种分析对象13|最优先要查清的三件事:合资的利润怎么分、有没有数值目标、半年现金流是多少14|评分45.91,评级C:资产下限可靠,成长与回报的证据尚未出现
归并到:F050
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接 / 支持;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:直接 / 支持;一手验证:08
FY3/27 interim release - full-year forecast left unchanged怎么使用:支持证据;一手验证:26
Split agreement approved - EGM and January 2027 effectiveness怎么使用:支持证据;一手验证:35;专项深挖:30
Production base - the Kuki works and what stays with the parent怎么使用:支持证据;外部现实校验:02、03;专项深挖:02、03
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged;支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness;支持证据|Accounting consequence - common-control split and continued consolidation;支持证据 / 外部现实(研究域02) / 外部现实(研究域03) / 定向深挖(研究域02) / 定向深挖(研究域03)|Production base - the Kuki works and what stays with the parent
完整研究记录(核对用)
研究原文:Until OEM pricing and savings allocation are disclosed, the thesis cannot be sized; the unknown caps confidence in the venture-profit claim.
内部研究类型:UNKNOWN_CONDITIONS_THESIS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F086|05|护城河在系统层面,产品层面很薄
研究范围:开放研究+35项覆盖检查
写入正文:05|护城河在系统层面,产品层面很薄09|市场为“交付”付钱,不为“宣布”付钱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(25项,重复标签已合并)
Corporate registry profile - identity and legal English name怎么使用:直接 / 支持;一手验证:01、23、33
FY3/27 interim earnings release - listing and share count怎么使用:直接 / 支持;一手验证:01、25
Company web profile - business description怎么使用:直接 / 支持;一手验证:02、03、10
FY3/26 third-quarter release - reportable segments怎么使用:直接 / 支持;一手验证:03、10
Segment results - nine months to December 2025怎么使用:直接 / 支持;一手验证:02;反向验证:03、15;专项深挖:02、03
Securities report data - major shareholders at FY3/26 year-end怎么使用:直接 / 支持;一手验证:09、24;反向验证:01
Securities report data - ownership by holder category怎么使用:直接 / 支持;一手验证:24
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接证据;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
FY3/27 interim release - balance sheet detail怎么使用:直接证据;一手验证:19、21;反向验证:07;专项深挖:18、19
Book-value anchor - equity per share against the market price怎么使用:直接证据;外部现实校验:21、29;反向验证:27;专项深挖:21、27、29
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接证据;一手验证:14、18、19、21、27、29
Production base - the Kuki works and what stays with the parent怎么使用:直接 / 支持;外部现实校验:02、03;专项深挖:02、03
Split agreement approved - EGM and January 2027 effectiveness怎么使用:直接 / 支持;一手验证:35;专项深挖:30
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:直接 / 支持;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
Catalyst calendar - EGM, split effectiveness and reporting dates怎么使用:直接 / 支持;一手验证:30;外部现实校验:30、35;专项深挖:30、35
Monthly price history - span and extremes (local assembly from mirror data)怎么使用:直接 / 支持;一手验证:34;同业比较:33;其他用途:历史
Five-year consolidated record from securities reports怎么使用:直接证据;一手验证:22、28;同业比较:09、10、27、34;其他用途:历史
Five-year record - sales, operating profit and EPS怎么使用:直接证据;一手验证:28;外部现实校验:22、28;专项深挖:22、28、33;同业比较:02、12、15、35;其他用途:历史
The FY3/24 peak and the two-year decline怎么使用:直接证据;外部现实校验:33;专项深挖:22、33;同业比较:22、28、29;其他用途:历史
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接 / 支持;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:直接 / 支持;一手验证:08
JFTC review summary - demand structure of the ductile pipe market怎么使用:直接证据;一手验证:05、11、12;同业比较:08;其他用途:历史
FY3/26 order environment - a full year of weak utility demand怎么使用:支持证据;外部现实校验:12;反向验证:02;专项深挖:12;同业比较:05、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域33)|Corporate registry profile - identity and legal English name;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域25)|FY3/27 interim earnings release - listing and share count;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域10)|Company web profile - business description;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域10)|FY3/26 third-quarter release - reportable segments;直接证据 / 支持证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025;直接证据 / 支持证据|Segment comparatives - nine months to December 2024;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域24) / 反证(研究域01)|Securities report data - major shareholders at FY3/26 year-end;直接证据 / 支持证据 / 一手证据(研究域24)|Securities report data - ownership by holder category;直接证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas;直接证据 / 一手证据(研究域19) / 一手证据(研究域21) / 反证(研究域07) / 定向深挖(研究域18) / 定向深挖(研究域19)|FY3/27 interim release - balance sheet detail;直接证据 / 外部现实(研究域21) / 外部现实(研究域29) / 反证(研究域27) / 定向深挖(研究域21) / 定向深挖(研究域27) / 定向深挖(研究域29)|Book-value anchor - equity per share against the market price;直接证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026;直接证据 / 支持证据 / 外部现实(研究域02) / 外部现实(研究域03) / 定向深挖(研究域02) / 定向深挖(研究域03)|Production base - the Kuki works and what stays with the parent;直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness;直接证据 / 支持证据|Accounting consequence - common-control split and continued consolidation;直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Catalyst calendar - EGM, split effectiveness and reporting dates;直接证据 / 支持证据 / 一手证据(研究域34) / 历史/同业比较(研究域33)|Monthly price history - span and extremes (local assembly from mirror data);直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域27) / 历史/同业比较(研究域34)|Five-year consolidated record from securities reports;直接证据 / 一手证据(研究域28) / 外部现实(研究域22) / 外部现实(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域33)|Five-year record - sales, operating profit and EPS;直接证据 / 外部现实(研究域33) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 定向深挖(研究域22) / 定向深挖(研究域33)|The FY3/24 peak and the two-year decline;直接证据 / 支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 历史/同业比较(研究域08)|JFTC review summary - demand structure of the ductile pipe market;支持证据 / 外部现实(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域11) / 反证(研究域02) / 定向深挖(研究域12)|FY3/26 order environment - a full year of weak utility demand
完整研究记录(核对用)
研究原文:Structural durability: durable franchise layer versus non-durable manufacturing economics|The durable core is a utility-supplier franchise since 1937 - specification positions in water, sewerage and gas networks, an installed base needing renewal, and ~JPY 10.0 billion equity with JPY 6,484 million retained earnings that carried a flat dividend through loss years without dilution. Not durable is standalone straight-pipe manufacturing in a halved, surplus-capacity market (sub-2% operating margins in two of the last three years, a loss-making core segment). The venture tries to stop the durable layer subsidising the non-durable one by mutualising manufacturing into a majority-owned plant. Every element is observable at dated points; falsifiers sit at segment profit, borrowings and the price floor.
内部研究类型:structural_durability_understanding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Holders are protected against catastrophe better than against mediocrity; the claim being bought is the venture increment above a JPY 400-600 million operating-profit normalisation.
不确定性(原始记录):The OEM pricing and savings rate are undisclosed until FY3/28.
F087|01|现价买的是合资之后的成本节约,这部分利润有多大目前无法测算
研究范围:开放研究+35项覆盖检查
写入正文:01|现价买的是合资之后的成本节约,这部分利润有多大目前无法测算02|利润是价格与成本之间的时滞价差,直管和配套业务的经济性不同
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(32项,重复标签已合并)
Corporate registry profile - identity and legal English name怎么使用:直接 / 支持;一手验证:01、23、33
FY3/27 interim earnings release - listing and share count怎么使用:直接 / 支持;一手验证:01、25
Company web profile - business description怎么使用:直接 / 支持;一手验证:02、03、10
FY3/26 third-quarter release - reportable segments怎么使用:直接 / 支持;一手验证:03、10
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:直接 / 支持;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
JFTC review summary - market definition, shares and remedies怎么使用:直接证据;一手验证:08、09、11、13
JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary怎么使用:直接证据;一手验证:13、33;反向验证:35;同业比较:04、07;其他用途:历史
Production base - the Kuki works and what stays with the parent怎么使用:直接证据;外部现实校验:02、03;专项深挖:02、03
Segment results - nine months to December 2025怎么使用:直接 / 支持;一手验证:02;反向验证:03、15;专项深挖:02、03
FY3/26 order environment - a full year of weak utility demand怎么使用:直接 / 支持;外部现实校验:12;反向验证:02;专项深挖:12;同业比较:05、11;其他用途:历史
JFTC review summary - demand structure of the ductile pipe market怎么使用:直接证据;一手验证:05、11、12;同业比较:08;其他用途:历史
Demand environment - utility orders subdued nationwide怎么使用:直接证据;外部现实校验:05;反向验证:11、12、19;专项深挖:05、11、12
FY3/27 interim release - qualitative drivers of the recovery怎么使用:直接证据;一手验证:05、06、14、15
FY3/26 interim release - mid-term management plan and lifecycle strategy怎么使用:直接 / 支持;一手验证:04;同业比较:03;其他用途:历史
Cost exposure - materials, energy and labour inflation怎么使用:直接证据;外部现实校验:06、14;反向验证:10、16、35;专项深挖:06、10、14
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:14、18、19、21、27、29
Five-year record - sales, operating profit and EPS怎么使用:直接 / 支持;一手验证:28;外部现实校验:22、28;专项深挖:22、28、33;同业比较:02、12、15、35;其他用途:历史
The FY3/24 peak and the two-year decline怎么使用:直接 / 支持;外部现实校验:33;专项深挖:22、33;同业比较:22、28、29;其他用途:历史
Five-year consolidated record from securities reports怎么使用:直接 / 支持;一手验证:22、28;同业比较:09、10、27、34;其他用途:历史
Working capital at the interim date怎么使用:直接证据;外部现实校验:19;反向验证:17;专项深挖:19
FY3/27 interim release - balance sheet detail怎么使用:直接证据;一手验证:19、21;反向验证:07;专项深挖:18、19
Book-value anchor - equity per share against the market price怎么使用:直接证据;外部现实校验:21、29;反向验证:27;专项深挖:21、27、29
FY3/26 full-year results compiled from the securities report怎么使用:直接 / 支持;一手验证:17、22;同业比较:18;其他用途:历史
Securities report data - major shareholders at FY3/26 year-end怎么使用:直接 / 支持;一手验证:09、24;反向验证:01
Securities report data - ownership by holder category怎么使用:直接 / 支持;一手验证:24
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接 / 支持;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
Officers and employees - EDINET-compiled data怎么使用:直接证据;一手验证:23;外部现实校验:23;专项深挖:23、24;同业比较:23;其他用途:历史
Dividend decision arithmetic - JPY 25 at an 88.1% payout怎么使用:直接 / 支持;外部现实校验:26;反向验证:25;专项深挖:25、26
Share history - the FY3/20 ten-for-one consolidation怎么使用:直接 / 支持;专项深挖:01;同业比较:01、21、24、25、26;其他用途:历史
Dividend decision for FY3/26 - stable-dividend policy怎么使用:直接证据;一手验证:26、29
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接证据;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域33)|Corporate registry profile - identity and legal English name;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域25)|FY3/27 interim earnings release - listing and share count;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域10)|Company web profile - business description;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域10)|FY3/26 third-quarter release - reportable segments;直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13)|JFTC review summary - market definition, shares and remedies;直接证据 / 一手证据(研究域13) / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域07) / 反证(研究域35)|JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary;直接证据 / 外部现实(研究域02) / 外部现实(研究域03) / 定向深挖(研究域02) / 定向深挖(研究域03)|Production base - the Kuki works and what stays with the parent;直接证据 / 支持证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025;直接证据 / 支持证据 / 外部现实(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域11) / 反证(研究域02) / 定向深挖(研究域12)|FY3/26 order environment - a full year of weak utility demand;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 历史/同业比较(研究域08)|JFTC review summary - demand structure of the ductile pipe market;直接证据 / 外部现实(研究域05) / 反证(研究域11) / 反证(研究域12) / 反证(研究域19) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment - utility orders subdued nationwide;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15)|FY3/27 interim release - qualitative drivers of the recovery;直接证据 / 支持证据 / 一手证据(研究域04) / 历史/同业比较(研究域03)|FY3/26 interim release - mid-term management plan and lifecycle strategy;直接证据 / 外部现实(研究域06) / 外部现实(研究域14) / 反证(研究域10) / 反证(研究域16) / 反证(研究域35) / 定向深挖(研究域06) / 定向深挖(研究域10) / 定向深挖(研究域14)|Cost exposure - materials, energy and labour inflation;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026;直接证据 / 支持证据|Segment comparatives - nine months to December 2024;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域22) / 外部现实(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域33)|Five-year record - sales, operating profit and EPS;直接证据 / 支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 定向深挖(研究域22) / 定向深挖(研究域33)|The FY3/24 peak and the two-year decline;直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域27) / 历史/同业比较(研究域34)|Five-year consolidated record from securities reports;直接证据 / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|Working capital at the interim date;直接证据 / 一手证据(研究域19) / 一手证据(研究域21) / 反证(研究域07) / 定向深挖(研究域18) / 定向深挖(研究域19)|FY3/27 interim release - balance sheet detail;直接证据 / 外部现实(研究域21) / 外部现实(研究域29) / 反证(研究域27) / 定向深挖(研究域21) / 定向深挖(研究域27) / 定向深挖(研究域29)|Book-value anchor - equity per share against the market price;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域22) / 历史/同业比较(研究域18)|FY3/26 full-year results compiled from the securities report;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域24) / 反证(研究域01)|Securities report data - major shareholders at FY3/26 year-end;直接证据 / 支持证据 / 一手证据(研究域24)|Securities report data - ownership by holder category;直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas;直接证据 / 一手证据(研究域23) / 外部现实(研究域23) / 历史/同业比较(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域24)|Officers and employees - EDINET-compiled data;直接证据 / 支持证据 / 外部现实(研究域26) / 反证(研究域25) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision arithmetic - JPY 25 at an 88.1% payout;直接证据 / 支持证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 定向深挖(研究域01)|Share history - the FY3/20 ten-for-one consolidation;直接证据 / 一手证据(研究域26) / 一手证据(研究域29)|Dividend decision for FY3/26 - stable-dividend policy;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping
完整研究记录(核对用)
研究原文:Durable Business Portrait: a sub-scale utility supplier, asset-backed, thin-spread and register-anchored|Foundation before change: how the company earns (a lagged price-versus-cost spread on flat volume), converts cash (heavy receivables and finished goods, thin operating cash), allocates capital (flat dividend, debt-funded investment, no equity action), and repairs itself (asset floor, retained earnings, attached services layer) - with returns near zero on a JPY 10 billion equity base. Current change (venture, furnace, H1 swing) overlays this foundation rather than replacing it.
内部研究类型:durable_business_portrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Capital efficiency, not growth, is the valuation question; mid-cycle margin sets value, not the H1 FY3/27 print or the trough.
不确定性(原始记录):Product-level profit, payables detail and ROIC are not disclosed.
F088|04|需求腰斩和产能过剩是同一件事的两面,合资是对准两者的唯一手段
研究范围:开放研究+35项覆盖检查
写入正文:04|需求腰斩和产能过剩是同一件事的两面,合资是对准两者的唯一手段
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(15项,重复标签已合并)
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:直接 / 支持;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
FY3/26 order environment - a full year of weak utility demand怎么使用:直接 / 支持;外部现实校验:12;反向验证:02;专项深挖:12;同业比较:05、11;其他用途:历史
JFTC review summary - demand structure of the ductile pipe market怎么使用:直接证据;一手验证:05、11、12;同业比较:08;其他用途:历史
Demand environment - utility orders subdued nationwide怎么使用:直接证据;外部现实校验:05;反向验证:11、12、19;专项深挖:05、11、12
Segment results - nine months to December 2025怎么使用:直接 / 支持;一手验证:02;反向验证:03、15;专项深挖:02、03
FY3/26 third-quarter release - reportable segments怎么使用:直接证据;一手验证:03、10
JFTC review summary - market definition, shares and remedies怎么使用:直接 / 支持;一手验证:08、09、11、13
JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary怎么使用:直接 / 支持;一手验证:13、33;反向验证:35;同业比较:04、07;其他用途:历史
Definitive agreement - company split and manufacturing joint venture with Kubota怎么使用:直接 / 支持;一手验证:07
Definitive agreement - venture structure and original schedule怎么使用:直接证据;外部现实校验:07;反向验证:33;专项深挖:07、08;同业比较:13、30;其他用途:历史
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接 / 支持;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:直接 / 支持;一手验证:08
FY3/26 interim release - mid-term management plan and lifecycle strategy怎么使用:直接证据;一手验证:04;同业比较:03;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;直接证据 / 支持证据 / 外部现实(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域11) / 反证(研究域02) / 定向深挖(研究域12)|FY3/26 order environment - a full year of weak utility demand;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 历史/同业比较(研究域08)|JFTC review summary - demand structure of the ductile pipe market;直接证据 / 外部现实(研究域05) / 反证(研究域11) / 反证(研究域12) / 反证(研究域19) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment - utility orders subdued nationwide;直接证据 / 支持证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025;直接证据 / 支持证据|Segment comparatives - nine months to December 2024;直接证据 / 一手证据(研究域03) / 一手证据(研究域10)|FY3/26 third-quarter release - reportable segments;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13)|JFTC review summary - market definition, shares and remedies;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域07) / 反证(研究域35)|JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary;直接证据 / 支持证据 / 一手证据(研究域07)|Definitive agreement - company split and manufacturing joint venture with Kubota;直接证据 / 外部现实(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域08)|Definitive agreement - venture structure and original schedule;直接证据 / 支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;直接证据|Accounting consequence - common-control split and continued consolidation;直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03)|FY3/26 interim release - mid-term management plan and lifecycle strategy
完整研究记录(核对用)
研究原文:Demand structure and industry structure are one fact read twice|The halved market (demand) is the surplus capacity (supply) that made the core segment loss-making; the venture is the single instrument addressed to both, so market-structure and segment domains share one falsifier in the first venture-era segment print.
内部研究类型:cross_domain_causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Success is cost earnings from utilisation; failure is capacity-sharing that socialises the industry's problem.
不确定性(原始记录):Kubota's plant closures matching the consolidation is not yet of record.
F089|06|电炉既是成本事件,也是监管资产,又是合资的共用平台
研究范围:开放研究+35项覆盖检查
写入正文:06|电炉既是成本事件,也是监管资产,又是合资的共用平台
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(16项,重复标签已合并)
FY3/26 third-quarter release - electric furnace conversion completed怎么使用:直接 / 支持;一手验证:04、06、20
FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion怎么使用:直接 / 支持;一手验证:20
Capacity investment of about JPY 2.7 billion at Kuki怎么使用:直接证据;外部现实校验:20;专项深挖:20
Electric furnace - timeline and CO2 target怎么使用:直接证据;外部现实校验:04、10;反向验证:06;专项深挖:04、06、10
Cost exposure - materials, energy and labour inflation怎么使用:直接证据;外部现实校验:06、14;反向验证:10、16、35;专项深挖:06、10、14;其他用途:反证
FY3/27 interim release - qualitative drivers of the recovery怎么使用:直接证据;一手验证:05、06、14、15
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接证据;一手验证:14、18、19、21、27、29
Definitive agreement - company split and manufacturing joint venture with Kubota怎么使用:直接 / 支持;一手验证:07
JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary怎么使用:直接 / 支持;一手验证:13、33;反向验证:35;同业比较:04、07;其他用途:历史
JFTC review summary - market definition, shares and remedies怎么使用:直接 / 支持;一手验证:08、09、11、13
Definitive agreement - venture structure and original schedule怎么使用:直接证据;外部现实校验:07;反向验证:33;专项深挖:07、08;同业比较:13、30;其他用途:历史
FY3/27 interim release - profit and loss detail怎么使用:直接 / 支持;一手验证:16;外部现实校验:15;反向验证:14;专项深挖:14、15、16
Prior-year one-offs - settlement gain and furnace trial costs怎么使用:直接 / 支持;一手验证:32;专项深挖:32;同业比较:16、32;其他用途:历史
Non-operating items - interest and fees rising with debt怎么使用:直接证据;一手验证:32;反向验证:18、29;同业比较:14;其他用途:历史
Nine-month FY3/26 income statement and depreciation step-up怎么使用:直接证据;一手验证:16;外部现实校验:16;专项深挖:16、17;同业比较:06、17、19、20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域06) / 一手证据(研究域20)|FY3/26 third-quarter release - electric furnace conversion completed;直接证据 / 支持证据 / 一手证据(研究域20)|FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion;直接证据 / 外部现实(研究域20) / 定向深挖(研究域20)|Capacity investment of about JPY 2.7 billion at Kuki;直接证据 / 外部现实(研究域04) / 外部现实(研究域10) / 反证(研究域06) / 定向深挖(研究域04) / 定向深挖(研究域06) / 定向深挖(研究域10)|Electric furnace - timeline and CO2 target;直接证据 / 反证 / 外部现实(研究域06) / 外部现实(研究域14) / 反证(研究域10) / 反证(研究域16) / 反证(研究域35) / 定向深挖(研究域06) / 定向深挖(研究域10) / 定向深挖(研究域14)|Cost exposure - materials, energy and labour inflation;直接证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15)|FY3/27 interim release - qualitative drivers of the recovery;直接证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域07)|Definitive agreement - company split and manufacturing joint venture with Kubota;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域07) / 反证(研究域35)|JFTC review closure - Kubota acquisition of a stake in the new manufacturing subsidiary;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域11) / 一手证据(研究域13)|JFTC review summary - market definition, shares and remedies;直接证据 / 外部现实(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域08)|Definitive agreement - venture structure and original schedule;直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域15) / 反证(研究域14) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域16)|FY3/27 interim release - profit and loss detail;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Prior-year one-offs - settlement gain and furnace trial costs;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域14) / 反证(研究域18) / 反证(研究域29)|Non-operating items - interest and fees rising with debt;直接证据 / 一手证据(研究域16) / 外部现实(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 定向深挖(研究域16) / 定向深挖(研究域17)|Nine-month FY3/26 income statement and depreciation step-up;直接证据|Accounting consequence - common-control split and continued consolidation
完整研究记录(核对用)
研究原文:The electric furnace as cost event, regulatory asset and venture platform|The furnace is a cost event (trial costs, then coke-to-electricity shift and depreciation step-up), the efficiency the JFTC credited under its Green Guidelines, and the physical platform of the shared plant; a change in any one reading changes the other two.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Venture utilisation must absorb the stepped-up depreciation or the asset is stranded.
不确定性(原始记录):Total furnace cost and net electricity-tariff effect not visible in a full year.
F090|06|杠杆是盈利能力的问题,不是再融资的问题
研究范围:开放研究+35项覆盖检查
写入正文:06|杠杆是盈利能力的问题,不是再融资的问题08|借款投资和固定分红是同一套资本政策,利息与分红要放在一起压力测试
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(16项,重复标签已合并)
FY3/26 cash flow compiled from the securities report怎么使用:直接 / 支持;一手验证:17;外部现实校验:17;反向验证:20、32;专项深挖:17、20
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接 / 支持;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
Non-operating items - interest and fees rising with debt怎么使用:直接 / 支持;一手验证:32;反向验证:18、29;同业比较:14;其他用途:历史
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:14、18、19、21、27、29
Dividend decision arithmetic - JPY 25 at an 88.1% payout怎么使用:直接 / 支持;外部现实校验:26;反向验证:25;专项深挖:25、26
Share history - the FY3/20 ten-for-one consolidation怎么使用:直接 / 支持;专项深挖:01;同业比较:01、21、24、25、26;其他用途:历史
Dividend decision for FY3/26 - stable-dividend policy怎么使用:直接证据;一手验证:26、29
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接 / 支持;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
Securities report data - ownership by holder category怎么使用:直接 / 支持;一手验证:24
Officers and employees - EDINET-compiled data怎么使用:直接证据;一手验证:23;外部现实校验:23;专项深挖:23、24;同业比较:23;其他用途:历史
FY3/27 interim release - full-year forecast left unchanged怎么使用:直接 / 支持;一手验证:26
Implied second half under the unchanged FY3/27 forecast怎么使用:直接 / 支持;反向验证:22、26、28、30;专项深挖:28、31
FY3/26 full-year results compiled from the securities report怎么使用:直接证据;一手验证:17、22;同业比较:18;其他用途:历史
Five-year consolidated record from securities reports怎么使用:直接证据;一手验证:22、28;同业比较:09、10、27、34;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域17) / 反证(研究域20) / 反证(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域20)|FY3/26 cash flow compiled from the securities report;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域14) / 反证(研究域18) / 反证(研究域29)|Non-operating items - interest and fees rising with debt;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026;直接证据 / 支持证据 / 外部现实(研究域26) / 反证(研究域25) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision arithmetic - JPY 25 at an 88.1% payout;直接证据 / 支持证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 定向深挖(研究域01)|Share history - the FY3/20 ten-for-one consolidation;直接证据 / 一手证据(研究域26) / 一手证据(研究域29)|Dividend decision for FY3/26 - stable-dividend policy;直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas;直接证据 / 支持证据 / 一手证据(研究域24)|Securities report data - ownership by holder category;直接证据 / 一手证据(研究域23) / 外部现实(研究域23) / 历史/同业比较(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域24)|Officers and employees - EDINET-compiled data;直接证据 / 支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged;直接证据 / 支持证据|H1 FY3/27 results - progress against the unchanged full-year plan;直接证据 / 支持证据 / 反证(研究域22) / 反证(研究域26) / 反证(研究域28) / 反证(研究域30) / 定向深挖(研究域28) / 定向深挖(研究域31)|Implied second half under the unchanged FY3/27 forecast;直接证据|FY3/27 first-quarter release and the initial full-year forecast;直接证据 / 一手证据(研究域17) / 一手证据(研究域22) / 历史/同业比较(研究域18)|FY3/26 full-year results compiled from the securities report;直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域27) / 历史/同业比较(研究域34)|Five-year consolidated record from securities reports
完整研究记录(核对用)
研究原文:Debt-funded transition and the flat dividend as one capital policy|Borrowings of JPY 10,399 million funded the furnace and venture while JPY 25 was paid from retained earnings through a loss year: the board chose to gear the transition and stabilise the payout simultaneously, so interest and dividend must be stress-tested together against thin implied H2 earnings. Debt rose, interest doubled and FY3/26 FCF was about -JPY 2,980 million, so the venture must produce savings.
内部研究类型:cross_domain_policy_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):No dilution or buyback support; per-share value moves only with earnings and the multiple; adjustment runs through interest cover, not equity issuance.
不确定性(原始记录):Covenants, rate structure and venture-era payout policy unknown.
F091|07|股东结构、交易清淡与价格走势互相印证,但因果只是推断
研究范围:开放研究+35项覆盖检查
写入正文:07|股东结构、交易清淡与价格走势互相印证,但因果只是推断10|股东结构与价格形态的联合推断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(13项,重复标签已合并)
Securities report data - major shareholders at FY3/26 year-end怎么使用:直接 / 支持;一手验证:09、24;反向验证:01
Securities report data - ownership by holder category怎么使用:直接 / 支持;一手验证:24
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接 / 支持;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
Officers and employees - EDINET-compiled data怎么使用:直接证据;一手验证:23;外部现实校验:23;专项深挖:23、24;同业比较:23;其他用途:历史
Dividend decision arithmetic - JPY 25 at an 88.1% payout怎么使用:直接 / 支持;外部现实校验:26;反向验证:25;专项深挖:25、26
Share history - the FY3/20 ten-for-one consolidation怎么使用:直接 / 支持;专项深挖:01;同业比较:01、21、24、25、26;其他用途:历史
Dividend decision for FY3/26 - stable-dividend policy怎么使用:直接证据;一手验证:26、29
Monthly price history - span and extremes (local assembly from mirror data)怎么使用:直接 / 支持;一手验证:34;同业比较:33;其他用途:历史
Monthly moving averages at October 2026 (local computation)怎么使用:直接 / 支持;一手验证:34;反向验证:34
Residence distribution of monthly closes, 2001-2026 (local computation)怎么使用:直接 / 支持;外部现实校验:34
Annual high, low and close, 2019-2026 (local computation)怎么使用:直接 / 支持;外部现实校验:34
Recent monthly path and volume, September 2025 to October 2026 (local computation)怎么使用:直接 / 支持;同业比较:31;其他用途:历史
Post-results market reaction - the 6 November 2026 session怎么使用:直接 / 支持;一手验证:31;外部现实校验:31;专项深挖:31、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域24) / 反证(研究域01)|Securities report data - major shareholders at FY3/26 year-end;直接证据 / 支持证据 / 一手证据(研究域24)|Securities report data - ownership by holder category;直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas;直接证据 / 一手证据(研究域23) / 外部现实(研究域23) / 历史/同业比较(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域24)|Officers and employees - EDINET-compiled data;直接证据 / 支持证据 / 外部现实(研究域26) / 反证(研究域25) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision arithmetic - JPY 25 at an 88.1% payout;直接证据 / 支持证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 定向深挖(研究域01)|Share history - the FY3/20 ten-for-one consolidation;直接证据 / 一手证据(研究域26) / 一手证据(研究域29)|Dividend decision for FY3/26 - stable-dividend policy;直接证据 / 支持证据 / 一手证据(研究域34) / 历史/同业比较(研究域33)|Monthly price history - span and extremes (local assembly from mirror data);直接证据 / 支持证据 / 一手证据(研究域34) / 反证(研究域34)|Monthly moving averages at October 2026 (local computation);直接证据 / 支持证据 / 外部现实(研究域34)|Residence distribution of monthly closes, 2001-2026 (local computation);直接证据 / 支持证据 / 外部现实(研究域34)|Annual high, low and close, 2019-2026 (local computation);直接证据 / 支持证据 / 历史/同业比较(研究域31)|Recent monthly path and volume, September 2025 to October 2026 (local computation);直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|Post-results market reaction - the 6 November 2026 session
完整研究记录(核对用)
研究原文:Register shape explains governance conduct and price behaviour|Two industrial anchors (~40%) and a ~48% retail unit base let the company undertake a decade-scale restructuring without market pressure and produce a stock that moves in climaxes and air pockets (September 2025; 6 November 2026) because the float is thin and uninstitutional. This is a cross-lane reading that references retained price evidence without redefining the protected Technical State.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Control is uncontestable and liquidity thin: permanent inputs to sizing and to the multiple.
不确定性(原始记录):Anchor intentions undisclosed; causality between float structure and price shape is inferential.
F092|09|市场为“交付”付钱,不为“宣布”付钱
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(14项,重复标签已合并)
Forecast-carry record - the FY3/26 initial forecast versus the outcome怎么使用:直接 / 支持;外部现实校验:32;反向验证:31;专项深挖:32、35
FY3/27 interim release - full-year forecast left unchanged怎么使用:直接 / 支持;一手验证:26
Implied second half under the unchanged FY3/27 forecast怎么使用:直接 / 支持;反向验证:22、26、28、30;专项深挖:28、31
Recent monthly path and volume, September 2025 to October 2026 (local computation)怎么使用:直接 / 支持;同业比较:31;其他用途:历史
Post-results market reaction - the 6 November 2026 session怎么使用:直接 / 支持;一手验证:31;外部现实校验:31;专项深挖:31、34
Market snapshot - price, 6 November 2026 close and derived multiples怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:27;反向验证:24;专项深挖:21、26、27、34
Book-value anchor - equity per share against the market price怎么使用:直接 / 支持;外部现实校验:21、29;反向验证:27;专项深挖:21、27、29
Non-operating items - interest and fees rising with debt怎么使用:直接证据;一手验证:32;反向验证:18、29;同业比较:14;其他用途:历史
Prior-year one-offs - settlement gain and furnace trial costs怎么使用:直接证据;一手验证:32;专项深挖:32;同业比较:16、32;其他用途:历史
FY3/27 interim release - profit and loss detail怎么使用:直接证据;一手验证:16;外部现实校验:15;反向验证:14;专项深挖:14、15、16
Nine-month FY3/26 income statement and depreciation step-up怎么使用:直接证据;一手验证:16;外部现实校验:16;专项深挖:16、17;同业比较:06、17、19、20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域32) / 反证(研究域31) / 定向深挖(研究域32) / 定向深挖(研究域35)|Forecast-carry record - the FY3/26 initial forecast versus the outcome;直接证据|FY3/27 first-quarter release and the initial full-year forecast;直接证据 / 支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged;直接证据 / 支持证据|H1 FY3/27 results - progress against the unchanged full-year plan;直接证据 / 支持证据 / 反证(研究域22) / 反证(研究域26) / 反证(研究域28) / 反证(研究域30) / 定向深挖(研究域28) / 定向深挖(研究域31)|Implied second half under the unchanged FY3/27 forecast;直接证据 / 支持证据 / 历史/同业比较(研究域31)|Recent monthly path and volume, September 2025 to October 2026 (local computation);直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|Post-results market reaction - the 6 November 2026 session;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域27) / 反证(研究域24) / 定向深挖(研究域21) / 定向深挖(研究域26) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market snapshot - price, 6 November 2026 close and derived multiples;直接证据 / 支持证据 / 外部现实(研究域21) / 外部现实(研究域29) / 反证(研究域27) / 定向深挖(研究域21) / 定向深挖(研究域27) / 定向深挖(研究域29)|Book-value anchor - equity per share against the market price;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域14) / 反证(研究域18) / 反证(研究域29)|Non-operating items - interest and fees rising with debt;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Prior-year one-offs - settlement gain and furnace trial costs;直接证据 / 一手证据(研究域16) / 外部现实(研究域15) / 反证(研究域14) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域16)|FY3/27 interim release - profit and loss detail;直接证据 / 一手证据(研究域16) / 外部现实(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 定向深挖(研究域16) / 定向深挖(研究域17)|Nine-month FY3/26 income statement and depreciation step-up;直接证据|Accounting consequence - common-control split and continued consolidation
完整研究记录(核对用)
研究原文:Forecast record, accounting reading and expectations|Revenue optimism carried unchanged (FY3/26) beside profit conservatism teaches the market to distrust the top line and test the bottom line, which is why an unchanged forecast with 72.3% progress was sold, not celebrated, in November 2026.
内部研究类型:cross_domain_expectation_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Burden of proof has migrated from the story to the prints; positioning is asymmetric if the venture works, unforgiving of delay.
不确定性(原始记录):No analyst consensus; expectations are read from price and multiples (inference).
F093|01|现价买的是合资之后的成本节约,这部分利润有多大目前无法测算
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|现价买的是合资之后的成本节约,这部分利润有多大目前无法测算09|市场为“交付”付钱,不为“宣布”付钱14|评分45.91,评级C:资产下限可靠,成长与回报的证据尚未出现
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(44项,重复标签已合并)
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接 / 支持;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:直接 / 支持;一手验证:08
FY3/27 interim release - full-year forecast left unchanged怎么使用:直接 / 支持;一手验证:26
JFTC - market structure and shares in small-diameter ductile pipe怎么使用:直接 / 支持;一手验证:35;外部现实校验:08、09、11;反向验证:05、13;专项深挖:05、08、09、11、13
Split agreement approved - EGM and January 2027 effectiveness怎么使用:直接 / 支持;一手验证:35;专项深挖:30
Catalyst calendar - EGM, split effectiveness and reporting dates怎么使用:直接 / 支持;一手验证:30;外部现实校验:30、35;专项深挖:30、35
Monthly price history - span and extremes (local assembly from mirror data)怎么使用:直接 / 支持;一手验证:34;同业比较:33;其他用途:历史
Market snapshot - price, 6 November 2026 close and derived multiples怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:27;反向验证:24;专项深挖:21、26、27、34
Book-value anchor - equity per share against the market price怎么使用:直接 / 支持;外部现实校验:21、29;反向验证:27;专项深挖:21、27、29
Five-year consolidated record from securities reports怎么使用:直接证据;一手验证:22、28;同业比较:09、10、27、34;其他用途:历史
Five-year record - sales, operating profit and EPS怎么使用:直接证据;一手验证:28;外部现实校验:22、28;专项深挖:22、28、33;同业比较:02、12、15、35;其他用途:历史
The FY3/24 peak and the two-year decline怎么使用:直接证据;外部现实校验:33;专项深挖:22、33;同业比较:22、28、29;其他用途:历史
Segment results - nine months to December 2025怎么使用:直接证据;一手验证:02;反向验证:03、15;专项深挖:02、03
FY3/26 full-year results compiled from the securities report怎么使用:直接证据;一手验证:17、22;同业比较:18;其他用途:历史
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接证据;一手验证:14、18、19、21、27、29
FY3/27 interim release - qualitative drivers of the recovery怎么使用:直接 / 支持;一手验证:05、06、14、15
FY3/27 interim earnings release - headline results怎么使用:直接 / 支持;一手验证:15
FY3/27 interim release - profit and loss detail怎么使用:直接 / 支持;一手验证:16;外部现实校验:15;反向验证:14;专项深挖:14、15、16
Demand environment - utility orders subdued nationwide怎么使用:直接 / 支持;外部现实校验:05;反向验证:11、12、19;专项深挖:05、11、12
Prior-year one-offs - settlement gain and furnace trial costs怎么使用:一手验证:32;专项深挖:32;同业比较:16、32;其他用途:反证、历史
JFTC - remedies and their ongoing obligations怎么使用:直接 / 支持;外部现实校验:13;反向验证:08;专项深挖:13
FY3/26 order environment - a full year of weak utility demand怎么使用:直接 / 支持;外部现实校验:12;反向验证:02;专项深挖:12;同业比较:05、11;其他用途:历史
JFTC review summary - demand structure of the ductile pipe market怎么使用:直接证据;一手验证:05、11、12;同业比较:08;其他用途:历史
Implied second half under the unchanged FY3/27 forecast怎么使用:直接 / 支持;反向验证:22、26、28、30;专项深挖:28、31
Forecast-carry record - the FY3/26 initial forecast versus the outcome怎么使用:直接 / 支持;外部现实校验:32;反向验证:31;专项深挖:32、35
Non-operating items - interest and fees rising with debt怎么使用:直接 / 支持;一手验证:32;反向验证:18、29;同业比较:14;其他用途:历史
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接 / 支持;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
FY3/26 cash flow compiled from the securities report怎么使用:直接证据;一手验证:17;外部现实校验:17;反向验证:20、32;专项深挖:17、20
Production base - the Kuki works and what stays with the parent怎么使用:支持证据;外部现实校验:02、03;专项深挖:02、03
FY3/26 interim release - mid-term management plan and lifecycle strategy怎么使用:直接证据;一手验证:04;同业比较:03;其他用途:历史
Mid-term plan - lifecycle initiatives without published numerical targets怎么使用:直接证据;反向验证:04;专项深挖:04
FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion怎么使用:直接证据;一手验证:20
Capacity investment of about JPY 2.7 billion at Kuki怎么使用:直接证据;外部现实校验:20;专项深挖:20
Nine-month FY3/26 income statement and depreciation step-up怎么使用:直接证据;一手验证:16;外部现实校验:16;专项深挖:16、17;同业比较:06、17、19、20;其他用途:历史
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接证据;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
Officers and employees - EDINET-compiled data怎么使用:直接证据;一手验证:23;外部现实校验:23;专项深挖:23、24;同业比较:23;其他用途:历史
Recent monthly path and volume, September 2025 to October 2026 (local computation)怎么使用:直接证据;同业比较:31;其他用途:历史
Dividend decision arithmetic - JPY 25 at an 88.1% payout怎么使用:直接证据;外部现实校验:26;反向验证:25;专项深挖:25、26
Dividend decision for FY3/26 - stable-dividend policy怎么使用:直接证据;一手验证:26、29
Definitive agreement - venture structure and original schedule怎么使用:直接证据;外部现实校验:07;反向验证:33;专项深挖:07、08;同业比较:13、30;其他用途:历史
Working capital at the interim date怎么使用:直接证据;外部现实校验:19;反向验证:17;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;直接证据 / 支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged;直接证据 / 支持证据 / 一手证据(研究域35) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 反证(研究域05) / 反证(研究域13) / 定向深挖(研究域05) / 定向深挖(研究域08) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域13)|JFTC - market structure and shares in small-diameter ductile pipe;直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness;直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域30) / 外部现实(研究域35) / 定向深挖(研究域30) / 定向深挖(研究域35)|Catalyst calendar - EGM, split effectiveness and reporting dates;直接证据 / 支持证据 / 一手证据(研究域34) / 历史/同业比较(研究域33)|Monthly price history - span and extremes (local assembly from mirror data);直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域27) / 反证(研究域24) / 定向深挖(研究域21) / 定向深挖(研究域26) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market snapshot - price, 6 November 2026 close and derived multiples;直接证据 / 支持证据 / 外部现实(研究域21) / 外部现实(研究域29) / 反证(研究域27) / 定向深挖(研究域21) / 定向深挖(研究域27) / 定向深挖(研究域29)|Book-value anchor - equity per share against the market price;直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域27) / 历史/同业比较(研究域34)|Five-year consolidated record from securities reports;直接证据 / 一手证据(研究域28) / 外部现实(研究域22) / 外部现实(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域33)|Five-year record - sales, operating profit and EPS;直接证据 / 外部现实(研究域33) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 定向深挖(研究域22) / 定向深挖(研究域33)|The FY3/24 peak and the two-year decline;直接证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025;直接证据 / 一手证据(研究域17) / 一手证据(研究域22) / 历史/同业比较(研究域18)|FY3/26 full-year results compiled from the securities report;直接证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15)|FY3/27 interim release - qualitative drivers of the recovery;直接证据 / 支持证据 / 一手证据(研究域15)|FY3/27 interim earnings release - headline results;直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域15) / 反证(研究域14) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域16)|FY3/27 interim release - profit and loss detail;直接证据 / 支持证据 / 外部现实(研究域05) / 反证(研究域11) / 反证(研究域12) / 反证(研究域19) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment - utility orders subdued nationwide;反证 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Prior-year one-offs - settlement gain and furnace trial costs;直接证据 / 支持证据|Accounting consequence - common-control split and continued consolidation;直接证据 / 支持证据 / 外部现实(研究域13) / 反证(研究域08) / 定向深挖(研究域13)|JFTC - remedies and their ongoing obligations;直接证据 / 支持证据 / 外部现实(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域11) / 反证(研究域02) / 定向深挖(研究域12)|FY3/26 order environment - a full year of weak utility demand;直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域12) / 历史/同业比较(研究域08)|JFTC review summary - demand structure of the ductile pipe market;直接证据 / 支持证据 / 反证(研究域22) / 反证(研究域26) / 反证(研究域28) / 反证(研究域30) / 定向深挖(研究域28) / 定向深挖(研究域31)|Implied second half under the unchanged FY3/27 forecast;直接证据 / 支持证据 / 外部现实(研究域32) / 反证(研究域31) / 定向深挖(研究域32) / 定向深挖(研究域35)|Forecast-carry record - the FY3/26 initial forecast versus the outcome;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域14) / 反证(研究域18) / 反证(研究域29)|Non-operating items - interest and fees rising with debt;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping;直接证据 / 一手证据(研究域17) / 外部现实(研究域17) / 反证(研究域20) / 反证(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域20)|FY3/26 cash flow compiled from the securities report;支持证据 / 外部现实(研究域02) / 外部现实(研究域03) / 定向深挖(研究域02) / 定向深挖(研究域03)|Production base - the Kuki works and what stays with the parent;直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03)|FY3/26 interim release - mid-term management plan and lifecycle strategy;直接证据 / 反证(研究域04) / 定向深挖(研究域04)|Mid-term plan - lifecycle initiatives without published numerical targets;直接证据|Segment comparatives - nine months to December 2024;直接证据 / 一手证据(研究域20)|FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion;直接证据 / 外部现实(研究域20) / 定向深挖(研究域20)|Capacity investment of about JPY 2.7 billion at Kuki;直接证据 / 一手证据(研究域16) / 外部现实(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 定向深挖(研究域16) / 定向深挖(研究域17)|Nine-month FY3/26 income statement and depreciation step-up;直接证据|FY3/27 first-quarter release and the initial full-year forecast;直接证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas;直接证据 / 一手证据(研究域23) / 外部现实(研究域23) / 历史/同业比较(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域24)|Officers and employees - EDINET-compiled data;直接证据 / 历史/同业比较(研究域31)|Recent monthly path and volume, September 2025 to October 2026 (local computation);直接证据 / 外部现实(研究域26) / 反证(研究域25) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision arithmetic - JPY 25 at an 88.1% payout;直接证据 / 一手证据(研究域26) / 一手证据(研究域29)|Dividend decision for FY3/26 - stable-dividend policy;直接证据 / 外部现实(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域08)|Definitive agreement - venture structure and original schedule;直接证据 / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|Working capital at the interim date
完整研究记录(核对用)
研究原文:Thesis, valuation bridge and dated falsification|Cost-consolidation claim: one plant, two makers' volume, separated sales and a parent keeping the steadier layer. Strongest counter-evidence - price-and-mix-only recovery, subdued volume, thin implied H2, rising interest, antitrust constraint, structural demand decline - conditions confidence and sizing; failure leaves a leveraged, asset-backed micro-cap at a deserved discount, not distress.
内部研究类型:thesis_falsification_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Two-step upside (ROE then multiple) versus a decade of ~0.4x book.
不确定性(原始记录):Confidence ~0.7; decisive unknowns held by management until FY3/28.
F094|06|五年的利润是一个利润率周期,销售额几乎没动
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(23项,重复标签已合并)
Five-year record - sales, operating profit and EPS怎么使用:直接 / 支持;一手验证:28;外部现实校验:22、28;专项深挖:22、28、33;同业比较:02、12、15、35;其他用途:历史
The FY3/24 peak and the two-year decline怎么使用:直接 / 支持;外部现实校验:33;专项深挖:22、33;同业比较:22、28、29;其他用途:历史
Five-year consolidated record from securities reports怎么使用:直接 / 支持;一手验证:22、28;同业比较:09、10、27、34;其他用途:历史
FY3/26 full-year results compiled from the securities report怎么使用:直接 / 支持;一手验证:17、22;同业比较:18;其他用途:历史
FY3/27 interim earnings release - headline results怎么使用:直接 / 支持;一手验证:15
Quarterly path of FY3/27 - Q1 and Q2 standalone results怎么使用:直接 / 支持;一手验证:12
Quarterly path arithmetic - Q1 loss to Q2 profit in FY3/27怎么使用:直接 / 支持;专项深挖:15
FY3/27 interim release - profit and loss detail怎么使用:直接 / 支持;一手验证:16;外部现实校验:15;反向验证:14;专项深挖:14、15、16
Prior-year one-offs - settlement gain and furnace trial costs怎么使用:直接 / 支持;一手验证:32;专项深挖:32;同业比较:16、32;其他用途:反证、历史
FY3/27 interim release - qualitative drivers of the recovery怎么使用:直接 / 支持;一手验证:05、06、14、15
Cost exposure - materials, energy and labour inflation怎么使用:直接证据;外部现实校验:06、14;反向验证:10、16、35;专项深挖:06、10、14;其他用途:反证
Demand environment - utility orders subdued nationwide怎么使用:直接 / 支持;外部现实校验:05;反向验证:11、12、19;专项深挖:05、11、12
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接证据;一手验证:14、18、19、21、27、29
Non-operating items - interest and fees rising with debt怎么使用:直接证据;一手验证:32;反向验证:18、29;同业比较:14;其他用途:历史
Nine-month FY3/26 income statement and depreciation step-up怎么使用:直接证据;一手验证:16;外部现实校验:16;专项深挖:16、17;同业比较:06、17、19、20;其他用途:历史
Segment results - nine months to December 2025怎么使用:直接证据;一手验证:02;反向验证:03、15;专项深挖:02、03
Electric furnace - timeline and CO2 target怎么使用:直接证据;外部现实校验:04、10;反向验证:06;专项深挖:04、06、10
FY3/26 third-quarter release - electric furnace conversion completed怎么使用:支持证据;一手验证:04、06、20
FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion怎么使用:支持证据;一手验证:20
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:支持证据;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:支持证据;一手验证:08
FY3/27 interim release - full-year forecast left unchanged怎么使用:支持证据;一手验证:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域22) / 外部现实(研究域28) / 历史/同业比较(研究域02) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域28) / 定向深挖(研究域33)|Five-year record - sales, operating profit and EPS;直接证据 / 支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 定向深挖(研究域22) / 定向深挖(研究域33)|The FY3/24 peak and the two-year decline;直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域27) / 历史/同业比较(研究域34)|Five-year consolidated record from securities reports;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域22) / 历史/同业比较(研究域18)|FY3/26 full-year results compiled from the securities report;直接证据 / 支持证据 / 一手证据(研究域15)|FY3/27 interim earnings release - headline results;直接证据 / 支持证据 / 一手证据(研究域12)|Quarterly path of FY3/27 - Q1 and Q2 standalone results;直接证据 / 支持证据 / 定向深挖(研究域15)|Quarterly path arithmetic - Q1 loss to Q2 profit in FY3/27;直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域15) / 反证(研究域14) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域16)|FY3/27 interim release - profit and loss detail;直接证据 / 支持证据 / 反证 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域32)|Prior-year one-offs - settlement gain and furnace trial costs;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15)|FY3/27 interim release - qualitative drivers of the recovery;直接证据 / 反证 / 外部现实(研究域06) / 外部现实(研究域14) / 反证(研究域10) / 反证(研究域16) / 反证(研究域35) / 定向深挖(研究域06) / 定向深挖(研究域10) / 定向深挖(研究域14)|Cost exposure - materials, energy and labour inflation;直接证据 / 支持证据 / 外部现实(研究域05) / 反证(研究域11) / 反证(研究域12) / 反证(研究域19) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域12)|Demand environment - utility orders subdued nationwide;直接证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域14) / 反证(研究域18) / 反证(研究域29)|Non-operating items - interest and fees rising with debt;直接证据 / 一手证据(研究域16) / 外部现实(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 定向深挖(研究域16) / 定向深挖(研究域17)|Nine-month FY3/26 income statement and depreciation step-up;直接证据|Accounting consequence - common-control split and continued consolidation;直接证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025;直接证据 / 外部现实(研究域04) / 外部现实(研究域10) / 反证(研究域06) / 定向深挖(研究域04) / 定向深挖(研究域06) / 定向深挖(研究域10)|Electric furnace - timeline and CO2 target;支持证据 / 一手证据(研究域04) / 一手证据(研究域06) / 一手证据(研究域20)|FY3/26 third-quarter release - electric furnace conversion completed;支持证据 / 一手证据(研究域20)|FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion;支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged
完整研究记录(核对用)
研究原文:Lagged spread ratchet: margin cycle on flat sales|Costs inflate continuously, prices revise in steps, depreciation steps up with each investment: profit quality is highest just after a revision round, where H1 FY3/27 sits. Volume is unchanged, so operating leverage multiplies recovery and decline alike; normalised margin lies mid-cycle.
内部研究类型:profit_quality_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Do not annualise the H1 print or the trough; underwrite flat-volume, price-variable earnings.
不确定性(原始记录):Split between price, mix and base effect not quantified; order backlog undisclosed.
F095|13|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口
研究范围:开放研究+35项覆盖检查
写入正文:13|第三层问题:治理全貌、2025年冲高的原因和其他披露缺口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(27项,重复标签已合并)
FY3/27 interim release - subsequent events: timetable and accounting怎么使用:直接 / 支持;一手验证:30
JFTC review chart - OEM scope of the joint venture怎么使用:直接 / 支持;一手验证:08
Split agreement approved - EGM and January 2027 effectiveness怎么使用:直接 / 支持;一手验证:35;专项深挖:30
FY3/26 interim release - mid-term management plan and lifecycle strategy怎么使用:直接证据;一手验证:04;同业比较:03;其他用途:历史
Mid-term plan - lifecycle initiatives without published numerical targets怎么使用:直接证据;反向验证:04;专项深挖:04
FY3/27 interim release - balance sheet at 30 September 2026怎么使用:直接证据;一手验证:14、18、19、21、27、29
FY3/26 cash flow compiled from the securities report怎么使用:直接证据;一手验证:17;外部现实校验:17;反向验证:20、32;专项深挖:17、20
Segment results - nine months to December 2025怎么使用:直接证据;一手验证:02;反向验证:03、15;专项深挖:02、03
FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion怎么使用:直接证据;一手验证:20
Capacity investment of about JPY 2.7 billion at Kuki怎么使用:直接证据;外部现实校验:20;专项深挖:20
Nine-month FY3/26 income statement and depreciation step-up怎么使用:直接证据;一手验证:16;外部现实校验:16;专项深挖:16、17;同业比较:06、17、19、20;其他用途:历史
Forecast-carry record - the FY3/26 initial forecast versus the outcome怎么使用:直接证据;外部现实校验:32;反向验证:31;专项深挖:32、35
Anchor holders and register - JFE Steel and Tokyo Gas怎么使用:直接证据;外部现实校验:01、24;反向验证:09、21、23;专项深挖:01、09、23、24
Officers and employees - EDINET-compiled data怎么使用:直接证据;一手验证:23;外部现实校验:23;专项深挖:23、24;同业比较:23;其他用途:历史
Recent monthly path and volume, September 2025 to October 2026 (local computation)怎么使用:直接证据;同业比较:31;其他用途:历史
Monthly price history - span and extremes (local assembly from mirror data)怎么使用:直接证据;一手验证:34;同业比较:33;其他用途:历史
Dividend decision arithmetic - JPY 25 at an 88.1% payout怎么使用:直接证据;外部现实校验:26;反向验证:25;专项深挖:25、26
Dividend decision for FY3/26 - stable-dividend policy怎么使用:直接证据;一手验证:26、29
Borrowings - year-end FY3/26 position and maturity reshaping怎么使用:直接证据;一手验证:18、25;外部现实校验:18、25;专项深挖:18、25、29
Definitive agreement - venture structure and original schedule怎么使用:直接证据;外部现实校验:07;反向验证:33;专项深挖:07、08;同业比较:13、30;其他用途:历史
JFTC - remedies and their ongoing obligations怎么使用:直接证据;外部现实校验:13;反向验证:08;专项深挖:13
Working capital at the interim date怎么使用:直接证据;外部现实校验:19;反向验证:17;专项深挖:19
FY3/27 interim release - full-year forecast left unchanged怎么使用:支持证据;一手验证:26
Production base - the Kuki works and what stays with the parent怎么使用:支持证据;外部现实校验:02、03;专项深挖:02、03
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|FY3/27 interim release - subsequent events: timetable and accounting;直接证据 / 支持证据 / 一手证据(研究域08)|JFTC review chart - OEM scope of the joint venture;直接证据 / 支持证据 / 一手证据(研究域35) / 定向深挖(研究域30)|Split agreement approved - EGM and January 2027 effectiveness;直接证据 / 支持证据|Accounting consequence - common-control split and continued consolidation;直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03)|FY3/26 interim release - mid-term management plan and lifecycle strategy;直接证据 / 反证(研究域04) / 定向深挖(研究域04)|Mid-term plan - lifecycle initiatives without published numerical targets;直接证据 / 一手证据(研究域14) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域27) / 一手证据(研究域29)|FY3/27 interim release - balance sheet at 30 September 2026;直接证据 / 一手证据(研究域17) / 外部现实(研究域17) / 反证(研究域20) / 反证(研究域32) / 定向深挖(研究域17) / 定向深挖(研究域20)|FY3/26 cash flow compiled from the securities report;直接证据 / 一手证据(研究域02) / 反证(研究域03) / 反证(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域03)|Segment results - nine months to December 2025;直接证据|Segment comparatives - nine months to December 2024;直接证据 / 一手证据(研究域20)|FY3/26 interim release - joint-venture capacity investment of about JPY 2.7 billion;直接证据 / 外部现实(研究域20) / 定向深挖(研究域20)|Capacity investment of about JPY 2.7 billion at Kuki;直接证据 / 一手证据(研究域16) / 外部现实(研究域16) / 历史/同业比较(研究域06) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 定向深挖(研究域16) / 定向深挖(研究域17)|Nine-month FY3/26 income statement and depreciation step-up;直接证据 / 外部现实(研究域32) / 反证(研究域31) / 定向深挖(研究域32) / 定向深挖(研究域35)|Forecast-carry record - the FY3/26 initial forecast versus the outcome;直接证据|FY3/27 first-quarter release and the initial full-year forecast;直接证据 / 外部现实(研究域01) / 外部现实(研究域24) / 反证(研究域09) / 反证(研究域21) / 反证(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域09) / 定向深挖(研究域23) / 定向深挖(研究域24)|Anchor holders and register - JFE Steel and Tokyo Gas;直接证据 / 一手证据(研究域23) / 外部现实(研究域23) / 历史/同业比较(研究域23) / 定向深挖(研究域23) / 定向深挖(研究域24)|Officers and employees - EDINET-compiled data;直接证据 / 历史/同业比较(研究域31)|Recent monthly path and volume, September 2025 to October 2026 (local computation);直接证据 / 一手证据(研究域34) / 历史/同业比较(研究域33)|Monthly price history - span and extremes (local assembly from mirror data);直接证据 / 外部现实(研究域26) / 反证(研究域25) / 定向深挖(研究域25) / 定向深挖(研究域26)|Dividend decision arithmetic - JPY 25 at an 88.1% payout;直接证据 / 一手证据(研究域26) / 一手证据(研究域29)|Dividend decision for FY3/26 - stable-dividend policy;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 外部现实(研究域18) / 外部现实(研究域25) / 定向深挖(研究域18) / 定向深挖(研究域25) / 定向深挖(研究域29)|Borrowings - year-end FY3/26 position and maturity reshaping;直接证据 / 外部现实(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域08)|Definitive agreement - venture structure and original schedule;直接证据 / 外部现实(研究域13) / 反证(研究域08) / 定向深挖(研究域13)|JFTC - remedies and their ongoing obligations;直接证据 / 外部现实(研究域19) / 反证(研究域17) / 定向深挖(研究域19)|Working capital at the interim date;支持证据 / 一手证据(研究域26)|FY3/27 interim release - full-year forecast left unchanged;支持证据 / 外部现实(研究域02) / 外部现实(研究域03) / 定向深挖(研究域02) / 定向深挖(研究域03)|Production base - the Kuki works and what stays with the parent
完整研究记录(核对用)
研究原文:Research Debt carried to the next Review|Priority-1 debt (OEM economics and post-split disclosure, mid-term targets, H1 cash flow) bears directly on the thesis; priority 2-3 items refine guidance credibility, capex sizing, governance and the cause of the 2025 pulse. Disclosure gaps are not negative evidence.
内部研究类型:research_debt_cluster
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Each debt item caps confidence in a specific judgment until the dated disclosures arrive.
不确定性(原始记录):Public-research paths are exhausted for current disclosures; resolution is future filings and releases.
F096|10|长期来看,价格大半时间停在1,000至2,000日元,2005年高点之后跌了十三年
写入正文:10|长期来看,价格大半时间停在1,000至2,000日元,2005年高点之后跌了十三年10|2025年9月放量冲高,当月即被打回,一月回踩失败后缩量下滑10|目前处在守底检验:价格贴着箱体下沿,三条均线给出上下两头的参照10|守底检验靠什么确认,什么会让它失败
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (RESEARCH_TRUTH.technical_state)
内部研究类型:protected_technical_synthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | 5949944bdaeaf702f3e55a871b1b78f977313ca2 |
| Delivery Commit SHA | 5949944bdaeaf702f3e55a871b1b78f977313ca2 |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | e23e97fd-4ef9-5c43-9772-9861ab34382f |
| Canonical Revision | 1 |