零部件业务已经显示出重新定价的能力:2026年3月期利润增长145.5%至109.17亿日元,约占分部利润的76%。自有资本比率维持在51%至53%,股息按净资产股息率(DOE)2.5%上下的公式累进,2027年3月期指引每股135日元,按3,130日元计股息率4.3%。市净率0.45至0.46倍,资产负债表被按对折定价。
7231
トピー工業株式会社(Topy Industries, Limited)
公司:トピー工業株式会社(Topy Industries, Limited),代码7231,在东证 Prime 市场与名古屋证券交易所 Premier 市场上市。 公司一句话:主营电炉炼钢(以废钢为原料)和钢铁制品,并向下游延伸到钢制与铝制车轮、工程机械用履带底盘部件;同时经营合成云母、建设、房地产和体育设施等小业务。 估值简报:股价2,980日元(2026年11月6日收盘),总市值717.5亿日元(按含库存股的发行股数)。预测PER 8.4倍(按2027年3月期(FY3/27)修订后每股收益356.04日元)。实绩PBR 0.45倍(按2026年3月期(FY3/26)期末每股净资产6,660.64日元)。ROE 7.3%(2026年3月期实绩,含证券出售收益)。预测股息率4.53%(2027年3月期每股股息135日元)。EV/EBITDA 5.7倍。EV 1,111.8亿日元=总市值+2026年9月30日净有息负债394.27亿日元。EBITDA 195.6亿日元=2026年3月期营业利润77.83亿日元+折旧117.77亿日元,两个口径的期间不同。
最近亮点:2026年11月6日披露的2027年3月期上半期(4–9月)业绩:销售额增长9.7%,营业利润增长10.9%至36.11亿日元,是上调后半年指引15亿日元的两倍多。零部件利润74.11亿日元创半年新高,钢铁亏损12.83亿日元。公司把全年营业利润指引上调到85亿日元,等于要求下半期赚到48.89亿日元。11月9日股价上涨5.03%,收于3,130日元。
最大的变数是盈利质量。2027年3月期上半期零部件利润里含一笔公司称为一次性、却没有披露金额的调整收益,74.11亿日元(利润率6.7%)有多少是真实的利润率重置,目前无法确定。钢铁则完全暴露在废钢与售价的价差上,下半期计划一旦落空,钢铁补不了位。
Kabugami Score 62.81/100(Score Version V3.2),评级 B,行动:持有观察,不追高。资产负债表和股息公式给了较厚的底部,但零部件临时收益的金额、钢铁价差,以及价格能否站上3,710日元都还没有答案,整体把握一般。 当前动作:持有观察,不追高。基本面上,资产负债表和股息公式提供了较厚的底部,价格约为账面价值的0.45至0.46倍;但盈利质量(一次性收益与零部件临时收益的金额)和钢铁价差都还没有答案,价格结构也处在“下行已结束、延续尚未确认”的阶段。已持有者继续持有,靠约4.3%至4.5%的股息等待;新增仓位更适合在2027年3月期下半期业绩兑现(营业利润约48.9亿日元、钢铁至少不亏)、零部件利润率在不依赖临时收益时仍然守住之后,或价格有效收于3,710日元之上时再分批考虑。若下半期计划落空且钢铁仍然亏损、零部件利润率回落到约4%以下、持股比例未在2027年3月前降到10%以下,或月收盘跌破2,615日元,应重新评估。
报告目录
01|投资问题与当前结论
01.1|结论:持有观察,不追高,价格里没有钢铁复苏,也没有计划失败
Kabugami Score 62.81/100,评级 B(Score Version V3.2),行动是持有观察,不追高。这个结论围绕一个问题:集团现在靠哪块业务赚钱,这个来源守不守得住。
答案是利润重心已经从钢铁移到零部件。2026年3月期营业利润增长46.8%至77.83亿日元,增量全部来自零部件,钢铁利润反而下降61.1%。零部件又撑起一套与账面价值挂钩的股东回报,而股价只有账面价值的0.45至0.46倍。市场仍在按旧的、由钢铁主导的周期股定价。
证据的分量并不均匀。已被观察到的事实只有一个:零部件重新定价的能力。已在执行的程序有一个:把政策持股变现,用于还款、分红和回购。尚未证明的是钢铁价差能否回归。
这个判断有一项主要限制。2027年3月期上半期零部件利润里含一笔临时调整收益,金额没有披露,所以零部件的真实利润率只能说低于报告的6.7%。
01.2|框架值得长期持有,盈利水平要按周期中位数定价
耐久的是框架,不是某一年的利润。框架包括六项:从废钢到合格零部件的一体化链条,零部件重新定价的能力,51%至53%的自有资本比率,可以出售的证券组合,锚定账面价值的回报公式,以及股东名册上的联盟伙伴。这六项在钢铁差的年份(2022年3月期、2027年3月期上半期)和好的年份(2024年3月期、2026年3月期)都被观察到,不取决于周期方向。
不耐久的是利润本身。过去五年营业利润在亏损17.06亿日元到盈利104.40亿日元之间摆动;报告净利润依赖证券出售;最新的零部件数字里又含一笔临时收益。三者都说明利润水平会继续跟着废钢价差和工程机械周期走。
所以判断分两层。框架可以持有,用来积累账面价值,并享受零部件的重新定价。盈利则按周期中位数估,大致是营业利润50亿至60亿日元。要上调这个口径,需要两个条件同时出现:钢铁在一个完整的废钢周期里至少守住盈亏平衡;零部件利润率在经历一轮价格谈判后,没有会计辅助仍然成立。
目前这两个条件都没有被检验。零部件的新定价框架只观察了大约两年,既没有经过完整的整车厂谈判,也没有经过完整的废钢周期。
01.3|什么会推翻这个判断,什么会加强它
推翻条件有四个。第一,下半期计划落空:2027年3月期第三季度钢铁仍在亏损。第二,零部件利润率在下一轮整车厂谈判中,或在临时调整效应年化消失后,回落到4%以下,说明这次重置带有会计和周期成分。第三,2027年3月前政策持股占净资产的比例没有通过出售降到10%以下。第四,价格上月线收盘跌破2,615日元,并明显跌破60个月均线(约2,234日元)。
加强判断的信号同样具体:下半期利润达到或超过修订后的指引,钢铁至少不亏;新的中期计划把剔除一次性收益后的ROE目标定在6.0%以上;月线收盘站上3,710日元。
除零部件定价谈判外,其余条件大约两个季度内都能观察到,谈判检验要到新中期计划的第一年才有结果。如果推翻条件始终没有出现,预期路径是账面价值积累加4.3%左右的股息,估值上修是额外收益。
02|公司本质与商业模式
02.1|集团是一条从废钢到零部件的链,只能看合并报表
トピー工業(Topy Industries, Limited,代码7231)是一家一体化的钢铁到零部件制造集团:丰桥工厂用电炉把废钢炼成钢,再做成钢铁制品,并在下游生产钢制与铝制车轮和工程机械用履带底盘部件。公司创立于1921年,现在的形态来自1964年的合并;股本209.83亿日元,已发行24,077,510股,合并子公司32家、关联公司4家,在7个国家有16个海外生产基地。
母公司单体的营业利润只有18.80亿日元,利润主要在子公司赚到,母公司净利润则靠股息和同样的证券出售收益撑起来。因此合并报表是唯一有意义的经济范围。少数股东权益和子公司层面的归属没有逐项拆出,集团边界目前只能从公司披露文件读取。
02.2|2026年3月期利润增长全部来自零部件,钢铁在拖后腿
2026年3月期销售额2,977.50亿日元,同比下降1.0%,营业利润增长46.8%至77.83亿日元,合并营业利润率2.6%。表面是一份增长的成绩单,拆开以后是另一个故事:零部件利润增长145.5%至109.17亿日元,利润率5.4%;钢铁利润下降61.1%至24.70亿日元,利润率2.8%,原因是废钢成本上升和修理费用。
这意味着集团的发动机已经换了:靠下游的利润率改革,取代了过去由钢铁担任的角色。钢铁分部里修理费用有多大,零部件的增长中结构改革与重新定价各占多少,披露文件没有分开量化。
02.3|其他业务规模很小,利润率最高也最稳
合成云母、建设、房地产和体育设施合并为「其他」,2026年3月期销售额68.89亿日元,利润8.82亿日元,利润率12.8%,只占集团销售额的2%左右。它是集团里利润率最高、周期性最弱的部分,体量小到不足以移动股权价值,但说明集团有能力经营不依赖周期的业务。各项业务自身的经济性没有展开研究。
02.4|三个阶段说明零部件主导的格局还很新
这家公司的历史可以分成三段。2021至2022年是疫情与钢铁下行期,经营连续亏损,2022年4月股价触及990日元的低点。2023至2024年3月期是钢铁价格上涨的阶段,销售额升到3,344.96亿日元的峰值,营业利润升到104.40亿日元的峰值。2026年3月期是零部件利润率重置:零部件利润增长145.5%,取代钢铁成为集团的发动机,同时证券出售开始为股东回报出资。自有资本比率从39.9%升到53.0%,是这段修复的财务印记。
三段里零部件主导的格局最新,也最少经过检验,所以应当用它自己约两年的证据评价,而不是套用更长的、钢铁主导时期的平均水平。
02.5|整体面貌:一条链、一个有护城河的引擎、一层厚的资产负债表
把前面几项合起来看,集团是一条一体化的链条:利润已经下移到有认证壁垒、被重新定过价的零部件,由一套保守的资产负债表和与账面价值挂钩的回报公式托住;钢铁是对价差敏感的选择权,利润水平带有明显的周期性。
对普通股东,这意味着可以拥有资产负债表积累和重新定价能力这一框架,但应当用周期中位数而不是峰值或谷底的盈利估值。零部件的耐久性只观察了大约两年,钢铁能否撑过一个完整的废钢周期也没有被证明。
03|产品、客户与供应链
03.1|两个引擎处在两个周期:废钢价差压钢铁,零部件重新定价托集团
集团的利润链可以用一条因果线讲清。废钢成本上升立刻压缩钢铁利润,售价要靠谈判才能跟上;零部件的重新定价和工程机械的销量,在分部层面把这块损失超额补回;之后一笔结构性的总部费用,又把一个强劲的零部件年份压成一个很薄的合并利润率。
所以分部结构比集团规模更重要:合并利润取决于零部件利润率能否扛过价格谈判,以及钢铁能否停止亏损。零部件的实际常态利润率因为那笔未披露的临时收益,目前还不清楚。
03.2|钢铁利润看价差,不看销量
电炉炼钢按市场价买废钢,却按谈判价卖产品,废钢在高位停留时,利润率会被压缩,直到售价调整追上来。2026年3月期钢铁利润下降61.1%,转折发生在下半年废钢价格上行之后。2027年3月期上半期更清楚:钢铁外部销售只下降3.4%,利润却从盈利14.96亿日元摆到亏损12.83亿日元,一年之间变动27.79亿日元。
销量几乎没动,利润却摆了这么大,说明这是价差事件,不是需求恶化。钢铁分部在废钢多高的价位上才能恢复盈利,公司的涨价假设是什么,都没有披露。
03.3|零部件贡献了集团利润的大头,靠的是价格形成而不是销量
2026年3月期零部件营业利润109.17亿日元,约占142.69亿日元分部利润的76%(钢铁24.70亿日元,其他8.82亿日元)。2027年3月期上半期的74.11亿日元,已经超过整个集团上半期36.11亿日元的合并营业利润,而钢铁同期转为亏损。零部件约占分部报告收入的三分之二,利润占比更高,所以向下游迁移是周期之内一条安静的结构性趋势。
这次利润率重置来自结构改革和「可持续售价」政策,不是销量增长,所以它能否持续,要看新的价格形成机制能否守住。目前能说的是,靠需求是不够的;报告的6.7%利润率之下,实际的常态水平没有量化,也没有经过一轮整车厂谈判检验。
03.4|需求集中在工程机械周期,上一轮高峰靠的也是它
工程机械的产量带动底盘部件需求,是零部件分部目前最大的增长来源,既推动了2027年3月期上半期的超预期,也承载下半期的计划;乘用车车轮销量在2026年3月期则有所下降。这类需求来自整车厂和机械厂商的生产计划,随机械与建设周期起伏。
问题在于,目前撑起预测的需求,和撑起上一轮峰值的是同一个周期。客户集中度、订单余额和下半期的生产计划都没有披露,业务结构的分散程度因此低于表面看到的样子。
03.5|增长方向目前只是选择权,没有被价格包含,也无法估价
计划点名的增长领域包括印度和印尼的铝制车轮(轻量化加新市场)、商用车用锻造铝轮和循环利用,但没有披露投资额、产能或回报数字,所以它们是故事上的选择权,不在已被定价的盈利基础里。技术上,公司的优势是累积下来的工艺冶金能力:电炉炼钢、一体化轧制成形和铝轻量化,记录中没有研发费用数字。这能支撑向下游迁移的叙事,但撑不起增长估值。
投资论点并不依赖这些方向。它们若成功是额外收益,销量、产能、联盟条款和研发投入目前都没有证据。
04|竞争格局与产业关系
04.1|日本制铁既是最大股东,又是钢铁业务的供应方和客户
日本制铁持有23.0%的表决权(直接22.1%,合计持有0.9%;按剔除库存股的股数是22.01%),在会计上是权益法下的联盟伙伴。它向公司供应一部分原料,同时又是公司轧制加工的客户,商业联系双向存在;披露文件明确写明,它对公司经营没有承认权。
这层关系把钢铁业务在商业上与日本最大的钢厂连在一起,但没有控制。具体的交易量、定价条款和联盟经济性都没有披露,也因此很难判断这份联盟在价差下行时能提供多少缓冲。
04.2|竞争对手一侧没有可用的数据,行业地位只能靠公司自述
这份研究没有取得竞争对手的财务数据、利润率对照和第三方市场份额数据,所以无法把零部件的地位和同业放在一张表里比较,行业地位只能按公司披露定性描述。这是目前证据最薄的领域,它限制的是对护城河和相对估值的判断,不代表竞争格局本身不利。要补上这一块,需要同业利润率与份额的独立来源。
05|护城河判断
05.1|护城河只在零部件,钢铁没有
真正的护城河在零部件:车轮和底盘部件进入整车厂与工程机械厂商的认证体系,切换成本在客户一侧,在位的供应商能够留下来。但这份优势要靠定期的价格谈判才能变成利润,所以价格框架的存续和认证本身一样重要。
反面证据同样清楚:零部件利润里含未披露金额的临时调整收益,钢铁上半期亏损12.83亿日元,说明集团另一半没有任何保护。钢铁没有差异化,利润跟着废钢价差走。两块业务不应该按同一档护城河估值,把有保护的零部件和没有保护的钢铁平均起来,会同时高估和低估。
这个判断没有第三方份额数据或竞争对手财务作对照,新的价格框架也没有经过一轮完整谈判。
05.2|护城河要兑现,取决于新价格框架撑过一轮谈判和一个废钢周期
认证带来的切换摩擦,是零部件能把原材料成本转嫁出去的前提;重新定价靠的是结构改革加售价政策,而不是销量。护城河在这里的成立条件有两个:价格形成机制在整车厂和机械厂商的年度谈判中不被收回,以及废钢周期回落时仍然成立。
目前这套机制只被观察了大约两年,钢铁能否撑过完整的废钢周期也没有被证明。如果它被证明是结构性的,集团利润的底盘会明显高于过去钢铁主导时期;如果只是会计与周期叠加,股价会回到纯价差周期股的定价。
06|财务质量与现金流
06.1|利润增长要先剥掉三层水分,才看得到经营趋势
2026年3月期净利润101.51亿日元,比经常利润86.18亿日元高出一截,原因是一笔71.43亿日元的政策持股出售收益,部分被7.54亿日元的减值和6.35亿日元的处置损失抵消。经常利润里含约8.35亿日元的持续性股息与权益法收益,所以它是更干净的锚。2027年3月期修订后的经常利润预测为86亿日元,与上年基本持平,净利润则预期下降,因为预测里没有假设出售持股;5月的初始指引里,净利润预计下降40.9%。
持股出售已经连续三个报告期补充报告利润,2027年3月期上半期又有13.71亿日元的收益,正在成为一种习惯,但可出售的持股是有限的。
三种机制同时在抬高报告利润:证券出售收益、用减值抵消收益,以及上半期零部件的会计方法变更。看经营趋势,需要把三者剥掉,再去看零部件利润率重置和钢铁价差。可持续的持股出售收益有多大,取决于剩余可出售的持股和股价。
06.2|ROE 7.3%过了目标线,是被证券出售收益抬上去的
2026年3月期报告ROE为7.3%,高于中期计划最终年度不低于6.0%的目标,但那是71.43亿日元证券出售收益推上去的,公司自己也说剔除这些收益之后的水平还需要提高。
按本次研究的粗略推算,经常利润86.18亿日元对约1,450亿日元的净资产,税前回报在6%上下,等于刚好踩在目标线上,而不是越过了它(税前税后及期间口径为本次研究的近似)。因此6.0%是仍需守住的底线,不是已经完成的里程碑。
投入资本回报率(ROIC)没有序列可查,公司2026年3月的资本成本应对文件已找到,但内容没有提取。在剔除资产出售的经常ROE明显越过目标之前,股价对账面价值的折价有一个合理的内核。
06.3|2027年3月期上半期:利润翻倍超预期,质量问题落在零部件上
上半期销售额增长9.7%,营业利润增长10.9%至36.11亿日元,是修订后半年指引15亿日元的两倍多。结构又一次翻转:零部件利润74.11亿日元创历史新高,利润率6.7%,外部销售增长16.2%;钢铁则亏损12.83亿日元。
节奏上,第一季度营业利润只有6.93亿日元,废钢价格飙升压住了钢铁价差,零部件的强势已经让公司8月上调了半年指引;第二季度一个季度就赚到29.18亿日元,零部件的价格调整在这个季度落地。这个先弱后强的节奏正是计划的设计,所以质量问题不在需求,而在零部件这个数字本身。
零部件上半期利润还含一笔临时的传导方式调整收益,公司标为一次性,没有披露金额。其中销量、汇率与这笔调整收益各占多少,也没有拆分。
06.4|零部件利润里那笔临时收益有多大,是最先要补上的缺口
公司把向整车厂客户反映原材料价格的方式做了变更,这在上半期零部件利润里产生一笔临时调整收益。公司点名了三个驱动因素:销量、汇率和这笔调整,同时说明调整是一次性的,但没有量化,所以零部件上半期真实利润率低于报告的6.7%,低多少未知。这是目前记录里最关键的计量缺口。
如果这笔收益很大,6.7%就高估了这次利润率重置,推翻条件中零部件利润率回落到4%以下的情形会更近。解决它的证据,是年度证券报告里的分部注释,或公司的说明材料。
06.5|总部费用每年吞掉六十多亿日元,把好年份也压成薄利润率
分部利润合计142.69亿日元,合并营业利润77.83亿日元,中间每年有60亿至65亿日元消失:总部与调整项消耗了分部利润的约45%,占销售额2.2%。2027年3月期上半期年化后量级相同,说明这是结构性的,不是一年的事件。
所以即便零部件创出5.4%的最好分部利润率,合并利润率也只有2.6%。薄利润率意味着每一个点的分部利润率变化,都会明显推动合并结果。这条调整线里中央费用与内部抵消各占多少,没有拆分。
06.6|收入看分部组合,不看增长率
2026年3月期收入下降1.0%,原因是钢铁价格和结构下降,零部件因重新定价增长5.7%;2027年3月期上半期收入增长9.7%,由零部件销量带动(外部销售增长16.2%),钢铁外部销售在涨价后仍下降3.4%。分部合计含分部间销售(钢铁约107亿日元),因此比重只是示意。
每一块日元从钢铁制品移到合格零部件,利润率大致翻倍,所以集团销售额持平,利润能力仍可能上升。全年的外部销售口径和分业务的量价拆分没有披露。
06.7|一个废钢价格,同时推动利润、库存、借款和现金
废钢在高位停留,压缩钢铁价差的同时,也把库存价值抬高了几十亿日元,并推高同一时期的借款,利润表、资产负债表和现金流在同一方向上被一个市场价格同时牵动。
数字上,库存从2026年3月期末的575.09亿日元升到2027年3月期上半期末的649.41亿日元,半年增加74.32亿日元,主要是原料价值;应收款465.44亿日元,应付款293.05亿日元。总资产增加136.94亿日元,自有资本比率从53.0%降到51.0%。借款净增约191亿日元,其中70亿日元债券到期被置换成银行借款。
2026年3月期经营现金流131.29亿日元,现金创造是真实的;上半期库存增长则是同一机制的反向体现。上半期现金流量表没有披露,现金消耗是从资产负债表变动推算的;库存增加反映原料涨价,不能当作需求强劲的证据。库存计价方法、是否套期,以及库存的所有权与变现性,都没有核实。
06.8|资产负债表够厚,能把周期挡在偿付能力之外
2026年3月期末自有资本比率53.0%,五年前是39.9%,2026年9月降到51.0%;净资产1,468.43亿日元。生息负债587亿日元左右,现金294亿日元左右,净负债约290亿日元;2026年9月在库存垫资和债券置换后升到约394亿日元,相对净资产仍然温和。投资有价证券267.13亿日元(半年末286.80亿日元),土地账面152.44亿日元,提供非经营性支撑;年末的市值自有资本比率为23.1%。
每股净资产在钢铁亏损的半年里仍从6,660.64日元升到6,863.81日元。剩余180亿日元债券的到期安排、借款契约条件,以及母公司对子公司现金的可动用程度,都没有核实。
06.9|经营现金流够覆盖投资,但回报由出售证券共同出资
2026年3月期经营现金流131.29亿日元,覆盖99.11亿日元的资本开支,后者低于117.77亿日元的折旧,是一种收割型的投入姿态。但投资现金流转正,完全来自124.46亿日元的证券出售款;融资现金流流出136.78亿日元,用于还款、股息和回购。
自由现金流为正但不算大,2026年3月期偏高的股东回报,有一部分是资产出售出资的。2027年3月期的经营现金流能否在不再出售资产的情况下同时覆盖资本开支和上调后的股息,目前未知。上半期的现金流量表没有披露。
07|股东、董事与治理
07.1|最大股东是商业伙伴,控制权事件的可能性很低
日本制铁的23.0%表决权,加上它既是原料供应方又是轧制加工客户的双向商业联系,使它更像锚定股东而不是控制者;披露文件写明它对公司经营没有承认权。结果是敌意或突发性的股东名册变动可能性很低,治理上的争论主要围绕经营,而不是控制权。
同时库存股占比升到12.0%,让剩下的流通股东更集中。大股东变动报告和完整股东名册,只检查到锚定股东为止。这个结构也意味着,估值上修必须来自盈利和资本政策,不太可能来自名册层面的事件。
07.2|治理方向与低市净率公司被要求的方向一致
2026年3月宣布转为监查等委员会设置公司,2025年5月废止收购防御措施,更新并公布了资本成本应对文件,调整子公司组合,每年8月回购。这些动作和市场对低市净率公司的要求一致,对0.46倍账面价值的估值是温和的支持。
它们影响的是估值倍数,不是近期盈利,所以不是论点的驱动力。董事会转型后的独立董事比例与技能构成,目前没有提取到可核实的材料。
08|资本政策
08.1|持股削减在出售上有进展,在比例上没有
政策持股占合并净资产的比例,2026年3月是11.3%(之前为14.8%)。低于10%的目标因股价上涨而落空,期限延到2027年3月。出售是真实的:2026年3月期有71.43亿日元收益,2027年3月期上半期又有13.71亿日元;2026年3月期124.46亿日元的出售款,流向了还款、股息和回购。
比例之所以落后,是因为剩下的持股在升值,投资有价证券账面到2026年9月又升至286.80亿日元。这个程序用出售量衡量是有进展的,用比例衡量还没有。2027年3月前比例能否通过出售,而不是价格波动降到10%以下,尚未确定;第二次延期会损害这套转换模式的可信度。
08.2|股息锚定账面价值,不锚定利润
公司在中期经营计划「Active & Challenge 2027」期间采用累进股息,并以净资产股息率(DOE)2.5%上下为指引。每股股息从85日元、103日元、130日元,升到2027年3月期指引的135日元,在修订后每股收益预测下的派息率为37.9%,而2027年3月期的初始利润预测其实是下调的。因为锚定的是账面价值,股息随资产负债表上升,不随钢铁周期波动,并已经在钢铁亏损的半期里照常执行。
未经检验的是合并亏损年份:采用这个公式以来还没有遇到过。该计划之后的回报框架是否延续,也未知,回购金额没有固定承诺。
08.3|回购是常设工具,每年8月执行,只会减少股数
库存股占发行股数的比例在十八个月内从8.4%升到12.0%(2,900,013股),每年8月执行。这减少了计算每股指标的股数,并独立于钢铁周期推动每股净资产增长,公司没有稀释的问题。
计算每股指标时要注意分母:发行股数是24,077,510股,剔除库存股后少约290万股,两种口径给出的估值数字不同。回购价格与账面价值的关系,以及资金中有多少来自出售证券,没有分析。
08.4|证券出售、还款、分红和回购连成一个循环,但供应有限
证券出售的现金用于还款、分红和回购,自有资本比率因此抬高,银行授信不受约束;锚定账面价值的股息加上回购,使每股净资产独立于钢铁周期积累,半年内从6,660.64日元升到6,863.81日元。2026年3月期偏高的回报,有一部分由出售证券共同出资,经营现金流只负责覆盖资本开支;资本开支也随零部件利润率移动,2027年3月期上半期公告了新的三和零部件履带工厂,用于优化底盘部件生产,工厂的成本、产能和节省额没有披露。
这个循环的天花板是可出售证券的有限性:股息收入每年都在增长,而经营利润在振荡。2027年3月前持股比例目标是否兑现,以及2027年3月期不靠资产出售时现金能否覆盖资本开支和股息,是这条路径的两个待验证点。
09|估值与安全边际
09.1|估值数字:价格是账面价值的一半,倍数口径要分清
截至研究截止日(2026年11月9日),估值采用2026年11月6日收盘价2,980日元。总市值717.5亿日元(按含库存股的24,077,510股)。预测PER 8.4倍(按修订后2027年3月期每股收益356.04日元)。实绩PBR 0.45倍(按2026年3月期末每股净资产6,660.64日元)。ROE 7.3%(含证券出售收益)。预测股息率4.53%(每股135日元)。EV/EBITDA 5.7倍。
EV 1,111.8亿日元是总市值加2026年9月30日的净有息负债394.27亿日元(短期借款322.35亿、债券180亿、长期借款206.45亿,扣除现金314.53亿日元)。EBITDA 195.6亿日元是2026年3月期营业利润77.83亿日元加折旧117.77亿日元。这两个口径期间不同,且9月的净负债被废钢推高的库存抬高,所以5.7倍只是参考。
11月9日股价升到3,130日元之后,对应上半期末每股净资产6,863.81日元的0.46倍,剔除库存股的市值约660亿日元,预测PER 8.8倍。价格日期、股数口径和账面日期都不同,不能混在一起。2026年3月期每股收益含一次性收益,6.7倍仅供参考。
09.2|市场给资产负债表打对折,同时对盈利给了正常倍数
3,130日元时市值约660亿至690亿日元,对应约0.46倍账面价值、8.8倍修订后的每股收益预测、4.3%的股息率。修订公布后一天上涨5.03%,说明市场认可了这次上调,但没有因此重估结构。
价格里的预期低且具体:达到修订后的预测,保住股息公式,钢铁不再出意外。价格付钱的是资产负债表修复和零部件的耐久性,没有为钢铁复苏付钱,也没有为下半期计划失败付钱。市场相信资产负债表、怀疑盈利,这和证据一致。折价缩小,要么靠周期中位数的盈利上升,要么靠资产负债表转换加速。
市场预期是从价格和倍数反推的,不是分析师一致预期;同业倍数没有取得。
09.3|按周期中位数盈利,估值是营业利润的10到13倍
盈利记录是一个周期,不是一条趋势:销售额在2023年3月期随钢铁价格上涨升到3,344.96亿日元的峰值,营业利润从2022年3月期亏损17.06亿日元摆到2024年3月期盈利104.40亿日元的峰值,区间121亿日元,均值59亿日元左右。
按分部估算常态盈利:钢铁在零到24.70亿日元之间,零部件在70亿至110亿日元(按重置后的利润率),其他约9亿日元,减去约65亿日元的总部费用,常态营业利润大致在50亿至70亿日元。660亿至690亿日元的市值,因此约是常态营业利润的10到13倍:零部件重置若是结构性的,这个倍数偏便宜;不是,则偏满。
这个区间是本次研究根据分部历史构造的,不是公司数字;钢铁在价差条件前后几乎是二元的,所以区间很宽。平均合并历史会把2023至2024年3月期钢铁涨价的收益当作可重复的东西。
09.4|盈利质量决定估值该锚定哪一行利润
估值应当锚定经常利润和分部的常态水平,不是净利润或7.3%的ROE。按这个口径,资本回报刚触及目标,没有明显越过资本成本,这是股价长期低于账面价值的合理原因之一,也是0.45倍不是纯粹错杀的原因。
具体地:2026年3月期的每股收益含71.43亿日元证券出售收益,用它算出的低倍数会误导;2027年3月期修订后的经常利润预测86亿日元基本持平,才是更干净的参照。零部件里那笔未披露的临时收益,会同时影响对常态盈利的估算。
09.5|下行保护是财务性的,不是经营性的
下行有几层保护:51%至53%的自有资本比率;约280亿至310亿日元现金,加上286.80亿日元可出售的证券组合(含132.39亿日元未实现收益准备);锚定账面价值的股息;钢铁下行期仍然盈利的零部件业务;以及有商业理由持股的锚定股东。
反面是,这家公司在2021年和2022年3月期出现过经营亏损,所以保护来自资产负债表,不来自经营。一个糟糕的年份损失的是盈利和估值倍数,不太可能是偿付能力或股息公式,前提是证券在接近账面价值时仍可出售,这一点在无序市场中没有被检验过。
土地账面152.44亿日元,是历史成本,市场价值没有披露,是估值表之外的未量化选择权;证券变现的税务成本、土地的变现性、管理层是否愿意出售,以及母公司能否使用这些现金,目前都未知,所以账面价值的一半并不等于纯粹的安全边际。
09.6|交易所对低于净资产倍率公司的压力,是缓慢而无日期的助力
东京证券交易所对股价低于账面价值的公司施压,这家0.46倍账面价值的公司正好在这个群体里。公司的资本成本应对、回购节奏和持股削减,是它有文件记录的回应。这是一个慢变化、没有日期的催化,更新后的资本成本应对文件的具体内容没有提取。
09.7|基本面便宜不能替价格结构背书
便宜和折价是基本面一侧的事实。11月9日业绩修订后股价上涨5.03%到3,130日元,这个价格响应是作为价格证据在技术部分单独使用的,基本面的便宜不能用来升级尚未确认的价格结构。价格上的推翻条件(月线收盘跌破2,615日元,60个月均线约2,234日元)由价格定义,在论点中是被对照而不是被重新定义。
10|Kabugami 技术结构
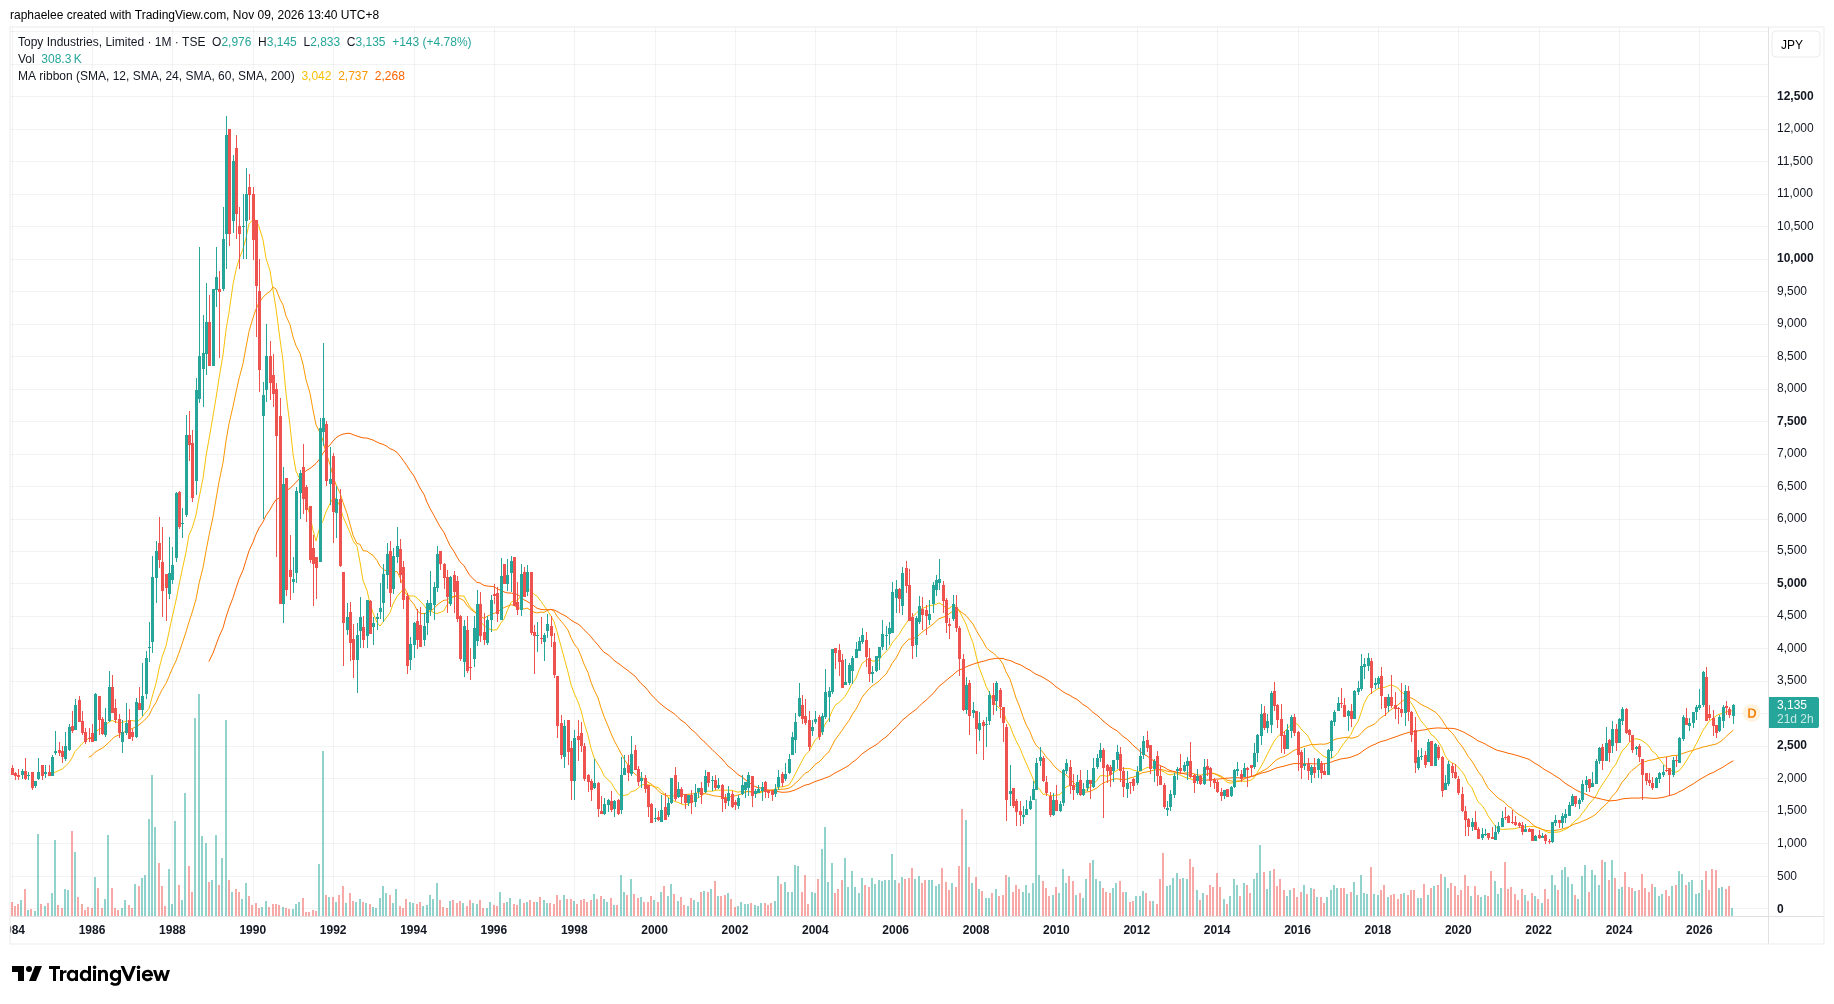
10.1|下行已经走完,现在要回答的是3,710日元之后站不站得住
这只股票的月线数据从2001年1月到2026年10月共310根,来自雅虎财经的原始(未复权)价格,加上2026年11月9日3,130日元的日线收盘。
价格历史可以分成几段。2001年到2007年2月是上升段,最高5,380日元,是窗口内最高水平。之后是崩落,以及十年宽幅振荡,区间大致在1,000日元到3,930日元,每一次反弹都比前一次低,是长期下行结构的特征。2020年到2022年4月是终端段,价格降到990日元,低于窗口内此前所有低点,比2007年高点低81.6%。
此后价格以阶梯方式重建:2023年收盘2,555日元,2024年深度回调低点1,664日元,2025年收盘3,095日元。2026年3月冲到3,710日元,此后七个月在2,615日元到3,195日元之间整理。
因此,这只股票当前的技术问题比整个生命周期的问题窄:2022年4月990日元结束的那段下行,是否已经让位于一个持久的新结构,2026年的高位整理是在保留涨幅,还是失败的开端。
10.2|年度低点连续四年抬高,2024年的深度回调守在远高于旧低点的位置
2022年4月以来,年度低点逐年抬高:990日元(2022年)、1,520日元、1,664日元、1,724日元,到2026年是2,615日元。唯一一次深度回调出现在2024年,低点1,664日元,远高于990日元的终端低点;2026年整理至今的低点2,615日元,又远高于2024年的低点。
每一次回落都在更高的位置被承接,而且深度越来越小,这是回复结构在起作用的特征,也是可以说下行已经完成、而不只是被打断的原因。回复的另一面,即价格在3,710日元之上被承接的能力,还没有被检验。
迁移的质量因此较高:它是分年度台阶推进的,中间有一次被保留的深度回调,每一步的低点成为下一步的底。唯一垂直的部分,就是2026年3月的那次冲高,也正是仍在等待确认的部分。这与2015年和2017年的高点不同——那两次冲高之后很快出现深度下跌,而这一次是七个月的守住。
从990日元回升到2,615日元至3,710日元区域,用了大约四年,是缓慢、分阶梯的修复,一个沉重的周期股往往这样,而不是一次尖锐的重估。2007年的高点仍是遥远的参照,不是近期目标。
10.3|2026年3月冲高没守住,之后七个月在2,615至3,195日元箱体里整理
2026年3月价格冲到3,710日元,当月收盘回落到2,900日元,月线振幅很宽,说明这次尝试没有被立即守住。它是一次没有成功的脉冲,其记忆现在成了结构的上沿:在月线收盘超过3,710日元之前,这个高点就是已被证明的买盘极限。
这次失败是有序的:价格回到一个箱体里整理,没有崩落。此后七个月的区间是2,615日元到3,195日元,在绝对价格上仍然很宽,成交量平平,所以这是高位整理,不是紧密压缩,单凭振幅不能判断很快会选择方向。
结构的观察指标有三个:12个月均线(约3,036日元)看短期结构是否保持,2,615日元的整理低点看箱体是否完整,3,710日元的冲高点看延续。10月收盘3,040日元正好落在第一个上,远在第二个之上,在第三个之下,没有任何一个指标触发结构性重置。
10.4|价格重心在12个月均线,但整体处在历史上少见的高位
当前结构的价格重心是3,036日元的12个月均线,10月收盘贴着它;同时价格稳稳站在24个月均线(约2,687日元)和60个月均线(约2,234日元)之上,2022年以来的涨幅没有被放弃。从整个历史分布看,长期反复停留的价格带是1,500日元到2,500日元,310根月线收盘里有150根落在这里。
也就是说,价格在近期结构的中心运行,但在历史分布的上部。2,615日元到3,710日元这一带,在历史上只在2005至2008年和2017年冲高期出现过,对这只股票是少见的位置,它本身就是下一步价格要确认或否定的事实。
下方的位置依次是2,615日元的整理低点、60个月均线约2,234日元、1,664日元的回调低点;上方是3,710日元的冲高点,其后是2017年高点3,930日元和2007年高点5,380日元。1,500日元到2,500日元那条旧价格带,是2022年以来的结构如果失败时的深层承接区。
10.5|价格对业绩事件的响应偏正面,价格与基本面在等同一个证据
在纯价格结构先形成之后,再看价格对公开事件的响应。2026年11月6日上半期业绩与上调预测公布后,11月9日股价上涨5.03%到3,130日元,仍在原有箱体之内:市场认可了这次上调,但没有重估结构。2023年以来,利好事件(2026年3月期业绩、11月的上调)使收盘价靠近阶段高点;8月较弱的第一季度公告没有击穿整理区间,利空被吸收在结构之内。
价格与业绩在时间上大致同步。2022年3月期的经营亏损和2022年4月的价格低点是同一个谷底,2023至2024年3月期的盈利恢复带动了价格恢复。现在的整理期,恰好覆盖报告利润质量受到质疑的阶段(2026年3月期的一次性收益,2027年3月期上半期的临时收益)。图形在等的,和基本面分析在等的是同一个证据。不能因此推断价格预知了未披露的信息。
这个跨领域对照是观察,不改写任何一方:基本面上资产负债表和股息的正面,不会改写价格结构尚未确认的状态;价格结构也不改变基本面的判断。基本面的便宜同样不能升级一个未确认的价格结构。
结构内部的矛盾在于海拔与历史:价格运行在历史上只有景气年份才到达的区域,而公司五年内营业利润从亏损17.06亿日元到盈利104.40亿日元的区间,还没有证明它能守住这个位置所暗示的水平。结构说下行结束了,盈利记录还没有说新的位置已经赚到了。
10.6|什么走势会确认,什么走势会推翻
当前的纯价格状态可以概括为:涨幅已经建立,高位守住,延续尚未确认。技术判断的把握一般。
加强判断的价格行为有三个:月线收盘站上3,710日元,把失败的脉冲变成延续;冬季业绩期内月线持续收在12个月均线(约3,036日元)上方;2027年的年度低点再次高于2026年的2,615日元,把阶梯延长到第五年。
推翻或大幅下调的价格行为也有三个:月线收盘跌破2,615日元,高位结构向下破坏;月线收盘跌破60个月均线(约2,234日元),价格回到旧的长期价格带;跌破2024年回调低点1,664日元,则2022年以来的上升段整体作废。
11|风险与催化剂
11.1|下半期要赚到48.89亿日元,钢铁要从亏损走到至少不亏
2027年3月期的计划从一开始就是下半期偏重的:5月的初始指引里,上半期营业利润只有10亿日元,全年80亿日元,87.5%压在下半期。11月上调到85亿日元后,下半期需要48.89亿日元,只比2026年3月期下半期的45.27亿日元高8.0%,经常利润预测86亿日元,基本持平。
公司给出的手段是涨价和结构改革,零部件销量保持,并提示能源成本是抵消的风险。钢铁要从上半期亏损12.83亿日元走向盈亏平衡或更好。
计划设计成先弱后强,所以单一季度的失望本身不是反对全年的证据,证据的重量在全年的缺口和其中的钢铁售价假设上。钢铁与零部件分部各自的拆分、废钢与售价的假设都没有披露。第三季度和全年业绩,是论点最近的检验。
11.2|宏观风险走的是价格通道,不是销量通道
宏观对这家公司的传导有四条有文件依据的通道:废钢价格(决定钢铁价差和库存价值)、与中东局势相关的能源价格(电炉成本,公司提示了下半期风险)、汇率(上半期零部件利润的一个已点名的贡献项)、以及美国贸易政策。废钢是按市场价买入的,其中一部分原料来自日本制铁,售价只能靠谈判追上,这个滞后就是传导机制。
美国关税对零部件的影响,在2026年3月期通过谈判压到有限程度,去掉了一项担忧。各通道的量化敏感度、废钢采购条款、套期,以及2027年3月期的关税结果,目前都没有披露或尚不可观察。观察这只股票,该盯的是废钢价格、能源价格和日元,不是GDP。
11.3|每个催化剂作用在估值的不同一环
2027年3月期第三季度与下半期的兑现,对照48.89亿日元的要求,是盈利的证明。「Active & Challenge 2027」之后的新计划,要看框架里ROE的目标是否高于6.0%。2027年3月前持股比例降到10%以下,是资产负债表转换的证明。铝制车轮扩张若披露量化数字,是增长选择权的证明。持续的回购则作用在每股价值的积累上。
投资者不需要等待某一个单一事件,证明点按季度到来。2027年3月之后的节点,时间点取决于披露日历,难以更准确地预测。
11.4|这几个推翻条件各在什么时候能看到
下半期计划落空,在2027年3月期第三季度(10–12月)的业绩里就能看到。零部件利润率回落到4%以下,会在临时调整效应年化消失的季度里显露,也可能出现在下一轮价格谈判之后;后者要等新中期计划的第一年才有结论。持股比例的结果在2027年3月之前揭晓。价格上的推翻条件,月线收盘跌破2,615日元,每个月末就能核对。
除了零部件定价谈判之外,其余条件大约两个季度之内都能观察到。
12|反常识发现
12.1|市场相信资产负债表、怀疑盈利,价格里的未来是最平淡的那个
一个有意思的错位是:同一家公司,资产负债表按账面价值的一半定价,盈利却按正常倍数定价。价格里嵌入的预期低而具体——达到修订后的预测,保住股息公式,钢铁不出意外。这种预期与证据一致,因为盈利质量确实有问题(报告利润含一次性收益,零部件含临时收益,钢铁价差无法预测)。
所以,钢铁价差回归是在价格之外的,下半期计划失败也是在价格之外的。11月修订后一天上涨5.03%,只是承认了上调,没有重估结构。股东在等待盈利质量被解决的同时,拿到一个4.3%到4.5%的股息。
12.2|上行与下行都押在两个领域的乘积上
情景价值集中在一个交互里:如果零部件的定价耐久性(业务模式层面的事实)守住,而钢铁价差只是停止恶化(市场层面的事实),合并营业利润会接近2024年3月期104.40亿日元的峰值,而资产负债表比当时强得多。重估的理由是这两个领域的乘积,不是其中任何一个。
反过来,如果零部件的重置被证明是会计加周期,股价会回到纯价差周期股的定价。两条腿目前都没有在同一个完整周期里被一起观察到,这个情景是有条件的,也没有量化。
13|下一次值得跟踪什么
13.1|最先要问的两件事:零部件的临时收益有多大,下半期利润从哪里来
零部件2027年3月期上半期利润74.11亿日元里,因原材料价格传导方式变更而产生的临时调整收益有多大?剔除它之后,这个分部的半年真实水平是多少?这是论点核心一环是否结构性的判断依据,金额若大,6.7%就高估了重置,推翻条件会更近。需要的证据是2027年3月期年度分部注释和公司说明材料。
修订预测里,下半期钢铁的隐含结果依据什么废钢价格和售价假设,钢铁在废钢多高的位置恢复盈利?下半期48.89亿日元里,钢铁价差恢复与零部件销量各占多少,有没有分部层面的拆分?这决定下半期指引是保守,还是要靠钢铁复苏,对应第三季度时钢铁仍亏损这个推翻条件。需要的证据是第三季度业绩和说明材料。
13.2|会改变回报框架和盈利口径的三件事
「Active & Challenge 2027」之后的新计划,营业利润和ROE的目标是多少,累进股息的DOE框架会不会延续?这决定剔除一次性收益之后的ROE目标是否高于6%,以及股息公式的可靠性,属于未来披露,目前没有可查的公开路径。
2027年3月前政策持股能否降到净资产的10%以下?投资有价证券的账面在2026年9月又升到286.80亿日元,再次落空会损害转换模式的可信度,取决于出售速度与股价。
管理层认为每个分部在中期废钢与工程机械需求水平上的周期中位数营业利润是多少,对照五年合并区间(亏损17.06亿日元到盈利104.40亿日元)?它会用公司口径替代本次研究构造的50亿至70亿日元区间,不过管理层不太可能披露分部的周期中位数。
13.3|新增资本能不能赚到高于资本成本的回报
印度和印尼铝制车轮扩张、商用车用锻造铝轮,预期销量、产能和回报是多少?新的三和零部件履带工厂花多少钱,合并了哪些生产,带来多少节省或产能?没有这些数字,资本投入的回报就无法评估,决定增量资本是否赚到高于资本成本的回报。需要的证据是综合报告、年度报告和工厂公告。
13.4|两个变化慢的因素:联盟股东与杠杆容忍度
日本制铁的23.0%持股或业务联盟会不会变化?在锚定股东普遍减持交叉持股的行业里,这会改变股东名册的稳定性和钢铁业务的商业往来;目前没有可查的公开路径,需要关注大股东变动报告。
上半期借款增加约191亿日元、同时偿还70亿日元债券之后,管理层认为对一个自有资本比率在53%上下的公司,合适的杠杆水平是多少?它决定废钢驱动的营运资金还能把总负债推高多远而不限制资本政策;管理层的杠杆容忍度没有披露。
13.5|证据边界一览:这些缺口限制把握,不是负面证据
目前材料里缺少的还有这些:竞争对手财务数据和利润率对照(最薄的一环)、第三方市场份额数据、研发费用数字、土地评估、2026年3月资本成本应对文件的内容。分析师一致预期和同业倍数同样没有取得。钢铁与零部件之间的内部转让价格、与日本制铁的联盟条款、剩余180亿日元债券的到期安排和董事会构成,也没有披露或提取。废钢采购条款与套期、2027年3月期关税结果、用于按资本回报做常态化的分部资本数据,以及ROIC序列,同样缺失。
其中一部分可以通过年度证券报告、综合报告或专门的同业比较补上,目前提供的材料里没有现成的公开路径。它们限制的是对竞争优势、相对估值和资本回报的把握,缺失本身不说明结果不好。
价格上要继续观察的是:月线收盘能否站上3,710日元,冬季业绩期后是否仍收在12个月均线上方,2027年的年度低点是否高于2,615日元。
14|Kabugami 评分卡
14.1|总分62.81/100,评级 B,整体把握一般
Kabugami Score V3.2 总分62.81/满分100,评级 B(B 档区间为55至64.9分)。八个维度得分相加等于总分。资产负债表、股息公式和价格结构给出了偏正面的底,扣分主要集中在盈利质量、零部件定价耐久性这两处还没有答案的地方,以及治理一项缺少可核实材料。行动是持有观察,不追高。
14.2|八个维度的得分与一句理由
财务韧性与下行防御:9.36/13。自有资本比率51%至53%,净负债相对净资产温和,但这家公司2021年和2022年3月期出现过经营亏损,防御来自资产负债表,不来自经营。
竞争优势与结构耐久性:8.12/14。零部件有认证带来的重新定价能力,但只观察了约两年,临时收益金额未披露;钢铁没有护城河。
盈利质量、现金转化与资本效率:8.84/17。报告利润含证券出售收益与临时收益,经常利润86.18亿日元才是较干净的锚,总部费用又把合并利润率压到2.6%。
商业结构、产品、客户与关键依赖:6.05/11。利润集中在零部件和工程机械周期,钢铁补不了位,客户集中度与订单余额没有披露。
估值与安全边际:10.2/15。0.45倍市净率和4.5%的预测股息率给出边际,但倍数口径混用,也没有一致预期和同业对照。
资本配置与股东回报:7.2/10。公式化的股息和每年回购有效,持股削减目标已延期一次,亏损年份的分红还没有经过检验。
治理、所有权与管理层:4.2/7。方向符合低市净率公司的要求,稳定股东降低了控制权风险,但董事会独立性未核实,也不是论点的驱动力。
Kabugami 技术结构:8.84/13。下行已结束、新结构已形成,3,710日元之上的延续尚未被收盘价确认。
14.3|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 9.36 | 2026年3月期末自有资本比率53.0%,2026年9月降至51.0%,净资产1,468.43亿日元;生息负债约587亿日元,现金约294亿日元,净负债约290亿日元,到2026年9月因库存垫资和债券置换升至约394亿日元,相对净资产仍属温和。投资有价证券约287亿日元、土地账面约152亿日元提供非经营性支撑。扣分点在于:这家公司2021年和2022年3月期出现过经营亏损,防御来自资产负债表而不是经营本身。 |
| 竞争优势与结构耐久性 | 14 | 8.12 | 真正的护城河只在零部件:车轮和履带底盘部件进入整车厂和工程机械厂商的认证体系,切换成本在客户一侧;2026年3月期零部件利润同比增长145.5%至109.17亿日元,上半期又创74.11亿日元新高,说明这家公司确实有重新定价的能力。钢铁业务没有差异化,只能跟着废钢价差走。两块业务不应按同一档护城河估值。 |
| 盈利质量、现金转化与资本效率 | 17 | 8.84 | 2026年3月期营业利润77.83亿日元(同比增长46.8%,营业利润率2.6%),但增量全部来自零部件,钢铁利润下降61.1%至24.70亿日元。净利润101.51亿日元含71.43亿日元证券出售收益,经常利润86.18亿日元才是更干净的锚;报告ROE为7.3%,剔除出售收益后约在6%上下,只是勉强站在计划目标6.0%的位置。集团总部和调整项每年吞掉约60至65亿日元,占分部利润约45%,使得最好的零部件年份也只换来2.6%的合并利润率。 |
| 商业结构、产品、客户与关键依赖 | 11 | 6.05 | 业务从电炉炼钢(以废钢为原料)一路延伸到钢铁制品、钢制和铝制车轮、工程机械底盘部件,另有合成云母、建设、房产、体育等小业务(合计销售额约69亿日元,利润率12.8%,是集团最稳定的一块)。零部件约占分部销售的三分之二,利润占比约76%,需求主要来自工程机械和车辆生产,这是上半期超预期的来源,也是下半期计划所依赖的同一个周期。 |
| 估值与安全边际 | 15 | 10.2 | 截至2026年11月6日收盘价2,980日元,市值约717.5亿日元(按发行股数含库存股),实际市净率0.45倍,预测市盈率8.4倍(按修订后2027年3月期每股收益356.04日元),预测股息率4.53%(股息135日元),企业价值倍数约5.7倍。11月9日股价涨至3,130日元,对应约0.46倍上半期末每股净资产6,863.81日元。市场给资产负债表打了对折,同时对中期盈利给了正常倍数。 |
| 资本配置与股东回报 | 10 | 7.2 | 股东回报有明确公式:以净资产股息率(DOE)约2.5%为准的累进股息,每股股息从85日元、103日元、130日元,到2027年3月期指引135日元(修订后每股收益预测对应派息率37.9%);每年8月回购,库存股占发行股数的比例在十八个月内从8.4%升到12.0%(290.0万股)。2026年3月期还出售了124.46亿日元证券,用于还款、股息和回购。持股占净资产的比例从14.8%降到11.3%。 |
| 治理、所有权与管理层 | 7 | 4.2 | 治理方向与市场对低市净率公司的要求一致:2026年3月宣布转为监查等委员会设置公司,2025年5月废止收购防御措施,更新并公布了资本成本应对文件,持续回购并调整子公司组合。日本制铁持有23.0%表决权(含合计0.9%),是权益法下的业务联盟伙伴,申报材料写明其对经营没有承认权;没有控制权的稳定股东使股东登记表上的事件风险较低,治理争论主要围绕经营而非控制权。 |
| Kabugami 技术结构 | 13 | 8.84 | 这只股票的月线完整生命周期中,2007年2月的高点5,380日元之后经历长期下行,2022年4月降至终点低位990日元(比高点低81.6%);此后年度低点逐年抬高(2023年、2024年、2025年、2026年),2024年的深度回调低点1,664日元远高于终点低位,价格长期站在24个月和60个月均线之上。2026年3月冲到3,710日元但月收盘回落至2,900日元,此后七个月在2,615至3,195日元区间内整理,11月9日收于3,130日元。判断:下行已结束,新一轮上升结构已经形成,但向上延续尚未确认。技术判断的把握一般偏上。 |
总分: 62.81 / 100 评级: B 操作建议: 持有观察,不追高。基本面上,资产负债表和股息公式提供了较厚的底部,价格约为账面价值的0.45至0.46倍;但盈利质量(一次性收益与零部件临时收益的金额)和钢铁价差都还没有答案,价格结构也处在“下行已结束、延续尚未确认”的阶段。已持有者继续持有,靠约4.3%至4.5%的股息等待;新增仓位更适合在2027年3月期下半期业绩兑现(营业利润约48.9亿日元、钢铁至少不亏)、零部件利润率在不依赖临时收益时仍然守住之后,或价格有效收于3,710日元之上时再分批考虑。若下半期计划落空且钢铁仍然亏损、零部件利润率回落到约4%以下、持股比例未在2027年3月前降到10%以下,或月收盘跌破2,615日元,应重新评估。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|数据来源与日期
公司一手披露包括:2026年5月12日的2026年3月期业绩公告(经 TDnet 披露),2026年6月24日提交的第132期证券报告书,2026年6月25日关于控股股东等事项的公告。还有2026年8月4日的2027年3月期第一季度公告,以及2026年11月6日的2027年3月期上半期公告(公司网站披露)。公司网站的五年财务摘要和 IR 新闻列表(2026年11月9日查阅)也用作核对。
外部与二手资料:经济产业省 G-Biz Info 的 EDINET 摘录(2026年11月9日)和 the-shashi.com 的十年财务摘要。另有 Finnhub 的行情快照(2026年11月9日取得,用于11月9日收盘价3,130日元与上涨5.03%)。价格结构使用经 Kabugami 本地整理的雅虎财经月线数据(月线截至2026年10月,数据到2026年10月27日,原始未复权)。
正式英文名取自证券报告书封面:Topy Industries, Limited。研究截止日为2026年11月9日;估值简报使用2026年11月6日的收盘价2,980日元,11月9日的价格是修订公布后的一次收盘观察。
15.2|证据限制与口径说明
估值倍数混用了不同的价格日期、发行股数与剔除库存股后的股数、不同的账面日期,EV/EBITDA 还把2026年9月的净负债与2026年3月期的EBITDA放在一起,这些是推算值,不是一手事实。市场预期是从价格和倍数反推的,没有取得分析师一致预期,也没有同业倍数。常态盈利区间(营业利润50亿至70亿日元)和约6%的税前ROE是本次研究的构造或近似,不是公司数字。
2027年3月期上半期的现金流量表没有披露,现金消耗是从资产负债表变动推算的;零部件临时调整收益的金额、竞争对手数据、土地评估、ROIC和资本成本应对文件的内容均未取得,详见“下一次值得跟踪什么”。这些缺口只说明材料不足,不说明结果不好。
价格结构只基于价格与成交量历史,没有使用基本面作为技术原因。本次没有提供图表。
15.3|研究用途与免责
本报告仅作研究和信息交流之用,不构成投资建议、证券买卖要约或收益承诺。报告中的判断、评分和行动表述,反映的是截至2026年11月9日可得公开资料下的研究结论,之后的公告和价格变化不在其中。投资有风险,读者应结合自身情况独立判断。本报告所依据的材料中未包含与该公司有关的利益关系信息。
主要资料来源
- FY3/26 results release, 12 May 2026, cover and summary tables
- 132nd-term securities report, filed 24 June 2026, cover and company outline
- G-Biz Info company extract
- Company financial highlights, five-year record
- Ten-year financial summary (securities-report based)
- Notice on matters concerning controlling shareholders etc., 25 June 2026
- H1 FY3/27 release, segment information
- Q1 FY3/27 release, 4 August 2026
- Vendor snapshot retrieved 9 November 2026
- Company IR news list, 2026 entries
- Monthly closes March to October 2026 and trading volume, locally recomputed
研究发现索引
展开本次 Review 的 81 项研究发现
F001|02|集团是一条从废钢到零部件的链,只能看合并报表
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|集团是一条从废钢到零部件的链,只能看合并报表15|数据来源与日期
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:直接证据;一手验证:01
132nd-term securities report, business description怎么使用:直接证据;一手验证:02、03、04、08、09、10
G-Biz Info company extract怎么使用:直接证据
Securities-report indicators via G-Biz Info怎么使用:直接证据;一手验证:08、09;专项深挖:01、08、09
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;直接证据 / 一手证据(研究域01)|132nd-term securities report, filed 24 June 2026, cover and company outline;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|132nd-term securities report, business description;直接证据|G-Biz Info company extract;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 定向深挖(研究域01) / 定向深挖(研究域08) / 定向深挖(研究域09)|Securities-report indicators via G-Biz Info;直接证据|FY3/26 release, parent-company (non-consolidated) results
完整研究记录(核对用)
研究原文:Topy Industries, Limited (7231, TSE Prime and Nagoya Premier) is an integrated steel-to-parts group: electric-furnace steelmaking from scrap at Toyohashi, steel products, and downstream steel and aluminium wheels and construction-machinery undercarriage components, plus a small tail of synthetic mica, construction, property and sports operations. Founded 1921, formed in present shape by the 1964 merger, capital JPY 20,983m, 24,077,510 shares issued, 32 consolidated subsidiaries and 4 affiliates, 16 overseas production bases in seven countries. The parent alone earns only JPY 1,880m of operating profit, so consolidated statements are the only meaningful economic perimeter. Legal English name on the securities-report cover is Topy Industries, Limited.
内部研究类型:company_identity_perimeter
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Ordinary shareholders own a cyclical integrated manufacturer whose profit is earned in subsidiaries; analysis must start from the steel-to-parts chain, not from a pure parts-maker frame.
不确定性(原始记录):Minority-interest and subsidiary-level attribution were not extracted; group boundary is read from filings only.
F002|01|框架值得长期持有,盈利水平要按周期中位数定价
研究范围:开放研究+35项覆盖检查
写入正文:01|框架值得长期持有,盈利水平要按周期中位数定价09|下行保护是财务性的,不是经营性的
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Company financial highlights, five-year record怎么使用:直接证据;同业比较:02、05、09、10、11、12、17、19、20、25、28;其他用途:历史
G-Biz Info extract of the FY3/26 securities report indicators怎么使用:直接证据;同业比较:01、18、26;其他用途:历史
Ten-year financial summary (securities-report based)怎么使用:直接证据;一手验证:12;同业比较:03、04、08、33;其他用途:历史
Company highlights, five-year profit record怎么使用:直接证据;一手验证:12、28、33;反向验证:29;专项深挖:12、28、33、34;同业比较:15、16、22、29、34、35;其他用途:历史
FY3/26 release, balance sheet怎么使用:直接证据
Notice on matters concerning controlling shareholders etc., 25 June 2026怎么使用:直接证据;一手验证:07、23
FY3/26 release, segment narrative - parts怎么使用:直接证据;一手验证:05、10;专项深挖:02、03、04、08、10
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25) / 历史/同业比较(研究域28)|Company financial highlights, five-year record;直接证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域18) / 历史/同业比较(研究域26)|G-Biz Info extract of the FY3/26 securities report indicators;直接证据 / 一手证据(研究域12) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域08) / 历史/同业比较(研究域33)|Ten-year financial summary (securities-report based);直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域22) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35) / 反证(研究域29) / 定向深挖(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域33) / 定向深挖(研究域34)|Company highlights, five-year profit record;直接证据|FY3/26 release, balance sheet;直接证据 / 一手证据(研究域07) / 一手证据(研究域23)|Notice on matters concerning controlling shareholders etc., 25 June 2026;直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;直接证据|H1 FY3/27 release, segment information
完整研究记录(核对用)
研究原文:What is durable is the frame, not the earnings level. Integration from scrap to qualified components, the parts segment's demonstrated ability to reprice, a 51-53% equity ratio, a sellable securities portfolio, a DOE-anchored return formula and an alliance anchor on the register have been observed in both bad steel years (FY3/22, H1 FY3/27) and good ones (FY3/24, FY3/26) without depending on cycle direction. What is not durable is any particular year's profit: the five-year operating range of JPY -1,706m to +10,440m, reported net income's dependence on portfolio sales, and a temporary element inside the latest parts figure all say earnings will keep moving with the scrap spread and the machinery cycle. The structural judgment is two-level: own the frame for balance-sheet compounding and parts repricing ability, but price earnings at through-cycle levels (roughly JPY 5-6bn operating profit) until steel holds at least breakeven through a full scrap cycle and the parts margin survives a negotiation round without accounting assistance.
内部研究类型:durable_business_portrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Separates what compounds (book value, dividend formula, repricing franchise) from what oscillates (spread-driven profit), which is the basis for valuing the equity at through-cycle rather than peak or trough earnings.
不确定性(原始记录):Parts margin durability has been observed for only about two years and has not been tested through a full OEM negotiation round or a full scrap cycle under the new pricing framework.
F003|02|2026年3月期利润增长全部来自零部件,钢铁在拖后腿
研究范围:开放研究+35项覆盖检查
写入正文:02|2026年3月期利润增长全部来自零部件,钢铁在拖后腿
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:直接 / 支持;一手验证:01
FY3/26 release, segment narrative怎么使用:直接 / 支持;一手验证:02;同业比较:06、14;其他用途:历史
FY3/26 release, consolidated statements of income怎么使用:直接证据;一手验证:33;专项深挖:01、12、13、17、33、34
FY3/26 release, segment narrative - steel怎么使用:直接证据;专项深挖:02、06
FY3/26 release, segment narrative - parts怎么使用:直接证据;一手验证:05、10;专项深挖:02、03、04、08、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;直接证据 / 一手证据(研究域33) / 定向深挖(研究域01) / 定向深挖(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域17) / 定向深挖(研究域33) / 定向深挖(研究域34)|FY3/26 release, consolidated statements of income;直接证据 / 定向深挖(研究域02) / 定向深挖(研究域06)|FY3/26 release, segment narrative - steel;直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;直接证据|FY3/26 release, margin structure (computed)
完整研究记录(核对用)
研究原文:FY3/26 operating profit rose 46.8% to JPY 7,783m on sales of JPY 297,750m (down 1.0%; a 2.6% consolidated margin), but the entire increase came from the parts segment (profit up 145.5% to JPY 10,917m at a 5.4% margin) while steel profit fell 61.1% to JPY 2,470m (2.8% margin) on scrap costs and repair expense. The headline growth is therefore a composition story: a downstream margin programme replaced steel as the group's engine.
内部研究类型:earnings_composition_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Group profit capacity now depends on one franchise (parts) carrying an unmoated, spread-exposed one (steel); every point of segment margin moves a thin consolidated margin materially.
不确定性(原始记录):Repair expense inside steel and the split between structural reform and repricing inside parts are not separately quantified.
F004|06|利润增长要先剥掉三层水分,才看得到经营趋势
研究范围:开放研究+35项覆盖检查
写入正文:06|利润增长要先剥掉三层水分,才看得到经营趋势09|盈利质量决定估值该锚定哪一行利润14|八个维度的得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
FY3/26 release, extraordinary items怎么使用:直接 / 支持
FY3/26 release, non-operating items怎么使用:直接 / 支持
FY3/26 release, extraordinary items and taxes怎么使用:直接证据;一手验证:16、32;专项深挖:16、32
H1 FY3/27 release, extraordinary items怎么使用:直接证据;一手验证:16;专项深挖:16;同业比较:32;其他用途:历史
FY3/26 release, balance sheet detail怎么使用:直接证据;一手验证:18、21、29;专项深挖:18、19、29
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:支持证据;一手验证:01
H1 FY3/27 release, revised FY3/27 forecast怎么使用:支持证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/26 release, extraordinary items;直接证据 / 支持证据|FY3/26 release, non-operating items;直接证据 / 一手证据(研究域16) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|FY3/26 release, extraordinary items and taxes;直接证据|FY3/26 release, FY3/27 initial forecast;直接证据 / 一手证据(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域16)|H1 FY3/27 release, extraordinary items;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;支持证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;支持证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast
完整研究记录(核对用)
研究原文:Reported FY3/26 net income of JPY 10,151m includes a JPY 7,143m one-off gain on sales of policy shareholdings (partly offset by impairment of JPY 754m and disposal losses of JPY 635m); ordinary profit of JPY 8,618m is the cleaner recurring anchor, including about JPY 835m of recurring dividend and equity-method income. The revised FY3/27 ordinary-profit forecast is JPY 8,600m, essentially flat, while net income is guided down because no shareholding sale is assumed. Shareholding-sale gains have now supplemented reported profit in three consecutive reporting periods (a further JPY 1,371m in H1 FY3/27), so portfolio sales are becoming a habit but remain finite in supply. Three separate mechanisms flatter reported profit - portfolio sales, impairment offsets and a pass-through accounting change - and each must be stripped to see the operating trend.
内部研究类型:profit_quality_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Valuation and return judgments should be anchored to ordinary profit and segment run rates, not reported net income or the reported ROE.
不确定性(原始记录):The size of recurring versus finite portfolio gains going forward depends on the remaining saleable holdings and market prices.
F005|06|ROE 7.3%过了目标线,是被证券出售收益抬上去的
研究范围:开放研究+35项覆盖检查
写入正文:06|ROE 7.3%过了目标线,是被证券出售收益抬上去的09|盈利质量决定估值该锚定哪一行利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 release, medium-term plan section怎么使用:直接 / 支持;一手验证:22;同业比较:13;其他用途:历史
FY3/26 release, extraordinary items and taxes怎么使用:直接 / 支持;一手验证:16、32;专项深挖:16、32
FY3/26 release, mid-plan ROE discussion怎么使用:直接 / 支持;一手验证:22;专项深挖:22
FY3/26 release, non-operating items怎么使用:直接证据
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域13)|FY3/26 release, medium-term plan section;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|FY3/26 release, extraordinary items and taxes;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域22)|FY3/26 release, mid-plan ROE discussion;直接证据|FY3/26 release, non-operating items
完整研究记录(核对用)
研究原文:Reported FY3/26 ROE of 7.3% clears the plan's FY2027 target of at least 6.0% only because JPY 7,143m of securities-sale gains lifted it; management itself says the ex-gain level still needs to rise. Ordinary profit of JPY 8,618m on about JPY 145bn of equity is roughly a 6% pre-tax return on equity, so the target is a floor still to be defended, not a milestone passed. No ROIC series was available and the company's March 2026 cost-of-capital response document was identified but not extracted.
内部研究类型:capital_efficiency_judgment
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Until recurring ROE clears the target without asset sales, the discount to book has a rational core; sustained sub-cost-of-capital returns justify a sub-1x multiple.
不确定性(原始记录):Pre-tax/after-tax and period-basis approximations are the review's own; ROIC and the quantified cost-of-capital response remain unknown.
F006|06|2027年3月期上半期:利润翻倍超预期,质量问题落在零部件上
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|2027年3月期上半期:利润翻倍超预期,质量问题落在零部件上
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Q1 FY3/27 release, 4 August 2026怎么使用:直接证据
H1 FY3/27 release, 6 November 2026, summary tables怎么使用:直接证据;一手验证:15;反向验证:35
H1 FY3/27 release, segment information - steel怎么使用:直接证据;一手验证:11、35;专项深挖:14、35
H1 FY3/27 release, segment information - parts怎么使用:直接证据;一手验证:32;专项深挖:05、10、14、15、32
查看完整证据标签(核对用)
直接证据|Q1 FY3/27 release, 4 August 2026;直接证据 / 一手证据(研究域15) / 反证(研究域35)|H1 FY3/27 release, 6 November 2026, summary tables;直接证据|H1 FY3/27 release, segment information;直接证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts
完整研究记录(核对用)
研究原文:H1 FY3/27 flipped the mix again: sales grew 9.7% and operating profit rose 10.9% to JPY 3,611m, more than twice the revised half-year guide of JPY 1,500m, because parts reached a record JPY 7,411m (6.7% margin; external sales up 16.2%) while steel lost JPY 1,283m. JPY 2,918m of the half's profit arrived in Q2 alone as parts price adjustments landed, after a weak Q1 (JPY 693m) in which steel spreads were hit by a scrap surge and parts strength led the company to raise the half-year guide in August. Parts profit includes a temporary pass-through-method gain the company flags as one-off.
内部研究类型:current_change_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The half-year beat is real but its quality attaches to the parts figure rather than to demand, so it supports the forecast raise without proving run-rate margins.
不确定性(原始记录):Composition of the Q2 parts profit between volume, currency and the temporary adjustment is undisclosed.
F007|03|钢铁利润看价差,不看销量
研究范围:开放研究+35项覆盖检查
写入正文:03|钢铁利润看价差,不看销量
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 release, segment narrative怎么使用:直接 / 支持;一手验证:02;同业比较:06、14;其他用途:历史
H1 FY3/27 release, steel business narrative怎么使用:直接 / 支持;一手验证:06、14
FY3/26 release, segment narrative - steel怎么使用:直接证据;专项深挖:02、06
H1 FY3/27 release, segment information - steel怎么使用:直接 / 支持;一手验证:11、35;专项深挖:14、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14)|H1 FY3/27 release, steel business narrative;直接证据 / 定向深挖(研究域02) / 定向深挖(研究域06)|FY3/26 release, segment narrative - steel;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel
完整研究记录(核对用)
研究原文:Steel profitability is a metal-spread problem, not a volume problem. The electric-furnace segment buys scrap at market prices and sells into negotiated prices, so a high scrap plateau compresses the margin until selling-price revisions catch up. FY3/26 steel profit fell 61.1% as scrap rose in the second half; in H1 FY3/27 steel external sales fell only 3.4% while profit swung JPY 2,779m (from +1,496m to -1,283m) year on year, a spread event on stable construction demand.
内部研究类型:causal_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Steel has no moat and no supplier-concentration rescue; only price pass-through protects margin, so steel is an option on spread normalisation rather than a foundation.
不确定性(原始记录):The scrap level at which steel returns to profit and the company's price-increase assumptions are undisclosed.
F008|03|零部件贡献了集团利润的大头,靠的是价格形成而不是销量
研究范围:开放研究+35项覆盖检查
写入正文:03|零部件贡献了集团利润的大头,靠的是价格形成而不是销量14|八个维度的得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 release, segment narrative怎么使用:直接 / 支持;一手验证:02;同业比较:06、14;其他用途:历史
H1 FY3/27 release, segment information怎么使用:直接 / 支持
FY3/26 release, segment narrative - parts怎么使用:直接 / 支持;一手验证:05、10;专项深挖:02、03、04、08、10
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
FY3/26 release, segment revenue mix (computed on reported segment totals)怎么使用:直接证据;一手验证:15;专项深挖:15
FY3/26 release, segment narrative - steel怎么使用:支持证据;专项深挖:02、06
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;直接证据 / 支持证据|H1 FY3/27 release, segment information;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|FY3/26 release, segment revenue mix (computed on reported segment totals);支持证据 / 定向深挖(研究域02) / 定向深挖(研究域06)|FY3/26 release, segment narrative - steel
完整研究记录(核对用)
研究原文:The parts segment is the earnings engine: JPY 10,917m of FY3/26 operating profit (about 76% of JPY 14,269m segment profit, after steel JPY 2,470m and other JPY 882m) and JPY 7,411m in H1 FY3/27, more than the whole consolidated H1 profit, against a steel segment that swung to loss. The margin reset results from structural reform and a 'sustainable selling price' policy rather than volume growth, so durability depends on holding the new price formation. Parts is about two-thirds of reported segment revenue but a larger share of profit, so mix shift toward downstream is a quiet structural trend inside the cycle.
内部研究类型:profit_engine
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Any failure of the new price formation would hit group profit immediately because steel cannot currently offset it.
不确定性(原始记录):Underlying run-rate margin below the reported 6.7% is unquantified; durability through an OEM negotiation round is untested.
F009|06|零部件利润里那笔临时收益有多大,是最先要补上的缺口
研究范围:开放研究+35项覆盖检查
写入正文:06|零部件利润里那笔临时收益有多大,是最先要补上的缺口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY3/27 release, segment information怎么使用:直接 / 支持
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
查看完整证据标签(核对用)
直接证据 / 支持证据|H1 FY3/27 release, segment information;直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts
完整研究记录(核对用)
研究原文:A change in the method of reflecting raw-material prices in selling prices to OEM customers produced a temporary adjustment gain inside H1 FY3/27 parts profit of JPY 7,411m. The company names three drivers (volume, currency and this adjustment) and flags the adjustment as one-off, but does not quantify it, so the segment's underlying half-year margin is somewhere below the reported 6.7%. This is the key measurement gap in the current record.
内部研究类型:accounting_timing_effect
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Segment margins for H1 FY3/27 should be read as overstated by an unknown amount until the annual report resolves it; it bears directly on whether the parts reset is structural.
不确定性(原始记录):Magnitude unknown; may be resolved by the annual securities-report segment note or briefing materials.
F010|11|下半期要赚到48.89亿日元,钢铁要从亏损走到至少不亏
研究范围:开放研究+35项覆盖检查
写入正文:11|下半期要赚到48.89亿日元,钢铁要从亏损走到至少不亏
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 release, FY3/27 initial forecast怎么使用:直接 / 支持;同业比较:30;其他用途:历史
H1 FY3/27 release, forecast revision and outlook怎么使用:直接 / 支持;一手验证:20;同业比较:27、31;其他用途:历史
Q1 FY3/27 release, 4 August 2026, summary and revision怎么使用:直接 / 支持;一手验证:05;专项深挖:05、11
H1 FY3/27 release, 6 November 2026, summary tables怎么使用:直接证据;一手验证:15;反向验证:35
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接 / 支持;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域30)|FY3/26 release, FY3/27 initial forecast;直接证据 / 支持证据 / 一手证据(研究域20) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|H1 FY3/27 release, forecast revision and outlook;直接证据 / 支持证据 / 一手证据(研究域05) / 定向深挖(研究域05) / 定向深挖(研究域11)|Q1 FY3/27 release, 4 August 2026, summary and revision;直接证据 / 一手证据(研究域15) / 反证(研究域35)|H1 FY3/27 release, 6 November 2026, summary tables;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 支持证据|H1 FY3/27 release, quarterly split (computed from Q1 and H1 releases)
完整研究记录(核对用)
研究原文:The FY3/27 plan was deliberately second-half-loaded from the start (opening H1 guide JPY 1,000m of a JPY 8,000m full-year operating profit; 87.5% in H2). The November 2026 revision to JPY 8,500m operating profit arithmetically requires JPY 4,889m in H2, only 8.0% above H2 FY3/26's JPY 4,527m, with ordinary profit roughly flat at JPY 8,600m. Management frames the means as price increases and structural reform with parts volumes holding, and flags energy costs as the offsetting risk; steel must move from the JPY 1,283m H1 loss toward breakeven or better. A weak Q1 followed by strong Q2 is the plan's designed rhythm, so evidential weight sits on the full-year bridge and its steel-price assumptions rather than any single quarter.
内部研究类型:forecast_bridge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The market has just been taught to trust a guide whose delivery depends on the scrap-versus-price race, so H2 delivery is the next proof point.
不确定性(原始记录):No segment-level bridge or scrap/selling-price assumptions are disclosed.
F011|06|总部费用每年吞掉六十多亿日元,把好年份也压成薄利润率
研究范围:35项覆盖检查
写入正文:06|总部费用每年吞掉六十多亿日元,把好年份也压成薄利润率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 release, consolidated statements of income怎么使用:直接证据;一手验证:33;专项深挖:01、12、13、17、33、34
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/26 release, segment profit reconciliation (computed from disclosed segment profits);直接证据 / 支持证据|H1 FY3/27 release, segment information - other and adjustments;直接证据|FY3/26 release, margin structure (computed);直接证据 / 一手证据(研究域33) / 定向深挖(研究域01) / 定向深挖(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域17) / 定向深挖(研究域33) / 定向深挖(研究域34)|FY3/26 release, consolidated statements of income
完整研究记录(核对用)
研究原文:Roughly JPY 6-6.5bn a year disappears between segment profit (JPY 14,269m) and consolidated operating profit (JPY 7,783m): the corporate centre and adjustments consume about 45% of what segments earn, a drag of about 2.2% of sales. H1 FY3/27 annualises to the same magnitude, confirming it is structural, not a one-year event. Even a good 5.4% best-segment margin leaves only a 2.6% consolidated margin.
内部研究类型:structural_margin_drag
内部来源标记:COVERAGE35
普通股东含义(原始记录):Operating leverage works both ways on a thin consolidated margin; the equity story is about spread and mix, not scale.
不确定性(原始记录):Composition of the adjustment line (central costs versus eliminations) is not decomposed.
F012|02|其他业务规模很小,利润率最高也最稳
研究范围:35项覆盖检查
写入正文:02|其他业务规模很小,利润率最高也最稳
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 release, segment narrative - other怎么使用:直接 / 支持
132nd-term securities report, business description怎么使用:直接证据;一手验证:02、03、04、08、09、10
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/26 release, segment narrative - other;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|132nd-term securities report, business description
完整研究记录(核对用)
研究原文:The 'other' portfolio (synthetic mica, construction, property, sports) earned JPY 882m at a 12.8% margin on JPY 6,889m of sales, about 2% of sales: the highest-margin and least cyclical part of the group, too small to move the equity case but evidence that the group can run non-cycle businesses profitably.
内部研究类型:minor_profit_pool
内部来源标记:COVERAGE35
普通股东含义(原始记录):A small stabiliser, not a thesis driver.
不确定性(原始记录):Business-level economics not extracted.
F013|09|按周期中位数盈利,估值是营业利润的10到13倍
研究范围:开放研究+35项覆盖检查
写入正文:09|按周期中位数盈利,估值是营业利润的10到13倍
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Company financial highlights, five-year record怎么使用:直接 / 支持;同业比较:02、05、09、10、11、12、17、19、20、25、28;其他用途:历史
Ten-year financial summary (securities-report based)怎么使用:直接 / 支持;一手验证:12;同业比较:03、04、08、33;其他用途:历史
Company highlights, five-year profit record怎么使用:直接 / 支持;一手验证:12、28、33;反向验证:29;专项深挖:12、28、33、34;同业比较:15、16、22、29、34、35;其他用途:历史
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
Vendor snapshot retrieved 9 November 2026怎么使用:支持证据;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25) / 历史/同业比较(研究域28)|Company financial highlights, five-year record;直接证据 / 支持证据 / 一手证据(研究域12) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域08) / 历史/同业比较(研究域33)|Ten-year financial summary (securities-report based);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域22) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35) / 反证(研究域29) / 定向深挖(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域33) / 定向深挖(研究域34)|Company highlights, five-year profit record;直接证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026
完整研究记录(核对用)
研究原文:The earnings record is a cycle, not a trend: sales peaked at JPY 334,496m with FY3/23 steel-price inflation; operating profit swung from a JPY 1,706m loss (FY3/22) to a JPY 10,440m peak (FY3/24), a JPY 12.1bn range around a mean of roughly JPY 5.9bn. A segment-level normalisation (steel between zero and JPY 2,470m, parts JPY 7-11bn on the reset margin, other about JPY 0.9bn, less about JPY 6.5bn of corporate costs) brackets normalised operating profit at roughly JPY 5-7bn; averaging consolidated history would import the FY3/23-24 steel-price inflation as if it were repeatable. The bracket is wide because steel is binary around spread conditions; the parts reset narrows it only if it holds.
内部研究类型:normalized_earnings_judgment
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Peak-year multiples are meaningless; at roughly JPY 66-69bn of market value the equity costs about 10-13 times normalised operating profit - cheap if the parts reset is structural, full if not.
不确定性(原始记录):The normalised build is this review's construction from segment history, not a company figure; segment capital data are not disclosed.
F014|06|一个废钢价格,同时推动利润、库存、借款和现金
研究范围:开放研究+35项覆盖检查
写入正文:06|一个废钢价格,同时推动利润、库存、借款和现金
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
H1 FY3/27 release, segment information怎么使用:直接 / 支持
FY3/26 release, balance sheet怎么使用:直接 / 支持
FY3/26 release, balance sheet detail怎么使用:直接证据;一手验证:18、21、29;专项深挖:18、19、29
FY3/26 release, cash-flow detail怎么使用:直接 / 支持;一手验证:17、19、20、25;专项深挖:17、20、25
H1 FY3/27 release, balance sheet怎么使用:直接证据;一手验证:18、29;专项深挖:18、20、29
H1 FY3/27 release, debt movements怎么使用:直接证据
H1 FY3/27 release, working capital怎么使用:直接 / 支持;一手验证:19;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 支持证据|H1 FY3/27 release, segment information;直接证据 / 支持证据|FY3/26 release, balance sheet;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域25) / 定向深挖(研究域17) / 定向深挖(研究域20) / 定向深挖(研究域25)|FY3/26 release, cash-flow detail;直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据|H1 FY3/27 release, debt movements;直接证据 / 支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|H1 FY3/27 release, working capital
完整研究记录(核对用)
研究原文:Working capital absorbs cash when scrap prices rise. Inventories climbed from JPY 57,509m at the FY3/26 year-end to JPY 64,941m at H1 FY3/27 (up JPY 7,432m, mostly raw-material value), with receivables of JPY 46,544m against payables of JPY 29,305m; total assets grew JPY 13,694m and the equity ratio eased to 51.0%. Borrowings rose about JPY 19.1bn while JPY 7,000m of bonds were redeemed, refinanced into bank debt. FY3/26 operating cash flow of JPY 13,129m was strong, but the H1 build shows the same mechanism in reverse. The scrap plateau therefore taxes the balance sheet as well as the margin. Half-year operating cash flow was not disclosed, so the cash cost is inferred from balance-sheet movement; inventory build here reflects raw-material price inflation rather than evidence of demand.
内部研究类型:cash_transmission_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Cash conversion, not demand, is the constraint to watch in a rising scrap market; reported profit and cash diverge when scrap moves.
不确定性(原始记录):H1 cash-flow statement unavailable; inventory costing basis and any hedging not disclosed; ownership/realisability of the inventory not examined.
F015|06|资产负债表够厚,能把周期挡在偿付能力之外
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表够厚,能把周期挡在偿付能力之外14|八个维度的得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
FY3/26 release, balance sheet怎么使用:直接 / 支持
G-Biz Info extract of the FY3/26 securities report indicators怎么使用:直接证据;同业比较:01、18、26;其他用途:历史
FY3/26 release, liabilities detail怎么使用:直接 / 支持
FY3/26 release, market-value equity ratio怎么使用:直接证据;一手验证:31;专项深挖:31
H1 FY3/27 release, balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、20、29
H1 FY3/27 release, debt movements怎么使用:直接证据
H1 FY3/27 release, equity movements and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21
FY3/26 release, balance sheet detail怎么使用:支持证据;一手验证:18、21、29;专项深挖:18、19、29
FY3/26 release, cross-shareholding disclosure怎么使用:支持证据;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/26 release, balance sheet;直接证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域18) / 历史/同业比较(研究域26)|G-Biz Info extract of the FY3/26 securities report indicators;直接证据 / 支持证据|FY3/26 release, liabilities detail;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|FY3/26 release, market-value equity ratio;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据|H1 FY3/27 release, debt movements;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|H1 FY3/27 release, equity movements and valuation reserves;支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;支持证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure
完整研究记录(核对用)
研究原文:Equity ratio 53.0% at FY3/26 (51.0% at H1 FY3/27), rising from 39.9% over five years; net assets JPY 146,843m; gross interest-bearing debt about JPY 58.7bn against cash of about JPY 29.4bn at FY3/26 (net debt near JPY 29bn), rising to about JPY 39.4bn net at 30 September 2026 after the inventory build and bond refinancing - still modest against equity. Investment securities of JPY 26,713m (JPY 28,680m at H1) and land at JPY 15,244m book give non-operating backing, and the market-value equity ratio was 23.1% at FY3/26. Book value per share compounded from JPY 6,660.64 to JPY 6,863.81 in six months despite a loss-making steel half.
内部研究类型:financial_resilience_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A thick equity layer absorbs the cycle rather than transmitting it to solvency, which underwrites the dividend formula and buyback.
不确定性(原始记录):Maturity ladder of the remaining JPY 18,000m of bonds and covenant detail not extracted; consolidated cash availability to the parent not analysed.
F016|09|下行保护是财务性的,不是经营性的
研究范围:35项覆盖检查
写入正文:09|下行保护是财务性的,不是经营性的
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 release, balance sheet怎么使用:直接证据
FY3/26 release, balance sheet detail怎么使用:直接证据;一手验证:18、21、29;专项深挖:18、19、29
H1 FY3/27 release, equity movements and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21
查看完整证据标签(核对用)
直接证据|FY3/26 release, balance sheet;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|H1 FY3/27 release, equity movements and valuation reserves
完整研究记录(核对用)
研究原文:Land is carried at JPY 15,244m book value (head office and plant sites at historical cost); its market value is not disclosed in the sources used, so it is an unquantified option that historical-cost accounting leaves off the valuation table. Investment securities, by contrast, are fully observable at fair value, with a JPY 13,239m unrealised-gain reserve inside net assets.
内部研究类型:unquantified_asset_option
内部来源标记:COVERAGE35
普通股东含义(原始记录):At about 0.46 times book the market pays for neither block at full value; the securities alone approximate a large fraction of market capitalisation, while land realisability and tax leakage on any monetisation are unknown.
不确定性(原始记录):No appraisal, encumbrance or tax-basis information; realisability and management willingness to monetise are unproven.
F017|08|持股削减在出售上有进展,在比例上没有
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 release, balance sheet怎么使用:直接证据
FY3/26 release, extraordinary items怎么使用:直接证据
FY3/26 release, policy shareholdings怎么使用:直接 / 支持
FY3/26 release, cross-shareholding disclosure怎么使用:直接 / 支持;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
H1 FY3/27 release, extraordinary items怎么使用:直接 / 支持;一手验证:16;专项深挖:16;同业比较:32;其他用途:历史
FY3/26 release, cash-flow statement怎么使用:直接证据;一手验证:17
查看完整证据标签(核对用)
直接证据|FY3/26 release, balance sheet;直接证据|FY3/26 release, extraordinary items;直接证据 / 支持证据|FY3/26 release, policy shareholdings;直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域16)|H1 FY3/27 release, extraordinary items;直接证据 / 一手证据(研究域17)|FY3/26 release, cash-flow statement
完整研究记录(核对用)
研究原文:Policy shareholdings stood at 11.3% of consolidated net assets at March 2026 (14.8% earlier); the sub-10% goal was missed on market prices and its deadline extended to March 2027. Disposals are real (JPY 7,143m gain in FY3/26, JPY 1,371m in H1 FY3/27, JPY 12,446m of FY3/26 proceeds recycled into debt repayment, dividends and buybacks) but the ratio lags because remaining holdings appreciated; investment-securities book value rose again to JPY 28,680m at September 2026. The programme is measurable in sales but not yet in the ratio.
内部研究类型:balance_sheet_conversion_programme
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A source of both reported profit and balance-sheet optionality, but a second extension would damage the credibility of the conversion pattern.
不确定性(原始记录):Whether the March 2027 target is met through disposals rather than price moves is open.
F018|08|股息锚定账面价值,不锚定利润
研究范围:开放研究+35项覆盖检查
写入正文:08|股息锚定账面价值,不锚定利润14|八个维度的得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 release, dividend policy and forecast怎么使用:直接 / 支持
FY3/26 release, dividends and per-share data怎么使用:直接 / 支持;一手验证:26;专项深挖:26、27
FY3/26 release, dividend forecast detail怎么使用:直接 / 支持
H1 FY3/27 release, share counts and balance sheet怎么使用:直接 / 支持;反向验证:01;同业比较:07、24;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/26 release, dividend policy and forecast;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域27)|FY3/26 release, dividends and per-share data;直接证据 / 支持证据|FY3/26 release, dividend forecast detail;直接证据 / 支持证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域24) / 反证(研究域01)|H1 FY3/27 release, share counts and balance sheet
完整研究记录(核对用)
研究原文:Shareholder returns follow a stated formula: a progressive dividend with a DOE guide of about 2.5% during the plan, paid at JPY 85, 103, 130 and guided to JPY 135 for FY3/27 (a 37.9% payout on the revised EPS forecast) even though the initial FY3/27 profit forecast fell. Because it is anchored to book value, the dividend ratchets with the balance sheet rather than the steel cycle and has been executed through a loss-making steel half; behaviour in a consolidated loss year is untested since adoption. Financial policy is formulaic and defensive: 53.0% equity ratio, DOE-anchored dividend and an annual August buyback.
内部研究类型:capital_return_policy
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The dividend is the most reliable number in the equity story and yields about 4.3-4.5% on the guide, paying holders to wait while earnings quality resolves.
不确定性(原始记录):The successor plan's return framework after FY2027 is unknown; no fixed buyback amount is committed.
F019|08|回购是常设工具,每年8月执行,只会减少股数
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY3/27 release, share counts and balance sheet怎么使用:直接证据;反向验证:01;同业比较:07、24;其他用途:历史
H1 FY3/27 release, share counts怎么使用:直接 / 支持;一手验证:24、26;专项深挖:24、26
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域24) / 反证(研究域01)|H1 FY3/27 release, share counts and balance sheet;直接证据 / 支持证据 / 一手证据(研究域24) / 一手证据(研究域26) / 定向深挖(研究域24) / 定向深挖(研究域26)|H1 FY3/27 release, share counts
完整研究记录(核对用)
研究原文:Buybacks are a standing August instrument, not a signal: treasury stock rose from 8.4% to 12.0% of issued shares (2,900,013 shares) in eighteen months, shrinking the share count on which per-share metrics are computed and compounding book value per share independently of the steel cycle. Share-count denominators therefore matter in per-share valuation (issued 24,077,510 versus ex-treasury).
内部研究类型:per_share_compounding_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The share count only falls; dilution is not part of this story.
不确定性(原始记录):Buyback prices versus book and funding source (partly securities proceeds) not analysed.
F020|04|日本制铁既是最大股东,又是钢铁业务的供应方和客户
研究范围:开放研究+35项覆盖检查
写入正文:04|日本制铁既是最大股东,又是钢铁业务的供应方和客户07|最大股东是商业伙伴,控制权事件的可能性很低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Notice on matters concerning controlling shareholders etc., 25 June 2026怎么使用:直接 / 支持;一手验证:07、23
Controlling-shareholder matters notice, 25 June 2026, shareholding table怎么使用:直接证据;一手验证:06、07、24;专项深挖:06、07、23、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域23)|Notice on matters concerning controlling shareholders etc., 25 June 2026;直接证据 / 一手证据(研究域06) / 一手证据(研究域07) / 一手证据(研究域24) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域23) / 定向深挖(研究域24)|Controlling-shareholder matters notice, 25 June 2026, shareholding table
完整研究记录(核对用)
研究原文:Nippon Steel holds 23.0% of voting rights (22.1% direct plus 0.9% aggregated; 22.01% of shares excluding treasury) as an equity-method alliance partner. It is simultaneously a register stabiliser, a supplier of part of the raw material and a customer for toll rolling, giving it commercial ties in both directions with the steel business, yet the filing states it holds no approval right over management. Ownership, governance and the steel segment's commercial position therefore cannot be analysed apart from each other.
内部研究类型:anchor_shareholder_relationship
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Aligns the steel business commercially with Japan's largest steelmaker without conferring control; the anchor's own portfolio policy is the one slow variable.
不确定性(原始记录):Alliance economics (volumes, pricing terms) and any change in the holding policy are not disclosed.
F021|07|最大股东是商业伙伴,控制权事件的可能性很低
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Controlling-shareholder matters notice, 25 June 2026, shareholding table怎么使用:直接 / 支持;一手验证:06、07、24;专项深挖:06、07、23、24
Notice on matters concerning controlling shareholders etc., 25 June 2026怎么使用:直接证据;一手验证:07、23
H1 FY3/27 release, share counts怎么使用:直接证据;一手验证:24、26;专项深挖:24、26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域07) / 一手证据(研究域24) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域23) / 定向深挖(研究域24)|Controlling-shareholder matters notice, 25 June 2026, shareholding table;直接证据 / 一手证据(研究域07) / 一手证据(研究域23)|Notice on matters concerning controlling shareholders etc., 25 June 2026;直接证据 / 一手证据(研究域24) / 一手证据(研究域26) / 定向深挖(研究域24) / 定向深挖(研究域26)|H1 FY3/27 release, share counts
完整研究记录(核对用)
研究原文:The 23.0% commercial-alliance holding stabilises the register and caps the probability of register-driven events; hostile or abrupt register change is unlikely, so the governance debate is operational rather than about control. The rising treasury share quietly concentrates remaining holders.
内部研究类型:register_stability_judgment
内部来源标记:COVERAGE35
普通股东含义(原始记录):Register-driven catalysts are unlikely; re-rating must come from earnings and capital policy.
不确定性(原始记录):Large-shareholding reports and the full register were not examined beyond the anchor.
F022|07|治理方向与低市净率公司被要求的方向一致
研究范围:开放研究+35项覆盖检查
写入正文:07|治理方向与低市净率公司被要求的方向一致14|八个维度的得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Company IR news list, 2026 entries怎么使用:直接证据;一手验证:13;同业比较:23;其他用途:历史
IR news list 2026: governance and capital items怎么使用:直接 / 支持;一手验证:23;专项深挖:13、23
Notice on matters concerning controlling shareholders etc., 25 June 2026怎么使用:直接证据;一手验证:07、23
Vendor snapshot retrieved 9 November 2026怎么使用:支持证据;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域23)|Company IR news list, 2026 entries;直接证据 / 支持证据 / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|IR news list 2026: governance and capital items;直接证据 / 一手证据(研究域07) / 一手证据(研究域23)|Notice on matters concerning controlling shareholders etc., 25 June 2026;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026
完整研究记录(核对用)
研究原文:Governance is moving in the direction the market asks of low price-to-book companies: transition to an audit-and-supervisory-committee structure announced March 2026, a published and updated cost-of-capital response, takeover defence abolished May 2025, active subsidiary portfolio changes and the annual buyback. It supports the re-rating case at about 0.46 times book but does not change near-term earnings.
内部研究类型:governance_direction
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A mild positive for the multiple, not a thesis driver.
不确定性(原始记录):Post-transition board independence and skill composition not extracted.
F023|09|交易所对低于净资产倍率公司的压力,是缓慢而无日期的助力
研究范围:开放研究
写入正文:09|交易所对低于净资产倍率公司的压力,是缓慢而无日期的助力
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Company IR news list, 2026 entries怎么使用:直接证据;一手验证:13;同业比较:23;其他用途:历史
Vendor snapshot retrieved 9 November 2026怎么使用:直接证据;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域23)|Company IR news list, 2026 entries;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026
完整研究记录(核对用)
研究原文:Tokyo Stock Exchange pressure on companies trading below book value addresses a population this stock sits squarely in at about 0.46 times book; the updated cost-of-capital response, the buyback cadence and the cross-shareholding programme are the company's documented answers.
内部研究类型:policy_context
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Provides external pressure that can convert balance-sheet assets and capital discipline into a narrower discount.
不确定性(原始记录):Content of the March 2026 response not extracted; policy pressure is a slow, non-dated catalyst.
F024|09|市场给资产负债表打对折,同时对盈利给了正常倍数
研究范围:开放研究+35项覆盖检查
写入正文:09|市场给资产负债表打对折,同时对盈利给了正常倍数12|市场相信资产负债表、怀疑盈利,价格里的未来是最平淡的那个14|八个维度的得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Vendor snapshot retrieved 9 November 2026怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接 / 支持;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
FY3/26 release, market-value equity ratio怎么使用:直接证据;一手验证:31;专项深挖:31
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|FY3/26 release, market-value equity ratio;直接证据|H1 FY3/27 release, 6 November 2026, summary tables;支持证据|H1 FY3/27 release, segment information
完整研究记录(核对用)
研究原文:The market prices the balance sheet at about half its book value and mid-cycle earnings at a full multiple: at JPY 3,130 after the November revision the equity was valued at roughly JPY 66-69bn (66bn on ex-treasury shares), about 0.46 times H1 book value per share of JPY 6,863.81 and about 8.8 times the revised FY3/27 EPS forecast of JPY 356.04 (6.7 times FY3/26 EPS, which contains one-off gains), with a dividend yield of about 4.3%. The +5.03% one-day response credited the revision without re-rating the structure. Embedded expectations are low and specific (deliver the revised forecast, keep the dividend formula, no steel surprise); the market believes the balance sheet and doubts the earnings, which matches the evidence. The price pays for balance-sheet repair and parts durability but not for a steel recovery or a failure of the H2 plan, and the gap closes only if through-cycle earnings rise or balance-sheet conversion accelerates.
内部研究类型:valuation_expectations_judgment
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The priced-in future is the dull one; both the steel option and balance-sheet conversion sit outside it, so shareholders are paid to wait while the earnings-quality question resolves.
不确定性(原始记录):Market expectations are inferred from price and multiples, not analyst consensus; peer multiples were not pulled; the FY3/26 P/E is shown for reference only.
F025|09|估值数字:价格是账面价值的一半,倍数口径要分清
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论09|估值数字:价格是账面价值的一半,倍数口径要分清15|数据来源与日期15|证据限制与口径说明
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Vendor snapshot retrieved 9 November 2026怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
H1 FY3/27 release, share counts and balance sheet怎么使用:直接 / 支持;反向验证:01;同业比较:07、24;其他用途:历史
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:直接 / 支持;一手验证:01
FY3/26 release, cash-flow statement怎么使用:直接 / 支持;一手验证:17
FY3/26 release, dividend policy and forecast怎么使用:直接 / 支持
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026;直接证据 / 支持证据|H1 FY3/27 release, 6 November 2026, summary tables;直接证据 / 支持证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域24) / 反证(研究域01)|H1 FY3/27 release, share counts and balance sheet;直接证据 / 支持证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;直接证据 / 支持证据 / 一手证据(研究域17)|FY3/26 release, cash-flow statement;直接证据 / 支持证据|FY3/26 release, dividend policy and forecast
完整研究记录(核对用)
研究原文:Valuation snapshot at the research cut-off (close of 6 November 2026; cut-off 9 November 2026): share price JPY 2,980; market capitalisation JPY 71.75bn (on 24,077,510 shares issued, including treasury shares); forecast PER 8.4x on revised FY3/27 EPS of JPY 356.04; actual PBR 0.45x on FY3/26-end net assets per share of JPY 6,660.64; FY3/26 reported ROE 7.3% (includes policy-shareholding sale gains); forecast dividend yield 4.53% on the FY3/27 JPY 135 forecast; EV/EBITDA 5.7x (EV JPY 111.18bn = market cap plus net interest-bearing debt of JPY 39,427m at 30 September 2026, being short-term borrowings JPY 32,235m, bonds JPY 18,000m and long-term borrowings JPY 20,645m less cash JPY 31,453m; EBITDA JPY 19.56bn = FY3/26 operating profit JPY 7,783m plus depreciation JPY 11,777m). Basis differences versus the post-reaction view (JPY 3,130 on 9 November; 0.46x on H1 book value; ex-treasury market value about JPY 66bn) must be kept distinct: different price date, share-count basis and book-value date. The EV/EBITDA mixes a September 2026 net-debt figure, inflated by the scrap-driven inventory build, with FY3/26 EBITDA.
内部研究类型:valuation_snapshot_with_basis
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Reference multiples for the point-in-time price; the discount to book and mid-single-digit EV/EBITDA frame the margin of safety but rest on mixed period bases.
不确定性(原始记录):Multiples mix price dates, share counts (issued versus ex-treasury), book-value dates and a period-mismatched EBITDA; they are derived inferences, not primary facts.
F026|03|增长方向目前只是选择权,没有被价格包含,也无法估价
研究范围:开放研究+35项覆盖检查
写入正文:03|增长方向目前只是选择权,没有被价格包含,也无法估价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 release, medium-term plan growth fields怎么使用:直接 / 支持;一手验证:03、04、11;专项深挖:03、04、07、09、11、30
132nd-term securities report, business description怎么使用:直接证据;一手验证:02、03、04、08、09、10
FY3/26 release, segment narrative - parts怎么使用:直接证据;一手验证:05、10;专项深挖:02、03、04、08、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域11) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域07) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域30)|FY3/26 release, medium-term plan growth fields;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|132nd-term securities report, business description;直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts
完整研究记录(核对用)
研究原文:The named growth fields - aluminium wheels in India and Indonesia (lightweighting plus new geographies), forged aluminium wheels for commercial vehicles and recycling - carry no disclosed capex, capacity or return figures, so they are options on the story rather than part of the priced earnings base. Technology is cumulative process metallurgy (electric-furnace steelmaking, integrated rolling and forming, aluminium light-weighting), without R&D spending figures in the record; it supports the mix-shift story but not a growth multiple.
内部研究类型:unpriced_growth_option
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The equity case does not require a technology breakthrough; any success is upside outside the price.
不确定性(原始记录):Volumes, capacity, returns, alliance terms and R&D spending are unknown.
F027|11|宏观风险走的是价格通道,不是销量通道
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY3/27 release, steel business narrative怎么使用:直接证据;一手验证:06、14
FY3/26 release, external environment narrative怎么使用:直接证据;一手验证:13、14
FY3/26 release, segment narrative怎么使用:直接证据;一手验证:02;同业比较:06、14;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 一手证据(研究域14)|H1 FY3/27 release, steel business narrative;直接证据 / 一手证据(研究域13) / 一手证据(研究域14)|FY3/26 release, external environment narrative;直接证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative
完整研究记录(核对用)
研究原文:Macro reaches this P&L through prices, not volumes. Scrap prices (steel spread and inventory values), Middle East-linked energy prices (electric-furnace costs, flagged by the company for H2 FY3/27), exchange rates (a named contributor to H1 parts profit) and US trade policy are the four documented channels. Scrap is bought at market with some raw-material purchases from Nippon Steel; selling prices catch up only through negotiation, and that lag is the transmission mechanism. US tariff exposure on parts was negotiated to limited impact in FY3/26, removing one feared drag.
内部研究类型:external_input_price_exposure
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Macro monitoring for this stock means watching the scrap price, energy and the yen, not GDP.
不确定性(原始记录):Quantified sensitivities, scrap procurement terms, hedging and the FY3/27 tariff outcome are undisclosed.
F028|03|需求集中在工程机械周期,上一轮高峰靠的也是它
研究范围:开放研究+35项覆盖检查
写入正文:03|需求集中在工程机械周期,上一轮高峰靠的也是它
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY3/27 release, 4 August 2026, summary and revision怎么使用:直接证据;一手验证:05;专项深挖:05、11
FY3/26 release, segment narrative - parts怎么使用:直接证据;一手验证:05、10;专项深挖:02、03、04、08、10
H1 FY3/27 release, segment information - steel怎么使用:直接证据;一手验证:11、35;专项深挖:14、35
查看完整证据标签(核对用)
直接证据|H1 FY3/27 release, segment information;直接证据 / 一手证据(研究域05) / 定向深挖(研究域05) / 定向深挖(研究域11)|Q1 FY3/27 release, 4 August 2026, summary and revision;直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;直接证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel
完整研究记录(核对用)
研究原文:Construction-machinery production drives demand for undercarriage components, the parts segment's largest current growth source; it drove the H1 FY3/27 beat and carries the second-half plan, while passenger-car wheel volumes had declined in FY3/26. Demand is derived from OEM production schedules, cyclical with machinery and construction cycles, and the demand that carries the current forecast is the same demand that carried the last peak.
内部研究类型:end_market_driver
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Concentration in one cycle is the exposure behind the parts engine.
不确定性(原始记录):No customer concentration, order backlog or OEM production plans for H2 are disclosed.
F029|04|竞争对手一侧没有可用的数据,行业地位只能靠公司自述
研究范围:35项覆盖检查
写入正文:04|竞争对手一侧没有可用的数据,行业地位只能靠公司自述05|护城河只在零部件,钢铁没有14|八个维度的得分与一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 release, segment narrative - parts怎么使用:直接证据;一手验证:05、10;专项深挖:02、03、04、08、10
132nd-term securities report, business description怎么使用:直接证据;一手验证:02、03、04、08、09、10
Securities-report indicators via G-Biz Info怎么使用:直接证据;一手验证:08、09;专项深挖:01、08、09
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|132nd-term securities report, business description;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 定向深挖(研究域01) / 定向深挖(研究域08) / 定向深挖(研究域09)|Securities-report indicators via G-Biz Info
完整研究记录(核对用)
研究原文:The one genuine moat sits in components: wheels and undercarriage parts are qualified into OEM programmes, switching costs sit with the customer, and incumbency persists, but the rent is collected only through periodic price negotiation, so the pricing framework matters as much as qualification. Steel is undifferentiated and priced against the scrap spread; the moat does not extend there. Valuation should not average a moated parts business with an unmoated steel business.
内部研究类型:competitive_position_judgment
内部来源标记:COVERAGE35
普通股东含义(原始记录):Pricing discipline once established with OEMs is a defensible asset; the steel side has no such protection.
不确定性(原始记录):No competitor financials or third-party market-share data were pulled; position is stated qualitatively from company disclosure, and the framework has not survived a full negotiation round.
F030|06|收入看分部组合,不看增长率
研究范围:35项覆盖检查
写入正文:06|收入看分部组合,不看增长率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 release, segment revenue mix (computed on reported segment totals)怎么使用:直接证据;一手验证:15;专项深挖:15
H1 FY3/27 release, 6 November 2026, summary tables怎么使用:直接证据;一手验证:15;反向验证:35
H1 FY3/27 release, segment information - steel怎么使用:直接证据;一手验证:11、35;专项深挖:14、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|FY3/26 release, segment revenue mix (computed on reported segment totals);直接证据 / 一手证据(研究域15) / 反证(研究域35)|H1 FY3/27 release, 6 November 2026, summary tables;直接证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据|H1 FY3/27 release, segment information
完整研究记录(核对用)
研究原文:FY3/26 revenue fell 1.0% on price and mix (steel down, parts up 5.7% on repricing); H1 FY3/27 revenue rose 9.7% led by parts volumes (external +16.2%) while steel external sales fell 3.4% despite price increases. Segment totals include intersegment sales (about JPY 10.7bn in steel), so shares are indicative. Each yen shifted from steel products to qualified components carries roughly double the margin, so flat group sales can still mean rising profit capacity.
内部研究类型:revenue_quality_finding
内部来源标记:COVERAGE35
普通股东含义(原始记录):Judge revenue by segment composition, not growth rate.
不确定性(原始记录):External-only segment revenue for the full year and sub-segment volume/price splits are not disclosed.
F031|06|经营现金流够覆盖投资,但回报由出售证券共同出资
研究范围:开放研究+35项覆盖检查
写入正文:06|经营现金流够覆盖投资,但回报由出售证券共同出资08|证券出售、还款、分红和回购连成一个循环,但供应有限
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 release, cash-flow statement怎么使用:直接证据;一手验证:17
FY3/26 release, cash-flow detail怎么使用:直接证据;一手验证:17、19、20、25;专项深挖:17、20、25
H1 FY3/27 release, forecast revision and outlook怎么使用:直接证据;一手验证:20;同业比较:27、31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域17)|FY3/26 release, cash-flow statement;直接证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域25) / 定向深挖(研究域17) / 定向深挖(研究域20) / 定向深挖(研究域25)|FY3/26 release, cash-flow detail;直接证据 / 一手证据(研究域20) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|H1 FY3/27 release, forecast revision and outlook
完整研究记录(核对用)
研究原文:FY3/26 operating cash flow of JPY 13,129m covered capital expenditure of JPY 9,911m (below depreciation of JPY 11,777m, a harvesting posture), but investing cash flow was positive only because of JPY 12,446m of securities-sale proceeds, and financing absorbed JPY 13,678m of debt repayment, dividends and buybacks. Free cash flow after capex is real but modest; the generous FY3/26 returns were co-funded by asset sales. The H1 FY3/27 release announced a new Sanwa Parts crawler-works plant to optimise undercarriage production - capital following the parts margin.
内部研究类型:cash_and_capital_deployment
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operations fund the factory and the portfolio funds deleveraging; whether FY3/27 operating cash covers capex and the raised dividend without further asset sales is unknown.
不确定性(原始记录):Plant cost, capacity and savings undisclosed; H1 FY3/27 cash flow not in the interim release.
F032|02|三个阶段说明零部件主导的格局还很新
研究范围:35项覆盖检查
写入正文:02|三个阶段说明零部件主导的格局还很新
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Company financial highlights, five-year record怎么使用:直接证据;同业比较:02、05、09、10、11、12、17、19、20、25、28;其他用途:历史
G-Biz Info extract of the FY3/26 securities report indicators怎么使用:直接证据;同业比较:01、18、26;其他用途:历史
Ten-year financial summary (securities-report based)怎么使用:直接证据;一手验证:12;同业比较:03、04、08、33;其他用途:历史
Company highlights, five-year profit record怎么使用:直接证据;一手验证:12、28、33;反向验证:29;专项深挖:12、28、33、34;同业比较:15、16、22、29、34、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25) / 历史/同业比较(研究域28)|Company financial highlights, five-year record;直接证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域18) / 历史/同业比较(研究域26)|G-Biz Info extract of the FY3/26 securities report indicators;直接证据 / 一手证据(研究域12) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域08) / 历史/同业比较(研究域33)|Ten-year financial summary (securities-report based);直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域22) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35) / 反证(研究域29) / 定向深挖(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域33) / 定向深挖(研究域34)|Company highlights, five-year profit record
完整研究记录(核对用)
研究原文:Three regimes: 2021-22, pandemic and steel downturn with consecutive operating losses and a price low of JPY 990 in April 2022; FY3/23-24, steel-price inflation carrying sales to JPY 334,496m and operating profit to the JPY 10,440m peak; FY3/26, the parts margin reset (profit +145.5%) replacing steel as the engine while portfolio sales began funding returns. The equity ratio's climb from 39.9% to 53.0% is the financial signature. The parts-led configuration is the newest and least tested.
内部研究类型:historical_turning_points
内部来源标记:COVERAGE35
普通股东含义(原始记录):History argues for judging the current regime on its own evidence (about two years) rather than the longer steel-led average.
不确定性(原始记录):Intra-year timing follows release calendar; regime durability unproven.
F033|09|下行保护是财务性的,不是经营性的
研究范围:35项覆盖检查
写入正文:09|下行保护是财务性的,不是经营性的
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 release, balance sheet怎么使用:直接证据
FY3/26 release, liabilities detail怎么使用:直接证据
FY3/26 release, market-value equity ratio怎么使用:直接证据;一手验证:31;专项深挖:31
H1 FY3/27 release, balance sheet怎么使用:直接证据;一手验证:18、29;专项深挖:18、20、29
Company highlights, five-year profit record怎么使用:直接证据;一手验证:12、28、33;反向验证:29;专项深挖:12、28、33、34;同业比较:15、16、22、29、34、35;其他用途:历史
查看完整证据标签(核对用)
直接证据|FY3/26 release, balance sheet;直接证据|FY3/26 release, liabilities detail;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|FY3/26 release, market-value equity ratio;直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域22) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35) / 反证(研究域29) / 定向深挖(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域33) / 定向深挖(研究域34)|Company highlights, five-year profit record
完整研究记录(核对用)
研究原文:Downside layers: a 51-53% equity ratio; cash of about JPY 28-31bn plus a sellable securities portfolio of JPY 28,680m; a dividend anchored to book value rather than earnings; a parts business that stayed profitable through the steel downturn; an anchor shareholder with commercial reasons to hold. Counterweight: the register produced operating losses in FY3/21 and FY3/22, so protection is financial, not operational. A bad year costs earnings and multiple, not solvency or the dividend formula, provided the securities portfolio remains saleable near book (untested in a disorderly market).
内部研究类型:downside_protection_layers
内部来源标记:COVERAGE35
普通股东含义(原始记录):Asymmetry supports holding through the cycle rather than trading it.
不确定性(原始记录):DOE dividend in a consolidated loss year is untested; securities saleability under stress and cash availability at the parent unknown.
F034|11|每个催化剂作用在估值的不同一环
研究范围:35项覆盖检查
写入正文:11|每个催化剂作用在估值的不同一环
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
FY3/26 release, cross-shareholding disclosure怎么使用:直接证据;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
FY3/26 release, medium-term plan growth fields怎么使用:直接证据;一手验证:03、04、11;专项深挖:03、04、07、09、11、30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域11) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域07) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域30)|FY3/26 release, medium-term plan growth fields
完整研究记录(核对用)
研究原文:Each catalyst works on a different term of the valuation: Q3 FY3/27 and H2 delivery against the JPY 4,889m bridge (earnings proof); the successor to 'Active & Challenge 2027' (framework, including whether ROE ambition exceeds 6%); completion of the sub-10% cross-shareholding target by March 2027 (balance-sheet conversion); any quantification of aluminium-wheel expansion; continued buybacks (per-share compounding).
内部研究类型:catalyst_calendar
内部来源标记:COVERAGE35
普通股东含义(原始记录):The investor is not waiting on a single event; proof points arrive quarterly.
不确定性(原始记录):Timing beyond the disclosure calendar is uncertain.
F035|12|上行与下行都押在两个领域的乘积上
研究范围:开放研究+35项覆盖检查
写入正文:12|上行与下行都押在两个领域的乘积上
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
H1 FY3/27 release, segment information - steel怎么使用:直接证据;一手验证:11、35;专项深挖:14、35
H1 FY3/27 release, segment information - parts怎么使用:直接证据;一手验证:32;专项深挖:05、10、14、15、32
G-Biz Info extract of the FY3/26 securities report indicators怎么使用:直接证据;同业比较:01、18、26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域18) / 历史/同业比较(研究域26)|G-Biz Info extract of the FY3/26 securities report indicators
完整研究记录(核对用)
研究原文:Scenario value is concentrated in one interaction: if parts pricing durability (a business-model fact) holds while the steel spread merely stops worsening (a market fact), consolidated operating profit approaches the FY3/24 peak with a far stronger balance sheet than the one that produced it. The re-rating case is the product of the two domains, not of either alone; if the parts reset proves accounting and cycle rather than structure, the stock returns to pure spread-cycle pricing.
内部研究类型:scenario_value_interaction
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Identifies the single interaction on which upside and downside scenarios turn.
不确定性(原始记录):The scenario is conditional and unquantified; neither leg has been observed together through a full cycle.
F036|01|结论:持有观察,不追高,价格里没有钢铁复苏,也没有计划失败
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论01|结论:持有观察,不追高,价格里没有钢铁复苏,也没有计划失败01|什么会推翻这个判断,什么会加强它11|这几个推翻条件各在什么时候能看到14|总分62.81/100,评级 B,整体把握一般15|研究用途与免责
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
H1 FY3/27 release, segment information - steel怎么使用:直接证据;一手验证:11、35;专项深挖:14、35
H1 FY3/27 release, segment information - parts怎么使用:直接证据;一手验证:32;专项深挖:05、10、14、15、32
FY3/26 release, policy shareholdings怎么使用:直接证据
Vendor snapshot retrieved 9 November 2026怎么使用:直接证据;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据|FY3/26 release, policy shareholdings;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026
完整研究记录(核对用)
研究原文:Thesis: Topy has quietly changed which business carries it - a repriced, qualified parts franchise now funds a DOE-anchored, book-compounding return stream on a 51-53% equity-ratio balance sheet, while steel and the securities portfolio are options rather than foundations - and at about 0.46 times book the market still prices the old steel-led company. Evidential weight: one demonstrated fact (parts repricing power), one demonstrated programme (balance-sheet conversion), one unproven option (steel spread normalisation). Falsifiers: (1) the H2 bridge misses with steel still loss-making at Q3; (2) parts margin falls back below about 4% at the next OEM negotiation round or as the pass-through effect annualises out; (3) the cross-shareholding ratio is not below 10% by March 2027 through disposals; (4) on price, a monthly close below JPY 2,615 and decisively below the 60-month average near JPY 2,234. Confirmation: H2 at or above the revised guide with steel at least breakeven, a successor plan raising recurring-ROE ambition, and a monthly close above JPY 3,710. If falsifiers stay silent, expected path is book-value compounding plus a 4.3% yield, with re-rating as upside.
内部研究类型:thesis_and_falsification
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Defines what would confirm or break the holding case; price falsifiers are retained as stated in the Technical-aligned research record.
不确定性(原始记录):Each falsifier is observable within about two quarters except the negotiation-round test, which resolves in the successor plan's first year.
F037|04|竞争对手一侧没有可用的数据,行业地位只能靠公司自述
研究范围:35项覆盖检查
写入正文:04|竞争对手一侧没有可用的数据,行业地位只能靠公司自述13|证据边界一览:这些缺口限制把握,不是负面证据15|证据限制与口径说明
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Securities-report indicators via G-Biz Info怎么使用:直接证据;一手验证:08、09;专项深挖:01、08、09
FY3/26 release, medium-term plan growth fields怎么使用:直接证据;一手验证:03、04、11;专项深挖:03、04、07、09、11、30
H1 FY3/27 release, equity movements and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21
Company IR news list, 2026 entries怎么使用:直接证据;一手验证:13;同业比较:23;其他用途:历史
Controlling-shareholder matters notice, 25 June 2026, shareholding table怎么使用:直接证据;一手验证:06、07、24;专项深挖:06、07、23、24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 定向深挖(研究域01) / 定向深挖(研究域08) / 定向深挖(研究域09)|Securities-report indicators via G-Biz Info;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域11) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域07) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域30)|FY3/26 release, medium-term plan growth fields;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|H1 FY3/27 release, equity movements and valuation reserves;直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域23)|Company IR news list, 2026 entries;直接证据 / 一手证据(研究域06) / 一手证据(研究域07) / 一手证据(研究域24) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域23) / 定向深挖(研究域24)|Controlling-shareholder matters notice, 25 June 2026, shareholding table
完整研究记录(核对用)
研究原文:Material evidence boundaries carried as Research Debt across domains: no competitor financials or margin benchmarks (the thinnest domain); no third-party market-share data; no R&D expenditure figures; no land appraisal; the March 2026 cost-of-capital response not extracted; no analyst consensus or peer multiples; internal transfer economics between steel and parts and alliance terms with Nippon Steel undisclosed; bond maturity profile for the remaining JPY 18,000m and board composition not extracted; scrap procurement terms and any hedging undisclosed; FY3/27 tariff outcome not yet observable; segment capital data for returns-based normalisation absent; ROIC series absent.
内部研究类型:research_debt_evidence_boundaries
内部来源标记:COVERAGE35
普通股东含义(原始记录):These gaps bound confidence on competitive position, relative valuation and capital returns without being negative evidence.
不确定性(原始记录):Several are resolvable through the securities report, integrated report or a dedicated peer pull; none has a reasonable current public path in the supplied record.
F038|06|零部件利润里那笔临时收益有多大,是最先要补上的缺口
研究范围:开放研究+35项覆盖检查
写入正文:06|零部件利润里那笔临时收益有多大,是最先要补上的缺口13|最先要问的两件事:零部件的临时收益有多大,下半期利润从哪里来
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY3/27 release, segment information - parts怎么使用:直接证据;一手验证:32;专项深挖:05、10、14、15、32
查看完整证据标签(核对用)
直接证据|H1 FY3/27 release, segment information;直接证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts
完整研究记录(核对用)
研究原文:How large is the temporary adjustment gain inside H1 FY3/27 parts profit of JPY 7,411m from the change in raw-material pass-through method, and what is the segment's underlying half-year run rate without it? If the gain is large, the 6.7% margin overstates the reset and falsifier (2) moves closer.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Decides whether parts durability, the core thesis leg, is structural.
不确定性(原始记录):Unresolved; next evidence: FY3/27 annual segment note and any briefing materials.
F039|13|最先要问的两件事:零部件的临时收益有多大,下半期利润从哪里来
研究范围:开放研究+35项覆盖检查
写入正文:13|最先要问的两件事:零部件的临时收益有多大,下半期利润从哪里来
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY3/27 release, forecast revision and outlook怎么使用:直接证据;一手验证:20;同业比较:27、31;其他用途:历史
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
H1 FY3/27 release, segment information - steel怎么使用:直接证据;一手验证:11、35;专项深挖:14、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域20) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|H1 FY3/27 release, forecast revision and outlook;直接证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel
完整研究记录(核对用)
研究原文:What scrap-price and selling-price assumptions underpin the revised forecast's implied H2 steel result, and at what scrap level does steel return to profit? Within the JPY 4,889m H2 operating profit, how much comes from steel spread recovery versus parts volumes, and is a segment-level bridge available?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Determines whether the H2 guide is conservative or dependent on steel recovery, i.e. falsifier (1).
不确定性(原始记录):Unresolved; next evidence: Q3 FY3/27 print and briefing materials.
F040|13|会改变回报框架和盈利口径的三件事
研究范围:开放研究+35项覆盖检查
写入正文:13|会改变回报框架和盈利口径的三件事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 release, medium-term plan section怎么使用:直接证据;一手验证:22;同业比较:13;其他用途:历史
FY3/26 release, mid-plan ROE discussion怎么使用:直接证据;一手验证:22;专项深挖:22
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域22) / 历史/同业比较(研究域13)|FY3/26 release, medium-term plan section;直接证据|FY3/26 release, dividend policy and forecast;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|FY3/26 release, mid-plan ROE discussion
完整研究记录(核对用)
研究原文:What does the successor plan after 'Active & Challenge 2027' target for operating profit and ROE, and does the progressive-dividend DOE framework survive into it?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Sets whether recurring ROE ambition rises above 6% and whether the dividend formula persists.
不确定性(原始记录):Future disclosure; no current public path.
F041|08|持股削减在出售上有进展,在比例上没有
研究范围:开放研究+35项覆盖检查
写入正文:08|持股削减在出售上有进展,在比例上没有13|会改变回报框架和盈利口径的三件事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 release, policy shareholdings怎么使用:直接证据
FY3/26 release, cross-shareholding disclosure怎么使用:直接证据;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
H1 FY3/27 release, extraordinary items怎么使用:直接证据;一手验证:16;专项深挖:16;同业比较:32;其他用途:历史
查看完整证据标签(核对用)
直接证据|FY3/26 release, policy shareholdings;直接证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;直接证据 / 一手证据(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域16)|H1 FY3/27 release, extraordinary items
完整研究记录(核对用)
研究原文:Will policy shareholdings fall below 10% of consolidated net assets by March 2027, given investment-securities book value rose again to JPY 28,680m by September 2026 on market prices?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A further missed target would damage the credibility of the balance-sheet conversion pattern (falsifier 3).
不确定性(原始记录):Depends on disposal pace and market prices through March 2027.
F042|13|新增资本能不能赚到高于资本成本的回报
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 release, medium-term plan growth fields怎么使用:直接证据;一手验证:03、04、11;专项深挖:03、04、07、09、11、30
H1 FY3/27 release, forecast revision and outlook怎么使用:直接证据;一手验证:20;同业比较:27、31;其他用途:历史
FY3/26 release, cash-flow detail怎么使用:直接证据;一手验证:17、19、20、25;专项深挖:17、20、25
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域11) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域07) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域30)|FY3/26 release, medium-term plan growth fields;直接证据 / 一手证据(研究域20) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|H1 FY3/27 release, forecast revision and outlook;直接证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域25) / 定向深挖(研究域17) / 定向深挖(研究域20) / 定向深挖(研究域25)|FY3/26 release, cash-flow detail
完整研究记录(核对用)
研究原文:What volumes, capacity and returns are expected from aluminium-wheel expansion in India and Indonesia and forged aluminium wheels for commercial vehicles, and what does the new Sanwa Parts crawler-works plant cost, what production does it consolidate, and what saving or capacity gain does it deliver? Without these, capital deployment returns remain unassessable.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Determines whether incremental capital earns above cost of capital.
不确定性(原始记录):No disclosed figures; next evidence: integrated report, annual report and plant announcements.
F043|13|两个变化慢的因素:联盟股东与杠杆容忍度
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Notice on matters concerning controlling shareholders etc., 25 June 2026怎么使用:直接证据;一手验证:07、23
Controlling-shareholder matters notice, 25 June 2026, shareholding table怎么使用:直接证据;一手验证:06、07、24;专项深挖:06、07、23、24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 一手证据(研究域23)|Notice on matters concerning controlling shareholders etc., 25 June 2026;直接证据 / 一手证据(研究域06) / 一手证据(研究域07) / 一手证据(研究域24) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域23) / 定向深挖(研究域24)|Controlling-shareholder matters notice, 25 June 2026, shareholding table
完整研究记录(核对用)
研究原文:Is any change expected in Nippon Steel's 23.0% holding or the business alliance, in a sector where anchor shareholders have been reducing cross-holdings?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A change would alter register stability and steel-segment commercial flows.
不确定性(原始记录):No current public path; monitor large-shareholding reports.
F044|13|两个变化慢的因素:联盟股东与杠杆容忍度
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY3/27 release, debt movements怎么使用:直接证据
H1 FY3/27 release, balance sheet怎么使用:直接证据;一手验证:18、29;专项深挖:18、20、29
FY3/26 release, liabilities detail怎么使用:直接证据
查看完整证据标签(核对用)
直接证据|H1 FY3/27 release, debt movements;直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据|FY3/26 release, liabilities detail
完整研究记录(核对用)
研究原文:After borrowings rose roughly JPY 19bn in H1 FY3/27 while a JPY 7,000m bond was redeemed, what leverage level does management regard as appropriate for a company with a 53% equity-ratio zone?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Bears on how far scrap-driven working capital can push gross debt before capital policy is constrained.
不确定性(原始记录):Management leverage tolerance not disclosed.
F045|13|会改变回报框架和盈利口径的三件事
研究范围:开放研究+35项覆盖检查
写入正文:13|会改变回报框架和盈利口径的三件事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Company highlights, five-year profit record怎么使用:直接证据;一手验证:12、28、33;反向验证:29;专项深挖:12、28、33、34;同业比较:15、16、22、29、34、35;其他用途:历史
Company financial highlights, five-year record怎么使用:直接证据;同业比较:02、05、09、10、11、12、17、19、20、25、28;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域22) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35) / 反证(研究域29) / 定向深挖(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域33) / 定向深挖(研究域34)|Company highlights, five-year profit record;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25) / 历史/同业比较(研究域28)|Company financial highlights, five-year record
完整研究记录(核对用)
研究原文:What does management regard as through-cycle operating profit of each segment at mid-cycle scrap and construction-demand levels, against the five-year consolidated range of JPY -1,706m to +10,440m?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Would replace this review's constructed normalisation bracket with a company view.
不确定性(原始记录):Management is unlikely to disclose segment through-cycle levels; the review's JPY 5-7bn bracket remains its own construction.
F046|04|日本制铁既是最大股东,又是钢铁业务的供应方和客户
研究范围:开放研究
写入正文:04|日本制铁既是最大股东,又是钢铁业务的供应方和客户07|最大股东是商业伙伴,控制权事件的可能性很低
归并到:F020
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Notice on matters concerning controlling shareholders etc., 25 June 2026怎么使用:直接 / 支持;一手验证:07、23
Controlling-shareholder matters notice, 25 June 2026, shareholding table怎么使用:直接证据;一手验证:06、07、24;专项深挖:06、07、23、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域23)|Notice on matters concerning controlling shareholders etc., 25 June 2026;直接证据 / 一手证据(研究域06) / 一手证据(研究域07) / 一手证据(研究域24) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域23) / 定向深挖(研究域24)|Controlling-shareholder matters notice, 25 June 2026, shareholding table
完整研究记录(核对用)
研究原文:Nippon Steel holds 23.0% of voting rights as an 'other related company' and Topy is its equity-method affiliate under a business alliance; the relationship stabilises and commercially aligns the steel business without conferring control.
内部研究类型:anchor_holder_equity_method_affiliate
内部来源标记:OPEN_DISCOVERY
F047|03|钢铁利润看价差,不看销量
研究范围:开放研究
写入正文:03|钢铁利润看价差,不看销量
归并到:F007
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/26 release, segment narrative怎么使用:直接 / 支持;一手验证:02;同业比较:06、14;其他用途:历史
H1 FY3/27 release, steel business narrative怎么使用:直接 / 支持;一手验证:06、14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14)|H1 FY3/27 release, steel business narrative
完整研究记录(核对用)
研究原文:The steel segment buys scrap at market while its selling prices are negotiated, so scrap plateaus compress the spread until price revisions catch up - the single largest swing factor in consolidated profit.
内部研究类型:input_price_supplier_exposure
内部来源标记:OPEN_DISCOVERY
F048|03|需求集中在工程机械周期,上一轮高峰靠的也是它
研究范围:开放研究
写入正文:03|需求集中在工程机械周期,上一轮高峰靠的也是它
归并到:F028
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Q1 FY3/27 release, 4 August 2026, summary and revision怎么使用:直接证据;一手验证:05;专项深挖:05、11
查看完整证据标签(核对用)
直接证据|H1 FY3/27 release, segment information;直接证据 / 一手证据(研究域05) / 定向深挖(研究域05) / 定向深挖(研究域11)|Q1 FY3/27 release, 4 August 2026, summary and revision
完整研究记录(核对用)
研究原文:Construction-machinery production drives undercarriage component volumes, which drove the H1 FY3/27 beat and carry the second-half plan.
内部研究类型:end_market_demand_driver
内部来源标记:OPEN_DISCOVERY
F049|06|零部件利润里那笔临时收益有多大,是最先要补上的缺口
研究范围:开放研究
写入正文:06|零部件利润里那笔临时收益有多大,是最先要补上的缺口
归并到:F009
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY3/27 release, segment information怎么使用:直接 / 支持
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
查看完整证据标签(核对用)
直接证据 / 支持证据|H1 FY3/27 release, segment information;直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts
完整研究记录(核对用)
研究原文:The change in the raw-material pass-through method produced a temporary H1 gain, meaning part of the record parts profit is an accounting-timing effect rather than run-rate margin.
内部研究类型:qualifies_run_rate
内部来源标记:OPEN_DISCOVERY
F050|06|利润增长要先剥掉三层水分,才看得到经营趋势
研究范围:开放研究
写入正文:06|利润增长要先剥掉三层水分,才看得到经营趋势09|盈利质量决定估值该锚定哪一行利润
归并到:F074
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 release, balance sheet怎么使用:直接证据
FY3/26 release, extraordinary items怎么使用:直接 / 支持
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:支持证据;一手验证:01
FY3/26 release, policy shareholdings怎么使用:支持证据
查看完整证据标签(核对用)
直接证据|FY3/26 release, balance sheet;直接证据 / 支持证据|FY3/26 release, extraordinary items;支持证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;支持证据|FY3/26 release, policy shareholdings
完整研究记录(核对用)
研究原文:Policy shareholdings, held under a public commitment to fall below 10% of net assets, supply both reported profit (JPY 7,143m FY3/26 gain) and balance-sheet optionality, lifting net income and ROE above operating reality.
内部研究类型:inflates_reported_profit
内部来源标记:OPEN_DISCOVERY
F051|08|证券出售、还款、分红和回购连成一个循环,但供应有限
研究范围:开放研究
写入正文:08|证券出售、还款、分红和回购连成一个循环,但供应有限
归并到:F076
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 release, dividend policy and forecast怎么使用:直接 / 支持
H1 FY3/27 release, share counts怎么使用:直接 / 支持;一手验证:24、26;专项深挖:24、26
H1 FY3/27 release, share counts and balance sheet怎么使用:支持证据;反向验证:01;同业比较:07、24;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/26 release, dividend policy and forecast;直接证据 / 支持证据 / 一手证据(研究域24) / 一手证据(研究域26) / 定向深挖(研究域24) / 定向深挖(研究域26)|H1 FY3/27 release, share counts;支持证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域24) / 反证(研究域01)|H1 FY3/27 release, share counts and balance sheet
完整研究记录(核对用)
研究原文:A DOE-anchored progressive dividend converts book-value growth into dividend growth and, with the recurring buyback, mechanically supports per-share metrics even in flat-earnings years.
内部研究类型:formula_supports_per_share
内部来源标记:OPEN_DISCOVERY
F052|09|市场给资产负债表打对折,同时对盈利给了正常倍数
研究范围:开放研究
写入正文:09|市场给资产负债表打对折,同时对盈利给了正常倍数
归并到:F078
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Company IR news list, 2026 entries怎么使用:直接证据;一手验证:13;同业比较:23;其他用途:历史
Vendor snapshot retrieved 9 November 2026怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
IR news list 2026: governance and capital items怎么使用:支持证据;一手验证:23;专项深挖:13、23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域23)|Company IR news list, 2026 entries;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026;支持证据 / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|IR news list 2026: governance and capital items
完整研究记录(核对用)
研究原文:At about 0.46 times book the company sits in the population the exchange's capital-cost reforms address; its cost-of-capital response and buyback cadence are its documented answers and a possible route to a narrower discount.
内部研究类型:external_policy_pressure_on_discount
内部来源标记:OPEN_DISCOVERY
F053|03|两个引擎处在两个周期:废钢价差压钢铁,零部件重新定价托集团
研究范围:开放研究
写入正文:03|两个引擎处在两个周期:废钢价差压钢铁,零部件重新定价托集团
归并到:F073
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 release, segment narrative - parts怎么使用:直接 / 支持;一手验证:05、10;专项深挖:02、03、04、08、10
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
FY3/26 release, segment narrative怎么使用:支持证据;一手验证:02;同业比较:06、14;其他用途:历史
FY3/26 release, segment narrative - steel怎么使用:支持证据;专项深挖:02、06
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;支持证据|H1 FY3/27 release, segment information;支持证据 / 定向深挖(研究域02) / 定向深挖(研究域06)|FY3/26 release, segment narrative - steel
完整研究记录(核对用)
研究原文:Parts profit, driven by vehicle and construction-machinery end demand, now exceeds the consolidated operating profit it feeds; its margin reset carries the group result and steel cannot currently offset a failure.
内部研究类型:drives_consolidated_profit
内部来源标记:OPEN_DISCOVERY
F054|11|下半期要赚到48.89亿日元,钢铁要从亏损走到至少不亏
研究范围:开放研究
写入正文:11|下半期要赚到48.89亿日元,钢铁要从亏损走到至少不亏
归并到:F077
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY3/27 release, segment information - steel怎么使用:直接证据;一手验证:11、35;专项深挖:14、35
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接 / 支持;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast
完整研究记录(核对用)
研究原文:The revised FY3/27 forecast requires steel to move from a JPY 1,283m H1 loss toward breakeven or better in H2 through price increases; the bridge is arithmetically modest but fully exposed to the scrap-versus-price race.
内部研究类型:forecast_dependence
内部来源标记:OPEN_DISCOVERY
F055|08|证券出售、还款、分红和回购连成一个循环,但供应有限
研究范围:开放研究
写入正文:08|证券出售、还款、分红和回购连成一个循环,但供应有限
归并到:F076
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 release, balance sheet detail怎么使用:直接证据;一手验证:18、21、29;专项深挖:18、19、29
FY3/26 release, dividends and per-share data怎么使用:直接 / 支持;一手验证:26;专项深挖:26、27
FY3/26 release, balance sheet怎么使用:支持证据
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域27)|FY3/26 release, dividends and per-share data;支持证据|FY3/26 release, balance sheet;支持证据|FY3/26 release, dividend forecast detail
完整研究记录(核对用)
研究原文:The 51-53% equity ratio and growing book value per share make the DOE dividend formula and annual buyback self-funding, so balance-sheet strength converts directly into shareholder return.
内部研究类型:capital_support_funds_returns
内部来源标记:OPEN_DISCOVERY
F056|07|最大股东是商业伙伴,控制权事件的可能性很低
研究范围:开放研究
归并到:F021
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Controlling-shareholder matters notice, 25 June 2026, shareholding table怎么使用:直接 / 支持;一手验证:06、07、24;专项深挖:06、07、23、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域07) / 一手证据(研究域24) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域23) / 定向深挖(研究域24)|Controlling-shareholder matters notice, 25 June 2026, shareholding table
完整研究记录(核对用)
研究原文:The 23.0% alliance holding with commercial ties in both directions makes hostile or abrupt register change unlikely and anchors governance debate in operations rather than control.
内部研究类型:stabilises
内部来源标记:OPEN_DISCOVERY
F057|06|一个废钢价格,同时推动利润、库存、借款和现金
研究范围:35项覆盖检查+开放研究
写入正文:06|一个废钢价格,同时推动利润、库存、借款和现金
归并到:F075
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
H1 FY3/27 release, steel business narrative怎么使用:直接证据;一手验证:06、14
H1 FY3/27 release, working capital怎么使用:直接 / 支持;一手验证:19;专项深挖:19
H1 FY3/27 release, debt movements怎么使用:直接证据
FY3/26 release, balance sheet怎么使用:支持证据
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 一手证据(研究域14)|H1 FY3/27 release, steel business narrative;直接证据 / 支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|H1 FY3/27 release, working capital;直接证据|H1 FY3/27 release, debt movements;支持证据|H1 FY3/27 release, segment information;支持证据|FY3/26 release, balance sheet
完整研究记录(核对用)
研究原文:The same high scrap plateau that compresses the steel spread inflates inventory values and pushes borrowings up, so one market price moves the P&L, balance sheet and cash flow in the same direction at once.
内部研究类型:same_driver_transmits_to_cash_and_debt
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F058|06|一个废钢价格,同时推动利润、库存、借款和现金
研究范围:35项覆盖检查
写入正文:06|一个废钢价格,同时推动利润、库存、借款和现金
归并到:F075
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY3/27 release, balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、20、29
H1 FY3/27 release, debt movements怎么使用:直接证据
FY3/26 release, liabilities detail怎么使用:直接 / 支持
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据|H1 FY3/27 release, debt movements;直接证据 / 支持证据|FY3/26 release, liabilities detail
完整研究记录(核对用)
研究原文:Inventory and receivable repricing grew assets faster than retained profit, easing the equity ratio from 53.0% to 51.0% and raising net debt, though the base remains strong.
内部研究类型:erodes_equity_ratio
内部来源标记:COVERAGE35
F059|06|总部费用每年吞掉六十多亿日元,把好年份也压成薄利润率
研究范围:35项覆盖检查
写入正文:06|总部费用每年吞掉六十多亿日元,把好年份也压成薄利润率
归并到:F011
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 release, consolidated statements of income怎么使用:直接证据;一手验证:33;专项深挖:01、12、13、17、33、34
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/26 release, segment profit reconciliation (computed from disclosed segment profits);直接证据 / 支持证据|H1 FY3/27 release, segment information - other and adjustments;直接证据 / 一手证据(研究域33) / 定向深挖(研究域01) / 定向深挖(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域17) / 定向深挖(研究域33) / 定向深挖(研究域34)|FY3/26 release, consolidated statements of income
完整研究记录(核对用)
研究原文:A structural JPY 6-6.5bn gap between segment and consolidated profit compresses even a strong parts year to a 2.6% consolidated margin.
内部研究类型:structural_deduction
内部来源标记:COVERAGE35
F060|13|证据边界一览:这些缺口限制把握,不是负面证据
研究范围:35项覆盖检查
写入正文:13|证据边界一览:这些缺口限制把握,不是负面证据
归并到:F080
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts
完整研究记录(核对用)
研究原文:The undisclosed size of the temporary adjustment is carried as the highest-priority Research Debt.
内部研究类型:unresolved_measurement_gap
内部来源标记:COVERAGE35
F061|06|利润增长要先剥掉三层水分,才看得到经营趋势
研究范围:开放研究
写入正文:06|利润增长要先剥掉三层水分,才看得到经营趋势09|盈利质量决定估值该锚定哪一行利润
归并到:F074
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 release, extraordinary items and taxes怎么使用:直接 / 支持;一手验证:16、32;专项深挖:16、32
FY3/26 release, mid-plan ROE discussion怎么使用:直接 / 支持;一手验证:22;专项深挖:22
FY3/26 release, medium-term plan section怎么使用:直接证据;一手验证:22;同业比较:13;其他用途:历史
FY3/26 release, extraordinary items怎么使用:支持证据
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:支持证据;一手验证:01
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|FY3/26 release, extraordinary items and taxes;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域22)|FY3/26 release, mid-plan ROE discussion;直接证据 / 一手证据(研究域22) / 历史/同业比较(研究域13)|FY3/26 release, medium-term plan section;支持证据|FY3/26 release, extraordinary items;支持证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables
完整研究记录(核对用)
研究原文:The one-off securities gain is what lifts reported ROE to 7.3%, above the 6.0% target; ex-gain returns are near or below the target.
内部研究类型:flatters
内部来源标记:OPEN_DISCOVERY
F062|08|证券出售、还款、分红和回购连成一个循环,但供应有限
研究范围:开放研究+35项覆盖检查
写入正文:08|证券出售、还款、分红和回购连成一个循环,但供应有限
归并到:F076
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 release, cash-flow statement怎么使用:直接证据;一手验证:17
FY3/26 release, cash-flow detail怎么使用:直接证据;一手验证:17、19、20、25;专项深挖:17、20、25
FY3/26 release, cross-shareholding disclosure怎么使用:直接证据;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
FY3/26 release, policy shareholdings怎么使用:支持证据
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域17)|FY3/26 release, cash-flow statement;直接证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域25) / 定向深挖(研究域17) / 定向深挖(研究域20) / 定向深挖(研究域25)|FY3/26 release, cash-flow detail;直接证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;支持证据|FY3/26 release, policy shareholdings
完整研究记录(核对用)
研究原文:Securities-sale proceeds of JPY 12,446m went out as debt repayment, dividends and buybacks, so portfolio conversion co-funded FY3/26 returns while operations covered capex.
内部研究类型:proceeds_fund_deleveraging_and_returns
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F063|09|市场给资产负债表打对折,同时对盈利给了正常倍数
研究范围:35项覆盖检查
写入正文:09|市场给资产负债表打对折,同时对盈利给了正常倍数
归并到:F078
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Company highlights, five-year profit record怎么使用:直接 / 支持;一手验证:12、28、33;反向验证:29;专项深挖:12、28、33、34;同业比较:15、16、22、29、34、35;其他用途:历史
Vendor snapshot retrieved 9 November 2026怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
H1 FY3/27 release, revised FY3/27 forecast怎么使用:支持证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域22) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35) / 反证(研究域29) / 定向深挖(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域33) / 定向深挖(研究域34)|Company highlights, five-year profit record;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026;支持证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast
完整研究记录(核对用)
研究原文:Through-cycle operating profit of roughly JPY 5-7bn determines whether the equity at JPY 66-69bn is cheap or full; peak-year multiples are not usable.
内部研究类型:normalisation_basis_for_multiple
内部来源标记:COVERAGE35
F064|09|市场给资产负债表打对折,同时对盈利给了正常倍数
研究范围:35项覆盖检查
写入正文:09|市场给资产负债表打对折,同时对盈利给了正常倍数
归并到:F078
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
H1 FY3/27 release, balance sheet怎么使用:直接证据;一手验证:18、29;专项深挖:18、20、29
FY3/26 release, market-value equity ratio怎么使用:直接证据;一手验证:31;专项深挖:31
H1 FY3/27 release, equity movements and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21
Vendor snapshot retrieved 9 November 2026怎么使用:支持证据;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
FY3/26 release, balance sheet detail怎么使用:支持证据;一手验证:18、21、29;专项深挖:18、19、29
FY3/26 release, cross-shareholding disclosure怎么使用:支持证据;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|FY3/26 release, market-value equity ratio;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|H1 FY3/27 release, equity movements and valuation reserves;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026;支持证据|H1 FY3/27 release, segment information;支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;支持证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure
完整研究记录(核对用)
研究原文:Book value per share of JPY 6,863.81 backed by an equity ratio above 50% gives a floor logic to the 0.46x multiple, but asset value should be read with tax leakage, realisability and parent-availability caveats unresolved.
内部研究类型:asset_backing_against_discount
内部来源标记:COVERAGE35
F065|02|整体面貌:一条链、一个有护城河的引擎、一层厚的资产负债表
研究范围:35项覆盖检查
写入正文:02|整体面貌:一条链、一个有护城河的引擎、一层厚的资产负债表05|护城河要兑现,取决于新价格框架撑过一轮谈判和一个废钢周期
归并到:F072
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 release, segment narrative - parts怎么使用:直接证据;一手验证:05、10;专项深挖:02、03、04、08、10
132nd-term securities report, business description怎么使用:直接证据;一手验证:02、03、04、08、09、10
FY3/26 release, segment narrative怎么使用:支持证据;一手验证:02;同业比较:06、14;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|132nd-term securities report, business description;支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;支持证据|H1 FY3/27 release, segment information
完整研究记录(核对用)
研究原文:OEM qualification and switching costs are the mechanism through which negotiated repricing is collected; the moat supports the parts reset only if the pricing framework survives negotiation rounds.
内部研究类型:supports_pricing_durability
内部来源标记:COVERAGE35
F066|12|上行与下行都押在两个领域的乘积上
研究范围:35项覆盖检查
写入正文:12|上行与下行都押在两个领域的乘积上
归并到:F035
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
H1 FY3/27 release, segment information - parts怎么使用:直接证据;一手验证:32;专项深挖:05、10、14、15、32
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
FY3/26 release, segment narrative怎么使用:支持证据;一手验证:02;同业比较:06、14;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;支持证据|H1 FY3/27 release, segment information
完整研究记录(核对用)
研究原文:Parts pricing durability is one of the two legs whose product defines the re-rating scenario.
内部研究类型:scenario_leg
内部来源标记:COVERAGE35
F067|12|上行与下行都押在两个领域的乘积上
研究范围:35项覆盖检查
写入正文:12|上行与下行都押在两个领域的乘积上
归并到:F035
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY3/27 release, segment information - steel怎么使用:直接 / 支持;一手验证:11、35;专项深挖:14、35
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast
完整研究记录(核对用)
研究原文:Steel spread merely ceasing to worsen is the second leg of the re-rating scenario.
内部研究类型:scenario_leg
内部来源标记:COVERAGE35
F068|01|结论:持有观察,不追高,价格里没有钢铁复苏,也没有计划失败
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|结论:持有观察,不追高,价格里没有钢铁复苏,也没有计划失败01|什么会推翻这个判断,什么会加强它14|总分62.81/100,评级 B,整体把握一般
归并到:F079
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接 / 支持;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
H1 FY3/27 release, segment information - steel怎么使用:直接证据;一手验证:11、35;专项深挖:14、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel
完整研究记录(核对用)
研究原文:A missed H2 bridge with steel still loss-making at Q3 is falsifier (1) of the thesis.
内部研究类型:falsifier_source
内部来源标记:COVERAGE35
F069|01|结论:持有观察,不追高,价格里没有钢铁复苏,也没有计划失败
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|结论:持有观察,不追高,价格里没有钢铁复苏,也没有计划失败01|什么会推翻这个判断,什么会加强它14|总分62.81/100,评级 B,整体把握一般
归并到:F079
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY3/27 release, segment information - parts怎么使用:直接证据;一手验证:32;专项深挖:05、10、14、15、32
H1 FY3/27 release, segment information怎么使用:直接 / 支持
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据 / 支持证据|H1 FY3/27 release, segment information
完整研究记录(核对用)
研究原文:Parts margin falling back below about 4% when the pass-through effect annualises out would show the reset was accounting and cycle, falsifier (2).
内部研究类型:falsifier_source
内部来源标记:COVERAGE35
F070|10|价格对业绩事件的响应偏正面,价格与基本面在等同一个证据
研究范围:开放研究
写入正文:10|价格对业绩事件的响应偏正面,价格与基本面在等同一个证据
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 release, extraordinary items怎么使用:直接 / 支持
H1 FY3/27 release, segment information - parts怎么使用:直接证据;一手验证:32;专项深挖:05、10、14、15、32
H1 FY3/27 release, extraordinary items怎么使用:直接证据;一手验证:16;专项深挖:16;同业比较:32;其他用途:历史
Monthly closes March to October 2026 and trading volume, locally recomputed怎么使用:直接证据;外部现实校验:13、23、30
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:支持证据;一手验证:01
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/26 release, extraordinary items;直接证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据 / 一手证据(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域16)|H1 FY3/27 release, extraordinary items;直接证据 / 外部现实(研究域13) / 外部现实(研究域23) / 外部现实(研究域30)|Monthly closes March to October 2026 and trading volume, locally recomputed;支持证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;支持证据|H1 FY3/27 release, segment information
完整研究记录(核对用)
研究原文:Cross-lane observation only: the fundamental lane's unresolved earnings-quality question (one-off gains in FY3/26, a flagged temporary gain in H1 FY3/27) is the same question the protected Technical State leaves open as 'continuation unconfirmed'. The fundamental positivity of the balance sheet and dividend does not rewrite that independent Technical State, and the Technical State does not alter the fundamental adjudication.
内部研究类型:cross_lane_question_alignment
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F071|09|基本面便宜不能替价格结构背书
写入正文:09|基本面便宜不能替价格结构背书10|价格对业绩事件的响应偏正面,价格与基本面在等同一个证据
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Vendor snapshot retrieved 9 November 2026怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
Monthly closes March to October 2026 and trading volume, locally recomputed怎么使用:直接证据;外部现实校验:13、23、30
Moving averages recomputed on monthly closes at October 2026怎么使用:直接证据;一手验证:34;外部现实校验:06、14、29;反向验证:34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026;直接证据 / 外部现实(研究域13) / 外部现实(研究域23) / 外部现实(研究域30)|Monthly closes March to October 2026 and trading volume, locally recomputed;直接证据 / 一手证据(研究域34) / 外部现实(研究域06) / 外部现实(研究域14) / 外部现实(研究域29) / 反证(研究域34)|Moving averages recomputed on monthly closes at October 2026;支持证据|H1 FY3/27 release, segment information
完整研究记录(核对用)
研究原文:Cross-lane: the fundamental discount-to-book and re-rating optionality is a separate lane from the pure price state; the post-revision +5.03% response to JPY 3,130 is consumed as price-response evidence within the Technical lane, and fundamental cheapness may not upgrade a non-confirming Technical State. The Technical falsifiers (monthly close below JPY 2,615, the 60-month average near JPY 2,234) remain price-defined and are mirrored, not redefined, in the thesis.
内部研究类型:cross_lane_non_rewrite_boundary
内部来源标记:TECHNICAL
F072|02|整体面貌:一条链、一个有护城河的引擎、一层厚的资产负债表
研究范围:开放研究+35项覆盖检查
写入正文:02|整体面貌:一条链、一个有护城河的引擎、一层厚的资产负债表05|护城河要兑现,取决于新价格框架撑过一轮谈判和一个废钢周期
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(34项,重复标签已合并)
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:直接证据;一手验证:01
132nd-term securities report, business description怎么使用:直接证据;一手验证:02、03、04、08、09、10
G-Biz Info company extract怎么使用:直接证据
Securities-report indicators via G-Biz Info怎么使用:直接证据;一手验证:08、09;专项深挖:01、08、09
Company financial highlights, five-year record怎么使用:直接 / 支持;同业比较:02、05、09、10、11、12、17、19、20、25、28;其他用途:历史
G-Biz Info extract of the FY3/26 securities report indicators怎么使用:直接证据;同业比较:01、18、26;其他用途:历史
Ten-year financial summary (securities-report based)怎么使用:直接 / 支持;一手验证:12;同业比较:03、04、08、33;其他用途:历史
Company highlights, five-year profit record怎么使用:直接 / 支持;一手验证:12、28、33;反向验证:29;专项深挖:12、28、33、34;同业比较:15、16、22、29、34、35;其他用途:历史
FY3/26 release, balance sheet怎么使用:直接 / 支持
Notice on matters concerning controlling shareholders etc., 25 June 2026怎么使用:直接 / 支持;一手验证:07、23
FY3/26 release, segment narrative - parts怎么使用:直接 / 支持;一手验证:05、10;专项深挖:02、03、04、08、10
H1 FY3/27 release, segment information怎么使用:直接 / 支持
FY3/26 release, segment narrative怎么使用:直接 / 支持;一手验证:02;同业比较:06、14;其他用途:历史
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
FY3/26 release, segment revenue mix (computed on reported segment totals)怎么使用:直接证据;一手验证:15;专项深挖:15
FY3/26 release, segment narrative - steel怎么使用:直接 / 支持;专项深挖:02、06
H1 FY3/27 release, steel business narrative怎么使用:直接 / 支持;一手验证:06、14
H1 FY3/27 release, segment information - steel怎么使用:直接 / 支持;一手验证:11、35;专项深挖:14、35
FY3/26 release, liabilities detail怎么使用:直接 / 支持
FY3/26 release, market-value equity ratio怎么使用:直接证据;一手验证:31;专项深挖:31
H1 FY3/27 release, balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、20、29
H1 FY3/27 release, debt movements怎么使用:直接证据
H1 FY3/27 release, equity movements and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21
FY3/26 release, balance sheet detail怎么使用:直接 / 支持;一手验证:18、21、29;专项深挖:18、19、29
FY3/26 release, cross-shareholding disclosure怎么使用:支持证据;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
FY3/26 release, dividend policy and forecast怎么使用:直接 / 支持
FY3/26 release, dividends and per-share data怎么使用:直接 / 支持;一手验证:26;专项深挖:26、27
FY3/26 release, dividend forecast detail怎么使用:直接 / 支持
H1 FY3/27 release, share counts and balance sheet怎么使用:直接 / 支持;反向验证:01;同业比较:07、24;其他用途:历史
Controlling-shareholder matters notice, 25 June 2026, shareholding table怎么使用:直接证据;一手验证:06、07、24;专项深挖:06、07、23、24
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
Vendor snapshot retrieved 9 November 2026怎么使用:支持证据;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;直接证据 / 一手证据(研究域01)|132nd-term securities report, filed 24 June 2026, cover and company outline;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|132nd-term securities report, business description;直接证据|G-Biz Info company extract;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 定向深挖(研究域01) / 定向深挖(研究域08) / 定向深挖(研究域09)|Securities-report indicators via G-Biz Info;直接证据|FY3/26 release, parent-company (non-consolidated) results;直接证据 / 支持证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25) / 历史/同业比较(研究域28)|Company financial highlights, five-year record;直接证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域18) / 历史/同业比较(研究域26)|G-Biz Info extract of the FY3/26 securities report indicators;直接证据 / 支持证据 / 一手证据(研究域12) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域08) / 历史/同业比较(研究域33)|Ten-year financial summary (securities-report based);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域22) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35) / 反证(研究域29) / 定向深挖(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域33) / 定向深挖(研究域34)|Company highlights, five-year profit record;直接证据 / 支持证据|FY3/26 release, balance sheet;直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域23)|Notice on matters concerning controlling shareholders etc., 25 June 2026;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;直接证据 / 支持证据|H1 FY3/27 release, segment information;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|FY3/26 release, segment revenue mix (computed on reported segment totals);直接证据 / 支持证据 / 定向深挖(研究域02) / 定向深挖(研究域06)|FY3/26 release, segment narrative - steel;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14)|H1 FY3/27 release, steel business narrative;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 支持证据|FY3/26 release, liabilities detail;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|FY3/26 release, market-value equity ratio;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据|H1 FY3/27 release, debt movements;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|H1 FY3/27 release, equity movements and valuation reserves;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;支持证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;直接证据 / 支持证据|FY3/26 release, dividend policy and forecast;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域27)|FY3/26 release, dividends and per-share data;直接证据 / 支持证据|FY3/26 release, dividend forecast detail;直接证据 / 支持证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域24) / 反证(研究域01)|H1 FY3/27 release, share counts and balance sheet;直接证据 / 一手证据(研究域06) / 一手证据(研究域07) / 一手证据(研究域24) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域23) / 定向深挖(研究域24)|Controlling-shareholder matters notice, 25 June 2026, shareholding table;直接证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026
完整研究记录(核对用)
研究原文:Durable Business Portrait: integrated chain, one moated engine, balance-sheet compounding|The company is an integrated scrap-to-component chain whose profit has moved downstream to a qualified, repriced parts franchise, carried by a conservative balance sheet and a book-value-anchored return formula; steel is a spread-exposed option and the earnings level is cyclical.
内部研究类型:durable_business_portrait_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Own the frame for balance-sheet compounding and demonstrated repricing; value earnings at through-cycle levels.
不确定性(原始记录):Parts durability tested for about two years only; steel viability through a full scrap cycle unproven.
F073|03|两个引擎处在两个周期:废钢价差压钢铁,零部件重新定价托集团
研究范围:开放研究+35项覆盖检查
写入正文:03|两个引擎处在两个周期:废钢价差压钢铁,零部件重新定价托集团
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(17项,重复标签已合并)
H1 FY3/27 release, steel business narrative怎么使用:直接 / 支持;一手验证:06、14
FY3/26 release, external environment narrative怎么使用:直接证据;一手验证:13、14
FY3/26 release, segment narrative怎么使用:直接 / 支持;一手验证:02;同业比较:06、14;其他用途:历史
FY3/26 release, segment narrative - steel怎么使用:直接 / 支持;专项深挖:02、06
H1 FY3/27 release, segment information - steel怎么使用:直接 / 支持;一手验证:11、35;专项深挖:14、35
H1 FY3/27 release, segment information怎么使用:直接 / 支持
Q1 FY3/27 release, 4 August 2026, summary and revision怎么使用:直接证据;一手验证:05;专项深挖:05、11
FY3/26 release, segment narrative - parts怎么使用:直接 / 支持;一手验证:05、10;专项深挖:02、03、04、08、10
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
FY3/26 release, segment revenue mix (computed on reported segment totals)怎么使用:直接证据;一手验证:15;专项深挖:15
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:直接 / 支持;一手验证:01
FY3/26 release, consolidated statements of income怎么使用:直接证据;一手验证:33;专项深挖:01、12、13、17、33、34
Q1 FY3/27 release, 4 August 2026怎么使用:直接证据
H1 FY3/27 release, 6 November 2026, summary tables怎么使用:直接证据;一手验证:15;反向验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14)|H1 FY3/27 release, steel business narrative;直接证据 / 一手证据(研究域13) / 一手证据(研究域14)|FY3/26 release, external environment narrative;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;直接证据 / 支持证据 / 定向深挖(研究域02) / 定向深挖(研究域06)|FY3/26 release, segment narrative - steel;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 支持证据|H1 FY3/27 release, segment information;直接证据 / 一手证据(研究域05) / 定向深挖(研究域05) / 定向深挖(研究域11)|Q1 FY3/27 release, 4 August 2026, summary and revision;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|FY3/26 release, segment revenue mix (computed on reported segment totals);直接证据 / 支持证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;直接证据 / 一手证据(研究域33) / 定向深挖(研究域01) / 定向深挖(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域17) / 定向深挖(研究域33) / 定向深挖(研究域34)|FY3/26 release, consolidated statements of income;直接证据|FY3/26 release, margin structure (computed);直接证据 / 支持证据|FY3/26 release, segment profit reconciliation (computed from disclosed segment profits);直接证据 / 支持证据|H1 FY3/27 release, segment information - other and adjustments;直接证据|Q1 FY3/27 release, 4 August 2026;直接证据 / 一手证据(研究域15) / 反证(研究域35)|H1 FY3/27 release, 6 November 2026, summary tables
完整研究记录(核对用)
研究原文:Two engines, two cycles: scrap spread squeezes steel while parts repricing carries the group|Scrap costs hit steel immediately while selling prices lag; parts repricing and construction-machinery volumes more than offset it at the segment level; a structural corporate drag then converts a strong parts year into a thin consolidated margin.
内部研究类型:main_causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Segment mix matters more than group scale; consolidated profit hinges on the parts margin surviving negotiation and steel stopping its losses.
不确定性(原始记录):Parts underlying run rate unknown because of the unquantified temporary gain.
F074|06|利润增长要先剥掉三层水分,才看得到经营趋势
研究范围:开放研究+35项覆盖检查
写入正文:06|利润增长要先剥掉三层水分,才看得到经营趋势09|盈利质量决定估值该锚定哪一行利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(21项,重复标签已合并)
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:直接 / 支持;一手验证:01
FY3/26 release, segment narrative怎么使用:直接 / 支持;一手验证:02;同业比较:06、14;其他用途:历史
FY3/26 release, consolidated statements of income怎么使用:直接证据;一手验证:33;专项深挖:01、12、13、17、33、34
FY3/26 release, segment narrative - steel怎么使用:直接证据;专项深挖:02、06
FY3/26 release, segment narrative - parts怎么使用:直接证据;一手验证:05、10;专项深挖:02、03、04、08、10
FY3/26 release, extraordinary items怎么使用:直接 / 支持
FY3/26 release, non-operating items怎么使用:直接 / 支持
FY3/26 release, extraordinary items and taxes怎么使用:直接 / 支持;一手验证:16、32;专项深挖:16、32
H1 FY3/27 release, extraordinary items怎么使用:直接 / 支持;一手验证:16;专项深挖:16;同业比较:32;其他用途:历史
FY3/26 release, balance sheet detail怎么使用:直接证据;一手验证:18、21、29;专项深挖:18、19、29
H1 FY3/27 release, revised FY3/27 forecast怎么使用:支持证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
FY3/26 release, medium-term plan section怎么使用:直接 / 支持;一手验证:22;同业比较:13;其他用途:历史
FY3/26 release, mid-plan ROE discussion怎么使用:直接 / 支持;一手验证:22;专项深挖:22
H1 FY3/27 release, segment information怎么使用:直接 / 支持
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
FY3/26 release, balance sheet怎么使用:直接证据
FY3/26 release, policy shareholdings怎么使用:直接 / 支持
FY3/26 release, cross-shareholding disclosure怎么使用:直接 / 支持;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
FY3/26 release, cash-flow statement怎么使用:直接证据;一手验证:17
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;直接证据 / 一手证据(研究域33) / 定向深挖(研究域01) / 定向深挖(研究域12) / 定向深挖(研究域13) / 定向深挖(研究域17) / 定向深挖(研究域33) / 定向深挖(研究域34)|FY3/26 release, consolidated statements of income;直接证据 / 定向深挖(研究域02) / 定向深挖(研究域06)|FY3/26 release, segment narrative - steel;直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;直接证据|FY3/26 release, margin structure (computed);直接证据 / 支持证据|FY3/26 release, extraordinary items;直接证据 / 支持证据|FY3/26 release, non-operating items;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|FY3/26 release, extraordinary items and taxes;直接证据|FY3/26 release, FY3/27 initial forecast;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域16)|H1 FY3/27 release, extraordinary items;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;支持证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域13)|FY3/26 release, medium-term plan section;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域22)|FY3/26 release, mid-plan ROE discussion;直接证据 / 支持证据|H1 FY3/27 release, segment information;直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据|FY3/26 release, balance sheet;直接证据 / 支持证据|FY3/26 release, policy shareholdings;直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;直接证据 / 一手证据(研究域17)|FY3/26 release, cash-flow statement
完整研究记录(核对用)
研究原文:Earnings-quality ladder: operating, ordinary, net profit and ROE|Profit quality is the hinge between domains: the same one-off items that flatter reported earnings (shareholding-sale gains in FY3/26 and H1 FY3/27, the temporary pass-through gain in H1 parts profit) must be stripped to reach ordinary profit of about JPY 8.6bn and a recurring ROE near the 6% target.
内部研究类型:profit_quality_hinge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Anchor valuation to ordinary profit and segment run rates, not reported net income or 7.3% ROE.
不确定性(原始记录):Size of the temporary gain and of remaining saleable holdings.
F075|06|一个废钢价格,同时推动利润、库存、借款和现金
研究范围:开放研究+35项覆盖检查
写入正文:06|一个废钢价格,同时推动利润、库存、借款和现金
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(17项,重复标签已合并)
H1 FY3/27 release, steel business narrative怎么使用:直接 / 支持;一手验证:06、14
FY3/26 release, external environment narrative怎么使用:直接证据;一手验证:13、14
FY3/26 release, segment narrative怎么使用:直接 / 支持;一手验证:02;同业比较:06、14;其他用途:历史
FY3/26 release, segment narrative - steel怎么使用:直接证据;专项深挖:02、06
H1 FY3/27 release, segment information - steel怎么使用:直接 / 支持;一手验证:11、35;专项深挖:14、35
H1 FY3/27 release, segment information怎么使用:直接 / 支持
FY3/26 release, balance sheet怎么使用:直接 / 支持
FY3/26 release, balance sheet detail怎么使用:直接 / 支持;一手验证:18、21、29;专项深挖:18、19、29
FY3/26 release, cash-flow detail怎么使用:直接 / 支持;一手验证:17、19、20、25;专项深挖:17、20、25
H1 FY3/27 release, balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、20、29
H1 FY3/27 release, debt movements怎么使用:直接证据
H1 FY3/27 release, working capital怎么使用:直接 / 支持;一手验证:19;专项深挖:19
G-Biz Info extract of the FY3/26 securities report indicators怎么使用:直接证据;同业比较:01、18、26;其他用途:历史
FY3/26 release, liabilities detail怎么使用:直接 / 支持
FY3/26 release, market-value equity ratio怎么使用:直接证据;一手验证:31;专项深挖:31
H1 FY3/27 release, equity movements and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21
FY3/26 release, cross-shareholding disclosure怎么使用:支持证据;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14)|H1 FY3/27 release, steel business narrative;直接证据 / 一手证据(研究域13) / 一手证据(研究域14)|FY3/26 release, external environment narrative;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;直接证据 / 定向深挖(研究域02) / 定向深挖(研究域06)|FY3/26 release, segment narrative - steel;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 支持证据|H1 FY3/27 release, segment information;直接证据 / 支持证据|FY3/26 release, balance sheet;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域25) / 定向深挖(研究域17) / 定向深挖(研究域20) / 定向深挖(研究域25)|FY3/26 release, cash-flow detail;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据|H1 FY3/27 release, debt movements;直接证据 / 支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|H1 FY3/27 release, working capital;直接证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域18) / 历史/同业比较(研究域26)|G-Biz Info extract of the FY3/26 securities report indicators;直接证据 / 支持证据|FY3/26 release, liabilities detail;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|FY3/26 release, market-value equity ratio;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|H1 FY3/27 release, equity movements and valuation reserves;支持证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure
完整研究记录(核对用)
研究原文:One scrap price moves P&L, inventory, debt and cash together|A high scrap plateau compresses the steel margin, inflates inventory values by billions of yen, and lifts borrowings in the same period, so industry, working-capital and leverage domains are a single mechanism.
内部研究类型:feedback_transmission_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Watch cash conversion and net debt alongside the spread; reported profit and cash diverge when scrap moves.
不确定性(原始记录):No H1 cash flow statement; hedging and inventory costing basis unknown.
F076|08|证券出售、还款、分红和回购连成一个循环,但供应有限
研究范围:开放研究+35项覆盖检查
写入正文:08|证券出售、还款、分红和回购连成一个循环,但供应有限
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(24项,重复标签已合并)
FY3/26 release, balance sheet怎么使用:直接 / 支持
FY3/26 release, extraordinary items怎么使用:直接证据
FY3/26 release, policy shareholdings怎么使用:直接 / 支持
FY3/26 release, cross-shareholding disclosure怎么使用:直接 / 支持;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
H1 FY3/27 release, extraordinary items怎么使用:直接 / 支持;一手验证:16;专项深挖:16;同业比较:32;其他用途:历史
FY3/26 release, cash-flow statement怎么使用:直接证据;一手验证:17
FY3/26 release, cash-flow detail怎么使用:直接证据;一手验证:17、19、20、25;专项深挖:17、20、25
H1 FY3/27 release, forecast revision and outlook怎么使用:直接证据;一手验证:20;同业比较:27、31;其他用途:历史
G-Biz Info extract of the FY3/26 securities report indicators怎么使用:直接证据;同业比较:01、18、26;其他用途:历史
FY3/26 release, liabilities detail怎么使用:直接 / 支持
FY3/26 release, market-value equity ratio怎么使用:直接证据;一手验证:31;专项深挖:31
H1 FY3/27 release, balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、20、29
H1 FY3/27 release, debt movements怎么使用:直接证据
H1 FY3/27 release, equity movements and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21
FY3/26 release, balance sheet detail怎么使用:直接 / 支持;一手验证:18、21、29;专项深挖:18、19、29
FY3/26 release, dividend policy and forecast怎么使用:直接 / 支持
FY3/26 release, dividends and per-share data怎么使用:直接 / 支持;一手验证:26;专项深挖:26、27
FY3/26 release, dividend forecast detail怎么使用:直接 / 支持
H1 FY3/27 release, share counts and balance sheet怎么使用:直接 / 支持;反向验证:01;同业比较:07、24;其他用途:历史
H1 FY3/27 release, share counts怎么使用:直接 / 支持;一手验证:24、26;专项深挖:24、26
Company IR news list, 2026 entries怎么使用:直接证据;一手验证:13;同业比较:23;其他用途:历史
Vendor snapshot retrieved 9 November 2026怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
IR news list 2026: governance and capital items怎么使用:直接 / 支持;一手验证:23;专项深挖:13、23
Notice on matters concerning controlling shareholders etc., 25 June 2026怎么使用:直接证据;一手验证:07、23
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/26 release, balance sheet;直接证据|FY3/26 release, extraordinary items;直接证据 / 支持证据|FY3/26 release, policy shareholdings;直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;直接证据 / 支持证据 / 一手证据(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域16)|H1 FY3/27 release, extraordinary items;直接证据 / 一手证据(研究域17)|FY3/26 release, cash-flow statement;直接证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域25) / 定向深挖(研究域17) / 定向深挖(研究域20) / 定向深挖(研究域25)|FY3/26 release, cash-flow detail;直接证据 / 一手证据(研究域20) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|H1 FY3/27 release, forecast revision and outlook;直接证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域18) / 历史/同业比较(研究域26)|G-Biz Info extract of the FY3/26 securities report indicators;直接证据 / 支持证据|FY3/26 release, liabilities detail;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|FY3/26 release, market-value equity ratio;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据|H1 FY3/27 release, debt movements;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|H1 FY3/27 release, equity movements and valuation reserves;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;直接证据 / 支持证据|FY3/26 release, dividend policy and forecast;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域27)|FY3/26 release, dividends and per-share data;直接证据 / 支持证据|FY3/26 release, dividend forecast detail;直接证据 / 支持证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域24) / 反证(研究域01)|H1 FY3/27 release, share counts and balance sheet;直接证据 / 支持证据 / 一手证据(研究域24) / 一手证据(研究域26) / 定向深挖(研究域24) / 定向深挖(研究域26)|H1 FY3/27 release, share counts;直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域23)|Company IR news list, 2026 entries;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026;直接证据 / 支持证据 / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|IR news list 2026: governance and capital items;直接证据 / 一手证据(研究域07) / 一手证据(研究域23)|Notice on matters concerning controlling shareholders etc., 25 June 2026
完整研究记录(核对用)
研究原文:Balance-sheet conversion loop: portfolio sales, deleveraging, DOE dividend and buyback|Portfolio sales fund deleveraging and returns, the equity ratio rises, bank access stays unconditional, and a DOE-anchored dividend plus buyback compound book value per share independently of the steel cycle (BVPS JPY 6,660.64 to 6,863.81 in six months).
内部研究类型:capital_conversion_loop
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The income stream has risen every year while operating profit oscillated; dependence on finite portfolio proceeds is the limit.
不确定性(原始记录):Portfolio supply is finite and the March 2027 ratio target is pending; FY3/27 cash cover of capex plus dividend without asset sales unknown.
F077|11|下半期要赚到48.89亿日元,钢铁要从亏损走到至少不亏
研究范围:开放研究+35项覆盖检查
写入正文:11|下半期要赚到48.89亿日元,钢铁要从亏损走到至少不亏
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(15项,重复标签已合并)
FY3/26 release, FY3/27 initial forecast怎么使用:直接 / 支持;同业比较:30;其他用途:历史
H1 FY3/27 release, forecast revision and outlook怎么使用:直接 / 支持;一手验证:20;同业比较:27、31;其他用途:历史
Q1 FY3/27 release, 4 August 2026, summary and revision怎么使用:直接 / 支持;一手验证:05;专项深挖:05、11
H1 FY3/27 release, 6 November 2026, summary tables怎么使用:直接证据;一手验证:15;反向验证:35
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接 / 支持;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
Q1 FY3/27 release, 4 August 2026怎么使用:直接证据
H1 FY3/27 release, segment information怎么使用:直接 / 支持
H1 FY3/27 release, segment information - steel怎么使用:直接 / 支持;一手验证:11、35;专项深挖:14、35
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
FY3/26 release, segment narrative怎么使用:直接 / 支持;一手验证:02;同业比较:06、14;其他用途:历史
H1 FY3/27 release, steel business narrative怎么使用:直接 / 支持;一手验证:06、14
FY3/26 release, segment narrative - steel怎么使用:直接证据;专项深挖:02、06
FY3/26 release, cross-shareholding disclosure怎么使用:直接证据;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
FY3/26 release, medium-term plan growth fields怎么使用:直接证据;一手验证:03、04、11;专项深挖:03、04、07、09、11、30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域30)|FY3/26 release, FY3/27 initial forecast;直接证据 / 支持证据 / 一手证据(研究域20) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|H1 FY3/27 release, forecast revision and outlook;直接证据 / 支持证据 / 一手证据(研究域05) / 定向深挖(研究域05) / 定向深挖(研究域11)|Q1 FY3/27 release, 4 August 2026, summary and revision;直接证据 / 一手证据(研究域15) / 反证(研究域35)|H1 FY3/27 release, 6 November 2026, summary tables;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 支持证据|H1 FY3/27 release, quarterly split (computed from Q1 and H1 releases);直接证据|Q1 FY3/27 release, 4 August 2026;直接证据 / 支持证据|H1 FY3/27 release, segment information;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14)|H1 FY3/27 release, steel business narrative;直接证据 / 定向深挖(研究域02) / 定向深挖(研究域06)|FY3/26 release, segment narrative - steel;直接证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域11) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域07) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域30)|FY3/26 release, medium-term plan growth fields
完整研究记录(核对用)
研究原文:FY3/27 second-half bridge and plan rhythm|A designed back-loaded plan whose revised H2 requirement is only 8.0% above last year's H2 but depends on steel price follow-through and unquantified parts run rate.
内部研究类型:forecast_test_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Q3 and full-year prints are the near-term proof or falsification of the thesis.
不确定性(原始记录):No segment bridge or price assumptions disclosed.
F078|09|市场给资产负债表打对折,同时对盈利给了正常倍数
研究范围:开放研究+35项覆盖检查
写入正文:09|市场给资产负债表打对折,同时对盈利给了正常倍数
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(28项,重复标签已合并)
Vendor snapshot retrieved 9 November 2026怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接 / 支持;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
FY3/26 release, market-value equity ratio怎么使用:直接证据;一手验证:31;专项深挖:31
H1 FY3/27 release, share counts and balance sheet怎么使用:直接 / 支持;反向验证:01;同业比较:07、24;其他用途:历史
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:直接 / 支持;一手验证:01
FY3/26 release, cash-flow statement怎么使用:直接 / 支持;一手验证:17
FY3/26 release, dividend policy and forecast怎么使用:直接 / 支持
Company financial highlights, five-year record怎么使用:直接 / 支持;同业比较:02、05、09、10、11、12、17、19、20、25、28;其他用途:历史
Ten-year financial summary (securities-report based)怎么使用:直接 / 支持;一手验证:12;同业比较:03、04、08、33;其他用途:历史
Company highlights, five-year profit record怎么使用:直接 / 支持;一手验证:12、28、33;反向验证:29;专项深挖:12、28、33、34;同业比较:15、16、22、29、34、35;其他用途:历史
FY3/26 release, balance sheet怎么使用:直接 / 支持
G-Biz Info extract of the FY3/26 securities report indicators怎么使用:直接证据;同业比较:01、18、26;其他用途:历史
FY3/26 release, liabilities detail怎么使用:直接 / 支持
H1 FY3/27 release, balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、20、29
H1 FY3/27 release, debt movements怎么使用:直接证据
H1 FY3/27 release, equity movements and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21
FY3/26 release, balance sheet detail怎么使用:直接 / 支持;一手验证:18、21、29;专项深挖:18、19、29
FY3/26 release, cross-shareholding disclosure怎么使用:支持证据;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
Company IR news list, 2026 entries怎么使用:直接证据;一手验证:13;同业比较:23;其他用途:历史
H1 FY3/27 release, segment information - steel怎么使用:直接 / 支持;一手验证:11、35;专项深挖:14、35
H1 FY3/27 release, segment information - parts怎么使用:直接证据;一手验证:32;专项深挖:05、10、14、15、32
FY3/26 release, medium-term plan growth fields怎么使用:直接 / 支持;一手验证:03、04、11;专项深挖:03、04、07、09、11、30
132nd-term securities report, business description怎么使用:直接证据;一手验证:02、03、04、08、09、10
FY3/26 release, segment narrative - parts怎么使用:直接证据;一手验证:05、10;专项深挖:02、03、04、08、10
IR news list 2026: governance and capital items怎么使用:支持证据;一手验证:23;专项深挖:13、23
FY3/26 release, segment narrative怎么使用:支持证据;一手验证:02;同业比较:06、14;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|FY3/26 release, market-value equity ratio;直接证据 / 支持证据|H1 FY3/27 release, 6 November 2026, summary tables;支持证据|H1 FY3/27 release, segment information;直接证据 / 支持证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域24) / 反证(研究域01)|H1 FY3/27 release, share counts and balance sheet;直接证据 / 支持证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;直接证据 / 支持证据 / 一手证据(研究域17)|FY3/26 release, cash-flow statement;直接证据 / 支持证据|FY3/26 release, dividend policy and forecast;直接证据 / 支持证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25) / 历史/同业比较(研究域28)|Company financial highlights, five-year record;直接证据 / 支持证据 / 一手证据(研究域12) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域08) / 历史/同业比较(研究域33)|Ten-year financial summary (securities-report based);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域22) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35) / 反证(研究域29) / 定向深挖(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域33) / 定向深挖(研究域34)|Company highlights, five-year profit record;直接证据 / 支持证据|FY3/26 release, balance sheet;直接证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域18) / 历史/同业比较(研究域26)|G-Biz Info extract of the FY3/26 securities report indicators;直接证据 / 支持证据|FY3/26 release, liabilities detail;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据|H1 FY3/27 release, debt movements;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|H1 FY3/27 release, equity movements and valuation reserves;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;支持证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域23)|Company IR news list, 2026 entries;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域11) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域07) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域30)|FY3/26 release, medium-term plan growth fields;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|132nd-term securities report, business description;直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;支持证据 / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|IR news list 2026: governance and capital items;支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative
完整研究记录(核对用)
研究原文:Valuation bridge: priced balance sheet, doubted earnings, normalised profit|At about 0.46x book and 8.8x revised EPS the market believes the balance sheet and doubts the earnings; normalised operating profit of JPY 5-7bn makes the equity roughly 10-13x mid-cycle operating profit, cheap only if the parts reset is structural. Growth options and land are outside the price.
内部研究类型:valuation_bridge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Holders earn about a 4.3% yield while waiting; re-rating requires rising through-cycle earnings or faster balance-sheet conversion.
不确定性(原始记录):Mixed price dates, share counts and book dates across the multiples; no consensus or peer multiples.
F079|01|结论:持有观察,不追高,价格里没有钢铁复苏,也没有计划失败
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论01|结论:持有观察,不追高,价格里没有钢铁复苏,也没有计划失败01|什么会推翻这个判断,什么会加强它14|总分62.81/100,评级 B,整体把握一般
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(39项,重复标签已合并)
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接 / 支持;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
H1 FY3/27 release, segment information - steel怎么使用:直接 / 支持;一手验证:11、35;专项深挖:14、35
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
FY3/26 release, policy shareholdings怎么使用:直接证据
Vendor snapshot retrieved 9 November 2026怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、07、09、16、18、21、22、24、26、32
G-Biz Info extract of the FY3/26 securities report indicators怎么使用:直接证据;同业比较:01、18、26;其他用途:历史
FY3/26 release, cross-shareholding disclosure怎么使用:直接 / 支持;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
FY3/26 release, medium-term plan growth fields怎么使用:直接 / 支持;一手验证:03、04、11;专项深挖:03、04、07、09、11、30
FY3/26 release, balance sheet怎么使用:直接 / 支持
FY3/26 release, liabilities detail怎么使用:直接 / 支持
FY3/26 release, market-value equity ratio怎么使用:直接证据;一手验证:31;专项深挖:31
H1 FY3/27 release, balance sheet怎么使用:直接 / 支持;一手验证:18、29;专项深挖:18、20、29
Company highlights, five-year profit record怎么使用:直接 / 支持;一手验证:12、28、33;反向验证:29;专项深挖:12、28、33、34;同业比较:15、16、22、29、34、35;其他用途:历史
Controlling-shareholder matters notice, 25 June 2026, shareholding table怎么使用:直接 / 支持;一手验证:06、07、24;专项深挖:06、07、23、24
Notice on matters concerning controlling shareholders etc., 25 June 2026怎么使用:直接证据;一手验证:07、23
H1 FY3/27 release, share counts怎么使用:直接证据;一手验证:24、26;专项深挖:24、26
FY3/26 release, segment narrative怎么使用:直接 / 支持;一手验证:02;同业比较:06、14;其他用途:历史
H1 FY3/27 release, segment information怎么使用:直接 / 支持
H1 FY3/27 release, 6 November 2026, summary tables怎么使用:直接 / 支持;一手验证:15;反向验证:35
H1 FY3/27 release, share counts and balance sheet怎么使用:直接 / 支持;反向验证:01;同业比较:07、24;其他用途:历史
FY3/26 results release, 12 May 2026, cover and summary tables怎么使用:直接 / 支持;一手验证:01
FY3/26 release, cash-flow statement怎么使用:直接 / 支持;一手验证:17
FY3/26 release, dividend policy and forecast怎么使用:直接 / 支持
Company financial highlights, five-year record怎么使用:直接 / 支持;同业比较:02、05、09、10、11、12、17、19、20、25、28;其他用途:历史
Ten-year financial summary (securities-report based)怎么使用:直接 / 支持;一手验证:12;同业比较:03、04、08、33;其他用途:历史
H1 FY3/27 release, debt movements怎么使用:直接证据
H1 FY3/27 release, equity movements and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21
FY3/26 release, balance sheet detail怎么使用:直接 / 支持;一手验证:18、21、29;专项深挖:18、19、29
Company IR news list, 2026 entries怎么使用:直接证据;一手验证:13;同业比较:23;其他用途:历史
132nd-term securities report, business description怎么使用:直接证据;一手验证:02、03、04、08、09、10
FY3/26 release, segment narrative - parts怎么使用:直接证据;一手验证:05、10;专项深挖:02、03、04、08、10
IR news list 2026: governance and capital items怎么使用:支持证据;一手验证:23;专项深挖:13、23
FY3/26 release, FY3/27 initial forecast怎么使用:直接 / 支持;同业比较:30;其他用途:历史
H1 FY3/27 release, forecast revision and outlook怎么使用:直接 / 支持;一手验证:20;同业比较:27、31;其他用途:历史
Q1 FY3/27 release, 4 August 2026, summary and revision怎么使用:直接 / 支持;一手验证:05;专项深挖:05、11
Q1 FY3/27 release, 4 August 2026怎么使用:直接证据
H1 FY3/27 release, steel business narrative怎么使用:直接 / 支持;一手验证:06、14
FY3/26 release, segment narrative - steel怎么使用:直接证据;专项深挖:02、06
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据|FY3/26 release, policy shareholdings;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域07) / 外部现实(研究域09) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域26) / 外部现实(研究域32)|Vendor snapshot retrieved 9 November 2026;直接证据 / 历史/同业比较(研究域01) / 历史/同业比较(研究域18) / 历史/同业比较(研究域26)|G-Biz Info extract of the FY3/26 securities report indicators;直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域11) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域07) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域30)|FY3/26 release, medium-term plan growth fields;直接证据 / 支持证据|FY3/26 release, balance sheet;直接证据 / 支持证据|FY3/26 release, liabilities detail;直接证据 / 一手证据(研究域31) / 定向深挖(研究域31)|FY3/26 release, market-value equity ratio;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域22) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35) / 反证(研究域29) / 定向深挖(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域33) / 定向深挖(研究域34)|Company highlights, five-year profit record;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域07) / 一手证据(研究域24) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域23) / 定向深挖(研究域24)|Controlling-shareholder matters notice, 25 June 2026, shareholding table;直接证据 / 一手证据(研究域07) / 一手证据(研究域23)|Notice on matters concerning controlling shareholders etc., 25 June 2026;直接证据 / 一手证据(研究域24) / 一手证据(研究域26) / 定向深挖(研究域24) / 定向深挖(研究域26)|H1 FY3/27 release, share counts;直接证据 / 支持证据 / 一手证据(研究域02) / 历史/同业比较(研究域06) / 历史/同业比较(研究域14)|FY3/26 release, segment narrative;直接证据 / 支持证据|H1 FY3/27 release, segment information;直接证据 / 支持证据 / 一手证据(研究域15) / 反证(研究域35)|H1 FY3/27 release, 6 November 2026, summary tables;直接证据 / 支持证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域24) / 反证(研究域01)|H1 FY3/27 release, share counts and balance sheet;直接证据 / 支持证据 / 一手证据(研究域01)|FY3/26 results release, 12 May 2026, cover and summary tables;直接证据 / 支持证据 / 一手证据(研究域17)|FY3/26 release, cash-flow statement;直接证据 / 支持证据|FY3/26 release, dividend policy and forecast;直接证据 / 支持证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25) / 历史/同业比较(研究域28)|Company financial highlights, five-year record;直接证据 / 支持证据 / 一手证据(研究域12) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域08) / 历史/同业比较(研究域33)|Ten-year financial summary (securities-report based);直接证据|H1 FY3/27 release, debt movements;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|H1 FY3/27 release, equity movements and valuation reserves;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域19) / 定向深挖(研究域29)|FY3/26 release, balance sheet detail;直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域23)|Company IR news list, 2026 entries;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|132nd-term securities report, business description;直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域08) / 定向深挖(研究域10)|FY3/26 release, segment narrative - parts;支持证据 / 一手证据(研究域23) / 定向深挖(研究域13) / 定向深挖(研究域23)|IR news list 2026: governance and capital items;直接证据 / 支持证据 / 历史/同业比较(研究域30)|FY3/26 release, FY3/27 initial forecast;直接证据 / 支持证据 / 一手证据(研究域20) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|H1 FY3/27 release, forecast revision and outlook;直接证据 / 支持证据 / 一手证据(研究域05) / 定向深挖(研究域05) / 定向深挖(研究域11)|Q1 FY3/27 release, 4 August 2026, summary and revision;直接证据 / 支持证据|H1 FY3/27 release, quarterly split (computed from Q1 and H1 releases);直接证据|Q1 FY3/27 release, 4 August 2026;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14)|H1 FY3/27 release, steel business narrative;直接证据 / 定向深挖(研究域02) / 定向深挖(研究域06)|FY3/26 release, segment narrative - steel
完整研究记录(核对用)
研究原文:Thesis, scenario interaction and falsification conditions|One demonstrated fact, one demonstrated programme and one unproven option, with four numeric or observable falsifiers.
内部研究类型:thesis_falsification_structure
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Book-value compounding plus yield if falsifiers stay silent; spread-cycle repricing if falsifier (2) triggers.
不确定性(原始记录):Negotiation-round test resolves only in the successor plan's first year.
F080|13|证据边界一览:这些缺口限制把握,不是负面证据
研究范围:开放研究+35项覆盖检查
写入正文:13|证据边界一览:这些缺口限制把握,不是负面证据
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(23项,重复标签已合并)
H1 FY3/27 release, segment information - parts怎么使用:直接 / 支持;一手验证:32;专项深挖:05、10、14、15、32
H1 FY3/27 release, forecast revision and outlook怎么使用:直接证据;一手验证:20;同业比较:27、31;其他用途:历史
H1 FY3/27 release, revised FY3/27 forecast怎么使用:直接证据;一手验证:27、28、30、35;专项深挖:22、27、28、30、31、35
H1 FY3/27 release, segment information - steel怎么使用:直接证据;一手验证:11、35;专项深挖:14、35
FY3/26 release, medium-term plan section怎么使用:直接证据;一手验证:22;同业比较:13;其他用途:历史
FY3/26 release, mid-plan ROE discussion怎么使用:直接证据;一手验证:22;专项深挖:22
FY3/26 release, policy shareholdings怎么使用:直接证据
FY3/26 release, cross-shareholding disclosure怎么使用:直接证据;一手验证:25、30;专项深挖:21、25;同业比较:21;其他用途:历史
H1 FY3/27 release, extraordinary items怎么使用:直接证据;一手验证:16;专项深挖:16;同业比较:32;其他用途:历史
FY3/26 release, medium-term plan growth fields怎么使用:直接证据;一手验证:03、04、11;专项深挖:03、04、07、09、11、30
FY3/26 release, cash-flow detail怎么使用:直接证据;一手验证:17、19、20、25;专项深挖:17、20、25
Notice on matters concerning controlling shareholders etc., 25 June 2026怎么使用:直接证据;一手验证:07、23
Controlling-shareholder matters notice, 25 June 2026, shareholding table怎么使用:直接证据;一手验证:06、07、24;专项深挖:06、07、23、24
H1 FY3/27 release, debt movements怎么使用:直接证据
H1 FY3/27 release, balance sheet怎么使用:直接证据;一手验证:18、29;专项深挖:18、20、29
FY3/26 release, liabilities detail怎么使用:直接证据
Company highlights, five-year profit record怎么使用:直接证据;一手验证:12、28、33;反向验证:29;专项深挖:12、28、33、34;同业比较:15、16、22、29、34、35;其他用途:历史
Company financial highlights, five-year record怎么使用:直接证据;同业比较:02、05、09、10、11、12、17、19、20、25、28;其他用途:历史
Securities-report indicators via G-Biz Info怎么使用:直接证据;一手验证:08、09;专项深挖:01、08、09
H1 FY3/27 release, equity movements and valuation reserves怎么使用:直接证据;一手验证:21;专项深挖:21
Company IR news list, 2026 entries怎么使用:直接证据;一手验证:13;同业比较:23;其他用途:历史
查看完整证据标签(核对用)
直接证据|H1 FY3/27 release, segment information;直接证据 / 支持证据 / 一手证据(研究域32) / 定向深挖(研究域05) / 定向深挖(研究域10) / 定向深挖(研究域14) / 定向深挖(研究域15) / 定向深挖(研究域32)|H1 FY3/27 release, segment information - parts;直接证据 / 一手证据(研究域20) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|H1 FY3/27 release, forecast revision and outlook;直接证据 / 一手证据(研究域27) / 一手证据(研究域28) / 一手证据(研究域30) / 一手证据(研究域35) / 定向深挖(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域28) / 定向深挖(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY3/27 release, revised FY3/27 forecast;直接证据 / 一手证据(研究域11) / 一手证据(研究域35) / 定向深挖(研究域14) / 定向深挖(研究域35)|H1 FY3/27 release, segment information - steel;直接证据 / 一手证据(研究域22) / 历史/同业比较(研究域13)|FY3/26 release, medium-term plan section;直接证据|FY3/26 release, dividend policy and forecast;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|FY3/26 release, mid-plan ROE discussion;直接证据|FY3/26 release, policy shareholdings;直接证据 / 一手证据(研究域25) / 一手证据(研究域30) / 历史/同业比较(研究域21) / 定向深挖(研究域21) / 定向深挖(研究域25)|FY3/26 release, cross-shareholding disclosure;直接证据 / 一手证据(研究域16) / 历史/同业比较(研究域32) / 定向深挖(研究域16)|H1 FY3/27 release, extraordinary items;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域11) / 定向深挖(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域07) / 定向深挖(研究域09) / 定向深挖(研究域11) / 定向深挖(研究域30)|FY3/26 release, medium-term plan growth fields;直接证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域25) / 定向深挖(研究域17) / 定向深挖(研究域20) / 定向深挖(研究域25)|FY3/26 release, cash-flow detail;直接证据 / 一手证据(研究域07) / 一手证据(研究域23)|Notice on matters concerning controlling shareholders etc., 25 June 2026;直接证据 / 一手证据(研究域06) / 一手证据(研究域07) / 一手证据(研究域24) / 定向深挖(研究域06) / 定向深挖(研究域07) / 定向深挖(研究域23) / 定向深挖(研究域24)|Controlling-shareholder matters notice, 25 June 2026, shareholding table;直接证据|H1 FY3/27 release, debt movements;直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域20) / 定向深挖(研究域29)|H1 FY3/27 release, balance sheet;直接证据|FY3/26 release, liabilities detail;直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域33) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域22) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35) / 反证(研究域29) / 定向深挖(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域33) / 定向深挖(研究域34)|Company highlights, five-year profit record;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25) / 历史/同业比较(研究域28)|Company financial highlights, five-year record;直接证据 / 一手证据(研究域08) / 一手证据(研究域09) / 定向深挖(研究域01) / 定向深挖(研究域08) / 定向深挖(研究域09)|Securities-report indicators via G-Biz Info;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|H1 FY3/27 release, equity movements and valuation reserves;直接证据 / 一手证据(研究域13) / 历史/同业比较(研究域23)|Company IR news list, 2026 entries
完整研究记录(核对用)
研究原文:Research Debt carried forward|The highest-value unresolved items are the parts run rate and the H2 composition; the rest bound confidence on competition, capital deployment and relative valuation.
内部研究类型:research_debt_cluster
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Resolution of the first two can move the thesis; the others mostly calibrate confidence.
不确定性(原始记录):Most items depend on future disclosure rather than a reasonable current public path.
F081|10|下行已经走完,现在要回答的是3,710日元之后站不站得住
写入正文:10|下行已经走完,现在要回答的是3,710日元之后站不站得住10|年度低点连续四年抬高,2024年的深度回调守在远高于旧低点的位置10|2026年3月冲高没守住,之后七个月在2,615至3,195日元箱体里整理10|价格重心在12个月均线,但整体处在历史上少见的高位10|价格对业绩事件的响应偏正面,价格与基本面在等同一个证据10|什么走势会确认,什么走势会推翻13|证据边界一览:这些缺口限制把握,不是负面证据14|八个维度的得分与一句理由15|证据限制与口径说明
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (RESEARCH_TRUTH.technical_state)
内部研究类型:protected_technical_synthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | 5c1e8b1fe5216f076974fe2f5b627484a90a594e |
| Delivery Commit SHA | 5c1e8b1fe5216f076974fe2f5b627484a90a594e |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | 3e3ebfa2-2705-573b-a4c9-abb70f329ac2 |
| Canonical Revision | 1 |