2026年2月期销售额1万1557.74亿日元,营业利润404.57亿日元,普通利润454.85亿日元,净利润305.06亿日元,全部创历史新高。普通利润从2021年2月期的182.98亿日元连涨五年,综合毛利率由7%左右升到9.2%。股东权益比率49.6%,带息负债一年减少近300亿日元,评级为 R&I A、JCR A+。
7485
岡谷鋼機株式会社(Okaya & Co., Ltd.)
公司一句话:岡谷鋼機株式会社(OKAYA & CO., LTD.,代码7485)仅在名古屋证券交易所 Premier 市场上市,1669年创业。主营钢材、特殊钢和有色金属的流通与加工,是专业贸易商(日语称商社)。同时经营半导体、电子元器件、电路基板和软件(信息电子),机械、成套设备、材料和能源相关贸易(产业素材),以及食品和消费品相关贸易(生活关联)。集团共100家公司,分布在23个国家。 估值简报:股价4,845日元(2026年11月6日收盘,2026年6月拆股后口径)/总市值1,883.7亿日元/预测市盈率5.8倍(按修正后的2027年2月期公司指引每股收益831.55日元)。实绩市净率0.38倍/ROE 6.9%(2026年2月期实绩)/预测股息率1.86%(2027年2月期预测每股股息90日元)。EV/EBITDA 7.3倍(EV=总市值+净有息负债1,551.98亿日元〔2026年8月31日〕=3,435.7亿日元;EBITDA=2026年2月期营业利润加折旧摊销=468.84亿日元;净负债日期与EBITDA期间不一致,仅作参考)
最近亮点:2026年9月30日公司公布五年中期经营计划「Global Innovation Change 2030(GIC 30)」,覆盖2027年2月期至2031年2月期,目标2031年2月期净利润400亿日元,比2026年2月期高31.1%。中期阶段,公司把2027年2月期普通利润预测从400亿日元上调到455亿日元(上调13.75%),预测每股收益831.55日元、预测每股股息90日元,普通利润有望连续第六年创新高。上调后的这组数字来自对中期资料的二手整理,中期决算原件和分板块数据尚未取得。
最主要的风险是时间:分红率只有10%左右,没有回购,GIC 30目前读到的材料里也没有数值化的资本效率承诺,留存利润继续堆高净资产,ROE停在7%上下,折价可能持续数年。另有两个变数:信息电子是利润最大的板块,也是最容易受器件投资周期冲击的板块;市场希望的交叉持股改革,会直接减少约五分之一来自持有证券的普通利润。
Kabugami 得分 64.22/100(评分版本 V3.2),评级 B。操作上以持有和有纪律地跟踪为主,不追高:盈利连续创新高、资产负债表厚实、估值偏低,不利情形更像长期没有回报,而不是本金受损;但价格已回到近年高位区,资本政策出现数值化承诺之前,折价缺少收窄的触发条件。可在回调靠近2026年2月期收盘折算价(4,935日元)时分批考虑,并按名古屋单一上市的流动性控制仓位。这个判断仍受几项未证实的事实限制:持有证券的市值和变现税负没有取得,中期业绩的分板块构成没有取得,GIC 30的数值细节没有取得,月线数据无法核对。研究截止2026年11月9日,价格取2026年11月6日收盘。 当前动作:以持有和有纪律地跟踪为主,不追高。基本面上盈利持续创新高、资产负债表厚实、估值处于低位(预测PER约5.8倍,PBR约0.38倍),下行偏向长期死钱而非本金受损;但价格已回到近年高位区,且资本政策没有出现数值化承诺前,折价缺少收窄的触发条件。可在回调靠近2026年2月期收盘区时分批考虑,并按名古屋单一上市的流动性来控制仓位。需要继续验证的节点:2026年12月下旬前后的第三季度发布、2027年3月的2027年2月期结果(GIC 30首年进展与是否出现资本政策表态)。价格回到约3400日元以下、普通利润低于358.5亿日元、电子板块利润减半或分红被削减,会改变这一判断;出现回购或数值化资本效率承诺则会加强。
报告目录
01|投资问题与当前结论
01.1|利润连年创新高,市场却只给净资产0.38倍
当前结论:这家公司的盈利已经被市场相信,净资产却没有被定价,判断为持有并验证,不追高。
证据很直接。2026年2月期普通利润454.85亿日元,预测市盈率只有5.8倍;同一时点市净率0.38倍。连续三年创纪录的利润,没有把市净率抬离0.38倍。市场愿意为盈利流付一个周期股的完整倍数,却不为账面净资产付价。
这个折价更像上市场所和资本政策的结果:只在名古屋交易所上市,分红率10%左右,没有回购,GIC 30也没有写数值化的资本效率目标。所以再来一份超预期的财报,并不足以重估股价,需要的是一个资本政策上的事实。另一种解释同样成立:市场也可能是在正确地折价低回报的留存资本和交叉持股的质量。公司没有分析师一致预期可用来检验这一点。
投资逻辑有两层。经营层靠产品结构向电子和增值加工倾斜,把毛利率逐年拉高;持股层靠持有证券的股息连续八年增长。两层叠加,在一个普通周期里,盈利维持在2026年2月期普通利润水平或更高是站得住的。这个判断取决于三个条件:电子业务的利润能否经得住器件周期,交叉持股最终怎么处理,以及短期内会不会出现资本政策催化。把握一般。
01.2|什么会推翻这个判断:三个基本面数字和一个反向条件
基本面上有三个会推翻判断的条件。第一,普通利润跌破2024年2月期的358.50亿日元,而且没有同等规模的宏观原因。第二,信息电子板块利润在器件下行期减半,说明结构改善买到的是波动,不是质量。第三,分红被削减,九年连续增加的记录中断。
另有一个反向条件:如果公司宣布回购或数值化的资本承诺,但盈利没有跟上,就推翻「折价被压住」这半个判断,因为那意味着留存资本的低回报才是折价的真正原因。
只是政策令人失望,本身不构成退出理由,它恰好是买入的前提。另有一个价格结构上的推翻条件,由独立的技术研究给出,详见技术结构一章:月线收盘回到约3,360至3,490日元区间,保留判断即被推翻。以上数值是研究判断,不是公司指引。
02|公司本质与商业模式
02.1|经营的是100家公司组成的贸易网络,不是名古屋总部
分析这家公司,应以集团合并口径为准,不能用名古屋母公司作为单位。岡谷鋼機(EDINET代码E02553)仅在名古屋证券交易所 Premier 市场上市,2月结算,1669年创业。它是轻资产的贸易和流通网络,分钢铁、信息电子、产业素材、生活关联四个板块。集团共100家公司(合并子公司78家、权益法关联公司22家),分布在23个国家。合并员工6,536人,母公司只有773人。
母公司2026年2月期销售额5,916.60亿日元,约占集团一半;营业利润165.41亿日元,只占集团404.57亿日元的41%。母公司钢铁销售额从2024年2月期的2,641.55亿日元降到2026年2月期的2,205.25亿日元,缩小的主要是母公司自己的国内钢铁业务,集团内其他公司补上了一部分。
合并报表不等于普通股东拥有全部。2026年2月期净资产5,176.80亿日元,其中归属母公司股东权益4,962.62亿日元,差额是少数股东权益等。22家权益法公司的利润也不是母公司可以自由调配的经营现金。目前没有公开资料可以拆出各子公司的利润,社长身份和家族关联的非上市企业也没有取得。
02.2|357年的老字号,抗得住单一冲击,最脆弱的是电子这一环
这家公司的结构耐久性比较高,来源有四层。四个板块的景气高点不同;100家公司分布在23个国家;库存周转只有1.5个月,钢价冲击更多变成利润波动,不容易变成资产负债表问题;持有证券的股息连续八年增长,再加上股东权益比率49.6%、净负债权益比0.3倍、利息保障倍数14.4倍、评级 A 和 A+ 的资产负债表,单一年度的冲击到不了权益。创业家族、银行、供应商、客户和员工都持有股份,战略突变和经营失败一样不容易发生。
指定的薄弱环节是电子:它既是增长和利润最大的来源,又是这个体量下周期最强的资产,占销售额约32%,还没有经历过完整的器件下行期。已有的压力样本只有2021年2月期,当年普通利润仍有182.98亿日元,但那是电子占比抬升之前的结构。
现有证据能证明公司挺得过任何一次已记录的压力;同时出现器件下行、国内钢铁转弱、交叉持股被迫低价出售的复合情形,没有先例,眼下也没有触发条件。本次的创纪录年度、中期上调和GIC 30,是叠加在这个基础之上的变化,没有改变基础。板块投入资本、应收账款账龄和复合压力下的表现都无法观察。
03|产品、客户与供应链
03.1|利润重心已从钢铁移到电子,钢铁成了压舱石
2026年2月期,信息电子板块首次在利润上超过钢铁,所以把这家公司叫做钢铁贸易商,已不准确。
信息电子销售额3,703.48亿日元,营业利润134.35亿日元,利润率3.6%,两年利润增长44%。钢铁销售额3,778.23亿日元,营业利润110.16亿日元,利润率2.9%;钢铁板块销售额从2024年2月期的4,248.65亿日元降到现在,利润却守在110亿日元上下。
产业素材销售额3,219.30亿日元,营业利润110.71亿日元,利润率3.4%,是四块里最稳的。生活关联销售额856.71亿日元,营业利润37.76亿日元,利润率4.4%,销售额增长22%,体量小,增速最快。
利润率的高低和业务的年龄正好相反。决定利润的是结构,不是规模。股东的增长敞口现在和半导体及器件投资相连,钢铁提供的是缓冲。电子内部的结构(存储、逻辑、元器件)和各板块占用的资本都没有披露,所以板块层面的资本回报算不出来。
03.2|需求来自客户的投资计划,利润随汽车、机械和器件周期转
这家公司卖的是别人周期里的流量。钢铁和产业素材主要流向日本汽车、工程机械和建设行业,历史上集中在中部制造业带,现在分布到23个国家,它们决定了约六成集团销售额的数量周期;半导体和电子器件客户则驱动增长更快、利润率更高的电子业务。公司用库存和授信平滑客户周期,自己并不定价。
传导大致滞后一个季度,所以四个板块中有两个的景气不由公司自己决定。前十大客户占比没有披露,客户集中度因此无法判断。
03.3|海外占36.2%,中国在缩小,谁来补上还没有答案
2026年2月期海外销售额4,188.53亿日元,占36.2%(2020年2月期为29.5%),集团100家公司中52家在海外。结构在换挡:按客户所在地,中国从2022年2月期的846.51亿日元降到666.40亿日元,亚洲其他地区(1,460.60亿日元)和欧美及其他地区(1,194.58亿日元)在增长。
海外是GIC 30明确的增长方向。尚未解决的问题有两个:中国是被有意压缩,还是被动流失;东南亚和美洲能否以集团平均利润率接住差额。海外利润率、币种构成和对冲比例都没有披露,要看2027年2月期资料里的所在地构成和分板块利润率。
03.4|钢铁板块销售下滑,有多少是结构性的
钢铁板块销售额两年内从4,248.65亿日元降到3,778.23亿日元,利润守在110亿日元左右,利润率从2.4%升到2.9%。这一数字既可能代表议价能力,也可能只是产品结构改善,没有份额数据能区分。国内汽车和建设需求下降、钢厂直销压力是结构性因素;价格和库存是周期性因素,各占多少还不能确定。竞争地位只能从利润的持续性推断,没有取得市场份额或排名。要看接下来几份财报里钢铁板块的走势,以及同业业绩。
04|竞争格局与产业关系
这家公司与产业链上下游的关系,是用股权和交易同时绑住的。日本制铁既是集团主要的钢材供应商,又持有4.51%的股份;机床企业大隈是客户,同时持有1.69%。这种交叉持股强化了供货安全和钢铁板块的连续性,也是钢厂整合或流通体制改革最先传导到公司的通道,依赖是双向的。
目前没有披露按供应商划分的采购占比,也没有披露是否存在排他安排。公司在国内钢铁分销领域的同业对比、市场份额和排名同样没有取得,竞争地位只能依据利润的持续性判断。钢厂体系如果改变分销方式,是可以迅速影响钢铁板块的唯一一类供应事件,目前没有迹象显示这一点。
05|护城河判断
这家公司的优势在于网络,而不在技术壁垒。长期客户关系、银行授信能力(低成本的银行融资线是竞争资产)、与钢厂和机床客户的互相持股,加上加工和物流的增值服务,使它能在客户周期里平滑供需、承担信用。综合毛利率从7%左右升到9.2%,说明增值服务和产品结构在起作用。
反面证据同样清楚。贸易商的营业利润率只有3%左右;钢铁板块销售额两年下降,母公司钢铁销售额同期从2,641.55亿日元降到2,205.25亿日元,份额或需求可能在流失,只是靠毛利率维持了利润。钢铁板块利润守在110亿日元,究竟是议价能力还是产品结构,没有份额数据可验证。电子业务的优势有多大、能否抵挡客户直接交易,也没有独立证据。
357年的存续记录说明公司熬得过多轮周期,不说明毛利率能守住。只要钢厂体系不改变分销方式、银行圈继续提供低成本资金,网络优势可以延续。这种优势让利润稳定,但强度不足以让股东长期享有超额回报。钢铁下滑中结构与周期各占多少、电子分项结构和板块投入资本,仍是缺失的信息。
06|财务质量与现金流
06.1|2026年2月期每条利润线都创纪录,且超出期初计划近两成
2026年2月期(2025年3月至2026年2月)销售额1万1557.74亿日元,营业利润404.57亿日元,普通利润454.85亿日元,净利润305.06亿日元,均为历史新高;总资产1万0011.64亿日元,首次超过1万亿日元。相对期初计划,营业利润高出19.0%,普通利润高出19.7%,净利润高出22.0%。
就已读到的材料看,这一年没有异常项。但2026年2月期决算短信注释里的特别损益没有取得,所以「干净」只限于已读范围。
06.2|利润增长靠毛利率抬升,不靠销量
普通利润从2021年2月期的182.98亿日元涨到454.85亿日元,约2.5倍,没有一个下行年份,销售额却只是温和增长。靠的是毛利率:综合毛利率从2021年2月期的6.8%升到9.2%。
2026年2月期上半年可以看到这个机制的缩影:销售额增长5.7%,毛利增长20.7%,到普通利润是增长28.4%(上半年销售额5,706亿日元,毛利523亿日元,普通利润244亿日元)。销管费用占销售额5.7%(654.66亿日元),毛利率每变动一点,利润就大幅变化。
毛利率提升在电子结构、增值加工和价格转嫁之间怎么分配,公司没有披露,这里的归因是推断,不是实测。
06.3|普通利润里有两台引擎:贸易利润和持有证券的股息
营业利润404.57亿日元到普通利润454.85亿日元,中间差的是净财务收益56.99亿日元:收到的股息和利息83.50亿日元,权益法收益8.05亿日元,减去利息支出34.56亿日元。收到的股息从2018年2月期的46.32亿日元连涨八年。
按总额计算,股息相当于普通利润的18%左右(未扣融资成本)。只看营业利润会低估循环利润约57亿日元;而无视它是交叉持股,又会高估这部分利润的质量。股息中利息与股票分红各占多少、预扣税等税务损耗,已读材料里没有拆分。
06.4|现金:年度现金流由年底营运资金决定
这家公司的现金转换是波动的。经营现金流在2025年2月期只有44.89亿日元,2026年2月期是479.99亿日元,两年利润水平相近。原因在于应收账款周转3.6个月,年底的营运资金进出主导了全年现金。2026年2月期投资现金流只流出93.87亿日元,融资现金流流出360.35亿日元(还债和分红),所以经营现金流基本等同于自由现金流;带息负债一年减少近300亿日元,由经营现金流支付。
对这家公司而言,投资项目是营运资金,不是设备。应收3.6个月、库存1.5个月、应付1.8个月,客户被净垫资约两个月;折旧只有64.27亿日元,销售额1.16万亿日元,轻资产特征很清楚。库存刻意偏轻,钢价下跌时的减值风险有限;银行圈的低成本授信是一项竞争资产。真正的损失渠道,是主要客户的应收账款出事,客户分散能压低这种风险。应收账款账龄和客户集中度没有披露,周转月数是公司自己的计算口径。2027年2月期各季度的现金流路径也没有取得。
06.5|资产负债表比业务需要的更厚,而且在扩张中变得更厚
2026年2月期总资产1万0011.64亿日元,权益4,962.62亿日元,股东权益比率49.6%(上年44.5%);带息负债1,613.26亿日元,比上年的1,916.87亿日元减少近300亿日元;净负债权益比0.3倍,利息保障倍数14.4倍,流动比率154%,评级 R&I 为 A,JCR 为 A+。扩张靠留存利润和证券估值,不靠借款。
这也是为什么利润创纪录而ROE只有6.9%、市净率只有0.38倍。低杠杆是相对巨额净资产而言:2026年8月31日净带息负债仍有1,551.98亿日元,现金只有200亿日元左右。公开的只有年末数据,年内因营运资金出现的借款峰值看不到。
06.6|这份利润还缺哪几块证据
这份利润记录没有发现明显问题,但证据是有边界的,部分「没有异常」的判断来自没有找到证据。以下几项没有取得:2026年2月期的特别损益和会计政策变更(决算短信注释),委托交易与自营交易的收入区分,板块投入资本和ROIC,应收账款账龄,前十大客户占比,公司官方的ROIC定义或目标,库存股数量。
2027年3月的决算短信和5月的有价证券报告书可以补上其中大部分。在此之前,普通股东面对的是一份有限的记录,普通的审计风险可以接受,不能据此排除问题。
07|股东、董事与治理
07.1|股东名册上每个相关方都有席位,没有人有不满
股东结构非常稳定,也因此没有外部推动力。创业家族合计17.6%:家族关联的房产公司岡谷不動産(Okaya Fudosan)12.60%,Atsukazu Okaya 5.01%。银行和保险环合计15.3%:三菱UFJ银行4.80%、三井住友信托银行4.17%、理索纳银行2.75%、损保日本1.95%、爱知银行1.62%,同时也提供营运资金授信。再加上员工持股会1.65%,前十大股东合计41%左右,股东只有5,422人。
家族、贷款人、供应商、客户和员工各持一块,谁都没有不满,所以没有可以逼出变化的事件。新股东买进来,是进入一间座位已被占满的房间。库存股数量没有取得(推算约占1%),信托银行名下的股份可能含托管头寸。
07.2|董事报酬不是问题,缺的是明确的资本效率门槛
2026年2月期16名内部董事合计报酬5.01亿日元,约占普通利润的1.1%,其中固定2.17亿日元、业绩挂钩现金2.36亿日元、退休金0.48亿日元;外部董事等0.31亿日元。留存利润没有流向薪酬,而是流向资产负债表。董事会16人,以内部人为主,按今天的标准偏大。
外部董事名单、委员会结构和社长身份没有取得。没有发现关联交易、利益冲突或业绩承诺不兑现的证据;相反,开盘指引一贯偏保守,兑现好。治理的弱点在于没有明确的资本效率门槛和外部视角。
07.3|接班和上市场所是外人看不到的两件事
16人内部董事会、17.6%的家族股权和没有披露的接班框架,意味着这份名册长期的行为取决于一家家族企业(岡谷不動産)内部的决定,外部股东看不到。家族接班的走向是开放问题,决定可能让名册的行为朝任何一个方向变。要看2027年5月的治理报告和股东大会资料,以及有价证券报告书里的名册变化。
上市场所同样是结构性因素。7485自1995年上市以来只在名古屋证券交易所 Premier 市场交易,在东证指数体系和东证的资本成本披露要求之外,股东5,422人,任何大宗卖出都可能让流动性出现缺口,指数资金完全绕开这只股票,也没有外部日程逼迫估值讨论。
上市场所是折价的结构性组成部分,如果有变化,会是董事会手里最大的一次重估事件。上市安排在GIC 30期间是否保持、拆股频率、股东优待和已经开始的英文披露能否替代缺失的压力,没有名古屋交易所治理举措的研究可以参考,只能看之后的上市、披露或资本政策公告。
08|资本政策
08.1|利润被留在公司里:分红率10%,没有回购
资本回报是最被卡住的一环。每股股息连续九年增加,2026年2月期为161日元(2026年6月拆股前口径),分红率10.2%;已读材料里没有回购,政策文本只承诺分红,没有分红率、DOE或总回报的数值承诺。2027年2月期股息已经上调过一次:从2026年3月计划的拆股后86日元,调到中期资料中的90日元(同口径约增5%),分红率约10.8%,因为预测每股收益也上调了。
留存利润堆进市场正在打折的那部分净资产。公司是轻资产模式,折旧只有64.27亿日元,没有资本开支理由要保留这么多,低分红是选择,不是约束。收益型股东只拿到约1.9%的股息率,回报要靠盈利增长和是否重估。政策文本来自对公司IR文字的二手整理,GIC 30日文全文里可能存在DOE或总回报的表述,没有取得。
08.2|ROE偏低是净资产堆出来的,低ROE和0.38倍市净率是同一件事
ROE 6.9%主要是厚净资产的算术结果,不能说明经营弱。股东权益比率49.6%,净负债权益比0.3倍;如果换成普通贸易公司35%左右的权益结构,同样利润对应的ROE接近10%。研究估计的股权成本是7%至9%(小规模、流动性差的股东名册),6.9%处于这个门槛的下沿或以下。GIC 30的盈利目标在净资产不变的前提下,只能把ROE推到8%至9%。
低ROE和0.38倍市净率,是同一个资本结构事实的两个面。这意味着缩小差距也可以靠资本结构政策,不只靠经营改善,举证责任落在资本政策一侧。限制在于:股权成本是研究估计,不是公司披露;35%的对照改变了分母口径(期末净资产与平均净资产),只能作说明;公司官方ROIC的定义和目标也没有取得。
08.3|持有证券既是收益资产,也是关系纽带,改革会减少普通利润
持有证券产生83.50亿日元的年度股息,同时是对银行、钢厂和客户的关系纽带,也是市场要求解除持股的对象。按市场自己给的约6倍倍数粗略资本化,这笔股息相当于约500亿日元,占1,883.7亿日元市值的四分之一左右。这是总额、税前、未扣融资成本的说明性算术,不是研究事实;而且持有证券的价值已包含在合并净资产里,在任何分部估值中都不能按全价再算一次。
交叉持股改革是双向的。市场想要的正是这件事,但普通利润约五分之一来自这部分股息,仓促或被迫出售会直接削弱这个收益来源,同时释放资本;继续不动,则保留治理折价。起步几年,改革是增值还是减值,取决于路径,不取决于方向。公司对持有证券的最终处理(减持、保留还是不表态)没有任何表态,要看资本政策公告或2027年3月决算时对GIC 30的补充。
08.4|GIC 30承诺的是盈利增长,没有承诺资本效率
GIC 30(2026年9月30日公布)目标2031年2月期净利润400亿日元,比2026年2月期的305.06亿日元高31.1%,数字与基数自洽,投资和增长的重点放在海外,定位是GIC 25的延续,目标是成为「真正的全球企业」。英文新闻稿没有销售额、利润率、ROE或分红率的数值目标;ROIC只在二手解读里被提到一次;净利润目标来自行业报纸,只有英文稿是直接读到的原文。
这个目标要靠海外以接近集团的利润率增长,同时中国在份额中缩小。它支撑盈利复利,却没有回答估值问题。销售额、营业利润、板块构成、海外占比、资本开支和并购的完整数值,目前都没有取得。
08.5|资本政策是连接盈利和估值的唯一一座桥
这条因果链有几个环节:资产负债表(权益49.6%、净负债权益比0.3倍)和持有证券股息,已经包含了重估需要的一切;留存带来的净资产和ROE拖累压住市净率;GIC 30是盈利计划,目前读到的材料里没有公布资本承诺,也没有跨过这座桥。第三季度和2027年3月的决算,验证的是盈利这一半;只有资本政策公告,才能验证另一半。
董事会会不会在2027年3月公布2027年2月期决算时,给GIC 30附上数值化的承诺(ROE或ROIC目标、DOE下限、分红路径),是对折价最重要的一个问题。这是未来才会披露的事,目前没有公开途径可以提前回答。两种答案方向相反:给出承诺,是重估的路径;第一年报告继续沉默,则印证低分红和净资产堆积是政策,不是疏忽。
上行对资本政策事件是凸性的,对盈利增长是线性的;没有政策动作,结果就是治理时间。持有证券的市值、变现税负和董事会意图,都是未知。
08.6|两次拆股和股东优待是扩大持股面的动作,不是增加回报
管理层在21个月内完成两次1拆2(2024年9月1日和2026年6月1日;现有股份38,880,000股),当时拆股前价格已达约10,000日元,同时设有股东优待(大米和图书卡)。这是有意扩大持股面和流动性的动作,但没有提高现金回报。如果持续多年,可能在不改变政策的情况下,慢慢缩小上市场所造成的折价,效果没有证明,持股人数和流动性变化没有被测量;股东优待来自二手整理。
09|估值与安全边际
09.1|买入价已经为失望预付了钱:预测市盈率5.8倍,市净率0.38倍
2026年11月6日收盘价4,845日元(拆股后口径),总市值1,883.7亿日元(38,880,000股)。预测市盈率(PER)5.8倍,用的是修正后的2027年2月期公司指引每股收益831.55日元;实绩市净率(PBR)0.38倍,对应2026年2月期末每股净资产12,895.73日元;ROE 6.9%(2026年2月期实绩);预测股息率1.86%,对应预测每股股息90日元;EV/EBITDA 7.3倍。
这些倍数的口径并不一致。预测市盈率和股息率用2027年2月期公司预测,市净率和ROE用2026年2月期实绩。EV用2026年8月31日的净带息负债1,551.98亿日元。EBITDA(468.84亿日元,营业利润加折旧64.27亿日元)却是上一年度,所以EV/EBITDA只能作参考。预测每股收益来自对中期资料的二手整理,没有取得实时报价或买卖盘面。
09.2|市场为盈利付了全价,却不为净资产付价
这个折价最合理的看法,是上市场所和资本政策的折价:名古屋单一上市、分红率10%左右、没有回购、GIC 30里ROIC只是顺带提到,而不是市场认为盈利不可靠。同一个市场给盈利流付出接近财年高点的倍数,却拒绝给账面价值付价。三年的创纪录利润没有把市净率抬离0.38倍,所以要重估,需要一个资本政策事实,而不是又一次盈利超预期。市场的解释也可能是对的:留存的低回报资本和交叉持股的质量,值得打折;没有分析师一致预期,预期无法检验。
还有一层限定,会让「相对净资产便宜」没有标题数字那么干净。2026年2月期权益从3,835.75亿日元增加到4,962.62亿日元,约增1,127亿日元。
净利润305.06亿日元减去大约35亿日元分红,留存利润只能解释270亿日元左右。约四分之三的增加来自其他权益项目,与公司所说的「靠留存利润和证券估值」一致。
这是综合层面的算术推断,增加部分里证券估值、汇兑折算和少数股东变动各占多少没有取得。分红35亿日元左右是推算值。
因此市净率0.38倍的分母,有一部分是随市场变动的持有证券估值,不全是累积的经营利润。
要拿到净资产价值,还得依靠资本政策,路径见资本政策一章。
09.3|正常化盈利:普通利润420亿至460亿日元,以税前口径计
正常化盈利应以普通利润为锚,不以营业利润为锚,因为持有证券的股息(83.50亿日元,连涨八年)在行为上是循环的,只是在会计分类上属于营业外。研究给出的跨周期普通利润区间是420亿至460亿日元,中期上调后的2027年2月期预测455亿日元处于区间中上部;2021年2月期的低谷(182.98亿日元)是已记录的压力下限,但那是电子占比抬升之前的结构。去掉持股收益,循环基础每年会低估约57亿日元。
要注意口径:普通利润是税前数,5.8倍的市盈率对应净利润。用1,883.7亿日元市值除以这个区间,是税前普通利润的4.1至4.5倍,不能和市盈率直接比较,也不能把两者当作同一口径的倍数。这个区间是研究的正常化判断,不是公司数据;2026年2月期特别项目的细节和税后正常化数字没有取得。
这条估值链的结构是:正常化盈利决定基数,倍数在市场里读到,折价靠资本政策来收窄,持有证券的价值未知,因而不能被计算两次。价值是真实的,但能否拿到取决于政策和持有证券的可变现价值。贸易利润和持有证券的利润理应对应不同的倍数,市场目前用同一个低倍数给两者定价。
09.4|持有证券的市值没有取得,不能在估值里按全价计入
持有证券的市值、未实现收益和变现时的税负,在有价证券报告书的投资证券明细里有,但这次没有取得,所以没有资本化任何数字。隐含资产价值、ROE分母的质量、交叉持股改革的取舍,都取决于它。前文约500亿日元只是用市场倍数对股息的说明性算术。这些资产的价值已在合并净资产里,不能在分部估值中再按全价算一次。2027年2月期有价证券报告书里的明细可以解决这个缺口。
09.5|公司开盘指引是底线,不是预测
这家公司的期初指引,实际是一条底线。2025年2月期期初普通利润计划340亿日元,实际419.21亿日元,高出23%;2026年2月期计划380亿日元,实际454.85亿日元,高出19.7%。2027年2月期期初计划普通利润400亿日元,比上一年下降,约七个月后中期阶段就上调到455亿日元(上调13.75%)。
因此对全年业绩的预期,是达到或高于上调后的线,风险偏向小幅超出,而不是不及,除非下半年器件周期出现转折。这个样本只有两个周期;中期上调的数据来自二手整理,中期决算原件和分板块表没有取得。
对股价来说,超预期是预期之内的行为,不会触发重估;这与市场对盈利用6倍左右定价、不论业绩的状态一致。
09.6|下行保护来自结构,不只来自低价
下行保护有四层:库存只有1.5个月、流动比率154%、净负债权益比0.3倍,把再融资风险拿掉;四个板块的景气高点不同;2021年2月期的低谷仍有182.98亿日元普通利润;价格已处于0.38倍净资产,对失望已有预付。正常周期下行,预计会损失三分之一到一半的盈利,不会动摇权益。实际损失更可能经由应收账款和库存减值出现,而结构正是为压低这两项设计的。
这一保护有一个缺口。2021年2月期的压力测试,发生在电子业务占比抬升之前,并非同口径;电子业务利润率(3.6%)能否在器件资本开支下行期保住,没有同口径历史。客户信用事件的历史、复合压力和年内营运资金峰值,也都不可观察。最坏的现实情形是长期没有回报,不是资本受损;若同时发生器件下行、国内钢铁转弱和被迫低价出售持股,则没有先例。
09.7|价格已回到高位区,盈利是否已被部分预付
价格台阶和盈利台阶在财年尺度上同步,市场已经开始为盈利付钱,同时仍拒绝为净资产付钱。10月底价格在5,000日元左右(拆股后口径),处于2026年2月期的高位区,11月6日收盘4,845日元略低于此。这既是估值信息,也限制了买入的安全边际:价格是否已经提前反映GIC 30的兑现,目前没有答案。这条跨维度判断只在财年尺度成立,技术部分的读数本身把握不大,也不改变独立技术状态,细节见技术结构一章。
10|Kabugami 技术结构
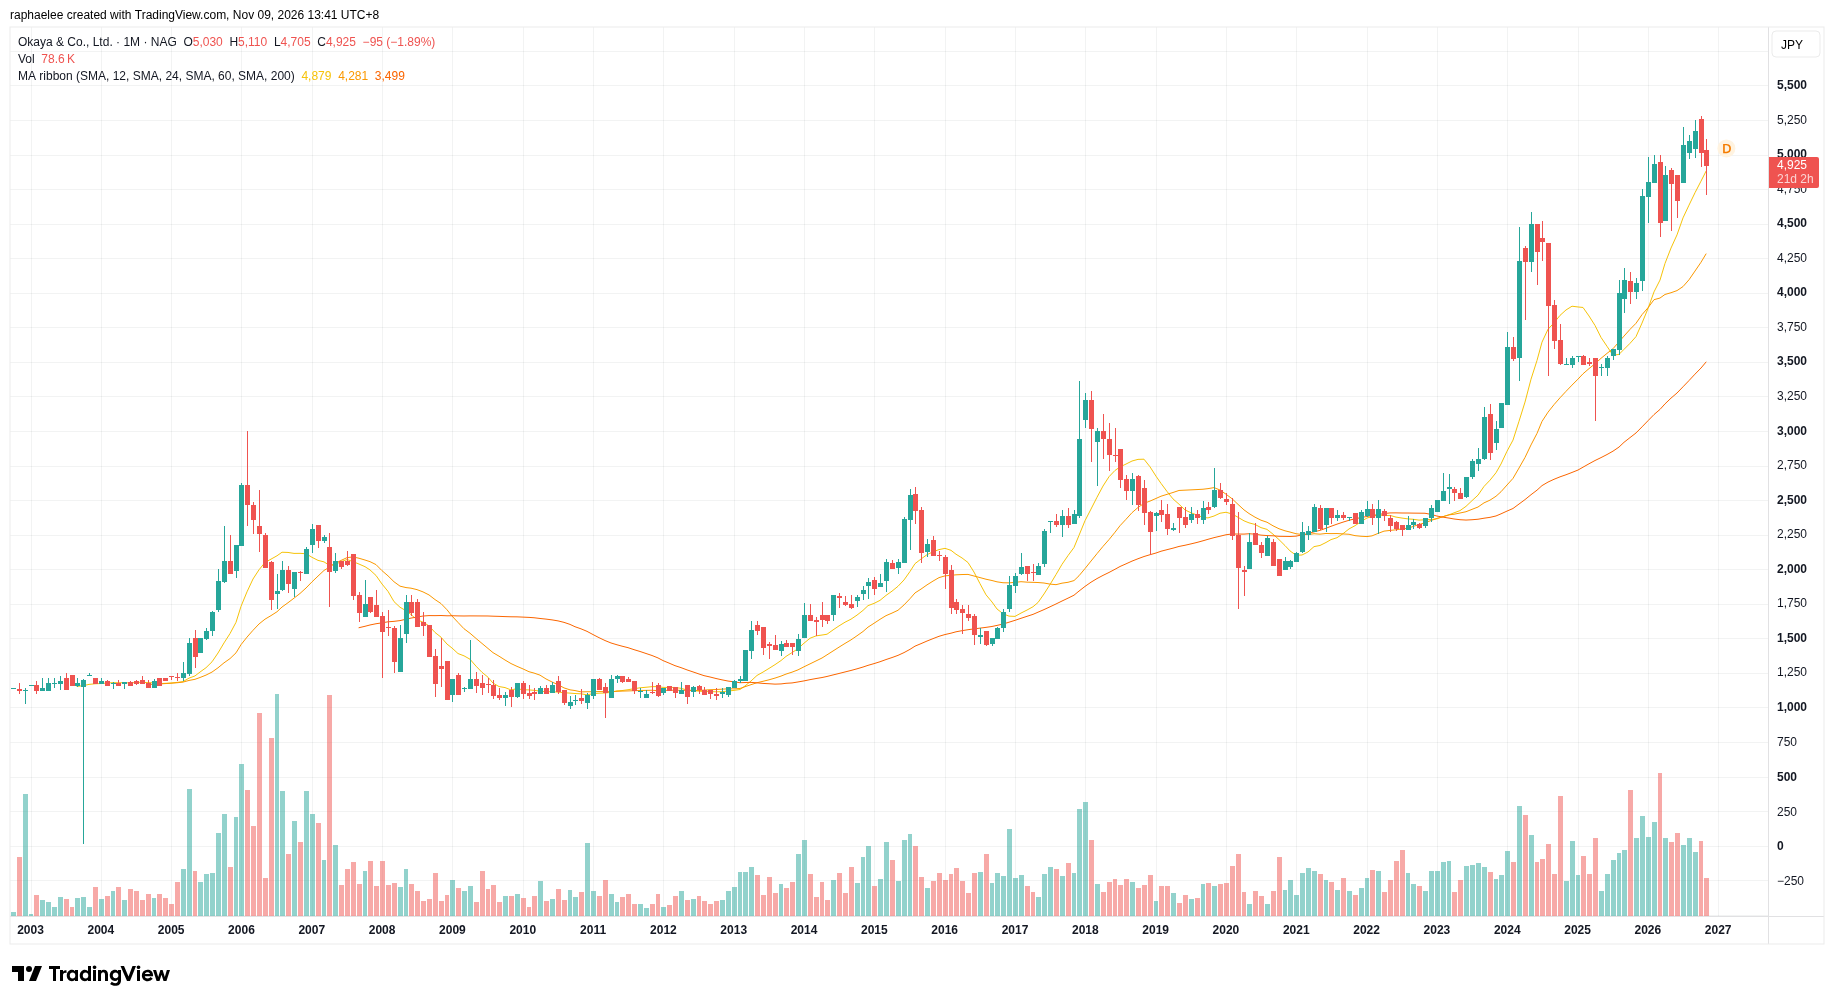
10.1|月线数据缺口:技术结论只能建立在年度价格带和既有结构读数上
这只股票的技术问题是:从长达十年的平台,走到财年高位区的这段上涨,是否已经是一次完成、并且站稳的台阶。本章把价格已经向上离开旧平台、多次回调都没有回到离开区域的状态,称为「成熟保留阶段」,下文只用这个名称。接下来要回答的,是什么价格行为会确认它,什么会推翻它。
数据有明确的缺口。7485只在名古屋证券交易所上市,研究使用的月线数据源不覆盖它,因此没有为这只股票计算月线均线、价格停留比例和成交量统计,本章也不做这方面的断言。
技术判断依赖三类材料:公司《Fact Book》里2018年2月期到2026年2月期的年度高低收盘价(拆股前口径,2024年9月拆股已追溯调整,2026年6月拆股未调整,折算时需减半);2026年11月9日冻结的月线全历史结构读数;以及2026年10月的几个带日期的收盘价(10月23日5,000日元,10月31日TradingView快照5,020日元)。以下价位均为2026年6月拆股后口径,另有标注的除外。
10.2|十年阶梯:平台、台阶、守住的回调、新高
冻结的月线读数把7485看作一道跨越世代的上升阶梯:长平台之后向上突破,台阶之间有2016年、2020年和2025年三次较深回调,每一次都没有回到之前离开的区域,每次再测试旧区域都比上次停得更高。2025年那次可以在年度价格带里验证;2016年和2020年只来自结构读数。
年度价格带记录了最近一段阶梯。2018年2月期到2023年2月期的年度高点大致在4,500至5,395日元之间(拆股前口径,折算后2,250左右至2,700日元),构成约六个财年的平台。
2024年2月期向上走出台阶,年度收盘7,060日元(折算后3,530日元)。2025年2月期回调到低点6,725日元(折算后3,363日元左右),仍明显高于旧平台顶部,最终收在6,970日元(折算后3,485日元)。
2026年2月期价格冲到10,000日元(折算后5,000日元),低点6,140日元(折算后3,070日元),收盘9,870日元(折算后4,935日元),是表里最高的年度收盘。
路径特征是台阶、测试、守住、延伸:平台,向上一步,一次高位的浅回调守住,加速到新的高位区,再在高位区停留到2026年10月。这是持股人不在强势中卖出的积累型路径。
结构上可以排出一个价格带次序。上沿是2026年2月期高位区(5,000日元左右)。
其下依次是2026年2月期收盘区(4,935日元左右)、2025年2月期收盘区(3,485日元左右)、2025年2月期回调低点(约3,363日元)和旧平台顶部(约2,700日元)。台阶是跨世代的,所以台阶内部的小幅波动在这个尺度上没有结构信息。
10.3|价格重心沿台阶上移,回调一次比一次停得高
价格重心是分级上移的,而不是漂移。平台期大致在2,500日元(折算后口径),2024年2月期到2025年2月期台阶和测试之后3,500日元左右,现在的高位区在4,900至5,000日元。每次上移,都由一次拒绝回到前一个重心的回调确认。回调停下来的位置就是重心所在,按冻结读数,它连续三次停得更高(2016年、2020年、2025年)。
市场的记忆就是这道阶梯本身:三次有记录的重度抛售都没有让价格回到它离开的区域,市场把旧价格当成了地板。只有未来某次回调收在旧区域内并停留,这份记忆才会减弱。
如果价格从高位区下行,较可能停下来的是这些台阶落点:先是2026年2月期收盘区(4,935日元左右),再是2025年2月期的落点(约3,360至3,490日元,上一次完整测试发生处),最后是旧平台顶部(约2,700日元)。当前高位区与2025年落点之间,没有记录显示的密集成交,一次跌穿第一个落点的下跌会穿过一段空档,这是世代阶梯的正常几何形状,本身不构成结构破坏。
在十年尺度上,每次冲击都在旧区域上方被消化,然后走上更高的台阶。下跌力度的逐步减弱,是冻结读数对点火前阶段的核心判断,年度低点总体抬高与之相符(2021年2月期3,425日元,2025年2月期6,725日元,2026年2月期6,140日元,均为拆股前口径,最后一年小幅低于前一年)。
其余几项分别如下。回撤形态上,2018年2月期到2023年2月期的长平台是压缩阶段,六个财年处于约20%的区间内,在2024年2月期向上解决;当前没有压缩判断,价格在延伸之后停在高位区,压缩判断需要月线精度。
回抽拓扑上,回报是一级级台阶,被长时间的横盘或下行测试隔开;2024年2月期到2026年2月期这三个财年兑现了这十年涨幅的大部分,未来的回报分布也可能是不平滑的,长期保留加上间歇性重估。失败的冲高上,2025年2月期的回调是有记录的一次:年内下探到6,725日元,没能触及旧平台就反转,收盘更高并随后创新高,卖方在远高于旧区域的位置失败,是当前高位区支撑逻辑的一部分。
停留判断上,价格在高位区的停留只来自冻结读数,月度停留比例没有计算,没有核对过的月线,给出百分比是虚假精确。恢复速度上,月数没法测量,替代证据是同一财年内的恢复:2025年2月期低点6,725日元,当年收盘6,970日元,2026年2月期再创新高。
涨跌响应上,年度价格带显示,阶梯内的下行年份相对此前的台阶较浅,向上的台阶较大(2026年2月期区间3,070至5,000日元),月度尺度的响应不对称统计因缺少数据而不给出。迁移质量上,现有证据显示质量较高:平台、2024年2月期台阶、2026年2月期高位区三次重心迁移,每次都有一次不回头的回调确认。
均线与振荡指标等观察指标需要月线,本次不做任何这类断言。
10.4|当前状态:成熟保留阶段,下一步是验证,不是启动
纯价格状态是成熟保留阶段:价格早已点火、多次走台阶,目前停在财年高位区(2026年10月5,000日元左右)。在这个框架里,它是持有并验证的状态,不是启动状态。剩下的技术工作,是持续观察保留是否成立。
这一状态内部有一个矛盾,两半都是结论,引用时不应只引其中一半:十年尺度的结构,达到了这套框架能给出的最强认证;而通常用来核对它的月线精度,在这只股票的数据里不存在。结构最强的股票,技术上的把握反而最低。技术判断把握不大。
确认保留的价格行为有三类:月线收盘在2026年12月下旬的第三季度发布窗口内,守在2026年2月期高位区(5,000日元左右)之上;月线收盘向上突破这个区域,说明重心再一次上移;较浅的确认也算数,即回调停在2026年2月期收盘区(4,935日元左右)或之上,回到高位区,期间没有收在2025年2月期落点之内。
会推翻或明显下调这个判断的价格行为同样明确:月线收盘回到2025年2月期落点区(约3,360至3,490日元),上一次获得确认的台阶,保留判断即被推翻;月线收盘回到旧平台内(低于约2,700日元),整个世代阶梯的判断作废。当前高位区与第一个推翻位之间,约有30%的空档、没有记录显示的密集成交,它是这道阶梯的已记录几何形状,不是安全边际。
10.5|价格台阶与盈利台阶在财年尺度上同步,价格是否已预付中期计划仍未知
在纯价格状态独立形成之后,再把价格与公开基本面对照。盈利台阶(2022年2月期到2026年2月期普通利润连续五年创新高)和价格台阶(平台、2024年2月期台阶、2025年2月期守住、2026年2月期新高)在财年尺度上是同步的。
价格在2024年2月期走出台阶,当年普通利润是358.50亿日元,已是连续第三个纪录。2025年2月期钢铁板块销售额下滑,价格没有回吐台阶,同期普通利润仍升到419.21亿日元。
2026年2月期价格延伸到新高,对应第五个纪录和首次突破1万亿日元的总资产。价格与基本面的时序关系是同步,不是价格领先,也不是基本面领先。
这说明市场已经开始为盈利付钱,同时仍不为净资产付钱。10月底价格在5,000日元左右,11月6日收盘4,845日元。悬而未决的问题是价格是否已经预付了GIC 30的兑现,这是一个技术状态只能提出、不能回答的估值问题。
这一对照不改变受保护的技术状态,也不提高它的技术把握:基本面的正面不能改写价格结构。事件层面的价格响应(日度)超出这只股票可用数据的范围,没有测量。这个判断只在财年尺度成立,月度尺度的验证无法进行。
10.6|两次1拆2让未复权的长期价格序列出现假暴跌
7485的价格序列有一个口径陷阱:2024年9月1日和2026年6月1日各做了一次1拆2。《Fact Book》的价格表追溯调整了2024年9月的拆股,但没有调整2026年6月那一次。任何未经复权的长期序列,都会在2024年9月和2026年6月出现假的腰斩式下跌,本章的价位对比都在一致口径上进行。
拆股本身是公司扩大持股面的流动性动作(现有股份38,880,000股,拆股前价格曾到约10,000日元),只是把报价机械地减半,没有结构含义,也不是价格状态的成因。拆股对持股人数和流动性的影响没有被测量。
11|风险与催化剂
11.1|最主要的风险是时间:折价可能比利润增长持续得更久
风险是具体的:分红率10%左右,没有回购,GIC 30里没有数值化的ROE、ROIC或DOE承诺。留存利润继续堆高净资产,ROE停在7%上下,折价可以在利润复利增长的同时持续数年。熊市情景是治理时间,不是经营失败,更像长期没有回报,而不是本金受损。
反方向的证据也存在:盈利已接近财年高点附近被定价,拆股和英文披露说明公司在做出一些渐进变化。
11.2|电子是增长引擎,也是最大的回撤敞口
电子业务提高了盈利的波动:半导体和器件元器件约占销售额32%,是最大的利润来源,器件资本开支周期比汽车周期更陡。公司自己的历史早于这个结构,2021年2月期不是同口径的压力测试,电子业务3.6%的利润率能否经得住器件下行期,没有答案。其他板块的景气高点不同,会减轻但不会消除这一敞口。一旦电子利润减半,就说明结构改善买到的是波动而不是质量,这是明确的推翻条件。
叠加起来,实际损失更可能来自应收账款而不是融资,正常下行大约损失三分之一到一半的盈利,复合压力没有先例,也没有触发条件。要看各板块业绩,直到下一轮器件下行,以及第三季度发布。
11.3|催化剂:盈利靠季报验证,折价靠资本政策验证
有日期的验证事件有两个。2027年2月期第三季度(9–11月)业绩预计在2026年12月下旬发布(日期为数据商估计,不是公司公告);这是第一份完全按拆股后股数披露的季度,将显示中期上调是否提前透支。2027年3月的2027年2月期决算是计划可信度事件:GIC 30第一年兑现情况,2028年2月期计划的口径(再次计划下降会印证保守习惯),以及任何资本政策的补充说明。GIC 30的进展报告周期未知。
没有日期但随时可能的是分红率、DOE、回购、交叉持股或上市场所方面的公告。三年的记录显示,盈利催化剂不足以推动净资产倍数重估,资本政策类催化剂才会。仓位应假设折价在盈利事件后仍然存在,只在资本事件后才会移动。
11.4|什么会推翻这个判断:两半判断各有各的检验
这个判断分两半:盈利复利,和折价被压住。三个基本面条件检验第一半:普通利润跌破358.50亿日元、电子利润减半、分红被削减。反向条件检验第二半:回购或数值化承诺出现,而盈利没有兑现。折价本身继续不动,是买入的前提,不构成推翻。价格结构上的推翻条件由独立的技术研究给出,不在这里重写。这些水平是研究判断,不是公司指引。
12|反常识发现
这个跨维度的发现是:造成十年阶梯的那个稳定股东结构,很可能也造成了0.38倍的市净率。创业家族17.6%、银行圈、钢厂与客户的交叉持股,使得抛压很难出现,也使每一种推动估值变化的外力都缺席:没有收购空间,没有指数资金,不在东证的信息披露体系内,没有激进股东规模的流通股。九年的分红连续增加、不回头的回调和折价,是同一个结构的几个后果。
拆股和股东优待是缓慢、局部的替代,补的是缺失的压力,效果没有证明。
这条解释的两半证据强度不同:股东结构一半有记录;价格一半依赖的是低技术把握的冻结读数。它不用来证明技术状态,只说明折价为何缺少触发。后果是,折价可能在没有来自公司内部的催化剂时无限期持续。
13|下一次值得跟踪什么
13.1|最该先弄清的问题:董事会会不会把资本政策数值化
董事会会不会在2027年3月公布2027年2月期决算时,给GIC 30附上ROE或ROIC目标、DOE下限或分红路径?这最重要,因为它是唯一能重新争论0.38倍折价的事件;给出承诺是重估的路径,第一年报告继续沉默,则印证低分红和净资产堆积就是政策。目前没有更早的公开途径可以回答。
同一个问题还连着上市场所:名古屋单一上市在GIC 30整个期间是否保持,拆股频率、股东优待和已经开始的英文披露,能否替代缺失的外部压力。要看上市、披露或资本政策方面的任何公告。
13.2|持有证券最终怎么处理,值多少钱
持有证券每年带来83.50亿日元股息,它的最终处理方向(减持、保留还是不表态)对普通利润和释放资本的含义正好相反。要回答这一点,需要有价证券报告书里投资证券明细的市值、未实现收益,以及变现时的税负;这是2027年5月前后的有价证券报告书可以解决的。没有这一项,隐含资产价值、ROE分母的质量和改革取舍都只能保持未知。
13.3|盈利的拆解:中期业绩里到底是谁在贡献
中期阶段把2027年2月期普通利润预测从400亿日元上调到455亿日元,意味着上半年很强,但分板块表没有取得。2027年2月期第三季度业绩(预计2026年12月下旬)是第一份能显示动能来自电子还是钢铁复苏的文件,需要对照中期决算原件。
GIC 30除2031年2月期净利润400亿日元之外的数值内容,包括销售额、营业利润、板块构成、海外占比、资本开支和并购额度,也没有取得;没有这个框架,计划的资本配置和海外回报无法检验,要看日文全文和2027年2月期决算说明。
另外三个问题:钢铁板块销售额下降有多少是结构性的,需要钢铁板块后续走势和同业业绩;中国是否被有意压缩、东南亚和美洲能否以同等利润率接上,需要2027年2月期的所在地构成;电子3.6%的利润率能否经得住器件下行,要等板块业绩穿过下一轮下行。
13.4|会计和披露:还缺哪些数字,以及谁来接班
2026年2月期的特别损益和会计政策变更、委托与自营交易的区分、板块投入资本与ROIC、应收账款账龄、前十大客户占比、官方ROIC定义和库存股数量,都要等2027年3月的决算短信和5月的有价证券报告书。
创业家族和岡谷不動産的接班走向,是一个外部股东看不到的决定,可能让名册的行为朝任何方向变;要看2027年5月的治理报告和股东大会资料,以及有价证券报告书里的名册变化。
技术上要看的是:月线收盘在第三季度发布窗口内能否守在约5,000日元之上,以及是否能取得经过核对的名古屋月线数据,让恢复速度和响应不对称可以测量。具体的确认和推翻价位见技术结构一章。
14|Kabugami 评分卡
14.1|总分64.22/100,评级B,处在B档上沿
Kabugami 评分版本 V3.2,八个模块满分合计100分,本次总分64.22/100,评级 B(B档为55至64.9分)。八个模块的得分加总为:10.66+8.68+11.05+7.48+11.25+3.50+3.15+8.45=64.22。
结论:盈利和资产负债表给了这家公司很扎实的得分,被压低的是资本配置和治理,也就是折价能否收窄的两个条件。操作上以持有和有纪律地跟踪为主,不追高;价格靠近2026年2月期收盘折算价(4,935日元)的回调可以分批考虑,仓位按名古屋单一上市的流动性控制。
需要继续验证的节点是2026年12月下旬前后的第三季度发布,和2027年3月的2027年2月期决算(GIC 30首年进展、是否出现资本政策表述)。价格回到约3,400日元以下、普通利润低于358.50亿日元、电子板块利润减半或分红被削减,会改变这个判断;出现回购或数值化的资本效率承诺则会加强。
14.2|财务和盈利:财务韧性10.66/13,盈利质量11.05/17
财务韧性与下行防御 10.66/13 分:股东权益比率49.6%,净负债权益比0.3倍,带息负债一年减少近300亿日元;没有给到更高,是因为净资产增量里约四分之三来自估值,且持有证券市值未知。
盈利质量、现金转化与资本效率 11.05/17 分:普通利润连续五年创新高,但ROE 6.9%处在研究估计的股权成本7%至9%的下沿,经营现金流在44.89亿和479.99亿日元之间摆动,毛利率改善的归因和特别损益未披露。
14.3|商业、竞争优势和估值:商业结构7.48/11,竞争优势8.68/14,估值11.25/15
商业结构、产品、客户与关键依赖 7.48/11 分:四个板块景气高点不同,海外占36.2%,但电子占销售额约32%且是最大利润来源,没有同口径的下行历史。
竞争优势与结构耐久性 8.68/14 分:网络型流通优势使综合毛利率从7%左右升到9.2%,但营业利润率只有3%左右,钢铁板块销售额两年下降,缺乏份额数据。
估值与安全边际 11.25/15 分:预测市盈率5.8倍、市净率0.38倍,下行更像长期没有回报;扣分处是净资产含估值成分、持有证券价值未标价,价格已回到高位区。
14.4|资本、治理和技术:资本配置3.50/10,治理3.15/7,技术结构8.45/13
资本配置与股东回报 3.50/10 分:分红率10%左右,没有回购,GIC 30没有数值化的资本效率承诺,是三项里得分最低的;九年连续增加股息和拆股只是部分抵消。
治理、所有权与管理层 3.15/7 分:家族、银行圈、供应商、客户和员工都有席位,结构稳定但没有外部压力;16名内部董事,接班框架未披露,薪酬本身不是问题。
Kabugami 技术结构 8.45/13 分:阶梯结构处于成熟保留阶段,三次回调没有回到旧区域;月线无法核对,所以得分被压在中上水平。技术得分只依据完整的受保护技术综合,不借用业绩改善。
14.5|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 10.66 | 2026年2月期总资产首次超过1万亿日元,净资产4962.62亿日元,股东权益比率49.6%(上年44.5%),带息负债降至1613.26亿日元(一年减少约300亿日元),净负债权益比约0.3倍,利息保障倍数14.4倍,流动比率154%,评级R&I为A、JCR为A+。资产扩张靠留存利润和证券估值,不靠借款。库存周期只有约1.5个月,钢价波动更多体现为利润波动,而不是资产负债表风险。 |
| 竞争优势与结构耐久性 | 14 | 8.68 | 公司创业于1669年,在23个国家有100家集团公司(合并子公司78家、权益法关联公司22家),靠的是长期客户关系、银行授信能力、与钢厂和机床客户的互相持股,以及加工和物流的增值服务。这是一张网络型的流通优势,不是技术或转换成本型壁垒;综合毛利率由约7%升到9.2%,说明增值服务和产品结构在发挥作用。 |
| 盈利质量、现金转化与资本效率 | 17 | 11.05 | 2026年2月期销售额1万1557.74亿日元、营业利润404.57亿日元、普通利润454.85亿日元、净利润305.06亿日元,普通利润连续五年创新高,且分别比期初计划高出约19%至22%。增长来自毛利率提升而非销量:上半年毛利增20.7%而销售额只增5.7%。但ROE只有6.9%,处于估计的股权成本(约7%至9%)的下沿甚至以下;经营现金流一年为44.89亿日元、一年为479.99亿日元,被营运资金波动主导。 |
| 商业结构、产品、客户与关键依赖 | 11 | 7.48 | 业务分为钢铁(销售额3778.23亿日元、营业利润110.16亿日元)、信息电子(3703.48亿日元、134.35亿日元,两年利润增44%)、产业素材(3219.30亿日元、110.71亿日元)和生活关联(856.71亿日元、37.76亿日元)四个板块,四块景气高点不同。海外销售4188.53亿日元,占36.2%,中国从846.51亿日元降到666.40亿日元,亚洲其他和欧美在增长。 |
| 估值与安全边际 | 15 | 11.25 | 2026年11月6日收盘价4845日元,市值约1883.7亿日元,按修正后的2027年2月期预测每股收益831.55日元,预测PER约5.8倍;按2026年2月期末每股净资产12,895.73日元,PBR约0.38倍;预测股息90日元,股息率约1.86%;EV/EBITDA约7.3倍(净负债取2026年8月末,EBITDA取上一年度,只能作参考)。将通常年份普通利润定在约420亿至460亿日元,市值相当于约4.1至4.5倍税前普通利润。 |
| 资本配置与股东回报 | 10 | 3.5 | 每股股息连续九年增加,但分红率只有约10%(2026年2月期10.2%),至今没有看到回购,政策文本只承诺分红而没有数值化的分红率、DOE或总还款承诺;2027年2月期股息从拆股后86日元上调到90日元,幅度约5%,仍在约10.8%的分红率之内。一年内两次1拆2(2024年9月和2026年6月,现有3888万股)和股东优待,是扩大持股面的动作,不是增加回报。 |
| 治理、所有权与管理层 | 7 | 3.15 | 股东结构非常稳定:创业家族合计约17.6%(冈谷不动产12.60%、冈谷笃一5.01%)、银行和保险环约15.3%(三菱UFJ4.80%、三井住友信托4.17%、理索纳2.75%、损保日本1.95%、爱知银行1.62%)、员工持股1.65%,前十大约41%,股东仅5422人。16名内部董事2026年2月期合计报酬5.01亿日元,约占普通利润1.1%,薪酬本身不是问题。 |
| Kabugami 技术结构 | 13 | 8.45 | 根据已完成的技术综合:价格长期走成阶梯,约六个财年的横盘平台在2024年2月期向上突破,2025年2月期回调后守住远高于旧平台的位置,2026年2月期再创新高,2026年10月底仍在约5000日元(拆股后口径)的高位区。结构处于成熟的保留阶段,三次回调都没有回到之前离开的区域。但由于只在名古屋交易所上市,没有可核对的月线数据,技术把握不大。 |
总分: 64.22 / 100 评级: B 操作建议: 以持有和有纪律地跟踪为主,不追高。基本面上盈利持续创新高、资产负债表厚实、估值处于低位(预测PER约5.8倍,PBR约0.38倍),下行偏向长期死钱而非本金受损;但价格已回到近年高位区,且资本政策没有出现数值化承诺前,折价缺少收窄的触发条件。可在回调靠近2026年2月期收盘区时分批考虑,并按名古屋单一上市的流动性来控制仓位。需要继续验证的节点:2026年12月下旬前后的第三季度发布、2027年3月的2027年2月期结果(GIC 30首年进展与是否出现资本政策表态)。价格回到约3400日元以下、普通利润低于358.5亿日元、电子板块利润减半或分红被削减,会改变这一判断;出现回购或数值化资本效率承诺则会加强。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|数据截止日和价格口径
研究截止日为2026年11月9日;估值使用的价格是2026年11月6日收盘价4,845日元,全部每股数据为2026年6月拆股后口径(38,880,000股)。倍数的期间并不一致。
预测市盈率和预测股息率基于2027年2月期公司预测,市净率和ROE基于2026年2月期实绩。EV用2026年8月31日的净带息负债1,551.98亿日元,EBITDA为2026年2月期的营业利润加折旧,所以EV/EBITDA只能作参考。
2027年2月期预测每股收益831.55日元和预测股息90日元来自对中期资料的二手整理。没有取得实时报价、买卖盘面或分析师一致预期。
15.2|主要来源和它们的限制
公司一手资料包括《Fact Book 2026》(2026年4月28日),含2026年2月期决算、板块、资产负债表、现金流、股息和年度价格带。另有2025年2月期决算短信及2026年2月期期初计划(2025年3月31日,经Jiji Equity转载的名古屋证券交易所披露)。
还有2026年2月期中期决算说明资料(2025年9月30日)和GIC 30英文新闻稿(2026年9月30日)。官方登记与股东名册来自经济产业省 G-Biz Info(基于EDINET,2026年5月26日);董事报酬和主要比率来自EDINET DB(2026年10月20日)。
二手或参考性来源包括:日刊工业新闻关于GIC 30目标的报道(2026年10月21日);Yoripoko投资者博客对中期资料、分红政策、股东优待和GIC 30的转述(2026年11月5日);TradingView的上市和价格快照(2026年10月31日);Shukatsu Ichiba和the-shashi的公司资料整理。上调后的2027年2月期预测、分红政策文本和GIC 30资本效率内容都来自转述,没有读到中期决算原件和GIC 30日文全文。
技术部分基于公司《Fact Book》的年度价格带、2026年11月9日冻结的月线结构读数和2026年10月的带日期收盘价;7485只在名古屋交易所上市,没有可核对的月线序列。本报告用于研究交流,不构成买卖建议;投资决策和损益由读者自行承担。
主要资料来源
- Legal identity and parent-company results from the FY2/2026 securities report (G-Biz Info, EDINET-derived)
- FY2/2024 interim tanshin: filing header and interim results
- Founding in 1669 and the 350-year continuity
- Fact Book 2026: group scale, employees and credit ratings
- Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas
- FY2/2026 key ratios compiled from the securities report (EDINET DB)
- FY2/2025 consolidated results (tanshin) and FY2/2026 initial guidance
- Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)
- FY2/2025 results briefing materials (31 March 2025)
- Ten-year consolidated financial history (the-shashi, securities-report based)
- New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)
- TradingView company profile: NAG:7485 Okaya & Co., Ltd.
- Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026
研究发现索引
展开本次 Review 的 67 项研究发现
F001|Okaya & Co., Ltd. (岡谷鋼機, EDINET E02553, Nagoya Premier Market only, code 7485, founded 1669, February year end) is an asset-light, four-segment trading and distribution network (steel; information & electronics; industrial materials; living-related products) of 100 group companies (78 consolidated subsidiaries, 22 equity-method affiliates) in 23 countries, with 6,536 consolidated employees against 773 at the parent. The parent books about half of group sales and only about 41 percent of group operating profit (JPY 16,541m of JPY 40,457m), and parent steel sales fell from JPY 264,155m (FY2/2024) to JPY 220,525m (FY2/2026). The investable entity is therefore the network; consolidated segment disclosure, not the Nagoya parent's legacy identity as a steel wholesaler, is the correct unit of analysis.
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|经营的是100家公司组成的贸易网络,不是名古屋总部
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(10项,重复标签已合并)
Legal identity and parent-company results from the FY2/2026 securities report (G-Biz Info, EDINET-derived)怎么使用:直接 / 支持;一手验证:01
FY2/2024 interim tanshin: filing header and interim results怎么使用:直接 / 支持;一手验证:01
Founding in 1669 and the 350-year continuity怎么使用:直接证据;一手验证:33;专项深挖:33;同业比较:01;其他用途:历史
Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas怎么使用:直接 / 支持;一手验证:02、07;专项深挖:07;同业比较:20;其他用途:历史
Employees: consolidated 6,536, parent 773 - the group is the company怎么使用:直接 / 支持;专项深挖:02
Parent versus group: parent operating profit JPY 16,541 million of the group's JPY 40,457 million怎么使用:直接 / 支持;反向验证:08、20;同业比较:04;其他用途:历史
Fact Book 2026: parent-company segment mix怎么使用:直接证据;一手验证:26;同业比较:35;其他用途:历史
Iron & Steel segment: FY2/2026 sales JPY 377,823 million, operating profit JPY 11,016 million怎么使用:支持证据;一手验证:08;反向验证:03、05、15;专项深挖:08;同业比较:06、10;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|Legal identity and parent-company results from the FY2/2026 securities report (G-Biz Info, EDINET-derived);直接证据 / 支持证据 / 一手证据(研究域01)|FY2/2024 interim tanshin: filing header and interim results;直接证据 / 定向深挖(研究域01)|Registered identity detail: EDINET E02553, corporate number, head office;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 定向深挖(研究域33)|Founding in 1669 and the 350-year continuity;直接证据|Fact Book 2026: group scale, employees and credit ratings;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域07) / 历史/同业比较(研究域20) / 定向深挖(研究域07)|Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas;直接证据 / 支持证据 / 定向深挖(研究域02)|Employees: consolidated 6,536, parent 773 - the group is the company;直接证据 / 支持证据 / 历史/同业比较(研究域04) / 反证(研究域08) / 反证(研究域20)|Parent versus group: parent operating profit JPY 16,541 million of the group's JPY 40,457 million;直接证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|Fact Book 2026: parent-company segment mix;支持证据 / 一手证据(研究域08) / 历史/同业比较(研究域06) / 历史/同业比较(研究域10) / 反证(研究域03) / 反证(研究域05) / 反证(研究域15) / 定向深挖(研究域08)|Iron & Steel segment: FY2/2026 sales JPY 377,823 million, operating profit JPY 11,016 million
完整研究记录(核对用)
研究原文:Okaya & Co., Ltd. (岡谷鋼機, EDINET E02553, Nagoya Premier Market only, code 7485, founded 1669, February year end) is an asset-light, four-segment trading and distribution network (steel; information & electronics; industrial materials; living-related products) of 100 group companies (78 consolidated subsidiaries, 22 equity-method affiliates) in 23 countries, with 6,536 consolidated employees against 773 at the parent. The parent books about half of group sales and only about 41 percent of group operating profit (JPY 16,541m of JPY 40,457m), and parent steel sales fell from JPY 264,155m (FY2/2024) to JPY 220,525m (FY2/2026). The investable entity is therefore the network; consolidated segment disclosure, not the Nagoya parent's legacy identity as a steel wholesaler, is the correct unit of analysis.
内部研究类型:ECONOMIC_IDENTITY_AND_PERIMETER
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Defines what the holder owns: a 357-year-old independent house whose economics sit mostly in subsidiaries, with no parent that can be assumed to act.
不确定性(原始记录):President identity and unlisted house entities around Okaya Fudosan were not extracted; no profit split among subsidiaries is public.
F002|06|2026年2月期每条利润线都创纪录,且超出期初计划近两成
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论06|2026年2月期每条利润线都创纪录,且超出期初计划近两成
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接 / 支持;一手验证:22
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接 / 支持;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|Fact Book 2026: FY2/2026 consolidated results highlights;直接证据|Fact Book 2026: FY2/2026 outcome versus the initial plan;直接证据 / 支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 支持证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026
完整研究记录(核对用)
研究原文:FY2/2026 (March 2025 to February 2026) was a record at every profit line: sales JPY 1,155,774m, operating profit JPY 40,457m, ordinary profit JPY 45,485m, net income JPY 30,506m, on total assets of JPY 1,001,164m (first year above JPY 1 trillion) and an equity ratio of 49.6 percent. Against the initial plan the delivery was +19.0 percent (operating), +19.7 percent (ordinary) and +22.0 percent (net).
内部研究类型:FACT_FINDING
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Sets the earnings base on which valuation multiples (about 5.8x PER) are read; the record is clean in the sources read.
不确定性(原始记录):FY2/2026 special-item detail from the tanshin notes was not retrieved, so 'clean' is bounded to the record read.
F003|09|公司开盘指引是底线,不是预测
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|公司开盘指引是底线,不是预测
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Guidance conservatism, two cycles documented怎么使用:直接 / 支持;外部现实校验:12;专项深挖:28、31
FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million怎么使用:直接证据;外部现实校验:30;反向验证:11、25、26;同业比较:12;其他用途:历史
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
H1 FY2/2026 gross-profit surge: +20.7 percent in the first half怎么使用:支持证据;反向验证:12;专项深挖:14
查看完整证据标签(核对用)
直接证据 / 支持证据|FY2/2025 consolidated results (tanshin) and FY2/2026 initial guidance;直接证据 / 支持证据|Fact Book 2026: FY2/2026 outcome versus the initial plan;直接证据 / 支持证据 / 外部现实(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域31)|Guidance conservatism, two cycles documented;直接证据 / 外部现实(研究域30) / 历史/同业比较(研究域12) / 反证(研究域11) / 反证(研究域25) / 反证(研究域26)|FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million;直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据|FY2/2025 results briefing materials (31 March 2025);支持证据|FY2/2026 interim results briefing materials (30 September 2025);支持证据 / 反证(研究域12) / 定向深挖(研究域14)|H1 FY2/2026 gross-profit surge: +20.7 percent in the first half
完整研究记录(核对用)
研究原文:Opening guidance at this issuer behaves as a floor, not a forecast. FY2/2025 (plan ordinary profit JPY 34,000m, delivered JPY 41,921m, +23 percent) and FY2/2026 (plan JPY 38,000m, delivered JPY 45,485m) both closed roughly one fifth above plan. The FY2/2027 initial plan (ordinary JPY 40,000m, a planned decline) was revised to JPY 45,500m at the interim stage (+13.75 percent within about seven months), with forecast EPS JPY 831.55 and dividend JPY 90 post-split; a sixth consecutive record is in sight. The prior for the full-year print is delivery at or above the revised line, with risk skewed to a small beat rather than a miss, barring a second-half device-cycle break.
内部研究类型:MANAGEMENT_BEHAVIOUR_PATTERN
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Reported 'beats' are expected behaviour and are not what re-rates the stock; this is consistent with the market capitalising earnings at about 6x regardless of prints.
不确定性(原始记录):Two cycles is a short sample; the interim revision rests on a secondary compilation (blog quoting H1 FY2/2027 materials), the primary interim release and segment table were not retrieved.
F004|03|利润重心已从钢铁移到电子,钢铁成了压舱石
研究范围:开放研究+35项覆盖检查
写入正文:03|利润重心已从钢铁移到电子,钢铁成了压舱石14|商业、竞争优势和估值:商业结构7.48/11,竞争优势8.68/14,估值11.25/15
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接 / 支持;一手验证:02、03;外部现实校验:09
Iron & Steel segment: FY2/2026 sales JPY 377,823 million, operating profit JPY 11,016 million怎么使用:直接 / 支持;一手验证:08;反向验证:03、05、15;专项深挖:08;同业比较:06、10;其他用途:历史
Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million怎么使用:直接 / 支持;一手验证:03;外部现实校验:35;反向验证:04、06、09、10、14;专项深挖:03;同业比较:33;其他用途:历史
Industrial Materials segment: FY2/2026 sales JPY 321,930 million, operating profit JPY 11,071 million怎么使用:直接 / 支持;专项深挖:09
Living-Related Products segment: FY2/2026 sales JPY 85,671 million, operating profit JPY 3,776 million怎么使用:直接 / 支持;专项深挖:10
Electronics book content: semiconductors, components, substrates, software怎么使用:直接证据;一手验证:04;外部现实校验:03;专项深挖:04
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域08) / 历史/同业比较(研究域06) / 历史/同业比较(研究域10) / 反证(研究域03) / 反证(研究域05) / 反证(研究域15) / 定向深挖(研究域08)|Iron & Steel segment: FY2/2026 sales JPY 377,823 million, operating profit JPY 11,016 million;直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域35) / 历史/同业比较(研究域33) / 反证(研究域04) / 反证(研究域06) / 反证(研究域09) / 反证(研究域10) / 反证(研究域14) / 定向深挖(研究域03)|Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million;直接证据 / 支持证据 / 定向深挖(研究域09)|Industrial Materials segment: FY2/2026 sales JPY 321,930 million, operating profit JPY 11,071 million;直接证据 / 支持证据 / 定向深挖(研究域10)|Living-Related Products segment: FY2/2026 sales JPY 85,671 million, operating profit JPY 3,776 million;直接证据 / 一手证据(研究域04) / 外部现实(研究域03) / 定向深挖(研究域04)|Electronics book content: semiconductors, components, substrates, software
完整研究记录(核对用)
研究原文:The profit engine has rotated: Information & Electronics (sales JPY 370,348m, operating profit JPY 13,435m, 3.6 percent margin, +44 percent profit in two years) now out-earns Iron & Steel (sales JPY 377,823m, operating profit JPY 11,016m, 2.9 percent margin), while steel segment sales fell from JPY 424,865m (FY2/2024) to JPY 377,823m with profit held near JPY 11bn. Industrial Materials (JPY 321,930m / JPY 11,071m, 3.4 percent) is the steadiest; Living-Related (JPY 85,671m / JPY 3,776m, 4.4 percent, +22 percent sales) is small but growing fastest. Margin ranking is the inverse of revenue age, so mix, not scale, drives profit and the 'steel trader' label misdescribes the earnings engine.
内部研究类型:STRUCTURAL_MIX_SHIFT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The shareholder's growth exposure is now semiconductor and device capex linked; steel contributes ballast, not growth.
不确定性(原始记录):Electronics sub-mix (memory vs logic vs components) and segment invested capital are not disclosed; segment returns on capital cannot be computed.
F005|06|利润增长靠毛利率抬升,不靠销量
研究范围:开放研究+35项覆盖检查
写入正文:06|利润增长靠毛利率抬升,不靠销量14|财务和盈利:财务韧性10.66/13,盈利质量11.05/17
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:直接 / 支持;一手验证:15、32;同业比较:02、11;其他用途:历史
Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent怎么使用:直接证据;外部现实校验:15;专项深挖:15
Margin stack FY2/2026: gross 9.2 percent, operating 3.5 percent, ordinary 3.9 percent怎么使用:直接证据;一手验证:16;专项深挖:16
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接证据;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:历史
H1 FY2/2026 gross-profit surge: +20.7 percent in the first half怎么使用:直接证据;反向验证:12;专项深挖:14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based);直接证据 / 外部现实(研究域15) / 定向深挖(研究域15)|Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Margin stack FY2/2026: gross 9.2 percent, operating 3.5 percent, ordinary 3.9 percent;直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 反证(研究域12) / 定向深挖(研究域14)|H1 FY2/2026 gross-profit surge: +20.7 percent in the first half
完整研究记录(核对用)
研究原文:Ordinary profit has set five consecutive records (JPY 18,298m in FY2/2021 to JPY 45,485m in FY2/2026, about 2.5x with no down year) while sales grew only modestly. Consolidated gross margin expanded from about 7 percent (6.8 percent in FY2/2021) to 9.2 percent. In H1 FY2/2026 gross profit rose 20.7 percent on sales up 5.7 percent, converting into ordinary profit +28.4 percent. The step-up is a margin and mix phenomenon (electronics, value-added processing, price pass-through) rather than a volume phenomenon. With SG&A at 5.7 percent of sales, small gross-margin changes dominate profit.
内部研究类型:MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Gross margin is the observable form of the moat compounding; it is also the variable that would show first if the mix reverses.
不确定性(原始记录):Causal split of the margin gain among electronics mix, value-added processing and price pass-through is not disclosed; attribution is inferred, not measured.
F006|06|普通利润里有两台引擎:贸易利润和持有证券的股息
研究范围:开放研究+35项覆盖检查
写入正文:06|普通利润里有两台引擎:贸易利润和持有证券的股息09|正常化盈利:普通利润420亿至460亿日元,以税前口径计
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Fact Book 2026: financial income detail - the second earnings engine怎么使用:直接 / 支持;外部现实校验:16、21
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接证据;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Equity-method income JPY 805 million across 22 affiliates怎么使用:直接证据;反向验证:16
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域21)|Fact Book 2026: financial income detail - the second earnings engine;直接证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 反证(研究域16)|Equity-method income JPY 805 million across 22 affiliates
完整研究记录(核对用)
研究原文:Ordinary profit is a two-engine number. Operating profit JPY 40,457m is lifted to JPY 45,485m by net financial income of +JPY 5,699m (dividends and interest received JPY 8,350m, equity-method income JPY 805m, interest paid JPY 3,456m). Dividends received have risen eight consecutive years from JPY 4,632m (FY2/2018). Gross dividends equal about 18 percent of ordinary profit before funding costs. A valuation that ignores the holdings stream understates recurring earnings power; one that ignores its cross-holding nature overstates its quality.
内部研究类型:EARNINGS_COMPOSITION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Trade profit and portfolio profit deserve different multiples; the market currently applies one low multiple to both.
不确定性(原始记录):Dividend stream composition (interest versus equity dividends) and withholding/tax leakage are not decomposed in the sources read.
F007|08|持有证券既是收益资产,也是关系纽带,改革会减少普通利润
研究范围:35项覆盖检查+开放研究
写入正文:08|持有证券既是收益资产,也是关系纽带,改革会减少普通利润09|持有证券的市值没有取得,不能在估值里按全价计入
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接证据;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Fact Book 2026: financial income detail - the second earnings engine怎么使用:直接证据;外部现实校验:16、21
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:直接证据;一手验证:27
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 外部现实(研究域16) / 外部现实(研究域21)|Fact Book 2026: financial income detail - the second earnings engine;直接证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026
完整研究记录(核对用)
研究原文:The listed holdings (policy shareholdings) behind JPY 8,350m of annual dividends are simultaneously an earnings asset, relationship cement with banks, mills and customers, and the object of market pressure for unwinding. Capitalising the gross dividend stream at the market's own roughly 6x gives about JPY 50bn, a material fraction (very roughly a quarter) of the JPY 188bn market capitalisation, but this is a gross, pre-tax, pre-funding-cost illustration, and the holdings' value is already inside the consolidated equity base, so it must not be counted again at full value in any sum-of-parts.
内部研究类型:HIDDEN_ASSET_AND_RELATIONSHIP_CEMENT
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Holders own an unmarked asset whose income compounds; its realisable value, tax leakage on monetisation and relationship cost of selling are not established.
不确定性(原始记录):Market value and unrealised gain of the portfolio exist in the securities report schedule but were not retrieved; no number is capitalised here. The roughly 50bn illustration is arithmetic on frozen inputs, not a research fact.
F008|08|持有证券既是收益资产,也是关系纽带,改革会减少普通利润
研究范围:35项覆盖检查+开放研究
写入正文:08|持有证券既是收益资产,也是关系纽带,改革会减少普通利润13|持有证券最终怎么处理,值多少钱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Fact Book 2026: financial income detail - the second earnings engine怎么使用:直接 / 支持;外部现实校验:16、21
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接 / 支持;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent怎么使用:直接 / 支持;外部现实校验:23、24;反向验证:13、21;专项深挖:24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域21)|Fact Book 2026: financial income detail - the second earnings engine;直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 支持证据 / 外部现实(研究域23) / 外部现实(研究域24) / 反证(研究域13) / 反证(研究域21) / 定向深挖(研究域24)|Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent
完整研究记录(核对用)
研究原文:Reform of cross-shareholdings, the very change the market wants, would mechanically cut ordinary profit: about a fifth of gross ordinary profit arrives as dividends from holdings. Hurried or forced sales would shrink that stream while releasing capital; continued inaction preserves the governance discount. The path, not the direction, determines whether reform adds or subtracts value in the first years. The intended end-state of the portfolio (reduction, hold, or silence) is unresolved.
内部研究类型:TWO_SIDED_RISK
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Reform and reported profit pull against each other in the short run; the market's preferred catalyst has an earnings cost.
不确定性(原始记录):No company statement on portfolio end-state; evidence that would resolve it is a capital-policy notice or GIC 30 elaboration at the March 2027 results.
F009|06|资产负债表比业务需要的更厚,而且在扩张中变得更厚
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表比业务需要的更厚,而且在扩张中变得更厚14|财务和盈利:财务韧性10.66/13,盈利质量11.05/17
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接 / 支持;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接 / 支持;一手验证:25;反向验证:18;专项深挖:18
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:直接 / 支持;一手验证:29;外部现实校验:18、22;专项深挖:22
Ratings path: JCR raised to A+, R&I at A怎么使用:直接 / 支持;一手验证:13;外部现实校验:07;专项深挖:13;同业比较:18;其他用途:历史
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接证据;一手验证:22
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域07) / 历史/同业比较(研究域18) / 定向深挖(研究域13)|Ratings path: JCR raised to A+, R&I at A;直接证据|Fact Book 2026: group scale, employees and credit ratings;直接证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB)
完整研究记录(核对用)
研究原文:The balance sheet is over-built for the business and strengthened while it grew: total assets JPY 1,001,164m, equity JPY 496,262m (49.6 percent, from 44.5 percent), interest-bearing debt JPY 161,326m (down from JPY 191,687m, about JPY 30bn lower), net D/E 0.3x, interest coverage 14.4x, current ratio 154 percent, ratings R&I A and JCR A+. The expansion was funded by retained earnings and securities valuations, not borrowing. This is why ROE is only 6.9 percent despite record profit and why the stock trades at about 0.38x book.
内部研究类型:BALANCE_SHEET_STRUCTURE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Financial distress is removed from the scenario set; the equity is a thick cushion and also the denominator that holds ROE down.
不确定性(原始记录):Year-end figures only; intra-year peak borrowings driven by working capital are not visible. Net interest-bearing debt was about JPY 155bn at 31 August 2026 with only about JPY 20bn of cash, so 'low leverage' is relative to a large equity base, not an absence of debt.
F010|09|市场为盈利付了全价,却不为净资产付价
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接证据;一手验证:25;反向验证:18;专项深挖:18
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接证据;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million;直接证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;直接证据|Fact Book 2026: FY2/2026 consolidated results highlights
完整研究记录(核对用)
研究原文:Derived from frozen operands: equity rose by about JPY 112.7bn in FY2/2026 (JPY 383,575m to JPY 496,262m), whereas net income of JPY 30.5bn less roughly JPY 3.5bn of dividends accounts for only about JPY 27bn of retained earnings. Roughly three quarters of the equity increase therefore came from other equity components, consistent with the source statement that the build was funded by retained earnings and securities valuations. Book value (and the 0.38x PBR denominator) is thus partly a mark-to-market of holdings and other valuation effects rather than purely accumulated operating profit.
内部研究类型:DERIVED_INFERENCE
内部来源标记:COVERAGE35
普通股东含义(原始记录):Qualifies how 'cheap' 0.38x book is: part of the book is valuation-sensitive holdings value and part of the ROE shortfall is a mark-to-market denominator effect that could reverse.
不确定性(原始记录):This is a Synthesis-level arithmetic inference; the decomposition of the non-retained portion (securities valuation, FX translation, minority changes) was not retrieved. Dividend of about JPY 3.5bn is the Coverage estimate.
F011|08|ROE偏低是净资产堆出来的,低ROE和0.38倍市净率是同一件事
研究范围:35项覆盖检查
写入正文:08|ROE偏低是净资产堆出来的,低ROE和0.38倍市净率是同一件事14|财务和盈利:财务韧性10.66/13,盈利质量11.05/17
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接 / 支持;一手验证:22
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:直接 / 支持;一手验证:29;外部现实校验:18、22;专项深挖:22
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接 / 支持;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent;直接证据 / 支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x
完整研究记录(核对用)
研究原文:ROE of 6.9 percent is an arithmetic consequence of the equity pile, not of weak operations. With a 49.6 percent equity ratio and 0.3x net D/E, the same profit on a normal trading-house capital structure (equity ratio near 35 percent) would print ROE near 10 percent. Against a reviewer-estimated cost of equity of roughly 7-9 percent for a small, illiquid register, reported ROE sits at or below the hurdle; the GIC 30 earnings target lifts ROE only to about 8-9 percent on a static equity base. The low ROE and the 0.38x PBR are the same fact seen from two sides.
内部研究类型:DERIVED_INFERENCE
内部来源标记:COVERAGE35
普通股东含义(原始记录):The shortfall is closable by capital-structure policy, not only by operating performance; burden of proof sits with capital policy.
不确定性(原始记录):Cost of capital is the reviewer's estimate, not company-disclosed; the 35 percent counterfactual changes denominator basis (point-in-time vs average equity) and is illustrative; no official ROIC definition or target was retrieved.
F012|08|利润被留在公司里:分红率10%,没有回购
研究范围:开放研究+35项覆盖检查
写入正文:08|利润被留在公司里:分红率10%,没有回购14|资本、治理和技术:资本配置3.50/10,治理3.15/7,技术结构8.45/13
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Fact Book 2026: dividend record and payout discipline怎么使用:直接证据;反向验证:22;同业比较:31;其他用途:历史
Dividend policy text as published on the company's IR pages怎么使用:直接 / 支持;外部现实校验:26;专项深挖:26
FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million怎么使用:直接 / 支持;外部现实校验:30;反向验证:11、25、26;同业比较:12;其他用途:历史
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:直接证据;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
Fact Book 2026: parent-company segment mix怎么使用:支持证据;一手验证:26;同业比较:35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;直接证据 / 支持证据 / 外部现实(研究域26) / 定向深挖(研究域26)|Dividend policy text as published on the company's IR pages;直接证据 / 支持证据 / 外部现实(研究域30) / 历史/同业比较(研究域12) / 反证(研究域11) / 反证(研究域25) / 反证(研究域26)|FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million;直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|Fact Book 2026: parent-company segment mix
完整研究记录(核对用)
研究原文:Capital return is the trapped point. Dividends per share have risen nine consecutive years to JPY 161 (pre-June-2026-split basis) at a payout ratio of about 10 percent (10.2 percent FY2/2026), with no buyback in the record read and a policy text that promises dividends without any numeric ratio, DOE or total-return commitment. The FY2/2027 dividend moved up once already, from JPY 86 post-split at the March 2026 plan to JPY 90 (about +5 percent like-for-like), inside a roughly 10.8 percent payout because forecast EPS rose. Retained earnings accumulate into the very equity the market discounts. With asset-light operations (depreciation JPY 6.4bn) there is no capex reason for low retention; it is a choice.
内部研究类型:CAPITAL_POLICY_FINDING
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Income holders are paid in patience (yield about 1.9 percent); total return must come from earnings growth and any re-rating, not from distributions.
不确定性(原始记录):Full Japanese GIC 30 text was not retrieved; DOE or total-return language may exist there. Policy text is from a secondary compilation of IR text.
F013|08|两次拆股和股东优待是扩大持股面的动作,不是增加回报
研究范围:35项覆盖检查
写入正文:08|两次拆股和股东优待是扩大持股面的动作,不是增加回报10|两次1拆2让未复权的长期价格序列出现假暴跌
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Two splits in two years: 1-for-2 in September 2024 and again in June 2026怎么使用:直接 / 支持;外部现实校验:25;反向验证:30、33;专项深挖:25
Shareholder benefits: rice and book cards (per the H1 FY2/2027 materials)怎么使用:直接 / 支持;专项深挖:32;同业比较:26;其他用途:历史
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接证据;反向验证:24;同业比较:25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域25) / 反证(研究域30) / 反证(研究域33) / 定向深挖(研究域25)|Two splits in two years: 1-for-2 in September 2024 and again in June 2026;直接证据 / 支持证据 / 历史/同业比较(研究域26) / 定向深挖(研究域32)|Shareholder benefits: rice and book cards (per the H1 FY2/2027 materials);直接证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);直接证据|Price-basis warning: two splits make unadjusted long charts misleading
完整研究记录(核对用)
研究原文:Management executed two 1-for-2 splits in 21 months (1 September 2024 and 1 June 2026; shares now 38,880,000) after the pre-split price reached about JPY 10,000, and runs a shareholder-benefit programme (rice and book cards). These are deliberate liquidity and register-broadening gestures that stop short of cash-return escalation, and may over years narrow the venue discount without a policy change. Any long price series not split-adjusted shows false halving in September 2024 and June 2026.
内部研究类型:REGISTER_BROADENING_ACTIONS
内部来源标记:COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Signals willingness to court retail holders without moving payout; effect on valuation is slow and unproven.
不确定性(原始记录):Effect on holder count or liquidity not measured; shareholder benefit is known via secondary compilation.
F014|11|最主要的风险是时间:折价可能比利润增长持续得更久
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论11|最主要的风险是时间:折价可能比利润增长持续得更久
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Fact Book 2026: dividend record and payout discipline怎么使用:直接 / 支持;反向验证:22;同业比较:31;其他用途:历史
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:直接 / 支持;同业比较:05;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接证据;反向验证:31;同业比较:13、22;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;直接证据 / 支持证据|Fact Book 2026: group scale, employees and credit ratings;直接证据 / 支持证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);直接证据 / 反证 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation)
完整研究记录(核对用)
研究原文:The trapped-value risk is concrete: at roughly 10 percent payout, no buyback and no numeric ROE/ROIC/DOE commitment in GIC 30, retained earnings keep swelling equity, ROE stays near 7 percent, and the discount can persist for years while profits compound. The bear case is governance time, not business failure.
内部研究类型:PRINCIPAL_RISK
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Dead money at a low multiple is the realistic adverse outcome, not capital impairment.
不确定性(原始记录):Counter-evidence exists: earnings are already priced near the fiscal-year high, splits and English disclosure suggest incremental change.
F015|01|利润连年创新高,市场却只给净资产0.38倍
研究范围:开放研究+35项覆盖检查
写入正文:01|利润连年创新高,市场却只给净资产0.38倍09|市场为盈利付了全价,却不为净资产付价14|商业、竞争优势和估值:商业结构7.48/11,竞争优势8.68/14,估值11.25/15
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:直接 / 支持;一手验证:27
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接 / 支持;一手验证:22
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接 / 支持;反向验证:31;同业比较:13、22;其他用途:历史
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接证据;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:反向验证:22;同业比较:31;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;直接证据 / 支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);直接证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x;反证 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline
完整研究记录(核对用)
研究原文:The roughly 0.38x PBR and about 6x PER are best read as a venue-and-capital-policy discount (Nagoya-only listing, about 10 percent payout, no buyback, ROIC mentioned only in passing in GIC 30) rather than a judgement that earnings are unsound: the market pays a full cyclical multiple for the earnings stream at the fiscal-year high zone while refusing to pay for book value. Re-rating therefore requires a capital-policy fact, not another earnings beat; three record years have not moved PBR off 0.38x.
内部研究类型:VALUATION_INTERPRETATION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Upside is convex to a policy event and linear to earnings; downside is protected by the balance sheet the market refuses to price.
不确定性(原始记录):Inference confidence moderate-high (0.82); alternative explanations include the market correctly discounting low-return retained capital and cross-holding quality. No analyst consensus exists to test expectations.
F016|09|买入价已经为失望预付了钱:预测市盈率5.8倍,市净率0.38倍
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论09|买入价已经为失望预付了钱:预测市盈率5.8倍,市净率0.38倍14|总分64.22/100,评级B,处在B档上沿15|数据截止日和价格口径15|主要来源和它们的限制
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:直接 / 支持;一手验证:27
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接 / 支持;反向验证:24;同业比较:25;其他用途:历史
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:直接 / 支持;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接 / 支持;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
Dated post-split closes, October 2026: JPY 5,000 at the 23 October close怎么使用:直接 / 支持;一手验证:31;反向验证:27;同业比较:34;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;直接证据 / 支持证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);直接证据 / 支持证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million;直接证据 / 支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x;直接证据 / 支持证据 / 一手证据(研究域31) / 历史/同业比较(研究域34) / 反证(研究域27)|Dated post-split closes, October 2026: JPY 5,000 at the 23 October close
完整研究记录(核对用)
研究原文:Point-in-time valuation (close 6 November 2026; research cut-off 9 November 2026): price JPY 4,845; market capitalisation JPY 188.37bn (38,880,000 post-split shares); forecast PER 5.8x on revised FY2/27 forecast EPS JPY 831.55; actual PBR 0.38x on FY2/26-end net assets per share JPY 12,895.73; ROE 6.9 percent (FY2/26 actual); forecast dividend yield 1.86 percent on JPY 90.00; EV/EBITDA 7.3x (EV JPY 343.57bn = market cap plus net interest-bearing debt JPY 155,198m at 31 August 2026; EBITDA JPY 46,884m = FY2/26 operating profit plus depreciation JPY 6,427m).
内部研究类型:VALUATION_SNAPSHOT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Anchors every multiple used in the Thesis; the price is slightly below the late-October ~JPY 5,000 level used in earlier compilations.
不确定性(原始记录):Forecast EPS derives from a secondary compilation of interim materials; EV/EBITDA mixes an interim net-debt date with a prior-year EBITDA, so it is indicative only; no live quote or order-book picture taken.
F017|09|正常化盈利:普通利润420亿至460亿日元,以税前口径计
研究范围:35项覆盖检查+开放研究
写入正文:09|正常化盈利:普通利润420亿至460亿日元,以税前口径计
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接 / 支持;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:历史
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接 / 支持;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:直接证据;一手验证:15、32;同业比较:02、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based)
完整研究记录(核对用)
研究原文:Normalised earnings power is best anchored on ordinary profit, not operating profit, because the holdings dividend stream (JPY 8,350m, eight years of growth) is recurring in behaviour though non-operating in classification. A through-cycle ordinary-profit band of roughly JPY 42-46bn is defensible, against which the interim-revised FY2/2027 guide of JPY 45.5bn sits mid-range; the FY2/2021 downturn year (JPY 18,298m) is the documented stress floor, though it predates the current electronics-heavy mix. Excluding the holdings stream understates the recurring base by about JPY 5.7bn a year.
内部研究类型:NORMALIZED_ECONOMICS
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):The market price is cheap against the band if it holds; fair only if governance time is priced in.
不确定性(原始记录):The band is the reviewer's normalisation, not company data; special-item detail for FY2/2026 and a post-tax normalised figure were not retrieved.
F018|06|现金:年度现金流由年底营运资金决定
研究范围:开放研究+35项覆盖检查
写入正文:06|现金:年度现金流由年底营运资金决定
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Cash conversion: operating cash flow JPY 47,999 million in FY2/2026 versus JPY 4,489 million in FY2/2025怎么使用:直接 / 支持;一手验证:17;外部现实校验:19、20;专项深挖:17;同业比较:32;其他用途:历史
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接证据;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months怎么使用:直接 / 支持;一手验证:19;外部现实校验:10、29;专项深挖:19;同业比较:15、17;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域19) / 外部现实(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域17)|Cash conversion: operating cash flow JPY 47,999 million in FY2/2026 versus JPY 4,489 million in FY2/2025;直接证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域10) / 外部现实(研究域29) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 定向深挖(研究域19)|Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months
完整研究记录(核对用)
研究原文:Cash conversion is volatile by construction. Operating cash flow was +JPY 4,489m in FY2/2025 and +JPY 47,999m in FY2/2026 on similar profit levels, because year-end working-capital swings in a 3.6-month receivables book dominate annual cash generation; investing outflow was only JPY 9,387m and financing -JPY 36,035m (debt repayment and dividends), so operating cash flow approximates free cash flow. The FY2/2026 debt reduction of about JPY 30bn was funded from operating cash flow.
内部研究类型:CASH_QUALITY_FINDING
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Dividend capacity should be judged on multi-year cash flow, which comfortably covers the roughly JPY 3.5bn dividend; any single year can mislead in either direction.
不确定性(原始记录):Quarterly cash-flow path within FY2/2027 not retrieved; ten-year series visible in the Fact Book but only two years extracted directly.
F019|06|现金:年度现金流由年底营运资金决定
研究范围:35项覆盖检查
写入正文:06|现金:年度现金流由年底营运资金决定
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months怎么使用:直接证据;一手验证:19;外部现实校验:10、29;专项深挖:19;同业比较:15、17;其他用途:历史
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:直接 / 支持;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
Cash conversion: operating cash flow JPY 47,999 million in FY2/2026 versus JPY 4,489 million in FY2/2025怎么使用:直接 / 支持;一手验证:17;外部现实校验:19、20;专项深挖:17;同业比较:32;其他用途:历史
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接 / 支持;一手验证:25;反向验证:18;专项深挖:18
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域19) / 外部现实(研究域10) / 外部现实(研究域29) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 定向深挖(研究域19)|Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months;直接证据 / 支持证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million;直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域19) / 外部现实(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域17)|Cash conversion: operating cash flow JPY 47,999 million in FY2/2026 versus JPY 4,489 million in FY2/2025;直接证据 / 支持证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million
完整研究记录(核对用)
研究原文:Working capital, not capex, is the group's investment programme. Receivables 3.6 months, inventory 1.5 months and payables 1.8 months mean customers are funded for about two months net; depreciation of JPY 6,427m on JPY 1.16 trillion sales confirms an asset-light model; SG&A (JPY 65,466m) is people and logistics. The deliberately light inventory limits steel-price writedown exposure; the cheap bank-ring lines are a competitive asset. Capital allocation choices are therefore choices about cash and securities, not plant.
内部研究类型:MECHANISM
内部来源标记:COVERAGE35
普通股东含义(原始记录):A receivables accident at a major customer is the realistic loss scenario; diversification across many accounts caps it. There is no capex excuse for low payout.
不确定性(原始记录):Receivables ageing and obligor concentration are not disclosed; turnover periods are the issuer's computed ratios.
F020|09|下行保护来自结构,不只来自低价
研究范围:35项覆盖检查
写入正文:09|下行保护来自结构,不只来自低价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months怎么使用:直接 / 支持;一手验证:19;外部现实校验:10、29;专项深挖:19;同业比较:15、17;其他用途:历史
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:直接 / 支持;一手验证:29;外部现实校验:18、22;专项深挖:22
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接 / 支持;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:历史
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接证据;一手验证:25;反向验证:18;专项深挖:18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域10) / 外部现实(研究域29) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 定向深挖(研究域19)|Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million
完整研究记录(核对用)
研究原文:Downside protection is structural rather than valuation-only: a 1.5-month inventory position, a 154 percent current ratio and 0.3x net D/E remove refinancing risk, four segments peak at different times, and the FY2/2021 downturn year still produced JPY 18,298m of ordinary profit. A price already at 0.38x book pre-pays for disappointment. Realistic losses come through receivables and inventory marks, which the structure minimises; a normal downturn should cost a third to a half of earnings, not the equity story.
内部研究类型:DOWNSIDE_STRUCTURE
内部来源标记:COVERAGE35
普通股东含义(原始记录):The adverse case is years of dead money, not capital impairment.
不确定性(原始记录):Customer-credit event history not disclosed; the FY2/2021 stress predates the current mix, so it is not like-for-like.
F021|09|下行保护来自结构,不只来自低价
研究范围:35项覆盖检查+开放研究
写入正文:09|下行保护来自结构,不只来自低价11|电子是增长引擎,也是最大的回撤敞口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million怎么使用:直接 / 支持;一手验证:03;外部现实校验:35;反向验证:04、06、09、10、14;专项深挖:03;同业比较:33;其他用途:历史
Electronics book content: semiconductors, components, substrates, software怎么使用:直接 / 支持;一手验证:04;外部现实校验:03;专项深挖:04
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接证据;一手验证:02、03;外部现实校验:09
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域35) / 历史/同业比较(研究域33) / 反证(研究域04) / 反证(研究域06) / 反证(研究域09) / 反证(研究域10) / 反证(研究域14) / 定向深挖(研究域03)|Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million;直接证据 / 支持证据 / 一手证据(研究域04) / 外部现实(研究域03) / 定向深挖(研究域04)|Electronics book content: semiconductors, components, substrates, software;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026;反证 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)
完整研究记录(核对用)
研究原文:The electronics engine raises earnings beta: semiconductors and device components are about 32 percent of sales and the largest profit pool, and device capex cycles are sharper than auto cycles. The group's own history predates this mix, so FY2/2021 is not a like-for-like stress test, and it is unknown whether the 3.6 percent segment margin survives a device-capex downturn. Other segments peak at different times, which damps but does not remove the exposure.
内部研究类型:STRUCTURAL_WEAK_SEAM
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):The growth engine is also the largest drawdown exposure; a halving of electronics profit is a stated falsifier of the quality of the mix shift.
不确定性(原始记录):Electronics sub-mix and segment-level cycle sensitivity are not disclosed; resolution evidence is segment results through the next device downturn and the Q3 print.
F022|03|需求来自客户的投资计划,利润随汽车、机械和器件周期转
研究范围:开放研究+35项覆盖检查
写入正文:03|需求来自客户的投资计划,利润随汽车、机械和器件周期转14|商业、竞争优势和估值:商业结构7.48/11,竞争优势8.68/14,估值11.25/15
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:直接证据;同业比较:05;其他用途:历史
End markets: automotive first, then construction and industrial machinery怎么使用:直接证据;一手验证:05、10;专项深挖:05;同业比较:08、09;其他用途:历史
Electronics book content: semiconductors, components, substrates, software怎么使用:直接证据;一手验证:04;外部现实校验:03;专项深挖:04
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接证据;一手验证:02、03;外部现实校验:09
查看完整证据标签(核对用)
直接证据|Fact Book 2026: FY2/2026 consolidated results highlights;直接证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 定向深挖(研究域05)|End markets: automotive first, then construction and industrial machinery;直接证据 / 一手证据(研究域04) / 外部现实(研究域03) / 定向深挖(研究域04)|Electronics book content: semiconductors, components, substrates, software;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026
完整研究记录(核对用)
研究原文:Demand is derived from customers' capex and production schedules. Japanese automotive and industrial-machinery (and construction) end markets absorb most steel and industrial-materials flow, concentrated historically in the Chubu belt and now spread across 23 countries, setting the volume cycle for roughly 60 percent of group sales; semiconductor and electronic-device end markets drive the faster-growing, higher-margin electronics book. Okaya sells into other companies' cycles and smooths them with inventory and credit.
内部研究类型:DEMAND_STRUCTURE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Earnings follow auto, machinery and device cycles with about a one-quarter lag; two of four segments are exogenous to Okaya's pricing.
不确定性(原始记录):Top-customer shares and customer concentration by name are not disclosed.
F023|03|海外占36.2%,中国在缩小,谁来补上还没有答案
研究范围:开放研究+35项覆盖检查
写入正文:03|海外占36.2%,中国在缩小,谁来补上还没有答案
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Fact Book 2026: overseas ratio and destination mix, FY2/2026怎么使用:直接 / 支持;外部现实校验:11、14;反向验证:32
Destination detail: China sales shrinking, Asia ex-China and the West growing怎么使用:直接 / 支持;一手验证:11、14;专项深挖:11
Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas怎么使用:直接证据;一手验证:02、07;专项深挖:07;同业比较:20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域11) / 外部现实(研究域14) / 反证(研究域32)|Fact Book 2026: overseas ratio and destination mix, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域14) / 定向深挖(研究域11)|Destination detail: China sales shrinking, Asia ex-China and the West growing;直接证据 / 一手证据(研究域02) / 一手证据(研究域07) / 历史/同业比较(研究域20) / 定向深挖(研究域07)|Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas;直接证据|Fact Book 2026: group scale, employees and credit ratings
完整研究记录(核对用)
研究原文:The overseas book is JPY 418,853m, 36.2 percent of sales (29.5 percent in FY2/2020), and is rotating: China destination sales fell from JPY 84,651m (FY2/2022) to JPY 66,640m (FY2/2026) while Asia ex-China (JPY 146,060m) and Europe/Americas/others (JPY 119,458m) grew; 52 of 100 group companies are overseas. It is the stated growth frontier of GIC 30. Whether China is being deliberately managed down and whether Southeast Asia and the Americas absorb the difference at group-average margin is unresolved.
内部研究类型:GROWTH_FRONTIER
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Overseas growth at group-average margin is the bridge between the FY2/2026 base and the FY2/2031 target; geographic risk is being rebalanced.
不确定性(原始记录):Overseas margin, currency split and hedge ratios are not disclosed; resolving evidence is destination mix and segment margins in FY2/2027 materials.
F024|07|股东名册上每个相关方都有席位,没有人有不满
研究范围:开放研究+35项覆盖检查
写入正文:07|股东名册上每个相关方都有席位,没有人有不满14|资本、治理和技术:资本配置3.50/10,治理3.15/7,技术结构8.45/13
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Top-ten shareholders at the FY2/2026 securities report (G-Biz Info, EDINET-derived)怎么使用:直接 / 支持;一手验证:24;外部现实校验:06
FY2/2024 interim tanshin: filing header and interim results怎么使用:直接 / 支持;一手验证:01
Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent怎么使用:直接证据;外部现实校验:23、24;反向验证:13、21;专项深挖:24
Bank and insurer bloc in the top ten怎么使用:直接证据;专项深挖:29;同业比较:07、23、24;其他用途:历史
Business-partner holders: Nippon Steel 4.51 percent, Okuma 1.69 percent, employee plan 1.65 percent怎么使用:直接证据;一手验证:06;外部现实校验:05;专项深挖:06
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接证据;反向验证:24;同业比较:25;其他用途:历史
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:支持证据;一手验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域06)|Top-ten shareholders at the FY2/2026 securities report (G-Biz Info, EDINET-derived);直接证据 / 支持证据 / 一手证据(研究域01)|FY2/2024 interim tanshin: filing header and interim results;直接证据 / 外部现实(研究域23) / 外部现实(研究域24) / 反证(研究域13) / 反证(研究域21) / 定向深挖(研究域24)|Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent;直接证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域29)|Bank and insurer bloc in the top ten;直接证据 / 一手证据(研究域06) / 外部现实(研究域05) / 定向深挖(研究域06)|Business-partner holders: Nippon Steel 4.51 percent, Okuma 1.69 percent, employee plan 1.65 percent;直接证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026
完整研究记录(核对用)
研究原文:The register is anchored by the founding family (Okaya Fudosan 12.60 percent, Atsukazu Okaya 5.01 percent; about 17.6 percent) with a bank and insurer ring about 15.3 percent combined (MUFG 4.80, Sumitomo Mitsui Trust 4.17, Resona 2.75, Sompo Japan 1.95, Aichi Bank 1.62) that also supplies working-capital lines, plus the employee plan (1.65 percent). Top ten hold about 41 percent among only 5,422 shareholders. Every constituency (family, lenders, supplier, customer, employees) holds a piece and none holds a grievance, so no forcing event exists.
内部研究类型:OWNERSHIP_STRUCTURE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Re-rating catalysts must come from inside the house; a new holder buys into a room where the seats are taken.
不确定性(原始记录):Treasury share count (implied about 1 percent) not retrieved; trust-bank holdings may include custody positions.
F025|04|最大的钢材供应商同时是股东,最大的机床客户也是股东
研究范围:开放研究+35项覆盖检查
写入正文:04|最大的钢材供应商同时是股东,最大的机床客户也是股东
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Top-ten shareholders at the FY2/2026 securities report (G-Biz Info, EDINET-derived)怎么使用:直接证据;一手验证:24;外部现实校验:06
Business-partner holders: Nippon Steel 4.51 percent, Okuma 1.69 percent, employee plan 1.65 percent怎么使用:直接证据;一手验证:06;外部现实校验:05;专项深挖:06
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域24) / 外部现实(研究域06)|Top-ten shareholders at the FY2/2026 securities report (G-Biz Info, EDINET-derived);直接证据 / 一手证据(研究域06) / 外部现实(研究域05) / 定向深挖(研究域06)|Business-partner holders: Nippon Steel 4.51 percent, Okuma 1.69 percent, employee plan 1.65 percent
完整研究记录(核对用)
研究原文:Nippon Steel is simultaneously the group's principal steel supplier and a 4.51 percent shareholder; machine-tool maker Okuma is a customer and a 1.69 percent shareholder. Trading relationships are bound in equity as well as in commerce, reinforcing supply security and steel-segment continuity, and are the channel through which mill consolidation or distribution reform would reach Okaya first. Dependence is two-sided.
内部研究类型:INDUSTRIAL_RELATIONSHIP
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A rupture with the mill system is the one supply event that could impair steel quickly; nothing in the record suggests it.
不确定性(原始记录):Purchase shares by supplier and any exclusivity arrangements are not disclosed.
F026|07|董事报酬不是问题,缺的是明确的资本效率门槛
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Director compensation FY2/2026: 16 internal directors, JPY 501 million total (EDINET DB)怎么使用:直接 / 支持;一手验证:23;专项深挖:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Director compensation FY2/2026: 16 internal directors, JPY 501 million total (EDINET DB)
完整研究记录(核对用)
研究原文:A 16-member internal board received JPY 501m in total in FY2/2026 (about 1.1 percent of ordinary profit; fixed JPY 217m, performance-linked cash JPY 236m, retirement JPY 48m); outside officers JPY 31m. Pay is not where retained earnings go; they go to the balance sheet. The board is large and insider-dominated by current norms.
内部研究类型:GOVERNANCE_FACT
内部来源标记:COVERAGE35
普通股东含义(原始记录):Incentives are not the problem; the issue is the absence of a stated capital-efficiency hurdle.
不确定性(原始记录):Outside-director roster, committee structure and president identity not retrieved.
F027|07|接班和上市场所是外人看不到的两件事
研究范围:35项覆盖检查+开放研究
写入正文:07|接班和上市场所是外人看不到的两件事13|会计和披露:还缺哪些数字,以及谁来接班
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Director compensation FY2/2026: 16 internal directors, JPY 501 million total (EDINET DB)怎么使用:直接 / 支持;一手验证:23;专项深挖:23
Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent怎么使用:直接 / 支持;外部现实校验:23、24;反向验证:13、21;专项深挖:24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Director compensation FY2/2026: 16 internal directors, JPY 501 million total (EDINET DB);直接证据 / 支持证据 / 外部现实(研究域23) / 外部现实(研究域24) / 反证(研究域13) / 反证(研究域21) / 定向深挖(研究域24)|Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent
完整研究记录(核对用)
研究原文:Succession and house governance are unpriced: a 16-member inside board, a family bloc of about 17.6 percent and no disclosed succession framework mean the register's long-run behaviour depends on decisions inside one family company (Okaya Fudosan) that outside holders cannot observe. The founding-family succession trajectory is an open question.
内部研究类型:GOVERNANCE_UNKNOWN
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):A family-company decision could change the register's behaviour, in either direction.
不确定性(原始记录):Evidence that would resolve it: governance report and AGM materials (May 2027), securities report register changes.
F028|07|接班和上市场所是外人看不到的两件事
研究范围:开放研究+35项覆盖检查
写入正文:07|接班和上市场所是外人看不到的两件事13|最该先弄清的问题:董事会会不会把资本政策数值化
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
TradingView company profile: NAG:7485 Okaya & Co., Ltd.怎么使用:直接 / 支持;外部现实校验:01、13
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接 / 支持;反向验证:24;同业比较:25;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接证据;反向验证:31;同业比较:13、22;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域13)|TradingView company profile: NAG:7485 Okaya & Co., Ltd.;直接证据 / 支持证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);直接证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation)
完整研究记录(核对用)
研究原文:7485 is listed only on the Nagoya Stock Exchange Premier Market (since the 1995 IPO), outside the TSE index complex and the TSE capital-cost disclosure regime, with 5,422 shareholders. Liquidity can gap on any block sale, index flows bypass the name, and no external calendar forces the valuation conversation. The venue is a structural component of the discount; any change would be the largest single re-rating event available to the board. Whether the listing persists through GIC 30 and what substitutes (split cadence, benefits, English disclosure already begun) is open.
内部研究类型:LISTING_STRUCTURE_RISK
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Unhedged liquidity and no forcing function; sizing should assume the discount persists until an internal decision changes it.
不确定性(原始记录):No Nagoya exchange governance initiatives were researched; resolving evidence is any listing, disclosure or capital-policy notice.
F029|08|GIC 30承诺的是盈利增长,没有承诺资本效率
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论08|GIC 30承诺的是盈利增长,没有承诺资本效率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:直接 / 支持;同业比较:05;其他用途:历史
Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026怎么使用:直接 / 支持;反向验证:28
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接证据;反向验证:31;同业比较:13、22;其他用途:历史
GIC 25 lookback: GIC 30 positioned as the successor plan怎么使用:直接 / 支持;反向验证:07、23;专项深挖:35;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);直接证据 / 支持证据 / 反证(研究域28)|Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026;直接证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);直接证据 / 支持证据 / 历史/同业比较(研究域30) / 反证(研究域07) / 反证(研究域23) / 定向深挖(研究域35)|GIC 25 lookback: GIC 30 positioned as the successor plan
完整研究记录(核对用)
研究原文:GIC 30 (announced 30 September 2026, FY2/2027-FY2/2031) targets net income of JPY 40bn in FY2/2031 (+31.1 percent versus JPY 30,506m; internally consistent) with investment and growth emphasised overseas, positioned as a continuation of GIC 25 and the aim of becoming 'a truly global company'. The English release states no numeric sales, margin, ROE or payout target; ROIC appears only once in a secondary reading. The plan underwrites earnings compounding but leaves the valuation question unanswered.
内部研究类型:STRATEGIC_PLAN
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A +31 percent five-year net-income path is consistent with mid-single-digit mix compounding, not a stretch, but does not itself address ROE or payout.
不确定性(原始记录):Net-income target comes from trade press; only the English release was read directly.
F030|01|利润连年创新高,市场却只给净资产0.38倍
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论01|利润连年创新高,市场却只给净资产0.38倍14|总分64.22/100,评级B,处在B档上沿
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接 / 支持;一手验证:02、03;外部现实校验:09
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:直接 / 支持;一手验证:15、32;同业比较:02、11;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接 / 支持;反向验证:31;同业比较:13、22;其他用途:历史
Fact Book 2026: overseas ratio and destination mix, FY2/2026怎么使用:直接 / 支持;外部现实校验:11、14;反向验证:32
Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent怎么使用:直接 / 支持;外部现实校验:15;专项深挖:15
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接 / 支持;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接 / 支持;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based);直接证据 / 支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);直接证据 / 支持证据 / 外部现实(研究域11) / 外部现实(研究域14) / 反证(研究域32)|Fact Book 2026: overseas ratio and destination mix, FY2/2026;直接证据 / 支持证据 / 外部现实(研究域15) / 定向深挖(研究域15)|Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent;直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x
完整研究记录(核对用)
研究原文:Two-layer compounding claim: operations compound through mix (electronics and value-added processing lifting gross margin year after year) and the holdings book compounds through rising dividends received, supported by a balance sheet (net D/E 0.3x, JCR A+) that removes distress from the scenario set. Normalised earnings power at or above the FY2/2026 ordinary-profit level through an ordinary cycle is supportable. The equity question is solely whether the market eventually prices either layer at more than 0.38x book while both are visible in the same filings: durable earnings trapped at a venue-and-policy discount.
内部研究类型:INVESTMENT_THESIS
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Return comes from earnings growth plus optional re-rating convex to a capital-policy event.
不确定性(原始记录):Confidence 0.8; depends on electronics durability, unresolved cross-holding path and absence of a capital-policy catalyst.
F031|01|什么会推翻这个判断:三个基本面数字和一个反向条件
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|什么会推翻这个判断:三个基本面数字和一个反向条件
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接证据;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:历史
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接证据;一手验证:02、03;外部现实校验:09
Fact Book 2026: dividend record and payout discipline怎么使用:直接证据;反向验证:22;同业比较:31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026;直接证据 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline
完整研究记录(核对用)
研究原文:Fundamental falsifiers: (a) ordinary profit falls below FY2/2024's JPY 35,850m without a macro cause of matching scale; (b) electronics segment profit halves in a device downturn, showing the mix shift bought beta, not quality; (c) the dividend is cut, breaking the nine-year permanence record. Reverse falsifier: a buyback or numeric capital commitment without earnings delivery would falsify the 'trapped' half of the thesis. Policy disappointment alone is not an exit, since it is the entry premise. A fourth, price-structure falsifier is owned by the protected Technical lane and is referenced, not restated or rewritten, here.
内部研究类型:FALSIFICATION_CONDITIONS
内部来源标记:COVERAGE35
普通股东含义(原始记录):Dated numeric falsifiers allow holding through noise; each print either touches one or not.
不确定性(原始记录):Levels are review judgements from documented figures, not company guidance.
F032|11|催化剂:盈利靠季报验证,折价靠资本政策验证
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|催化剂:盈利靠季报验证,折价靠资本政策验证
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Next print calendar: Q3 FY2/2027 results expected late December 2026 (vendor estimate)怎么使用:直接 / 支持;一手验证:30;专项深挖:30
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million怎么使用:直接 / 支持;外部现实校验:30;反向验证:11、25、26;同业比较:12;其他用途:历史
GIC 25 lookback: GIC 30 positioned as the successor plan怎么使用:直接 / 支持;反向验证:07、23;专项深挖:35;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Next print calendar: Q3 FY2/2027 results expected late December 2026 (vendor estimate);直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 支持证据 / 外部现实(研究域30) / 历史/同业比较(研究域12) / 反证(研究域11) / 反证(研究域25) / 反证(研究域26)|FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million;直接证据 / 支持证据 / 历史/同业比较(研究域30) / 反证(研究域07) / 反证(研究域23) / 定向深挖(研究域35)|GIC 25 lookback: GIC 30 positioned as the successor plan;支持证据|FY2/2026 interim results briefing materials (30 September 2025)
完整研究记录(核对用)
研究原文:Dated verification events: the Q3 FY2/2027 print (expected about 25 December 2026, a vendor estimate; the first print on the post-split share count, showing whether the interim revision was front-loaded); the FY2/2027 results in March 2027 (first-year GIC 30 delivery, FY2/2028 plan posture where another guided decline would confirm the conservatism pattern, and any capital-policy elaboration). Undated but live: any payout, DOE, buyback, cross-holding or venue notice. Earnings catalysts alone have a three-year record of not re-rating the book multiple.
内部研究类型:CATALYST_CALENDAR
内部来源标记:COVERAGE35
普通股东含义(原始记录):Size positions assuming the discount survives earnings catalysts and moves on capital ones.
不确定性(原始记录):December date is vendor estimate; GIC 30 progress-report cadence unknown.
F033|09|价格已回到高位区,盈利是否已被部分预付
研究范围:开放研究
写入正文:09|价格已回到高位区,盈利是否已被部分预付10|价格台阶与盈利台阶在财年尺度上同步,价格是否已预付中期计划仍未知
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Fiscal-year price ranges FY2/2018-FY2/2026 (Fact Book stock indicators, pre-June-2026-split basis)怎么使用:直接证据;一手验证:34
Frozen Muse Market chart reading, steel selection pass (9 November 2026), over the TradingView Nagoya monthly chart怎么使用:直接证据;外部现实校验:31、34;反向验证:35
Dated post-split closes, October 2026: JPY 5,000 at the 23 October close怎么使用:直接证据;一手验证:31;反向验证:27;同业比较:34;其他用途:历史
TradingView price snapshot: JPY 5,020 (late October 2026)怎么使用:直接证据;反向验证:34
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:直接证据;一手验证:27
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接证据;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域34)|Fiscal-year price ranges FY2/2018-FY2/2026 (Fact Book stock indicators, pre-June-2026-split basis);直接证据 / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域35)|Frozen Muse Market chart reading, steel selection pass (9 November 2026), over the TradingView Nagoya monthly chart;直接证据 / 一手证据(研究域31) / 历史/同业比较(研究域34) / 反证(研究域27)|Dated post-split closes, October 2026: JPY 5,000 at the 23 October close;直接证据 / 反证(研究域34)|TradingView price snapshot: JPY 5,020 (late October 2026);直接证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;直接证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x
完整研究记录(核对用)
研究原文:Fundamental-versus-price relationship, formed after both lanes were independently mature: the earnings staircase (five consecutive ordinary-profit records) and the price staircase are synchronised at fiscal grain, and the price ended October 2026 at about JPY 5,000 post-split on its FY2/2026 high zone (JPY 4,845 at the 6 November close), so the market has begun to pay for earnings while still refusing to pay for book. Open question: whether price has pre-paid GIC 30 delivery. This cross-lane view relates to, but does not alter, the separate protected Technical Synthesis; fundamental positivity does not rewrite its state or its LOW technical confidence, and event-level response was not measurable for this Nagoya-only code.
内部研究类型:CROSS_LANE_TIMING_SEMANTIC
内部来源标记:OPEN_DISCOVERY / TECHNICAL
普通股东含义(原始记录):The holder is late in a long move on price structure while fundamentals and valuation still show an unpriced governance discount; both facts must be held together.
不确定性(原始记录):Monthly-grain verification is unavailable for the Nagoya code; the chart reading is the frozen campaign pass and technical confidence is LOW. Timing inference at fiscal grain only.
F034|09|持有证券的市值没有取得,不能在估值里按全价计入
研究范围:35项覆盖检查
写入正文:09|持有证券的市值没有取得,不能在估值里按全价计入13|持有证券最终怎么处理,值多少钱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接证据;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Fact Book 2026: financial income detail - the second earnings engine怎么使用:直接证据;外部现实校验:16、21
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接证据;一手验证:25;反向验证:18;专项深挖:18
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 外部现实(研究域16) / 外部现实(研究域21)|Fact Book 2026: financial income detail - the second earnings engine;直接证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million
完整研究记录(核对用)
研究原文:The market value and unrealised gain of the holdings portfolio, and its tax leakage if monetised, were not retrieved though the securities-report investment-securities schedule exists. Hidden-asset value, ROE denominator quality and the cross-holding reform trade-off all depend on it.
内部研究类型:RESEARCH_DEBT
内部来源标记:COVERAGE35
普通股东含义(原始记录):Could change how much of 0.38x book is liquid, realisable value versus mark-to-market.
不确定性(原始记录):Resolution: FY2/2027 securities report schedule of investment securities with market values.
F035|06|这份利润还缺哪几块证据
研究范围:35项覆盖检查
写入正文:06|这份利润还缺哪几块证据13|会计和披露:还缺哪些数字,以及谁来接班
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:直接证据;一手验证:15、32;同业比较:02、11;其他用途:历史
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接证据;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months怎么使用:直接证据;一手验证:19;外部现实校验:10、29;专项深挖:19;同业比较:15、17;其他用途:历史
Margin stack FY2/2026: gross 9.2 percent, operating 3.5 percent, ordinary 3.9 percent怎么使用:直接证据;一手验证:16;专项深挖:16
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based);直接证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;直接证据 / 一手证据(研究域19) / 外部现实(研究域10) / 外部现实(研究域29) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 定向深挖(研究域19)|Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Margin stack FY2/2026: gross 9.2 percent, operating 3.5 percent, ordinary 3.9 percent
完整研究记录(核对用)
研究原文:Disclosure gaps carried as UNKNOWN: FY2/2026 special gains/losses and accounting-policy changes from the tanshin notes; principal-versus-agent revenue split by segment; segment invested capital and ROIC; receivables ageing; top-customer shares; official ROIC definition or target; treasury share count. The accounting-anomaly judgement ('nothing anomalous') rests partly on absence of evidence.
内部研究类型:RESEARCH_DEBT
内部来源标记:COVERAGE35
普通股东含义(原始记录):Holders face ordinary audit risk on the retrieved record, not forensic risk, but the record is bounded.
不确定性(原始记录):Resolution: FY2/2027 tanshin notes (March 2027) and securities report (May 2027).
F036|13|盈利的拆解:中期业绩里到底是谁在贡献
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接证据;同业比较:27、28;其他用途:历史
Next print calendar: Q3 FY2/2027 results expected late December 2026 (vendor estimate)怎么使用:直接证据;一手验证:30;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Next print calendar: Q3 FY2/2027 results expected late December 2026 (vendor estimate)
完整研究记录(核对用)
研究原文:What did the H1 FY2/2027 interim print contain at segment level? The revision of ordinary profit from JPY 40,000m to JPY 45,500m implies a strong first half, but the interim segment table was not retrieved; the Q3 FY2/2027 print (about late December 2026) is the first document that can show whether electronics momentum or steel recovery drove it.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Decides whether the guidance upgrade carries electronics beta or broad recovery.
不确定性(原始记录):Currently resolvable only by the Q3 print or retrieval of the primary interim release.
F037|13|盈利的拆解:中期业绩里到底是谁在贡献
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:直接证据;同业比较:05;其他用途:历史
Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026怎么使用:直接证据;反向验证:28
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接证据;反向验证:31;同业比较:13、22;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);直接证据 / 反证(研究域28)|Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026;直接证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation)
完整研究记录(核对用)
研究原文:Full numeric content of GIC 30 beyond the FY2/2031 net-income target of JPY 40bn (sales, operating profit, segment mix, overseas ratio, capex and M&A envelopes) is unknown; the English release carries none and trade press gives only the net-income line.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Without the envelope, the plan's capital allocation and overseas economics cannot be tested.
不确定性(原始记录):Resolution: full Japanese GIC 30 materials and FY2/2027 results commentary.
F038|08|资本政策是连接盈利和估值的唯一一座桥
研究范围:开放研究
写入正文:08|资本政策是连接盈利和估值的唯一一座桥13|最该先弄清的问题:董事会会不会把资本政策数值化
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Fact Book 2026: dividend record and payout discipline怎么使用:直接证据;反向验证:22;同业比较:31;其他用途:历史
Dividend policy text as published on the company's IR pages怎么使用:直接证据;外部现实校验:26;专项深挖:26
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:直接证据;同业比较:05;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接证据;反向验证:31;同业比较:13、22;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;直接证据 / 外部现实(研究域26) / 定向深挖(研究域26)|Dividend policy text as published on the company's IR pages;直接证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);直接证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation)
完整研究记录(核对用)
研究原文:Will capital policy move (payout ratio, DOE, first buyback), and will the board attach numeric capital-efficiency commitments (ROE/ROIC target, DOE floor, payout path) at the FY2/2027 results in March 2027? Nine years of dividend increases at about 10 percent payout, no repurchase in the record read, and no numeric commitment leave the largest valuation lever untouched; continued silence at the first-year report would confirm that low payout and the equity build are policy, not oversight.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The single event that could re-argue the 0.38x discount; opposite answers imply a re-rating path or years of dead money.
不确定性(原始记录):Future disclosure; no current public path beyond the March 2027 results and any notice.
F039|03|钢铁板块销售下滑,有多少是结构性的
研究范围:开放研究+35项覆盖检查
写入正文:03|钢铁板块销售下滑,有多少是结构性的13|盈利的拆解:中期业绩里到底是谁在贡献
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Iron & Steel segment: FY2/2026 sales JPY 377,823 million, operating profit JPY 11,016 million怎么使用:直接证据;一手验证:08;反向验证:03、05、15;专项深挖:08;同业比较:06、10;其他用途:历史
Fact Book 2026: parent-company segment mix怎么使用:直接证据;一手验证:26;同业比较:35;其他用途:历史
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接证据;一手验证:02、03;外部现实校验:09
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域08) / 历史/同业比较(研究域06) / 历史/同业比较(研究域10) / 反证(研究域03) / 反证(研究域05) / 反证(研究域15) / 定向深挖(研究域08)|Iron & Steel segment: FY2/2026 sales JPY 377,823 million, operating profit JPY 11,016 million;直接证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|Fact Book 2026: parent-company segment mix;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026
完整研究记录(核对用)
研究原文:How much of the steel segment's two-year sales decline (JPY 424,865m to JPY 377,823m) is structural (domestic auto and construction demand, mill direct-sales pressure) versus cyclical price and inventory effects, given segment profit held near JPY 11bn? Margin rose from 2.4 to 2.9 percent, but whether that is pricing power or mix is not established; competitive position was inferred from profit persistence, not share data.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Distinguishes slow share bleed from a cyclical dip in the ballast segment.
不确定性(原始记录):No market-share or ranking data retrieved; resolution via steel segment trajectory in coming prints and peer results.
F040|06|利润增长靠毛利率抬升,不靠销量
研究范围:开放研究+35项覆盖检查
写入正文:06|利润增长靠毛利率抬升,不靠销量14|财务和盈利:财务韧性10.66/13,盈利质量11.05/17
归并到:F005
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接 / 支持;一手验证:02、03;外部现实校验:09
Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent怎么使用:直接证据;外部现实校验:15;专项深挖:15
H1 FY2/2026 gross-profit surge: +20.7 percent in the first half怎么使用:直接证据;反向验证:12;专项深挖:14
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:支持证据;一手验证:15、32;同业比较:02、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026;直接证据 / 外部现实(研究域15) / 定向深挖(研究域15)|Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent;直接证据 / 反证(研究域12) / 定向深挖(研究域14)|H1 FY2/2026 gross-profit surge: +20.7 percent in the first half;支持证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based)
完整研究记录(核对用)
研究原文:Electronics and value-added mix shift lifts consolidated gross margin and converts modest sales growth into much faster profit growth.
内部研究类型:CAUSES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F041|06|普通利润里有两台引擎:贸易利润和持有证券的股息
研究范围:35项覆盖检查+开放研究
写入正文:06|普通利润里有两台引擎:贸易利润和持有证券的股息09|正常化盈利:普通利润420亿至460亿日元,以税前口径计
归并到:F006
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接证据;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Fact Book 2026: financial income detail - the second earnings engine怎么使用:直接 / 支持;外部现实校验:16、21
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域21)|Fact Book 2026: financial income detail - the second earnings engine
完整研究记录(核对用)
研究原文:The holdings portfolio's dividends supply the second earnings engine that puts ordinary profit above operating profit.
内部研究类型:PRODUCES
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F042|08|资本政策是连接盈利和估值的唯一一座桥
研究范围:开放研究+35项覆盖检查
写入正文:08|资本政策是连接盈利和估值的唯一一座桥09|市场为盈利付了全价,却不为净资产付价
归并到:F062
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(10项,重复标签已合并)
Fact Book 2026: dividend record and payout discipline怎么使用:直接 / 支持;反向验证:22;同业比较:31;其他用途:历史
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接 / 支持;一手验证:25;反向验证:18;专项深挖:18
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:支持证据;同业比较:05;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:反向验证:31;同业比较:13、22;其他用途:反证、历史
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:支持证据;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:支持证据;一手验证:29;外部现实校验:18、22;专项深挖:22
Ratings path: JCR raised to A+, R&I at A怎么使用:支持证据;一手验证:13;外部现实校验:07;专项深挖:13;同业比较:18;其他用途:历史
Fact Book 2026: parent-company segment mix怎么使用:支持证据;一手验证:26;同业比较:35;其他用途:历史
Dividend policy text as published on the company's IR pages怎么使用:支持证据;外部现实校验:26;专项深挖:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;直接证据 / 支持证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million;支持证据|Fact Book 2026: group scale, employees and credit ratings;支持证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);反证 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);支持证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent;支持证据 / 一手证据(研究域13) / 外部现实(研究域07) / 历史/同业比较(研究域18) / 定向深挖(研究域13)|Ratings path: JCR raised to A+, R&I at A;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|Fact Book 2026: parent-company segment mix;支持证据 / 外部现实(研究域26) / 定向深挖(研究域26)|Dividend policy text as published on the company's IR pages
完整研究记录(核对用)
研究原文:Roughly 10 percent payout and no buyback retain earnings into an ever-larger equity base and equity ratio.
内部研究类型:ACCUMULATES_INTO
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F043|08|ROE偏低是净资产堆出来的,低ROE和0.38倍市净率是同一件事
研究范围:35项覆盖检查
写入正文:08|ROE偏低是净资产堆出来的,低ROE和0.38倍市净率是同一件事14|财务和盈利:财务韧性10.66/13,盈利质量11.05/17
归并到:F011
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接 / 支持;一手验证:22
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:直接 / 支持;一手验证:29;外部现实校验:18、22;专项深挖:22
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:支持证据;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent;支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x
完整研究记录(核对用)
研究原文:The thick equity base is the arithmetic reason ROE is 6.9 percent despite record profit.
内部研究类型:MECHANICALLY_DEPRESSES
内部来源标记:COVERAGE35
F044|08|ROE偏低是净资产堆出来的,低ROE和0.38倍市净率是同一件事
研究范围:35项覆盖检查
写入正文:08|ROE偏低是净资产堆出来的,低ROE和0.38倍市净率是同一件事14|财务和盈利:财务韧性10.66/13,盈利质量11.05/17
归并到:F011
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接 / 支持;一手验证:22
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接 / 支持;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:支持证据;一手验证:27
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:支持证据;反向验证:31;同业比较:13、22;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:反向验证:22;同业比较:31;其他用途:反证、历史
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:支持证据;一手验证:29;外部现实校验:18、22;专项深挖:22
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x;支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);反证 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent
完整研究记录(核对用)
研究原文:Low ROE and the 0.38x PBR are two views of the same capital-structure fact.
内部研究类型:SAME_FACT_FROM_OTHER_SIDE
内部来源标记:COVERAGE35
F045|09|市场为盈利付了全价,却不为净资产付价
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接证据;一手验证:25;反向验证:18;专项深挖:18
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接证据;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:支持证据;一手验证:27
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:支持证据;一手验证:22
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:支持证据;反向验证:31;同业比较:13、22;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:反向验证:22;同业比较:31;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million;直接证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);反证 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline
完整研究记录(核对用)
研究原文:Because much of the equity increase is valuation-driven, 'cheap versus book' is less clean than the headline PBR suggests.
内部研究类型:QUALIFIES
内部来源标记:COVERAGE35
F046|12|同一个稳定股东结构,既托住了价格台阶,也压住了净资产估值
研究范围:开放研究+35项覆盖检查
写入正文:12|同一个稳定股东结构,既托住了价格台阶,也压住了净资产估值
归并到:F061
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
Top-ten shareholders at the FY2/2026 securities report (G-Biz Info, EDINET-derived)怎么使用:直接 / 支持;一手验证:24;外部现实校验:06
Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent怎么使用:直接证据;外部现实校验:23、24;反向验证:13、21;专项深挖:24
Bank and insurer bloc in the top ten怎么使用:直接证据;专项深挖:29;同业比较:07、23、24;其他用途:历史
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接证据;反向验证:24;同业比较:25;其他用途:历史
FY2/2024 interim tanshin: filing header and interim results怎么使用:支持证据;一手验证:01
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:支持证据;一手验证:27
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:支持证据;一手验证:22
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:支持证据;反向验证:31;同业比较:13、22;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:反向验证:22;同业比较:31;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域06)|Top-ten shareholders at the FY2/2026 securities report (G-Biz Info, EDINET-derived);直接证据 / 外部现实(研究域23) / 外部现实(研究域24) / 反证(研究域13) / 反证(研究域21) / 定向深挖(研究域24)|Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent;直接证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域29)|Bank and insurer bloc in the top ten;直接证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);支持证据 / 一手证据(研究域01)|FY2/2024 interim tanshin: filing header and interim results;支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);反证 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline
完整研究记录(核对用)
研究原文:A stable register removes takeover surface, activist-sized float and index flow, so the discount has no forcing function.
内部研究类型:SUSTAINS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F047|12|同一个稳定股东结构,既托住了价格台阶,也压住了净资产估值
研究范围:开放研究+35项覆盖检查
写入正文:12|同一个稳定股东结构,既托住了价格台阶,也压住了净资产估值
归并到:F061
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
TradingView company profile: NAG:7485 Okaya & Co., Ltd.怎么使用:直接 / 支持;外部现实校验:01、13
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接 / 支持;反向验证:24;同业比较:25;其他用途:历史
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:支持证据;一手验证:27
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:支持证据;一手验证:22
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:支持证据;反向验证:31;同业比较:13、22;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:反向验证:22;同业比较:31;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域13)|TradingView company profile: NAG:7485 Okaya & Co., Ltd.;直接证据 / 支持证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);反证 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline
完整研究记录(核对用)
研究原文:Nagoya-only listing keeps the name outside TSE index and capital-cost disclosure pressure.
内部研究类型:SUSTAINS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F048|08|持有证券既是收益资产,也是关系纽带,改革会减少普通利润
研究范围:35项覆盖检查
写入正文:08|持有证券既是收益资产,也是关系纽带,改革会减少普通利润13|持有证券最终怎么处理,值多少钱
归并到:F008
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Fact Book 2026: financial income detail - the second earnings engine怎么使用:直接 / 支持;外部现实校验:16、21
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接 / 支持;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:支持证据;反向验证:22;同业比较:31;其他用途:历史
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:支持证据;同业比较:05;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:反向验证:31;同业比较:13、22;其他用途:反证、历史
Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent怎么使用:支持证据;外部现实校验:23、24;反向验证:13、21;专项深挖:24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域21)|Fact Book 2026: financial income detail - the second earnings engine;直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;支持证据 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;支持证据|Fact Book 2026: group scale, employees and credit ratings;支持证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);反证 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);支持证据 / 外部现实(研究域23) / 外部现实(研究域24) / 反证(研究域13) / 反证(研究域21) / 定向深挖(研究域24)|Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent
完整研究记录(核对用)
研究原文:The reform that would release trapped capital (cross-holding unwinds) would cut the dividend stream supporting ordinary profit, so releasing value and protecting reported earnings pull in opposite directions in the short run.
内部研究类型:TRADEOFF_WITH
内部来源标记:COVERAGE35
F049|09|下行保护来自结构,不只来自低价
研究范围:35项覆盖检查
写入正文:09|下行保护来自结构,不只来自低价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million怎么使用:直接 / 支持;一手验证:03;外部现实校验:35;反向验证:04、06、09、10、14;专项深挖:03;同业比较:33;其他用途:历史
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接 / 支持;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:反证、历史
Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months怎么使用:支持证据;一手验证:19;外部现实校验:10、29;专项深挖:19;同业比较:15、17;其他用途:历史
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:支持证据;一手验证:29;外部现实校验:18、22;专项深挖:22
Electronics book content: semiconductors, components, substrates, software怎么使用:支持证据;一手验证:04;外部现实校验:03;专项深挖:04
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域35) / 历史/同业比较(研究域33) / 反证(研究域04) / 反证(研究域06) / 反证(研究域09) / 反证(研究域10) / 反证(研究域14) / 定向深挖(研究域03)|Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million;直接证据 / 支持证据 / 反证 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);支持证据 / 一手证据(研究域19) / 外部现实(研究域10) / 外部现实(研究域29) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 定向深挖(研究域19)|Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months;支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent;支持证据 / 一手证据(研究域04) / 外部现实(研究域03) / 定向深挖(研究域04)|Electronics book content: semiconductors, components, substrates, software
完整研究记录(核对用)
研究原文:The documented FY2/2021 earnings floor predates the electronics-heavy mix, so it is not a like-for-like stress test of the current structure.
内部研究类型:QUALIFIES
内部来源标记:COVERAGE35
F050|11|催化剂:盈利靠季报验证,折价靠资本政策验证
研究范围:35项覆盖检查+开放研究
写入正文:00|报告身份、评分与核心结论11|催化剂:盈利靠季报验证,折价靠资本政策验证
归并到:F032
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
Next print calendar: Q3 FY2/2027 results expected late December 2026 (vendor estimate)怎么使用:直接 / 支持;一手验证:30;专项深挖:30
FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million怎么使用:直接 / 支持;外部现实校验:30;反向验证:11、25、26;同业比较:12;其他用途:历史
Guidance conservatism, two cycles documented怎么使用:支持证据;外部现实校验:12;专项深挖:28、31
H1 FY2/2026 gross-profit surge: +20.7 percent in the first half怎么使用:支持证据;反向验证:12;专项深挖:14
GIC 25 lookback: GIC 30 positioned as the successor plan怎么使用:支持证据;反向验证:07、23;专项深挖:35;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 支持证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Next print calendar: Q3 FY2/2027 results expected late December 2026 (vendor estimate);直接证据 / 支持证据 / 外部现实(研究域30) / 历史/同业比较(研究域12) / 反证(研究域11) / 反证(研究域25) / 反证(研究域26)|FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million;支持证据|FY2/2025 consolidated results (tanshin) and FY2/2026 initial guidance;支持证据|Fact Book 2026: FY2/2026 outcome versus the initial plan;支持证据|FY2/2026 interim results briefing materials (30 September 2025);支持证据 / 外部现实(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域31)|Guidance conservatism, two cycles documented;支持证据 / 反证(研究域12) / 定向深挖(研究域14)|H1 FY2/2026 gross-profit surge: +20.7 percent in the first half;支持证据 / 历史/同业比较(研究域30) / 反证(研究域07) / 反证(研究域23) / 定向深挖(研究域35)|GIC 25 lookback: GIC 30 positioned as the successor plan
完整研究记录(核对用)
研究原文:The guidance-conservatism prior is tested at the Q3 print and the March 2027 results.
内部研究类型:VERIFIED_BY
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F051|06|现金:年度现金流由年底营运资金决定
研究范围:35项覆盖检查
写入正文:06|现金:年度现金流由年底营运资金决定
归并到:F018
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months怎么使用:直接 / 支持;一手验证:19;外部现实校验:10、29;专项深挖:19;同业比较:15、17;其他用途:历史
Cash conversion: operating cash flow JPY 47,999 million in FY2/2026 versus JPY 4,489 million in FY2/2025怎么使用:直接 / 支持;一手验证:17;外部现实校验:19、20;专项深挖:17;同业比较:32;其他用途:历史
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:支持证据;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:支持证据;一手验证:25;反向验证:18;专项深挖:18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域10) / 外部现实(研究域29) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 定向深挖(研究域19)|Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months;直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域19) / 外部现实(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域17)|Cash conversion: operating cash flow JPY 47,999 million in FY2/2026 versus JPY 4,489 million in FY2/2025;支持证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million;支持证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million
完整研究记录(核对用)
研究原文:The receivables-heavy, asset-light working-capital structure explains why annual operating cash flow swings between JPY 4.5bn and JPY 48bn on similar profit.
内部研究类型:EXPLAINS
内部来源标记:COVERAGE35
F052|08|资本政策是连接盈利和估值的唯一一座桥
研究范围:开放研究+35项覆盖检查
写入正文:08|资本政策是连接盈利和估值的唯一一座桥09|市场为盈利付了全价,却不为净资产付价
归并到:F062
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:直接 / 支持;同业比较:05;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接证据;反向验证:31;同业比较:13、22;其他用途:历史
Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026怎么使用:支持证据;反向验证:28
GIC 25 lookback: GIC 30 positioned as the successor plan怎么使用:支持证据;反向验证:07、23;专项深挖:35;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);直接证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);支持证据 / 反证(研究域28)|Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026;支持证据 / 历史/同业比较(研究域30) / 反证(研究域07) / 反证(研究域23) / 定向深挖(研究域35)|GIC 25 lookback: GIC 30 positioned as the successor plan
完整研究记录(核对用)
研究原文:GIC 30 commits to earnings growth but, in the materials read, carries no capital-efficiency or payout commitment.
内部研究类型:LEAVES_UNRESOLVED
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F053|08|GIC 30承诺的是盈利增长,没有承诺资本效率
研究范围:开放研究+35项覆盖检查
写入正文:08|GIC 30承诺的是盈利增长,没有承诺资本效率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Fact Book 2026: overseas ratio and destination mix, FY2/2026怎么使用:直接 / 支持;外部现实校验:11、14;反向验证:32
Destination detail: China sales shrinking, Asia ex-China and the West growing怎么使用:直接 / 支持;一手验证:11、14;专项深挖:11
Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026怎么使用:直接 / 支持;反向验证:28
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:支持证据;同业比较:05;其他用途:历史
GIC 25 lookback: GIC 30 positioned as the successor plan怎么使用:支持证据;反向验证:07、23;专项深挖:35;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域11) / 外部现实(研究域14) / 反证(研究域32)|Fact Book 2026: overseas ratio and destination mix, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域14) / 定向深挖(研究域11)|Destination detail: China sales shrinking, Asia ex-China and the West growing;直接证据 / 支持证据 / 反证(研究域28)|Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026;支持证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);支持证据 / 历史/同业比较(研究域30) / 反证(研究域07) / 反证(研究域23) / 定向深挖(研究域35)|GIC 25 lookback: GIC 30 positioned as the successor plan
完整研究记录(核对用)
研究原文:The FY2/2031 net-income target depends on overseas growth at near-group margin, with China shrinking in the mix.
内部研究类型:CARRIES_PLAN_DELIVERY
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F054|12|同一个稳定股东结构,既托住了价格台阶,也压住了净资产估值
研究范围:35项覆盖检查
写入正文:12|同一个稳定股东结构,既托住了价格台阶,也压住了净资产估值
归并到:F061
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Two splits in two years: 1-for-2 in September 2024 and again in June 2026怎么使用:直接 / 支持;外部现实校验:25;反向验证:30、33;专项深挖:25
Shareholder benefits: rice and book cards (per the H1 FY2/2027 materials)怎么使用:直接 / 支持;专项深挖:32;同业比较:26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域25) / 反证(研究域30) / 反证(研究域33) / 定向深挖(研究域25)|Two splits in two years: 1-for-2 in September 2024 and again in June 2026;直接证据 / 支持证据 / 历史/同业比较(研究域26) / 定向深挖(研究域32)|Shareholder benefits: rice and book cards (per the H1 FY2/2027 materials)
完整研究记录(核对用)
研究原文:Splits and shareholder benefits may widen the holder base and slowly narrow the venue discount without a policy change; effect unproven.
内部研究类型:MAY_SLOWLY_NARROW
内部来源标记:COVERAGE35
F055|09|正常化盈利:普通利润420亿至460亿日元,以税前口径计
研究范围:35项覆盖检查+开放研究
写入正文:09|正常化盈利:普通利润420亿至460亿日元,以税前口径计
归并到:F064
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接 / 支持;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:历史
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接 / 支持;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:支持证据;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:支持证据;同业比较:27、28;其他用途:历史
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:支持证据;一手验证:27
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:支持证据;反向验证:24;同业比较:25;其他用途:历史
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:支持证据;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
Dated post-split closes, October 2026: JPY 5,000 at the 23 October close怎么使用:支持证据;一手验证:31;反向验证:27;同业比较:34;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x;支持证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;支持证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);支持证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million;支持证据 / 一手证据(研究域31) / 历史/同业比较(研究域34) / 反证(研究域27)|Dated post-split closes, October 2026: JPY 5,000 at the 23 October close
完整研究记录(核对用)
研究原文:The normalised ordinary-profit band is the earnings base against which the point-in-time multiples are judged, with basis (pre-tax vs net) kept distinct.
内部研究类型:ANCHORS
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
F056|09|持有证券的市值没有取得,不能在估值里按全价计入
研究范围:35项覆盖检查
写入正文:09|持有证券的市值没有取得,不能在估值里按全价计入13|持有证券最终怎么处理,值多少钱
归并到:F034
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接证据;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years
完整研究记录(核对用)
研究原文:Absent the portfolio's market value and tax basis, hidden-asset value cannot responsibly be capitalised.
内部研究类型:LIMITS_VALUATION_OF
内部来源标记:COVERAGE35
F057|01|什么会推翻这个判断:三个基本面数字和一个反向条件
研究范围:35项覆盖检查
写入正文:01|什么会推翻这个判断:三个基本面数字和一个反向条件11|什么会推翻这个判断:两半判断各有各的检验
归并到:F063
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接证据;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:历史
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接 / 支持;一手验证:02、03;外部现实校验:09
Fact Book 2026: dividend record and payout discipline怎么使用:直接证据;反向验证:22;同业比较:31;其他用途:历史
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:支持证据;一手验证:15、32;同业比较:02、11;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:支持证据;反向验证:31;同业比较:13、22;其他用途:历史
Fact Book 2026: overseas ratio and destination mix, FY2/2026怎么使用:支持证据;外部现实校验:11、14;反向验证:32
Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent怎么使用:支持证据;外部现实校验:15;专项深挖:15
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:支持证据;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:支持证据;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026;直接证据 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;支持证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based);支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);支持证据 / 外部现实(研究域11) / 外部现实(研究域14) / 反证(研究域32)|Fact Book 2026: overseas ratio and destination mix, FY2/2026;支持证据 / 外部现实(研究域15) / 定向深挖(研究域15)|Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent;支持证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x
完整研究记录(核对用)
研究原文:Dated numeric falsifiers define what would disconfirm the two-layer compounding thesis from either side.
内部研究类型:TESTS
内部来源标记:COVERAGE35
F058|09|价格已回到高位区,盈利是否已被部分预付
研究范围:开放研究
写入正文:09|价格已回到高位区,盈利是否已被部分预付10|价格台阶与盈利台阶在财年尺度上同步,价格是否已预付中期计划仍未知
归并到:F033
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Fiscal-year price ranges FY2/2018-FY2/2026 (Fact Book stock indicators, pre-June-2026-split basis)怎么使用:直接证据;一手验证:34
Frozen Muse Market chart reading, steel selection pass (9 November 2026), over the TradingView Nagoya monthly chart怎么使用:直接证据;外部现实校验:31、34;反向验证:35
Dated post-split closes, October 2026: JPY 5,000 at the 23 October close怎么使用:直接证据;一手验证:31;反向验证:27;同业比较:34;其他用途:历史
TradingView price snapshot: JPY 5,020 (late October 2026)怎么使用:直接证据;反向验证:34
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域34)|Fiscal-year price ranges FY2/2018-FY2/2026 (Fact Book stock indicators, pre-June-2026-split basis);直接证据 / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域35)|Frozen Muse Market chart reading, steel selection pass (9 November 2026), over the TradingView Nagoya monthly chart;直接证据 / 一手证据(研究域31) / 历史/同业比较(研究域34) / 反证(研究域27)|Dated post-split closes, October 2026: JPY 5,000 at the 23 October close;直接证据 / 反证(研究域34)|TradingView price snapshot: JPY 5,020 (late October 2026)
完整研究记录(核对用)
研究原文:The cross-lane timing view references the protected Technical Synthesis as a whole; it adds a separate cross-lane meaning and does not flatten, redefine or alter the independent Pure Technical Truth.
内部研究类型:REFERENCES_WHOLE_WITHOUT_REWRITING
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F059|02|357年的老字号,抗得住单一冲击,最脆弱的是电子这一环
研究范围:开放研究+35项覆盖检查
写入正文:02|357年的老字号,抗得住单一冲击,最脆弱的是电子这一环05|护城河是流通网络和授信能力,不是技术或切换成本14|商业、竞争优势和估值:商业结构7.48/11,竞争优势8.68/14,估值11.25/15
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(40项,重复标签已合并)
Legal identity and parent-company results from the FY2/2026 securities report (G-Biz Info, EDINET-derived)怎么使用:直接 / 支持;一手验证:01
FY2/2024 interim tanshin: filing header and interim results怎么使用:直接 / 支持;一手验证:01
Founding in 1669 and the 350-year continuity怎么使用:直接证据;一手验证:33;专项深挖:33;同业比较:01;其他用途:历史
Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas怎么使用:直接 / 支持;一手验证:02、07;专项深挖:07;同业比较:20;其他用途:历史
Employees: consolidated 6,536, parent 773 - the group is the company怎么使用:直接 / 支持;专项深挖:02
Parent versus group: parent operating profit JPY 16,541 million of the group's JPY 40,457 million怎么使用:直接 / 支持;反向验证:08、20;同业比较:04;其他用途:历史
Fact Book 2026: parent-company segment mix怎么使用:直接证据;一手验证:26;同业比较:35;其他用途:历史
Iron & Steel segment: FY2/2026 sales JPY 377,823 million, operating profit JPY 11,016 million怎么使用:直接 / 支持;一手验证:08;反向验证:03、05、15;专项深挖:08;同业比较:06、10;其他用途:历史
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:直接证据;同业比较:05;其他用途:历史
End markets: automotive first, then construction and industrial machinery怎么使用:直接证据;一手验证:05、10;专项深挖:05;同业比较:08、09;其他用途:历史
Electronics book content: semiconductors, components, substrates, software怎么使用:直接 / 支持;一手验证:04;外部现实校验:03;专项深挖:04
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接 / 支持;一手验证:02、03;外部现实校验:09
Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million怎么使用:直接 / 支持;一手验证:03;外部现实校验:35;反向验证:04、06、09、10、14;专项深挖:03;同业比较:33;其他用途:历史
Industrial Materials segment: FY2/2026 sales JPY 321,930 million, operating profit JPY 11,071 million怎么使用:直接 / 支持;专项深挖:09
Living-Related Products segment: FY2/2026 sales JPY 85,671 million, operating profit JPY 3,776 million怎么使用:直接 / 支持;专项深挖:10
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:直接 / 支持;一手验证:15、32;同业比较:02、11;其他用途:历史
Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent怎么使用:直接证据;外部现实校验:15;专项深挖:15
Margin stack FY2/2026: gross 9.2 percent, operating 3.5 percent, ordinary 3.9 percent怎么使用:直接证据;一手验证:16;专项深挖:16
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接 / 支持;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:反证、历史
H1 FY2/2026 gross-profit surge: +20.7 percent in the first half怎么使用:直接证据;反向验证:12;专项深挖:14
Fact Book 2026: financial income detail - the second earnings engine怎么使用:直接 / 支持;外部现实校验:16、21
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接证据;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Equity-method income JPY 805 million across 22 affiliates怎么使用:直接证据;反向验证:16
Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months怎么使用:直接 / 支持;一手验证:19;外部现实校验:10、29;专项深挖:19;同业比较:15、17;其他用途:历史
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:直接 / 支持;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
Cash conversion: operating cash flow JPY 47,999 million in FY2/2026 versus JPY 4,489 million in FY2/2025怎么使用:直接 / 支持;一手验证:17;外部现实校验:19、20;专项深挖:17;同业比较:32;其他用途:历史
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接 / 支持;一手验证:25;反向验证:18;专项深挖:18
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接 / 支持;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:直接 / 支持;一手验证:29;外部现实校验:18、22;专项深挖:22
Ratings path: JCR raised to A+, R&I at A怎么使用:直接 / 支持;一手验证:13;外部现实校验:07;专项深挖:13;同业比较:18;其他用途:历史
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接证据;一手验证:22
Top-ten shareholders at the FY2/2026 securities report (G-Biz Info, EDINET-derived)怎么使用:直接 / 支持;一手验证:24;外部现实校验:06
Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent怎么使用:直接证据;外部现实校验:23、24;反向验证:13、21;专项深挖:24
Bank and insurer bloc in the top ten怎么使用:直接证据;专项深挖:29;同业比较:07、23、24;其他用途:历史
Business-partner holders: Nippon Steel 4.51 percent, Okuma 1.69 percent, employee plan 1.65 percent怎么使用:直接证据;一手验证:06;外部现实校验:05;专项深挖:06
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接证据;反向验证:24;同业比较:25;其他用途:历史
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:支持证据;一手验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|Legal identity and parent-company results from the FY2/2026 securities report (G-Biz Info, EDINET-derived);直接证据 / 支持证据 / 一手证据(研究域01)|FY2/2024 interim tanshin: filing header and interim results;直接证据 / 定向深挖(研究域01)|Registered identity detail: EDINET E02553, corporate number, head office;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 定向深挖(研究域33)|Founding in 1669 and the 350-year continuity;直接证据|Fact Book 2026: group scale, employees and credit ratings;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域07) / 历史/同业比较(研究域20) / 定向深挖(研究域07)|Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas;直接证据 / 支持证据 / 定向深挖(研究域02)|Employees: consolidated 6,536, parent 773 - the group is the company;直接证据 / 支持证据 / 历史/同业比较(研究域04) / 反证(研究域08) / 反证(研究域20)|Parent versus group: parent operating profit JPY 16,541 million of the group's JPY 40,457 million;直接证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|Fact Book 2026: parent-company segment mix;直接证据 / 支持证据 / 一手证据(研究域08) / 历史/同业比较(研究域06) / 历史/同业比较(研究域10) / 反证(研究域03) / 反证(研究域05) / 反证(研究域15) / 定向深挖(研究域08)|Iron & Steel segment: FY2/2026 sales JPY 377,823 million, operating profit JPY 11,016 million;直接证据|Fact Book 2026: FY2/2026 consolidated results highlights;直接证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 定向深挖(研究域05)|End markets: automotive first, then construction and industrial machinery;直接证据 / 支持证据 / 一手证据(研究域04) / 外部现实(研究域03) / 定向深挖(研究域04)|Electronics book content: semiconductors, components, substrates, software;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域35) / 历史/同业比较(研究域33) / 反证(研究域04) / 反证(研究域06) / 反证(研究域09) / 反证(研究域10) / 反证(研究域14) / 定向深挖(研究域03)|Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million;直接证据 / 支持证据 / 定向深挖(研究域09)|Industrial Materials segment: FY2/2026 sales JPY 321,930 million, operating profit JPY 11,071 million;直接证据 / 支持证据 / 定向深挖(研究域10)|Living-Related Products segment: FY2/2026 sales JPY 85,671 million, operating profit JPY 3,776 million;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based);直接证据 / 外部现实(研究域15) / 定向深挖(研究域15)|Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Margin stack FY2/2026: gross 9.2 percent, operating 3.5 percent, ordinary 3.9 percent;直接证据 / 支持证据 / 反证 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 反证(研究域12) / 定向深挖(研究域14)|H1 FY2/2026 gross-profit surge: +20.7 percent in the first half;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域21)|Fact Book 2026: financial income detail - the second earnings engine;直接证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 反证(研究域16)|Equity-method income JPY 805 million across 22 affiliates;直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域10) / 外部现实(研究域29) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 定向深挖(研究域19)|Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months;直接证据 / 支持证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million;直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域19) / 外部现实(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域17)|Cash conversion: operating cash flow JPY 47,999 million in FY2/2026 versus JPY 4,489 million in FY2/2025;直接证据 / 支持证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million;直接证据 / 支持证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域07) / 历史/同业比较(研究域18) / 定向深挖(研究域13)|Ratings path: JCR raised to A+, R&I at A;直接证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域06)|Top-ten shareholders at the FY2/2026 securities report (G-Biz Info, EDINET-derived);直接证据 / 外部现实(研究域23) / 外部现实(研究域24) / 反证(研究域13) / 反证(研究域21) / 定向深挖(研究域24)|Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent;直接证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域29)|Bank and insurer bloc in the top ten;直接证据 / 一手证据(研究域06) / 外部现实(研究域05) / 定向深挖(研究域06)|Business-partner holders: Nippon Steel 4.51 percent, Okuma 1.69 percent, employee plan 1.65 percent;直接证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026
完整研究记录(核对用)
研究原文:Durable business portrait: a diversified flow-trading network with a thick balance sheet and a second dividend engine|Structural durability is high and multiply sourced: four segments with different cycles, a network of 100 group companies in 23 countries, inventory discipline (1.5 months) that turns steel-price shocks into margin events rather than balance-sheet events, a holdings dividend stream up eight years, and a balance sheet (49.6 percent equity, 0.3x net D/E, 14.4x coverage, A/A+ ratings) that keeps single-year shocks away from the equity. A founding-family anchor inside an aligned register of banks, supplier, customer and employees makes abrupt strategic change as unlikely as abrupt failure (357-year survival). Designated weak seam: electronics, now the growth and highest-margin book, is the most cyclical asset carried at this scale and has not been through a full device downturn at about 32 percent of sales. The structure survives any single documented stress; the compound scenario (device downturn plus domestic steel slump plus a cross-holding unwind forced at bad prices) has no precedent and no present trigger. Current changes (record year, interim revision, GIC 30) overlay this foundation rather than replace it.
内部研究类型:DURABLE_BUSINESS_PORTRAIT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Holders own an asset-light network whose adverse case is dead money rather than impairment; growth exposure is device-capex linked.
不确定性(原始记录):Rests on documented ten-year series and balance-sheet ratios; segment capital, receivables ageing and compound-stress behaviour are not observable.
F060|09|价格已回到高位区,盈利是否已被部分预付
研究范围:开放研究+35项覆盖检查
写入正文:09|价格已回到高位区,盈利是否已被部分预付10|价格台阶与盈利台阶在财年尺度上同步,价格是否已预付中期计划仍未知
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(20项,重复标签已合并)
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接 / 支持;一手验证:22
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接 / 支持;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:直接 / 支持;一手验证:15、32;同业比较:02、11;其他用途:历史
Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent怎么使用:直接证据;外部现实校验:15;专项深挖:15
Margin stack FY2/2026: gross 9.2 percent, operating 3.5 percent, ordinary 3.9 percent怎么使用:直接证据;一手验证:16;专项深挖:16
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接证据;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:历史
H1 FY2/2026 gross-profit surge: +20.7 percent in the first half怎么使用:直接证据;反向验证:12;专项深挖:14
Fiscal-year price ranges FY2/2018-FY2/2026 (Fact Book stock indicators, pre-June-2026-split basis)怎么使用:直接证据;一手验证:34
Frozen Muse Market chart reading, steel selection pass (9 November 2026), over the TradingView Nagoya monthly chart怎么使用:直接证据;外部现实校验:31、34;反向验证:35
Dated post-split closes, October 2026: JPY 5,000 at the 23 October close怎么使用:直接 / 支持;一手验证:31;反向验证:27;同业比较:34;其他用途:历史
TradingView price snapshot: JPY 5,020 (late October 2026)怎么使用:直接证据;反向验证:34
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:直接 / 支持;一手验证:27
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接 / 支持;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接 / 支持;反向验证:31;同业比较:13、22;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:反向验证:22;同业比较:31;其他用途:反证、历史
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接 / 支持;反向验证:24;同业比较:25;其他用途:历史
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:直接 / 支持;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
查看完整证据标签(核对用)
直接证据 / 支持证据|Fact Book 2026: FY2/2026 consolidated results highlights;直接证据|Fact Book 2026: FY2/2026 outcome versus the initial plan;直接证据 / 支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 支持证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based);直接证据 / 外部现实(研究域15) / 定向深挖(研究域15)|Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Margin stack FY2/2026: gross 9.2 percent, operating 3.5 percent, ordinary 3.9 percent;直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 反证(研究域12) / 定向深挖(研究域14)|H1 FY2/2026 gross-profit surge: +20.7 percent in the first half;直接证据 / 一手证据(研究域34)|Fiscal-year price ranges FY2/2018-FY2/2026 (Fact Book stock indicators, pre-June-2026-split basis);直接证据 / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域35)|Frozen Muse Market chart reading, steel selection pass (9 November 2026), over the TradingView Nagoya monthly chart;直接证据 / 支持证据 / 一手证据(研究域31) / 历史/同业比较(研究域34) / 反证(研究域27)|Dated post-split closes, October 2026: JPY 5,000 at the 23 October close;直接证据 / 反证(研究域34)|TradingView price snapshot: JPY 5,020 (late October 2026);直接证据 / 支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;直接证据 / 支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x;直接证据 / 支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);反证 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 支持证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);直接证据 / 支持证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million
完整研究记录(核对用)
研究原文:Earnings staircase and price staircase move together; the disagreement is about the register, not the business|The profit staircase (five consecutive ordinary-profit records, FY2/2022-FY2/2026) and the price staircase (shelf, FY2/2024 step, FY2/2025 retention, FY2/2026 high) are synchronised at fiscal grain, which is why the market grants earnings a full cyclical multiple yet gives the balance sheet no multiple at all. The disagreement is about the register, not the business. This is a cross-lane relationship and does not rewrite the protected Technical truth, whose confidence is LOW.
内部研究类型:CROSS_DOMAIN_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Earnings are already believed; re-rating requires the other half of the story.
不确定性(原始记录):Fiscal-grain synchrony only; no event-level response measured; Technical confidence LOW.
F061|12|同一个稳定股东结构,既托住了价格台阶,也压住了净资产估值
研究范围:开放研究+35项覆盖检查
写入正文:12|同一个稳定股东结构,既托住了价格台阶,也压住了净资产估值
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(20项,重复标签已合并)
Top-ten shareholders at the FY2/2026 securities report (G-Biz Info, EDINET-derived)怎么使用:直接 / 支持;一手验证:24;外部现实校验:06
FY2/2024 interim tanshin: filing header and interim results怎么使用:直接 / 支持;一手验证:01
Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent怎么使用:直接证据;外部现实校验:23、24;反向验证:13、21;专项深挖:24
Bank and insurer bloc in the top ten怎么使用:直接证据;专项深挖:29;同业比较:07、23、24;其他用途:历史
Business-partner holders: Nippon Steel 4.51 percent, Okuma 1.69 percent, employee plan 1.65 percent怎么使用:直接证据;一手验证:06;外部现实校验:05;专项深挖:06
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接 / 支持;反向验证:24;同业比较:25;其他用途:历史
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:直接 / 支持;一手验证:27
TradingView company profile: NAG:7485 Okaya & Co., Ltd.怎么使用:直接 / 支持;外部现实校验:01、13
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接 / 支持;反向验证:31;同业比较:13、22;其他用途:历史
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接 / 支持;一手验证:22
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接证据;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:直接证据;反向验证:22;同业比较:31;其他用途:反证、历史
Dividend policy text as published on the company's IR pages怎么使用:直接 / 支持;外部现实校验:26;专项深挖:26
FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million怎么使用:直接 / 支持;外部现实校验:30;反向验证:11、25、26;同业比较:12;其他用途:历史
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:直接证据;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
Fact Book 2026: parent-company segment mix怎么使用:支持证据;一手验证:26;同业比较:35;其他用途:历史
Two splits in two years: 1-for-2 in September 2024 and again in June 2026怎么使用:直接 / 支持;外部现实校验:25;反向验证:30、33;专项深挖:25
Shareholder benefits: rice and book cards (per the H1 FY2/2027 materials)怎么使用:直接 / 支持;专项深挖:32;同业比较:26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域06)|Top-ten shareholders at the FY2/2026 securities report (G-Biz Info, EDINET-derived);直接证据 / 支持证据 / 一手证据(研究域01)|FY2/2024 interim tanshin: filing header and interim results;直接证据 / 外部现实(研究域23) / 外部现实(研究域24) / 反证(研究域13) / 反证(研究域21) / 定向深挖(研究域24)|Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent;直接证据 / 历史/同业比较(研究域07) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域29)|Bank and insurer bloc in the top ten;直接证据 / 一手证据(研究域06) / 外部现实(研究域05) / 定向深挖(研究域06)|Business-partner holders: Nippon Steel 4.51 percent, Okuma 1.69 percent, employee plan 1.65 percent;直接证据 / 支持证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);直接证据 / 支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域13)|TradingView company profile: NAG:7485 Okaya & Co., Ltd.;直接证据 / 支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);直接证据 / 支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x;直接证据 / 反证 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;直接证据 / 支持证据 / 外部现实(研究域26) / 定向深挖(研究域26)|Dividend policy text as published on the company's IR pages;直接证据 / 支持证据 / 外部现实(研究域30) / 历史/同业比较(研究域12) / 反证(研究域11) / 反证(研究域25) / 反证(研究域26)|FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million;直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|Fact Book 2026: parent-company segment mix;直接证据 / 支持证据 / 外部现实(研究域25) / 反证(研究域30) / 反证(研究域33) / 定向深挖(研究域25)|Two splits in two years: 1-for-2 in September 2024 and again in June 2026;直接证据 / 支持证据 / 历史/同业比较(研究域26) / 定向深挖(研究域32)|Shareholder benefits: rice and book cards (per the H1 FY2/2027 materials);直接证据|Price-basis warning: two splits make unadjusted long charts misleading
完整研究记录(核对用)
研究原文:One stable register explains both the staircase and the discount|The same stable-holder structure (family about 17.6 percent, bank ring, mill and customer cross-holdings) that yields non-returning pullbacks on the chart and nine-year dividend permanence also yields the 0.38x PBR, because it removes every forcing event: no takeover surface, no index flow, no TSE disclosure regime, no activist-sized float. Splits and benefits are slow, partial substitutes for the missing pressure.
内部研究类型:CROSS_DOMAIN_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):The discount can persist indefinitely without a catalyst generated inside the house.
不确定性(原始记录):The chart half rests on the frozen low-confidence technical reading; the register half is documented.
F062|08|资本政策是连接盈利和估值的唯一一座桥
研究范围:开放研究+35项覆盖检查
写入正文:08|资本政策是连接盈利和估值的唯一一座桥09|市场为盈利付了全价,却不为净资产付价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(23项,重复标签已合并)
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接 / 支持;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接 / 支持;一手验证:25;反向验证:18;专项深挖:18
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:直接 / 支持;一手验证:29;外部现实校验:18、22;专项深挖:22
Ratings path: JCR raised to A+, R&I at A怎么使用:直接 / 支持;一手验证:13;外部现实校验:07;专项深挖:13;同业比较:18;其他用途:历史
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接 / 支持;一手验证:22
Fact Book 2026: financial income detail - the second earnings engine怎么使用:直接 / 支持;外部现实校验:16、21
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接 / 支持;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Equity-method income JPY 805 million across 22 affiliates怎么使用:直接证据;反向验证:16
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:直接 / 支持;一手验证:27
Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent怎么使用:直接 / 支持;外部现实校验:23、24;反向验证:13、21;专项深挖:24
Fact Book 2026: dividend record and payout discipline怎么使用:直接 / 支持;反向验证:22;同业比较:31;其他用途:反证、历史
Dividend policy text as published on the company's IR pages怎么使用:直接 / 支持;外部现实校验:26;专项深挖:26
FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million怎么使用:直接 / 支持;外部现实校验:30;反向验证:11、25、26;同业比较:12;其他用途:历史
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:直接证据;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
Fact Book 2026: parent-company segment mix怎么使用:支持证据;一手验证:26;同业比较:35;其他用途:历史
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:直接 / 支持;同业比较:05;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接 / 支持;反向验证:31;同业比较:13、22;其他用途:反证、历史
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接 / 支持;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026怎么使用:直接 / 支持;反向验证:28
GIC 25 lookback: GIC 30 positioned as the successor plan怎么使用:直接 / 支持;反向验证:07、23;专项深挖:35;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域07) / 历史/同业比较(研究域18) / 定向深挖(研究域13)|Ratings path: JCR raised to A+, R&I at A;直接证据 / 支持证据|Fact Book 2026: group scale, employees and credit ratings;直接证据 / 支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域21)|Fact Book 2026: financial income detail - the second earnings engine;直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 反证(研究域16)|Equity-method income JPY 805 million across 22 affiliates;直接证据 / 支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;直接证据 / 支持证据 / 外部现实(研究域23) / 外部现实(研究域24) / 反证(研究域13) / 反证(研究域21) / 定向深挖(研究域24)|Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent;直接证据 / 支持证据 / 反证 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;直接证据 / 支持证据 / 外部现实(研究域26) / 定向深挖(研究域26)|Dividend policy text as published on the company's IR pages;直接证据 / 支持证据 / 外部现实(研究域30) / 历史/同业比较(研究域12) / 反证(研究域11) / 反证(研究域25) / 反证(研究域26)|FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million;直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|Fact Book 2026: parent-company segment mix;直接证据 / 支持证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);直接证据 / 支持证据 / 反证 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);直接证据 / 支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x;直接证据|Fact Book 2026: FY2/2026 consolidated results highlights;直接证据 / 支持证据 / 反证(研究域28)|Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026;直接证据 / 支持证据 / 历史/同业比较(研究域30) / 反证(研究域07) / 反证(研究域23) / 定向深挖(研究域35)|GIC 25 lookback: GIC 30 positioned as the successor plan
完整研究记录(核对用)
研究原文:Capital policy is the only bridge between the earnings half and the valuation half|The balance sheet (49.6 percent equity, 0.3x net D/E, a holdings dividend stream worth about a fifth of gross ordinary profit) already contains everything a re-rating would need. GIC 30 is an earnings plan with no published capital commitments in the materials read and deliberately does not cross the bridge yet. Q3 and March 2027 are verification venues for earnings; only a policy notice would verify the other half. Cross-holding reform is itself two-sided, and part of book value is valuation-driven.
内部研究类型:CROSS_DOMAIN_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Upside is convex to a policy event and linear to earnings; absent policy, the outcome is governance time.
不确定性(原始记录):Holdings market value, tax leakage and board intent are unknown.
F063|01|什么会推翻这个判断:三个基本面数字和一个反向条件
研究范围:35项覆盖检查+开放研究
写入正文:01|什么会推翻这个判断:三个基本面数字和一个反向条件11|什么会推翻这个判断:两半判断各有各的检验
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(19项,重复标签已合并)
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接 / 支持;一手验证:02、03;外部现实校验:09
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:直接 / 支持;一手验证:15、32;同业比较:02、11;其他用途:历史
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接 / 支持;反向验证:31;同业比较:13、22;其他用途:历史
Fact Book 2026: overseas ratio and destination mix, FY2/2026怎么使用:直接 / 支持;外部现实校验:11、14;反向验证:32
Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent怎么使用:直接 / 支持;外部现实校验:15;专项深挖:15
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接 / 支持;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接 / 支持;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接 / 支持;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:直接证据;反向验证:22;同业比较:31;其他用途:历史
Next print calendar: Q3 FY2/2027 results expected late December 2026 (vendor estimate)怎么使用:直接 / 支持;一手验证:30;专项深挖:30
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million怎么使用:直接 / 支持;外部现实校验:30;反向验证:11、25、26;同业比较:12;其他用途:历史
GIC 25 lookback: GIC 30 positioned as the successor plan怎么使用:直接 / 支持;反向验证:07、23;专项深挖:35;同业比较:30;其他用途:历史
Guidance conservatism, two cycles documented怎么使用:直接 / 支持;外部现实校验:12;专项深挖:28、31
H1 FY2/2026 gross-profit surge: +20.7 percent in the first half怎么使用:支持证据;反向验证:12;专项深挖:14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based);直接证据 / 支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);直接证据 / 支持证据 / 外部现实(研究域11) / 外部现实(研究域14) / 反证(研究域32)|Fact Book 2026: overseas ratio and destination mix, FY2/2026;直接证据 / 支持证据 / 外部现实(研究域15) / 定向深挖(研究域15)|Gross margin expanded for nine years: 6.7-7.0 percent to 9.2 percent;直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;直接证据 / 支持证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Next print calendar: Q3 FY2/2027 results expected late December 2026 (vendor estimate);直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 支持证据 / 外部现实(研究域30) / 历史/同业比较(研究域12) / 反证(研究域11) / 反证(研究域25) / 反证(研究域26)|FY2/2027 initial plan (March 2026): sales JPY 1,150,000 million, operating profit JPY 35,000 million;直接证据 / 支持证据 / 历史/同业比较(研究域30) / 反证(研究域07) / 反证(研究域23) / 定向深挖(研究域35)|GIC 25 lookback: GIC 30 positioned as the successor plan;支持证据|FY2/2026 interim results briefing materials (30 September 2025);直接证据 / 支持证据|FY2/2025 consolidated results (tanshin) and FY2/2026 initial guidance;直接证据 / 支持证据|Fact Book 2026: FY2/2026 outcome versus the initial plan;直接证据 / 支持证据 / 外部现实(研究域12) / 定向深挖(研究域28) / 定向深挖(研究域31)|Guidance conservatism, two cycles documented;直接证据|FY2/2025 results briefing materials (31 March 2025);支持证据 / 反证(研究域12) / 定向深挖(研究域14)|H1 FY2/2026 gross-profit surge: +20.7 percent in the first half
完整研究记录(核对用)
研究原文:Two-layer compounding thesis with asymmetric falsifiers|Durable operating and holdings compounding trapped at a venue-and-policy discount; fundamental falsifiers (profit below JPY 35,850m, electronics profit halving, dividend cut) are slow, the reverse falsifier (buyback without earnings) tests the trapped half, and a price-structure falsifier is owned by the protected Technical lane.
内部研究类型:THESIS_AND_FALSIFICATION
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Exit discipline is pre-written; policy disappointment alone is the entry premise, not an exit.
不确定性(原始记录):Falsification levels are review judgements.
F064|09|正常化盈利:普通利润420亿至460亿日元,以税前口径计
研究范围:35项覆盖检查+开放研究
写入正文:09|正常化盈利:普通利润420亿至460亿日元,以税前口径计
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(17项,重复标签已合并)
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接 / 支持;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:历史
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接 / 支持;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接 / 支持;同业比较:27、28;其他用途:历史
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:直接证据;一手验证:15、32;同业比较:02、11;其他用途:历史
Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026怎么使用:直接 / 支持;一手验证:27
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接 / 支持;反向验证:24;同业比较:25;其他用途:历史
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:直接 / 支持;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x怎么使用:直接 / 支持;外部现实校验:27;反向验证:29;专项深挖:27、34;同业比较:21;其他用途:历史
Dated post-split closes, October 2026: JPY 5,000 at the 23 October close怎么使用:直接 / 支持;一手验证:31;反向验证:27;同业比较:34;其他用途:历史
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接 / 支持;一手验证:22
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接 / 支持;反向验证:31;同业比较:13、22;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:反向验证:22;同业比较:31;其他用途:反证、历史
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:直接 / 支持;一手验证:29;外部现实校验:18、22;专项深挖:22
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接证据;一手验证:25;反向验证:18;专项深挖:18
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接证据;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Fact Book 2026: financial income detail - the second earnings engine怎么使用:直接证据;外部现实校验:16、21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based);直接证据 / 支持证据 / 一手证据(研究域27)|Fact Book 2026: per-share and market indicators, FY2/2018-FY2/2026;直接证据 / 支持证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);直接证据 / 支持证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million;直接证据 / 支持证据 / 外部现实(研究域27) / 历史/同业比较(研究域21) / 反证(研究域29) / 定向深挖(研究域27) / 定向深挖(研究域34)|Market pricing at the FY2/2026 close: capitalisation JPY 191,873 million, PER 6.2x, PBR 0.38x;直接证据 / 支持证据 / 一手证据(研究域31) / 历史/同业比较(研究域34) / 反证(研究域27)|Dated post-split closes, October 2026: JPY 5,000 at the 23 October close;直接证据 / 支持证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 支持证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);反证 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent;直接证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million;直接证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;直接证据|Fact Book 2026: FY2/2026 consolidated results highlights;直接证据 / 外部现实(研究域16) / 外部现实(研究域21)|Fact Book 2026: financial income detail - the second earnings engine
完整研究记录(核对用)
研究原文:Normalised earnings to price: what 0.38x book and 5.8x PER imply|The market pays about 5.8x forward earnings and 0.38x book; normalised ordinary profit of roughly JPY 42-46bn (pre-tax) makes the price cheap if the band holds. The discount reads as a capital-policy and venue artefact, qualified by the valuation-driven component of equity and an unmarked holdings portfolio that must not be double-counted.
内部研究类型:VALUATION_BRIDGE
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Value is real but access to it depends on policy and on realisable holdings value.
不确定性(原始记录):Mixed-period basis, pre-tax versus net-income basis and secondary forecast source limit precision.
F065|09|下行保护来自结构,不只来自低价
研究范围:35项覆盖检查
写入正文:09|下行保护来自结构,不只来自低价11|电子是增长引擎,也是最大的回撤敞口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(16项,重复标签已合并)
Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months怎么使用:直接 / 支持;一手验证:19;外部现实校验:10、29;专项深挖:19;同业比较:15、17;其他用途:历史
Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent怎么使用:直接 / 支持;一手验证:29;外部现实校验:18、22;专项深挖:22
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:直接 / 支持;一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:反证、历史
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接 / 支持;一手验证:25;反向验证:18;专项深挖:18
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接 / 支持;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Ratings path: JCR raised to A+, R&I at A怎么使用:直接 / 支持;一手验证:13;外部现实校验:07;专项深挖:13;同业比较:18;其他用途:历史
FY2/2026 key ratios compiled from the securities report (EDINET DB)怎么使用:直接证据;一手验证:22
Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million怎么使用:直接 / 支持;一手验证:20;外部现实校验:04;反向验证:02、17、19;专项深挖:20
Cash conversion: operating cash flow JPY 47,999 million in FY2/2026 versus JPY 4,489 million in FY2/2025怎么使用:直接 / 支持;一手验证:17;外部现实校验:19、20;专项深挖:17;同业比较:32;其他用途:历史
Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million怎么使用:直接 / 支持;一手验证:03;外部现实校验:35;反向验证:04、06、09、10、14;专项深挖:03;同业比较:33;其他用途:历史
Electronics book content: semiconductors, components, substrates, software怎么使用:直接 / 支持;一手验证:04;外部现实校验:03;专项深挖:04
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接证据;一手验证:02、03;外部现实校验:09
Fact Book 2026: overseas ratio and destination mix, FY2/2026怎么使用:直接 / 支持;外部现实校验:11、14;反向验证:32
Destination detail: China sales shrinking, Asia ex-China and the West growing怎么使用:直接 / 支持;一手验证:11、14;专项深挖:11
Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas怎么使用:直接证据;一手验证:02、07;专项深挖:07;同业比较:20;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域10) / 外部现实(研究域29) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 定向深挖(研究域19)|Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months;直接证据 / 支持证据 / 一手证据(研究域29) / 外部现实(研究域18) / 外部现实(研究域22) / 定向深挖(研究域22)|Safety ratios: net debt/equity 0.3x, interest coverage 14.4x, current ratio 154.0 percent;直接证据 / 支持证据 / 反证 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);直接证据 / 支持证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million;直接证据 / 支持证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域07) / 历史/同业比较(研究域18) / 定向深挖(研究域13)|Ratings path: JCR raised to A+, R&I at A;直接证据|Fact Book 2026: group scale, employees and credit ratings;直接证据 / 一手证据(研究域22)|FY2/2026 key ratios compiled from the securities report (EDINET DB);直接证据 / 支持证据 / 一手证据(研究域20) / 外部现实(研究域04) / 反证(研究域02) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域20)|Cost structure: SG&A JPY 65,466 million, depreciation JPY 6,427 million;直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域19) / 外部现实(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域17)|Cash conversion: operating cash flow JPY 47,999 million in FY2/2026 versus JPY 4,489 million in FY2/2025;直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域35) / 历史/同业比较(研究域33) / 反证(研究域04) / 反证(研究域06) / 反证(研究域09) / 反证(研究域10) / 反证(研究域14) / 定向深挖(研究域03)|Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million;直接证据 / 支持证据 / 一手证据(研究域04) / 外部现实(研究域03) / 定向深挖(研究域04)|Electronics book content: semiconductors, components, substrates, software;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026;直接证据 / 支持证据 / 外部现实(研究域11) / 外部现实(研究域14) / 反证(研究域32)|Fact Book 2026: overseas ratio and destination mix, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域14) / 定向深挖(研究域11)|Destination detail: China sales shrinking, Asia ex-China and the West growing;直接证据 / 一手证据(研究域02) / 一手证据(研究域07) / 历史/同业比较(研究域20) / 定向深挖(研究域07)|Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas
完整研究记录(核对用)
研究原文:Downside layers and the electronics seam|Four layers of protection (balance sheet, inventory discipline, segment and geographic spread, documented downturn floor) plus a low price; the weak seam is electronics beta and the pre-mix stress sample, with losses most plausibly arriving through receivables rather than financing.
内部研究类型:DOWNSIDE_AND_SELF_REPAIR
内部来源标记:COVERAGE35
普通股东含义(原始记录):Capital impairment is remote; dead money and a one-third to one-half earnings dip in a normal downturn are the realistic adverse cases.
不确定性(原始记录):No compound-stress precedent; intra-year working-capital peaks unobserved.
F066|13|最该先弄清的问题:董事会会不会把资本政策数值化
研究范围:开放研究+35项覆盖检查
写入正文:13|最该先弄清的问题:董事会会不会把资本政策数值化13|盈利的拆解:中期业绩里到底是谁在贡献
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(29项,重复标签已合并)
Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation)怎么使用:直接证据;同业比较:27、28;其他用途:历史
Next print calendar: Q3 FY2/2027 results expected late December 2026 (vendor estimate)怎么使用:直接证据;一手验证:30;专项深挖:30
New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release)怎么使用:直接 / 支持;同业比较:05;其他用途:历史
Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026怎么使用:直接 / 支持;反向验证:28
Reading of GIC 30's capital-efficiency content (secondary compilation)怎么使用:直接证据;反向验证:31;同业比较:13、22;其他用途:历史
Fact Book 2026: dividend record and payout discipline怎么使用:直接证据;反向验证:22;同业比较:31;其他用途:历史
Dividend policy text as published on the company's IR pages怎么使用:直接证据;外部现实校验:26;专项深挖:26
Iron & Steel segment: FY2/2026 sales JPY 377,823 million, operating profit JPY 11,016 million怎么使用:直接证据;一手验证:08;反向验证:03、05、15;专项深挖:08;同业比较:06、10;其他用途:历史
Fact Book 2026: parent-company segment mix怎么使用:直接证据;一手验证:26;同业比较:35;其他用途:历史
Fact Book 2026: segment sales and operating profit, FY2/2026怎么使用:直接证据;一手验证:02、03;外部现实校验:09
Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years怎么使用:直接 / 支持;一手验证:21;外部现实校验:28;专项深挖:21;同业比较:16;其他用途:历史
Fact Book 2026: financial income detail - the second earnings engine怎么使用:直接 / 支持;外部现实校验:16、21
Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million怎么使用:直接证据;一手验证:25;反向验证:18;专项深挖:18
Ten-year consolidated financial history (the-shashi, securities-report based)怎么使用:直接证据;一手验证:15、32;同业比较:02、11;其他用途:历史
Fact Book 2026: balance sheet and cash flow, FY2/2026怎么使用:直接证据;一手验证:18;外部现实校验:17、32;同业比较:03、19;其他用途:历史
Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months怎么使用:直接证据;一手验证:19;外部现实校验:10、29;专项深挖:19;同业比较:15、17;其他用途:历史
Margin stack FY2/2026: gross 9.2 percent, operating 3.5 percent, ordinary 3.9 percent怎么使用:直接证据;一手验证:16;专项深挖:16
Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent怎么使用:直接 / 支持;外部现实校验:23、24;反向验证:13、21;专项深挖:24
Director compensation FY2/2026: 16 internal directors, JPY 501 million total (EDINET DB)怎么使用:直接 / 支持;一手验证:23;专项深挖:23
TradingView company profile: NAG:7485 Okaya & Co., Ltd.怎么使用:直接 / 支持;外部现实校验:01、13
Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026)怎么使用:直接 / 支持;反向验证:24;同业比较:25;其他用途:历史
Fact Book 2026: overseas ratio and destination mix, FY2/2026怎么使用:直接 / 支持;外部现实校验:11、14;反向验证:32
Destination detail: China sales shrinking, Asia ex-China and the West growing怎么使用:直接 / 支持;一手验证:11、14;专项深挖:11
Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas怎么使用:直接证据;一手验证:02、07;专项深挖:07;同业比较:20;其他用途:历史
Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million怎么使用:直接 / 支持;一手验证:03;外部现实校验:35;反向验证:04、06、09、10、14;专项深挖:03;同业比较:33;其他用途:历史
Electronics book content: semiconductors, components, substrates, software怎么使用:直接 / 支持;一手验证:04;外部现实校验:03;专项深挖:04
Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026)怎么使用:一手验证:12、28、35;外部现实校验:33;专项深挖:12;同业比较:14、29;其他用途:反证、历史
GIC 25 lookback: GIC 30 positioned as the successor plan怎么使用:支持证据;反向验证:07、23;专项深挖:35;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域28)|Interim-stage FY2/2027 guidance as republished from the H1 FY2/2027 briefing materials (secondary compilation);直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|Next print calendar: Q3 FY2/2027 results expected late December 2026 (vendor estimate);直接证据 / 支持证据 / 历史/同业比较(研究域05)|New medium-term plan 'Global Innovation Change 2030 (GIC 30)' (English news release);直接证据 / 支持证据 / 反证(研究域28)|Nikkan Kogyo Shimbun: GIC 30 targets FY2/2031 net income of JPY 40 billion, +31 percent versus FY2/2026;直接证据 / 历史/同业比较(研究域13) / 历史/同业比较(研究域22) / 反证(研究域31)|Reading of GIC 30's capital-efficiency content (secondary compilation);直接证据 / 历史/同业比较(研究域31) / 反证(研究域22)|Fact Book 2026: dividend record and payout discipline;直接证据 / 外部现实(研究域26) / 定向深挖(研究域26)|Dividend policy text as published on the company's IR pages;直接证据 / 一手证据(研究域08) / 历史/同业比较(研究域06) / 历史/同业比较(研究域10) / 反证(研究域03) / 反证(研究域05) / 反证(研究域15) / 定向深挖(研究域08)|Iron & Steel segment: FY2/2026 sales JPY 377,823 million, operating profit JPY 11,016 million;直接证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|Fact Book 2026: parent-company segment mix;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 外部现实(研究域09)|Fact Book 2026: segment sales and operating profit, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域21) / 外部现实(研究域28) / 历史/同业比较(研究域16) / 定向深挖(研究域21)|Dividends received: JPY 8,350 million in FY2/2026, rising for eight consecutive years;直接证据 / 支持证据 / 外部现实(研究域16) / 外部现实(研究域21)|Fact Book 2026: financial income detail - the second earnings engine;直接证据 / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|Deleveraging inside growth: interest-bearing debt JPY 191,687 million to JPY 161,326 million;直接证据 / 一手证据(研究域15) / 一手证据(研究域32) / 历史/同业比较(研究域02) / 历史/同业比较(研究域11)|Ten-year consolidated financial history (the-shashi, securities-report based);直接证据 / 一手证据(研究域18) / 外部现实(研究域17) / 外部现实(研究域32) / 历史/同业比较(研究域03) / 历史/同业比较(研究域19)|Fact Book 2026: balance sheet and cash flow, FY2/2026;直接证据 / 一手证据(研究域19) / 外部现实(研究域10) / 外部现实(研究域29) / 历史/同业比较(研究域15) / 历史/同业比较(研究域17) / 定向深挖(研究域19)|Working-capital discipline: receivables 3.6 months, inventory 1.5 months, payables 1.8 months;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|Margin stack FY2/2026: gross 9.2 percent, operating 3.5 percent, ordinary 3.9 percent;直接证据 / 支持证据 / 外部现实(研究域23) / 外部现实(研究域24) / 反证(研究域13) / 反证(研究域21) / 定向深挖(研究域24)|Founding-family bloc: Okaya Fudosan 12.60 percent plus Atsukazu Okaya 5.01 percent;直接证据 / 支持证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Director compensation FY2/2026: 16 internal directors, JPY 501 million total (EDINET DB);直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域13)|TradingView company profile: NAG:7485 Okaya & Co., Ltd.;直接证据 / 支持证据 / 历史/同业比较(研究域25) / 反证(研究域24)|Share count and register scale: 19,440,000 shares issued, 5,422 shareholders (February 2026);直接证据 / 支持证据 / 外部现实(研究域11) / 外部现实(研究域14) / 反证(研究域32)|Fact Book 2026: overseas ratio and destination mix, FY2/2026;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域14) / 定向深挖(研究域11)|Destination detail: China sales shrinking, Asia ex-China and the West growing;直接证据 / 一手证据(研究域02) / 一手证据(研究域07) / 历史/同业比较(研究域20) / 定向深挖(研究域07)|Group footprint at H1 FY2/2026: 100 related companies, 48 domestic and 52 overseas;直接证据|Fact Book 2026: group scale, employees and credit ratings;直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域35) / 历史/同业比较(研究域33) / 反证(研究域04) / 反证(研究域06) / 反证(研究域09) / 反证(研究域10) / 反证(研究域14) / 定向深挖(研究域03)|Information & Electronics segment: FY2/2026 sales JPY 370,348 million, operating profit JPY 13,435 million;直接证据 / 支持证据 / 一手证据(研究域04) / 外部现实(研究域03) / 定向深挖(研究域04)|Electronics book content: semiconductors, components, substrates, software;反证 / 一手证据(研究域12) / 一手证据(研究域28) / 一手证据(研究域35) / 外部现实(研究域33) / 历史/同业比较(研究域14) / 历史/同业比较(研究域29) / 定向深挖(研究域12)|Ordinary profit record streak: JPY 18,298 million (FY2/2021) to JPY 45,485 million (FY2/2026);支持证据 / 历史/同业比较(研究域30) / 反证(研究域07) / 反证(研究域23) / 定向深挖(研究域35)|GIC 25 lookback: GIC 30 positioned as the successor plan
完整研究记录(核对用)
研究原文:High-value unresolved questions carried forward|Unresolved items ranked by consequence: capital-policy movement and capital-efficiency commitments; cross-holding end-state and holdings market value; segment drivers of the interim revision; GIC 30 numeric envelope; electronics margin through a device downturn; structural versus cyclical steel decline; China rotation; succession and listing path; special-item and segment-capital disclosure gaps. Next evidence: Q3 FY2/2027 print (about late December 2026), FY2/2027 results and tanshin notes (March 2027), securities report and governance report (May 2027).
内部研究类型:RESEARCH_DEBT_COLLECTION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):These determine whether the discount closes or persists and how robust the mix thesis is.
不确定性(原始记录):Mostly future disclosure; no further high-VOI public path is currently reasonable.
F067|10|月线数据缺口:技术结论只能建立在年度价格带和既有结构读数上
写入正文:10|月线数据缺口:技术结论只能建立在年度价格带和既有结构读数上10|十年阶梯:平台、台阶、守住的回调、新高10|价格重心沿台阶上移,回调一次比一次停得高10|当前状态:成熟保留阶段,下一步是验证,不是启动13|会计和披露:还缺哪些数字,以及谁来接班14|资本、治理和技术:资本配置3.50/10,治理3.15/7,技术结构8.45/13
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (dereference-only)
内部研究类型:PROTECTED_TECHNICAL_SYNTHESIS
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | f584bc51840860dba181e852b118ff80a52f8d64 |
| Delivery Commit SHA | f584bc51840860dba181e852b118ff80a52f8d64 |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | e864799c-1352-5339-b191-9a30847f6a10 |
| Canonical Revision | 1 |