公司主动压缩低毛利的分销销售,2025年3月期销售额下降13.0%,营业利润反而增长9.7%;毛利率由20.9%升到22.9%,2027年3月期上半年再升到23.5%。2026年3月期营业利润80.12亿日元,创历史纪录;经营现金流106.61亿日元,是净利润的1.8倍。资产负债表几乎没有负债,权益比率59.2%,净金融资产近140亿日元,分红比例稳定在40%上下。
9991
ジェコス株式会社(GECOSS Corporation)
ジェコス株式会社(GECOSS Corporation,东证Prime市场,代码9991)主营建筑用重型临时工程:租赁和销售临时钢材,承接临时工程的设计与施工,制造钢构件和桥梁;同时经营建设机械租赁,并在新加坡、越南设有小规模业务。公司自1968年起经营,1994年上市。2026年3月期(FY3/26)销售额1,156.80亿日元,重型临时工程约占九成。JFE集团合计持有39.49%表决权,公司是其权益法关联公司;Mizuho Lease持有20.04%。
最近亮点:2026年11月5日,公司公布2027年3月期(FY3/27)上半年(4–9月)业绩:销售额570.95亿日元(同比增长4.0%),营业利润41.90亿日元(增长12.3%),期内没有特别项目。同日上调全年指引:销售额1,180亿日元,营业利润92.00亿日元(增长14.8%),年度分红由69日元上调至75日元。 估值简报:股价1,755日元(2026年11月6日收盘)/总市值593.1亿日元/预测市盈率9.4倍(按公司修订后每股收益187.24日元,属公司指引口径)/实绩市净率0.83倍(按2026年3月期末每股净资产2,118.51日元;按2026年9月末账面为0.82倍)/净资产收益率8.5%(2026年3月期实绩;预测8.73%为数据商口径的推算值)/预测股息率4.27%(年度分红75日元)/EV/EBITDA 4.4倍(EV 501.9亿日元=总市值减净现金91.24亿日元,净现金为2026年9月末现金124.04亿日元减借款32.80亿日元;EBITDA 113.00亿日元=2026年3月期营业利润80.12亿日元加折旧32.88亿日元,为上一财年口径)。
利润几乎全部来自重型临时工程一个板块的定价纪律,该板块占分部毛利润的95%以上。修订后的指引要求下半年销售额基本持平(同比增长0.2%),营业利润却增长17.0%,营业利润率升到8.2%。公司没有披露订单余额,固定价格合同占比也不明,2026年3月期还首次出现3.14亿日元的订单亏损准备金。
结论:持有并继续观察,不追高。Kabugami评分68.05/100,评级B+(评分版本V3.2)。这是一次由定价纪律推动的利润率改造,结论取决于订单余额缺失、亏损准备金去向和海外利润不明这几项尚未查清的事实。 依据:营业利润持续创纪录,现金转化强,下行有净金融资产和稳定分红支撑;但市净率0.8倍的目标已提前达成,股价也站在历史高位区域,再往上要看净资产收益率的证据。 翻转条件:2027年1至2月的第三季度财报或5月的全年财报显示下半年营业利润率明显低于8.2%,订单亏损准备金扩大,资本回报方案停止推进,或大股东改变立场。 当前动作:持有并继续观察,不追高。基本面是在大股东稳定的结构内,由利润率改善推动的盈利兑现,下行有净金融资产和稳定分红支撑;但股价已经站上历史高位区域,0.8倍市净率目标也已提前达成,进一步重估要靠投入资本回报率的证据。2027年1至2月的第3季度决算和5月的全年决算与新年度指引,是决定论点成立与否的两次验证;若下半年营业利润率未达约8.2%、订单亏损准备金扩大,或资本回报方案不再推进,应重新评估;月收盘价跌破1,443日元也要重新评估。
报告目录
01|投资问题与当前结论
01.1|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上
ジェコス的核心问题是:一家主动缩小收入的公司,能否把更干净的产品组合持续变成营业利润,并让股东真正拿到回报。当前判断是可以,但条件很具体,也还没有完全验证。
故事从一个反常的事实开始。2025年3月期销售额下降13.0%,营业利润却增长9.7%,因为管理层把低毛利的分销销售从钢材收入的四成左右压到两成五左右。此后毛利率由20.9%升到22.9%,再升到2027年3月期上半年的23.5%。营业利润由68.51亿日元增至80.12亿日元,指引又上调到92.00亿日元。这条因果链的拆解见第6章。
这条利润线同时托着三件事:近乎无负债的资产负债表,40%上下的分红,以及市净率由不足0.5倍升到0.82倍。三者能否延续,取决于利润率这一个机制。公司利润的95%以上来自重型临时工程一个板块,所以论点实际上等于这个板块的定价纪律,监测要看分部数据,集团合计数字会滞后。
反证同样具体:人手紧张、建设成本高位;固定价格合同在成本落定前就已定价;2026年3月期出现首次订单亏损准备金3.14亿日元;海外业务利润无法拆分。股价结构的确认与失效条件放在第10章,这里不重复,也不据此改写价格结论。整体判断把握一般,主要因为没有订单余额可供检验。
01.2|下半年要交出8.2%的营业利润率,这是利润率承诺,不是需求承诺
把修订后的全年指引减去上半年实绩,下半年需要销售额609.05亿日元,同比只增长0.2%;营业利润50.10亿日元,增长17.0%;经常利润增长13.8%,净利润增长11.3%。隐含的营业利润率是8.2%,2026年3月期下半年为7.0%,2027年3月期上半年为7.3%。
季节性没有异常:上半年完成了修订后全年营业利润的45.5%,上年同期为46.6%。所以风险不在需求的时间分布,而在利润率能否再往上爬两个季度。公司没有披露订单余额,这个8.2%的误差范围无法从公开资料算出。
第一次检验是2027年1月下旬至2月初的第三季度财报(日期按往年规律预期)。
预收款项的增加(见第6章)可以佐证后续工作量,但不能替代订单数据。
01.3|两次业绩披露之间,论点怎样被确认
确认的标准有两条:2027年3月期营业利润达到或超过92.00亿日元;中期计划结束后的接替框架给出净资产收益率和股东回报的数值承诺。这种确认只是阶段性的,因为2028年3月期的产品组合和成本会重新提出同样的问题。
推翻的条件放在第11章,列出了具体信号和日期。检验窗口以2027年5月的全年财报为界。
有两项上行因素没有计入:租赁设备的利用率经济性和土地价值。海外业务的利润无法估算,同样没有计入。第一个失败信号会是什么,目前无法判断。
02|公司本质与商业模式
02.1|一家把租赁钢材和工程设计绑在一起的临时工程公司
ジェコス主营建筑现场用的重型临时工程,分四块:租赁和销售临时钢材,承接临时工程的设计与施工,制造钢构件和桥梁,以及租赁建设机械。总部在东京,财年到3月底,资本金43.98亿日元,EDINET代码E02782。
2026年3月期销售额1,156.80亿日元。分部口径下,重型临时工程销售额(含内部交易)1,036.43亿日元,建设机械147.65亿日元,合并调整为减2.86亿日元。重型临时工程内部分三个领域:临时钢材620.39亿日元(持平),临时工程施工300.39亿日元(增长17.6%),钢构及桥梁115.65亿日元(下降5.2%)。
运营资产的核心是租赁钢材,记在存货里:2026年3月末282.44亿日元,2026年9月末285.91亿日元,相当于全年销售额的24%。钢材买入后反复出租、维护,最后出售或报废。公司没有披露开工率、设备年龄和单吨经济性,这块资产的回报只能从分部利润推算。
在股权上,JFE Steel直接持有27.63%,JFE Holdings合计39.49%,公司是JFE集团的权益法关联公司,不是合并子公司,没有任何一方过半数。2026年2月公告了代表董事变更,本次研究只读到披露抬头,内容没有细读;Yoshiyuki Nobusa社长在整个期间任职不变。
02.2|利润集中在一个板块:重型临时工程占分部毛利润的95%以上
重型临时工程在2026年3月期贡献分部毛利润的95.7%,2027年3月期上半年为95.2%。按经常利润口径,前者分别为86.04亿日元和44.03亿日元,建设机械只有3.91亿日元和2.20亿日元。重型临时工程持有1,225.37亿日元总资产中的1,196.07亿日元。
公司的分散是领域上的分散(钢材、施工、钢构),分部上的分散并不存在。该板块的分部利润率由2025年3月期的6.6%升到2026年3月期的8.3%。
三点口径需要说明。分部利润按经常利润定义,分部利润率不等于营业利润率;上述占比是合并调整前的数字;材料领域内租赁与销售的比例没有进一步拆分。
建设机械2027年3月期上半年的利润改善,部分靠出售二手设备;海外业务的贡献没有披露。
02.3|耐久的部分是需求、设备和资产负债表,脆弱的部分是定价纪律和股东名册
把整家公司放在一起看:一批租赁钢材加一套工程设计能力,附在首都圈和公共部门的每一个建设项目上;96%左右的分部毛利润来自一个板块;权益比率59.2%,几乎没有有息负债;约40%的利润用于分红;金融资产约140亿日元。
耐久的有四项:临时工程的需求,设备的可得性和工程设计的参考业绩,资产负债表,以及已被观察到的管理层行为(为改善产品组合接受收入下降,分红按比例上调,以低于净资产的价格扩张)。
脆弱的有两项:利润集中在一个板块的定价纪律;两位大股东合计持有约60%表决权,名册在一次披露中就可能改变。具体的薄弱点包括:合同在成本落定前定价;机械设备回报偏低;海外业务利润不透明;少数股东权益在增长载体中占比上升。这些问题会先出现在分部披露、准备金、大股东公告和每股收益的滞后上,不会先出现在集团合计数字里。
这些判断依靠有日期的可观察机制(毛利率、分红比例、预收款项、大股东持股公告),不依靠对建设周期的预测。边界在于:没有披露开工率、订单余额、同业对比和分地区利润;对周期幅度的判断只来自一份八年的汇总业绩记录。
最近的变化(创纪录的营业利润、上调后的指引)叠加在这个基础上,不能替代这个基础。
02.4|新加坡与越南业务:以选择权看待,利润无法核实
海外业务围绕新加坡平台搭建,由三家公司组成。FUCHI做重型临时工程,持股70%。JS Tan Consultants做建设咨询,2026年7月并表,现金流出7.08亿日元,商誉由8.06亿日元增至14.94亿日元。Gecoss Vietnam做临时工程设计。14个月内两次新加坡收购,价格都伴随着低于净资产的会计处理。
它的资产负债表规模可以衡量:商誉加上30%的少数股东权益合计近60亿日元。收入和利润没有分地区披露,证券报告里的地区信息本次没有读取。所以只能把它当作选择权,不能当作盈利。
悬而未决的问题是:这个业务群到底贡献多少利润,如果新加坡建设放缓,集团的暴露有多大。这需要分地区披露,或证券报告里的地区信息来回答。
03|产品、客户与供应链
03.1|需求来自首都圈再开发和公共工程,业务量有保证,利润由定价决定
公司的需求环境在两份财报里表述一致:公共工程稳定,民间设备投资回升,但人手紧张、建设成本高,个别项目被修订、取消或延后。在这个背景下,公司所在的东京首都圈大型再开发项目需求稳固,2026年3月期和2027年3月期上半年都出现项目顺利启动、顺利推进的情形。
也就是说,业务量能拿到,利润取决于定价纪律。公司的应对措施是争取与设计等成本相称的对价、扩大首都圈施工能力,并发展钢构及桥梁(基础设施更新)、挡土相关领域、土木订单和海外业务。
没有给出市场规模数字。首都圈再开发这一波能持续多久,订单余额是多少,都没有公开信息可查。公司也没有披露前五大客户占比。
03.2|钢铁行业同时是供应商、客户和股东
钢铁行业通过三个渠道进入公司的利润表。作为供应商:租赁设备和材料领域持续买钢,设备账面285.91亿日元,重置成本随钢价上升,可部分通过租金和材料定价回收。作为客户:钢构及桥梁(2026年3月期115.65亿日元)和钢厂相关临时工程依赖钢铁和基础设施投资。作为股东:JFE集团持有39.49%,并派驻四名出向人员。
结果是:钢铁下行先通过钢构订单量影响公司,再通过设备经济性影响公司;单纯的钢价上涨,对能够重新定价的设备所有者近乎中性偏正面。公司没有披露钢价敏感度,这里的映射只是结构性的,没有量化。
04|竞争格局与产业关系
04.1|产业关系:大股东、扩张载体和提携伙伴共同决定经济与控制权怎样到达上市股东
这家公司的关系网可以分为四层:作为大股东兼钢铁产业链伙伴的JFE集团,既是资本也是渠道的Mizuho Lease,承载扩张的FUCHI和Rental System,以及一项刚签订的轻资本提携。竞争对手方面,公司没有披露同业对比,竞争位置只能从自身利润率走势判断。
生态的健康状况,会先反映在分部产品组合和股东名册行为上,之后才显示在集团收入里。各项合作的条款和载体层面的回报均未披露。
04.2|JFE集团:39.49%的大股东,同时也是公司的钢材来源、钢构原料和客户
JFE Steel直接持有27.63%,JFE Holdings合计39.49%,属权益法关联公司的母公司一方,派驻四名出向人员。钢铁对公司同时是材料投入、钢构原料,也是部分客户行业。
这一层关系解释了股东名册为什么稳定,也解释了公司的盈利为什么与钢铁周期有关。JFE未来意图无法判断。
04.3|Mizuho Lease:2024年4月入股的20.04%股东,也是机械业务的合作方
Mizuho Lease自2024年4月的资本与业务提携起持有20.04%。2025年9月,公司、合并子公司Rental System和Mizuho Lease又缔结了三方提携,扩大建设机械业务;2026年3月期,Rental System的第三方配股吸收了15.80亿日元少数股东出资。Mizuho Lease派驻一名董事和一名出向人员。
一个持有20%的股东,同时又是机械业务的资金和渠道伙伴。提携的合同深度和经济条件没有公开。
04.4|FUCHI与Rental System:把海外和机械做成了有外部共同股东的载体
FUCHI Pte. Ltd.(新加坡)2023年起是权益法关联公司,2025年8月公司认购第三方配股,持股提高到70%并连同两家子公司并表。同一笔交易产生4.01亿日元的负商誉收益和4.18亿日元的阶段取得损失,净额约为减0.17亿日元:集团以低于净资产的价格买下一个运营平台,同时把自己早先的持股减值。权益法损益的变动也部分来自FUCHI退出权益法范围。FUCHI的利润贡献没有单独披露。
Rental System是并表的建设机械租赁载体,也是三方提携的当事方。它的第三方配股,使非控制性权益由0.05亿日元增至44亿日元以上。载体层面的回报未披露。
04.5|Nihon Kiso Gijutsu:不投入资本的相邻业务提携
2026年10月,公司与Nihon Kiso Gijutsu Co., Ltd.(障碍物清除和地基改良的专业承包商)缔结业务提携,目的是强化现有业务,并在临时工程核心业务的相邻领域创造新业务。这笔提携没有资本投入,与机械业务路线是同样的轻资产做法,也显示管理层偏好围绕核心业务向周边扩展。
提携条款和贡献均未披露,提携本身只有两个月。
05|护城河判断
公司的优势由三项组成:285.91亿日元的租赁钢材设备,工程设计经验,以及首都圈大型再开发项目的施工业绩。放弃低毛利分销后,毛利率从20.9%升到22.9%,再升到23.5%,说明在现有产品组合上确实有一定的议价空间。
证据的局限同样清楚。毛利率走势来自公司自己的财报,没有客户、竞争对手或行业数据独立印证;设备利用率、设备年龄、订单余额和同业对比都没有披露。2026年3月期首次出现的订单亏损准备金,说明至少有一份合同定价低于完工成本,与“定价纪律已成体系”的说法并不一致。
耐久性取决于钢材和人工成本的上涨能否持续传导到合同价格,以及首都圈大型项目能持续多久。成本再度加速上涨、定价调整遇阻,这项判断就要下调;毛利率离天花板还有多远,要等2027年3月期全年的分部毛利率才能回答。
06|财务质量与现金流
06.1|收入减少166亿日元利润反而上升:毛利率抬升靠的是产品组合和定价
用收入增速筛选这家公司,会得到相反的结论。2025年3月期销售额减少166.44亿日元(下降13.0%,至1,115.50亿日元),这是公司主动压缩低毛利分销交易的结果:分销在钢材收入中的占比从四成左右降到两成五左右。重型临时工程的经常利润仍增加了2.89亿日元,达到66.30亿日元。
此后毛利率的轨迹是20.9%(2025年3月期)、22.9%(2026年3月期)、23.5%(2027年3月期上半年)。同期销售管理费在绝对额上还在增加,2026年3月期由164.59亿日元增至184.51亿日元,含人员和奖金准备金上升。所以营业杠杆来自毛利率,也就是产品组合和定价,不来自压缩费用。
公司所说的定价改善,是争取与设计等成本相称的对价,把过去按吨数卖钢时没有收费的工程内容收回来。2026年3月期临时钢材领域持平在620.39亿日元,而施工领域增长17.6%,增长来自卖工程的领域,不是卖吨数的领域。该板块的分部利润率(经常利润口径)由6.6%升到8.3%。
压缩分销被公司描述为已走完一轮,之后的增长应当是不靠产品组合帮忙的增长,这一点要由2027年3月期的几次业绩来检验。这套机制的天花板,目前无法从公开资料估算。
06.2|2026年3月期的增长要看营业利润线:经常利润里有5.47亿日元的营业外支撑
2026年3月期营业利润80.12亿日元(增长16.9%,创纪录),经常利润87.09亿日元(增长28.2%)。两者的差距,是理解这一年的关键。
营业外项目中,可识别的支撑合计5.47亿日元:汇兑收益1.96亿日元,补偿金收入0.94亿日元,出售证券收益0.47亿日元,权益法投资收益转为正的2.10亿日元(上年为亏损2.17亿日元)。特别项目净增2.03亿日元:FUCHI并表产生的负商誉收益4.01亿日元和出售证券收益2.20亿日元,减去阶段取得损失4.18亿日元。
税前利润89.12亿日元,所得税29.52亿日元,有效税率33.1%,少数股东损益1.07亿日元,归属母公司净利润58.53亿日元(增长28.8%),每股收益173.96日元。
公司自己也是这样看的:2026年5月制定的2027年3月期初始指引是营业利润84.00亿日元(增长4.8%),经常利润86.00亿日元(下降1.3%),因为汇兑收益和补偿金不会重复。分部利润按经常利润口径定义,所以分部利润率不等于营业利润率。
边界是:税收在各盈利层之间的分摊,公司没有公布;本报告按全年有效税率估算。
06.3|第二季度经常利润下降6%,营业利润却在增长
这个差异可以用来检验上面的拆分。把第一季度经常利润(22.90亿日元)从上半年累计(43.82亿日元)里减掉,2027年3月期第二季度单季经常利润为20.92亿日元;上年同期为22.26亿日元,同比下降6%。同一时期,上半年营业利润增长12.3%。
单季数字由相减得到,不是公司直接披露的数字。原因在上年同期:上年第二季度所在的半年带着2026年3月期的营业外支撑,而本期第二季度没有。第一季度经常利润同比增长20.8%,基数同样受到扭曲。只看经常利润的读者会认为这一季度变差,看营业利润线则恰恰相反。
06.4|2027年3月期上半年:没有特别项目的增长,全年指引随之上调
2027年3月期上半年销售额570.95亿日元(增长4.0%),营业利润41.90亿日元(增长12.3%),经常利润43.82亿日元(增长6.3%),净利润28.52亿日元(增长3.5%),中期每股收益84.75日元。毛利率由23.0%升到23.5%,营业利润率由6.8%升到7.3%。上年同期含FUCHI的两项特别项目,这半年一项也没有,增长完全来自经营。
11月5日公司把全年指引上调为:销售额1,180亿日元,营业利润92.00亿日元(增长14.8%,若达成为连续第二年创纪录),经常利润96.00亿日元,净利润63.00亿日元,每股收益187.24日元。年度分红由69日元提高到75日元,中期27日元,年末48日元,分红比例40.1%。
综合收益下降22.0%,为25.18亿日元,原因是证券估值准备金减少,这是资产负债表上的市场影响,与盈利无关。指引能否兑现,取决于下半年的隐含利润率(见第1章和第11章)。
06.5|订单亏损准备金3.14亿日元:定价纪律已成体系的反证
2026年3月期资产负债表上首次出现订单亏损准备金3.14亿日元。它证明至少有一份合同的定价低于完工成本,而这恰好发生在定价改善就是论点的年份。
它对应的是一份合同还是一类合同,目前不清楚。第三季度或全年数字如果让它扩大,“定价纪律已经成体系”这个前提就会从根基上松动。金额很小,要检验的内容很大。
相关的两个悬而未决的问题:毛利率还有多少上升空间,来自价格对价和产品组合的余量有多大,成本通胀再度加速会怎样;机械业务靠出售二手设备带来利润的模式,最终设备规模是多少。2027年3月期全年毛利率、分部利润率和证券报告附注,是解答它们的资料。
06.6|客户预收款增长75.1%,是仅有的前向需求信号
公司不披露订单余额,所以收入的可见度要靠间接信号。合同负债(工程开始前收到的客户款项)由32.85亿日元增至57.51亿日元,增长75.1%,约占销售额5.0%,约为应收款和合同资产的19%,所在的流动负债整体只增长10.5%。
这与施工领域增长17.6%以及项目顺利启动的描述一致:客户在为更多工作预先付款。但预收款项不是已确认的收入,也不是已经赚到的现金;各份合同的预收条款也没有披露。缺少订单余额是披露上的限制,不构成需求走弱的证据。
06.7|资产负债表近乎无负债,约束在于资产赚到的回报
2026年9月末,现金124.04亿日元,投资证券48.61亿日元,借款32.80亿日元,权益比率59.2%。公司披露的有息负债(含租赁)在2026年3月末为37亿日元,约为净资产的0.05倍;2026年3月期的利息支出只有0.71亿日元。
总资产1,217.85亿日元里,租赁钢材285.91亿日元,应收款和债权335.82亿日元,土地131.65亿日元(按历史成本)。坏账准备只有0.61亿日元。
偿债不是这家公司的研究问题。真正的约束是这堆资产赚到的回报。应收款账龄、未使用的授信额度和契约条款没有披露。
06.8|现金转化很强,但单年数字不宜年化
2026年3月期经营现金流106.61亿日元,是净利润(含少数股东)的1.8倍。拆开看:折旧32.88亿日元,应收款和合同资产减少29.79亿日元,存货减少9.45亿日元,另一方面应付款减少41.24亿日元,缴税23.65亿日元。2027年3月期上半年经营现金流47.05亿日元。
应收款和应付款在两次披露之间会因项目时间摆动30亿至40亿日元,所以单年的转化率不宜直接年化。结构上的事实是:这个模式自己为自己融资。业务转型、FUCHI和JS Tan两笔收购以及不断上调的分红,都没有靠净借款。
留下的就是金融资产这块余量,约140亿日元,它如何使用是第8章的问题。2027年3月期全年的经营现金流与修订后利润的对照,尚不能知道。
06.9|经常性净资产收益率只有7.8%,低于报告口径的8.5%
2026年3月期报告口径净资产收益率8.5%,分子是58.53亿日元,平均净资产约688亿日元。剔除一次性项目后,以营业利润80.12亿日元按33.1%有效税率计算,经常性分子约为53.6亿日元,经常性净资产收益率7.8%。2025年3月期报告口径为7.0%,2027年3月期预测为8.73%。
三个数字口径不同:实绩报告口径、剔除一次性后的经常口径、预测口径,不能直接连成一条线。分部层面的资产回报(经常利润口径)是:重型临时工程7.2%,建设机械4.1%。决定市净率论点的水平是个位数的高位,目前接近而尚未到达。
公司没有披露按领域的投入资本回报率,也没有披露或估算股权资本成本,所以本报告不对资本成本下结论。
06.10|建设机械:需求不构成约束,资本回报才是
重型临时工程的分部资产1,196.07亿日元,经常利润口径回报率7.2%;建设机械分部资产95.34亿日元,回报率4.1%(销售额147.65亿日元,利润率2.6%),却消耗了集团折旧32.88亿日元中的17.46亿日元,占一半以上。
机械租赁设备账面净值2026年3月末为40.65亿日元,2026年9月末降到37.15亿日元,因为公司在替换和出售设备做优化。Mizuho Lease提携和Rental System共同出资,针对的就是这种资产重、回报薄的经济性。
最终设备规模、利用率和提携的经济条件均未披露。机械业务约占分部毛利润的4%,改善对集团净资产收益率的拉动有限。
07|股东、董事与治理
07.1|两个大股东合计握有60%上下的表决权:名册稳定,流动性受限
JFE Steel直接持有27.63%,JFE Holdings合计39.49%(2026年3月31日),公司因此是权益法关联公司,不是子公司;Mizuho Lease持有20.04%,同时是资本与业务提携的伙伴。这些比例与2024年6月(27.62%、39.47%、20.03%)基本没有变化。
两位大股东合计约六成表决权,自由流通股约四成,也就是1,360万股左右,日均成交额只有9,200万日元;融券余额几乎没有,贝塔值0.53。11月6日(上调指引后第一个交易日)成交72,600股,约合1.27亿日元。建仓和减仓都需要数日,价格走势的平滑,部分来自流动性本身。
大股东背后的信托银行和机构持股没有提取,大量持股报告书也没有阅读。
07.2|JFE和Mizuho Lease诉求不同,议程仍在经营层手里
JFE看重一家稳定的钢铁产业链关联公司(四名出向人员,钢材供应和客户有交集);Mizuho Lease看重通过机械业务和Rental System变现的租赁合作(一名董事、一名出向人员)。公司披露的做法是:风险管理事项事先向两家沟通和报告,管理决策自行作出,没有需要披露的重大关联交易。
2024年以来的记录支持这一点。利润率优先的策略,对任何一家大股东都不是自然会提出的要求,却在没有披露异议的情况下执行了。分红上调、新加坡扩张同样如此。这是一种协商出来的自主权。
边界在于,这是根据行为和时间点做的推断,没有董事会纪要作依据,也无法证明资本政策的转向来自任何一方。
07.3|Mizuho Lease可能是推动资本讨论的一方,目前只是时间上的相关
一家持股20.04%的租赁专业公司,同时参与Rental System投资和机械业务提携,既有动机,也有话语体系去追问资本问题:把分红比例写成政策、设备回报、一直没有动用的回购。公司资本政策的加速,确实从2024年4月其入股起算。
但另一种解释同样成立:这套政策可能由经营层自己发起。两种解释目前都没有直接证据,提携的条款也没有公开。如果前一种成立,下一阶段的资本纪律就有一个看得见的推动方。
07.4|董事会像管理利润表一样管理股东名册
2026年有一连串动作:两次上调分红;5月重新引入股东优待(2016年曾废止旧制度,内容在7月确定);2026年6月起转为监查等委员会设置公司,并设立自愿的提名和薪酬委员会;多次举办个人投资者说明会。
自由流通股本身无法扩大,这套组合是为扩大边际买家。如果奏效,流动性折价会在净资产收益率之外独立收窄。这些工具的金额很小,对流动性的效果尚未得到证明。
07.5|少数股东权益开始分走增长载体的利润
非控制性权益由2025年3月期的0.05亿日元增至2026年3月期的44.03亿日元(2026年9月末44.62亿日元),来自FUCHI并表(30%少数股东)和Rental System的配股(15.80亿日元出资)。少数股东分走了2026年3月期1.07亿日元和2027年3月期上半年1.14亿日元的净利润,占集团利润4%左右。
少数股东都集中在两个增长载体:新加坡和机械。这两块跑得越快,归属母公司的每股利润增长就越落后于集团增长。未来的占比取决于这两个载体的相对盈利。
07.6|大股东一次披露,就可能改写估值体系
低概率、影响全面:JFE决定并表或出售,或Mizuho Lease决定退出,都会在一次披露里让股价剧烈重估。同样的稀薄流通盘,平时让价格走得平滑,遇到大股东规模的交易,就会让成交混乱。
公开资料里没有迹象显示会有变动,在披露之前也不会有先兆。概率无法从公开信息估计。
08|资本政策
08.1|分红比例就是承诺,日元金额只是结果
公司没有书面的派息政策,但分红有清晰的规律:每股54日元(派息率40.1%)、69日元(39.7%)、2027年3月期预测75日元(40.1%)。2026年1月上调年末分红,2026年11月再上调中期和年末,两次都随业绩披露、按利润比例上调。
2026年3月期几乎没有回购,库存股只占已发行股份的0.44%,尽管净金融资产近140亿日元。最近的一次回购是2023年的ToSTNeT-3购买并注销。董事会把比例当作承诺,把金额当作结果,这正是正式政策想要写下来的内容。
预测股息率4.27%,由经常性盈利覆盖约1.9倍。这条规则是行为上的,不是书面目标。
08.2|东证的资本成本要求是外部时钟,中期计划是内部尺子
公司在2024年10月披露了对东证资本成本要求的回应,并在中期经营计划里设了市净率目标。这个外部时钟把一个沉睡的关联公司,推成了利润率、分红和股东沟通的组合方案。它下一步的要求(给出高于账面价值的路径)比刚刚达成的更难,这份顺风是借来的。2024年10月回应文件的内容本次没有取得。
中期经营计划(2026年3月期至2028年3月期,2025年3月26日公布)以营业利润为首要指标。成长投资上限约250亿日元(含并购),已经使用的部分是FUCHI、JS Tan、土地以及设备和工厂投资,远低于上限,大部分还没有动用。营业利润两年间累计跟踪增长34%(68.51亿日元到指引92.00亿日元)。计划最后一年的销售额和营业利润目标没有取得。
计划到期本身就是催化剂:2027年5月的2028年3月期指引,是第一次看这套框架会不会带着更硬的数字续约。
08.3|市净率0.8倍的目标提前两年达成,一半靠账面、一半靠股价
中期计划把2028年3月期前市净率至少0.8倍设为目标。路径是:2024年9月不足0.5倍,2025年11月接近0.7倍,2026年11月0.82倍。每股净资产同期由1,970日元升到2,119日元,再到2,144日元左右,所以重估的一半发生在账面上,一半发生在股价上。
这也改变了后面的争论:重估会不会发生已经不是问题,问题是净资产收益率能否保持得足够高,使市场愿意接近1倍账面。提前达成的目标,抬高了下一个目标的证据分量,也抬高了未达成的代价。两个市净率口径(0.82倍与0.83倍)源于账面基准不同。
08.4|近140亿日元的金融资产尚未动用,回购工具有先例
净金融资产近140亿日元,是自然的资金来源,可以用于回购、特别分红或并购。目前没有动用:2026年只有分红上调、股东优待、治理改革和低价扩张在动,回购没有动。
最便宜的催化剂是把行为变成承诺:写明派息比例或净资产股息率下限,首次授权回购或注销库存股,公布中期计划最后一年的数值目标。2027年5月公布2028年3月期指引时,是这三件事最自然的场合。董事会也可以选择不写;没有数字,本身就是答案。
具体悬而未决的问题:派息规则会不会被正式化;中期计划结束后的接替框架带有哪些数值承诺(目标净资产收益率、权益比率或净金融资产水平);闲置的回购工具会不会被使用。Mizuho Lease如果确是推动方,这几个问题就有了推动者。
09|估值与安全边际
09.1|估值数字的口径各不相同,需要放在一起读
按2026年11月6日收盘价1,755日元,总市值593.1亿日元(已发行33,795,746股,含库存股149,533股,占0.44%)。
预测市盈率9.4倍,用的是公司修订后的2027年3月期每股收益187.24日元,属于公司指引口径,既不是实绩,也不是市场一致预期。实绩市净率0.83倍,用2026年3月期末每股净资产2,118.51日元;改用2026年9月末账面(2,144日元左右)则为0.82倍。净资产收益率8.5%是2026年3月期的公司实绩。预测股息率4.27%,对应年度分红75日元。
EV/EBITDA为4.4倍:EV 501.9亿日元,等于总市值减净现金91.24亿日元(2026年9月末现金124.04亿日元减借款32.80亿日元,不计证券);EBITDA 113.00亿日元,是2026年3月期营业利润80.12亿日元加折旧32.88亿日元,属于上一财年口径。
另一个口径把证券也扣掉:净金融资产近140亿日元,EV降到453亿日元左右,为预测营业利润的4.9倍。两种EV并存,是因为一个只算现金,一个同时算证券。
09.2|折价来自股东名册和资本回报,与盈利质量关系不大
市场用9.4倍预测盈利、0.82倍账面价值,给一家净现金发行人定价;营业利润对应的EV只有4.9倍。公司的盈利项目逐项披露,噪声有明细,折价的原因在别处:约六成表决权被锁定,自由流通股稀薄,经常性净资产收益率(2026年3月期7.8%,2027年3月期预测8.73%)仍低于市场愿意给出平价的水平。
价值可以拆成三块相加:营业业务按个位数倍数计价;金融资产按面值计价;资本政策正式化和下一个计划带来的期权价值。目前的价格付了第一块,并付了第二块的一部分。
折价有一个机械的消失条件:经常性净资产收益率达到两位数,或者金融资产被还给股东。市净率目标已达成,意味着安全边际比2025年薄,往后靠的是净资产收益率的证据,不是同一份账面上的倍数扩张。
本报告没有给出目标价或现金流折现模型。市场会给2027年3月期和2028年3月期指引多少倍数,目前未知。估值判断把握一般。
09.3|金融资产相当于市值的24%,是下行缓冲,也是尚未动用的选项
2026年9月末净金融资产139.85亿日元:现金124.04亿日元加投资证券48.61亿日元,减借款32.80亿日元,相当于近593亿日元市值的24%,账面净资产的19%。2026年3月末为132.59亿日元。
这个数字有明确的计算口径:证券按市价计算,证券组合的估值准备金在2027年3月期上半年减少5.54亿日元;退休金资产63.36亿日元对应负债4.45亿日元,是真实盈余,但不可分配,所以不计入;土地按历史成本,没有评估价值。这部分资产在估值里是加项,不是盈利。
09.4|最坏情形是估值问题,不是偿债问题
下行缓冲由资产和收入构成,没有杠杆:账面净资产721.28亿日元对593亿日元市值;净金融资产140亿日元;75日元分红由经常性盈利覆盖约1.9倍,并在最近两个调整点都上调了;最差的近年(2023年3月期经常利润49.03亿日元)也只是利润变小,没有亏损。几乎没有负债去放大下行。
一个盘整年配上低倍数的低谷盈利,价格可能回落三分之一左右,但按已观察到的先例,不会危及持仓。库存和土地按账面或成本计价,没有做折价分析,租赁设备的变现价值也不清楚。各情景的概率没有断言。
资产负债表的价值位于技术上的失效位置之上;价格结构即使破位,下行也属于估值问题,不涉及偿债。
10|Kabugami 技术结构
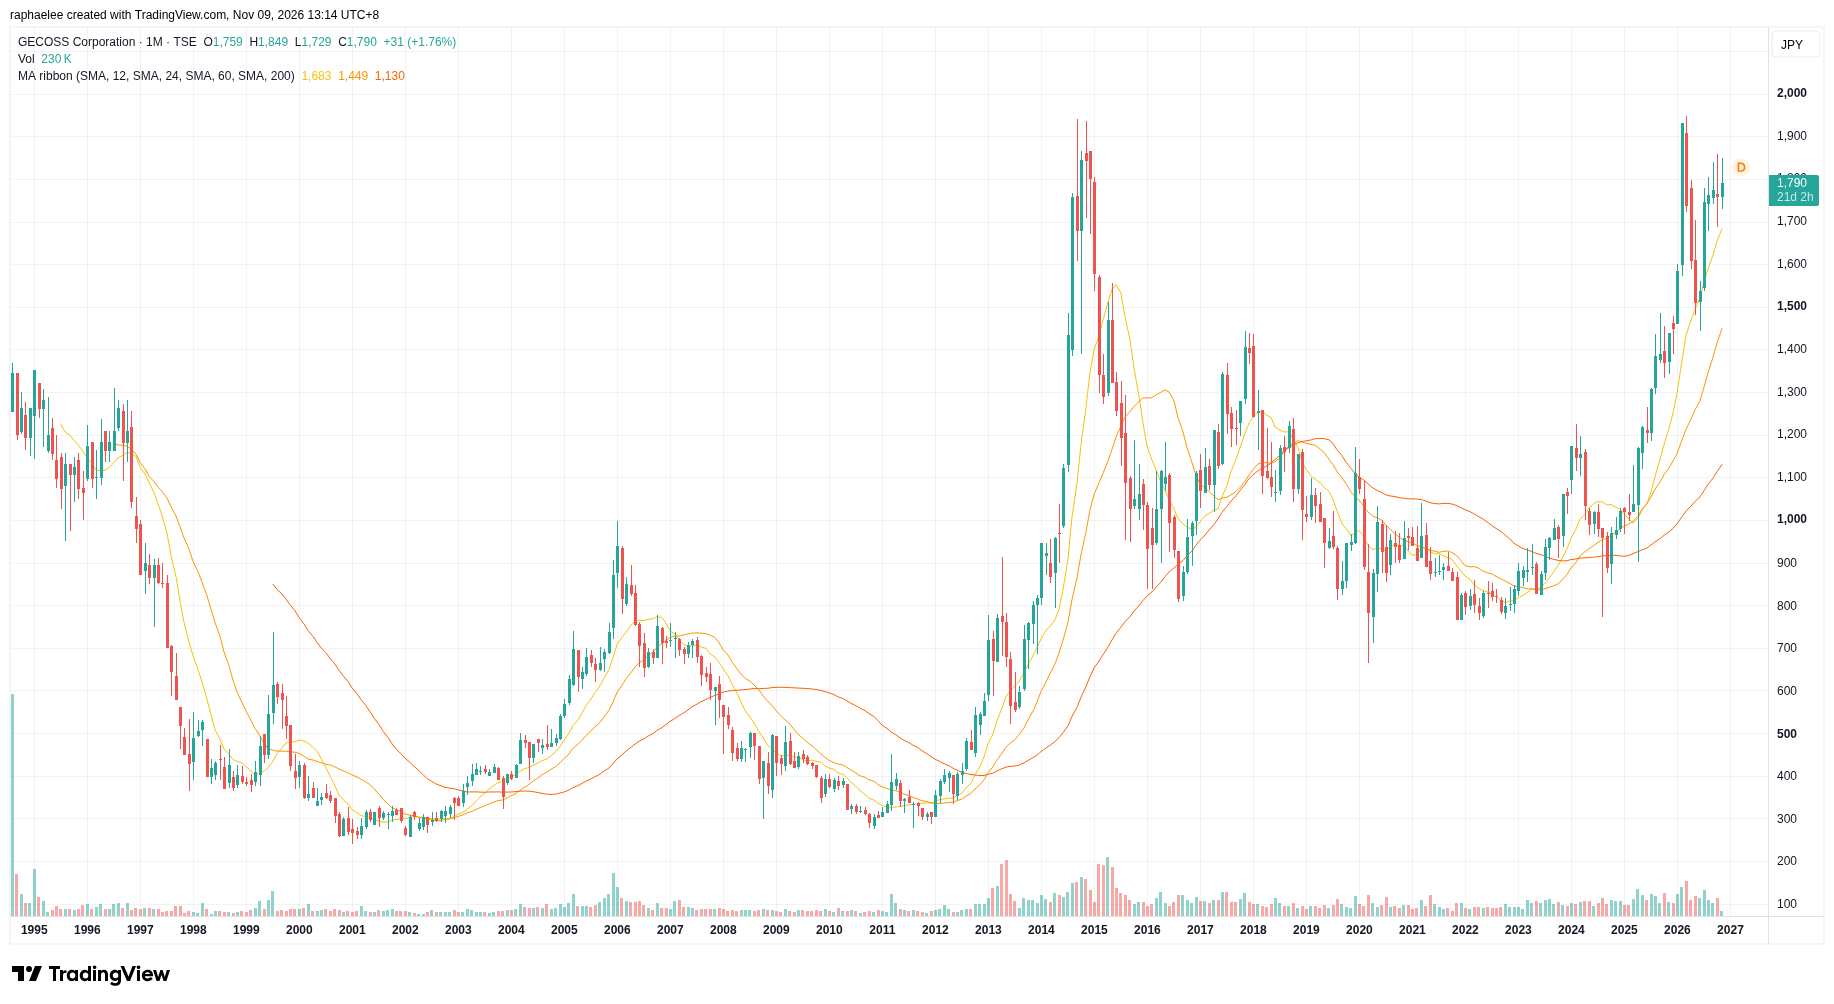
10.1|要回答的问题:1,940日元的旧高点,是被盈利正式超越,还是2014年冲高失败的重演
本章只看价格本身。观察日为2026年11月9日。数据是2001年1月至2026年10月的310根月线(Yahoo Finance图表数据,原始价格,序列中没有拆股类断点)。10月月线截至29日,尚未走完;最近的日线收盘是11月6日的1,755日元,来自外部行情快照;周线结构没有提供。
2026年2月的月收盘1,931日元,是公司历史上最高的月收盘;3月盘中最高1,948日元,只比2014年9月的1,940日元高出8日元。随后价格回撤到1,443日元,再修复到1,757日元,位于三条均线之上。
这引出本章的问题:这是2014年那次冲高被提前打出的价位、如今终于站稳,还是同一类形态的重演?
10.2|二十多年的底部、一次失败的冲高和一次台阶式突破
价格从2001年1月的240日元低点起步,2005年和2006年的年度高点为907日元和997日元,经金融危机跌到2010年的274日元,2013年回到912日元。2014年9月,价格冲高到1,940日元,当年收盘1,802日元。这次冲高失败:2015年低点948日元,收盘1,037日元,涨幅被放弃,此后很长时间里,长线持有人记住了一件事:这只股票的垂直新高,过去是被卖掉的。
2015年至2024年,价格在950至1,450日元一带的主要运行区间内运行;剔除2015年,年度高点在859至1,443日元之间,2020年3月的低点665日元是这段时期的最低价。2014年的1,940日元高点,压了十一年多。
突破是分步完成的。2025年,高点1,485日元,收盘1,451日元,刚好高于旧区间的上沿;2026年2月月收盘1,931日元,3月盘中1,948日元。路径可以概括为几步。2001年从240日元起步,2014年冲高1,940日元,2015年回落到948日元。2015至2024年是长期区间。2025年收盘站上旧上沿,2026年创历史新高,随后回撤到1,443日元,再修复到1,746至1,775日元。
10.3|回撤精确停在旧上沿:压力位变成了支撑位
2026年4月至6月的回撤,低点是1,443日元,恰好落在2015至2024年主要运行区间的上沿,也就是2025年收盘(1,451日元)首次越过的位置。旧压力位在第一次像样的回踩中变成了支撑位。
对照2014年:那次冲高后的第一次回撤(2015年)一路没有被止住,直到涨幅被放弃。这是2025至2026年这轮上涨与2014年最清楚的区别。
回撤之后的修复,7月至10月的月收盘依次是1,746日元、1,763日元、1,775日元、1,757日元(10月为未走完的月线)。10月月线开盘1,765日元,最高1,858日元,最低1,688日元,成交972,300股。
10.4|2026年的高点没有出现2015年那样的高潮放量
成交量把两轮上涨区分得很清楚。整个序列里成交最大的月份是2015年4月,3,391,600股,那是旧冲高的出货高潮。2026年这轮上涨最大的月份是3月的1,998,900股(2月为1,609,200股),约为2015年那次高潮的59%。7月修复月成交1,426,400股,是3月以来最强的上涨月;9月缩到705,500股,没有出现出货式放量。
截至2026年10月的十二个月,月均成交量1,106,467股,比前十二个月的964,217股增长14.8%:参与度是逐步积累的,没有一次性冲顶。这一轮上涨还没有遇到曾经终结2014至2015年那一轮的投机性放量,所以它的顶部,如果会出现,也还没有留下相应的量价痕迹。
价格位置:10月月线收盘1,757日元,处于上市以来全部价格区间(240至1,948日元)的88.8%位置,高于310个月收盘中的97.4%。只有七个月收盘更高,其中四个是2014年那次失败冲高自己打出的(2014年8月、10月、11月、12月)。距最高月收盘1,931日元回落9.0%,距盘中高点回落9.8%。
10.5|价格重心、压力位与支撑位:现在处在历史上几乎没有成交的区域
完整价格生命史的重心,是2015至2024年那段950至1,450日元的主要运行区间;60个月均线(约1,113日元)穿过它的上半部。1,757日元高出这个区间上沿21%:突破已是事实;但失败的话,两三根月线就可能回到区间里。
均线位置:12个月均线1,653.7日元,24个月均线1,414.9日元,60个月均线1,113.2日元;价格分别高出6.2%、24.2%、57.8%。
向上,只有历史纪录区1,931至1,948日元,再往上没有任何历史成交。向下,先是12个月均线1,654日元一带,然后是1,415至1,451日元的密集区,这里旧区间上沿、2025年收盘和24个月均线重合,是突破一旦失败时价格的重心所在。目前价格处在均线和纪录区之间的稀薄地带,历史上几乎没有在这里成交过,所以无论向哪边,穿越这一带都往往很快。
月线振幅在消化期里收窄:2026年3月为1,723至1,948日元,9月至10月的月线只有几百日元宽,在1,690至1,860日元之间,处于12个月均线上方。这是一次压缩,向哪个方向解开,价格本身还没有给出答案。
10.6|旧记忆仍在,承接力也在:上行像台阶,下行可能很快
这只股票的价格记忆被一件事支配:2014年9月冲到1,940日元,随后在2015年全部放弃。每个长线持有人都看到过它打出垂直新高再还回去,这就是2026年2至3月在几乎同一价位(1,948日元对1,940日元)遇到的抛压。这次失败的冲高压了十一年,在月收盘站上1,931日元并守住之前,这层抛压仍悬在头上;一旦守住,旧的记忆就算了结,价格上方将没有历史压力位。
承接力体现在两处:回撤精确停在旧上沿(1,443日元),修复月份把价格收窄在1,688至1,858日元,没有一根高潮量柱。来自2014年记忆的抛压,正在被吸收,衰竭的速度比价格下跌的速度更快,这是承接的特征,不是出货的特征。
响应是不对称的。从旧区间出来的上涨缓慢而呈台阶式(收盘价从1,020日元到1,931日元用了两年);2026年3月到6月的回撤,四个月就抹去约四分之一的价格。所以仓位的时点应尊重这种不对称,失效位置应当用月收盘价,而不是盘中价格。
恢复速度也一样:价格现在比最高月收盘低9.0%,已经过去八个月,远比2014年冲高后的路径慢(那次约十五个月内跌去一半)。这里的下跌更像记忆持有人在强势中获利了结,而不是被迫抛售;成交稀薄的自由流通盘也制造不出被迫抛售的量。
10.7|迁移质量:台阶式的收盘、渐进的放量,没有对应2015年的高潮
2025至2026年突破的质量较好:价格上涨伴随成交量逐步放大(十二个月均量同比增长14.8%),收盘分步推高(先是1,451日元,再到1,931日元),没有在单个月垂直拉升。曾经终结2014至2015年那轮上涨的高潮量(2015年4月的3,391,600股)没有对应物:2026年这轮上涨最大的月份只有它的59%。
这个结构由三层嵌套构成:二十多年的底部;底部上沿的2014年失败冲高;以及2025至2026年的台阶式突破。其中只有最年轻的一层,也就是突破之后的消化,目前还在运动。
10.8|当前状态:突破成立、仍在消化,高度与买盘之间有一处矛盾
纯价格状态:二十六年的底部,一次失败的冲高,一次越过冲高上沿的台阶式突破,一次精确的回踩支撑,以及均线上方四个月的消化。一次年轻的第二轮行情,目前状态良好,下一次决定性的价格运动要等它所等待的业绩披露之后。
内部的矛盾在高度与买盘之间:价格处在自身历史97.4%的月收盘之上,而这种位置通常是出货的位置;成交量却只有上一次高潮的一半左右,承接方更像是4.27%股息率(分红持续上调)带来的收益型买盘,来自一个四成的自由流通盘。价格之所以高,是因为股东名册稳定;它只有在大股东和收益型买盘都在的时候才守得住。这是关于持股人的陈述,与业务本身无关。
观察指标是月收盘价对三个位置:12个月均线1,654日元(消化期的下沿)、被回踩的旧上沿一带1,415至1,451日元(结构位)、纪录收盘1,931日元(确认位)。10月未走完的月线读数是:在消化下沿之上,远高于结构位,低于确认位,也就是一个站稳的突破等待检验,既没有确认为新的运行区间,也没有失败。技术判断把握一般:只有月线,周线结构没有提供,10月月线还没走完,价格是否已提前反映资本政策正式化和中期计划最后一年的目标,也无法判断。
10.9|价格追认了已披露的利润率改造,11月上调没有得到价格确认
以上纯价格状态形成之后,再对照公开的基本面事件,只看价格怎样响应。2014年的冲高紧跟2026年3月期之前一年(2015年3月期)的盈利高潮(经常利润增长56.5%)。2025至2026年的突破则出现在利润率改造已被多次披露之后:2025年5月起,2026年5月、2026年11月业绩都披露了改造的结果,而价格的决定性突破(2026年2月月收盘1,931日元)出现得更晚。这一轮,价格是追认已披露的经营记录,没有抢在前面。
2026年11月5日上调指引后的首个交易日(11月6日),价格收盘下跌2.55%,成交72,600股,属于普通水平,没有出现技术上的确认。持有人为已经兑现的业绩定价,没有为指引定价;对这次上调的评判,要等第三季度和全年两次披露之后的价格响应,不在上调当天。价格是否已经提前反映资本政策正式化和计划最后一年的目标,这一次的反应很淡,说明还没有。
资产负债表的价值位于技术上的失效位置之上:净金融资产占市值24%,账面每股净资产2,144日元左右,都高于1,443日元和1,415日元一带。价格结构即使破位,下行也属于估值问题,不涉及偿债。
10.10|价格后续要出现什么才算确认,出现什么就被推翻
确认有三条:月收盘价站上1,931日元(2026年2月的纪录收盘),并在下一个月继续守住,旧冲高的记忆即告了结,第二轮行情得到确认;月收盘价突破纪录区且成交量超过2026年3月(近200万股),说明买盘不再局限于稳定的股东名册;若在业绩偏弱的披露期里,价格回踩12个月均线(1,654日元一带)后成交缩量并守住,则说明这是消化期的新支撑。
失效也有三条:月收盘价跌破1,443日元(2026年6月回踩低点,也是旧区间上沿),突破的下方防线被破,旧压力位变支撑位的判断被推翻;月收盘价跌破24个月均线一带(1,415日元左右),价格回到旧的主要运行区间,第二轮行情的结构本身被推翻;出现2015年式的放量高潮(单月成交约300万股以上),并在纪录区收出长上影线,就等于打出了目前这轮上涨所缺少的出货特征。
11|风险与催化剂
11.1|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位
修订后的需求条件很具体,所以也很脆弱:下半年销售额持平,营业利润却要增长17%,等于要求毛利率机制在财报自己描述的环境里再往上走两个季度。这个环境是人手紧张、建设成本高位,部分项目已被修订、取消或延后。
固定价格合同又把风险放大:收入在成本落定前就已合同化,人工紧、材料贵,而且没有订单余额可以用来压力测试已嵌入的利润率。财报同时写出了不利因素(人工和材料成本)和应对办法(争取与设计成本相称的对价),所以利润率是已合同化工作上,实现价格与实现成本之间的双向博弈。固定价格合同在合同簿里的占比没有披露。
如果落空,就会检验利润率改善有没有一个低于指引水平的天花板,并削弱资本讨论背后的可信度。
11.2|订单亏损准备金和其他结构性薄弱点要最先留意
订单亏损准备金3.14亿日元(对应对象不明,详见第6章)是最早的预警信号:如果第三季度或全年披露让它放大,定价纪律已成体系这一前提就会松动。
其他薄弱点已在第2章列出:单一板块的定价纪律、合同在成本落定前定价、可能在一次披露内改变体制的股东名册、低回报的机械设备、不透明的海外业务,以及增长载体里持续上升的少数股东权益。它们的概率和规模大多没有披露。有一点可以事先设定:这些问题都会先出现在分部披露、准备金、大股东公告和每股收益的滞后上,不会先出现在集团合计数字里。
11.3|大股东变动是低概率的体制性事件
JFE决定并表或出售,Mizuho Lease决定退出,任何一方都会让股价在一次披露中剧烈重估,稀薄的自由流通盘又会让大股东规模的交易变得混乱。没有迹象显示会有变动,在披露之前也不会有先兆。概率无法从公开信息估计。
11.4|催化剂:从现在到2027年5月,只有一次业绩检验
最近的几个有日期的节点是:2026年12月1日起支付的中期分红27日元;2027年1月下旬至2月初的第三季度财报(2026年度第三季度财报在1月29日发布,外部日历指向2027年2月2日;以上日期是按往年规律的预期,尚未确认);2027年5月的全年财报;2027年6月的股东大会。
第三季度财报会披露下半年的第一个季度,对照8.2%的利润率要求,显示合同负债和施工领域是否继续增长,并可能像2026年1月的先例那样带来年末分红调整。2027年5月的全年财报公布2027年3月期的成绩、2028年3月期(中期计划最后一年)的指引和年末分红48日元。从现在到5月,只有一次业绩检验。
这次检验之所以决定论点,是因为下半年能否兑现,直接决定11月上调是变成可信度资产,还是重新打开利润率天花板的问题。大股东公告、大额订单、并购之类的突发事件,无法提前排日历。
11.5|最便宜的催化剂:把分红行为变成书面承诺
正式的派息比例或净资产股息率下限,第一次回购授权或库存股注销,以及中期计划最后一年数值目标的公布,每一项都把已观察到的行为变成承诺,且不需要更好的经营数字。2027年5月的全年财报,也就是2028年3月期指引的发布时点,是这三件事的自然场合。董事会也可以不写;没有数字,本身就是答案。
11.6|什么会推翻这个判断
基本面上有四项会推翻判断:下半年营业利润率明显低于8.2%,也就是利润率机制遇到天花板;订单亏损准备金扩大;2028年3月期框架放弃资本回报方案;大股东改变公司的地位。
确认则需要:2027年3月期营业利润达到或超过92.00亿日元,并出现带有净资产收益率和股东回报数值承诺的接替框架。确认只是暂时的,因为交付之后,问题会在2028年3月期的产品组合和成本上重新提出。
早期预警信号有三个:连续两个季度某个领域收缩、订单亏损准备金增加,以及大股东方面的持股公告。价格结构的确认位和失效位见第10章,这里不重复。检验窗口在2027年5月的全年财报公布时关闭。
12|反常识发现
12.1|按收入增速筛选,会把这家公司的故事读反
2025年3月期销售额下降13.0%,任何以收入增长为条件的筛选器都会把它排除在外;同一年,营业利润增长9.7%。这个预期差,是这份研究里最容易被忽略的一点。
收入下降是公司主动选择:把低毛利的分销交易压缩,换来更高的毛利率。而且销售管理费在两年里都在增加,说明改善来自产品组合和定价,不来自压缩成本。如果只看收入,或者只看经常利润(其中有5.47亿日元营业外支撑),都会读到另一个故事。
这个机制能走多远仍是未知:毛利率的天花板在哪里,还没有答案(见第13章)。
12.2|价格晚于利润率改造:这一轮是追认,没有抢跑
这只股票的第一段上涨,价格冲高紧跟2015年3月期的盈利高潮,随后全部放弃。第二段方向相反:利润率改造被多次披露之后,价格才在2026年2月完成决定性突破。两段的先后关系不同,意味着名册这一次是在已披露的经营记录面前才行动。
这个时序对照只描述价格与基本面谁先谁后,不改写任何一边的结论。价格是否也提前反映了下一阶段(资本政策正式化和计划最后一年的目标),目前看没有,11月上调当天价格的冷淡反应与这一点一致。
13|下一次值得跟踪什么
13.1|十个未决问题多数只能等披露来回答
下面十个问题,多数取决于未来的披露(第三季度财报、2027年5月的全年财报和接替框架、2027年6月的公告),或者取决于本次没有取得的原始文件。目前没有哪条合理的公开途径,能在这些披露之前明显改变判断。
第三季度财报预计在2027年1月下旬至2月初,是两次检验中的第一次。价格结构的后续确认和失效条件见第10章。
13.2|最优先的三个问题:下半年能否交付,毛利率有没有天花板,接替框架给不给数字
下半年营业利润能否达到50.10亿日元(同比增长17.0%,销售额只增长0.2%)?这决定11月上调变成可信度资产,还是重新打开利润率天花板的问题。要看第三季度的订单、项目进度和下半年完工项目的毛利率,答案来自2027年1月下旬至2月初的第三季度财报,以及2027年5月的全年财报。反面的答案会削弱利润率的故事。
毛利率还在上升吗?它从20.9%升到22.9%再到23.5%,要问的是价格对价和产品组合还剩多少余量,成本通胀再度加速时会怎样。答案在2027年3月期全年毛利率和分部利润率里;成本高位下毛利率能否守住23%以上,目前未知。
中期计划结束后,接替框架会给出哪些数值承诺:最后一年和下一个计划的营业利润、净资产收益率、派息规则正式化、资产负债表的终点(目标权益比率或净金融资产水平)?2027年5月的全年财报是第一个场合;没有数字本身就是答案。这决定市净率目标达成之后,重估能否靠净资产收益率的证据继续。
13.3|第二层问题:计划目标、分红规则和闲置的回购
中期计划最后一年(2028年3月期)的销售额和营业利润目标究竟是多少,2027年5月的指引会对照它设定,还是悄悄取代它?计划文件里的目标本次没有取得,需要从原文读取,没有它,计划的评分只能用披露里看得见的项目来搭。
40%上下的分红规则会不会被正式化:写成派息比例、净资产股息率下限,或者包含回购的总回报框架?市净率0.8倍目标已提前达成,2026年3月期又几乎没有回购,尽管公司是净现金。2024年10月成本资本回应文件的内容,本次没有取得。正式化会把行为变成承诺,可能压缩名册折价。
闲置的工具会不会被用起来:回购授权、注销库存股,或明确的总回报政策?2023年的ToSTNeT-3回购并注销,说明这些工具在董事会的工具箱里。近140亿日元金融资产如何使用,只能由董事会行动来回答,时间未知。
13.4|第三层问题:海外规模、亏损准备金、大股东和设备利用率
海外业务群到底有多大?FUCHI、JS Tan和Gecoss Vietnam放在重型临时工程里,没有单独的收入和利润披露;它们贡献多少,新加坡建设放缓时集团暴露多大?证券报告里的地区信息本次没有读取,目前只能用商誉和少数股东权益的规模去界定。在分地区披露出现之前,这块业务无法定价。
3.14亿日元的订单亏损准备金对应的是一份合同还是一类合同?机械业务靠出售二手设备带来利润的模式,有没有披露的最终设备规模?第三季度和全年准备金的变动,以及2027年3月期证券报告的附注,是解答它的资料;它决定定价纪律是否真正成体系。
双大股东结构会不会改变?JFE Holdings的39.49%和Mizuho Lease的20.04%自2024年以来没有变化;任何一方变动,都会同时改写名册、流通盘和估值体系。大量持股报告书和2027年6月的控股股东公告会显示变动,概率无法估计。
租赁钢材(285.91亿日元)的利用率和重置经济性如何?没有找到利用率或设备年龄的披露,所以公司最大的运营资产,回报只能从分部利润(7.2%的经常利润口径资产回报率)推断。只有公司披露或行业数据才能解决,目前在已读来源里没有找到。
14|Kabugami 评分卡
14.1|总分68.05/100,评级B+:基本面扎实,估值与价格都已部分兑现
评分版本V3.2,满分100分,八个模块的得分相加得到总分68.05分,评级B+(65至74.9分)。操作判断是:持有并继续观察,不追高。
理由:利润率改造带来的盈利兑现发生在稳定的股东结构内,下行有净金融资产和稳定分红支撑;但股价已站上历史高位区域,0.8倍市净率目标也已提前达成,进一步重估要靠投入资本回报率的证据。2027年1至2月的第三季度财报和5月的全年财报,是两次检验。若下半年营业利润率达不到8.2%、订单亏损准备金扩大、资本回报方案不再推进,或月收盘价跌破1,443日元,应重新评估。
14.2|财务韧性与下行防御 11.05/13 分:几乎无负债,下行是估值问题
净金融资产近140亿日元,约占市值的24%,权益比率59.2%,2026年3月期经营现金流106.61亿日元;应收款账龄、授信额度、设备和土地的变现价值没有披露,这些限制了满分。
14.3|竞争优势与结构耐久性 8.68/14 分:有议价迹象,缺外部验证
毛利率由20.9%升到23.5%,说明产品组合改善有效;但首次出现订单亏损准备金3.14亿日元,开工率、订单余额和同业对比都没有披露,约95%的分部利润集中在一个板块。
14.4|盈利质量、现金转化与资本效率 11.56/17 分:现金转化好,资本回报仍偏低
营业利润80.12亿日元创纪录,现金转化良好;扣除一次性因素后经常性净资产收益率7.8%,低于市场给平价所需的水平,订单余额缺失使下半年8.2%的利润率无法估算误差范围。
14.5|商业结构、产品、客户与关键依赖 6.6/11 分:业务量有保证,利润依赖单一板块
重型临时工程约占销售的90%、分部毛利润的96%;预收款项57.51亿日元(增长75.1%)是少数可见的前向需求信号;客户集中度、固定价格合同占比和海外利润都没有披露。
14.6|估值与安全边际 10.8/15 分:个位数倍数,但安全边际比2025年薄
预测市盈率9.4倍、市净率0.83倍、预测股息率4.27%,EV为预测营业利润的4.9倍;折价主要来自股东结构和资本回报;0.8倍目标已达成,没有现金流折现或目标价。
14.7|资本配置与股东回报 6.2/10 分:分红规律清楚,回购和书面政策缺位
派息比例连续三期在40%上下,两次上调;但没有书面派息政策,2026年3月期几乎没有回购,近140亿日元金融资产尚未动用。
14.8|治理、所有权与管理层 4.06/7 分:自主权有行为证据,大股东意图无法判断
没有任何一方过半数,两位大股东合计约60%;经营层推行了利润率优先的策略而没有披露异议;大股东意图、合作条款和变动概率均无法从公开资料判断。
14.9|Kabugami 技术结构 9.1/13 分:旧压力位变支撑,但月收盘尚未站稳1,931日元
回撤精确停在旧上沿,修复期没有高潮放量,旧状态的控制力明显减弱,新状态已部分建立;月收盘价尚未站上1,931日元,周线结构没有提供,确认仍未完成。
14.10|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 11.05 | 公司几乎无有息负债,自有资金支撑经营:2026年9月末现金124.04亿日元、投资证券48.61亿日元,借款32.80亿日元,净金融资产约140亿日元,约占593亿日元市值的24%;权益比率59.2%,利息支出仅0.71亿日元。2026年3月期经营现金流106.61亿日元,约为净利润的1.8倍,收购FUCHI、JS Tan、涨股息和业务转型都没有靠净借款。下行风险更像估值问题,而不是偿债问题。 |
| 竞争优势与结构耐久性 | 14 | 8.68 | 公司在重型临时工程租赁、设计施工领域有租赁钢材设备(285.91亿日元)、工程设计经验和首都圈大型再开发项目的施工参考,已经通过压缩低毛利的分销销售,把毛利率从20.9%提到22.9%,再到23.5%(2027年3月期上半年)。这说明在现有产品组合上有一定议价空间,但护城河证据主要来自公司自身的利润率走势,缺少外部独立验证。 |
| 盈利质量、现金转化与资本效率 | 17 | 11.56 | 2026年3月期营业利润80.12亿日元(增长16.9%,创纪录),经常利润87.09亿日元,其中约5.47亿日元来自汇兑收益、补偿金、证券出售收益和权益法投资收益摆动等营业外项目,特别项目净增2.03亿日元。扣除一次性因素后,经常性ROE约7.8%,低于报告口径的8.5%,预测2027年3月期为8.73%。现金转化良好,但资本回报仍低于市场给出平价估值所需的水平。 |
| 商业结构、产品、客户与关键依赖 | 11 | 6.6 | 业务集中在重型临时工程,约占销售的90%、分部毛利润的96%;材料租售(约620亿日元,持平)、工程(约300亿日元,增长17.6%)和钢构桥梁(约116亿日元,下降5.2%)构成收入。需求面是首都圈再开发和公共工程,供给面依赖钢材,JFE集团既是大股东,也与公司在钢材供应和客户上有交集。客户预收款项57.51亿日元,同比增长75.1%,是少数可见的前向需求信号。 |
| 估值与安全边际 | 15 | 10.8 | 按2026年11月6日收盘价1,755日元,市值约593亿日元;按公司修订后的2027年3月期每股收益187.24日元,预测市盈率9.4倍;按2026年3月期末每股净资产2,118.51日元,市净率0.83倍;预测股息收益率4.27%,约为经常性盈利的1.9倍覆盖。扣除净金融资产约140亿日元后,企业价值约453亿日元,约为预测营业利润的4.9倍。市场对一个净现金的发行人给出个位数倍数,折价主要来自股东结构和资本回报不足,而不是盈利质量。 |
| 资本配置与股东回报 | 10 | 6.2 | 分红有实际的规律:派息率约40.1%(54日元)、39.7%(69日元)、预测40.1%(75日元),并在2026年1月和11月两次上调;2026年5月重新引入股东优待制度,又多次举行个人投资者说明会。但没有写明的派息政策,2026年3月期几乎没有回购,库存股只占已发行股份0.44%,即使净金融资产约140亿日元。上一次回购是2023年的ToSTNeT-3回购并注销。 |
| 治理、所有权与管理层 | 7 | 4.06 | 公司是JFE集团的权益法关联公司(JFE合计表决权39.49%),Mizuho Lease持有20.04%,没有任何一方过半数,两大股东合计约60%,自由流通部分约40%,日均成交额约9,200万日元。2026年6月转为监查等委员会设置公司,并设立自愿提名和报酬委员会。2024年以来,公司推行了任何一家大股东都未必会主动要求的“利润率优先”策略,没有披露异议,说明经营层有实际议程权。 |
| Kabugami 技术结构 | 13 | 9.1 | 价格结构显示,2014年9月冲高到1,940日元后失败,随后约十年在约950至1,450日元的长期价格带内运行;2025年收盘1,451日元站上旧上沿,2026年2月月收盘1,931日元创历史新高,3月盘中最高1,948日元。2026年4月至6月回撤到1,443日元,恰好落在旧上沿,随后数月收在1,746至1,775日元,位于十二个月均线(约1,654日元)上方。旧状态的控制力明显减弱,新状态已部分建立,但月收盘价尚未站稳1,931日元之上,所以确认仍未完成。 |
总分: 68.05 / 100 评级: B+ 操作建议: 持有并继续观察,不追高。基本面是在大股东稳定的结构内,由利润率改善推动的盈利兑现,下行有净金融资产和稳定分红支撑;但股价已经站上历史高位区域,0.8倍市净率目标也已提前达成,进一步重估要靠投入资本回报率的证据。2027年1至2月的第3季度决算和5月的全年决算与新年度指引,是决定论点成立与否的两次验证;若下半年营业利润率未达约8.2%、订单亏损准备金扩大,或资本回报方案不再推进,应重新评估;月收盘价跌破1,443日元也要重新评估。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|数据截止日与主要来源
研究截止日为2026年11月9日。价格与估值数据取自2026年11月6日收盘(股价1,755日元)。月线序列覆盖2001年1月至2026年10月,10月月线截至29日,尚未走完。
公司一手资料:2026年3月期决算短信(2026年5月11日,东京证券交易所披露);2027年3月期上半年决算短信及上调指引与分红通知(2026年11月5日);控股股东等相关事项通知(2026年6月29日,持股状态为2026年3月31日);第一季度决算(2026年7月29日,经irbank汇编);以及公司披露一览(2026年)。
二手资料:2025年5月30日和2025年11月10日的业绩说明会文字记录(Logmi Finance,经Minkabu转载),用于核对中期计划、分销销售压缩和市净率路径;irbank等TDnet衍生的行情数据商,用于市值、市盈率、市净率、股息率、日均成交额和年度高低点;价格序列为Yahoo Finance图表数据,经本地汇编。官方英文名取自公司自己的英文版决算短信:GECOSS CORPORATION。
15.2|证据的限制:哪些事实尚未核实,会怎样限制判断
以下事实目前没有核实,分别限制了对应的判断:订单余额和固定价格合同占比未披露,所以下半年8.2%的利润率无法估算误差范围;订单亏损准备金对应的合同未知,所以“定价纪律已成体系”只能作为有条件的判断;新加坡和越南业务的收入与利润没有分地区披露,证券报告里的地区信息本次没有读取,所以海外只能当作选择权;中期计划最后一年的目标和2024年10月成本资本回应文件的内容没有取得;2026年2月代表董事变更只读了披露抬头;大股东背后的信托银行持股和大量持股报告书没有读取;租赁钢材的利用率和设备年龄没有披露。
口径方面:分部利润按经常利润口径;估值倍数各自的基准已在第9章写明(预测市盈率为公司指引口径,两种EV口径不同);财报日期(2027年1月下旬至2月初、5月、6月)是按往年规律的预期,尚未确认;第二季度单季经常利润由相减得到。价格结构只依据月线判断,周线结构没有提供。这些缺口不等于公司在这些方面的实际表现较差,它们只表示相应结论目前还不能被资料证实。
本报告基于公开资料,用于研究,不构成买卖建议。价格、估值和公开披露会随时间变化。
主要资料来源
- Issuer identity: GECOSS Corporation, TSE Prime 9991, EDINET E02782, business since 1968
- Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary
- The pivot from revenue to profit: low-margin distribution sales suppressed from about 40% to about 25% of steel-material sales
- H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items
- Q1 FY3/2027: ordinary profit of JPY 2,290 million, +20.8% year on year
- Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit
- Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment
- Locally recomputed monthly series: span, extremes and basis
研究发现索引
展开本次 Review 的 107 项研究发现
F001|GECOSS Corporation (ジェコス株式会社, 9991, TSE Prime, EDINET E02782, operating since 1968, listed 1994) is a heavy-temporary-works company: rental and sale of temporary steel materials, temporary-works design and construction, steel fabrication and bridges, plus construction-machinery rental, with a small Singapore/Vietnam cluster. FY3/26 sales were JPY 115,680 million; heavy temporary works is about 90% of sales and about 96% of gross segment profit. It is an equity-method affiliate of the JFE group (39.49% of votes) with Mizuho Lease at 20.04%; no holder has a majority.
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论02|一家把租赁钢材和工程设计绑在一起的临时工程公司15|数据截止日与主要来源
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Issuer identity: GECOSS Corporation, TSE Prime 9991, EDINET E02782, business since 1968怎么使用:直接 / 支持;一手验证:01
FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields怎么使用:直接 / 支持;一手验证:02、03、05、08、09、10、15
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接 / 支持;一手验证:01、23、24;外部现实校验:07
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|Issuer identity: GECOSS Corporation, TSE Prime 9991, EDINET E02782, business since 1968;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域15)|FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary
完整研究记录(核对用)
研究原文:GECOSS Corporation (ジェコス株式会社, 9991, TSE Prime, EDINET E02782, operating since 1968, listed 1994) is a heavy-temporary-works company: rental and sale of temporary steel materials, temporary-works design and construction, steel fabrication and bridges, plus construction-machinery rental, with a small Singapore/Vietnam cluster. FY3/26 sales were JPY 115,680 million; heavy temporary works is about 90% of sales and about 96% of gross segment profit. It is an equity-method affiliate of the JFE group (39.49% of votes) with Mizuho Lease at 20.04%; no holder has a majority.
内部研究类型:ENTITY_IDENTITY_AND_PERIMETER
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Fixes the investable perimeter: affiliate-not-subsidiary status and a two-anchor register define governance, float and valuation for ordinary shareholders.
不确定性(原始记录):Content of the February 2026 representative-director change was read only from filing headers (Nobusa continuous as president).
F002|06|收入减少166亿日元利润反而上升:毛利率抬升靠的是产品组合和定价
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|收入减少166亿日元利润反而上升:毛利率抬升靠的是产品组合和定价12|按收入增速筛选,会把这家公司的故事读反14|竞争优势与结构耐久性 8.68/14 分:有议价迹象,缺外部验证
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items怎么使用:直接 / 支持
Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%怎么使用:直接 / 支持;一手验证:16
Segment profit concentration: heavy temporary works earns about 96% of gross segment profit怎么使用:直接证据;一手验证:02、16;反向验证:08;专项深挖:02、08
查看完整证据标签(核对用)
直接证据 / 支持证据|The pivot from revenue to profit: low-margin distribution sales suppressed from about 40% to about 25% of steel-material sales;直接证据 / 支持证据|Distribution-sales suppression in detail: the FY3/25 revenue fall of JPY 16.6 billion was the policy, not the market;直接证据 / 支持证据|FY3/2026 consolidated results: record operating profit of JPY 8,012 million;直接证据 / 支持证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items;直接证据 / 支持证据 / 一手证据(研究域16)|Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%;直接证据 / 一手证据(研究域02) / 一手证据(研究域16) / 反证(研究域08) / 定向深挖(研究域02) / 定向深挖(研究域08)|Segment profit concentration: heavy temporary works earns about 96% of gross segment profit
完整研究记录(核对用)
研究原文:The revenue decline was a choice: FY3/25 sales fell 13.0% because management cut low-margin distribution sales from about 40% to about 25% of steel-material revenue while operating profit still rose 9.7%. Gross margin then compounded 20.9% (FY3/25) to 22.9% (FY3/26) to 23.5% (H1 FY3/27) on mix and price-adequacy work (consideration matched to design and execution cost); SG&A rose in absolute terms in both years, so the operating leverage is revenue-quality, not cost-cutting. Screening on revenue growth inverts the story. Segment margin of heavy temporary works stepped from 6.6% to 8.3% on the ordinary-profit basis.
内部研究类型:CAUSAL_MECHANISM_STRATEGIC_CHOICE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):This is the engine of record operating profit and of the re-rating; it is a management-controlled mechanism, not a market gift.
不确定性(原始记录):Distribution-suppression is described as having run its course, so future growth must be mix-neutral; ceiling of the programme is an open question (see Research Debt).
F003|06|2026年3月期的增长要看营业利润线:经常利润里有5.47亿日元的营业外支撑
研究范围:开放研究+35项覆盖检查
写入正文:06|2026年3月期的增长要看营业利润线:经常利润里有5.47亿日元的营业外支撑14|盈利质量、现金转化与资本效率 11.56/17 分:现金转化好,资本回报仍偏低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Accounting note: segment profit is ordinary profit, so segment margins are not operating margins怎么使用:直接证据;一手验证:32;反向验证:02、16
FY3/26 earnings-quality bridge: operating 8,012 to ordinary 8,709 to pre-tax 8,912 to net 5,853怎么使用:直接证据;一手验证:28;反向验证:32;专项深挖:28
FUCHI step-acquisition mechanics: how one deal produced both a JPY 401 million gain and a JPY 418 million loss怎么使用:直接证据;一手验证:32;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 consolidated results: record operating profit of JPY 8,012 million;直接证据 / 支持证据|FY3/2026 one-off layers: negative goodwill and a step-acquisition loss below the line, FX and compensation inside ordinary profit;直接证据|FY3/2027 initial guidance (May 2026): operating profit up, ordinary profit guided down as one-offs drop out;直接证据 / 一手证据(研究域32) / 反证(研究域02) / 反证(研究域16)|Accounting note: segment profit is ordinary profit, so segment margins are not operating margins;直接证据 / 一手证据(研究域28) / 反证(研究域32) / 定向深挖(研究域28)|FY3/26 earnings-quality bridge: operating 8,012 to ordinary 8,709 to pre-tax 8,912 to net 5,853;直接证据 / 一手证据(研究域32) / 定向深挖(研究域32)|FUCHI step-acquisition mechanics: how one deal produced both a JPY 401 million gain and a JPY 418 million loss
完整研究记录(核对用)
研究原文:FY3/26 must be read on the operating line. Operating profit JPY 8,012 million (+16.9%, record) sits below ordinary profit JPY 8,709 million (+28.2%), which contains about JPY 547 million of identifiable non-operating supports (FX gain 196, compensation received 94, securities-sale gain 47, equity-method swing to +210); special items add a net JPY 203 million (negative goodwill 401 and securities sale 220 against a FUCHI step-acquisition loss of 418). The company guided FY3/27 ordinary profit down at inception while guiding operating profit up (initial: operating JPY 8,400 million, ordinary JPY 8,600 million). Segment profit is defined on the ordinary basis, so segment margins are not operating margins.
内部研究类型:EARNINGS_QUALITY_BRIDGE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Readers screening on ordinary or net profit misread both FY3/26 growth and later quarters; the recurring layer must be built from the operating line before any multiple means anything.
不确定性(原始记录):Tax allocation between earnings layers uses the year's effective rate (33.1%); layer-by-layer tax split not published.
F004|06|第二季度经常利润下降6%,营业利润却在增长
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Q2 FY3/27 standalone: ordinary profit of about JPY 2,092 million, down about 6% - the base-effect quarter inside a growing half怎么使用:直接 / 支持;反向验证:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域28)|Q2 FY3/27 standalone: ordinary profit of about JPY 2,092 million, down about 6% - the base-effect quarter inside a growing half;直接证据 / 支持证据|Q1 FY3/2027: ordinary profit of JPY 2,290 million, +20.8% year on year;直接证据 / 支持证据|FY3/2026 one-off layers: negative goodwill and a step-acquisition loss below the line, FX and compensation inside ordinary profit
完整研究记录(核对用)
研究原文:Standalone Q2 FY3/27 ordinary profit was about JPY 2,092 million versus about JPY 2,226 million a year earlier (about -6%), while H1 operating profit grew 12.3%. Differencing proves that the ordinary line, not the business, deteriorated in that quarter, because the prior-year quarter carried part of FY3/26's non-operating supports. Q1 had printed ordinary profit of JPY 2,290 million (+20.8%) on a similarly distorted base.
内部研究类型:BASE_EFFECT_ANOMALY
内部来源标记:COVERAGE35
普通股东含义(原始记录):Quarterly prints of this company must be read on the operating line; an ordinary-line reader sees deterioration where the business improved.
不确定性(原始记录):Standalone Q2 is derived by differencing, not directly reported.
F005|06|2027年3月期上半年:没有特别项目的增长,全年指引随之上调
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论06|2027年3月期上半年:没有特别项目的增长,全年指引随之上调
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items怎么使用:直接 / 支持
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接 / 支持
查看完整证据标签(核对用)
直接证据 / 支持证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items;直接证据|H1 FY3/2027 segments: heavy temporary works JPY 4,403 million of ordinary-basis profit; machinery profit up 34% on used-asset sales;直接证据 / 支持证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75
完整研究记录(核对用)
研究原文:H1 FY3/27 grew without special items: sales JPY 57,095 million (+4.0%), operating profit JPY 4,190 million (+12.3%), gross margin 23.5%, operating margin 7.3%. On 5 November 2026 the company raised FY3/27 guidance to sales JPY 118,000 million and operating profit JPY 9,200 million (+14.8%), ordinary JPY 9,600 million, net income JPY 6,300 million, EPS JPY 187.24, and lifted the annual dividend forecast from JPY 69 to JPY 75 (about 40.1% payout). Comprehensive income fell 22.0% on a securities valuation reserve decline, a balance-sheet market effect, not an earnings effect.
内部研究类型:CURRENT_CHANGE_EVENT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Second consecutive record operating profit if delivered, with a dividend increase sized to the existing ratio.
不确定性(原始记录):Delivery depends on the implied second half; the Q3 tanshin is the first check.
F006|01|下半年要交出8.2%的营业利润率,这是利润率承诺,不是需求承诺
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|下半年要交出8.2%的营业利润率,这是利润率承诺,不是需求承诺11|催化剂:从现在到2027年5月,只有一次业绩检验
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接 / 支持;一手验证:35;反向验证:12、30;专项深挖:16、35
H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items怎么使用:直接 / 支持
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接证据
查看完整证据标签(核对用)
直接证据 / 支持证据|Forecast arithmetic: the revised FY3/27 plan requires a second-half operating profit of JPY 5,010 million, +17% on the prior second half;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据 / 支持证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items;直接证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75
完整研究记录(核对用)
研究原文:Subtracting H1 actuals from the revised forecast requires a second half of JPY 60,905 million sales (+0.2% year on year) and JPY 5,010 million operating profit (+17.0%; ordinary +13.8%, net income +11.3%), an implied operating margin of 8.2% versus 7.0% in H2 FY3/26 and 7.3% in H1 FY3/27. Seasonality is normal (H1 delivered 45.5% of the revised full-year operating profit versus 46.6% a year earlier), so this is a margin promise, not a demand or phasing promise. Two quarters decide it; the first prints late January / early February 2027.
内部研究类型:FALSIFIABLE_FORECAST_ARITHMETIC
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Concentrates the year's verdict and management credibility in one checkable margin step.
不确定性(原始记录):Error bars on embedded margins cannot be computed from primary sources because no order backlog is disclosed.
F007|11|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位
研究范围:开放研究
写入正文:11|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high怎么使用:直接 / 支持;一手验证:05、10、11、12、14
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接 / 支持;一手验证:06、18、19、20、21
查看完整证据标签(核对用)
直接证据 / 支持证据|Forecast arithmetic: the revised FY3/27 plan requires a second-half operating profit of JPY 5,010 million, +17% on the prior second half;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域10) / 一手证据(研究域11) / 一手证据(研究域12) / 一手证据(研究域14)|Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million
完整研究记录(核对用)
研究原文:The revised forecast's demand is specific and fragile: flat second-half sales with a 17% operating-profit increase requires the gross-margin programme to compound for two more quarters in an environment the filings describe as tight labour and high construction costs, with some projects revised, cancelled or postponed.
内部研究类型:RISK_CONDITION
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):A miss would test whether the margin programme has a ceiling below the guided level and weaken the credibility behind the capital argument.
不确定性(原始记录):Magnitude cannot be sized without backlog disclosure.
F008|11|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位
研究范围:35项覆盖检查
写入正文:11|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure怎么使用:直接 / 支持;反向验证:06、14;专项深挖:06、14
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接 / 支持;反向验证:05、11;专项深挖:05、11
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接 / 支持;一手验证:35;反向验证:12、30;专项深挖:16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure;直接证据 / 支持证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement
完整研究记录(核对用)
研究原文:Fixed-price exposure runs through the works book: revenue is contracted before costs are final, labour is tight and materials are dear, and no backlog is disclosed against which to stress embedded margins. The filings name both the headwind (labour and materials cost) and the countermeasure (obtaining consideration commensurate with design cost), so margin is a two-sided contest between realized prices and realized costs on work already contracted.
内部研究类型:RISK_CONDITION
内部来源标记:COVERAGE35
普通股东含义(原始记录):Margin timing risk between contract price and completion cost sits with shareholders.
不确定性(原始记录):The fixed-price share of the contracted book is not disclosed.
F009|06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证
研究范围:开放研究+35项覆盖检查
写入正文:06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证11|订单亏损准备金和其他结构性薄弱点要最先留意14|竞争优势与结构耐久性 8.68/14 分:有议价迹象,缺外部验证
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接 / 支持;一手验证:06、18、19、20、21
Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure怎么使用:直接 / 支持;反向验证:06、14;专项深挖:06、14
Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%怎么使用:直接 / 支持;一手验证:16
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure;直接证据 / 支持证据 / 一手证据(研究域16)|Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%
完整研究记录(核对用)
研究原文:A first-time provision for loss on orders of JPY 314 million appeared on the FY3/26 balance sheet, proving at least one contract was priced below completion cost in the very years the pricing programme is the thesis. It is unexplained: it is not known whether it attaches to one contract or a class. If Q3 or full-year prints enlarge it, the premise that pricing discipline is now systematic weakens at its foundation.
内部研究类型:EARNINGS_QUALITY_CRACK
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Early-warning signal on the central pricing mechanism; small in yen, large in what it could falsify.
不确定性(原始记录):Counterparty, contract history and direction of movement unknown.
F010|06|客户预收款增长75.1%,是仅有的前向需求信号
研究范围:开放研究+35项覆盖检查
写入正文:06|客户预收款增长75.1%,是仅有的前向需求信号14|商业结构、产品、客户与关键依赖 6.6/11 分:业务量有保证,利润依赖单一板块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接 / 支持;反向验证:05、11;专项深挖:05、11
Customer advances in detail: contract liabilities of JPY 5,751 million fund about 5% of annual sales in advance怎么使用:直接 / 支持;一手验证:15;专项深挖:15、19
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接 / 支持;一手验证:06、18、19、20、21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set;直接证据 / 支持证据 / 一手证据(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Customer advances in detail: contract liabilities of JPY 5,751 million fund about 5% of annual sales in advance;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million
完整研究记录(核对用)
研究原文:Contract liabilities (customer advances) rose 75.1% from JPY 3,285 million to JPY 5,751 million in FY3/26, about 5.0% of sales and about 19% of the receivables-and-contract-assets book, inside current liabilities that rose only 10.5%. With no order backlog disclosed, this is the closest forward-demand sensor in the filing set, consistent with works growth (+17.6%) and smooth project starts: forward demand is corroborated by prepayment behaviour but not quantified.
内部研究类型:DEMAND_SIGNAL
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Substitute for a backlog; a rising balance supports the second-half delivery, but advances are not recognized revenue or cash earned.
不确定性(原始记录):Absence of a backlog series is a disclosure limitation, not negative evidence; advance terms by contract unknown.
F011|06|资产负债表近乎无负债,约束在于资产赚到的回报
研究范围:35项覆盖检查+开放研究
写入正文:06|资产负债表近乎无负债,约束在于资产赚到的回报14|财务韧性与下行防御 11.05/13 分:几乎无负债,下行是估值问题
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接 / 支持;一手验证:06、18、19、20、21
Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition怎么使用:直接 / 支持;一手验证:18
Debt stack: company-disclosed interest-bearing debt of JPY 3.7 billion, D/E of 0.05 times怎么使用:直接证据;一手验证:25;反向验证:18
Working capital anatomy: receivables and claims of JPY 36,552 million against payables of JPY 23,095 million怎么使用:直接证据;一手验证:06、19;反向验证:15、17
Dividend record: JPY 54 (FY3/25) to JPY 69 (FY3/26), payout ratios of 40.1% and 39.7%怎么使用:支持证据;一手验证:26
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:支持证据
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 支持证据 / 一手证据(研究域18)|Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition;直接证据 / 一手证据(研究域25) / 反证(研究域18)|Debt stack: company-disclosed interest-bearing debt of JPY 3.7 billion, D/E of 0.05 times;直接证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域15) / 反证(研究域17)|Working capital anatomy: receivables and claims of JPY 36,552 million against payables of JPY 23,095 million;支持证据 / 一手证据(研究域26)|Dividend record: JPY 54 (FY3/25) to JPY 69 (FY3/26), payout ratios of 40.1% and 39.7%;支持证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75
完整研究记录(核对用)
研究原文:The balance sheet is close to debt-free and self-funded: at September 2026 cash JPY 12,404 million and investment securities JPY 4,861 million against borrowings JPY 3,280 million; equity ratio 59.2%; interest-bearing debt about 0.05 times equity (company-disclosed JPY 3.7 billion at FY3/26 including leases); interest paid only JPY 71 million. Total assets JPY 121,785 million include rental steel JPY 28,591 million, receivables and claims JPY 33,582 million and land JPY 13,165 million at cost. Receivables allowance is trivial (JPY 61 million).
内部研究类型:FINANCIAL_STRUCTURE
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Solvency is not a research question here; the constraint is the return earned on the asset pile.
不确定性(原始记录):Receivable ageing, committed lines and covenants not disclosed.
F012|08|近140亿日元的金融资产尚未动用,回购工具有先例
研究范围:35项覆盖检查
写入正文:08|近140亿日元的金融资产尚未动用,回购工具有先例09|金融资产相当于市值的24%,是下行缓冲,也是尚未动用的选项
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接 / 支持;一手验证:21、29;反向验证:20;专项深挖:18、21
Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition怎么使用:直接 / 支持;一手验证:18
Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit怎么使用:直接 / 支持;一手验证:27、31;反向验证:22;专项深挖:27、31
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation;直接证据 / 支持证据 / 一手证据(研究域18)|Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 反证(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit
完整研究记录(核对用)
研究原文:Net financial assets were about JPY 14.0 billion at September 2026 (cash 12,404 plus securities 4,861 less borrowings 3,280), about 24% of the roughly JPY 59.3 billion market capitalisation and about 19% of book equity (FY3/26: JPY 13,259 million). The securities portfolio moves with markets (valuation reserve fell JPY 554 million in H1). A retirement-benefit asset of JPY 6,336 million against a JPY 445 million liability is real but not distributable and is excluded; land is at historical cost with no appraisal.
内部研究类型:HIDDEN_ASSET_VALUATION_COMPONENT
内部来源标记:COVERAGE35
普通股东含义(原始记录):The financial sleeve is downside ballast and the natural funder of buybacks, special dividends or acquisitions; it belongs in valuation as an additive piece, not as earnings.
不确定性(原始记录):Net financial assets here count securities at market and exclude pension and land; the EV in the valuation snapshot nets cash only, so the two EV bases differ.
F013|06|现金转化很强,但单年数字不宜年化
研究范围:35项覆盖检查
写入正文:06|现金转化很强,但单年数字不宜年化
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Cash conversion FY3/26: operating cash flow of JPY 10,661 million against net income of JPY 5,960 million怎么使用:直接 / 支持;一手验证:17;专项深挖:17
H1 FY3/27 cash walk: operating inflow of JPY 4,705 million; the JS Tan acquisition inside investing outflow怎么使用:直接 / 支持;一手验证:17;反向验证:19
Debt stack: company-disclosed interest-bearing debt of JPY 3.7 billion, D/E of 0.05 times怎么使用:直接 / 支持;一手验证:25;反向验证:18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|Cash conversion FY3/26: operating cash flow of JPY 10,661 million against net income of JPY 5,960 million;直接证据 / 支持证据 / 一手证据(研究域17) / 反证(研究域19)|H1 FY3/27 cash walk: operating inflow of JPY 4,705 million; the JS Tan acquisition inside investing outflow;直接证据|FY3/2026 cash flow: operating inflow of JPY 10,661 million funds everything;直接证据 / 支持证据 / 一手证据(研究域25) / 反证(研究域18)|Debt stack: company-disclosed interest-bearing debt of JPY 3.7 billion, D/E of 0.05 times
完整研究记录(核对用)
研究原文:Cash conversion is structural: FY3/26 operating cash flow JPY 10,661 million was 1.8 times net income (depreciation 3,288, receivables decrease 2,979, inventory decrease 945, less payables decrease 4,124 and tax 2,365); H1 FY3/27 added JPY 4,705 million. The FUCHI and JS Tan acquisitions, rising dividends and the transformation were all funded without net borrowing. Payables and receivables swing JPY 3-4 billion between prints on project timing, so single-year conversion should not be annualized.
内部研究类型:CASH_MECHANISM
内部来源标记:COVERAGE35
普通股东含义(原始记录):The model self-funds its growth and distribution; cash-based valuation must use multi-year sums.
不确定性(原始记录):FY3/27 full-year operating cash flow against revised profit is not yet known.
F014|08|分红比例就是承诺,日元金额只是结果
研究范围:开放研究+35项覆盖检查
写入正文:08|分红比例就是承诺,日元金额只是结果14|资本配置与股东回报 6.2/10 分:分红规律清楚,回购和书面政策缺位
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Dividend record: JPY 54 (FY3/25) to JPY 69 (FY3/26), payout ratios of 40.1% and 39.7%怎么使用:直接 / 支持;一手验证:26
Equity walk and treasury: retained earnings compound; buybacks are historical, not current怎么使用:直接 / 支持;一手验证:25
Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated怎么使用:直接 / 支持;一手验证:26;专项深挖:26
The dividend-raise pattern: January 2026 lifted the FY3/26 year-end to JPY 44; November 2026 lifted both FY3/27 legs怎么使用:直接证据;一手验证:30;反向验证:26;专项深挖:30
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接证据;反向验证:23
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接证据
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 54 (FY3/25) to JPY 69 (FY3/26), payout ratios of 40.1% and 39.7%;直接证据 / 支持证据 / 一手证据(研究域25)|Equity walk and treasury: retained earnings compound; buybacks are historical, not current;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated;直接证据 / 一手证据(研究域30) / 反证(研究域26) / 定向深挖(研究域30)|The dividend-raise pattern: January 2026 lifted the FY3/26 year-end to JPY 44; November 2026 lifted both FY3/27 legs;直接证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals;直接证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75
完整研究记录(核对用)
研究原文:The return contract is a de facto rule, not a stated one: payout ratios of 40.1% (JPY 54), 39.7% (JPY 69) and a forecast 40.1% (JPY 75) across three years; year-end dividends raised at earnings prints (January 2026; November 2026 interim JPY 27, year-end JPY 48). Buybacks were effectively nil in FY3/26 despite net financial assets of about JPY 14.0 billion; treasury shares are 0.44% of issued; the last buyback was a 2023 ToSTNeT-3 purchase with cancellation. The board treats the ratio as the commitment and the yen amount as the residual; formalisation is a free catalyst not yet used. Forecast yield is 4.27%, covered about 1.9 times by recurring earnings.
内部研究类型:CAPITAL_RETURN_RULE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Income holders can underwrite the dividend; the buyback is unpriced optionality on top. No formal payout target was found.
不确定性(原始记录):Rule is behavioural; dividend per share is not affected by the recurring/reported distinction except through the formula.
F015|07|董事会像管理利润表一样管理股东名册
研究范围:35项覆盖检查
写入正文:07|董事会像管理利润表一样管理股东名册
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接 / 支持;反向验证:23
Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach怎么使用:直接 / 支持;一手验证:13、23
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接 / 支持;反向验证:24;专项深挖:24
查看完整证据标签(核对用)
直接证据 / 支持证据|Engagement instruments: a shareholder-benefit scheme introduced in 2026, repeated individual-investor seminars;直接证据 / 支持证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23)|Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach;直接证据 / 支持证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided
完整研究记录(核对用)
研究原文:The board is managing the register as deliberately as the P&L: two dividend raises in 2026, a revived shareholder-benefit scheme (introduced May 2026, a predecessor having been abolished in 2016), an audit-and-supervisory-committee transition with voluntary nomination and compensation committees (effective June 2026), and repeated individual-investor seminars. It is a coherent programme to broaden the marginal buyer base of a stock whose float cannot broaden by itself; if it works, a liquidity discount compresses independently of ROE.
内部研究类型:MANAGEMENT_BEHAVIOUR
内部来源标记:COVERAGE35
普通股东含义(原始记录):Spending effort on the register's composition, not only its returns, is evidence of intent toward re-rating.
不确定性(原始记录):Instruments are small in yen terms; effect on liquidity unproven.
F016|07|少数股东权益开始分走增长载体的利润
研究范围:35项覆盖检查
写入正文:07|少数股东权益开始分走增长载体的利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Non-controlling interests: from JPY 5 million to JPY 4,403 million in one year - the FUCHI and Rental System effect怎么使用:直接 / 支持;反向验证:25;专项深挖:25;同业比较:35;其他用途:历史
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域25) / 定向深挖(研究域25)|Non-controlling interests: from JPY 5 million to JPY 4,403 million in one year - the FUCHI and Rental System effect;直接证据 / 支持证据|FUCHI Pte. Ltd. (Singapore): from equity-method affiliate to 70%-owned consolidated subsidiary in August 2025;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025
完整研究记录(核对用)
研究原文:Non-controlling interests rose from JPY 5 million to JPY 4,403 million in FY3/26 (JPY 4,462 million at September 2026) on the FUCHI consolidation (30% minority) and the Rental System allotment (JPY 1,580 million paid in), and took JPY 107 million of FY3/26 and JPY 114 million of H1 FY3/27 net income, about 4% of group profit. Minorities sit in the two growth vehicles (Singapore, machinery).
内部研究类型:PER_SHARE_ATTRIBUTION
内部来源标记:COVERAGE35
普通股东含义(原始记录):Parent per-share growth will lag group growth while overseas and machinery vehicles outperform.
不确定性(原始记录):Future minority share depends on the growth vehicles' relative profit.
F017|08|市净率0.8倍的目标提前两年达成,一半靠账面、一半靠股价
研究范围:开放研究+35项覆盖检查
写入正文:08|市净率0.8倍的目标提前两年达成,一半靠账面、一半靠股价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接 / 支持;一手验证:13;外部现实校验:04、10
The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)怎么使用:直接 / 支持;反向验证:13;专项深挖:13
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 支持证据 / 反证(研究域13) / 定向深挖(研究域13)|The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026);直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;反证|FY3/2026 one-off layers: negative goodwill and a step-acquisition loss below the line, FX and compensation inside ordinary profit
完整研究记录(核对用)
研究原文:The mid-term plan's PBR target (at least 0.8 times by FY3/28) has effectively been met two years early: just under 0.5 times (September 2024), about 0.7 times (November 2025), 0.82 times (November 2026 aggregator snapshot). Book value per share rose from JPY 1,970 to JPY 2,119 to about JPY 2,144, so roughly half the re-rating was earned in the book and half in the price. The debate shifts from whether re-rating happens to whether ROE can be carried high enough to argue for parity (1.0 times); an early-met target raises the evidentiary weight, and the cost of missing, of the next target.
内部研究类型:CAPITAL_TARGET_DELIVERY
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Defines how much of the re-rating is behind the holder and what must now come from ROE evidence instead of multiple expansion.
不确定性(原始记录):Attribution between book growth and price is arithmetic from per-share book at different dates; 0.82 versus 0.83 reflects book basis.
F018|06|经常性净资产收益率只有7.8%,低于报告口径的8.5%
研究范围:35项覆盖检查
写入正文:06|经常性净资产收益率只有7.8%,低于报告口径的8.5%09|折价来自股东名册和资本回报,与盈利质量关系不大14|盈利质量、现金转化与资本效率 11.56/17 分:现金转化好,资本回报仍偏低
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%怎么使用:直接 / 支持;一手验证:22、28;专项深挖:22
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%怎么使用:直接证据;一手验证:22;反向验证:09;专项深挖:09
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 定向深挖(研究域22)|ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%;直接证据 / 支持证据|FY3/2026 consolidated results: record operating profit of JPY 8,012 million;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;直接证据 / 一手证据(研究域22) / 反证(研究域09) / 定向深挖(研究域09)|Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%
完整研究记录(核对用)
研究原文:Recurring ROE is lower than reported and rising into the forecast: about 7.8% for FY3/26 after removing one-off layers from the reported 8.5% (numerator from operating profit JPY 8,012 million taxed at 33.1%, about JPY 5.36 billion, on average equity of about JPY 68.8 billion), against 7.0% reported for FY3/25 and a forecast 8.73% for FY3/27. Segment returns on assets are 7.2% (heavy temporary) and 4.1% (machinery) on the ordinary basis. The level that decides the PBR argument is the high single digits, approached but not yet reached.
内部研究类型:CAPITAL_EFFICIENCY
内部来源标记:COVERAGE35
普通股东含义(原始记录):The discount to book is the market's verdict that recurring returns still trail the cost of equity; closing it requires ROE evidence.
不确定性(原始记录):Reported ROE (8.5%) vs recurring (7.8%) vs forecast (8.73%) are on different bases; ROIC by field and the cost of equity are not disclosed or estimated.
F019|09|折价来自股东名册和资本回报,与盈利质量关系不大
研究范围:35项覆盖检查
写入正文:09|折价来自股东名册和资本回报,与盈利质量关系不大14|估值与安全边际 10.8/15 分:个位数倍数,但安全边际比2025年薄
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit怎么使用:直接 / 支持;一手验证:27、31;反向验证:22;专项深挖:27、31
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接 / 支持;反向验证:24;专项深挖:24
ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%怎么使用:直接 / 支持;一手验证:22、28;专项深挖:22
Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion怎么使用:直接证据;一手验证:29;反向验证:21;专项深挖:29
Price cross-check: fiscal-year extremes from the exchange record agree with the local monthly series怎么使用:外部现实校验:27、31;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 反证(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit;直接证据 / 支持证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided;直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 定向深挖(研究域22)|ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%;直接证据 / 一手证据(研究域29) / 反证(研究域21) / 定向深挖(研究域29)|Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion;反证 / 外部现实(研究域27) / 外部现实(研究域31)|Price cross-check: fiscal-year extremes from the exchange record agree with the local monthly series
完整研究记录(核对用)
研究原文:The valuation discount is a register and ROE discount, not an earnings-quality discount: at 9.4 times forecast earnings, 0.82 times book and an enterprise value of about JPY 45.3 billion (about 4.9 times forecast operating profit; net of net financial assets of about JPY 14.0 billion), the market pays single-digit multiples for itemised earnings from a net-cash issuer because 60% of votes are anchored, float is thin and ROE still trails the return the market demands for parity. Value resolves into three additive pieces: the operating engine at a single-digit multiple, the financial sleeve at face value, and the optionality of capital formalisation and the next plan; the price pays for the first and part of the second.
内部研究类型:VALUATION_JUDGMENT
内部来源标记:COVERAGE35
普通股东含义(原始记录):Risk-reward is balanced-to-favourable for holders who can wait for two verdict prints; the discount has a mechanical expiry if recurring ROE reaches double digits or the sleeve is returned.
不确定性(原始记录):No target price or DCF is asserted; the multiple the market applies to FY3/27 and FY3/28 guidance is unknown.
F020|09|估值数字的口径各不相同,需要放在一起读
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论09|估值数字的口径各不相同,需要放在一起读14|估值与安全边际 10.8/15 分:个位数倍数,但安全边际比2025年薄15|数据截止日与主要来源
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接 / 支持;一手验证:06、18、19、20、21
Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition怎么使用:直接 / 支持;一手验证:18
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接 / 支持
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;直接证据 / 支持证据|FY3/2026 consolidated results: record operating profit of JPY 8,012 million;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 支持证据|FY3/2026 cash flow: operating inflow of JPY 10,661 million funds everything;直接证据 / 支持证据 / 一手证据(研究域18)|Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition;直接证据 / 支持证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75
完整研究记录(核对用)
研究原文:Valuation snapshot (price at the 6 November 2026 close; research cut-off 9 November 2026): price JPY 1,755; market capitalisation JPY 59.31 billion (x 33,795,746 issued shares); forecast PER 9.4x on revised FY3/27 EPS JPY 187.24; actual PBR 0.83x on FY3/26-end net assets per share JPY 2,118.51; ROE 8.5% (FY3/26 reported); forecast dividend yield 4.27% on JPY 75; EV/EBITDA 4.4x (EV JPY 50.19 billion = market cap less net cash JPY 9,124 million, i.e. cash and deposits 12,404 less borrowings 3,280 at 30 September 2026; EBITDA JPY 11,300 million = FY3/26 operating profit 8,012 plus depreciation 3,288).
内部研究类型:VALUATION_SNAPSHOT_WITH_BASIS
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Reference multiples at the review cut-off; each is a derived value whose basis must travel with it.
不确定性(原始记录):Bases differ across the map: PBR 0.83x uses FY3/26 book (JPY 2,118.51) while 0.82x uses September book (about JPY 2,144); EV/EBITDA 4.4x nets cash only and uses trailing EBITDA, whereas the EV of about JPY 45.3 billion nets securities too; share denominator is issued shares including 149,533 treasury shares (0.44%); PER is on a company forecast, not actual or consensus.
F021|07|两个大股东合计握有60%上下的表决权:名册稳定,流动性受限
研究范围:开放研究+35项覆盖检查
写入正文:07|两个大股东合计握有60%上下的表决权:名册稳定,流动性受限14|治理、所有权与管理层 4.06/7 分:自主权有行为证据,大股东意图无法判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接 / 支持;一手验证:01、23、24;外部现实校验:07
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接证据;反向验证:24;专项深挖:24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;直接证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided
完整研究记录(核对用)
研究原文:Control is anchored but not held: JFE Steel directly holds 27.63% and JFE Holdings 39.49% in aggregate, making GECOSS an equity-method affiliate, not a subsidiary; Mizuho Lease holds 20.04% as shareholder and capital-and-business alliance partner; positions are essentially unchanged since June 2024 (27.62% / 39.47% / 20.03%). Together the anchors hold about 60% of votes, leaving a free float of about 40% (roughly 13.6 million shares) and average daily traded value of only about JPY 92 million; margin short interest is effectively absent and beta is 0.53. Position entry and exit are multi-day exercises, and the price record's smoothness is partly a liquidity artefact.
内部研究类型:OWNERSHIP_REGISTER
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Liquidity, not control contests, is the ownership issue for outside holders until the day it is control.
不确定性(原始记录):Trust-bank and institutional holdings behind the anchors were not extracted; large-shareholding filings not read.
F022|07|JFE和Mizuho Lease诉求不同,议程仍在经营层手里
研究范围:35项覆盖检查
写入正文:07|JFE和Mizuho Lease诉求不同,议程仍在经营层手里14|治理、所有权与管理层 4.06/7 分:自主权有行为证据,大股东意图无法判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接 / 支持;一手验证:01、23、24;外部现实校验:07
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
Related-party texture: prior consultation on risk matters, own decisions, no material transactions noted怎么使用:直接证据;反向验证:01;专项深挖:01、23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据 / 支持证据|The pivot from revenue to profit: low-margin distribution sales suppressed from about 40% to about 25% of steel-material sales;直接证据 / 反证(研究域01) / 定向深挖(研究域01) / 定向深挖(研究域23)|Related-party texture: prior consultation on risk matters, own decisions, no material transactions noted
完整研究记录(核对用)
研究原文:The two anchors pull in different directions: JFE seeks a stable steel-value-chain affiliate (four secondees, shared steel customer and supplier relations); Mizuho Lease seeks a leasing partnership monetised through the machinery business and Rental System (one director, one secondee). The company says it consults and reports to both in advance on risk matters but decides independently, with no material transactions noted. The record since 2024 - a margin-first strategy neither anchor would naturally impose, executed without disclosed objection - supports that operating management is genuinely setting the agenda: a negotiated autonomy.
内部研究类型:GOVERNANCE_MECHANISM
内部来源标记:COVERAGE35
普通股东含义(原始记录):Governance is a tailwind for the capital thesis and the register's defining risk at once.
不确定性(原始记录):Inference from behavioural timing, not from board minutes; attribution of the capital turn to either anchor is not proven.
F023|07|Mizuho Lease可能是推动资本讨论的一方,目前只是时间上的相关
研究范围:35项覆盖检查
写入正文:07|Mizuho Lease可能是推动资本讨论的一方,目前只是时间上的相关08|近140亿日元的金融资产尚未动用,回购工具有先例
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
Related-party texture: prior consultation on risk matters, own decisions, no material transactions noted怎么使用:直接 / 支持;反向验证:01;专项深挖:01、23
Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales怎么使用:直接 / 支持;反向验证:03、07;专项深挖:07
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:一手验证:01、23、24;外部现实校验:07;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据 / 支持证据 / 反证(研究域01) / 定向深挖(研究域01) / 定向深挖(研究域23)|Related-party texture: prior consultation on risk matters, own decisions, no material transactions noted;直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域07) / 定向深挖(研究域07)|Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales;反证 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary
完整研究记录(核对用)
研究原文:Mizuho Lease is the register's plausible change agent: a leasing specialist holding 20.04%, co-invested inside Rental System and partnered in the machinery segment, has both incentive and vocabulary to press the capital questions (formalised payout, fleet returns, the unused buyback). The capital programme's acceleration dates from its April 2024 entry.
内部研究类型:CAUSAL_HYPOTHESIS
内部来源标记:COVERAGE35
普通股东含义(原始记录):If correct, the next phase of capital discipline has an identifiable sponsor on the register.
不确定性(原始记录):Timing correlation only; the counter-reading is that operating management originated the programme (see anchor tension). Alliance terms beyond disclosed structures are not public.
F024|07|大股东一次披露,就可能改写估值体系
研究范围:35项覆盖检查
写入正文:07|大股东一次披露,就可能改写估值体系11|大股东变动是低概率的体制性事件
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接 / 支持;一手验证:01、23、24;外部现实校验:07
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接 / 支持;反向验证:24;专项深挖:24
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 支持证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%
完整研究记录(核对用)
研究原文:Anchor risk is low-probability and total: a JFE decision to consolidate or sell, or a Mizuho decision to exit, would re-rate the stock violently in one disclosure, and the same thin float that smooths ordinary trading would make any anchor-sized flow disorderly. Nothing in the record suggests movement and nothing would precede it but a disclosure.
内部研究类型:REGISTER_REGIME_RISK
内部来源标记:COVERAGE35
普通股东含义(原始记录):A regime event rather than a trade, in either direction.
不确定性(原始记录):Probability cannot be estimated from public information.
F025|01|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上02|利润集中在一个板块:重型临时工程占分部毛利润的95%以上14|商业结构、产品、客户与关键依赖 6.6/11 分:业务量有保证,利润依赖单一板块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Segment profit concentration: heavy temporary works earns about 96% of gross segment profit怎么使用:直接 / 支持;一手验证:02、16;反向验证:08;专项深挖:02、08
FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields怎么使用:直接 / 支持;一手验证:02、03、05、08、09、10、15
Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%怎么使用:直接证据;一手验证:03、04、08、11;专项深挖:03
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:支持证据;一手验证:04、07
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域16) / 反证(研究域08) / 定向深挖(研究域02) / 定向深挖(研究域08)|Segment profit concentration: heavy temporary works earns about 96% of gross segment profit;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域15)|FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields;直接证据 / 支持证据|H1 FY3/2027 segments: heavy temporary works JPY 4,403 million of ordinary-basis profit; machinery profit up 34% on used-asset sales;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域11) / 定向深挖(研究域03)|Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%;支持证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)
完整研究记录(核对用)
研究原文:Profit concentration is extreme and disclosed: heavy temporary works supplies about 95.7% (FY3/26) and 95.2% (H1 FY3/27) of gross segment profit (ordinary basis: JPY 8,604 million and JPY 4,403 million versus machinery JPY 391 million and JPY 220 million), and holds JPY 119,607 million of JPY 122,537 million of total assets. The machinery segment's H1 improvement leaned partly on used-asset sales, and the overseas cluster's contribution is undisclosed. Diversification is by field (materials 62,039 flat; works 30,039 +17.6%; fabrication 11,565 -5.2%) and geography inside one segment, not across segments: the group is for profit purposes a single segment's pricing discipline.
内部研究类型:STRUCTURAL_FRAGILITY
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The thesis is a single engine; monitoring belongs at segment level, not group level.
不确定性(原始记录):Shares are on the ordinary-profit basis and gross of the consolidation adjustment; no finer revenue split of the materials field (rental versus sale).
F026|06|建设机械:需求不构成约束,资本回报才是
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%怎么使用:直接 / 支持;一手验证:22;反向验证:09;专项深挖:09
Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales怎么使用:直接 / 支持;反向验证:03、07;专项深挖:07
FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields怎么使用:直接 / 支持;一手验证:02、03、05、08、09、10、15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 定向深挖(研究域09)|Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%;直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域07) / 定向深挖(研究域07)|Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域15)|FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields
完整研究记录(核对用)
研究原文:Heavy temporary works earns a 7.2% ordinary return on segment assets of JPY 119,607 million, while construction machinery earns 4.1% on JPY 9,534 million (2.6% margin on JPY 14,765 million of sales) and consumes JPY 1,746 million, over half, of group depreciation of JPY 3,288 million. The fleet (JPY 4,065 million net at FY3/26, JPY 3,715 million at September 2026) is being optimised by replacement and used-asset sales; machinery is where capital productivity, not demand, is the constraint, and the Mizuho / Rental System alliance (September 2025) is aimed at exactly this.
内部研究类型:CAPITAL_PRODUCTIVITY_PROBLEM
内部来源标记:COVERAGE35
普通股东含义(原始记录):Small segment (about 4% of gross segment profit) but the one place the group admitted an outside co-owner; improvement would lift group ROE at the margin.
不确定性(原始记录):End-state fleet size, utilisation and alliance economics undisclosed; segment returns are ordinary-basis.
F027|01|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上01|两次业绩披露之间,论点怎样被确认14|总分68.05/100,评级B+:基本面扎实,估值与价格都已部分兑现
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items怎么使用:直接 / 支持
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接 / 支持
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接 / 支持;一手验证:13;外部现实校验:04、10
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接证据;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high怎么使用:一手验证:05、10、11、12、14;其他用途:反证
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:一手验证:01、23、24;外部现实校验:07;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items;直接证据 / 支持证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 支持证据|Forecast arithmetic: the revised FY3/27 plan requires a second-half operating profit of JPY 5,010 million, +17% on the prior second half;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;反证 / 一手证据(研究域05) / 一手证据(研究域10) / 一手证据(研究域11) / 一手证据(研究域12) / 一手证据(研究域14)|Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high;反证 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary
完整研究记录(核对用)
研究原文:GECOSS is a margin transformation compounding inside an anchored register: a company that deliberately shrank revenue to clean its mix now converts it into record operating profit (JPY 8,012 million, then JPY 9,200 million forecast), funds a 40%-payout dividend yielding 4.27% from a near-debt-free balance sheet, and has just crossed the 0.8-times-book target at 0.82 times. It works if the implied second half is delivered (operating profit JPY 5,010 million, +17%, flat sales), the FY3/28 guidance in May 2027 carries the margin programme and capital questions into the plan's final year, and the price holds its 2025-2026 breakout. It fails if the margin programme stalls (cost inflation outpacing price adequacy), or if either anchor's stance changes the company's status. Risk-reward at the review date is balanced-to-favourable for patient holders and is not a momentum proposition.
内部研究类型:THESIS
内部来源标记:OPEN_DISCOVERY / TECHNICAL
普通股东含义(原始记录):The adjudicated investment judgment; conditional on dated verdicts, not a forecast of the construction cycle.
不确定性(原始记录):Counter-evidence: the loss-order provision, fixed-price exposure and the unproven overseas contribution; the thesis's technical clause refers to the protected Technical structure and does not alter it.
F028|01|两次业绩披露之间,论点怎样被确认
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|两次业绩披露之间,论点怎样被确认11|什么会推翻这个判断14|总分68.05/100,评级B+:基本面扎实,估值与价格都已部分兑现
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接证据;一手验证:35;反向验证:12、30;专项深挖:16、35
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接证据;一手验证:35
Disclosure calendar: the dated verdicts ahead怎么使用:直接证据;一手验证:30;反向验证:35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed;直接证据 / 一手证据(研究域30) / 反证(研究域35)|Disclosure calendar: the dated verdicts ahead
完整研究记录(核对用)
研究原文:Fundamental kill set: the implied second half misses widely (margin-programme ceiling), the loss-order provision grows, the FY3/28 framework abandons the capital programme, or an anchor changes the company's status. Confirm set: FY3/27 delivered at or above JPY 9,200 million operating profit and a successor framework with numeric ROE and return commitments. Early warning signs: two consecutive quarters of field contraction, a growing loss-order provision, or an anchor-shareholder filing. Confirmation is provisional: delivery re-opens the question at FY3/28's mix and costs. Price-structure confirmation and failure levels live in the protected Technical structure and are not restated here. Excluded upsides: fleet utilisation economics, land value; unsized: the overseas cluster's profit. The falsification window closes with the May 2027 print.
内部研究类型:FALSIFICATION_AND_CONFIRMATION_SET
内部来源标记:COVERAGE35
普通股东含义(原始记录):Lets the Thesis be held to its own standard: two prints decide it.
不确定性(原始记录):The first failing signpost, if any, is unknown.
F029|11|催化剂:从现在到2027年5月,只有一次业绩检验
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|催化剂:从现在到2027年5月,只有一次业绩检验13|十个未决问题多数只能等披露来回答15|证据的限制:哪些事实尚未核实,会怎样限制判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Disclosure calendar: the dated verdicts ahead怎么使用:直接 / 支持;一手验证:30;反向验证:35
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接 / 支持;一手验证:35;反向验证:12、30;专项深挖:16、35
The dividend-raise pattern: January 2026 lifted the FY3/26 year-end to JPY 44; November 2026 lifted both FY3/27 legs怎么使用:直接 / 支持;一手验证:30;反向验证:26;专项深挖:30
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接 / 支持
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接 / 支持;一手验证:13;外部现实校验:04、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 反证(研究域35)|Disclosure calendar: the dated verdicts ahead;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据 / 支持证据 / 一手证据(研究域30) / 反证(研究域26) / 定向深挖(研究域30)|The dividend-raise pattern: January 2026 lifted the FY3/26 year-end to JPY 44; November 2026 lifted both FY3/27 legs;直接证据 / 支持证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;支持证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items
完整研究记录(核对用)
研究原文:Nearest dated verdicts: the JPY 27 interim dividend payable from 1 December 2026; the Q3 FY3/27 tanshin (late January to early February 2027; Q3 FY3/26 was 29 January 2026, external calendars point to 2 February 2027), which prints the first quarter of the implied second half against the 8.2% margin requirement, shows whether contract liabilities and the works field keep building, and may carry a year-end dividend adjustment on the January 2026 precedent; the FY3/27 full-year print in May 2027, which delivers the plan's second-year score, FY3/28 guidance for the plan's final year and the JPY 48 year-end dividend; the June 2027 AGM. Between this review and May there is exactly one earnings verdict.
内部研究类型:CATALYST_CALENDAR
内部来源标记:COVERAGE35
普通股东含义(原始记录):Position timing should be built around the two prints rather than the tape of a thin-float stock.
不确定性(原始记录):Dates are patterned expectations, not confirmed; unscheduled catalysts (anchor filings, large orders, M&A) cannot be calendared.
F030|08|近140亿日元的金融资产尚未动用,回购工具有先例
研究范围:35项覆盖检查
写入正文:08|近140亿日元的金融资产尚未动用,回购工具有先例11|最便宜的催化剂:把分红行为变成书面承诺14|资本配置与股东回报 6.2/10 分:分红规律清楚,回购和书面政策缺位
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated怎么使用:直接 / 支持;一手验证:26;专项深挖:26
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接 / 支持;反向验证:23
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接 / 支持;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated;直接证据 / 支持证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals;直接证据 / 支持证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed
完整研究记录(核对用)
研究原文:Formalisation is the cheapest available catalyst: a stated payout ratio or DOE floor, a first buyback authorisation or treasury cancellation, or publication of the mid-term plan's final-year numerical targets would each convert observed behaviour into commitment; the May 2027 print, which sets FY3/28 guidance for the plan's last year, is the natural venue for all three.
内部研究类型:CATALYST_OPTION
内部来源标记:COVERAGE35
普通股东含义(原始记录):Unpriced upside in the board's gift that does not require better operating numbers.
不确定性(原始记录):The board may choose not to formalise; absence of numbers would itself be the answer.
F031|09|最坏情形是估值问题,不是偿债问题
研究范围:35项覆盖检查
写入正文:09|最坏情形是估值问题,不是偿债问题14|财务韧性与下行防御 11.05/13 分:几乎无负债,下行是估值问题
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion怎么使用:直接证据;一手验证:29;反向验证:21;专项深挖:29
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接证据;一手验证:21、29;反向验证:20;专项深挖:18、21
Historical turning points: the FY3/15 spike year, the FY3/22-23 trough, the FY3/25 pivot怎么使用:直接证据;一手验证:33;专项深挖:12、33、34;同业比较:01、02、03、04、05、06、07、08、09、10、11、12、13、14、15、16、17、18、19、20、21、22、23、24、25、26、28、29、30、32、34;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域29) / 反证(研究域21) / 定向深挖(研究域29)|Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion;直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域05) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域34) / 定向深挖(研究域12) / 定向深挖(研究域33) / 定向深挖(研究域34)|Historical turning points: the FY3/15 spike year, the FY3/22-23 trough, the FY3/25 pivot
完整研究记录(核对用)
研究原文:Downside is built from asset and income absorbers, not leverage: book equity JPY 72,128 million against about JPY 59.3 billion market capitalisation; net financial assets about JPY 14.0 billion; JPY 75 dividend covered about 1.9 times by recurring earnings and raised at each of the last two revision points; and a demand base that carried the worst recent year (FY3/23 ordinary profit JPY 4,903 million) to a smaller profit, not a loss. A digestion year at trough multiples of trough recurring earnings could plausibly cost about a third of the price, but not the position on observed precedent. There is effectively no debt to amplify a downturn.
内部研究类型:DOWNSIDE_PROTECTION
内部来源标记:COVERAGE35
普通股东含义(原始记录):The bad case is a valuation case rather than a solvency case.
不确定性(原始记录):Scenario probabilities are not asserted; inventory and land are carried at book/cost with no haircut analysis, and the fleet's realisable value is unknown.
F032|10|回撤精确停在旧上沿:压力位变成了支撑位
写入正文:10|回撤精确停在旧上沿:压力位变成了支撑位10|2026年的高点没有出现2015年那样的高潮放量10|当前状态:突破成立、仍在消化,高度与买盘之间有一处矛盾15|数据截止日与主要来源
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Locally recomputed monthly series: span, extremes and basis怎么使用:直接证据;一手验证:34
Averages and position at the October 2026 partial close: above all three averages, at 88.8% of the life range怎么使用:直接 / 支持;反向验证:27、29、31
The first life: 2001-2013 base, the September 2014 spike to JPY 1,940, and the 2015 collapse怎么使用:直接 / 支持;同业比较:27、31、33;其他用途:历史
The long residence (2015-2024) and the 2025-2026 breakout through the 2014 ceiling怎么使用:直接 / 支持;一手验证:34;反向验证:33
Volume structure: the 2026 highs were made on ordinary volume, far below the 2015 climax怎么使用:直接 / 支持;反向验证:34
Price cross-check: fiscal-year extremes from the exchange record agree with the local monthly series怎么使用:外部现实校验:27、31;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域34)|Locally recomputed monthly series: span, extremes and basis;直接证据 / 支持证据 / 反证(研究域27) / 反证(研究域29) / 反证(研究域31)|Averages and position at the October 2026 partial close: above all three averages, at 88.8% of the life range;直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域31) / 历史/同业比较(研究域33)|The first life: 2001-2013 base, the September 2014 spike to JPY 1,940, and the 2015 collapse;直接证据 / 支持证据 / 一手证据(研究域34) / 反证(研究域33)|The long residence (2015-2024) and the 2025-2026 breakout through the 2014 ceiling;直接证据 / 支持证据 / 反证(研究域34)|Volume structure: the 2026 highs were made on ordinary volume, far below the 2015 climax;反证 / 外部现实(研究域27) / 外部现实(研究域31)|Price cross-check: fiscal-year extremes from the exchange record agree with the local monthly series
完整研究记录(核对用)
研究原文:Three price-structure Claims are retained as stated by Research without restating the Technical Synthesis: (a) the June 2026 retracement low of JPY 1,443 landed on the 2015-2024 residence top that the 2025 close of JPY 1,451 first exceeded, read as the ceiling retested as a floor, unlike 2014's first pullback which was never stopped; (b) the 2026 advance's heaviest month (March 2026, 1,998,900 shares) was about 59% of the April 2015 distribution climax (3,391,600) with twelve-month volume up 14.8%, so the advance has not yet printed a distribution signature; (c) at 88.8% of life range, above 97.4% of monthly closes and all three averages but only 9.0% below the highest close, the chart reads as a held verdict awaiting the earnings prints. The authoritative Pure Technical Truth is the protected structure.
内部研究类型:CLAIM_LEVEL_PRICE_OBSERVATIONS
内部来源标记:TECHNICAL
普通股东含义(原始记录):Gives the reader the price context for the dated earnings verdicts; does not stand in for Technical State.
不确定性(原始记录):Claims are inferences from monthly bars (weekly structure not supplied; October 2026 bar partial); they may not be used to rewrite the protected Technical structure.
F033|04|JFE集团:39.49%的大股东,同时也是公司的钢材来源、钢构原料和客户
研究范围:开放研究
写入正文:04|JFE集团:39.49%的大股东,同时也是公司的钢材来源、钢构原料和客户
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07
FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields怎么使用:直接证据;一手验证:02、03、05、08、09、10、15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域15)|FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields
完整研究记录(核对用)
研究原文:JFE Holdings / JFE Steel: anchor shareholder group (27.63% direct; 39.49% aggregate), equity-method parent-side related company; four JFE Steel secondees; steel is simultaneously the company's material input, fabrication feedstock and part of its customer base.
内部研究类型:RELATED_ENTITY
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Explains register stability and steel-cycle linkage.
不确定性(原始记录):Future JFE intentions unknown.
F034|04|Mizuho Lease:2024年4月入股的20.04%股东,也是机械业务的合作方
研究范围:开放研究
写入正文:04|Mizuho Lease:2024年4月入股的20.04%股东,也是机械业务的合作方
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接证据;一手验证:07;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据|H1 FY3/2027 segments: heavy temporary works JPY 4,403 million of ordinary-basis profit; machinery profit up 34% on used-asset sales
完整研究记录(核对用)
研究原文:Mizuho Lease (8425): 20.04% holder since the April 2024 capital and business alliance; co-investor in Rental System (JPY 1,580 million paid in during FY3/26); partner in the September 2025 three-way machinery alliance; one director concurrently on the GECOSS board and one secondee.
内部研究类型:RELATED_ENTITY
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Capital and channel at once; plausible source of financial-owner discipline.
不确定性(原始记录):Alliance contractual depth and economics undisclosed.
F035|04|FUCHI与Rental System:把海外和机械做成了有外部共同股东的载体
研究范围:开放研究+35项覆盖检查
写入正文:04|FUCHI与Rental System:把海外和机械做成了有外部共同股东的载体
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FUCHI step-acquisition mechanics: how one deal produced both a JPY 401 million gain and a JPY 418 million loss怎么使用:直接证据;一手验证:32;专项深挖:32
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:直接证据;一手验证:04、07
查看完整证据标签(核对用)
直接证据|FUCHI Pte. Ltd. (Singapore): from equity-method affiliate to 70%-owned consolidated subsidiary in August 2025;直接证据 / 一手证据(研究域32) / 定向深挖(研究域32)|FUCHI step-acquisition mechanics: how one deal produced both a JPY 401 million gain and a JPY 418 million loss;直接证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)
完整研究记录(核对用)
研究原文:FUCHI Pte. Ltd. (Singapore): acquired as an equity-method affiliate in 2023, consolidated at 70% in August 2025 with two subsidiaries, booking a JPY 401 million negative-goodwill gain and a JPY 418 million step-acquisition loss from one transaction (net about -JPY 17 million). The group bought control of an operating platform for less than net asset value while writing down its earlier stake, consistent with bargain discipline; its entry also explains part of the equity-method line's swing.
内部研究类型:RELATED_ENTITY
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Converts the overseas story from a stake into an operation inside the profit-earning segment.
不确定性(原始记录):Profit contribution not separately disclosed.
F036|04|FUCHI与Rental System:把海外和机械做成了有外部共同股东的载体
研究范围:开放研究
写入正文:04|FUCHI与Rental System:把海外和机械做成了有外部共同股东的载体
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接证据;一手验证:07;外部现实校验:23
Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition怎么使用:直接证据;一手验证:18
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据|FY3/2026 cash flow: operating inflow of JPY 10,661 million funds everything;直接证据 / 一手证据(研究域18)|Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition
完整研究记录(核对用)
研究原文:Rental System Co., Ltd.: consolidated construction-machinery rental vehicle, party to the three-way alliance; its third-party allotment lifted non-controlling interests from JPY 5 million to over JPY 4.4 billion in FY3/26.
内部研究类型:RELATED_ENTITY
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The structural experiment in sharing the asset-heavy rental model with a leasing specialist.
不确定性(原始记录):Vehicle-level returns undisclosed.
F037|02|新加坡与越南业务:以选择权看待,利润无法核实
研究范围:开放研究+35项覆盖检查
写入正文:02|新加坡与越南业务:以选择权看待,利润无法核实
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:直接证据;一手验证:04、07
The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin怎么使用:直接证据;反向验证:04;专项深挖:04
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October);直接证据 / 反证(研究域04) / 定向深挖(研究域04)|The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin;直接证据|FUCHI Pte. Ltd. (Singapore): from equity-method affiliate to 70%-owned consolidated subsidiary in August 2025
完整研究记录(核对用)
研究原文:The Singapore platform: FUCHI (heavy temporary works, 70%), JS Tan Consultants (construction consultancy, consolidated July 2026, JPY 708 million cash outflow, goodwill from JPY 806 million to JPY 1,494 million) and Gecoss Vietnam (temporary-works design), assembled for mutual synergy. Its balance-sheet mass (goodwill plus the 30% minority, about JPY 6 billion together) is measurable but its revenue and profit are not disclosed by geography; two Singapore additions in fourteen months were at bargain-accounted prices. It is carried as optionality, not as earnings. The one domain that could not be integrated across lanes is this cluster's profit: the accounts disclose its mass but not its earnings, and the price record cannot price what the accounts do not disclose.
内部研究类型:GROWTH_OPTION_WITH_OPACITY
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Growth option inside the core segment, whose size shareholders cannot verify; exposure if Singapore construction slows is unknown.
不确定性(原始记录):Geographic information in the securities report was not read; contribution can be bounded only by balance-sheet mass.
F038|04|Nihon Kiso Gijutsu:不投入资本的相邻业务提携
研究范围:开放研究
写入正文:04|Nihon Kiso Gijutsu:不投入资本的相邻业务提携
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:直接证据;一手验证:04、07
Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%怎么使用:直接证据;一手验证:03、04、08、11;专项深挖:03
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October);直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域11) / 定向深挖(研究域03)|Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%
完整研究记录(核对用)
研究原文:Nihon Kiso Gijutsu Co., Ltd.: specialist contractor in obstacle removal and ground improvement; business alliance concluded October 2026 to strengthen existing operations and create business adjacent to the temporary-works core without capital commitment.
内部研究类型:RELATED_ENTITY
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Extends works capability asset-light, signalling the growth vector management prefers.
不确定性(原始记录):Terms and contribution undisclosed; alliance is two months old.
F039|03|需求来自首都圈再开发和公共工程,业务量有保证,利润由定价决定
研究范围:开放研究
写入正文:03|需求来自首都圈再开发和公共工程,业务量有保证,利润由定价决定
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high怎么使用:直接证据;一手验证:05、10、11、12、14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 一手证据(研究域11) / 一手证据(研究域12) / 一手证据(研究域14)|Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high;直接证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items
完整研究记录(核对用)
研究原文:Japanese construction investment: public-works demand is stable, private capital spending recovering, and the company's territory centres on large Tokyo-metropolitan redevelopment with smooth starts and progress in both FY3/26 and H1 FY3/27; the same filings name tight labour supply, high construction costs and individual projects revised, cancelled or postponed. Volume is available; margin is decided by pricing discipline.
内部研究类型:END_MARKET
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The equity is a derivative on Japanese construction investment with a pricing-discipline overlay.
不确定性(原始记录):Duration of the capital-region redevelopment wave and order backlog unknown; no market-size figure asserted.
F040|03|钢铁行业同时是供应商、客户和股东
研究范围:开放研究+35项覆盖检查
写入正文:03|钢铁行业同时是供应商、客户和股东
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields怎么使用:直接证据;一手验证:02、03、05、08、09、10、15
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接证据;一手验证:06、18、19、20、21
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07
Steel-cycle frame: the parent industry is customer, supplier and shareholder at once怎么使用:直接证据;一手验证:14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域15)|FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields;直接证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 一手证据(研究域14)|Steel-cycle frame: the parent industry is customer, supplier and shareholder at once
完整研究记录(核对用)
研究原文:Japanese steel industry: dual exposure. As supplier, the rental fleet (JPY 28,591 million, 24% of sales) is a steel-price exposure whose replacement cost rises with the market, partly recoverable through rental pricing; as customer, steel fabrication and bridges (JPY 11,565 million) and mill-related works depend on steel and infrastructure investment; as shareholder, JFE holds 39.49%. A steel downturn reaches the P&L through fabrication volumes first and fleet economics second; a price rise alone is near neutral-to-positive for a fleet owner who can re-price.
内部研究类型:END_MARKET_AND_INPUT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Partly self-hedging on price, wholly exposed on steel volumes and mill capex.
不确定性(原始记录):No steel-price sensitivity disclosed; mapping is structural.
F041|08|东证的资本成本要求是外部时钟,中期计划是内部尺子
研究范围:开放研究+35项覆盖检查
写入正文:08|东证的资本成本要求是外部时钟,中期计划是内部尺子
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接证据;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach怎么使用:直接证据;一手验证:13、23
The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)怎么使用:直接证据;反向验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;直接证据 / 一手证据(研究域13) / 一手证据(研究域23)|Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach;直接证据 / 反证(研究域13) / 定向深挖(研究域13)|The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)
完整研究记录(核对用)
研究原文:TSE Prime cost-of-capital framework: the company published its response in October 2024 and set the PBR target in the mid-term plan; the framework is the external, dated clock that converted an anchored register into a margin, dividend and engagement programme. Its next demand (a credible path above book value) is harder than the one just met, and the tailwind is rented rather than owned.
内部研究类型:POLICY_ACTOR
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Exchange pressure ratchets: meeting 0.8 times invites the question of 1.0 times and the ROE to justify it.
不确定性(原始记录):The October 2024 response document's text was not captured.
F042|08|东证的资本成本要求是外部时钟,中期计划是内部尺子
研究范围:开放研究+35项覆盖检查
写入正文:08|东证的资本成本要求是外部时钟,中期计划是内部尺子
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接证据;一手验证:35
The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)怎么使用:直接证据;反向验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed;直接证据 / 反证(研究域13) / 定向深挖(研究域13)|The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)
完整研究记录(核对用)
研究原文:Mid-term management plan FY3/26-FY3/28 (announced 26 March 2025): operating profit is the headline KPI; PBR of at least 0.8 times by FY3/28 (met); growth investment of up to about JPY 25 billion over three years including M&A, deployed so far through FUCHI, JS Tan, land and fleet and factory investment, well inside the envelope. Operating profit is tracking +34% over two years (JPY 6,851 million to forecast JPY 9,200 million). The plan's final-year numerical sales and operating-profit targets were not captured. Plan expiry is itself a catalyst date.
内部研究类型:PLAN_FRAMEWORK
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The May 2027 guidance is the first verdict on whether the framework renews with harder numbers.
不确定性(原始记录):Final-year targets unread; most of the JPY 25 billion envelope remains undeployed.
F043|11|催化剂:从现在到2027年5月,只有一次业绩检验
研究范围:开放研究
写入正文:11|催化剂:从现在到2027年5月,只有一次业绩检验13|最优先的三个问题:下半年能否交付,毛利率有没有天花板,接替框架给不给数字
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接证据;一手验证:35;反向验证:12、30;专项深挖:16、35
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接证据;反向验证:05、11;专项深挖:05、11
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据|Forecast arithmetic: the revised FY3/27 plan requires a second-half operating profit of JPY 5,010 million, +17% on the prior second half;直接证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set
完整研究记录(核对用)
研究原文:Will the implied second half of FY3/27 deliver? The revised plan requires second-half operating profit of JPY 5,010 million (+17.0%) on essentially flat sales of JPY 60,905 million; what do Q3 order intake, project progress rates and the gross margin on work completing in the second half say by the Q3 tanshin?
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Resolution decides whether the November revision becomes a credibility asset or reopens the margin-ceiling question.
不确定性(原始记录):Resolved by the Q3 tanshin (late January / early February 2027) and the May 2027 full-year print; the opposite answer weakens the margin story; no reasonable current public path exists before then.
F044|06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证
研究范围:开放研究
写入正文:06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证13|最优先的三个问题:下半年能否交付,毛利率有没有天花板,接替框架给不给数字
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%怎么使用:直接证据;一手验证:16
Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure怎么使用:直接证据;反向验证:06、14;专项深挖:06、14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域16)|Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%;直接证据 / 反证(研究域06) / 反证(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure;直接证据|Distribution-sales suppression in detail: the FY3/25 revenue fall of JPY 16.6 billion was the policy, not the market
完整研究记录(核对用)
研究原文:Is the gross-margin programme still compounding or approaching its ceiling? Gross margin has risen 20.9% to 22.9% to 23.5%; what remains available from price adequacy and mix, and what happens if construction-cost inflation re-accelerates?
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Determines whether operating profit growth is a staircase or a one-time reset.
不确定性(原始记录):Resolved by FY3/27 full-year gross and segment margins; whether gross margin can hold above 23% under renewed cost inflation is unknown.
F045|13|第二层问题:计划目标、分红规则和闲置的回购
研究范围:开放研究
写入正文:13|第二层问题:计划目标、分红规则和闲置的回购15|证据的限制:哪些事实尚未核实,会怎样限制判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed
完整研究记录(核对用)
研究原文:What are the mid-term plan's actual final-year (FY3/28) numerical targets for sales and operating profit, and will May 2027 guidance be set against them or quietly replace them? The plan document's targets were not captured and must be read from the original.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Without the targets the plan scoreboard is built only from filing-visible items.
不确定性(原始记录):The original plan document is the evidence that would resolve it; it was not retrieved in this research.
F046|08|近140亿日元的金融资产尚未动用,回购工具有先例
研究范围:开放研究
写入正文:08|近140亿日元的金融资产尚未动用,回购工具有先例13|第二层问题:计划目标、分红规则和闲置的回购
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated怎么使用:直接证据;一手验证:26;专项深挖:26
Equity walk and treasury: retained earnings compound; buybacks are historical, not current怎么使用:直接证据;一手验证:25
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接证据;反向验证:23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated;直接证据 / 一手证据(研究域25)|Equity walk and treasury: retained earnings compound; buybacks are historical, not current;直接证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals
完整研究记录(核对用)
研究原文:Will the de facto 40% payout rule be formalised - as a stated payout ratio, a DOE floor or a total-return framework including buybacks - now that the PBR 0.8-times target is met? Buybacks were effectively nil in FY3/26 despite a net-cash balance sheet.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Formalisation converts behaviour into commitment and could compress the register discount.
不确定性(原始记录):May 2027 announcements are the first venue; the 2024 cost-of-capital response text was not captured.
F047|02|新加坡与越南业务:以选择权看待,利润无法核实
研究范围:开放研究+35项覆盖检查
写入正文:02|新加坡与越南业务:以选择权看待,利润无法核实13|第三层问题:海外规模、亏损准备金、大股东和设备利用率15|证据的限制:哪些事实尚未核实,会怎样限制判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin怎么使用:直接证据;反向验证:04;专项深挖:04
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:直接证据;一手验证:04、07
查看完整证据标签(核对用)
直接证据 / 反证(研究域04) / 定向深挖(研究域04)|The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin;直接证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October);直接证据|FUCHI Pte. Ltd. (Singapore): from equity-method affiliate to 70%-owned consolidated subsidiary in August 2025
完整研究记录(核对用)
研究原文:How large is the overseas cluster really? FUCHI, JS Tan and Gecoss Vietnam sit inside the heavy-temporary segment with no separate revenue or profit disclosure; what do they contribute, and what is the group's exposure if Singapore construction slows?
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The growth option cannot be sized or priced until geographic disclosure appears.
不确定性(原始记录):Securities-report geographic information was not read; bounded only by goodwill and minority footprints.
F048|06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证
研究范围:开放研究
写入正文:06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证13|第三层问题:海外规模、亏损准备金、大股东和设备利用率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接证据;一手验证:06、18、19、20、21
Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales怎么使用:直接证据;反向验证:03、07;专项深挖:07
Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure怎么使用:直接证据;反向验证:06、14;专项深挖:06、14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 反证(研究域03) / 反证(研究域07) / 定向深挖(研究域07)|Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales;直接证据 / 反证(研究域06) / 反证(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure
完整研究记录(核对用)
研究原文:What does the JPY 314 million provision for loss on orders attach to - one contract or a class - and does the machinery segment's fleet-optimisation model (profit partly from used-asset sales) have a disclosed end-state fleet size?
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Bears on whether pricing discipline is systematic and on machinery profit quality.
不确定性(原始记录):Movement in the provision at Q3 and full year and the FY3/27 securities report notes would resolve it.
F049|13|第三层问题:海外规模、亏损准备金、大股东和设备利用率
研究范围:开放研究
写入正文:13|第三层问题:海外规模、亏损准备金、大股东和设备利用率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接证据;反向验证:24;专项深挖:24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided
完整研究记录(核对用)
研究原文:Does the dual-anchor structure ever change? JFE Holdings at 39.49% and Mizuho Lease at 20.04% have been static since 2024; any movement - consolidation by JFE, an increase or exit by Mizuho - would rewrite the register, float and valuation regime at once.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Binary regime risk and potential catalyst.
不确定性(原始记录):Large-shareholding filings and the June 2027 controlling-shareholder notice would show it; probability not estimable.
F050|13|第三层问题:海外规模、亏损准备金、大股东和设备利用率
研究范围:开放研究+35项覆盖检查
写入正文:13|第三层问题:海外规模、亏损准备金、大股东和设备利用率
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
The rental asset base: JPY 28,244 million of steel materials and JPY 33,133 million of inventories fund the model怎么使用:直接证据;一手验证:09、20;反向验证:10;专项深挖:10、20
Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%怎么使用:直接证据;一手验证:22;反向验证:09;专项深挖:09
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域09) / 一手证据(研究域20) / 反证(研究域10) / 定向深挖(研究域10) / 定向深挖(研究域20)|The rental asset base: JPY 28,244 million of steel materials and JPY 33,133 million of inventories fund the model;直接证据 / 一手证据(研究域22) / 反证(研究域09) / 定向深挖(研究域09)|Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%
完整研究记录(核对用)
研究原文:What is the utilisation and replacement economics of the rental steel fleet (JPY 28,591 million)? No utilisation rate or fleet-age disclosure was found; without it the return on the group's largest operating asset can only be inferred from segment profit (7.2% ordinary return on segment assets).
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The fleet is the equity claim's core; its true returns, replacement cost under steel inflation and any unrealised value are unquantified.
不确定性(原始记录):Only company disclosure or industry data could resolve it; none found in the sources read.
F051|08|近140亿日元的金融资产尚未动用,回购工具有先例
研究范围:开放研究+35项覆盖检查
写入正文:08|近140亿日元的金融资产尚未动用,回购工具有先例13|最优先的三个问题:下半年能否交付,毛利率有没有天花板,接替框架给不给数字
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接证据;一手验证:35
Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated怎么使用:直接证据;一手验证:26;专项深挖:26
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed;直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated
完整研究记录(核对用)
研究原文:What numerical commitments will the successor framework carry when the mid-term plan ends - final-year and next-plan targets for operating profit, ROE, payout formalisation and the balance sheet's end-state (a target equity ratio or net-financial-asset level)? The FY3/27 results announcement in May 2027 is the first venue; absence of numbers would itself be the answer.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Decides whether the re-rating continues on ROE evidence beyond the met 0.8-times target.
不确定性(原始记录):Future disclosure; no current public path.
F052|08|近140亿日元的金融资产尚未动用,回购工具有先例
研究范围:开放研究+35项覆盖检查
写入正文:08|近140亿日元的金融资产尚未动用,回购工具有先例13|第二层问题:计划目标、分红规则和闲置的回购
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Equity walk and treasury: retained earnings compound; buybacks are historical, not current怎么使用:直接证据;一手验证:25
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接证据;反向验证:23
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接证据;一手验证:21、29;反向验证:20;专项深挖:18、21
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域25)|Equity walk and treasury: retained earnings compound; buybacks are historical, not current;直接证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals;直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation
完整研究记录(核对用)
研究原文:Will the unused instruments ever be used - a buyback authorisation, treasury cancellation or a stated total-return policy - now that the dividend-only programme has met the PBR target early? The 2023 ToSTNeT-3 purchase-and-cancellation shows the instruments exist in this board's repertoire.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Deployment of the roughly JPY 14.0 billion financial sleeve is the open capital question.
不确定性(原始记录):Resolved only by board action; timing unknown.
F053|07|JFE和Mizuho Lease诉求不同,议程仍在经营层手里
研究范围:开放研究
写入正文:07|JFE和Mizuho Lease诉求不同,议程仍在经营层手里14|治理、所有权与管理层 4.06/7 分:自主权有行为证据,大股东意图无法判断
归并到:F022
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07
FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields怎么使用:直接证据;一手验证:02、03、05、08、09、10、15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域15)|FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields
完整研究记录(核对用)
研究原文:JFE group is the anchor shareholder group (39.49% aggregate, equity-method parent side) and steel ecosystem partner; the anchor explains register stability and leaves operating management formally independent in a way the post-2024 record corroborates.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F054|04|Mizuho Lease:2024年4月入股的20.04%股东,也是机械业务的合作方
研究范围:开放研究
写入正文:04|Mizuho Lease:2024年4月入股的20.04%股东,也是机械业务的合作方
归并到:F034
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接证据;一手验证:07;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据|H1 FY3/2027 segments: heavy temporary works JPY 4,403 million of ordinary-basis profit; machinery profit up 34% on used-asset sales
完整研究记录(核对用)
研究原文:Mizuho Lease is simultaneously capital (20.04%) and channel (machinery alliance, Rental System co-investment); its leasing economics are the machinery expansion route and its stake gives a financial owner's incentive for distribution and valuation discipline.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F055|04|FUCHI与Rental System:把海外和机械做成了有外部共同股东的载体
研究范围:开放研究
写入正文:04|FUCHI与Rental System:把海外和机械做成了有外部共同股东的载体
归并到:F035
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
完整研究记录(核对用)
研究原文:FUCHI is the overseas core subsidiary (70% since August 2025); it sits inside the profit-earning segment, explains part of H1 FY3/27 growth and its purchase accounting marks how the group prices expansion - opportunistically, below book.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F056|04|FUCHI与Rental System:把海外和机械做成了有外部共同股东的载体
研究范围:开放研究
写入正文:04|FUCHI与Rental System:把海外和机械做成了有外部共同股东的载体
归并到:F036
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接证据;一手验证:07;外部现实校验:23
Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition怎么使用:直接证据;一手验证:18
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据|FY3/2026 cash flow: operating inflow of JPY 10,661 million funds everything;直接证据 / 一手证据(研究域18)|Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition
完整研究记录(核对用)
研究原文:Rental System is where the Mizuho alliance becomes concrete: the one place the group admitted an outside co-owner in an asset-heavy segment of about 4% of gross segment profit.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F057|03|需求来自首都圈再开发和公共工程,业务量有保证,利润由定价决定
研究范围:开放研究
写入正文:03|需求来自首都圈再开发和公共工程,业务量有保证,利润由定价决定
归并到:F039
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high怎么使用:直接证据;一手验证:05、10、11、12、14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 一手证据(研究域11) / 一手证据(研究域12) / 一手证据(研究域14)|Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high;直接证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items
完整研究记录(核对用)
研究原文:Demand is a tailwind with a cost headwind: volume is available, so the question is whether pricing discipline keeps converting it into margin.
内部研究类型:END_MARKET
内部来源标记:OPEN_DISCOVERY
F058|03|钢铁行业同时是供应商、客户和股东
研究范围:开放研究
写入正文:03|钢铁行业同时是供应商、客户和股东
归并到:F040
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields怎么使用:直接证据;一手验证:02、03、05、08、09、10、15
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接证据;一手验证:06、18、19、20、21
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域15)|FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields;直接证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary
完整研究记录(核对用)
研究原文:Steel prices reach the P&L from both sides - replacement cost of the rental fleet and the fabrication order book - so exposure is partly self-hedging on price and wholly exposed on steel volumes and mill capital spending.
内部研究类型:END_MARKET_AND_INPUT_DUAL_EXPOSURE
内部来源标记:OPEN_DISCOVERY
F059|08|东证的资本成本要求是外部时钟,中期计划是内部尺子
研究范围:开放研究
写入正文:08|东证的资本成本要求是外部时钟,中期计划是内部尺子
归并到:F041
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接证据;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach怎么使用:直接证据;一手验证:13、23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;直接证据 / 一手证据(研究域13) / 一手证据(研究域23)|Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach
完整研究记录(核对用)
研究原文:The exchange cost-of-capital framework is a genuine actor: the external clock that converted a sleepy affiliate register into a margin, dividend and engagement programme; its next demand (a path above book value) is harder than the one just met.
内部研究类型:POLICY
内部来源标记:OPEN_DISCOVERY
F060|08|东证的资本成本要求是外部时钟,中期计划是内部尺子
研究范围:开放研究
写入正文:08|东证的资本成本要求是外部时钟,中期计划是内部尺子
归并到:F042
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接证据;一手验证:35
The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)怎么使用:直接证据;反向验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed;直接证据 / 反证(研究域13) / 定向深挖(研究域13)|The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)
完整研究记录(核对用)
研究原文:The mid-term plan governs the company in its second year; its expiry makes the FY3/28 guidance in May 2027 the first verdict on whether the framework renews with harder numbers, and the board's early delivery of the PBR target prices its credibility into that moment.
内部研究类型:POLICY
内部来源标记:OPEN_DISCOVERY
F061|01|下半年要交出8.2%的营业利润率,这是利润率承诺,不是需求承诺
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|下半年要交出8.2%的营业利润率,这是利润率承诺,不是需求承诺11|催化剂:从现在到2027年5月,只有一次业绩检验
归并到:F006
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接证据;一手验证:35;反向验证:12、30;专项深挖:16、35
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接证据;反向验证:05、11;专项深挖:05、11
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据|Forecast arithmetic: the revised FY3/27 plan requires a second-half operating profit of JPY 5,010 million, +17% on the prior second half;直接证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set
完整研究记录(核对用)
研究原文:The year's verdict is concentrated in one margin step, pre-funded in part by contract liabilities of JPY 5,751 million and the works pipeline described as progressing smoothly; delivery turns the revision into a credibility asset and carries the FY3/28 debate, a miss reopens the margin-ceiling question.
内部研究类型:END_MARKET
内部来源标记:OPEN_DISCOVERY
F062|04|Nihon Kiso Gijutsu:不投入资本的相邻业务提携
研究范围:开放研究
写入正文:04|Nihon Kiso Gijutsu:不投入资本的相邻业务提携
归并到:F038
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:直接证据;一手验证:04、07
Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%怎么使用:直接证据;一手验证:03、04、08、11;专项深挖:03
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October);直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域11) / 定向深挖(研究域03)|Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%
完整研究记录(核对用)
研究原文:The alliance extends works capability without capital commitment - the same asset-light pattern as the machinery route - and signals adjacency around the core as the preferred growth vector.
内部研究类型:PARTNER
内部来源标记:OPEN_DISCOVERY
F063|02|新加坡与越南业务:以选择权看待,利润无法核实
研究范围:开放研究
写入正文:02|新加坡与越南业务:以选择权看待,利润无法核实
归并到:F037
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:直接证据;一手验证:04、07
The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin怎么使用:直接证据;反向验证:04;专项深挖:04
查看完整证据标签(核对用)
直接证据|FUCHI Pte. Ltd. (Singapore): from equity-method affiliate to 70%-owned consolidated subsidiary in August 2025;直接证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October);直接证据 / 反证(研究域04) / 定向深挖(研究域04)|The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin
完整研究记录(核对用)
研究原文:The Singapore platform is the plan's growth option bought at bargain prices; its risk is opacity, so it is bounded by balance-sheet mass but not verified until geographic disclosure appears.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F064|02|新加坡与越南业务:以选择权看待,利润无法核实
研究范围:开放研究
写入正文:02|新加坡与越南业务:以选择权看待,利润无法核实
归并到:F037
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
完整研究记录(核对用)
研究原文:FUCHI is the platform around which JS Tan and Gecoss Vietnam are assembled.
内部研究类型:PART_OF
内部来源标记:OPEN_DISCOVERY
F065|07|少数股东权益开始分走增长载体的利润
研究范围:35项覆盖检查
写入正文:07|少数股东权益开始分走增长载体的利润
归并到:F016
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Non-controlling interests: from JPY 5 million to JPY 4,403 million in one year - the FUCHI and Rental System effect怎么使用:直接证据;反向验证:25;专项深挖:25;同业比较:35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域35) / 反证(研究域25) / 定向深挖(研究域25)|Non-controlling interests: from JPY 5 million to JPY 4,403 million in one year - the FUCHI and Rental System effect;直接证据|FUCHI Pte. Ltd. (Singapore): from equity-method affiliate to 70%-owned consolidated subsidiary in August 2025
完整研究记录(核对用)
研究原文:The 70% consolidation creates a 30% minority claim in the Singapore vehicle.
内部研究类型:CREATES_MINORITY_CLAIM
内部来源标记:COVERAGE35
F066|07|少数股东权益开始分走增长载体的利润
研究范围:35项覆盖检查
写入正文:07|少数股东权益开始分走增长载体的利润
归并到:F016
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Non-controlling interests: from JPY 5 million to JPY 4,403 million in one year - the FUCHI and Rental System effect怎么使用:直接证据;反向验证:25;专项深挖:25;同业比较:35;其他用途:历史
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接证据;一手验证:07;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域35) / 反证(研究域25) / 定向深挖(研究域25)|Non-controlling interests: from JPY 5 million to JPY 4,403 million in one year - the FUCHI and Rental System effect;直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据|FY3/2026 cash flow: operating inflow of JPY 10,661 million funds everything
完整研究记录(核对用)
研究原文:The third-party allotment (JPY 1,580 million paid in) brings an outside co-owner into the machinery vehicle.
内部研究类型:CREATES_MINORITY_CLAIM
内部来源标记:COVERAGE35
F067|01|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上
研究范围:开放研究+35项覆盖检查
写入正文:01|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上01|下半年要交出8.2%的营业利润率,这是利润率承诺,不是需求承诺06|收入减少166亿日元利润反而上升:毛利率抬升靠的是产品组合和定价11|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位11|什么会推翻这个判断
归并到:F101
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%怎么使用:直接证据;一手验证:16
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接证据;一手验证:35;反向验证:12、30;专项深挖:16、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域16)|Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%;直接证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据|Distribution-sales suppression in detail: the FY3/25 revenue fall of JPY 16.6 billion was the policy, not the market
完整研究记录(核对用)
研究原文:The implied second half is the same margin programme that printed 20.9% to 22.9% to 23.5% at the gross line, asked to compound for two more quarters on flat volume.
内部研究类型:CAUSAL_DEPENDENCY
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F068|06|第二季度经常利润下降6%,营业利润却在增长
研究范围:35项覆盖检查
归并到:F004
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Q2 FY3/27 standalone: ordinary profit of about JPY 2,092 million, down about 6% - the base-effect quarter inside a growing half怎么使用:直接证据;反向验证:28
查看完整证据标签(核对用)
直接证据|FY3/2026 one-off layers: negative goodwill and a step-acquisition loss below the line, FX and compensation inside ordinary profit;直接证据 / 反证(研究域28)|Q2 FY3/27 standalone: ordinary profit of about JPY 2,092 million, down about 6% - the base-effect quarter inside a growing half;直接证据|Q1 FY3/2027: ordinary profit of JPY 2,290 million, +20.8% year on year
完整研究记录(核对用)
研究原文:FY3/26's non-operating supports inflate the prior-year base, which makes the standalone Q2 ordinary line fall while the operating line grew.
内部研究类型:EXPLAINS
内部来源标记:COVERAGE35
F069|06|经常性净资产收益率只有7.8%,低于报告口径的8.5%
研究范围:35项覆盖检查
写入正文:06|经常性净资产收益率只有7.8%,低于报告口径的8.5%09|折价来自股东名册和资本回报,与盈利质量关系不大14|盈利质量、现金转化与资本效率 11.56/17 分:现金转化好,资本回报仍偏低
归并到:F018
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%怎么使用:直接证据;一手验证:22、28;专项深挖:22
查看完整证据标签(核对用)
直接证据|FY3/2026 one-off layers: negative goodwill and a step-acquisition loss below the line, FX and compensation inside ordinary profit;直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 定向深挖(研究域22)|ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%
完整研究记录(核对用)
研究原文:Removing the one-off layers moves FY3/26 ROE from 8.5% reported to about 7.8% recurring, the base of the PBR argument.
内部研究类型:NORMALIZES
内部来源标记:COVERAGE35
F070|01|下半年要交出8.2%的营业利润率,这是利润率承诺,不是需求承诺
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|下半年要交出8.2%的营业利润率,这是利润率承诺,不是需求承诺11|催化剂:从现在到2027年5月,只有一次业绩检验
归并到:F006
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接证据
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接证据;一手验证:35;反向验证:12、30;专项深挖:16、35
查看完整证据标签(核对用)
直接证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items;直接证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75;直接证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement
完整研究记录(核对用)
研究原文:The H1 results and revised full-year forecast define the second-half requirement by subtraction.
内部研究类型:DEFINES
内部来源标记:OPEN_DISCOVERY
F071|06|客户预收款增长75.1%,是仅有的前向需求信号
研究范围:35项覆盖检查
写入正文:06|客户预收款增长75.1%,是仅有的前向需求信号14|商业结构、产品、客户与关键依赖 6.6/11 分:业务量有保证,利润依赖单一板块
归并到:F010
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接证据;反向验证:05、11;专项深挖:05、11
Customer advances in detail: contract liabilities of JPY 5,751 million fund about 5% of annual sales in advance怎么使用:直接证据;一手验证:15;专项深挖:15、19
查看完整证据标签(核对用)
直接证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set;直接证据 / 一手证据(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Customer advances in detail: contract liabilities of JPY 5,751 million fund about 5% of annual sales in advance
完整研究记录(核对用)
研究原文:Rising customer advances corroborate, without quantifying, forward work behind the flat-sales second half.
内部研究类型:CORROBORATES_DEMAND
内部来源标记:COVERAGE35
F072|11|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位
研究范围:35项覆盖检查
写入正文:11|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位
归并到:F008
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure怎么使用:直接证据;反向验证:06、14;专项深挖:06、14
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接证据;反向验证:05、11;专项深挖:05、11
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接证据;一手验证:35;反向验证:12、30;专项深挖:16、35
查看完整证据标签(核对用)
直接证据 / 反证(研究域06) / 反证(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure;直接证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set;直接证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement
完整研究记录(核对用)
研究原文:Fixed-price contracting with undisclosed backlog means the 8.2% implied margin is an estimate whose error bars primary sources cannot supply.
内部研究类型:QUALIFIES
内部来源标记:COVERAGE35
F073|11|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位
研究范围:开放研究
写入正文:11|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位
归并到:F007
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high怎么使用:直接证据;一手验证:05、10、11、12、14
查看完整证据标签(核对用)
直接证据|Forecast arithmetic: the revised FY3/27 plan requires a second-half operating profit of JPY 5,010 million, +17% on the prior second half;直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 一手证据(研究域11) / 一手证据(研究域12) / 一手证据(研究域14)|Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high
完整研究记录(核对用)
研究原文:Tight labour, high costs and cancelled or postponed projects are the filings' own conditions against the implied margin step.
内部研究类型:COUNTER_EVIDENCE_CONDITION
内部来源标记:OPEN_DISCOVERY
F074|06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证
研究范围:35项覆盖检查
写入正文:06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证11|订单亏损准备金和其他结构性薄弱点要最先留意14|竞争优势与结构耐久性 8.68/14 分:有议价迹象,缺外部验证
归并到:F009
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接证据;一手验证:06、18、19、20、21
Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure怎么使用:直接证据;反向验证:06、14;专项深挖:06、14
Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%怎么使用:直接证据;一手验证:16
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 反证(研究域06) / 反证(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure;直接证据 / 一手证据(研究域16)|Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%
完整研究记录(核对用)
研究原文:An underwater contract in the book is inconsistent with the claim that pricing discipline is already systematic; its trajectory tests the mechanism's foundation.
内部研究类型:COUNTER_EVIDENCE
内部来源标记:COVERAGE35
F075|09|折价来自股东名册和资本回报,与盈利质量关系不大
研究范围:开放研究+35项覆盖检查
写入正文:09|折价来自股东名册和资本回报,与盈利质量关系不大
归并到:F103
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)怎么使用:直接证据;反向验证:13;专项深挖:13
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%怎么使用:直接证据;一手验证:22、28;专项深挖:22
查看完整证据标签(核对用)
直接证据 / 反证(研究域13) / 定向深挖(研究域13)|The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026);直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 定向深挖(研究域22)|ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%
完整研究记录(核对用)
研究原文:With the target met, remaining valuation upside depends on recurring ROE rather than multiple expansion on the same book.
内部研究类型:REFRAMES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F076|09|折价来自股东名册和资本回报,与盈利质量关系不大
研究范围:35项覆盖检查
写入正文:09|折价来自股东名册和资本回报,与盈利质量关系不大
归并到:F103
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%怎么使用:直接证据;一手验证:22、28;专项深挖:22
Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit怎么使用:直接证据;一手验证:27、31;反向验证:22;专项深挖:27、31
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域22) / 一手证据(研究域28) / 定向深挖(研究域22)|ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 反证(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit
完整研究记录(核对用)
研究原文:Recurring ROE of about 7.8% to 8.7% still trails parity-justifying returns, sustaining the discount until ROE evidence or sleeve return arrives.
内部研究类型:DRIVES
内部来源标记:COVERAGE35
F077|09|折价来自股东名册和资本回报,与盈利质量关系不大
研究范围:35项覆盖检查
写入正文:09|折价来自股东名册和资本回报,与盈利质量关系不大
归并到:F103
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接证据;反向验证:24;专项深挖:24
Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit怎么使用:直接证据;一手验证:27、31;反向验证:22;专项深挖:27、31
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 反证(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit
完整研究记录(核对用)
研究原文:Anchored votes and a thin float are the register component of the discount, independent of earnings quality.
内部研究类型:DRIVES
内部来源标记:COVERAGE35
F078|07|董事会像管理利润表一样管理股东名册
研究范围:35项覆盖检查
写入正文:07|董事会像管理利润表一样管理股东名册
归并到:F015
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接证据;反向验证:23
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接证据;反向验证:24;专项深挖:24
查看完整证据标签(核对用)
直接证据|Engagement instruments: a shareholder-benefit scheme introduced in 2026, repeated individual-investor seminars;直接证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals;直接证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided
完整研究记录(核对用)
研究原文:Retail engagement and benefit-scheme measures target the liquidity component of the discount.
内部研究类型:ADDRESSES
内部来源标记:COVERAGE35
F079|09|最坏情形是估值问题,不是偿债问题
研究范围:35项覆盖检查
写入正文:09|最坏情形是估值问题,不是偿债问题14|财务韧性与下行防御 11.05/13 分:几乎无负债,下行是估值问题
归并到:F031
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接证据;一手验证:21、29;反向验证:20;专项深挖:18、21
Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion怎么使用:直接证据;一手验证:29;反向验证:21;专项深挖:29
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation;直接证据 / 一手证据(研究域29) / 反证(研究域21) / 定向深挖(研究域29)|Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion
完整研究记录(核对用)
研究原文:Net financial assets of about 24% of capitalisation are downside ballast and unspent optionality.
内部研究类型:SUPPORTS
内部来源标记:COVERAGE35
F080|06|现金转化很强,但单年数字不宜年化
研究范围:35项覆盖检查
写入正文:06|现金转化很强,但单年数字不宜年化
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Cash conversion FY3/26: operating cash flow of JPY 10,661 million against net income of JPY 5,960 million怎么使用:直接证据;一手验证:17;专项深挖:17
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接证据;一手验证:21、29;反向验证:20;专项深挖:18、21
Debt stack: company-disclosed interest-bearing debt of JPY 3.7 billion, D/E of 0.05 times怎么使用:直接证据;一手验证:25;反向验证:18
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域17) / 定向深挖(研究域17)|Cash conversion FY3/26: operating cash flow of JPY 10,661 million against net income of JPY 5,960 million;直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation;直接证据 / 一手证据(研究域25) / 反证(研究域18)|Debt stack: company-disclosed interest-bearing debt of JPY 3.7 billion, D/E of 0.05 times
完整研究记录(核对用)
研究原文:Self-funded growth and distribution leave a growing financial sleeve as the model's residual.
内部研究类型:FUNDS
内部来源标记:COVERAGE35
F081|08|近140亿日元的金融资产尚未动用,回购工具有先例
研究范围:开放研究+35项覆盖检查
写入正文:08|近140亿日元的金融资产尚未动用,回购工具有先例11|最便宜的催化剂:把分红行为变成书面承诺14|资本配置与股东回报 6.2/10 分:分红规律清楚,回购和书面政策缺位
归并到:F030
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated怎么使用:直接证据;一手验证:26;专项深挖:26
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接证据;反向验证:23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated;直接证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals
完整研究记录(核对用)
研究原文:A consistent but informal 40% rule makes formalisation a low-cost step that could be taken in May 2027.
内部研究类型:ENABLES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F082|07|Mizuho Lease可能是推动资本讨论的一方,目前只是时间上的相关
研究范围:35项覆盖检查
写入正文:07|Mizuho Lease可能是推动资本讨论的一方,目前只是时间上的相关08|近140亿日元的金融资产尚未动用,回购工具有先例
归并到:F023
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接证据;一手验证:07;外部现实校验:23
Related-party texture: prior consultation on risk matters, own decisions, no material transactions noted怎么使用:直接证据;反向验证:01;专项深挖:01、23
Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales怎么使用:直接证据;反向验证:03、07;专项深挖:07
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据 / 反证(研究域01) / 定向深挖(研究域01) / 定向深挖(研究域23)|Related-party texture: prior consultation on risk matters, own decisions, no material transactions noted;直接证据 / 反证(研究域03) / 反证(研究域07) / 定向深挖(研究域07)|Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales
完整研究记录(核对用)
研究原文:A leasing-specialist anchor is a plausible sponsor for formalised payout and buyback questions; the counter-reading is operating management originating the programme.
内部研究类型:POSSIBLE_DRIVER
内部来源标记:COVERAGE35
F083|06|建设机械:需求不构成约束,资本回报才是
研究范围:35项覆盖检查
归并到:F026
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales怎么使用:直接证据;反向验证:03、07;专项深挖:07
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接证据;一手验证:07;外部现实校验:23
Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%怎么使用:直接证据;一手验证:22;反向验证:09;专项深挖:09
查看完整证据标签(核对用)
直接证据 / 反证(研究域03) / 反证(研究域07) / 定向深挖(研究域07)|Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales;直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据 / 一手证据(研究域22) / 反证(研究域09) / 定向深挖(研究域09)|Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%
完整研究记录(核对用)
研究原文:The Mizuho alliance and Rental System co-investment are aimed at the machinery segment's heavy-asset, thin-return economics.
内部研究类型:ADDRESSES
内部来源标记:COVERAGE35
F084|01|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上02|利润集中在一个板块:重型临时工程占分部毛利润的95%以上14|商业结构、产品、客户与关键依赖 6.6/11 分:业务量有保证,利润依赖单一板块
归并到:F025
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Segment profit concentration: heavy temporary works earns about 96% of gross segment profit怎么使用:直接证据;一手验证:02、16;反向验证:08;专项深挖:02、08
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域16) / 反证(研究域08) / 定向深挖(研究域02) / 定向深挖(研究域08)|Segment profit concentration: heavy temporary works earns about 96% of gross segment profit;直接证据|H1 FY3/2027 segments: heavy temporary works JPY 4,403 million of ordinary-basis profit; machinery profit up 34% on used-asset sales
完整研究记录(核对用)
研究原文:The thesis is one segment's pricing discipline; concentration makes monitoring a segment-level task.
内部研究类型:QUALIFIES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F085|01|两次业绩披露之间,论点怎样被确认
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|两次业绩披露之间,论点怎样被确认11|什么会推翻这个判断14|总分68.05/100,评级B+:基本面扎实,估值与价格都已部分兑现
归并到:F028
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接证据;一手验证:35;反向验证:12、30;专项深挖:16、35
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed
完整研究记录(核对用)
研究原文:The dated kill and confirm set holds the Thesis to its own standard.
内部研究类型:FALSIFIES_OR_CONFIRMS
内部来源标记:COVERAGE35
F086|11|催化剂:从现在到2027年5月,只有一次业绩检验
研究范围:开放研究
写入正文:11|催化剂:从现在到2027年5月,只有一次业绩检验13|最优先的三个问题:下半年能否交付,毛利率有没有天花板,接替框架给不给数字
归并到:F043
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接证据;一手验证:35;反向验证:12、30;专项深挖:16、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement
完整研究记录(核对用)
研究原文:The open delivery question conditions the implied-second-half judgment.
内部研究类型:RESEARCH_DEBT_QUALIFIES
内部来源标记:OPEN_DISCOVERY
F087|06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证
研究范围:开放研究
写入正文:06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证13|最优先的三个问题:下半年能否交付,毛利率有没有天花板,接替框架给不给数字
归并到:F044
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%怎么使用:直接证据;一手验证:16
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域16)|Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%
完整研究记录(核对用)
研究原文:The ceiling of the margin programme conditions the durability of the core mechanism.
内部研究类型:RESEARCH_DEBT_QUALIFIES
内部来源标记:OPEN_DISCOVERY
F088|13|第二层问题:计划目标、分红规则和闲置的回购
研究范围:开放研究
写入正文:13|第二层问题:计划目标、分红规则和闲置的回购15|证据的限制:哪些事实尚未核实,会怎样限制判断
归并到:F045
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment
完整研究记录(核对用)
研究原文:Unread final-year targets limit the plan scoreboard.
内部研究类型:RESEARCH_DEBT_QUALIFIES
内部来源标记:OPEN_DISCOVERY
F089|08|近140亿日元的金融资产尚未动用,回购工具有先例
研究范围:开放研究
写入正文:08|近140亿日元的金融资产尚未动用,回购工具有先例13|第二层问题:计划目标、分红规则和闲置的回购
归并到:F046
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated怎么使用:直接证据;一手验证:26;专项深挖:26
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated
完整研究记录(核对用)
研究原文:Whether the rule is formalised conditions how binding the dividend contract is.
内部研究类型:RESEARCH_DEBT_QUALIFIES
内部来源标记:OPEN_DISCOVERY
F090|02|新加坡与越南业务:以选择权看待,利润无法核实
研究范围:开放研究+35项覆盖检查
写入正文:02|新加坡与越南业务:以选择权看待,利润无法核实13|第三层问题:海外规模、亏损准备金、大股东和设备利用率15|证据的限制:哪些事实尚未核实,会怎样限制判断
归并到:F047
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin怎么使用:直接证据;反向验证:04;专项深挖:04
查看完整证据标签(核对用)
直接证据 / 反证(研究域04) / 定向深挖(研究域04)|The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin
完整研究记录(核对用)
研究原文:Undisclosed overseas earnings keep the cluster as optionality.
内部研究类型:RESEARCH_DEBT_QUALIFIES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F091|06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证
研究范围:开放研究
写入正文:06|订单亏损准备金3.14亿日元:定价纪律已成体系的反证13|第三层问题:海外规模、亏损准备金、大股东和设备利用率
归并到:F048
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接证据;一手验证:06、18、19、20、21
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million
完整研究记录(核对用)
研究原文:The unexplained attachment of the provision conditions its weight as counter-evidence.
内部研究类型:RESEARCH_DEBT_QUALIFIES
内部来源标记:OPEN_DISCOVERY
F092|13|第三层问题:海外规模、亏损准备金、大股东和设备利用率
研究范围:开放研究
写入正文:13|第三层问题:海外规模、亏损准备金、大股东和设备利用率
归并到:F049
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary
完整研究记录(核对用)
研究原文:Future anchor movement is the unresolved side of the register-regime risk.
内部研究类型:RESEARCH_DEBT_QUALIFIES
内部来源标记:OPEN_DISCOVERY
F093|08|近140亿日元的金融资产尚未动用,回购工具有先例
研究范围:开放研究+35项覆盖检查
写入正文:08|近140亿日元的金融资产尚未动用,回购工具有先例13|最优先的三个问题:下半年能否交付,毛利率有没有天花板,接替框架给不给数字
归并到:F051
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed
完整研究记录(核对用)
研究原文:Successor commitments determine whether the framework renews with harder numbers.
内部研究类型:RESEARCH_DEBT_QUALIFIES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F094|08|近140亿日元的金融资产尚未动用,回购工具有先例
研究范围:开放研究+35项覆盖检查
写入正文:08|近140亿日元的金融资产尚未动用,回购工具有先例13|第二层问题:计划目标、分红规则和闲置的回购
归并到:F052
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Equity walk and treasury: retained earnings compound; buybacks are historical, not current怎么使用:直接证据;一手验证:25
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接证据;反向验证:23
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接证据;一手验证:21、29;反向验证:20;专项深挖:18、21
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域25)|Equity walk and treasury: retained earnings compound; buybacks are historical, not current;直接证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals;直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation
完整研究记录(核对用)
研究原文:Deployment of the financial sleeve is the unresolved use of the balance-sheet ballast.
内部研究类型:RESEARCH_DEBT_QUALIFIES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F095|10|回撤精确停在旧上沿:压力位变成了支撑位
写入正文:10|回撤精确停在旧上沿:压力位变成了支撑位10|2026年的高点没有出现2015年那样的高潮放量10|当前状态:突破成立、仍在消化,高度与买盘之间有一处矛盾15|数据截止日与主要来源
归并到:F032
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Locally recomputed monthly series: span, extremes and basis怎么使用:直接证据;一手验证:34
Averages and position at the October 2026 partial close: above all three averages, at 88.8% of the life range怎么使用:直接 / 支持;反向验证:27、29、31
The first life: 2001-2013 base, the September 2014 spike to JPY 1,940, and the 2015 collapse怎么使用:直接 / 支持;同业比较:27、31、33;其他用途:历史
The long residence (2015-2024) and the 2025-2026 breakout through the 2014 ceiling怎么使用:直接 / 支持;一手验证:34;反向验证:33
Volume structure: the 2026 highs were made on ordinary volume, far below the 2015 climax怎么使用:直接 / 支持;反向验证:34
Price cross-check: fiscal-year extremes from the exchange record agree with the local monthly series怎么使用:外部现实校验:27、31;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域34)|Locally recomputed monthly series: span, extremes and basis;直接证据 / 支持证据 / 反证(研究域27) / 反证(研究域29) / 反证(研究域31)|Averages and position at the October 2026 partial close: above all three averages, at 88.8% of the life range;直接证据 / 支持证据 / 历史/同业比较(研究域27) / 历史/同业比较(研究域31) / 历史/同业比较(研究域33)|The first life: 2001-2013 base, the September 2014 spike to JPY 1,940, and the 2015 collapse;直接证据 / 支持证据 / 一手证据(研究域34) / 反证(研究域33)|The long residence (2015-2024) and the 2025-2026 breakout through the 2014 ceiling;直接证据 / 支持证据 / 反证(研究域34)|Volume structure: the 2026 highs were made on ordinary volume, far below the 2015 climax;反证 / 外部现实(研究域27) / 外部现实(研究域31)|Price cross-check: fiscal-year extremes from the exchange record agree with the local monthly series
完整研究记录(核对用)
研究原文:The Claim-level price observations are a view of, and defer to, the protected Technical structure as a whole; they neither restate nor alter it.
内部研究类型:CLAIM_LEVEL_VIEW_OF_PROTECTED_STRUCTURE
内部来源标记:TECHNICAL
F096|10|价格追认了已披露的利润率改造,11月上调没有得到价格确认
写入正文:10|价格追认了已披露的利润率改造,11月上调没有得到价格确认12|价格晚于利润率改造:这一轮是追认,没有抢跑
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
The long residence (2015-2024) and the 2025-2026 breakout through the 2014 ceiling怎么使用:直接证据;一手验证:34;反向验证:33
查看完整证据标签(核对用)
直接证据|FY3/2026 consolidated results: record operating profit of JPY 8,012 million;直接证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items;直接证据|The pivot from revenue to profit: low-margin distribution sales suppressed from about 40% to about 25% of steel-material sales;直接证据 / 一手证据(研究域34) / 反证(研究域33)|The long residence (2015-2024) and the 2025-2026 breakout through the 2014 ceiling
完整研究记录(核对用)
研究原文:Fundamentals and price agree on sequence: the margin transformation printed in May 2025, May 2026 and November 2026 while the decisive price break came only after the second print; the chart is the register's delayed ratification of the operating record, not a speculation ahead of it. The relation compares timing and does not rewrite either lane.
内部研究类型:CROSS_LANE_TIMING
内部来源标记:TECHNICAL
F097|08|市净率0.8倍的目标提前两年达成,一半靠账面、一半靠股价
研究范围:35项覆盖检查
写入正文:08|市净率0.8倍的目标提前两年达成,一半靠账面、一半靠股价
归并到:F017
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)怎么使用:直接证据;反向验证:13;专项深挖:13
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接证据;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
查看完整证据标签(核对用)
直接证据 / 反证(研究域13) / 定向深挖(研究域13)|The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026);直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%
完整研究记录(核对用)
研究原文:The PBR target's early delivery was achieved half in the book and half in the price, so further re-rating toward 1.0 times must come increasingly from ROE evidence rather than multiple expansion on the same book.
内部研究类型:CROSS_LANE_CONSTRAINT
内部来源标记:COVERAGE35 / TECHNICAL
F098|10|价格追认了已披露的利润率改造,11月上调没有得到价格确认
写入正文:10|价格追认了已披露的利润率改造,11月上调没有得到价格确认
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接证据
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接证据;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
查看完整证据标签(核对用)
直接证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%
完整研究记录(核对用)
研究原文:The November revision received no technical confirmation: the post-print session closed down 2.55% on ordinary volume, so the research dates its verdict to the Q3 and full-year prints rather than to the revision itself.
内部研究类型:CROSS_LANE_EVENT_RESPONSE
内部来源标记:TECHNICAL
F099|09|最坏情形是估值问题,不是偿债问题
研究范围:35项覆盖检查
写入正文:09|最坏情形是估值问题,不是偿债问题10|价格追认了已披露的利润率改造,11月上调没有得到价格确认
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接证据;一手验证:21、29;反向验证:20;专项深挖:18、21
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接证据;一手验证:06、18、19、20、21
Averages and position at the October 2026 partial close: above all three averages, at 88.8% of the life range怎么使用:直接证据;反向验证:27、29、31
The long residence (2015-2024) and the 2025-2026 breakout through the 2014 ceiling怎么使用:直接证据;一手验证:34;反向验证:33
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation;直接证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 反证(研究域27) / 反证(研究域29) / 反证(研究域31)|Averages and position at the October 2026 partial close: above all three averages, at 88.8% of the life range;直接证据 / 一手证据(研究域34) / 反证(研究域33)|The long residence (2015-2024) and the 2025-2026 breakout through the 2014 ceiling
完整研究记录(核对用)
研究原文:Balance-sheet strength (net financial assets about 24% of capitalisation, book about JPY 2,144 per share) sits above the technical falsification levels (JPY 1,443, then about JPY 1,415): a structure break would still leave the price far above the asset-backed floor, making the downside case a valuation case rather than a solvency case.
内部研究类型:CROSS_LANE_ASYMMETRY
内部来源标记:COVERAGE35 / TECHNICAL
F100|02|耐久的部分是需求、设备和资产负债表,脆弱的部分是定价纪律和股东名册
研究范围:开放研究+35项覆盖检查
写入正文:02|耐久的部分是需求、设备和资产负债表,脆弱的部分是定价纪律和股东名册05|护城河成立的证据主要来自公司自己的利润率,缺少外部独立验证
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(44项,重复标签已合并)
Issuer identity: GECOSS Corporation, TSE Prime 9991, EDINET E02782, business since 1968怎么使用:直接 / 支持;一手验证:01
FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields怎么使用:直接 / 支持;一手验证:02、03、05、08、09、10、15
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接 / 支持;一手验证:01、23、24;外部现实校验:07
H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items怎么使用:直接 / 支持
Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%怎么使用:直接 / 支持;一手验证:16
Segment profit concentration: heavy temporary works earns about 96% of gross segment profit怎么使用:直接 / 支持;一手验证:02、16;反向验证:08;专项深挖:02、08
Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%怎么使用:直接证据;一手验证:03、04、08、11;专项深挖:03
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:直接 / 支持;一手验证:04、07
Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high怎么使用:直接证据;一手验证:05、10、11、12、14
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接 / 支持;一手验证:06、18、19、20、21
Steel-cycle frame: the parent industry is customer, supplier and shareholder at once怎么使用:直接证据;一手验证:14
Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition怎么使用:直接 / 支持;一手验证:18
Debt stack: company-disclosed interest-bearing debt of JPY 3.7 billion, D/E of 0.05 times怎么使用:直接 / 支持;一手验证:25;反向验证:18
Working capital anatomy: receivables and claims of JPY 36,552 million against payables of JPY 23,095 million怎么使用:直接证据;一手验证:06、19;反向验证:15、17
Dividend record: JPY 54 (FY3/25) to JPY 69 (FY3/26), payout ratios of 40.1% and 39.7%怎么使用:直接 / 支持;一手验证:26
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接 / 支持
Cash conversion FY3/26: operating cash flow of JPY 10,661 million against net income of JPY 5,960 million怎么使用:直接 / 支持;一手验证:17;专项深挖:17
H1 FY3/27 cash walk: operating inflow of JPY 4,705 million; the JS Tan acquisition inside investing outflow怎么使用:直接 / 支持;一手验证:17;反向验证:19
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接 / 支持;一手验证:21、29;反向验证:20;专项深挖:18、21
Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit怎么使用:直接 / 支持;一手验证:27、31;反向验证:22;专项深挖:27、31
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接 / 支持;反向验证:24;专项深挖:24
Related-party texture: prior consultation on risk matters, own decisions, no material transactions noted怎么使用:直接证据;反向验证:01;专项深挖:01、23
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接 / 支持;反向验证:23
Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach怎么使用:直接 / 支持;一手验证:13、23
Equity walk and treasury: retained earnings compound; buybacks are historical, not current怎么使用:直接 / 支持;一手验证:25
Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated怎么使用:直接 / 支持;一手验证:26;专项深挖:26
The dividend-raise pattern: January 2026 lifted the FY3/26 year-end to JPY 44; November 2026 lifted both FY3/27 legs怎么使用:直接证据;一手验证:30;反向验证:26;专项深挖:30
Non-controlling interests: from JPY 5 million to JPY 4,403 million in one year - the FUCHI and Rental System effect怎么使用:直接 / 支持;反向验证:25;专项深挖:25;同业比较:35;其他用途:历史
Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%怎么使用:直接 / 支持;一手验证:22;反向验证:09;专项深挖:09
Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales怎么使用:直接 / 支持;反向验证:03、07;专项深挖:07
The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin怎么使用:直接证据;反向验证:04;专项深挖:04
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接 / 支持;反向验证:05、11;专项深挖:05、11
Customer advances in detail: contract liabilities of JPY 5,751 million fund about 5% of annual sales in advance怎么使用:直接 / 支持;一手验证:15;专项深挖:15、19
Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion怎么使用:直接证据;一手验证:29;反向验证:21;专项深挖:29
Historical turning points: the FY3/15 spike year, the FY3/22-23 trough, the FY3/25 pivot怎么使用:直接证据;一手验证:33;专项深挖:12、33、34;同业比较:01、02、03、04、05、06、07、08、09、10、11、12、13、14、15、16、17、18、19、20、21、22、23、24、25、26、28、29、30、32、34;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|Issuer identity: GECOSS Corporation, TSE Prime 9991, EDINET E02782, business since 1968;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域15)|FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 支持证据|The pivot from revenue to profit: low-margin distribution sales suppressed from about 40% to about 25% of steel-material sales;直接证据 / 支持证据|Distribution-sales suppression in detail: the FY3/25 revenue fall of JPY 16.6 billion was the policy, not the market;直接证据 / 支持证据|FY3/2026 consolidated results: record operating profit of JPY 8,012 million;直接证据 / 支持证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items;直接证据 / 支持证据 / 一手证据(研究域16)|Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域16) / 反证(研究域08) / 定向深挖(研究域02) / 定向深挖(研究域08)|Segment profit concentration: heavy temporary works earns about 96% of gross segment profit;直接证据 / 支持证据|H1 FY3/2027 segments: heavy temporary works JPY 4,403 million of ordinary-basis profit; machinery profit up 34% on used-asset sales;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域11) / 定向深挖(研究域03)|Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October);直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 一手证据(研究域11) / 一手证据(研究域12) / 一手证据(研究域14)|Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 一手证据(研究域14)|Steel-cycle frame: the parent industry is customer, supplier and shareholder at once;直接证据 / 支持证据 / 一手证据(研究域18)|Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition;直接证据 / 支持证据 / 一手证据(研究域25) / 反证(研究域18)|Debt stack: company-disclosed interest-bearing debt of JPY 3.7 billion, D/E of 0.05 times;直接证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域15) / 反证(研究域17)|Working capital anatomy: receivables and claims of JPY 36,552 million against payables of JPY 23,095 million;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 54 (FY3/25) to JPY 69 (FY3/26), payout ratios of 40.1% and 39.7%;直接证据 / 支持证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75;直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|Cash conversion FY3/26: operating cash flow of JPY 10,661 million against net income of JPY 5,960 million;直接证据 / 支持证据 / 一手证据(研究域17) / 反证(研究域19)|H1 FY3/27 cash walk: operating inflow of JPY 4,705 million; the JS Tan acquisition inside investing outflow;直接证据|FY3/2026 cash flow: operating inflow of JPY 10,661 million funds everything;直接证据 / 支持证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 反证(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;直接证据 / 支持证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided;直接证据 / 反证(研究域01) / 定向深挖(研究域01) / 定向深挖(研究域23)|Related-party texture: prior consultation on risk matters, own decisions, no material transactions noted;直接证据 / 支持证据|Engagement instruments: a shareholder-benefit scheme introduced in 2026, repeated individual-investor seminars;直接证据 / 支持证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23)|Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach;直接证据 / 支持证据 / 一手证据(研究域25)|Equity walk and treasury: retained earnings compound; buybacks are historical, not current;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated;直接证据 / 一手证据(研究域30) / 反证(研究域26) / 定向深挖(研究域30)|The dividend-raise pattern: January 2026 lifted the FY3/26 year-end to JPY 44; November 2026 lifted both FY3/27 legs;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域25) / 定向深挖(研究域25)|Non-controlling interests: from JPY 5 million to JPY 4,403 million in one year - the FUCHI and Rental System effect;直接证据 / 支持证据|FUCHI Pte. Ltd. (Singapore): from equity-method affiliate to 70%-owned consolidated subsidiary in August 2025;直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 定向深挖(研究域09)|Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%;直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域07) / 定向深挖(研究域07)|Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales;直接证据 / 反证(研究域04) / 定向深挖(研究域04)|The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin;直接证据 / 支持证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set;直接证据 / 支持证据 / 一手证据(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Customer advances in detail: contract liabilities of JPY 5,751 million fund about 5% of annual sales in advance;直接证据 / 一手证据(研究域29) / 反证(研究域21) / 定向深挖(研究域29)|Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域05) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域34) / 定向深挖(研究域12) / 定向深挖(研究域33) / 定向深挖(研究域34)|Historical turning points: the FY3/15 spike year, the FY3/22-23 trough, the FY3/25 pivot
完整研究记录(核对用)
研究原文:Durable business portrait and structural durability of GECOSS|A rental-steel fleet plus engineering niche attached to every construction project in the capital region and public sector, earning about 96% of gross segment profit in one segment, self-funded with an equity ratio near 59% and effectively no debt, distributing about 40% of earnings, with a financial sleeve of about JPY 14.0 billion. Durable: temporary-works demand, fleet availability and engineering references, balance sheet, and demonstrated management behaviour (a revenue sacrifice accepted to fix mix, dividend raises sized to a ratio, bargain-priced expansion). Fragile in two specific ways: profit concentration in one engine's pricing discipline, and a register where two anchors hold about 60% of votes, which stabilises everything until one moves. Confidence rests on observable dated mechanisms (gross-margin line, payout ratio, advances balance, anchors' filings), not on a forecast of the construction cycle. Current change (record operating profit, raised forecast) is overlaid on this foundation, not substituted for it.
内部研究类型:DURABLE_BUSINESS_PORTRAIT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Ordinary holders own a self-funding, pricing-led niche with a thin, anchored float; durability is high on solvency and demand, conditional on pricing discipline and register stability.
不确定性(原始记录):No utilisation, backlog, peer benchmarking or geographic profit disclosure; cycle amplitude measured on a compiled eight-year headline record.
F101|01|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上
研究范围:开放研究+35项覆盖检查
写入正文:01|一次靠定价纪律推动的利润率改造,成败押在下半年的一个利润率台阶上01|下半年要交出8.2%的营业利润率,这是利润率承诺,不是需求承诺06|收入减少166亿日元利润反而上升:毛利率抬升靠的是产品组合和定价11|第一风险:下半年的利润率台阶,遇上人手紧张和成本高位11|什么会推翻这个判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(22项,重复标签已合并)
H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items怎么使用:直接 / 支持
Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%怎么使用:直接 / 支持;一手验证:16
Segment profit concentration: heavy temporary works earns about 96% of gross segment profit怎么使用:直接证据;一手验证:02、16;反向验证:08;专项深挖:02、08
Accounting note: segment profit is ordinary profit, so segment margins are not operating margins怎么使用:直接证据;一手验证:32;反向验证:02、16
FY3/26 earnings-quality bridge: operating 8,012 to ordinary 8,709 to pre-tax 8,912 to net 5,853怎么使用:直接证据;一手验证:28;反向验证:32;专项深挖:28
FUCHI step-acquisition mechanics: how one deal produced both a JPY 401 million gain and a JPY 418 million loss怎么使用:直接证据;一手验证:32;专项深挖:32
Q2 FY3/27 standalone: ordinary profit of about JPY 2,092 million, down about 6% - the base-effect quarter inside a growing half怎么使用:直接 / 支持;反向验证:28
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接 / 支持
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接 / 支持;一手验证:35;反向验证:12、30;专项深挖:16、35
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接 / 支持;反向验证:05、11;专项深挖:05、11
Customer advances in detail: contract liabilities of JPY 5,751 million fund about 5% of annual sales in advance怎么使用:直接 / 支持;一手验证:15;专项深挖:15、19
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接 / 支持;一手验证:06、18、19、20、21
Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high怎么使用:直接 / 支持;一手验证:05、10、11、12、14
Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure怎么使用:直接 / 支持;反向验证:06、14;专项深挖:06、14
查看完整证据标签(核对用)
直接证据 / 支持证据|The pivot from revenue to profit: low-margin distribution sales suppressed from about 40% to about 25% of steel-material sales;直接证据 / 支持证据|Distribution-sales suppression in detail: the FY3/25 revenue fall of JPY 16.6 billion was the policy, not the market;直接证据 / 支持证据|FY3/2026 consolidated results: record operating profit of JPY 8,012 million;直接证据 / 支持证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items;直接证据 / 支持证据 / 一手证据(研究域16)|Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%;直接证据 / 一手证据(研究域02) / 一手证据(研究域16) / 反证(研究域08) / 定向深挖(研究域02) / 定向深挖(研究域08)|Segment profit concentration: heavy temporary works earns about 96% of gross segment profit;直接证据 / 支持证据|FY3/2026 one-off layers: negative goodwill and a step-acquisition loss below the line, FX and compensation inside ordinary profit;直接证据|FY3/2027 initial guidance (May 2026): operating profit up, ordinary profit guided down as one-offs drop out;直接证据 / 一手证据(研究域32) / 反证(研究域02) / 反证(研究域16)|Accounting note: segment profit is ordinary profit, so segment margins are not operating margins;直接证据 / 一手证据(研究域28) / 反证(研究域32) / 定向深挖(研究域28)|FY3/26 earnings-quality bridge: operating 8,012 to ordinary 8,709 to pre-tax 8,912 to net 5,853;直接证据 / 一手证据(研究域32) / 定向深挖(研究域32)|FUCHI step-acquisition mechanics: how one deal produced both a JPY 401 million gain and a JPY 418 million loss;直接证据 / 支持证据 / 反证(研究域28)|Q2 FY3/27 standalone: ordinary profit of about JPY 2,092 million, down about 6% - the base-effect quarter inside a growing half;直接证据 / 支持证据|Q1 FY3/2027: ordinary profit of JPY 2,290 million, +20.8% year on year;直接证据|H1 FY3/2027 segments: heavy temporary works JPY 4,403 million of ordinary-basis profit; machinery profit up 34% on used-asset sales;直接证据 / 支持证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75;直接证据 / 支持证据|Forecast arithmetic: the revised FY3/27 plan requires a second-half operating profit of JPY 5,010 million, +17% on the prior second half;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据 / 支持证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set;直接证据 / 支持证据 / 一手证据(研究域15) / 定向深挖(研究域15) / 定向深挖(研究域19)|Customer advances in detail: contract liabilities of JPY 5,751 million fund about 5% of annual sales in advance;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域10) / 一手证据(研究域11) / 一手证据(研究域12) / 一手证据(研究域14)|Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high;直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure
完整研究记录(核对用)
研究原文:Chosen revenue sacrifice to clean mix to margin to record operating profit to a checkable second-half promise|Volume-first selling pushed ordinary profit down two years; management cut distribution sales, accepted a 13.0% revenue fall, and compounded price-adequacy on the cleaned mix. Gross margin 20.9% to 22.9% to 23.5% produced record operating profit and a raised forecast whose implied second half (8.2% operating margin on flat sales) is a pure margin promise. The chain is read on the operating line because one-offs distort the ordinary line and standalone quarters. Counter-evidence: tight labour and high costs, fixed-price contracting without disclosed backlog, and an unexplained JPY 314 million loss-order provision.
内部研究类型:MAIN_CAUSAL_CHAIN
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operating profit compounding at a mid-teens rate on a cleaned mix drives earnings power, dividend and re-rating; a stall at the margin programme is the principal fundamental failure path.
不确定性(原始记录):Ceiling of the programme and embedded margins on contracted work cannot be sized from primary sources.
F102|08|东证的资本成本要求是外部时钟,中期计划是内部尺子
研究范围:开放研究+35项覆盖检查
写入正文:08|东证的资本成本要求是外部时钟,中期计划是内部尺子
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(26项,重复标签已合并)
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接 / 支持;一手验证:13;外部现实校验:04、10
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach怎么使用:直接 / 支持;一手验证:13、23
The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)怎么使用:直接 / 支持;反向验证:13;专项深挖:13
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接 / 支持;一手验证:35
Dividend record: JPY 54 (FY3/25) to JPY 69 (FY3/26), payout ratios of 40.1% and 39.7%怎么使用:直接 / 支持;一手验证:26
Equity walk and treasury: retained earnings compound; buybacks are historical, not current怎么使用:直接 / 支持;一手验证:25
Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated怎么使用:直接 / 支持;一手验证:26;专项深挖:26
The dividend-raise pattern: January 2026 lifted the FY3/26 year-end to JPY 44; November 2026 lifted both FY3/27 legs怎么使用:直接证据;一手验证:30;反向验证:26;专项深挖:30
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接 / 支持;反向验证:23
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接证据
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接 / 支持;反向验证:24;专项深挖:24
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07;其他用途:反证
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
Related-party texture: prior consultation on risk matters, own decisions, no material transactions noted怎么使用:直接 / 支持;反向验证:01;专项深挖:01、23
Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales怎么使用:直接 / 支持;反向验证:03、07;专项深挖:07
ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%怎么使用:直接 / 支持;一手验证:22、28;专项深挖:22
Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%怎么使用:直接证据;一手验证:22;反向验证:09;专项深挖:09
Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit怎么使用:直接 / 支持;一手验证:27、31;反向验证:22;专项深挖:27、31
Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion怎么使用:直接证据;一手验证:29;反向验证:21;专项深挖:29
Price cross-check: fiscal-year extremes from the exchange record agree with the local monthly series怎么使用:外部现实校验:27、31;其他用途:反证
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接证据;一手验证:21、29;反向验证:20;专项深挖:18、21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23)|Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach;直接证据 / 支持证据 / 反证(研究域13) / 定向深挖(研究域13)|The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026);直接证据 / 支持证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed;反证|FY3/2026 one-off layers: negative goodwill and a step-acquisition loss below the line, FX and compensation inside ordinary profit;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 54 (FY3/25) to JPY 69 (FY3/26), payout ratios of 40.1% and 39.7%;直接证据 / 支持证据 / 一手证据(研究域25)|Equity walk and treasury: retained earnings compound; buybacks are historical, not current;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated;直接证据 / 一手证据(研究域30) / 反证(研究域26) / 定向深挖(研究域30)|The dividend-raise pattern: January 2026 lifted the FY3/26 year-end to JPY 44; November 2026 lifted both FY3/27 legs;直接证据 / 支持证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals;直接证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75;直接证据 / 支持证据|Engagement instruments: a shareholder-benefit scheme introduced in 2026, repeated individual-investor seminars;直接证据 / 支持证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided;直接证据 / 反证 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据|H1 FY3/2027 segments: heavy temporary works JPY 4,403 million of ordinary-basis profit; machinery profit up 34% on used-asset sales;直接证据 / 支持证据 / 反证(研究域01) / 定向深挖(研究域01) / 定向深挖(研究域23)|Related-party texture: prior consultation on risk matters, own decisions, no material transactions noted;直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域07) / 定向深挖(研究域07)|Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales;直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 定向深挖(研究域22)|ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%;直接证据 / 支持证据|FY3/2026 consolidated results: record operating profit of JPY 8,012 million;直接证据 / 一手证据(研究域22) / 反证(研究域09) / 定向深挖(研究域09)|Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 反证(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit;直接证据 / 一手证据(研究域29) / 反证(研究域21) / 定向深挖(研究域29)|Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion;反证 / 外部现实(研究域27) / 外部现实(研究域31)|Price cross-check: fiscal-year extremes from the exchange record agree with the local monthly series;直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation
完整研究记录(核对用)
研究原文:Exchange pressure, anchored register and the capital programme|A dated external commitment (PBR at least 0.8 times) converted an anchored register into margin, dividend, engagement and governance actions; the target was met two years early, half through book growth and half through price. The next stage is an ROE argument for parity with book, with a 40% informal payout, an unused buyback and a net financial sleeve as the unpriced capital instruments, and Mizuho Lease as the plausible financial-owner sponsor. Policy support is rented, not owned.
内部研究类型:CAPITAL_AND_REGISTER_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Further re-rating depends on recurring ROE evidence or deployment of the sleeve; formalisation in May 2027 is a low-cost upside event.
不确定性(原始记录):Attribution of the capital turn to an anchor is inference from timing; final-year and successor targets are unread or undisclosed.
F103|09|折价来自股东名册和资本回报,与盈利质量关系不大
研究范围:开放研究+35项覆盖检查
写入正文:09|折价来自股东名册和资本回报,与盈利质量关系不大
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(23项,重复标签已合并)
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接 / 支持;一手验证:06、18、19、20、21
Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition怎么使用:直接 / 支持;一手验证:18
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接 / 支持
Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit怎么使用:直接 / 支持;一手验证:27、31;反向验证:22;专项深挖:27、31
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接 / 支持;反向验证:24;专项深挖:24
ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%怎么使用:直接 / 支持;一手验证:22、28;专项深挖:22
Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion怎么使用:直接证据;一手验证:29;反向验证:21;专项深挖:29
Price cross-check: fiscal-year extremes from the exchange record agree with the local monthly series怎么使用:外部现实校验:27、31;其他用途:反证
Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%怎么使用:直接证据;一手验证:22;反向验证:09;专项深挖:09
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接 / 支持;一手验证:21、29;反向验证:20;专项深挖:18、21
Historical turning points: the FY3/15 spike year, the FY3/22-23 trough, the FY3/25 pivot怎么使用:直接证据;一手验证:33;专项深挖:12、33、34;同业比较:01、02、03、04、05、06、07、08、09、10、11、12、13、14、15、16、17、18、19、20、21、22、23、24、25、26、28、29、30、32、34;其他用途:历史
Accounting note: segment profit is ordinary profit, so segment margins are not operating margins怎么使用:直接证据;一手验证:32;反向验证:02、16
FY3/26 earnings-quality bridge: operating 8,012 to ordinary 8,709 to pre-tax 8,912 to net 5,853怎么使用:直接证据;一手验证:28;反向验证:32;专项深挖:28
FUCHI step-acquisition mechanics: how one deal produced both a JPY 401 million gain and a JPY 418 million loss怎么使用:直接证据;一手验证:32;专项深挖:32
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接 / 支持;一手验证:01、23、24;外部现实校验:07
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)怎么使用:直接证据;反向验证:13;专项深挖:13
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;直接证据 / 支持证据|FY3/2026 consolidated results: record operating profit of JPY 8,012 million;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 支持证据|FY3/2026 cash flow: operating inflow of JPY 10,661 million funds everything;直接证据 / 支持证据 / 一手证据(研究域18)|Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition;直接证据 / 支持证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 反证(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域31)|Valuation cross-section at the review date: 9.4 times forecast earnings, 0.82 times book, enterprise value about 4.9 times forecast operating profit;直接证据 / 支持证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided;直接证据 / 支持证据 / 一手证据(研究域22) / 一手证据(研究域28) / 定向深挖(研究域22)|ROE decomposition: reported 8.5% for FY3/26; the recurring layer is about 7.8% and the forecast 8.73%;直接证据 / 一手证据(研究域29) / 反证(研究域21) / 定向深挖(研究域29)|Downside coverage: book equity of JPY 72,128 million against a capitalisation of about JPY 59.3 billion;反证 / 外部现实(研究域27) / 外部现实(研究域31)|Price cross-check: fiscal-year extremes from the exchange record agree with the local monthly series;直接证据 / 一手证据(研究域22) / 反证(研究域09) / 定向深挖(研究域09)|Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%;直接证据 / 支持证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域04) / 历史/同业比较(研究域05) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域22) / 历史/同业比较(研究域23) / 历史/同业比较(研究域24) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域30) / 历史/同业比较(研究域32) / 历史/同业比较(研究域34) / 定向深挖(研究域12) / 定向深挖(研究域33) / 定向深挖(研究域34)|Historical turning points: the FY3/15 spike year, the FY3/22-23 trough, the FY3/25 pivot;直接证据 / 支持证据|FY3/2026 one-off layers: negative goodwill and a step-acquisition loss below the line, FX and compensation inside ordinary profit;直接证据|FY3/2027 initial guidance (May 2026): operating profit up, ordinary profit guided down as one-offs drop out;直接证据 / 一手证据(研究域32) / 反证(研究域02) / 反证(研究域16)|Accounting note: segment profit is ordinary profit, so segment margins are not operating margins;直接证据 / 一手证据(研究域28) / 反证(研究域32) / 定向深挖(研究域28)|FY3/26 earnings-quality bridge: operating 8,012 to ordinary 8,709 to pre-tax 8,912 to net 5,853;直接证据 / 一手证据(研究域32) / 定向深挖(研究域32)|FUCHI step-acquisition mechanics: how one deal produced both a JPY 401 million gain and a JPY 418 million loss;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据 / 反证(研究域13) / 定向深挖(研究域13)|The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026);直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment
完整研究记录(核对用)
研究原文:Valuation bridge: operating engine, financial sleeve and optionality|Recurring earnings are built from the operating line (not reported profit); the financial sleeve is added at face value; the multiple paid (9.4 times forecast earnings, 0.82-0.83 times book, 4.27% yield) discounts the register and ROE gap rather than earnings quality. Downside is absorbed by assets and the dividend ratio, not leverage.
内部研究类型:VALUATION_BRIDGE_AND_DOWNSIDE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Balanced-to-favourable risk-reward for holders able to wait for two verdict prints; derived multiples must be read with their stated bases.
不确定性(原始记录):No DCF or target price; EV and PBR bases differ across derived values; securities at market, land at cost, pension surplus excluded.
F104|02|耐久的部分是需求、设备和资产负债表,脆弱的部分是定价纪律和股东名册
研究范围:开放研究+35项覆盖检查
写入正文:02|耐久的部分是需求、设备和资产负债表,脆弱的部分是定价纪律和股东名册11|订单亏损准备金和其他结构性薄弱点要最先留意
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(20项,重复标签已合并)
Segment profit concentration: heavy temporary works earns about 96% of gross segment profit怎么使用:直接 / 支持;一手验证:02、16;反向验证:08;专项深挖:02、08
FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields怎么使用:直接 / 支持;一手验证:02、03、05、08、09、10、15
Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%怎么使用:直接证据;一手验证:03、04、08、11;专项深挖:03
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:直接 / 支持;一手验证:04、07
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接 / 支持;一手验证:06、18、19、20、21
Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure怎么使用:直接 / 支持;反向验证:06、14;专项深挖:06、14
Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%怎么使用:直接 / 支持;一手验证:16
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接 / 支持;反向验证:05、11;专项深挖:05、11
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接 / 支持;一手验证:35;反向验证:12、30;专项深挖:16、35
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接 / 支持;一手验证:01、23、24;外部现实校验:07
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接 / 支持;反向验证:24;专项深挖:24
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%怎么使用:直接 / 支持;一手验证:22;反向验证:09;专项深挖:09
Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales怎么使用:直接 / 支持;反向验证:03、07;专项深挖:07
The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin怎么使用:直接证据;反向验证:04;专项深挖:04
Non-controlling interests: from JPY 5 million to JPY 4,403 million in one year - the FUCHI and Rental System effect怎么使用:直接 / 支持;反向验证:25;专项深挖:25;同业比较:35;其他用途:历史
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接 / 支持;一手验证:07;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域16) / 反证(研究域08) / 定向深挖(研究域02) / 定向深挖(研究域08)|Segment profit concentration: heavy temporary works earns about 96% of gross segment profit;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域15)|FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields;直接证据 / 支持证据|H1 FY3/2027 segments: heavy temporary works JPY 4,403 million of ordinary-basis profit; machinery profit up 34% on used-asset sales;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域11) / 定向深挖(研究域03)|Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October);直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 支持证据 / 反证(研究域06) / 反证(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure;直接证据 / 支持证据 / 一手证据(研究域16)|Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%;直接证据 / 支持证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 支持证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 定向深挖(研究域09)|Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%;直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域07) / 定向深挖(研究域07)|Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales;直接证据 / 反证(研究域04) / 定向深挖(研究域04)|The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin;直接证据 / 支持证据|FUCHI Pte. Ltd. (Singapore): from equity-method affiliate to 70%-owned consolidated subsidiary in August 2025;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域25) / 定向深挖(研究域25)|Non-controlling interests: from JPY 5 million to JPY 4,403 million in one year - the FUCHI and Rental System effect;直接证据 / 支持证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据|FY3/2026 cash flow: operating inflow of JPY 10,661 million funds everything
完整研究记录(核对用)
研究原文:Structural weaknesses: concentration, contract pricing, anchor regime, opaque growth|Weaknesses are specific: one segment's pricing discipline, contracts priced before costs are final, a register that can change regime in one disclosure, a low-return machinery fleet, an undisclosed overseas cluster, and a growing minority share of the growth vehicles.
内部研究类型:STRUCTURAL_WEAKNESS_SET
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Each weakness shows up first in segment disclosure, provisions, anchor filings or per-share lag, not in headline group numbers.
不确定性(原始记录):Probabilities and sizes largely undisclosed.
F105|04|产业关系:大股东、扩张载体和提携伙伴共同决定经济与控制权怎样到达上市股东
研究范围:开放研究+35项覆盖检查
写入正文:04|产业关系:大股东、扩张载体和提携伙伴共同决定经济与控制权怎样到达上市股东
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(25项,重复标签已合并)
Issuer identity: GECOSS Corporation, TSE Prime 9991, EDINET E02782, business since 1968怎么使用:直接 / 支持;一手验证:01
FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields怎么使用:直接 / 支持;一手验证:02、03、05、08、09、10、15
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接 / 支持;一手验证:01、23、24;外部现实校验:07
The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025怎么使用:直接证据;一手验证:07;外部现实校验:23
FUCHI step-acquisition mechanics: how one deal produced both a JPY 401 million gain and a JPY 418 million loss怎么使用:直接证据;一手验证:32;专项深挖:32
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:直接证据;一手验证:04、07
Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition怎么使用:直接证据;一手验证:18
The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin怎么使用:直接证据;反向验证:04;专项深挖:04
Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%怎么使用:直接证据;一手验证:03、04、08、11;专项深挖:03
Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high怎么使用:直接证据;一手验证:05、10、11、12、14
H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items怎么使用:直接 / 支持
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接证据;一手验证:06、18、19、20、21
Steel-cycle frame: the parent industry is customer, supplier and shareholder at once怎么使用:直接证据;一手验证:14
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%怎么使用:直接证据;一手验证:27、31;外部现实校验:01、02、03、05、06、08、09、11、12、13、14、15、16、17、18、19、20、21、22、24、25、26、28、29、30、32、33、34、35
Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach怎么使用:直接证据;一手验证:13、23
The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026)怎么使用:直接证据;反向验证:13;专项深挖:13
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接证据;一手验证:35
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接 / 支持;一手验证:35;反向验证:12、30;专项深挖:16、35
5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75怎么使用:直接证据
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接证据;反向验证:05、11;专项深挖:05、11
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|Issuer identity: GECOSS Corporation, TSE Prime 9991, EDINET E02782, business since 1968;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10) / 一手证据(研究域15)|FY3/2026 segments (profit measured on the ordinary-profit basis) and business fields;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 一手证据(研究域07) / 外部现实(研究域23)|The Mizuho Lease alliance: capital and business alliance of April 2024, extended into the machinery business in September 2025;直接证据|H1 FY3/2027 segments: heavy temporary works JPY 4,403 million of ordinary-basis profit; machinery profit up 34% on used-asset sales;直接证据|FUCHI Pte. Ltd. (Singapore): from equity-method affiliate to 70%-owned consolidated subsidiary in August 2025;直接证据 / 一手证据(研究域32) / 定向深挖(研究域32)|FUCHI step-acquisition mechanics: how one deal produced both a JPY 401 million gain and a JPY 418 million loss;直接证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October);直接证据|FY3/2026 cash flow: operating inflow of JPY 10,661 million funds everything;直接证据 / 一手证据(研究域18)|Balance sheet at September 2026: equity ratio 59.2%, cash JPY 12,404 million, goodwill up on the JS Tan acquisition;直接证据 / 反证(研究域04) / 定向深挖(研究域04)|The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin;直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域08) / 一手证据(研究域11) / 定向深挖(研究域03)|Field dynamics inside heavy temporary works: materials flat by policy, works +17.6%, fabrication -5.2%;直接证据 / 一手证据(研究域05) / 一手证据(研究域10) / 一手证据(研究域11) / 一手证据(研究域12) / 一手证据(研究域14)|Demand environment per the filings: capital-region redevelopment firm, public works stable, labour tight and construction costs high;直接证据 / 支持证据|H1 FY3/2027 results (5 November 2026): operating profit JPY 4,190 million, +12.3%, with no special items;直接证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 一手证据(研究域14)|Steel-cycle frame: the parent industry is customer, supplier and shareholder at once;直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域11) / 外部现实(研究域12) / 外部现实(研究域13) / 外部现实(研究域14) / 外部现实(研究域15) / 外部现实(研究域16) / 外部现实(研究域17) / 外部现实(研究域18) / 外部现实(研究域19) / 外部现实(研究域20) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域30) / 外部现实(研究域32) / 外部现实(研究域33) / 外部现实(研究域34) / 外部现实(研究域35)|Market snapshot, 6-9 November 2026: price JPY 1,755, capitalisation about JPY 59.3 billion, forward PER 9.4 times, PBR 0.82 times, yield 4.27%;直接证据 / 一手证据(研究域13) / 一手证据(研究域23)|Governance and engagement cadence in 2026: audit-committee transition, a shareholder-benefit scheme, personal-investor outreach;直接证据 / 反证(研究域13) / 定向深挖(研究域13)|The PBR path: just under 0.5 times (September 2024) to about 0.7 (November 2025) to 0.82 (November 2026);直接证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed;直接证据 / 支持证据|Forecast arithmetic: the revised FY3/27 plan requires a second-half operating profit of JPY 5,010 million, +17% on the prior second half;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据|5 November 2026: full-year forecast raised across the board and the dividend lifted to JPY 75;直接证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set
完整研究记录(核对用)
研究原文:Industrial relationships, ownership vehicles and policy actors|Anchor shareholders, expansion vehicles, end markets and policy actors form the relationship matrix through which economics and control reach the listed shareholder.
内部研究类型:INDUSTRIAL_RELATIONSHIP_MAP
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Ecosystem health shows up in segment mix and register behaviour before group revenue.
不确定性(原始记录):Alliance terms and vehicle-level returns undisclosed.
F106|13|十个未决问题多数只能等披露来回答
研究范围:开放研究+35项覆盖检查
写入正文:13|十个未决问题多数只能等披露来回答15|证据的限制:哪些事实尚未核实,会怎样限制判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(21项,重复标签已合并)
Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement怎么使用:直接证据;一手验证:35;反向验证:12、30;专项深挖:16、35
Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set怎么使用:直接证据;反向验证:05、11;专项深挖:05、11
Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%怎么使用:直接证据;一手验证:16
Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure怎么使用:直接证据;反向验证:06、14;专项深挖:06、14
Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment怎么使用:直接证据;一手验证:13;外部现实校验:04、10
Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed怎么使用:直接证据;一手验证:35
Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated怎么使用:直接证据;一手验证:26;专项深挖:26
Equity walk and treasury: retained earnings compound; buybacks are historical, not current怎么使用:直接证据;一手验证:25
Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals怎么使用:直接证据;反向验证:23
The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin怎么使用:直接证据;反向验证:04;专项深挖:04
Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October)怎么使用:直接证据;一手验证:04、07
FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million怎么使用:直接证据;一手验证:06、18、19、20、21
Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales怎么使用:直接证据;反向验证:03、07;专项深挖:07
Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary怎么使用:直接证据;一手验证:01、23、24;外部现实校验:07
Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided怎么使用:直接证据;反向验证:24;专项深挖:24
The rental asset base: JPY 28,244 million of steel materials and JPY 33,133 million of inventories fund the model怎么使用:直接证据;一手验证:09、20;反向验证:10;专项深挖:10、20
Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%怎么使用:直接证据;一手验证:22;反向验证:09;专项深挖:09
Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation怎么使用:直接证据;一手验证:21、29;反向验证:20;专项深挖:18、21
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域30) / 定向深挖(研究域16) / 定向深挖(研究域35)|Implied second half in detail: sales JPY 60,905 million, operating profit JPY 5,010 million, an 8.2% margin requirement;直接证据|Forecast arithmetic: the revised FY3/27 plan requires a second-half operating profit of JPY 5,010 million, +17% on the prior second half;直接证据 / 反证(研究域05) / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域11)|Order visibility: no backlog is disclosed; contract liabilities (+75.1%) are the closest demand sensor in the filing set;直接证据 / 一手证据(研究域16)|Margin bridge: gross margin 20.9% to 22.9% to 23.5%; operating margin 6.1% to 6.9% to 7.3%;直接证据 / 反证(研究域06) / 反证(研究域14) / 定向深挖(研究域06) / 定向深挖(研究域14)|Labour, costs and the pass-through contest: the filings name both the headwind and the countermeasure;直接证据|Distribution-sales suppression in detail: the FY3/25 revenue fall of JPY 16.6 billion was the policy, not the market;直接证据 / 一手证据(研究域13) / 外部现实(研究域04) / 外部现实(研究域10)|Mid-term plan (2025-2027): operating profit is the headline KPI, PBR of at least 0.8 times is the capital target, about JPY 25 billion of growth investment;直接证据 / 一手证据(研究域35)|Plan scoreboard at the plan's midpoint: operating profit tracking +34% over two years; the JPY 25 billion investment envelope partly deployed;直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|Payout arithmetic: 40.1%, 39.7%, and 40.1% forecast - a de facto 40% rule, unstated;直接证据 / 一手证据(研究域25)|Equity walk and treasury: retained earnings compound; buybacks are historical, not current;直接证据 / 反证(研究域23)|Capital and corporate instruments in motion during 2026: two dividend raises, a benefit scheme, a governance transition, two deals;直接证据 / 反证(研究域04) / 定向深挖(研究域04)|The overseas book: goodwill of JPY 1,494 million, no geographic revenue split in the tanshin;直接证据 / 一手证据(研究域04) / 一手证据(研究域07)|Overseas expansion in 2026: JS Tan Consultants consolidated (July), a business alliance with Nihon Kiso Gijutsu (October);直接证据|FUCHI Pte. Ltd. (Singapore): from equity-method affiliate to 70%-owned consolidated subsidiary in August 2025;直接证据 / 一手证据(研究域06) / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域20) / 一手证据(研究域21)|FY3/2026 balance sheet: 58.2% equity ratio, rental steel of JPY 28,244 million, borrowings of only JPY 2,909 million;直接证据 / 反证(研究域03) / 反证(研究域07) / 定向深挖(研究域07)|Construction machinery: a small segment being rebuilt with a leasing partner, profit partly from asset sales;直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24) / 外部现实(研究域07)|Ownership (31 March 2026): JFE group 39.49% of voting rights, Mizuho Lease 20.04% - an equity-method affiliate, not a subsidiary;直接证据 / 反证(研究域24) / 定向深挖(研究域24)|Float and liquidity: about 40% free float on anchored registers; margin-buy balance small but one-sided;直接证据 / 一手证据(研究域09) / 一手证据(研究域20) / 反证(研究域10) / 定向深挖(研究域10) / 定向深挖(研究域20)|The rental asset base: JPY 28,244 million of steel materials and JPY 33,133 million of inventories fund the model;直接证据 / 一手证据(研究域22) / 反证(研究域09) / 定向深挖(研究域09)|Segment asset intensity: heavy temporary works holds JPY 119,607 million of assets for a 7.2% ordinary return; machinery 4.1%;直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 反证(研究域20) / 定向深挖(研究域18) / 定向深挖(研究域21)|Net financial assets: about JPY 14.0 billion at September 2026, about 24% of the market capitalisation
完整研究记录(核对用)
研究原文:Carried Research Debt with resolving evidence|Ten unresolved questions, mostly dependent on future disclosure (Q3 tanshin, May 2027 print and successor framework, June 2027 notices) or on documents not retrieved; none has a reasonable current public path likely to change the judgment.
内部研究类型:RESEARCH_DEBT_SET
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The first three (second-half delivery, margin ceiling, successor commitments) are priority 1 and decide the Thesis.
不确定性(原始记录):No new public research is currently justified; future disclosures resolve them.
F107|10|要回答的问题:1,940日元的旧高点,是被盈利正式超越,还是2014年冲高失败的重演
写入正文:10|要回答的问题:1,940日元的旧高点,是被盈利正式超越,还是2014年冲高失败的重演10|二十多年的底部、一次失败的冲高和一次台阶式突破10|回撤精确停在旧上沿:压力位变成了支撑位10|2026年的高点没有出现2015年那样的高潮放量10|价格重心、压力位与支撑位:现在处在历史上几乎没有成交的区域10|旧记忆仍在,承接力也在:上行像台阶,下行可能很快10|迁移质量:台阶式的收盘、渐进的放量,没有对应2015年的高潮10|当前状态:突破成立、仍在消化,高度与买盘之间有一处矛盾10|价格后续要出现什么才算确认,出现什么就被推翻14|Kabugami 技术结构 9.1/13 分:旧压力位变支撑,但月收盘尚未站稳1,931日元
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (dereference-only)
内部研究类型:PROTECTED_TECHNICAL_SYNTHESIS
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | 4eedf28df05f1b4ebc0c85de2dbda4f8a6babc89 |
| Delivery Commit SHA | 4eedf28df05f1b4ebc0c85de2dbda4f8a6babc89 |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | ff9c0833-c182-532c-927f-f2df6b6a3197 |
| Canonical Revision | 1 |