市值294.7亿日元,而2026年6月底的现金和投资证券合计接近400亿日元;权益比率69.8%,2026年3月期利息保障倍数87倍,没有发行新股。分红连续五年提高,每股从8.0日元升到25.3日元,2027年3月期预测30.6日元,按648日元计股息率4.72%。
5363
東京窯業株式会社(TYK CORPORATION)
東京窯業株式会社(TYK CORPORATION,东证 Standard 市场,代码5363)主营钢铁厂炼钢用的耐火砖和不定形耐火材料,同时生产非铁金属熔炼用的石墨坩埚和精细陶瓷,另经营环境设备、窑炉机械、施工、维修和运输等小业务。公司1947年创立,运营基地在岐阜县多治见,2026年10月14日起在名古屋证券交易所 Main 市场同步上市。
最近亮点:2026年11月4日,公司确认出售東北特殊鋼(Tohoku Special Steel)股份,实现20.97亿日元出售收益,并表示无需修改2027年3月期预测;这笔收益自5月起就已计入45.30亿日元的净利润预测。确认之后股价回落到11月6日的648日元。下一个节点是11月12日的中期业绩。
主业需求跟着日本粗钢产量走,2026年3月期粗钢产量下降3.2%,销量上限逐年下移;证券组合又会在同一次衰退里和钢铁需求一起受损。股东登记簿由钢铁伙伴、银行和客户构成,外部没有力量推动资产释放,折价只能靠分红公式缓慢收窄。日均成交只有6.8万股左右,大额持仓退出需要时间。
结论:综合得分63.23/100(评分版本V3.2),评级B,持有型配置,不追高。折价如果收窄,靠的是按30%左右派息率执行的分红公式,增长和一次性重估都不是主要路径;土地价值、证券组合构成和新材料业务经济性目前无法核实,限制了对安全边际和增长的判断强度。 依据:现金加证券高于市值,权益比率近70%,分红在营业利润下降23.6%的年份仍提高19%;价格上2023年以来年度低点逐年抬高,但已处在上市以来的最高区域。 翻转条件:2027年5月的年末分红低于21.3日元且没有经营原因,或下一期计划放弃30%派息承诺。 估值简报(价格截至2026年11月6日收盘):股价648日元/总市值294.7亿日元/预测PER 6.4倍(该预测含20.97亿日元一次性收益,正常化后倍数更高)。实绩PBR 0.61倍(按2026年3月期末每股净资产1,061.72日元)/ROE 8.5%(2026年3月期实绩)/预测股息率4.72%(按2027年3月期预测分红30.6日元)。EV/EBITDA 3.4倍(EV 156.4亿日元=总市值减2026年6月30日净现金138.3亿日元)。EBITDA 45.8亿日元=2026年3月期营业利润34.42亿日元加折旧11.34亿日元,资产负债表日与利润期间不同。 当前动作:持有型配置,不追高。核心逻辑是约4.7%的公式化股息加缓慢折价收窄,而不是增长或事件驱动的重估。2026年11月12日的中期业绩、2027年5月的年末分红和中期计划修订,是依次检验分红渠道的节点;在这些节点确认派息路径不变时可继续持有或在回调中分批增加。不为2028年的计划目标付费。头寸大小要考虑流动性,块头资金退出需要时间。若年末分红低于21.3日元且没有经营原因,或30%派息承诺被放弃,需要重新评估。
报告目录
01|投资问题与当前结论
01.1|折价能否靠分红公式收窄,要比国内需求萎缩得更快
当前判断:持有型配置,不追高;综合得分63.23/100,评级B。折价如果收窄,靠的是分红公式,增长和一次性重估都不是主要路径。
公司市值294.7亿日元,低于2026年6月底的现金和投资证券合计400亿日元左右。资产摆在公司里,少数股东却拿不到:登记簿由钢铁伙伴、银行和客户组成,防御政策连年续期,没有外部力量推动公司释放资产。折价因此是治理上的价格。
那么钱靠什么到达少数股东?目前只有一条被验证的路:30%左右的派息率,机械地用在含证券收益的净利润上。每股分红从2022年3月期的8.0日元升到2026年3月期的25.3日元,2027年3月期预测30.6日元。2026年3月期营业利润下降23.6%,分红仍提高19%。按648日元计,预测股息率4.72%。
问题就变成速度之争:分红推动的折价收窄,对比日本钢铁产量下降造成的主业萎缩。2022年3月期至2027年3月期的记录里,分红在缓慢获胜,2023年以来的股价阶梯已经反映了这一点。每年11月的中期业绩和5月的全年业绩,都会重新确认或改写派息路径。这一判断把握一般,取决于公式能否延续,以及会不会出现回购、提高派息比例这类加快收窄的机制变化。
操作上,2026年11月12日的中期业绩、2027年5月的年末分红和中期计划决定,是依次检验分红渠道的节点。节点确认派息路径不变时,可以继续持有,或在回调中分批增加。2028年度的计划目标不值得为之付钱。仓位要按流动性来定,大额资金退出需要谈判。
01.2|分红渠道断掉的四个信号
这个判断可以被日期明确的事实推翻:2027年5月决定的年末分红低于21.3日元且没有经营原因;下一期计划放弃或稀释30%派息承诺;营业利润连续两年低于30亿日元;证券变现停止。每一项发生,都意味着过去唯一在收窄折价的机制失效。逐项怎样检验,见第11章。价格结构自己的失效条件另列在第10章,与这里互不替代。
02|公司本质与商业模式
02.1|股东实际拥有的是一个母公司加子公司、没有控股股东的集团
東京窯業株式会社(TYK CORPORATION)1947年2月5日创立,法定总部在东京都港区,运营基地在岐阜县多治见。股票在东证 Standard 市场上市,2026年10月14日起在名古屋证券交易所 Main 市场同步上市,没有控股股东。母公司注册资本23.98亿日元,母公司员工400人,集团员工合计927人左右。
业务按单一可报告分部(耐火材料相关)披露,再按日本、北美、欧洲、亚洲分地区。核心产品是钢厂用的耐火砖和不定形耐火材料、非铁金属用石墨坩埚,以及精细陶瓷;环境设备、窑炉机械、施工、维修和运输归入「其他」。
看公司时要先分清母子。2026年3月期母公司单体营收252.88亿日元、净利润27.75亿日元,合并口径为314.85亿日元和37.41亿日元。子公司因此贡献了五分之一左右的营收和四分之一左右的利润,其中一部分利润由外部少数股东分享,对股东的影响见第6章。
还有一处身份信息没有解释:公司现在的展示名称写作「TYK (Tokyo Yogyo)」,没有任何来源说明这是更名还是重组。
02.2|长期面貌:一个把钢铁需求转成现金的小众产品,加一个比工厂还大的证券组合
这家公司的长期结构不靠增长支撑,十年来也没有增长。它由四块拼成:一个有专利深度的耐火材料利基,把正在缩小的钢铁需求转成稳定现金;一个比厂房资产还大的证券组合,每年带来股息,并不时在友好的产业圈内按全价变现;一张几乎抗冲击的资产负债表;以及一个公开的派息公式,2023年以来把经营和组合利润的30%左右传给少数股东。
不耐久的部分同样清楚:日本粗钢产量每年下降,增长业务无法验证,保护这套结构的封闭性也限制了价值传到股价的速度。2022年3月期至2027年3月期的证据显示,这是缩小的钢铁需求和不断累积的分红之间的赛跑,分红在缓慢领先。厚实的资产负债表还资助了海外本地制造,今天它成了经营上的对冲。
股东拿到的是一个双引擎的权利,慢速的工业年金加一个金融组合,放在封闭的股东结构里。回报按公式速度到达,净现金和资产保护缓冲下行,主要风险是多年的时间成本,不是偿付。
几件事尚未查清:一个完整投入成本周期里的日本分部利润率、先进材料的经济性、证券组合构成和土地价值。在严重衰退里,两个引擎还会同时受损。
03|产品、客户与供应链
03.1|需求跟着日本粗钢走,销量上限每年下移
耐火材料在炼钢中被消耗,需求跟粗钢产量走,中间隔着钢厂换衬的时滞。日本粗钢产量2026年3月期下降3.2%,为8,033万吨,处在长期下降通道。日本分部贡献了五分之四的分部利润,2026年3月期为30.88亿日元,同比下降22.1%,原因是销售结构变差。
2027年3月期一季度(4–6月)更能看出问题所在:粗钢产量上升1.0%到2,035万吨,日本分部营收却下降9.3%到52.61亿日元,利润下降26.2%到7.53亿日元。缺口出在钢厂的需求结构和下单时点,不是产量塌陷。订单积压、客户集中度,以及钢产量和公司订单之间的时滞,公司都没有披露。
客户和股东在很大程度上重叠。JFE Steel既是客户,又持股4.19%。钢铁企业一方面决定着核心业务的需求,一方面坐在股东登记簿上,这让订单更稳,也让控制权更稳。
日本粗钢产量的序列,设定了正常化营业利润的国内销量上限,每一个国内销量假设都从它出发。要避免的错误,是把它当作会向上拐头的周期。
03.2|海外利润在填补国内缺口,但只有一个季度的数据
2027年3月期一季度,北美营收增长8.2%到11.13亿日元,利润增长79.1%到1.06亿日元;欧洲营收增长17.3%到12.69亿日元,利润增长58.3%到1.18亿日元;亚洲营收持平,利润下降10.0%到0.18亿日元。海外占分部利润的比例,从此前财年的九分之一左右升到四分之一左右。
原因在本地制造。北美和欧洲在当地生产、当地销售,集团利润不再和日本粗钢产量一一对应。这是经营业务里唯一在改善的特征。
但基数很小,只有一个季度,亚洲还在走弱。从集团内部结构看,日本母公司一季度集团内部销售10.53亿日元,对外营收52.61亿日元,北美和亚洲几乎没有内部销售,说明出口和供应中心在日本母公司,海外子公司以本地制造销售为主。因此海外利润增长不应读成母公司出口走强:转移结构和当地需求决定海外利润,两者都没有披露,也影响母子之间利润归属和少数股东分走的部分。
这块利润还带着政策变数。2026年3月期北美营收下降12.5%到40.69亿日元,利润下降33.4%到2.92亿日元,公司把原因归于美国关税政策。关税敏感度和对冲比例都没有披露,关税消息可能先于销量影响分部利润。
集团的资产负债表厚度是海外本地制造的资金来源:过去的保守,成了今天的分散。海外的稳定是目前的证据,国内销量回升则是需要避免的误判。
03.3|计划里的增长业务,从披露中看不见
中期经营计划把增长交给先进材料和环境创造,加上海外耐火材料,国内耐火材料被定位为大而低增长的现金来源。但业绩文件从未单独列出这两块业务。
能看到的只有「其他」类:环境设备、窑炉机械、施工、维修和运输。2026年3月期营收3.40亿日元,约占集团1%,分部利润1.11亿日元;2027年3月期一季度营收0.84亿日元,利润0.40亿日元。利润率不低,但基数很小,更像耐火材料周边的服务性业务,还不是第二引擎。
计划也没有披露新材料的分部营收目标。外部读者因此无法从披露中验证增长这条腿,市场拒绝为它定价,是对一个无法验证的说法的理性反应。公司是否会单独披露这些业务的营收和利润,是下一次需要追踪的问题。
04|竞争格局与产业关系
耐火材料的竞争在两端不同。功能性高端产品,也就是流量控制、吹气搅拌和测量类,经过钢厂认证后替换成本较高;通用耐火砖则按价格切换,公司自己也承认价格竞争激烈。2026年3月期毛利率从28.6%降到26.4%,反映了产品结构上的争夺正在发生。
竞争对手的价格、产能和客户关系,本次研究没有读到,行业份额数据公司也没有披露,因此市场地位只能是结构性推断。产业关系上,钢铁圈既是客户也是股东,细节见第7章;这层关系稳定订单,同时让价格谈判带上关系约束。
05|护城河判断
05.1|护城河护住的是单价,不是销量
公司持有364项专利、40项外观设计和26项商标,员工平均工龄男性18.4年、女性16.5年。这些结构性证据,加上功能性产品在钢厂的认证黏性,支撑了一个高端利基:吨位下降时,守住单价和产品结构。
这层保护只到价格为止。通用砖类按价格切换,2026年3月期产品结构变差,毛利率下降2.2个百分点。壁垒是局部的,所以股东在价格上有保护,在数量上没有。日本分部的毛利率和利润,是最直接的预警指标。
证据本身偏间接:专利数量、工龄和股东登记簿的重叠,不是客户留存率或实现的价格溢价。公司没有披露后两者,竞争对手一侧的证据也没有取得,所以护城河到底有多厚,外部无法验证。这块利基同时是长期面貌里最可信的一块,也是先进材料故事要长出来的种子。
05.2|一组没有披露的数据,限制了对护城河和增长的信心
研究在以下项目上停在了披露边界:产品层面的收入、价格和利润;客户集中度和订单积压;供应商集中度、合同期限和对冲比例;研发投入和专利产品收入占比;客户留存率和实现的价格溢价;市场份额;ROIC和资本成本门槛;分项目资本开支;客户付款条件;钢产量与公司订单之间的时滞。
这些项目目前都没有公开路径,公司不单独披露本身不算已经查清,它们逐项保持为未知,没有被当成确定的好或坏。其合计后果是,护城河、正常化盈利和增长三个判断都不宜给出过高的把握。下一批可用的证据,是中期计划更新里的产品或分部拆分,以及今后业绩快报的文字说明;每次公布时的分部利润率,是目前可用的替代观察指标。
06|财务质量与现金流
06.1|营业利润降了、净利润反而升了:这是同一个机制,不是两个故事
2026年3月期营业利润下降23.6%到34.42亿日元,净利润却增长19.5%到37.41亿日元。先看营业线:产品结构变差,毛利从91.35亿日元降到83.02亿日元,毛利率从28.6%降到26.4%;销管费从46.32亿日元增加到48.60亿日元;两项合计,营业利润少了10.62亿日元。
营业线以下,利润被两次补回。受取股息4.04亿日元、汇兑收益2.63亿日元,把经常利润托到42.69亿日元(同比下降15.2%);特别利益里11.90亿日元的证券出售收益,则让净利润反超。
这类出售收益不是一次性的。2025年3月期已有3.74亿日元,2027年3月期预计20.97亿日元,年年出现,每年净利润的增长主要取决于卖了多少。对照2025年3月期:营业利润45.04亿日元(近年峰值),经常利润50.33亿日元,净利润31.30亿日元。
所以营业线才是耐火材料业务的真实尺度,净利润被投资组合托高。证券收益里有多少来自交叉持股解除、多少来自主动交易,除已披露的具体交易外没有拆分。
06.2|正常化盈利:经常利润36亿至42亿日元,不含出售收益
把这几层拆开后,正常化盈利可以这样估:经常利润在36亿至42亿日元,其中营业核心32亿至36亿日元。组合带来的经常性收益5.5亿日元左右,包括股息(2025年3月期3.66亿日元、2026年3月期4.04亿日元)和利息、租金合计1.5亿日元上下。汇兑当作均值为零的噪音。不含证券出售收益的正常化净利润,在26亿至30亿日元。
以此对照,计划里2028年度58亿日元的营业利润目标,按现有证据不是一个正常年份。2027年3月期预测营业利润35.50亿日元,落在营业核心区间的上沿,预测净利润45.30亿日元则含20.97亿日元出售收益。
日本粗钢产量的下降设定了营业核心的上限,正常化中的每个国内销量假设都在它之下。这一区间是研究推断,不是公司披露;三年的数据窗口也看不到一个完整投入成本周期里的日本分部利润率。
06.3|资产负债表几乎抗冲击:问题不在偿付,而在谁能拿到
权益比率从2022年3月期到2026年3月期依次为67.3%、68.7%、68.9%、69.1%、70.4%,2026年6月底约为69.8%。2026年3月期利息保障倍数87.2倍,现金流量对有息负债为1.1年,短期借款34亿日元左右且多年不变,从未发行新股,没有稀释。
市值占总资产的比例五年里从未超过37%(27.5%、29.2%、36.9%、36.4%、36.6%),说明折价是长期现象,不是某个事件造成的。资本政策的问题因此不是筹资,而是留着不用。
06.4|资产负债表的重心已经移到证券组合上
2026年6月底,现金171.88亿日元,投资证券229.87亿日元,合计400亿日元左右,对比294.7亿日元的市值,权益比率69.8%。一个季度里,总资产从669.95亿日元升到724.93亿日元,几乎全由投资证券带动。证券增加53.89亿日元(新购入加按市价重估),权益里的证券估值准备金从74.86亿日元升到107.50亿日元,递延税负债从27.83亿日元升到43.01亿日元。
市场实际上是在给耐火材料业务、厂房和土地一个扣税和扣少数股东之前为负的价值。问题不是资产是否存在,而是少数股东能否拿到。计算时要注意口径:这里用的是11月6日股价对6月30日资产负债表,证券按市价,现金里有一部分是合并现金。
另一道扣减是少数股东。非控制权益68.41亿日元,占净资产12.7%,2026年3月期分走利润3.66亿日元(2025年3月期为6.70亿日元),并领取分红1.74亿日元。集团利润和资产里总有一小块到不了母公司股东手里;哪些子公司承载少数股东、其现金能否上交,目前资料没有给出细节。
06.5|利润能转成现金,但设备已经折旧到底,回报被抬高了
2026年3月期经营现金流30.63亿日元(下降7.1%),对营业利润34.42亿日元的转化尚可。投资现金流出15.49亿日元(设备加购入证券),筹资现金流出11.49亿日元(主要是分红),所有投资之后的自由现金流分红前为15亿日元左右。
2026年6月底应收款94.70亿日元,存货114.93亿日元(其中原材料41.78亿日元),对照单季营收79.46亿日元。对于按订单生产的供应商,这是沉重但稳定的占用,相对400亿日元的现金和证券变化很慢。原材料和能源成本的时滞,是毛利率的变量,通过提价部分转嫁,但有延迟。客户付款条件、应收款转让、供应商集中度和对冲安排都没有披露,一季度也没有单独的现金流量表。
生产设备方面,有形固定资产净值只有101.82亿日元,窑炉和机械原值218.76亿日元、累计折旧196.98亿日元,已折旧九成左右。在建工程从6.45亿日元降到1.89亿日元,年末没有大型产能项目在建。2027年3月期一季度折旧增长14%到2.75亿日元(上年同期2.40亿日元),替换周期开始转动。收益基础压在折旧殆尽的设备和账面49.28亿日元的土地上,将来重建会先压低回报再提高,分项目资本开支和维持性与增长性的拆分也没有披露。
06.6|ROE是政策维持出来的数字,不是经营赚出来的
2026年3月期ROE为8.5%,2027年3月期预测8.95%,都达到了计划8%以上的底线。但分子里含组合收益和出售收益,分母每年随留存的估值收益变大:留下70%左右的利润,以单位数回报累积,权益增长就快于营业利润增长。
结果是,ROE成了组合必须不断喂养的跑步机,派息公式也顺带在维持这个比率。要靠营业利润单独守住8%,目前还没有证明。管理层的资本成本和ROIC都没有披露,ROE在经营、组合收益和出售收益三部分的拆分也不可得。
06.7|三种会计呈现,会让只看一行数字的人两头判错
这家公司的账目是诚实的(日本会计准则,一季度财务报表经Fujimi Audit Corporation中期审阅),但三种呈现容易产生误导的标题。其一,2025年3月期到2027年3月期,净利润增长由证券收益决定。
其二,综合收益被组合市价变动主导:2027年3月期一季度综合收益42.37亿日元,其中32.83亿日元是证券未实现收益;母公司综合收益41.24亿日元,母公司净利润只有7.90亿日元,组合把权益账户抬高的速度是经营赚钱速度的五倍。其三,递延税负债一个季度就增加15.18亿日元,是这些估值收益的税影;季度税费按全年预估有效税率计算,季度净利润会随预测口径波动。
这些规则解释了为什么每个口径给出不同的故事,也解释了为什么只看一行的筛选会在两个方向上错判公司。证券组合里有没有藏在准备金里的未实现亏损,从汇总数字看不到。
07|股东、董事与治理
07.1|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产
大规模收购应对方针(防御政策)2026年5月19日再次续期,此前2014年、2017年、2020年、2023年一路续期。前十大股东合计47.8%左右,没有活跃投资者,也没有能单独行动的持股方;2019至2020年以后没有回购;市净率十六年一直在0.25倍至0.88倍之间。
管理层是传统董事会,社长牛込伸孝,2026年6月例行改选,没有代表人变更。约束公司的只有计划里公布的承诺。记录里没有任何东西迫使资产释放,所以折价是治理上的价格,只有分红公式能缓慢侵蚀它。
因此这条结论分两头:认为管理层会被迫释放资产的逻辑,与记录相矛盾;只需要耐心等分红公式的逻辑,与记录相符。后者有证据:公式连续三年按承诺兑现。董事会技能构成和完整的治理报告没有单独读到。
07.2|股东登记簿就是客户、贷款人和钢铁伙伴的名单
2026年3月期前十大股东依次是:大同特殊钢(Daido Steel)11.75%,瑞穗银行4.98%,十六银行4.87%,大垣共立银行4.87%,爱知银行4.36%。其后是JFE Steel 4.19%,冈谷钢机4.12%,中部钢板3.06%,日本制钢所3.03%,山口银行2.47%,合计47.7%至47.8%。
这份名单是客户、贷款人和钢铁伙伴,而且持股不动。JFE既是客户又是股东。大同特殊钢同时是第一大股东、東北特殊鋼的要约方和交易对手。瑞穗和四家地方银行构成传统的稳定股东,它们支撑防御姿态和公司极低的借款成本,也最不可能要求释放资产。
有一处算术需要更正:资料里引用的大同加银行合计26.5%,与个别持股加总不符。五家银行合计21.5%左右,加上大同是33.3%,钢铁伙伴四家合计14.4%,所以本报告采用个别持股数据。信托银行名下的实益持股看不到,大同是否打算进一步调整涉及公司的钢铁圈持股网络,也没有披露。
07.3|中期计划同时承载增长承诺和分红承诺,两条腿可以分开兑现
中期经营计划(2024–2028年度,2023年11月14日公布)要求2028年度营收440亿日元以上(以2023年度300亿日元预测为起点)、营业利润58亿日元以上(起点32亿日元)、ROE 8%以上、派息率30%以上并持续提高每股分红。
2026年3月期营收314.85亿日元、营业利润34.42亿日元,距目标很远;两年内营收需要年复合增长18%左右(该数字是推算),而2027年3月期一季度营收又下降了。计划今天只是方向声明,不是预测。回报和派息两条腿在纸面上已经达成,ROE 8.5%、派息率30.1%,但是靠证券出售收益,不是靠经营增长。
同一份计划既是增长承诺又是分配承诺,所以增长这条腿可以失败,分配这条腿照样兑现。增长被分配给了账目里无法单独看到的业务,市场对此不定价(预测PER 6.4倍、市净率0.6倍上下),是对无法验证的说法的理性反应。公司会修订、推迟还是照旧,要到2027年5月才知道。不要为计划目标付钱。
07.4|社长继任和董事会结构没有披露
2026年6月的董事会改选只新增了一名管理部门董事、一人退任,社长未变。继任路径是否存在、董事会内经营、管理和外部董事的比例有没有变化,所读资料都没有给出。在这样封闭的股东结构下,领导层更替是资本政策出现变化的一个自然时点,因此这一空白会影响判断。可能的解答来自治理报告、股东大会材料或继任公告。
08|资本政策
08.1|分红公式把证券收益也分给了少数股东
每股分红依次为:2022年3月期8.0日元(派息率20.4%)、12.0日元(25.1%)、16.2日元(30.2%)、21.2日元(30.0%)、2026年3月期25.3日元(30.1%)。2027年3月期预测30.6日元,由中期9.3日元和年末21.3日元组成。计划承诺30%以上并持续提高,2024年3月期到2026年3月期的派息率与承诺吻合。零碎的日元数就是公式的指纹。
2026年3月期宣布分红9.78亿日元(上年7.40亿日元),其中付给母公司股东9.76亿日元、付给少数股东1.74亿日元,留存收益仍从312.60亿日元增加到340.24亿日元。库存股稳定在2.41亿日元左右。营业利润下降23.6%的年份,分红提高19%,因为公式机械地适用于净利润,含证券收益,所以组合收益会以分红的形式到达少数股东。
这也是折价收窄的速度:折价按公式的速度收窄,不按资产价值的速度。按648日元,预测股息率4.72%。公式在计划期之后是否延续没有证明;计划写的是「30%以上」,管理层可以提高,但没有披露触发条件。
08.2|東北特殊鋼的出售:第一次证明隐含资产能按全价变成现金
2026年5月15日(董事会决议为5月11日),公司与大同特殊钢签订不参加要约协议:大同是東北特殊鋼收购要约的发起方,也是公司的第一大股东(11.75%)。公司不应募,在合并挤出的临时股东大会上投赞成票,之后把持有的全部東北特殊鋼股份卖给東北特殊鋼自己。20.97亿日元的收益,从5月19日起就写进了2027年3月期净利润预测45.30亿日元;11月4日出售实现,通知确认不修改预测。
这笔收益是真实的现金,但它是在钢铁圈内谈出来的,不是市场发现的。它是对隐含资产能否按全价变现的第一个大规模证明,也是剩余组合以后如何变现的模板,节奏由这个圈子决定。20.97亿日元约占市值的7%(跨越不同日期的推算比较),经年末分红进入30%公式。市场对已知消息不再付钱:确认之后价格回落。剩余持股是否还有类似交易,没有披露。
08.3|自2019至2020年回购以后,股东回报只有分红
记录里最近一次回购是2019年6月决议、2020年初前每月公告进度,伴随2019至2020年的员工持股信托(ESOP)和2020年3月向第三方配售处分库存股。2021至2026年没有回购授权,库存股静止在2.41亿日元左右。
权益比率接近70%,现金加证券高于市值,股价约0.6倍账面价值。在这样的条件下,回购会是加快折价收窄最有力的工具;没有回购,就把折价留给了按公式速度的缓慢侵蚀,留存的现金只能以单位数回报累积或闲置。下一期计划是否加入回购,还是这个缺席是一个少数股东应当视为长期的稳定偏好,目前没有任何披露信号,也是最大的变数。
08.4|名古屋同步上市不改变股本和价值
2026年10月14日起,公司在名古屋证券交易所 Main 市场同步上市(ISIN JP3589400005,交易单位100股),不发行新股、不融资、不改变控制权的算术。它是面向多治见和岐阜本地投资者的曝光措施,影响只可能通过流动性和关注度传导。目前还没有证据显示交易变得更深,11月初日均成交约6.8万股。
09|估值与安全边际
09.1|估值简报:低倍数,低于账面价值,但口径要分清
价格截至2026年11月6日收盘。股价648日元;总市值294.7亿日元(已发行4,547.7万股);预测PER 6.4倍,基于2027年3月期预测EPS 101.95日元,而该预测含20.97亿日元一次性收益;实绩PBR 0.61倍(按2026年3月期末每股净资产1,061.72日元);ROE 8.5%(2026年3月期,公司口径实绩);预测股息率4.72%(预测分红30.6日元);EV/EBITDA 3.4倍,其中EV 156.4亿日元=总市值减2026年6月30日净现金138.3亿日元,EBITDA 45.8亿日元=2026年3月期营业利润34.42亿日元加折旧11.34亿日元。
这些比率有几处口径差异,需要同时读。聚合网站给出的PBR 0.57倍用的是另一种净资产口径,与这里按期末每股净资产的0.61倍不同;EV里的净现金是6月底的,EBITDA是2026年3月期的,两者期间不同;发行股数4,547.7万股,与计算EPS和每股净资产用的扣除库存股后4,443.1万股也不同;预测PER含一次性收益,所以正常化后的倍数更高。预测ROE 8.95%是聚合网站给出的预测值,不是公司披露。
09.2|资产打折之后,每股归属价值仍明显高于股价
现金加证券400亿日元左右,高于294.7亿日元的市值。把它换算成普通股东的价值,要先扣几项:递延税约占证券未实现收益的三分之一,因为递延税负债一个季度增加15.18亿日元,几乎对应证券估值准备金的增加;少数股东权益68.41亿日元;土地按账面价值计。扣完之后,每股归属资产价值仍明显高于648日元,这个差距是治理价格,不是资产不足。
反证在土地上:49.28亿日元的土地按历史成本入账,没有评估,市价高于还是低于账面、有无环境整治负债,上下两个方向都没有量化。证券估值准备金里有没有未实现亏损,也看不到。
还有一个本季度才出现的问题:证券一个季度增加了53.89亿日元(229.87亿日元),哪些是新购入、哪些是重估,以及东北特殊钢出售之后组合是否仍是买家,都没有披露。这决定留存的现金是被再投入更多股票风险,还是在等待分配。判断资产价值的强度,因此受限于这几项未知。
09.3|价格已经假定折价长期存在,买入的是公式股息加一个期权
648日元对应预测PER 6.4倍,那个预测含一次性收益;相对正常化营业利润32亿至36亿日元,大致是8至9倍(研究推断)。市净率2010年以来一直在0.25倍至0.88倍,市场十六年里从未按账面价值给这份股东登记簿定价。
既然价格已经假定折价是永久的,只要分红持续兑现,就能在没有任何治理变化的情况下复利出一次缓慢的重估。市场买的是公式输入的变化,不是确认:11月4日确认出售收益后价格回落,正是这样。没有分析师一致预期可以对照,边际买家是谁也观察不到。
对买入者来说,得到的是4.7%的公式化股息收益,外加分红或回购提速时的期权,而不是一次性的折价修复。为折价突然关闭付钱,是在为记录里没有支持的事件付钱。同样,不要把计划的2028年度目标当成估值的支撑。
09.4|这一轮股价上涨,基本是在为分红路径和资产变现付钱
公开价格记录是:2023年6月以来连续41个月收盘在60个月均线之上,年度低点依次抬高到262、347、402、536日元,2026年9月创735日元的上市最高价;同期营收持平,分红路径一路向上。两者同时发生,在基本面一侧的看法是:市场付钱的是分红路径和资产事件,不是增长。
这是关联,不是已证明的因果,边际买家也观察不到。对估值的含义是:到目前为止的重估由分配供应,继续往前,要看公式能否继续兑现。价格结构自己的判断,在第10章。
09.5|流动性限制了位置大小,报价高估大额持仓能实现的价值
2026年11月6日成交68,200股,一半左右的股东登记簿不交易,流通盘天然偏薄,大额持有者只能通过谈判慢慢退出,屏幕报价高于一整块持仓的可实现价值。名古屋同步上市是否真正加深流动性,目前没有观察到;自由流通比例是从登记簿推出的。因此折价收窄只能逐步发生,仓位大小由耐心和块头流动性决定。
10|Kabugami 技术结构
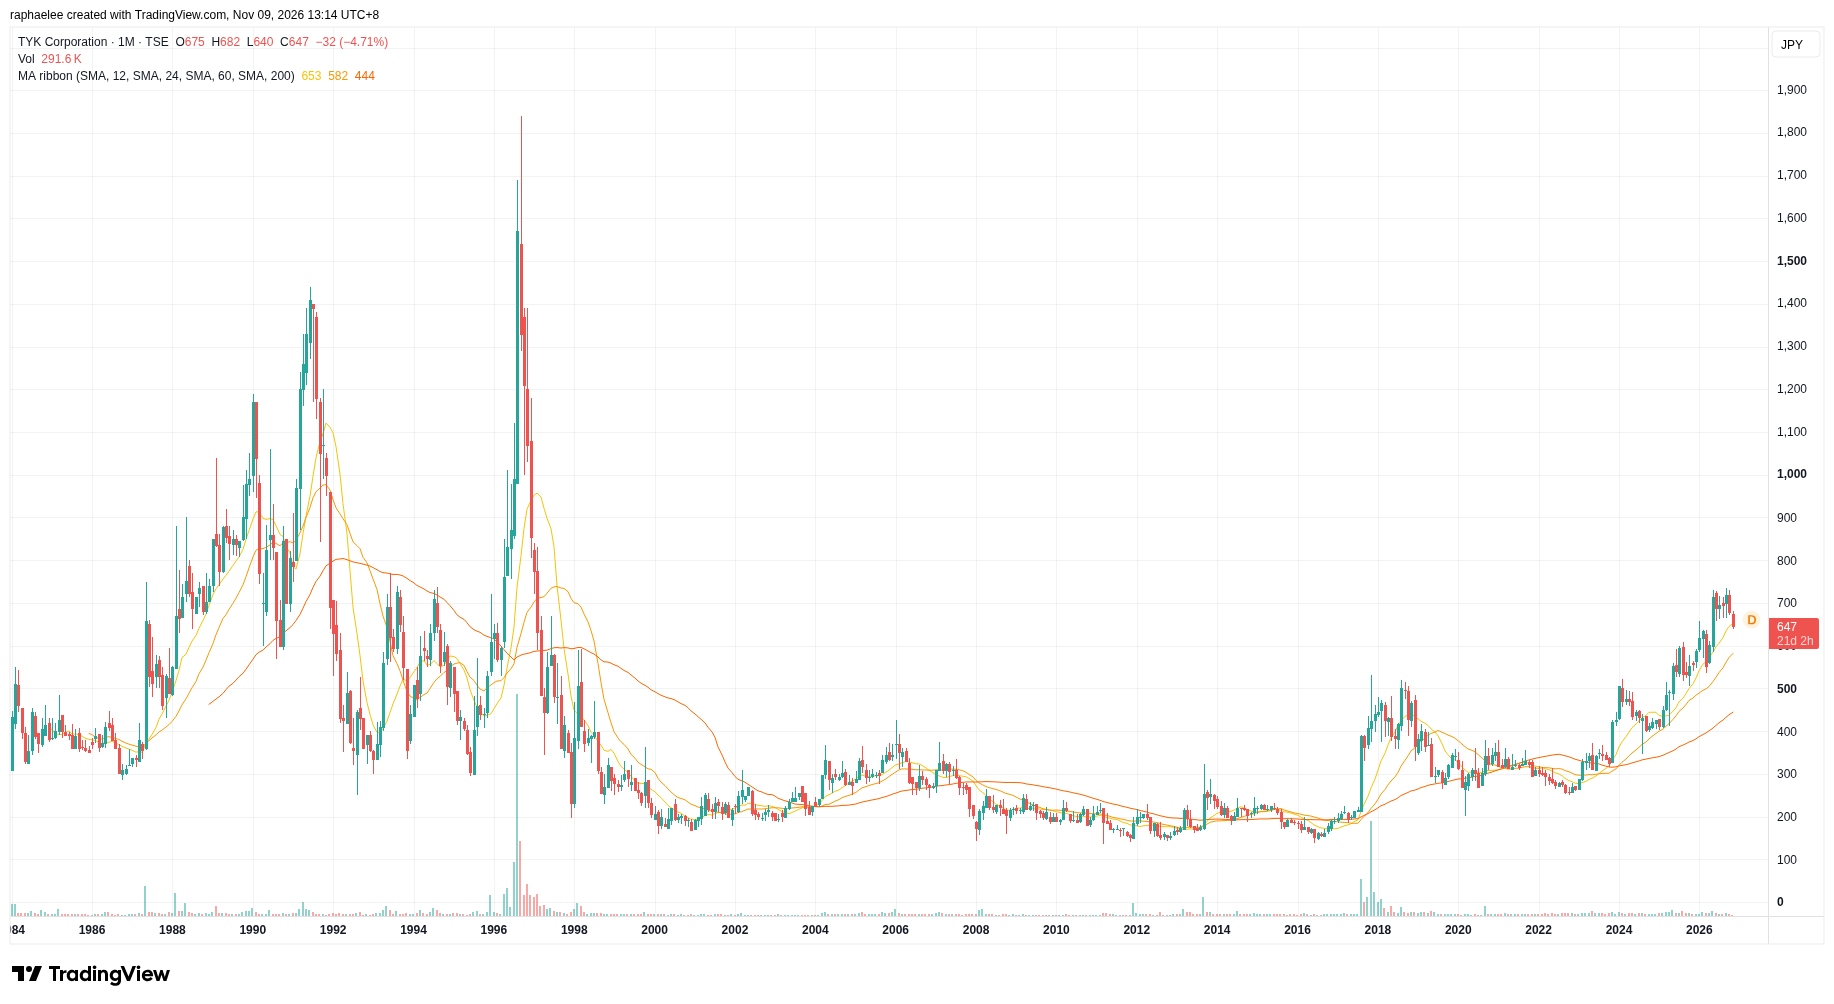
10.1|要回答的问题:2023年起的阶梯,是已经站稳,还是在高位整理中走坏
本章只看价格本身。观察基准是2001年1月至2026年10月的310根月线(收录到10月27日),2026年11月的月线尚未收完,不作确认依据;最新日线是11月6日收盘648日元,成交68,200股。
核心问题是:价格在136至531日元的区间里度过四分之一个世纪之后,2023年以来阶梯式上行到上市最高位,是否已经在旧区间上方站稳;2026年5月起在731至735日元压力位下方的整理,是对这轮上涨的消化,还是走坏的开始。
10.2|上市以来四个阶段,2023年起这一段性质不同
2001年至2016年,价格在136至425日元之间磨了十五年,最低是2011年3月的136日元。2017年出现一次脉冲,年成交量1.56亿股左右,冲到531日元,随后全部回吐,2020年跌到201日元,2019至2022年在201至417日元之间徘徊。
2023年起结构变了:年度低点逐年抬高,依次是262、347、402、536日元;年度高点同步抬高,依次是444、522、609、735日元。各年区间逐年上移,彼此重叠,成交量并不突出。2026年5月起进入高位整理,区间在536至735日元之间,历史最高价735日元出现在2026年9月。
2017年那次脉冲是旧记录里的失败案例:成交量放大到常态的二十倍,涨幅完全回吐,过冲花了五年才消化完。当前这一轮形态相反:台阶多,量温和,这轮上涨里成交最大的月份是2026年5月的292万股,还不到2017年全年成交量的五十分之一。
10.3|低点逐年抬高、均线整齐上行、回撤很快收回
60个月均线从2023年6月的324日元升到2026年10月的439日元,每个月都在上移;2023年6月起连续41个月收盘在它之上(2023年3至5月有过一次下穿)。12个月均线在2024年上穿24个月均线后,一直在上方。2026年10月收盘696日元,12个月均线646日元、24个月均线573日元、60个月均线439日元,价格在三条上行均线之上,位于整个上市区间的93.5%处,比历史最高价低5.3%。
回撤方面,2024年8月跌到347日元,2026年3月盘中洗到536日元(当月收盘552日元),两次都在两个月内收回,台阶没有被破坏。快速收回是当前状态的特征;以后若回撤的收回明显变慢,本身就是状态变坏的提醒。价格重心大致在24个月均线573日元附近,近期围绕12个月均线646日元回旋。
10.4|高位消化:五个月窄幅整理压在731至735日元压力位下
本章把价格贴着历史高位下方窄幅整理、均线仍全部向上排列的状态,称作高位消化。2026年5月出现脉冲,当月区间586至731日元,成交292万股,是当年最大;6月到10月,月内高点在714至735日元,低点在657至672日元,收盘在688至719日元,区间逐月收窄,月成交99万至147万股,没有放量冲顶。10月收盘696日元,11月6日回到648日元,比25日参考价701日元低7.6%。
压力位在731至735日元,已触及两次(2026年5月、9月),之上没有任何成交记录,月线收盘站上就是上市以来从未到过的价格区域。支撑位依次是整理底部657至665日元、24个月均线573日元、2026年3月低点536日元、60个月均线439日元。
按量价看,这更像在压力位下方积蓄,而不是向下派发。压缩本身不等于看多,要看收回能力和重心能否继续抬高。旧的长期下行状态已经明显失去控制力,更高的运行区间大体建立,但缺少一次月线收盘突破735日元的确认;从696回到648日元,说明消化仍在进行。
10.5|价格对消息的反应:买变化,不买已知消息的确认
纯价格状态形成之后,再看两次公开事件后价格怎么走。2026年5月19日公司披露全年业绩和预测,東北特殊鋼的20.97亿日元出售收益已包含在预测内;5月月线冲高到731日元,成交292万股。11月4日公司确认同一笔收益实现,两个交易日后的11月6日收盘落到648日元,是缓慢下滑,没有脉冲。前一次事件带来脉冲并留下更高区间,后一次只是确认,价格没有反应。
时序上,2023年阶梯启动时营业利润还没有改善;2026年海外利润的改善,最近才开始跟上价格。价格结构的变化早于后来被公开确认的基本面变化,价格与基本面是价格领先的关系。
这是对价格响应的观察,关联而不是已证明的因果,边际买家也观察不到;基本面不改变上面已经形成的价格判断,价格是否站稳只由价格自己的行为决定。
10.6|接下来用什么价格行为来确认,什么会推翻
确认的价格行为有三项:月线收盘站上735日元,把上市最高价变成支撑,进入没有成交记录的区域;下一次回调中,月线收盘仍守在24个月均线(573日元左右)之上,保住年度低点逐年抬高的链条(262、347、402、536日元);在派息路径变化类消息之后(如11月12日中期业绩)再次放量,这是价格对消息的响应,不预设消息结果。
推翻的价格行为有三项:月线收盘跌破60个月均线(439日元左右),结束41个月的连续站稳;2027年的年度高点和低点同时低于2026年的735日元和536日元,逆转四年的阶梯;月线收盘跌破2026年3月低点536日元,破坏当年的低点抬高链条。三个观察位置分别是收盘对60个月均线、536日元低点和731至735日元压力位。
结构内部有一处没有解决的矛盾:价格在上市最高位附近,而国内营收基数在缩小,价格已经走在营收前面。这一状态的把握一般,原因是当前价格处在25年上市以来的最高区域,上方没有历史成交可参照,日均成交也很薄。
11|风险与催化剂
11.1|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
证券组合把股市风险带进了一家工业公司。2027年3月期一季度的账面能看出量级:含少数股东的净利润8.66亿日元,综合收益却是42.37亿日元,其中32.83亿日元是证券未实现收益经其他综合收益进入权益。股市回撤时,估值准备金、股息收入(2026年3月期4.04亿日元)和以后的出售收益会同时缩小,递延税和少数股东还会在每笔收益里先拿走一部分。
钢铁需求下行时,耐火材料销量下降,同一次衰退又让证券组合下跌,所以工业业务和金融组合的分散在平时有效,在最需要的时候失效。相关程度没有测量,这是推断。下行保护因此来自资产覆盖,不来自利润稳定。
其他失败路径更慢:钢铁与股市同步下行;分红渠道中断;在薄而锁定的流通盘里再多年停在宽折价。公司没有偿付路径,风险是时间成本和退出流动性,不是破产。资产覆盖限制亏损,限制不了时间。
另一个变数是关税:2026年3月期北美利润下降33.4%,公司归因于美国关税政策,承担海外对冲的这块利润自带政策变数,敏感度没有量化。
11.2|三个日期会依次检验分红渠道
2026年11月12日是最近的节点,在本报告日期之后三天。2024年11月14日和2025年11月14日,公司都在中期业绩当天修订全年预测并提高中期和年末分红预测,一年的分配实际上在中期业绩时敲定;两次观察,第三次重复与否,正是11月12日要检验的。
这次要看的是预测隐含的偏弱二季度。中期预测营收158.85亿日元、经常利润20.85亿日元、净利润13.75亿日元,减去一季度实绩,隐含二季度单季经常利润8.61亿日元左右,低于上年同期的9.41亿日元。
一种读法是计划性保守:预测5月就已定下,出售收益本来就在里面,一季度和11月4日都有意没有改。另一种读法是日本钢厂订单真的在变弱,一季度日本分部营收下降9.3%已有暗示。
支持前者的证据是预测结构本身,这是推断,不能当事实;11月12日之后的结果在本报告截止之外。
2027年5月有两件事:年末分红预测21.3日元(上年16.0日元)随全年业绩决定;如果经营利润只是小幅恢复,这笔分红照付,就证明公式适用于证券收益,不只适用于经营利润。同月,中期计划只剩一年,管理层必须修订、推迟或维持2028年度440亿日元营收和58亿日元营业利润的目标,选择哪一种目前未知。
11.3|什么会推翻这个判断
分红渠道是判断的唯一支点,下面四件事各自拿走它的一部分。年末分红低于21.3日元且没有经营原因,在2027年5月验证,说明公式不再对证券收益适用。下一期计划放弃或稀释30%派息承诺,同样在2027年5月,说明连公式本身都不再受约束。营业利润连续两年低于30亿日元,在2028年3月期业绩时验证,打破32亿至36亿日元的营业核心区间,主业萎缩快过分红。证券变现停止,意味着供应分红的第二个引擎熄火。
反过来,单个中期业绩的波动不构成推翻:退出纪律是公式的断裂,不是中期的噪音。价格结构自己的推翻条件另列在第10章。
12|反常识发现
最不显眼的发现,是治理、资产和回报其实是同一个机制。事情的顺序是:钢铁圈里一个友好的股东,也就是第一大股东大同特殊钢,重组了東北特殊鋼;公司不是被动卖家,而是合同上的合作方,不应募、投赞成票、再把股份卖给对方;公司因此按全价释放了一块交叉持股;收益5月就进了预测,30%的派息公式会把其中一部分作为抬高的年末分红派出去。
大同在这条链上有三个身份:第一大股东、要约方、交易对手。这个钢铁圈既保护了公司,让它没有外部压力,也决定了资产什么时候变现。少数股东享受圈子里的资产交易带来的好处,代价是同一种封闭性造成的折价。
这条链还能解释一个看似矛盾的价格行为:收益是5月就已在预测里的,11月4日确认时价格不再反应。把握这条链,就能看懂为什么这家公司的价值只通过分红公式往外走,也能看出能否加速取决于圈子里下一次交易何时发生,而大同接下来是否还有类似安排,目前没有披露。
13|下一次值得跟踪什么
13.1|11月12日的中期业绩要回答什么
偏弱的二季度是计划性保守,还是日本钢厂订单真的在变弱?这决定市场该怎样看预测,因为预测隐含的二季度经常利润8.61亿日元左右,低于上年同期9.41亿日元,而一季度日本分部营收已下降9.3%。
公司会不会在这次中期业绩里重复前两年的做法,修订预测并提高分红路径?这是分红渠道本年度的第一次检验。两个问题的回答,都在2026年11月12日的中期业绩快报里;这次业绩在本报告截止日期之后。
13.2|2027年5月:计划、回购和增长业务披露
2028年度440亿日元营收和58亿日元营业利润的目标,会被修订、推迟还是重新设定?营收要年复合增长18%左右才能达到,这是下一期计划能否保持可信度的起点,也是改变派息或回购政策的自然时点。
下一期计划会不会加入回购,还是自2020年以来没有回购是少数股东应当视为长期的偏好?在股价约0.6倍账面价值、现金加证券高于市值、权益比率接近70%的条件下,回购是最强的加速器,没有它,折价只按公式速度收窄;证据是新计划的资本政策页。
先进材料和环境创造的营收和利润是多少,公司会不会单独披露?没有披露,增长这条腿就无法验证,证据是分部拆分或计划更新。
13.3|资产侧:组合买了什么,土地值多少,大同想做什么,流动性会不会变深
一个季度增加的53.89亿日元投资证券,具体买了哪些名字、多少是新购入多少是市价重估,东北特殊钢出售之后组合还是不是买家?这决定留存现金是被再投入更多股票风险,还是在等待分配。可解答的证据是2027年3月期中期的证券明细、大量持股报告,或2027年3月期有价证券报告书里的持股表。
账面49.28亿日元的土地,市场价值是多少,是否有隐藏的未实现收益或整治负债?账面没有评估,两个方向都没量化,是资产打折后安全边际无法收口的一项。证据会来自评估、土地出售或环境披露。
大同特殊钢(11.75%)在配合東北特殊鋼重组之后,是否还打算调整涉及公司的钢铁圈持股网络,是作为持有者、目标还是买家?这决定资产变现的下一步。登记簿里信托银行名下的实益持股,也没有可见路径。
名古屋同步上市会不会明显加深流动性?11月初日均成交约6.8万股,一半左右登记簿不交易,只有后续成交数据能回答。
13.4|治理空白与披露边界:这些问题没有当前公开路径
社长继任路径是否存在,2026年6月的董事会改选有没有改变经营、管理和外部董事的平衡?这在封闭股东结构里关系到资本政策何时可能改变;证据是治理报告、股东大会材料或继任公告。
产品利润、客户集中度、订单积压、供应商与对冲、研发回报、客户留存、市场份额、ROIC和资本成本、分项目资本开支、付款条件,这一整组没有披露的数据,限制了护城河、正常化盈利和增长三个判断的可信度。目前没有公开路径,下一次的证据来自计划更新里的分部拆分和以后业绩快报的文字说明。
价格上要看的,是月线收盘能否站上735日元,以及回调时能否守住24个月均线(573日元左右),详见第10章。以上十个悬而未决的问题加这一组披露边界,合在一起决定了单次业绩应当占判断多大权重。
14|Kabugami 评分卡
14.1|综合得分63.23/100,评级B
评分版本V3.2,满分100,评级B对应55至64.9分。得分63.23/100。结论判断:资产和资产负债表很强,估值有保护,但盈利质量被证券收益托高,护城河证据偏间接,封闭的股东结构拖低治理,所以停在B档。八个模块的得分如下。
14.2|八个模块的得分和各自一句理由
财务韧性与下行防御 11.05/13 分:权益比率70.4%、利息保障倍数87倍,现金加证券高于市值;扣分在于这些资产并非都能由母公司普通股东支配,证券构成和土地价值也无法核实。
竞争优势与结构耐久性 7.7/14 分:专利和认证黏性保护单价,保护不到销量,客户留存和价格溢价都没有披露。
盈利质量、现金转化与资本效率 8.5/17 分:营业利润下降23.6%而净利润上升,证券收益托高了利润,ROE 8.5%靠政策维持,ROIC和资本成本未披露。
商业结构、产品、客户与关键依赖 5.5/11 分:销量跟着日本粗钢走,海外一季度改善但只有一个季度,客户集中度和订单积压没有披露。
估值与安全边际 11.25/15 分:市净率0.61倍、预测股息率4.72%,资产打折后仍高于股价;价格已假定折价长期存在,土地价值和子公司现金可上交程度未知,限制了上限。
资本配置与股东回报 6.2/10 分:派息率连续三年30%左右、没有稀释;扣分在于自2020年以来没有回购,70%的利润留在单位数回报的资产里,后续派息政策未披露。
治理、所有权与管理层 3.15/7 分:防御政策连年续期、登记簿封闭,没有外部力量推动资产释放;公司确实按承诺派息。
Kabugami 技术结构 9.88/13 分:阶梯式上行、连续41个月站在60个月均线之上,但已在历史最高区域,缺少突破735日元的月线确认。
合计63.23/100分。
14.3|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 11.05 | 权益比率连续五年从67.3%升到70.4%,2026年3月期利息保障倍数约87倍,短期借款约34亿日元且长期不变。2026年6月底现金约172亿日元、投资证券约230亿日元,合计约400亿日元,超过约295亿日元的市值。偿债和再融资几乎不构成风险,从未发行新股,也没有稀释。扣分点在于现金和证券并非全部可由母公司普通股东自由支配,少数股东权益约68.4亿日元,证券未实现收益还对应递延税负债。 |
| 竞争优势与结构耐久性 | 14 | 7.7 | 公司在钢铁用耐火材料、石墨坩埚和精细陶瓷领域持有364项专利,员工平均工龄约16.5至18.4年。在流量控制、吹气搅拌、测量等功能性高端产品上有一定客户认证黏性,能够在吨位下降时守住单价和产品结构。但这一壁垒只保护单价,不保护销量,通用砖类产品仍按价格切换,公司自己也承认价格竞争激烈。 |
| 盈利质量、现金转化与资本效率 | 17 | 8.5 | 2026年3月期营业利润下降23.6%到34.42亿日元,净利润却增长19.5%到37.41亿日元。差距来自营业外项目:受取股息4.04亿日元、汇兑收益2.63亿日元,以及11.9亿日元的证券出售收益。营业利润是耐火材料业务的真实尺度,净利润被投资组合托高。经营现金流30.63亿日元,对营业利润的转化尚可,主要是固定资产折旧较重、设备已折旧约九成,投资压力小。ROE约8.5%,但分子里含组合收益和卖出收益,分母每年随留存的估值收益增长,是政策维持出来的数字,不是经营赚出来的。 |
| 商业结构、产品、客户与关键依赖 | 11 | 5.5 | 业务靠钢铁厂的炼钢耗材需求,需求跟粗钢产量走,存在换衬周期的时滞。日本分部贡献约五分之四的分部利润(2026年3月期30.88亿日元,同比下降22.1%)。2027年3月期第一季度钢产量增长1.0%,日本分部收入却下降9.3%,说明问题出在钢厂的需求结构和时点上。海外制造把一部分风险移出日本,海外占分部利润的比例从约九分之一升到约四分之一。日本母公司同时是集团的出口与供应中心,内部销售10.53亿日元。 |
| 估值与安全边际 | 15 | 11.25 | 股价648日元(2026年11月6日),市值约295亿日元,预测市盈率6.4倍(该预测包含20.97亿日元的一次性出售收益),市净率0.61倍,预测股息率4.72%,企业价值约156亿日元。现金加证券约400亿日元超过市值。把递延税、少数股东权益和土地按账面价值计后,每股归属资产价值仍明显高于股价,资产价值保护较强。我们把正常化营业盈利按约8至9倍的估值来看,股价已经是在假定折价长期存在的前提下定价。 |
| 资本配置与股东回报 | 10 | 6.2 | 公司执行约30%的派息比例(含证券收益),每股分红从2022年3月期的8.0日元提高到2026年3月期的25.3日元,2027年3月期预测30.6日元,派息率2024年至2026年3月期分别为30.2%、30.0%、30.1%,与中期计划承诺一致。2026年3月期营业利润下降23.6%,分红仍提高了19%。没有发行新股,也没有稀释。主要不足是自2019至2020年以来没有回购,库存股约2.41亿日元不变,70%的利润留在公司,投向回报率只有单位数的证券和现金。 |
| 治理、所有权与管理层 | 7 | 3.15 | 2026年5月再次续期了大规模收购应对方针(防御政策),此前从2014年起一路续期。前十大股东合计约47.8%,由钢铁伙伴、银行和客户构成,没有活跃投资者,也没有能单独行动的持股方。十六年来没有外部力量推动资产释放,市净率一直低于0.9倍。管理层是传统董事会,社长为牛込伸孝,2026年6月例行改选,没有代表人变更。公司实际做到了公布的承诺,派息公式连续三年兑现。 |
| Kabugami 技术结构 | 13 | 9.88 | 月线结构显示2023年以来的阶梯式上行:年度低点依次抬高到262、347、402、536日元,年度高点抬高到444、522、609、735日元;自2023年6月起连续41个月收盘价位于60个月均线之上,该均线从约324日元升到约439日元。2026年5月以后在731至735日元的上沿下方压缩整理,成交量温和,没有放量出货。判断为高位的成熟消化,既不是扩张也不是反转。旧的长期下行状态已经明显失去控制力,新的更高运行区间大体已建立,但尚缺少一次月线收盘突破735日元的确认。 |
总分: 63.23 / 100 评级: B 操作建议: 持有型配置,不追高。核心逻辑是约4.7%的公式化股息加缓慢折价收窄,而不是增长或事件驱动的重估。2026年11月12日的中期业绩、2027年5月的年末分红和中期计划修订,是依次检验分红渠道的节点;在这些节点确认派息路径不变时可继续持有或在回调中分批增加。不为2028年的计划目标付费。头寸大小要考虑流动性,块头资金退出需要时间。若年末分红低于21.3日元且没有经营原因,或30%派息承诺被放弃,需要重新评估。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|来源和截止时间
报告日期2026年11月9日;价格数据截至2026年11月6日收盘(648日元,成交68,200股)。月线价格序列由雅虎财经(Yahoo Finance)月线本地整理,收录到2026年10月27日,2026年11月的月线未收完,不作确认依据。
主要来源是公司披露文件。2026年5月19日的2026年3月期业绩快报、2026年8月12日的2027年3月期一季度业绩快报、2026年11月4日的出售收益通知,均经TDnet披露,经IRBANK文件库取得。
另有2023年11月14日的中期经营计划2024–2028,以及2026年10月7日的名古屋证券交易所上市文件。2026年6月25日经G-Biz Info(经济产业省)转载的有价证券报告书数据,含公司注册名称TYK CORPORATION、股东登记簿和专利登记。
IRBANK的股价页和适时披露索引(2026年11月6日、11月9日)是聚合数据,用于核对价格区间、PBR区间、分红记录和披露日期,不是一手来源。
15.2|证据限制
11月12日的中期业绩在报告截止之后,没有纳入。未取得竞争对手一侧的证据;没有分析师一致预期可对照;产品利润、客户集中度、订单积压、研发回报、资本成本等公司没有披露,逐项保持为未知,没有当作确定的好或坏。土地市场价值、证券组合构成和未实现亏损、子公司现金可上交程度,也没有公开路径。
几处数字口径不一致,已在正文说明:聚合网站的PBR 0.57倍与按期末每股净资产的0.61倍不同;EV和EBITDA的期间不同;已发行股数与扣除库存股后的股数不同;资料中引用的26.5%合计持股与个别持股加总(约33%)不符,本报告采用个别持股。正常化盈利区间、8至9倍的正常化倍数和价格与基本面的关联,是研究推断,不是公司披露。
本次没有使用Owner月线图,第10章为纯文字分析。公司现在的展示名称「TYK (Tokyo Yogyo)」没有来源解释。
15.3|研究目的与免责声明
本报告用于投资研究,仅供参考,不构成投资建议或买卖要约。证券价格会波动,阅读者应结合自身情况独立判断,并自行承担投资决策的后果。报告所用材料中没有包含研究方对该公司的持仓信息,因此未就利益冲突作持仓方面的披露。
主要资料来源
- Securities report data for TYK (FY3/2026): registered identity and English name
- Nagoya Stock Exchange listing document for 5363: listing particulars and display name
- FY3/2026 results (tanshin): parent-only results against consolidated
- Q1 FY3/2027 results (tanshin): the non-operating income stack
- Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised
- IRBANK stock page for 5363: the sixteen-year PBR band
- IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast
- Medium-term plan 2024-2028: capital policy - payout floor and rising DPS
- IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since
- IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print
- Locally recomputed monthly series from the assembled price history (Yahoo Finance via the A0 mirror): full-span structure
研究发现索引
展开本次 Review 的 72 项研究发现
F001|02|股东实际拥有的是一个母公司加子公司、没有控股股东的集团
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|股东实际拥有的是一个母公司加子公司、没有控股股东的集团15|来源和截止时间
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Securities report data for TYK (FY3/2026): registered identity and English name怎么使用:直接 / 支持;一手验证:01
Nagoya Stock Exchange listing document for 5363: listing particulars and display name怎么使用:直接 / 支持;一手验证:01
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接 / 支持;一手验证:05、07、24;反向验证:01、13、23、29
FY3/2026 results (tanshin): parent-only results against consolidated怎么使用:直接 / 支持;同业比较:02;其他用途:历史
Nagoya Stock Exchange listing document: capital and listing facts怎么使用:直接证据;外部现实校验:01、13;同业比较:25;其他用途:历史
FY3/2026 results (tanshin): the non-controlling interest economy怎么使用:支持证据;反向验证:18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|Securities report data for TYK (FY3/2026): registered identity and English name;直接证据 / 支持证据 / 一手证据(研究域01)|Nagoya Stock Exchange listing document for 5363: listing particulars and display name;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 支持证据 / 历史/同业比较(研究域02)|FY3/2026 results (tanshin): parent-only results against consolidated;直接证据 / 外部现实(研究域01) / 外部现实(研究域13) / 历史/同业比较(研究域25)|Nagoya Stock Exchange listing document: capital and listing facts;支持证据 / 反证(研究域18)|FY3/2026 results (tanshin): the non-controlling interest economy
完整研究记录(核对用)
研究原文:The investable entity is Tokyo Yogyo Kabushiki Kaisha, English name TYK CORPORATION (code 5363). It was founded in 1947 and makes steelmaking refractories (brick and monolithics), graphite crucibles and fine ceramics. It is listed on TSE Standard, with a Nagoya Main dual listing from 14 Oct 2026, and has no controlling shareholder. Parent-only FY3/26 revenue was JPY 25,288m and net income JPY 2,775m, against consolidated JPY 31,485m and JPY 3,741m. Subsidiaries therefore supply about a fifth of revenue and a quarter of profit, and some of that profit is shared with outside minorities.
内部研究类型:economic_identity_and_perimeter
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Fixes which economic claim the ordinary shareholder owns: a parent-plus-subsidiaries group inside an insider-held register, where part of group profit does not reach parent shareholders.
不确定性(原始记录):The company now styles itself 'TYK (Tokyo Yogyo)' in its display name. No source explains whether this is a rebrand or a reorganisation.
F002|08|名古屋同步上市不改变股本和价值
研究范围:开放研究+35项覆盖检查
写入正文:08|名古屋同步上市不改变股本和价值
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Nagoya Stock Exchange listing document: capital and listing facts怎么使用:直接 / 支持;外部现实校验:01、13;同业比较:25;其他用途:历史
Nagoya Stock Exchange listing document for 5363: listing particulars and display name怎么使用:直接证据;一手验证:01
查看完整证据标签(核对用)
直接证据 / 支持证据|Nagoya Stock Exchange listing document: dual listing on the home-region exchange;直接证据 / 支持证据 / 外部现实(研究域01) / 外部现实(研究域13) / 历史/同业比较(研究域25)|Nagoya Stock Exchange listing document: capital and listing facts;直接证据 / 一手证据(研究域01)|Nagoya Stock Exchange listing document for 5363: listing particulars and display name
完整研究记录(核对用)
研究原文:The Nagoya Main dual listing from 14 Oct 2026 (ISIN JP3589400005, 100-share unit) issues no shares, raises no capital and changes no control arithmetic. It is a visibility and local-investor measure for the Tajimi/Gifu home region. Any effect arrives through liquidity and attention, not through the balance sheet.
内部研究类型:corporate_action_context
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Neutral on value and dilution; at most a modest liquidity and attention tailwind.
不确定性(原始记录):No evidence yet that the listing deepens trading. Daily volume was about 68,000 shares in early November 2026.
F003|06|营业利润降了、净利润反而升了:这是同一个机制,不是两个故事
研究范围:开放研究+35项覆盖检查
写入正文:06|营业利润降了、净利润反而升了:这是同一个机制,不是两个故事14|八个模块的得分和各自一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 results (tanshin): headline consolidated results怎么使用:直接 / 支持;一手验证:05、12、15
FY3/2026 results (tanshin): profit bridge from operating to net income怎么使用:直接 / 支持;一手验证:06、14、16、28
FY3/2026 results (tanshin): prior-year comparative - the FY3/25 peak operating year怎么使用:直接 / 支持;一手验证:33;同业比较:12、15、16、19、28;其他用途:历史
Q1 FY3/2027 results (tanshin): the non-operating income stack怎么使用:直接证据;一手验证:16;外部现实校验:28;专项深挖:16;同业比较:14;其他用途:历史
FY3/2026 results (tanshin): dividend income inside ordinary profit across both years怎么使用:直接证据;一手验证:28;外部现实校验:16;专项深挖:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域28)|FY3/2026 results (tanshin): profit bridge from operating to net income;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域28)|FY3/2026 results (tanshin): prior-year comparative - the FY3/25 peak operating year;直接证据 / 一手证据(研究域16) / 外部现实(研究域28) / 历史/同业比较(研究域14) / 定向深挖(研究域16)|Q1 FY3/2027 results (tanshin): the non-operating income stack;直接证据 / 一手证据(研究域28) / 外部现实(研究域16) / 定向深挖(研究域28)|FY3/2026 results (tanshin): dividend income inside ordinary profit across both years
完整研究记录(核对用)
研究原文:The FY3/26 headline pair (operating profit -23.6% to JPY 3,442m, net income +19.5% to JPY 3,741m) is one mechanism, not two stories. Mix shift cut gross margin from 28.6% to 26.4% and SG&A rose from JPY 4,632m to JPY 4,860m, which cut operating profit by JPY 1,062m. Below the operating line, dividends received of JPY 404m and an FX gain of JPY 263m lifted ordinary profit, and a JPY 1,190m securities-sale gain rebuilt net income. FY3/25 already carried a JPY 374m gain and FY3/27 carries JPY 2,097m, so sale gains recur and decide net-income growth year by year. The operating line is the honest measure of the refractory business, and net income is flattered by the portfolio.
内部研究类型:profit_quality_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Screening on net income growth misreads this company. The shareholder should value operating and ordinary profit ex-gains and treat sale gains as a separate, lumpy annuity.
不确定性(原始记录):The split of securities gains between cross-holding unwinds and active portfolio trading is undisclosed beyond named transactions.
F004|06|正常化盈利:经常利润36亿至42亿日元,不含出售收益
研究范围:35项覆盖检查
写入正文:06|正常化盈利:经常利润36亿至42亿日元,不含出售收益
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results (tanshin): profit bridge from operating to net income怎么使用:直接 / 支持;一手验证:06、14、16、28
Q1 FY3/2027 results (tanshin): the non-operating income stack怎么使用:直接 / 支持;一手验证:16;外部现实校验:28;专项深挖:16;同业比较:14;其他用途:历史
FY3/2026 results (tanshin): dividend income inside ordinary profit across both years怎么使用:直接 / 支持;一手验证:28;外部现实校验:16;专项深挖:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域28)|FY3/2026 results (tanshin): profit bridge from operating to net income;直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域28) / 历史/同业比较(研究域14) / 定向深挖(研究域16)|Q1 FY3/2027 results (tanshin): the non-operating income stack;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域16) / 定向深挖(研究域28)|FY3/2026 results (tanshin): dividend income inside ordinary profit across both years
完整研究记录(核对用)
研究原文:Normalised earnings power is anchored on ordinary profit of about JPY 3.6-4.2bn. That is an operating core of JPY 3.2-3.6bn plus about JPY 0.55bn of recurring portfolio income (dividends, interest, rent), with FX as zero-mean noise. Normalised net income ex securities-sale gains is about JPY 2.6-3.0bn. The plan's JPY 5.8bn operating target is not a normal year on current evidence. This is a Research inference built from reported FY3/25-FY3/26 P&L lines and Q1 FY3/27 detail.
内部研究类型:normalized_earnings_anchor
内部来源标记:COVERAGE35
普通股东含义(原始记录):This is the earnings base to capitalise. The portfolio's capital value forms the margin of safety separately.
不确定性(原始记录):A three-year window cannot show mid-cycle Japan-segment margin through a full input-cost cycle. The anchor is an inference, not a disclosed figure.
F005|03|海外利润在填补国内缺口,但只有一个季度的数据
研究范围:开放研究+35项覆盖检查
写入正文:03|海外利润在填补国内缺口,但只有一个季度的数据
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:直接 / 支持;一手验证:12;外部现实校验:15;反向验证:05、19
Q1 FY3/2027 results (tanshin): geographic segment results怎么使用:直接 / 支持;反向验证:14
FY3/2026 results (tanshin): geographic segment results怎么使用:直接 / 支持;一手验证:02、06、14、15;同业比较:05;其他用途:历史
Q1 FY3/2027 results (tanshin): segment internal sales and where exports sit怎么使用:直接证据;专项深挖:02、15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;直接证据 / 支持证据 / 反证(研究域14)|Q1 FY3/2027 results (tanshin): geographic segment results;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): geographic segment results;直接证据 / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 results (tanshin): segment internal sales and where exports sit
完整研究记录(核对用)
研究原文:In Q1 FY3/27 North America profit rose 79.1% and Europe 58.3% while Japan fell 26.2%. Overseas share of segment profit rose from about a ninth in FY3/26 to about a quarter. The cause is local manufacture in both regions, so group profit no longer moves one-for-one with Japanese crude steel. It is the one improving feature of the operating business. The base is small: Q1 overseas segment profits are JPY 106m and JPY 118m, and Asia is flat-to-down.
内部研究类型:operating_hedge_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Group operating profit is less hostage to Japanese steel than the headline mix suggests, which partly slows the erosion of the normalised earnings band.
不确定性(原始记录):One quarter of data. Structural persistence is inferred (confidence about 0.75) and the tariff beta of North America remains. Local demand and transfer structure are undisclosed.
F006|03|海外利润在填补国内缺口,但只有一个季度的数据
研究范围:35项覆盖检查
写入正文:03|海外利润在填补国内缺口,但只有一个季度的数据
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Q1 FY3/2027 results (tanshin): segment internal sales and where exports sit怎么使用:直接 / 支持;专项深挖:02、15
Q1 FY3/2027 results (tanshin): geographic segment results怎么使用:直接 / 支持;反向验证:14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 results (tanshin): segment internal sales and where exports sit;直接证据 / 支持证据 / 反证(研究域14)|Q1 FY3/2027 results (tanshin): geographic segment results
完整研究记录(核对用)
研究原文:Japan booked JPY 1,053m of intersegment sales in Q1 against external revenue of JPY 5,261m. North America and Asia book almost none. The Japanese parent is the group's export and supply engine, while overseas units mainly manufacture and sell locally. Transfer structure and local demand, not the parent's order book, drive the overseas profit now cushioning the group.
内部研究类型:group_structure_mechanism
内部来源标记:COVERAGE35
普通股东含义(原始记录):Overseas profit growth should not be read as export strength of the parent, and attribution between parent and subsidiaries affects NCI leakage.
不确定性(原始记录):Transfer pricing and the local-demand drivers are not disclosed. Inferred at confidence 0.75.
F007|03|海外利润在填补国内缺口,但只有一个季度的数据
研究范围:开放研究
写入正文:03|海外利润在填补国内缺口,但只有一个季度的数据11|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/2026 results (tanshin): geographic segment results怎么使用:直接证据;一手验证:02、06、14、15;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): geographic segment results
完整研究记录(核对用)
研究原文:The company cites US tariff policy as a cause of North America's FY3/26 profit decline of 33.4% (revenue -12.5% to JPY 4,069m, profit JPY 292m). The fastest-growing profit pool therefore carries a policy beta that management cannot hedge operationally. Tariff headlines can move segment profit before volume.
内部研究类型:policy_exposure
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Qualifies the overseas-hedge story: the offsetting profit pool is itself exposed to trade policy.
不确定性(原始记录):No quantified sensitivity is disclosed. Hedge ratios are undisclosed.
F008|03|需求跟着日本粗钢走,销量上限每年下移
研究范围:开放研究+35项覆盖检查
写入正文:03|需求跟着日本粗钢走,销量上限每年下移14|八个模块的得分和各自一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 results (tanshin): headline consolidated results怎么使用:直接 / 支持;一手验证:05、12、15
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:直接 / 支持;一手验证:12;外部现实校验:15;反向验证:05、19
FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers怎么使用:直接证据;一手验证:11;外部现实校验:02、05、06、09、12、14;专项深挖:05、11、14
FY3/2026 results (tanshin): geographic segment results怎么使用:直接证据;一手验证:02、06、14、15;同业比较:05;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域14) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域14)|FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers;直接证据 / 一手证据(研究域02) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): geographic segment results
完整研究记录(核对用)
研究原文:Refractories are consumed in steelmaking, so demand follows crude steel tonnage with relining lags. Japanese crude steel fell 3.2% to 80.33 Mt in FY3/26 and is in structural decline. In Q1 FY3/27 steel output rose 1.0% to 20.35 Mt, yet Japan segment revenue fell 9.3%, so the shortfall is demand mix and timing at mills, not output collapse. Japan supplies about four fifths of segment profit (JPY 3,088m in FY3/26, -22.1% on mix). The domestic volume ceiling falls every year and must be outrun by mix and overseas growth indefinitely. The error to avoid is treating this as a cycle that will turn up.
内部研究类型:structural_demand_constraint
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The shareholder's volume outlook is the Japanese steel industry's outlook. Revenue is reliable per tonne but capped and shrinking, which is a valuation input rather than a surprise risk.
不确定性(原始记录):Order backlog, customer concentration and the lag between steel output and TYK orders are undisclosed.
F009|08|東北特殊鋼的出售:第一次证明隐含资产能按全价变成现金
研究范围:开放研究+35项覆盖检查
写入正文:08|東北特殊鋼的出售:第一次证明隐含资产能按全价变成现金
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 results (tanshin): material subsequent event - the Tohoku Special Steel agreement怎么使用:直接 / 支持
Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised怎么使用:直接 / 支持;同业比较:30;其他用途:历史
FY3/2027 company forecast as maintained at the Q1 print怎么使用:直接 / 支持;一手验证:30;外部现实校验:35;反向验证:12、15
FY3/2026 results (tanshin): subsequent-event detail - the squeeze-out mechanics怎么使用:直接证据;同业比较:07;其他用途:历史
Notice of 4 November 2026: the counterparty web around the Tohoku transaction怎么使用:直接证据;一手验证:07;专项深挖:07
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 results (tanshin): material subsequent event - the Tohoku Special Steel agreement;直接证据 / 支持证据 / 历史/同业比较(研究域30)|Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised;直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域35) / 反证(研究域12) / 反证(研究域15)|FY3/2027 company forecast as maintained at the Q1 print;直接证据 / 历史/同业比较(研究域07)|FY3/2026 results (tanshin): subsequent-event detail - the squeeze-out mechanics;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Notice of 4 November 2026: the counterparty web around the Tohoku transaction
完整研究记录(核对用)
研究原文:On 15 May 2026 TYK signed a non-tender agreement with Daido Steel (the offeror, and TYK's largest holder at 11.75%) over the Tohoku Special Steel tender. TYK would not tender, would vote for the squeeze-out consolidation, and would then sell all of its shares to Tohoku itself. A JPY 2,097m gain was embedded in the FY3/27 net income forecast (JPY 4,530m) from 19 May. On 4 Nov 2026 the sale was realised and the notice confirmed no forecast revision. The gain is real cash economics, but it was negotiated inside the steel family, not discovered by a market. It is the first large proof that the hidden portfolio converts to cash at full value, and it is the template for further realisations.
内部研究类型:asset_realisation_event
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):JPY 2,097m is about 7% of market capitalisation and feeds the 30% payout formula through the year-end dividend. The price faded after the confirmation, so the market treated it as already known.
不确定性(原始记录):Whether further web transactions involving TYK's remaining holdings are contemplated is undisclosed. The 7%-of-market-cap ratio is a derived comparison across different dates.
F010|06|资产负债表几乎抗冲击:问题不在偿付,而在谁能拿到
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表几乎抗冲击:问题不在偿付,而在谁能拿到
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:直接 / 支持;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接证据;一手验证:18、21、29
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:直接证据;一手验证:17、19、25;外部现实校验:20
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接 / 支持;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
Nagoya Stock Exchange listing document: capital and listing facts怎么使用:直接证据;外部现实校验:01、13;同业比较:25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;直接证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;直接证据 / 外部现实(研究域01) / 外部现实(研究域13) / 历史/同业比较(研究域25)|Nagoya Stock Exchange listing document: capital and listing facts
完整研究记录(核对用)
研究原文:Equity ratio rose 67.3 / 68.7 / 68.9 / 69.1 / 70.4% across FY3/22-FY3/26, with about 69.8% at June 2026. Interest coverage was 87x in FY3/26 and cash-flow-to-debt was 1.1 years. Short-term borrowings are about JPY 3.4bn and static. The market-value equity ratio has never exceeded 37% of total assets in five years, so the discount is chronic, not event-driven. There has been no equity issuance and no dilution, so the capital-policy question is retention without purpose, not funding.
内部研究类型:balance_sheet_resilience_record
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Solvency and refinancing risk are negligible. The shareholder's exposure is custody and access to the assets, plus opportunity cost.
不确定性(原始记录):The portfolio's name-by-name composition is only partly public.
F011|06|资产负债表的重心已经移到证券组合上
研究范围:开放研究
写入正文:06|资产负债表的重心已经移到证券组合上09|资产打折之后,每股归属价值仍明显高于股价14|八个模块的得分和各自一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026
完整研究记录(核对用)
研究原文:At June 2026 cash of JPY 17.2bn plus investment securities of JPY 23.0bn total about JPY 40bn, against market capitalisation of about JPY 29.5bn, on a 69.8% equity ratio. In one quarter securities rose JPY 5,389m (purchases plus marks), the valuation reserve rose from JPY 7,486m to JPY 10,750m, and DTL rose from JPY 2,783m to JPY 4,301m. The market is pricing the refractory franchise, land and plant at a negative value before tax and minority haircuts. The question is not whether the assets exist but whether minorities will ever receive them. Operands mix a 6 Nov price with a 30 Jun balance sheet, and securities are at market while cash is partly consolidated cash.
内部研究类型:balance_sheet_centre_of_gravity
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The dominant valuation fact. Access, not existence, is the variable.
不确定性(原始记录):Comparison date mismatch (June balance sheet, November price). Availability of consolidated cash and securities to parent ordinary shareholders is subject to tax and minority claims.
F012|09|资产打折之后,每股归属价值仍明显高于股价
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio怎么使用:直接 / 支持;一手验证:32;外部现实校验:18、29;反向验证:21;专项深挖:18、29
FY3/2026 results (tanshin): land and the physical footprint怎么使用:直接证据;专项深挖:21;同业比较:21;其他用途:反证、历史
FY3/2026 results (tanshin): the non-controlling interest economy怎么使用:直接证据;反向验证:18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域18) / 外部现实(研究域29) / 反证(研究域21) / 定向深挖(研究域18) / 定向深挖(研究域29)|Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio;直接证据 / 反证 / 历史/同业比较(研究域21) / 定向深挖(研究域21)|FY3/2026 results (tanshin): land and the physical footprint;直接证据 / 反证(研究域18)|FY3/2026 results (tanshin): the non-controlling interest economy
完整研究记录(核对用)
研究原文:After punitive haircuts (deferred tax on unrealised portfolio gains, minorities' share, land at book) the asset value attributable to a share exceeds the JPY 648 price by a wide margin. The gap is a governance price, not an asset shortfall. The DTL shadow takes roughly a third of unrealised gains on realisation. Counter-evidence is that land is carried at JPY 4,928m historical cost with no appraisal, so the land leg is unquantified in both directions. Asset value and obligation or transferability must be assessed symmetrically: tax leakage, NCI claims and upstreaming limits are part of the haircut.
内部研究类型:asset_backing_adjudication
内部来源标记:COVERAGE35
普通股东含义(原始记录):Net asset backing per share (BPS JPY 1,061.72 at FY3/26) versus a JPY 648 price is the margin of safety. Time and access, not solvency, is the enemy.
不确定性(原始记录):Land market value, unrealised losses netted inside the reserve and composition risk are not visible. Inference confidence about 0.75.
F013|06|资产负债表的重心已经移到证券组合上
研究范围:35项覆盖检查
写入正文:06|资产负债表的重心已经移到证券组合上09|资产打折之后,每股归属价值仍明显高于股价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/2026 results (tanshin): the non-controlling interest economy怎么使用:直接 / 支持;反向验证:18
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域18)|FY3/2026 results (tanshin): the non-controlling interest economy;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026
完整研究记录(核对用)
研究原文:Non-controlling interests hold JPY 6,841m (12.7% of net assets), took JPY 366m of FY3/26 profit (JPY 670m in FY3/25) and received JPY 174m of dividends. A persistent slice of group earnings and assets never reaches parent shareholders, and deferred taxes and minorities take their share of every portfolio gain.
内部研究类型:value_leakage_mechanism
内部来源标记:COVERAGE35
普通股东含义(原始记录):A permanent small leakage between consolidated profit and the ordinary shareholder's claim. Group asset values must be netted for it.
不确定性(原始记录):Which subsidiaries carry the minorities and how upstreamable their cash is are not detailed in the sources read.
F014|08|分红公式把证券收益也分给了少数股东
研究范围:开放研究+35项覆盖检查
写入正文:08|分红公式把证券收益也分给了少数股东09|价格已经假定折价长期存在,买入的是公式股息加一个期权14|八个模块的得分和各自一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:直接 / 支持;一手验证:26;同业比较:35;其他用途:历史
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:直接 / 支持;一手验证:17、19、25;外部现实校验:20
IRBANK dividend record for TYK: per-share history and payout ratios怎么使用:直接证据;一手验证:26;专项深挖:26
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接证据;一手验证:22;专项深挖:22
FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings怎么使用:直接证据;外部现实校验:17、19、25;同业比较:32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators;直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|IRBANK dividend record for TYK: per-share history and payout ratios;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS;直接证据 / 外部现实(研究域17) / 外部现实(研究域19) / 外部现实(研究域25) / 历史/同业比较(研究域32)|FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings
完整研究记录(核对用)
研究原文:A payout of about 30% of earnings, including securities gains, has lifted DPS from JPY 8.0 (FY3/22) to 12.0, 16.2, 21.2 and 25.3 (FY3/26), and to a forecast JPY 30.6 for FY3/27. Payout ratios were 30.2%, 30.0% and 30.1% in FY3/24-26, matching the plan's commitment. The dividend rose 19% in a year when operating profit fell 23.6%. Because the formula is applied mechanically, portfolio gains reach minorities as dividends, and the discount closes at the speed of the formula, not at the speed of asset value. At JPY 648 the forecast yield is 4.72%.
内部研究类型:distribution_transmission_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The only demonstrated channel by which value reaches minorities, and the thesis's main observable.
不确定性(原始记录):Management could raise the payout (the plan says '30% or more') but no trigger is disclosed. The formula's continuation beyond the plan period is unproven.
F015|11|三个日期会依次检验分红渠道
研究范围:35项覆盖检查
写入正文:11|三个日期会依次检验分红渠道
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:直接 / 支持;一手验证:26;同业比较:35;其他用途:历史
IRBANK dividend record for TYK: per-share history and payout ratios怎么使用:直接 / 支持;一手验证:26;专项深挖:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|IRBANK dividend record for TYK: per-share history and payout ratios
完整研究记录(核对用)
研究原文:The FY3/27 year-end dividend is forecast at JPY 21.3 per share, against JPY 16.0 paid for FY3/26. It will be decided with the May 2027 results. Paying it in full in a year when operating profit recovers only modestly would prove the payout formula applies to portfolio gains as well as operating earnings.
内部研究类型:dated_catalyst
内部来源标记:COVERAGE35
普通股东含义(原始记录):A dividend below JPY 21.3 without an operating cause is the first falsifier of the distribution channel.
不确定性(原始记录):Depends on realised full-year earnings and management discretion.
F016|08|自2019至2020年回购以后,股东回报只有分红
研究范围:开放研究+35项覆盖检查
写入正文:08|自2019至2020年回购以后,股东回报只有分红13|2027年5月:计划、回购和增长业务披露
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since怎么使用:直接 / 支持;一手验证:25;反向验证:26;专项深挖:25;同业比较:13、23、33;其他用途:历史
FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings怎么使用:直接 / 支持;外部现实校验:17、19、25;同业比较:32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域13) / 历史/同业比较(研究域23) / 历史/同业比较(研究域33) / 反证(研究域26) / 定向深挖(研究域25)|IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域19) / 外部现实(研究域25) / 历史/同业比较(研究域32)|FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings;直接证据|FY3/2026 results (tanshin): per-share data and share counts
完整研究记录(核对用)
研究原文:Shareholder return in the current plan period is the dividend alone. The last buyback ran in 2019-2020, alongside an ESOP trust and a treasury-share disposal by third-party allotment in March 2020. No authorisation appears in the 2021-2026 record. Treasury stock is static at about JPY 241m. With an equity ratio near 70%, cash and securities above market capitalisation and the stock at about 0.6x book, the open question is whether the next plan adds buybacks or whether this absence is a settled preference minorities should treat as permanent.
内部研究类型:capital_policy_gap
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A buyback at 0.6x book would be the strongest accelerant of discount closure. Its absence leaves the discount to formula-speed erosion, and the retained cash earns single-digit returns or merely accumulates.
不确定性(原始记录):Open question; there is no disclosed trigger. It is a Research Debt item for the next plan.
F017|11|三个日期会依次检验分红渠道
研究范围:35项覆盖检查
写入正文:11|三个日期会依次检验分红渠道
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
IRBANK timely-disclosure index for TYK: the November dividend-revision pattern怎么使用:直接 / 支持;一手验证:30;专项深挖:30、35;同业比较:26;其他用途:历史
IRBANK timely-disclosure index for TYK: FY3/26 interim revisions - the beat-and-raise half怎么使用:直接 / 支持;外部现实校验:30;专项深挖:12、33
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 历史/同业比较(研究域26) / 定向深挖(研究域30) / 定向深挖(研究域35)|IRBANK timely-disclosure index for TYK: the November dividend-revision pattern;直接证据 / 支持证据 / 外部现实(研究域30) / 定向深挖(研究域12) / 定向深挖(研究域33)|IRBANK timely-disclosure index for TYK: FY3/26 interim revisions - the beat-and-raise half
完整研究记录(核对用)
研究原文:In both FY3/25 and FY3/26 the forecast revision and the interim and year-end dividend raise landed together with the November H1 tanshin (14 Nov 2024, 14 Nov 2025). The year's distribution is effectively set at the interim print, once H1 earnings and any portfolio gains are visible. The FY3/27 H1 print is on 12 Nov 2026.
内部研究类型:disclosure_pattern
内部来源标记:COVERAGE35
普通股东含义(原始记录):The November print is the distribution-setting event of the corporate year.
不确定性(原始记录):Two observations; a third repetition is exactly what the 12 Nov print tests.
F018|11|三个日期会依次检验分红渠道
研究范围:开放研究+35项覆盖检查
写入正文:11|三个日期会依次检验分红渠道13|11月12日的中期业绩要回答什么
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2027 company forecast as maintained at the Q1 print怎么使用:直接 / 支持;一手验证:30;外部现实校验:35;反向验证:12、15
Q1 FY3/2027 results (tanshin): forecast table and the unchanged-stance statement怎么使用:直接 / 支持;反向验证:25、30
IRBANK timely-disclosure index for TYK: the November dividend-revision pattern怎么使用:直接证据;一手验证:30;专项深挖:30、35;同业比较:26;其他用途:历史
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:直接证据;一手验证:12;外部现实校验:15;反向验证:05、19
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:支持证据;一手验证:26;同业比较:35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域35) / 反证(研究域12) / 反证(研究域15)|FY3/2027 company forecast as maintained at the Q1 print;直接证据 / 支持证据 / 反证(研究域25) / 反证(研究域30)|Q1 FY3/2027 results (tanshin): forecast table and the unchanged-stance statement;直接证据 / 一手证据(研究域30) / 历史/同业比较(研究域26) / 定向深挖(研究域30) / 定向深挖(研究域35)|IRBANK timely-disclosure index for TYK: the November dividend-revision pattern;直接证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast
完整研究记录(核对用)
研究原文:The FY3/27 forecast (revenue JPY 31,770m, operating profit JPY 3,550m, ordinary JPY 4,170m, net income JPY 4,530m, EPS JPY 101.95) was set on 19 May and left unchanged at Q1 and again at the 4 Nov gain notice. The H1 forecast minus Q1 actuals implies a Q2 standalone ordinary profit of about JPY 861m, below about JPY 941m a year earlier. This is read as planned conservatism, since the gain was inside the forecast from the start, rather than a warning. The unresolved questions are whether the 12 Nov 2026 H1 tanshin repeats the pattern of revising the forecast and dividend path, and whether the soft Q2 reflects actual softness in Japanese mill orders that the Q1 segment data hint at (Japan revenue -9.3%).
内部研究类型:near_term_verification_event_and_research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The nearest verification event, three days after the review date. A beat-and-raise would reinforce the distribution channel. A Q2 miss with no dividend step would test the conservatism reading.
不确定性(原始记录):The conservatism-versus-softness reading rests on forecast structure and inference (confidence about 0.7). The post-review print is out of cutoff scope.
F019|07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产
研究范围:开放研究+35项覆盖检查
写入正文:07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产09|价格已经假定折价长期存在,买入的是公式股息加一个期权14|八个模块的得分和各自一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接 / 支持;一手验证:05、07、24;反向验证:01、13、23、29
IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal怎么使用:直接 / 支持;一手验证:13、23;反向验证:07、24
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence怎么使用:直接 / 支持;一手验证:13;外部现实校验:23;专项深挖:13;同业比较:24;其他用途:历史
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接 / 支持;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
IRBANK timely-disclosure index for TYK: 2026 governance and officer events怎么使用:直接证据;一手验证:23;专项深挖:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 反证(研究域07) / 反证(研究域24)|IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域13)|IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|IRBANK timely-disclosure index for TYK: 2026 governance and officer events
完整研究记录(核对用)
研究原文:Governance insulation is documented. The large-scale-purchase response policy (anti-takeover defence) was renewed again on 19 May 2026, in a line of renewals back through 2014. The top-ten register of banks and steel partners holds about 47.8%, there has been no buyback since 2019-2020, and PBR has stayed in 0.25-0.88x for sixteen years. Management is a conventional board under President Nobutaka Ushigome, refreshed routinely in June 2026 with no representative change, and the soft constraints are the plan's published commitments. Nothing in the record forces asset release, so the discount is a governance price that only the distribution formula can erode, slowly. Any thesis requiring management to be forced is contradicted by the record. Any thesis requiring only patience is supported by it.
内部研究类型:governance_insulation_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Explains why the discount persists and why distributions, not a bid or an activist, are the channel. The entrenchment risk is that the market expects the discount to persist.
不确定性(原始记录):Board skills composition and the full governance report were not separately read.
F020|07|股东登记簿就是客户、贷款人和钢铁伙伴的名单
研究范围:开放研究+35项覆盖检查
写入正文:07|股东登记簿就是客户、贷款人和钢铁伙伴的名单13|资产侧:组合买了什么,土地值多少,大同想做什么,流动性会不会变深15|证据限制
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接证据;一手验证:05、07、24;反向验证:01、13、23、29
Securities report data for TYK: register concentration and the absence of a controller怎么使用:直接证据;一手验证:24;外部现实校验:07;专项深挖:24;同业比较:01;其他用途:历史
Notice of 4 November 2026: the counterparty web around the Tohoku transaction怎么使用:直接证据;一手验证:07;专项深挖:07
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 定向深挖(研究域24)|Securities report data for TYK: register concentration and the absence of a controller;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Notice of 4 November 2026: the counterparty web around the Tohoku transaction
完整研究记录(核对用)
研究原文:The FY3/26 top ten: Daido Steel 11.75%, Mizuho 4.98%, Juroku 4.87%, Ogaki Kyoritsu 4.87%, Aichi 4.36%, JFE Steel 4.19%, Okaya Koki 4.12%, Chubu Steel Plate 3.06%, Japan Steel Works 3.03% and Yamaguchi 2.47% (about 47.7-47.8% in total). The register is the customer, lender and steel-partner list, held still: no activist and no holder able to act alone. JFE is both customer and shareholder. Daido is simultaneously anchor holder, Tohoku offeror and transaction counterparty. Arithmetic check on the stated figures: the five banks sum to about 21.5% and Daido plus banks to about 33.3%, so the '26.5%' cited in the sources does not reconcile with the individual holdings. Whether Daido intends any further reordering of the steel-ecosystem web involving TYK (as holder, target or buyer) is an open question.
内部研究类型:ownership_web
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A non-trading register converts governance into a negotiation among insiders that minorities can only observe. It stabilises orders and control, and thins the float.
不确定性(原始记录):Beneficial holdings inside trust-bank names are not visible. Daido's intentions are unknown. The 26.5% aggregate in the sources conflicts with individual shareholdings, so the individual holdings are used.
F021|07|中期计划同时承载增长承诺和分红承诺,两条腿可以分开兑现
研究范围:开放研究
写入正文:07|中期计划同时承载增长承诺和分红承诺,两条腿可以分开兑现09|价格已经假定折价长期存在,买入的是公式股息加一个期权
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Medium-term management plan 2024-2028: the FY2028 numerical targets怎么使用:直接 / 支持;一手验证:09、11;反向验证:08、22
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:直接 / 支持;一手验证:22;反向验证:09、11、31、33、35
FY3/2026 results (tanshin): business definition and segment architecture怎么使用:直接 / 支持;一手验证:02、03、08、09、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域11) / 反证(研究域08) / 反证(研究域22)|Medium-term management plan 2024-2028: the FY2028 numerical targets;直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|FY3/2026 results (tanshin): business definition and segment architecture
完整研究记录(核对用)
研究原文:The FY2024-2028 plan targets FY2028 revenue of JPY 44.0bn or more (from a JPY 30.0bn FY2023 base), operating profit of JPY 5.8bn or more, ROE of 8% or more and payout of 30% or more with rising DPS. FY3/26 printed JPY 31.5bn and JPY 3.4bn, and Q1 FY3/27 revenue fell again, so revenue would need to compound at about 18% for two years. The plan is unreachable on the current trajectory and functions as a statement of direction, not a forecast. The return and payout legs are already met on paper, but with the help of securities-sale gains.
内部研究类型:plan_credibility_gap
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Growth expectations priced off the plan target rather than pond arithmetic are the main way to overpay for this stock.
不确定性(原始记录):Whether the targets will be revised, deferred or re-based is unknown until May 2027. The 18% figure is a derived requirement.
F022|03|计划里的增长业务,从披露中看不见
研究范围:开放研究+35项覆盖检查
写入正文:03|计划里的增长业务,从披露中看不见13|2027年5月:计划、回购和增长业务披露
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 results (tanshin): what the 'other' category contains怎么使用:直接 / 支持;反向验证:02、04、10;同业比较:03;其他用途:历史
Medium-term plan 2024-2028: the business portfolio framing怎么使用:直接 / 支持;专项深挖:08;同业比较:08;其他用途:历史
FY3/2026 results (tanshin): the 'other' businesses inside the group怎么使用:直接 / 支持;反向验证:03
Medium-term plan 2024-2028: where the growth is supposed to come from怎么使用:直接证据;外部现实校验:08、11;反向验证:20;专项深挖:09
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域03) / 反证(研究域02) / 反证(研究域04) / 反证(研究域10)|FY3/2026 results (tanshin): what the 'other' category contains;直接证据 / 支持证据 / 历史/同业比较(研究域08) / 定向深挖(研究域08)|Medium-term plan 2024-2028: the business portfolio framing;直接证据 / 支持证据 / 反证(研究域03)|FY3/2026 results (tanshin): the 'other' businesses inside the group;直接证据 / 外部现实(研究域08) / 外部现实(研究域11) / 反证(研究域20) / 定向深挖(研究域09)|Medium-term plan 2024-2028: where the growth is supposed to come from
完整研究记录(核对用)
研究原文:The plan assigns growth to advanced materials and environmental creation and to overseas refractories, treating refractories as the large, low-growth cash generator. No results document breaks those businesses out. The residual 'other' category (environmental products, kiln machinery, construction, repair, transport) is about JPY 340m revenue (about 1%) with JPY 111m profit, and no segment revenue target for new materials is disclosed. The growth claim is therefore unfalsifiable from disclosure. The open question is whether the company will ever disclose the revenue and profit of these businesses separately.
内部研究类型:disclosure_boundary_with_research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The market's refusal to price the growth claim (6.4x, about 0.6x book) is the rational response to an unverifiable claim.
不确定性(原始记录):Revenue and profit of advanced materials and environmental creation are undisclosed. Resolving evidence would be a segment breakout or plan update.
F023|11|三个日期会依次检验分红渠道
研究范围:开放研究
写入正文:11|三个日期会依次检验分红渠道13|2027年5月:计划、回购和增长业务披露
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Medium-term management plan 2024-2028: the FY2028 numerical targets怎么使用:直接 / 支持;一手验证:09、11;反向验证:08、22
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:直接 / 支持;一手验证:22;反向验证:09、11、31、33、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域11) / 反证(研究域08) / 反证(研究域22)|Medium-term management plan 2024-2028: the FY2028 numerical targets;直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets
完整研究记录(核对用)
研究原文:The FY3/27 results in May 2027 force the medium-term plan question with one year left to run. Management must revise, defer or defend FY2028 targets of JPY 44.0bn revenue and JPY 5.8bn operating profit that the current trajectory cannot reach. The open question is whether they will be revised, deferred or re-based.
内部研究类型:dated_catalyst_and_research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The largest scheduled information event for the growth claim. A new plan is also the natural occasion to change payout or buyback policy.
不确定性(原始记录):Management choice among revise, defer and defend is unknown.
F024|11|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
研究范围:开放研究+35项覆盖检查
写入正文:11|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income怎么使用:直接证据;一手验证:32;反向验证:16、28;专项深挖:32
Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio怎么使用:直接证据;一手验证:32;外部现实校验:18、29;反向验证:21;专项深挖:18、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域28) / 定向深挖(研究域32)|Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income;直接证据 / 一手证据(研究域32) / 外部现实(研究域18) / 外部现实(研究域29) / 反证(研究域21) / 定向深挖(研究域18) / 定向深挖(研究域29)|Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio
完整研究记录(核对用)
研究原文:The securities portfolio imports equity-market beta into an industrial shell. A market drawdown would cut the valuation reserve, dividend income (JPY 404m in FY3/26) and future sale gains at the same time as it pressured the share price. Deferred taxes and non-controlling interests take their share of every gain before minorities see it. Q1 FY3/27 shows the scale: comprehensive income JPY 4,237m against net income JPY 866m, with JPY 3,283m of unrealised gains through OCI.
内部研究类型:risk_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The shareholder's true macro hedge ratio is unusual: equity-market falls hurt reported equity faster than a steel downturn does.
不确定性(原始记录):Portfolio composition is partially disclosed, and any unrealised losses netted inside the reserve are not visible.
F025|11|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
研究范围:开放研究
写入正文:11|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/2026 results (tanshin): headline consolidated results怎么使用:直接 / 支持;一手验证:05、12、15
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells
完整研究记录(核对用)
研究原文:The two engines correlate in a true downturn: a recession cuts steel output and refractory volumes at the same time as it marks down the securities portfolio and its dividend stream. The apparent diversification between the industrial annuity and the financial portfolio fails exactly when it is needed.
内部研究类型:risk_mechanism
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Limits the downside-protection argument to asset coverage; it does not stabilise earnings in a recession.
不确定性(原始记录):Inference at confidence 0.8; the correlation magnitude is not measured.
F026|09|流动性限制了位置大小,报价高估大额持仓能实现的价值
研究范围:开放研究+35项覆盖检查
写入正文:09|流动性限制了位置大小,报价高估大额持仓能实现的价值13|资产侧:组合买了什么,土地值多少,大同想做什么,流动性会不会变深
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print怎么使用:直接 / 支持;外部现实校验:27、31;专项深挖:31、34
IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture怎么使用:直接 / 支持;外部现实校验:34
Securities report data for TYK: register concentration and the absence of a controller怎么使用:直接证据;一手验证:24;外部现实校验:07;专项深挖:24;同业比较:01;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域27) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print;直接证据 / 支持证据 / 外部现实(研究域34)|IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 定向深挖(研究域24)|Securities report data for TYK: register concentration and the absence of a controller
完整研究记录(核对用)
研究原文:About 68,200 shares traded on 6 Nov 2026 at JPY 648. About half the register does not trade, so the float is structurally thin and any holder of size exits by negotiation over time. The quoted price overstates realisable value for a block. The open question is whether the Nagoya dual listing measurably deepens liquidity or whether the thin float persists.
内部研究类型:liquidity_constraint_and_research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Amplifies price moves in both directions and caps institutional sponsorship, so position sizing is set by patience and block size.
不确定性(原始记录):Liquidity effect of the Nagoya listing is unobserved. The free float percentage is inferred from the register.
F027|09|估值简报:低倍数,低于账面价值,但口径要分清
研究范围:开放研究+35项覆盖检查
写入正文:09|估值简报:低倍数,低于账面价值,但口径要分清15|来源和截止时间
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture怎么使用:直接 / 支持;外部现实校验:34
FY3/2027 company forecast as maintained at the Q1 print怎么使用:直接 / 支持;一手验证:30;外部现实校验:35;反向验证:12、15
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:直接 / 支持;一手验证:17、19、25;外部现实校验:20
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 支持证据 / 外部现实(研究域34)|IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture;直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域35) / 反证(研究域12) / 反证(研究域15)|FY3/2027 company forecast as maintained at the Q1 print;直接证据 / 支持证据|FY3/2026 results (tanshin): per-share data and share counts;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells
完整研究记录(核对用)
研究原文:Price JPY 648 at the 6 Nov 2026 close; market capitalisation JPY 29.47bn (45,477,000 issued shares); forecast PER 6.4x on forecast EPS JPY 101.95 (which contains the JPY 2,097m one-off gain); PBR 0.61x on FY3/26 BPS JPY 1,061.72; FY3/26 ROE 8.5% as reported; forecast yield 4.72% on JPY 30.60; EV/EBITDA 3.4x (EV JPY 15.64bn after net cash JPY 13.83bn at 30 Jun 2026; EBITDA JPY 4.58bn = FY3/26 operating profit JPY 3,442m plus depreciation JPY 1,134m). Operand basis matters: the aggregator shows 0.57x PBR, a different net-asset basis from the 0.61x on year-end BPS; the EV bridge mixes a June balance sheet with FY3/26 EBITDA; issued shares (45.477m) differ from the 44.431m ex-treasury shares used for EPS and BPS; and the PER is on a forecast including a one-off gain.
内部研究类型:valuation_snapshot_with_operand_identity
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Gives the priced-in picture: low single-digit multiple on earnings and a discount to book despite net cash.
不确定性(原始记录):Derived ratios inherit the basis mismatches named above. Forecast PER is flattered by the gain, so normalised multiples are higher.
F028|09|价格已经假定折价长期存在,买入的是公式股息加一个期权
研究范围:35项覆盖检查+开放研究
写入正文:09|价格已经假定折价长期存在,买入的是公式股息加一个期权14|八个模块的得分和各自一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:直接 / 支持;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接证据;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print怎么使用:直接证据;外部现实校验:27、31;专项深挖:31、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios;直接证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;直接证据 / 外部现实(研究域27) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print
完整研究记录(核对用)
研究原文:At JPY 648 the shares trade at 6.4x a forecast EPS that contains a one-off gain, and at roughly 8-9x normalised operating earnings. PBR has ranged 0.25-0.88x since 2010, so the market has never paid book for this register. The price already assumes the discount is permanent, so continued distribution delivery alone can compound a slow re-rating without any governance change. The market pays for changes in the formula's inputs, not for their confirmation, as the fade after the 4 Nov gain notice illustrated.
内部研究类型:market_expectation_inference
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):The shareholder buys a 4.7% formula coupon plus an option on faster release. Paying for a sudden closing of the discount would be paying for an event the record does not support.
不确定性(原始记录):The 8-9x normalised multiple is an inference. The marginal buyer's identity is unobservable and there is no analyst consensus.
F029|04|竞争对手一侧的证据没有取得,现有判断主要来自公司自述和结构性线索
研究范围:35项覆盖检查
写入正文:04|竞争对手一侧的证据没有取得,现有判断主要来自公司自述和结构性线索05|护城河护住的是单价,不是销量14|八个模块的得分和各自一句理由
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Securities report data for TYK: intellectual property as the technology record怎么使用:直接 / 支持;一手验证:04、10;外部现实校验:03;专项深挖:04、10
Securities report data for TYK: workforce stability indicators怎么使用:直接 / 支持;外部现实校验:04、10
Securities report data for TYK: parent scale, plants and patent stock怎么使用:直接证据;专项深挖:01、03;同业比较:10;其他用途:历史
FY3/2026 results (tanshin): business definition and segment architecture怎么使用:直接证据;一手验证:02、03、08、09、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 外部现实(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|Securities report data for TYK: intellectual property as the technology record;直接证据 / 支持证据 / 外部现实(研究域04) / 外部现实(研究域10)|Securities report data for TYK: workforce stability indicators;直接证据 / 历史/同业比较(研究域10) / 定向深挖(研究域01) / 定向深挖(研究域03)|Securities report data for TYK: parent scale, plants and patent stock;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|FY3/2026 results (tanshin): business definition and segment architecture
完整研究记录(核对用)
研究原文:The technology and workforce record (364 patents, 40 designs, 26 trademarks; average tenure of 16.5-18.4 years) supports a defensible niche in functional, high-grade refractories (flow control, purging, measurement) rather than commodity brick. Qualification stickiness protects price per tonne at the functional end, not volume. The commodity end switches on price. This is where the Japan segment's mix battle is fought, and the mix shift cut gross margin 2.2 points in FY3/26. The moat is structural (patents, tenure, register overlap), not measured through retention or price-premium series. Competitor-side evidence was not read, and the company describes severe price competition.
内部研究类型:moat_and_technology_judgment
内部来源标记:COVERAGE35
普通股东含义(原始记录):The shareholder is protected on price and exposed on volume. Japan segment gross margin is the early-warning gauge.
不确定性(原始记录):No disclosed retention or realised-premium data. R&D spend and product-level P&L are undisclosed. Inference at confidence 0.7.
F030|06|利润能转成现金,但设备已经折旧到底,回报被抬高了
研究范围:35项覆盖检查
写入正文:06|利润能转成现金,但设备已经折旧到底,回报被抬高了
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/2026 results (tanshin): the productive asset base is old and largely depreciated怎么使用:直接 / 支持;一手验证:20;专项深挖:20;同业比较:04、06;其他用途:历史
Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell怎么使用:直接 / 支持;一手验证:17、20;专项深挖:06、17
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 定向深挖(研究域20)|FY3/2026 results (tanshin): the productive asset base is old and largely depreciated;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 定向深挖(研究域06) / 定向深挖(研究域17)|Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell
完整研究记录(核对用)
研究原文:Net tangible fixed assets are only JPY 10,182m. Kilns and machinery are about 90% depreciated (JPY 21,876m gross against JPY 19,698m accumulated depreciation). Construction in progress fell from JPY 645m to JPY 189m in FY3/26, so no major capacity project was under way at year-end. Q1 FY3/27 depreciation rose 14% to JPY 275m, signalling that replacement has begun to turn. Reported returns are flattered by a written-down plant base, and a future rebuild would compress them before it grew them.
内部研究类型:capital_intensity_state
内部来源标记:COVERAGE35
普通股东含义(原始记录):A quiet haircut to apply to steady-state returns. The cash conversion is high precisely because the asset base is old.
不确定性(原始记录):The capex plan by project and year, and the maintenance-versus-growth split, are undisclosed.
F031|06|利润能转成现金,但设备已经折旧到底,回报被抬高了
研究范围:35项覆盖检查
写入正文:06|利润能转成现金,但设备已经折旧到底,回报被抬高了
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:直接证据;一手验证:17、19、25;外部现实校验:20
Q1 FY3/2027 results (tanshin): working capital and balance-sheet movements怎么使用:直接证据;一手验证:19;反向验证:06、17、32;专项深挖:19
Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell怎么使用:直接证据;一手验证:17、20;专项深挖:06、17
FY3/2026 results (tanshin): the productive asset base is old and largely depreciated怎么使用:直接证据;一手验证:20;专项深挖:20;同业比较:04、06;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators;直接证据 / 一手证据(研究域19) / 反证(研究域06) / 反证(研究域17) / 反证(研究域32) / 定向深挖(研究域19)|Q1 FY3/2027 results (tanshin): working capital and balance-sheet movements;直接证据 / 一手证据(研究域17) / 一手证据(研究域20) / 定向深挖(研究域06) / 定向深挖(研究域17)|Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell;直接证据 / 一手证据(研究域20) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 定向深挖(研究域20)|FY3/2026 results (tanshin): the productive asset base is old and largely depreciated
完整研究记录(核对用)
研究原文:FY3/26 operating cash flow was JPY 3,063m against operating profit of JPY 3,442m. Investing outflow was JPY 1,549m (plant plus securities purchases) and financing outflow JPY 1,149m (mostly dividends), so free cash flow after all investing was about JPY 1.5bn before dividends. At 30 Jun 2026 receivables were about JPY 9.5bn and inventories about JPY 11.5bn (raw materials 4.2bn) against quarterly revenue of JPY 7.9bn. Working capital is a heavy but stable load for a made-to-order supplier, and moves slowly relative to the roughly JPY 40bn cash-and-securities pile. Raw-material and energy cost lag is a margin variable, partially passed through with delay.
内部研究类型:cash_conversion_and_working_capital
内部来源标记:COVERAGE35
普通股东含义(原始记录):This is not a paper-profit company; the debate is about who controls the accumulated cash.
不确定性(原始记录):Customer payment terms, factoring, supplier concentration and hedging are undisclosed. Q1 has no quarterly cash-flow statement.
F032|06|ROE是政策维持出来的数字,不是经营赚出来的
研究范围:35项覆盖检查
写入正文:06|ROE是政策维持出来的数字,不是经营赚出来的
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:直接证据;一手验证:22;反向验证:09、11、31、33、35
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接证据;一手验证:22;专项深挖:22
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接证据;一手验证:27、29、31;外部现实校验:21、22、26
FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings怎么使用:直接证据;外部现实校验:17、19、25;同业比较:32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS;直接证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 外部现实(研究域17) / 外部现实(研究域19) / 外部现实(研究域25) / 历史/同业比较(研究域32)|FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings
完整研究记录(核对用)
研究原文:FY3/26 ROE was about 8.5% and the FY3/27 forecast is 8.95%, meeting the plan's 8% floor. The numerator includes recurring portfolio income and sale gains, and the denominator grows every year with retained valuation gains. Retaining about 70% of earnings at single-digit returns compounds the equity base faster than operating profit grows, so ROE is a treadmill the portfolio must keep feeding. The payout formula therefore also maintains the ratio. ROE here is a policy output, defended with distributions and gains before it is earned with volume. Management's cost of capital is undisclosed.
内部研究类型:capital_efficiency_mechanism
内部来源标记:COVERAGE35
普通股东含义(原始记录):Do not read the 8% plan target as operating performance. Holding it on operating earnings alone is not yet demonstrated.
不确定性(原始记录):No stated ROIC or cost of capital; ROE decomposition into operating, portfolio-income and gain components is not disclosed.
F033|06|三种会计呈现,会让只看一行数字的人两头判错
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income怎么使用:直接证据;一手验证:32;反向验证:16、28;专项深挖:32
Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio怎么使用:直接证据;一手验证:32;外部现实校验:18、29;反向验证:21;专项深挖:18、29
Q1 FY3/2027 results (tanshin): audit and accounting basis怎么使用:直接证据;外部现实校验:32
Q1 FY3/2027 results (tanshin): the non-operating income stack怎么使用:直接证据;一手验证:16;外部现实校验:28;专项深挖:16;同业比较:14;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域28) / 定向深挖(研究域32)|Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income;直接证据 / 一手证据(研究域32) / 外部现实(研究域18) / 外部现实(研究域29) / 反证(研究域21) / 定向深挖(研究域18) / 定向深挖(研究域29)|Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio;直接证据 / 外部现实(研究域32)|Q1 FY3/2027 results (tanshin): audit and accounting basis;直接证据 / 一手证据(研究域16) / 外部现实(研究域28) / 历史/同业比较(研究域14) / 定向深挖(研究域16)|Q1 FY3/2027 results (tanshin): the non-operating income stack
完整研究记录(核对用)
研究原文:The accounts are honest (Japanese GAAP, Fujimi Audit Corporation interim review), but three presentational traps generate misleading headlines. Net income growth is decided by securities gains in FY3/25-FY3/27. Comprehensive income is dominated by portfolio marks (JPY 3,283m of Q1 FY3/27's JPY 4,237m). Deferred tax liabilities grew JPY 1,518m in one quarter as the shadow of those marks. Quarterly tax uses an estimated full-year effective rate, so quarterly net income moves with forecast mix.
内部研究类型:presentation_anomaly
内部来源标记:COVERAGE35
普通股东含义(原始记录):A shareholder who reads headlines will alternately overpay for 'growth' and panic at 'declines' that are portfolio artefacts. One who reads the bridge is protected.
不确定性(原始记录):Whether any holdings carry unrealised losses inside the reserve is not visible from the aggregates.
F034|09|这一轮股价上涨,基本是在为分红路径和资产变现付钱
写入正文:09|这一轮股价上涨,基本是在为分红路径和资产变现付钱10|价格对消息的反应:买变化,不买已知消息的确认
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Locally recomputed monthly series from the assembled price history (Yahoo Finance via the A0 mirror): full-span structure怎么使用:直接 / 支持;一手验证:34;同业比较:27;其他用途:历史
Locally recomputed monthly series: annual highs, lows and closes, 2018-2026怎么使用:直接 / 支持;一手验证:34
Locally recomputed monthly series: 2026 range position and average configuration怎么使用:直接 / 支持;一手验证:31;反向验证:34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域34) / 历史/同业比较(研究域27)|Locally recomputed monthly series from the assembled price history (Yahoo Finance via the A0 mirror): full-span structure;直接证据 / 支持证据 / 一手证据(研究域34)|Locally recomputed monthly series: annual highs, lows and closes, 2018-2026;直接证据 / 支持证据 / 一手证据(研究域31) / 反证(研究域34)|Locally recomputed monthly series: 2026 range position and average configuration
完整研究记录(核对用)
研究原文:Public price facts (41 consecutive monthly closes above the 60-month average since June 2023, annual lows rising 262 / 347 / 402 / 536, a lifetime high of JPY 735 in September 2026) coincided with flat revenue and a rising payout path. In the Fundamental lane this is read as a distribution-led re-rating: the market has paid for the payout path and the asset events, not for growth. This node is a cross-lane interpretation of public price facts against Fundamental Research. It neither restates nor alters the protected Technical State.
内部研究类型:cross_lane_fundamental_technical_interpretation
内部来源标记:TECHNICAL
普通股东含义(原始记录):The re-rating to date was paid for by distributions, so further progress depends on the formula continuing to deliver.
不确定性(原始记录):Association, not proven causation (confidence about 0.8). The marginal buyer is unobservable. Any independent Technical conclusion lives only in the protected structure.
F035|01|折价能否靠分红公式收窄,要比国内需求萎缩得更快
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|折价能否靠分红公式收窄,要比国内需求萎缩得更快14|综合得分63.23/100,评级B15|研究目的与免责声明
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
Locally assembled monthly price history for 5363: span, range and moving averages怎么使用:直接 / 支持;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 支持证据 / 一手证据(研究域35)|Locally assembled monthly price history for 5363: span, range and moving averages
完整研究记录(核对用)
研究原文:The investment question is whether the discount closes through the one channel that demonstrably works - rising formula-driven distributions fed by both engines (operating and portfolio) - faster than the domestic refractory base erodes. On the FY3/22-FY3/27 record the distributions are winning slowly, which is what the 2023-2026 price staircase already reflects. The upgraded framing is an asset box with a governance discount whose closure speed equals formula speed, not a growth story. Each November interim print and each May results day resets the distribution path.
内部研究类型:investment_thesis
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Defines the judgement: hold-type exposure to a 4.7% coupon plus slow drift.
不确定性(原始记录):Confidence about 0.7. Hinges on formula persistence and absence of a mechanism change (buyback, payout raise, large realisation) that would speed closure.
F036|01|分红渠道断掉的四个信号
研究范围:35项覆盖检查
写入正文:01|分红渠道断掉的四个信号11|什么会推翻这个判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:直接 / 支持;一手验证:26;同业比较:35;其他用途:历史
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接 / 支持;一手验证:22;专项深挖:22
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS
完整研究记录(核对用)
研究原文:The thesis fails observably if the distribution channel breaks. Falsifiers are: a year-end dividend below JPY 21.3 without an operating cause (tested May 2027); abandonment or dilution of the 30% payout commitment in the next plan (May 2027); operating profit below JPY 3.0bn for two consecutive years, breaking the normalised band (tested at FY3/28 results); and a halt to portfolio realisation. Each would remove the only mechanism that has been closing the discount.
内部研究类型:falsification_conditions
内部来源标记:COVERAGE35
普通股东含义(原始记录):Gives the shareholder a mechanical, dated discipline: hold while the formula delivers, reassess on a formula break.
不确定性(原始记录):Fundamental falsifiers only; Technical falsifiers belong to the protected structure and are not duplicated here.
F037|09|资产打折之后,每股归属价值仍明显高于股价
研究范围:开放研究
写入正文:09|资产打折之后,每股归属价值仍明显高于股价13|资产侧:组合买了什么,土地值多少,大同想做什么,流动性会不会变深
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接证据;一手验证:18、21;反向验证:27
Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised怎么使用:直接证据;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;直接证据|FY3/2026 results (tanshin): material subsequent event - the Tohoku Special Steel agreement;直接证据 / 历史/同业比较(研究域30)|Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised
完整研究记录(核对用)
研究原文:What did the JPY 5,389m single-quarter increase in investment securities (to JPY 22,987m) consist of: which names were bought, how much was new purchase versus mark-to-market, and is the portfolio still a buyer after the Tohoku position was sold in November 2026? The balance-sheet movement is documented but its composition is not.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Determines whether retained cash is being redeployed into more equity beta or waiting to be distributed.
不确定性(原始记录):Resolving evidence is the H1 FY3/27 filing's securities detail, any large-holder disclosure or the FY3/27 securities report holdings table.
F038|09|资产打折之后,每股归属价值仍明显高于股价
研究范围:开放研究+35项覆盖检查
写入正文:09|资产打折之后,每股归属价值仍明显高于股价13|资产侧:组合买了什么,土地值多少,大同想做什么,流动性会不会变深
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
FY3/2026 results (tanshin): land and the physical footprint怎么使用:直接证据;专项深挖:21;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域21) / 定向深挖(研究域21)|FY3/2026 results (tanshin): land and the physical footprint
完整研究记录(核对用)
研究原文:What is the market value of the land bank carried at JPY 4,928m at historical cost across the Tajimi-centred plant network? Does any site carry unrealised gains or remediation liabilities that the book value conceals? No revaluation or appraisal appears in the record, so the gap is undisclosed in both directions.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The one asset whose uplift or liability is unquantified in both directions, so the asset-backing haircut cannot be closed.
不确定性(原始记录):Resolving evidence would be an appraisal, a site sale or environmental disclosure.
F039|07|社长继任和董事会结构没有披露
研究范围:开放研究+35项覆盖检查
写入正文:07|社长继任和董事会结构没有披露13|治理空白与披露边界:这些问题没有当前公开路径
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
IRBANK timely-disclosure index for TYK: 2026 governance and officer events怎么使用:直接证据;一手验证:23;专项深挖:23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|IRBANK timely-disclosure index for TYK: 2026 governance and officer events
完整研究记录(核对用)
研究原文:Is there a disclosed succession path for the presidency, and did the June 2026 board refresh (a new administration-division director, one retirement, no change of representative) change the balance between operating, administration and outside directors in any way that matters for capital policy? Succession planning and board skills are not disclosed in the sources read.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Leadership change is a plausible occasion for a capital-policy change in an insulated register.
不确定性(原始记录):Resolving evidence would be the governance report, AGM materials or a succession announcement.
F040|05|一组没有披露的数据,限制了对护城河和增长的信心
研究范围:35项覆盖检查
写入正文:05|一组没有披露的数据,限制了对护城河和增长的信心13|治理空白与披露边界:这些问题没有当前公开路径
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/2026 results (tanshin): business definition and segment architecture怎么使用:直接证据;一手验证:02、03、08、09、10
FY3/2026 results (tanshin): what the 'other' category contains怎么使用:直接证据;反向验证:02、04、10;同业比较:03;其他用途:历史
Q1 FY3/2027 results (tanshin): working capital and balance-sheet movements怎么使用:直接证据;一手验证:19;反向验证:06、17、32;专项深挖:19
FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers怎么使用:直接证据;一手验证:11;外部现实校验:02、05、06、09、12、14;专项深挖:05、11、14
Securities report data for TYK: intellectual property as the technology record怎么使用:直接证据;一手验证:04、10;外部现实校验:03;专项深挖:04、10
Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell怎么使用:直接证据;一手验证:17、20;专项深挖:06、17
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|FY3/2026 results (tanshin): business definition and segment architecture;直接证据 / 历史/同业比较(研究域03) / 反证(研究域02) / 反证(研究域04) / 反证(研究域10)|FY3/2026 results (tanshin): what the 'other' category contains;直接证据 / 一手证据(研究域19) / 反证(研究域06) / 反证(研究域17) / 反证(研究域32) / 定向深挖(研究域19)|Q1 FY3/2027 results (tanshin): working capital and balance-sheet movements;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域14) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域14)|FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 外部现实(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|Securities report data for TYK: intellectual property as the technology record;直接证据 / 一手证据(研究域17) / 一手证据(研究域20) / 定向深挖(研究域06) / 定向深挖(研究域17)|Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell
完整研究记录(核对用)
研究原文:Coverage research left a cluster of undisclosed items that bound confidence: product-level revenue, price and margin; customer concentration and backlog; supplier concentration, contract tenors and hedge ratios; R&D spend and revenue from patented products; customer retention and realised price premiums; market share data; the ROIC and cost-of-capital hurdle; capex by project; customer payment terms; and the lag between steel output and TYK orders. None has a current public path, and company non-disclosure alone is not treated as completion. Each remains a bounded UNKNOWN. Nothing here was converted to certainty.
内部研究类型:research_debt_cluster
内部来源标记:COVERAGE35
普通股东含义(原始记录):Caps how high confidence can go on the moat, normalised-earnings and growth judgements. Segment margin at each print is the standing proxy.
不确定性(原始记录):Next evidence: product or segment breakouts in plan updates, future tanshin narratives.
F041|08|東北特殊鋼的出售:第一次证明隐含资产能按全价变成现金
研究范围:开放研究+35项覆盖检查
写入正文:08|東北特殊鋼的出售:第一次证明隐含资产能按全价变成现金12|一笔收益把登记簿、证券组合和分红公式连成了一条链
归并到:F066
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接证据;一手验证:05、07、24;反向验证:01、13、23、29
Notice of 4 November 2026: the counterparty web around the Tohoku transaction怎么使用:直接证据;一手验证:07;专项深挖:07
Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised怎么使用:支持证据;同业比较:30;其他用途:历史
FY3/2027 company forecast as maintained at the Q1 print怎么使用:支持证据;一手验证:30;外部现实校验:35;反向验证:12、15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Notice of 4 November 2026: the counterparty web around the Tohoku transaction;支持证据|FY3/2026 results (tanshin): material subsequent event - the Tohoku Special Steel agreement;支持证据 / 历史/同业比较(研究域30)|Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised;支持证据 / 一手证据(研究域30) / 外部现实(研究域35) / 反证(研究域12) / 反证(研究域15)|FY3/2027 company forecast as maintained at the Q1 print
完整研究记录(核对用)
研究原文:Daido Steel, TYK's largest shareholder (11.75%), was the offeror in the Tohoku reorganisation. Its cooperation arrangement unlocked the JPY 2,097m gain, so capital-web cooperation is a real value channel and Daido's intentions frame future asset moves.
内部研究类型:anchor_holder_enabled_transaction
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F042|08|東北特殊鋼的出售:第一次证明隐含资产能按全价变成现金
研究范围:开放研究
写入正文:08|東北特殊鋼的出售:第一次证明隐含资产能按全价变成现金12|一笔收益把登记簿、证券组合和分红公式连成了一条链
归并到:F066
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/2026 results (tanshin): material subsequent event - the Tohoku Special Steel agreement怎么使用:直接 / 支持
Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised怎么使用:直接 / 支持;同业比较:30;其他用途:历史
FY3/2027 company forecast as maintained at the Q1 print怎么使用:支持证据;一手验证:30;外部现实校验:35;反向验证:12、15
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:支持证据;一手验证:18、21、29
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:支持证据;一手验证:18、21;反向验证:27
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:支持证据;一手验证:27、29、31;外部现实校验:21、22、26
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 results (tanshin): material subsequent event - the Tohoku Special Steel agreement;直接证据 / 支持证据 / 历史/同业比较(研究域30)|Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised;支持证据 / 一手证据(研究域30) / 外部现实(研究域35) / 反证(研究域12) / 反证(研究域15)|FY3/2027 company forecast as maintained at the Q1 print;支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026
完整研究记录(核对用)
研究原文:TYK's former cross-holding in Tohoku was sold back to Tohoku itself at full value inside the steel family. This is the template for how the remaining portfolio may be monetised, at a pace the family chooses.
内部研究类型:template_for_portfolio_monetisation
内部来源标记:OPEN_DISCOVERY
F043|03|需求跟着日本粗钢走,销量上限每年下移
研究范围:开放研究
写入正文:03|需求跟着日本粗钢走,销量上限每年下移07|股东登记簿就是客户、贷款人和钢铁伙伴的名单
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接证据;一手验证:05、07、24;反向验证:01、13、23、29
FY3/2026 results (tanshin): geographic segment results怎么使用:直接证据;一手验证:02、06、14、15;同业比较:05;其他用途:历史
FY3/2026 results (tanshin): headline consolidated results怎么使用:支持证据;一手验证:05、12、15
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:支持证据;一手验证:12;外部现实校验:15;反向验证:05、19
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 一手证据(研究域02) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): geographic segment results;支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;支持证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026
完整研究记录(核对用)
研究原文:Japanese steelmakers (incl. JFE Steel, a 4.19% holder) are both the demand side of the core business and part of the register. Refractory consumption follows their relining cycles, and the overlap stabilises orders and control at once.
内部研究类型:customer_shareholder_overlap_demand_dependence
内部来源标记:OPEN_DISCOVERY
F044|07|股东登记簿就是客户、贷款人和钢铁伙伴的名单
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接 / 支持;一手验证:05、07、24;反向验证:01、13、23、29
Securities report data for TYK: register concentration and the absence of a controller怎么使用:直接证据;一手验证:24;外部现实校验:07;专项深挖:24;同业比较:01;其他用途:历史
IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal怎么使用:支持证据;一手验证:13、23;反向验证:07、24
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:支持证据;一手验证:27、29、31;外部现实校验:21、22、26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 定向深挖(研究域24)|Securities report data for TYK: register concentration and the absence of a controller;支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 反证(研究域07) / 反证(研究域24)|IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal;支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026
完整研究记录(核对用)
研究原文:Mizuho and the four regional banks (Juroku, Ogaki Kyoritsu, Aichi, Yamaguchi) form the traditional stable-shareholder bloc. It underpins the defence posture and the low cost of the minimal debt carried, and is the least likely to demand asset release. The sources cite about 26.5% for Daido plus banks, but the listed holdings sum to roughly 33%.
内部研究类型:stable_holder_bloc_underpins_defence
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F045|03|需求跟着日本粗钢走,销量上限每年下移
研究范围:开放研究+35项覆盖检查
写入正文:03|需求跟着日本粗钢走,销量上限每年下移06|正常化盈利:经常利润36亿至42亿日元,不含出售收益
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/2026 results (tanshin): headline consolidated results怎么使用:直接 / 支持;一手验证:05、12、15
FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers怎么使用:直接证据;一手验证:11;外部现实校验:02、05、06、09、12、14;专项深挖:05、11、14
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:支持证据;一手验证:12;外部现实校验:15;反向验证:05、19
FY3/2026 results (tanshin): profit bridge from operating to net income怎么使用:支持证据;一手验证:06、14、16、28
Q1 FY3/2027 results (tanshin): the non-operating income stack怎么使用:支持证据;一手验证:16;外部现实校验:28;专项深挖:16;同业比较:14;其他用途:历史
FY3/2026 results (tanshin): dividend income inside ordinary profit across both years怎么使用:支持证据;一手验证:28;外部现实校验:16;专项深挖:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域14) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域14)|FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers;支持证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域28)|FY3/2026 results (tanshin): profit bridge from operating to net income;支持证据 / 一手证据(研究域16) / 外部现实(研究域28) / 历史/同业比较(研究域14) / 定向深挖(研究域16)|Q1 FY3/2027 results (tanshin): the non-operating income stack;支持证据 / 一手证据(研究域28) / 外部现实(研究域16) / 定向深挖(研究域28)|FY3/2026 results (tanshin): dividend income inside ordinary profit across both years
完整研究记录(核对用)
研究原文:The Japanese crude steel series (80.33 Mt in FY3/26, 20.35 Mt in Q1 FY3/27) sets the domestic volume ceiling. Every domestic volume assumption in the normalised operating core is downstream of it, and its slow decline is the gravity the mix-and-overseas story must escape.
内部研究类型:volume_ceiling_sets_operating_core
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F046|03|海外利润在填补国内缺口,但只有一个季度的数据
研究范围:开放研究
写入正文:03|海外利润在填补国内缺口,但只有一个季度的数据11|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
归并到:F007
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results (tanshin): geographic segment results怎么使用:直接 / 支持;一手验证:02、06、14、15;同业比较:05;其他用途:历史
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:支持证据;一手验证:12;外部现实校验:15;反向验证:05、19
Q1 FY3/2027 results (tanshin): geographic segment results怎么使用:支持证据;反向验证:14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): geographic segment results;支持证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;支持证据 / 反证(研究域14)|Q1 FY3/2027 results (tanshin): geographic segment results
完整研究记录(核对用)
研究原文:US tariff policy is cited as a cause of North America's FY3/26 profit decline of 33.4%. The exposure runs through US steel demand and the segment's local cost base, so the profit pool now cushioning the group carries a policy beta management cannot hedge operationally.
内部研究类型:policy_beta_qualifies_hedge
内部来源标记:OPEN_DISCOVERY
F047|03|计划里的增长业务,从披露中看不见
研究范围:开放研究+35项覆盖检查
写入正文:03|计划里的增长业务,从披露中看不见13|2027年5月:计划、回购和增长业务披露
归并到:F022
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Medium-term management plan 2024-2028: the FY2028 numerical targets怎么使用:直接 / 支持;一手验证:09、11;反向验证:08、22
Medium-term plan 2024-2028: where the growth is supposed to come from怎么使用:直接证据;外部现实校验:08、11;反向验证:20;专项深挖:09
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:支持证据;一手验证:22;反向验证:09、11、31、33、35
FY3/2026 results (tanshin): business definition and segment architecture怎么使用:支持证据;一手验证:02、03、08、09、10
FY3/2026 results (tanshin): what the 'other' category contains怎么使用:支持证据;反向验证:02、04、10;同业比较:03;其他用途:历史
Medium-term plan 2024-2028: the business portfolio framing怎么使用:支持证据;专项深挖:08;同业比较:08;其他用途:历史
FY3/2026 results (tanshin): the 'other' businesses inside the group怎么使用:支持证据;反向验证:03
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域11) / 反证(研究域08) / 反证(研究域22)|Medium-term management plan 2024-2028: the FY2028 numerical targets;直接证据 / 外部现实(研究域08) / 外部现实(研究域11) / 反证(研究域20) / 定向深挖(研究域09)|Medium-term plan 2024-2028: where the growth is supposed to come from;支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|FY3/2026 results (tanshin): business definition and segment architecture;支持证据 / 历史/同业比较(研究域03) / 反证(研究域02) / 反证(研究域04) / 反证(研究域10)|FY3/2026 results (tanshin): what the 'other' category contains;支持证据 / 历史/同业比较(研究域08) / 定向深挖(研究域08)|Medium-term plan 2024-2028: the business portfolio framing;支持证据 / 反证(研究域03)|FY3/2026 results (tanshin): the 'other' businesses inside the group
完整研究记录(核对用)
研究原文:The advanced-materials and environmental-creation demand the plan points to (fine ceramics for electronics and automotive uses, environmental products) sits inside undisclosed parts of the segment accounts. If it is real at scale the FY2028 targets have a leg to stand on, but disclosure does not let an outsider verify it, which is itself the finding.
内部研究类型:unverifiable_support_for_target
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F048|07|中期计划同时承载增长承诺和分红承诺,两条腿可以分开兑现
研究范围:开放研究+35项覆盖检查
写入正文:07|中期计划同时承载增长承诺和分红承诺,两条腿可以分开兑现08|分红公式把证券收益也分给了少数股东
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Medium-term plan 2024-2028: where the growth is supposed to come from怎么使用:直接证据;外部现实校验:08、11;反向验证:20;专项深挖:09
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接证据;一手验证:22;专项深挖:22
Medium-term management plan 2024-2028: the FY2028 numerical targets怎么使用:支持证据;一手验证:09、11;反向验证:08、22
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:支持证据;一手验证:22;反向验证:09、11、31、33、35
FY3/2026 results (tanshin): business definition and segment architecture怎么使用:支持证据;一手验证:02、03、08、09、10
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:支持证据;一手验证:26;同业比较:35;其他用途:历史
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:支持证据;一手验证:17、19、25;外部现实校验:20
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域08) / 外部现实(研究域11) / 反证(研究域20) / 定向深挖(研究域09)|Medium-term plan 2024-2028: where the growth is supposed to come from;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS;支持证据 / 一手证据(研究域09) / 一手证据(研究域11) / 反证(研究域08) / 反证(研究域22)|Medium-term management plan 2024-2028: the FY2028 numerical targets;支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|FY3/2026 results (tanshin): business definition and segment architecture;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators
完整研究记录(核对用)
研究原文:The medium-term plan is simultaneously the growth promise (FY2028 revenue JPY 44.0bn+, operating profit JPY 5.8bn+) and the distribution promise (ROE 8%+, payout 30%+ with rising DPS). Its FY3/27 reckoning is the largest scheduled information event, and the growth leg can fail while the distribution leg is delivered.
内部研究类型:same_plan_carries_growth_and_distribution_promise
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F049|07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产
研究范围:开放研究+35项覆盖检查
写入正文:07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产08|分红公式把证券收益也分给了少数股东
归并到:F070
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence怎么使用:直接 / 支持;一手验证:13;外部现实校验:23;专项深挖:13;同业比较:24;其他用途:历史
IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal怎么使用:直接 / 支持;一手验证:13、23;反向验证:07、24
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接 / 支持;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:支持证据;一手验证:05、07、24;反向验证:01、13、23、29
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:支持证据;一手验证:27、29、31;外部现实校验:21、22、26
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:支持证据;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域13)|IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 反证(研究域07) / 反证(研究域24)|IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios
完整研究记录(核对用)
研究原文:The anti-takeover defence, renewed in May 2026 in an unbroken line since at least 2014, converts the friendly register into a near-absolute block on hostile approaches. That is why the discount must be closed by distributions rather than by a bid, and why sixteen years below 0.9x PBR says the market expects it to persist.
内部研究类型:defence_forces_discount_closure_through_distribution
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F050|11|三个日期会依次检验分红渠道
研究范围:开放研究+35项覆盖检查
写入正文:11|三个日期会依次检验分红渠道13|11月12日的中期业绩要回答什么
归并到:F018
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY3/2027 results (tanshin): forecast table and the unchanged-stance statement怎么使用:直接 / 支持;反向验证:25、30
FY3/2027 company forecast as maintained at the Q1 print怎么使用:直接 / 支持;一手验证:30;外部现实校验:35;反向验证:12、15
Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised怎么使用:支持证据;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域25) / 反证(研究域30)|Q1 FY3/2027 results (tanshin): forecast table and the unchanged-stance statement;直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域35) / 反证(研究域12) / 反证(研究域15)|FY3/2027 company forecast as maintained at the Q1 print;支持证据|FY3/2026 results (tanshin): material subsequent event - the Tohoku Special Steel agreement;支持证据 / 历史/同业比较(研究域30)|Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised
完整研究记录(核对用)
研究原文:Inside the unchanged FY3/27 forecast the JPY 2,097m gain was already booked in H2 terms. The forecast's internal shape therefore places management's own caution not in the gain, which is done, but in second-half domestic volumes. This is why the 4 Nov notice needed no revision.
内部研究类型:forecast_shape_embeds_realised_gain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F051|04|竞争对手一侧的证据没有取得,现有判断主要来自公司自述和结构性线索
研究范围:开放研究+35项覆盖检查
写入正文:04|竞争对手一侧的证据没有取得,现有判断主要来自公司自述和结构性线索05|护城河护住的是单价,不是销量14|八个模块的得分和各自一句理由
归并到:F029
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Securities report data for TYK: intellectual property as the technology record怎么使用:直接 / 支持;一手验证:04、10;外部现实校验:03;专项深挖:04、10
Securities report data for TYK: parent scale, plants and patent stock怎么使用:直接证据;专项深挖:01、03;同业比较:10;其他用途:历史
Securities report data for TYK: workforce stability indicators怎么使用:支持证据;外部现实校验:04、10
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 外部现实(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|Securities report data for TYK: intellectual property as the technology record;直接证据 / 历史/同业比较(研究域10) / 定向深挖(研究域01) / 定向深挖(研究域03)|Securities report data for TYK: parent scale, plants and patent stock;支持证据 / 外部现实(研究域04) / 外部现实(研究域10)|Securities report data for TYK: workforce stability indicators
完整研究记录(核对用)
研究原文:The 364-patent base and functional product range (flow control, purging, measurement) defend mix and price per tonne as tonnage shrinks. It is the credible part of the quality claim and the seed from which the advanced-materials story would have to grow.
内部研究类型:mix_defends_price_per_tonne_against_shrinking_tonnage
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F052|06|正常化盈利:经常利润36亿至42亿日元,不含出售收益
研究范围:35项覆盖检查
写入正文:06|正常化盈利:经常利润36亿至42亿日元,不含出售收益
归并到:F004
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 results (tanshin): profit bridge from operating to net income怎么使用:直接 / 支持;一手验证:06、14、16、28
Q1 FY3/2027 results (tanshin): the non-operating income stack怎么使用:直接 / 支持;一手验证:16;外部现实校验:28;专项深挖:16;同业比较:14;其他用途:历史
FY3/2026 results (tanshin): dividend income inside ordinary profit across both years怎么使用:直接 / 支持;一手验证:28;外部现实校验:16;专项深挖:28
FY3/2026 results (tanshin): headline consolidated results怎么使用:支持证据;一手验证:05、12、15
FY3/2026 results (tanshin): prior-year comparative - the FY3/25 peak operating year怎么使用:支持证据;一手验证:33;同业比较:12、15、16、19、28;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域28)|FY3/2026 results (tanshin): profit bridge from operating to net income;直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域28) / 历史/同业比较(研究域14) / 定向深挖(研究域16)|Q1 FY3/2027 results (tanshin): the non-operating income stack;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域16) / 定向深挖(研究域28)|FY3/2026 results (tanshin): dividend income inside ordinary profit across both years;支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域28)|FY3/2026 results (tanshin): prior-year comparative - the FY3/25 peak operating year
完整研究记录(核对用)
研究原文:The layered P&L (mix-driven operating line, a recurring JPY 0.55bn portfolio-income layer, and lumpy sale gains below) is the basis for excluding gains and keeping dividend income in the normalised earnings anchor.
内部研究类型:decomposition_defines_normalised_basis
内部来源标记:COVERAGE35
F053|07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产
研究范围:开放研究+35项覆盖检查
写入正文:07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产08|分红公式把证券收益也分给了少数股东
归并到:F070
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence怎么使用:直接证据;一手验证:13;外部现实校验:23;专项深挖:13;同业比较:24;其他用途:历史
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接证据;一手验证:22;专项深挖:22
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:直接 / 支持;一手验证:26;同业比较:35;其他用途:历史
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:支持证据;一手验证:05、07、24;反向验证:01、13、23、29
IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal怎么使用:支持证据;一手验证:13、23;反向验证:07、24
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:支持证据;一手验证:27、29、31;外部现实校验:21、22、26
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:支持证据;一手验证:18、21、29
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:支持证据;一手验证:17、19、25;外部现实校验:20
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 外部现实(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域13)|IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 反证(研究域07) / 反证(研究域24)|IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal;支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;支持证据 / 一手证据(研究域35)|Locally assembled monthly price history for 5363: span, range and moving averages;支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators
完整研究记录(核对用)
研究原文:With no forcing mechanism on management, the self-imposed payout formula is the only demonstrated channel for value to reach minorities, delivered on schedule three years running.
内部研究类型:insulation_makes_distribution_the_only_channel
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F054|09|这一轮股价上涨,基本是在为分红路径和资产变现付钱
研究范围:开放研究
写入正文:09|这一轮股价上涨,基本是在为分红路径和资产变现付钱10|价格对消息的反应:买变化,不买已知消息的确认
归并到:F034
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:直接 / 支持;一手验证:26;同业比较:35;其他用途:历史
Locally recomputed monthly series: annual highs, lows and closes, 2018-2026怎么使用:直接 / 支持;一手验证:34
Locally recomputed monthly series: 2026 range position and average configuration怎么使用:直接 / 支持;一手验证:31;反向验证:34
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:支持证据;一手验证:17、19、25;外部现实校验:20
Locally recomputed monthly series from the assembled price history (Yahoo Finance via the A0 mirror): full-span structure怎么使用:支持证据;一手验证:34;同业比较:27;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域34)|Locally recomputed monthly series: annual highs, lows and closes, 2018-2026;直接证据 / 支持证据 / 一手证据(研究域31) / 反证(研究域34)|Locally recomputed monthly series: 2026 range position and average configuration;支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators;支持证据 / 一手证据(研究域34) / 历史/同业比较(研究域27)|Locally recomputed monthly series from the assembled price history (Yahoo Finance via the A0 mirror): full-span structure
完整研究记录(核对用)
研究原文:The rising distribution path and asset events coincide with the 2023-2026 rising-low price staircase while revenue was flat. This is treated as association with a plausible funded mechanism, not as proven causation.
内部研究类型:distribution_path_associated_with_rerating
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F055|09|这一轮股价上涨,基本是在为分红路径和资产变现付钱
写入正文:09|这一轮股价上涨,基本是在为分红路径和资产变现付钱10|价格对消息的反应:买变化,不买已知消息的确认
归并到:F034
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Locally recomputed monthly series from the assembled price history (Yahoo Finance via the A0 mirror): full-span structure怎么使用:直接 / 支持;一手验证:34;同业比较:27;其他用途:历史
Locally recomputed monthly series: annual highs, lows and closes, 2018-2026怎么使用:直接 / 支持;一手验证:34
Locally recomputed monthly series: 2026 range position and average configuration怎么使用:支持证据;一手验证:31;反向验证:34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域34) / 历史/同业比较(研究域27)|Locally recomputed monthly series from the assembled price history (Yahoo Finance via the A0 mirror): full-span structure;直接证据 / 支持证据 / 一手证据(研究域34)|Locally recomputed monthly series: annual highs, lows and closes, 2018-2026;支持证据 / 一手证据(研究域31) / 反证(研究域34)|Locally recomputed monthly series: 2026 range position and average configuration
完整研究记录(核对用)
研究原文:The Fundamental-side interpretation of public price facts refers to the independent protected Technical Synthesis as a whole. It does not rewrite, flatten or substitute for it, and Fundamental positivity does not alter any non-confirming Technical State.
内部研究类型:references_protected_technical_structure_as_whole
内部来源标记:TECHNICAL
F056|11|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
研究范围:开放研究
写入正文:11|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
归并到:F025
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 results (tanshin): headline consolidated results怎么使用:直接 / 支持;一手验证:05、12、15
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:支持证据;一手验证:18、21、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026
完整研究记录(核对用)
研究原文:The equity-market exposure of the portfolio and the steel-tonnage exposure of the refractory business are hit by the same recession, so the portfolio's downside protection is asset coverage, not earnings stability.
内部研究类型:shared_exposure_defeats_diversification
内部来源标记:OPEN_DISCOVERY
F057|09|资产打折之后,每股归属价值仍明显高于股价
研究范围:开放研究+35项覆盖检查
归并到:F012
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio怎么使用:直接 / 支持;一手验证:32;外部现实校验:18、29;反向验证:21;专项深挖:18、29
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:支持证据;一手验证:27、29、31;外部现实校验:21、22、26
FY3/2026 results (tanshin): land and the physical footprint怎么使用:专项深挖:21;同业比较:21;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域18) / 外部现实(研究域29) / 反证(研究域21) / 定向深挖(研究域18) / 定向深挖(研究域29)|Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;反证 / 历史/同业比较(研究域21) / 定向深挖(研究域21)|FY3/2026 results (tanshin): land and the physical footprint
完整研究记录(核对用)
研究原文:The gross cash-plus-securities figure above market capitalisation is reduced by deferred tax on unrealised gains and the minorities' share before it becomes ordinary-shareholder value. The adjudicated value still exceeds the price by a wide margin.
内部研究类型:gross_value_qualified_by_haircuts
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F058|09|资产打折之后,每股归属价值仍明显高于股价
研究范围:35项覆盖检查
归并到:F012
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 results (tanshin): the non-controlling interest economy怎么使用:直接 / 支持;反向验证:18
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:支持证据;一手验证:18、21;反向验证:27
Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio怎么使用:支持证据;一手验证:32;外部现实校验:18、29;反向验证:21;专项深挖:18、29
FY3/2026 results (tanshin): land and the physical footprint怎么使用:专项深挖:21;同业比较:21;其他用途:反证、历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域18)|FY3/2026 results (tanshin): the non-controlling interest economy;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;支持证据 / 一手证据(研究域32) / 外部现实(研究域18) / 外部现实(研究域29) / 反证(研究域21) / 定向深挖(研究域18) / 定向深挖(研究域29)|Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio;反证 / 历史/同业比较(研究域21) / 定向深挖(研究域21)|FY3/2026 results (tanshin): land and the physical footprint
完整研究记录(核对用)
研究原文:JPY 6,841m of minority claims inside net assets reduce what attributes to a parent share. This is a symmetric obligation that must accompany any asset-based downside argument.
内部研究类型:minority_claim_reduces_attributable_value
内部来源标记:COVERAGE35
F059|03|海外利润在填补国内缺口,但只有一个季度的数据
研究范围:开放研究
写入正文:03|海外利润在填补国内缺口,但只有一个季度的数据
归并到:F005
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:直接 / 支持;一手验证:12;外部现实校验:15;反向验证:05、19
Q1 FY3/2027 results (tanshin): geographic segment results怎么使用:直接 / 支持;反向验证:14
FY3/2026 results (tanshin): geographic segment results怎么使用:支持证据;一手验证:02、06、14、15;同业比较:05;其他用途:历史
FY3/2026 results (tanshin): headline consolidated results怎么使用:支持证据;一手验证:05、12、15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;直接证据 / 支持证据 / 反证(研究域14)|Q1 FY3/2027 results (tanshin): geographic segment results;支持证据 / 一手证据(研究域02) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): geographic segment results;支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results
完整研究记录(核对用)
研究原文:Rising overseas profit partly offsets the declining domestic volume ceiling. The offset is small in absolute terms and has been observed over a single quarter.
内部研究类型:partial_offset
内部来源标记:OPEN_DISCOVERY
F060|07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产
研究范围:35项覆盖检查
写入正文:07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产08|分红公式把证券收益也分给了少数股东
归并到:F070
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接证据;一手验证:22;专项深挖:22
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:直接证据;一手验证:22;反向验证:09、11、31、33、35
FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings怎么使用:直接证据;外部现实校验:17、19、25;同业比较:32;其他用途:历史
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:支持证据;一手验证:26;同业比较:35;其他用途:历史
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:支持证据;一手验证:17、19、25;外部现实校验:20
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS;直接证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets;直接证据 / 外部现实(研究域17) / 外部现实(研究域19) / 外部现实(研究域25) / 历史/同业比较(研究域32)|FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators
完整研究记录(核对用)
研究原文:Because retained earnings compound the equity base faster than operating profit grows, the payout formula doubles as ROE maintenance, together with portfolio gains.
内部研究类型:payout_maintains_ratio
内部来源标记:COVERAGE35
F061|09|流动性限制了位置大小,报价高估大额持仓能实现的价值
研究范围:开放研究+35项覆盖检查
写入正文:09|流动性限制了位置大小,报价高估大额持仓能实现的价值13|资产侧:组合买了什么,土地值多少,大同想做什么,流动性会不会变深
归并到:F026
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture怎么使用:直接 / 支持;外部现实校验:34
IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print怎么使用:直接 / 支持;外部现实校验:27、31;专项深挖:31、34
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:支持证据;一手验证:27、29、31;外部现实校验:21、22、26
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:支持证据;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域34)|IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture;直接证据 / 支持证据 / 外部现实(研究域27) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print;支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios
完整研究记录(核对用)
研究原文:With about 68,000 shares traded a day and about half the register locked, the quoted price overstates realisable value for a block, and the re-rating proceeds incrementally.
内部研究类型:thin_float_qualifies_quoted_price
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
F062|06|三种会计呈现,会让只看一行数字的人两头判错
研究范围:35项覆盖检查
归并到:F033
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income怎么使用:直接证据;一手验证:32;反向验证:16、28;专项深挖:32
Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio怎么使用:直接证据;一手验证:32;外部现实校验:18、29;反向验证:21;专项深挖:18、29
Q1 FY3/2027 results (tanshin): the non-operating income stack怎么使用:直接证据;一手验证:16;外部现实校验:28;专项深挖:16;同业比较:14;其他用途:历史
FY3/2026 results (tanshin): headline consolidated results怎么使用:支持证据;一手验证:05、12、15
FY3/2026 results (tanshin): profit bridge from operating to net income怎么使用:支持证据;一手验证:06、14、16、28
FY3/2026 results (tanshin): prior-year comparative - the FY3/25 peak operating year怎么使用:支持证据;一手验证:33;同业比较:12、15、16、19、28;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域28) / 定向深挖(研究域32)|Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income;直接证据 / 一手证据(研究域32) / 外部现实(研究域18) / 外部现实(研究域29) / 反证(研究域21) / 定向深挖(研究域18) / 定向深挖(研究域29)|Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio;直接证据 / 一手证据(研究域16) / 外部现实(研究域28) / 历史/同业比较(研究域14) / 定向深挖(研究域16)|Q1 FY3/2027 results (tanshin): the non-operating income stack;支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域28)|FY3/2026 results (tanshin): profit bridge from operating to net income;支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域28)|FY3/2026 results (tanshin): prior-year comparative - the FY3/25 peak operating year
完整研究记录(核对用)
研究原文:The presentation rules (gains below the line, marks through OCI) are why each headline aggregate tells a different story, and why screens reading only one line misprice the company in both directions.
内部研究类型:explains_misleading_headlines
内部来源标记:COVERAGE35
F063|07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产
研究范围:开放研究+35项覆盖检查
写入正文:07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产08|分红公式把证券收益也分给了少数股东
归并到:F070
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since怎么使用:直接 / 支持;一手验证:25;反向验证:26;专项深挖:25;同业比较:13、23、33;其他用途:历史
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接证据;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings怎么使用:支持证据;外部现实校验:17、19、25;同业比较:32;其他用途:历史
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:支持证据;一手验证:27、29、31;外部现实校验:21、22、26
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:支持证据;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域13) / 历史/同业比较(研究域23) / 历史/同业比较(研究域33) / 反证(研究域26) / 定向深挖(研究域25)|IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since;直接证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;支持证据 / 外部现实(研究域17) / 外部现实(研究域19) / 外部现实(研究域25) / 历史/同业比较(研究域32)|FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings;支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios
完整研究记录(核对用)
研究原文:The absence of any buyback at about 0.6x book leaves discount closure to formula-speed distributions. A first buyback would be a mechanism change the price does not assume.
内部研究类型:absent_accelerant
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F064|10|要回答的问题:2023年起的阶梯,是已经站稳,还是在高位整理中走坏
写入正文:10|要回答的问题:2023年起的阶梯,是已经站稳,还是在高位整理中走坏10|上市以来四个阶段,2023年起这一段性质不同10|低点逐年抬高、均线整齐上行、回撤很快收回10|高位消化:五个月窄幅整理压在731至735日元压力位下10|价格对消息的反应:买变化,不买已知消息的确认10|接下来用什么价格行为来确认,什么会推翻13|治理空白与披露边界:这些问题没有当前公开路径14|八个模块的得分和各自一句理由
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (RESEARCH_TRUTH.technical_state)
内部研究类型:protected_technical_synthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
F065|02|长期面貌:一个把钢铁需求转成现金的小众产品,加一个比工厂还大的证券组合
研究范围:开放研究+35项覆盖检查
写入正文:02|长期面貌:一个把钢铁需求转成现金的小众产品,加一个比工厂还大的证券组合05|护城河护住的是单价,不是销量
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(42项,重复标签已合并)
Securities report data for TYK (FY3/2026): registered identity and English name怎么使用:直接 / 支持;一手验证:01
Nagoya Stock Exchange listing document for 5363: listing particulars and display name怎么使用:直接 / 支持;一手验证:01
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接 / 支持;一手验证:05、07、24;反向验证:01、13、23、29
FY3/2026 results (tanshin): parent-only results against consolidated怎么使用:直接 / 支持;同业比较:02;其他用途:历史
Nagoya Stock Exchange listing document: capital and listing facts怎么使用:直接证据;外部现实校验:01、13;同业比较:25;其他用途:历史
FY3/2026 results (tanshin): the non-controlling interest economy怎么使用:直接 / 支持;反向验证:18
FY3/2026 results (tanshin): headline consolidated results怎么使用:直接 / 支持;一手验证:05、12、15
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:直接 / 支持;一手验证:12;外部现实校验:15;反向验证:05、19
FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers怎么使用:直接证据;一手验证:11;外部现实校验:02、05、06、09、12、14;专项深挖:05、11、14
FY3/2026 results (tanshin): geographic segment results怎么使用:直接 / 支持;一手验证:02、06、14、15;同业比较:05;其他用途:历史
Securities report data for TYK: intellectual property as the technology record怎么使用:直接 / 支持;一手验证:04、10;外部现实校验:03;专项深挖:04、10
Securities report data for TYK: workforce stability indicators怎么使用:直接 / 支持;外部现实校验:04、10
Securities report data for TYK: parent scale, plants and patent stock怎么使用:直接证据;专项深挖:01、03;同业比较:10;其他用途:历史
FY3/2026 results (tanshin): business definition and segment architecture怎么使用:直接证据;一手验证:02、03、08、09、10
Q1 FY3/2027 results (tanshin): geographic segment results怎么使用:直接 / 支持;反向验证:14
Q1 FY3/2027 results (tanshin): segment internal sales and where exports sit怎么使用:直接证据;专项深挖:02、15
FY3/2026 results (tanshin): profit bridge from operating to net income怎么使用:直接 / 支持;一手验证:06、14、16、28
FY3/2026 results (tanshin): prior-year comparative - the FY3/25 peak operating year怎么使用:直接 / 支持;一手验证:33;同业比较:12、15、16、19、28;其他用途:历史
Q1 FY3/2027 results (tanshin): the non-operating income stack怎么使用:直接 / 支持;一手验证:16;外部现实校验:28;专项深挖:16;同业比较:14;其他用途:历史
FY3/2026 results (tanshin): dividend income inside ordinary profit across both years怎么使用:直接 / 支持;一手验证:28;外部现实校验:16;专项深挖:28
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:直接 / 支持;一手验证:17、19、25;外部现实校验:20
Q1 FY3/2027 results (tanshin): working capital and balance-sheet movements怎么使用:直接证据;一手验证:19;反向验证:06、17、32;专项深挖:19
Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell怎么使用:直接 / 支持;一手验证:17、20;专项深挖:06、17
FY3/2026 results (tanshin): the productive asset base is old and largely depreciated怎么使用:直接 / 支持;一手验证:20;专项深挖:20;同业比较:04、06;其他用途:历史
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:直接 / 支持;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接 / 支持;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio怎么使用:直接 / 支持;一手验证:32;外部现实校验:18、29;反向验证:21;专项深挖:18、29
FY3/2026 results (tanshin): land and the physical footprint怎么使用:直接证据;专项深挖:21;同业比较:21;其他用途:反证、历史
IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal怎么使用:直接 / 支持;一手验证:13、23;反向验证:07、24
IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence怎么使用:直接 / 支持;一手验证:13;外部现实校验:23;专项深挖:13;同业比较:24;其他用途:历史
IRBANK timely-disclosure index for TYK: 2026 governance and officer events怎么使用:直接证据;一手验证:23;专项深挖:23
Securities report data for TYK: register concentration and the absence of a controller怎么使用:直接证据;一手验证:24;外部现实校验:07;专项深挖:24;同业比较:01;其他用途:历史
Notice of 4 November 2026: the counterparty web around the Tohoku transaction怎么使用:直接证据;一手验证:07;专项深挖:07
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:直接 / 支持;一手验证:26;同业比较:35;其他用途:历史
IRBANK dividend record for TYK: per-share history and payout ratios怎么使用:直接证据;一手验证:26;专项深挖:26
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接证据;一手验证:22;专项深挖:22
FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings怎么使用:直接证据;外部现实校验:17、19、25;同业比较:32;其他用途:历史
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:直接证据;一手验证:22;反向验证:09、11、31、33、35
Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income怎么使用:直接证据;一手验证:32;反向验证:16、28;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|Securities report data for TYK (FY3/2026): registered identity and English name;直接证据 / 支持证据 / 一手证据(研究域01)|Nagoya Stock Exchange listing document for 5363: listing particulars and display name;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 支持证据 / 历史/同业比较(研究域02)|FY3/2026 results (tanshin): parent-only results against consolidated;直接证据 / 外部现实(研究域01) / 外部现实(研究域13) / 历史/同业比较(研究域25)|Nagoya Stock Exchange listing document: capital and listing facts;直接证据 / 支持证据 / 反证(研究域18)|FY3/2026 results (tanshin): the non-controlling interest economy;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域14) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域14)|FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): geographic segment results;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 外部现实(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|Securities report data for TYK: intellectual property as the technology record;直接证据 / 支持证据 / 外部现实(研究域04) / 外部现实(研究域10)|Securities report data for TYK: workforce stability indicators;直接证据 / 历史/同业比较(研究域10) / 定向深挖(研究域01) / 定向深挖(研究域03)|Securities report data for TYK: parent scale, plants and patent stock;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|FY3/2026 results (tanshin): business definition and segment architecture;直接证据 / 支持证据 / 反证(研究域14)|Q1 FY3/2027 results (tanshin): geographic segment results;直接证据 / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 results (tanshin): segment internal sales and where exports sit;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域28)|FY3/2026 results (tanshin): profit bridge from operating to net income;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域28)|FY3/2026 results (tanshin): prior-year comparative - the FY3/25 peak operating year;直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域28) / 历史/同业比较(研究域14) / 定向深挖(研究域16)|Q1 FY3/2027 results (tanshin): the non-operating income stack;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域16) / 定向深挖(研究域28)|FY3/2026 results (tanshin): dividend income inside ordinary profit across both years;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators;直接证据 / 一手证据(研究域19) / 反证(研究域06) / 反证(研究域17) / 反证(研究域32) / 定向深挖(研究域19)|Q1 FY3/2027 results (tanshin): working capital and balance-sheet movements;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 定向深挖(研究域06) / 定向深挖(研究域17)|Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell;直接证据 / 支持证据 / 一手证据(研究域20) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 定向深挖(研究域20)|FY3/2026 results (tanshin): the productive asset base is old and largely depreciated;直接证据 / 支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域18) / 外部现实(研究域29) / 反证(研究域21) / 定向深挖(研究域18) / 定向深挖(研究域29)|Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio;直接证据 / 反证 / 历史/同业比较(研究域21) / 定向深挖(研究域21)|FY3/2026 results (tanshin): land and the physical footprint;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 反证(研究域07) / 反证(研究域24)|IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域13)|IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|IRBANK timely-disclosure index for TYK: 2026 governance and officer events;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 定向深挖(研究域24)|Securities report data for TYK: register concentration and the absence of a controller;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Notice of 4 November 2026: the counterparty web around the Tohoku transaction;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|IRBANK dividend record for TYK: per-share history and payout ratios;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS;直接证据 / 外部现实(研究域17) / 外部现实(研究域19) / 外部现实(研究域25) / 历史/同业比较(研究域32)|FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings;直接证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域28) / 定向深挖(研究域32)|Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income
完整研究记录(核对用)
研究原文:Durable Business Portrait: qualified refractory niche, large securities portfolio, fortress balance sheet, formula distribution|The durable core is not growth, which has been absent for a decade. It is an assembly: a qualified, patent-deep refractory niche that converts a shrinking steel pond into steady cash; a securities portfolio larger than the plant base that pays dividends and periodically realises full-value gains inside a friendly industrial web; a fortress balance sheet that makes the structure nearly shock-proof; and a published payout formula that has since 2023 transmitted about 30% of operating and portfolio earnings alike to minorities. What is not durable: domestic tonnage falls every year, the growth quadrant is unverifiable, and the insulation that protects the assembly also caps the speed at which value reaches the share price. The structure is a race between a shrinking pond and a compounding distribution, and on the FY3/22-FY3/27 evidence the distribution is winning slowly. The fortress balance sheet funded overseas local manufacture, which is now the operating hedge.
内部研究类型:durable_business_portrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The shareholder owns a two-engine claim (a slow industrial annuity plus a financial portfolio) inside an insulated register. The return arrives at formula speed, cushioned by net cash and asset backing, with opportunity cost over years as the principal risk rather than solvency.
不确定性(原始记录):Mid-cycle Japan margin, advanced-materials economics, portfolio composition and land value are unresolved, and the two engines correlate in a severe downturn.
F066|08|東北特殊鋼的出售:第一次证明隐含资产能按全价变成现金
研究范围:开放研究+35项覆盖检查
写入正文:08|東北特殊鋼的出售:第一次证明隐含资产能按全价变成现金12|一笔收益把登记簿、证券组合和分红公式连成了一条链
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(18项,重复标签已合并)
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接 / 支持;一手验证:05、07、24;反向验证:01、13、23、29
Securities report data for TYK: register concentration and the absence of a controller怎么使用:直接证据;一手验证:24;外部现实校验:07;专项深挖:24;同业比较:01;其他用途:历史
Notice of 4 November 2026: the counterparty web around the Tohoku transaction怎么使用:直接证据;一手验证:07;专项深挖:07
FY3/2026 results (tanshin): material subsequent event - the Tohoku Special Steel agreement怎么使用:直接 / 支持
Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised怎么使用:直接 / 支持;同业比较:30;其他用途:历史
FY3/2027 company forecast as maintained at the Q1 print怎么使用:直接 / 支持;一手验证:30;外部现实校验:35;反向验证:12、15
FY3/2026 results (tanshin): subsequent-event detail - the squeeze-out mechanics怎么使用:直接证据;同业比较:07;其他用途:历史
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:直接 / 支持;一手验证:26;同业比较:35;其他用途:历史
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:直接 / 支持;一手验证:17、19、25;外部现实校验:20
IRBANK dividend record for TYK: per-share history and payout ratios怎么使用:直接 / 支持;一手验证:26;专项深挖:26
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接证据;一手验证:22;专项深挖:22
FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings怎么使用:直接证据;外部现实校验:17、19、25;同业比较:32;其他用途:历史
IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence怎么使用:直接证据;一手验证:13;外部现实校验:23;专项深挖:13;同业比较:24;其他用途:历史
IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal怎么使用:支持证据;一手验证:13、23;反向验证:07、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 定向深挖(研究域24)|Securities report data for TYK: register concentration and the absence of a controller;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Notice of 4 November 2026: the counterparty web around the Tohoku transaction;直接证据 / 支持证据|FY3/2026 results (tanshin): material subsequent event - the Tohoku Special Steel agreement;直接证据 / 支持证据 / 历史/同业比较(研究域30)|Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised;直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域35) / 反证(研究域12) / 反证(研究域15)|FY3/2027 company forecast as maintained at the Q1 print;直接证据 / 历史/同业比较(研究域07)|FY3/2026 results (tanshin): subsequent-event detail - the squeeze-out mechanics;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|IRBANK dividend record for TYK: per-share history and payout ratios;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS;直接证据 / 外部现实(研究域17) / 外部现实(研究域19) / 外部现实(研究域25) / 历史/同业比较(研究域32)|FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings;直接证据 / 一手证据(研究域13) / 外部现实(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域13)|IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence;支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 反证(研究域07) / 反证(研究域24)|IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal;支持证据 / 一手证据(研究域35)|Locally assembled monthly price history for 5363: span, range and moving averages
完整研究记录(核对用)
研究原文:Tohoku chain: register, portfolio and dividend as one mechanism|A friendly holder's reorganisation released a cross-holding at full value, the gain entered the forecast in May, and the payout formula will pay about 30% of it out as the raised year-end dividend. Governance, assets and return are one causal mechanism, not three topics.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Minorities benefit from the web's asset deals and pay for it with the discount that the same insulation creates.
不确定性(原始记录):Whether further web transactions follow is unknown. The year-end dividend is decided with the May 2027 results.
F067|07|中期计划同时承载增长承诺和分红承诺,两条腿可以分开兑现
研究范围:开放研究+35项覆盖检查
写入正文:07|中期计划同时承载增长承诺和分红承诺,两条腿可以分开兑现09|价格已经假定折价长期存在,买入的是公式股息加一个期权
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(14项,重复标签已合并)
Medium-term management plan 2024-2028: the FY2028 numerical targets怎么使用:直接 / 支持;一手验证:09、11;反向验证:08、22
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:直接 / 支持;一手验证:22;反向验证:09、11、31、33、35
FY3/2026 results (tanshin): business definition and segment architecture怎么使用:直接 / 支持;一手验证:02、03、08、09、10
FY3/2026 results (tanshin): what the 'other' category contains怎么使用:直接 / 支持;反向验证:02、04、10;同业比较:03;其他用途:历史
Medium-term plan 2024-2028: the business portfolio framing怎么使用:直接 / 支持;专项深挖:08;同业比较:08;其他用途:历史
FY3/2026 results (tanshin): the 'other' businesses inside the group怎么使用:直接 / 支持;反向验证:03
Medium-term plan 2024-2028: where the growth is supposed to come from怎么使用:直接证据;外部现实校验:08、11;反向验证:20;专项深挖:09
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:直接 / 支持;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接证据;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print怎么使用:直接证据;外部现实校验:27、31;专项深挖:31、34
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接证据;一手验证:22;专项深挖:22
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:支持证据;一手验证:26;同业比较:35;其他用途:历史
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:支持证据;一手验证:17、19、25;外部现实校验:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域11) / 反证(研究域08) / 反证(研究域22)|Medium-term management plan 2024-2028: the FY2028 numerical targets;直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|FY3/2026 results (tanshin): business definition and segment architecture;直接证据 / 支持证据 / 历史/同业比较(研究域03) / 反证(研究域02) / 反证(研究域04) / 反证(研究域10)|FY3/2026 results (tanshin): what the 'other' category contains;直接证据 / 支持证据 / 历史/同业比较(研究域08) / 定向深挖(研究域08)|Medium-term plan 2024-2028: the business portfolio framing;直接证据 / 支持证据 / 反证(研究域03)|FY3/2026 results (tanshin): the 'other' businesses inside the group;直接证据 / 外部现实(研究域08) / 外部现实(研究域11) / 反证(研究域20) / 定向深挖(研究域09)|Medium-term plan 2024-2028: where the growth is supposed to come from;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios;直接证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;直接证据 / 外部现实(研究域27) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators
完整研究记录(核对用)
研究原文:Plan credibility and the segment-disclosure gap|Growth is assigned to businesses the accounts do not isolate, so the plan cannot be verified. The market's refusal to price it (6.4x, about 0.6x book) is the rational response to an unverifiable claim rather than neglect.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Do not pay for the plan target. The May 2027 reckoning is the scheduled test.
不确定性(原始记录):Revise, defer or defend is unresolved, and new-materials economics are undisclosed.
F068|03|海外利润在填补国内缺口,但只有一个季度的数据
研究范围:开放研究+35项覆盖检查
写入正文:03|海外利润在填补国内缺口,但只有一个季度的数据
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(11项,重复标签已合并)
FY3/2026 results (tanshin): headline consolidated results怎么使用:直接 / 支持;一手验证:05、12、15
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:直接 / 支持;一手验证:12;外部现实校验:15;反向验证:05、19
FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers怎么使用:直接证据;一手验证:11;外部现实校验:02、05、06、09、12、14;专项深挖:05、11、14
FY3/2026 results (tanshin): geographic segment results怎么使用:直接 / 支持;一手验证:02、06、14、15;同业比较:05;其他用途:历史
Q1 FY3/2027 results (tanshin): geographic segment results怎么使用:直接 / 支持;反向验证:14
Q1 FY3/2027 results (tanshin): segment internal sales and where exports sit怎么使用:直接 / 支持;专项深挖:02、15
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:直接 / 支持;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接证据;一手验证:18、21、29
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:直接证据;一手验证:17、19、25;外部现实校验:20
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接 / 支持;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
Nagoya Stock Exchange listing document: capital and listing facts怎么使用:直接证据;外部现实校验:01、13;同业比较:25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域14) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域14)|FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): geographic segment results;直接证据 / 支持证据 / 反证(研究域14)|Q1 FY3/2027 results (tanshin): geographic segment results;直接证据 / 支持证据 / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 results (tanshin): segment internal sales and where exports sit;直接证据 / 支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;直接证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;直接证据 / 外部现实(研究域01) / 外部现实(研究域13) / 历史/同业比较(研究域25)|Nagoya Stock Exchange listing document: capital and listing facts
完整研究记录(核对用)
研究原文:Overseas hedge funded by yesterday's conservatism|The fortress balance sheet, built by decades of retained refractory cash flow, funded local manufacture abroad, which is now the operating hedge. Yesterday's conservatism is today's diversification. The hedge carries tariff beta and rests on one quarter of strong data.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Overseas steadiness is the current evidence; domestic volume recovery is the falsifiable mistake.
不确定性(原始记录):Persistence beyond Q1 FY3/27 and the transfer-versus-local-demand split are undisclosed.
F069|01|折价能否靠分红公式收窄,要比国内需求萎缩得更快
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|折价能否靠分红公式收窄,要比国内需求萎缩得更快11|什么会推翻这个判断14|综合得分63.23/100,评级B
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(52项,重复标签已合并)
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
Locally assembled monthly price history for 5363: span, range and moving averages怎么使用:直接 / 支持;一手验证:35
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:直接 / 支持;一手验证:26;同业比较:35;其他用途:历史
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接 / 支持;一手验证:22;专项深挖:22
IRBANK dividend record for TYK: per-share history and payout ratios怎么使用:直接 / 支持;一手验证:26;专项深挖:26
FY3/2027 company forecast as maintained at the Q1 print怎么使用:直接 / 支持;一手验证:30;外部现实校验:35;反向验证:12、15
Q1 FY3/2027 results (tanshin): forecast table and the unchanged-stance statement怎么使用:直接 / 支持;反向验证:25、30
IRBANK timely-disclosure index for TYK: the November dividend-revision pattern怎么使用:直接 / 支持;一手验证:30;专项深挖:30、35;同业比较:26;其他用途:历史
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:直接 / 支持;一手验证:12;外部现实校验:15;反向验证:05、19
Medium-term management plan 2024-2028: the FY2028 numerical targets怎么使用:直接 / 支持;一手验证:09、11;反向验证:08、22
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:直接 / 支持;一手验证:22;反向验证:09、11、31、33、35
IRBANK timely-disclosure index for TYK: FY3/26 interim revisions - the beat-and-raise half怎么使用:直接 / 支持;外部现实校验:30;专项深挖:12、33
IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture怎么使用:直接 / 支持;外部现实校验:34
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:直接 / 支持;一手验证:17、19、25;外部现实校验:20
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:直接 / 支持;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接 / 支持;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print怎么使用:直接证据;外部现实校验:27、31;专项深挖:31、34
IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence怎么使用:直接 / 支持;一手验证:13;外部现实校验:23;专项深挖:13;同业比较:24;其他用途:历史
IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal怎么使用:直接 / 支持;一手验证:13、23;反向验证:07、24
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接 / 支持;一手验证:05、07、24;反向验证:01、13、23、29
IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since怎么使用:直接 / 支持;一手验证:25;反向验证:26;专项深挖:25;同业比较:13、23、33;其他用途:历史
FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings怎么使用:直接 / 支持;外部现实校验:17、19、25;同业比较:32;其他用途:历史
Securities report data for TYK (FY3/2026): registered identity and English name怎么使用:直接 / 支持;一手验证:01
Nagoya Stock Exchange listing document for 5363: listing particulars and display name怎么使用:直接 / 支持;一手验证:01
FY3/2026 results (tanshin): parent-only results against consolidated怎么使用:直接 / 支持;同业比较:02;其他用途:历史
Nagoya Stock Exchange listing document: capital and listing facts怎么使用:直接证据;外部现实校验:01、13;同业比较:25;其他用途:历史
FY3/2026 results (tanshin): the non-controlling interest economy怎么使用:直接 / 支持;反向验证:18
FY3/2026 results (tanshin): headline consolidated results怎么使用:直接 / 支持;一手验证:05、12、15
FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers怎么使用:直接证据;一手验证:11;外部现实校验:02、05、06、09、12、14;专项深挖:05、11、14
FY3/2026 results (tanshin): geographic segment results怎么使用:直接 / 支持;一手验证:02、06、14、15;同业比较:05;其他用途:历史
Securities report data for TYK: intellectual property as the technology record怎么使用:直接 / 支持;一手验证:04、10;外部现实校验:03;专项深挖:04、10
Securities report data for TYK: workforce stability indicators怎么使用:直接 / 支持;外部现实校验:04、10
Securities report data for TYK: parent scale, plants and patent stock怎么使用:直接证据;专项深挖:01、03;同业比较:10;其他用途:历史
FY3/2026 results (tanshin): business definition and segment architecture怎么使用:直接证据;一手验证:02、03、08、09、10
Q1 FY3/2027 results (tanshin): geographic segment results怎么使用:直接 / 支持;反向验证:14
Q1 FY3/2027 results (tanshin): segment internal sales and where exports sit怎么使用:直接证据;专项深挖:02、15
FY3/2026 results (tanshin): profit bridge from operating to net income怎么使用:直接 / 支持;一手验证:06、14、16、28
FY3/2026 results (tanshin): prior-year comparative - the FY3/25 peak operating year怎么使用:直接 / 支持;一手验证:33;同业比较:12、15、16、19、28;其他用途:历史
Q1 FY3/2027 results (tanshin): the non-operating income stack怎么使用:直接 / 支持;一手验证:16;外部现实校验:28;专项深挖:16;同业比较:14;其他用途:历史
FY3/2026 results (tanshin): dividend income inside ordinary profit across both years怎么使用:直接 / 支持;一手验证:28;外部现实校验:16;专项深挖:28
Q1 FY3/2027 results (tanshin): working capital and balance-sheet movements怎么使用:直接证据;一手验证:19;反向验证:06、17、32;专项深挖:19
Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell怎么使用:直接 / 支持;一手验证:17、20;专项深挖:06、17
FY3/2026 results (tanshin): the productive asset base is old and largely depreciated怎么使用:直接 / 支持;一手验证:20;专项深挖:20;同业比较:04、06;其他用途:历史
Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio怎么使用:直接 / 支持;一手验证:32;外部现实校验:18、29;反向验证:21;专项深挖:18、29
FY3/2026 results (tanshin): land and the physical footprint怎么使用:直接证据;专项深挖:21;同业比较:21;其他用途:反证、历史
IRBANK timely-disclosure index for TYK: 2026 governance and officer events怎么使用:直接证据;一手验证:23;专项深挖:23
Securities report data for TYK: register concentration and the absence of a controller怎么使用:直接证据;一手验证:24;外部现实校验:07;专项深挖:24;同业比较:01;其他用途:历史
Notice of 4 November 2026: the counterparty web around the Tohoku transaction怎么使用:直接证据;一手验证:07;专项深挖:07
Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income怎么使用:直接证据;一手验证:32;反向验证:16、28;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 支持证据 / 一手证据(研究域35)|Locally assembled monthly price history for 5363: span, range and moving averages;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS;直接证据 / 支持证据 / 一手证据(研究域26) / 定向深挖(研究域26)|IRBANK dividend record for TYK: per-share history and payout ratios;直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域35) / 反证(研究域12) / 反证(研究域15)|FY3/2027 company forecast as maintained at the Q1 print;直接证据 / 支持证据 / 反证(研究域25) / 反证(研究域30)|Q1 FY3/2027 results (tanshin): forecast table and the unchanged-stance statement;直接证据 / 支持证据 / 一手证据(研究域30) / 历史/同业比较(研究域26) / 定向深挖(研究域30) / 定向深挖(研究域35)|IRBANK timely-disclosure index for TYK: the November dividend-revision pattern;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域11) / 反证(研究域08) / 反证(研究域22)|Medium-term management plan 2024-2028: the FY2028 numerical targets;直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets;直接证据 / 支持证据 / 外部现实(研究域30) / 定向深挖(研究域12) / 定向深挖(研究域33)|IRBANK timely-disclosure index for TYK: FY3/26 interim revisions - the beat-and-raise half;直接证据 / 支持证据 / 外部现实(研究域34)|IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture;直接证据 / 支持证据|FY3/2026 results (tanshin): per-share data and share counts;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;直接证据 / 支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;直接证据 / 外部现实(研究域27) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域13)|IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 反证(研究域07) / 反证(研究域24)|IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域13) / 历史/同业比较(研究域23) / 历史/同业比较(研究域33) / 反证(研究域26) / 定向深挖(研究域25)|IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域19) / 外部现实(研究域25) / 历史/同业比较(研究域32)|FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings;直接证据 / 支持证据 / 一手证据(研究域01)|Securities report data for TYK (FY3/2026): registered identity and English name;直接证据 / 支持证据 / 一手证据(研究域01)|Nagoya Stock Exchange listing document for 5363: listing particulars and display name;直接证据 / 支持证据 / 历史/同业比较(研究域02)|FY3/2026 results (tanshin): parent-only results against consolidated;直接证据 / 外部现实(研究域01) / 外部现实(研究域13) / 历史/同业比较(研究域25)|Nagoya Stock Exchange listing document: capital and listing facts;直接证据 / 支持证据 / 反证(研究域18)|FY3/2026 results (tanshin): the non-controlling interest economy;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域14) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域14)|FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): geographic segment results;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 外部现实(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|Securities report data for TYK: intellectual property as the technology record;直接证据 / 支持证据 / 外部现实(研究域04) / 外部现实(研究域10)|Securities report data for TYK: workforce stability indicators;直接证据 / 历史/同业比较(研究域10) / 定向深挖(研究域01) / 定向深挖(研究域03)|Securities report data for TYK: parent scale, plants and patent stock;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|FY3/2026 results (tanshin): business definition and segment architecture;直接证据 / 支持证据 / 反证(研究域14)|Q1 FY3/2027 results (tanshin): geographic segment results;直接证据 / 定向深挖(研究域02) / 定向深挖(研究域15)|Q1 FY3/2027 results (tanshin): segment internal sales and where exports sit;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域16) / 一手证据(研究域28)|FY3/2026 results (tanshin): profit bridge from operating to net income;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域12) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域28)|FY3/2026 results (tanshin): prior-year comparative - the FY3/25 peak operating year;直接证据 / 支持证据 / 一手证据(研究域16) / 外部现实(研究域28) / 历史/同业比较(研究域14) / 定向深挖(研究域16)|Q1 FY3/2027 results (tanshin): the non-operating income stack;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域16) / 定向深挖(研究域28)|FY3/2026 results (tanshin): dividend income inside ordinary profit across both years;直接证据 / 一手证据(研究域19) / 反证(研究域06) / 反证(研究域17) / 反证(研究域32) / 定向深挖(研究域19)|Q1 FY3/2027 results (tanshin): working capital and balance-sheet movements;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 定向深挖(研究域06) / 定向深挖(研究域17)|Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell;直接证据 / 支持证据 / 一手证据(研究域20) / 历史/同业比较(研究域04) / 历史/同业比较(研究域06) / 定向深挖(研究域20)|FY3/2026 results (tanshin): the productive asset base is old and largely depreciated;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域18) / 外部现实(研究域29) / 反证(研究域21) / 定向深挖(研究域18) / 定向深挖(研究域29)|Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio;直接证据 / 反证 / 历史/同业比较(研究域21) / 定向深挖(研究域21)|FY3/2026 results (tanshin): land and the physical footprint;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|IRBANK timely-disclosure index for TYK: 2026 governance and officer events;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 定向深挖(研究域24)|Securities report data for TYK: register concentration and the absence of a controller;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Notice of 4 November 2026: the counterparty web around the Tohoku transaction;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域28) / 定向深挖(研究域32)|Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income
完整研究记录(核对用)
研究原文:Thesis: formula-speed discount closure versus domestic erosion, with dated falsifiers|The question upgraded from 'asset box versus insulated stagnation' to whether formula-driven distributions close the discount faster than the domestic base erodes. The record says they are, slowly. Dated tests are the 12 Nov 2026 interim print, the May 2027 year-end dividend and plan decision, and the FY3/28 operating band.
内部研究类型:thesis_and_falsification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Hold-type exposure to a roughly 4.7% formula coupon plus an option on faster release; exit discipline is a formula break, not interim noise.
不确定性(原始记录):Thesis confidence is about 0.7. Fundamental falsifiers are separate from protected Technical falsifiers.
F070|07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产
研究范围:开放研究+35项覆盖检查
写入正文:07|封闭的股东结构加防御政策:没有任何力量在逼公司释放资产08|分红公式把证券收益也分给了少数股东
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(20项,重复标签已合并)
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接 / 支持;一手验证:05、07、24;反向验证:01、13、23、29
IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal怎么使用:直接 / 支持;一手验证:13、23;反向验证:07、24
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence怎么使用:直接 / 支持;一手验证:13;外部现实校验:23;专项深挖:13;同业比较:24;其他用途:历史
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接 / 支持;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
IRBANK timely-disclosure index for TYK: 2026 governance and officer events怎么使用:直接证据;一手验证:23;专项深挖:23
Securities report data for TYK: register concentration and the absence of a controller怎么使用:直接证据;一手验证:24;外部现实校验:07;专项深挖:24;同业比较:01;其他用途:历史
Notice of 4 November 2026: the counterparty web around the Tohoku transaction怎么使用:直接证据;一手验证:07;专项深挖:07
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:直接 / 支持;一手验证:26;同业比较:35;其他用途:历史
FY3/2026 results (tanshin): cash flow and financial indicators怎么使用:直接 / 支持;一手验证:17、19、25;外部现实校验:20
IRBANK dividend record for TYK: per-share history and payout ratios怎么使用:直接证据;一手验证:26;专项深挖:26
Medium-term plan 2024-2028: capital policy - payout floor and rising DPS怎么使用:直接证据;一手验证:22;专项深挖:22
FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings怎么使用:直接 / 支持;外部现实校验:17、19、25;同业比较:32;其他用途:历史
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:直接证据;一手验证:22;反向验证:09、11、31、33、35
IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since怎么使用:直接 / 支持;一手验证:25;反向验证:26;专项深挖:25;同业比较:13、23、33;其他用途:历史
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:直接 / 支持;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print怎么使用:直接证据;外部现实校验:27、31;专项深挖:31、34
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:支持证据;一手验证:18、21、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 反证(研究域07) / 反证(研究域24)|IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域13)|IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|IRBANK timely-disclosure index for TYK: 2026 governance and officer events;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 定向深挖(研究域24)|Securities report data for TYK: register concentration and the absence of a controller;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Notice of 4 November 2026: the counterparty web around the Tohoku transaction;直接证据 / 支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 一手证据(研究域25) / 外部现实(研究域20)|FY3/2026 results (tanshin): cash flow and financial indicators;直接证据 / 一手证据(研究域26) / 定向深挖(研究域26)|IRBANK dividend record for TYK: per-share history and payout ratios;直接证据 / 一手证据(研究域22) / 定向深挖(研究域22)|Medium-term plan 2024-2028: capital policy - payout floor and rising DPS;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域19) / 外部现实(研究域25) / 历史/同业比较(研究域32)|FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings;直接证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets;直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域13) / 历史/同业比较(研究域23) / 历史/同业比较(研究域33) / 反证(研究域26) / 定向深挖(研究域25)|IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since;直接证据|FY3/2026 results (tanshin): per-share data and share counts;直接证据 / 支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios;直接证据 / 外部现实(研究域27) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print;支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;支持证据 / 一手证据(研究域35)|Locally assembled monthly price history for 5363: span, range and moving averages
完整研究记录(核对用)
研究原文:Governance insulation, distribution formula and discount closure|Friendly register and defence policy mean no external pressure to release assets, so the portfolio compounds inside the company. The only demonstrated release is the 30% payout formula, which also maintains ROE. The discount therefore erodes at formula speed, and only a mechanism change (buyback, payout raise, large realisation) would speed it.
内部研究类型:main_causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A slow, observable, formula-paced return rather than an event-driven re-rating.
不确定性(原始记录):Formula persistence beyond the plan period and the absence of any buyback trigger are unknown.
F071|11|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
研究范围:开放研究+35项覆盖检查
写入正文:11|最大的风险:钢铁需求和证券组合会在同一次衰退里一起受损
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(20项,重复标签已合并)
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接 / 支持;一手验证:18、21;反向验证:27
FY3/2026 results (tanshin): balance sheet at 31 March 2026怎么使用:直接 / 支持;一手验证:18、21、29
Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income怎么使用:直接证据;一手验证:32;反向验证:16、28;专项深挖:32
Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio怎么使用:直接 / 支持;一手验证:32;外部现实校验:18、29;反向验证:21;专项深挖:18、29
FY3/2026 results (tanshin): headline consolidated results怎么使用:直接 / 支持;一手验证:05、12、15
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:直接 / 支持;一手验证:12;外部现实校验:15;反向验证:05、19
FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers怎么使用:直接证据;一手验证:11;外部现实校验:02、05、06、09、12、14;专项深挖:05、11、14
FY3/2026 results (tanshin): geographic segment results怎么使用:直接证据;一手验证:02、06、14、15;同业比较:05;其他用途:历史
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接 / 支持;一手验证:05、07、24;反向验证:01、13、23、29
IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal怎么使用:直接 / 支持;一手验证:13、23;反向验证:07、24
IRBANK stock page snapshot for 5363 as of 6 November 2026怎么使用:直接 / 支持;一手验证:27、29、31;外部现实校验:21、22、26
IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence怎么使用:直接 / 支持;一手验证:13;外部现实校验:23;专项深挖:13;同业比较:24;其他用途:历史
IRBANK stock page for 5363: the sixteen-year PBR band怎么使用:直接 / 支持;一手验证:27;外部现实校验:24;专项深挖:27;同业比较:31;其他用途:历史
IRBANK timely-disclosure index for TYK: 2026 governance and officer events怎么使用:直接证据;一手验证:23;专项深挖:23
IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print怎么使用:直接 / 支持;外部现实校验:27、31;专项深挖:31、34
IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture怎么使用:直接 / 支持;外部现实校验:34
Securities report data for TYK: register concentration and the absence of a controller怎么使用:直接证据;一手验证:24;外部现实校验:07;专项深挖:24;同业比较:01;其他用途:历史
FY3/2026 results (tanshin): land and the physical footprint怎么使用:直接证据;专项深挖:21;同业比较:21;其他用途:反证、历史
FY3/2026 results (tanshin): the non-controlling interest economy怎么使用:直接 / 支持;反向验证:18
FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios怎么使用:支持证据;外部现实校验:33;同业比较:09、11、17、18、20、22;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 results (tanshin): balance sheet at 31 March 2026;直接证据 / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域28) / 定向深挖(研究域32)|Q1 FY3/2027 results (tanshin): comprehensive income dwarfs net income;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域18) / 外部现实(研究域29) / 反证(研究域21) / 定向深挖(研究域18) / 定向深挖(研究域29)|Q1 FY3/2027 results (tanshin): the deferred-tax shadow of the portfolio;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域12) / 一手证据(研究域15)|FY3/2026 results (tanshin): headline consolidated results;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域14) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域14)|FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers;直接证据 / 一手证据(研究域02) / 一手证据(研究域06) / 一手证据(研究域14) / 一手证据(研究域15) / 历史/同业比较(研究域05)|FY3/2026 results (tanshin): geographic segment results;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 反证(研究域07) / 反证(研究域24)|IRBANK timely-disclosure index for TYK: the anti-takeover defence renewal;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域29) / 一手证据(研究域31) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26)|IRBANK stock page snapshot for 5363 as of 6 November 2026;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域23) / 历史/同业比较(研究域24) / 定向深挖(研究域13)|IRBANK timely-disclosure index for TYK: the defence-policy renewal cadence;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域24) / 历史/同业比较(研究域31) / 定向深挖(研究域27)|IRBANK stock page for 5363: the sixteen-year PBR band;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|IRBANK timely-disclosure index for TYK: 2026 governance and officer events;直接证据 / 支持证据 / 外部现实(研究域27) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print;直接证据 / 支持证据 / 外部现实(研究域34)|IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 定向深挖(研究域24)|Securities report data for TYK: register concentration and the absence of a controller;直接证据 / 反证 / 历史/同业比较(研究域21) / 定向深挖(研究域21)|FY3/2026 results (tanshin): land and the physical footprint;直接证据 / 支持证据 / 反证(研究域18)|FY3/2026 results (tanshin): the non-controlling interest economy;支持证据 / 外部现实(研究域33) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22)|FY3/2026 results (tanshin): five-year indicator trend - equity ratio and cash-flow ratios
完整研究记录(核对用)
研究原文:Downside and failure paths: correlated engines, portfolio beta, entrenchment, thin float|No solvency path exists, so the failure paths are slow: a synchronised steel and equity-market downturn, a broken payout channel, and sixteen more years at a wide discount in a thin, locked float. Asset backing limits loss but not time.
内部研究类型:downside_and_failure_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Risk is opportunity cost and exit liquidity, not ruin.
不确定性(原始记录):Land value, portfolio composition and the correlation magnitude are not quantified.
F072|13|治理空白与披露边界:这些问题没有当前公开路径
研究范围:开放研究+35项覆盖检查
写入正文:13|治理空白与披露边界:这些问题没有当前公开路径15|证据限制
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(29项,重复标签已合并)
FY3/2027 company forecast as maintained at the Q1 print怎么使用:直接 / 支持;一手验证:30;外部现实校验:35;反向验证:12、15
Q1 FY3/2027 results (tanshin): forecast table and the unchanged-stance statement怎么使用:直接 / 支持;反向验证:25、30
IRBANK timely-disclosure index for TYK: the November dividend-revision pattern怎么使用:直接证据;一手验证:30;专项深挖:30、35;同业比较:26;其他用途:历史
Q1 FY3/2027 results (tanshin): headline results for April-June 2026怎么使用:直接证据;一手验证:12;外部现实校验:15;反向验证:05、19
IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast怎么使用:支持证据;一手验证:26;同业比较:35;其他用途:历史
Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells怎么使用:直接证据;一手验证:18、21;反向验证:27
Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised怎么使用:直接证据;同业比较:30;其他用途:历史
FY3/2026 results (tanshin): what the 'other' category contains怎么使用:直接 / 支持;反向验证:02、04、10;同业比较:03;其他用途:历史
Medium-term plan 2024-2028: the business portfolio framing怎么使用:直接 / 支持;专项深挖:08;同业比较:08;其他用途:历史
FY3/2026 results (tanshin): the 'other' businesses inside the group怎么使用:直接 / 支持;反向验证:03
Medium-term plan 2024-2028: where the growth is supposed to come from怎么使用:直接证据;外部现实校验:08、11;反向验证:20;专项深挖:09
Medium-term management plan 2024-2028: the FY2028 numerical targets怎么使用:直接 / 支持;一手验证:09、11;反向验证:08、22
Plan progress read from FY3/2026 actuals against the FY2028 targets怎么使用:直接 / 支持;一手验证:22;反向验证:09、11、31、33、35
Securities report data for TYK (FY3/2026): the top-ten shareholder register怎么使用:直接证据;一手验证:05、07、24;反向验证:01、13、23、29
Securities report data for TYK: register concentration and the absence of a controller怎么使用:直接证据;一手验证:24;外部现实校验:07;专项深挖:24;同业比较:01;其他用途:历史
Notice of 4 November 2026: the counterparty web around the Tohoku transaction怎么使用:直接证据;一手验证:07;专项深挖:07
FY3/2026 results (tanshin): land and the physical footprint怎么使用:直接证据;专项深挖:21;同业比较:21;其他用途:历史
IRBANK timely-disclosure index for TYK: 2026 governance and officer events怎么使用:直接证据;一手验证:23;专项深挖:23
IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since怎么使用:直接 / 支持;一手验证:25;反向验证:26;专项深挖:25;同业比较:13、23、33;其他用途:历史
FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings怎么使用:直接 / 支持;外部现实校验:17、19、25;同业比较:32;其他用途:历史
IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print怎么使用:直接 / 支持;外部现实校验:27、31;专项深挖:31、34
IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture怎么使用:直接 / 支持;外部现实校验:34
FY3/2026 results (tanshin): business definition and segment architecture怎么使用:直接证据;一手验证:02、03、08、09、10
Q1 FY3/2027 results (tanshin): working capital and balance-sheet movements怎么使用:直接证据;一手验证:19;反向验证:06、17、32;专项深挖:19
FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers怎么使用:直接证据;一手验证:11;外部现实校验:02、05、06、09、12、14;专项深挖:05、11、14
Securities report data for TYK: intellectual property as the technology record怎么使用:直接证据;一手验证:04、10;外部现实校验:03;专项深挖:04、10
Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell怎么使用:直接证据;一手验证:17、20;专项深挖:06、17
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域35) / 反证(研究域12) / 反证(研究域15)|FY3/2027 company forecast as maintained at the Q1 print;直接证据 / 支持证据 / 反证(研究域25) / 反证(研究域30)|Q1 FY3/2027 results (tanshin): forecast table and the unchanged-stance statement;直接证据 / 一手证据(研究域30) / 历史/同业比较(研究域26) / 定向深挖(研究域30) / 定向深挖(研究域35)|IRBANK timely-disclosure index for TYK: the November dividend-revision pattern;直接证据 / 一手证据(研究域12) / 外部现实(研究域15) / 反证(研究域05) / 反证(研究域19)|Q1 FY3/2027 results (tanshin): headline results for April-June 2026;支持证据 / 一手证据(研究域26) / 历史/同业比较(研究域35)|IRBANK dividend record for TYK: five consecutive increases and the FY3/27 forecast;直接证据 / 一手证据(研究域18) / 一手证据(研究域21) / 反证(研究域27)|Q1 FY3/2027 results (tanshin): balance sheet at 30 June 2026 - the securities book swells;直接证据|FY3/2026 results (tanshin): material subsequent event - the Tohoku Special Steel agreement;直接证据 / 历史/同业比较(研究域30)|Notice of 4 November 2026: the JPY 2,097 million securities-sale gain is realised;直接证据 / 支持证据 / 历史/同业比较(研究域03) / 反证(研究域02) / 反证(研究域04) / 反证(研究域10)|FY3/2026 results (tanshin): what the 'other' category contains;直接证据 / 支持证据 / 历史/同业比较(研究域08) / 定向深挖(研究域08)|Medium-term plan 2024-2028: the business portfolio framing;直接证据 / 支持证据 / 反证(研究域03)|FY3/2026 results (tanshin): the 'other' businesses inside the group;直接证据 / 外部现实(研究域08) / 外部现实(研究域11) / 反证(研究域20) / 定向深挖(研究域09)|Medium-term plan 2024-2028: where the growth is supposed to come from;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域11) / 反证(研究域08) / 反证(研究域22)|Medium-term management plan 2024-2028: the FY2028 numerical targets;直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域11) / 反证(研究域31) / 反证(研究域33) / 反证(研究域35)|Plan progress read from FY3/2026 actuals against the FY2028 targets;直接证据 / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域24) / 反证(研究域01) / 反证(研究域13) / 反证(研究域23) / 反证(研究域29)|Securities report data for TYK (FY3/2026): the top-ten shareholder register;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 历史/同业比较(研究域01) / 定向深挖(研究域24)|Securities report data for TYK: register concentration and the absence of a controller;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Notice of 4 November 2026: the counterparty web around the Tohoku transaction;直接证据 / 历史/同业比较(研究域21) / 定向深挖(研究域21)|FY3/2026 results (tanshin): land and the physical footprint;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|IRBANK timely-disclosure index for TYK: 2026 governance and officer events;直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域13) / 历史/同业比较(研究域23) / 历史/同业比较(研究域33) / 反证(研究域26) / 定向深挖(研究域25)|IRBANK timely-disclosure index for TYK: buyback history - 2019 programme, nothing since;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域19) / 外部现实(研究域25) / 历史/同业比较(研究域32)|FY3/2026 results (tanshin): statement of changes in equity - dividends inside retained earnings;直接证据|FY3/2026 results (tanshin): per-share data and share counts;直接证据 / 支持证据 / 外部现实(研究域27) / 外部现实(研究域31) / 定向深挖(研究域31) / 定向深挖(研究域34)|IRBANK stock page for 5363: the FY3/26 trading range and the November 2026 print;直接证据 / 支持证据 / 外部现实(研究域34)|IRBANK stock page for 5363: daily print of 6 November 2026 and volume texture;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域08) / 一手证据(研究域09) / 一手证据(研究域10)|FY3/2026 results (tanshin): business definition and segment architecture;直接证据 / 一手证据(研究域19) / 反证(研究域06) / 反证(研究域17) / 反证(研究域32) / 定向深挖(研究域19)|Q1 FY3/2027 results (tanshin): working capital and balance-sheet movements;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域14) / 定向深挖(研究域05) / 定向深挖(研究域11) / 定向深挖(研究域14)|FY3/2026 and Q1 FY3/2027 results: the crude-steel demand backdrop in the company's own numbers;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 外部现实(研究域03) / 定向深挖(研究域04) / 定向深挖(研究域10)|Securities report data for TYK: intellectual property as the technology record;直接证据 / 一手证据(研究域17) / 一手证据(研究域20) / 定向深挖(研究域06) / 定向深挖(研究域17)|Q1 FY3/2027 results (tanshin): depreciation trend as the capex tell
完整研究记录(核对用)
研究原文:Research Debt carried forward|Ten open questions and a Coverage disclosure-boundary cluster remain. Near-term items resolve at the 12 Nov 2026 H1 print and the May 2027 results; others (land value, new-materials economics, succession, composition) have no current public path.
内部研究类型:research_debt_register
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):They bound confidence in the moat, normalised earnings and growth judgements, and condition how much weight the thesis puts on any single print.
不确定性(原始记录):Each item carries its own resolving evidence in its node.
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | a3fd8dfeb664a7b1432d3b3d16d9e6148687085d |
| Delivery Commit SHA | a3fd8dfeb664a7b1432d3b3d16d9e6148687085d |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | a4b211bc-406e-54b9-a57c-0087e93b865d |
| Canonical Revision | 1 |