基本盘稳:权益比率54.1%,近五年营业现金流全部为正,有息负债从2023年6月期的103.27亿日元降到67.68亿日元,净现金按JINGI口径转正(+6.19亿日元),全程没有增资。分红设有净资产股息率不低于2.5%的下限,2027年6月期预测分红22日元。股价603日元,市净率0.91倍,预测市盈率8.19倍。
5698
株式会社エンビプロ・ホールディングス(ENVIPRO HOLDINGS Inc.)
株式会社エンビプロ・ホールディングス(ENVIPRO HOLDINGS Inc.,东证Standard市场,代码5698)是总部在静冈县富士宫市的纯控股公司,主营废金属和产业废弃物的破碎、分选回收,产出铁屑、有色金属、塑料和橡胶;同时经营锂离子电池回收、金属与物流贸易,以及环境咨询和残障福利服务。
最近亮点:2026年6月期经常利润35.82亿日元,同比增长194.6%,销售额却下降9.5%,处理量下降19.6%至49.1万吨。管理层自己的拆解把23.66亿日元增幅中的23.35亿日元归于购销价差。2027年6月期指引经常利润31亿日元(下降13.5%),电池回收因承包商火灾只给0.5亿日元。2027年6月期一季度(7–9月)财报(业绩快报)按往年惯例预计在2026年11月13日前后发布,研究截止时尚未公布。
利润主要来自金属购销价差。价差回落时,经常利润可能回到2023至2025年6月期12.16亿至19.02亿日元的低谷区间,而高价位累积的库存和应收款会在回调时释放现金,同时压缩利润率。平价年份的底部盈利有没有抬高,要等2027年6月期实绩;电池回收何时恢复,公司没有给出日期。
Kabugami评分59.51/100,评级B(评分版本V3.2)。暂不追高,列入重点观察,等一季度财报和11月月线收盘再决定是否建小仓位。这个判断以平价年份底部盈利抬高为前提,而该前提要靠未公布的2027年6月期实绩验证,电池恢复时间、保险最终赔付和价差正常水平也都无法确认,把握一般。技术上旧的下跌已经结束,新状态尚未成立,月线正在底部上沿604至654日元价格带接受测试。 估值简报:股价603日元(2026年11月6日收盘)/总市值182.81亿日元(按发行股数,未扣库存股)/预测PER 8.19倍(按公司预测EPS 73.67日元)/实绩PBR 0.91倍。ROE 13.6%(2026年6月期实绩,公司预测2027年6月期为11.1%)/预测股息率3.65%(年分红22日元)。EV/EBITDA 3.8倍(EV 173.4亿日元=总市值减净现金9.4亿日元〔2026年6月30日〕;EBITDA 46.2亿日元=2026年6月期营业利润32.24亿日元加折旧13.97亿日元)。 当前动作:暂不追高,列入重点观察。先等2027年6月期第一季度决算(预计2026年11月13日前后)和11月月线收盘,再决定是否建立小仓位。基本面验证的重点是资源板块在平价下能否接近约29亿日元的计划、电池板块的恢复安排;价格验证的重点是月线能否收回654日元以上并守住604日元。流通盘偏小,仓位要考虑退出的难度。
报告目录
01|投资问题与当前结论
01.1|要回答的问题:平价年份的底部盈利有没有抬高
Kabugami评分59.51/100,评级B,暂不追高。这家公司的基本面站得住,但周期性盈利还没有被证明抬高了底部,所以先观察。
过去五年经常利润依次是41.67亿、19.02亿、17.83亿、12.16亿和35.82亿日元,平均25.3亿日元,中位数19.0亿日元。2023至2025年6月期的12亿至19亿日元,是价差不帮忙时的低谷区间。2027年6月期31亿日元的指引高于这三个低谷年的任何一年,等于管理层在暗示底部已经抬高。
这个暗示对不对,是整个研究的核心问题。如果深度分选、炉渣回收和业务结构调整真把底部抬向25亿日元,2027年6月期指引在没有价格帮助的情况下可以达到甚至超出,折价才有收窄的理由。如果2027年6月期只做到指引、价差也只是持平,2026年6月期的利润就是价格行情,公司仍是一家价格合理的周期股。结论取决于尚未公布的实绩,把握一般。
验证标准也很具体:资源板块在平价下接近约29亿日元的计划,电池板块恢复有安排。拖累延伸到2028年6月期而没有产能决策,同样会推翻这个判断。
01.2|2026年6月期利润猛增来自价差,出货量其实在下降
2026年6月期经常利润35.82亿日元,增长194.6%;营业利润32.24亿日元,增长231.6%。同期销售额下降9.5%至444.30亿日元,处理量下降19.6%至49.1万吨。利润在业务量收缩的基础上翻了几倍。
管理层在业绩说明会上的增减拆解很直接:经常利润从12.16亿日元增至35.82亿日元,价差一项贡献了23.35亿日元,占23.66亿日元增幅的绝大部分;权益法收益多了1.23亿日元;人工费上涨被消化。毛利率从17.2%升到22.5%,销管费减少7.05亿日元,边际贡献增长24.2%,EBITDA增长97.2%至46.24亿日元。
这样看,这一年主要是价差抬高了每吨的赚头,而不是业务量扩张。更要紧的后果是,价差能给股东加利润,回落时也会同样拿走。销管费减少的7.05亿日元里,有多少是一次性、有多少是改革成果,公司没有拆开;价格与结构改革各自贡献多少,也无法从外部分开。
01.3|2027年6月期指引按平价、带着电池拖累来定
2027年6月期指引:销售额490亿日元(增长10.3%),营业利润27亿日元(下降16.3%),经常利润31亿日元(下降13.5%),净利润21亿日元(下降13.4%),每股收益73.67日元,处理量目标55万吨。
利润下降有两个原因。一是电池回收板块受承包商火灾影响,利润计划从7.04亿日元降到0.5亿日元;二是指引假设价格持平,净价差贡献只算增加2.06亿日元,对应的成本增加5.64亿日元(人工3.40亿,设备2.24亿)。2026年6月期里,公司做过两次上调(2026年2月12日和7月30日),最终业绩高于最后一次指引。以此对照撤回中期计划之前每份计划首年都要下调的做法,这份指引看上去是按底线来定的。
要留意保守的位置:电池板块是公司自己控制不了的部分,保守恰恰集中在那里。一年改善的修订记录也不能当成体制变化。管理层把2027年6月期说成打基础的一年,并强调计划是要兑现的承诺,不是上限。
02|公司本质与商业模式
02.1|真正耐久的是分选能力,周围的利润和产能都带周期性
Envipro耐久的部分是分选能力这套组合:1950年以富士宫的废铁商店起家建立的收货网络,1997年管理层押下的大型破碎线,许可资质,以及与市政打了十多年的交道。公司在日本最早出口废铁,2010年成立控股公司,2013年上市东证二部,2018年升入一部,2025年9月18日从Prime转到Standard市场。
这套能力装在已大幅折旧的设备里:机械设备账面原值171.71亿日元,累计折旧138.59亿日元,已折掉81%;土地按38.41亿日元的历史成本入账。围绕这个核心的东西都带周期或过渡色彩:金属价差,火灾后的电池产能,贸易账面因净额确认而失真的规模,以及一年前才立下的管理原则。
耐久性可以归结为一个问题:改革后的公司,在价格持平的年份能不能比2023至2025年6月期(经常利润12亿至19亿日元)赚得更多。净现金、54.1%的权益比率和连续五年为正的营业现金流,让公司有足够的时间等答案。分红下限在等待期间给股东付钱。
集团由11家合并子公司构成。资源回收是Econecol(2025年7月1日吸收合并了Genau),贸易是NEWSCON、Cytellus和Astco,咨询是Bright Innovation,电池回收是VOLTA。
单独上市的橡胶制造商日东化工(Nitto Kako,东证Standard 5104)也在合并范围内,另有两家权益法关联公司。护城河的证据全部来自公司自述,没有第三方的回收率或收货份额数据,要等2027年6月期平价年份的实绩来检验。
02.2|同样的吨位,赚的是买进废料与卖出再生材料之间的价差
这门生意的收入引擎是价差期权:同样的吨位,利润取决于废料买价与回收材料卖价之间的差。利润对金属价格的弹性,远大于对业务量的弹性。2026年6月期(处理量下降、利润增长数倍)和2024年6月期(价格偏软,每股收益仅17.9日元)是这个期权的两端。
传导链是这样的:金属价格推动价差,价差而不是业务量决定资源板块的利润,资产基本不变,利润弹性就被放大。高价位把利润的一部分压在库存和应收款里,价格回头时利润率被压缩,现金同时释放。股东面对的是围绕一个未被证明的中间水平上下摆动的盈利,而不是稳定的增长曲线。至于价差在铁、有色、橡胶和炉渣之间怎么分,公司没有披露。
02.3|资源回收是利润发动机,资产只多了8.6%
2026年6月期分部利润按经常利润口径计算。资源回收26.27亿日元(上年11.59亿日元),电池回收7.04亿日元(上年2.24亿日元)。全球贸易7.03亿日元(上年2.70亿日元),其他业务0.40亿日元(上年亏损0.17亿日元)。集团调整为负4.94亿日元,合计合并经常利润35.82亿日元。
资源板块的期末分部资产从212.37亿日元增至230.62亿日元,只增长8.6%,而利润翻了一倍多。按期末分部资产粗算,资源板块的利润率从约5.5%升到约11.4%,这是资产回报的提高,不是产能的扩张。同一板块还装着全部5.14亿日元权益法收益(来自Abizu和Fuji Ecocycle两家关联公司),所以这个利润是工厂经济和关联公司收益的混合。
板块内部,橡胶是最大的外部收入线,为60.62亿日元,其次是有色金属54.14亿日元和铁27.95亿日元。贸易板块则以铁为主,达143.86亿日元。看起来显眼的大宗铁并不是利润核心,经过加工的橡胶和有色流才是。产品线以下的利润没有披露。
02.4|咨询和福利业务在缩小,处置方式是资本配置的试金石
其他板块(环境咨询和残障福利服务)销售额降到4.50亿日元,利润0.40亿日元。上年亏损,原因是咨询订单减少和福利使用者减少。它们处在En-Vision2035所强调的分选技术之外,保留它更像出于社会使命,而不是经济理由。金额小,但看新社长怎样处理它,是观察资本配置纪律的清楚窗口。公司没有表态这个板块的战略地位。
03|产品、客户与供应链
03.1|被定为2030年后增长担当的电池回收,眼下被承包商火灾卡住
电池回收板块2027年6月期的利润被压得很低,原因是2026年6月的一场火灾。负责锂离子电池预处理的外部承包商着火,库存被烧毁,公司计入约1.30亿日元的灾害损失(合计1.31亿日元),产能受限延续到2027年6月期。板块利润指引从7.04亿日元降到0.5亿日元,约6.5亿日元的差额直接落在合并指引上。
指引里的保险赔付只是估计值,产能限制没有承诺结束日期。公司在与承包商谈判,并寻找新的预处理伙伴。承包商的身份、重启条件、最终赔付和备用伙伴的数量都没有披露。这家承包商是公司把预处理放在单一外部路径上的结果,管理层把它当作运营设计缺陷来整改。
当前的瓶颈在预处理产能,不是原料需求。2026年6月期这个板块的固定资产新增只有0.20亿日元,说明它的产能有一部分在集团之外,对承包商的依赖是实打实的。2027年6月期的行动包括提高现有工厂的生产率和黑粉回收率,推进新工厂,扩大与集团内外伙伴的收集网络。
03.2|火灾使新电池工厂成为战略的关键路径
被指定为2030年后增长担当的板块,现在偏偏无法生产,这就让一个资本决策排到了战略前面:新电池工厂的容量、投资额、时点和资金安排,比炉渣的合同增长更早决定增长故事能否兑现。好在公司有净现金和自筹资金能力,问题从偿债转向配置纪律。新工厂的投资规模、产能和日程都没有披露,这是目前最大的缺口。
03.3|炉渣回收是资本最轻的增长腿,但看不到它的单独利润
贵金属炉渣回收从城市垃圾焚烧灰和破碎残渣中回收金、银、铜、铂和钯。原料是别人的废物流,靠合同扩大收货,而不是靠买入商品,所以对营运资金的占用比贸易账面轻。2026年3月环境省修订了设施采购指南,这是自2013年11月以来的第一次,把飞灰资源回收写进官方采购规格手册,公司称这是它与市政培育十多年的领域被正式写入标准。
管理层提出两条杠杆:通过工艺改造提高每吨回收品位,以及随着更多市政把灰处理外包而扩大收货。市政老化的焚烧设施无法全部自建,给了民间运营商接手部分一般废弃物功能的空间。
但这条腿没有单独的收入或利润披露,合同层面的量、时间和经济性都不清楚,市政接受的速度也不知道。它可能是抬高底部最干净的路径,目前却无法从外部核实。
03.4|聚合物循环是十年期的选项,投入先于收益
聚合物循环业务有三条线:2025年6月期投产的RPF燃料工厂;日东化工橡胶垫业务,计划在2027年6月期下半年扩产,彩色橡胶碎片已在上半年推出;以及与荏原环境成套设备(Ebara Environmental Plant)的化学回收示范,Envipro负责原料采购管理。En-Vision2035把社会实装放在十年窗口里,没有任何分部损益单独反映它,示范阶段的经济性也未披露。把它当成长期选项,而不是预测里的项目,资本支出会先发生。
需求侧只有零星信息:钢厂对废铁的实物需求依然坚挺,汽车和零部件厂对物流代理的需求稳定,但客户名单和集中度没有披露。
04|竞争格局与产业关系
04.1|利润和风险主要经由金属价格、一家承包商和关联公司收益传导
公司的产业关系可以按经济传导方向排列。
金属价格:国内废钢价和全球金属价格决定价差。2026年6月期铁屑均价每吨45,616日元,上涨6.8%;铜、金、银创历史新高。这一项在2026年6月期贡献23.35亿日元,在2023至2025年6月期则是拖累。目前价格是处在周期顶部还是平台,没有人知道。
日东化工(东证Standard 5104):合并的上市橡胶子公司,位于资源板块内,提供板块最大的外部收入线(橡胶),同时是一块在母公司账上有自己市价的上市股份。少数股东权益占比和子公司利润贡献没有单独披露。
Abizu和Fuji Ecocycle:两家权益法关联公司,全部在资源板块,权益法收益从3.90亿日元升到5.14亿日元,占经常利润14%。财务报表不并表,对母公司的分红政策也未知。
创业家族的资产公司Windelight持股38.03%,是约47.5%家族持股的锚;环境省指南修订、电池预处理承包商、东证Standard市场、AI分选合作伙伴伊亚斯科技(Earth Technica)和荏原环境成套设备,分别在后文对应的章节讲解。
04.2|竞争对手和同业倍数没有可核实的对比
研究没有做具名同业的回收率或收货份额对比,也没有找到分析师预期和同业估值倍数。所以公司在竞争中的位置,目前只能依据公司披露和价差表现来判断,无法借第三方基准校准。对方的财务大多未披露,这是对本章判断的主要限制。
05|护城河判断
05.1|优势有,但耐久性要等平价年份的数据证明
护城河来自隐性经验和关系:自行设计的分选工艺(磁选、风选、比重选、涡电流和传感器分选)、1997年起积累的破碎线、收货网络和许可。它没有专利或合同壁垒,侵蚀会先表现为平价年份价差被压缩。
分选技术是唯一可信的底部抬升因素:回收得越深,每吨价值越高,在任何价格水平上都成立。与伊亚斯科技约四年的AI分选联合开发,把多传感器光学、AI图像和3D分析、机器人结合起来,目标是减少对熟练工人的依赖,应对分选人才短缺。它现在不产生利润,是对未来十年分选优势的投入。公司还强调通过工艺改造提高回收的贵金属品位,而不是多买原料。
反证也摆在这里:2026年6月期利润增幅的大部分来自价差,处理量下降了19.6%,其中一部分是主动放弃低价值大宗物料。公司没有单独披露研发费用,也没有第三方的回收率对比。结论只能是有一定优势,耐久性尚待验证。
05.2|单点依赖是护城河的反面证据
一家承包商的火灾拿走了电池板块一年的产能。生产分选优势的设备已折旧81%,更新开支会持续增加。母公司本部只有61人,却要管理11家子公司。控制权集中在一个家族手里。管理层把火灾定性为运营设计缺陷,认为这种单点失效是其他集中风险的样板:每一项都在管理,没有一项被消除。
后果是,新的单点失效会再拿走一年的某个板块,而新资产基础会在新产能赚钱之前摊薄资本回报。子公司的管理深度和备用伙伴数量都没有披露。
06|财务质量与现金流
06.1|利润质量比上一年好,但有三处读数偏差
2026年6月期的利润质量比上一年高。税前利润33.66亿日元,是在特别项目净额为负的情况下取得的:灾害损失1.31亿日元,减损0.94亿日元,固定资产处置0.36亿日元,合计损失2.60亿日元,对比收益0.45亿日元。2025年6月期的税前利润15.16亿日元里,包含6.00亿日元的保险和补助收益(保险3.72亿,补助2.04亿)。
偏差有三处。第一,权益法收益5.14亿日元占经常利润14.3%,经常利润线里有一部分是关联公司收益。第二,外汇损失连续两年(1.33亿、1.39亿日元),公司没有披露对冲。第三,销售额和利润率都有扭曲,见下一节。扣除被抬高的上年基数后,真实改善很大,但小于表面倍数。关联公司的财务未并表,但没有迹象显示存在错报。
还有一个与资本回报相关的读数:ROE 13.6%,ROIC按JINGI口径在10.1%到12.1%之间,只略高于公司自己估计的约10%股本成本。五年ROE依次为21.6%、7.7%、3.2%、7.0%和13.6%,说明公司平均而言只是赚回资本成本,超出的部分集中在价差冲高的年份。
06.2|销售额会误导,应该看每吨价差
报告销售额低估了活动量,原因有两层。一是2026年6月期部分贸易账面由总额确认改为净额(价差)确认,机械地压低了销售额,业务本身没有缩小;净额化涉及的收入规模,公司没有量化。二是合并销售额三年连降,从573.19亿日元降到444.30亿日元,同时利润集中到加工产品线上。
后果是,7.3%的营业利润率(上年2.0%)看起来比真实改善更漂亮,2027年6月期销售额增长10.3%的指引也不宜与历史简单比较。更诚实的分母是处理量和每吨价差;不过处理量本身也含有放弃低价值大宗物料的结构效应。以销售额为基础的倍数,都需要这样修正。
06.3|现金流五年为正,但利润的一部分压在库存和应收款里
营业现金流五年全部为正:38.73亿、23.32亿、29.40亿、34.70亿和30.72亿日元,包括净利润只有5.37亿日元的2024年6月期。累计约157亿日元,与当前总市值相近。2026年6月期资本开支9.47亿日元,自由现金流大致21亿日元。
利润猛增的同一年,库存增加14.16亿日元(资产负债表上增加12.82亿日元至45.32亿日元),应收款增加12.14亿日元(资产负债表增加12.51亿日元至48.48亿日元),合计占用约26亿日元,其中13.67亿日元由应付款增加来垫付。这些都是高价位下形成的。价格回调时,这条传送带倒着转:现金释放,同时利润率被压缩,所以利润与现金流会在转折点朝相反方向走,两者都是真的。库存按品种的价格敏感度没有披露,现金释放的速度也未知。
06.4|资产负债表保守,下行风险在盈利而不在偿债
2026年6月30日总资产347.12亿日元,权益比率54.1%,每股净资产659.26日元。有息负债从2023年6月期的103.27亿日元降到67.68亿日元,现金及存款74.98亿日元,长期借款减少5.81亿日元至30.68亿日元。净现金按JINGI口径为+6.19亿日元,五年窗口内第一次转正,没有靠增资。最大的非有息负债是11.35亿日元的退职金负债,另有资产除去义务2.06亿日元。
净现金的口径在不同来源之间不同:计算EV时用的是9.4亿日元,JINGI口径是6.19亿日元。设备更新和新电池工厂会占用现金,这是内部消化的问题,不是生存问题。真正没有保护的是利润:价差逆转时,资产负债表帮不了股东。
07|股东、董事与治理
07.1|家族握有约47.5%股份,少数股东承担折价
创业家族的Windelight(38.03%)、Sano Maruka(7.02%)、社长佐野文胜(2.42%)和其他家族成员合计持有约47.5%(不含库存股),自由流通约42%。日本主托管银行信托账户持股4.56%,信托账户背后的实际持有人看不到。公司2025年9月18日由Prime转入Standard市场,没有披露回到Prime的路径。
这些结构说明,价格靠财报证据一点点累积来修正,而不是靠套利。控制权永远在家族,不会有收购或退出压力,但少数股东要接受治理折价和流动性限制,建仓和退出都要考虑盘子大小。2026年7月17日的融资余额显示买方526,200股、卖方只有100股,相当于不含库存股的1.8%,价格的涨跌都会因这类单边杠杆而被放大。
07.2|撤回中期计划后,每一份单年计划就是承诺
公司在2025年8月20日撤回了滚动中期计划,原因是最近三份计划的首年预测都要下调。10%(中期)和15%(长期)的ROE目标不再是固定目标,现在的原则是:十年期定性愿景En-Vision2035(到2036年6月期)、每年发布并兑现的单年利润计划、以及让资本回报持续高于约10%的股本成本。这个成本是管理层自己的估计。
没有多年目标可躲,每年的计划就是承诺,指引的保守构造本身就是一个治理信号。2026年6月期是新体制下的第一年:两次上调,业绩高于最后一次指引。但一年的改善不能当成体制变化。2027年6月期预测ROE 11.1%,比10%只高出约一个点,是新原则下第一个真正紧张的年份。公司是否会为En-Vision2035公布阶段性指标,不得而知。
07.3|内部人信号很弱,社长交接的细节不清楚
2026年10月28日,公司把50,203股库存股以每股741日元(合计0.372亿日元)作为限制性股票,授予46名董事和员工。741日元高于2026年6月期末每股净资产659日元,也高于11月6日的收盘价603日元。它显示内部人愿意承担多年的股权敞口,对管理层把指引当底线的说法有一点印证,但授予价可能按更早时点的参考价设定,也不是自有资金买入,信息量低。
领导层方面,佐野文胜接任社长,创业一代的佐野富胜在2026年8月的说明会记录中是会长。交接的确切时点和董事会变化没有在所用材料中确认。子公司管理深度未披露,新社长在日东化工、外围业务和库存股上的取舍,是目前看得到的自由度。
08|资本政策
08.1|分红下限让收入更稳,回购节奏则随意
回报政策以净资产股息率(DOE)不低于2.5%为下限。2026年6月期分红25日元(派息率29.4%,管理层口径DOE 3.8%,决算短信口径4.0%),2027年6月期预测22日元(派息率29.9%,DOE 3.1%)。过去五年分红是25、14、6、15、25日元,政策就是为了避免2024年6月期那样的6日元低谷再现。2027年6月期名义分红下调,是跟着预测利润走,不是框架改变。
回购补充了回报:2025年6月期7.89亿日元,2026年6月期1.73亿日元(说明会口径1.72亿日元)。2026年6月期分红7.12亿日元,加回购合计回报8.85亿日元,约占净利润的37%,这是在净现金转正的同时完成的,没有借钱。
这套组合是新原则的资本回报宪法:DOE下限稳定收入,机会性回购约束净现金的使用。风险在于家族控制的净现金公司可能回报偏少,而不是被稀释。回购会不会重新加速到2025年6月期水平,没有明确目标,杠杆和现金水平也没有设定目标。
08.2|每股收益里有一部分来自股数减少
发行股数保持30,317,388股,库存股增至1,811,673股,约占发行股数的6.0%(上年1,661,184股)。平均股数从29,997,980股降到28,462,432股,上年回购在本年度被年化,机械上给每股收益带来约5%的助力。所以2026年6月期每股收益增长里,有一部分来自股数减少,不是盈利。
稀释同样可见:股票期权相关的潜在股份1,139,681股,是基本每股收益85.16日元与稀释后81.88日元之间的差距。期权行权价和日程没有披露。授予限制性股票的库存股也部分抵消回购的每股效果。稀释受期权池上限的约束。
08.3|新电池工厂和外围业务考验配置纪律
净现金转正、股价低于账面、库存股占6%,使资金配置成为下一步看点:新电池工厂要花多少钱、什么时候开工、怎么融资,目前都没有披露;日东化工、缩小中的咨询和福利业务、库存股怎样处理,是新社长在文件中留下的三个可见的自由度。这些决定将决定净现金和低于账面的股价会不会被转化为每股价值。
09|估值与安全边际
09.1|股价是在为低谷盈利定价
2026年11月6日收盘价603日元,总市值182.81亿日元(603日元乘以30,317,388股发行股数,没有扣除库存股)。预测市盈率8.19倍(按公司预测每股收益73.67日元),实绩市净率0.91倍(2026年6月期末每股净资产659.26日元)。
2026年6月期ROE 13.6%,预测股息率3.65%(年分红22日元)。EV/EBITDA 3.8倍:EV为173.4亿日元(扣除2026年6月30日净现金9.4亿日元),EBITDA 46.2亿日元(营业利润32.24亿日元加折旧13.97亿日元)。
以2026年6月期的高点盈利来看,这家公司明显便宜;以低谷盈利来看,大致合理。市盈率在周期里的变化可以说明:按2025年6月期低谷盈利算大致15倍,按2026年6月期约7倍。折价的来源前文已讲:家族控股、约42%的自由流通、转入Standard市场后的机构关注减少,以及盈利的周期性。
各项倍数的口径不同:总市值用发行股数,净现金有两种口径(9.4亿日元与+6.19亿日元),市盈率基于公司预测。没有同业倍数和分析师预期可比。
09.2|估值的分歧归结为底部盈利是15亿还是25亿日元
估值争论可以压缩成一个数字:平价年份的经常利润。五年平均25.3亿日元、中位数19.0亿日元,但2022年6月期的价差高峰把平均数拉高了,窗口选择会改变结论。底部在12亿至19亿日元之间时,当前价格是对周期股的充分定价;如果结构改革把底部抬到25亿日元,现在的价格就有较好的安全边际。
2027年6月期指引31亿日元高于所有软价年份,是管理层关于底部已抬高的隐含主张。判断它是否成立,要看资源板块在价格不再帮忙时的回报是否留在2026年6月期附近(计划约29亿日元)。正常年份的价格假设未知,JINGI给出了两种ROIC口径。
重估需要的是底部被证实,而不是高点被重复。
09.3|隐含资产是选择权,不是估值支柱
土地按历史成本38.41亿日元、投资证券40.73亿日元(含上市子公司日东化工的股份)、库存股按成本8.71亿日元入账,机械设备已折旧到原值的约19%。这些都没有按市价重估,0.91倍市净率已经含有保守的账面基础,但没有重估证据能估出差距。日东化工在母公司的账上有自己的市价,合并报表没有回答部分上市折价的问题;少数股东权益和子公司股份不要重复计价。资产只在资本政策把价值释放出来时才有意义。
10|Kabugami 技术结构
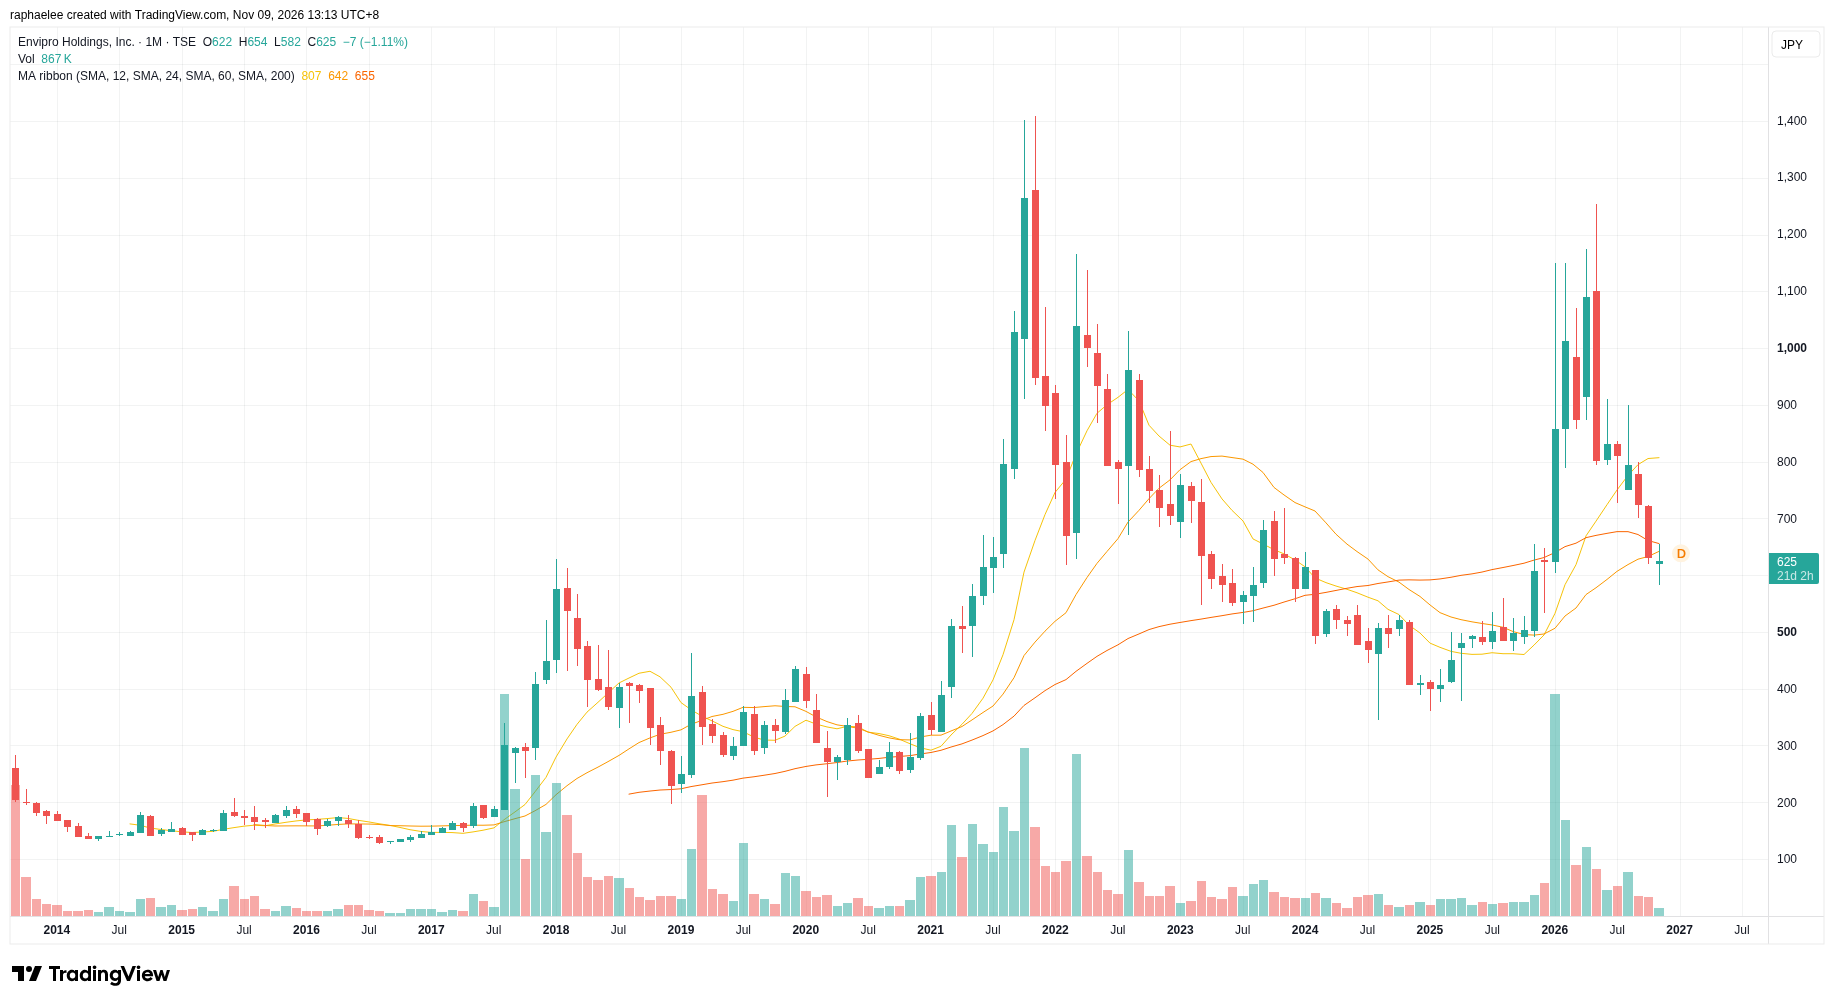
10.1|技术问题:2026年的放量冲高是新阶段的起点,还是旧区间里的一次脉冲
价格结构给出的结论是:旧的下跌已经结束,新状态尚未成立,现在处在测试这个状态的回抽阶段。这一章只用价格与成交量,不借用业绩或公司消息来解释。
观察日期2026年11月9日。数据是2013年9月上市到2026年10月的158根月线(Yahoo Finance,复权后的连续序列,数据到2026年10月27日,末尾有缺口),加上2026年11月6日日线收盘603日元。这里没有提供Owner月线图,下文只依据价格数据。
技术上的问题是:公司在2024至2025年完成了一轮长达三年的下跌,2025年出现第一个更高的年度低点,2026年1月出现上市以来最大的成交量,5月涨到1,253日元,随后连续五个月收盘走低,11月6日日线收603日元。这是紧随衰竭之后的增长阶段,只是第一次保留测试失败;还是旧分布里的一次脉冲,正在回到它从未真正离开的密集区?
10.2|上市13年的价格路径:两次失败的冲高,三年阴跌,2025年才抬高低点
2013年9月上市时,股价在240至560日元区间,2016年8月衰减到上市以来的最低点126日元。2017年12月冲到521日元,2018年到628日元,随后退回210至500日元的平台,第一次冲高失败。2021年11月,金属超级周期把股价推到上市以来的最高点1,409日元。
此后的下跌分成三段:年度低点依次是2022年的618日元、2023年的514日元和2024年8月的345日元,每一段仍在创新低,说明衰竭没有完成。2025年出现全结构里第一个更高的年度低点361日元,全年形成361至654日元的底部区间,年末收于624日元。
再往前的路径是:2026年1月在底部区间上以29.38万手以上的纪录成交量放量启动(29.38百万股),高点1,150日元,收858日元;2月收于1,012日元;5月盘中冲到1,253日元,收盘803日元,留下一根高位长上影线;6月至10月连续五个月收盘走低,依次为831、812、793、726和637日元。
10.3|2026年的冲高没有守住:5月高点1,253日元,收盘只有803日元
1月的放量启动是这只股票从未出现过的量级:29.38百万股,此后春季17至20百万股,到10月缩到5.84百万股。2月收盘1,012日元,是这一轮的最高月线收盘,此后没有再有月线收盘站上1,012日元。5月冲到1,253日元却收在803日元,是买盘在高位的极限。
这一轮的记忆很清楚。2017至2018年同样的脉冲在相近位置失败并退回平台,所以现在这次的举证责任在于守住涨幅,而不是点燃行情。与2017年不同的地方是,这一次成交量大得多,下面的底部也完整得多。在月线收盘超过1,253日元之前,这根5月K线就是公认的压力。
10月月线区间625至723日元,已经远窄于1月的604至1,150日元,缩量回落的方式正是回到旧价格带时的常见样子。
10.4|价格重心回到24个月均线,周围没有中间台阶
10月收盘637日元,几乎正好在24个月均线633日元上;60个月均线661日元已从上方被跌破;12个月均线806日元在价格上方27%处,是脉冲留下的头顶记忆。价格处在上市以来区间(126至1,409日元)高度的约39.8%,位置偏下。
下方的支撑依次是:604至654日元的底部上沿价格带(1月启动低点604日元、2025年高点654日元、2025年12月收盘624日元),然后是2025年9月低点466日元,再往下是345至361日元的底部地板;底部区间内部的466至533日元是更深的支撑区。上方压力依次是:10月高点723日元、12个月均线806日元、6月高点911日元和2月收盘1,012日元、1,150至1,253日元的脉冲区,再往上只剩2021年的1,409日元。
上市13年里收盘大多在126至654日元之间,站上654日元以上的时间很少,集中在2021至2022年那一段和2026年上半年。这意味着现在的回抽是回到价格最常停留的位置。从654日元到1,150日元之间没有此前上涨留下的中间台阶,所以真正的结构性事件是底部上沿的测试,不是半空中的某个价位。
10.5|下跌动能已经耗尽,上行的恢复力只证明过一次脉冲
下跌方这边可以证明:2022、2023、2024年的每一段下跌跌幅一段比一段小,年度低点序列以更高的361日元收尾,这是供给耗尽的几何特征。
上行方只证明了脉冲:1月的放量和2月1,012日元的收盘说明有大资金愿意在这个位置买,但连续五个月收盘走低,说明买盘还没有组织成真正的增长阶段该有的阶梯式台阶。
从旧高点1,409日元算起的恢复也很慢:五年里最高月线收盘是1,012日元(2026年2月),为高点的72%,现在回吐到637日元,只剩45%。1,409日元更像是上市以来的最终压力,不是可投资期限内的目标。
2026年的冲高是迁出2025年底部区间的质量最高的一次:纪录成交量、两个月涨幅90%、收盘价到了2022年以来未见的位置。但它只有一个脉冲的深度,保留已经没有通过第一次测试。按照这只股票2017年和2021年的先例,真正的迁移与脉冲只有一个区别,就是回抽到底部上沿时发生了什么,这份证据还在写。
10.6|现在的状态:改变已尝试,裁决落在604至654日元价格带
纯价格上的当前状态是:一轮完整的长期下跌,一次纪录成交量的启动,第一次保留测试失败,回抽正在测试底部上沿。这个回抽被吸收的位置,恰好是真正的状态改变会被吸收的位置,但吸收还没有被证明,11月6日日线收603日元,说明测试在观察日仍在进行。
三个参照位定下检验标准:654日元(2025年底部上沿)看状态是否保留,604日元(2026年1月启动低点)看脉冲是否完整,1,253日元(5月高点)看能否延续。10月收盘637日元刚好在第一个之下、第二个之上、第三个之远下;11月6日日线603日元已在盘中压到第二个参照位。11月月线收盘低于604日元,将是回抽变成重新进入底部区间的第一份硬证据。
内部矛盾是位置与证明:价格是603至637日元,说明2026年的行情失败了;但证明新状态成立或失败的证据,要等这个月的月线收盘才完整。
往上确认需要看到: 11月至12月月线收盘收回654日元之上,回抽变成已完成的测试; 月线收盘站上12个月均线(806日元左右),重新进入脉冲的成交区; 月线收盘超过1,253日元,推翻失败脉冲的记忆; 2027年的年度低点高于466日元,延续345、361、466这条逐步抬高的低点序列。
什么会推翻现在的判断: 月线收盘低于604日元,说明是重新进入底部区间; 月线放量跌破466日元(2025年9月低点),重新打开底部内部; 回测345至361日元的底部地板,整个2026年的行情就被归入旧分布里的脉冲。
10.7|价格与业绩公布的先后:价格在两个方向上都先于账面
以上价格状态独立形成之后,再对照公开业绩,价格是一个领先指标。1月的放量启动,早于2026年6月期利润在8月公布两个报告期;5月至10月的下跌,则发生在市场消化下调指引和火灾的过程中。
2026年6月期历史最佳的业绩(8月13日公布,经常利润增长194.6%)公布之后,价格没有上涨,8月收793日元,9月收726日元,10月收637日元,因为同一份公告把2027年6月期的利润下调,并披露了电池火灾的拖累。7月30日上调预测的通知发出时,6月和7月的月线收盘(831日元、812日元)已在回落。
对照点已经出现:2027年6月期一季度财报预计在2026年11月13日前后发布,这一周价格正在测试604至654日元的价格带,所以基本面和价格结构的两份裁决会在几周内一起到来。好的财报不能改写价格状态,也不会因此把技术判断调高。
这个先后关系只依据少数几个有日期的事件,没有独立证据说明市场提前知道了未披露的信息。
11|风险与催化剂
11.1|价差回落时,利润下降和现金释放会同时发生
最主要的基本面风险是价差回落。2026年6月期给公司加上23.35亿日元的机制,在2023至2025年6月期因价格正常化而拿走了利润,经常利润依次是19.02亿、17.83亿和12.16亿日元。
2026年6月期的利润还伴随着高价位下的库存(增加14.16亿日元)和应收款(增加12.14亿日元)累积,由应付款增加13.67亿日元来垫付。价格回调时,现金流和利润会朝相反方向走:现金释放,利润率收窄。仓位应该预期到盈利与现金的背离。库存的品种构成及价格敏感度没有披露,现金释放速度未知;价格目前是周期顶部还是平台,也没有结论。
11.2|电池恢复延期和物流、汇率是次一级的风险
电池板块是2027年6月期指引里最大的单项变数。恢复变慢,或保险赔付比估计少,会直接拉低合并预测,影响约6.5亿日元的板块利润,并延后2030年后增长担当的时间表。
次一级的是物流和汇率。霍尔木兹海峡的实际封闭,已经扰乱了2026年6月期物流代理业务中运往迪拜的货物。出口导向的贸易账面也暴露在航运和制裁冲击下,这些不会出现在价格序列里。外汇损失连续两年(1.33亿日元、1.39亿日元),公司的定价有一部分与美元挂钩,除此之外没有披露对冲安排。电池原料钴、镍、锂价格因供应受限而偏强。这些相对经常利润较小,但持续存在,处在价格这一主要暴露的下面。
11.3|催化剂按财报日期排好,其余靠事件
最近的一个是2027年6月期一季度(7–9月)财报,按公司2024年和2025年都在11月13日发布的惯例,预计在2026年11月13日前后,介于研究截止日和报告日之间,研究截止时尚未公布。它会显示保守的全年指引是否按进度走、火灾对电池板块销量造成了什么影响,以及资源价差有没有撑过秋季的价格平台。
之后可以预见的事件有:电池预处理恢复或新伙伴的披露,新电池工厂的决定,以及2027年2月的中期财报。财报节奏是日历固定的,恢复和工厂决定则要看事件。这个判断要在两个季度里分出高下,靠的是财报,不是故事。价格方面,同期的验证点是月线能否收回654日元、守住604日元。
11.4|什么会推翻这个判断
判断的核心是底部盈利抬高。以下几种情况会推翻它:2027年6月期实绩只做到指引或更低,而价差只是持平,说明2026年6月期的利润是价格,底部没变,公司仍是一家价格合理的周期股;资源板块利润显著低于约29亿日元的计划;电池拖累延伸到2028年6月期而没有产能决策。
反过来,指引在平价下被超出、资源板块利润接近29亿日元,才会加强这个判断。这一判断在未公布的实绩出来之前一直是有条件的。
12|反常识发现
12.1|撤回中期计划,反而抬高了考核标准
撤回多年目标常被当作降低要求,这里的效果相反。没有三到五年目标可以躲,每一份单年计划都成了承诺。2027年6月期的指引按平价设定,预测ROE 11.1%,只比约10%的股本成本高出一个点,是这套原则下第一个真正紧张的年份。过去的做法是首年就下调,现在按底线定,再加两次上调的记录,这个变化值得跟踪,但只有一年样本。
12.2|指引的保守程度,集中在公司控制不了的地方
2027年6月期指引的保守,有一部分来自电池板块被火灾压住,这是管理层无法决定的变量;净价差只给了增加2.06亿日元,则是管理层可以选择的保守。两种保守的含义不同:前者对应一年的不确定性,后者对应对底部的判断。把二者混在一起,就会高估这份指引是在「留余地」。
12.3|账面和价格在不同时间说出了不同的话
2026年6月期是历史最佳,价格却在公布后继续走低;价格的放量启动早在利润公布之前两个报告期就出现了。账面反映的是已经发生的价差,价格交易的是下一年的指引和火灾。这两者的缺口,是比任何单一数字更有价值的线索:一季度财报和11月月线收盘会在同一批日子里给出两份裁决。
13|下一次值得跟踪什么
13.1|一季度财报说明全年指引在按进度走吗
这是最近、最快见分晓的问题,几天内就会出结果。2027年6月期一季度(7–9月)财报预计在2026年11月13日前后发布,研究截止时尚未公布,要看全年指引的进度,以及电池板块在产能受限下披露的销量。如果进度领先,说明指引是底线;如果落后,它更像上限。这份披露在研究截止之后才会公开,属于下一次报告。
13.2|电池产能何时恢复,新工厂花多少钱
这个问题直接改变合并预测,也决定增长担当的时间表。要看的是:出事的承包商路径何时重启,或者哪些新伙伴上线;保险最终赔付与预测中的估计额差多少;新电池工厂的产能、投资额、时点,以及如何由已转为净现金的资产负债表来支付。目前没有承诺的恢复日期,赔付只是估计。答案偏慢、偏小,合并预测会被直接拉低。
13.3|价格从高位回调后,价差还能保留多少
这是决定估值的底部问题。如果铁屑和贵金属价格从纪录高位回调,资源板块2026年6月期的价差能保留多少?2023至2025年6月期的经常利润(19.02亿、17.83亿、12.16亿日元)是下行模板,要看底部是否已更高。贸易利润从2.70亿日元升到7.03亿日元,在价差回归后有多少保留,也要看,因为净额确认让账面规模更难判断。这两项只有在价格持平或下跌的季度才能分出答案。
13.4|管理层会不会给En-Vision2035设置可度量的中间指标
撤回中期计划后,单年计划是唯一可评分的承诺。要看公司是否会公布收货量、分部回报、炉渣合同等阶段性指标,否则十年期的增长腿一直没法打分。管理层意图未知。
13.5|净现金和低于账面的股价会不会被转成每股价值
超出DOE下限之后,回购节奏会不会重新加速到2025年6月期的7.89亿日元?新社长会不会改变对日东化工、缩小中的咨询和福利业务、库存股的处理?目前没有杠杆、现金水平或回购节奏的目标,这个问题决定净现金能否变成每股价值。
13.6|炉渣和市政合同什么时候能被量化
这是被指定为近期增长担当的一条腿,目前无法估算规模。要看第一批包含灰回收的一般废弃物功能合同何时披露,相对资源板块239.40亿日元的销售规模有多大;市政合同把2026年3月的指南修订转化为吨位有多快;炉渣业务会不会单独披露收入或利润。目前没有合同层面的量或时间表。
13.7|价格要看的下一批证据
价格这边最先要看的是11月月线收盘:能否收回654日元,守住604日元。往上再看月线能否站上12个月均线806日元,以及能否超过1,253日元;往下看466日元和345至361日元的地板是否被再次触及。基本面和价格的两份裁决会在同一批日子里到来。
14|Kabugami 评分卡
14.1|总分59.51/100,评级B,评分版本V3.2
下面每个模块的得分按「得分/满分」写,八个模块满分合计100,得分合计59.51。评级B,反映的是基本盘稳固、周期性盈利尚待验证,把握一般。
财务韧性与下行防御:9.75/13。权益比率54.1%,有息负债下降,净现金转正,五年营业现金流全为正;没有保护的是盈利,不是偿债。 竞争优势与结构耐久性:7.7/14。有收货网络、破碎线和市政关系,但证据全部来自公司自述,耐久性要等平价年份检验。 盈利质量、现金转化与资本效率:9.86/17。利润质量比上年好,但大部分增幅来自价差,ROIC只略高于股本成本。 商业结构、产品、客户与关键依赖:5.5/11。电池板块因承包商单点失效,利润指引从7.04亿降到0.5亿日元,增长故事暂时无法在利润表核实。 估值与安全边际:10.2/15。0.91倍市净率、8.19倍预测市盈率,对高点盈利便宜,对低谷盈利大致合理。 资本配置与股东回报:6.5/10。分红下限稳定了收入,回购随意,积极程度尚未被证明。 治理、所有权与管理层:3.5/7。家族控制约47.5%,指引纪律有一年改善,少数股东承担治理折价。 Kabugami技术结构:6.5/13。旧下跌已结束,新状态尚未成立,回抽正在底部上沿测试。
14.2|操作上暂不追高,等一季度财报和11月月线
暂不追高,列入重点观察。先等2027年6月期一季度财报(预计2026年11月13日前后)和11月月线收盘,再决定是否建立小仓位。基本面验证的重点是资源板块在平价下能否接近约29亿日元的计划,以及电池板块的恢复安排;价格验证的重点是月线能否收回654日元以上并守住604日元。流通盘偏小,仓位要考虑退出的难度。三个模块(盈利质量、竞争优势、估值)都取决于平价年份底部盈利,一季度财报公布后,任何一个模块都可能上调或下调。
14.3|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 9.75 | 权益比率54.1%,有息负债从2023年6月期的103.27亿日元降到67.68亿日元,首次在五年窗口内转为净现金(约6.19亿日元,口径按公司披露)。过去五年营业现金流全部为正,包括2024年6月期净利润仅5.37亿日元的低谷年,且未靠增资。2026年6月期资本开支9.47亿日元,自由现金流约21亿日元。财务上能撑过价差下行周期,真正没有保护的是盈利,而不是偿债。 |
| 竞争优势与结构耐久性 | 14 | 7.7 | 优势来自1950年代建立的收货网络、1997年投入的破碎线、许可资质和与市政多年积累的关系,以及自行设计的分选工艺。这是依赖隐性经验和关系的优势,不是专利或合同壁垒。目前所有证据都来自公司自述,没有第三方的回收率对比,也没有收货份额数据。判断为有一定优势、但耐久性尚待验证。 |
| 盈利质量、现金转化与资本效率 | 17 | 9.86 | 2026年6月期经常利润35.82亿日元(+194.6%)、营业利润32.24亿日元(+231.6%),销售额反而下降9.5%。管理层自己的增益拆解把大部分增幅归因于购销价差。质量比上年好:税前利润33.66亿日元里特别项目净为负,而2025年6月期含约6亿日元的保险和补助收益。ROE为13.6%,ROIC约10%至12%,只略高于约10%的股本成本。五年经常利润平均约25.3亿日元,中位数19.0亿日元。 |
| 商业结构、产品、客户与关键依赖 | 11 | 5.5 | 商业结构高度依赖资源回收板块(约26.27亿日元,占经常利润大部分),电池回收板块约7.04亿日元,国际贸易约7.03亿日元,其他业务约0.4亿日元。橡胶(外部销售约60.62亿日元)是资源板块最大的收入线。2026年6月的火灾烧毁了负责锂电池预处理的外部承包商的库存,电池板块利润指引从约7.04亿日元降到约0.5亿日元。被定位为2030年后增长引擎的板块,眼下反而无法生产。 |
| 估值与安全边际 | 15 | 10.2 | 2026年11月6日收盘603日元,市值约182.8亿日元(按发行股数,未扣库存股),预测市盈率8.19倍(按公司指引每股收益73.67日元),实际市净率0.91倍,预测股息收益率3.65%,EV/EBITDA约3.8倍。以高点盈利来看明显便宜;以低谷盈利来看大致合理。折价的原因是家族持股约47.5%、自由流通约42%、转到标准市场后机构关注较少,以及盈利的周期性。 |
| 资本配置与股东回报 | 10 | 6.5 | 2026年6月期每股股息25日元(派息率约29.4%),2027年6月期预测22日元(约29.9%),政策是股息占净资产比例不低于2.5%,目的是避免2024年6月期股息只有6日元的情况。2025年6月期回购约7.89亿日元,2026年6月期约1.73亿日元,合计股东回报约8.85亿日元(约占净利润37%),且在净现金转正的同时完成。2027年6月期股息下调是跟随预测利润,不是政策变化。 |
| 治理、所有权与管理层 | 7 | 3.5 | 创业家族通过Windelight(38.03%)、Sano Maruka(7.02%)、社长佐野文胜(2.42%)等合计控制约47.5%股份,自由流通约42%,2025年9月18日从东证Prime转到标准市场。2025年8月撤回滚动中期计划(连续三期首年下调后),改为单年利润计划加2036年愿景。2026年有两次上调和一次超出指引的业绩,说明指引纪律有改善。 |
| Kabugami 技术结构 | 13 | 6.5 | 价格体系显示一轮长达三年的下跌已经结束:年度低点从618日元降到514日元、345日元,2025年出现首个更高的低点361日元,并在2025年形成361至654日元的底部区间。2026年1月以历史最大成交量启动,5月最高到1,253日元,但月线收盘只有803日元;6月至10月连续五个月收盘走低,10月收于637日元,11月6日日线收603日元,回到底部区间的上沿。旧的下跌过程明显减弱,新状态尚未成立,仍在等待判断。 |
总分: 59.51 / 100 评级: B 操作建议: 暂不追高,列入重点观察。先等2027年6月期第一季度决算(预计2026年11月13日前后)和11月月线收盘,再决定是否建立小仓位。基本面验证的重点是资源板块在平价下能否接近约29亿日元的计划、电池板块的恢复安排;价格验证的重点是月线能否收回654日元以上并守住604日元。流通盘偏小,仓位要考虑退出的难度。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|来源日期与数据截止
本报告的研究截止在2026年11月9日前,价格与市场数据截至2026年11月6日收盘(603日元)。核心来源包括:东证披露的2026年6月期财报(业绩快报,2026年8月13日)及2025年8月的上年对比;2026年8月26日业绩说明会实录(2026年8月31日经东证披露);2026年6月期有价证券报告(2026年9月18日,经G-Biz Info、IRBANK、Kitaishihon转载);JPX的市场转板清单(2025年9月18日);公司业务说明材料(2022年1月);IRBANK的2026年11月6日行情和披露清单;JINGI基于EDINET的五年序列;Japan IR转载的2026年10月28日限制性股票处分通知;以及Yahoo Finance的月线序列(至2026年10月27日)。
公司披露没有重大期后事项,年度的决算、有价证券报告、股东大会(2026年9月29日)和分红支付(9月30日起)都已完成。2027年6月期一季度财报在研究截止时尚未公布,研究截止之后才公开的信息属于下一次报告。
15.2|数据和判断的限制
公司的竞争优势、回收率和炉渣经济性都来自公司自述,没有第三方基准。总市值按发行股数计算,未扣除约6.0%的库存股;净现金有两种口径(9.4亿日元与+6.19亿日元);预测市盈率基于公司预测的每股收益;没有同业倍数和分析师预期。
关联公司、承包商、股东信托账户背后的持有人,以及日东化工的少数股东权益,都没有披露。融资余额数据的日期是2026年7月17日。
月线序列的末尾有缺口(数据到2026年10月27日),11月的月线收盘在观察日尚未完成。IRBANK和JINGI是整理公开文件的二手来源。
电池恢复时间、保险最终赔付、新工厂投资和平价年份的价差,在目前都无法确认。
本报告仅用于研究,不构成投资建议。评分和评级是对研究结论的概括,不是对价格走势的预测;股价、盈利和现金流都可能与本报告的判断不一致,重大风险见第11章,投资决定应由读者自行承担。
主要资料来源
- Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013
- Management's framing of FY6/26: structural-reform results, not only market luck (briefing)
- FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build
- Cash-flow trajectory: operating cash flow positive in every one of the five years
- The 30 July 2026 revision: forecast and dividend raised ahead of the annual print
- FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine
- Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million
- Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)
- JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025
- Restricted-stock disposal completed 28 October 2026: 50,203 treasury shares at JPY 741
- Group composition from the FY6/26 securities report: eleven consolidated subsidiaries
- Assembled monthly price history, September 2013 - October 2026 (158 bars)
研究发现索引
展开本次 Review 的 86 项研究发现
F001|02|真正耐久的是分选能力,周围的利润和产能都带周期性
研究范围:开放研究+35项覆盖检查
写入正文:02|真正耐久的是分选能力,周围的利润和产能都带周期性05|优势有,但耐久性要等平价年份的数据证明14|总分59.51/100,评级B,评分版本V3.2
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:直接证据;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
Management's framing of FY6/26: structural-reform results, not only market luck (briefing)怎么使用:直接证据;一手验证:04、10;专项深挖:02、16
AI sorting co-development with Earth Technica (briefing)怎么使用:直接证据;一手验证:04、07;专项深挖:04
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接证据;一手验证:18、19、21、29;外部现实校验:17
Cash-flow trajectory: operating cash flow positive in every one of the five years怎么使用:直接证据;一手验证:17;外部现实校验:29;专项深挖:17
Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million怎么使用:直接证据;一手验证:20;反向验证:04、10、20
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域16)|Management's framing of FY6/26: structural-reform results, not only market luck (briefing);直接证据 / 一手证据(研究域04) / 一手证据(研究域07) / 定向深挖(研究域04)|AI sorting co-development with Earth Technica (briefing);直接证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 一手证据(研究域17) / 外部现实(研究域29) / 定向深挖(研究域17)|Cash-flow trajectory: operating cash flow positive in every one of the five years;直接证据 / 一手证据(研究域20) / 反证(研究域04) / 反证(研究域10) / 反证(研究域20)|Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million
完整研究记录(核对用)
研究原文:The durable element of Envipro is the sorting franchise: a 1950-vintage intake network, the 1997 shredder bet, permits and a decade of municipal relationships, housed in written-down plant (machinery 81% depreciated) and historical-cost land. Everything around that core is cyclical or transitional: the metal-price spread, battery capacity after the fire, the trading book's reported scale (netting convention), and a one-year-old governance doctrine. Durability reduces to one testable question: does the reformed franchise earn more in a flat-price year than the old one did in FY6/23-25 (ordinary profit JPY 1.2-1.9 billion)? Net cash, a 54.1% equity ratio and five years of positive operating cash flow let the company survive long enough to answer; the DOE floor pays shareholders while waiting.
内部研究类型:durable_business_portrait_core
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Defines what the ordinary shareholder owns: a tacit-know-how franchise with a price-cyclical earnings overlay and a self-funding balance sheet.
不确定性(原始记录):Moat evidence is issuer-asserted; no third-party benchmark of recovery rates or intake share; durability is tested only by FY6/27 flat-price prints.
F002|02|同样的吨位,赚的是买进废料与卖出再生材料之间的价差
研究范围:开放研究
写入正文:02|同样的吨位,赚的是买进废料与卖出再生材料之间的价差
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:直接 / 支持;一手验证:02;外部现实校验:16
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure怎么使用:直接 / 支持;一手验证:07、16
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域16)|FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure
完整研究记录(核对用)
研究原文:The economic engine is a price-spread option attached to a shredding and sorting asset: the same tonnes earn the spread between scrap purchase prices and recovered-material sale prices, so profit elasticity to metal prices dwarfs volume elasticity. FY6/26 (volume down, profit tripled) and FY6/24 (EPS JPY 17.9 in a soft price year) are the two poles.
内部研究类型:economic_mechanism
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Earnings arrive in price-driven waves; the shareholder return stream is floored by policy (DOE), not by the model.
不确定性(原始记录):Spread split by material (iron, non-ferrous, rubber, slag) is not disclosed.
F003|01|2026年6月期利润猛增来自价差,出货量其实在下降
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|2026年6月期利润猛增来自价差,出货量其实在下降06|利润质量比上一年好,但有三处读数偏差
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:直接 / 支持;外部现实校验:22
FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure怎么使用:直接证据;一手验证:07、16
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:直接 / 支持;一手验证:02;外部现实校验:16
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026;直接证据 / 一手证据(研究域07) / 一手证据(研究域16)|FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure;直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story
完整研究记录(核对用)
研究原文:FY6/26 ordinary profit of JPY 3,582 million (+194.6%) and operating profit of JPY 3,224 million (+231.6%) came with sales down 9.5% and handled volume down 19.6% to 491 thousand tonnes; management's own bridge assigns JPY 2,335 million of the JPY 2,366 million ordinary-profit increase to the purchase-sale spread. It was a price-margin event on a shrinking physical base. Gross margin rose from 17.2% to 22.5%, SG&A fell JPY 705 million, contribution margin rose 24.2% and EBITDA rose 97.2% to JPY 4,624 million.
内部研究类型:observed_fact_cluster
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The headline profit surge says little about volume franchise growth; it is a spread reading that can reverse.
不确定性(原始记录):The one-off versus recurring split of the JPY 705 million SG&A reduction is not decomposed; 'structural reform' share of the gain vs price share is not separately measurable.
F004|02|资源回收是利润发动机,资产只多了8.6%
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY6/26 segment results (segment profit reconciles to ordinary profit)怎么使用:直接 / 支持;一手验证:02、32
Segment assets, depreciation and capex by segment, FY6/26 segment note怎么使用:直接 / 支持;外部现实校验:20
Segment comparatives, FY6/25: the profit step-up measured against the soft year怎么使用:直接 / 支持;专项深挖:01;同业比较:03、06、07、15、16、19、20、32;其他用途:历史
Segment revenue composition (external sales by product line), FY6/26 segment note怎么使用:直接证据;一手验证:03;外部现实校验:02、15;专项深挖:03
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域32)|FY6/26 segment results (segment profit reconciles to ordinary profit);直接证据 / 支持证据 / 外部现实(研究域20)|Segment assets, depreciation and capex by segment, FY6/26 segment note;直接证据 / 支持证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域01)|Segment comparatives, FY6/25: the profit step-up measured against the soft year;直接证据 / 一手证据(研究域03) / 外部现实(研究域02) / 外部现实(研究域15) / 定向深挖(研究域03)|Segment revenue composition (external sales by product line), FY6/26 segment note
完整研究记录(核对用)
研究原文:Segment profit (ordinary-profit basis) shows resource recycling as the engine: JPY 2,627 million of JPY 3,582 million consolidated (vs JPY 1,159 million), battery recycling JPY 704 million, global trading JPY 703 million, other JPY 40 million, corporate adjustments minus JPY 494 million. Resource profit roughly doubled on segment assets that grew only 8.6% (JPY 21,237 to 23,062 million), so the step-up is a return-on-assets event, not a capacity event; all JPY 514 million of equity-method income also sits in this segment, and rubber (JPY 6,062 million external) is its largest revenue line.
内部研究类型:segment_profit_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Whether the resource segment holds near its JPY 2,900 million plan on flat prices is the single most informative test of the reform claim.
不确定性(原始记录):Product-line profit below segment level is not disclosed; ordinary-profit basis includes affiliate income, so segment 'plant economics' are blended with affiliate contributions.
F005|06|销售额会误导,应该看每吨价差
研究范围:35项覆盖检查
写入正文:06|销售额会误导,应该看每吨价差
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Segment revenue composition (external sales by product line), FY6/26 segment note怎么使用:直接 / 支持;一手验证:03;外部现实校验:02、15;专项深挖:03
FY6/26 briefing: price backdrop and the accounting reason sales fell怎么使用:直接 / 支持;一手验证:05、08、11、15;外部现实校验:12、14
Revenue-recognition change in the trading book, from the segment commentary怎么使用:直接 / 支持;一手验证:15、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域02) / 外部现实(研究域15) / 定向深挖(研究域03)|Segment revenue composition (external sales by product line), FY6/26 segment note;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域11) / 一手证据(研究域15) / 外部现实(研究域12) / 外部现实(研究域14)|FY6/26 briefing: price backdrop and the accounting reason sales fell;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域32)|Revenue-recognition change in the trading book, from the segment commentary
完整研究记录(核对用)
研究原文:Reported sales understate activity twice over: part of the trading book moved from gross to net (spread) revenue recognition in FY6/26, and consolidated sales have fallen three years running (57,319 to 44,430 million) while profit concentrated in processed lines. Margin-on-sales optics (7.3% operating margin) flatter the improvement; handled tonnage and spread per tonne are the honest denominators, although tonnage is itself partly a mix effect from deprioritised low-value bulk flows.
内部研究类型:measurement_hazard
内部来源标记:COVERAGE35
普通股东含义(原始记录):Sales-based multiples and margins are distorted versus history; per-tonne or spread measures should be used.
不确定性(原始记录):The exact revenue quantum moved to net recognition is not quantified.
F006|06|利润质量比上一年好,但有三处读数偏差
研究范围:35项覆盖检查
写入正文:06|利润质量比上一年好,但有三处读数偏差14|总分59.51/100,评级B,评分版本V3.2
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure怎么使用:直接 / 支持;一手验证:07、16
Special-items quality: FY6/26 profit is cleaner than FY6/25's怎么使用:直接证据;一手验证:16;外部现实校验:32;反向验证:28、32;专项深挖:32
Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur怎么使用:直接证据;外部现实校验:02;反向验证:14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域16)|FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure;直接证据 / 一手证据(研究域16) / 外部现实(研究域32) / 反证(研究域28) / 反证(研究域32) / 定向深挖(研究域32)|Special-items quality: FY6/26 profit is cleaner than FY6/25's;直接证据 / 外部现实(研究域02) / 反证(研究域14)|Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur
完整研究记录(核对用)
研究原文:FY6/26 earnings are higher quality than FY6/25's: pre-tax profit of JPY 3,366 million was reached with special items net negative (disaster JPY 131 million, impairment JPY 94 million), whereas FY6/25's JPY 1,516 million included JPY 600 million of insurance and subsidy gains. Equity-method income (JPY 514 million, 14.3% of ordinary profit) and recurring FX losses (JPY 139 million) show the ordinary-profit line is partly an affiliate-income construct. Net of the flattered FY6/25 base and netted sales, the honest improvement is large but smaller than headline multiples.
内部研究类型:profit_quality_judgment
内部来源标记:COVERAGE35
普通股东含义(原始记录):Only the spread-driven, structurally earned part of the gain deserves capitalisation.
不确定性(原始记录):Affiliate financials are not consolidated; none of the reading hazards suggests misstatement.
F007|03|被定为2030年后增长担当的电池回收,眼下被承包商火灾卡住
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论03|被定为2030年后增长担当的电池回收,眼下被承包商火灾卡住11|电池恢复延期和物流、汇率是次一级的风险12|指引的保守程度,集中在公司控制不了的地方14|总分59.51/100,评级B,评分版本V3.2
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:直接 / 支持;一手验证:35
Battery-recycling recovery actions and the new-plant project (briefing)怎么使用:直接证据;专项深挖:06、11、20、30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing);直接证据 / 定向深挖(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域20) / 定向深挖(研究域30)|Battery-recycling recovery actions and the new-plant project (briefing)
完整研究记录(核对用)
研究原文:A June 2026 fire at the contractor performing pre-processing for lithium-ion battery recycling destroyed stored inventory (JPY 130 million disaster loss) and restricts capacity into FY6/27. Segment profit is guided from JPY 704 million to JPY 50 million. The forecast embeds estimated (not final) insurance proceeds and a capacity constraint with no committed end date; negotiations and a partner search are underway. The segment designated as the post-2030 growth carrier is the one currently unable to produce, which also puts the new-plant project on the strategy's critical path.
内部研究类型:swing_factor_with_open_timeline
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Slower restoration or a smaller settlement moves the consolidated forecast directly; the drag is about JPY 650 million of segment profit.
不确定性(原始记录):Contractor identity, restart conditions, final insurance settlement and partner bench depth are undisclosed.
F008|01|2027年6月期指引按平价、带着电池拖累来定
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|2027年6月期指引按平价、带着电池拖累来定07|撤回中期计划后,每一份单年计划就是承诺12|撤回中期计划,反而抬高了考核标准12|指引的保守程度,集中在公司控制不了的地方
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:直接 / 支持;一手验证:35
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:直接 / 支持;一手验证:28、35;反向验证:12、22;专项深挖:35
The 30 July 2026 revision: forecast and dividend raised ahead of the annual print怎么使用:直接 / 支持;外部现实校验:31;反向验证:31;专项深挖:31;同业比较:30;其他用途:历史
FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine怎么使用:支持证据;一手验证:23、31;反向验证:23、33;同业比较:13、31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|FY6/27 full-year forecast: higher sales, lower profit, published 13 August 2026;直接证据 / 支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing);直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);直接证据 / 支持证据 / 外部现实(研究域31) / 历史/同业比较(研究域30) / 反证(研究域31) / 定向深挖(研究域31)|The 30 July 2026 revision: forecast and dividend raised ahead of the annual print;直接证据|FY6/27 positioned as a base-building year: investment continues through the forecast decline (briefing);支持证据 / 一手证据(研究域23) / 一手证据(研究域31) / 历史/同业比较(研究域13) / 历史/同业比较(研究域31) / 反证(研究域23) / 反证(研究域33)|FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine
完整研究记录(核对用)
研究原文:FY6/27 guidance (sales JPY 49,000 million +10.3%, operating profit JPY 2,700 million -16.3%, ordinary profit JPY 3,100 million -13.5%, net income JPY 2,100 million, EPS JPY 73.67, tonnage target 550 thousand tonnes) is a deliberate down year assuming net spread contribution of only +JPY 206 million against JPY 564 million of cost increases (personnel +340, equipment +224), with the battery segment crippled. It follows a year of two upward revisions (12 February and 30 July 2026) and a print above the final guide, versus the withdrawn-plan era of first-year downgrades. It is constructed as a floor-setting exercise, though the conservatism sits partly where the company cannot control it (the battery segment). Management also frames the year as base-building with the plan as a commitment, not a ceiling.
内部研究类型:guidance_construction
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A tracking or beating guide on flat prices would validate that the floor rose; a miss means FY6/26 was price.
不确定性(原始记录):One year of improved revision behaviour is not a regime; net spread assumption cannot be verified from outside.
F009|07|撤回中期计划后,每一份单年计划就是承诺
研究范围:开放研究+35项覆盖检查
写入正文:07|撤回中期计划后,每一份单年计划就是承诺08|新电池工厂和外围业务考验配置纪律12|撤回中期计划,反而抬高了考核标准
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine怎么使用:直接 / 支持;一手验证:23、31;反向验证:23、33;同业比较:13、31;其他用途:历史
Capital-efficiency doctrine in the securities report: beat the ~10% cost of equity every year怎么使用:直接 / 支持;一手验证:22;专项深挖:22、25
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:直接 / 支持;一手验证:28、35;反向验证:12、22;专项深挖:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域31) / 历史/同业比较(研究域13) / 历史/同业比较(研究域31) / 反证(研究域23) / 反证(研究域33)|FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域25)|Capital-efficiency doctrine in the securities report: beat the ~10% cost of equity every year;直接证据 / 一手证据(研究域11)|En-Vision2035: the ten-year vision and its three priority businesses (briefing);直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)
完整研究记录(核对用)
研究原文:The rolling mid-term plan was withdrawn in August 2025 after three consecutive plans needed first-year downgrades; the ROE targets (10% medium-term, 15% long-term) are no longer fixed goals. The doctrine is now En-Vision2035 (qualitative ten-year vision to FY6/36), single-year profit plans published and delivered one at a time, and sustaining returns above an estimated ~10% cost of equity. With no multi-year targets to hide behind, each single-year plan is the promise: FY6/27's forecast ROE of 11.1% clears the bar by about one point, the first genuinely tight year; FY6/26 ROE 13.6% cleared it comfortably.
内部研究类型:governance_doctrine
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Promise-keeping on annual plans is the governance metric that prices the register; ROE headroom against the cost of equity is thin in a flat-price year.
不确定性(原始记录):Cost-of-equity methodology is management's own estimate; whether any intermediate En-Vision2035 markers will be published is unknown.
F010|08|分红下限让收入更稳,回购节奏则随意
研究范围:开放研究+35项覆盖检查
写入正文:08|分红下限让收入更稳,回购节奏则随意14|总分59.51/100,评级B,评分版本V3.2
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Dividend record and FY6/27 dividend forecast (tanshin dividend table)怎么使用:直接 / 支持;一手验证:26
Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing)怎么使用:直接 / 支持;一手验证:25、26
Dividend history: the JPY 6 trough of FY6/24 and the return to JPY 25怎么使用:直接证据;外部现实校验:26;专项深挖:26;同业比较:25、26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and FY6/27 dividend forecast (tanshin dividend table);直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing);直接证据 / 外部现实(研究域26) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 定向深挖(研究域26)|Dividend history: the JPY 6 trough of FY6/24 and the return to JPY 25
完整研究记录(核对用)
研究原文:Returns are floored by policy: dividend-on-equity minimum of 2.5%, FY6/26 dividend JPY 25 (payout 29.4%, DOE 3.8% on management's measure; the tanshin shows 4.0%), FY6/27 forecast JPY 22 (payout ~29.9%, DOE 3.1%), designed to prevent a repeat of the JPY 6 FY6/24 trough (dividends 25/14/6/15/25 across FY6/22-26). Buybacks of JPY 789 million (FY6/25) and JPY 173 million (FY6/26; JPY 172 million per briefing) supplemented it; FY6/26 total return of about JPY 885 million (~37% of net income) was paid while net cash turned positive (+JPY 619 million). The nominal FY6/27 dividend cut follows the forecast profit decline, not a change in framework.
内部研究类型:capital_return_policy
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Income reliability has structurally improved; the buyback pace remains discretionary and the risk is under-distribution by a family-controlled net-cash register, not dilution.
不确定性(原始记录):Whether buybacks re-accelerate toward FY6/25's level; minor source differences in DOE measure (3.8% vs 4.0%) and buyback figure (172 vs 173 million).
F011|08|每股收益里有一部分来自股数减少
研究范围:35项覆盖检查
写入正文:08|每股收益里有一部分来自股数减少
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Share count, treasury stock and dilution at the FY6/26 close怎么使用:直接 / 支持;一手验证:25;反向验证:25
Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26)怎么使用:直接 / 支持;外部现实校验:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25) / 反证(研究域25)|Share count, treasury stock and dilution at the FY6/26 close;直接证据 / 支持证据 / 外部现实(研究域25)|Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26)
完整研究记录(核对用)
研究原文:Dilution is modest and visible: 1,139,681 potential shares from stock acquisition rights separate basic EPS (JPY 85.16) from diluted EPS (JPY 81.88); issued shares are unchanged at 30,317,388 with treasury at 1,811,673 (about 6.0%); the average share count fell to 28,462,432 from 29,997,980 as the FY6/25 buyback annualised, a mechanical EPS tailwind of roughly five percent. A further 50,203 treasury shares were granted as restricted stock to 46 directors and employees.
内部研究类型:dilution_and_per_share_mechanics
内部来源标记:COVERAGE35
普通股东含义(原始记录):Part of FY6/26 EPS growth is share-count shrinkage, not earnings; dilution is capped at the disclosed option pool.
不确定性(原始记录):Option exercise prices and schedules are not detailed in the tanshin.
F012|07|内部人信号很弱,社长交接的细节不清楚
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26)怎么使用:直接 / 支持;外部现实校验:25
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、21、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域25)|Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26);直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million
完整研究记录(核对用)
研究原文:On 28 October 2026 the company completed the disposal of 50,203 treasury shares as restricted-stock compensation to 46 directors and employees at JPY 741 per share (JPY 37.2 million), above the FY6/26 book value (JPY 659) and above the 6 November close (JPY 603). It is a small, dated insider data point weakly corroborating management's view of the guide as a floor, and a retention instrument.
内部研究类型:insider_reference_point
内部来源标记:COVERAGE35
普通股东含义(原始记录):Insiders accepted multi-year equity exposure at a level the market has not revisited; weak evidence only.
不确定性(原始记录):Grant price and vesting terms may reflect a reference price set earlier; low independent information content; not a purchase with own money.
F013|06|资产负债表保守,下行风险在盈利而不在偿债
研究范围:35项覆盖检查
写入正文:06|资产负债表保守,下行风险在盈利而不在偿债14|总分59.51/100,评级B,评分版本V3.2
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接 / 支持;一手验证:18、19、21、29;外部现实校验:17
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:直接 / 支持;一手验证:17、20;外部现实校验:19
Balance-sheet trajectory: net cash turned positive for the first time in the five-year window怎么使用:直接证据;一手验证:18、29;专项深挖:18、29;同业比较:21、24;其他用途:历史
Cash-flow trajectory: operating cash flow positive in every one of the five years怎么使用:直接 / 支持;一手验证:17;外部现实校验:29;专项深挖:17
Retirement and restoration obligations: the quiet liabilities怎么使用:直接证据;外部现实校验:18;反向验证:18、21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million;直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 定向深挖(研究域18) / 定向深挖(研究域29)|Balance-sheet trajectory: net cash turned positive for the first time in the five-year window;直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域29) / 定向深挖(研究域17)|Cash-flow trajectory: operating cash flow positive in every one of the five years;直接证据 / 外部现实(研究域18) / 反证(研究域18) / 反证(研究域21)|Retirement and restoration obligations: the quiet liabilities
完整研究记录(核对用)
研究原文:The balance sheet is conservatively geared: equity ratio 54.1%, book value per share JPY 659.26, interest-bearing debt down from JPY 10,327 million (FY6/23) to JPY 6,768 million, net cash positive (+JPY 619 million, JINGI cash-equivalents basis) for the first time in the five-year window, achieved without equity raising. Operating cash flow was positive in all five years (3,873 / 2,332 / 2,940 / 3,470 / 3,072 million), including the FY6/24 trough with net income of JPY 537 million; cumulative ~JPY 15.7 billion roughly equals the market capitalisation. FY6/26 capex of JPY 947 million left free cash flow of roughly JPY 2.1 billion after a ~JPY 2.6 billion working-capital build. Retirement obligations (JPY 1,135 million) are the largest non-debt liability.
内部研究类型:financial_resilience
内部来源标记:COVERAGE35
普通股东含义(原始记录):The register self-funds through the cycle; a dilutive rescue is unrealistic and capital survival through a trough is demonstrated; downside is earnings volatility, not solvency.
不确定性(原始记录):Net cash definition differs between sources (tanshin cash and deposits JPY 7,498 million vs JINGI basis); earnings downside (spread reversal) is unprotected.
F014|07|家族握有约47.5%股份,少数股东承担折价
研究范围:开放研究+35项覆盖检查
写入正文:07|家族握有约47.5%股份,少数股东承担折价09|股价是在为低谷盈利定价14|总分59.51/100,评级B,评分版本V3.2
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:直接 / 支持;一手验证:01、23、24
JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025怎么使用:直接证据;一手验证:01、13、33;反向验证:01、09
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、21、35
Restricted-stock disposal completed 28 October 2026: 50,203 treasury shares at JPY 741怎么使用:直接证据;一手验证:24;外部现实校验:01;专项深挖:24
Margin-trading balance: one-sided retail leverage after the spike怎么使用:直接证据;外部现实校验:24;反向验证:24、26、27、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info);直接证据 / 一手证据(研究域01) / 一手证据(研究域13) / 一手证据(研究域33) / 反证(研究域01) / 反证(研究域09)|JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million;直接证据 / 一手证据(研究域24) / 外部现实(研究域01) / 定向深挖(研究域24)|Restricted-stock disposal completed 28 October 2026: 50,203 treasury shares at JPY 741;直接证据 / 外部现实(研究域24) / 反证(研究域24) / 反证(研究域26) / 反证(研究域27) / 反证(研究域34)|Margin-trading balance: one-sided retail leverage after the spike
完整研究记录(核对用)
研究原文:Founding-family vehicles Windelight (38.03%) and Sano Maruka (7.02%), President Fumikatsu Sano (2.42%) and other family names hold roughly 47.5% of shares excluding treasury; free float is ~42%; the listing moved from Prime to Standard on 18 September 2025. The price (JPY 603 on 6 November 2026) is 0.91x book and 8.2x forecast earnings after a 13.6% ROE year because ~58% of the stock cannot trade, the venue carries thinner sponsorship, and the earnings stream is visibly price-cyclical. Margin balances are one-sided (526,200 long vs 100 short shares in July 2026), amplifying price moves both ways.
内部研究类型:control_and_venue_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Minorities price a governance and liquidity discount; mispricing corrects through evidence accumulation (prints) rather than arbitrage; sizing must respect liquidity.
不确定性(原始记录):Beneficial holders behind trust accounts are not visible; no Prime return path disclosed.
F015|09|估值的分歧归结为底部盈利是15亿还是25亿日元
研究范围:开放研究+35项覆盖检查
写入正文:09|估值的分歧归结为底部盈利是15亿还是25亿日元14|操作上暂不追高,等一季度财报和11月月线
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
ROIC estimates and cash conversion (JINGI computed indicators)怎么使用:直接证据;一手验证:22;外部现实校验:27、28;专项深挖:12、27、28
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:直接证据;一手验证:28、35;反向验证:12、22;专项深挖:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;直接证据 / 一手证据(研究域22) / 外部现实(研究域27) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域27) / 定向深挖(研究域28)|ROIC estimates and cash conversion (JINGI computed indicators);直接证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)
完整研究记录(核对用)
研究原文:The register's real question is the height of the mid-cycle floor. Five-year ordinary profit (JPY 4,167 / 1,902 / 1,783 / 1,216 / 3,582 million) averages ~JPY 2,530 million (median 1,902) and brackets a soft-price trough band of JPY 1.2-1.9 billion; ROE ran 21.6 / 7.7 / 3.2 / 7.0 / 13.6% and ROIC ~10-12% against a ~10% cost of equity. FY6/27's price-blind guide of JPY 3,100 million sits above every soft year, management's implicit claim that the floor rose. If structural reform lifted the trough toward JPY 2.5 billion the guide is beatable; if not, it is the ceiling of a normal year.
内部研究类型:normalized_earnings_question
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The entire valuation debate reduces to this number: capitalising JPY 2.5 billion gives a mid-single-digit earnings yield on a net-cash balance sheet; JPY 1.5 billion gives a fully priced cyclical.
不确定性(原始记录):Sensitive to window choice (FY6/22 spike inflates averages); the price deck of a normal year is unknown; JINGI gives two ROIC treatments.
F016|06|现金流五年为正,但利润的一部分压在库存和应收款里
研究范围:开放研究+35项覆盖检查
写入正文:06|现金流五年为正,但利润的一部分压在库存和应收款里11|价差回落时,利润下降和现金释放会同时发生
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:直接 / 支持;一手验证:02;外部现实校验:16
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接 / 支持;一手验证:18、19、21、29;外部现实校验:17
Working capital absorbed the profit: inventories and receivables built at high prices怎么使用:直接 / 支持;一手验证:19;反向验证:02、08、15、16、17、19、29;专项深挖:19
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:直接 / 支持;一手验证:17、20;外部现实校验:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 支持证据 / 一手证据(研究域19) / 反证(研究域02) / 反证(研究域08) / 反证(研究域15) / 反证(研究域16) / 反证(研究域17) / 反证(研究域19) / 反证(研究域29) / 定向深挖(研究域19)|Working capital absorbed the profit: inventories and receivables built at high prices;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million
完整研究记录(核对用)
研究原文:Spread compression is symmetric: the mechanism that added JPY 2,335 million in FY6/26 subtracted through FY6/23-25 as prices normalised. FY6/26 profit was accompanied by an inventory build (JPY 1,416 million in the cash-flow statement; balance sheet +1,282 to JPY 4,532 million) and receivables build (JPY 1,214-1,251 million to JPY 4,848 million) at record prices, funded by a JPY 1,367 million rise in payables. In a price correction the belt runs backwards: cash is released but margins compress, so cash flow and earnings move in opposite directions at the turn.
内部研究类型:risk_and_balance_sheet_transmission
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Profit partly held in stock and receivables carried at record prices can unwind against margins; position sizing should expect earnings-cash divergence.
不确定性(原始记录):Inventory composition by material and its price sensitivity are not disclosed; speed of cash release unknown.
F017|05|单点依赖是护城河的反面证据
研究范围:开放研究+35项覆盖检查
写入正文:05|单点依赖是护城河的反面证据
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million怎么使用:直接证据;一手验证:20;反向验证:04、10、20
The holding company is thin: 61 standalone employees; group scale from operating subsidiaries怎么使用:直接证据;外部现实校验:23
Safety and dependency: the fire's lesson as management states it (briefing)怎么使用:直接证据;反向验证:06、07、13
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:支持证据;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 一手证据(研究域20) / 反证(研究域04) / 反证(研究域10) / 反证(研究域20)|Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million;直接证据 / 外部现实(研究域23)|The holding company is thin: 61 standalone employees; group scale from operating subsidiaries;直接证据 / 反证(研究域06) / 反证(研究域07) / 反证(研究域13)|Safety and dependency: the fire's lesson as management states it (briefing);支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)
完整研究记录(核对用)
研究原文:Single-point dependencies are the register's operating signature: one contractor's fire removed a year of battery capacity; the plant base producing the sorting advantage is 81% depreciated (machinery gross JPY 17,171 million) with replacement capex a rising claim; the standalone holding company is a thin 61-person head office steering eleven subsidiaries; and control sits with one family. Management treats the fire as an operational-design failure to engineer out, but each concentration is managed, not eliminated.
内部研究类型:structural_weakness
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Another single-point failure would remove another year of a segment; returns on capital will be diluted by the new asset base before new capacity earns.
不确定性(原始记录):Subsidiary-level management depth and the partner bench are undisclosed; new battery plant capex is unquantified.
F018|07|内部人信号很弱,社长交接的细节不清楚
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:直接 / 支持;一手验证:01、23、24
The holding company is thin: 61 standalone employees; group scale from operating subsidiaries怎么使用:直接 / 支持;外部现实校验:23
Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26)怎么使用:直接 / 支持;外部现实校验:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info);直接证据 / 支持证据 / 外部现实(研究域23)|The holding company is thin: 61 standalone employees; group scale from operating subsidiaries;直接证据 / 支持证据 / 外部现实(研究域25)|Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26)
完整研究记录(核对用)
研究原文:The presidency has passed from founder-generation Tomikazu Sano (now chairman per the August 2026 briefing record) to Fumikatsu Sano; the family bloc controls the register and a 61-person head office steers eleven subsidiaries. The restricted-stock grant to 46 staff is a retention instrument, but subsidiary management depth is not disclosed.
内部研究类型:key_person_risk
内部来源标记:COVERAGE35
普通股东含义(原始记录):Capital-allocation behaviour of the new presidency (subsidiary Nitto Kako, peripheral businesses, treasury stock) is the visible degree of freedom.
不确定性(原始记录):Exact transition date and board-level changes not pinned in the sources used.
F019|03|炉渣回收是资本最轻的增长腿,但看不到它的单独利润
研究范围:开放研究+35项覆盖检查
写入正文:03|炉渣回收是资本最轻的增长腿,但看不到它的单独利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Precious-metal slag business: March 2026 ministry guideline revision (briefing)怎么使用:直接 / 支持;一手验证:10、13
Precious-metal slag mechanics: two axes - grade and intake (briefing)怎么使用:直接 / 支持;专项深挖:10、13
Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)怎么使用:直接 / 支持;一手验证:05、09;外部现实校验:13;专项深挖:09
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域13)|Precious-metal slag business: March 2026 ministry guideline revision (briefing);直接证据 / 支持证据 / 定向深挖(研究域10) / 定向深挖(研究域13)|Precious-metal slag mechanics: two axes - grade and intake (briefing);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域09) / 外部现实(研究域13) / 定向深挖(研究域09)|Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)
完整研究记录(核对用)
研究原文:Precious-metal slag recovery (gold, silver, copper, platinum, palladium from municipal incinerator ash and shredder dust) monetises other parties' waste streams under municipal contracts and scales with intake agreements rather than commodity purchases, a structurally less working-capital-hungry leg than trading. The March 2026 Ministry of the Environment guideline revision, the first since November 2013, documented fly-ash recovery in the official procurement handbook. Management's levers are higher recovered grade per tonne and wider intake as municipalities outsource ash handling. No separate revenue or profit is published.
内部研究类型:growth_leg_capital_light
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The cleanest candidate for lifting the trough without commodity exposure, but unverifiable from disclosures.
不确定性(原始记录):Contract-level volumes, timing and economics undisclosed; pace of municipal adoption unknown.
F020|03|聚合物循环是十年期的选项,投入先于收益
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing)怎么使用:直接 / 支持;专项深挖:07
En-Vision2035: the ten-year vision and its three priority businesses (briefing)怎么使用:直接 / 支持;一手验证:11
查看完整证据标签(核对用)
直接证据 / 支持证据 / 定向深挖(研究域07)|Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing);直接证据 / 支持证据 / 一手证据(研究域11)|En-Vision2035: the ten-year vision and its three priority businesses (briefing)
完整研究记录(核对用)
研究原文:The polymer circular-economy leg runs three tracks: the RPF plant (started FY6/25), Nitto Kako's rubber-mat capacity expansion planned for the second half of FY6/27 (colour rubber chips launched in H1), and an Ebara chemical-recycling demonstration in which Envipro manages feedstock procurement. En-Vision2035 assigns social implementation to a ten-year window; no segment P&L isolates it.
内部研究类型:long_dated_option
内部来源标记:COVERAGE35
普通股东含义(原始记录):A decade-long option, not a forecast item; capex precedes earnings.
不确定性(原始记录):Demonstration-stage economics undisclosed.
F021|05|优势有,但耐久性要等平价年份的数据证明
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Management's framing of FY6/26: structural-reform results, not only market luck (briefing)怎么使用:直接证据;一手验证:04、10;专项深挖:02、16
AI sorting co-development with Earth Technica (briefing)怎么使用:直接证据;一手验证:04、07;专项深挖:04
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:直接证据;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
Precious-metal slag business: March 2026 ministry guideline revision (briefing)怎么使用:直接证据;一手验证:10、13
Resource-recycling strategy: deeper sorting, higher-value recovery, municipal ash (briefing)怎么使用:直接证据;专项深挖:08
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域16)|Management's framing of FY6/26: structural-reform results, not only market luck (briefing);直接证据 / 一手证据(研究域04) / 一手证据(研究域07) / 定向深挖(研究域04)|AI sorting co-development with Earth Technica (briefing);直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;直接证据 / 一手证据(研究域10) / 一手证据(研究域13)|Precious-metal slag business: March 2026 ministry guideline revision (briefing);直接证据 / 定向深挖(研究域08)|Resource-recycling strategy: deeper sorting, higher-value recovery, municipal ash (briefing)
完整研究记录(核对用)
研究原文:The sorting technology (magnetic, wind, gravity, eddy-current and sensor sorting on self-designed plants since the 1997 shredder) is the only credible trough-lifter: deeper recovery raises value per tonne at any price level. A roughly four-year AI-sorting co-development with Earth Technica (multi-sensor optics, AI image/3D analysis, robotics) targets productivity independent of skilled operators amid a staff shortage. The moat is tacit and relational rather than legal; erosion would show first as spread compression in flat-price years. Management also emphasises process redesign to raise recovered precious-metal grade rather than buying more feedstock.
内部研究类型:technology_moat_input
内部来源标记:COVERAGE35
普通股东含义(原始记录):Technology defends the spread; its payoff appears as spread resilience in flat years, not as separate revenue.
不确定性(原始记录):No R&D expense line; no third-party recovery-rate benchmark; no named-peer comparison was performed.
F022|09|隐含资产是选择权,不是估值支柱
研究范围:35项覆盖检查
写入正文:09|隐含资产是选择权,不是估值支柱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million怎么使用:直接 / 支持;一手验证:20;反向验证:04、10、20
Retirement and restoration obligations: the quiet liabilities怎么使用:直接 / 支持;外部现实校验:18;反向验证:18、21
Listed-subsidiary linkage: Nitto Kako (5104) inside the register怎么使用:直接 / 支持;一手验证:21;专项深挖:21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20) / 反证(研究域04) / 反证(研究域10) / 反证(研究域20)|Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million;直接证据 / 支持证据 / 外部现实(研究域18) / 反证(研究域18) / 反证(研究域21)|Retirement and restoration obligations: the quiet liabilities;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21)|Listed-subsidiary linkage: Nitto Kako (5104) inside the register
完整研究记录(核对用)
研究原文:A real but unquantified asset ledger: land at JPY 3,841 million historical cost, investment securities of JPY 4,073 million (including the listed Nitto Kako stake) and treasury shares of JPY 871 million at cost, with machinery written down to ~19% of gross. None is marked in the accounts, so 0.91x book already embeds a conservative carrying basis; no revaluation evidence exists to size the gap. Nitto Kako (TSE Standard 5104) carries its own market price inside the parent's register, posing a partial-listing discount question the consolidated accounts do not answer.
内部研究类型:hidden_asset_ledger
内部来源标记:COVERAGE35
普通股东含义(原始记录):Optionality, not thesis; matters only if capital policy ever surfaces value; minority and perimeter claims must not be double counted.
不确定性(原始记录):Land market value and full securities breakdown undisclosed.
F023|11|电池恢复延期和物流、汇率是次一级的风险
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels怎么使用:直接 / 支持;一手验证:14;外部现实校验:03、05、06、08、11、12;反向验证:05
Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur怎么使用:直接 / 支持;外部现实校验:02;反向验证:14
Trading segment: what the netting change means and what management says about the book (briefing)怎么使用:直接 / 支持;反向验证:11;专项深挖:05、14、15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 反证(研究域05)|Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels;直接证据 / 支持证据 / 外部现实(研究域02) / 反证(研究域14)|Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur;直接证据 / 支持证据 / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域14) / 定向深挖(研究域15)|Trading segment: what the netting change means and what management says about the book (briefing)
完整研究记录(核对用)
研究原文:Trade-route geopolitics reaches the register through logistics: the Strait of Hormuz closure disrupted Dubai-bound cargo in the agency business in FY6/26, and the export-oriented trading book is exposed to shipping and sanction shocks absent from any price series. Foreign-exchange losses recurred for two consecutive years (JPY 133 million, then JPY 139 million) beneath the operating line in a group with partly dollar-linked pricing; no hedging is disclosed beyond that. Battery raw materials (cobalt, nickel, lithium) were firm on supply constraints.
内部研究类型:macro_transmission_risks
内部来源标记:COVERAGE35
普通股东含义(原始记录):Small against ordinary profit but persistent; they sit beneath the dominant price exposure.
不确定性(原始记录):FX hedging practice, if any, is not disclosed.
F024|11|催化剂按财报日期排好,其余靠事件
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|催化剂按财报日期排好,其余靠事件14|操作上暂不追高,等一季度财报和11月月线
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Disclosure chronology: first-quarter results habitually land on 13 November怎么使用:直接 / 支持;一手验证:30
Subsequent events: none disclosed (tanshin, subsequent-events note)怎么使用:直接 / 支持;一手验证:30
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|Disclosure chronology: first-quarter results habitually land on 13 November;直接证据 / 支持证据 / 一手证据(研究域30)|Subsequent events: none disclosed (tanshin, subsequent-events note);直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)
完整研究记录(核对用)
研究原文:The FY6/27 first-quarter tanshin was not published at the research cut-off; on the company's calendar (13 November in both 2024 and 2025) it is expected around 13 November 2026, between cut-off and review date. It will show whether the conservative full-year guide is tracking, what the fire did to battery volumes, and whether the resource spread survived the autumn price plateau. Later datable catalysts: battery pre-processing restoration or partner disclosure, the new battery plant decision and the February 2027 interim print (first FY6/26 revision occasion).
内部研究类型:dated_catalyst_calendar
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The thesis resolves on prints within two quarters, not on narrative events.
不确定性(原始记录):Only the reporting cadence is calendar-fixed; restoration and plant decisions are event-driven.
F025|02|咨询和福利业务在缩小,处置方式是资本配置的试金石
研究范围:35项覆盖检查
写入正文:02|咨询和福利业务在缩小,处置方式是资本配置的试金石08|新电池工厂和外围业务考验配置纪律
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
The 'other' segment is shrinking: consulting orders down, welfare users down怎么使用:直接 / 支持;反向验证:03
En-Vision2035: the ten-year vision and its three priority businesses (briefing)怎么使用:直接 / 支持;一手验证:11
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域03)|The 'other' segment is shrinking: consulting orders down, welfare users down;直接证据 / 支持证据 / 一手证据(研究域11)|En-Vision2035: the ten-year vision and its three priority businesses (briefing)
完整研究记录(核对用)
研究原文:The other segment (sustainability consulting and disability-welfare services) shrank to sales of JPY 450 million and profit of JPY 40 million after a loss-making FY6/25, on fewer consulting orders and fewer welfare users. It sits outside the sorting-technology franchise that En-Vision2035 elevates; its retention is best explained by social-mission identity rather than economics.
内部研究类型:peripheral_business_test
内部来源标记:COVERAGE35
普通股东含义(原始记录):Its disposition (grow, hold, exit) is a clean test of the new presidency's capital-allocation discipline; economically immaterial today.
不确定性(原始记录):No management statement on the segment's strategic status.
F026|研究发现
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Subsequent events: none disclosed (tanshin, subsequent-events note)怎么使用:直接 / 支持;一手验证:30
AGM and payment calendar: results 13 August, AGM 29 September, dividend from 30 September怎么使用:直接 / 支持;专项深挖:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|Subsequent events: none disclosed (tanshin, subsequent-events note);直接证据 / 支持证据 / 定向深挖(研究域23)|AGM and payment calendar: results 13 August, AGM 29 September, dividend from 30 September
完整研究记录(核对用)
研究原文:The tanshin discloses no material subsequent events after the FY6/26 close, and the annual governance cycle (results 13 August, securities report 18 September, AGM 29 September, dividend payment from 30 September) is complete at the cut-off; the Q1 print is the only pending item.
内部研究类型:information_state
内部来源标记:COVERAGE35
普通股东含义(原始记录):The register's information set is clean; stale numbers are the main reader risk once Q1 prints.
不确定性(原始记录):Anything first published after the cut-off belongs to a later Review.
F027|01|要回答的问题:平价年份的底部盈利有没有抬高
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|要回答的问题:平价年份的底部盈利有没有抬高14|操作上暂不追高,等一季度财报和11月月线
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:直接 / 支持;一手验证:28、35;反向验证:12、22;专项深挖:35
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
ROIC estimates and cash conversion (JINGI computed indicators)怎么使用:直接 / 支持;一手验证:22;外部现实校验:27、28;专项深挖:12、27、28
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:直接证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域27) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域27) / 定向深挖(研究域28)|ROIC estimates and cash conversion (JINGI computed indicators);直接证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)
完整研究记录(核对用)
研究原文:Envipro is a family-controlled sorting-technology franchise whose earnings are a levered play on metal-price spreads, priced below book because the market capitalises the trough of that cycle and the opacity of a Standard-market, low-float register. The falsifiable core is the trough: if structural reform (deeper sorting, slag intake, portfolio mix) has lifted mid-cycle ordinary profit from JPY 1.2-1.9 billion toward JPY 2.5 billion or more, the FY6/27 guide, set with no price help and a crippled battery segment, will be met or beaten and the discount should narrow. If FY6/27 prints at or below guide with the spread merely flat, the FY6/26 surge was price and the register remains a cyclical at a fair price. Confirmation: guide beaten on flat prices and resource profit near JPY 2,900 million; falsification also includes battery drag extending into FY6/28 without a capacity decision.
内部研究类型:investment_thesis_with_falsification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Two quarters decide the position's core claim; price evidence and fundamental evidence resolve in the same weeks.
不确定性(原始记录):Conditional on unprinted FY6/27 evidence; Research confidence medium.
F028|09|股价是在为低谷盈利定价
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论09|股价是在为低谷盈利定价14|总分59.51/100,评级B,评分版本V3.2
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、21、35
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:直接 / 支持;外部现实校验:22
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接 / 支持;一手验证:18、19、21、29;外部现实校验:17
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:直接 / 支持;一手验证:17、20;外部现实校验:19
Dividend record and FY6/27 dividend forecast (tanshin dividend table)怎么使用:直接 / 支持;一手验证:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million;直接证据 / 支持证据|FY6/27 full-year forecast: higher sales, lower profit, published 13 August 2026;直接证据 / 支持证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and FY6/27 dividend forecast (tanshin dividend table)
完整研究记录(核对用)
研究原文:At the 6 November 2026 close: share price JPY 603; market capitalisation JPY 18.28 billion (603 x 30,317,388 issued shares, treasury not deducted); forecast PER 8.19x on FY6/27 forecast EPS of JPY 73.67; actual PBR 0.91x on FY6/26 net assets per share of JPY 659.26; FY6/26 ROE 13.6% as reported; forecast dividend yield 3.65% on JPY 22; EV/EBITDA 3.8x (EV JPY 17.34 billion after net cash of JPY 0.94 billion at 30 June 2026; EBITDA JPY 4.62 billion = operating profit JPY 3,224 million plus depreciation JPY 1,397 million). On peak earnings the register is optically cheap; on trough earnings fairly priced; a ~15x multiple of FY6/25 trough earnings versus ~7x FY6/26 shows the cycle in the multiple.
内部研究类型:valuation_snapshot
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Re-rating requires trough evidence, not peak repetition; the below-book price is the market's standing verdict on trough earnings and control.
不确定性(原始记录):Net cash differs by definition (JPY 0.94 billion in EV vs +JPY 619 million JINGI); market cap uses issued shares including ~6.0% treasury; PER is on company forecast EPS; no peer multiples or analyst consensus exist in the sources.
F029|07|家族握有约47.5%股份,少数股东承担折价
研究范围:开放研究
写入正文:07|家族握有约47.5%股份,少数股东承担折价09|股价是在为低谷盈利定价14|总分59.51/100,评级B,评分版本V3.2
归并到:F014
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:直接证据;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)
完整研究记录(核对用)
研究原文:Windelight Co., Ltd. (founding-family asset vehicle): largest shareholder at 38.03% of shares excluding treasury, anchoring the ~47.5% family bloc.
内部研究类型:related_company
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Permanent control: no contest or exit overhang from the bloc, but a governance discount for minorities.
不确定性(原始记录):Vehicle's own balance sheet and intentions undisclosed.
F030|04|利润和风险主要经由金属价格、一家承包商和关联公司收益传导
研究范围:开放研究+35项覆盖检查
写入正文:04|利润和风险主要经由金属价格、一家承包商和关联公司收益传导
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Group composition from the FY6/26 securities report: eleven consolidated subsidiaries怎么使用:直接证据;一手验证:06;外部现实校验:07
Listed-subsidiary linkage: Nitto Kako (5104) inside the register怎么使用:直接证据;一手验证:21;专项深挖:21
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 外部现实(研究域07)|Group composition from the FY6/26 securities report: eleven consolidated subsidiaries;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|Listed-subsidiary linkage: Nitto Kako (5104) inside the register
完整研究记录(核对用)
研究原文:Nitto Kako Co., Ltd. (TSE Standard 5104): consolidated listed rubber-products subsidiary inside the resource segment, with a stated FY6/27 capacity expansion in the second half.
内部研究类型:related_company
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Supplies the rubber profit stream and a separately priced listed stake inside the parent's register.
不确定性(原始记录):Minority interest share and subsidiary profit contribution not isolated.
F031|04|利润和风险主要经由金属价格、一家承包商和关联公司收益传导
研究范围:开放研究+35项覆盖检查
写入正文:04|利润和风险主要经由金属价格、一家承包商和关联公司收益传导
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure怎么使用:直接证据;一手验证:07、16
Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur怎么使用:直接证据;外部现实校验:02;反向验证:14
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 一手证据(研究域16)|FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure;直接证据 / 外部现实(研究域02) / 反证(研究域14)|Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur
完整研究记录(核对用)
研究原文:Abizu Co., Ltd. and Fuji Ecocycle Co., Ltd. (equity-method affiliates inside the resource segment): combined equity income rose from JPY 390 million to JPY 514 million, 14% of consolidated ordinary profit.
内部研究类型:related_company
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A material, lightly disclosed contributor whose accounts are not consolidated.
不确定性(原始记录):Affiliate financials and dividend policy to the parent unknown.
F032|04|利润和风险主要经由金属价格、一家承包商和关联公司收益传导
研究范围:开放研究
写入正文:04|利润和风险主要经由金属价格、一家承包商和关联公司收益传导
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:直接证据;一手验证:02;外部现实校验:16
FY6/26 briefing: price backdrop and the accounting reason sales fell怎么使用:直接证据;一手验证:05、08、11、15;外部现实校验:12、14
Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels怎么使用:直接证据;一手验证:14;外部现实校验:03、05、06、08、11、12;反向验证:05
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;直接证据 / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域11) / 一手证据(研究域15) / 外部现实(研究域12) / 外部现实(研究域14)|FY6/26 briefing: price backdrop and the accounting reason sales fell;直接证据 / 一手证据(研究域14) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 反证(研究域05)|Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels
完整研究记录(核对用)
研究原文:Domestic scrap and global metal prices (iron scrap average JPY 45,616/t, +6.8%; copper, gold and silver at record highs in FY6/26) set the purchase-sale spread.
内部研究类型:external_driver
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The single largest profit variable: +JPY 2,335 million in FY6/26, negative through FY6/23-25.
不确定性(原始记录):Whether FY6/26 marks a cycle top or a plateau is unknown.
F033|03|炉渣回收是资本最轻的增长腿,但看不到它的单独利润
研究范围:开放研究+35项覆盖检查
写入正文:03|炉渣回收是资本最轻的增长腿,但看不到它的单独利润
归并到:F019
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Precious-metal slag business: March 2026 ministry guideline revision (briefing)怎么使用:直接证据;一手验证:10、13
Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)怎么使用:直接证据;一手验证:05、09;外部现实校验:13;专项深挖:09
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域10) / 一手证据(研究域13)|Precious-metal slag business: March 2026 ministry guideline revision (briefing);直接证据 / 一手证据(研究域05) / 一手证据(研究域09) / 外部现实(研究域13) / 定向深挖(研究域09)|Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)
完整研究记录(核对用)
研究原文:Ministry of the Environment waste-facility guidelines, March 2026 revision (first since November 2013), documenting fly-ash resource recovery in the official procurement specification handbook.
内部研究类型:policy_driver
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Turns a decade of municipal development into a standards-backed intake channel; a one-way ratchet.
不确定性(原始记录):Pace of municipal adoption and any further revisions unknown; evidence is issuer-reported.
F034|03|被定为2030年后增长担当的电池回收,眼下被承包商火灾卡住
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论03|被定为2030年后增长担当的电池回收,眼下被承包商火灾卡住11|电池恢复延期和物流、汇率是次一级的风险12|指引的保守程度,集中在公司控制不了的地方14|总分59.51/100,评级B,评分版本V3.2
归并到:F007
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接证据;一手验证:06;外部现实校验:30;反向验证:30、35
Safety and dependency: the fire's lesson as management states it (briefing)怎么使用:直接证据;反向验证:06、07、13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 反证(研究域06) / 反证(研究域07) / 反证(研究域13)|Safety and dependency: the fire's lesson as management states it (briefing)
完整研究记录(核对用)
研究原文:The lithium-ion battery pre-processing contractor (fire site, unnamed): the outsourced route whose June 2026 fire destroyed stored inventory and restricted capacity into FY6/27.
内部研究类型:supplier_dependency
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Demonstrated single-point failure behind the battery profit swing from JPY 704 million to JPY 50 million.
不确定性(原始记录):Identity, restart conditions and partner bench undisclosed.
F035|07|家族握有约47.5%股份,少数股东承担折价
研究范围:开放研究
写入正文:07|家族握有约47.5%股份,少数股东承担折价09|股价是在为低谷盈利定价14|总分59.51/100,评级B,评分版本V3.2
归并到:F014
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025怎么使用:直接证据;一手验证:01、13、33;反向验证:01、09
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域13) / 一手证据(研究域33) / 反证(研究域01) / 反证(研究域09)|JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025
完整研究记录(核对用)
研究原文:Tokyo Stock Exchange Standard market: listing venue since the 18 September 2025 transfer from Prime, with thinner institutional sponsorship and liquidity.
内部研究类型:market_venue
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):A structural component of the discount alongside family control and 42% float.
不确定性(原始记录):No Prime return path disclosed.
F036|05|优势有,但耐久性要等平价年份的数据证明
研究范围:开放研究+35项覆盖检查
归并到:F021
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
AI sorting co-development with Earth Technica (briefing)怎么使用:直接证据;一手验证:04、07;专项深挖:04
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域07) / 定向深挖(研究域04)|AI sorting co-development with Earth Technica (briefing)
完整研究记录(核对用)
研究原文:Earth Technica Co., Ltd. (plant engineering): joint-development partner of about four years for the AI sorting line.
内部研究类型:technology_partner
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Technology roadmap defending the sorting moat against a skilled-operator shortage; no current P&L contribution.
不确定性(原始记录):Deployment timing and recovery-rate claims undisclosed.
F037|03|聚合物循环是十年期的选项,投入先于收益
研究范围:开放研究+35项覆盖检查
归并到:F020
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing)怎么使用:直接证据;专项深挖:07
查看完整证据标签(核对用)
直接证据 / 定向深挖(研究域07)|Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing)
完整研究记录(核对用)
研究原文:Ebara Environmental Plant Co., Ltd.: partner in the chemical-recycling demonstration for the polymer business, with Envipro managing feedstock procurement.
内部研究类型:industrial_partner
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Industrial-scale validation partner for a demonstration-stage leg.
不确定性(原始记录):Economics undisclosed.
F038|13|一季度财报说明全年指引在按进度走吗
研究范围:开放研究+35项覆盖检查
写入正文:13|一季度财报说明全年指引在按进度走吗
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Disclosure chronology: first-quarter results habitually land on 13 November怎么使用:直接 / 支持;一手验证:30
Subsequent events: none disclosed (tanshin, subsequent-events note)怎么使用:直接 / 支持;一手验证:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|Disclosure chronology: first-quarter results habitually land on 13 November;直接证据 / 支持证据 / 一手证据(研究域30)|Subsequent events: none disclosed (tanshin, subsequent-events note)
完整研究记录(核对用)
研究原文:The FY6/27 first-quarter tanshin (expected around 13 November 2026) had not been published at the cut-off. When it prints: is the quarter tracking the conservative full-year guide, and what does it disclose about battery volumes under the capacity constraint? Opposite answers separate a floor-setting guide from a ceiling.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Highest-priority next-Review starting point; resolves in days.
不确定性(原始记录):Future disclosure first public after the cut-off; belongs to a later Review.
F039|13|电池产能何时恢复,新工厂花多少钱
研究范围:开放研究+35项覆盖检查
写入正文:13|电池产能何时恢复,新工厂花多少钱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
Battery-recycling recovery actions and the new-plant project (briefing)怎么使用:直接证据;专项深挖:06、11、20、30
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:直接 / 支持;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 定向深挖(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域20) / 定向深挖(研究域30)|Battery-recycling recovery actions and the new-plant project (briefing);直接证据 / 支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)
完整研究记录(核对用)
研究原文:Battery capacity: when does the fire-damaged contractor route restart or which additional partners come online, what is the final insurance settlement against estimated proceeds in the FY6/27 forecast, and what capacity, capex, timing and funding will the new battery plant carry from the now net-cash balance sheet?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Moves consolidated forecast directly and determines the post-2030 growth carrier's timeline.
不确定性(原始记录):No committed recovery date; settlement estimates only.
F040|13|价格从高位回调后,价差还能保留多少
研究范围:开放研究+35项覆盖检查
写入正文:13|价格从高位回调后,价差还能保留多少
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/26 segment results (segment profit reconciles to ordinary profit)怎么使用:直接证据;一手验证:02、32
Segment comparatives, FY6/25: the profit step-up measured against the soft year怎么使用:直接证据;专项深挖:01;同业比较:03、06、07、15、16、19、20、32;其他用途:历史
Revenue-recognition change in the trading book, from the segment commentary怎么使用:直接证据;一手验证:15、32
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:支持证据;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:支持证据;一手验证:02;外部现实校验:16
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:支持证据;一手验证:18、19、21、29;外部现实校验:17
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 一手证据(研究域02) / 一手证据(研究域32)|FY6/26 segment results (segment profit reconciles to ordinary profit);直接证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域01)|Segment comparatives, FY6/25: the profit step-up measured against the soft year;直接证据 / 一手证据(研究域15) / 一手证据(研究域32)|Revenue-recognition change in the trading book, from the segment commentary;支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build
完整研究记录(核对用)
研究原文:If iron-scrap and precious-metal prices correct from record levels, how much of the resource segment's spread survives (FY6/23-25 ordinary profit 1,902 / 1,783 / 1,216 million is the downside template; is the trough now higher?), and how much of the trading profit step-up (JPY 270 million to JPY 703 million) survives spread normalisation given that the netting change makes the book's scale harder to read?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The trough question that sets the valuation.
不确定性(原始记录):Resolved only by flat- or falling-price quarters.
F041|13|管理层会不会给En-Vision2035设置可度量的中间指标
研究范围:开放研究
写入正文:13|管理层会不会给En-Vision2035设置可度量的中间指标
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine怎么使用:直接 / 支持;一手验证:23、31;反向验证:23、33;同业比较:13、31;其他用途:历史
Capital-efficiency doctrine in the securities report: beat the ~10% cost of equity every year怎么使用:支持证据;一手验证:22;专项深挖:22、25
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:支持证据;一手验证:28、35;反向验证:12、22;专项深挖:35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域11)|En-Vision2035: the ten-year vision and its three priority businesses (briefing);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域31) / 历史/同业比较(研究域13) / 历史/同业比较(研究域31) / 反证(研究域23) / 反证(研究域33)|FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine;支持证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域25)|Capital-efficiency doctrine in the securities report: beat the ~10% cost of equity every year;支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)
完整研究记录(核对用)
研究原文:Under the withdrawn-plan doctrine, will management publish any measurable intermediate markers for En-Vision2035 (intake volumes, segment returns, slag contracts), or does the single-year plan remain the only gradeable promise through 2036?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Determines whether long-horizon growth legs can be graded at all.
不确定性(原始记录):Management intent unknown.
F042|13|净现金和低于账面的股价会不会被转成每股价值
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(9项,重复标签已合并)
Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26)怎么使用:直接 / 支持;外部现实校验:25
Share count, treasury stock and dilution at the FY6/26 close怎么使用:直接证据;一手验证:25;反向验证:25
Listed-subsidiary linkage: Nitto Kako (5104) inside the register怎么使用:直接证据;一手验证:21;专项深挖:21
The 'other' segment is shrinking: consulting orders down, welfare users down怎么使用:直接 / 支持;反向验证:03
Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing)怎么使用:支持证据;一手验证:25、26
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:支持证据;一手验证:01、23、24
The holding company is thin: 61 standalone employees; group scale from operating subsidiaries怎么使用:支持证据;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域25)|Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26);直接证据 / 一手证据(研究域25) / 反证(研究域25)|Share count, treasury stock and dilution at the FY6/26 close;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|Listed-subsidiary linkage: Nitto Kako (5104) inside the register;直接证据 / 支持证据 / 反证(研究域03)|The 'other' segment is shrinking: consulting orders down, welfare users down;支持证据 / 一手证据(研究域26)|Dividend record and FY6/27 dividend forecast (tanshin dividend table);支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing);支持证据 / 一手证据(研究域11)|En-Vision2035: the ten-year vision and its three priority businesses (briefing);支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info);支持证据 / 外部现实(研究域23)|The holding company is thin: 61 standalone employees; group scale from operating subsidiaries
完整研究记录(核对用)
研究原文:Capital allocation beyond the DOE floor: with net cash positive, treasury stock at ~6% of issued shares and the price below book, does the buyback pace re-accelerate toward FY6/25's JPY 789 million, and does the new presidency change the treatment of the listed subsidiary Nitto Kako, the shrinking consulting/welfare businesses or the treasury-stock position?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Decides whether net cash and a below-book price are converted into per-share value.
不确定性(原始记录):No stated target for leverage, cash level or buyback pace.
F043|13|炉渣和市政合同什么时候能被量化
研究范围:开放研究+35项覆盖检查
写入正文:13|炉渣和市政合同什么时候能被量化
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Precious-metal slag business: March 2026 ministry guideline revision (briefing)怎么使用:直接 / 支持;一手验证:10、13
Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)怎么使用:直接 / 支持;一手验证:05、09;外部现实校验:13;专项深挖:09
Precious-metal slag mechanics: two axes - grade and intake (briefing)怎么使用:直接 / 支持;专项深挖:10、13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域13)|Precious-metal slag business: March 2026 ministry guideline revision (briefing);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域09) / 外部现实(研究域13) / 定向深挖(研究域09)|Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing);直接证据 / 支持证据 / 定向深挖(研究域10) / 定向深挖(研究域13)|Precious-metal slag mechanics: two axes - grade and intake (briefing)
完整研究记录(核对用)
研究原文:Municipal and slag conversion: when do the first general-waste function contracts (including ash recovery) reach disclosure at what scale relative to the resource segment's JPY 23,940 million sales base, how quickly do municipal contracts turn the March 2026 guideline revision into tonnage, and will the slag business's revenue or profit ever be disclosed separately?
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The designated near-term growth carrier cannot currently be sized.
不确定性(原始记录):No contract-level volumes or timelines disclosed.
F044|10|价格与业绩公布的先后:价格在两个方向上都先于账面
研究范围:开放研究+35项覆盖检查
写入正文:10|价格与业绩公布的先后:价格在两个方向上都先于账面11|催化剂按财报日期排好,其余靠事件12|账面和价格在不同时间说出了不同的话13|价格要看的下一批证据
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(10项,重复标签已合并)
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:直接证据;外部现实校验:22
Disclosure chronology: first-quarter results habitually land on 13 November怎么使用:直接 / 支持;一手验证:30
Subsequent events: none disclosed (tanshin, subsequent-events note)怎么使用:直接 / 支持;一手验证:30
Assembled monthly price history, September 2013 - October 2026 (158 bars)怎么使用:直接证据;外部现实校验:34
The generational path: two failed spikes before the 2025 base怎么使用:直接证据;一手验证:34
The 2026 pulse and its failure to retain: May high 1,253, five consecutive lower closes怎么使用:直接证据;一手验证:34
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:支持证据;一手验证:27、31;外部现实校验:01、09、21、35
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:支持证据;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026;直接证据|FY6/27 full-year forecast: higher sales, lower profit, published 13 August 2026;直接证据 / 支持证据 / 一手证据(研究域30)|Disclosure chronology: first-quarter results habitually land on 13 November;直接证据 / 支持证据 / 一手证据(研究域30)|Subsequent events: none disclosed (tanshin, subsequent-events note);直接证据 / 外部现实(研究域34)|Assembled monthly price history, September 2013 - October 2026 (158 bars);直接证据 / 一手证据(研究域34)|The generational path: two failed spikes before the 2025 base;直接证据 / 一手证据(研究域34)|The 2026 pulse and its failure to retain: May high 1,253, five consecutive lower closes;直接证据 / 外部现实(研究域34)|Daily cross-check: fiscal-year range and the 6 November 2026 close of JPY 603;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million;支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)
完整研究记录(核对用)
研究原文:Fundamental-lane and Technical-lane evidence are both pending in the same weeks: the accounts printed a record FY6/26 in August 2026 and guided down, the market price kept declining after that print, and the deciding fundamental evidence (the Q1 tanshin around 13 November 2026) coincides with the deciding evidence the Technical lane itself defines. This node records only timing coincidence and the accounts/price gap; the independent Technical State is read by dereferencing the protected structure and is neither confirmed nor altered by Fundamental positivity.
内部研究类型:cross_lane_timing_context
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):Sizing should respect that both verdicts are pending and arrive together; a good fundamental print does not override a non-confirming price state.
不确定性(原始记录):Event-response inference rests on a small number of dated events; no independent evidence the market anticipated undisclosed information.
F045|07|家族握有约47.5%股份,少数股东承担折价
研究范围:开放研究
写入正文:07|家族握有约47.5%股份,少数股东承担折价09|股价是在为低谷盈利定价14|总分59.51/100,评级B,评分版本V3.2
归并到:F014
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:直接 / 支持;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)
完整研究记录(核对用)
研究原文:Windelight's 38.03% stake anchors permanent family control: stable, no contest, but a governance discount for minorities.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F046|04|利润和风险主要经由金属价格、一家承包商和关联公司收益传导
研究范围:开放研究+35项覆盖检查
写入正文:04|利润和风险主要经由金属价格、一家承包商和关联公司收益传导
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Group composition from the FY6/26 securities report: eleven consolidated subsidiaries怎么使用:直接证据;一手验证:06;外部现实校验:07
Segment revenue composition (external sales by product line), FY6/26 segment note怎么使用:直接 / 支持;一手验证:03;外部现实校验:02、15;专项深挖:03
Listed-subsidiary linkage: Nitto Kako (5104) inside the register怎么使用:直接证据;一手验证:21;专项深挖:21
FY6/26 briefing: price backdrop and the accounting reason sales fell怎么使用:支持证据;一手验证:05、08、11、15;外部现实校验:12、14
Revenue-recognition change in the trading book, from the segment commentary怎么使用:支持证据;一手验证:15、32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 外部现实(研究域07)|Group composition from the FY6/26 securities report: eleven consolidated subsidiaries;直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域02) / 外部现实(研究域15) / 定向深挖(研究域03)|Segment revenue composition (external sales by product line), FY6/26 segment note;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|Listed-subsidiary linkage: Nitto Kako (5104) inside the register;支持证据 / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域11) / 一手证据(研究域15) / 外部现实(研究域12) / 外部现实(研究域14)|FY6/26 briefing: price backdrop and the accounting reason sales fell;支持证据 / 一手证据(研究域15) / 一手证据(研究域32)|Revenue-recognition change in the trading book, from the segment commentary
完整研究记录(核对用)
研究原文:Nitto Kako supplies the rubber stream (the resource segment's largest external revenue line) and a separately priced listed stake inside the parent's register.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F047|02|资源回收是利润发动机,资产只多了8.6%
研究范围:开放研究
归并到:F004
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure怎么使用:直接证据;一手验证:07、16
Segment comparatives, FY6/25: the profit step-up measured against the soft year怎么使用:直接 / 支持;专项深挖:01;同业比较:03、06、07、15、16、19、20、32;其他用途:历史
Segment assets, depreciation and capex by segment, FY6/26 segment note怎么使用:支持证据;外部现实校验:20
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域07) / 一手证据(研究域16)|FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure;直接证据 / 支持证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域01)|Segment comparatives, FY6/25: the profit step-up measured against the soft year;支持证据 / 外部现实(研究域20)|Segment assets, depreciation and capex by segment, FY6/26 segment note
完整研究记录(核对用)
研究原文:Equity income of JPY 514 million (14% of ordinary profit) from Abizu and Fuji Ecocycle sits entirely in the resource segment; ordinary-profit quality depends partly on unconsolidated affiliates.
内部研究类型:OTHER_RELATED_COMPANY
内部来源标记:OPEN_DISCOVERY
F048|02|同样的吨位,赚的是买进废料与卖出再生材料之间的价差
研究范围:开放研究
写入正文:02|同样的吨位,赚的是买进废料与卖出再生材料之间的价差06|现金流五年为正,但利润的一部分压在库存和应收款里
归并到:F077
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:直接 / 支持;一手验证:02;外部现实校验:16
FY6/26 briefing: price backdrop and the accounting reason sales fell怎么使用:直接证据;一手验证:05、08、11、15;外部现实校验:12、14
Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels怎么使用:直接证据;一手验证:14;外部现实校验:03、05、06、08、11、12;反向验证:05
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:支持证据;外部现实校验:22
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:支持证据;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:支持证据;一手验证:18、19、21、29;外部现实校验:17
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;直接证据 / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域11) / 一手证据(研究域15) / 外部现实(研究域12) / 外部现实(研究域14)|FY6/26 briefing: price backdrop and the accounting reason sales fell;直接证据 / 一手证据(研究域14) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 反证(研究域05)|Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels;支持证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026;支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build
完整研究记录(核对用)
研究原文:The metal-price complex sets the spread: it added JPY 2,335 million in FY6/26 and subtracted through FY6/23-25.
内部研究类型:END_MARKET
内部来源标记:OPEN_DISCOVERY
F049|03|炉渣回收是资本最轻的增长腿,但看不到它的单独利润
研究范围:开放研究+35项覆盖检查
写入正文:03|炉渣回收是资本最轻的增长腿,但看不到它的单独利润
归并到:F019
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Precious-metal slag business: March 2026 ministry guideline revision (briefing)怎么使用:直接 / 支持;一手验证:10、13
Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)怎么使用:直接 / 支持;一手验证:05、09;外部现实校验:13;专项深挖:09
Precious-metal slag mechanics: two axes - grade and intake (briefing)怎么使用:支持证据;专项深挖:10、13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域13)|Precious-metal slag business: March 2026 ministry guideline revision (briefing);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域09) / 外部现实(研究域13) / 定向深挖(研究域09)|Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing);支持证据 / 定向深挖(研究域10) / 定向深挖(研究域13)|Precious-metal slag mechanics: two axes - grade and intake (briefing)
完整研究记录(核对用)
研究原文:The March 2026 guideline revision formalises the slag business's municipal market and gives the capital-lightest growth leg a standards-backed intake channel.
内部研究类型:POLICY
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F050|03|被定为2030年后增长担当的电池回收,眼下被承包商火灾卡住
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论03|被定为2030年后增长担当的电池回收,眼下被承包商火灾卡住11|电池恢复延期和物流、汇率是次一级的风险12|指引的保守程度,集中在公司控制不了的地方14|总分59.51/100,评级B,评分版本V3.2
归并到:F007
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:支持证据;一手验证:35
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:支持证据;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing);支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)
完整研究记录(核对用)
研究原文:The outsourced pre-processing route is the demonstrated single-point failure: battery profit guided from JPY 704 million to JPY 50 million until capacity is restored or replaced.
内部研究类型:SUPPLIER
内部来源标记:OPEN_DISCOVERY
F051|07|家族握有约47.5%股份,少数股东承担折价
研究范围:开放研究
写入正文:07|家族握有约47.5%股份,少数股东承担折价09|股价是在为低谷盈利定价14|总分59.51/100,评级B,评分版本V3.2
归并到:F014
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025怎么使用:直接证据;一手验证:01、13、33;反向验证:01、09
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:支持证据;一手验证:27、31;外部现实校验:01、09、21、35
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:支持证据;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域13) / 一手证据(研究域33) / 反证(研究域01) / 反证(研究域09)|JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million;支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)
完整研究记录(核对用)
研究原文:The Standard-market venue is a structural component of the valuation discount alongside family control and 42% float.
内部研究类型:POLICY
内部来源标记:OPEN_DISCOVERY
F052|05|优势有,但耐久性要等平价年份的数据证明
研究范围:开放研究+35项覆盖检查
归并到:F021
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
AI sorting co-development with Earth Technica (briefing)怎么使用:直接证据;一手验证:04、07;专项深挖:04
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域07) / 定向深挖(研究域04)|AI sorting co-development with Earth Technica (briefing)
完整研究记录(核对用)
研究原文:The AI sorting co-development is the roadmap for defending the sorting moat against the skilled-operator shortage, with no current P&L contribution.
内部研究类型:TECHNOLOGY
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F053|01|要回答的问题:平价年份的底部盈利有没有抬高
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|要回答的问题:平价年份的底部盈利有没有抬高11|什么会推翻这个判断
归并到:F082
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Disclosure chronology: first-quarter results habitually land on 13 November怎么使用:直接 / 支持;一手验证:30
Subsequent events: none disclosed (tanshin, subsequent-events note)怎么使用:直接 / 支持;一手验证:30
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:支持证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|Disclosure chronology: first-quarter results habitually land on 13 November;直接证据 / 支持证据 / 一手证据(研究域30)|Subsequent events: none disclosed (tanshin, subsequent-events note);支持证据|FY6/27 full-year forecast: higher sales, lower profit, published 13 August 2026;支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)
完整研究记录(核对用)
研究原文:The unprinted Q1 tanshin is the nearest dated test of the conservative FY6/27 guide and of post-fire battery volumes; tracking or beating validates the floor-setting reading.
内部研究类型:END_MARKET_TEST
内部来源标记:OPEN_DISCOVERY
F054|03|聚合物循环是十年期的选项,投入先于收益
研究范围:开放研究+35项覆盖检查
归并到:F020
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing)怎么使用:直接 / 支持;专项深挖:07
查看完整证据标签(核对用)
直接证据 / 支持证据 / 定向深挖(研究域07)|Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing);支持证据 / 一手证据(研究域11)|En-Vision2035: the ten-year vision and its three priority businesses (briefing)
完整研究记录(核对用)
研究原文:The Ebara demonstration gives the polymer leg an industrial-scale validation partner; economics are demonstration-stage and undisclosed.
内部研究类型:CUSTOMER
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F055|08|分红下限让收入更稳,回购节奏则随意
研究范围:开放研究+35项覆盖检查
写入正文:08|分红下限让收入更稳,回购节奏则随意
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing)怎么使用:直接 / 支持;一手验证:25、26
Dividend history: the JPY 6 trough of FY6/24 and the return to JPY 25怎么使用:直接证据;外部现实校验:26;专项深挖:26;同业比较:25、26;其他用途:历史
FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine怎么使用:支持证据;一手验证:23、31;反向验证:23、33;同业比较:13、31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing);直接证据 / 外部现实(研究域26) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 定向深挖(研究域26)|Dividend history: the JPY 6 trough of FY6/24 and the return to JPY 25;支持证据 / 一手证据(研究域26)|Dividend record and FY6/27 dividend forecast (tanshin dividend table);支持证据 / 一手证据(研究域23) / 一手证据(研究域31) / 历史/同业比较(研究域13) / 历史/同业比较(研究域31) / 反证(研究域23) / 反证(研究域33)|FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine
完整研究记录(核对用)
研究原文:The 2.5% DOE floor plus opportunistic buybacks is the capital-return constitution of the post-plan doctrine, stabilising income through the cycle and disciplining the net-cash balance sheet.
内部研究类型:CAPITAL_POLICY_IMPLEMENTATION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F056|02|同样的吨位,赚的是买进废料与卖出再生材料之间的价差
研究范围:开放研究
写入正文:02|同样的吨位,赚的是买进废料与卖出再生材料之间的价差06|现金流五年为正,但利润的一部分压在库存和应收款里
归并到:F077
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:直接 / 支持;一手验证:02;外部现实校验:16
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure怎么使用:支持证据;一手验证:07、16
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:支持证据;外部现实校验:22
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);支持证据 / 一手证据(研究域07) / 一手证据(研究域16)|FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure;支持证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026
完整研究记录(核对用)
研究原文:The price-spread option mechanism explains why volume fell while profit tripled.
内部研究类型:explains
内部来源标记:OPEN_DISCOVERY
F057|06|现金流五年为正,但利润的一部分压在库存和应收款里
研究范围:开放研究+35项覆盖检查
写入正文:06|现金流五年为正,但利润的一部分压在库存和应收款里11|价差回落时,利润下降和现金释放会同时发生12|账面和价格在不同时间说出了不同的话
归并到:F079
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:直接 / 支持;一手验证:02;外部现实校验:16
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
Working capital absorbed the profit: inventories and receivables built at high prices怎么使用:直接 / 支持;一手验证:19;反向验证:02、08、15、16、17、19、29;专项深挖:19
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:支持证据;一手验证:18、19、21、29;外部现实校验:17
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:支持证据;一手验证:17、20;外部现实校验:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 支持证据 / 一手证据(研究域19) / 反证(研究域02) / 反证(研究域08) / 反证(研究域15) / 反证(研究域16) / 反证(研究域17) / 反证(研究域19) / 反证(研究域29) / 定向深挖(研究域19)|Working capital absorbed the profit: inventories and receivables built at high prices;支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million
完整研究记录(核对用)
研究原文:The same spread that produced FY6/26 profit created working-capital positions at record prices that unwind against margins in a correction.
内部研究类型:reversal_risk_and_balance_sheet_shadow
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F058|01|2027年6月期指引按平价、带着电池拖累来定
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|2027年6月期指引按平价、带着电池拖累来定07|撤回中期计划后,每一份单年计划就是承诺12|撤回中期计划,反而抬高了考核标准12|指引的保守程度,集中在公司控制不了的地方
归并到:F008
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:直接 / 支持;一手验证:35
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:支持证据;一手验证:28、35;反向验证:12、22;专项深挖:35
The 30 July 2026 revision: forecast and dividend raised ahead of the annual print怎么使用:支持证据;外部现实校验:31;反向验证:31;专项深挖:31;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing);直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);支持证据|FY6/27 full-year forecast: higher sales, lower profit, published 13 August 2026;支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);支持证据 / 外部现实(研究域31) / 历史/同业比较(研究域30) / 反证(研究域31) / 定向深挖(研究域31)|The 30 July 2026 revision: forecast and dividend raised ahead of the annual print
完整研究记录(核对用)
研究原文:The fire-constrained battery segment is one of the two stated reasons for the FY6/27 profit decline and is where the guide's conservatism cannot be controlled by management.
内部研究类型:constrains
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F059|09|估值的分歧归结为底部盈利是15亿还是25亿日元
研究范围:开放研究+35项覆盖检查
写入正文:09|估值的分歧归结为底部盈利是15亿还是25亿日元14|操作上暂不追高,等一季度财报和11月月线
归并到:F015
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:直接 / 支持;一手验证:28、35;反向验证:12、22;专项深挖:35
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:支持证据;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
The 30 July 2026 revision: forecast and dividend raised ahead of the annual print怎么使用:支持证据;外部现实校验:31;反向验证:31;专项深挖:31;同业比较:30;其他用途:历史
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:支持证据;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;支持证据 / 外部现实(研究域31) / 历史/同业比较(研究域30) / 反证(研究域31) / 定向深挖(研究域31)|The 30 July 2026 revision: forecast and dividend raised ahead of the annual print;支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)
完整研究记录(核对用)
研究原文:A price-blind guide above every soft-year outcome is management's implicit claim that the mid-cycle floor rose.
内部研究类型:implicit_claim_about
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F060|01|要回答的问题:平价年份的底部盈利有没有抬高
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|要回答的问题:平价年份的底部盈利有没有抬高11|什么会推翻这个判断
归并到:F082
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:直接 / 支持;一手验证:28、35;反向验证:12、22;专项深挖:35
ROIC estimates and cash conversion (JINGI computed indicators)怎么使用:直接 / 支持;一手验证:22;外部现实校验:27、28;专项深挖:12、27、28
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:支持证据;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域27) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域27) / 定向深挖(研究域28)|ROIC estimates and cash conversion (JINGI computed indicators);支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013
完整研究记录(核对用)
研究原文:The trough height is the falsifiable core of the Thesis.
内部研究类型:falsifiable_core_of
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F061|07|家族握有约47.5%股份,少数股东承担折价
研究范围:开放研究
写入正文:07|家族握有约47.5%股份,少数股东承担折价09|股价是在为低谷盈利定价
归并到:F081
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:直接 / 支持;一手验证:01、23、24
JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025怎么使用:直接证据;一手验证:01、13、33;反向验证:01、09
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、21、35
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:支持证据;外部现实校验:22
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:支持证据;一手验证:18、19、21、29;外部现实校验:17
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:支持证据;一手验证:17、20;外部现实校验:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info);直接证据 / 一手证据(研究域01) / 一手证据(研究域13) / 一手证据(研究域33) / 反证(研究域01) / 反证(研究域09)|JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million;支持证据|FY6/27 full-year forecast: higher sales, lower profit, published 13 August 2026;支持证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026;支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million;支持证据 / 一手证据(研究域26)|Dividend record and FY6/27 dividend forecast (tanshin dividend table)
完整研究记录(核对用)
研究原文:Family control, ~42% float and the Standard venue explain why the register trades at 0.91x book after a 13.6% ROE year.
内部研究类型:sets_discount
内部来源标记:OPEN_DISCOVERY
F062|09|隐含资产是选择权,不是估值支柱
研究范围:35项覆盖检查
写入正文:09|隐含资产是选择权,不是估值支柱
归并到:F022
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million怎么使用:直接 / 支持;一手验证:20;反向验证:04、10、20
Retirement and restoration obligations: the quiet liabilities怎么使用:直接 / 支持;外部现实校验:18;反向验证:18、21
Listed-subsidiary linkage: Nitto Kako (5104) inside the register怎么使用:直接 / 支持;一手验证:21;专项深挖:21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20) / 反证(研究域04) / 反证(研究域10) / 反证(研究域20)|Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million;直接证据 / 支持证据 / 外部现实(研究域18) / 反证(研究域18) / 反证(研究域21)|Retirement and restoration obligations: the quiet liabilities;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21)|Listed-subsidiary linkage: Nitto Kako (5104) inside the register
完整研究记录(核对用)
研究原文:Unmarked land, securities and written-down plant add optionality but no revaluation evidence; they are not a valuation pillar.
内部研究类型:qualifies_as_optionality
内部来源标记:COVERAGE35
F063|07|撤回中期计划后,每一份单年计划就是承诺
研究范围:开放研究+35项覆盖检查
写入正文:07|撤回中期计划后,每一份单年计划就是承诺08|新电池工厂和外围业务考验配置纪律12|撤回中期计划,反而抬高了考核标准
归并到:F009
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine怎么使用:直接 / 支持;一手验证:23、31;反向验证:23、33;同业比较:13、31;其他用途:历史
Capital-efficiency doctrine in the securities report: beat the ~10% cost of equity every year怎么使用:直接 / 支持;一手验证:22;专项深挖:22、25
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:支持证据;一手验证:28、35;反向验证:12、22;专项深挖:35
The 30 July 2026 revision: forecast and dividend raised ahead of the annual print怎么使用:支持证据;外部现实校验:31;反向验证:31;专项深挖:31;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域31) / 历史/同业比较(研究域13) / 历史/同业比较(研究域31) / 反证(研究域23) / 反证(研究域33)|FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域25)|Capital-efficiency doctrine in the securities report: beat the ~10% cost of equity every year;直接证据|FY6/27 positioned as a base-building year: investment continues through the forecast decline (briefing);支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);支持证据 / 外部现实(研究域31) / 历史/同业比较(研究域30) / 反证(研究域31) / 定向深挖(研究域31)|The 30 July 2026 revision: forecast and dividend raised ahead of the annual print
完整研究记录(核对用)
研究原文:With multi-year targets withdrawn, the single-year guide is the only gradeable commitment, so its conservative construction is itself a governance signal.
内部研究类型:makes_plan_the_promise
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F064|02|资源回收是利润发动机,资产只多了8.6%
研究范围:35项覆盖检查
归并到:F004
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Segment comparatives, FY6/25: the profit step-up measured against the soft year怎么使用:直接 / 支持;专项深挖:01;同业比较:03、06、07、15、16、19、20、32;其他用途:历史
Segment assets, depreciation and capex by segment, FY6/26 segment note怎么使用:直接 / 支持;外部现实校验:20
Management's framing of FY6/26: structural-reform results, not only market luck (briefing)怎么使用:直接证据;一手验证:04、10;专项深挖:02、16
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:支持证据;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:支持证据;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域01)|Segment comparatives, FY6/25: the profit step-up measured against the soft year;直接证据 / 支持证据 / 外部现实(研究域20)|Segment assets, depreciation and capex by segment, FY6/26 segment note;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域16)|Management's framing of FY6/26: structural-reform results, not only market luck (briefing);支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013
完整研究记录(核对用)
研究原文:Whether resource-segment return on a barely grown asset base stays near the FY6/26 level when prices stop helping is the operational test of a raised floor.
内部研究类型:tests
内部来源标记:COVERAGE35
F065|03|炉渣回收是资本最轻的增长腿,但看不到它的单独利润
研究范围:35项覆盖检查
写入正文:03|炉渣回收是资本最轻的增长腿,但看不到它的单独利润
归并到:F019
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Precious-metal slag mechanics: two axes - grade and intake (briefing)怎么使用:直接 / 支持;专项深挖:10、13
Precious-metal slag business: March 2026 ministry guideline revision (briefing)怎么使用:直接 / 支持;一手验证:10、13
Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)怎么使用:支持证据;一手验证:05、09;外部现实校验:13;专项深挖:09
查看完整证据标签(核对用)
直接证据 / 支持证据 / 定向深挖(研究域10) / 定向深挖(研究域13)|Precious-metal slag mechanics: two axes - grade and intake (briefing);直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域13)|Precious-metal slag business: March 2026 ministry guideline revision (briefing);支持证据 / 一手证据(研究域05) / 一手证据(研究域09) / 外部现实(研究域13) / 定向深挖(研究域09)|Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)
完整研究记录(核对用)
研究原文:Slag recovery is a capital-light leg inside resource recycling whose profit is not separated, so its contribution to the step-up cannot be verified.
内部研究类型:undisclosed_contributor_to
内部来源标记:COVERAGE35
F066|05|单点依赖是护城河的反面证据
研究范围:35项覆盖检查
写入正文:05|单点依赖是护城河的反面证据
归并到:F017
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
Safety and dependency: the fire's lesson as management states it (briefing)怎么使用:直接证据;反向验证:06、07、13
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:支持证据;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 反证(研究域06) / 反证(研究域07) / 反证(研究域13)|Safety and dependency: the fire's lesson as management states it (briefing);支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)
完整研究记录(核对用)
研究原文:The fire is the demonstrated instance of a broader single-point pattern (contractor, aged plant, thin head office, one family).
内部研究类型:generalises
内部来源标记:COVERAGE35
F067|03|火灾使新电池工厂成为战略的关键路径
研究范围:35项覆盖检查
写入正文:03|火灾使新电池工厂成为战略的关键路径08|新电池工厂和外围业务考验配置纪律
归并到:F080
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接 / 支持;一手验证:18、19、21、29;外部现实校验:17
Balance-sheet trajectory: net cash turned positive for the first time in the five-year window怎么使用:直接证据;一手验证:18、29;专项深挖:18、29;同业比较:21、24;其他用途:历史
Battery-recycling recovery actions and the new-plant project (briefing)怎么使用:直接证据;专项深挖:06、11、20、30
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:支持证据;一手验证:17、20;外部现实校验:19
Cash-flow trajectory: operating cash flow positive in every one of the five years怎么使用:支持证据;一手验证:17;外部现实校验:29;专项深挖:17
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 定向深挖(研究域18) / 定向深挖(研究域29)|Balance-sheet trajectory: net cash turned positive for the first time in the five-year window;直接证据 / 定向深挖(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域20) / 定向深挖(研究域30)|Battery-recycling recovery actions and the new-plant project (briefing);支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million;支持证据 / 一手证据(研究域17) / 外部现实(研究域29) / 定向深挖(研究域17)|Cash-flow trajectory: operating cash flow positive in every one of the five years
完整研究记录(核对用)
研究原文:Net cash and self-funding cash flow let the group pursue the new-plant project internally, shifting the question from solvency to allocation discipline.
内部研究类型:funds_replacement_capacity
内部来源标记:COVERAGE35
F068|09|股价是在为低谷盈利定价
研究范围:35项覆盖检查
写入正文:09|股价是在为低谷盈利定价09|估值的分歧归结为底部盈利是15亿还是25亿日元
归并到:F083
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Revenue-recognition change in the trading book, from the segment commentary怎么使用:直接 / 支持;一手验证:15、32
Segment revenue composition (external sales by product line), FY6/26 segment note怎么使用:直接 / 支持;一手验证:03;外部现实校验:02、15;专项深挖:03
FY6/26 briefing: price backdrop and the accounting reason sales fell怎么使用:支持证据;一手验证:05、08、11、15;外部现实校验:12、14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域32)|Revenue-recognition change in the trading book, from the segment commentary;直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域02) / 外部现实(研究域15) / 定向深挖(研究域03)|Segment revenue composition (external sales by product line), FY6/26 segment note;支持证据 / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域11) / 一手证据(研究域15) / 外部现实(研究域12) / 外部现实(研究域14)|FY6/26 briefing: price backdrop and the accounting reason sales fell
完整研究记录(核对用)
研究原文:Netted trading sales and falling reported sales distort sales-based multiples and margins versus history.
内部研究类型:distorts_multiples
内部来源标记:COVERAGE35
F069|07|内部人信号很弱,社长交接的细节不清楚
研究范围:35项覆盖检查
归并到:F012
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26)怎么使用:直接 / 支持;外部现实校验:25
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、21、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域25)|Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26);直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million
完整研究记录(核对用)
研究原文:Insiders accepting equity at JPY 741 weakly corroborates reading the guide as a floor.
内部研究类型:weakly_corroborates
内部来源标记:COVERAGE35
F070|08|每股收益里有一部分来自股数减少
研究范围:35项覆盖检查
写入正文:08|每股收益里有一部分来自股数减少
归并到:F011
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Share count, treasury stock and dilution at the FY6/26 close怎么使用:直接 / 支持;一手验证:25;反向验证:25
Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26)怎么使用:直接 / 支持;外部现实校验:25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25) / 反证(研究域25)|Share count, treasury stock and dilution at the FY6/26 close;直接证据 / 支持证据 / 外部现实(研究域25)|Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26)
完整研究记录(核对用)
研究原文:Option-pool dilution and restricted grants partly offset the per-share effect of buybacks.
内部研究类型:offsets_per_share_effect
内部来源标记:COVERAGE35
F071|11|电池恢复延期和物流、汇率是次一级的风险
研究范围:35项覆盖检查
归并到:F023
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels怎么使用:直接 / 支持;一手验证:14;外部现实校验:03、05、06、08、11、12;反向验证:05
Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur怎么使用:直接 / 支持;外部现实校验:02;反向验证:14
Trading segment: what the netting change means and what management says about the book (briefing)怎么使用:支持证据;反向验证:11;专项深挖:05、14、15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 反证(研究域05)|Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels;直接证据 / 支持证据 / 外部现实(研究域02) / 反证(研究域14)|Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur;支持证据 / 反证(研究域11) / 定向深挖(研究域05) / 定向深挖(研究域14) / 定向深挖(研究域15)|Trading segment: what the netting change means and what management says about the book (briefing)
完整研究记录(核对用)
研究原文:Logistics and FX channels sit beneath the dominant price exposure of the spread option.
内部研究类型:secondary_exposure_to
内部来源标记:COVERAGE35
F072|10|价格与业绩公布的先后:价格在两个方向上都先于账面
研究范围:开放研究
写入正文:10|价格与业绩公布的先后:价格在两个方向上都先于账面11|催化剂按财报日期排好,其余靠事件12|账面和价格在不同时间说出了不同的话13|价格要看的下一批证据
归并到:F044
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Assembled monthly price history, September 2013 - October 2026 (158 bars)怎么使用:直接证据;外部现实校验:34
The generational path: two failed spikes before the 2025 base怎么使用:直接证据;一手验证:34
The 2026 pulse and its failure to retain: May high 1,253, five consecutive lower closes怎么使用:直接证据;一手验证:34
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域34)|Assembled monthly price history, September 2013 - October 2026 (158 bars);直接证据 / 一手证据(研究域34)|The generational path: two failed spikes before the 2025 base;直接证据 / 一手证据(研究域34)|The 2026 pulse and its failure to retain: May high 1,253, five consecutive lower closes;直接证据 / 外部现实(研究域34)|Daily cross-check: fiscal-year range and the 6 November 2026 close of JPY 603
完整研究记录(核对用)
研究原文:Cross-lane timing context refers to the protected Technical Synthesis as a whole; it neither flattens nor redefines it, and Fundamental positivity may not rewrite a non-confirming Technical State.
内部研究类型:cross_lane_timing_reference_without_rewrite
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F073|10|价格与业绩公布的先后:价格在两个方向上都先于账面
研究范围:开放研究
写入正文:10|价格与业绩公布的先后:价格在两个方向上都先于账面11|催化剂按财报日期排好,其余靠事件12|账面和价格在不同时间说出了不同的话13|价格要看的下一批证据
归并到:F044
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Disclosure chronology: first-quarter results habitually land on 13 November怎么使用:直接 / 支持;一手验证:30
Subsequent events: none disclosed (tanshin, subsequent-events note)怎么使用:直接 / 支持;一手验证:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|Disclosure chronology: first-quarter results habitually land on 13 November;直接证据 / 支持证据 / 一手证据(研究域30)|Subsequent events: none disclosed (tanshin, subsequent-events note);直接证据 / 外部现实(研究域34)|Daily cross-check: fiscal-year range and the 6 November 2026 close of JPY 603
完整研究记录(核对用)
研究原文:The deciding fundamental print falls in the same weeks as the Technical lane's pending evidence.
内部研究类型:timing_coincidence
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F074|01|要回答的问题:平价年份的底部盈利有没有抬高
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|要回答的问题:平价年份的底部盈利有没有抬高11|什么会推翻这个判断
归并到:F082
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Disclosure chronology: first-quarter results habitually land on 13 November怎么使用:直接 / 支持;一手验证:30
Subsequent events: none disclosed (tanshin, subsequent-events note)怎么使用:直接 / 支持;一手验证:30
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:支持证据;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:支持证据;一手验证:28、35;反向验证:12、22;专项深挖:35
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:支持证据;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
ROIC estimates and cash conversion (JINGI computed indicators)怎么使用:支持证据;一手验证:22;外部现实校验:27、28;专项深挖:12、27、28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|Disclosure chronology: first-quarter results habitually land on 13 November;直接证据 / 支持证据 / 一手证据(研究域30)|Subsequent events: none disclosed (tanshin, subsequent-events note);支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;支持证据 / 一手证据(研究域22) / 外部现实(研究域27) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域27) / 定向深挖(研究域28)|ROIC estimates and cash conversion (JINGI computed indicators)
完整研究记录(核对用)
研究原文:The Q1 print is the first dated evidence bearing on the Thesis falsifiers.
内部研究类型:first_evidence_for
内部来源标记:OPEN_DISCOVERY
F075|13|价格从高位回调后,价差还能保留多少
研究范围:开放研究
写入正文:13|价格从高位回调后,价差还能保留多少
归并到:F040
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:支持证据;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:支持证据;一手验证:02;外部现实校验:16
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:支持证据;一手验证:18、19、21、29;外部现实校验:17
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build
完整研究记录(核对用)
研究原文:Spread survival under a price correction is the unresolved input to the floor estimate.
内部研究类型:unresolved_input_to
内部来源标记:OPEN_DISCOVERY
F076|13|电池产能何时恢复,新工厂花多少钱
研究范围:开放研究
写入正文:13|电池产能何时恢复,新工厂花多少钱
归并到:F039
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:直接 / 支持;一手验证:35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)
完整研究记录(核对用)
研究原文:Restoration timing and settlement size feed directly into the FY6/27 consolidated guide.
内部研究类型:unresolved_input_to
内部来源标记:OPEN_DISCOVERY
F077|02|同样的吨位,赚的是买进废料与卖出再生材料之间的价差
研究范围:开放研究+35项覆盖检查
写入正文:02|同样的吨位,赚的是买进废料与卖出再生材料之间的价差06|现金流五年为正,但利润的一部分压在库存和应收款里
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(20项,重复标签已合并)
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:直接 / 支持;一手验证:02;外部现实校验:16
FY6/26 briefing: price backdrop and the accounting reason sales fell怎么使用:直接 / 支持;一手验证:05、08、11、15;外部现实校验:12、14
Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels怎么使用:直接证据;一手验证:14;外部现实校验:03、05、06、08、11、12;反向验证:05
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure怎么使用:直接 / 支持;一手验证:07、16
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:直接 / 支持;外部现实校验:22
FY6/26 segment results (segment profit reconciles to ordinary profit)怎么使用:直接 / 支持;一手验证:02、32
Segment assets, depreciation and capex by segment, FY6/26 segment note怎么使用:直接 / 支持;外部现实校验:20
Segment comparatives, FY6/25: the profit step-up measured against the soft year怎么使用:直接 / 支持;专项深挖:01;同业比较:03、06、07、15、16、19、20、32;其他用途:历史
Segment revenue composition (external sales by product line), FY6/26 segment note怎么使用:直接 / 支持;一手验证:03;外部现实校验:02、15;专项深挖:03
Revenue-recognition change in the trading book, from the segment commentary怎么使用:直接 / 支持;一手验证:15、32
Special-items quality: FY6/26 profit is cleaner than FY6/25's怎么使用:直接证据;一手验证:16;外部现实校验:32;反向验证:28、32;专项深挖:32
Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur怎么使用:直接证据;外部现实校验:02;反向验证:14
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接 / 支持;一手验证:18、19、21、29;外部现实校验:17
Working capital absorbed the profit: inventories and receivables built at high prices怎么使用:直接 / 支持;一手验证:19;反向验证:02、08、15、16、17、19、29;专项深挖:19
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:直接 / 支持;一手验证:17、20;外部现实校验:19
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
ROIC estimates and cash conversion (JINGI computed indicators)怎么使用:直接证据;一手验证:22;外部现实校验:27、28;专项深挖:12、27、28
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:直接证据;一手验证:28、35;反向验证:12、22;专项深挖:35
Management's framing of FY6/26: structural-reform results, not only market luck (briefing)怎么使用:直接证据;一手验证:04、10;专项深挖:02、16
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域11) / 一手证据(研究域15) / 外部现实(研究域12) / 外部现实(研究域14)|FY6/26 briefing: price backdrop and the accounting reason sales fell;直接证据 / 一手证据(研究域14) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 反证(研究域05)|Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域16)|FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure;直接证据 / 支持证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域32)|FY6/26 segment results (segment profit reconciles to ordinary profit);直接证据 / 支持证据 / 外部现实(研究域20)|Segment assets, depreciation and capex by segment, FY6/26 segment note;直接证据 / 支持证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域01)|Segment comparatives, FY6/25: the profit step-up measured against the soft year;直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域02) / 外部现实(研究域15) / 定向深挖(研究域03)|Segment revenue composition (external sales by product line), FY6/26 segment note;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域32)|Revenue-recognition change in the trading book, from the segment commentary;直接证据 / 一手证据(研究域16) / 外部现实(研究域32) / 反证(研究域28) / 反证(研究域32) / 定向深挖(研究域32)|Special-items quality: FY6/26 profit is cleaner than FY6/25's;直接证据 / 外部现实(研究域02) / 反证(研究域14)|Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 支持证据 / 一手证据(研究域19) / 反证(研究域02) / 反证(研究域08) / 反证(研究域15) / 反证(研究域16) / 反证(研究域17) / 反证(研究域19) / 反证(研究域29) / 定向深挖(研究域19)|Working capital absorbed the profit: inventories and receivables built at high prices;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million;直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;直接证据 / 一手证据(研究域22) / 外部现实(研究域27) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域27) / 定向深挖(研究域28)|ROIC estimates and cash conversion (JINGI computed indicators);直接证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域16)|Management's framing of FY6/26: structural-reform results, not only market luck (briefing)
完整研究记录(核对用)
研究原文:Metal-price spread to cash, margin and shareholder outcome|Price moves the purchase-sale spread; the spread, not volume, drives segment profit on a near-fixed asset base; profit is partly parked in working capital at record prices; reversal compresses margin while releasing cash. The open question is whether reform raised the floor.
内部研究类型:main_causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Earnings are cyclical waves around an unproven mid-cycle floor; per-tonne measures, not sales, are the honest read.
不确定性(原始记录):Spread by material undisclosed; floor unproven until flat-price prints.
F078|02|真正耐久的是分选能力,周围的利润和产能都带周期性
研究范围:开放研究+35项覆盖检查
写入正文:02|真正耐久的是分选能力,周围的利润和产能都带周期性05|优势有,但耐久性要等平价年份的数据证明
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(31项,重复标签已合并)
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:直接证据;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
Management's framing of FY6/26: structural-reform results, not only market luck (briefing)怎么使用:直接证据;一手验证:04、10;专项深挖:02、16
AI sorting co-development with Earth Technica (briefing)怎么使用:直接证据;一手验证:04、07;专项深挖:04
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接 / 支持;一手验证:18、19、21、29;外部现实校验:17
Cash-flow trajectory: operating cash flow positive in every one of the five years怎么使用:直接 / 支持;一手验证:17;外部现实校验:29;专项深挖:17
Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million怎么使用:直接 / 支持;一手验证:20;反向验证:04、10、20
Precious-metal slag business: March 2026 ministry guideline revision (briefing)怎么使用:直接 / 支持;一手验证:10、13
Resource-recycling strategy: deeper sorting, higher-value recovery, municipal ash (briefing)怎么使用:直接证据;专项深挖:08
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:直接 / 支持;一手验证:17、20;外部现实校验:19
Balance-sheet trajectory: net cash turned positive for the first time in the five-year window怎么使用:直接证据;一手验证:18、29;专项深挖:18、29;同业比较:21、24;其他用途:历史
Retirement and restoration obligations: the quiet liabilities怎么使用:直接 / 支持;外部现实校验:18;反向验证:18、21
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:直接 / 支持;一手验证:01、23、24
JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025怎么使用:直接证据;一手验证:01、13、33;反向验证:01、09
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、21、35
Restricted-stock disposal completed 28 October 2026: 50,203 treasury shares at JPY 741怎么使用:直接证据;一手验证:24;外部现实校验:01;专项深挖:24
Margin-trading balance: one-sided retail leverage after the spike怎么使用:直接证据;外部现实校验:24;反向验证:24、26、27、34
FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine怎么使用:直接 / 支持;一手验证:23、31;反向验证:23、33;同业比较:13、31;其他用途:历史
Capital-efficiency doctrine in the securities report: beat the ~10% cost of equity every year怎么使用:直接 / 支持;一手验证:22;专项深挖:22、25
En-Vision2035: the ten-year vision and its three priority businesses (briefing)怎么使用:直接 / 支持;一手验证:11
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:直接 / 支持;一手验证:28、35;反向验证:12、22;专项深挖:35
Listed-subsidiary linkage: Nitto Kako (5104) inside the register怎么使用:直接 / 支持;一手验证:21;专项深挖:21
Precious-metal slag mechanics: two axes - grade and intake (briefing)怎么使用:直接 / 支持;专项深挖:10、13
Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)怎么使用:直接 / 支持;一手验证:05、09;外部现实校验:13;专项深挖:09
Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing)怎么使用:直接 / 支持;专项深挖:07
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
The holding company is thin: 61 standalone employees; group scale from operating subsidiaries怎么使用:直接证据;外部现实校验:23
Safety and dependency: the fire's lesson as management states it (briefing)怎么使用:直接证据;反向验证:06、07、13
Dividend record and FY6/27 dividend forecast (tanshin dividend table)怎么使用:直接 / 支持;一手验证:26
Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing)怎么使用:直接 / 支持;一手验证:25、26
Dividend history: the JPY 6 trough of FY6/24 and the return to JPY 25怎么使用:直接证据;外部现实校验:26;专项深挖:26;同业比较:25、26;其他用途:历史
Battery-recycling recovery actions and the new-plant project (briefing)怎么使用:直接证据;专项深挖:06、11、20、30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 定向深挖(研究域02) / 定向深挖(研究域16)|Management's framing of FY6/26: structural-reform results, not only market luck (briefing);直接证据 / 一手证据(研究域04) / 一手证据(研究域07) / 定向深挖(研究域04)|AI sorting co-development with Earth Technica (briefing);直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域29) / 定向深挖(研究域17)|Cash-flow trajectory: operating cash flow positive in every one of the five years;直接证据 / 支持证据 / 一手证据(研究域20) / 反证(研究域04) / 反证(研究域10) / 反证(研究域20)|Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域13)|Precious-metal slag business: March 2026 ministry guideline revision (briefing);直接证据 / 定向深挖(研究域08)|Resource-recycling strategy: deeper sorting, higher-value recovery, municipal ash (briefing);直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million;直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 定向深挖(研究域18) / 定向深挖(研究域29)|Balance-sheet trajectory: net cash turned positive for the first time in the five-year window;直接证据 / 支持证据 / 外部现实(研究域18) / 反证(研究域18) / 反证(研究域21)|Retirement and restoration obligations: the quiet liabilities;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info);直接证据 / 一手证据(研究域01) / 一手证据(研究域13) / 一手证据(研究域33) / 反证(研究域01) / 反证(研究域09)|JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million;直接证据 / 一手证据(研究域24) / 外部现实(研究域01) / 定向深挖(研究域24)|Restricted-stock disposal completed 28 October 2026: 50,203 treasury shares at JPY 741;直接证据 / 外部现实(研究域24) / 反证(研究域24) / 反证(研究域26) / 反证(研究域27) / 反证(研究域34)|Margin-trading balance: one-sided retail leverage after the spike;直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域31) / 历史/同业比较(研究域13) / 历史/同业比较(研究域31) / 反证(研究域23) / 反证(研究域33)|FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域25)|Capital-efficiency doctrine in the securities report: beat the ~10% cost of equity every year;直接证据 / 支持证据 / 一手证据(研究域11)|En-Vision2035: the ten-year vision and its three priority businesses (briefing);直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21)|Listed-subsidiary linkage: Nitto Kako (5104) inside the register;直接证据 / 支持证据 / 定向深挖(研究域10) / 定向深挖(研究域13)|Precious-metal slag mechanics: two axes - grade and intake (briefing);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域09) / 外部现实(研究域13) / 定向深挖(研究域09)|Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing);直接证据 / 支持证据 / 定向深挖(研究域07)|Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing);直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 外部现实(研究域23)|The holding company is thin: 61 standalone employees; group scale from operating subsidiaries;直接证据 / 反证(研究域06) / 反证(研究域07) / 反证(研究域13)|Safety and dependency: the fire's lesson as management states it (briefing);直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and FY6/27 dividend forecast (tanshin dividend table);直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing);直接证据 / 外部现实(研究域26) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 定向深挖(研究域26)|Dividend history: the JPY 6 trough of FY6/24 and the return to JPY 25;直接证据 / 定向深挖(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域20) / 定向深挖(研究域30)|Battery-recycling recovery actions and the new-plant project (briefing)
完整研究记录(核对用)
研究原文:Durable Business Portrait: sorting franchise under a price-cyclical overlay|A tacit-know-how franchise, self-funded and net cash, with permanent family control, concentrated single-point dependencies, capital-light and long-dated growth legs, and a policy-floored return stream; change (spread surge, fire, doctrine) is overlaid on this foundation.
内部研究类型:durable_business_portrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Survival and income are protected; value creation depends on the trough rising and on allocation discipline under family control.
不确定性(原始记录):Moat is issuer-asserted; growth legs undisclosed at P&L level.
F079|06|现金流五年为正,但利润的一部分压在库存和应收款里
研究范围:开放研究+35项覆盖检查
写入正文:06|现金流五年为正,但利润的一部分压在库存和应收款里11|价差回落时,利润下降和现金释放会同时发生12|账面和价格在不同时间说出了不同的话
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(12项,重复标签已合并)
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:直接 / 支持;一手验证:02;外部现实校验:16
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接 / 支持;一手验证:18、19、21、29;外部现实校验:17
Working capital absorbed the profit: inventories and receivables built at high prices怎么使用:直接 / 支持;一手验证:19;反向验证:02、08、15、16、17、19、29;专项深挖:19
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:直接 / 支持;一手验证:17、20;外部现实校验:19
Balance-sheet trajectory: net cash turned positive for the first time in the five-year window怎么使用:直接证据;一手验证:18、29;专项深挖:18、29;同业比较:21、24;其他用途:历史
Cash-flow trajectory: operating cash flow positive in every one of the five years怎么使用:直接 / 支持;一手验证:17;外部现实校验:29;专项深挖:17
Retirement and restoration obligations: the quiet liabilities怎么使用:直接证据;外部现实校验:18;反向验证:18、21
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:直接 / 支持;外部现实校验:22
FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure怎么使用:直接 / 支持;一手验证:07、16
Special-items quality: FY6/26 profit is cleaner than FY6/25's怎么使用:直接证据;一手验证:16;外部现实校验:32;反向验证:28、32;专项深挖:32
Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur怎么使用:直接证据;外部现实校验:02;反向验证:14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 支持证据 / 一手证据(研究域19) / 反证(研究域02) / 反证(研究域08) / 反证(研究域15) / 反证(研究域16) / 反证(研究域17) / 反证(研究域19) / 反证(研究域29) / 定向深挖(研究域19)|Working capital absorbed the profit: inventories and receivables built at high prices;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million;直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 定向深挖(研究域18) / 定向深挖(研究域29)|Balance-sheet trajectory: net cash turned positive for the first time in the five-year window;直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域29) / 定向深挖(研究域17)|Cash-flow trajectory: operating cash flow positive in every one of the five years;直接证据 / 外部现实(研究域18) / 反证(研究域18) / 反证(研究域21)|Retirement and restoration obligations: the quiet liabilities;直接证据 / 支持证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026;直接证据 / 支持证据 / 一手证据(研究域07) / 一手证据(研究域16)|FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure;直接证据 / 一手证据(研究域16) / 外部现实(研究域32) / 反证(研究域28) / 反证(研究域32) / 定向深挖(研究域32)|Special-items quality: FY6/26 profit is cleaner than FY6/25's;直接证据 / 外部现实(研究域02) / 反证(研究域14)|Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur
完整研究记录(核对用)
研究原文:Working capital ties the cycle to the balance sheet|Record prices inflated inventories and receivables in the same year they inflated profit; a correction compresses margins and releases cash at once, so the income statement and cash-flow statement will disagree at the turn and both will be right.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Expect earnings-cash divergence at the price turn.
不确定性(原始记录):Release size and speed unknown.
F080|03|火灾使新电池工厂成为战略的关键路径
研究范围:开放研究+35项覆盖检查
写入正文:03|火灾使新电池工厂成为战略的关键路径08|新电池工厂和外围业务考验配置纪律
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(17项,重复标签已合并)
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:直接 / 支持;一手验证:35
Battery-recycling recovery actions and the new-plant project (briefing)怎么使用:直接证据;专项深挖:06、11、20、30
Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million怎么使用:直接证据;一手验证:20;反向验证:04、10、20
The holding company is thin: 61 standalone employees; group scale from operating subsidiaries怎么使用:直接证据;外部现实校验:23
Safety and dependency: the fire's lesson as management states it (briefing)怎么使用:直接证据;反向验证:06、07、13
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:支持证据;一手验证:01、23、24
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接 / 支持;一手验证:18、19、21、29;外部现实校验:17
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:直接 / 支持;一手验证:17、20;外部现实校验:19
Balance-sheet trajectory: net cash turned positive for the first time in the five-year window怎么使用:直接证据;一手验证:18、29;专项深挖:18、29;同业比较:21、24;其他用途:历史
Cash-flow trajectory: operating cash flow positive in every one of the five years怎么使用:直接 / 支持;一手验证:17;外部现实校验:29;专项深挖:17
Retirement and restoration obligations: the quiet liabilities怎么使用:直接证据;外部现实校验:18;反向验证:18、21
Precious-metal slag business: March 2026 ministry guideline revision (briefing)怎么使用:直接 / 支持;一手验证:10、13
Precious-metal slag mechanics: two axes - grade and intake (briefing)怎么使用:直接 / 支持;专项深挖:10、13
Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)怎么使用:直接 / 支持;一手验证:05、09;外部现实校验:13;专项深挖:09
Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing)怎么使用:直接 / 支持;专项深挖:07
En-Vision2035: the ten-year vision and its three priority businesses (briefing)怎么使用:直接 / 支持;一手验证:11
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing);直接证据 / 定向深挖(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域20) / 定向深挖(研究域30)|Battery-recycling recovery actions and the new-plant project (briefing);直接证据 / 一手证据(研究域20) / 反证(研究域04) / 反证(研究域10) / 反证(研究域20)|Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million;直接证据 / 外部现实(研究域23)|The holding company is thin: 61 standalone employees; group scale from operating subsidiaries;直接证据 / 反证(研究域06) / 反证(研究域07) / 反证(研究域13)|Safety and dependency: the fire's lesson as management states it (briefing);支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info);直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million;直接证据 / 一手证据(研究域18) / 一手证据(研究域29) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 定向深挖(研究域18) / 定向深挖(研究域29)|Balance-sheet trajectory: net cash turned positive for the first time in the five-year window;直接证据 / 支持证据 / 一手证据(研究域17) / 外部现实(研究域29) / 定向深挖(研究域17)|Cash-flow trajectory: operating cash flow positive in every one of the five years;直接证据 / 外部现实(研究域18) / 反证(研究域18) / 反证(研究域21)|Retirement and restoration obligations: the quiet liabilities;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域13)|Precious-metal slag business: March 2026 ministry guideline revision (briefing);直接证据 / 支持证据 / 定向深挖(研究域10) / 定向深挖(研究域13)|Precious-metal slag mechanics: two axes - grade and intake (briefing);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域09) / 外部现实(研究域13) / 定向深挖(研究域09)|Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing);直接证据 / 支持证据 / 定向深挖(研究域07)|Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing);直接证据 / 支持证据 / 一手证据(研究域11)|En-Vision2035: the ten-year vision and its three priority businesses (briefing)
完整研究记录(核对用)
研究原文:The battery fire turns an operating event into a capital-decision critical path|The segment designated as post-2030 growth carrier cannot currently produce, so the new-plant project, a capital decision, becomes the strategy's critical path ahead of contract-driven slag growth.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Strategy timing now depends on battery capacity decisions and their funding.
不确定性(原始记录):Plant capex, capacity and schedule undisclosed.
F081|07|家族握有约47.5%股份,少数股东承担折价
研究范围:开放研究+35项覆盖检查
写入正文:07|家族握有约47.5%股份,少数股东承担折价09|股价是在为低谷盈利定价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(13项,重复标签已合并)
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:直接 / 支持;一手验证:01、23、24
JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025怎么使用:直接证据;一手验证:01、13、33;反向验证:01、09
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、21、35
Restricted-stock disposal completed 28 October 2026: 50,203 treasury shares at JPY 741怎么使用:直接证据;一手验证:24;外部现实校验:01;专项深挖:24
Margin-trading balance: one-sided retail leverage after the spike怎么使用:直接证据;外部现实校验:24;反向验证:24、26、27、34
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:直接 / 支持;外部现实校验:22
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接 / 支持;一手验证:18、19、21、29;外部现实校验:17
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:直接 / 支持;一手验证:17、20;外部现实校验:19
Dividend record and FY6/27 dividend forecast (tanshin dividend table)怎么使用:直接 / 支持;一手验证:26
Disclosure chronology: first-quarter results habitually land on 13 November怎么使用:直接 / 支持;一手验证:30
Subsequent events: none disclosed (tanshin, subsequent-events note)怎么使用:直接 / 支持;一手验证:30
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info);直接证据 / 一手证据(研究域01) / 一手证据(研究域13) / 一手证据(研究域33) / 反证(研究域01) / 反证(研究域09)|JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million;直接证据 / 一手证据(研究域24) / 外部现实(研究域01) / 定向深挖(研究域24)|Restricted-stock disposal completed 28 October 2026: 50,203 treasury shares at JPY 741;直接证据 / 外部现实(研究域24) / 反证(研究域24) / 反证(研究域26) / 反证(研究域27) / 反证(研究域34)|Margin-trading balance: one-sided retail leverage after the spike;直接证据 / 支持证据|FY6/27 full-year forecast: higher sales, lower profit, published 13 August 2026;直接证据 / 支持证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and FY6/27 dividend forecast (tanshin dividend table);直接证据 / 支持证据 / 一手证据(研究域30)|Disclosure chronology: first-quarter results habitually land on 13 November;直接证据 / 支持证据 / 一手证据(研究域30)|Subsequent events: none disclosed (tanshin, subsequent-events note);直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)
完整研究记录(核对用)
研究原文:Control structure explains valuation persistence|A 47.5% family bloc, 42% float and Standard-market sponsorship mean mispricing corrects through evidence accumulation rather than arbitrage, matching the print-based catalyst calendar on which the thesis is graded.
内部研究类型:cross_domain_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Re-rating is slow and evidence-driven; liquidity constrains sizing.
不确定性(原始记录):No analyst coverage or peer multiples found.
F082|01|要回答的问题:平价年份的底部盈利有没有抬高
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|要回答的问题:平价年份的底部盈利有没有抬高11|什么会推翻这个判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(17项,重复标签已合并)
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:直接 / 支持;一手验证:28、35;反向验证:12、22;专项深挖:35
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
ROIC estimates and cash conversion (JINGI computed indicators)怎么使用:直接 / 支持;一手验证:22;外部现实校验:27、28;专项深挖:12、27、28
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:直接 / 支持;一手验证:35
The 30 July 2026 revision: forecast and dividend raised ahead of the annual print怎么使用:直接 / 支持;外部现实校验:31;反向验证:31;专项深挖:31;同业比较:30;其他用途:历史
FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine怎么使用:支持证据;一手验证:23、31;反向验证:23、33;同业比较:13、31;其他用途:历史
Disclosure chronology: first-quarter results habitually land on 13 November怎么使用:直接 / 支持;一手验证:30
Subsequent events: none disclosed (tanshin, subsequent-events note)怎么使用:直接 / 支持;一手验证:30
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
Battery-recycling recovery actions and the new-plant project (briefing)怎么使用:直接证据;专项深挖:06、11、20、30
FY6/26 segment results (segment profit reconciles to ordinary profit)怎么使用:直接 / 支持;一手验证:02、32
Segment assets, depreciation and capex by segment, FY6/26 segment note怎么使用:直接 / 支持;外部现实校验:20
Segment comparatives, FY6/25: the profit step-up measured against the soft year怎么使用:直接 / 支持;专项深挖:01;同业比较:03、06、07、15、16、19、20、32;其他用途:历史
Segment revenue composition (external sales by product line), FY6/26 segment note怎么使用:直接证据;一手验证:03;外部现实校验:02、15;专项深挖:03
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;直接证据 / 支持证据 / 一手证据(研究域22) / 外部现实(研究域27) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域27) / 定向深挖(研究域28)|ROIC estimates and cash conversion (JINGI computed indicators);直接证据 / 支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing);直接证据 / 支持证据|FY6/27 full-year forecast: higher sales, lower profit, published 13 August 2026;直接证据 / 支持证据 / 外部现实(研究域31) / 历史/同业比较(研究域30) / 反证(研究域31) / 定向深挖(研究域31)|The 30 July 2026 revision: forecast and dividend raised ahead of the annual print;直接证据|FY6/27 positioned as a base-building year: investment continues through the forecast decline (briefing);支持证据 / 一手证据(研究域23) / 一手证据(研究域31) / 历史/同业比较(研究域13) / 历史/同业比较(研究域31) / 反证(研究域23) / 反证(研究域33)|FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine;直接证据 / 支持证据 / 一手证据(研究域30)|Disclosure chronology: first-quarter results habitually land on 13 November;直接证据 / 支持证据 / 一手证据(研究域30)|Subsequent events: none disclosed (tanshin, subsequent-events note);直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 定向深挖(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域20) / 定向深挖(研究域30)|Battery-recycling recovery actions and the new-plant project (briefing);直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域32)|FY6/26 segment results (segment profit reconciles to ordinary profit);直接证据 / 支持证据 / 外部现实(研究域20)|Segment assets, depreciation and capex by segment, FY6/26 segment note;直接证据 / 支持证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域01)|Segment comparatives, FY6/25: the profit step-up measured against the soft year;直接证据 / 一手证据(研究域03) / 外部现实(研究域02) / 外部现实(研究域15) / 定向深挖(研究域03)|Segment revenue composition (external sales by product line), FY6/26 segment note
完整研究记录(核对用)
研究原文:Thesis and falsification: has the trough risen?|The thesis is a measurement claim about the trough; falsifiers are published prints: Q1 and interim FY6/27 tanshin and resource-segment profit versus the JPY 2,900 million plan.
内部研究类型:thesis_and_falsification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Two quarters decide the core claim.
不确定性(原始记录):Research confidence medium; unprinted evidence.
F083|09|股价是在为低谷盈利定价
研究范围:开放研究+35项覆盖检查
写入正文:09|股价是在为低谷盈利定价09|估值的分歧归结为底部盈利是15亿还是25亿日元
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(22项,重复标签已合并)
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、21、35
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:直接 / 支持;外部现实校验:22
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:直接 / 支持;一手验证:18、19、21、29;外部现实校验:17
FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million怎么使用:直接 / 支持;一手验证:17、20;外部现实校验:19
Dividend record and FY6/27 dividend forecast (tanshin dividend table)怎么使用:直接 / 支持;一手验证:26
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:直接 / 支持;一手验证:01、23、24
JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025怎么使用:直接证据;一手验证:01、13、33;反向验证:01、09
Restricted-stock disposal completed 28 October 2026: 50,203 treasury shares at JPY 741怎么使用:直接证据;一手验证:24;外部现实校验:01;专项深挖:24
Margin-trading balance: one-sided retail leverage after the spike怎么使用:直接证据;外部现实校验:24;反向验证:24、26、27、34
Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million怎么使用:直接 / 支持;一手验证:20;反向验证:04、10、20
Retirement and restoration obligations: the quiet liabilities怎么使用:直接 / 支持;外部现实校验:18;反向验证:18、21
Listed-subsidiary linkage: Nitto Kako (5104) inside the register怎么使用:直接 / 支持;一手验证:21;专项深挖:21
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:直接 / 支持;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
ROIC estimates and cash conversion (JINGI computed indicators)怎么使用:直接证据;一手验证:22;外部现实校验:27、28;专项深挖:12、27、28
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:直接证据;一手验证:28、35;反向验证:12、22;专项深挖:35
Segment revenue composition (external sales by product line), FY6/26 segment note怎么使用:直接 / 支持;一手验证:03;外部现实校验:02、15;专项深挖:03
FY6/26 briefing: price backdrop and the accounting reason sales fell怎么使用:直接 / 支持;一手验证:05、08、11、15;外部现实校验:12、14
Revenue-recognition change in the trading book, from the segment commentary怎么使用:直接 / 支持;一手验证:15、32
Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing)怎么使用:直接 / 支持;一手验证:25、26
Dividend history: the JPY 6 trough of FY6/24 and the return to JPY 25怎么使用:直接证据;外部现实校验:26;专项深挖:26;同业比较:25、26;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million;直接证据 / 支持证据|FY6/27 full-year forecast: higher sales, lower profit, published 13 August 2026;直接证据 / 支持证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域20) / 外部现实(研究域19)|FY6/26 cash flows: operating cash flow JPY 3,071 million against capex of JPY 947 million;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record and FY6/27 dividend forecast (tanshin dividend table);直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info);直接证据 / 一手证据(研究域01) / 一手证据(研究域13) / 一手证据(研究域33) / 反证(研究域01) / 反证(研究域09)|JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025;直接证据 / 一手证据(研究域24) / 外部现实(研究域01) / 定向深挖(研究域24)|Restricted-stock disposal completed 28 October 2026: 50,203 treasury shares at JPY 741;直接证据 / 外部现实(研究域24) / 反证(研究域24) / 反证(研究域26) / 反证(研究域27) / 反证(研究域34)|Margin-trading balance: one-sided retail leverage after the spike;直接证据 / 支持证据 / 一手证据(研究域20) / 反证(研究域04) / 反证(研究域10) / 反证(研究域20)|Fixed-asset age: machinery is 81% depreciated; land carried at JPY 3,841 million;直接证据 / 支持证据 / 外部现实(研究域18) / 反证(研究域18) / 反证(研究域21)|Retirement and restoration obligations: the quiet liabilities;直接证据 / 支持证据 / 一手证据(研究域21) / 定向深挖(研究域21)|Listed-subsidiary linkage: Nitto Kako (5104) inside the register;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;直接证据 / 一手证据(研究域22) / 外部现实(研究域27) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域27) / 定向深挖(研究域28)|ROIC estimates and cash conversion (JINGI computed indicators);直接证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域02) / 外部现实(研究域15) / 定向深挖(研究域03)|Segment revenue composition (external sales by product line), FY6/26 segment note;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域11) / 一手证据(研究域15) / 外部现实(研究域12) / 外部现实(研究域14)|FY6/26 briefing: price backdrop and the accounting reason sales fell;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域32)|Revenue-recognition change in the trading book, from the segment commentary;直接证据 / 支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing);直接证据 / 外部现实(研究域26) / 历史/同业比较(研究域25) / 历史/同业比较(研究域26) / 定向深挖(研究域26)|Dividend history: the JPY 6 trough of FY6/24 and the return to JPY 25
完整研究记录(核对用)
研究原文:Valuation bridge from trough or peak earnings to a below-book price|The multiple is a trough bet in disguise: optically cheap on peak earnings, fairly priced on trough earnings; discount reflects control, venue and cyclicality; hidden assets are optionality.
内部研究类型:valuation_bridge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Re-rating needs trough evidence, not peak repetition.
不确定性(原始记录):Operand bases differ (issued vs outstanding shares, net cash definitions).
F084|04|利润和风险主要经由金属价格、一家承包商和关联公司收益传导
研究范围:开放研究+35项覆盖检查
写入正文:04|利润和风险主要经由金属价格、一家承包商和关联公司收益传导04|竞争对手和同业倍数没有可核实的对比
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(26项,重复标签已合并)
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:直接 / 支持;一手验证:01、23、24
Group composition from the FY6/26 securities report: eleven consolidated subsidiaries怎么使用:直接证据;一手验证:06;外部现实校验:07
Listed-subsidiary linkage: Nitto Kako (5104) inside the register怎么使用:直接证据;一手验证:21;专项深挖:21
FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure怎么使用:直接证据;一手验证:07、16
Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur怎么使用:直接证据;外部现实校验:02;反向验证:14
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:直接 / 支持;一手验证:02;外部现实校验:16
FY6/26 briefing: price backdrop and the accounting reason sales fell怎么使用:直接 / 支持;一手验证:05、08、11、15;外部现实校验:12、14
Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels怎么使用:直接证据;一手验证:14;外部现实校验:03、05、06、08、11、12;反向验证:05
Precious-metal slag business: March 2026 ministry guideline revision (briefing)怎么使用:直接 / 支持;一手验证:10、13
Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)怎么使用:直接 / 支持;一手验证:05、09;外部现实校验:13;专项深挖:09
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
Safety and dependency: the fire's lesson as management states it (briefing)怎么使用:直接证据;反向验证:06、07、13
JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025怎么使用:直接证据;一手验证:01、13、33;反向验证:01、09
AI sorting co-development with Earth Technica (briefing)怎么使用:直接证据;一手验证:04、07;专项深挖:04
Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing)怎么使用:直接 / 支持;专项深挖:07
Segment revenue composition (external sales by product line), FY6/26 segment note怎么使用:直接 / 支持;一手验证:03;外部现实校验:02、15;专项深挖:03
Revenue-recognition change in the trading book, from the segment commentary怎么使用:支持证据;一手验证:15、32
Segment comparatives, FY6/25: the profit step-up measured against the soft year怎么使用:直接 / 支持;专项深挖:01;同业比较:03、06、07、15、16、19、20、32;其他用途:历史
Segment assets, depreciation and capex by segment, FY6/26 segment note怎么使用:支持证据;外部现实校验:20
FY6/26 consolidated results (tanshin headline), published 13 August 2026怎么使用:支持证据;外部现实校验:22
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:支持证据;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:支持证据;一手验证:18、19、21、29;外部现实校验:17
Precious-metal slag mechanics: two axes - grade and intake (briefing)怎么使用:支持证据;专项深挖:10、13
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:支持证据;一手验证:35
Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million怎么使用:支持证据;一手验证:27、31;外部现实校验:01、09、21、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info);直接证据 / 一手证据(研究域06) / 外部现实(研究域07)|Group composition from the FY6/26 securities report: eleven consolidated subsidiaries;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|Listed-subsidiary linkage: Nitto Kako (5104) inside the register;直接证据 / 一手证据(研究域07) / 一手证据(研究域16)|FY6/26 profit-and-loss detail: gross margin, SG&A and non-operating structure;直接证据 / 外部现实(研究域02) / 反证(研究域14)|Non-operating structure: equity-method income is 14% of ordinary profit; FX losses recur;直接证据 / 支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域08) / 一手证据(研究域11) / 一手证据(研究域15) / 外部现实(研究域12) / 外部现实(研究域14)|FY6/26 briefing: price backdrop and the accounting reason sales fell;直接证据 / 一手证据(研究域14) / 外部现实(研究域03) / 外部现实(研究域05) / 外部现实(研究域06) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 反证(研究域05)|Stated environment and frictions in the FY6/26 tanshin text: Hormuz, FX losses, price levels;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域13)|Precious-metal slag business: March 2026 ministry guideline revision (briefing);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域09) / 外部现实(研究域13) / 定向深挖(研究域09)|Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing);直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 反证(研究域06) / 反证(研究域07) / 反证(研究域13)|Safety and dependency: the fire's lesson as management states it (briefing);直接证据 / 一手证据(研究域01) / 一手证据(研究域13) / 一手证据(研究域33) / 反证(研究域01) / 反证(研究域09)|JPX market-transfer list: Envipro Holdings moved from Prime to Standard on 18 September 2025;直接证据 / 一手证据(研究域04) / 一手证据(研究域07) / 定向深挖(研究域04)|AI sorting co-development with Earth Technica (briefing);直接证据 / 支持证据 / 定向深挖(研究域07)|Polymer circular-economy business: RPF plant, Nitto Kako expansion, Ebara demonstration (briefing);直接证据 / 支持证据 / 一手证据(研究域03) / 外部现实(研究域02) / 外部现实(研究域15) / 定向深挖(研究域03)|Segment revenue composition (external sales by product line), FY6/26 segment note;支持证据 / 一手证据(研究域15) / 一手证据(研究域32)|Revenue-recognition change in the trading book, from the segment commentary;直接证据 / 支持证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域01)|Segment comparatives, FY6/25: the profit step-up measured against the soft year;支持证据 / 外部现实(研究域20)|Segment assets, depreciation and capex by segment, FY6/26 segment note;支持证据 / 外部现实(研究域22)|FY6/26 consolidated results (tanshin headline), published 13 August 2026;支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;支持证据 / 定向深挖(研究域10) / 定向深挖(研究域13)|Precious-metal slag mechanics: two axes - grade and intake (briefing);支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing);支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域35)|Market snapshot, 6 November 2026: close JPY 603, market capitalisation JPY 18,281 million;支持证据 / 一手证据(研究域11)|En-Vision2035: the ten-year vision and its three priority businesses (briefing)
完整研究记录(核对用)
研究原文:Related companies and external drivers|Industrial and ownership relationships by direction of economic transmission.
内部研究类型:related_company_pool
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Profit and risk transmit mainly through prices, one contractor and affiliate income.
不确定性(原始记录):Counterparty financials largely undisclosed.
F085|13|炉渣和市政合同什么时候能被量化
研究范围:开放研究+35项覆盖检查
写入正文:13|炉渣和市政合同什么时候能被量化
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(28项,重复标签已合并)
Disclosure chronology: first-quarter results habitually land on 13 November怎么使用:直接 / 支持;一手验证:30
Subsequent events: none disclosed (tanshin, subsequent-events note)怎么使用:直接 / 支持;一手验证:30
Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A)怎么使用:直接 / 支持;一手验证:06;外部现实校验:30;反向验证:30、35
Battery-recycling recovery actions and the new-plant project (briefing)怎么使用:直接证据;专项深挖:06、11、20、30
FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing)怎么使用:直接 / 支持;一手验证:35
Five-year consolidated series from the securities reports (JINGI compilation)怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;同业比较:02、05、08、09、10、11、12、14、17、18、22、27、28、29、33、35;其他用途:历史
FY6/26 segment results (segment profit reconciles to ordinary profit)怎么使用:直接证据;一手验证:02、32
Segment comparatives, FY6/25: the profit step-up measured against the soft year怎么使用:直接证据;专项深挖:01;同业比较:03、06、07、15、16、19、20、32;其他用途:历史
Revenue-recognition change in the trading book, from the segment commentary怎么使用:直接证据;一手验证:15、32
Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013怎么使用:支持证据;一手验证:09、33;外部现实校验:04、10;同业比较:01、04、23;其他用途:历史
FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story怎么使用:支持证据;一手验证:02;外部现实校验:16
FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build怎么使用:支持证据;一手验证:18、19、21、29;外部现实校验:17
En-Vision2035: the ten-year vision and its three priority businesses (briefing)怎么使用:直接 / 支持;一手验证:11
FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine怎么使用:直接 / 支持;一手验证:23、31;反向验证:23、33;同业比较:13、31;其他用途:历史
Capital-efficiency doctrine in the securities report: beat the ~10% cost of equity every year怎么使用:支持证据;一手验证:22;专项深挖:22、25
FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing)怎么使用:支持证据;一手验证:28、35;反向验证:12、22;专项深挖:35
Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26)怎么使用:直接 / 支持;外部现实校验:25
Share count, treasury stock and dilution at the FY6/26 close怎么使用:直接证据;一手验证:25;反向验证:25
Listed-subsidiary linkage: Nitto Kako (5104) inside the register怎么使用:直接证据;一手验证:21;专项深挖:21
The 'other' segment is shrinking: consulting orders down, welfare users down怎么使用:直接 / 支持;反向验证:03
Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing)怎么使用:支持证据;一手验证:25、26
Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info)怎么使用:支持证据;一手验证:01、23、24
The holding company is thin: 61 standalone employees; group scale from operating subsidiaries怎么使用:支持证据;外部现实校验:23
Precious-metal slag business: March 2026 ministry guideline revision (briefing)怎么使用:直接 / 支持;一手验证:10、13
Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing)怎么使用:直接 / 支持;一手验证:05、09;外部现实校验:13;专项深挖:09
Precious-metal slag mechanics: two axes - grade and intake (briefing)怎么使用:直接 / 支持;专项深挖:10、13
ROIC estimates and cash conversion (JINGI computed indicators)怎么使用:支持证据;一手验证:22;外部现实校验:27、28;专项深挖:12、27、28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|Disclosure chronology: first-quarter results habitually land on 13 November;直接证据 / 支持证据 / 一手证据(研究域30)|Subsequent events: none disclosed (tanshin, subsequent-events note);直接证据 / 支持证据 / 一手证据(研究域06) / 外部现实(研究域30) / 反证(研究域30) / 反证(研究域35)|Battery-recycling fire: JPY 130 million disaster loss and an open recovery timetable (briefing Q&A);直接证据 / 定向深挖(研究域06) / 定向深挖(研究域11) / 定向深挖(研究域20) / 定向深挖(研究域30)|Battery-recycling recovery actions and the new-plant project (briefing);直接证据 / 支持证据 / 一手证据(研究域35)|FY6/27 segment forecasts and the two stated reasons for the profit decline (briefing);直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域05) / 历史/同业比较(研究域08) / 历史/同业比较(研究域09) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域33) / 历史/同业比较(研究域35)|Five-year consolidated series from the securities reports (JINGI compilation);直接证据 / 一手证据(研究域02) / 一手证据(研究域32)|FY6/26 segment results (segment profit reconciles to ordinary profit);直接证据 / 历史/同业比较(研究域03) / 历史/同业比较(研究域06) / 历史/同业比较(研究域07) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域32) / 定向深挖(研究域01)|Segment comparatives, FY6/25: the profit step-up measured against the soft year;直接证据 / 一手证据(研究域15) / 一手证据(研究域32)|Revenue-recognition change in the trading book, from the segment commentary;支持证据 / 一手证据(研究域09) / 一手证据(研究域33) / 外部现实(研究域04) / 外部现实(研究域10) / 历史/同业比较(研究域01) / 历史/同业比较(研究域04) / 历史/同业比较(研究域23)|Issuer history: founded as a Fujinomiya scrap dealer in 1950; shredder bet in 1997; listed 2013;支持证据 / 一手证据(研究域02) / 外部现实(研究域16)|FY6/26 results briefing transcript: the ordinary-profit bridge is a spread story;支持证据 / 一手证据(研究域18) / 一手证据(研究域19) / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17)|FY6/26 balance sheet: equity ratio 54.1%, inventories and receivables build;直接证据 / 支持证据 / 一手证据(研究域11)|En-Vision2035: the ten-year vision and its three priority businesses (briefing);直接证据 / 支持证据 / 一手证据(研究域23) / 一手证据(研究域31) / 历史/同业比较(研究域13) / 历史/同业比较(研究域31) / 反证(研究域23) / 反证(研究域33)|FY6/26 securities report: withdrawal of the mid-term plan and the new capital-efficiency doctrine;支持证据 / 一手证据(研究域22) / 定向深挖(研究域22) / 定向深挖(研究域25)|Capital-efficiency doctrine in the securities report: beat the ~10% cost of equity every year;支持证据 / 一手证据(研究域28) / 一手证据(研究域35) / 反证(研究域12) / 反证(研究域22) / 定向深挖(研究域35)|FY6/27 ordinary-profit bridge: spread plus JPY 206 million against cost headwinds (briefing);直接证据 / 支持证据 / 外部现实(研究域25)|Buyback execution in the cash-flow statement: JPY 789 million (FY6/25), JPY 173 million (FY6/26);直接证据 / 一手证据(研究域25) / 反证(研究域25)|Share count, treasury stock and dilution at the FY6/26 close;直接证据 / 一手证据(研究域21) / 定向深挖(研究域21)|Listed-subsidiary linkage: Nitto Kako (5104) inside the register;直接证据 / 支持证据 / 反证(研究域03)|The 'other' segment is shrinking: consulting orders down, welfare users down;支持证据 / 一手证据(研究域26)|Dividend record and FY6/27 dividend forecast (tanshin dividend table);支持证据 / 一手证据(研究域25) / 一手证据(研究域26)|Shareholder-return framework: DOE floor of 2.5% and continued buybacks (briefing);支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Corporate registry and FY6/26 securities-report data for Envipro Holdings (G-Biz Info);支持证据 / 外部现实(研究域23)|The holding company is thin: 61 standalone employees; group scale from operating subsidiaries;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域13)|Precious-metal slag business: March 2026 ministry guideline revision (briefing);直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域09) / 外部现实(研究域13) / 定向深挖(研究域09)|Infrastructure-partner ambition: municipal waste functions as the new demand frontier (briefing);直接证据 / 支持证据 / 定向深挖(研究域10) / 定向深挖(研究域13)|Precious-metal slag mechanics: two axes - grade and intake (briefing);支持证据 / 一手证据(研究域22) / 外部现实(研究域27) / 外部现实(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域27) / 定向深挖(研究域28)|ROIC estimates and cash conversion (JINGI computed indicators)
完整研究记录(核对用)
研究原文:Prioritised Research Debt for the next Review|Ten open questions grouped by shared mechanism; Q1 print first, battery capacity and spread survival next.
内部研究类型:research_debt_ledger
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Each could change the floor, the guide or the allocation outcome.
不确定性(原始记录):Several resolve only after the cut-off.
F086|10|技术问题:2026年的放量冲高是新阶段的起点,还是旧区间里的一次脉冲
写入正文:00|报告身份、评分与核心结论10|技术问题:2026年的放量冲高是新阶段的起点,还是旧区间里的一次脉冲10|上市13年的价格路径:两次失败的冲高,三年阴跌,2025年才抬高低点10|2026年的冲高没有守住:5月高点1,253日元,收盘只有803日元10|价格重心回到24个月均线,周围没有中间台阶10|下跌动能已经耗尽,上行的恢复力只证明过一次脉冲10|现在的状态:改变已尝试,裁决落在604至654日元价格带10|价格与业绩公布的先后:价格在两个方向上都先于账面14|总分59.51/100,评级B,评分版本V3.2
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (dereference only)
内部研究类型:protected_technical_synthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | e2c891cd5fb8f08a89638ca56daa00033003d72b |
| Delivery Commit SHA | e2c891cd5fb8f08a89638ca56daa00033003d72b |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | 66d9274d-4fe9-505c-87d4-2f42bc19eff2 |
| Canonical Revision | 1 |