公司有净现金14.2亿日元,权益比率63.9%,上市以来股本没有变动,扩张全靠留存利润、银行借款和租赁。市值46.2亿日元低于母公司净资产53.62亿日元。在这个价格上,持有人拿到约2.4%的股息,同时等待拆除板块的利润修复得到确认。三菱商事合作和住之江场地目前没有计入任何价值。
5699
株式会社イボキン(IBOKIN Co.,Ltd.)
株式会社イボキン(IBOKIN Co.,Ltd.,东证Standard市场,代码5699)总部在兵库县たつの市,主营建筑物和工厂设备的拆除工程,同时经营产业废弃物的收集、处理与最终填埋,以及铁与非铁废金属的加工和销售。2025年12月期销售额100.06亿日元,其中拆除34.61亿日元、环境20.26亿日元、金属45.19亿日元。
最近亮点:2026年12月期(FY12/26)上半年(1–6月)营业利润上涨135.2%至4.35亿日元,销售额49.05亿日元。拆除板块利润由亏损5600万日元转为盈利1.92亿日元,这一项几乎解释了全部增量。公司指引没有调整,隐含下半年营业利润3.65亿日元,比上半年低16%。 估值简报(价格截至2026年11月6日收盘):股价1349日元;总市值46.2亿日元(按已发行342.72万股,含库存股);预测市盈率8.46倍(按2026年12月期指引每股收益159.42日元);实绩市净率0.87倍(按2025年12月期末每股净资产1558.34日元,按2026年6月账面约为0.83倍);ROE 12.4%(2025年12月期实绩,含特别收益;IRBANK口径预测ROE为9.77%,属第三方推算);预测股息率2.37%(年度每股32日元);EV/EBITDA 3.3倍(EV=总市值+净有息负债,合32.1亿日元;净现金14.2亿日元取2026年6月末,按现金及存款减借款计,未扣租赁债务3.78亿日元;EBITDA 9.9亿日元=2025年12月期营业利润加折旧摊销)。
最大的变数是拆除板块的成本估算:利润由少数大项目的估算准确度决定,目前只有一个干净的半年。废钢价格反转会同时压低金属和环境两个板块。成交极度稀薄,近半数表决权在创业家族集团内,且未披露继承安排,退出需要折价。
综合评分59.4/100,评级B(评分版本V3.2)。暂不追高或重仓,把它当作带资产垫层、需要时间验证的小仓位观察标的。已持有者可以继续持有,新增资金宜等预计在11月13日至14日公布的第三季度业绩,再分批建仓。上半年的修复只有半年证据,第三季度业绩在冻结资料时尚未公布,所以这个判断把握一般。 当前动作:暂不追高或重仓,把它当作带资产垫层、需要时间验证的小仓位观察标的。已持有者可继续持有;新增资金宜等预计在11月13日至14日公布的第三季度业绩,重点看九个月累计的解体利润率是否守住上半年水平、全年公司指引是否维持,再分批、耐心建仓,不在稀薄成交中追价。若解体业务再次出现成本超支、持证监督员继续减少、下一个中期计划下调2033年愿景而没有资本政策补偿,或应收款再次占用现金,则降低判断,因为此时当前折价才是公允价。
报告目录
01|投资问题与当前结论
01.1|上半年的利润修复,是能力提高还是坏项目过期
这只股票现在最该回答的问题只有一个:拆除板块在2026年12月期上半年的利润修复,能不能延续。上半年板块利润由亏损5600万日元转为盈利1.92亿日元,增减2.48亿日元。集团营业利润因此上涨135.2%至4.35亿日元,营业利润率8.9%,上年同期为4.0%。
拆除板块的利润取决于少数大项目的成本估算,需求不是决定因素。2025年12月期该板块收入增长36.7%,利润反而下降43.7%至2.03亿日元,原因是几个项目的实际成本大幅超出估算。上半年,去年的坏项目陆续完工,利润随之转正。
现有证据区分不了两种解释。一种是自有监督员、超大型机械、石棉和重型拆解能力带来的估算能力提高。另一种是今年恰好没有遇到去年那样的坏项目。项目层面的利润率分布和中标率没有披露,一个干净的半年也没法替两种解释裁决。
01.2|评级B:资产垫层够厚,但要先等第三季度业绩
综合评分59.4/100,评级B(评分版本V3.2)。动作上,暂不追高或重仓,把它当作带资产垫层、需要时间验证的小仓位观察标的。已持有者可以继续持有。新增资金宜等预计在11月13日至14日公布的第三季度业绩,重点看九个月累计的拆除利润率是否守住上半年水平,全年指引是否维持,然后分批、耐心建仓,不在稀薄成交中追价。
如果修复来自可延续的能力,这家公司就是一家净现金、正常化普通利润在6亿至8亿日元、分红稳定的企业,市值却低于账面净资产,三菱商事通道和住之江场地还没有被定价。如果修复只是计算效应,利润区间中心会向下沿移动,当前折价就是合理价格。
这个判断的核心是一项能力主张:估算能力和产能是否真的在增强。能推翻它的证据也是能力观察,包括利润率、监督员人数、订单转化和应收款,价格涨跌不在其中。把握一般,因为支撑它的只有半年业绩,第三季度业绩在冻结资料时还没有公布。
01.3|利润区间、账目和折价其实是同一个问题
拆除板块的利润波动、利润区间的宽度,以及市值低于净资产这一折价,是从三个角度看同一件事:成本估算做得准不准。拆除利润决定区间的中心和宽度,区间的位置又决定当前价格算贵还是算便宜。2025年12月期印出来的净利润还含约1.4亿日元不会重复的特别利润,必须先剔除才能用这个区间。
所以第三季度业绩一次观察,会同时回答三个问题,既能重估盈利质量,也能重估区间,也能重估折价。因为这种一对三的关系,一个读数就可能让持仓被重估或被下调。第三季度业绩在冻结资料时尚未公布,结果未知。
02|公司本质与商业模式
02.1|一个拆除合同带来三次收入,价值按整条链算
三个板块是同一条物理链。拆除板块拿下工程并执行拆除,环境板块收集、处理并填埋由此产生的产业废弃物,金属板块加工并出售这些工程里产生的废钢。一个拆除合同因此产生三个收入事件:合同本身、废弃物流和废钢流。公司把一站式服务打包成「拆除总承包」概念,一个拆除工程的价值,有一部分在它带来的废弃物和废钢里。
2025年12月期销售额:拆除34.61亿日元、环境20.26亿日元、金属45.19亿日元。上半年板块利润合计等于合并营业利润,没有总部费用调整。板块之间的内部转让价格和整条链的收益没有披露,所以板块利润是观察链条收益的唯一替代指标,不能当作链条全貌。
02.2|公司靠分步买下产能增长,再花几年消化
这家公司的变化方式是买入产能,再花几年消化。1984年创业,2003年改名。2017年4月全资收购国虎工业(Kunitora Kogyo),2018年在JASDAQ上市,2022年转入东证Standard市场。2023年至2025年是最近一轮扩建:130吨级超大型机械、Mitsue和住之江场地。国虎工业是小规模买入产能的样板,Mitsue把同样的做法放大了。
当前是第三轮消化期,2024年12月期的利润峰值出现在上一轮扩建之后。今天买入的股东买在消化中途,回报窗口更可能在两到三年以后,不在下一次业绩里。2018年上市以前的私有时期财务数据没有读到。
Mitsue Co., Ltd.从2025年1月起并表(持股90.9%),把石棉拆除、拆除施工和大型重型机械纳入自有能力,也产生了集团第一块少数股东权益(约3000万日元)。它以低于净资产的价格买入,确认了6260万日元负商誉收益,说明这类产能的卖方市场很薄。2025年12月期合并经常利润比母公司高1.01亿日元,合并销售额多4.51亿日元,子公司已经是净贡献者,当年利润下降是母公司拆除估算出的问题。Mitsue全年贡献还看不到。
02.3|企业结构耐久,盈利流只有条件性
耐久的是盈利下面的那套组合:特定场所的许可、关西土地稀缺地区的自有处理场、超大型机械、持证监督员,以及净现金和63.9%的权益比率,上市后没有摊薄。这套组合挺过了一轮废钢价格周期、一次利润腰斩后的恢复,以及转入东证Standard市场,现在正被Mitsue、住之江和三菱商事框架加厚。
脆弱点也在结构里。盈利取决于几个大合同的成本估算,增长取决于上半年反而减少的监督员队伍,控制权在一个家族手里,且没有披露继承安排。盈利在5.45亿至8.24亿日元的经常利润区间里来回摆动。判断是企业大概率持续存在,而盈利流能否站在区间中心还是区间下沿,要看接下来两次业绩。这个组合只基于一个干净的半年拆除业绩和公司自己披露的产能事实。
03|产品、客户与供应链
03.1|三个板块的利润来源各不相同
2026年12月期上半年外部销售额与板块利润:拆除11.34亿日元、利润1.92亿日元(上年同期14.17亿日元、亏损5600万日元);环境11.33亿日元、利润1.16亿日元(9.95亿日元、1.26亿日元);金属26.38亿日元、利润1.27亿日元(22.11亿日元、1.15亿日元)。拆除收入下降是因为新建工程开工减少,利润却在去年坏项目完工、高难度大项目推进后大幅改善。
同一个拆除工程会同时给环境板块送去废弃物,给金属板块送去废钢,所以拆除板块的接单质量会传导到另外两个板块的吞吐量。
03.2|需求池很长,但在手订单只够一个季度
拆除需求来自日本建筑和设备存量陆续到更新年限。中期计划提到累计超过3000万亿日元的建设存量,这个池子会增长几十年。这一框架出自公司自己的计划,日本拆除行业的独立市场规模数据没有取得。
需求池长,不代表这家公司的订单可见度高。拆除在手订单2026年6月为6.18亿日元,2025年末为8.29亿日元,只覆盖板块经营规模大约一个季度。行业层面可见度好,公司层面可见度弱。环境板块的废弃物吞吐量在这家公司是持平或下降的,增长约束在产能,需求并不缺,所以环境吞吐量的增长要打折来看。
03.3|持证监督员是产能的法律闸门,人数在下降
持证现场监督员决定能承接多少拆除工程。人数2023年是26人,2025年末41人,2026年6月38人,年末目标是56人,还差约18人净增,只剩六个月。2026年4月录用了两名印尼实习生,计划再录用14人,但实习生要经过较长时间才能成为持证监督员,真正卡住项目执行的持证层没有增长。
人数下降的原因没有披露:可能是流失、资格重新分类,也可能是招募没有成功。无论哪种,增长、中期计划的可信度和承接大项目的能力都跟着这个人数走,所以招聘披露对这家公司就是战略披露。监督员对计划的约束,也解释了为什么废钢结构调整的指标达标,而吞吐量和监督员指标没有达标:问题在公司内部的交付能力,需求端没有问题。
03.4|环境板块的吞吐量已经落后于计划
2026年12月期上半年环境板块废弃物吞吐量10,748吨,折合年化约2.15万吨,低于2023年起点2.2万吨,更低于2.7万吨的计划目标。板块利润从1.26亿日元降到1.16亿日元,因为上年同期有一个富含有价物的大工程。
这个板块的利润稳定靠的是产品组合和价格,吞吐量没有贡献。住之江场地是计划指定的补救办法,开业日期因此是这个板块的验证点。吞吐量持平的原因没有披露:可能是产能限制,也可能是需求不足,两者对住之江的价值含义不同。
03.5|废钢价格同时影响三个板块
金属和环境板块是废钢价格的接受者,赚的是加工差价;同一个价格还通过回收废钢的价值影响拆除板块。2026年12月期上半年铁类废钢均价比上年高约19%,抬高了金属板块利润。2025年12月期平均价下降,两个板块的收入都下降。
价格反转因此会同时冲击两个板块,板块之间的分散是经营意义上的,在经济意义上它们暴露在同一变量下。没有使用外部废钢价格序列,也没有公布敏感度表,2026年下半年的价格路径在冻结资料时无法观察。
04|竞争格局与产业关系
04.1|三菱商事合作是一个选择权,还没有变成收入
2026年4月21日,公司与三菱商事(Mitsui & Co.)签署了战略业务合作备忘录,对接方是金属资源本部的钢铁原料部。合作有四项内容:研究向大型钢厂高效稳定供应拆除废钢的体系;提取并可视化精细的物料平衡和碳数据;IBOKIN参与三菱商事集团及其客户的拆除项目(公告称已经开始);三菱商事支持向土壤改良等静脉产业领域扩展。
公告没有附上数量、价格、排他条款和时间表,2026年12月期的指引也不依赖它。所以它是对业务质量和废钢变现质量的选择权,不是当前收入,现价似乎没有为它付钱。如果合作不转化,损失的只是这份选择权。如果转化,会同时出现三个证据:拆除订单、服务收入的性质,以及护城河的证据。三菱商事渠道的拆除是否已经产生收入没有披露,管理层会不会披露进展也不确定。
04.2|钢厂需求决定废钢价格,传到三个板块
钢厂对废钢的需求定下铁类废钢的价格,是这家公司最重要的外部对手方。价格直接进入金属板块,通过回收资源销售进入环境板块,通过回收废钢的价值进入拆除板块。2026年上半年均价上涨约19%,2025年12月期下跌,两年的方向相反,三个板块的收入跟着移动。
行业竞争是区域性的,按能力分层,同业数据没有取得。具体的竞争位置和护城河见护城河一节。
05|护城河判断
05.1|护城河是一组叠加条件,价值在于对手配齐所需的时间
保护公司不被复制的是一组条件:特定场所的废弃物处理和填埋许可(公司章程的经营目的条款勾出了许可范围)、关西土地稀缺地区的自有处理场、超大型机械、持证监督员,以及已经嵌入业主合规流程的资料。每一项单独都可以复制,价值在于对手在同一地区把整条链配齐要花多长时间。
竞争是区域性、按能力分层的,定价能力只存在于难度最高的那一层项目。这条护城河对金属板块的废钢价格敞口没有任何帮助,某个场所一旦出现许可或合规事故,损失会不成比例。
反证同样明确:2025年12月期拆除收入增长36.7%,板块利润下降43.7%,说明公司在成本估算上并没有可靠的定价优势。中标率、投标利润率、许可续期记录和监管处分都没有披露,竞争对手数据也没有取得,在东京等大都市圈与更大对手的竞争力没有验证。
05.2|超大型机械决定谁能接高难度工程
机械群包括130吨级的SK1300DLC(2023年8月)和两台ZX1800K-3(第二台2025年9月),加上已申请专利的拔桩工法。它决定哪些高难度、高利润项目能接,并扩大可投标范围。机械的回报体现在拆除板块的利润率里,不会出现在一个技术板块里。
远程操作和AI分拣是另一层:2022年12月在公司工厂做过无人远程操作的验证,2023年签过两份福岛第一核电站的工法研究合同。这些主题针对劳动力短缺和危险作业,只算选择权,近期没有收入。单台机械的利用率和收益、研发支出都没有披露。
05.3|碳数据能力是进入大业主名单的筛选条件
每个项目的二氧化碳排放和物料平衡数据,是公司赢得工程时的真实差异点。它与公司2023年加入GX联盟、RE Action承诺和EcoVadis银牌评级相呼应,这些都是大型业主筛选静脉产业供应商的指标。数据附着在拆除合同上,同时喂给三个板块,三菱商事合作也是围绕这一层展开的。
监管提高了成为合格静脉产业经营者的固定成本,这会压住小对手。服务的定价和客户采用度没有披露,2023年12月资本成本回应的内容也没有重读。
05.4|护城河靠什么维持,什么会削弱它
维持这组条件需要许可持续有效、监督员队伍不萎缩、机械保持较高负荷并维持安全合规记录。它对公司的贡献主要体现在拆除和环境板块在关西圈的利润率质量上,目前能看到的唯一间接证据,是拆除板块上半年由亏转盈,持续性只有半年证据。
削弱它的力量在结构内部:监督员数量下降、盈利依赖少数大项目的估算、家族控股。护城河当前不宜被当作支撑高估值倍数的壁垒。
06|财务质量与现金流
06.1|印出来的净利润,比可重复的盈利高出约五分之一
2025年12月期净利润上涨15.0%至5.98亿日元,营业利润却下降19.5%至6.43亿日元,经常利润下降19.2%至6.66亿日元。差别在经常利润线以下:特别利润合计1.42亿日元,包括保险收入7770万日元、收购Mitsue产生的负商誉收益6260万日元,以及200万日元的固定资产出售收益;特别损失1200万日元。税前利润7.96亿日元,比经常利润高1.3亿日元。
负商誉说明收购便宜,保险收入是真实现金,但两者都不会重复。按它们估值,净利润被高估了约五分之一,普通利润才是合适的锚。2026年12月期指引的净利润下降12.4%至5.24亿日元,正好是这一一次性基数的镜像。保险收入背后的事件,在已读资料里没有说明。
06.2|集团利润的起伏,几乎都出在拆除板块的估算上
2026年12月期上半年,集团营业利润从1.85亿日元升到4.35亿日元,增加约2.5亿日元,拆除板块的转盈一项就贡献了2.48亿日元。环境板块下降1000万日元,金属板块多出1200万日元,几乎互相抵消。因为拆除的利润由少数大项目的成本估算决定,集团利润的波动几乎等于这个板块估算精度的波动。
上半年经常利润4.31亿日元,是营业利润的99%,财务噪声很小。这个半年比较干净,也正因如此单独一个半年不够下结论:它不能区分能力和去年坏项目的完工。
06.3|全年指引暗含一个更软的下半年
2026年12月期指引在中期业绩时保持不变:销售额105亿日元、营业利润8亿日元、经常利润7.78亿日元、净利润5.24亿日元,每股收益159.42日元。扣掉上半年实绩,下半年隐含销售额55.95亿日元、营业利润3.65亿日元、经常利润3.47亿日元、净利润2.37亿日元,营业利润比上半年低16%。
最符合2025年12月期超支教训的解读是审慎:只按项目账面一定能交付的部分给指引,把完工带来的超预期留给结果。另外两种可能是已知的项目组合偏软,或者住之江和招聘带来的成本。管理层没有披露原因,审慎还是真有软区,要等第三季度和全年业绩才知道。
单季度数字也不能直接外推。第一季度营业利润2.69亿日元,占上半年约62%,隐含第二季度只有1.66亿日元,与上年先弱后强的走势相反。利润跟着项目完工日期走,半年和全年才是这家公司能传递信号的最小单位,季度不要年化。
06.4|三个板块的收入可靠度,与利润可靠度几乎相反
金属收入等于吞吐吨数乘市场价格,上半年处理28,178吨,其中88%经过自有工厂,2025年12月期是79%。环境板块是合同处理收入加与价格挂钩的资源销售。拆除是项目完工确认收入,在手订单覆盖很短。
收入的可重复性排序是环境最高、金属次之、拆除最低,而利润的可靠度却几乎反过来。金属吨数从2023年的10万吨降到2025年12月期的74,484吨,一部分是主动调整,转向在自有工厂加工,那里才赚得到利润,所以只看吨数会误读这个板块。完工确认依据估算的收入、应收款账龄、重复客户比例都没有详细披露。
06.5|利润走在现金前面:回款时点是主要的变数
2025年12月期经营现金流只有7200万日元(上年9.32亿日元),税前利润却有7.96亿日元。应收款和合同资产从10.93亿日元升到17.22亿日元,增长57%而销售额只增长3.6%,占用现金6.15亿日元,同时还缴了3.42亿日元税款。2026年12月期上半年回补了一部分:经营现金流10.43亿日元,应收款减少2.28亿日元,合同负债增加1.5亿日元。
这是同一个完工时点现象的现金一面。利润质量、现金转化和完工日期是同一个机制,一个大项目的开票时点就能让年度现金增减数亿日元。完工集中的2026年下半年,即使利润指引达成,现金也可能再度偏弱。
净现金让公司可以消化这种错期,所以单年现金偏弱是时点风险,不是偿债风险,除非应收款质量变差。现金转化要用两年窗口来判断。如果利润指引达成而现金偏弱,这件事本身不足以推翻判断。应收款账龄、质保金和客户集中度都没有披露。
06.6|资产负债表靠留存利润和借款扩张,没有摊薄股东
2025年是扩张年。土地从8.7亿日元升到19.5亿日元(买入住之江场地),租赁资产从0.98亿日元升到4.61亿日元。长期借款升到8.02亿日元(新增9亿日元授信),总资产增长28%到81.05亿日元。资本开支14.37亿日元,折旧3.44亿日元。2026年6月末权益比率63.9%,现金及存款22.75亿日元,借款8.6亿日元,净现金约14.2亿日元。
股本自成立以来没有变动,增长靠留存利润、银行借款和租赁,慢增长和不摊薄是同一个政策的两面。未提取授信额度、表外承诺和住之江剩余成本没有披露。
06.7|利息支出十二倍跳升,原因还没有解释
2026年12月期上半年支付利息1940万日元,上年同期只有160万日元,增长约十二倍,同期借款却从10.96亿日元降到8.6亿日元。公司笼统归因于与资本投资相伴的借款利息。
绝对金额相对于4.31亿日元经常利润很小。如果是手续费或利率重设,它是一次性的;如果边际融资成本结构性上升,借款支撑产能的模式就要面对更高门槛。利率固定还是浮动、授信条款都没有披露,这里只记下一个待澄清的事实,没有做解读。
06.8|正常化盈利中心在6.5亿至7.5亿日元,区间上下两成
盈利能力以经常利润为锚。母公司五年经常利润在5.45亿至8.24亿日元之间摆动,没有趋势;合并经常利润2024年12月期8.24亿日元、2025年12月期6.66亿日元,2026年12月期指引7.78亿日元。正常化中心在6.5亿至7.5亿日元,宽度上下两成,这是本研究自己的构造,公司没有公布剔除一次性因素后的利润口径。
五年合并营业利润路径是4.86亿、5.84亿、7.99亿、6.43亿日元,2026年指引为8亿日元,增长呈阶梯状,指引只比2024年的峰值高一点,销售额却多约9%。Mitsue能否抬高中心,现在还看不到。区间宽度由拆除估算的波动决定,其他板块的贡献更稳也更薄。
07|股东、董事与治理
07.1|一半表决权在创业家族,少数股东依赖家族的资本纪律
HS Kosan持有38.94%,创业者兼社长高桥克己持有11.07%,合计约一半表决权。往下股权分散,没有有分量的机构股东。资本政策、继承和任何重估事件,都在家族范围内决定,经营者和控股集团是同一方,管理质量和治理风险是同一个变量。
控制和资本是同一件事:分红固定、回购很小、扩张靠借款而不是分配或增发。资产负债表上有约3亿日元的董事退休慰劳金,没有披露继承安排,公司合并员工191人。创业者主导的扩建(Mitsue、住之江)推进很快,也带来对关键人物的依赖。HS Kosan的性质与意图、创业者的年龄和任期、任何继承或流动性安排都没有披露,股东名册为2025年12月期数据。
对少数股东来说,控股折价和流动性折价是结构性的。继承事件在任一方向上都会是重估事件,时点无法预测。
07.2|中期计划交付记录:产品结构达标,产能和财务目标落空
2024–2026年中期计划的最终年度财务目标会落空:2026年12月期指引(销售额105亿日元、营业利润8亿日元)低于计划的115亿日元和9亿日元,而且在2026年2月、一个季度都还没发生时就已经让步。
非财务指标好坏参半:废钢处理结构调整已经完成(处理74,484吨,目标77,000吨,主动压缩),环境吞吐量落后于2023年起点(21,395吨对22,000吨),持证监督员远低于56人的目标。落空的是产能,需求没有问题。
计划把2024–2028年定为投资阶段,2029年起进入回收阶段,2033年愿景是销售额300亿日元、营业利润25亿日元、员工350人,约为2025年12月期销售额的三倍。这个愿景要靠监督员和反复的产能增加,所以计划交付记录是判断现在该给愿景多少价值的先验。下一个计划预计在2027年2月业绩前后公布,会不会保留2033年愿景,以及在什么时点公布,目前未知。
08|资本政策
08.1|股东回报只有一笔固定的分红
实际的股东回报就是年末分红每股32日元,约1.05亿日元一年,2024年12月期、2025年12月期和2026年12月期指引都一样,没有中期分红。派息率分别是20.3%、17.6%和20.1%,占净资产约2.1%至2.3%。2025年利润下降时它没有动,2026年上半年利润大增时也没有动。
回购规模很小:2024年12月期2470万日元,2025年12月期310万日元,库存股仍是140,292股,占已发行股数4.1%。2024年8月9日决定的一轮回购在2025年5月2日完成,更早的一轮在2023年4月28日完成。公司在2023年12月14日披露过对东证资本成本要求的回应,内容没有重读;研究问题里把这份回应写作2023年2月,披露索引写的是12月14日,来源之间的日期不一致,这里按索引记录并保留这个矛盾。
以现价看,约2.4%的股息像债券式收入,回报要靠再评价,不能靠分红增长。提高分红或规模可观的回购,会是资本政策转向的信号。分红是否提高的讨论集中在2月的业绩公布,董事会提高分红的门槛没有披露。创业家控制偏向产能投资,不偏向分配,这解释了固定的分红。
08.2|扩张靠留存、借款和租赁,增长慢但不摊薄
资本政策的另一面是融资方式:股本自成立以来没有动,2025年12月期的土地、租赁资产和长期借款扩张全部由留存利润、银行借款和租赁支撑。2026年6月末仍是净现金,所以任何一次未来的增发都值得重新审视,因为它与现有政策相反。边际融资成本是否抬高,见财务质量一节的利息支出。
08.3|Mitsue和住之江:买产能的账怎么算
Mitsue低于净资产价格买入,确认负商誉收益6260万日元,也带来第一块少数股东权益。新增资本的回报(相对资本成本的增量ROIC)没有披露,只能通过之后的板块利润间接验证。
住之江场地(大阪,约900坪,2025年12月取得,目标2027年开业)是增长确定性最高的一项:阪神(尼崎)业务已满产,新场地把拆除需求最密的大都市圈里未满足的吞吐量转化成环境和金属板块的量,不需要创造新需求。2025年至2027年的投资阶段压低自由现金流,回报要出现在2027至2028年的板块利润里。剩余资本开支、开业成本、新增产能和许可进展都没有披露,延期会推后回报窗口。
09|估值与安全边际
09.1|市值低于净资产,价格大致落在盈利区间的下沿
2026年11月6日收盘价1349日元,总市值46.2亿日元(按342.72万已发行股,含140,292股库存股)。按2026年12月期指引每股收益159.42日元,预测市盈率8.46倍;按2025年12月期末每股净资产1558.34日元,实绩市净率0.87倍;2025年12月期ROE 12.4%,含特别收益;预测股息率2.37%;EV约32.1亿日元,EV/EBITDA 3.3倍(EBITDA 9.9亿日元=2025年12月期营业利润加折旧)。
口径要说明:市净率0.83倍来自IRBANK按2026年6月账面(每股约1631日元)计算,0.87倍用的是2025年12月期末账面,差别在账面日期。IRBANK预测ROE 9.77%,与公司披露的实绩ROE 12.4%口径不同。倍数来自一个稀薄市场的单次价格,没有分析师共识,各来源的口径差异会传到推导值上。
市值低于母公司净资产53.62亿日元,同时公司持有净现金。这个折价的看法是:市场按盈利区间的下沿定价,对三菱商事通道、住之江和资本政策变化几乎没有给价值。
09.2|折价等于区间中心和下沿之间的距离
折价的大小约等于盈利区间中心(经常利润6.5亿至7.5亿日元)与下沿之间的差距,再加上控股和流动性折价。区间宽度由拆除估算的稳定性决定,安全边际也靠这个稳定性。2025年12月期印出来的净利润含约1.4亿日元特别利润,如果据此估价,会高估盈利能力,所以估值要放在剔除后的普通利润上。
这条链是同一个问题的估值一面:拆除利润率决定区间位置,区间位置决定折价是机会还是合理定价。第三季度业绩之后,区间中心有机会被确认,也有机会被压向下沿。
09.3|下行保护保的是亏损幅度,不是持有时间
对这家体量的公司,下行保护是实在的:净现金约14.2亿日元,权益比率63.9%,土地账面18.28亿日元,母公司净资产53.62亿日元,约为总市值的116%。2025年12月期利润下降时,分红也维持住了。所以最坏情形更像在折价状态下长期停留,本金受损的可能性较小。
保护是按账面价值衡量的,压力下的变现价值没有披露。更关键的是,环境、石棉相关和其他或有负债在已读资料中没有量化,表外保证和采购承诺也没有细节,这对运营最终填埋场的拆除企业是实质缺口,可能侵蚀资产垫层。这个缺口要靠2026年12月期年度证券报告的或有负债附注和拨备变动来解决,目前没有可行的公开路径。资产与现金支撑的是进场价格,支撑不了时间,一旦退出,成交稀薄意味着要折价。
09.4|非经营资产有限,土地和证券不宜多算
投资证券6.61亿日元,对应2.74亿日元的未实现估值差额;保险准备金约1.17亿日元;土地按历史成本计,没有披露评估价。2026年上半年出售了一块土地,收入1.29亿日元,土地账面由19.5亿日元降到18.28亿日元。土地大部分就是经营用的处理场,上调估值带有推测性。证券差额是真实的,但按市价波动。证券构成和土地市价都没有披露,资产价值支撑的是低于净资产的进场价,估值时不要把它加到披露的证券差额之外。
09.5|市场预期只能从价格和指引里推出来
这只股票没有分析师覆盖,也没有一致预期,市场预期只能从报价和指引的算术里读。市场的中心看法似乎是盈利长期停在区间下沿。预期差就是区间中心的兑现与区间下沿定价之间的距离,这个距离要靠业绩来合上,叙事做不到。这里的预期是推断出来的,没有被观察到。
对耐心的持有人,不对称偏向有利;风险是时间、流动性和融资多头的放大。
09.6|成交稀薄意味着退出要付折价
月成交量只有6万至20万股,2026年11月6日下跌4.8%时只成交17,300股,当天公司没有披露任何消息。融资多头余额217,200股(2026年7月中旬数据),约占约329万股流通股的6.6%,超过一个月的典型成交量,融资空头为零。价格可以在没有消息的情况下跳空,失望的业绩会被融资多头放大。仓位大小和入场耐心比择时精度更重要。
10|Kabugami 技术结构
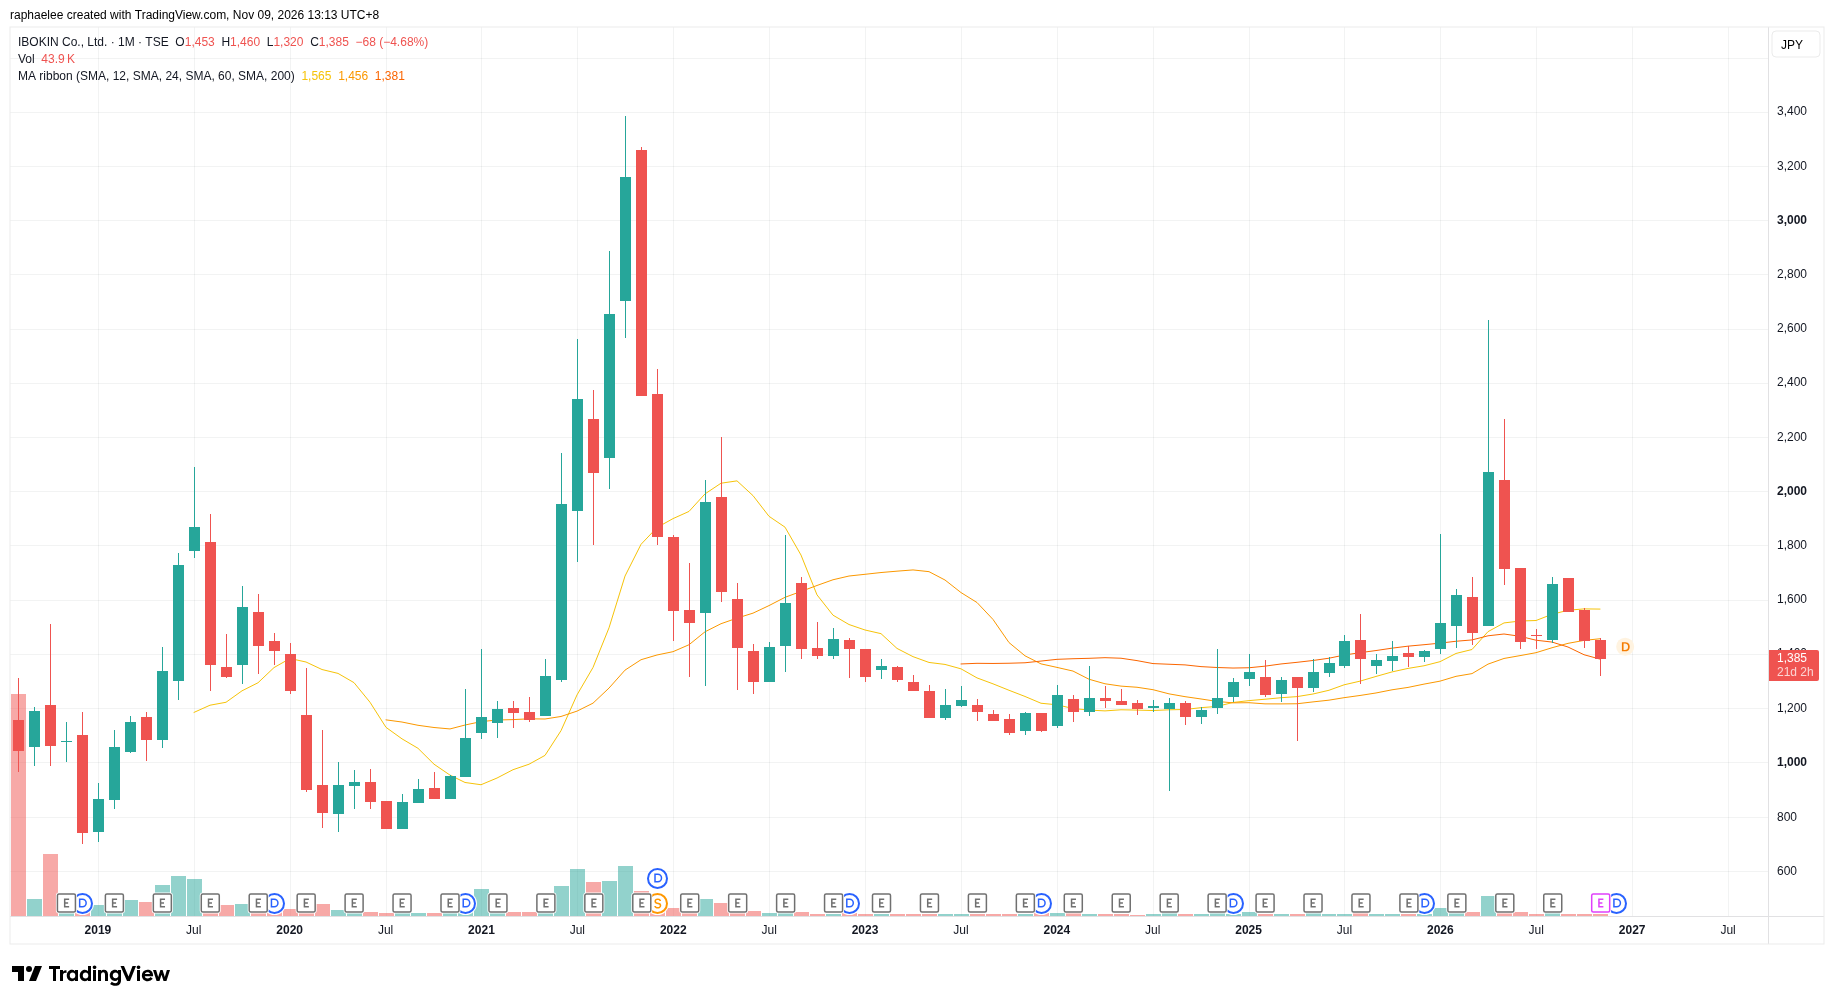
10.1|价格走完了上市后的长期下跌,多年箱体上方还没有人接手
这只股票的技术问题是:它经历过两次冲出箱体后都被打回,一次是2021年的投机高点,一次是2026年4月的合作脉冲,现在价格站在60个月均线上方,是多年来第一次停这么久。这是在业绩修复的支持下悄悄抬高重心,还是又一次被下一份令人失望的业绩赶回去?
依据是2018年8月上市至2026年10月的99根月线,加上11月6日的日线收盘价。月线已按2021年12月的1拆2调整:窗口高点3,385日元出现在2021年10月,低点699日元出现在2018年12月,与IRBANK按拆股调整的年度区间一致。数据截至2026年10月27日,11月月线尚未收完。
上市阶段(2018至2019年)价格从699日元一年内涨到2,090日元,随后腰斩。2020至2021年的投机阶段把价格推到3,385日元,2022年回吐了大部分。2023至2025年是长期箱体:年度波动区间895至1,548日元,收盘价多在1,120至1,420日元,月成交量萎缩到7万至11万股。2024年一度下探到895日元,打断了箱体的底部。
10.2|2026年4月的放量脉冲,两个月内被完全回吐
2026年4月是近期最关键的一根月线:开盘1,508日元,最高2,632日元,收盘2,070日元,成交量约123万股,是这只股票平时月成交量的17倍。5月收盘1,718日元(最高2,266日元),6月收盘1,449日元,回到脉冲前的水平。8月反弹到收盘1,659日元,到10月又回到1,449日元。
这说明高于1,700日元的区域还没有持有人在守。在没有基本面消息放量把月收盘价推过2,632日元之前,这个高点就是事件买盘的上限。脉冲的失败比较有序:价格没有回到箱体深处,而是在1,400至1,660日元之间停留了五个月,这是它与2021年那次冲高之后回落的区别。
距离2021年高点也很远:五年后价格回到高点的43%,脉冲那个月曾摸到高点的78%,旧高点只是一个遥远的心理上限,真正的问题是箱体上沿1,550至1,660日元能不能变成下沿。箱体上方除了2026年稀薄的成交,没有此前上涨留下的台阶,任何新的上涨都要自己搭台阶。
10.3|重心在抬高,但证据只有两年
10月月线收盘1,449日元,24个月均线约1,450日元,两者几乎重合。60个月均线1,397日元在下方,是托底的候选位,12个月均线1,566日元因为窗口里还含着4月的脉冲而偏高,压在上面。价格处在自己两年重心上。
低点序列的证据是这样:2018至2022年年度低点从699日元抬到1,252日元,2024年下探895日元打断,2025年低点1,080日元,2026年低点约1,400日元,抬高的低点只在最近两年重新出现。所以这更像一个近期边缘在抬高的箱体,称不上典型的下跌后逐步收敛。
6月至10月月线收盘在1,449至1,659日元,波动收窄,成交从4月脉冲回落到10万至20万股,是轻度压缩。这只股票长时间安静以后,历史上往往以事件的方式剧烈收场(比如2026年4月),所以这次压缩要看作围绕消息盘整,不是安静的吸筹。
支撑位依次是1,397至1,400日元(60个月均线和2026年低点)、1,080日元(2025年低点)、895日元(2024年低点);压力位是1,659日元,再往上是2,266至2,632日元的脉冲区域,其上只有2021年的高点3,385日元。早期699至1,100日元的箱体仍是长期底部。
当前的价格状态可以定义为「箱体上沿试探」:价格在多年箱体的上沿附近横向停留,等待业绩给出方向。旧的下行过程基本结束,新的上行状态还没有建立。技术判断把握一般。
10.4|价格先动了一次,业绩修复却没有得到同样的价格认可
以上是纯价格判断。把公开事件放在它后面对照,时间关系是这样的:4月21日披露的三菱商事合作,对应4月的放量脉冲;8月公布的拆除利润率修复,没有出现可与4月相比的价格反应,8月收盘反弹到1,659日元,10月又回到1,449日元。价格先动了一次,而业绩上的修复后来才被公开确认,但价格没有为它停留下来。
11月6日又给了一个相反的例子:没有任何公司披露,价格下跌4.8%,成交只有17,300股。这个市场会立刻为故事付钱,没有消息时随便漂移。4月的脉冲和11月的下跌都不是业绩推动的,因为这段停留还没有遇到过业绩。
第三季度业绩预计在11月13日至14日公布,会是这段停留遇到的第一次业绩事件。它给出的价格反应,比2026年已有的两次反应信息量都大,价格状态与账目现在在等同一份证据。这是跨领域的对照,没有改动上面的纯价格判断。
10.5|成交稀薄让单日价格的信号失真
从价格噪声的角度看,这只股票月成交量只有6万至20万股,2023至2025年平均7万至11万股。流通股约329万股,正常月份换手率只有2%至3%。融资多头余额217,200股(2026年7月中旬)高于一个月的典型成交量,空头为零。结果是单日价格可以没有消息就大幅移动,单次收盘价携带的信息很少,一次失望的业绩也可能被融资多头放大成更深的回落。看价格状态应该看月线收盘,不看单日。
10.6|什么价格行为会确认这个状态,什么会推翻它
确认需要看到三件事:月线收盘在2026年11月和2027年2月的业绩季里守住60个月均线(约1,397日元),把它从上方压力变成下方托底;月线收盘在放量且有基本面消息的情况下超过2026年8月的反弹高点1,659日元,打开箱体上沿;2026年年度低点不低于1,400日元,2027年的低点再高于它,把两年抬高的低点连成序列。11月6日日线收盘1,349日元已落在60个月均线下方,但11月月线尚未收完,目前不能当作确认或否定。
推翻或明显降级的条件同样有三个:月线收盘跌破60个月均线(约1,397日元),价格回到箱体内部,停留的说法不成立;月线收盘跌破2025年低点1,080日元,说明这次停留只是脉冲的残留;放量重新测试2024年低点895日元,会重新打开699至744日元的早期箱体。
11|风险与催化剂
11.1|第三季度业绩是最近的检验,之后有一串有日期的后续
2026年12月期第三季度(7–9月)业绩是最近的验证事件。公司2023至2025年每年都在11月14日公布,在2026年11月9日披露索引里这一格仍是空白,所以按节奏推断预计在11月13日至14日公布,日期是推断出来的,九个月结果在冻结资料时未知。
它会显示拆除利润率在九个月里是否守住(上半年半年板块利润约1.9亿日元的水平)。之后有一串有日期的检验:2026年12月期全年业绩和下一个中期计划(2027年2月至3月)、住之江开业(2027年)、第一批披露的三菱商事渠道交易,以及分红或回购的调整。每一项对应论点的一个变量,所以这是一份验证日程。
11.2|下半年软不软,第三季度和全年业绩会给答案
指引隐含的下半年营业利润比上半年低16%,原因没有披露。第三季度和全年业绩可以区分两种可能:审慎指引,完工带来超预期;还是真的有一段偏软的项目组合。如果是后者,又遇到第二次下调指引,对估算可信度的质疑会重新打开。只要兑现在隐含水平,就是验证了审慎。
11.3|废钢价格反转会同时打到两个板块
金属板块直接出售价格,环境板块的回收资源收入按同一个市场定价,所以价格反转是同时击中两个板块的风险。2025年12月期两个板块收入同时下降,就是证据。没有对冲工具,防御靠净现金。2026年下半年的价格路径在冻结资料时不可观察。
11.4|监督员人数是增长的前置条件,也是前瞻信号
持证监督员人数决定拆除产能、计划可信度和2033年愿景。人数在2026年上半年从41人降到38人,目标是56人。后续披露的数字会说明下降是暂时的还是在延续。如果继续减少,大项目承接能力会在2027年之前受限。下降原因没有披露。
11.5|住之江开业和三菱商事转化是两个有日期的催化剂
住之江开业(2027年目标)把环境和金属的吞吐量缺口变成产能,延期会推后回报窗口。三菱商事合作转化为已披露的交易,会同时在拆除订单、服务收入性质和护城河证据上显现,不转化只损失这份选择权。两者都落在未来四个报告期内。合作目前没有披露交易、数量、价格或排他条款,也不清楚管理层是否会披露进展。
11.6|价格和账目在等同一份证据
价格这段停留的起点是一次合作事件,不是业绩。第三季度业绩会让价格状态第一次遇到业绩事件,这一点只是时间上的对照,不改变技术判断。业绩要是确认修复,价格和账目会同时被验证;业绩要是显示成本再次超支,两者会一起落空。成交稀薄会让价格反应带有噪声。
11.7|什么会推翻这个判断
这个判断的前提是拆除利润率修复来自可延续的能力。下面任何一项出现,都说明修复只是计算效应,利润区间向下沿移动,当前的折价就是合理价格:
第三季度或全年业绩里拆除板块再次因新的成本超支而回落,不能维持上半年约1.9亿日元的半年板块利润水平;持证监督员继续减少;下一个中期计划下调2033年愿景,同时没有分红或回购的补偿;应收款再次占用现金,连续第二年。
如果被推翻,对应的动作是在稀薄成交中以结构性折价退出。反过来,下行有净现金和资产垫层,推翻窗口只有两次业绩,所以这个论点检验成本很低。
12|反常识发现
这次研究里值得单独拎出来的,是三个与表面数字方向相反的地方,它们的价值在于改变估值锚和仓位方式。
第一,2025年12月期的净利润在涨,营业利润却在跌。净利润增长15.0%,营业利润下降19.5%,里面约1.4亿日元的特别利润不会再来。看净利润的人会高估这家公司的盈利能力约五分之一。
第二,三个板块看起来分散,实际在同一个价格变量下。废钢价格的反转同时压低金属和环境的收入,拆除板块还通过回收废钢的价值间接暴露,分散是经营上的,经济上并不分散。
第三,价格为合作消息放量17倍,却没有为拆除利润率修复付出可比的价格。市场更愿意为故事付钱,这让下一次真正的业绩事件格外有信息量。
13|下一次值得跟踪什么
下面的问题按重要性排列,每一个都写明为什么重要和什么证据能解决。大多数要等未来披露,目前没有可行的公开路径。
第三季度业绩会显示什么?它决定九个月累计拆除利润率是否守住上半年水平,全年指引能否维持,是论点最近的检验。预计在11月13日至14日公布,需要看拆除板块利润和全年指引。
不变的指引里为什么藏着一个更弱的下半年?隐含营业利润3.65亿日元比上半年4.35亿日元低。如果是审慎,是好事;如果是已知的项目偏软,或住之江和招聘的成本,意味着区间中心偏低。要看第三季度和全年业绩。
三菱商事合作会不会在2027年转化为披露的交易?需要看拆除订单或钢厂废钢供应安排的数量。转化会同时是订单、服务性质和护城河证据;不转化只损失一份选择权。
下一个中期计划会不会保留2033年愿景?预计在2027年2月业绩前后公布,要看愿景数字、监督员和吞吐量目标,以及资本政策是否同步调整。
监督员人数为什么从41人降到38人?是流失、重新分类还是招募不力,决定2027年承接大项目的能力。要看后续的人数披露和招聘进度。
利息支出为什么升到1940万日元?是手续费、利率重设,还是新的年化水平,决定借款支撑产能的模式要不要面对更高门槛。要看利率条款和授信条款。
住之江还需要多少资本开支和开业成本,会增加多少阪神区域产能?这决定2027至2028年的回报窗口。
创业家族有没有继承或持股安排,会不会考虑流动性或回购?继承事件会是任一方向上的重估事件。
2026年12月期业绩会不会带来分红上调或规模可观的回购?不上调的话,董事会设定的门槛是什么?
环境、石棉相关和其他或有负债有多大?需要2026年12月期年度证券报告的或有负债附注和拨备变动。这决定资产垫层有多厚,是下行保护里目前最大的缺口。
14|Kabugami 评分卡
14.1|综合评分59.4/100,评级B
评分版本V3.2,满分100,由八个模块的得分相加,各模块以得分/满分表示。评级B的区间是55至64.9分。判断是:财务底子扎实,价格也有安全边际,但盈利质量只有半年证据,护城河、资本配置和治理偏中间,技术状态在等业绩。
财务韧性与下行防御 9.88/13:净现金约14.2亿日元,权益比率63.9%,没有摊薄;或有负债没有量化,限制了更高的分数。
竞争优势与结构耐久性 8.4/14:许可、场地、机械和合规数据是一组叠加条件,但中标率和定价证据缺失,拆除板块估算也没有表现出定价优势。
盈利质量、现金转化与资本效率 8.84/17:拆除利润由少数大项目的估算决定,利润走在现金前面,只有一个干净的半年,是这家公司最大的变数。
商业结构、产品、客户与关键依赖 6.38/11:三个板块是一条物理链,增长约束是监督员人数,废钢价格同时影响两个板块。
估值与安全边际 11.25/15:市净率0.87倍、预测市盈率8.46倍、净现金,价格大致落在盈利区间下沿;退出要付折价。
资本配置与股东回报 5.0/10:分红固定在每股32日元,回购规模很小,增长靠留存和借款。
治理、所有权与管理层 3.15/7:约一半表决权在创业家族,没有披露继承安排,计划目标落空。
Kabugami技术结构 6.5/13:旧的下行过程基本结束,新的上行状态尚未建立,价格在等第一次业绩裁决。
八项合计59.4/100。第三季度业绩如果确认拆除利润率可持续,盈利质量、护城河和估值的得分有上升空间;如果再次出现成本超支,这几项会一起下调。
14.2|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 9.88 | 2026年6月末现金及存款22.75亿日元,借款8.6亿日元,净现金约14.2亿日元,权益比率63.9%,上市以来股本未变,扩张靠留存利润、银行借款和租赁,没有摊薄股东。2025年12月期资本开支14.37亿日元、折旧3.44亿日元,总资产增长28%,资产负债表仍然稳健。对这家体量的公司,下行保护是实在的,但保护的是亏损的幅度,不是持有的时间。 |
| 竞争优势与结构耐久性 | 14 | 8.4 | 公司的护城河是一组叠加的条件,而不是单一壁垒:特定场所的废弃物处理和填埋许可、关西土地稀缺地区的自有处理场、130吨级超大型拆解机械、持证现场监督员,以及已嵌入业主合规流程的减碳和物料平衡数据。每一项单独都能被复制,价值在于对手在同一地区把整条链配齐所需的时间。竞争是区域性、按能力分层的,定价能力只存在于项目难度最高的那一层。 |
| 盈利质量、现金转化与资本效率 | 17 | 8.84 | 盈利质量是这家公司最大的变数。解体板块靠成本估算赚钱或亏钱,2025年12月期收入增长36.7%、板块利润下降43.7%至2.03亿日元;2026年上半年板块利润从亏损5600万日元转为盈利1.92亿日元,带动集团营业利润增长135.2%至4.35亿日元,营业利润率8.9%(上年同期4.0%)。2025年12月期净利润增长15.0%至5.98亿日元,其中约1.4亿日元是负商誉收益6260万日元和保险收入7770万日元,营业利润实际下降19.5%,印出来的净利润高估了可重复盈利约五分之一。 |
| 商业结构、产品、客户与关键依赖 | 11 | 6.38 | 解体、环境、金属三块是同一条物理链:拆解拿到工程,环境板块收集处理和填埋废料,金属板块加工并出售废钢,一个解体工程产生三次收入事件。2025年12月期销售额分别为解体34.61亿日元、环境20.26亿日元、金属45.19亿日元。需求端是日本建筑和设备存量陆续到更新年限,计划中提到累计超过3000万亿日元的建设存量,需求池很长;真正的增长约束是能力,而不是订单。 |
| 估值与安全边际 | 15 | 11.25 | 2026年11月6日收盘价1349日元,市值约46.2亿日元(按已发行股数342.72万股),按公司指引每股收益159.42日元的预测市盈率约8.5倍,按2025年12月期末每股净资产1558.34日元的市净率约0.87倍(按2026年6月账面值约0.83倍),预测股息率2.37%,企业价值约32.1亿日元,EV/EBITDA约3.3倍。市值低于母公司净资产53.62亿日元,价格大致相当于正常化盈利区间的下沿,对三菱商事通道、住之江和资本政策变化几乎没有给价值。 |
| 资本配置与股东回报 | 10 | 5 | 实际的股东回报只有分红:年末每股32日元(约1.05亿日元),2024年12月期、2025年12月期和2026年12月期预测都不变,没有中期分红,派息率约20%,占净资产约2.1%至2.3%。利润下降时没有降,上半年利润大增也没有提。回购规模很小(2024年12月期2470万日元,2025年12月期310万日元),库存股仍为4.1%(14.03万股)。资本配置的重心是以收购方式分步购买产能:国虎工业(2017年)、三枝(2025年,低于净资产收购并产生负商誉)、住之江场地。 |
| 治理、所有权与管理层 | 7 | 3.15 | 约一半表决权在创业家族集团内:HS Kosan持有38.94%,创业者兼社长高桥克己持有11.07%,其余股东分散,没有有分量的机构股东。经营者和控股集团是同一方,管理质量和治理风险是同一个变量。资产负债表上有约3亿日元的董事退休慰劳金,没有披露继承安排;集团合并员工191人,创业者主导的建设项目(三枝、住之江)推进很快,也带来关键人物依赖。 |
| Kabugami 技术结构 | 13 | 6.5 | 自2018年上市以来价格区间为699日元至3385日元(已按2021年12月的1拆2调整)。经历上市期、2021年10月的投机顶、2023年至2025年的长期横盘、2024年下探895日元后,2026年4月因三菱商事合作出现一次放量脉冲(高点2632日元,成交量约为平时17倍),两个月内被完全回吐。此后价格在约1400至1660日元之间运行,10月月线收盘1449日元,恰在24个月均线(约1450日元)附近,位于60个月均线(约1397日元)之上。11月6日收盘1349日元、下跌4.8%而成交仅1.73万股,日线已落在60个月均线下方,但该月月线尚未收完,不能作为确认依据。旧的下行过程基本结束,新的上行状态尚未建立。 |
总分: 59.4 / 100 评级: B 操作建议: 暂不追高或重仓,把它当作带资产垫层、需要时间验证的小仓位观察标的。已持有者可继续持有;新增资金宜等预计在11月13日至14日公布的第三季度业绩,重点看九个月累计的解体利润率是否守住上半年水平、全年公司指引是否维持,再分批、耐心建仓,不在稀薄成交中追价。若解体业务再次出现成本超支、持证监督员继续减少、下一个中期计划下调2033年愿景而没有资本政策补偿,或应收款再次占用现金,则降低判断,因为此时当前折价才是公允价。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
本报告的研究日期为2026年11月9日。使用的公开资料包括:公司2025年12月期财报(2026年2月13日披露)、2026年12月期第一季度财报(2026年5月15日)、上半年财报和上半年业绩说明材料(2026年8月10日)。
另有2024–2026年中期经营计划(2024年3月28日)、与三菱商事的合作备忘录(2026年4月21日,PR TIMES)、证券报告数据(2026年3月23日,通过G-Biz Info转载EDINET数据)和公司章程。行情和披露记录来自IRBANK的行情页面(2026年11月6日)和适时披露索引(2026年11月9日)。
价格历史来自雅虎财经图表数据的本地整理,月线截至2026年10月27日,另加11月6日日线收盘价。
限制如下。第三季度业绩在冻结资料时没有公布,九个月结果未知。没有分析师覆盖和一致预期。倍数来自一个稀薄市场的单次价格,各来源的账面日期和ROE口径不同。
2026年下半年废钢价格、拆除行业的独立市场规模数据、竞争对手数据都没有取得,也没有使用外部废钢价格序列。正常化盈利区间是本研究自己构造的,公司没有披露剔除一次性因素后的口径。2023年12月资本成本回应的内容没有重读。融资余额数据为2026年7月中旬,股东名册为2025年12月期数据。
本报告仅用于研究,不构成投资建议,也不保证未来表现。所有材料来自公开披露,投资决定及其后果由读者自行负责。
主要资料来源
- Securities report data for IBOKIN (FY12/2025): major shareholders and company profile
- Articles of incorporation: registered English name and business purposes
- FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume
- H1 FY12/2026 results briefing materials: management's framing of the strategy
- H1 FY12/2026 interim results (tanshin): headline earnings
- Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system
- Medium-term management plan 2024-2026: targets and ten-year vision
- Q1 FY12/2026 results (tanshin): management narrative for the first quarter
- IRBANK stock page snapshot for 5699 (6 November 2026)
- IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023
- Locally recomputed monthly series: the April 2026 volume pulse and its retracement
研究发现索引
展开本次 Review 的 69 项研究发现
F001|02|一个拆除合同带来三次收入,价值按整条链算
研究范围:开放研究+35项覆盖检查
写入正文:02|一个拆除合同带来三次收入,价值按整条链算03|三个板块的利润来源各不相同
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、23、24
Articles of incorporation: registered English name and business purposes怎么使用:直接 / 支持;一手验证:01;同业比较:13;其他用途:历史
Securities report data for IBOKIN (FY12/2025): subsidiaries and employees怎么使用:直接 / 支持;同业比较:07;其他用途:历史
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接证据;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
H1 FY12/2026 results briefing materials: management's framing of the strategy怎么使用:直接证据;一手验证:02、08;专项深挖:02、08
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Securities report data for IBOKIN (FY12/2025): major shareholders and company profile;直接证据 / 支持证据 / 一手证据(研究域01) / 历史/同业比较(研究域13)|Articles of incorporation: registered English name and business purposes;直接证据 / 支持证据 / 历史/同业比较(研究域07)|Securities report data for IBOKIN (FY12/2025): subsidiaries and employees;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume;直接证据 / 一手证据(研究域02) / 一手证据(研究域08) / 定向深挖(研究域02) / 定向深挖(研究域08)|H1 FY12/2026 results briefing materials: management's framing of the strategy
完整研究记录(核对用)
研究原文:IBOKIN (5699) is a Hyogo-based demolition-and-recycling group whose three segments are one physical chain. Demolition wins and executes the dismantling, environment collects, treats and landfills the waste, and metals processes and sells the scrap. Each demolition mandate therefore produces three revenue events (the contract, the waste flow and the scrap flow), so chain capture is the unit of value, not segment share. FY12/25 sales were demolition JPY 3,461m, environment JPY 2,026m and metals JPY 4,519m.
内部研究类型:business_model_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Earnings quality depends on chain capture rates and any internal transfer pricing, neither of which is disclosed. Segment profit is the only observable proxy.
不确定性(原始记录):Inter-segment transfer pricing and chain-level economics are not disclosed.
F002|01|上半年的利润修复,是能力提高还是坏项目过期
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|上半年的利润修复,是能力提高还是坏项目过期06|集团利润的起伏,几乎都出在拆除板块的估算上14|综合评分59.4/100,评级B
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接 / 支持;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins怎么使用:直接证据;一手验证:16;反向验证:14、19、32;专项深挖:16、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume;直接证据 / 一手证据(研究域16) / 反证(研究域14) / 反证(研究域19) / 反证(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins
完整研究记录(核对用)
研究原文:Demolition is the swing segment because its profit is made or lost in cost estimation on a few large projects, not in demand. FY12/25 revenue rose 36.7% while segment profit fell 43.7% to JPY 203m on estimate misses. In H1 FY12/26 segment profit moved from a JPY 56m loss to a JPY 192m profit as those projects rolled off, a swing of about JPY 248m, and this drove group operating profit up 135.2% to JPY 435m on sales of JPY 4,905m. Environment contributed JPY 116m and metals JPY 127m. H1 operating margin was 8.9%, up from 4.0%. The open question is whether the repair is a durable capability or the absence of last year's bad projects.
内部研究类型:swing_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):This one variable drives group earnings volatility, the normalised band, the valuation discount and the verdict on the thesis.
不确定性(原始记录):Project-level margin dispersion and win rates are undisclosed. One clean half cannot separate capability from roll-off arithmetic.
F003|03|废钢价格同时影响三个板块
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论03|废钢价格同时影响三个板块11|废钢价格反转会同时打到两个板块12|三个与表面数字相反的读数
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接 / 支持;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
H1 FY12/2026 results briefing materials: scrap-price backdrop and segment narratives怎么使用:直接 / 支持;一手验证:12;外部现实校验:02、05、11、15、19
FY12/2025 results (tanshin): the FY12/25 scrap-price backdrop怎么使用:直接证据;一手验证:12;专项深挖:12、14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域11) / 外部现实(研究域15) / 外部现实(研究域19)|H1 FY12/2026 results briefing materials: scrap-price backdrop and segment narratives;直接证据 / 一手证据(研究域12) / 定向深挖(研究域12) / 定向深挖(研究域14)|FY12/2025 results (tanshin): the FY12/25 scrap-price backdrop
完整研究记录(核对用)
研究原文:Metals and environment are scrap-price takers earning a processing margin, and the same price also touches demolition through recovered-scrap value. In H1 FY12/26 a ferrous average about 19% higher lifted metals profit. Environment profit eased because the prior year held an unusually valuable one-off job. In FY12/25 the average fell and revenue dropped in both segments. A price reversal therefore hits two segments at once, so the diversification is operational, not economic. The H2 FY12/26 price path is unobservable at the freeze date.
内部研究类型:external_price_exposure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Earnings should be capitalised at mid-band, not at a single print. Net cash, not hedging, is the defence.
不确定性(原始记录):No external price series was used and no sensitivity table is published. Scrap pricing in H2 FY12/26 is unknown.
F004|06|印出来的净利润,比可重复的盈利高出约五分之一
研究范围:开放研究
写入正文:06|印出来的净利润,比可重复的盈利高出约五分之一12|三个与表面数字相反的读数
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/2025 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:32;其他用途:历史
FY12/2025 results (tanshin): special profits and losses below the ordinary line怎么使用:直接 / 支持;一手验证:32;反向验证:28;同业比较:16、35;其他用途:历史
H1 FY12/2026 interim results (tanshin): interest expense step-change怎么使用:直接证据;一手验证:14、32;反向验证:16、18、20、25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域32)|FY12/2025 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域35) / 反证(研究域28)|FY12/2025 results (tanshin): special profits and losses below the ordinary line;直接证据 / 一手证据(研究域14) / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域18) / 反证(研究域20) / 反证(研究域25)|H1 FY12/2026 interim results (tanshin): interest expense step-change
完整研究记录(核对用)
研究原文:FY12/25 net income rose 15.0% to JPY 598m while operating profit fell 19.5%, because about JPY 140m of special profits sat below the ordinary line. These were a JPY 62.6m negative-goodwill gain on the Mitsue acquisition and JPY 77.7m of insurance income. The FY12/26 forecast net decline of 12.4% is the mirror image. Printed net income overstates recurring power by roughly a fifth. The negative goodwill reflects a cheap acquisition and the insurance income is cash, but neither recurs.
内部研究类型:accounting_distortion
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Valuation anchored on printed FY12/25 net income inherits the distortion. Ordinary profit is the correct anchor.
不确定性(原始记录):The underlying event behind the insurance income is not described in the sources read.
F005|07|一半表决权在创业家族,少数股东依赖家族的资本纪律
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论07|一半表决权在创业家族,少数股东依赖家族的资本纪律
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、23、24
Securities report data for IBOKIN (FY12/2025): subsidiaries and employees怎么使用:直接 / 支持;同业比较:07;其他用途:历史
Securities report data for IBOKIN (FY12/2025): the top-ten register in detail怎么使用:直接证据;一手验证:24;外部现实校验:07、23;反向验证:01;专项深挖:24
Securities report data for IBOKIN: employee counts and group scale怎么使用:直接证据;一手验证:23;专项深挖:23
Securities report data for IBOKIN (FY12/2025): history, capital and listing path怎么使用:直接证据;一手验证:09、25、33;专项深挖:01、25、33;同业比较:01、23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Securities report data for IBOKIN (FY12/2025): major shareholders and company profile;直接证据 / 支持证据 / 历史/同业比较(研究域07)|Securities report data for IBOKIN (FY12/2025): subsidiaries and employees;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 外部现实(研究域23) / 反证(研究域01) / 定向深挖(研究域24)|Securities report data for IBOKIN (FY12/2025): the top-ten register in detail;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Securities report data for IBOKIN: employee counts and group scale;直接证据 / 一手证据(研究域09) / 一手证据(研究域25) / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域25) / 定向深挖(研究域33)|Securities report data for IBOKIN (FY12/2025): history, capital and listing path
完整研究记录(核对用)
研究原文:About half the votes sit in the founding bloc: HS Kosan 38.94% and founder-president Katsumi Takahashi 11.07%. The register below that is dispersed and has no institutional holder of consequence. Capital policy, succession and any re-rating event are decided inside the founding perimeter. Control and capital are one story: a flat dividend, small buybacks and expansion funded by debt, not distributions or equity. A directors' retirement allowance of about JPY 300m sits on the balance sheet, and no succession arrangement is disclosed. The group has 191 consolidated employees. The founder's programme (Mitsue, Suminoe) was executed fast, which brings key-man exposure with it.
内部研究类型:governance_control
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Minority holders depend on family capital discipline. Any succession event would be a re-rating event in either direction, and the control and illiquidity discount is structural.
不确定性(原始记录):The intentions of HS Kosan, the founder's age and tenure, and any succession or liquidity plan are not disclosed. Register data is as of FY12/25.
F006|07|一半表决权在创业家族,少数股东依赖家族的资本纪律
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论07|一半表决权在创业家族,少数股东依赖家族的资本纪律
归并到:F005
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): major shareholders and company profile怎么使用:直接证据;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Securities report data for IBOKIN (FY12/2025): major shareholders and company profile
完整研究记录(核对用)
研究原文:HS Kosan Co., Ltd. is the largest shareholder at 38.94% of issued shares, part of the founding bloc.
内部研究类型:related_entity
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Its decisions on capital policy and exit shape the minority outcome.
不确定性(原始记录):The holder's nature and intentions are not described in any primary source read.
F007|07|一半表决权在创业家族,少数股东依赖家族的资本纪律
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论07|一半表决权在创业家族,少数股东依赖家族的资本纪律
归并到:F005
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): major shareholders and company profile怎么使用:直接证据;一手验证:01、23、24
Securities report data for IBOKIN (FY12/2025): history, capital and listing path怎么使用:直接证据;一手验证:09、25、33;专项深挖:01、25、33;同业比较:01、23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Securities report data for IBOKIN (FY12/2025): major shareholders and company profile;直接证据 / 一手证据(研究域09) / 一手证据(研究域25) / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域25) / 定向深挖(研究域33)|Securities report data for IBOKIN (FY12/2025): history, capital and listing path
完整研究记录(核对用)
研究原文:Katsumi Takahashi is the founder, representative director-president and 11.07% holder. The operating founder and the controlling bloc are the same party, so management quality and governance risk are one variable.
内部研究类型:related_entity
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Key-man dependence and the FY12/25-era build-out are his programme.
不确定性(原始记录):Succession is undisclosed.
F008|04|三菱商事合作是一个选择权,还没有变成收入
研究范围:开放研究+35项覆盖检查
写入正文:04|三菱商事合作是一个选择权,还没有变成收入11|住之江开业和三菱商事转化是两个有日期的催化剂
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system怎么使用:直接 / 支持;一手验证:07
Mitsui & Co. alliance release: the four workstreams in detail怎么使用:直接证据;一手验证:07;专项深挖:07
Securities report data for IBOKIN (FY12/2025): the top-ten register in detail怎么使用:直接证据;一手验证:24;外部现实校验:07、23;反向验证:01;专项深挖:24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07)|Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Mitsui & Co. alliance release: the four workstreams in detail;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 外部现实(研究域23) / 反证(研究域01) / 定向深挖(研究域24)|Securities report data for IBOKIN (FY12/2025): the top-ten register in detail
完整研究记录(核对用)
研究原文:The 21 April 2026 Mitsui & Co. MOU has four workstreams: a stable scrap supply system to major steelmakers, material-balance and carbon data, IBOKIN's participation in Mitsui-group demolition projects (stated as already beginning), and soil-remediation expansion support. It attaches no volumes, prices, exclusivity or dates, and nothing in the FY12/26 forecast depends on it. It is an option on volume quality and scrap realisation, not current revenue, and the price does not appear to pay for it. Its conversion into disclosed transactions is the catalyst to verify.
内部研究类型:strategic_option
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Non-conversion costs only the option. Conversion would show up simultaneously as deal flow, service-revenue character and moat evidence.
不确定性(原始记录):Whether Mitsui-channel demolition has produced any revenue is not disclosed, and so is whether management will disclose progress at all.
F009|02|公司靠分步买下产能增长,再花几年消化
研究范围:开放研究
归并到:F035
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): subsidiaries and employees怎么使用:直接证据;同业比较:07;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域07)|Securities report data for IBOKIN (FY12/2025): subsidiaries and employees
完整研究记录(核对用)
研究原文:Kunitora Kogyo Co., Ltd. has been a wholly owned subsidiary since April 2017. It shows the group uses small acquisitions to internalise processing and works capacity, a template the Mitsue deal repeated at larger scale.
内部研究类型:related_entity
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Evidence of a repeated capacity-by-acquisition pattern.
不确定性(原始记录):Standalone economics are not disclosed.
F010|02|公司靠分步买下产能增长,再花几年消化
研究范围:开放研究+35项覆盖检查
写入正文:02|公司靠分步买下产能增长,再花几年消化08|Mitsue和住之江:买产能的账怎么算
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): subsidiaries and employees怎么使用:直接 / 支持;同业比较:07;其他用途:历史
FY12/2025 results (tanshin): special profits and losses below the ordinary line怎么使用:直接证据;一手验证:32;反向验证:28;同业比较:16、35;其他用途:历史
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域07)|Securities report data for IBOKIN (FY12/2025): subsidiaries and employees;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域35) / 反证(研究域28)|FY12/2025 results (tanshin): special profits and losses below the ordinary line;直接证据 / 支持证据|FY12/2025 results (tanshin): parent-only results against consolidated;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit
完整研究记录(核对用)
研究原文:Mitsue Co., Ltd. has been consolidated since January 2025 (90.9% held). It brought asbestos removal, demolition construction and large heavy machinery in-house. It was acquired below net asset value, producing the JPY 62.6m negative-goodwill gain, and it created the group's first minority interest (about JPY 30m). Consolidated FY12/25 ordinary profit exceeded the parent's by about JPY 101m on JPY 451m more sales, so subsidiaries are net contributors and the FY12/25 profit decline was a parent demolition-estimation event. In-house capability widens the biddable project set and removes a subcontractor margin layer on the high-difficulty work whose pricing caused the overruns.
内部研究类型:acquisition_capability
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):It mechanically supports the margin-repair thesis. The low purchase price signals a thin seller's market for such capacity.
不确定性(原始记录):Mitsue's full-year contribution to the earnings band is not yet observable.
F011|03|需求池很长,但在手订单只够一个季度
研究范围:开放研究+35项覆盖检查
写入正文:03|需求池很长,但在手订单只够一个季度
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Medium-term management plan 2024-2026: targets and ten-year vision怎么使用:直接证据;一手验证:05、11、14;反向验证:09;同业比较:04、30;其他用途:历史
H1 FY12/2026 results briefing materials: metals segment detail怎么使用:直接证据;一手验证:15;专项深挖:15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域14) / 历史/同业比较(研究域04) / 历史/同业比较(研究域30) / 反证(研究域09)|Medium-term management plan 2024-2026: targets and ten-year vision;直接证据 / 一手证据(研究域05)|Q1 FY12/2026 results (tanshin): management narrative for the first quarter;直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|H1 FY12/2026 results briefing materials: metals segment detail
完整研究记录(核对用)
研究原文:Demolition demand is a stock-turnover flow set by the age of Japan's building and plant stock. The plan frames over JPY 3,000 trillion of cumulative construction stock reaching renewal age, so the pool grows for decades. The environment waste volume leg is flat or shrinking at this company. Backlog cover is only about one quarter of segment run-rate (JPY 618m at June 2026; JPY 829m at FY12/25), so visibility is good at industry level and weak at company level.
内部研究类型:end_market
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Capacity, not order demand, is the growth constraint. Environment volume growth should be discounted.
不确定性(原始记录):Independent market-size data for Japanese demolition was not obtained, and the framing is the company's own plan.
F012|06|全年指引暗含一个更软的下半年
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|全年指引暗含一个更软的下半年11|下半年软不软,第三季度和全年业绩会给答案
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
FY12/2026 consolidated forecast as first issued with the FY12/2025 results怎么使用:直接 / 支持;同业比较:31;其他用途:历史
H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half怎么使用:直接 / 支持;一手验证:31、35;反向验证:30;专项深挖:31、35
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接 / 支持;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;直接证据 / 支持证据 / 历史/同业比较(研究域31)|FY12/2026 consolidated forecast as first issued with the FY12/2025 results;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume
完整研究记录(核对用)
研究原文:The FY12/26 forecast was left unchanged at the interim print (sales JPY 10,500m, operating profit JPY 800m, ordinary JPY 778m, net JPY 524m, EPS JPY 159.42). H1 delivered JPY 435m of operating profit, so the implied H2 is JPY 365m of operating profit on JPY 5,595m of sales and JPY 237m of net income, about 16% below H1. The reading that fits the post-overrun experience is prudence: guide to what the project book can certainly deliver and let completions surprise upward. The alternatives are a known softer project mix, or costs at Suminoe and in hiring.
内部研究类型:forecast_arithmetic
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Delivery at merely the implied level validates prudence. A second forecast cut would reopen the estimation-credibility question.
不确定性(原始记录):Management's reason is not disclosed. Prudence versus a soft patch is unresolved until the Q3 and annual prints.
F013|06|全年指引暗含一个更软的下半年
研究范围:开放研究+35项覆盖检查
写入正文:06|全年指引暗含一个更软的下半年
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
查看完整证据标签(核对用)
直接证据 / 支持证据|Q1 FY12/2026 results (tanshin): first-quarter earnings;直接证据 / 支持证据|Q1 FY12/2026 results (tanshin): the front-loaded quarter and the implied Q2
完整研究记录(核对用)
研究原文:Quarterly profit is project-completion driven. Q1 FY12/26 produced JPY 269m of operating profit (about 62% of H1) and the implied Q2 about JPY 166m. This is the reverse of the prior year, when a weak H1 became a strong H2. Half-year and full-year prints are the smallest units that carry signal, and quarters should not be annualised.
内部研究类型:earnings_shape
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Prevents misreading single-quarter prints in either direction.
不确定性(原始记录):Completion dates are not disclosed.
F014|07|中期计划交付记录:产品结构达标,产能和财务目标落空
研究范围:开放研究+35项覆盖检查
写入正文:07|中期计划交付记录:产品结构达标,产能和财务目标落空
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Medium-term management plan 2024-2026: targets and ten-year vision怎么使用:直接 / 支持;一手验证:05、11、14;反向验证:09;同业比较:04、30;其他用途:历史
Medium-term management plan 2024-2026: non-financial KPI table怎么使用:直接 / 支持;同业比较:06、11;其他用途:历史
FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end怎么使用:直接 / 支持;反向验证:06
Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023怎么使用:直接证据;专项深挖:28;同业比较:02、09、28、33;其他用途:历史
Medium-term management plan 2024-2026: staging and the 2033 vision怎么使用:直接 / 支持;一手验证:09;专项深挖:05、09、11
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域14) / 历史/同业比较(研究域04) / 历史/同业比较(研究域30) / 反证(研究域09)|Medium-term management plan 2024-2026: targets and ten-year vision;直接证据 / 支持证据 / 历史/同业比较(研究域06) / 历史/同业比较(研究域11)|Medium-term management plan 2024-2026: non-financial KPI table;直接证据 / 支持证据 / 反证(研究域06)|FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域28) / 历史/同业比较(研究域33) / 定向深挖(研究域28)|Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023;直接证据 / 支持证据 / 一手证据(研究域09) / 定向深挖(研究域05) / 定向深挖(研究域09) / 定向深挖(研究域11)|Medium-term management plan 2024-2026: staging and the 2033 vision
完整研究记录(核对用)
研究原文:The 2024-2026 medium-term plan will miss its final-year headline targets. FY12/26 guidance (sales JPY 10.5bn, operating profit JPY 800m) concedes the JPY 11.5bn and JPY 900m targets, and it was conceded in February, before any quarter of the year. KPIs are mixed: the scrap-mix shift is achieved (74,484 tonnes handled against a 77,000 target), environment intake is behind its 2023 start (21,395 against 22,000), and supervisors are far behind (against 56). The miss is a capacity story, not a demand story. The plan stages 2024-2028 as investment and recovery from 2029, with a 2033 vision of JPY 30bn sales and JPY 2.5bn operating profit, about triple FY12/25 sales. The five-year consolidated operating-profit path (486/584/799/643, 800 forecast) shows step-like growth. The next plan, expected around the February 2027 results, will show whether the 2033 vision and capital policy survive the 2024-2026 delivery record.
内部研究类型:plan_credibility
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The plan's delivery pattern is the prior for how much of the 2033 vision to capitalise today.
不确定性(原始记录):Whether the successor plan keeps the 2033 vision, and when it will be published, are unknown.
F015|03|持证监督员是产能的法律闸门,人数在下降
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end怎么使用:直接 / 支持;反向验证:06
H1 FY12/2026 results briefing materials: operating KPIs and volumes怎么使用:直接 / 支持;一手验证:06;反向验证:08、10、13、35
Medium-term management plan 2024-2026: non-financial KPI table怎么使用:直接 / 支持;同业比较:06、11;其他用途:历史
Articles of incorporation: business purposes as the licensed scope怎么使用:直接证据;一手验证:06、10、13;专项深挖:10
H1 FY12/2026 results briefing materials: hiring, foreign trainees and human capital怎么使用:直接证据;外部现实校验:06;反向验证:04;专项深挖:06
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域06)|FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域08) / 反证(研究域10) / 反证(研究域13) / 反证(研究域35)|H1 FY12/2026 results briefing materials: operating KPIs and volumes;直接证据 / 支持证据 / 历史/同业比较(研究域06) / 历史/同业比较(研究域11)|Medium-term management plan 2024-2026: non-financial KPI table;直接证据 / 一手证据(研究域06) / 一手证据(研究域10) / 一手证据(研究域13) / 定向深挖(研究域10)|Articles of incorporation: business purposes as the licensed scope;直接证据 / 外部现实(研究域06) / 反证(研究域04) / 定向深挖(研究域06)|H1 FY12/2026 results briefing materials: hiring, foreign trainees and human capital
完整研究记录(核对用)
研究原文:Licensed site supervisors are the binding constraint on demolition capacity. The count went 26 (2023), 41 (FY12/25 year-end), 38 (June 2026) against a target of 56 for end-2026. The target now needs about eighteen net additions in six months. Two Indonesian trainees were hired in April 2026, with fourteen more planned, but the licensed layer that legally gates project execution is not growing. The question is attrition, reclassification or hiring failure.
内部研究类型:capacity_constraint
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Growth, plan credibility and the capacity to take large projects all scale with licensed headcount, so a hiring disclosure is a strategy disclosure.
不确定性(原始记录):The cause of the decline is undisclosed. The trainee pipeline has a long lag.
F016|06|利息支出十二倍跳升,原因还没有解释
研究范围:开放研究+35项覆盖检查
写入正文:06|利息支出十二倍跳升,原因还没有解释
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): interest expense step-change怎么使用:直接 / 支持;一手验证:14、32;反向验证:16、18、20、25
H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins怎么使用:直接 / 支持;一手验证:16;反向验证:14、19、32;专项深挖:16、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域18) / 反证(研究域20) / 反证(研究域25)|H1 FY12/2026 interim results (tanshin): interest expense step-change;直接证据 / 支持证据 / 一手证据(研究域16) / 反证(研究域14) / 反证(研究域19) / 反证(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins
完整研究记录(核对用)
研究原文:Interest paid rose roughly twelvefold to JPY 19.4m in H1 FY12/26 from JPY 1.6m while borrowings fell from JPY 1,096m to JPY 860m. The company attributes it generally to borrowing accompanying capital investment. The amount is small against JPY 431m of ordinary profit. If it is fees or a rate reset it is a one-off, but if marginal funding cost has structurally risen, the debt-funded capacity model carries a higher hurdle.
内部研究类型:unexplained_anomaly
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Absolute materiality is capped by size. It matters as a signal of funding-cost structure.
不确定性(原始记录):Whether rates are fixed or floating, and the facility terms, are undisclosed. It is recorded as a fact to clarify, not interpret.
F017|06|利润走在现金前面:回款时点是主要的变数
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/2025 balance sheet: the receivables build that absorbed operating cash flow怎么使用:直接 / 支持;一手验证:19;外部现实校验:32;反向验证:15、17、35;专项深挖:17、19
FY12/2025 consolidated cash flow: capex year funded by long-term borrowing怎么使用:直接 / 支持;一手验证:17;同业比较:19、20、25;其他用途:历史
H1 FY12/2026 interim results (tanshin): cash flow statement怎么使用:直接证据;一手验证:17、19
FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities怎么使用:直接证据;一手验证:18、20、21、25;专项深挖:18;同业比较:29;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域32) / 反证(研究域15) / 反证(研究域17) / 反证(研究域35) / 定向深挖(研究域17) / 定向深挖(研究域19)|FY12/2025 balance sheet: the receivables build that absorbed operating cash flow;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25)|FY12/2025 consolidated cash flow: capex year funded by long-term borrowing;直接证据 / 一手证据(研究域17) / 一手证据(研究域19)|H1 FY12/2026 interim results (tanshin): cash flow statement;直接证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域25) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities
完整研究记录(核对用)
研究原文:FY12/25 operating cash flow was only JPY 72m (JPY 932m the prior year) on JPY 796m of pre-tax profit, because receivables and contract assets rose 57% (JPY 1,093m to JPY 1,722m, a JPY 615m cash absorption) on 3.6% sales growth, with JPY 342m of tax also paid. H1 FY12/26 reversed part of this: operating cash flow was JPY 1,043m, with a JPY 228m receivable decrease and a JPY 150m rise in contract liabilities. In completion-heavy periods profit runs ahead of cash, and one large project's billing can move annual cash by hundreds of millions of yen. A completion-heavy H2 FY12/26 could repeat the pattern even if the profit forecast is met.
内部研究类型:cash_conversion_risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Cash conversion must be judged over two-year windows. A weak cash print alongside a met profit forecast would not alone break the thesis.
不确定性(原始记录):Receivable ageing, disputes or retention balances and customer concentration are undisclosed.
F018|06|资产负债表靠留存利润和借款扩张,没有摊薄股东
研究范围:开放研究+35项覆盖检查
写入正文:06|资产负债表靠留存利润和借款扩张,没有摊薄股东08|扩张靠留存、借款和租赁,增长慢但不摊薄
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、29;反向验证:21
FY12/2025 consolidated cash flow: capex year funded by long-term borrowing怎么使用:直接 / 支持;一手验证:17;同业比较:19、20、25;其他用途:历史
FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities怎么使用:直接 / 支持;一手验证:18、20、21、25;专项深挖:18;同业比较:29;其他用途:历史
Securities report data for IBOKIN (FY12/2025): history, capital and listing path怎么使用:直接证据;一手验证:09、25、33;专项深挖:01、25、33;同业比较:01、23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 反证(研究域21)|H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25)|FY12/2025 consolidated cash flow: capex year funded by long-term borrowing;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域25) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities;直接证据 / 一手证据(研究域09) / 一手证据(研究域25) / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域25) / 定向深挖(研究域33)|Securities report data for IBOKIN (FY12/2025): history, capital and listing path
完整研究记录(核对用)
研究原文:The balance sheet funds the growth programme without equity dilution. FY12/25 was the expansion year: land rose JPY 870m to JPY 1,950m on the Suminoe acquisition, lease assets rose JPY 98m to JPY 461m, long-term borrowings rose to JPY 802m on JPY 900m of new facilities, total assets grew 28% to JPY 8,105m, and capex was JPY 1,437m against depreciation of JPY 344m. Capital has been unchanged since incorporation and growth is funded by retained earnings, bank debt and leases. At June 2026 the equity ratio was 63.9%, cash and deposits were JPY 2,275m against JPY 860m of borrowings, and the group was net cash. Slow growth and no dilution are two sides of one policy.
内部研究类型:capital_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Any future equity raise would itself be a signal worth re-underwriting.
不确定性(原始记录):Undrawn facility headroom, off-balance-sheet commitments and the remaining Suminoe cost are not disclosed.
F019|09|下行保护保的是亏损幅度,不是持有时间
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|下行保护保的是亏损幅度,不是持有时间14|综合评分59.4/100,评级B
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、29;反向验证:21
H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half怎么使用:直接 / 支持;一手验证:21、29;外部现实校验:17;专项深挖:29
IRBANK stock page snapshot for 5699 (6 November 2026)怎么使用:直接证据;一手验证:27、31;外部现实校验:01、09、14、16、18、21、22、26、28、29、35;反向验证:24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 反证(研究域21)|H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17) / 定向深挖(研究域29)|H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5699 (6 November 2026)
完整研究记录(核对用)
研究原文:Downside protection is concrete for a company this size. Net cash is about JPY 1.4bn, the equity ratio is 63.9%, and land is carried at JPY 1,828m. Parent equity is JPY 5,362m, about 116% of the roughly JPY 4.6bn market capitalisation at the 6 November 2026 close. The dividend was held through the FY12/25 profit fall. Protection limits the severity of loss, not its duration, so the downside case is a long stay at a discount, not insolvency.
内部研究类型:downside_protection
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The protection argues for patience capital, and exit would be at a discount on thin volume.
不确定性(原始记录):Protection is measured on book values. Realisable values in a stress sale are not disclosed.
F020|06|正常化盈利中心在6.5亿至7.5亿日元,区间上下两成
研究范围:开放研究+35项覆盖检查
写入正文:06|正常化盈利中心在6.5亿至7.5亿日元,区间上下两成09|折价等于区间中心和下沿之间的距离15|资料来源的日期和这份报告的边界
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators怎么使用:直接 / 支持;一手验证:28;反向验证:27;同业比较:12、14、35;其他用途:历史
FY12/2025 results (tanshin): special profits and losses below the ordinary line怎么使用:直接 / 支持;一手验证:32;反向验证:28;同业比较:16、35;其他用途:历史
FY12/2025 results (tanshin): prior-year comparatives - FY12/2024 as the band's top怎么使用:直接 / 支持;一手验证:28;同业比较:17、18、22;其他用途:历史
Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023怎么使用:直接 / 支持;专项深挖:28;同业比较:02、09、28、33;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域35) / 反证(研究域27)|Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域35) / 反证(研究域28)|FY12/2025 results (tanshin): special profits and losses below the ordinary line;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22)|FY12/2025 results (tanshin): prior-year comparatives - FY12/2024 as the band's top;直接证据 / 支持证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域28) / 历史/同业比较(研究域33) / 定向深挖(研究域28)|Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023
完整研究记录(核对用)
研究原文:Normalised earnings power is anchored on ordinary profit. The parent's five-year ordinary profit has oscillated between JPY 545m and JPY 824m with no trend. Consolidated ordinary profit was JPY 824m in FY12/24 and JPY 666m in FY12/25, and the FY12/26 forecast is JPY 778m. The normalised centre is near JPY 650-750m, with a band width of about plus or minus 20%. FY12/25 printed net income is flattered by about JPY 140m of non-recurring items. The FY12/26 forecast only just exceeds the FY12/24 peak operating profit on about 9% more sales.
内部研究类型:normalised_economics
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Band width is the key valuation parameter, and the margin of safety rests on the band's stability.
不确定性(原始记录):This is research's own construction, since the company publishes no underlying-profit measure. Whether Mitsue lifts the centre is not observable yet.
F021|09|市值低于净资产,价格大致落在盈利区间的下沿
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|市值低于净资产,价格大致落在盈利区间的下沿14|综合评分59.4/100,评级B15|资料来源的日期和这份报告的边界
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
IRBANK stock page snapshot for 5699 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、14、16、18、21、22、26、28、29、35;反向验证:24
H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half怎么使用:直接 / 支持;一手验证:31、35;反向验证:30;专项深挖:31、35
FY12/2025 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:32;其他用途:历史
H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、29;反向验证:21
FY12/2025 consolidated cash flow: capex year funded by long-term borrowing怎么使用:直接 / 支持;一手验证:17;同业比较:19、20、25;其他用途:历史
FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
FY12/2025 results (tanshin): share counts - issued, treasury and averages怎么使用:直接证据;一手验证:27;专项深挖:27
IRBANK stock page for 5699: daily print of 6 November 2026 and volume context怎么使用:直接证据;外部现实校验:27、31、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5699 (6 November 2026);直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域32)|FY12/2025 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 反证(研究域21)|H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25)|FY12/2025 consolidated cash flow: capex year funded by long-term borrowing;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity;直接证据 / 一手证据(研究域27) / 定向深挖(研究域27)|FY12/2025 results (tanshin): share counts - issued, treasury and averages;直接证据 / 外部现实(研究域27) / 外部现实(研究域31) / 外部现实(研究域34)|IRBANK stock page for 5699: daily print of 6 November 2026 and volume context
完整研究记录(核对用)
研究原文:Valuation at the 6 November 2026 close: share price JPY 1,349; market capitalisation JPY 4.62bn on 3,427,200 issued shares (an issued-share basis that includes the 140,292 treasury shares); forecast PER 8.46x on FY12/26 forecast EPS of JPY 159.42; actual PBR 0.87x on FY12/25-end net assets per share of JPY 1,558.34; FY12/25 ROE 12.4% (flattered by special gains); forecast dividend yield 2.37% on JPY 32; EV/EBITDA 3.3x (EV JPY 3.21bn after net cash of JPY 1.42bn at 30 June 2026; EBITDA JPY 0.99bn = FY12/25 operating profit plus depreciation). The market capitalisation is below parent equity of JPY 5,362m, and the discount is read as pricing normalised earnings near the bottom of the band, with zero value for the Mitsui channel, Suminoe and any capital-policy change.
内部研究类型:valuation_snapshot
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Entry pays for asset cover and a 2.4% yield while waiting. Re-rating must come from prints and catalysts, not distribution growth.
不确定性(原始记录):Multiples come from one thin-market print, with no analyst consensus. PBR, ROE and PER bases differ across sources and the derived values depend on those dates and denominators.
F022|09|成交稀薄意味着退出要付折价
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论09|成交稀薄意味着退出要付折价10|成交稀薄让单日价格的信号失真
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
IRBANK stock page for 5699: trading thinness and margin positioning怎么使用:直接 / 支持;外部现实校验:08、12、20、24、30;专项深挖:34
IRBANK stock page for 5699: split-adjusted annual price ranges and margin balance怎么使用:直接 / 支持;外部现实校验:33;反向验证:34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域08) / 外部现实(研究域12) / 外部现实(研究域20) / 外部现实(研究域24) / 外部现实(研究域30) / 定向深挖(研究域34)|IRBANK stock page for 5699: trading thinness and margin positioning;直接证据 / 支持证据 / 外部现实(研究域33) / 反证(研究域34)|IRBANK stock page for 5699: split-adjusted annual price ranges and margin balance
完整研究记录(核对用)
研究原文:Trading is extremely thin. Monthly volume runs 60,000-200,000 shares, and the 6 November 2026 session fell 4.8% on 17,300 shares with no disclosure. A margin long balance of 217,200 shares (about 6.6% of the roughly 3.29m free float, exceeding a typical month's volume) sits against zero shorts. The price can gap on no information and single prints carry little signal. Position sizing and entry patience matter more than timing precision.
内部研究类型:market_structure_risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
普通股东含义(原始记录):A disappointing print can be amplified by margin longs. Exit costs are real.
不确定性(原始记录):The margin balance is dated mid-July 2026.
F023|03|环境板块的吞吐量已经落后于计划
研究范围:开放研究+35项覆盖检查
写入正文:03|环境板块的吞吐量已经落后于计划
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY12/2026 results briefing materials: environment segment detail怎么使用:直接 / 支持;反向验证:03、11
Medium-term management plan 2024-2026: non-financial KPI table怎么使用:直接 / 支持;同业比较:06、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域11)|H1 FY12/2026 results briefing materials: environment segment detail;直接证据 / 支持证据 / 历史/同业比较(研究域06) / 历史/同业比较(研究域11)|Medium-term management plan 2024-2026: non-financial KPI table
完整研究记录(核对用)
研究原文:The environment segment is quietly off-plan. H1 FY12/26 intake was 10,748 tonnes, about 21,500 annualised, below the 2023 starting point of 22,000 and far below the 27,000-tonne target. Segment profit eased from JPY 126m to JPY 116m. Profit stability comes from mix and prices, not volume. Suminoe is the designated fix, so its opening date is a segment-level verification point.
内部研究类型:segment_delivery_gap
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Discount any expectation of environment volume growth until the new yard converts.
不确定性(原始记录):Why intake is flat is not disclosed. It could be capacity-limited or demand-limited.
F024|08|Mitsue和住之江:买产能的账怎么算
研究范围:开放研究+35项覆盖检查
写入正文:08|Mitsue和住之江:买产能的账怎么算11|住之江开业和三菱商事转化是两个有日期的催化剂
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY12/2026 results briefing materials: the Suminoe yard project怎么使用:直接 / 支持;一手验证:20;专项深挖:20
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities怎么使用:直接证据;一手验证:18、20、21、25;专项深挖:18;同业比较:29;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|H1 FY12/2026 results briefing materials: the Suminoe yard project;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域25) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities
完整研究记录(核对用)
研究原文:The Suminoe yard in Osaka (about 900 tsubo, acquired December 2025, opening targeted in FY2027) is the highest-certainty growth item. The Hanshin (Amagasaki) operation is at its capacity limit, so the yard converts existing unmet throughput in the densest demolition market into environment and metals volume without needing new demand. The FY12/25-27 investment stage depresses free cash flow, and returns must appear in FY12/27-28 segment profit.
内部研究类型:capacity_project
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A dated catalyst and the plan's physical answer to its constraint. Delay would postpone the payoff window.
不确定性(原始记录):The remaining capex, the opening cost, the added capacity and licensing progress are undisclosed.
F025|05|碳数据能力是进入大业主名单的筛选条件
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY12/2026 results briefing materials: demolition technology and carbon services怎么使用:直接 / 支持;一手验证:03、08;专项深挖:03
Medium-term management plan 2024-2026: sustainability and carbon management怎么使用:直接 / 支持;一手验证:13;外部现实校验:03、04、10;专项深挖:13
IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023怎么使用:直接证据;一手验证:22;外部现实校验:13、25;反向验证:07;专项深挖:22
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域08) / 定向深挖(研究域03)|H1 FY12/2026 results briefing materials: demolition technology and carbon services;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域10) / 定向深挖(研究域13)|Medium-term management plan 2024-2026: sustainability and carbon management;直接证据 / 一手证据(研究域22) / 外部现实(研究域13) / 外部现实(研究域25) / 反证(研究域07) / 定向深挖(研究域22)|IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023
完整研究记录(核对用)
研究原文:Per-project CO2 and material-balance data is a genuine differentiator in winning work. It is the service layer the Mitsui alliance is built around. It matches the GX League participation (2023), the RE Action commitment and the EcoVadis Silver credentials that large owners screen for, and it attaches to demolition mandates feeding all three segments. Regulation raises the fixed cost of being a credible venous operator, which taxes small rivals.
内部研究类型:differentiator_capability
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A compliance trend turns into chain-level deal flow if the capability is held early.
不确定性(原始记录):Service pricing and uptake are not disclosed. The content of the December 2023 capital-cost response was not re-read.
F026|05|超大型机械决定谁能接高难度工程
研究范围:开放研究+35项覆盖检查
写入正文:05|超大型机械决定谁能接高难度工程
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY12/2026 results briefing materials: large demolition machinery and capability build-out怎么使用:直接证据;一手验证:04、10;同业比较:08;其他用途:历史
H1 FY12/2026 results briefing materials: demolition technology and carbon services怎么使用:直接证据;一手验证:03、08;专项深挖:03
Medium-term management plan 2024-2026: technology development themes怎么使用:直接证据;一手验证:04;专项深挖:04;同业比较:03、10;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 历史/同业比较(研究域08)|H1 FY12/2026 results briefing materials: large demolition machinery and capability build-out;直接证据 / 一手证据(研究域03) / 一手证据(研究域08) / 定向深挖(研究域03)|H1 FY12/2026 results briefing materials: demolition technology and carbon services;直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03) / 历史/同业比较(研究域10) / 定向深挖(研究域04)|Medium-term management plan 2024-2026: technology development themes
完整研究记录(核对用)
研究原文:The super-large demolition machinery fleet comprises the 130-tonne-class SK1300DLC (August 2023) and two ZX1800K-3 units (the second in September 2025), plus a pile-pulling method with a patent application filed. Remote-operation and AI-sorting themes (with Fukushima Daiichi method-study contracts in 2023) target labour shortage and hazardous work, not near-term revenue. The fleet gates the high-difficulty, high-margin project class and widens biddable scope.
内部研究类型:physical_moat_asset
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Machinery returns appear in demolition margins, not in a technology segment. The remote and AI layer is an option only.
不确定性(原始记录):Utilisation rates and per-machine economics are undisclosed, and no R&D spending line is disclosed.
F027|11|第三季度业绩是最近的检验,之后有一串有日期的后续
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论11|第三季度业绩是最近的检验,之后有一串有日期的后续15|资料来源的日期和这份报告的边界
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar怎么使用:直接 / 支持;一手验证:30
H1 FY12/2026 results briefing materials: the Suminoe yard project怎么使用:直接 / 支持;一手验证:20;专项深挖:20
Mitsui & Co. alliance release: the four workstreams in detail怎么使用:直接 / 支持;一手验证:07;专项深挖:07
IRBANK timely-disclosure index for IBOKIN: Q3 publication cadence 2023-2025怎么使用:直接证据;一手验证:30;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|H1 FY12/2026 results briefing materials: the Suminoe yard project;直接证据 / 支持证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Mitsui & Co. alliance release: the four workstreams in detail;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|IRBANK timely-disclosure index for IBOKIN: Q3 publication cadence 2023-2025
完整研究记录(核对用)
研究原文:The Q3 FY12/26 tanshin is the nearest verification event. It was published on 14 November in each of 2023-2025, and the entry was blank at 9 November 2026, so a print is expected on 13-14 November 2026, immediately before the review date. It will show whether demolition margins held through nine months (the H1 level of roughly JPY 190m of half-year segment profit broadly held). Dated sequels follow: the FY12/26 annual results and next plan (February-March 2027), the Suminoe opening (FY2027), the first disclosed Mitsui-channel transactions, and any dividend or buyback reset. Each maps to one thesis variable, so the calendar is a verification schedule.
内部研究类型:catalyst_calendar
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Dated answers allow re-underwriting at each print.
不确定性(原始记录):The date is inferred from cadence. The Q3 print was unpublished when research was frozen, so the nine-month result is unknown here.
F028|08|股东回报只有一笔固定的分红
研究范围:开放研究+35项覆盖检查
写入正文:08|股东回报只有一笔固定的分红
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
IRBANK timely-disclosure index for IBOKIN: buyback history in detail怎么使用:直接 / 支持;反向验证:23、26;同业比较:24;其他用途:历史
IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023怎么使用:直接证据;一手验证:22;外部现实校验:13、25;反向验证:07;专项深挖:22
查看完整证据标签(核对用)
直接证据 / 支持证据|H1 FY12/2026 results briefing materials: dividend record and stated policy;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 反证(研究域23) / 反证(研究域26)|IRBANK timely-disclosure index for IBOKIN: buyback history in detail;直接证据 / 一手证据(研究域26)|H1 FY12/2026 interim results (tanshin): dividend table - no interim dividend;直接证据 / 一手证据(研究域22) / 外部现实(研究域13) / 外部现实(研究域25) / 反证(研究域07) / 定向深挖(研究域22)|IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023
完整研究记录(核对用)
研究原文:Shareholder return in practice is the dividend alone. It is a flat JPY 32 year-end payment (about JPY 105m a year) held across FY12/24, FY12/25 and the FY12/26 forecast, with no interim dividend. The payout ratio was 20.3%, 17.6% and about 20.1% (dividend on equity about 2.1-2.3%). It moved neither on the FY12/25 profit fall nor on the H1 rebound. Buybacks were small (JPY 24.7m in FY12/24 and JPY 3.1m in FY12/25), so treasury shares stayed at 4.1% (140,292). A buyback round decided on 9 August 2024 was completed on 2 May 2025, and an earlier round was completed on 28 April 2023. A capital-cost response was disclosed on 14 December 2023, though its content was not re-read. Distribution debate is concentrated in the February results announcement.
内部研究类型:shareholder_return
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A yield of about 2.4% is bond-like income. Returns must come from re-rating, and a step-up or buyback at scale would be a capital-policy signal.
不确定性(原始记录):The board's hurdle for a rise is undisclosed. The open question text refers to a February 2023 capital-cost response, while the disclosure index dates it 14 December 2023, so the exact date is carried as inconsistent across source texts.
F029|01|评级B:资产垫层够厚,但要先等第三季度业绩
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|评级B:资产垫层够厚,但要先等第三季度业绩14|综合评分59.4/100,评级B
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system怎么使用:直接 / 支持;一手验证:07
Medium-term management plan 2024-2026: targets and ten-year vision怎么使用:直接 / 支持;一手验证:05、11、14;反向验证:09;同业比较:04、30;其他用途:历史
H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half怎么使用:直接 / 支持;一手验证:31、35;反向验证:30;专项深挖:31、35
H1 FY12/2026 results briefing materials: operating KPIs and volumes怎么使用:直接证据;一手验证:06;反向验证:08、10、13、35
FY12/2025 balance sheet: the receivables build that absorbed operating cash flow怎么使用:直接证据;一手验证:19;外部现实校验:32;反向验证:15、17、35;专项深挖:17、19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 支持证据 / 一手证据(研究域07)|Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域14) / 历史/同业比较(研究域04) / 历史/同业比较(研究域30) / 反证(研究域09)|Medium-term management plan 2024-2026: targets and ten-year vision;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half;直接证据 / 一手证据(研究域06) / 反证(研究域08) / 反证(研究域10) / 反证(研究域13) / 反证(研究域35)|H1 FY12/2026 results briefing materials: operating KPIs and volumes;直接证据 / 一手证据(研究域19) / 外部现实(研究域32) / 反证(研究域15) / 反证(研究域17) / 反证(研究域35) / 定向深挖(研究域17) / 定向深挖(研究域19)|FY12/2025 balance sheet: the receivables build that absorbed operating cash flow
完整研究记录(核对用)
研究原文:The investment question is whether demolition's H1 FY12/26 margin repair is a durable cost-estimation capability (supervisors, machinery, in-house asbestos and heavy-lift) or merely the absence of last year's bad projects. If durable, a net-cash group earning a normalised ordinary profit of JPY 600-800m and paying a stable dividend is mispriced below book, with the Mitsui channel and Suminoe as unpriced options. The thesis fails in an observable way. Demolition margins would collapse again on new cost overruns in the Q3 or annual prints, supervisors would fall further, the next plan would cut the 2033 vision without a capital-policy offset, or receivables would absorb cash for a second year. In that case the repair was roll-off arithmetic, the band drops toward its bottom, and the below-book price is fair.
内部研究类型:thesis_falsification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The falsification window is short (two prints) and the downside is asset-cushioned. If falsified, the action is exit into thin liquidity at a structural discount.
不确定性(原始记录):Unresolved until the dated prints arrive.
F030|05|护城河是一组叠加条件,价值在于对手配齐所需的时间
研究范围:35项覆盖检查
写入正文:05|护城河是一组叠加条件,价值在于对手配齐所需的时间
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Articles of incorporation: business purposes as the licensed scope怎么使用:直接证据;一手验证:06、10、13;专项深挖:10
H1 FY12/2026 results briefing materials: large demolition machinery and capability build-out怎么使用:直接证据;一手验证:04、10;同业比较:08;其他用途:历史
H1 FY12/2026 results briefing materials: demolition technology and carbon services怎么使用:直接证据;一手验证:03、08;专项深挖:03
H1 FY12/2026 results briefing materials: management's framing of the strategy怎么使用:直接证据;一手验证:02、08;专项深挖:02、08
H1 FY12/2026 results briefing materials: operating KPIs and volumes怎么使用:直接证据;一手验证:06;反向验证:08、10、13、35
Medium-term management plan 2024-2026: sustainability and carbon management怎么使用:直接证据;一手验证:13;外部现实校验:03、04、10;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 一手证据(研究域10) / 一手证据(研究域13) / 定向深挖(研究域10)|Articles of incorporation: business purposes as the licensed scope;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 历史/同业比较(研究域08)|H1 FY12/2026 results briefing materials: large demolition machinery and capability build-out;直接证据 / 一手证据(研究域03) / 一手证据(研究域08) / 定向深挖(研究域03)|H1 FY12/2026 results briefing materials: demolition technology and carbon services;直接证据 / 一手证据(研究域02) / 一手证据(研究域08) / 定向深挖(研究域02) / 定向深挖(研究域08)|H1 FY12/2026 results briefing materials: management's framing of the strategy;直接证据 / 一手证据(研究域06) / 反证(研究域08) / 反证(研究域10) / 反证(研究域13) / 反证(研究域35)|H1 FY12/2026 results briefing materials: operating KPIs and volumes;直接证据 / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域10) / 定向深挖(研究域13)|Medium-term management plan 2024-2026: sustainability and carbon management
完整研究记录(核对用)
研究原文:Protection against replication is a bundle, not a single barrier: site-specific waste and landfill permits (the purposes clause maps the permit perimeter), owned processing yards in a land-constrained region, super-large machinery, licensed supervisors and customer documentation that embeds the group in owners' compliance processes. Each element is replicable alone, and the value is the time a rival needs to assemble the chain in the same region. Competition is local and capability-tiered, so pricing power exists only in the top project-difficulty tier. The moat does nothing for the metals price exposure. A permit or compliance failure at one site would be disproportionately costly.
内部研究类型:moat_bundle
内部来源标记:COVERAGE35
普通股东含义(原始记录):It protects margin quality in demolition and environment in the Kansai radius, but is unproven in metropolitan work against larger rivals.
不确定性(原始记录):Win rates, bid margins, permit renewal history and any regulatory action are undisclosed. No competitor data was obtained.
F031|06|三个板块的收入可靠度,与利润可靠度几乎相反
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
H1 FY12/2026 results briefing materials: metals segment detail怎么使用:直接证据;一手验证:15;专项深挖:15
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接证据;一手验证:15、16、35
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接证据;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域15) / 定向深挖(研究域15)|H1 FY12/2026 results briefing materials: metals segment detail;直接证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 一手证据(研究域05)|Q1 FY12/2026 results (tanshin): management narrative for the first quarter;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume
完整研究记录(核对用)
研究原文:Revenue quality differs by segment. Metals revenue is tonnage times market price (28,178 tonnes in H1 FY12/26, 88% through own plants versus 79% in FY12/25). Environment mixes contracted treatment with price-linked resource sales. Demolition is project-completion revenue with short backlog cover. Repeatability ranks environment highest, metals next and demolition lowest, while profit reliability ranks almost inversely. The decline in metals tonnage from 100,000 to 74,484 is partly deliberate, a shift to own-plant processing where margin is made, so tonnage alone misreads the segment.
内部研究类型:revenue_quality_profile
内部来源标记:COVERAGE35
普通股东含义(原始记录):Trust the forecast at the year level, not the quarter.
不确定性(原始记录):Contract-asset ageing, revenue recognised on estimates and repeat-customer share are not detailed.
F032|09|下行保护保的是亏损幅度,不是持有时间
研究范围:35项覆盖检查
写入正文:09|下行保护保的是亏损幅度,不是持有时间13|下一次要先解决的几个问题
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half怎么使用:直接证据;一手验证:21、29;外部现实校验:17;专项深挖:29
FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities怎么使用:直接证据;一手验证:18、20、21、25;专项深挖:18;同业比较:29;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17) / 定向深挖(研究域29)|H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half;直接证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域25) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities
完整研究记录(核对用)
研究原文:Environmental, asbestos-related and other contingent liabilities are not quantified in the sources read, which is a genuine gap for a demolition and landfill operator. Off-balance-sheet guarantees and purchase obligations are also not detailed.
内部研究类型:research_debt_unknown
内部来源标记:COVERAGE35
普通股东含义(原始记录):Could erode the asset cushion that anchors the downside case, in a business that operates a final landfill.
不确定性(原始记录):The FY12/26 annual securities-report notes on contingent liabilities and any provision movement would resolve it. It is not resolvable from the current public path.
F033|09|市场预期只能从价格和指引里推出来
研究范围:35项覆盖检查
写入正文:09|市场预期只能从价格和指引里推出来15|资料来源的日期和这份报告的边界
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half怎么使用:直接证据;一手验证:31、35;反向验证:30;专项深挖:31、35
IRBANK stock page snapshot for 5699 (6 November 2026)怎么使用:直接证据;一手验证:27、31;外部现实校验:01、09、14、16、18、21、22、26、28、29、35;反向验证:24
IRBANK stock page for 5699: daily print of 6 November 2026 and volume context怎么使用:直接证据;外部现实校验:27、31、34
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5699 (6 November 2026);直接证据 / 外部现实(研究域27) / 外部现实(研究域31) / 外部现实(研究域34)|IRBANK stock page for 5699: daily print of 6 November 2026 and volume context
完整研究记录(核对用)
研究原文:No analyst coverage or consensus exists, so priced expectations are read only from the quote and the forecast arithmetic. The market's central belief appears to be band-bottom earnings indefinitely. The expectations gap is the distance between band-centre delivery and band-bottom pricing, and it closes on prints, not narrative.
内部研究类型:expectations_state
内部来源标记:COVERAGE35
普通股东含义(原始记录):The asymmetry favours the patient holder. The risk is time, illiquidity and margin-long amplification.
不确定性(原始记录):Priced expectations are inferred, not observed.
F034|09|非经营资产有限,土地和证券不宜多算
研究范围:35项覆盖检查
写入正文:09|非经营资产有限,土地和证券不宜多算
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half怎么使用:直接证据;一手验证:21、29;外部现实校验:17;专项深挖:29
FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities怎么使用:直接证据;一手验证:18、20、21、25;专项深挖:18;同业比较:29;其他用途:历史
FY12/2025 statement of changes in equity: retained earnings, treasury and valuation reserve怎么使用:直接证据;专项深挖:21;同业比较:21、26、27;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17) / 定向深挖(研究域29)|H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half;直接证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域25) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities;直接证据 / 历史/同业比较(研究域21) / 历史/同业比较(研究域26) / 历史/同业比较(研究域27) / 定向深挖(研究域21)|FY12/2025 statement of changes in equity: retained earnings, treasury and valuation reserve
完整研究记录(核对用)
研究原文:Non-operating value is limited. Investment securities were JPY 661m with a JPY 274m unrealised reserve, insurance reserves about JPY 117m, and land at historical cost with no appraisal disclosed (land fell to JPY 1,828m after a parcel sale of JPY 129m). The land is partly operational, since the yards are the business, so uplift is speculative. The securities reserve is real but market-marked.
内部研究类型:non_operating_assets
内部来源标记:COVERAGE35
普通股东含义(原始记录):Asset value supports the below-book entry but should not be capitalised beyond the disclosed securities reserve.
不确定性(原始记录):Securities composition and land market value are not in the sources read.
F035|02|公司靠分步买下产能增长,再花几年消化
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): history, capital and listing path怎么使用:直接证据;一手验证:09、25、33;专项深挖:01、25、33;同业比较:01、23;其他用途:历史
Locally recomputed monthly series: the April 2026 volume pulse and its retracement怎么使用:直接证据;一手验证:33、34
Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023怎么使用:直接证据;专项深挖:28;同业比较:02、09、28、33;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域09) / 一手证据(研究域25) / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域25) / 定向深挖(研究域33)|Securities report data for IBOKIN (FY12/2025): history, capital and listing path;直接证据 / 一手证据(研究域33) / 一手证据(研究域34)|Locally recomputed monthly series: the April 2026 volume pulse and its retracement;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域28) / 历史/同业比较(研究域33) / 定向深挖(研究域28)|Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023
完整研究记录(核对用)
研究原文:The company changes by acquiring capacity in steps and then digesting it for years. The milestones are the 1984 founding, the 2003 rename, the 2017 Kunitora deal, the 2018 JASDAQ listing, the 2022 TSE Standard move, and the 2023-2025 build (SK1300DLC, Mitsue, Suminoe). The current digestion phase is the third such cycle, and the FY12/24 peak followed the earlier build. Holders are buying mid-digestion, and the payoff window is argued to be two to three years out, not the next print.
内部研究类型:historical_pattern
内部来源标记:COVERAGE35
普通股东含义(原始记录):The historical template argues for patience.
不确定性(原始记录):Pre-2018 private-era financials are not in the sources read.
F036|07|一半表决权在创业家族,少数股东依赖家族的资本纪律
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论07|一半表决权在创业家族,少数股东依赖家族的资本纪律
归并到:F005
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Securities report data for IBOKIN (FY12/2025): major shareholders and company profile
完整研究记录(核对用)
研究原文:HS Kosan holds 38.94% and together with the founder controls about half the votes, so control sits inside the founding perimeter.
内部研究类型:controlling_shareholder
内部来源标记:OPEN_DISCOVERY
F037|07|一半表决权在创业家族,少数股东依赖家族的资本纪律
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论07|一半表决权在创业家族,少数股东依赖家族的资本纪律
归并到:F005
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、23、24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Securities report data for IBOKIN (FY12/2025): major shareholders and company profile
完整研究记录(核对用)
研究原文:The founder-president holds 11.07%, so the operating founder and the controlling bloc are one party.
内部研究类型:founder_management_capital
内部来源标记:OPEN_DISCOVERY
F038|04|三菱商事合作是一个选择权,还没有变成收入
研究范围:开放研究
写入正文:04|三菱商事合作是一个选择权,还没有变成收入11|住之江开业和三菱商事转化是两个有日期的催化剂
归并到:F008
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system怎么使用:直接 / 支持;一手验证:07
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07)|Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system
完整研究记录(核对用)
研究原文:The MOU gives potential demolition deal flow and scrap realisation quality at no cost in the current forecast. Conversion into disclosed transactions is the item to verify.
内部研究类型:strategic_alliance_mou
内部来源标记:OPEN_DISCOVERY
F039|02|公司靠分步买下产能增长,再花几年消化
研究范围:开放研究
归并到:F035
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): subsidiaries and employees怎么使用:直接证据;同业比较:07;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 历史/同业比较(研究域07)|Securities report data for IBOKIN (FY12/2025): subsidiaries and employees
完整研究记录(核对用)
研究原文:Kunitora Kogyo has been a wholly owned subsidiary since April 2017, internalising capacity in Hyogo.
内部研究类型:wholly_owned_subsidiary
内部来源标记:OPEN_DISCOVERY
F040|02|公司靠分步买下产能增长,再花几年消化
研究范围:开放研究
写入正文:02|公司靠分步买下产能增长,再花几年消化08|Mitsue和住之江:买产能的账怎么算
归并到:F010
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): subsidiaries and employees怎么使用:直接 / 支持;同业比较:07;其他用途:历史
FY12/2025 results (tanshin): special profits and losses below the ordinary line怎么使用:直接证据;一手验证:32;反向验证:28;同业比较:16、35;其他用途:历史
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:支持证据;一手验证:15、16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域07)|Securities report data for IBOKIN (FY12/2025): subsidiaries and employees;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域35) / 反证(研究域28)|FY12/2025 results (tanshin): special profits and losses below the ordinary line;支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit
完整研究记录(核对用)
研究原文:Mitsue (90.9%, from January 2025) internalises asbestos and heavy-machinery capability, supporting the margin-repair thesis and showing the seller's market for such capacity is thin.
内部研究类型:consolidated_subsidiary
内部来源标记:OPEN_DISCOVERY
F041|04|钢厂需求决定废钢价格,传到三个板块
研究范围:开放研究
写入正文:04|钢厂需求决定废钢价格,传到三个板块
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY12/2026 results briefing materials: scrap-price backdrop and segment narratives怎么使用:直接 / 支持;一手验证:12;外部现实校验:02、05、11、15、19
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:支持证据;一手验证:15、16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域02) / 外部现实(研究域05) / 外部现实(研究域11) / 外部现实(研究域15) / 外部现实(研究域19)|H1 FY12/2026 results briefing materials: scrap-price backdrop and segment narratives;支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit
完整研究记录(核对用)
研究原文:Steelmaker demand sets the ferrous scrap price (about 19% higher in H1 FY12/26, lower in FY12/25). The price touches metals directly, environment through recycled-resource sales, and demolition through recovered scrap.
内部研究类型:end_market_price_setting
内部来源标记:OPEN_DISCOVERY
F042|03|需求池很长,但在手订单只够一个季度
研究范围:开放研究
写入正文:03|需求池很长,但在手订单只够一个季度
归并到:F011
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Medium-term management plan 2024-2026: targets and ten-year vision怎么使用:直接证据;一手验证:05、11、14;反向验证:09;同业比较:04、30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域14) / 历史/同业比较(研究域04) / 历史/同业比较(研究域30) / 反证(研究域09)|Medium-term management plan 2024-2026: targets and ten-year vision
完整研究记录(核对用)
研究原文:Demand is the sequential ageing of over JPY 3,000 trillion of construction stock reaching renewal age. This makes it a stock-turnover flow, so the plan treats supervisor capacity, not order demand, as the constraint.
内部研究类型:end_market_demand_pool
内部来源标记:OPEN_DISCOVERY
F043|06|全年指引暗含一个更软的下半年
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论06|全年指引暗含一个更软的下半年11|下半年软不软,第三季度和全年业绩会给答案
归并到:F012
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half怎么使用:直接证据;一手验证:31、35;反向验证:30;专项深挖:31、35
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
FY12/2026 consolidated forecast as first issued with the FY12/2025 results怎么使用:支持证据;同业比较:31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half;直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;支持证据 / 历史/同业比较(研究域31)|FY12/2026 consolidated forecast as first issued with the FY12/2025 results
完整研究记录(核对用)
研究原文:H2 must deliver sales JPY 5,595m, operating profit JPY 365m and net income JPY 237m, about 16% below the first half's operating profit. The year's verdict rests on an unprinted second half whose bar is low.
内部研究类型:forecast_arithmetic_expectation
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F044|07|中期计划交付记录:产品结构达标,产能和财务目标落空
研究范围:开放研究+35项覆盖检查
写入正文:07|中期计划交付记录:产品结构达标,产能和财务目标落空
归并到:F014
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Medium-term management plan 2024-2026: targets and ten-year vision怎么使用:直接 / 支持;一手验证:05、11、14;反向验证:09;同业比较:04、30;其他用途:历史
Medium-term management plan 2024-2026: non-financial KPI table怎么使用:直接 / 支持;同业比较:06、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域14) / 历史/同业比较(研究域04) / 历史/同业比较(研究域30) / 反证(研究域09)|Medium-term management plan 2024-2026: targets and ten-year vision;直接证据 / 支持证据 / 历史/同业比较(研究域06) / 历史/同业比较(研究域11)|Medium-term management plan 2024-2026: non-financial KPI table;支持证据 / 反证(研究域06)|FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end
完整研究记录(核对用)
研究原文:The 2024-2026 plan and 2033 vision are the measuring rod for the next plan. Its delivery pattern (mix achieved, capacity behind, financial targets conceded early) is the prior for how much of the vision to capitalise.
内部研究类型:governing_policy_framework
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F045|05|超大型机械决定谁能接高难度工程
研究范围:开放研究+35项覆盖检查
写入正文:05|超大型机械决定谁能接高难度工程
归并到:F026
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
H1 FY12/2026 results briefing materials: large demolition machinery and capability build-out怎么使用:直接证据;一手验证:04、10;同业比较:08;其他用途:历史
H1 FY12/2026 results briefing materials: demolition technology and carbon services怎么使用:直接证据;一手验证:03、08;专项深挖:03
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 历史/同业比较(研究域08)|H1 FY12/2026 results briefing materials: large demolition machinery and capability build-out;直接证据 / 一手证据(研究域03) / 一手证据(研究域08) / 定向深挖(研究域03)|H1 FY12/2026 results briefing materials: demolition technology and carbon services
完整研究记录(核对用)
研究原文:The super-large machinery fleet is the physical moat gating high-difficulty, high-margin demolition work in a labour-short industry.
内部研究类型:technology_capability_base
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F046|05|碳数据能力是进入大业主名单的筛选条件
研究范围:开放研究+35项覆盖检查
归并到:F025
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Medium-term management plan 2024-2026: sustainability and carbon management怎么使用:直接 / 支持;一手验证:13;外部现实校验:03、04、10;专项深挖:13
H1 FY12/2026 results briefing materials: demolition technology and carbon services怎么使用:直接 / 支持;一手验证:03、08;专项深挖:03
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域10) / 定向深挖(研究域13)|Medium-term management plan 2024-2026: sustainability and carbon management;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域08) / 定向深挖(研究域03)|H1 FY12/2026 results briefing materials: demolition technology and carbon services
完整研究记录(核对用)
研究原文:GX League, RE Action, EcoVadis and per-project CO2 accounting make environmental data a condition of winning large owners' mandates. The same data layer is a named Mitsui workstream.
内部研究类型:regulatory_commercial_environment
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F047|03|持证监督员是产能的法律闸门,人数在下降
研究范围:开放研究+35项覆盖检查
写入正文:03|持证监督员是产能的法律闸门,人数在下降11|监督员人数是增长的前置条件,也是前瞻信号
归并到:F065
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end怎么使用:直接 / 支持;反向验证:06
H1 FY12/2026 results briefing materials: operating KPIs and volumes怎么使用:直接 / 支持;一手验证:06;反向验证:08、10、13、35
Medium-term management plan 2024-2026: non-financial KPI table怎么使用:直接 / 支持;同业比较:06、11;其他用途:历史
Medium-term management plan 2024-2026: targets and ten-year vision怎么使用:支持证据;一手验证:05、11、14;反向验证:09;同业比较:04、30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域06)|FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域08) / 反证(研究域10) / 反证(研究域13) / 反证(研究域35)|H1 FY12/2026 results briefing materials: operating KPIs and volumes;直接证据 / 支持证据 / 历史/同业比较(研究域06) / 历史/同业比较(研究域11)|Medium-term management plan 2024-2026: non-financial KPI table;支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域14) / 历史/同业比较(研究域04) / 历史/同业比较(研究域30) / 反证(研究域09)|Medium-term management plan 2024-2026: targets and ten-year vision
完整研究记录(核对用)
研究原文:The supervisor count caps demolition capacity and therefore plan delivery. Intake and supervisor KPIs were missed while the volume-mix KPI was met, which points to internal delivery constraints.
内部研究类型:constrains
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F048|01|利润区间、账目和折价其实是同一个问题
研究范围:开放研究+35项覆盖检查
写入正文:01|利润区间、账目和折价其实是同一个问题09|折价等于区间中心和下沿之间的距离
归并到:F064
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接 / 支持;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
FY12/2025 results (tanshin): prior-year comparatives - FY12/2024 as the band's top怎么使用:直接 / 支持;一手验证:28;同业比较:17、18、22;其他用途:历史
Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators怎么使用:支持证据;一手验证:28;反向验证:27;同业比较:12、14、35;其他用途:历史
FY12/2025 results (tanshin): special profits and losses below the ordinary line怎么使用:支持证据;一手验证:32;反向验证:28;同业比较:16、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22)|FY12/2025 results (tanshin): prior-year comparatives - FY12/2024 as the band's top;支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域35) / 反证(研究域27)|Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators;支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域35) / 反证(研究域28)|FY12/2025 results (tanshin): special profits and losses below the ordinary line
完整研究记录(核对用)
研究原文:Demolition estimation variance sets the width and centre of the earnings band, since the other segments contribute a steadier, thinner spread over scrap.
内部研究类型:determines_band
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F049|01|利润区间、账目和折价其实是同一个问题
研究范围:开放研究+35项覆盖检查
写入正文:01|利润区间、账目和折价其实是同一个问题09|折价等于区间中心和下沿之间的距离
归并到:F064
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY12/2025 results (tanshin): special profits and losses below the ordinary line怎么使用:直接 / 支持;一手验证:32;反向验证:28;同业比较:16、35;其他用途:历史
FY12/2025 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:32;其他用途:历史
Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators怎么使用:支持证据;一手验证:28;反向验证:27;同业比较:12、14、35;其他用途:历史
FY12/2025 results (tanshin): prior-year comparatives - FY12/2024 as the band's top怎么使用:支持证据;一手验证:28;同业比较:17、18、22;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域35) / 反证(研究域28)|FY12/2025 results (tanshin): special profits and losses below the ordinary line;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域32)|FY12/2025 consolidated results (tanshin): headline earnings and year-on-year changes;支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域35) / 反证(研究域27)|Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators;支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22)|FY12/2025 results (tanshin): prior-year comparatives - FY12/2024 as the band's top
完整研究记录(核对用)
研究原文:The roughly JPY 140m of FY12/25 special profits must be removed before the band is used.
内部研究类型:must_be_stripped_before_use
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F050|01|利润区间、账目和折价其实是同一个问题
研究范围:开放研究
写入正文:01|利润区间、账目和折价其实是同一个问题09|折价等于区间中心和下沿之间的距离
归并到:F064
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK stock page snapshot for 5699 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、14、16、18、21、22、26、28、29、35;反向验证:24
Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators怎么使用:直接证据;一手验证:28;反向验证:27;同业比较:12、14、35;其他用途:历史
H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026怎么使用:支持证据;一手验证:18、29;反向验证:21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5699 (6 November 2026);直接证据 / 一手证据(研究域28) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域35) / 反证(研究域27)|Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators;支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 反证(研究域21)|H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026
完整研究记录(核对用)
研究原文:The market capitalises roughly the bottom of the band while the group holds net cash, so the discount equals the gap between band-centre and band-bottom delivery.
内部研究类型:anchors
内部来源标记:OPEN_DISCOVERY
F051|09|下行保护保的是亏损幅度,不是持有时间
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、29;反向验证:21
H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half怎么使用:直接 / 支持;一手验证:21、29;外部现实校验:17;专项深挖:29
IRBANK stock page snapshot for 5699 (6 November 2026)怎么使用:支持证据;一手验证:27、31;外部现实校验:01、09、14、16、18、21、22、26、28、29、35;反向验证:24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 反证(研究域21)|H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17) / 定向深挖(研究域29)|H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half;支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5699 (6 November 2026)
完整研究记录(核对用)
研究原文:Asset and net-cash cover support a below-book entry price but not its duration, and unquantified contingent liabilities qualify the cover.
内部研究类型:supports_entry
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F052|02|公司靠分步买下产能增长,再花几年消化
研究范围:开放研究
写入正文:02|公司靠分步买下产能增长,再花几年消化08|Mitsue和住之江:买产能的账怎么算
归并到:F010
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): subsidiaries and employees怎么使用:直接 / 支持;同业比较:07;其他用途:历史
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域07)|Securities report data for IBOKIN (FY12/2025): subsidiaries and employees;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit
完整研究记录(核对用)
研究原文:In-house asbestos and heavy-lift work widens the biddable set and removes a subcontractor margin layer on the high-difficulty projects behind the FY12/25 overruns.
内部研究类型:supports_mechanism
内部来源标记:OPEN_DISCOVERY
F053|03|环境板块的吞吐量已经落后于计划
研究范围:35项覆盖检查
写入正文:03|环境板块的吞吐量已经落后于计划
归并到:F023
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
H1 FY12/2026 results briefing materials: the Suminoe yard project怎么使用:直接 / 支持;一手验证:20;专项深挖:20
H1 FY12/2026 results briefing materials: environment segment detail怎么使用:直接 / 支持;反向验证:03、11
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:支持证据;一手验证:15、16、35
Medium-term management plan 2024-2026: non-financial KPI table怎么使用:支持证据;同业比较:06、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|H1 FY12/2026 results briefing materials: the Suminoe yard project;直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域11)|H1 FY12/2026 results briefing materials: environment segment detail;支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;支持证据 / 历史/同业比较(研究域06) / 历史/同业比较(研究域11)|Medium-term management plan 2024-2026: non-financial KPI table
完整研究记录(核对用)
研究原文:Suminoe is the designated fix for the environment intake shortfall, so its opening date verifies the segment.
内部研究类型:designated_fix
内部来源标记:COVERAGE35
F054|04|三菱商事合作是一个选择权,还没有变成收入
研究范围:开放研究+35项覆盖检查
写入正文:04|三菱商事合作是一个选择权,还没有变成收入11|住之江开业和三菱商事转化是两个有日期的催化剂
归并到:F066
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system怎么使用:直接 / 支持;一手验证:07
H1 FY12/2026 results briefing materials: demolition technology and carbon services怎么使用:直接 / 支持;一手验证:03、08;专项深挖:03
Medium-term management plan 2024-2026: sustainability and carbon management怎么使用:直接 / 支持;一手验证:13;外部现实校验:03、04、10;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07)|Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域08) / 定向深挖(研究域03)|H1 FY12/2026 results briefing materials: demolition technology and carbon services;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域10) / 定向深挖(研究域13)|Medium-term management plan 2024-2026: sustainability and carbon management
完整研究记录(核对用)
研究原文:The Mitsui data workstream is the same CO2 and material-balance capability, so conversion would appear simultaneously as deal flow, service-revenue character and moat evidence.
内部研究类型:shares_data_layer
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F055|06|利润走在现金前面:回款时点是主要的变数
研究范围:开放研究+35项覆盖检查
归并到:F067
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY12/2025 balance sheet: the receivables build that absorbed operating cash flow怎么使用:直接 / 支持;一手验证:19;外部现实校验:32;反向验证:15、17、35;专项深挖:17、19
H1 FY12/2026 interim results (tanshin): cash flow statement怎么使用:直接证据;一手验证:17、19
FY12/2025 consolidated cash flow: capex year funded by long-term borrowing怎么使用:直接 / 支持;一手验证:17;同业比较:19、20、25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域32) / 反证(研究域15) / 反证(研究域17) / 反证(研究域35) / 定向深挖(研究域17) / 定向深挖(研究域19)|FY12/2025 balance sheet: the receivables build that absorbed operating cash flow;直接证据 / 一手证据(研究域17) / 一手证据(研究域19)|H1 FY12/2026 interim results (tanshin): cash flow statement;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25)|FY12/2025 consolidated cash flow: capex year funded by long-term borrowing
完整研究记录(核对用)
研究原文:The cash side of the same completion-timing phenomenon: profit quality, cash conversion and completion dates are one mechanism, carried by net cash.
内部研究类型:same_mechanism_cash_side
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F056|06|利息支出十二倍跳升,原因还没有解释
研究范围:开放研究+35项覆盖检查
写入正文:06|利息支出十二倍跳升,原因还没有解释
归并到:F016
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): interest expense step-change怎么使用:直接 / 支持;一手验证:14、32;反向验证:16、18、20、25
H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins怎么使用:直接 / 支持;一手验证:16;反向验证:14、19、32;专项深挖:16、32
H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026怎么使用:支持证据;一手验证:18、29;反向验证:21
FY12/2025 consolidated cash flow: capex year funded by long-term borrowing怎么使用:支持证据;一手验证:17;同业比较:19、20、25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域18) / 反证(研究域20) / 反证(研究域25)|H1 FY12/2026 interim results (tanshin): interest expense step-change;直接证据 / 支持证据 / 一手证据(研究域16) / 反证(研究域14) / 反证(研究域19) / 反证(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins;支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 反证(研究域21)|H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026;支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25)|FY12/2025 consolidated cash flow: capex year funded by long-term borrowing
完整研究记录(核对用)
研究原文:If the interest step-up reflects a structurally higher marginal funding cost, the debt-funded capacity model carries a higher hurdle than assumed.
内部研究类型:qualifies
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F057|07|一半表决权在创业家族,少数股东依赖家族的资本纪律
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论07|一半表决权在创业家族,少数股东依赖家族的资本纪律
归并到:F005
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、23、24
FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
IRBANK timely-disclosure index for IBOKIN: buyback history in detail怎么使用:直接 / 支持;反向验证:23、26;同业比较:24;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Securities report data for IBOKIN (FY12/2025): major shareholders and company profile;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 反证(研究域23) / 反证(研究域26)|IRBANK timely-disclosure index for IBOKIN: buyback history in detail
完整研究记录(核对用)
研究原文:Founder control favours capacity investment over distributions, which explains the flat dividend and token buybacks.
内部研究类型:shapes
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F058|11|下半年软不软,第三季度和全年业绩会给答案
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar怎么使用:直接 / 支持;一手验证:30
H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half怎么使用:直接 / 支持;一手验证:31、35;反向验证:30;专项深挖:31、35
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:支持证据;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume
完整研究记录(核对用)
研究原文:The Q3 print and the annual results test whether the implied soft second half is prudence or a real soft patch.
内部研究类型:tests
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F059|01|评级B:资产垫层够厚,但要先等第三季度业绩
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|评级B:资产垫层够厚,但要先等第三季度业绩11|什么会推翻这个判断
归并到:F068
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar怎么使用:直接 / 支持;一手验证:30
H1 FY12/2026 results briefing materials: the Suminoe yard project怎么使用:直接 / 支持;一手验证:20;专项深挖:20
Mitsui & Co. alliance release: the four workstreams in detail怎么使用:直接 / 支持;一手验证:07;专项深挖:07
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:支持证据;一手验证:15、16、35
H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half怎么使用:支持证据;一手验证:31、35;反向验证:30;专项深挖:31、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|H1 FY12/2026 results briefing materials: the Suminoe yard project;直接证据 / 支持证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Mitsui & Co. alliance release: the four workstreams in detail;支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half
完整研究记录(核对用)
研究原文:Each dated catalyst maps to one falsifier or confirmer of the thesis: margin durability, plan credibility, capacity conversion, channel conversion and capital policy.
内部研究类型:verifies_or_falsifies
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F060|01|评级B:资产垫层够厚,但要先等第三季度业绩
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|评级B:资产垫层够厚,但要先等第三季度业绩11|什么会推翻这个判断
归并到:F068
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system怎么使用:支持证据;一手验证:07
Medium-term management plan 2024-2026: targets and ten-year vision怎么使用:支持证据;一手验证:05、11、14;反向验证:09;同业比较:04、30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;支持证据 / 一手证据(研究域07)|Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system;支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域14) / 历史/同业比较(研究域04) / 历史/同业比较(研究域30) / 反证(研究域09)|Medium-term management plan 2024-2026: targets and ten-year vision
完整研究记录(核对用)
研究原文:Whether H1 repair is capability or roll-off arithmetic is the thesis variable.
内部研究类型:central_variable
内部来源标记:OPEN_DISCOVERY
F061|10|价格先动了一次,业绩修复却没有得到同样的价格认可
研究范围:开放研究+35项覆盖检查
写入正文:10|价格先动了一次,业绩修复却没有得到同样的价格认可11|价格和账目在等同一份证据12|三个与表面数字相反的读数
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar怎么使用:直接 / 支持;一手验证:30
Mitsui & Co. alliance release: the four workstreams in detail怎么使用:直接证据;一手验证:07;专项深挖:07
Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), August 2018 to October 2026怎么使用:直接证据;一手验证:34
Locally recomputed monthly series: the April 2026 volume pulse and its retracement怎么使用:直接证据;一手验证:33、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Mitsui & Co. alliance release: the four workstreams in detail;直接证据 / 一手证据(研究域34)|Locally recomputed monthly series from the assembled price history (Yahoo Finance chart API basis), August 2018 to October 2026;直接证据 / 一手证据(研究域33) / 一手证据(研究域34)|Locally recomputed monthly series: the April 2026 volume pulse and its retracement
完整研究记录(核对用)
研究原文:This is a cross-lane reading and does not alter the protected Technical Truth. The price's young residence began on an alliance event (the April 2026 pulse), not on earnings, and it meets its first earnings event in the Q3 print. The price-state evidence is then waiting on the same fundamental evidence as the accounts.
内部研究类型:cross_lane_price_awaits_fundamental_verdict
内部来源标记:OPEN_DISCOVERY / COVERAGE35 / TECHNICAL
F062|10|价格走完了上市后的长期下跌,多年箱体上方还没有人接手
写入正文:00|报告身份、评分与核心结论10|价格走完了上市后的长期下跌,多年箱体上方还没有人接手10|2026年4月的放量脉冲,两个月内被完全回吐10|重心在抬高,但证据只有两年10|价格先动了一次,业绩修复却没有得到同样的价格认可10|什么价格行为会确认这个状态,什么会推翻它14|综合评分59.4/100,评级B15|资料来源的日期和这份报告的边界
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (dereference only)
内部研究类型:protected_technical_synthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
F063|02|企业结构耐久,盈利流只有条件性
研究范围:开放研究+35项覆盖检查
写入正文:02|企业结构耐久,盈利流只有条件性05|护城河靠什么维持,什么会削弱它
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(33项,重复标签已合并)
Securities report data for IBOKIN (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、23、24
Articles of incorporation: registered English name and business purposes怎么使用:直接 / 支持;一手验证:01;同业比较:13;其他用途:历史
Securities report data for IBOKIN (FY12/2025): subsidiaries and employees怎么使用:直接 / 支持;同业比较:07;其他用途:历史
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接 / 支持;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
H1 FY12/2026 results briefing materials: management's framing of the strategy怎么使用:直接证据;一手验证:02、08;专项深挖:02、08
Articles of incorporation: business purposes as the licensed scope怎么使用:直接证据;一手验证:06、10、13;专项深挖:10
H1 FY12/2026 results briefing materials: large demolition machinery and capability build-out怎么使用:直接证据;一手验证:04、10;同业比较:08;其他用途:历史
H1 FY12/2026 results briefing materials: demolition technology and carbon services怎么使用:直接证据;一手验证:03、08;专项深挖:03
H1 FY12/2026 results briefing materials: operating KPIs and volumes怎么使用:直接 / 支持;一手验证:06;反向验证:08、10、13、35
Medium-term management plan 2024-2026: sustainability and carbon management怎么使用:直接证据;一手验证:13;外部现实校验:03、04、10;专项深挖:13
Medium-term management plan 2024-2026: technology development themes怎么使用:直接证据;一手验证:04;专项深挖:04;同业比较:03、10;其他用途:历史
H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、29;反向验证:21
FY12/2025 consolidated cash flow: capex year funded by long-term borrowing怎么使用:直接 / 支持;一手验证:17;同业比较:19、20、25;其他用途:历史
FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities怎么使用:直接 / 支持;一手验证:18、20、21、25;专项深挖:18;同业比较:29;其他用途:历史
Securities report data for IBOKIN (FY12/2025): history, capital and listing path怎么使用:直接证据;一手验证:09、25、33;专项深挖:01、25、33;同业比较:01、23;其他用途:历史
H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half怎么使用:直接 / 支持;一手验证:21、29;外部现实校验:17;专项深挖:29
IRBANK stock page snapshot for 5699 (6 November 2026)怎么使用:直接证据;一手验证:27、31;外部现实校验:01、09、14、16、18、21、22、26、28、29、35;反向验证:24
Securities report data for IBOKIN (FY12/2025): the top-ten register in detail怎么使用:直接证据;一手验证:24;外部现实校验:07、23;反向验证:01;专项深挖:24
Securities report data for IBOKIN: employee counts and group scale怎么使用:直接证据;一手验证:23;专项深挖:23
FY12/2025 results (tanshin): special profits and losses below the ordinary line怎么使用:直接 / 支持;一手验证:32;反向验证:28;同业比较:16、35;其他用途:历史
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
H1 FY12/2026 results briefing materials: the Suminoe yard project怎么使用:直接 / 支持;一手验证:20;专项深挖:20
FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end怎么使用:直接 / 支持;反向验证:06
Medium-term management plan 2024-2026: non-financial KPI table怎么使用:直接 / 支持;同业比较:06、11;其他用途:历史
H1 FY12/2026 results briefing materials: hiring, foreign trainees and human capital怎么使用:直接证据;外部现实校验:06;反向验证:04;专项深挖:06
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins怎么使用:直接证据;一手验证:16;反向验证:14、19、32;专项深挖:16、32
Locally recomputed monthly series: the April 2026 volume pulse and its retracement怎么使用:直接证据;一手验证:33、34
Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023怎么使用:直接 / 支持;专项深挖:28;同业比较:02、09、28、33;其他用途:历史
Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators怎么使用:直接 / 支持;一手验证:28;反向验证:27;同业比较:12、14、35;其他用途:历史
FY12/2025 results (tanshin): prior-year comparatives - FY12/2024 as the band's top怎么使用:直接 / 支持;一手验证:28;同业比较:17、18、22;其他用途:历史
H1 FY12/2026 results briefing materials: environment segment detail怎么使用:直接 / 支持;反向验证:03、11
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Securities report data for IBOKIN (FY12/2025): major shareholders and company profile;直接证据 / 支持证据 / 一手证据(研究域01) / 历史/同业比较(研究域13)|Articles of incorporation: registered English name and business purposes;直接证据 / 支持证据 / 历史/同业比较(研究域07)|Securities report data for IBOKIN (FY12/2025): subsidiaries and employees;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume;直接证据 / 一手证据(研究域02) / 一手证据(研究域08) / 定向深挖(研究域02) / 定向深挖(研究域08)|H1 FY12/2026 results briefing materials: management's framing of the strategy;直接证据 / 一手证据(研究域06) / 一手证据(研究域10) / 一手证据(研究域13) / 定向深挖(研究域10)|Articles of incorporation: business purposes as the licensed scope;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 历史/同业比较(研究域08)|H1 FY12/2026 results briefing materials: large demolition machinery and capability build-out;直接证据 / 一手证据(研究域03) / 一手证据(研究域08) / 定向深挖(研究域03)|H1 FY12/2026 results briefing materials: demolition technology and carbon services;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域08) / 反证(研究域10) / 反证(研究域13) / 反证(研究域35)|H1 FY12/2026 results briefing materials: operating KPIs and volumes;直接证据 / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域10) / 定向深挖(研究域13)|Medium-term management plan 2024-2026: sustainability and carbon management;直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03) / 历史/同业比较(研究域10) / 定向深挖(研究域04)|Medium-term management plan 2024-2026: technology development themes;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 反证(研究域21)|H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25)|FY12/2025 consolidated cash flow: capex year funded by long-term borrowing;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域25) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities;直接证据 / 一手证据(研究域09) / 一手证据(研究域25) / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域25) / 定向深挖(研究域33)|Securities report data for IBOKIN (FY12/2025): history, capital and listing path;直接证据 / 支持证据 / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17) / 定向深挖(研究域29)|H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5699 (6 November 2026);直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 外部现实(研究域23) / 反证(研究域01) / 定向深挖(研究域24)|Securities report data for IBOKIN (FY12/2025): the top-ten register in detail;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Securities report data for IBOKIN: employee counts and group scale;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域35) / 反证(研究域28)|FY12/2025 results (tanshin): special profits and losses below the ordinary line;直接证据 / 支持证据|FY12/2025 results (tanshin): parent-only results against consolidated;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|H1 FY12/2026 results briefing materials: the Suminoe yard project;直接证据 / 支持证据 / 反证(研究域06)|FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end;直接证据 / 支持证据 / 历史/同业比较(研究域06) / 历史/同业比较(研究域11)|Medium-term management plan 2024-2026: non-financial KPI table;直接证据 / 外部现实(研究域06) / 反证(研究域04) / 定向深挖(研究域06)|H1 FY12/2026 results briefing materials: hiring, foreign trainees and human capital;直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;直接证据 / 一手证据(研究域16) / 反证(研究域14) / 反证(研究域19) / 反证(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins;直接证据 / 一手证据(研究域33) / 一手证据(研究域34)|Locally recomputed monthly series: the April 2026 volume pulse and its retracement;直接证据 / 支持证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域28) / 历史/同业比较(研究域33) / 定向深挖(研究域28)|Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域35) / 反证(研究域27)|Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22)|FY12/2025 results (tanshin): prior-year comparatives - FY12/2024 as the band's top;直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域11)|H1 FY12/2026 results briefing materials: environment segment detail
完整研究记录(核对用)
研究原文:Durable business portrait: durable enterprise, conditional earnings stream|The durable core is the assembly beneath the earnings, not the earnings, which oscillate in a JPY 545-824m ordinary-profit band. The assembly comprises site-specific permits, owned yards in a land-constrained region, super-large machinery, a licensed supervisor corps, and net cash with a 63.9% equity ratio and no post-IPO dilution. It has survived a scrap cycle, a profit halving and recovery, and a market-segment change, and is being thickened by Mitsue, Suminoe and the Mitsui framework. The fragilities are structural: earnings depend on cost estimation in a handful of large contracts, growth depends on a supervisor pipeline that shrank in the latest half, and control rests on one family with no disclosed succession. Durability is high for the enterprise and conditional for the earnings stream.
内部研究类型:durable_business_portrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The enterprise likely persists, but the shareholder return depends on whether earnings sit at the band's centre or bottom, which the next two prints discipline.
不确定性(原始记录):Rests on one clean half-year of demolition execution and company-disclosed capacity facts.
F064|01|利润区间、账目和折价其实是同一个问题
研究范围:开放研究+35项覆盖检查
写入正文:01|利润区间、账目和折价其实是同一个问题09|折价等于区间中心和下沿之间的距离
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(18项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接 / 支持;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins怎么使用:直接证据;一手验证:16;反向验证:14、19、32;专项深挖:16、32
Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators怎么使用:直接 / 支持;一手验证:28;反向验证:27;同业比较:12、14、35;其他用途:历史
FY12/2025 results (tanshin): special profits and losses below the ordinary line怎么使用:直接 / 支持;一手验证:32;反向验证:28;同业比较:16、35;其他用途:历史
FY12/2025 results (tanshin): prior-year comparatives - FY12/2024 as the band's top怎么使用:直接 / 支持;一手验证:28;同业比较:17、18、22;其他用途:历史
Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023怎么使用:直接 / 支持;专项深挖:28;同业比较:02、09、28、33;其他用途:历史
IRBANK stock page snapshot for 5699 (6 November 2026)怎么使用:直接 / 支持;一手验证:27、31;外部现实校验:01、09、14、16、18、21、22、26、28、29、35;反向验证:24
H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half怎么使用:直接 / 支持;一手验证:31、35;反向验证:30;专项深挖:31、35
FY12/2025 consolidated results (tanshin): headline earnings and year-on-year changes怎么使用:直接 / 支持;一手验证:22;同业比较:32;其他用途:历史
H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、29;反向验证:21
FY12/2025 consolidated cash flow: capex year funded by long-term borrowing怎么使用:直接 / 支持;一手验证:17;同业比较:19、20、25;其他用途:历史
FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
FY12/2025 results (tanshin): share counts - issued, treasury and averages怎么使用:直接证据;一手验证:27;专项深挖:27
IRBANK stock page for 5699: daily print of 6 November 2026 and volume context怎么使用:直接证据;外部现实校验:27、31、34
FY12/2026 consolidated forecast as first issued with the FY12/2025 results怎么使用:直接 / 支持;同业比较:31;其他用途:历史
H1 FY12/2026 interim results (tanshin): interest expense step-change怎么使用:直接证据;一手验证:14、32;反向验证:16、18、20、25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume;直接证据 / 一手证据(研究域16) / 反证(研究域14) / 反证(研究域19) / 反证(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域12) / 历史/同业比较(研究域14) / 历史/同业比较(研究域35) / 反证(研究域27)|Securities report data for IBOKIN (FY12/2025): parent-only five-year indicators;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域16) / 历史/同业比较(研究域35) / 反证(研究域28)|FY12/2025 results (tanshin): special profits and losses below the ordinary line;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域22)|FY12/2025 results (tanshin): prior-year comparatives - FY12/2024 as the band's top;直接证据 / 支持证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域28) / 历史/同业比较(研究域33) / 定向深挖(研究域28)|Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5699 (6 November 2026);直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half;直接证据 / 支持证据 / 一手证据(研究域22) / 历史/同业比较(研究域32)|FY12/2025 consolidated results (tanshin): headline earnings and year-on-year changes;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 反证(研究域21)|H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25)|FY12/2025 consolidated cash flow: capex year funded by long-term borrowing;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity;直接证据 / 一手证据(研究域27) / 定向深挖(研究域27)|FY12/2025 results (tanshin): share counts - issued, treasury and averages;直接证据 / 外部现实(研究域27) / 外部现实(研究域31) / 外部现实(研究域34)|IRBANK stock page for 5699: daily print of 6 November 2026 and volume context;直接证据 / 支持证据 / 历史/同业比较(研究域31)|FY12/2026 consolidated forecast as first issued with the FY12/2025 results;直接证据 / 一手证据(研究域14) / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域18) / 反证(研究域20) / 反证(研究域25)|H1 FY12/2026 interim results (tanshin): interest expense step-change
完整研究记录(核对用)
研究原文:Demolition estimation quality as the shared spine of operations, accounts and valuation|Segment profit swings, the width of the earnings band and the below-book valuation are the same question observed from three domains, so the Q3 FY12/26 print speaks to all three at once.
内部研究类型:cross_domain_causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):One observation can re-rate or de-rate the position.
不确定性(原始记录):The Q3 print was not yet published at the freeze date.
F065|03|持证监督员是产能的法律闸门,人数在下降
研究范围:开放研究+35项覆盖检查
写入正文:03|持证监督员是产能的法律闸门,人数在下降11|监督员人数是增长的前置条件,也是前瞻信号
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(15项,重复标签已合并)
FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end怎么使用:直接 / 支持;反向验证:06
H1 FY12/2026 results briefing materials: operating KPIs and volumes怎么使用:直接 / 支持;一手验证:06;反向验证:08、10、13、35
Medium-term management plan 2024-2026: non-financial KPI table怎么使用:直接 / 支持;同业比较:06、11;其他用途:历史
Articles of incorporation: business purposes as the licensed scope怎么使用:直接证据;一手验证:06、10、13;专项深挖:10
H1 FY12/2026 results briefing materials: hiring, foreign trainees and human capital怎么使用:直接证据;外部现实校验:06;反向验证:04;专项深挖:06
Medium-term management plan 2024-2026: targets and ten-year vision怎么使用:直接 / 支持;一手验证:05、11、14;反向验证:09;同业比较:04、30;其他用途:历史
Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023怎么使用:直接证据;专项深挖:28;同业比较:02、09、28、33;其他用途:历史
Medium-term management plan 2024-2026: staging and the 2033 vision怎么使用:直接 / 支持;一手验证:09;专项深挖:05、09、11
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接 / 支持;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins怎么使用:直接证据;一手验证:16;反向验证:14、19、32;专项深挖:16、32
H1 FY12/2026 results briefing materials: environment segment detail怎么使用:直接 / 支持;反向验证:03、11
H1 FY12/2026 results briefing materials: the Suminoe yard project怎么使用:直接 / 支持;一手验证:20;专项深挖:20
FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities怎么使用:直接证据;一手验证:18、20、21、25;专项深挖:18;同业比较:29;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域06)|FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域08) / 反证(研究域10) / 反证(研究域13) / 反证(研究域35)|H1 FY12/2026 results briefing materials: operating KPIs and volumes;直接证据 / 支持证据 / 历史/同业比较(研究域06) / 历史/同业比较(研究域11)|Medium-term management plan 2024-2026: non-financial KPI table;直接证据 / 一手证据(研究域06) / 一手证据(研究域10) / 一手证据(研究域13) / 定向深挖(研究域10)|Articles of incorporation: business purposes as the licensed scope;直接证据 / 外部现实(研究域06) / 反证(研究域04) / 定向深挖(研究域06)|H1 FY12/2026 results briefing materials: hiring, foreign trainees and human capital;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域14) / 历史/同业比较(研究域04) / 历史/同业比较(研究域30) / 反证(研究域09)|Medium-term management plan 2024-2026: targets and ten-year vision;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域28) / 历史/同业比较(研究域33) / 定向深挖(研究域28)|Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023;直接证据 / 支持证据 / 一手证据(研究域09) / 定向深挖(研究域05) / 定向深挖(研究域09) / 定向深挖(研究域11)|Medium-term management plan 2024-2026: staging and the 2033 vision;直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume;直接证据 / 一手证据(研究域16) / 反证(研究域14) / 反证(研究域19) / 反证(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins;直接证据 / 支持证据 / 反证(研究域03) / 反证(研究域11)|H1 FY12/2026 results briefing materials: environment segment detail;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|H1 FY12/2026 results briefing materials: the Suminoe yard project;直接证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域25) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities
完整研究记录(核对用)
研究原文:Supervisor headcount as strategy disclosure|Plan targets, demolition capacity and the 2033 vision all scale with licensed headcount, which fell in H1 FY12/26, so a hiring disclosure is functionally a strategy disclosure for this issuer.
内部研究类型:cross_domain_causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Growth credibility depends on a labour market the company does not control.
不确定性(原始记录):Cause of the headcount decline is undisclosed.
F066|04|三菱商事合作是一个选择权,还没有变成收入
研究范围:开放研究+35项覆盖检查
写入正文:04|三菱商事合作是一个选择权,还没有变成收入11|住之江开业和三菱商事转化是两个有日期的催化剂
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system怎么使用:直接 / 支持;一手验证:07
Mitsui & Co. alliance release: the four workstreams in detail怎么使用:直接证据;一手验证:07;专项深挖:07
Securities report data for IBOKIN (FY12/2025): the top-ten register in detail怎么使用:直接证据;一手验证:24;外部现实校验:07、23;反向验证:01;专项深挖:24
H1 FY12/2026 results briefing materials: demolition technology and carbon services怎么使用:直接 / 支持;一手验证:03、08;专项深挖:03
Medium-term management plan 2024-2026: sustainability and carbon management怎么使用:直接 / 支持;一手验证:13;外部现实校验:03、04、10;专项深挖:13
IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023怎么使用:直接证据;一手验证:22;外部现实校验:13、25;反向验证:07;专项深挖:22
H1 FY12/2026 results briefing materials: large demolition machinery and capability build-out怎么使用:直接证据;一手验证:04、10;同业比较:08;其他用途:历史
Medium-term management plan 2024-2026: technology development themes怎么使用:直接证据;一手验证:04;专项深挖:04;同业比较:03、10;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域07)|Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Mitsui & Co. alliance release: the four workstreams in detail;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 外部现实(研究域23) / 反证(研究域01) / 定向深挖(研究域24)|Securities report data for IBOKIN (FY12/2025): the top-ten register in detail;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域08) / 定向深挖(研究域03)|H1 FY12/2026 results briefing materials: demolition technology and carbon services;直接证据 / 支持证据 / 一手证据(研究域13) / 外部现实(研究域03) / 外部现实(研究域04) / 外部现实(研究域10) / 定向深挖(研究域13)|Medium-term management plan 2024-2026: sustainability and carbon management;直接证据 / 一手证据(研究域22) / 外部现实(研究域13) / 外部现实(研究域25) / 反证(研究域07) / 定向深挖(研究域22)|IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023;直接证据 / 一手证据(研究域04) / 一手证据(研究域10) / 历史/同业比较(研究域08)|H1 FY12/2026 results briefing materials: large demolition machinery and capability build-out;直接证据 / 一手证据(研究域04) / 历史/同业比较(研究域03) / 历史/同业比较(研究域10) / 定向深挖(研究域04)|Medium-term management plan 2024-2026: technology development themes
完整研究记录(核对用)
研究原文:Mitsui alliance and carbon-data capability as one conversion path|The commercial alliance and the technical and regulatory data capability are one mechanism. Conversion evidence, if it comes, would appear simultaneously as deal flow, service-revenue character and moat observation.
内部研究类型:cross_domain_causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Option value accrues to shareholders if it converts, and disappointment costs only the option.
不确定性(原始记录):No transactions are disclosed yet.
F067|06|利润走在现金前面:回款时点是主要的变数
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(12项,重复标签已合并)
FY12/2025 balance sheet: the receivables build that absorbed operating cash flow怎么使用:直接 / 支持;一手验证:19;外部现实校验:32;反向验证:15、17、35;专项深挖:17、19
FY12/2025 consolidated cash flow: capex year funded by long-term borrowing怎么使用:直接 / 支持;一手验证:17;同业比较:19、20、25;其他用途:历史
H1 FY12/2026 interim results (tanshin): cash flow statement怎么使用:直接证据;一手验证:17、19
FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities怎么使用:直接 / 支持;一手验证:18、20、21、25;专项深挖:18;同业比较:29;其他用途:历史
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接 / 支持;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins怎么使用:直接证据;一手验证:16;反向验证:14、19、32;专项深挖:16、32
H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026怎么使用:直接 / 支持;一手验证:18、29;反向验证:21
Securities report data for IBOKIN (FY12/2025): history, capital and listing path怎么使用:直接证据;一手验证:09、25、33;专项深挖:01、25、33;同业比较:01、23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 外部现实(研究域32) / 反证(研究域15) / 反证(研究域17) / 反证(研究域35) / 定向深挖(研究域17) / 定向深挖(研究域19)|FY12/2025 balance sheet: the receivables build that absorbed operating cash flow;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19) / 历史/同业比较(研究域20) / 历史/同业比较(研究域25)|FY12/2025 consolidated cash flow: capex year funded by long-term borrowing;直接证据 / 一手证据(研究域17) / 一手证据(研究域19)|H1 FY12/2026 interim results (tanshin): cash flow statement;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域25) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities;直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume;直接证据 / 一手证据(研究域16) / 反证(研究域14) / 反证(研究域19) / 反证(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29) / 反证(研究域21)|H1 FY12/2026 interim results (tanshin): balance sheet at 30 June 2026;直接证据 / 一手证据(研究域09) / 一手证据(研究域25) / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域25) / 定向深挖(研究域33)|Securities report data for IBOKIN (FY12/2025): history, capital and listing path;直接证据 / 支持证据|Q1 FY12/2026 results (tanshin): first-quarter earnings;直接证据 / 支持证据|Q1 FY12/2026 results (tanshin): the front-loaded quarter and the implied Q2
完整研究记录(核对用)
研究原文:Contracting model, working capital and net-cash cushion|The FY12/25 receivables build and its H1 reversal show that profit quality, cash conversion and demolition completion timing are one mechanism. Net cash lets the group carry it without financial stress.
内部研究类型:cross_domain_causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A weak single-year cash print is a timing risk, not a solvency risk, unless receivables quality deteriorates.
不确定性(原始记录):Receivable ageing is undisclosed.
F068|01|评级B:资产垫层够厚,但要先等第三季度业绩
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|评级B:资产垫层够厚,但要先等第三季度业绩11|什么会推翻这个判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(22项,重复标签已合并)
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system怎么使用:直接 / 支持;一手验证:07
Medium-term management plan 2024-2026: targets and ten-year vision怎么使用:直接 / 支持;一手验证:05、11、14;反向验证:09;同业比较:04、30;其他用途:历史
H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half怎么使用:直接 / 支持;一手验证:31、35;反向验证:30;专项深挖:31、35
H1 FY12/2026 results briefing materials: operating KPIs and volumes怎么使用:直接证据;一手验证:06;反向验证:08、10、13、35
FY12/2025 balance sheet: the receivables build that absorbed operating cash flow怎么使用:直接证据;一手验证:19;外部现实校验:32;反向验证:15、17、35;专项深挖:17、19
IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar怎么使用:直接 / 支持;一手验证:30
H1 FY12/2026 results briefing materials: the Suminoe yard project怎么使用:直接 / 支持;一手验证:20;专项深挖:20
Mitsui & Co. alliance release: the four workstreams in detail怎么使用:直接 / 支持;一手验证:07;专项深挖:07
IRBANK timely-disclosure index for IBOKIN: Q3 publication cadence 2023-2025怎么使用:直接证据;一手验证:30;专项深挖:30
Medium-term management plan 2024-2026: non-financial KPI table怎么使用:直接 / 支持;同业比较:06、11;其他用途:历史
FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end怎么使用:直接 / 支持;反向验证:06
Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023怎么使用:直接证据;专项深挖:28;同业比较:02、09、28、33;其他用途:历史
Medium-term management plan 2024-2026: staging and the 2033 vision怎么使用:直接 / 支持;一手验证:09;专项深挖:05、09、11
FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
IRBANK timely-disclosure index for IBOKIN: buyback history in detail怎么使用:直接 / 支持;反向验证:23、26;同业比较:24;其他用途:历史
IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023怎么使用:直接证据;一手验证:22;外部现实校验:13、25;反向验证:07;专项深挖:22
IRBANK stock page snapshot for 5699 (6 November 2026)怎么使用:直接证据;一手验证:27、31;外部现实校验:01、09、14、16、18、21、22、26、28、29、35;反向验证:24
IRBANK stock page for 5699: daily print of 6 November 2026 and volume context怎么使用:直接证据;外部现实校验:27、31、34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 支持证据 / 一手证据(研究域07)|Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域14) / 历史/同业比较(研究域04) / 历史/同业比较(研究域30) / 反证(研究域09)|Medium-term management plan 2024-2026: targets and ten-year vision;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half;直接证据 / 一手证据(研究域06) / 反证(研究域08) / 反证(研究域10) / 反证(研究域13) / 反证(研究域35)|H1 FY12/2026 results briefing materials: operating KPIs and volumes;直接证据 / 一手证据(研究域19) / 外部现实(研究域32) / 反证(研究域15) / 反证(研究域17) / 反证(研究域35) / 定向深挖(研究域17) / 定向深挖(研究域19)|FY12/2025 balance sheet: the receivables build that absorbed operating cash flow;直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|H1 FY12/2026 results briefing materials: the Suminoe yard project;直接证据 / 支持证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Mitsui & Co. alliance release: the four workstreams in detail;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|IRBANK timely-disclosure index for IBOKIN: Q3 publication cadence 2023-2025;直接证据 / 支持证据 / 历史/同业比较(研究域06) / 历史/同业比较(研究域11)|Medium-term management plan 2024-2026: non-financial KPI table;直接证据 / 支持证据 / 反证(研究域06)|FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域28) / 历史/同业比较(研究域33) / 定向深挖(研究域28)|Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023;直接证据 / 支持证据 / 一手证据(研究域09) / 定向深挖(研究域05) / 定向深挖(研究域09) / 定向深挖(研究域11)|Medium-term management plan 2024-2026: staging and the 2033 vision;直接证据 / 支持证据|H1 FY12/2026 results briefing materials: dividend record and stated policy;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 反证(研究域23) / 反证(研究域26)|IRBANK timely-disclosure index for IBOKIN: buyback history in detail;直接证据 / 一手证据(研究域26)|H1 FY12/2026 interim results (tanshin): dividend table - no interim dividend;直接证据 / 一手证据(研究域22) / 外部现实(研究域13) / 外部现实(研究域25) / 反证(研究域07) / 定向深挖(研究域22)|IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023;直接证据 / 一手证据(研究域27) / 一手证据(研究域31) / 外部现实(研究域01) / 外部现实(研究域09) / 外部现实(研究域14) / 外部现实(研究域16) / 外部现实(研究域18) / 外部现实(研究域21) / 外部现实(研究域22) / 外部现实(研究域26) / 外部现实(研究域28) / 外部现实(研究域29) / 外部现实(研究域35) / 反证(研究域24)|IRBANK stock page snapshot for 5699 (6 November 2026);直接证据 / 外部现实(研究域27) / 外部现实(研究域31) / 外部现实(研究域34)|IRBANK stock page for 5699: daily print of 6 November 2026 and volume context
完整研究记录(核对用)
研究原文:Thesis, falsifiers and dated verification calendar|The thesis is a capability claim about estimation and capacity, and its falsifiers are capability observations (margins, headcount, backlog conversion, receivables), not price moves.
内部研究类型:thesis_and_verification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A short falsification window with asset-cushioned downside makes the thesis testable cheaply.
不确定性(原始记录):Resolution depends on prints not yet published.
F069|13|下一次要先解决的几个问题
研究范围:开放研究+35项覆盖检查
写入正文:13|下一次要先解决的几个问题
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(32项,重复标签已合并)
IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar怎么使用:直接 / 支持;一手验证:30
H1 FY12/2026 results briefing materials: the Suminoe yard project怎么使用:直接 / 支持;一手验证:20;专项深挖:20
Mitsui & Co. alliance release: the four workstreams in detail怎么使用:直接 / 支持;一手验证:07;专项深挖:07
IRBANK timely-disclosure index for IBOKIN: Q3 publication cadence 2023-2025怎么使用:直接证据;一手验证:30;专项深挖:30
H1 FY12/2026 interim results (tanshin): headline earnings怎么使用:直接 / 支持;反向验证:31
FY12/2026 consolidated forecast as first issued with the FY12/2025 results怎么使用:直接 / 支持;同业比较:31;其他用途:历史
H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half怎么使用:直接 / 支持;一手验证:31、35;反向验证:30;专项深挖:31、35
FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume怎么使用:直接 / 支持;一手验证:02、03;反向验证:12、29、33;同业比较:05、15、16;其他用途:历史
Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system怎么使用:直接 / 支持;一手验证:07
Securities report data for IBOKIN (FY12/2025): the top-ten register in detail怎么使用:直接证据;一手验证:24;外部现实校验:07、23;反向验证:01;专项深挖:24
Medium-term management plan 2024-2026: targets and ten-year vision怎么使用:直接 / 支持;一手验证:05、11、14;反向验证:09;同业比较:04、30;其他用途:历史
Medium-term management plan 2024-2026: non-financial KPI table怎么使用:直接 / 支持;同业比较:06、11;其他用途:历史
FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end怎么使用:直接 / 支持;反向验证:06
Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023怎么使用:直接证据;专项深挖:28;同业比较:02、09、28、33;其他用途:历史
Medium-term management plan 2024-2026: staging and the 2033 vision怎么使用:直接 / 支持;一手验证:09;专项深挖:05、09、11
H1 FY12/2026 results briefing materials: operating KPIs and volumes怎么使用:直接 / 支持;一手验证:06;反向验证:08、10、13、35
Articles of incorporation: business purposes as the licensed scope怎么使用:直接证据;一手验证:06、10、13;专项深挖:10
H1 FY12/2026 results briefing materials: hiring, foreign trainees and human capital怎么使用:直接证据;外部现实校验:06;反向验证:04;专项深挖:06
H1 FY12/2026 interim results (tanshin): interest expense step-change怎么使用:直接 / 支持;一手验证:14、32;反向验证:16、18、20、25
H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins怎么使用:直接 / 支持;一手验证:16;反向验证:14、19、32;专项深挖:16、32
H1 FY12/2026 results briefing materials: segment sales and profit怎么使用:直接 / 支持;一手验证:15、16、35
FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities怎么使用:直接证据;一手验证:18、20、21、25;专项深挖:18;同业比较:29;其他用途:历史
Securities report data for IBOKIN (FY12/2025): major shareholders and company profile怎么使用:直接 / 支持;一手验证:01、23、24
Securities report data for IBOKIN (FY12/2025): subsidiaries and employees怎么使用:直接 / 支持;同业比较:07;其他用途:历史
Securities report data for IBOKIN: employee counts and group scale怎么使用:直接证据;一手验证:23;专项深挖:23
Securities report data for IBOKIN (FY12/2025): history, capital and listing path怎么使用:直接证据;一手验证:09、25、33;专项深挖:01、25、33;同业比较:01、23;其他用途:历史
FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity怎么使用:直接 / 支持;一手验证:26;反向验证:22;专项深挖:26
IRBANK timely-disclosure index for IBOKIN: buyback history in detail怎么使用:直接 / 支持;反向验证:23、26;同业比较:24;其他用途:历史
IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023怎么使用:直接证据;一手验证:22;外部现实校验:13、25;反向验证:07;专项深挖:22
H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half怎么使用:直接证据;一手验证:21、29;外部现实校验:17;专项深挖:29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30)|IRBANK timely-disclosure index for IBOKIN (E34130): buybacks, capital-cost response, Q3 calendar;直接证据 / 支持证据 / 一手证据(研究域20) / 定向深挖(研究域20)|H1 FY12/2026 results briefing materials: the Suminoe yard project;直接证据 / 支持证据 / 一手证据(研究域07) / 定向深挖(研究域07)|Mitsui & Co. alliance release: the four workstreams in detail;直接证据 / 一手证据(研究域30) / 定向深挖(研究域30)|IRBANK timely-disclosure index for IBOKIN: Q3 publication cadence 2023-2025;直接证据 / 支持证据 / 反证(研究域31)|H1 FY12/2026 interim results (tanshin): headline earnings;直接证据 / 支持证据 / 历史/同业比较(研究域31)|FY12/2026 consolidated forecast as first issued with the FY12/2025 results;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|H1 FY12/2026 interim results (tanshin): forecast maintained and the implied second half;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 反证(研究域12) / 反证(研究域29) / 反证(研究域33)|FY12/2025 results (tanshin): segment review - demolition cost overruns, metals volume;直接证据 / 支持证据 / 一手证据(研究域07)|Strategic business alliance (MOU) with Mitsui & Co. for a stable metal-scrap supply system;直接证据 / 一手证据(研究域24) / 外部现实(研究域07) / 外部现实(研究域23) / 反证(研究域01) / 定向深挖(研究域24)|Securities report data for IBOKIN (FY12/2025): the top-ten register in detail;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域11) / 一手证据(研究域14) / 历史/同业比较(研究域04) / 历史/同业比较(研究域30) / 反证(研究域09)|Medium-term management plan 2024-2026: targets and ten-year vision;直接证据 / 支持证据 / 历史/同业比较(研究域06) / 历史/同业比较(研究域11)|Medium-term management plan 2024-2026: non-financial KPI table;直接证据 / 支持证据 / 反证(研究域06)|FY12/2025 results (tanshin): demolition backlog and supervisor count at year-end;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域28) / 历史/同业比较(研究域33) / 定向深挖(研究域28)|Medium-term management plan 2024-2026: consolidated actuals for 2022 and 2023;直接证据 / 支持证据 / 一手证据(研究域09) / 定向深挖(研究域05) / 定向深挖(研究域09) / 定向深挖(研究域11)|Medium-term management plan 2024-2026: staging and the 2033 vision;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域08) / 反证(研究域10) / 反证(研究域13) / 反证(研究域35)|H1 FY12/2026 results briefing materials: operating KPIs and volumes;直接证据 / 一手证据(研究域06) / 一手证据(研究域10) / 一手证据(研究域13) / 定向深挖(研究域10)|Articles of incorporation: business purposes as the licensed scope;直接证据 / 外部现实(研究域06) / 反证(研究域04) / 定向深挖(研究域06)|H1 FY12/2026 results briefing materials: hiring, foreign trainees and human capital;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域32) / 反证(研究域16) / 反证(研究域18) / 反证(研究域20) / 反证(研究域25)|H1 FY12/2026 interim results (tanshin): interest expense step-change;直接证据 / 支持证据 / 一手证据(研究域16) / 反证(研究域14) / 反证(研究域19) / 反证(研究域32) / 定向深挖(研究域16) / 定向深挖(研究域32)|H1 FY12/2026 interim results (tanshin): profit-and-loss detail and margins;直接证据 / 支持证据 / 一手证据(研究域15) / 一手证据(研究域16) / 一手证据(研究域35)|H1 FY12/2026 results briefing materials: segment sales and profit;直接证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域25) / 历史/同业比较(研究域29) / 定向深挖(研究域18)|FY12/2025 balance sheet detail: land, leases, long-term debt and legacy liabilities;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域23) / 一手证据(研究域24)|Securities report data for IBOKIN (FY12/2025): major shareholders and company profile;直接证据 / 支持证据 / 历史/同业比较(研究域07)|Securities report data for IBOKIN (FY12/2025): subsidiaries and employees;直接证据 / 一手证据(研究域23) / 定向深挖(研究域23)|Securities report data for IBOKIN: employee counts and group scale;直接证据 / 一手证据(研究域09) / 一手证据(研究域25) / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域23) / 定向深挖(研究域01) / 定向深挖(研究域25) / 定向深挖(研究域33)|Securities report data for IBOKIN (FY12/2025): history, capital and listing path;直接证据 / 支持证据|H1 FY12/2026 results briefing materials: dividend record and stated policy;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域22) / 定向深挖(研究域26)|FY12/2025 results (tanshin): dividend table - totals, payout and dividend on equity;直接证据 / 支持证据 / 历史/同业比较(研究域24) / 反证(研究域23) / 反证(研究域26)|IRBANK timely-disclosure index for IBOKIN: buyback history in detail;直接证据 / 一手证据(研究域26)|H1 FY12/2026 interim results (tanshin): dividend table - no interim dividend;直接证据 / 一手证据(研究域22) / 外部现实(研究域13) / 外部现实(研究域25) / 反证(研究域07) / 定向深挖(研究域22)|IRBANK timely-disclosure index for IBOKIN: capital-cost response disclosure of December 2023;直接证据 / 一手证据(研究域21) / 一手证据(研究域29) / 外部现实(研究域17) / 定向深挖(研究域29)|H1 FY12/2026 interim results (tanshin): balance-sheet movements in the half
完整研究记录(核对用)
研究原文:Open research debt carried forward|The questions are the Q3 margin print, the reason for the soft implied H2, Mitsui conversion, the successor plan, supervisor trajectory, the interest step-up, Suminoe cost and capacity, succession and liquidity, dividend or buyback reset, and unquantified contingent liabilities. Each has concrete next evidence in its node.
内部研究类型:research_debt_set
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Each can change the normalised band, the plan credibility or the downside, and most resolve within the next four reporting periods.
不确定性(原始记录):No reasonable current public path exists for most, because they depend on future disclosures.
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | 03ce439d51380008da66dc3dd8f0e6d0c13a7d1b |
| Delivery Commit SHA | 03ce439d51380008da66dc3dd8f0e6d0c13a7d1b |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | 0f4076ff-d3a2-54dd-a35a-234229799fe1 |
| Canonical Revision | 1 |