净现金约60亿日元,约占市值的35%,自有资本比率85.3%,主要风险是估值长期停滞,而不是财务困境。2026年3月期回购8.35亿日元,库存股占比由0.8%升到4.3%,分红由52日元提高到54日元,再计划提高到60日元,说明资本回报已经起步。
7299
フジオーゼックス株式会社(FUJI OOZX Inc.)
フジオーゼックス株式会社(FUJI OOZX Inc.,东证 Standard 市场,代码7299)主营汽车发动机用的进气门和排气门,同时生产气门座、锁夹和弹簧座,按发动机厂商的规格在日本、墨西哥、中国和印度尼西亚制造;另有一项小业务,生产半导体生产线用的自动控制设备零部件。公司由大同特殊钢(Daido Steel)控股。
最近亮点:2027年3月期(FY3/27)上半年(4–9月)销售额145.42亿日元,上涨2.6%;营业利润17.31亿日元,上涨61.8%;经常利润16.93亿日元,上涨47.1%。10月27日公司把全年经常利润预测上调到29.20亿日元(原26.00亿日元),分红预测由54日元提高到60日元,股价次日大幅回吐,11月6日收于1,675日元。估值简报(2026年11月6日收盘):股价1,675日元;总市值172.2亿日元(按已发行10,279,750股计算,含库存股);预测市盈率(PER)8.9倍(按上调后预测每股收益187.70日元);实绩市净率(PBR)0.51倍(按2026年3月期末每股净资产3,254.46日元);ROE 6.9%(2026年3月期实绩);预测股息率3.58%(按预测分红60日元);EV/EBITDA 2.3倍(EV=总市值172.2亿日元减2026年9月末净现金58.0亿日元,得114.2亿日元;EBITDA=2026年3月期营业利润25.06亿日元加折旧24.47亿日元,得49.53亿日元)。以上几项口径有混用:PBR用年末而非9月末净资产,EV把9月末净现金与2026年3月期全年EBITDA相配,现金定义在不同来源间也不一致,倍数只作参考。
核心产品绑定内燃机,电动车每多一点份额就直接减少气门需求,中国业务已因此萎缩。大同特殊钢是否长期持有、增持或减持,公司没有披露;资本回报没有写下来的承诺框架,现金有可能只是继续堆积。
综合评分62.56/100(评分版本V3.2),B级。建议观察并分批建立小仓位,不追高,不宜重仓:回报要靠资本分配兑现,不靠行业增长。依据是净现金约占市值三成半、PBR 0.51倍、分红和回购已经起步,下行主要是估值长期停滞。证据充分程度把握一般:大同特殊钢的持股意图、关税返还和一次性收益的金额、2026中期经营计划的数字目标都没有披露。新中期计划没有资本回报框架、下半年证明上半年利润率只是时间差,或月线跌破1,565日元,判断将转向有强资产负债表的价值陷阱。 当前动作:观察并分批建立小仓位,不追高。核心逻辑是净现金约占市值三成半、PBR约0.5倍、分红和回购已经起步,下行主要是估值长期停滞,不是财务困境。但回报要靠资本分配兑现,不靠行业增长,因此不宜重仓。后续确认点有三个:2027年1月前后的三季度业绩(在制品能否转为销售、下半年利润是否真的放缓)、2027年5月新中期计划是否给出派息率、净资产分红率或回购框架,以及月线能否收在2250日元之上。如果新计划没有资本框架而现金继续堆积,或下半年证明上半年利润率只是关税返还和转嫁时间差,或月线跌破1565日元,应重新评估,判断将转向有强资产负债表的价值陷阱。
报告目录
01|投资问题与当前结论
01.1|这只股票值不值得买,取决于两件慢事谁先到
核心问题是:一家主力产品绑定内燃机、但近期需求被混合动力延长的公司,能否在电动化触及核心产品之前,把85%的自有资本比率、约60亿日元净现金和刚起步的分红加回购,变成可持续的每股价值。第二层问题是,大同特殊钢持有54%表决权,对少数股东意味着什么。
完整研究之后,这个问题更像两个缓慢过程的赛跑。一边是低价位上持续的资本回报,另一边是不断收窄这块细分市场的动力总成转型。两边都看得见,也都不快。
资产负债表替这场赛跑买了时间。公司不向市场要钱,就能分红、回购、建墨西哥新厂,所以真正的问题只剩现金是否被用掉。现金若只是继续堆积,折价在发动机市场没有高增长的前提下收窄不了;回报若持续兑现,在0.5倍净资产的价位上,每股资产价值会机械上升。
这个判断有一个公开资料解不开的前提:大同特殊钢打算长期持有、增持还是减持,公司没有披露。2027年5月的新中期计划,是第一份有日期的证据。
01.2|论点是折价缓慢收窄,推翻条件有三项
当前判断:细分龙头加强大资产负债表,被按衰退和现金困局永远持续来定价。支撑折价收窄的有四件事:经营杠杆、首次大额回购、上升中的分红和北美混动产能。它们指向资本回报与业绩兑现,不指向增长。论点的确定性中等。
估值上,资产给出下限:净现金约占市值35%,没有大规模交叉持股可释放。按约10亿至29亿日元的正常化经常利润区间,市值对应6至17倍。接近资本成本的回报解释了一部分折价,母公司控制和流通股比例解释了其余部分。所以要重估,需要看到资本回报持续兑现,或流通股、控制权出现事件,而不是单纯便宜。
三项推翻条件有明确日期:一是2027年5月的新中期计划没有资本回报框架,而现金继续堆积;二是2027年3月期下半年显示,上半年利润率是关税返还和成本转嫁的时间差,不是水平上移;三是中国业务由萎缩走到减值,北美没有对冲。条件成立,这只股票就成了资产负债表很强的价值陷阱:没有财务困境,但也没有持有的理由。
02|公司本质与商业模式
02.1|持有的是一个受母公司控制的子公司的少数股权
フジオーゼックス(FUJI OOZX Inc.,代码7299)自称是日本最大的发动机气门制造商,国内份额约33%、全球约15%。这两个数字来自二手汇编,没有经过独立核验,只用来说明位置,不参与计算。公司1951年12月作为Sonoike Valve Co., Ltd.创立于东京品川,1953年大同特殊钢入股,1992年12月改名,总部与主工厂在静冈县菊川市。已发行10,279,750股,股本30.19亿日元。
投资者能拿到的权益,是大同特殊钢控股的一家上市子公司的少数股权。母公司单体销售额222.30亿日元,占合并的76%;母公司单体营业利润22.45亿日元,经常利润26.00亿日元。大部分经济利益留在日本母公司,海外子公司贡献的是销量,以及税务和关税的一次性影响。
02.2|收入是发动机产量的派生需求,利润是价格与成本的差
集团只有一个经营分部,汽车零部件,约占销售的96%,另有一个「其他」分部。汽车零部件的收入来自发动机生产计划:每台发动机配固定数量的气门,按车型项目与整车厂谈价,利润率很薄。
这意味着合并利润率直接反映气门的定价能力。没有第二个业务可以掩盖转嫁失败,经营杠杆向上向下都很大。持久的东西有三样:位置、资产负债表,以及成本转嫁机制;不持久的是任何一年的利润水平,它由发动机产量和谈判带来的转嫁时滞决定,也不包括这块细分市场本身,它的规模以内燃机产量为上限。治理权在母公司手里。
现有披露还回答不了几个问题:客户和项目构成没有披露,销售增长中的销量、价格和并表因素也没有拆分。
02.3|半导体控制部件只占销售约4%,是期权,不是驱动
唯一不绑定发动机的增长业务规模很小,但已有起色。「其他」分部(半导体生产线自动控制设备零部件,2024年7月起并入P&M)2026年3月期销售额11.46亿日元,上涨36.1%,利润由亏损1.20亿日元转为盈利0.34亿日元。2027年3月期上半年销售额7.72亿日元,上涨42.0%,利润由0.06亿日元升到0.91亿日元。
它的体量还不足以改写利润区间。P&M单独的盈利和收购价格没有披露,该分部的增长可能含并表效应。继续翻倍的利润,会是多元化价值最早的证据。
03|产品、客户与供应链
03.1|需求在三个方向轮动,合并增速只剩低个位数
2027年3月期上半年,日本国内销售上涨6.2%,来自日本整车生产恢复和设备相关需求;北美因混合动力需求坚挺和新订单增长;中国因新能源车替代汽油车而大幅下滑,海外销售合计下降4.1%。三个互不相关的动力总成故事相互抵消,合并销售只上涨2.6%,而利润弹性很强。2026年3月期的销售增长13.9%里,国内上涨8.6%(含P&M并表),海外上涨25.9%。
背后的机制是派生需求:气门销量跟随日本、北美和中国的内燃机与混合动力发动机产量。同一批汽车,只要发动机不再是内燃机或混动,就不再产生气门需求。收入质量因此越来越取决于一个地区的混动周期。
客户名称、混动车型在自身气门销量中的占比、按动力总成划分的需求,公司都没有披露。
03.2|主要材料经母公司集团进来,价格靠定期协商
2026年3月期公司向大同特殊钢集团的贸易公司Daido Kogyo采购33.20亿日元的气门用钢、模具钢、包层材料和加工件,年末应付账款3.45亿日元,电子记录债务11.25亿日元。价格按整体成本和市场价格定期协商。
因此钢价周期和集团定价惯例,会直接传到气门利润率。协商用的价格公式没有披露。
03.3|美国关税是一条双向的利润线
墨西哥子公司缴纳的美国关税,在2026年3月期是利润的压力;2027年3月期上半年又有一部分关税返还支撑了利润,并计入销货成本。这使报告利润围绕经营趋势的波动范围变宽。
关税走的是与排放政策不同的通道:后者通过动力总成构成起作用,前者直接进入墨西哥工厂的损益。返还金额和今后的关税水平都没有披露。
04|竞争格局与产业关系
除公司外,日本国内还有少数专业气门厂商,海外则是全球动力总成供应商,市场总量以内燃机产量为上限。上文的国内约33%、全球约15%份额来自二手汇编,没有独立核验,也没有拿竞争对手的成本、价格和产能做过对比,所以这里只能判断公司在一个狭窄细分市场里居前,不能据此推出它在更大的替代市场里同样有议价权。真正的替代选项是电动车项目不再需要气门。
产业关系里最重要的一条是大同特殊钢:公司是该集团唯一的发动机气门制造商,也通过集团采购主要材料。具体治理与定价影响见股东与治理一章。
05|护城河判断
05.1|护城河守住的是现有项目的份额和价差
气门是失效关键部件,按发动机项目逐一认证,用特殊材料和包层工艺制造,如钠冷空心气门,以及适配碳中和燃料的高功能设计。公司的研发费用只有几千万日元,因为技术体现在材料和工艺里,账面看不到专利或品牌。
客户为很小的成本差异去重新认证一个与安全相关的零件,意愿很低;细分市场又小、规格要求严,新进入者不划算。所以它守的是现有发动机项目生命周期内的份额和价差,每个新项目都要重新争取,电动车项目里则没有内容。
这一判断主要是结构推断。合同条款、项目得失率、专利和空心气门溢价都没有披露,也没有同业基准。2026年3月期销售创纪录而营业利润下降4.2%,也说明份额和规模不会自动变成议价能力。
05.2|内燃机依赖决定护城河的有效期,下降路径可能更长更平
护城河保护的范围,随内燃机产量缩减而收窄。中国曾是集团的增长市场,现在已因新能源车替代而萎缩。管理层的展望称,主要市场的电动车普及放缓,混合动力和插电混动需求上升,碳中和燃料延长发动机寿命,使下降路径比早先情景更长更平。这是公司自己的表述,没有独立的市场规模序列可对照。
两种极端之间的差距就是风险所在:混动延长下的数十年下降,与电动车快速普及下的几年下降。估值应按一条较长的下降尾部来算,既不按悬崖,也不按增长。电动化速度是外生变量,公司控制不了。
06|财务质量与现金流
06.1|上半年利润大增,全年上调却把压力留给下半年
2027年3月期上半年,销售额145.42亿日元(上涨2.6%),营业利润17.31亿日元(上涨61.8%),经常利润16.93亿日元(上涨47.1%),净利润11.94亿日元(上涨22.0%)。汽车零部件分部利润16.40亿日元,上涨54.2%,而分部销售额137.70亿日元,只上涨1.1%。毛利率由22.5%升到25.7%,毛利由31.93亿日元增至37.31亿日元。利润弹性来自成本下降和工资上涨的价格转嫁,不来自销量。
10月27日全年预测上调为销售额292.00亿日元、营业利润和经常利润各29.20亿日元、净利润18.50亿日元,原来分别是280.00亿、26.00亿、26.00亿和17.00亿日元。净利润里包含Maruyoshi Manufacturing(清算中的子公司)固定资产出售收益1.01亿日元,毛利里还包含金额未披露的关税返还,所以干净的利润水平拆不出来。
06.2|上一年是销量创纪录,价差却没跟上
2026年3月期销售额升到290.93亿日元,上涨13.9%,创纪录,营业利润却下降4.2%到25.06亿日元,汽车零部件分部利润下降9.7%。应对销量增加的成本、关税、人工和高企的材料价格,都跑在价格转嫁前面。经常利润上涨17.2%到27.43亿日元,靠的是2.2亿日元的汇兑收益。
半年之后情形反了:2027年3月期上半年销售只升2.6%,营业利润升61.8%。这与滞后的价格转嫁追上了成本相符,所以这一轮利润跳升,可能既有永久性的水平上移,也有时间差的成分。这是依据时间先后做出的推断,因果归属没有被证明。
也就是说,钢材、工资和关税成本立刻进入销货成本,价格则靠谈判调整,利润率沿成本周期有时滞地起伏。任何单个半年的利润率,都不能当成新常态;要看到两个连续半期站在新水平上,才可信。
06.3|看经常利润,别看净利润
2026年3月期净利润上涨38.6%到21.44亿日元,而营业利润在下降4.2%。差距来自一串一次性项目:墨西哥子公司递延所得税资产重估带来的税项收益、1.52亿日元保险金(对应0.94亿日元减值损失),以及2.2亿日元汇兑收益。2027年3月期上半年的净利润里,则有1.01亿日元资产出售收益和金额未披露的关税返还。
递延所得税资产由7.03亿日元升到10.54亿日元,它不是现金,可用性也没有被证明。用报告净利润估值,会在利润好看的年份多付钱。这家公司一次性项目密度高,剔除一次性影响是常规动作,以经常利润为准。
关税返还金额和其中资产出售的占比,至今没有拆分。两者占上半年利润超预期的多少,决定了新的利润率是价格转嫁的水平上移,还是时间差的噪声。能解答它的证据,要等三季度和年度的特别项目行,或管理层的量化说明,也可能永远不会单独披露。
06.4|利润转现金的比率高,现金流撑得起全部股东回报
2026年3月期营业现金流50.28亿日元,由税前利润28.01亿日元加折旧24.47亿日元构成;五年平均营业现金流约为净利润的两倍(第三方数据)。资本开支20.94亿日元,低于折旧,说明成熟、折旧充分的资产基础把利润转成现金的比率高。按营业现金流减资本开支粗算,2026年3月期自由现金流约29.34亿日元。2027年3月期上半年营业现金流22.51亿日元。
这使分红、回购和墨西哥扩产都靠内部现金流支付,不动资产负债表。墨西哥项目是第一个明显的例外:资本开支先压低自由现金流,再带来利润,会呈现J形曲线。维护性与扩张性资本开支没有拆分。
06.5|在制品增加4.94亿日元,是提前生产还是积压
2027年3月期上半年在制品增加4.94亿日元,达26.81亿日元,是该半年营业现金流最大的占用项。2026年3月期末的营运资金大致相当于两个月销售:应收账款和电子记录债权合计约60亿日元,存货62.97亿日元,应付账款和电子记录债务约38.8亿日元。
两种读法并存。一种是为下半年交付提前生产,这支持上调后的预测;另一种是,如果隐含的下半年放缓兑现,它就是库存积压的第一个信号。三季度资产负债表是第一次检验。在制品属于日本还是墨西哥、权属与可变现性、成本计价基础,都没有披露。
06.6|几乎没有杠杆,但净现金口径要带着保留看
2026年9月末自有资本比率85.3%,总资产386.73亿日元,净资产335.46亿日元,负债合计51.27亿日元,短期借款为零。负债以应付账款和电子记录债务为主。2026年3月期净现金约60亿日元(现金65.07亿日元,有息负债4.73亿日元),约相当于市值172亿日元的35%。母公司没有贷款或担保。所以剩下的风险全在经营和资金用途上。
口径要保留:2026年9月末现金及等价物74.29亿日元,现金及存款58.01亿日元,净现金多少取决于定义;海外子公司的现金能否上交母公司,也没有披露。土地约34亿日元,按历史成本入账。
这个资产负债表让公司不向市场要钱,就能同时承担墨西哥转型和股东回报,稀释风险为零,真正的风险是现金被闲置。内燃机动力总成的时钟在多年里缩小这块市场,净现金和85%的自有资本比率,则让公司在这期间有能力回报股东、投入新产能。
06.7|资本回报贴着资本成本,解释了为什么净资产只值一半
近五年ROE为3.8%、2.2%、6.8%、5.2%和6.9%,ROIC约6.0%至6.5%,大致在资本成本附近,而不是明显高于。2026年3月期ROE 6.9%略高于汽车零部件行业中位数(约6.1%),PBR却处在行业的低端。操作位置居中,估值位置偏低。
85%的自有资本比率下,闲置现金稀释了ROE,所以价值要靠资本回报和折价收窄,而不是经营复利。两点保留:ROIC是第三方计算,公司自己的资本成本估计没有披露;2026年3月期ROE的提高里,有一部分来自税项和汇兑项目。
07|股东、董事与治理
07.1|大同特殊钢同时是控股股东、材料渠道和管理层来源
大同特殊钢直接持有47.95%的表决权,合计54.25%(2026年3月31日)。公司是集团唯一的发动机气门制造商,2026年3月期向集团贸易公司采购33.20亿日元材料,价格定期协商;12名董事中2名兼任大同特殊钢职务,社长杉江(Sugie Ikuo)1988年进入大同特殊钢,2024年转任公司顾问,2025年6月出任社长。没有来自母公司的贷款或担保。
控制权稳定,控制变动风险低。少数股东真正面对的,是共存的条件:原材料价格和部分利润分配,是少数股东看不到的关联方谈判。大同特殊钢与Daido Kogyo的价格公式没有披露。
07.2|少数股东保护是程序性的,结果看不到
公司是设监查委员会的公司,12名董事中4名为独立外部董事,并设有由独立外部董事担任主席的母子上市公司治理委员会,审查关联交易。保护是程序性的,不是结构性的;委员会的审查结果没有披露,股东沟通或投票记录也没有证据。
所以治理质量要看它产生的定价和资本决策,不能只看董事会构成。改善通常先在分红政策上出现,其次才是董事会。
07.3|流通股比例刚好高于上市维持线,持股意图是最大的变数
自由流通股比例约37.8%(第三方汇编),刚好高于东证 Standard 市场继续上市的门槛。大额回购如果没有母公司配合出售,会进一步压缩流通股,所以资本回报和保持流通比例相互牵制。库存股已占4.3%。具体门槛的算法和库存股的处理,没有独立核对。
大同特殊钢是长期持有、增持还是减持,没有披露。这是整个论点里无法靠公开资料消除的未知,控制着回购节奏、流通股和任何控制权事件。
08|资本政策
08.1|分红和回购在2026年3月期同时转向,但还没到制度化
2026年3月期回购8.35亿日元,含2026年1月通过东证ToSTNeT-3场外立会交易的购买,库存股由78,745股(0.8%)增至446,777股(4.3%);之后部分库存股用于限制性股票薪酬和员工持股会,2026年9月末降到379,355股。分红由52日元到54日元,再计划60日元(预测股息率3.58%)。
分红5.52亿日元加回购8.35亿日元,合计13.87亿日元,约占当前市值的8%,由营业现金流支付。但派息率反而从34.3%降到25.4%,净资产分红率只有约1.7%至1.9%,公司也没有写明派息率、净资产分红率或回购框架。方向对股东友好,节奏却完全由管理层决定。
一年还不能算新的常态,计划中的60日元是预测,不是已宣布的分红。每股口径上,已发行10,279,750股,2027年3月期上半年加权平均9,856,097股。
08.2|墨西哥扩产是唯一的销量增长引擎,回报目标没有披露
墨西哥子公司FUJI OOZX MEXICO(瓜纳华托州)投资1,017.5万美元(约15亿日元),把产能提高到每月230万支气门,2026年8月开工,2027年10月投产,针对北美坚挺的混动需求。在建工程已由5.36亿日元升到12.37亿日元,投产公告发布前就有产能项目在进行。2026年3月期资本开支低于折旧,说明投资在多年的收割之后重新加速。公司称对2027年3月期影响轻微。
同一座工厂既承接增长,又是缴纳关税、如今部分获返还的地方,需求论点和关税论点在这个工厂层面合为一个问题。
项目的目标回报、北美客户的数量承诺、在建工程总规模和服务哪些工厂与产品,都没有披露,所以这笔增长性开支还没法对照资本成本检验。
08.3|计划末期的一批动作指向同一个方向,但这是推断
2026中期经营计划(2024年3月制定,覆盖2025年3月至2027年3月期)的最后两年里,动作集中出现。2024年1月是股票分拆和股东优待制度,2024年7月并入P&M。
2026年1月是首次大额回购,2026年2月决定清算Maruyoshi Manufacturing(2026年9月解散)。2026年4月Jatos吸收合并Tetos,2026年7月宣布墨西哥扩产。
它们的共同方向是聚焦气门核心和北美,培育一个非发动机业务,并开始回馈现金。
把这些动作读成一个收尾计划,是本研究的推断。它是政策转向,还是计划期的集中动作,要看2027年5月的新中期计划。
08.4|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑
营业现金流和无杠杆的资产负债表,让公司可以在回报现金和扩建墨西哥产能之间选择;母公司控制和刚好高于上市门槛的流通股,限制回购能走多远;没有写明的框架,则让管理层不受约束。
如果转向形成复利,折价下的每股资产价值会机械上升;如果现金继续堆积,就不会。2027年5月的新中期计划是否承诺派息率、净资产分红率或回购框架,是论点的第一个有日期的证据。2026中期经营计划最终年度的数字目标本研究没有取得,所以也无法比较上调后的2027年3月期预测与原计划目标。若新计划没有框架而现金继续堆积,论点就变弱。
09|估值与安全边际
09.1|市场为控制权和衰退定价,不是为账面资产定价
2026年11月6日收盘价1,675日元(当日下跌4.23%),总市值172.2亿日元;预测PER 8.9倍,预测每股收益187.70日元;PBR 0.51倍,每股净资产3,254.46日元;2026年3月期ROE 6.9%;预测股息率3.58%;EV/EBITDA 2.3倍,EV 114.2亿日元,EBITDA 49.53亿日元。口径有混用:总市值含库存股,PBR用年末净资产,EV把9月末净现金与全年EBITDA相配,现金口径又不一致,所以倍数只是参考。
折价是这个市场的长期特征。2010年以来PBR一直在0.18倍至0.69倍之间,不会自动回归。净现金约占市值35%,接近资本成本的回报解释了折价为什么与算术不矛盾,母公司控制和较薄的流通股解释其余部分。重估需要证据:持续的资本回报,或流通股、控制权事件,不是便宜。没有分析师一致预期可作对照。
09.2|市场买的是低谷到中间,不是预测高点
2022年3月期至2026年3月期经常利润为17.84亿、10.52亿、19.28亿、23.40亿、27.43亿日元,上调后的2027年3月期预测29.20亿日元,处在这个区间的顶端。按约10亿至29亿日元的正常化区间,172.2亿日元市值对应6至17倍;以19亿日元左右的中间值计,约为9倍。
这个区间是披露的五个年度,不是拟合模型,税率正常化和净增减拆解也没有建模。上半年的利润率是否把区间整体上移,要看到连续两个半年才算。
09.3|下行是长年停滞,不是财务困境
2023年3月期是近五年的低谷,经常利润仍有10.52亿日元,自有资本比率约80%。有了约60亿日元净现金,现实的亏损情景是:多年低个位数ROE,股价长期停在0.3至0.5倍净资产,现金继续积累。电动化加速,或中国工厂减值(可能,但没有量化),会压低销量或增加减记。这个情景来自公司自己的低谷和估值历史,不是压力测试。
资产没有隐含的大幅释放空间:投资有价证券只有1.29亿日元,172.2亿日元市值与335.46亿日元净资产之间的差,靠的是按历史成本入账的土地(账面约34亿日元,评估值没有披露)和现金,不是交叉持股。Maruyoshi的资产出售收益1.01亿日元,是一个很小的变现先例。涉及受控实体资产的变现,会遇到少数股东权益和税收摩擦。资产价值给估值提供下限,但不变现、不投入,就不会复利。
09.4|上调之后股价回吐,市场只为兑现付钱
10月27日上调预测并提高分红后,股价次日在获利回吐中大幅下跌,11月6日收盘1,675日元,比10月末收盘1,870日元低约10%。在0.5倍净资产的位置上,利好被卖出,持股人关心的是下半年的衔接和资本政策,不是2027年3月期的数字。预期现在要求的是兑现,不是公告。
这条证据来自一篇二手市场报道加第三方行情数据,卖方身份无从得知,所以只能当作对市场态度的解读。
10|Kabugami 技术结构
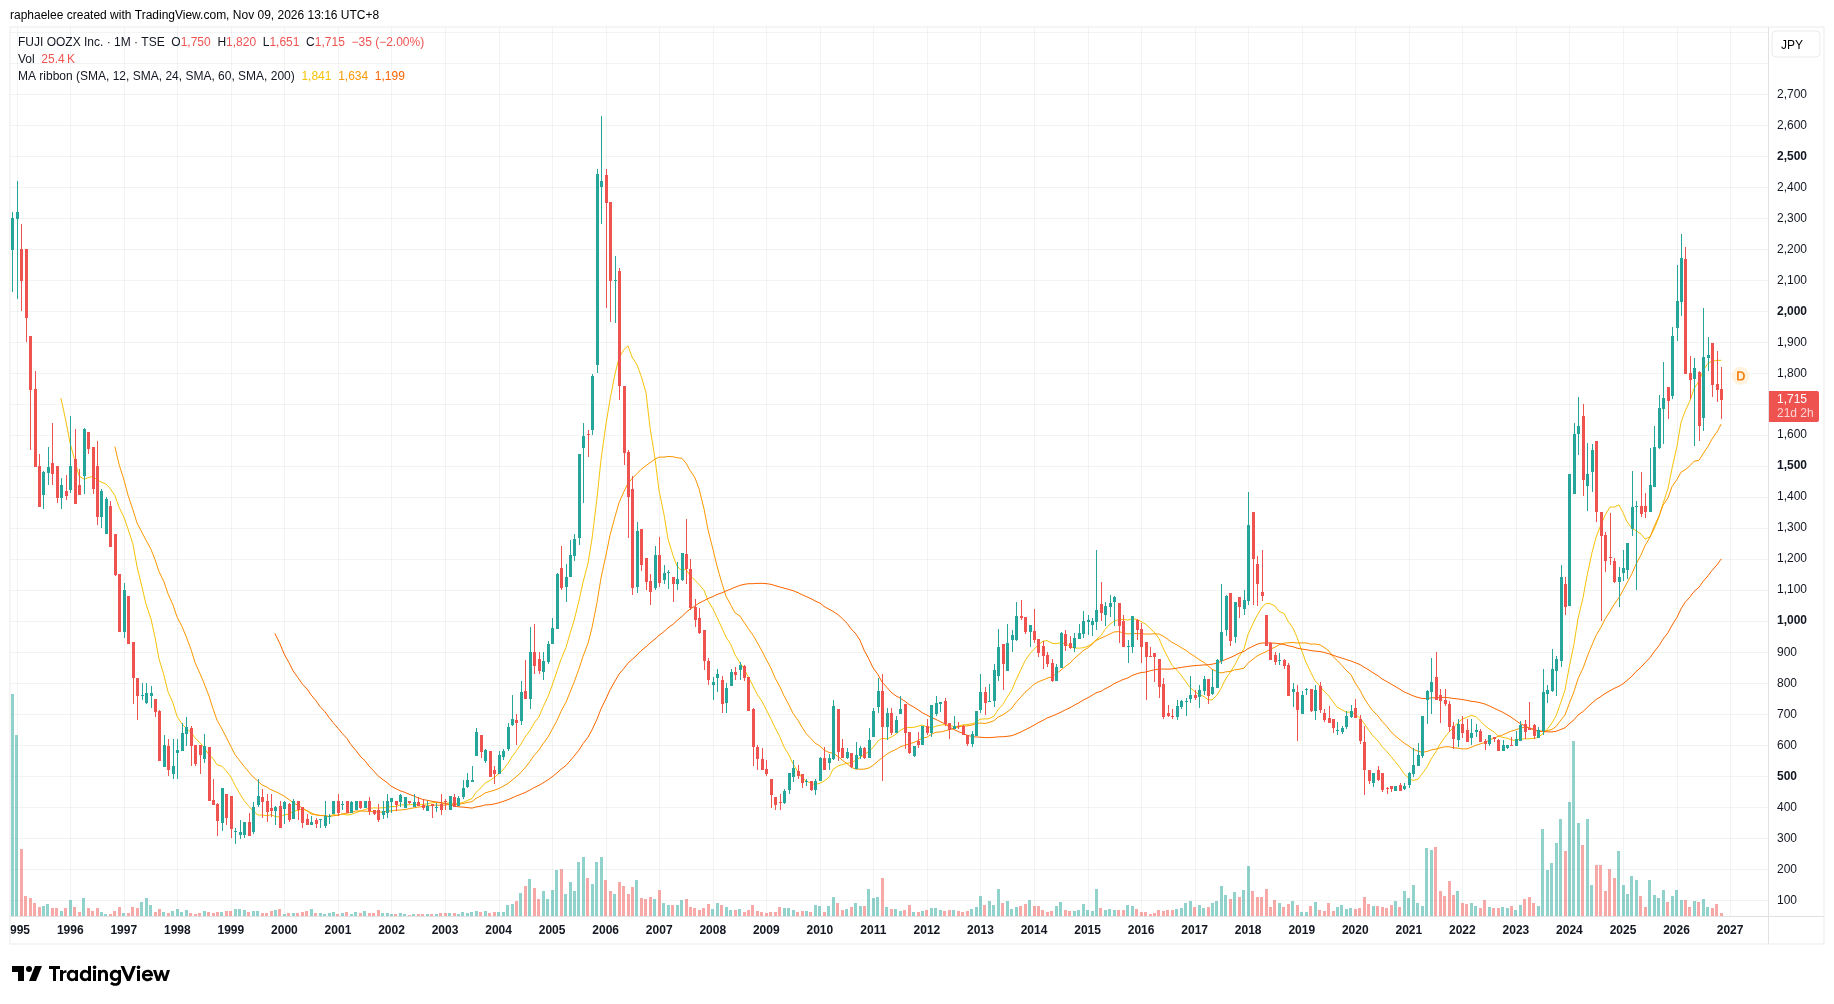
10.1|2,250日元的高点失败之后,问题是整固还是新一轮下跌
价格结构的结论是:长期下跌已经结束,新的上升腿已经建立,但2026年2月对旧高度的第一次检验被拒绝,上行是否被接受尚未确认。
要回答的问题是:2026年2月高点2,250日元,是2005年12月高点2,630日元以来的最高价,却在一个月内失败;此后3月至5月深度回撤到1,565日元,再做近半年的底部。这是上升腿的整固,还是像2015年、2018年高点之后那样多年下跌的第一段?
观察区间是2001年1月至2026年10月共310根月线(拆股调整后的连续序列),外加2026年11月6日日线收盘1,675日元。
10.2|从2005年的2,630日元到2020年的438日元,再到逐级抬高的新结构
2001年至2005年,价格从约384日元涨到2,630日元(2005年12月),那是中国繁荣年代的一代高点。随后是长期下跌:2008年崩塌;2011年至2013年在800至1,230日元之间震荡;2015年高点1,230日元;2018年1月冲高到1,416日元,当年内塌回611日元。每一次反弹都低于上一次,是下降结构的典型特征。
2020年3月洗盘到438日元,比高点低83%,2020年至2022年在438至899日元之间做出低位底部。2023年起性质变了:成交量升到2010年代常态的约5倍,价格涨到1,180日元。
2024年3月冲高到1,722日元,8月经历一次剧烈回撤,低点999日元守住。2025年是台阶式上行,年内低点1,100日元(4月),12月收盘1,919日元。
2026年2月触及2,250日元,3月大幅回落(收盘1,800日元),5月见底1,565日元。此后6月至10月做底,区间1,565至2,009日元,10月收盘1,870日元,11月6日收于1,675日元。
10.3|年度低点连续四年抬高,两次深度回撤都在远高于旧底部的位置止住
这是判断下跌结束的证据:年度低点2023年599日元、2024年999日元、2025年1,100日元、2026年1,565日元,连续四年抬高。2024年和2026年两次深度回撤,都在远高于2020年底部的位置被承接;每一级上升都伴随5至9倍于2010年代的成交量,每一级的低点成了下一级的底板。这也是为什么能说下跌结束了,而不只是被打断。
对比2018年,从1,416日元塌到611日元;2024年的回撤止于999日元,2026年止于1,565日元。每次下跌都在更高位置被止住,是下方承接力增强的表现。上方则没有证据:在2,250日元之上,只有一次尝试,一个月内失败。从2020年的438日元到这次2,250日元的尝试,用了将近六年,回升是逐级的、缓慢的,与绑定发动机项目的周期股相符;2005年的高点仍然是遥远的参照和心理上限,不是近期目标。
价格自2023年以来持续运行在60个月均线上方。1,565至2,250日元这个价格带上一次被占据,是2005至2006年的高点期,几年里只有寥寥几个月,所以停留在这个高度本身就是下一步要被证实或否定的事实。
10.4|上方是失败的记忆,下方是一级级承接位
2026年2月的2,250日元,以及随后3月收盘1,800日元,是目前起支配作用的失败冲击:在月线收盘超过2,250日元之前,这个价位就是买盘能力的已证上限。它的失败相对有秩序,价格落进1,565日元的底部,没有塌向旧平台,这与2015年、2018年开启多年下跌的失败不同。
向下的承接位依次是:2026年5月低点1,565日元;60个月均线约1,183日元;2024年和2025年低点所在的999至1,100日元一带。向上依次是7月高点2,009日元、2月高点2,250日元,再往上只剩2005年的2,630日元。600至1,200日元这个价格带,曾承接2011年至2023年的大多数收盘,是现有结构若完全失败时的深层停留带。
2026年6至10月月线单月振幅收窄到约150至440日元,对比3月下跌时的411日元区间,是一个宽底部内的温和压缩,只支持耐心,不构成时机判断:这个底部可以向任一方向解决,压缩按这只股票自己的历史也还不算紧。近期结构的价格重心在12个月均线1,851日元附近,10月收盘1,870日元几乎正好落在上面;整个上市以来的价格重心则在600至1,200日元的平台。
价格站在近期结构的重心上,却远高于整个生命史的重心:10月收盘位于全区间的67%,11月6日收盘为58%。11月6日1,675日元收在12个月与24个月均线之间,是警戒位置,还不构成结构重置。
10.5|利好被卖出,价格比业绩走得早,也在和业绩等同一份证据
在纯价格结构已经形成之后,再对照公开事件。2026年10月27日,公司公布上半年超预期的业绩、上调全年预测并提高分红。价格的反应是当日冲高,随后在获利回吐中大幅回落,11月6日收盘1,675日元,低于公告前的价位,比10月收盘低约10%。市场认可了上半年的兑现,随即把问题重定价到隐含偏弱的下半年。这与2023年的行为相反:那时价格为承诺付钱,现在只为兑现付钱;2024年8月的剧烈下跌在999日元被买入,这次的利好却被卖出。
时序上,价格先于业绩:2023年的放量突破,比2025年3月期和2026年3月期的业绩高点早了一年多。如今价格与业绩一起在等:2026年的盘整,恰好覆盖了新利润率水平的质量(成本转嫁式上移,还是返还带来的时间差)和隐含的下半年放缓,要由1月和5月的两次业绩来解决。这里的基本面事件只是价格反应的参照,没有改写价格结构的结论。
结构矛盾是高度与盈利质量:价格停在只有高点年代才到过的区间,PBR却只有0.5倍,全周期ROE为2%至7%,最新的利润超预期又部分依赖关税返还和资产出售收益。价格结构说下跌已经结束,新的上升腿存在;而业绩记录还没有给出连续两个半年站在新利润率水平上的证据,来说明这个高度是赚来的。
确认条件有三项:月线收盘站上2,250日元,把失败的冲击转为延续;月线在2027年1月业绩季内守住12个月均线(约1,851日元),底部的重心不变;2027年的年度低点高于1,565日元,把逐年抬高的台阶延长到第五年。失效条件同样明确:月线收盘跌破1,565日元,底部向下破位;月线跌破60个月均线(约1,183日元),价格回到长期停留的价格带;跌穿2024年8月的999日元,则2022年以来的上升腿整体失效。
目前的描述只能是:下跌已结束,上升腿仍在,底部仍在抬高,延续未确认。技术判断的把握一般。
11|风险与催化剂
11.1|最大的结构风险是电动化速度,它决定下降尾部有多长
风险一是动力总成转型。电动车每多一点份额,气门需求就完全消失,中国已在发生。管理层认为电动车普及放缓、混动和碳中和燃料延长发动机寿命,但这是公司框架,没有独立的市场规模序列。真正要看的触发信号,是北美混动需求能否持续抵消中国的下滑,以及公司是否开始量化混动对销量的贡献。
风险二是2027年3月期下半年。隐含的下半年经常利润约12.27亿日元,比上年同期低约23%,说明上半年的利润率不一定是新水平。风险三是中国业务减值,以及关税政策的双向波动;这两项目前都无法量化。
11.2|三个有日期的催化剂,每一个都是用证据回答一个具体问题
2027年1月前后的三季度业绩:在制品增加的4.94亿日元要转成销售,隐含的下半年衔接要接受检验。2027年5月的全年业绩与新中期计划:看有没有资本回报框架。2027年10月墨西哥新产能投产。
这几件事的作用是解决已列出的未知,不是制造动量。接下来两次业绩,每一次都能按它们披露的一次性项目大小,把隐含的全年数字推高或拉低。新中期计划的发布时间是预期,不是公司承诺,其中是否含有资本框架也不知道。
11.3|下半年检验:隐含放缓、在制品增加和一个卖出利好的市场
上调预测证明了上半年兑现,却隐含下半年经常利润比上年同期低约23%;在制品增加等待转化;市场又卖出了这次上调。三者合起来,让2027年1月的业绩成为第一次实质检验,看利润率水平是不是重置。
确认,支持兑现叙事;在制品持续增加或下半年偏弱,则会让利润率读法退回时间差。这个判断来自指引的算术和一篇市场反应报道,关税返还金额也没有量化。
12|反常识发现
全年经常利润预测29.20亿日元,减去已实现的上半年16.93亿日元,隐含下半年经常利润约12.27亿日元。上年同期(2026年3月期全年27.43亿日元减上半年11.51亿日元)是15.92亿日元,所以隐含下半年低约23%;隐含下半年净利润约6.56亿日元。这一水平落在五年经常利润区间的中下部。
所以这次上调证明的是兑现,不是下半年加速。它要么是保守,要么是公司自己也承认上半年的利润率(含关税返还)不是新常态。市场在上调后卖出,与关注这一桥梁一致,不是关注全年数字。这是对公司指引的推算,不是公司披露的下半年计划,关税返还金额未知,所以不能直接下结论。
13|下一次值得跟踪什么
13.1|新中期计划会不会写下资本回报框架
这条最重要,因为它决定资本回报是承诺还是管理层的酌情决定。问题是:2027年5月随全年业绩公布的新中期计划,是否承诺派息率、净资产分红率或回购框架?上调后的2027年3月期预测与2026中期经营计划最终年度的数字目标相比如何,本研究没有取得这些目标。现在净资产分红率只有约1.7%至1.9%,没有框架就没有约束管理层的东西。
若没有框架而现金继续堆积,论点变弱。能解答它的证据,是新中期计划文件和计划目标披露;这是未来披露,目前没有可行的公开路径。
13.2|上半年超预期里,关税返还和资产出售占多少
这决定利润区间是否整体上移。关税返还和Maruyoshi的1.01亿日元资产出售收益,在上半年利润超预期里占多少?中期决算说明没有量化返还金额。答案能分开价格转嫁的水平上移和时间差的噪声。能解答的证据:三季度和年度的特别项目行,或管理层的量化说明;它也可能始终不会单独披露。
13.3|在制品增加的4.94亿日元,三季度是否已转成销售
这是检验「提前生产」与「库存积压」两种读法的第一步。上半年在制品增加4.94亿日元,三季度是转成了下半年销售,还是仍留在存货里?解答的证据是2027年1月前后公布的三季度资产负债表,属于未来披露,也属于下一次研究。
13.4|按动力总成和地区的需求路径,以及中国业务的规模
这两项决定下降尾部是数十年还是几年,也牵涉论点的第三项推翻条件。第一,公司是否按动力总成和地区披露气门需求路径,是否量化过混动销量如何抵消电动车替代?目前只有分地区销售和定性说明,混动在自身销量中的占比没有披露。第二,中国业务的状态和规模如何,是重组还是减值候选?子公司层面的财务数据,除了分部和附注,没有披露。
除了管理层的说明,目前没有找到其他合理的公开来源。
13.5|墨西哥项目的目标回报、客户承诺和在建工程总规模
没有这些,增长性资本开支就没法对照资本成本检验,决定它是创造价值还是摊薄ROIC。问题有两个:1,017.5万美元、月产230万支的项目,目标回报是多少,有什么北美数量承诺?以及12.37亿日元(2026年3月期末)的在建工程总规模多大,服务哪些工厂和产品?公司没有披露目标回报或客户承诺。
13.6|大同特殊钢打算持有、增持还是减持
这是论点中心那个无法消除的未知,决定回购节奏、流通股比例和任何控制权事件。问题是:东证对流通股的要求,是否会逼迫母公司的决定?目前没有披露,也没有合理的公开路径可以现在解决。
13.7|七项待解问题各自限制哪一个判断
这七项问题都受制于未来披露或公司不披露:新中期计划与资本框架限制资本配置判断,关税返还限制利润质量,在制品和下半年限制近期兑现的判断,需求路径限制下降尾部的长度,中国业务限制减值风险,墨西哥回报限制增长资本的检验,母公司意图限制重估路径。其中三季度资产负债表和新中期计划,都发生在本次研究截止日之后,属于下一次研究。
14|Kabugami 评分卡
14.1|综合得分62.56/100,B级,观察并小仓位分批建立
评分版本V3.2,八个模块得分合计62.56/100,对应B级(55至64.9分档)。结论:观察并分批建立小仓位,不追高。核心理由是净现金约占市值三成半、PBR约0.5倍、分红和回购已经起步,下行主要是估值长期停滞,不是财务困境;但回报要靠资本分配兑现,不靠行业增长,因此不宜重仓。后续确认点有三个:2027年1月前后的三季度业绩、2027年5月新中期计划是否给出资本框架、月线能否收在2,250日元之上。证据充分程度把握一般。
14.2|财务、护城河、盈利质量和商业结构四项得分
财务韧性与下行防御 11.05/13:自有资本比率85.3%,短期借款为零,净现金约占市值35%,所有分红、回购和墨西哥扩产都由内部现金流支付;现金口径和母公司可用现金未披露,所以不再上调。
竞争优势与结构耐久性 8.68/14:按发动机项目认证的失效关键部件,让份额和价差在项目期内较稳,更像下行保护,不是上行来源;关键切换假设无法核实,保护范围又随内燃机缩小。
盈利质量、现金转化与资本效率 9.35/17:现金转化好,但上半年利润有关税返还和一次性收益的成分,下半年隐含放缓,ROE与ROIC在资本成本附近;利润质量要连续两个半年验证。
商业结构、产品、客户与关键依赖 5.5/11:收入是发动机产量的派生需求,约96%集中在汽车零部件,客户、项目和动力总成构成都没有披露。
14.3|估值、资本配置和治理三项得分
估值与安全边际 10.8/15:PBR 0.51倍、预测PER 8.9倍、净现金约占市值35%,买入价已经假设中间水平盈利;利好被卖出,说明折价靠兑现才能收窄,且没有一致预期可对照。
资本配置与股东回报 5.8/10:2026年3月期回购与分红合计13.87亿日元,方向友好,但没有写明框架,派息率反而下降;上限受制于承诺缺失和母公司持股意图未知。
治理、所有权与管理层 2.8/7:大同特殊钢兼任控股股东、材料渠道和管理层来源,保护是程序性的,审查结果未披露。折价已在PBR里体现,这里只评价控制结构本身。
14.4|技术结构得分8.58/13:下跌状态明显减弱,新状态尚未完全确立
Kabugami 技术结构 8.58/13:年度低点连续四年抬高,两次深度回撤都在远高于旧底部处止住,但2,250日元的第一次检验失败,近半年底部的方向没有解决,技术可信度中等。对股东来说,这是有限的正向优势,不是确认;价格结构和利润质量问的是同一个问题,答案很可能在2027年1月和5月的业绩前后一起出现。
14.5|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 11.05 | 2026年9月末自有资本比率85.3%,总资产386.73亿日元,负债合计仅51.27亿日元,短期借款为零。2026年3月期净现金约60亿日元,约相当于市值172亿日元的35%。母公司没有贷款或担保,财务风险基本不存在,剩下的只有经营风险和资金如何使用的问题。 |
| 竞争优势与结构耐久性 | 14 | 8.68 | 公司是日本最大的发动机气门厂商,自称国内份额约三成、全球约一成半,份额数据来自二手汇编,未经独立核验。护城河来自按发动机项目逐一认证的失效关键部件、材料和包层工艺。客户为了很小的成本差异去重新认证安全相关零件,意愿很低,所以能守住份额和价差。 |
| 盈利质量、现金转化与资本效率 | 17 | 9.35 | 经营现金转化好,但利润水平的可信度和资本回报都偏弱。2027年3月期上半年营业利润17.31亿日元(增61.8%),销售额只增2.6%,利润弹性来自成本下降和价格转嫁。全年指引上调后,隐含下半年经常利润约12.27亿日元,比上年同期低约23%。ROE近五年在2.2%至6.9%之间,ROIC约6%至6.5%,大致在资本成本附近。 |
| 商业结构、产品、客户与关键依赖 | 11 | 5.5 | 公司只有一个主要业务,汽车零部件约占销售的96%,收入是发动机产量的派生需求。母公司单体销售222.3亿日元,占合并的76%。需求在轮动而不是在增长:日本国内因生产恢复上半年增6.2%,北美因混动需求坚挺而增长,中国因新能源车替代而大幅下滑,合并销售只增2.6%。供应上,2026年3月期向大同特殊钢集团的贸易公司采购了33.2亿日元的原材料,价格定期协商。 |
| 估值与安全边际 | 15 | 10.8 | 以2026年11月6日收盘价1675日元计,市值约172.2亿日元;按上调后的2027年3月期每股收益预测187.70日元,预期PER约8.9倍;以2026年3月期末每股净资产3254.46日元计,PBR约0.51倍;预期股息率3.58%;EV/EBITDA约2.3倍。口径略有混合(市值含库存股、PBR用年末净资产、EV用9月末净现金),倍数是参考值,不是精确值。 |
| 资本配置与股东回报 | 10 | 5.8 | 2026年3月期股东回报出现拐点:回购8.35亿日元,库存股由78,745股(0.8%)增至446,777股(4.3%);分红由52日元到54日元,再到计划60日元。分红和回购合计约13.9亿日元,约占当前市值的8%,由经营现金流支付。但没有明确的派息率、净资产分红率或回购框架,派息率反而从34.3%降到25.4%,净资产分红率只有约1.7%至1.9%。 |
| 治理、所有权与管理层 | 7 | 2.8 | 大同特殊钢直接持有47.95%的表决权,合计54.25%;它同时是控股股东、主要材料渠道和管理层来源。12名董事中2名兼任大同特殊钢职务,社长自2025年6月起出身于大同特殊钢。公司为设监查委员会公司,4名独立董事,设有由独立外部董事担任主席的母子上市治理委员会,负责审查关联交易,但审查结果未披露。 |
| Kabugami 技术结构 | 13 | 8.58 | 月线数据覆盖2001年1月至2026年10月,加上2026年11月6日的日线收盘1675日元。长期下跌已经结束并形成新结构:年度低点连续四年抬高(2023年599日元、2024年999日元、2025年1100日元、2026年1565日元),2024年和2026年两次深度回撤都在远高于旧底部的位置止住。但2026年2月上冲到2250日元(约为2005年高点2630日元的86%)一个月内失败,此后五个月在1565日元到2009日元之间做底。当前价格在12个月均线与24个月均线之间。 |
总分: 62.56 / 100 评级: B 操作建议: 观察并分批建立小仓位,不追高。核心逻辑是净现金约占市值三成半、PBR约0.5倍、分红和回购已经起步,下行主要是估值长期停滞,不是财务困境。但回报要靠资本分配兑现,不靠行业增长,因此不宜重仓。后续确认点有三个:2027年1月前后的三季度业绩(在制品能否转为销售、下半年利润是否真的放缓)、2027年5月新中期计划是否给出派息率、净资产分红率或回购框架,以及月线能否收在2250日元之上。如果新计划没有资本框架而现金继续堆积,或下半年证明上半年利润率只是关税返还和转嫁时间差,或月线跌破1565日元,应重新评估,判断将转向有强资产负债表的价值陷阱。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|数据截止与来源:基本面截至2026年10月27日披露,价格截至2026年11月6日收盘
本报告研究日期为2026年11月9日;股价和估值以2026年11月6日收盘为准。公司披露来自东证 TDnet,包括以下几份。
2026年10月27日的2027年3月期中期决算短信,内容是上半年业绩、预测上调和分红预测。2026年5月13日的2026年3月期决算短信。
2025年10月28日的2026年3月期中期决算短信,作为同比基期。2026年6月17日的控股股东披露,内容是大同特殊钢持股、关联交易和治理。
另有公司官网2026年7月27日的墨西哥子公司产能扩充公告。公司沿革引自2017年6月公布的有价证券报告书。
行情与第三方数据来自以下来源。IRBANK提供披露索引、2026年11月6日行情和PBR历史。
JINGI提供五年财务汇总、ROIC、净现金、行业比较和流通股比例(2026年10月1日)。J-LiC提供董事资料。
维基百科提供公司市场地位(2026年8月30日)。TradingView News/DZH Financial Research提供2026年10月28日的股价反应报道。
月线价格数据来自雅虎财经(2001年1月至2026年10月,数据缺尾部,截至2026年10月27日已接受),外加11月6日的日线收盘。
15.2|证据的限制和免责声明
几项关键数字来自第三方汇编,而不是一手披露:国内约33%和全球约15%的份额、流通股比例约37.8%、ROIC、五年ROE和行业中位数比较,都没有独立核验。市值按已发行股数(含库存股)计算,PBR用年末净资产,EV混用9月末净现金与全年EBITDA,现金定义在来源间不一致,所以估值倍数只作参考。没有分析师一致预期,买卖双方的身份和动机无法观察,股价对上调的反应只依据一篇二手报道和行情数据。
下半年利润、三季度资产负债表、新中期计划和关税返还金额,属于本次研究日期之后才会公布、或公司可能始终不单独披露的信息,已在待解问题中逐项列出,不应当作已经确认或已经排除。
本报告仅作研究交流,不构成投资建议,也不保证任何价格或收益结果;读者应自行判断并承担决策风险。
主要资料来源
- Annual securities report (yuukasyouken houkokusho), company overview and history sections
- FUJI OOZX company profile: market position, plants and subsidiary history
- FY3/26 results release, group composition and segment constitution
- FY3/27 interim results release, product and segment description
- Disclosure concerning the controlling shareholder (Daido Steel), June 2026
- FY3/26 interim (H1) consolidated results release, headline results
- JINGI company page for 7299: five-year ordinary-profit series
- Notice of production capacity expansion at the Mexican subsidiary
- IRBANK disclosure index for FUJI OOZX: corporate-action turning points
- J-LiC officer database for 7299: president's career history from the 98th-term securities report
- IRBANK stock page for 7299: latest daily close, 6 November 2026
- Market report on the share-price reaction to the October 2026 forecast raise
研究发现索引
展开本次 Review 的 70 项研究发现
F001|02|持有的是一个受母公司控制的子公司的少数股权
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|持有的是一个受母公司控制的子公司的少数股权04|竞争位置只有公司自述和二手资料,没有同业对比15|数据截止与来源:基本面截至2026年10月27日披露,价格截至2026年11月6日收盘
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Annual securities report (yuukasyouken houkokusho), company overview and history sections怎么使用:直接证据;一手验证:01;同业比较:01、33;其他用途:历史
FUJI OOZX company profile: market position, plants and subsidiary history怎么使用:直接证据;一手验证:09;反向验证:01;同业比较:03、07、08;其他用途:历史
FY3/26 results release, group composition and segment constitution怎么使用:直接证据;一手验证:01;专项深挖:01
FY3/27 interim results release, product and segment description怎么使用:直接证据;一手验证:03;反向验证:03;专项深挖:03、34
FY3/26 results release, non-consolidated (parent-only) results怎么使用:直接证据;一手验证:02;专项深挖:02
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 历史/同业比较(研究域01) / 历史/同业比较(研究域33)|Annual securities report (yuukasyouken houkokusho), company overview and history sections;直接证据 / 一手证据(研究域09) / 历史/同业比较(研究域03) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 反证(研究域01)|FUJI OOZX company profile: market position, plants and subsidiary history;直接证据 / 一手证据(研究域01) / 定向深挖(研究域01)|FY3/26 results release, group composition and segment constitution;直接证据 / 一手证据(研究域03) / 反证(研究域03) / 定向深挖(研究域03) / 定向深挖(研究域34)|FY3/27 interim results release, product and segment description;直接证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, non-consolidated (parent-only) results
完整研究记录(核对用)
研究原文:FUJI OOZX Inc. (7299, TSE Standard) is Japan's largest engine-valve maker (company-claimed ~33% domestic and ~15% world share). It was founded in 1951, renamed in 1992 and has its head office and main plant in Kikugawa, Shizuoka. It has 10,279,750 shares issued and capital of JPY 3,019 million. It sells intake and exhaust valves, valve seats, cotters and retainers made to engine-maker specifications in Japan, Mexico, China and Indonesia. A small 'other' segment makes semiconductor-line control parts. The investable claim is a minority stake in a Daido Steel-controlled subsidiary whose economics sit mostly in the Japanese parent (76% of sales).
内部研究类型:company_identity_perimeter
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Every later judgment is read through the fact that minorities own a claim on a controlled subsidiary, not on an independent company.
不确定性(原始记录):Share and position figures come from a secondary compilation and are used only for position, not calculation; no independent market-share audit exists.
F002|01|这只股票值不值得买,取决于两件慢事谁先到
研究主题:核心投资问题 · 研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|这只股票值不值得买,取决于两件慢事谁先到
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接证据;同业比较:17、18、19、25;其他用途:历史
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接证据;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FUJI OOZX company profile: market position, plants and subsidiary history怎么使用:直接证据;一手验证:09;反向验证:01;同业比较:03、07、08;其他用途:历史
查看完整证据标签(核对用)
直接证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;直接证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;直接证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026;直接证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 一手证据(研究域09) / 历史/同业比较(研究域03) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 反证(研究域01)|FUJI OOZX company profile: market position, plants and subsidiary history
完整研究记录(核对用)
研究原文:The question completed Research leaves is whether a company whose core product is tied to the combustion engine, but whose near-term demand is extended by the hybrid revival, can turn an 85% equity ratio, ~JPY 6 billion of net cash and a newly progressive dividend-and-buyback policy into durable per-share value before electrification reaches its core product. A second part is what Daido Steel's 54% control means for minorities along the way. After Coverage, the question is better framed as a race between two slow processes: compounding capital return at a deep discount, and the powertrain clock that shrinks the niche.
内部研究类型:core_investment_question
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):It sets what the equity outcome depends on: allocation and delivery, not engine-market growth or solvency.
不确定性(原始记录):Daido Steel's intentions are the irreducible unknown; the successor plan (May 2027) is the first dated evidence.
F003|06|上半年利润大增,全年上调却把压力留给下半年
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论06|上半年利润大增,全年上调却把压力留给下半年
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:35;反向验证:28
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接证据;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FY3/26 interim (H1) consolidated results release, headline results怎么使用:直接证据;一手验证:28;反向验证:35;同业比较:05、12;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 支持证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;直接证据 / 一手证据(研究域35) / 反证(研究域28)|FY3/27 interim results release, segment information;直接证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 一手证据(研究域28) / 历史/同业比较(研究域05) / 历史/同业比较(研究域12) / 反证(研究域35)|FY3/26 interim (H1) consolidated results release, headline results
完整研究记录(核对用)
研究原文:H1 FY3/27 (to 30 Sep 2026) delivered a beat: sales JPY 14,542m (+2.6%), operating profit JPY 1,731m (+61.8%), ordinary profit JPY 1,693m (+47.1%), net income JPY 1,194m (+22.0%). On 27 Oct 2026 the FY3/27 forecast was raised to sales JPY 29,200m, operating and ordinary profit JPY 2,920m and net income JPY 1,850m (from JPY 2,600m / 2,600m / 1,700m). The dividend forecast was raised to JPY 60 from 54. Profit leverage came from cost reduction and price pass-through on near-flat sales. Net income also includes a JPY 101m asset-sale gain and the profit line includes an unquantified tariff refund.
内部研究类型:current_change_finding
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Proves first-half delivery and raises the cash return, but the pass-through reset is only one half old.
不确定性(原始记录):The refund and asset-sale gain are not quantified in the release, so the clean run-rate cannot be isolated.
F004|12|上调预测证明了上半年兑现,却暗示下半年更弱
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 interim (H1) consolidated results release, headline results怎么使用:直接 / 支持;一手验证:28;反向验证:35;同业比较:05、12;其他用途:历史
FY3/26 full-year consolidated results release, headline results怎么使用:直接证据;同业比较:32、35;其他用途:历史
JINGI company page for 7299: five-year ordinary-profit series怎么使用:直接证据;一手验证:28;外部现实校验:15;专项深挖:28
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域05) / 历史/同业比较(研究域12) / 反证(研究域35)|FY3/26 interim (H1) consolidated results release, headline results;直接证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 历史/同业比较(研究域32) / 历史/同业比较(研究域35)|FY3/26 full-year consolidated results release, headline results;直接证据 / 一手证据(研究域28) / 外部现实(研究域15) / 定向深挖(研究域28)|JINGI company page for 7299: five-year ordinary-profit series
完整研究记录(核对用)
研究原文:The raised forecast is first-half loaded. Full-year ordinary profit JPY 2,920m less H1 JPY 1,693m implies H2 ordinary profit of about JPY 1,227m, roughly 23% below H2 FY3/26 (JPY 2,743m less 1,151m = JPY 1,592m). Implied H2 net income is about JPY 656m. The revision therefore proves delivery rather than a second-half acceleration, and the implied H2 level sits near the lower-middle of the five-year ordinary-profit band. It is either conservatism or an admission that the H1 margin level (including the tariff refund) is not the new run-rate.
内部研究类型:implied_expectation_gap
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The market's focus has moved to this bridge, not the full-year number.
不确定性(原始记录):A derived inference from company guidance, not a disclosed H2 plan; the tariff refund size is unknown.
F005|06|上一年是销量创纪录,价差却没跟上
研究范围:开放研究+35项覆盖检查
写入正文:06|上一年是销量创纪录,价差却没跟上
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 full-year consolidated results release, headline results怎么使用:直接 / 支持;同业比较:32、35;其他用途:历史
FY3/26 full-year results release, qualitative review of operations怎么使用:直接 / 支持;一手验证:32;同业比较:06、13、14、16;其他用途:历史
FY3/26 results release, domestic and overseas sales split怎么使用:直接证据;一手验证:02、15;专项深挖:02、15、35
FY3/26 results release, composition of sales growth怎么使用:直接证据;一手验证:15;反向验证:02、15;专项深挖:15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域32) / 历史/同业比较(研究域35)|FY3/26 full-year consolidated results release, headline results;直接证据|FY3/26 full-year results release, segment information;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域06) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16)|FY3/26 full-year results release, qualitative review of operations;直接证据 / 一手证据(研究域02) / 一手证据(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域15) / 定向深挖(研究域35)|FY3/26 results release, domestic and overseas sales split;直接证据 / 一手证据(研究域15) / 反证(研究域02) / 反证(研究域15) / 定向深挖(研究域15)|FY3/26 results release, composition of sales growth
完整研究记录(核对用)
研究原文:FY3/26 was volume without spread. Sales rose 13.9% to a record JPY 29,093m (domestic +8.6% including the P&M consolidation; overseas +25.9%) but operating profit fell 4.2% to JPY 2,506m and automobile-parts segment profit fell 9.7%. Volume-response costs, tariffs, labour and materials outran price pass-through. Ordinary profit rose 17.2% to JPY 2,743m only with the help of a JPY 220m FX gain.
内部研究类型:historical_mechanism_finding
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Shows the operating-leverage downside: record sales did not create profit when costs led prices.
不确定性(原始记录):The release does not split FY3/26 growth into volume, price and P&M consolidation.
F006|06|看经常利润,别看净利润
研究范围:开放研究+35项覆盖检查
写入正文:06|看经常利润,别看净利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 full-year results release, qualitative review of operations怎么使用:直接 / 支持;一手验证:32;同业比较:06、13、14、16;其他用途:历史
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接 / 支持;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FY3/26 results release, catalogue of non-recurring items怎么使用:直接 / 支持;一手验证:32;外部现实校验:16;反向验证:32;专项深挖:32
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:直接证据;反向验证:29;同业比较:20、21、24;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域06) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16)|FY3/26 full-year results release, qualitative review of operations;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域16) / 反证(研究域32) / 定向深挖(研究域32)|FY3/26 results release, catalogue of non-recurring items;直接证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026
完整研究记录(核对用)
研究原文:Ordinary profit, not net income, is the recurring anchor. FY3/26 net income (+38.6% to JPY 2,144m) was lifted by a Mexican deferred-tax credit from revaluing deferred tax assets, JPY 152m of insurance proceeds against a JPY 94m impairment, and the JPY 220m FX gain below the operating line, while operating profit fell 4.2%. H1 FY3/27 net income carries a JPY 101m Maruyoshi asset-sale gain and the tariff refund. One-off density is a recurring property of this register, so quality adjustment is standing procedure. Capitalising reported net income overpays in good-print years.
内部研究类型:earnings_quality_adjustment
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Prevents using flattered or depressed net income as the valuation base.
不确定性(原始记录):Deferred-tax credit size and tariff-refund amount are not separately disclosed; the deferred-tax asset is not cash and its usability is unproven.
F007|06|几乎没有杠杆,但净现金口径要带着保留看
研究范围:开放研究+35项覆盖检查
写入正文:06|几乎没有杠杆,但净现金口径要带着保留看14|财务、护城河、盈利质量和商业结构四项得分
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接 / 支持;外部现实校验:17、18
FY3/27 interim results release, liabilities and equity structure怎么使用:直接 / 支持;一手验证:18、25;反向验证:18;专项深挖:18
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:直接证据;反向验证:29;同业比较:20、21、24;其他用途:历史
FY3/26 results release, non-operating asset balances怎么使用:直接证据;一手验证:21;反向验证:21;专项深挖:21
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接证据;同业比较:17、18、19、25;其他用途:历史
FY3/26 results release, working-capital balances怎么使用:支持证据;一手验证:19;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|FY3/27 interim results release, liabilities and equity structure;直接证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026;直接证据 / 一手证据(研究域21) / 反证(研究域21) / 定向深挖(研究域21)|FY3/26 results release, non-operating asset balances;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/26 results release, working-capital balances
完整研究记录(核对用)
研究原文:The balance sheet is a fortress. At 30 Sep 2026 the equity ratio was 85.3% on total assets of JPY 38,673m, net assets were JPY 33,546m, total liabilities only JPY 5,127m and short-term borrowings zero. FY3/26 net cash was about JPY 6.0bn (cash JPY 6,507m against debt JPY 473m), roughly 35% of the JPY 17.2bn market capitalisation. Liabilities are mostly trade payables and electronic obligations, so financial leverage is effectively absent. Land of about JPY 3.4bn is carried at historical cost. All residual risk is operating and allocative.
内部研究类型:balance_sheet_resilience
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Removes the distress scenario and replaces it with an opportunity-cost question about idle cash.
不确定性(原始记录):Cash measures differ across sources (cash and equivalents JPY 7,429m vs cash and deposits JPY 5,801m at 30 Sep 2026), so the net-cash figure depends on definition; parent-available versus subsidiary cash is not separately disclosed.
F008|08|分红和回购在2026年3月期同时转向,但还没到制度化
研究范围:开放研究+35项覆盖检查
写入正文:08|分红和回购在2026年3月期同时转向,但还没到制度化14|估值、资本配置和治理三项得分
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接 / 支持;同业比较:17、18、19、25;其他用途:历史
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:直接 / 支持;反向验证:29;同业比较:20、21、24;其他用途:历史
FY3/26 full-year results release, dividends and initial FY3/27 forecast怎么使用:直接证据;一手验证:26、35;同业比较:26;其他用途:历史
FY3/26 results release, treasury-share purchases and disposals怎么使用:直接证据;一手验证:25;专项深挖:24、25
FY3/26 results release, dividend record and payout ratios怎么使用:直接 / 支持;一手验证:26;反向验证:25、26;专项深挖:26、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;直接证据 / 支持证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026;直接证据 / 一手证据(研究域26) / 一手证据(研究域35) / 历史/同业比较(研究域26)|FY3/26 full-year results release, dividends and initial FY3/27 forecast;直接证据 / 一手证据(研究域25) / 定向深挖(研究域24) / 定向深挖(研究域25)|FY3/26 results release, treasury-share purchases and disposals;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域25) / 反证(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域35)|FY3/26 results release, dividend record and payout ratios;直接证据|FY3/27 interim results release, share counts
完整研究记录(核对用)
研究原文:Capital return inflected in FY3/26. JPY 835m of buybacks (including the January 2026 ToSTNeT-3 purchase) took treasury shares from 78,745 (0.8%) to 446,777 (4.3%). Treasury shares were partly recycled to 379,355 for restricted-stock compensation and the employee shareholding association. Dividends moved JPY 52 - 54 - 60 planned (3.58% forecast yield). The payout ratio nonetheless fell from 34.3% to 25.4% as earnings rose, dividend-on-equity is only about 1.7-1.9%, and no payout, DOE or buyback framework is stated. FY3/26 returns of about JPY 1.39bn were roughly 8% of current market value and were funded from operating cash flow.
内部研究类型:capital_allocation_inflection
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The direction is shareholder-friendly, but with no commitment device the pace is discretionary and the cash pile still grows.
不确定性(原始记录):One year is not yet a regime; the planned JPY 60 dividend is a forecast, not a declaration.
F009|08|墨西哥扩产是唯一的销量增长引擎,回报目标没有披露
研究范围:开放研究+35项覆盖检查
写入正文:08|墨西哥扩产是唯一的销量增长引擎,回报目标没有披露
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接 / 支持;一手验证:20
FY3/27 interim results release, regional demand review怎么使用:直接证据;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/26 results release, capital expenditure and construction in progress怎么使用:直接证据;一手验证:20;反向验证:20;专项深挖:20
FY3/27 interim results release, consolidated cash flow statement怎么使用:直接证据;一手验证:17;外部现实校验:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 一手证据(研究域20) / 反证(研究域20) / 定向深挖(研究域20)|FY3/26 results release, capital expenditure and construction in progress;直接证据 / 一手证据(研究域17) / 外部现实(研究域19)|FY3/27 interim results release, consolidated cash flow statement
完整研究记录(核对用)
研究原文:The growth bet is geographic, not product. The Mexican subsidiary (FUJI OOZX MEXICO, Guanajuato) is investing US$10.175m (about JPY 1.5bn) to lift capacity to 2.3 million valves per month. Construction started in August 2026 and operations are scheduled for October 2027, aimed at firm North American hybrid demand. Construction in progress had already jumped from JPY 536m to JPY 1,237m at FY3/26, and capex (JPY 2,094m) ran below depreciation (JPY 2,447m), so investment is re-accelerating after years of harvesting. The same plant complex paid the tariffs now partly refunded. Expect a J-curve: capex trims FCF before it adds profit.
内部研究类型:growth_capex_bet
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The only volume-growth engine; its return decides whether capital deployment beats returning cash.
不确定性(原始记录):Target return, customer volume commitments and total CIP programme size are undisclosed; effect on FY3/27 is described as minor.
F010|02|半导体控制部件只占销售约4%,是期权,不是驱动
研究范围:开放研究+35项覆盖检查
写入正文:02|半导体控制部件只占销售约4%,是期权,不是驱动
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:35;反向验证:28
FY3/26 results release, medium-term plan themes on new-business development怎么使用:直接证据;一手验证:07;专项深挖:07
IRBANK disclosure index for FUJI OOZX: corporate-action turning points怎么使用:直接证据;一手验证:33;外部现实校验:07、20;反向验证:33;专项深挖:07、33;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域28)|FY3/27 interim results release, segment information;直接证据|FY3/26 full-year results release, segment information;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|FY3/26 results release, medium-term plan themes on new-business development;直接证据 / 一手证据(研究域33) / 外部现实(研究域07) / 外部现实(研究域20) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域33)|IRBANK disclosure index for FUJI OOZX: corporate-action turning points
完整研究记录(核对用)
研究原文:The only non-engine growth leg is small but real. The 'other' segment (semiconductor-line automatic-control parts, with P&M consolidated from July 2024) grew sales 36.1% in FY3/26 to JPY 1,146m, moving from a JPY 120m loss to JPY 34m profit. In H1 FY3/27 sales rose 42.0% to JPY 772m and profit rose from JPY 6m to JPY 91m. At about 4% of sales it is an option, not a driver.
内部研究类型:diversification_option
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A non-engine profit leg of real size would rewrite the earnings band and the post-engine narrative, but it is not yet large enough.
不确定性(原始记录):P&M's standalone earnings and purchase price are undisclosed; the segment may include acquisition effects.
F011|07|大同特殊钢同时是控股股东、材料渠道和管理层来源
研究范围:开放研究+35项覆盖检查
写入正文:07|大同特殊钢同时是控股股东、材料渠道和管理层来源
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Disclosure concerning the controlling shareholder (Daido Steel), June 2026怎么使用:直接 / 支持;一手验证:24
Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance怎么使用:直接证据;一手验证:06、23;外部现实校验:23
J-LiC officer database for 7299: president's career history from the 98th-term securities report怎么使用:直接证据;同业比较:23;其他用途:历史
Controlling-shareholder disclosure: raw-material procurement through the Daido group怎么使用:直接 / 支持;一手验证:06;反向验证:06;专项深挖:06、23
J-LiC officer database for 7299: board composition and president's background怎么使用:直接证据;一手验证:23;反向验证:23;专项深挖:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026;直接证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域23)|Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance;直接证据 / 历史/同业比较(研究域23)|J-LiC officer database for 7299: president's career history from the 98th-term securities report;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域06) / 定向深挖(研究域06) / 定向深挖(研究域23)|Controlling-shareholder disclosure: raw-material procurement through the Daido group;直接证据 / 一手证据(研究域23) / 反证(研究域23) / 定向深挖(研究域23)|J-LiC officer database for 7299: board composition and president's background
完整研究记录(核对用)
研究原文:Control and supply both run through Daido Steel. It holds 47.95% of voting rights directly and 54.25% combined (31 Mar 2026). Fuji Oozex is the group's only engine-valve manufacturer. It bought JPY 3,320m of valve steel, die steel, cladding materials and processed parts in FY3/26 from Daido Kogyo, the group's trading arm, with prices negotiated periodically on overall cost and market prices (payables JPY 345m plus electronic obligations JPY 1,125m at year-end). Two of twelve directors hold concurrent Daido posts and the president has been a Daido career executive since June 2025. There are no loans or guarantees from the parent.
内部研究类型:control_and_supply_dependency
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The parent is simultaneously controller, principal materials channel and management source, so margin and capital policy are partly set in a related-party negotiation minorities cannot observe.
不确定性(原始记录):The pricing formula with Daido Kogyo and the parent's long-term holding intention are undisclosed.
F012|07|少数股东保护是程序性的,结果看不到
研究范围:35项覆盖检查
写入正文:07|少数股东保护是程序性的,结果看不到14|估值、资本配置和治理三项得分
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance怎么使用:直接 / 支持;一手验证:06、23;外部现实校验:23
J-LiC officer database for 7299: board composition and president's background怎么使用:直接 / 支持;一手验证:23;反向验证:23;专项深挖:23
J-LiC officer database for 7299: president's career history from the 98th-term securities report怎么使用:直接证据;同业比较:23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域23)|Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance;直接证据 / 支持证据 / 一手证据(研究域23) / 反证(研究域23) / 定向深挖(研究域23)|J-LiC officer database for 7299: board composition and president's background;直接证据 / 历史/同业比较(研究域23)|J-LiC officer database for 7299: president's career history from the 98th-term securities report
完整研究记录(核对用)
研究原文:Governance is parent-led with formal minority protections: a company-with-audit-committee structure, twelve directors of whom four are independent outsiders, and a governance committee for parent-subsidiary listed companies chaired by an independent outside director that reviews related-party transactions. Protection is procedural, not structural; the committee's review outcomes are not disclosed. Improvement would show in payout policy before board composition.
内部研究类型:governance_mechanism
内部来源标记:COVERAGE35
普通股东含义(原始记录):Governance quality is the discount; judge it by the pricing and capital decisions it produces.
不确定性(原始记录):Committee outcomes and any engagement or voting evidence are not in the evidence set.
F013|09|市场为控制权和衰退定价,不是为账面资产定价
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论09|市场为控制权和衰退定价,不是为账面资产定价15|数据截止与来源:基本面截至2026年10月27日披露,价格截至2026年11月6日收盘15|证据的限制和免责声明
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
IRBANK stock page for 7299: latest daily close, 6 November 2026怎么使用:直接 / 支持;一手验证:31;外部现实校验:34、35
FY3/26 full-year consolidated results release, headline results怎么使用:直接 / 支持;同业比较:32、35;其他用途:历史
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接 / 支持;同业比较:17、18、19、25;其他用途:历史
FY3/26 full-year results release, dividends and initial FY3/27 forecast怎么使用:直接 / 支持;一手验证:26、35;同业比较:26;其他用途:历史
IRBANK stock page for 7299: price, market capitalisation and valuation snapshot怎么使用:直接证据;一手验证:27;外部现实校验:01、24、31
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域34) / 外部现实(研究域35)|IRBANK stock page for 7299: latest daily close, 6 November 2026;直接证据 / 支持证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;直接证据 / 支持证据 / 历史/同业比较(研究域32) / 历史/同业比较(研究域35)|FY3/26 full-year consolidated results release, headline results;直接证据 / 支持证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;直接证据 / 支持证据 / 一手证据(研究域26) / 一手证据(研究域35) / 历史/同业比较(研究域26)|FY3/26 full-year results release, dividends and initial FY3/27 forecast;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|IRBANK stock page for 7299: price, market capitalisation and valuation snapshot
完整研究记录(核对用)
研究原文:Valuation at the 6 Nov 2026 close (research cut-off 9 Nov 2026): price JPY 1,675 (-4.23% on the day); market capitalisation JPY 17.22bn (JPY 1,675 x 10,279,750 issued shares); forecast PER 8.9x on revised FY3/27 forecast EPS JPY 187.70; actual PBR 0.51x on FY3/26-end net assets per share JPY 3,254.46; FY3/26 reported ROE 6.9%; forecast dividend yield 3.58% on the JPY 60 forecast dividend; EV/EBITDA 2.3x (EV JPY 11.42bn after net cash JPY 5.80bn at 30 Sep 2026; EBITDA JPY 4.95bn = FY3/26 operating profit JPY 2,506m + depreciation JPY 2,447m).
内部研究类型:valuation_snapshot
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Reference multiples for the discount-versus-delivery debate.
不确定性(原始记录):Mixed bases: market cap uses issued shares including 379,355 treasury shares; PBR uses year-end rather than September book; EV combines a Sept net-cash measure with FY3/26 actual EBITDA; cash definitions differ. The multiples are indicative, not precise.
F014|09|市场为控制权和衰退定价,不是为账面资产定价
研究范围:开放研究+35项覆盖检查
写入正文:09|市场为控制权和衰退定价,不是为账面资产定价14|估值、资本配置和治理三项得分
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
IRBANK stock page for 7299: price, market capitalisation and valuation snapshot怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
IRBANK stock page for 7299: fiscal-year high/low prices and PBR history怎么使用:直接 / 支持;外部现实校验:27、29;同业比较:27、31;其他用途:历史
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接 / 支持;外部现实校验:17、18
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:直接证据;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
JINGI company page for 7299: ROE and ROIC history怎么使用:直接证据;一手验证:22;反向验证:09、22;专项深挖:22
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|IRBANK stock page for 7299: price, market capitalisation and valuation snapshot;直接证据 / 支持证据 / 外部现实(研究域27) / 外部现实(研究域29) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|IRBANK stock page for 7299: fiscal-year high/low prices and PBR history;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels;直接证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield;直接证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域22) / 定向深挖(研究域22)|JINGI company page for 7299: ROE and ROIC history
完整研究记录(核对用)
研究原文:At 0.5x book and under 9x raised-forecast earnings, the market prices the Daido-controlled thin float and the combustion-engine decline, not the balance sheet. PBR has stayed between 0.18x and 0.69x every year since 2010, so the discount is a structural feature of the register rather than a dislocation that will mean-revert unaided. Net cash is about 35% of market value, and returns near the cost of capital explain why the discount does not contradict arithmetic. Re-rating needs evidence: compounding capital return or a float/control event, not cheapness.
内部研究类型:valuation_interpretation
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Defines what must change for the discount to narrow.
不确定性(原始记录):No analyst consensus is in the evidence set to compare against.
F015|02|收入是发动机产量的派生需求,利润是价格与成本的差
研究主题:商业模式 · 研究范围:开放研究+35项覆盖检查
写入正文:02|收入是发动机产量的派生需求,利润是价格与成本的差
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
FY3/26 results release, group composition and segment constitution怎么使用:直接 / 支持;一手验证:01;专项深挖:01
FY3/26 results release, non-consolidated (parent-only) results怎么使用:直接 / 支持;一手验证:02;专项深挖:02
FY3/26 results release, domestic and overseas sales split怎么使用:直接 / 支持;一手验证:02、15;专项深挖:02、15、35
FY3/27 interim results release, segment information怎么使用:直接 / 支持;一手验证:35;反向验证:28
FY3/27 interim results release, product and segment description怎么使用:直接证据;一手验证:03;反向验证:03;专项深挖:03、34
FY3/27 interim results release, segment profit inflection怎么使用:直接证据;一手验证:16;专项深挖:16
Controlling-shareholder disclosure: raw-material procurement through the Daido group怎么使用:支持证据;一手验证:06;反向验证:06;专项深挖:06、23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 定向深挖(研究域01)|FY3/26 results release, group composition and segment constitution;直接证据 / 支持证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, non-consolidated (parent-only) results;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域15) / 定向深挖(研究域35)|FY3/26 results release, domestic and overseas sales split;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域28)|FY3/27 interim results release, segment information;直接证据 / 一手证据(研究域03) / 反证(研究域03) / 定向深挖(研究域03) / 定向深挖(研究域34)|FY3/27 interim results release, product and segment description;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, segment profit inflection;支持证据|FY3/26 full-year results release, segment information;支持证据 / 一手证据(研究域06) / 反证(研究域06) / 定向深挖(研究域06) / 定向深挖(研究域23)|Controlling-shareholder disclosure: raw-material procurement through the Daido group
完整研究记录(核对用)
研究原文:The group has one operating segment, automobile parts (~96% of sales), plus 'other'. Parent-only sales of JPY 22,230m are 76% of the consolidated total, so the economics are those of a Japanese parent with an overseas production perimeter. Revenue is a derivative of engine build schedules: a fixed valve content per engine sold into negotiated model programmes at thin margins. The consolidated margin is therefore a direct read on valve pricing power, with no second engine to mask a failed pass-through. Operating leverage is high both ways.
内部研究类型:business_model
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Shareholders own a volume derivative; sales records do not guarantee profit records.
不确定性(原始记录):No customer or programme split and no volume/price/consolidation decomposition of revenue.
F016|03|需求在三个方向轮动,合并增速只剩低个位数
研究范围:开放研究+35项覆盖检查
写入正文:03|需求在三个方向轮动,合并增速只剩低个位数14|财务、护城河、盈利质量和商业结构四项得分
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接 / 支持;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FY3/27 interim results release, regional demand review怎么使用:直接 / 支持;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
FY3/27 interim results release, industry conditions in the interim period怎么使用:直接 / 支持;一手验证:12;外部现实校验:05、14;反向验证:12;专项深挖:05、12
FY3/26 results release, composition of sales growth怎么使用:直接证据;一手验证:15;反向验证:02、15;专项深挖:15
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域05) / 外部现实(研究域14) / 反证(研究域12) / 定向深挖(研究域05) / 定向深挖(研究域12)|FY3/27 interim results release, industry conditions in the interim period;直接证据 / 一手证据(研究域15) / 反证(研究域02) / 反证(研究域15) / 定向深挖(研究域15)|FY3/26 results release, composition of sales growth
完整研究记录(核对用)
研究原文:Demand is rotating rather than growing. Domestic sales rose 6.2% in H1 on Japanese production recovery and equipment demand, North America grew on firm hybrid demand and new orders, and China fell sharply as new-energy vehicles displaced gasoline cars, so overseas sales fell 4.1% and consolidated sales grew only 2.6% despite strong profit leverage. Three unrelated powertrain stories net into one growth rate, and revenue quality increasingly depends on one region's hybrid cycle.
内部研究类型:demand_structure
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Consolidated growth stays low-single-digit in good years unless North America accelerates; volume is not the equity story.
不确定性(原始记录):Customer names, hybrid share of own valve volumes and demand by powertrain are undisclosed.
F017|05|内燃机依赖决定护城河的有效期,下降路径可能更长更平
研究范围:开放研究+35项覆盖检查
写入正文:05|内燃机依赖决定护城河的有效期,下降路径可能更长更平11|最大的结构风险是电动化速度,它决定下降尾部有多长
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接 / 支持;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FUJI OOZX company profile: market position, plants and subsidiary history怎么使用:直接 / 支持;一手验证:09;反向验证:01;同业比较:03、07、08;其他用途:历史
FY3/26 results release, industry outlook in the forecast assumptions怎么使用:直接证据;一手验证:11;反向验证:11;专项深挖:11
FY3/27 interim results release, regional demand review怎么使用:直接证据;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 支持证据 / 一手证据(研究域09) / 历史/同业比较(研究域03) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 反证(研究域01)|FUJI OOZX company profile: market position, plants and subsidiary history;直接证据 / 一手证据(研究域11) / 反证(研究域11) / 定向深挖(研究域11)|FY3/26 results release, industry outlook in the forecast assumptions;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review
完整研究记录(核对用)
研究原文:The core product is bound to internal-combustion engines. Every point of battery-electric mix gain removes engine-valve demand entirely, and China, historically a growth market for the group, is already shrinking for exactly this reason. Management's outlook says BEV adoption is slowing in major markets while hybrid/PHEV demand rises and carbon-neutral fuels extend engine life, so the decline path looks longer and flatter than earlier scenarios. The range between a hybrid-extended decline measured in decades and a fast-BEV decline in years is the risk.
内部研究类型:structural_risk
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Sets the terminal-value ceiling: valuation should capitalise a long tail, neither a cliff nor growth.
不确定性(原始记录):Management's outlook is company framing; no independent market-size series was pulled and BEV adoption pace is exogenous.
F018|04|竞争位置只有公司自述和二手资料,没有同业对比
研究范围:开放研究+35项覆盖检查
写入正文:04|竞争位置只有公司自述和二手资料,没有同业对比05|护城河守住的是现有项目的份额和价差14|财务、护城河、盈利质量和商业结构四项得分
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 results release, medium-term plan themes and research expense怎么使用:直接 / 支持;一手验证:04、10;反向验证:04;专项深挖:04、10
FUJI OOZX company profile: competitive position of Japanese engine-valve makers怎么使用:直接 / 支持;一手验证:08、10;外部现实校验:03、04;反向验证:08、10;专项深挖:08、10
JINGI company page for 7299: industry comparison panel (EDINET database)怎么使用:直接 / 支持;一手验证:09;外部现实校验:10、22;专项深挖:09
FUJI OOZX company profile: market position, plants and subsidiary history怎么使用:直接证据;一手验证:09;反向验证:01;同业比较:03、07、08;其他用途:历史
FY3/26 results release, the 2026 medium-term management plan's three themes怎么使用:直接证据;一手验证:33;专项深挖:04、33;同业比较:04、10;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 反证(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域10)|FY3/26 results release, medium-term plan themes and research expense;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域10) / 外部现实(研究域03) / 外部现实(研究域04) / 反证(研究域08) / 反证(研究域10) / 定向深挖(研究域08) / 定向深挖(研究域10)|FUJI OOZX company profile: competitive position of Japanese engine-valve makers;直接证据 / 支持证据 / 一手证据(研究域09) / 外部现实(研究域10) / 外部现实(研究域22) / 定向深挖(研究域09)|JINGI company page for 7299: industry comparison panel (EDINET database);直接证据 / 一手证据(研究域09) / 历史/同业比较(研究域03) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 反证(研究域01)|FUJI OOZX company profile: market position, plants and subsidiary history;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域33)|FY3/26 results release, the 2026 medium-term management plan's three themes
完整研究记录(核对用)
研究原文:The moat is qualification and process depth, not brand or patents visible in the accounts. Valves are failure-critical, specification-bound parts qualified per engine programme, made with materials and cladding know-how (sodium-filled hollow valves, carbon-neutral-fuel-compatible and high-function designs), so R&D expense is small. Switching means requalifying a safety-relevant part for negligible cost saving, and the niche is too small and specification-bound to invite entry. The moat defends share and spread for the life of an engine programme, is re-contested at each new programme, and has no content in BEV programmes.
内部研究类型:moat_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Supports the downside case (share retention) more than the upside case.
不确定性(原始记录):No contract terms, programme win/loss rates, patent data or hollow-valve price premium disclosed; competitor benchmarking was not pulled; the moat reading is structural inference.
F019|06|上一年是销量创纪录,价差却没跟上
研究范围:开放研究+35项覆盖检查
写入正文:06|上一年是销量创纪录,价差却没跟上14|财务、护城河、盈利质量和商业结构四项得分
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/27 interim results release, gross margin bridge怎么使用:直接 / 支持;一手验证:16;专项深挖:16
FY3/27 interim results release, segment profit inflection怎么使用:直接 / 支持;一手验证:16;专项深挖:16
Controlling-shareholder disclosure: raw-material procurement through the Daido group怎么使用:直接证据;一手验证:06;反向验证:06;专项深挖:06、23
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/26 full-year results release, qualitative review of operations怎么使用:直接证据;一手验证:32;同业比较:06、13、14、16;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, gross margin bridge;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, segment profit inflection;直接证据 / 一手证据(研究域06) / 反证(研究域06) / 定向深挖(研究域06) / 定向深挖(研究域23)|Controlling-shareholder disclosure: raw-material procurement through the Daido group;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域06) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16)|FY3/26 full-year results release, qualitative review of operations
完整研究记录(核对用)
研究原文:Margin equals negotiated prices minus steel, wage and tariff costs with a lag. Interim gross margin expanded from 22.5% to 25.7% (gross profit JPY 3,193m - 3,731m on sales +2.6%) and automobile-parts segment profit growth swung from -9.7% in FY3/26 to +54.2% in H1 FY3/27, driven by cost reduction and pass-through of wage increases rather than volume. The lag compresses margin on the way up the cost cycle and releases it on the way down. Pass-through is durable as a mechanism, but any single half's margin is not. Steel enters through the Daido channel, and the tariff refund sits inside cost of sales.
内部研究类型:causal_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Profit quality is improving operationally, but each period needs one-offs stripped before the trend is read.
不确定性(原始记录):Refund size is unknown, so the clean pass-through effect cannot be isolated; H2 margin bridge unresolved.
F020|06|利润转现金的比率高,现金流撑得起全部股东回报
研究范围:开放研究+35项覆盖检查
写入正文:06|利润转现金的比率高,现金流撑得起全部股东回报
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 results release, operating cash flow composition怎么使用:直接 / 支持;一手验证:17;专项深挖:17
FY3/26 results release, capital expenditure and construction in progress怎么使用:直接 / 支持;一手验证:20;反向验证:20;专项深挖:20
FY3/27 interim results release, consolidated cash flow statement怎么使用:直接证据;一手验证:17;外部现实校验:19
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接证据;同业比较:17、18、19、25;其他用途:历史
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接证据;外部现实校验:17、18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|FY3/26 results release, operating cash flow composition;直接证据 / 支持证据 / 一手证据(研究域20) / 反证(研究域20) / 定向深挖(研究域20)|FY3/26 results release, capital expenditure and construction in progress;直接证据 / 一手证据(研究域17) / 外部现实(研究域19)|FY3/27 interim results release, consolidated cash flow statement;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;直接证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels
完整研究记录(核对用)
研究原文:Operating cash flow was JPY 5,028m in FY3/26 (pre-tax profit JPY 2,801m + depreciation JPY 2,447m), about twice net income on average over five years, and JPY 2,251m in H1 FY3/27. A mature, heavily depreciated asset base converts profit to cash at a high rate (capex JPY 2,094m versus depreciation JPY 2,447m), so free cash flow stays strongly positive and funds all shareholder returns without touching the balance sheet. The Mexico programme is the first material exception.
内部研究类型:cash_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Cash generation, not earnings growth, funds the return story; rising capex will trim FCF first.
不确定性(原始记录):Maintenance-versus-expansion capex split undisclosed; FCF here is OCF less tangible-asset purchases.
F021|06|在制品增加4.94亿日元,是提前生产还是积压
研究范围:开放研究+35项覆盖检查
写入正文:06|在制品增加4.94亿日元,是提前生产还是积压
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, inventory build in the interim period怎么使用:直接 / 支持;一手验证:19;反向验证:17、19;专项深挖:19
FY3/26 results release, working-capital balances怎么使用:直接证据;一手验证:19;专项深挖:19
FY3/27 interim results release, consolidated cash flow statement怎么使用:直接证据;一手验证:17;外部现实校验:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域19)|FY3/27 interim results release, inventory build in the interim period;直接证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/26 results release, working-capital balances;直接证据 / 一手证据(研究域17) / 外部现实(研究域19)|FY3/27 interim results release, consolidated cash flow statement
完整研究记录(核对用)
研究原文:Work in process rose JPY 494m in H1 to JPY 2,681m, the largest operating-cash-flow absorption of the half. Working capital runs at about two months of sales (FY3/26 receivables ~JPY 6.0bn, inventories JPY 6.3bn, payables ~JPY 3.9bn). The build is either production ahead of second-half deliveries (supporting the raised forecast) or the first sign of an inventory overhang if the implied weaker second half disappoints. Conversion by the Q3 balance sheet is the test.
内部研究类型:balance_sheet_watch_item
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A cheap early read on whether the H2 forecast and demand are real; a build that persists would signal slippage.
不确定性(原始记录):Whether the WIP is Japan- or Mexico-bound, and its ownership/realisability and costing basis, are undisclosed.
F022|09|下行是长年停滞,不是财务困境
研究范围:35项覆盖检查
写入正文:09|下行是长年停滞,不是财务困境
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 results release, non-operating asset balances怎么使用:直接 / 支持;一手验证:21;反向验证:21;专项深挖:21
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:直接证据;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域21) / 反证(研究域21) / 定向深挖(研究域21)|FY3/26 results release, non-operating asset balances;直接证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield
完整研究记录(核对用)
研究原文:There is no large hidden-asset unlock. Investment securities are only JPY 129m, so the gap between the JPY 17.2bn market value and JPY 33.5bn of net assets rests on land at historical cost (JPY 3.4bn book) and on the cash pile, not on a cross-shareholding portfolio. The Maruyoshi asset-sale gain is a small precedent for monetisation. Asset value supports a valuation floor but does not compound unless realised or deployed.
内部研究类型:asset_realisability
内部来源标记:COVERAGE35
普通股东含义(原始记录):The discount is an allocation/governance discount, not an information gap about hidden assets.
不确定性(原始记录):Appraised land values undisclosed; any monetisation of the controlled-entity assets would face minority-claim and tax friction.
F023|06|资本回报贴着资本成本,解释了为什么净资产只值一半
研究范围:35项覆盖检查
写入正文:06|资本回报贴着资本成本,解释了为什么净资产只值一半
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
JINGI company page for 7299: ROE and ROIC history怎么使用:直接 / 支持;一手验证:22;反向验证:09、22;专项深挖:22
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接证据;外部现实校验:17、18
JINGI company page for 7299: industry comparison panel (EDINET database)怎么使用:直接证据;一手验证:09;外部现实校验:10、22;专项深挖:09
JINGI company page for 7299: five-year financial summary compiled from securities reports怎么使用:直接证据;同业比较:02、09、11、15、22、28、29、34、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域22) / 定向深挖(研究域22)|JINGI company page for 7299: ROE and ROIC history;直接证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels;直接证据 / 一手证据(研究域09) / 外部现实(研究域10) / 外部现实(研究域22) / 定向深挖(研究域09)|JINGI company page for 7299: industry comparison panel (EDINET database);直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域15) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35)|JINGI company page for 7299: five-year financial summary compiled from securities reports
完整研究记录(核对用)
研究原文:ROE has ranged from 2.2% to 6.9% over five years (3.8, 2.2, 6.8, 5.2, 6.9) and ROIC is around 6.0-6.5%, so returns hover around a plausible cost of capital. FY3/26 ROE of 6.9% is slightly above the auto-parts sector median (~6.1%) while PBR (0.5x) sits at the sector's discounted end. Idle cash at an 85% equity ratio dilutes ROE, so value must come from capital return and discount narrowing rather than compounding operations.
内部研究类型:capital_efficiency
内部来源标记:COVERAGE35
普通股东含义(原始记录):Fundamental counterpart of a sub-book valuation.
不确定性(原始记录):ROIC is an aggregator computation; the company's own WACC estimate is undisclosed; some of the ROE gain in FY3/26 came from tax and FX items.
F024|07|流通股比例刚好高于上市维持线,持股意图是最大的变数
研究范围:开放研究+35项覆盖检查
写入正文:07|流通股比例刚好高于上市维持线,持股意图是最大的变数15|证据的限制和免责声明
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
JINGI company page for 7299: shareholder and float indicators怎么使用:直接 / 支持;一手验证:24;外部现实校验:13;反向验证:24;专项深挖:13、24、34
FY3/26 results release, treasury-share purchases and disposals怎么使用:直接 / 支持;一手验证:25;专项深挖:24、25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域13) / 反证(研究域24) / 定向深挖(研究域13) / 定向深挖(研究域24) / 定向深挖(研究域34)|JINGI company page for 7299: shareholder and float indicators;直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域24) / 定向深挖(研究域25)|FY3/26 results release, treasury-share purchases and disposals;直接证据|FY3/27 interim results release, share counts;直接证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026
完整研究记录(核对用)
研究原文:The free float of about 37.8% sits just above the TSE Standard continued-listing threshold. A large buyback that retires shares without a matching parent sell-down would tighten the float further, so capital return and float maintenance pull in opposite directions. Daido's holding intention is undisclosed. Treasury holding of 4.3% already reduces outstanding shares, and the float ratio figure is an aggregator's compiled number.
内部研究类型:mechanical_constraint
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A mechanical limit on the pace of buybacks, and a potential catalyst if the parent restructures.
不确定性(原始记录):The exact listing threshold arithmetic and how treasury shares are treated were not independently confirmed in the evidence set.
F025|09|市场买的是低谷到中间,不是预测高点
研究范围:开放研究+35项覆盖检查
写入正文:09|市场买的是低谷到中间,不是预测高点
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
JINGI company page for 7299: five-year ordinary-profit series怎么使用:直接 / 支持;一手验证:28;外部现实校验:15;专项深挖:28
JINGI company page for 7299: balance-sheet resilience indicators怎么使用:直接证据;一手验证:29;专项深挖:18、29
FY3/26 interim (H1) consolidated results release, headline results怎么使用:直接证据;一手验证:28;反向验证:35;同业比较:05、12;其他用途:历史
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:支持证据;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域15) / 定向深挖(研究域28)|JINGI company page for 7299: five-year ordinary-profit series;直接证据 / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|JINGI company page for 7299: balance-sheet resilience indicators;直接证据 / 一手证据(研究域28) / 历史/同业比较(研究域05) / 历史/同业比较(研究域12) / 反证(研究域35)|FY3/26 interim (H1) consolidated results release, headline results;直接证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;支持证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield
完整研究记录(核对用)
研究原文:Ordinary profit over FY3/22-FY3/26 was JPY 1,784 / 1,052 / 1,928 / 2,340 / 2,743m, and the revised FY3/27 forecast of JPY 2,920m sits at the top of that band. A normalised band of roughly JPY 1.0-2.9bn values the JPY 17.2bn market capitalisation at about 6-17x through-cycle earnings, with a mid-band of about JPY 1.9bn. The market is paying for the trough-to-mid part, not the forecast peak. Whether H1's margin resets the band upward is unproven until two consecutive halves are seen.
内部研究类型:normalized_economics
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Paying about 9x the top of the band is paying about 13-17x trough earnings.
不确定性(原始记录):The band is the five disclosed years, not a fitted model; the tax-rate normalisation and net-income bridge are not modelled.
F026|09|下行是长年停滞,不是财务困境
研究范围:35项覆盖检查
写入正文:09|下行是长年停滞,不是财务困境
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
JINGI company page for 7299: balance-sheet resilience indicators怎么使用:直接 / 支持;一手验证:29;专项深挖:18、29
JINGI company page for 7299: five-year financial summary compiled from securities reports怎么使用:直接证据;同业比较:02、09、11、15、22、28、29、34、35;其他用途:历史
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接证据;外部现实校验:17、18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|JINGI company page for 7299: balance-sheet resilience indicators;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域15) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35)|JINGI company page for 7299: five-year financial summary compiled from securities reports;直接证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels
完整研究记录(核对用)
研究原文:The downside case is stagnation, not distress. Even the FY3/23 trough produced JPY 1,052m of ordinary profit at an 80% equity ratio, and with net cash of ~JPY 6bn the realistic loss scenario is years of low-single-digit ROE at a persistent discount (0.3-0.5x book) while cash accumulates. A faster BEV transition or a China-plant impairment (plausible but unquantified) would compress volumes or add write-downs. The balance sheet converts downside into time and makes buybacks at low prices possible.
内部研究类型:downside_scenario
内部来源标记:COVERAGE35
普通股东含义(原始记录):Capital loss risk comes from multiple stagnation and opportunity cost, not impairment of the claim.
不确定性(原始记录):Built from the company's own trough and valuation history, not a stress model; China plant impairment not quantified.
F027|11|三个有日期的催化剂,每一个都是用证据回答一个具体问题
研究范围:35项覆盖检查
写入正文:11|三个有日期的催化剂,每一个都是用证据回答一个具体问题
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record怎么使用:直接 / 支持;一手验证:30;外部现实校验:25、33;反向验证:30;专项深挖:30
IRBANK disclosure index for FUJI OOZX (E02225): results releases, buyback notices, integrated report怎么使用:直接证据;外部现实校验:30
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接证据;一手验证:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域25) / 外部现实(研究域33) / 反证(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record;直接证据 / 外部现实(研究域30)|IRBANK disclosure index for FUJI OOZX (E02225): results releases, buyback notices, integrated report;直接证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary
完整研究记录(核对用)
研究原文:The dated catalysts are the Q3 FY3/27 release around January 2027 (the WIP build must convert to sales and the H2 bridge tested), the FY3/27 year-end release in May 2027 with the successor to the 2026 medium-term plan, and the Mexico plant start in October 2027. Each is evidentiary, resolving a named open question rather than creating momentum. The next two prints can each move the implied full year by the size of the one-offs they reveal.
内部研究类型:dated_catalyst_path
内部来源标记:COVERAGE35
普通股东含义(原始记录):Defines when the thesis can be confirmed or falsified.
不确定性(原始记录):The successor plan's timing is an expectation, not a company commitment, and whether it will contain a capital framework is unknown.
F028|09|上调之后股价回吐,市场只为兑现付钱
研究范围:35项覆盖检查
写入正文:09|上调之后股价回吐,市场只为兑现付钱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Market report on the share-price reaction to the October 2026 forecast raise怎么使用:直接 / 支持;一手验证:31;外部现实校验:35;反向验证:31;专项深挖:31
IRBANK stock page for 7299: latest daily close, 6 November 2026怎么使用:直接 / 支持;一手验证:31;外部现实校验:34、35
IRBANK stock page for 7299: price, market capitalisation and valuation snapshot怎么使用:直接证据;一手验证:27;外部现实校验:01、24、31
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域35) / 反证(研究域31) / 定向深挖(研究域31)|Market report on the share-price reaction to the October 2026 forecast raise;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域34) / 外部现实(研究域35)|IRBANK stock page for 7299: latest daily close, 6 November 2026;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|IRBANK stock page for 7299: price, market capitalisation and valuation snapshot
完整研究记录(核对用)
研究原文:The market's verdict on the raise is visible: after the 27 Oct 2026 forecast and dividend raise the shares fell sharply on profit-taking the next day and closed 6 Nov at JPY 1,675, about 10% below the October close of JPY 1,870. Good news is faded at 0.5x book, and the marginal holder's question is the H2 bridge and capital policy, not the FY3/27 number. Expectations now require delivery, not announcements.
内部研究类型:expectation_signal
内部来源标记:COVERAGE35
普通股东含义(原始记录):Near-term returns depend on delivery against a sceptical register.
不确定性(原始记录):No analyst consensus; sellers' identity unknowable; the market report is a single secondary source plus aggregator price data.
F029|08|计划末期的一批动作指向同一个方向,但这是推断
研究范围:35项覆盖检查
写入正文:08|计划末期的一批动作指向同一个方向,但这是推断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
IRBANK disclosure index for FUJI OOZX: corporate-action turning points怎么使用:直接 / 支持;一手验证:33;外部现实校验:07、20;反向验证:33;专项深挖:07、33;同业比较:30;其他用途:历史
FY3/26 results release, the 2026 medium-term management plan's three themes怎么使用:直接 / 支持;一手验证:33;专项深挖:04、33;同业比较:04、10;其他用途:历史
FY3/27 interim results release, notes on significant subsidiary changes and treasury shares怎么使用:直接证据;一手验证:07;反向验证:07
FY3/26 results release, medium-term plan themes on new-business development怎么使用:直接证据;一手验证:07;专项深挖:07
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域33) / 外部现实(研究域07) / 外部现实(研究域20) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域33)|IRBANK disclosure index for FUJI OOZX: corporate-action turning points;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域33)|FY3/26 results release, the 2026 medium-term management plan's three themes;直接证据 / 一手证据(研究域07) / 反证(研究域07)|FY3/27 interim results release, notes on significant subsidiary changes and treasury shares;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|FY3/26 results release, medium-term plan themes on new-business development
完整研究记录(核对用)
研究原文:The final two years of the 2026 medium-term plan (FY3/25-FY3/27, formulated March 2024) concentrate change: the January 2024 stock split and shareholder-benefit programme, P&M consolidation (July 2024), the first large buyback (January 2026), the Maruyoshi liquidation decision (February 2026; dissolved September 2026), the Jatos-Tetos merger (April 2026) and the Mexico expansion (July 2026). They share one direction: concentrate on the valve core and North America, seed a non-engine leg and start returning the cash pile. Whether this is a regime change or a plan-period flourish is decided by the successor plan in May 2027.
内部研究类型:strategic_turning_point
内部来源标记:COVERAGE35
普通股东含义(原始记录):The capital-policy turn is the one that matters most to minorities and the least contractually committed.
不确定性(原始记录):Reading these actions as a closing programme is this research's inference.
F030|01|论点是折价缓慢收窄,推翻条件有三项
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|论点是折价缓慢收窄,推翻条件有三项14|综合得分62.56/100,B级,观察并小仓位分批建立
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:35;反向验证:28
FY3/26 full-year results release, dividends and initial FY3/27 forecast怎么使用:直接 / 支持;一手验证:26、35;同业比较:26;其他用途:历史
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:直接证据;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接 / 支持;同业比较:17、18、19、25;其他用途:历史
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接 / 支持;一手验证:20
Market report on the share-price reaction to the October 2026 forecast raise怎么使用:直接证据;一手验证:31;外部现实校验:35;反向验证:31;专项深挖:31
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:一手验证:05、13;外部现实校验:32;反向验证:05、16、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域35) / 反证(研究域28)|FY3/27 interim results release, segment information;直接证据 / 支持证据 / 一手证据(研究域26) / 一手证据(研究域35) / 历史/同业比较(研究域26)|FY3/26 full-year results release, dividends and initial FY3/27 forecast;直接证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield;直接证据 / 支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;直接证据 / 支持证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;直接证据 / 一手证据(研究域31) / 外部现实(研究域35) / 反证(研究域31) / 定向深挖(研究域31)|Market report on the share-price reaction to the October 2026 forecast raise;反证 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position
完整研究记录(核对用)
研究原文:Thesis: a niche-leading, parent-controlled engine-valve maker with a fortress balance sheet is priced (0.5x book, ~9x peak-band earnings) as if decline and cash-trapping were permanent. Operating leverage, a first large buyback, a rising dividend and North American hybrid capacity support a slow narrowing of that discount through capital return and delivery, not growth. Confidence is moderate. Falsifiers: (1) the successor plan (May 2027) arrives with no capital framework while cash keeps accumulating; (2) H2 FY3/27 shows the H1 margin was refund and pass-through timing rather than a reset; (3) China moves from decline to impairment without a North American offset. If falsified, the position becomes a value trap with a strong balance sheet: not distress, but no reason to own.
内部研究类型:thesis_and_falsification
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):States what would make the discount narrow and what would kill the case.
不确定性(原始记录):Daido Steel's intentions remain the irreducible unknown.
F031|03|美国关税是一条双向的利润线
研究范围:35项覆盖检查+开放研究
写入正文:03|美国关税是一条双向的利润线
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接证据;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FY3/26 full-year results release, qualitative review of operations怎么使用:直接证据;一手验证:32;同业比较:06、13、14、16;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域06) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16)|FY3/26 full-year results release, qualitative review of operations
完整研究记录(核对用)
研究原文:US tariff policy on Mexican production is a recurring two-way P&L line. Tariffs paid by the Mexican subsidiary were a profit headwind in FY3/26, and a partial refund supported H1 FY3/27 profit, sitting inside cost of sales. This widens the range of reported outcomes around the operating trend. It is a different channel from emissions policy, which acts through powertrain mix. The refund size and the remaining tariff run-rate are undisclosed.
内部研究类型:policy_transmission
内部来源标记:COVERAGE35 / OPEN_DISCOVERY
普通股东含义(原始记录):Policy is a recurring P&L and valuation factor, so the margin level cannot be read without it.
不确定性(原始记录):Amount of the refund and forward tariff exposure are not disclosed.
F032|08|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑
研究范围:开放研究+35项覆盖检查
写入正文:08|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑13|新中期计划会不会写下资本回报框架
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/26 results release, the 2026 medium-term management plan's three themes怎么使用:直接证据;一手验证:33;专项深挖:04、33;同业比较:04、10;其他用途:历史
FY3/26 results release, dividend record and payout ratios怎么使用:直接证据;一手验证:26;反向验证:25、26;专项深挖:26、35
FY3/26 full-year results release, dividends and initial FY3/27 forecast怎么使用:直接证据;一手验证:26、35;同业比较:26;其他用途:历史
IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record怎么使用:直接证据;一手验证:30;外部现实校验:25、33;反向验证:30;专项深挖:30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域33)|FY3/26 results release, the 2026 medium-term management plan's three themes;直接证据 / 一手证据(研究域26) / 反证(研究域25) / 反证(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域35)|FY3/26 results release, dividend record and payout ratios;直接证据 / 一手证据(研究域26) / 一手证据(研究域35) / 历史/同业比较(研究域26)|FY3/26 full-year results release, dividends and initial FY3/27 forecast;直接证据 / 一手证据(研究域30) / 外部现实(研究域25) / 外部现实(研究域33) / 反证(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record
完整研究记录(核对用)
研究原文:Research Debt: does the successor medium-term plan (expected with FY3/27 results in May 2027) commit to a payout ratio, DOE or buyback framework, and how does the revised FY3/27 forecast compare with the 2026 plan's final-year numerical targets (which this research did not obtain)? Currently dividend-on-equity is only ~1.7-1.9% and no framework exists to hold management to the new trajectory. If no framework appears while cash keeps accumulating, the thesis weakens. Resolving evidence: the successor plan document and plan-target disclosure.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Decides whether capital return is a commitment or a discretion.
不确定性(原始记录):Future disclosure; no reasonable current public path exists, and the plan's numerical targets were not obtained.
F033|06|看经常利润,别看净利润
研究范围:开放研究+35项覆盖检查
写入正文:06|看经常利润,别看净利润13|上半年超预期里,关税返还和资产出售占多少
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接证据;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/27 interim results release, gross margin bridge怎么使用:直接证据;一手验证:16;专项深挖:16
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, gross margin bridge
完整研究记录(核对用)
研究原文:Research Debt: how much of the H1 FY3/27 profit beat came from the Mexican tariff refund and the JPY 101m Maruyoshi asset-sale gain? The release does not quantify the refund. The answer separates a pass-through reset from timing noise and conditions the credibility of the new margin level. Resolving evidence: the Q3 and year-end special-items lines or any quantified management commentary.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Determines whether the normalised earnings band shifts up.
不确定性(原始记录):May never be separately disclosed.
F034|13|在制品增加的4.94亿日元,三季度是否已转成销售
研究范围:开放研究+35项覆盖检查
写入正文:13|在制品增加的4.94亿日元,三季度是否已转成销售
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim results release, inventory build in the interim period怎么使用:直接证据;一手验证:19;反向验证:17、19;专项深挖:19
FY3/26 results release, working-capital balances怎么使用:直接证据;一手验证:19;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域19)|FY3/27 interim results release, inventory build in the interim period;直接证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/26 results release, working-capital balances
完整研究记录(核对用)
研究原文:Research Debt: did the JPY 494m interim WIP build convert into second-half sales, or did it remain as inventory at Q3? Resolving evidence: the Q3 FY3/27 balance sheet (around January 2027), which is future disclosure.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):First test of the production-ahead reading versus an overhang.
不确定性(原始记录):Post-cutoff evidence; belongs to the next Review.
F035|13|按动力总成和地区的需求路径,以及中国业务的规模
研究范围:开放研究+35项覆盖检查
写入正文:13|按动力总成和地区的需求路径,以及中国业务的规模
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, regional demand review怎么使用:直接证据;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
FY3/26 results release, industry outlook in the forecast assumptions怎么使用:直接证据;一手验证:11;反向验证:11;专项深挖:11
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接证据;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review;直接证据 / 一手证据(研究域11) / 反证(研究域11) / 定向深挖(研究域11)|FY3/26 results release, industry outlook in the forecast assumptions;直接证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position
完整研究记录(核对用)
研究原文:Research Debt: what is the disclosed demand path for engine valves by powertrain and region, and has the company quantified how hybrid volumes offset BEV substitution? Today only the regional sales split and qualitative commentary exist, and the hybrid share of own volumes is undisclosed. This bounds the length of the decline tail that valuation should capitalise.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Sets the range between a decades-long tail and a years-long decline.
不确定性(原始记录):No reasonable public source identified beyond management commentary.
F036|13|按动力总成和地区的需求路径,以及中国业务的规模
研究范围:开放研究+35项覆盖检查
写入正文:13|按动力总成和地区的需求路径,以及中国业务的规模
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接证据;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FY3/27 interim results release, product and segment description怎么使用:直接证据;一手验证:03;反向验证:03;专项深挖:03、34
FY3/27 interim results release, regional demand review怎么使用:直接证据;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 一手证据(研究域03) / 反证(研究域03) / 定向深挖(研究域03) / 定向深挖(研究域34)|FY3/27 interim results release, product and segment description;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review
完整研究记录(核对用)
研究原文:Research Debt: what is the status and scale of the China operation as Chinese gasoline-car volumes shrink, and is it a restructuring or impairment candidate? Falsifier (3) of the thesis depends on this; subsidiary-level financials are not disclosed beyond segment and note data.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A plausible but unquantified write-down item and a thesis falsifier.
不确定性(原始记录):Subsidiary-level data absent.
F037|08|墨西哥扩产是唯一的销量增长引擎,回报目标没有披露
研究范围:开放研究+35项覆盖检查
写入正文:08|墨西哥扩产是唯一的销量增长引擎,回报目标没有披露13|墨西哥项目的目标回报、客户承诺和在建工程总规模
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接证据;一手验证:20
FY3/26 results release, capital expenditure and construction in progress怎么使用:直接证据;一手验证:20;反向验证:20;专项深挖:20
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;直接证据 / 一手证据(研究域20) / 反证(研究域20) / 定向深挖(研究域20)|FY3/26 results release, capital expenditure and construction in progress
完整研究记录(核对用)
研究原文:Research Debt: what return does the Mexico expansion (US$10.175m, 2.3m valves per month) target and what North American volume commitments support it, and how large is the total construction-in-progress programme (JPY 1,237m at FY3/26) and which plants and products does it serve? Without these, the growth capex cannot be tested against the cost of capital.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Determines whether growth capex creates value or just dilutes ROIC.
不确定性(原始记录):Company has not disclosed target returns or customer commitments.
F038|07|流通股比例刚好高于上市维持线,持股意图是最大的变数
研究范围:开放研究+35项覆盖检查
写入正文:07|流通股比例刚好高于上市维持线,持股意图是最大的变数13|大同特殊钢打算持有、增持还是减持
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
JINGI company page for 7299: shareholder and float indicators怎么使用:直接证据;一手验证:24;外部现实校验:13;反向验证:24;专项深挖:13、24、34
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026;直接证据 / 一手证据(研究域24) / 外部现实(研究域13) / 反证(研究域24) / 定向深挖(研究域13) / 定向深挖(研究域24) / 定向深挖(研究域34)|JINGI company page for 7299: shareholder and float indicators
完整研究记录(核对用)
研究原文:Research Debt: does Daido Steel intend to hold, raise or reduce its stake over time, and could TSE float expectations pressure that decision? This is the irreducible unknown at the centre of the thesis and governs buyback pace, float and any control event.
内部研究类型:research_debt
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The binding constraint on re-rating through float or control events.
不确定性(原始记录):Undisclosed and not reasonably resolvable by public research now.
F039|07|大同特殊钢同时是控股股东、材料渠道和管理层来源
研究范围:开放研究
写入正文:07|大同特殊钢同时是控股股东、材料渠道和管理层来源
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Disclosure concerning the controlling shareholder (Daido Steel), June 2026怎么使用:直接 / 支持;一手验证:24
Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance怎么使用:直接证据;一手验证:06、23;外部现实校验:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026;直接证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域23)|Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance
完整研究记录(核对用)
研究原文:Daido Steel is parent with 47.95% direct and 54.25% combined voting rights; no loans or guarantees from the parent. Control is settled and stable, so the minority question is the terms of coexistence rather than the risk of a control change.
内部研究类型:controls
内部来源标记:OPEN_DISCOVERY
F040|03|主要材料经母公司集团进来,价格靠定期协商
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance怎么使用:直接证据;一手验证:06、23;外部现实校验:23
Controlling-shareholder disclosure: raw-material procurement through the Daido group怎么使用:直接 / 支持;一手验证:06;反向验证:06;专项深挖:06、23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域23)|Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域06) / 定向深挖(研究域06) / 定向深挖(研究域23)|Controlling-shareholder disclosure: raw-material procurement through the Daido group
完整研究记录(核对用)
研究原文:Daido Kogyo, the Daido group's trading arm, supplied JPY 3,320m of valve steel, die steel and materials in FY3/26 at periodically negotiated prices, so steel-price cycles and group pricing practice transmit directly into the valve margin.
内部研究类型:supplies_cost_input_to
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F041|03|需求在三个方向轮动,合并增速只剩低个位数
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接 / 支持;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FUJI OOZX company profile: market position, plants and subsidiary history怎么使用:直接 / 支持;一手验证:09;反向验证:01;同业比较:03、07、08;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 支持证据 / 一手证据(研究域09) / 历史/同业比较(研究域03) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 反证(研究域01)|FUJI OOZX company profile: market position, plants and subsidiary history
完整研究记录(核对用)
研究原文:Valve volumes follow combustion and hybrid engine production in Japan, North America and China. End demand is a derivative of powertrain mix, not vehicle demand alone, so the same vehicle parc yields valve demand only while engines are combustion or hybrid.
内部研究类型:derived_demand_constraint
内部来源标记:OPEN_DISCOVERY
F042|08|墨西哥扩产是唯一的销量增长引擎,回报目标没有披露
研究范围:开放研究
写入正文:08|墨西哥扩产是唯一的销量增长引擎,回报目标没有披露
归并到:F009
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接 / 支持;一手验证:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary
完整研究记录(核对用)
研究原文:The wholly owned Mexican subsidiary is the site of the US$10.175m expansion to 2.3m valves per month from October 2027. It is simultaneously the North American growth engine and the point where US trade policy enters the P&L.
内部研究类型:owns_production_subsidiary
内部来源标记:OPEN_DISCOVERY
F043|06|上一年是销量创纪录,价差却没跟上
研究范围:开放研究+35项覆盖检查
写入正文:06|上一年是销量创纪录,价差却没跟上
归并到:F065
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接 / 支持;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FY3/26 full-year results release, qualitative review of operations怎么使用:直接 / 支持;一手验证:32;同业比较:06、13、14、16;其他用途:历史
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域06) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16)|FY3/26 full-year results release, qualitative review of operations;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary
完整研究记录(核对用)
研究原文:US tariffs on Mexican production reduced FY3/26 profit and a partial refund supported H1 FY3/27 profit. Trade policy is now a recurring P&L line in both directions, widening reported outcomes around the operating trend.
内部研究类型:policy_to_producer_profit
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F044|02|半导体控制部件只占销售约4%,是期权,不是驱动
研究范围:开放研究
写入正文:02|半导体控制部件只占销售约4%,是期权,不是驱动
归并到:F010
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接 / 支持;一手验证:35;反向验证:28
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/26 full-year results release, segment information;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域28)|FY3/27 interim results release, segment information
完整研究记录(核对用)
研究原文:P&M, acquired July 2024 inside the non-automotive segment, grew segment sales +36.1% in FY3/26 and profit from JPY 6m to JPY 91m in H1 FY3/27. It is the only growth leg not tied to combustion engines, but is about 4% of sales.
内部研究类型:diversification_seed_against_concentration
内部来源标记:OPEN_DISCOVERY
F045|08|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑
研究范围:开放研究+35项覆盖检查
写入正文:08|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑
归并到:F068
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance怎么使用:直接证据;一手验证:06、23;外部现实校验:23
IRBANK stock page for 7299: price, market capitalisation and valuation snapshot怎么使用:直接证据;一手验证:27;外部现实校验:01、24、31
JINGI company page for 7299: shareholder and float indicators怎么使用:直接证据;一手验证:24;外部现实校验:13;反向验证:24;专项深挖:13、24、34
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:支持证据;同业比较:17、18、19、25;其他用途:历史
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:支持证据;反向验证:29;同业比较:20、21、24;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域23)|Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|IRBANK stock page for 7299: price, market capitalisation and valuation snapshot;直接证据 / 一手证据(研究域24) / 外部现实(研究域13) / 反证(研究域24) / 定向深挖(研究域13) / 定向深挖(研究域24) / 定向深挖(研究域34)|JINGI company page for 7299: shareholder and float indicators;支持证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026;支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;支持证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026
完整研究记录(核对用)
研究原文:With about 62% of votes in the parent orbit and a ~38% float, minorities receive the dividend (JPY 60 planned) and were the counterparties to the FY3/26 buyback. The float's return depends on the parent's tolerance for a rising payout and buyback pace.
内部研究类型:conditions_minority_return
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F046|02|收入是发动机产量的派生需求,利润是价格与成本的差
研究范围:开放研究+35项覆盖检查
写入正文:02|收入是发动机产量的派生需求,利润是价格与成本的差
归并到:F063
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, segment profit inflection怎么使用:直接 / 支持;一手验证:16;专项深挖:16
FY3/27 interim results release, gross margin bridge怎么使用:直接 / 支持;一手验证:16;专项深挖:16
FY3/27 interim results release, segment information怎么使用:直接 / 支持;一手验证:35;反向验证:28
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, segment profit inflection;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, gross margin bridge;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域28)|FY3/27 interim results release, segment information;支持证据|FY3/26 full-year results release, segment information
完整研究记录(核对用)
研究原文:The automobile-parts segment profit (JPY 1,640m in H1 FY3/27) is nearly the consolidated operating profit it feeds (JPY 1,731m). The group result is the spread between steel-driven costs and negotiated prices, with no second engine to mask a failed pass-through.
内部研究类型:segment_spread_is_group_result
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F047|01|论点是折价缓慢收窄,推翻条件有三项
研究范围:开放研究+35项覆盖检查
写入正文:01|论点是折价缓慢收窄,推翻条件有三项09|市场为控制权和衰退定价,不是为账面资产定价
归并到:F067
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 results release, non-operating asset balances怎么使用:直接 / 支持;一手验证:21;反向验证:21;专项深挖:21
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:直接证据;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接 / 支持;外部现实校验:17、18
IRBANK stock page for 7299: price, market capitalisation and valuation snapshot怎么使用:支持证据;一手验证:27;外部现实校验:01、24、31
IRBANK stock page for 7299: fiscal-year high/low prices and PBR history怎么使用:支持证据;外部现实校验:27、29;同业比较:27、31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域21) / 反证(研究域21) / 定向深挖(研究域21)|FY3/26 results release, non-operating asset balances;直接证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels;支持证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|IRBANK stock page for 7299: price, market capitalisation and valuation snapshot;支持证据 / 外部现实(研究域27) / 外部现实(研究域29) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|IRBANK stock page for 7299: fiscal-year high/low prices and PBR history
完整研究记录(核对用)
研究原文:Net cash (~35% of market capitalisation), land at old cost and negligible investment securities set the valuation floor by assets rather than earnings momentum. The debate is the size of the discount applied to assets controlled by a parent, not whether the assets exist.
内部研究类型:sets_valuation_floor
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F048|08|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑
研究范围:开放研究+35项覆盖检查
写入正文:08|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑
归并到:F068
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
JINGI company page for 7299: shareholder and float indicators怎么使用:直接 / 支持;一手验证:24;外部现实校验:13;反向验证:24;专项深挖:13、24、34
FY3/26 results release, treasury-share purchases and disposals怎么使用:直接 / 支持;一手验证:25;专项深挖:24、25
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域13) / 反证(研究域24) / 定向深挖(研究域13) / 定向深挖(研究域24) / 定向深挖(研究域34)|JINGI company page for 7299: shareholder and float indicators;直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域24) / 定向深挖(研究域25)|FY3/26 results release, treasury-share purchases and disposals
完整研究记录(核对用)
研究原文:A float of about 37.8% just above the continued-listing threshold quietly caps buyback pace and keeps the parent-shareholding question alive. Capital return and float maintenance pull in opposite directions.
内部研究类型:constrains_pace
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F049|08|墨西哥扩产是唯一的销量增长引擎,回报目标没有披露
研究范围:开放研究
写入正文:08|墨西哥扩产是唯一的销量增长引擎,回报目标没有披露
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接 / 支持;一手验证:20
FY3/27 interim results release, regional demand review怎么使用:直接证据;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:支持证据;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review;支持证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position
完整研究记录(核对用)
研究原文:Mexican capacity of 2.3m valves per month from October 2027 is being built against firm North American hybrid demand. This fuses the demand thesis and the tariff thesis into one plant-level question, and the group's only volume-growth engine is North American hybrids produced in Mexico.
内部研究类型:capacity_built_against_demand
内部来源标记:OPEN_DISCOVERY
F050|06|上一年是销量创纪录,价差却没跟上
研究范围:开放研究+35项覆盖检查
写入正文:06|上一年是销量创纪录,价差却没跟上
归并到:F065
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 full-year consolidated results release, headline results怎么使用:直接 / 支持;同业比较:32、35;其他用途:历史
FY3/26 full-year results release, qualitative review of operations怎么使用:直接 / 支持;一手验证:32;同业比较:06、13、14、16;其他用途:历史
FY3/27 interim results release, gross margin bridge怎么使用:直接 / 支持;一手验证:16;专项深挖:16
FY3/27 interim results release, segment profit inflection怎么使用:支持证据;一手验证:16;专项深挖:16
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域32) / 历史/同业比较(研究域35)|FY3/26 full-year consolidated results release, headline results;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域06) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16)|FY3/26 full-year results release, qualitative review of operations;直接证据 / 支持证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, gross margin bridge;支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, segment profit inflection
完整研究记录(核对用)
研究原文:FY3/26's cost-led compression (operating profit -4.2% on +13.9% sales) reversed into H1 FY3/27's pass-through-led expansion (operating profit +61.8% on +2.6% sales). This is consistent with a lagged pass-through catching up, so the swing may reflect timing as much as a permanent reset.
内部研究类型:lagged_reversal
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F051|12|上调预测证明了上半年兑现,却暗示下半年更弱
研究范围:开放研究
归并到:F004
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/26 interim (H1) consolidated results release, headline results怎么使用:直接 / 支持;一手验证:28;反向验证:35;同业比较:05、12;其他用途:历史
查看完整证据标签(核对用)
直接证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 支持证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域05) / 历史/同业比较(研究域12) / 反证(研究域35)|FY3/26 interim (H1) consolidated results release, headline results
完整研究记录(核对用)
研究原文:The raised full-year guidance minus delivered H1 implies a weaker H2 than H2 FY3/26, so the revision proves first-half delivery but not acceleration.
内部研究类型:arithmetic_implication
内部来源标记:OPEN_DISCOVERY
F052|06|在制品增加4.94亿日元,是提前生产还是积压
研究范围:35项覆盖检查
写入正文:06|在制品增加4.94亿日元,是提前生产还是积压11|下半年检验:隐含放缓、在制品增加和一个卖出利好的市场
归并到:F066
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, inventory build in the interim period怎么使用:直接 / 支持;一手验证:19;反向验证:17、19;专项深挖:19
FY3/26 interim (H1) consolidated results release, headline results怎么使用:支持证据;一手验证:28;反向验证:35;同业比较:05、12;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域19)|FY3/27 interim results release, inventory build in the interim period;直接证据 / 支持证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域05) / 历史/同业比较(研究域12) / 反证(研究域35)|FY3/26 interim (H1) consolidated results release, headline results
完整研究记录(核对用)
研究原文:WIP conversion by Q3 tests whether H2 is conservative guidance (build converts to sales) or a genuine slowdown (inventory overhang).
内部研究类型:early_test_of
内部来源标记:COVERAGE35
F053|06|上一年是销量创纪录,价差却没跟上
研究范围:35项覆盖检查
写入正文:06|上一年是销量创纪录,价差却没跟上
归并到:F065
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/27 interim results release, gross margin bridge怎么使用:直接 / 支持;一手验证:16;专项深挖:16
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/27 interim results release, segment profit inflection怎么使用:支持证据;一手验证:16;专项深挖:16
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, gross margin bridge;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, segment profit inflection
完整研究记录(核对用)
研究原文:The tariff refund sits inside cost of sales and so inflates the 25.7% interim gross margin by an unknown amount, limiting how much of the pass-through gain is clean.
内部研究类型:contaminates_margin_read
内部来源标记:COVERAGE35
F054|08|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑
研究范围:35项覆盖检查
写入正文:08|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑
归并到:F068
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/26 results release, operating cash flow composition怎么使用:直接 / 支持;一手验证:17;专项深挖:17
FY3/26 results release, capital expenditure and construction in progress怎么使用:直接 / 支持;一手验证:20;反向验证:20;专项深挖:20
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接 / 支持;同业比较:17、18、19、25;其他用途:历史
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:支持证据;反向验证:29;同业比较:20、21、24;其他用途:历史
FY3/26 results release, dividend record and payout ratios怎么使用:支持证据;一手验证:26;反向验证:25、26;专项深挖:26、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|FY3/26 results release, operating cash flow composition;直接证据 / 支持证据 / 一手证据(研究域20) / 反证(研究域20) / 定向深挖(研究域20)|FY3/26 results release, capital expenditure and construction in progress;直接证据 / 支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;支持证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026;支持证据 / 一手证据(研究域26) / 反证(研究域25) / 反证(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域35)|FY3/26 results release, dividend record and payout ratios
完整研究记录(核对用)
研究原文:High cash conversion from a mature asset base funds the dividend and buyback entirely from operating cash flow, so returns can rise without financial strain. Mexico capex will absorb part of that cash from FY3/27.
内部研究类型:funds
内部来源标记:COVERAGE35
F055|01|这只股票值不值得买,取决于两件慢事谁先到
研究范围:35项覆盖检查
写入正文:01|这只股票值不值得买,取决于两件慢事谁先到05|内燃机依赖决定护城河的有效期,下降路径可能更长更平
归并到:F064
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18
FY3/27 interim results release, liabilities and equity structure怎么使用:直接证据;一手验证:18、25;反向验证:18;专项深挖:18
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接 / 支持;一手验证:20
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:支持证据;外部现实校验:17、18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 一手证据(研究域18) / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|FY3/27 interim results release, liabilities and equity structure;直接证据 / 支持证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels
完整研究记录(核对用)
研究原文:Net cash and an 85% equity ratio let the company fund the Mexico transition and shareholder returns without asking the market for money, so dilution risk is nil and the risk is cash trapping.
内部研究类型:funds_without_external_capital
内部来源标记:COVERAGE35
F056|01|论点是折价缓慢收窄,推翻条件有三项
研究范围:35项覆盖检查
写入正文:01|论点是折价缓慢收窄,推翻条件有三项09|市场为控制权和衰退定价,不是为账面资产定价
归并到:F067
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
JINGI company page for 7299: ROE and ROIC history怎么使用:直接 / 支持;一手验证:22;反向验证:09、22;专项深挖:22
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:直接证据;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
IRBANK stock page for 7299: price, market capitalisation and valuation snapshot怎么使用:支持证据;一手验证:27;外部现实校验:01、24、31
IRBANK stock page for 7299: fiscal-year high/low prices and PBR history怎么使用:支持证据;外部现实校验:27、29;同业比较:27、31;其他用途:历史
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:支持证据;外部现实校验:17、18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域22) / 定向深挖(研究域22)|JINGI company page for 7299: ROE and ROIC history;直接证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|IRBANK stock page for 7299: price, market capitalisation and valuation snapshot;支持证据 / 外部现实(研究域27) / 外部现实(研究域29) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|IRBANK stock page for 7299: fiscal-year high/low prices and PBR history;支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels
完整研究记录(核对用)
研究原文:Returns near the cost of capital are the fundamental counterpart of the 0.5x PBR: the market is not mispricing assets so much as pricing the low spread on them.
内部研究类型:explains
内部来源标记:COVERAGE35
F057|01|论点是折价缓慢收窄,推翻条件有三项
研究范围:开放研究+35项覆盖检查
写入正文:01|论点是折价缓慢收窄,推翻条件有三项09|市场为控制权和衰退定价,不是为账面资产定价
归并到:F067
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
J-LiC officer database for 7299: board composition and president's background怎么使用:直接 / 支持;一手验证:23;反向验证:23;专项深挖:23
Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance怎么使用:直接 / 支持;一手验证:06、23;外部现实校验:23
IRBANK stock page for 7299: fiscal-year high/low prices and PBR history怎么使用:直接 / 支持;外部现实校验:27、29;同业比较:27、31;其他用途:历史
IRBANK stock page for 7299: price, market capitalisation and valuation snapshot怎么使用:支持证据;一手验证:27;外部现实校验:01、24、31
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:支持证据;外部现实校验:17、18
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域23) / 反证(研究域23) / 定向深挖(研究域23)|J-LiC officer database for 7299: board composition and president's background;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域23)|Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance;直接证据 / 支持证据 / 外部现实(研究域27) / 外部现实(研究域29) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|IRBANK stock page for 7299: fiscal-year high/low prices and PBR history;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|IRBANK stock page for 7299: price, market capitalisation and valuation snapshot;支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels
完整研究记录(核对用)
研究原文:Parent control, related-party supply and procedural-only minority protection keep a structural governance and float discount (PBR below 0.7x for sixteen years) that only compounding capital return can narrow.
内部研究类型:contributes_to
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F058|01|这只股票值不值得买,取决于两件慢事谁先到
研究范围:35项覆盖检查
写入正文:01|这只股票值不值得买,取决于两件慢事谁先到05|内燃机依赖决定护城河的有效期,下降路径可能更长更平
归并到:F064
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FUJI OOZX company profile: market position, plants and subsidiary history怎么使用:直接 / 支持;一手验证:09;反向验证:01;同业比较:03、07、08;其他用途:历史
FY3/26 results release, industry outlook in the forecast assumptions怎么使用:直接证据;一手验证:11;反向验证:11;专项深挖:11
JINGI company page for 7299: five-year ordinary-profit series怎么使用:直接 / 支持;一手验证:28;外部现实校验:15;专项深挖:28
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:支持证据;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:支持证据;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域09) / 历史/同业比较(研究域03) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 反证(研究域01)|FUJI OOZX company profile: market position, plants and subsidiary history;直接证据 / 一手证据(研究域11) / 反证(研究域11) / 定向深挖(研究域11)|FY3/26 results release, industry outlook in the forecast assumptions;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域15) / 定向深挖(研究域28)|JINGI company page for 7299: five-year ordinary-profit series;支持证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;支持证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield
完整研究记录(核对用)
研究原文:Combustion dependence caps how long the normalised ordinary-profit band can persist and is why mid-band, not peak-band, earnings are the sober anchor.
内部研究类型:bounds_durability_of
内部来源标记:COVERAGE35
F059|06|在制品增加4.94亿日元,是提前生产还是积压
研究范围:35项覆盖检查
写入正文:06|在制品增加4.94亿日元,是提前生产还是积压11|下半年检验:隐含放缓、在制品增加和一个卖出利好的市场
归并到:F066
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Market report on the share-price reaction to the October 2026 forecast raise怎么使用:直接 / 支持;一手验证:31;外部现实校验:35;反向验证:31;专项深挖:31
IRBANK stock page for 7299: latest daily close, 6 November 2026怎么使用:直接 / 支持;一手验证:31;外部现实校验:34、35
FY3/26 interim (H1) consolidated results release, headline results怎么使用:支持证据;一手验证:28;反向验证:35;同业比较:05、12;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域35) / 反证(研究域31) / 定向深挖(研究域31)|Market report on the share-price reaction to the October 2026 forecast raise;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域34) / 外部现实(研究域35)|IRBANK stock page for 7299: latest daily close, 6 November 2026;直接证据 / 支持证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域05) / 历史/同业比较(研究域12) / 反证(研究域35)|FY3/26 interim (H1) consolidated results release, headline results
完整研究记录(核对用)
研究原文:The sell-the-news response to the raise is consistent with the market focusing on the implied weaker H2 and the quality of the margin level rather than the headline raise.
内部研究类型:reprices_toward
内部来源标记:COVERAGE35
F060|13|七项待解问题各自限制哪一个判断
研究范围:35项覆盖检查
写入正文:13|七项待解问题各自限制哪一个判断
归并到:F069
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/26 results release, the 2026 medium-term management plan's three themes怎么使用:直接证据;一手验证:33;专项深挖:04、33;同业比较:04、10;其他用途:历史
IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record怎么使用:直接证据;一手验证:30;外部现实校验:25、33;反向验证:30;专项深挖:30
FY3/26 full-year results release, dividends and initial FY3/27 forecast怎么使用:支持证据;一手验证:26、35;同业比较:26;其他用途:历史
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:支持证据;同业比较:17、18、19、25;其他用途:历史
Notice of production capacity expansion at the Mexican subsidiary怎么使用:支持证据;一手验证:20
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:一手验证:05、13;外部现实校验:32;反向验证:05、16、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域33)|FY3/26 results release, the 2026 medium-term management plan's three themes;直接证据 / 一手证据(研究域30) / 外部现实(研究域25) / 外部现实(研究域33) / 反证(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record;支持证据 / 一手证据(研究域26) / 一手证据(研究域35) / 历史/同业比较(研究域26)|FY3/26 full-year results release, dividends and initial FY3/27 forecast;支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;支持证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;反证 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position
完整研究记录(核对用)
研究原文:The successor plan's capital framework is the first dated falsifier or confirmation of the thesis.
内部研究类型:decisive_unresolved_evidence_for
内部来源标记:COVERAGE35
F061|10|利好被卖出,价格比业绩走得早,也在和业绩等同一份证据
研究范围:35项覆盖检查
写入正文:10|利好被卖出,价格比业绩走得早,也在和业绩等同一份证据
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Market report on the share-price reaction to the October 2026 forecast raise怎么使用:直接 / 支持;一手验证:31;外部现实校验:35;反向验证:31;专项深挖:31
IRBANK stock page for 7299: latest daily close, 6 November 2026怎么使用:直接 / 支持;一手验证:31;外部现实校验:34、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域35) / 反证(研究域31) / 定向深挖(研究域31)|Market report on the share-price reaction to the October 2026 forecast raise;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域34) / 外部现实(研究域35)|IRBANK stock page for 7299: latest daily close, 6 November 2026;直接证据 / 支持证据|FY3/27 interim results release, revised full-year forecast and dividend forecast
完整研究记录(核对用)
研究原文:The fundamental event record (27 Oct 2026 beat, raise, dividend raise) and the observed post-event close are cross-referenced to the protected Technical Synthesis as a whole. This relation does not alter, extend or reinterpret that Technical truth; the Technical State keeps its own non-confirming status (continuation unconfirmed), and positive fundamental delivery does not rewrite it.
内部研究类型:fundamental_event_context_for_price_response
内部来源标记:COVERAGE35 / TECHNICAL
F062|10|2,250日元的高点失败之后,问题是整固还是新一轮下跌
写入正文:10|2,250日元的高点失败之后,问题是整固还是新一轮下跌10|从2005年的2,630日元到2020年的438日元,再到逐级抬高的新结构10|年度低点连续四年抬高,两次深度回撤都在远高于旧底部的位置止住10|上方是失败的记忆,下方是一级级承接位10|利好被卖出,价格比业绩走得早,也在和业绩等同一份证据14|技术结构得分8.58/13:下跌状态明显减弱,新状态尚未完全确立15|数据截止与来源:基本面截至2026年10月27日披露,价格截至2026年11月6日收盘
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (RESEARCH_TRUTH.technical_state)
内部研究类型:protected_technical_synthesis
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
F063|02|收入是发动机产量的派生需求,利润是价格与成本的差
研究范围:开放研究+35项覆盖检查
写入正文:02|收入是发动机产量的派生需求,利润是价格与成本的差
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(45项,重复标签已合并)
Annual securities report (yuukasyouken houkokusho), company overview and history sections怎么使用:直接证据;一手验证:01;同业比较:01、33;其他用途:历史
FUJI OOZX company profile: market position, plants and subsidiary history怎么使用:直接 / 支持;一手验证:09;反向验证:01;同业比较:03、07、08;其他用途:历史
FY3/26 results release, group composition and segment constitution怎么使用:直接 / 支持;一手验证:01;专项深挖:01
FY3/27 interim results release, product and segment description怎么使用:直接证据;一手验证:03;反向验证:03;专项深挖:03、34
FY3/26 results release, non-consolidated (parent-only) results怎么使用:直接 / 支持;一手验证:02;专项深挖:02
FY3/26 results release, domestic and overseas sales split怎么使用:直接 / 支持;一手验证:02、15;专项深挖:02、15、35
FY3/27 interim results release, segment information怎么使用:直接 / 支持;一手验证:35;反向验证:28
FY3/27 interim results release, segment profit inflection怎么使用:直接 / 支持;一手验证:16;专项深挖:16
Controlling-shareholder disclosure: raw-material procurement through the Daido group怎么使用:直接 / 支持;一手验证:06;反向验证:06;专项深挖:06、23
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接 / 支持;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FY3/27 interim results release, regional demand review怎么使用:直接 / 支持;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
FY3/27 interim results release, industry conditions in the interim period怎么使用:直接 / 支持;一手验证:12;外部现实校验:05、14;反向验证:12;专项深挖:05、12
FY3/26 results release, composition of sales growth怎么使用:直接证据;一手验证:15;反向验证:02、15;专项深挖:15
FY3/26 results release, industry outlook in the forecast assumptions怎么使用:直接证据;一手验证:11;反向验证:11;专项深挖:11
FY3/26 results release, medium-term plan themes and research expense怎么使用:直接 / 支持;一手验证:04、10;反向验证:04;专项深挖:04、10
FUJI OOZX company profile: competitive position of Japanese engine-valve makers怎么使用:直接 / 支持;一手验证:08、10;外部现实校验:03、04;反向验证:08、10;专项深挖:08、10
JINGI company page for 7299: industry comparison panel (EDINET database)怎么使用:直接 / 支持;一手验证:09;外部现实校验:10、22;专项深挖:09
FY3/26 results release, the 2026 medium-term management plan's three themes怎么使用:直接证据;一手验证:33;专项深挖:04、33;同业比较:04、10;其他用途:历史
FY3/27 interim results release, gross margin bridge怎么使用:直接 / 支持;一手验证:16;专项深挖:16
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/26 full-year results release, qualitative review of operations怎么使用:直接证据;一手验证:32;同业比较:06、13、14、16;其他用途:历史
FY3/26 results release, operating cash flow composition怎么使用:直接 / 支持;一手验证:17;专项深挖:17
FY3/26 results release, capital expenditure and construction in progress怎么使用:直接 / 支持;一手验证:20;反向验证:20;专项深挖:20
FY3/27 interim results release, consolidated cash flow statement怎么使用:直接证据;一手验证:17;外部现实校验:19
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接证据;同业比较:17、18、19、25;其他用途:历史
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接 / 支持;外部现实校验:17、18
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18
FY3/27 interim results release, liabilities and equity structure怎么使用:直接 / 支持;一手验证:18、25;反向验证:18;专项深挖:18
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:直接证据;反向验证:29;同业比较:20、21、24;其他用途:历史
FY3/26 results release, non-operating asset balances怎么使用:直接 / 支持;一手验证:21;反向验证:21;专项深挖:21
FY3/26 results release, working-capital balances怎么使用:支持证据;一手验证:19;专项深挖:19
Disclosure concerning the controlling shareholder (Daido Steel), June 2026怎么使用:直接 / 支持;一手验证:24
Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance怎么使用:直接 / 支持;一手验证:06、23;外部现实校验:23
J-LiC officer database for 7299: president's career history from the 98th-term securities report怎么使用:直接证据;同业比较:23;其他用途:历史
J-LiC officer database for 7299: board composition and president's background怎么使用:直接 / 支持;一手验证:23;反向验证:23;专项深挖:23
JINGI company page for 7299: ROE and ROIC history怎么使用:直接 / 支持;一手验证:22;反向验证:09、22;专项深挖:22
JINGI company page for 7299: five-year financial summary compiled from securities reports怎么使用:直接证据;同业比较:02、09、11、15、22、28、29、34、35;其他用途:历史
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:直接证据;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
JINGI company page for 7299: shareholder and float indicators怎么使用:直接 / 支持;一手验证:24;外部现实校验:13;反向验证:24;专项深挖:13、24、34
FY3/26 results release, treasury-share purchases and disposals怎么使用:直接 / 支持;一手验证:25;专项深挖:24、25
JINGI company page for 7299: balance-sheet resilience indicators怎么使用:直接 / 支持;一手验证:29;专项深挖:18、29
FY3/26 results release, medium-term plan themes on new-business development怎么使用:直接证据;一手验证:07;专项深挖:07
IRBANK disclosure index for FUJI OOZX: corporate-action turning points怎么使用:直接证据;一手验证:33;外部现实校验:07、20;反向验证:33;专项深挖:07、33;同业比较:30;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 历史/同业比较(研究域01) / 历史/同业比较(研究域33)|Annual securities report (yuukasyouken houkokusho), company overview and history sections;直接证据 / 支持证据 / 一手证据(研究域09) / 历史/同业比较(研究域03) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 反证(研究域01)|FUJI OOZX company profile: market position, plants and subsidiary history;直接证据 / 支持证据 / 一手证据(研究域01) / 定向深挖(研究域01)|FY3/26 results release, group composition and segment constitution;直接证据 / 一手证据(研究域03) / 反证(研究域03) / 定向深挖(研究域03) / 定向深挖(研究域34)|FY3/27 interim results release, product and segment description;直接证据 / 支持证据 / 一手证据(研究域02) / 定向深挖(研究域02)|FY3/26 results release, non-consolidated (parent-only) results;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域15) / 定向深挖(研究域35)|FY3/26 results release, domestic and overseas sales split;直接证据 / 支持证据 / 一手证据(研究域35) / 反证(研究域28)|FY3/27 interim results release, segment information;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, segment profit inflection;直接证据 / 支持证据|FY3/26 full-year results release, segment information;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域06) / 定向深挖(研究域06) / 定向深挖(研究域23)|Controlling-shareholder disclosure: raw-material procurement through the Daido group;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 支持证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review;直接证据 / 支持证据 / 一手证据(研究域12) / 外部现实(研究域05) / 外部现实(研究域14) / 反证(研究域12) / 定向深挖(研究域05) / 定向深挖(研究域12)|FY3/27 interim results release, industry conditions in the interim period;直接证据 / 一手证据(研究域15) / 反证(研究域02) / 反证(研究域15) / 定向深挖(研究域15)|FY3/26 results release, composition of sales growth;直接证据 / 一手证据(研究域11) / 反证(研究域11) / 定向深挖(研究域11)|FY3/26 results release, industry outlook in the forecast assumptions;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域10) / 反证(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域10)|FY3/26 results release, medium-term plan themes and research expense;直接证据 / 支持证据 / 一手证据(研究域08) / 一手证据(研究域10) / 外部现实(研究域03) / 外部现实(研究域04) / 反证(研究域08) / 反证(研究域10) / 定向深挖(研究域08) / 定向深挖(研究域10)|FUJI OOZX company profile: competitive position of Japanese engine-valve makers;直接证据 / 支持证据 / 一手证据(研究域09) / 外部现实(研究域10) / 外部现实(研究域22) / 定向深挖(研究域09)|JINGI company page for 7299: industry comparison panel (EDINET database);直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域33)|FY3/26 results release, the 2026 medium-term management plan's three themes;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, gross margin bridge;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 一手证据(研究域32) / 历史/同业比较(研究域06) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16)|FY3/26 full-year results release, qualitative review of operations;直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|FY3/26 results release, operating cash flow composition;直接证据 / 支持证据 / 一手证据(研究域20) / 反证(研究域20) / 定向深挖(研究域20)|FY3/26 results release, capital expenditure and construction in progress;直接证据 / 一手证据(研究域17) / 外部现实(研究域19)|FY3/27 interim results release, consolidated cash flow statement;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels;直接证据 / 支持证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|FY3/27 interim results release, liabilities and equity structure;直接证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026;直接证据 / 支持证据 / 一手证据(研究域21) / 反证(研究域21) / 定向深挖(研究域21)|FY3/26 results release, non-operating asset balances;支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/26 results release, working-capital balances;直接证据 / 支持证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域23)|Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance;直接证据 / 历史/同业比较(研究域23)|J-LiC officer database for 7299: president's career history from the 98th-term securities report;直接证据 / 支持证据 / 一手证据(研究域23) / 反证(研究域23) / 定向深挖(研究域23)|J-LiC officer database for 7299: board composition and president's background;直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域22) / 定向深挖(研究域22)|JINGI company page for 7299: ROE and ROIC history;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域15) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35)|JINGI company page for 7299: five-year financial summary compiled from securities reports;直接证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield;直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域13) / 反证(研究域24) / 定向深挖(研究域13) / 定向深挖(研究域24) / 定向深挖(研究域34)|JINGI company page for 7299: shareholder and float indicators;直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域24) / 定向深挖(研究域25)|FY3/26 results release, treasury-share purchases and disposals;直接证据|FY3/27 interim results release, share counts;直接证据 / 支持证据 / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|JINGI company page for 7299: balance-sheet resilience indicators;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|FY3/26 results release, medium-term plan themes on new-business development;直接证据 / 一手证据(研究域33) / 外部现实(研究域07) / 外部现实(研究域20) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域33)|IRBANK disclosure index for FUJI OOZX: corporate-action turning points
完整研究记录(核对用)
研究原文:Durable Business Portrait: a niche share-holder with a fortress balance sheet inside a parent group|The company earns a specification-bound niche spread on engine production through qualification depth and a position inside the Daido group, converts it to cash at a high rate on a depreciated asset base, keeps no debt, and earns near its cost of capital. What is durable is position, balance sheet and the pass-through mechanism. What is not durable is any year's profit level, which is set by engine volumes and a negotiated pass-through lag, nor the niche itself, which is bounded by combustion-engine production. Governance sits with the parent.
内部研究类型:durable_business_portrait
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Downside is stagnation at a discount, not distress; upside depends on allocation and delivery rather than growth.
不确定性(原始记录):Programme-level, customer-level and powertrain-level data are undisclosed; competitor benchmarking was not obtained.
F064|01|这只股票值不值得买,取决于两件慢事谁先到
研究范围:开放研究+35项覆盖检查
写入正文:01|这只股票值不值得买,取决于两件慢事谁先到05|内燃机依赖决定护城河的有效期,下降路径可能更长更平
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(32项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接 / 支持;同业比较:17、18、19、25;其他用途:历史
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接 / 支持;一手验证:05、13;外部现实校验:32;反向验证:05、16、35;其他用途:反证
FUJI OOZX company profile: market position, plants and subsidiary history怎么使用:直接 / 支持;一手验证:09;反向验证:01;同业比较:03、07、08;其他用途:历史
FY3/26 results release, industry outlook in the forecast assumptions怎么使用:直接证据;一手验证:11;反向验证:11;专项深挖:11
FY3/27 interim results release, regional demand review怎么使用:直接证据;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:直接 / 支持;反向验证:29;同业比较:20、21、24;其他用途:历史
FY3/26 full-year results release, dividends and initial FY3/27 forecast怎么使用:直接 / 支持;一手验证:26、35;同业比较:26;其他用途:历史
FY3/26 results release, treasury-share purchases and disposals怎么使用:直接证据;一手验证:25;专项深挖:24、25
FY3/26 results release, dividend record and payout ratios怎么使用:直接 / 支持;一手验证:26;反向验证:25、26;专项深挖:26、35
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接 / 支持;外部现实校验:17、18
FY3/27 interim results release, liabilities and equity structure怎么使用:直接 / 支持;一手验证:18、25;反向验证:18;专项深挖:18
FY3/26 results release, non-operating asset balances怎么使用:直接证据;一手验证:21;反向验证:21;专项深挖:21
FY3/26 results release, working-capital balances怎么使用:支持证据;一手验证:19;专项深挖:19
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接 / 支持;一手验证:20
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/26 results release, capital expenditure and construction in progress怎么使用:直接 / 支持;一手验证:20;反向验证:20;专项深挖:20
FY3/27 interim results release, consolidated cash flow statement怎么使用:直接证据;一手验证:17;外部现实校验:19
JINGI company page for 7299: five-year ordinary-profit series怎么使用:直接 / 支持;一手验证:28;外部现实校验:15;专项深挖:28
JINGI company page for 7299: balance-sheet resilience indicators怎么使用:直接证据;一手验证:29;专项深挖:18、29
FY3/26 interim (H1) consolidated results release, headline results怎么使用:直接证据;一手验证:28;反向验证:35;同业比较:05、12;其他用途:历史
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:直接 / 支持;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:35;反向验证:28
Market report on the share-price reaction to the October 2026 forecast raise怎么使用:直接证据;一手验证:31;外部现实校验:35;反向验证:31;专项深挖:31
IRBANK disclosure index for FUJI OOZX: corporate-action turning points怎么使用:直接 / 支持;一手验证:33;外部现实校验:07、20;反向验证:33;专项深挖:07、33;同业比较:30;其他用途:历史
FY3/26 results release, the 2026 medium-term management plan's three themes怎么使用:直接 / 支持;一手验证:33;专项深挖:04、33;同业比较:04、10;其他用途:历史
FY3/27 interim results release, notes on significant subsidiary changes and treasury shares怎么使用:直接证据;一手验证:07;反向验证:07
FY3/26 results release, medium-term plan themes on new-business development怎么使用:直接证据;一手验证:07;专项深挖:07
FY3/26 results release, operating cash flow composition怎么使用:直接 / 支持;一手验证:17;专项深挖:17
查看完整证据标签(核对用)
直接证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;直接证据 / 支持证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;直接证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026;直接证据 / 支持证据 / 反证 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 支持证据 / 一手证据(研究域09) / 历史/同业比较(研究域03) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 反证(研究域01)|FUJI OOZX company profile: market position, plants and subsidiary history;直接证据 / 一手证据(研究域11) / 反证(研究域11) / 定向深挖(研究域11)|FY3/26 results release, industry outlook in the forecast assumptions;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review;直接证据 / 支持证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026;直接证据 / 支持证据 / 一手证据(研究域26) / 一手证据(研究域35) / 历史/同业比较(研究域26)|FY3/26 full-year results release, dividends and initial FY3/27 forecast;直接证据 / 一手证据(研究域25) / 定向深挖(研究域24) / 定向深挖(研究域25)|FY3/26 results release, treasury-share purchases and disposals;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域25) / 反证(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域35)|FY3/26 results release, dividend record and payout ratios;直接证据|FY3/27 interim results release, share counts;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|FY3/27 interim results release, liabilities and equity structure;直接证据 / 一手证据(研究域21) / 反证(研究域21) / 定向深挖(研究域21)|FY3/26 results release, non-operating asset balances;支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/26 results release, working-capital balances;直接证据 / 支持证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 支持证据 / 一手证据(研究域20) / 反证(研究域20) / 定向深挖(研究域20)|FY3/26 results release, capital expenditure and construction in progress;直接证据 / 一手证据(研究域17) / 外部现实(研究域19)|FY3/27 interim results release, consolidated cash flow statement;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域15) / 定向深挖(研究域28)|JINGI company page for 7299: five-year ordinary-profit series;直接证据 / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|JINGI company page for 7299: balance-sheet resilience indicators;直接证据 / 一手证据(研究域28) / 历史/同业比较(研究域05) / 历史/同业比较(研究域12) / 反证(研究域35)|FY3/26 interim (H1) consolidated results release, headline results;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield;直接证据 / 一手证据(研究域35) / 反证(研究域28)|FY3/27 interim results release, segment information;直接证据 / 一手证据(研究域31) / 外部现实(研究域35) / 反证(研究域31) / 定向深挖(研究域31)|Market report on the share-price reaction to the October 2026 forecast raise;直接证据 / 支持证据 / 一手证据(研究域33) / 外部现实(研究域07) / 外部现实(研究域20) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域33)|IRBANK disclosure index for FUJI OOZX: corporate-action turning points;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域33)|FY3/26 results release, the 2026 medium-term management plan's three themes;直接证据 / 一手证据(研究域07) / 反证(研究域07)|FY3/27 interim results release, notes on significant subsidiary changes and treasury shares;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|FY3/26 results release, medium-term plan themes on new-business development;直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|FY3/26 results release, operating cash flow composition
完整研究记录(核对用)
研究原文:Two slow clocks: compounding capital return versus the powertrain transition|What is durable here is position rather than growth: the largest share of a specification-bound niche, a materials and production position inside the Daido group, an unlevered balance sheet and a price structure whose declines have been arrested higher. The investment question resolves into a race between compounding capital return at a deep discount and the powertrain transition shrinking the niche. Both are observable and neither is fast. Falsifiers are dated: the May 2027 successor plan, the two prints before it, and the monthly price sensors recorded in the protected Technical Synthesis.
内部研究类型:structural_durability_race
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The balance sheet buys time for the capital-return clock to compound; if cash merely accumulates, the discount cannot narrow without heroic engine-market growth.
不确定性(原始记录):Pace of BEV transition is exogenous; Daido's intentions undisclosed.
F065|06|上一年是销量创纪录,价差却没跟上
研究范围:开放研究+35项覆盖检查
写入正文:06|上一年是销量创纪录,价差却没跟上
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(23项,重复标签已合并)
FY3/26 full-year consolidated results release, headline results怎么使用:直接 / 支持;同业比较:32、35;其他用途:历史
FY3/26 full-year results release, qualitative review of operations怎么使用:直接 / 支持;一手验证:32;同业比较:06、13、14、16;其他用途:历史
FY3/26 results release, domestic and overseas sales split怎么使用:直接证据;一手验证:02、15;专项深挖:02、15、35
FY3/26 results release, composition of sales growth怎么使用:直接证据;一手验证:15;反向验证:02、15;专项深挖:15
FY3/27 interim results release, gross margin bridge怎么使用:直接 / 支持;一手验证:16;专项深挖:16
FY3/27 interim results release, segment profit inflection怎么使用:直接 / 支持;一手验证:16;专项深挖:16
Controlling-shareholder disclosure: raw-material procurement through the Daido group怎么使用:直接 / 支持;一手验证:06;反向验证:06;专项深挖:06、23
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接 / 支持;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:35;反向验证:28
FY3/26 interim (H1) consolidated results release, headline results怎么使用:直接证据;一手验证:28;反向验证:35;同业比较:05、12;其他用途:历史
FY3/26 results release, catalogue of non-recurring items怎么使用:直接 / 支持;一手验证:32;外部现实校验:16;反向验证:32;专项深挖:32
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:直接证据;反向验证:29;同业比较:20、21、24;其他用途:历史
JINGI company page for 7299: five-year ordinary-profit series怎么使用:直接 / 支持;一手验证:28;外部现实校验:15;专项深挖:28
JINGI company page for 7299: balance-sheet resilience indicators怎么使用:直接证据;一手验证:29;专项深挖:18、29
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:支持证据;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
Disclosure concerning the controlling shareholder (Daido Steel), June 2026怎么使用:直接 / 支持;一手验证:24
Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance怎么使用:直接证据;一手验证:06、23;外部现实校验:23
J-LiC officer database for 7299: president's career history from the 98th-term securities report怎么使用:直接证据;同业比较:23;其他用途:历史
J-LiC officer database for 7299: board composition and president's background怎么使用:直接证据;一手验证:23;反向验证:23;专项深挖:23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 历史/同业比较(研究域32) / 历史/同业比较(研究域35)|FY3/26 full-year consolidated results release, headline results;直接证据|FY3/26 full-year results release, segment information;直接证据 / 支持证据 / 一手证据(研究域32) / 历史/同业比较(研究域06) / 历史/同业比较(研究域13) / 历史/同业比较(研究域14) / 历史/同业比较(研究域16)|FY3/26 full-year results release, qualitative review of operations;直接证据 / 一手证据(研究域02) / 一手证据(研究域15) / 定向深挖(研究域02) / 定向深挖(研究域15) / 定向深挖(研究域35)|FY3/26 results release, domestic and overseas sales split;直接证据 / 一手证据(研究域15) / 反证(研究域02) / 反证(研究域15) / 定向深挖(研究域15)|FY3/26 results release, composition of sales growth;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, gross margin bridge;直接证据 / 支持证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, segment profit inflection;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域06) / 定向深挖(研究域06) / 定向深挖(研究域23)|Controlling-shareholder disclosure: raw-material procurement through the Daido group;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 支持证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 支持证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;直接证据 / 一手证据(研究域35) / 反证(研究域28)|FY3/27 interim results release, segment information;直接证据 / 一手证据(研究域28) / 历史/同业比较(研究域05) / 历史/同业比较(研究域12) / 反证(研究域35)|FY3/26 interim (H1) consolidated results release, headline results;直接证据 / 支持证据 / 一手证据(研究域32) / 外部现实(研究域16) / 反证(研究域32) / 定向深挖(研究域32)|FY3/26 results release, catalogue of non-recurring items;直接证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域15) / 定向深挖(研究域28)|JINGI company page for 7299: five-year ordinary-profit series;直接证据 / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|JINGI company page for 7299: balance-sheet resilience indicators;支持证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield;直接证据 / 支持证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026;直接证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域23)|Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance;直接证据 / 历史/同业比较(研究域23)|J-LiC officer database for 7299: president's career history from the 98th-term securities report;直接证据 / 一手证据(研究域23) / 反证(研究域23) / 定向深挖(研究域23)|J-LiC officer database for 7299: board composition and president's background
完整研究记录(核对用)
研究原文:From cost-led compression to pass-through-led expansion, with one-offs in between|Steel, wage and tariff costs enter cost of sales immediately while prices move by negotiation, so margin follows the cost cycle with a lag. FY3/26 shows the squeeze (record sales, lower operating profit, FX-assisted ordinary profit, tax-flattered net income); H1 FY3/27 shows the release (higher margin on flat sales), partly helped by a tariff refund and asset-sale gain. The clean trend sits in ordinary profit, and the band of JPY 1.0-2.9bn is the sober anchor.
内部研究类型:causal_chain
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Valuing on reported net income or on the forecast peak overpays; the margin reset is unproven until two halves at the new level.
不确定性(原始记录):Refund and deferred-tax credit sizes undisclosed; causal attribution between pass-through timing and reset is inferential.
F066|06|在制品增加4.94亿日元,是提前生产还是积压
研究范围:开放研究+35项覆盖检查
写入正文:06|在制品增加4.94亿日元,是提前生产还是积压11|下半年检验:隐含放缓、在制品增加和一个卖出利好的市场
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(18项,重复标签已合并)
FY3/27 interim results release, segment information怎么使用:直接证据;一手验证:35;反向验证:28
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接证据;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FY3/26 interim (H1) consolidated results release, headline results怎么使用:直接 / 支持;一手验证:28;反向验证:35;同业比较:05、12;其他用途:历史
FY3/26 full-year consolidated results release, headline results怎么使用:直接证据;同业比较:32、35;其他用途:历史
JINGI company page for 7299: five-year ordinary-profit series怎么使用:直接证据;一手验证:28;外部现实校验:15;专项深挖:28
FY3/27 interim results release, inventory build in the interim period怎么使用:直接 / 支持;一手验证:19;反向验证:17、19;专项深挖:19
FY3/26 results release, working-capital balances怎么使用:直接证据;一手验证:19;专项深挖:19
FY3/27 interim results release, consolidated cash flow statement怎么使用:直接证据;一手验证:17;外部现实校验:19
Market report on the share-price reaction to the October 2026 forecast raise怎么使用:直接 / 支持;一手验证:31;外部现实校验:35;反向验证:31;专项深挖:31
IRBANK stock page for 7299: latest daily close, 6 November 2026怎么使用:直接 / 支持;一手验证:31;外部现实校验:34、35
IRBANK stock page for 7299: price, market capitalisation and valuation snapshot怎么使用:直接证据;一手验证:27;外部现实校验:01、24、31
IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record怎么使用:直接 / 支持;一手验证:30;外部现实校验:25、33;反向验证:30;专项深挖:30
IRBANK disclosure index for FUJI OOZX (E02225): results releases, buyback notices, integrated report怎么使用:直接证据;外部现实校验:30
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接证据;一手验证:20
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/27 interim results release, gross margin bridge怎么使用:直接证据;一手验证:16;专项深挖:16
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/27 interim (H1) consolidated results release, headline results;直接证据 / 支持证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;直接证据 / 一手证据(研究域35) / 反证(研究域28)|FY3/27 interim results release, segment information;直接证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 支持证据 / 一手证据(研究域28) / 历史/同业比较(研究域05) / 历史/同业比较(研究域12) / 反证(研究域35)|FY3/26 interim (H1) consolidated results release, headline results;直接证据 / 历史/同业比较(研究域32) / 历史/同业比较(研究域35)|FY3/26 full-year consolidated results release, headline results;直接证据 / 一手证据(研究域28) / 外部现实(研究域15) / 定向深挖(研究域28)|JINGI company page for 7299: five-year ordinary-profit series;直接证据 / 支持证据 / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域19)|FY3/27 interim results release, inventory build in the interim period;直接证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/26 results release, working-capital balances;直接证据 / 一手证据(研究域17) / 外部现实(研究域19)|FY3/27 interim results release, consolidated cash flow statement;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域35) / 反证(研究域31) / 定向深挖(研究域31)|Market report on the share-price reaction to the October 2026 forecast raise;直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域34) / 外部现实(研究域35)|IRBANK stock page for 7299: latest daily close, 6 November 2026;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|IRBANK stock page for 7299: price, market capitalisation and valuation snapshot;直接证据 / 支持证据 / 一手证据(研究域30) / 外部现实(研究域25) / 外部现实(研究域33) / 反证(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record;直接证据 / 外部现实(研究域30)|IRBANK disclosure index for FUJI OOZX (E02225): results releases, buyback notices, integrated report;直接证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, gross margin bridge
完整研究记录(核对用)
研究原文:The second-half bridge: implied slowdown, WIP build and a market that sold the raise|The raise shows H1 delivery, yet implies H2 ordinary profit about 23% below the prior-year H2, the interim WIP build awaits conversion, and the market sold the news. Together these frame the January 2027 print as the first evidentiary test of whether the margin level is a reset.
内部研究类型:expectation_delivery_test
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Near-term outcomes depend on the Q3 bridge; confirmation supports the delivery narrative, a persistent WIP build or a weak H2 would revert the margin reading to timing.
不确定性(原始记录):Derived from guidance arithmetic and a single market-reaction report; tariff refund unquantified.
F067|01|论点是折价缓慢收窄,推翻条件有三项
研究范围:开放研究+35项覆盖检查
写入正文:01|论点是折价缓慢收窄,推翻条件有三项09|市场为控制权和衰退定价,不是为账面资产定价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(23项,重复标签已合并)
IRBANK stock page for 7299: latest daily close, 6 November 2026怎么使用:直接 / 支持;一手验证:31;外部现实校验:34、35
FY3/26 full-year consolidated results release, headline results怎么使用:直接 / 支持;同业比较:32、35;其他用途:历史
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接 / 支持;同业比较:17、18、19、25;其他用途:历史
FY3/26 full-year results release, dividends and initial FY3/27 forecast怎么使用:直接 / 支持;一手验证:26、35;同业比较:26;其他用途:历史
IRBANK stock page for 7299: price, market capitalisation and valuation snapshot怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、24、31
IRBANK stock page for 7299: fiscal-year high/low prices and PBR history怎么使用:直接 / 支持;外部现实校验:27、29;同业比较:27、31;其他用途:历史
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接 / 支持;外部现实校验:17、18
IRBANK stock page for 7299: valuation multiples and dividend yield怎么使用:直接 / 支持;一手验证:27、35;外部现实校验:09、21、26、28;反向验证:27;专项深挖:27
JINGI company page for 7299: ROE and ROIC history怎么使用:直接 / 支持;一手验证:22;反向验证:09、22;专项深挖:22
JINGI company page for 7299: five-year ordinary-profit series怎么使用:直接 / 支持;一手验证:28;外部现实校验:15;专项深挖:28
JINGI company page for 7299: balance-sheet resilience indicators怎么使用:直接 / 支持;一手验证:29;专项深挖:18、29
FY3/26 interim (H1) consolidated results release, headline results怎么使用:直接证据;一手验证:28;反向验证:35;同业比较:05、12;其他用途:历史
JINGI company page for 7299: industry comparison panel (EDINET database)怎么使用:直接证据;一手验证:09;外部现实校验:10、22;专项深挖:09
JINGI company page for 7299: five-year financial summary compiled from securities reports怎么使用:直接证据;同业比较:02、09、11、15、22、28、29、34、35;其他用途:历史
FY3/27 interim results release, liabilities and equity structure怎么使用:直接 / 支持;一手验证:18、25;反向验证:18;专项深挖:18
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:直接证据;反向验证:29;同业比较:20、21、24;其他用途:历史
FY3/26 results release, non-operating asset balances怎么使用:直接 / 支持;一手验证:21;反向验证:21;专项深挖:21
FY3/26 results release, working-capital balances怎么使用:支持证据;一手验证:19;专项深挖:19
Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance怎么使用:直接 / 支持;一手验证:06、23;外部现实校验:23
J-LiC officer database for 7299: board composition and president's background怎么使用:直接 / 支持;一手验证:23;反向验证:23;专项深挖:23
J-LiC officer database for 7299: president's career history from the 98th-term securities report怎么使用:直接证据;同业比较:23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域31) / 外部现实(研究域34) / 外部现实(研究域35)|IRBANK stock page for 7299: latest daily close, 6 November 2026;直接证据 / 支持证据|FY3/27 interim results release, revised full-year forecast and dividend forecast;直接证据 / 支持证据 / 历史/同业比较(研究域32) / 历史/同业比较(研究域35)|FY3/26 full-year consolidated results release, headline results;直接证据 / 支持证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;直接证据 / 支持证据 / 一手证据(研究域26) / 一手证据(研究域35) / 历史/同业比较(研究域26)|FY3/26 full-year results release, dividends and initial FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|IRBANK stock page for 7299: price, market capitalisation and valuation snapshot;直接证据 / 支持证据 / 外部现实(研究域27) / 外部现实(研究域29) / 历史/同业比较(研究域27) / 历史/同业比较(研究域31)|IRBANK stock page for 7299: fiscal-year high/low prices and PBR history;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels;直接证据 / 支持证据 / 一手证据(研究域27) / 一手证据(研究域35) / 外部现实(研究域09) / 外部现实(研究域21) / 外部现实(研究域26) / 外部现实(研究域28) / 反证(研究域27) / 定向深挖(研究域27)|IRBANK stock page for 7299: valuation multiples and dividend yield;直接证据 / 支持证据 / 一手证据(研究域22) / 反证(研究域09) / 反证(研究域22) / 定向深挖(研究域22)|JINGI company page for 7299: ROE and ROIC history;直接证据 / 支持证据 / 一手证据(研究域28) / 外部现实(研究域15) / 定向深挖(研究域28)|JINGI company page for 7299: five-year ordinary-profit series;直接证据 / 支持证据 / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|JINGI company page for 7299: balance-sheet resilience indicators;直接证据 / 一手证据(研究域28) / 历史/同业比较(研究域05) / 历史/同业比较(研究域12) / 反证(研究域35)|FY3/26 interim (H1) consolidated results release, headline results;直接证据 / 一手证据(研究域09) / 外部现实(研究域10) / 外部现实(研究域22) / 定向深挖(研究域09)|JINGI company page for 7299: industry comparison panel (EDINET database);直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域15) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35)|JINGI company page for 7299: five-year financial summary compiled from securities reports;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|FY3/27 interim results release, liabilities and equity structure;直接证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026;直接证据 / 支持证据 / 一手证据(研究域21) / 反证(研究域21) / 定向深挖(研究域21)|FY3/26 results release, non-operating asset balances;支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/26 results release, working-capital balances;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域23)|Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance;直接证据 / 支持证据 / 一手证据(研究域23) / 反证(研究域23) / 定向深挖(研究域23)|J-LiC officer database for 7299: board composition and president's background;直接证据 / 历史/同业比较(研究域23)|J-LiC officer database for 7299: president's career history from the 98th-term securities report
完整研究记录(核对用)
研究原文:What the market pays for: 0.5x book, ~9x peak-band earnings, 35% net cash|The valuation prices control and decline, not assets or current earnings. Assets set a floor (net cash ~35% of market value, no hidden cross-holdings), normalised earnings of JPY 1.0-2.9bn give 6-17x, returns near cost of capital justify part of the discount, and parent control and float explain the rest. Re-rating requires evidence of compounding return or a float or control event.
内部研究类型:valuation_bridge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Entry price already assumes mid-band delivery; the downside is multiple stagnation and opportunity cost.
不确定性(原始记录):Mixed share-count, cash and period bases in the snapshot; no consensus comparison.
F068|08|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑
研究范围:开放研究+35项覆盖检查
写入正文:08|现金、回购、墨西哥和流通股上限,构成母公司控制下的资本配置赛跑
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(30项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接 / 支持;外部现实校验:17、18
FY3/27 interim results release, liabilities and equity structure怎么使用:直接 / 支持;一手验证:18、25;反向验证:18;专项深挖:18
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:直接 / 支持;反向验证:29;同业比较:20、21、24;其他用途:历史
FY3/26 results release, non-operating asset balances怎么使用:直接证据;一手验证:21;反向验证:21;专项深挖:21
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接 / 支持;同业比较:17、18、19、25;其他用途:历史
FY3/26 results release, working-capital balances怎么使用:支持证据;一手验证:19;专项深挖:19
FY3/26 results release, operating cash flow composition怎么使用:直接 / 支持;一手验证:17;专项深挖:17
FY3/26 results release, capital expenditure and construction in progress怎么使用:直接 / 支持;一手验证:20;反向验证:20;专项深挖:20
FY3/27 interim results release, consolidated cash flow statement怎么使用:直接证据;一手验证:17;外部现实校验:19
FY3/26 full-year results release, dividends and initial FY3/27 forecast怎么使用:直接 / 支持;一手验证:26、35;同业比较:26;其他用途:历史
FY3/26 results release, treasury-share purchases and disposals怎么使用:直接 / 支持;一手验证:25;专项深挖:24、25
FY3/26 results release, dividend record and payout ratios怎么使用:直接 / 支持;一手验证:26;反向验证:25、26;专项深挖:26、35
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接 / 支持;一手验证:20
FY3/27 interim results release, regional demand review怎么使用:直接证据;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
JINGI company page for 7299: shareholder and float indicators怎么使用:直接 / 支持;一手验证:24;外部现实校验:13;反向验证:24;专项深挖:13、24、34
Disclosure concerning the controlling shareholder (Daido Steel), June 2026怎么使用:直接 / 支持;一手验证:24
Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance怎么使用:直接证据;一手验证:06、23;外部现实校验:23
J-LiC officer database for 7299: president's career history from the 98th-term securities report怎么使用:直接证据;同业比较:23;其他用途:历史
Controlling-shareholder disclosure: raw-material procurement through the Daido group怎么使用:直接 / 支持;一手验证:06;反向验证:06;专项深挖:06、23
J-LiC officer database for 7299: board composition and president's background怎么使用:直接证据;一手验证:23;反向验证:23;专项深挖:23
IRBANK disclosure index for FUJI OOZX: corporate-action turning points怎么使用:直接 / 支持;一手验证:33;外部现实校验:07、20;反向验证:33;专项深挖:07、33;同业比较:30;其他用途:历史
FY3/26 results release, the 2026 medium-term management plan's three themes怎么使用:直接 / 支持;一手验证:33;专项深挖:04、33;同业比较:04、10;其他用途:历史
FY3/27 interim results release, notes on significant subsidiary changes and treasury shares怎么使用:直接证据;一手验证:07;反向验证:07
FY3/26 results release, medium-term plan themes on new-business development怎么使用:直接证据;一手验证:07;专项深挖:07
IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record怎么使用:直接证据;一手验证:30;外部现实校验:25、33;反向验证:30;专项深挖:30
IRBANK stock page for 7299: price, market capitalisation and valuation snapshot怎么使用:直接证据;一手验证:27;外部现实校验:01、24、31
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:一手验证:05、13;外部现实校验:32;反向验证:05、16、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|FY3/27 interim results release, liabilities and equity structure;直接证据 / 支持证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026;直接证据 / 一手证据(研究域21) / 反证(研究域21) / 定向深挖(研究域21)|FY3/26 results release, non-operating asset balances;直接证据 / 支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/26 results release, working-capital balances;直接证据 / 支持证据 / 一手证据(研究域17) / 定向深挖(研究域17)|FY3/26 results release, operating cash flow composition;直接证据 / 支持证据 / 一手证据(研究域20) / 反证(研究域20) / 定向深挖(研究域20)|FY3/26 results release, capital expenditure and construction in progress;直接证据 / 一手证据(研究域17) / 外部现实(研究域19)|FY3/27 interim results release, consolidated cash flow statement;直接证据 / 支持证据 / 一手证据(研究域26) / 一手证据(研究域35) / 历史/同业比较(研究域26)|FY3/26 full-year results release, dividends and initial FY3/27 forecast;直接证据 / 支持证据 / 一手证据(研究域25) / 定向深挖(研究域24) / 定向深挖(研究域25)|FY3/26 results release, treasury-share purchases and disposals;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域25) / 反证(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域35)|FY3/26 results release, dividend record and payout ratios;直接证据|FY3/27 interim results release, share counts;直接证据 / 支持证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 支持证据 / 一手证据(研究域24) / 外部现实(研究域13) / 反证(研究域24) / 定向深挖(研究域13) / 定向深挖(研究域24) / 定向深挖(研究域34)|JINGI company page for 7299: shareholder and float indicators;直接证据 / 支持证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026;直接证据 / 一手证据(研究域06) / 一手证据(研究域23) / 外部现实(研究域23)|Disclosure concerning the controlling shareholder (Daido Steel), transactions and governance;直接证据 / 历史/同业比较(研究域23)|J-LiC officer database for 7299: president's career history from the 98th-term securities report;直接证据 / 支持证据 / 一手证据(研究域06) / 反证(研究域06) / 定向深挖(研究域06) / 定向深挖(研究域23)|Controlling-shareholder disclosure: raw-material procurement through the Daido group;直接证据 / 一手证据(研究域23) / 反证(研究域23) / 定向深挖(研究域23)|J-LiC officer database for 7299: board composition and president's background;直接证据 / 支持证据 / 一手证据(研究域33) / 外部现实(研究域07) / 外部现实(研究域20) / 历史/同业比较(研究域30) / 反证(研究域33) / 定向深挖(研究域07) / 定向深挖(研究域33)|IRBANK disclosure index for FUJI OOZX: corporate-action turning points;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域33)|FY3/26 results release, the 2026 medium-term management plan's three themes;直接证据 / 一手证据(研究域07) / 反证(研究域07)|FY3/27 interim results release, notes on significant subsidiary changes and treasury shares;直接证据 / 一手证据(研究域07) / 定向深挖(研究域07)|FY3/26 results release, medium-term plan themes on new-business development;直接证据 / 一手证据(研究域30) / 外部现实(研究域25) / 外部现实(研究域33) / 反证(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域24) / 外部现实(研究域31)|IRBANK stock page for 7299: price, market capitalisation and valuation snapshot;反证 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position
完整研究记录(核对用)
研究原文:Capital allocation under parent control: cash, buybacks, Mexico and the float ceiling|Operating cash flow and an unlevered balance sheet let the company choose between returning cash and building Mexican capacity. Parent control and a float just above the listing threshold bound how far buybacks can go, and there is no stated framework to commit management. The plan-end cluster of actions suggests a policy turn, but only the successor plan can show whether it is a regime.
内部研究类型:capital_allocation_mechanism
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):If the turn compounds, per-share asset value rises mechanically at a discount; if cash accumulates, it cannot.
不确定性(原始记录):No formal capital policy; Daido's holding intention undisclosed.
F069|13|七项待解问题各自限制哪一个判断
研究范围:开放研究+35项覆盖检查
写入正文:13|七项待解问题各自限制哪一个判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(17项,重复标签已合并)
FY3/26 results release, the 2026 medium-term management plan's three themes怎么使用:直接证据;一手验证:33;专项深挖:04、33;同业比较:04、10;其他用途:历史
FY3/26 results release, dividend record and payout ratios怎么使用:直接证据;一手验证:26;反向验证:25、26;专项深挖:26、35
FY3/26 full-year results release, dividends and initial FY3/27 forecast怎么使用:直接 / 支持;一手验证:26、35;同业比较:26;其他用途:历史
IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record怎么使用:直接证据;一手验证:30;外部现实校验:25、33;反向验证:30;专项深挖:30
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接证据;一手验证:05、13;外部现实校验:32;反向验证:05、16、35;其他用途:反证
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/27 interim results release, gross margin bridge怎么使用:直接证据;一手验证:16;专项深挖:16
FY3/27 interim results release, inventory build in the interim period怎么使用:直接证据;一手验证:19;反向验证:17、19;专项深挖:19
FY3/26 results release, working-capital balances怎么使用:直接证据;一手验证:19;专项深挖:19
FY3/27 interim results release, regional demand review怎么使用:直接证据;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
FY3/26 results release, industry outlook in the forecast assumptions怎么使用:直接证据;一手验证:11;反向验证:11;专项深挖:11
FY3/27 interim results release, product and segment description怎么使用:直接证据;一手验证:03;反向验证:03;专项深挖:03、34
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接 / 支持;一手验证:20
FY3/26 results release, capital expenditure and construction in progress怎么使用:直接证据;一手验证:20;反向验证:20;专项深挖:20
JINGI company page for 7299: shareholder and float indicators怎么使用:直接证据;一手验证:24;外部现实校验:13;反向验证:24;专项深挖:13、24、34
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:支持证据;同业比较:17、18、19、25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域04) / 历史/同业比较(研究域10) / 定向深挖(研究域04) / 定向深挖(研究域33)|FY3/26 results release, the 2026 medium-term management plan's three themes;直接证据 / 一手证据(研究域26) / 反证(研究域25) / 反证(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域35)|FY3/26 results release, dividend record and payout ratios;直接证据 / 支持证据 / 一手证据(研究域26) / 一手证据(研究域35) / 历史/同业比较(研究域26)|FY3/26 full-year results release, dividends and initial FY3/27 forecast;直接证据 / 一手证据(研究域30) / 外部现实(研究域25) / 外部现实(研究域33) / 反证(研究域30) / 定向深挖(研究域30)|IRBANK disclosure index for FUJI OOZX: dated catalysts in the disclosure record;直接证据 / 反证 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 一手证据(研究域16) / 定向深挖(研究域16)|FY3/27 interim results release, gross margin bridge;直接证据 / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域19) / 定向深挖(研究域19)|FY3/27 interim results release, inventory build in the interim period;直接证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/26 results release, working-capital balances;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review;直接证据 / 一手证据(研究域11) / 反证(研究域11) / 定向深挖(研究域11)|FY3/26 results release, industry outlook in the forecast assumptions;直接证据 / 一手证据(研究域03) / 反证(研究域03) / 定向深挖(研究域03) / 定向深挖(研究域34)|FY3/27 interim results release, product and segment description;直接证据 / 支持证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;直接证据 / 一手证据(研究域20) / 反证(研究域20) / 定向深挖(研究域20)|FY3/26 results release, capital expenditure and construction in progress;直接证据 / 一手证据(研究域24)|Disclosure concerning the controlling shareholder (Daido Steel), June 2026;直接证据 / 一手证据(研究域24) / 外部现实(研究域13) / 反证(研究域24) / 定向深挖(研究域13) / 定向深挖(研究域24) / 定向深挖(研究域34)|JINGI company page for 7299: shareholder and float indicators;支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators
完整研究记录(核对用)
研究原文:Research Debt carried to the next Review|All carried questions are bounded by future disclosure or company non-disclosure; none has a reasonable current public path likely to change the Thesis, so Research Stop holds and no reopen is required.
内部研究类型:research_debt_set
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Each debt conditions confidence in a specific mechanism: capital policy, margin quality, H2 bridge, demand tail, China exposure, Mexico return and parent intention.
不确定性(原始记录):Several (Q3 balance sheet, successor plan) are post-cutoff evidence belonging to later Reviews.
F070|06|几乎没有杠杆,但净现金口径要带着保留看
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(21项,重复标签已合并)
FY3/27 interim results release, consolidated balance sheet at 30 September 2026怎么使用:直接 / 支持;一手验证:18
JINGI company page for 7299: net cash, ROIC and cash-flow quality panels怎么使用:直接 / 支持;外部现实校验:17、18
FY3/27 interim results release, liabilities and equity structure怎么使用:直接 / 支持;一手验证:18、25;反向验证:18;专项深挖:18
FY3/26 full-year results release, consolidated balance sheet at 31 March 2026怎么使用:直接 / 支持;反向验证:29;同业比较:20、21、24;其他用途:历史
FY3/26 results release, non-operating asset balances怎么使用:直接证据;一手验证:21;反向验证:21;专项深挖:21
FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators怎么使用:直接 / 支持;同业比较:17、18、19、25;其他用途:历史
FY3/26 results release, working-capital balances怎么使用:支持证据;一手验证:19;专项深挖:19
FY3/27 interim results release, qualitative review of operations and financial position怎么使用:直接 / 支持;一手验证:05、13;外部现实校验:32;反向验证:05、16、35
FUJI OOZX company profile: market position, plants and subsidiary history怎么使用:直接 / 支持;一手验证:09;反向验证:01;同业比较:03、07、08;其他用途:历史
FY3/26 results release, industry outlook in the forecast assumptions怎么使用:直接证据;一手验证:11;反向验证:11;专项深挖:11
FY3/27 interim results release, regional demand review怎么使用:直接证据;一手验证:05;外部现实校验:02、08、11、12;专项深挖:05
FY3/26 full-year results release, dividends and initial FY3/27 forecast怎么使用:直接证据;一手验证:26、35;同业比较:26;其他用途:历史
FY3/26 results release, treasury-share purchases and disposals怎么使用:直接证据;一手验证:25;专项深挖:24、25
FY3/26 results release, dividend record and payout ratios怎么使用:直接 / 支持;一手验证:26;反向验证:25、26;专项深挖:26、35
Notice of production capacity expansion at the Mexican subsidiary怎么使用:直接 / 支持;一手验证:20
FY3/27 interim results release, tariff refund at the Mexican subsidiary怎么使用:直接证据;一手验证:13;反向验证:13;专项深挖:13
FY3/26 results release, capital expenditure and construction in progress怎么使用:直接证据;一手验证:20;反向验证:20;专项深挖:20
FY3/27 interim results release, consolidated cash flow statement怎么使用:直接证据;一手验证:17;外部现实校验:19
JINGI company page for 7299: balance-sheet resilience indicators怎么使用:直接 / 支持;一手验证:29;专项深挖:18、29
JINGI company page for 7299: five-year financial summary compiled from securities reports怎么使用:直接证据;同业比较:02、09、11、15、22、28、29、34、35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18)|FY3/27 interim results release, consolidated balance sheet at 30 September 2026;直接证据 / 支持证据 / 外部现实(研究域17) / 外部现实(研究域18)|JINGI company page for 7299: net cash, ROIC and cash-flow quality panels;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域25) / 反证(研究域18) / 定向深挖(研究域18)|FY3/27 interim results release, liabilities and equity structure;直接证据 / 支持证据 / 历史/同业比较(研究域20) / 历史/同业比较(研究域21) / 历史/同业比较(研究域24) / 反证(研究域29)|FY3/26 full-year results release, consolidated balance sheet at 31 March 2026;直接证据 / 一手证据(研究域21) / 反证(研究域21) / 定向深挖(研究域21)|FY3/26 results release, non-operating asset balances;直接证据 / 支持证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域19) / 历史/同业比较(研究域25)|FY3/26 full-year results release, consolidated cash flow statement and cash-flow indicators;支持证据 / 一手证据(研究域19) / 定向深挖(研究域19)|FY3/26 results release, working-capital balances;直接证据 / 支持证据 / 一手证据(研究域05) / 一手证据(研究域13) / 外部现实(研究域32) / 反证(研究域05) / 反证(研究域16) / 反证(研究域35)|FY3/27 interim results release, qualitative review of operations and financial position;直接证据 / 支持证据 / 一手证据(研究域09) / 历史/同业比较(研究域03) / 历史/同业比较(研究域07) / 历史/同业比较(研究域08) / 反证(研究域01)|FUJI OOZX company profile: market position, plants and subsidiary history;直接证据 / 一手证据(研究域11) / 反证(研究域11) / 定向深挖(研究域11)|FY3/26 results release, industry outlook in the forecast assumptions;直接证据 / 一手证据(研究域05) / 外部现实(研究域02) / 外部现实(研究域08) / 外部现实(研究域11) / 外部现实(研究域12) / 定向深挖(研究域05)|FY3/27 interim results release, regional demand review;直接证据 / 一手证据(研究域26) / 一手证据(研究域35) / 历史/同业比较(研究域26)|FY3/26 full-year results release, dividends and initial FY3/27 forecast;直接证据 / 一手证据(研究域25) / 定向深挖(研究域24) / 定向深挖(研究域25)|FY3/26 results release, treasury-share purchases and disposals;直接证据 / 支持证据 / 一手证据(研究域26) / 反证(研究域25) / 反证(研究域26) / 定向深挖(研究域26) / 定向深挖(研究域35)|FY3/26 results release, dividend record and payout ratios;直接证据|FY3/27 interim results release, share counts;直接证据 / 支持证据 / 一手证据(研究域20)|Notice of production capacity expansion at the Mexican subsidiary;直接证据 / 一手证据(研究域13) / 反证(研究域13) / 定向深挖(研究域13)|FY3/27 interim results release, tariff refund at the Mexican subsidiary;直接证据 / 一手证据(研究域20) / 反证(研究域20) / 定向深挖(研究域20)|FY3/26 results release, capital expenditure and construction in progress;直接证据 / 一手证据(研究域17) / 外部现实(研究域19)|FY3/27 interim results release, consolidated cash flow statement;直接证据 / 支持证据 / 一手证据(研究域29) / 定向深挖(研究域18) / 定向深挖(研究域29)|JINGI company page for 7299: balance-sheet resilience indicators;直接证据 / 历史/同业比较(研究域02) / 历史/同业比较(研究域09) / 历史/同业比较(研究域11) / 历史/同业比较(研究域15) / 历史/同业比较(研究域22) / 历史/同业比较(研究域28) / 历史/同业比较(研究域29) / 历史/同业比较(研究域34) / 历史/同业比较(研究域35)|JINGI company page for 7299: five-year financial summary compiled from securities reports
完整研究记录(核对用)
研究原文:The balance sheet bridges the two clocks|The powertrain clock shrinks the niche over years, while about JPY 6bn of net cash and an 85% equity ratio let the company return capital and fund the Mexico transition without asking the market for money in the meantime.
内部研究类型:cross_domain_bridge
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Time is financed internally; the question is whether it is used.
不确定性(原始记录):Cash definitions differ across sources.
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | 07c340172c03146c55b0ece8f33bef8074da87f3 |
| Delivery Commit SHA | 07c340172c03146c55b0ece8f33bef8074da87f3 |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | 42db5839-3fc8-5e65-9c2f-5346d46958ea |
| Canonical Revision | 1 |