现金、存款和投资证券合计456.68亿日元,相当于市值的108%;公司无借款,自有资本比率89.2%。阴极块靠认证和使用记录守住地位,2026年3月期销量大跌时毛利率仍在31%以上。每股100日元的分红下限在亏损年度也没有改动,按现价股息率4.90%;2026年回购已完成,并出现首次证券出售。
5304
SECカーボン株式会社(SEC Carbon, Ltd.)
公司一句话:SECカーボン株式会社(SEC Carbon, Ltd.,东证 Standard 市场,代码5304)主营铝电解用石墨化阴极块,同时生产电炉炼钢用的人造石墨电极、碳素特种制品和微粉;总部在兵库县尼崎,主要工厂在京都府福知山和冈山。2026年3月期(FY3/26)销售额中,阴极块占67.5%,电极占17.9%,碳素特种制品占11.5%,微粉及其他占3.1%。 估值简报:股价2,042日元(2026年11月6日收盘)/总市值422.6亿日元(按已发行股数,含库存股)。预测 PER 13.6倍(公司指引每股收益149.64日元)/实绩 PBR 0.53倍(2026年3月期末每股净资产3,871.46日元)。ROE 实绩-0.1%(2026年3月期,净亏损年度),预测3.87%(推算)/预测股息率4.90%(每股100日元)。EV/EBITDA 4.1倍。EV=总市值+净有息负债;公司无借款,按2026年6月30日净现金176.0亿日元扣减,得246.5亿日元。EBITDA=2026年3月期营业利润40.08亿日元+折旧20.48亿日元=60.6亿日元,两者期间口径不同。
最近亮点:2026年3月期营业利润下降41.3%至40.08亿日元,电极设备计提减值60.63亿日元,全年净亏损0.74亿日元,营业现金流却上升71%至77.66亿日元。2027年3月期第一季度阴极块销售额上升51.8%,其中含中东发货顺延;公司指引原样保留。中期决算预计在11月12日至13日发布,评审日尚未公布。
阴极块去库存若再度反复,或冶炼厂再次推迟换衬,周期这一条腿就会消失,而新完工设备已把固定成本抬高,低谷会更贵。订单量和换衬计划没有披露,第一季度的反弹里还含发货顺延。另一条腿同样没有保证:控股集团是否愿意把金融资产转成每股价值,没有时间表,也没有意图声明。
结论:Kabugami 评分61.39/100(V3.2),评级 B;以持有或小仓位分批为主,不追价。资产覆盖和约5%的分红提供了安全垫,但低谷利润上并不便宜,技术面也还没有确认。 关键依据:现金与证券已超过整家公司的市值,价格反映的是对资本政策的折价;2026年的废止计划、减值、回购和证券出售既可能是方向转变,也可能只是一组一次性事件,目前无法区分,阴极块订单与控股集团意图均未披露。 翻转条件:中期决算若出现指引下调且阴极块销量下降,或出现阴极块相关资产减值、分红公式下调,应重新评估甚至退出;出现有数字的库存股注销、证券出售或分红下限提高,可逐步加仓。 当前动作:以持有或小仓位分批为主,不追价。估值与资产覆盖提供了约5%的分红和较大的安全垫,但低谷利润上并不便宜,技术面也没有给出确认。预计11月12日至13日发布的中期决算是最近的检验:重点看阴极块销量是否超过指引隐含的偏弱第二季度,以及全年指引能否保持。若阴极块销量延续、同时出现有数字的库存股注销、证券出售或分红下限提高,可以逐步增加;若指引下调且阴极块销量下降、出现阴极块相关资产减值或分红公式被下调,应重新评估甚至退出。薄流通股意味着建仓和退出都要控制规模。
报告目录
01|投资问题与当前结论
01.1|股价在押一个治理问题,周期只是第二个期权
这只股票的价格,更像是对一个治理问题的预测。2026年11月6日收盘2,042日元,总市值422.6亿日元;2027年3月期第一季度末,现金、存款和投资证券合计456.68亿日元,相当于市值的108%。按市场定价,工厂、土地和存货等于白送。
资产既然已经盖过了整家公司的价格,问题就变成:这堆金融资产何时、以什么方式变成每股价值。研究下来,有两个有日期的过程可能先后兑现。一个是阴极块的更换周期,销量回升并带出营业杠杆,要在2027年3月期下半年的数字里看到。另一个是2030年框架里的资本政策支柱,把现金和证券转成回购、注销或分红,规模要大到少数股东量得出来。两者基本独立。
等待期间有补偿:公司指引每股100日元分红,按现价股息率4.90%。这个判断有两处没有定论。资本转化一条没有期限,控股集团的意图也没有披露;周期一条要靠评审日之后的季报来检验。
01.2|两条腿各自会倒,只有阴极块资产减值会伤到根本
投资结论是一个并列条件:低谷加转化期权。任何一条腿失败,只拿走一部分价值,另一条腿重新定价;唯一例外是阴极块相关资产减值,那会动摇现金牛本身。两条腿都不兑现时,每股100日元的分红和缓慢回购只是持有收益,不构成催化剂。
最强的反证来自两个方向。一是阴极块去库存若复发,或冶炼厂再次推迟换衬,周期这条腿就没有了,只剩持有收益。二是2026年的一连串动作——废止中期计划、减值、回购、首次出售证券、更换代表董事——可能只是一组一次性事件。
两种看法现在都说得通。若是方向转变,今天的价格是对一项会重估资产的低谷定价;若是一次性事件,对周期股而言价格大体公允。中期决算、全年决算和后续有没有新的资本政策工具,才能把两者区分开。历史上这家公司每一次转折都由产品周期带来,2026年是第一次管理层和股东名册层面的动作多过周期事件,这一点是否持续,现在无法判断。
01.3|什么会推翻这个判断
推翻条件全部定义在公司披露和财报数字上,不定义在股价上:价格可以推翻时机,推翻不了判断。
五个可观察的信号:中期决算下调指引,同时阴极块销量下降;出现第二次减值,或任何阴极块相关资产的减值,后者直接攻击核心业务;分红公式被下调;证券组合原封不动、回购停止,一直持续到2028年3月期;在大型换衬项目中出现份额流失的证据。
每个信号拿走一条腿,由另一条腿重新定价。控股集团的意图是剩下的未知数,没有任何披露制度要求它说明。当前操作倾向:持有或小仓位分批,不追价;若阴极块销量延续、同时出现有数字的库存股注销、证券出售或分红下限提高,可以逐步增加;流通股很薄,建仓和退出都要控制规模。
02|公司本质与商业模式
02.1|三分之二的收入押在一个产品的更换周期上
SECカーボン株式会社(SEC Carbon, Ltd.)是1934年创立的独立碳素制品厂商,总部在兵库县尼崎,生产集中在京都府福知山工厂,另有冈山工厂。合并员工约270人,人均销售额0.93亿日元,是资本和工艺密集型的材料企业。
公司只有一个报告分部,按产品披露:2026年3月期销售额251.01亿日元,其中铝电解用石墨化阴极块(SK-B)169.49亿日元,占67.5%;人造石墨电极44.82亿日元,占17.9%;碳素特种制品28.96亿日元,占11.5%;微粉及其他7.72亿日元,占3.1%。
阴极块在铝冶炼厂电解槽翻修和新建冶炼厂时消耗,电极用于电炉炼钢。公司把通过认证的耗材,卖进别的行业的维护和运行日历:约73%的销售在海外,57.8%经由住友集团的一家贸易渠道。股东因此持有的是同时受铝业维护周期和钢铁开工影响的企业,其中前者占大头。
分产品利润没有披露,模式只能在收入和集团毛利率层面描述。公司的英文名称来自日经公司概况和 EDINET 文件头。
02.2|合并范围基本等于母公司,没有隐藏的子公司利润
母公司单体销售额245.22亿日元,占合并的97.7%,少数股东权益只有0.14亿日元,所以集团在经济上就是母公司加几家小子公司,不存在需要另外加总的子公司价值,也没有少数股东分走利润。
唯一值得一提的是日本电极(Nippon Denkyoku):2026年3月期公司买入这家电极行业小型关联公司的股份并纳入权益法,当年亏损0.16亿日元,2027年3月期第一季度亏损0.47亿日元。这笔投资发生在公司自己的电极设备被减值的同一年。它的战略目的在已读文件中没有说明,规模目前可以忽略。
02.3|企业耐久,股票有条件
把各部分拼起来,持久的核心是一家通过认证的耗材企业,外面裹着一层资本过剩的、由关系股东持有的外壳。阴极块靠认证和使用记录进入全球铝冶炼厂,并在二十世纪的工艺积累上生产;外壳是89%的自有资本、零借款和456.68亿日元的金融资产,使公司可以等过任何客户主导的周期。
脆弱点同样是结构性的:三分之二收入跟着一个产品的维护日历;第二块业务已被正式减值;四分之三的销售出口,且集中在一个渠道;控股的股东名册还没有以可测量的速度把外壳转成每股价值。企业层面的自我修复能力很强,最坏情形需要阴极块业务本身断裂、控股集团卖股,或一次重大的投资失误。
护城河的证据来自利润率的表现,产品利润、合同和独立份额数据读不到,所以这是推断,不是验证过的事实。
03|产品、客户与供应链
03.1|一个产品的更换周期,决定了这家公司的利润表
阴极块占销售额67.5%,在铝冶炼厂电解槽翻修或新建冶炼厂时消耗,需求以项目为单位成块出现,集中在中东、加拿大、巴西和亚洲。2026年3月期的地区销售额是:日本67.45亿日元(占26.9%),美洲58.88亿日元(加拿大27.57亿日元、巴西27.27亿日元),亚洲和中东76.31亿日元,欧洲18.49亿日元,其他地区29.86亿日元。
2026年3月期阴极块销售额下降23.0%,原因是冶炼厂更新放缓,以及客户去库存拖得比预期更久。固定成本摊在更少的收入上,集团营业利润因此下降41.3%。先出问题的是周期,竞争和成本都不是第一原因。日元走弱增厚了出口收入,把一部分下滑盖住了;日元一旦回升,或去库存复发,销量低谷的真实深度才会暴露。
2027年3月期第一季度,阴极块销售额37.74亿日元,上升51.8%。公司说冶炼厂的库存调整已转向解决,同时部分中东发货从上一季度顺延而来,所以反弹里有一部分是发货时点,不全是销量斜率。订单、在手订单和冶炼厂换衬计划都没有披露,这是当前读不出的一块。其余产品线分化:电极8.19亿日元,下降18.9%;碳素特种制品7.27亿日元,上升5.1%;微粉及其他2.21亿日元,上升16.4%。
03.2|住友集团既是57.8%收入的出口,又是5.02%的股东
Sumisho CRM(住友商事集团的碳素原料公司)2026年3月期承接145.14亿日元销售额,占57.8%;上一年是207.68亿日元,占66.6%。比例下降只是因为渠道里最集中的阴极块跌得最多。阴极块周期回到高点时,三分之二的收入会再次经过同一家对手方的账本,所以这种集中在程度上随周期,在性质上是固定的。
住友商事同时持有5.02%的股份,利益方向一致,但这并不能消除住友集团碳素战略、信用条件或渠道利润分配改变带来的风险。商业条款、渠道的利润分成,以及对住友集团策略变化的承受力,都无法从财报中检验。到目前没有观察到不利事件。
03.3|订单数据缺位,是判断复苏斜率的最大缺口
阴极块去库存是否真的结束,决定营业利润能否恢复,也决定新增固定成本是杠杆还是负担。第一季度的反弹含发货顺延,订单量和下半年、2028年3月期的换衬安排又没有披露,所以复苏斜率现在无法确认。
如果去库存复发,周期这条腿失败;如果已经结束,更高固定成本基数上的营业杠杆会很陡。能回答这个问题的是中期决算里的分产品销售额,以及之后任何订单或换衬计划的披露。
04|竞争格局与产业关系
04.1|周期处在复苏早期,但这家公司的低谷可以拖两年
2024年3月期是本轮周期的高点。用2025年3月期财报的同比数字倒推,当年销售额为373亿日元,营业利润102亿日元;两年下来销售额减少约三分之一,经常利润减少一半。经常利润在十年里有两次五倍级的摆动:2019年3月期171.09亿日元,2021年3月期34.93亿日元,2024年3月期115.55亿日元,2026年3月期56.83亿日元。上面的高点数字是倒推所得,不是披露原值。
低谷内部的形状是逐季回升:2026年3月期第一季度营业利润6.09亿日元(利润率13.9%),第二季度9.70亿日元(16.4%),这是管理层说第一季度是底部的全部依据。当前周期是分裂的:阴极块订单已经转向,电极仍在下跌。按三到五年从谷底到顶峰的规律,位置在复苏早期;但过去两年的下滑说明,这里的低谷可以持续整整两年。
第二季度阴极块销量是否确认拐点,还是第一季度只是发货时点,决定这个判断。没有读到行业整体销量数据。
04.2|同业利润增长27.0%,行业疲弱不能当作借口
规模更大的同业东海碳素(Tokai Carbon,5301)11月5日公布2026年12月期第三季度累计业绩:销售额增长15.3%,营业利润增长32.0%,经常利润增长27.0%,全年指引保持。增长由炭黑和精细碳素带动。
这排除了碳素行业整体疲弱的解释:SEC Carbon 的弱势来自电极和阴极块换衬日历这两项公司层面的暴露。同时,也要承认东海碳素的产品更广(炭黑、工业炉等),可比性只是部分成立,也没有读到独立的份额数据。反过来说,行业景气不会为公司的未达预期兜底。
04.3|电极是被进口价格定价的业务,减值承认了这一点
2026年5月14日,公司对人造石墨电极制造设备计提60.63亿日元减值,理由是市场环境变化使设备可回收金额低于账面价值。这是管理层首次明确承认,两项传统业务里有一项撑不住账面价值,它不是阴极块。
电极的长期方向其实有利:电炉炼钢靠废钢和脱碳在抢份额。但当下边际价格由中国和印度的低价进口品决定,同时粗钢产量疲软。2026年3月期电极销售额只下降0.9%,是靠价格和产品结构硬撑出来的,减值等于说这种防守在现有账面价值下维持不下去;2027年3月期第一季度电极销售额下降18.9%。
减值之后电极业务是收缩产能、退到有利润的规格,还是按减值后的成本继续运转,公司没有说明,海外产能退出和进口价格走势也没有观察到。
05|护城河判断
05.1|护城河来自认证和失败成本,证据是利润率而非合同
阴极块的壁垒是认证带来的在位优势。阴极块一旦失效,冶炼厂要损失一个电解槽,所以通过认证的供应商能一直留在换衬日历里,竞争靠的是使用寿命和交货可靠性,不是每吨价格。
证据是利润率的行为:2026年3月期销量大跌,毛利率仍有31.2%,近几年区间在31%至36%,营业利润率16%。诀窍体现在工艺、设备和人员里,不容易短期复制。两条产品线在同一个周期里结果不同,因为竞争场地不同:阴极块比的是认证,电极比的是价格,所以后者出现了减值,前者没有。
这条护城河是从利润率和失败成本的逻辑推断出来的,没有读到合同条款或独立份额数据。侵蚀会很慢:来自对手多年认证成功,或冶炼技术变化;同样的保守性也让新产品导入变慢,限制了从这条护城河里扩张出新的利润来源。在某个大型换衬项目里出现份额流失的证据,会是最直接的推翻信号。
05.2|耐久对企业成立,对股票有条件
这家公司熬过了2008年金融危机(这一点来自背景资料,不是本次读到的一手文件)、电极超级周期的上升和崩塌,以及两年的客户去库存,在最差的近年仍保持16%的营业利润率。89%的自有资本、零借款和456.68亿日元的金融资产,使它可以等过任何客户主导的周期。
但企业能活下来,和股价能反映这份耐久是两回事。三分之二的收入跟着一个产品的维护日历,第二块业务已被减值,四分之三的销售经一个渠道出口,而控股的股东名册还没有以可测量的速度把外壳转成每股价值。股票的耐久,取决于富山和董事会里的决定,而不是炉子里的事。
06|财务质量与现金流
06.1|账面亏损是承认,不是现金事件
2026年3月期的数字乍看像崩盘:销售额251.01亿日元,下降19.5%;营业利润40.08亿日元,下降41.3%;经常利润56.83亿日元,下降26.3%;全年净亏损0.74亿日元。经常利润已连续两年下滑,2024年3月期约115.55亿日元,2025年3月期77.16亿日元(后者数字由同比比例推出)。
从营业利润到净亏损的距离,几乎都是那笔60.63亿日元的减值。公司还入账了18.52亿日元的递延税调整收益,税金科目因此净回收3.49亿日元,才把税前亏损4.23亿日元收窄成0.74亿日元的净亏损;这笔税收益由减值本身产生,不会重复。综合收益是58.31亿日元,因为证券估值收益把它撑了起来。
电极设备被减掉的账面价值,也会机械地降低以后这条线的折旧,所以电极业务出现更小的亏损甚至小幅盈利,是预料之中的算术,只有价格或销量的改善才算复苏。折旧节省额没有按产品线披露。减值后的电极去向,也就是缩产、转向可守规格还是原样运转,公司没有交代。
06.2|利润率下降来自销量,不来自成本
2026年3月期毛利率从35.6%降到31.2%,原因是固定生产成本摊在少了19.5%的收入上。销售管理费减少4.56亿日元,降到38.13亿日元,营业利润率仍从21.9%降到16.0%。销量一回来,杠杆会很快显现;但2027年3月期第一季度销量大增,毛利率却只回到32.1%,煅烧焦、无烟煤、沥青和电力的涨价抵消了一部分收益。
折旧也在抬高固定成本:从13.04亿日元升到20.48亿日元,第一季度单季4.30亿日元。价格能否传导,只能从毛利率里看到;原料和能源的价差对利润的影响,没有被单独剥出来,产品别利润和供应合同也没有披露。
06.3|经常利润里有约三分之一不是卖碳素赚来的
2026年3月期营业外收益17.16亿日元,其中分红8.45亿日元、补助金4.45亿日元(上一年仅0.26亿日元)、汇兑收益1.89亿日元、利息1.31亿日元,把经常利润推到比营业利润高出42%。碳素业务本身的经常性营业层面利润,大致在40亿至44亿日元之间。
这个数字里叠着三种耐久性不同的利润:阴极块的营业利润率(随周期,但是真实的)、电极的利润率(已减值,有争议)、金融收益(稳定,与经营无关)。任何从经常利润出发的正常化,都会继承这份美化。补助金是否会持续,已读文件中没有解释。
另有四项披露事项在经营现实和账面利润之间:电极减值(是经济意义上的承认,不是装饰);减值带来的18.52亿日元递延税调整收益(不会重复,使2026年3月期的净利润比2027年3月期的正常税负更好看);4.45亿日元补助金;以及2026年6月19日对该期财报的数字部分更正。这些事项都没有显示隐瞒,会计整体偏保守并附有说明。更正通知的具体数字和税务、补助注释没有逐行核对,2026年6月19日提交的证券报告附注是参考依据。
06.4|亏损年度反而更有现金,复苏年度现金会被吸走
2026年3月期营业现金流上升71%,达到77.66亿日元,原因是60.63亿日元的减值和20.48亿日元的折旧都不涉及现金,缴纳的现金税降到10.73亿日元,销量下降时应收和库存还会释放出资金。公司在亏损年度比盈利年度更有现金。
同一个机制反着走:应收账款约94亿日元,应付只有19.34亿日元,净应收近74亿日元,约占一年销售额的30%,再加上182.52亿日元的存货(其中在制品117.66亿日元,占年销售额的47%)。上行期占用现金,所以2025年3月期营业现金流45.48亿日元,低于经常利润77.16亿日元;下行期释放现金,2026年3月期77.66亿日元,高于经常利润56.83亿日元。
当年投资现金流是-71.39亿日元:有形资产购置35.67亿日元、投资证券购入19.59亿日元、定期存款净转入15.70亿日元;融资现金流-20.11亿日元,基本是20.04亿日元分红。现金及现金等价物36.13亿日元,低于资产负债表上的175.33亿日元现金和存款,差额是三个月以上的定期存款。
反向已经开始:2027年3月期第一季度应收减少23.88亿日元,每一层存货都在增加,应付增加5.09亿日元,是工厂在为销量回升备货。复苏期利润不会一比一变成现金,存货增加本身也不能当作需求证据;2027年3月期现金被重新占用的速度,尚无依据判断。收入层面,换衬不能无限期推迟,2026年3月期的下降有一部分是递延而不是丢失,但如果冶炼厂永久关闭,递延就会变成损失,目前没有关闭的证据。
06.5|没有借款的资产负债表:金融资产比有形资产还大
2026年3月末总资产870.16亿日元,净资产776.28亿日元,自有资本比率89.2%,没有借款,有息负债对营业现金流的比值连续五年为0.0年。现金和存款175.33亿日元加投资证券278.13亿日元(估值准备149.24亿日元),占总资产52%,而有形固定资产净额只有133.16亿日元。
到2027年3月期第一季度末,现金与证券合计456.68亿日元。自有资本比率在2024年3月期的重投资阶段降到83.0%,之后靠留存收益和估值收益恢复,没有发新股。
同一个事实有三个价格:它是下行防御,也是股本回报率的天花板,还是低市净率的来源。这种结构的把握较高,因为数字来自报表。限定条件是:证券按市价,土地和设备按历史成本;持仓名单和取得成本在证券报告附表里,第一季度的证券估值部分来自关系持股,未必能自由出售,变现还要付税费和关系成本;市值分母包含库存股。
07|股东、董事与治理
07.1|股东名册就是折价:控股集团加两家商社
股东名册是折价的来源。大谷钢业(Otani Steel Corporation)持有19.85%,每年提交控股股东报告,大谷家族的实体和个人一并提交大量持股报告;三菱商事持有9.78%,住友商事5.02%(后者还经手58%的销售);日本信托银行信托账户4.89%,日本碳素4.06%,三菱UFJ银行2.66%,大和工业2.38%,日铁工程2.09%,股东共4,922人。以上持股数据截至2026年3月31日。
有效流通股很薄:截至11月6日,五日平均成交量约5.9万股,7月17日的融资买入余额是融券的20.96倍;11月6日在没有财报消息的情况下,13.49万股成交(比常态多75%)就让股价下跌4.18%。这样的结构两头都稳:没有内部机制推动折价收窄,也没有被迫卖出的人。
控股集团对这笔持股的长期意图没有披露,2026年6月更换代表董事是否改变了资本配置议程,同样没有说明。年内持股变化只能通过大量持股报告看到,融资融券数据是7月17日的快照。这一环节很可能长期无法靠披露解决。
07.2|股东名册和证券组合互为镜像
日本碳素(同业,上市公司)持有4.06%,钢铁企业大和工业持有2.38%,银行和商社遍布其中;公司自己的投资证券278.13亿日元,估值收益占一半以上,主要来自长期持有的关系股。这张网既是名册的缓冲垫,也是折价的发动机:它挡住了敌意的变革压力,也保证流通股无法把变革提前定价。
住友集团同时是57.8%收入的渠道和5.02%的股东,商业依赖和名册稳定是同一种关系在两张表里的两面。保护免受冲击,与单一对手方的暴露,一起出现。
2027年3月期第一季度的证券出售带来5.27亿日元收益,是本次研究里看到的第一次主动减持。持仓名单、取得成本,以及哪些是互相承诺的持股,没有读到,所以这张网到底有多松,没有证据。
07.3|2026年管理层的动作偏积极,但规模都不大
2026年的治理日历很密。4月10日废止中期计划,4月24日提交控股股东报告。5月14日同日公布决算、减值、回购授权和分红决定。6月8日宣布更换代表董事(6月26日股东大会前),6月19日对财报数字部分作更正。6月至8月每月发布回购进度,9月16日宣布回购完成。
董事会是在控股集团划定的边界内争取可信度:在公告里承认失败,而不是粉饰。新任管理层的议程在已读文件里没有说明,董事会构成和治理报告也没有重新逐项核对,新管理层第一个完整年度的业绩还没有出来。
07.4|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回
2026年4月10日,公司废止了第九个三年中期计划,改为“2030 Make Real”:2031年3月期目标为销售额540亿日元、营业利润100亿日元、ROE 12%,两个支柱是强化增长战略和推进资本政策。被废止的计划曾以2027年3月期销售额440亿日元、营业利润80亿日元为目标,一个月后公布的2027年3月期指引是265亿日元和34亿日元,分别低了40%和58%。
连计划文件自己对2026年3月期的展望(销售额292亿日元)也比实绩(251.01亿日元)高出14%,而且发布只比财报早五周,说明近期预测有乐观偏差。2031年3月期销售额目标比2026年3月期的两倍还多,在成熟、增长缓慢的市场里,意味着要么份额上升,要么出现一轮超级周期,要么两者兼有。所以它更像一项要靠财报重新赢回的愿望,不是路径。
增长从哪里来,公司没有说明。特种碳素和微粉合计只占销售额的14.6%,它们能否大到对540亿日元目标有意义,目前没有依据。
07.5|2026年是方向转变,还是一组一次性事件
历史上这家公司的每一次转折都是产品周期带来的:2019年3月期的超级周期及回吐,2024年3月期的第二个高点。2026年第一次出现管理层和股东名册的动作多过周期事件:废止计划、减值、回购、证券出售、更换代表董事。
看法A:这是转向资本和治理,今天的价格是对一项会重估资产的低谷定价。看法B:这是一组一次性事件,价格对周期股大体公允。两者目前无法分辨,中期决算、全年决算以及后续是否出现新的资本政策工具,才能区分,沉默本身就是B的证据。
08|资本政策
08.1|分红下限在亏损年度也没动,波动由分红比例吸收
分红政策是每股100日元与合并分红比例30%中取高者。2025年3月期和2026年3月期各支付20.04亿日元,亏损年度公式不变;2027年3月期预测每股100日元(中期50日元、期末50日元),对应预测分红比例66.8%,起作用的是下限条款,不是比例条款。
对净资产的分红率,2025年3月期是2.8%,2026年3月期是2.6%;按11月的价格是4.9%的股息率。因为每股100日元照付,盈利波动被推到分红比例里,没人交易的指标吸收了冲击,股息率和价格底部保持稳定。需要盯住的是分红比例上升。公式只有董事会修改才会下调,是否有一天上调,是目前还没看到的信号。
08.2|回购方向已经打开,规模太小,推不动折价
2026年5月14日(公布业绩当天)授权的回购,第一季度买入207,500股、5.29亿日元(均价2,549日元左右),9月16日完成;2024年6月和9月也有场外回购。库存股从646,695股增至854,195股(占已发行股份的4.1%),发行股数保持20,694,340股,加权平均股数从20,135,249股降到19,975,434股。2026年的平均买入价比11月6日收盘价高约25%。
按约2,549日元回购,对应每股净资产3,871日元,是向留下的股东转移价值;但每年5亿至10亿日元的节奏,只能让776亿日元的净资产收缩约1%。2027年3月期第一季度净利润12.24亿日元,净资产却减少0.52亿日元:利润几乎被等额返还,金融资产的堆没有缩小。库存股没有注销,所以回购还是可逆的,每股效应只是部分的;是否注销、是否把有效流通股和 Standard 市场的流动性纳入资本政策,还是把名册稳定本身当作政策,目前没有答案。
08.3|12%的股本回报率目标,隐含着股本要缩小
ROE在2024年3月期是10.8%,计划文件估计2026年3月期为4%至5%(实绩因净亏损为-0.1%),2027年3月期预测3.9%。2031年3月期的12%目标,按现有股本约776亿日元需要约93亿日元净利润,是2027年3月期预测的三倍。
所以这个目标暗含的是两个承诺:利润恢复和股本缩小,而只有第一个有数字。被废止的计划曾把2030年3月期的ROE定为8%,说明管理层原来预期利润这条腿承担大头;新政策把“推进资本政策”列为支柱,却没有量化两者的比例,公司的资本成本估计也没有读到。董事会假设的拆分、有没有中间目标(分红净资产比、总回报率、证券出售金额),决定这个目标是承诺还是愿望,答案要看2027年5月的决算资料或任何阶段性公告。
08.4|资本在换方向:电极减值,同时新设备完工,新工程又开工
2026年3月期公司对电极设备减值60.63亿日元,同一年一项大型设施完工:在建工程从85.05亿日元降到15.52亿日元,机器设备原值增加29.56亿日元,建筑增加10.90亿日元。此后又有新工程开工,2027年3月期第一季度在建工程26.74亿日元,当季增加11.21亿日元。折旧从13.04亿日元升到20.48亿日元,第一季度单季4.30亿日元。
资本在从大宗电极转走,但文件没有说转向什么、预期回报多少,新工程做什么产品、预算多大都没有披露。固定成本的底部在复苏之前先被抬高:阴极块销量兑现,营业杠杆会很陡;落空,低谷就更贵。机器设备原值481.59亿日元,已有90%折旧,旧设备更新的需要也在其中。
08.5|资本政策要有数字,才算催化剂
资本政策支柱只有在带上数字时才变成催化剂:注销库存股、量化的证券出售计划、上调分红下限,或以亿日元而不是千万日元计的回购。2026年的记录(回购完成、首次出售证券、ROE目标)说明这些工具没有被堵住,所以下一次任何一项披露都会直接重估折价。
这三件事目前都没有明显移动股本,这正是价格定价的缺口。证券出售、库存股注销、更大回购、更高分红下限能否出现,什么时候出现,没有时间表;能回答的是有数字的公告、2027年5月的分红决定,以及2027年6月证券报告里的明细。上文所说的关系持股网络(278.13亿日元证券)既是折价的来源,也是这些工具能动用的最大一笔资源。
09|估值与安全边际
09.1|低谷利润不算便宜,资产却被打了五折
2026年11月6日收盘2,042日元(当日下跌4.18%),总市值422.6亿日元,按已发行20,694,340股计算,含库存股;9月回购完成后库存股比例可能高于第一季度末的4.1%,扣除库存股后市值会略低。预测市盈率13.6倍(公司指引每股收益149.64日元),实绩市净率0.53倍(PBR;IRBANK 显示0.52倍),预测股息率4.90%,EV/EBITDA 4.1倍。
2026年3月期 ROE 实绩-0.1%,预测3.87%。
同一个价格有两种面孔。按2027年3月期预测净利润30亿日元,倍数近14倍,对低谷利润并不便宜;按近五年平均经常利润72.7亿日元(税前),市值不到其6倍。两个倍数的差距,是市场给周期性开出的价。
EV/EBITDA 的口径不统一:EV 用2026年6月30日净现金,EBITDA 用2026年3月期全年;净现金与前文“现金加证券”的口径也不同,后者包含关系持股。没有读到机构一致预期,11月6日之后的价格变化也没有计入。
09.2|折价是对资本政策的折价,不是对破产或业务的折价
市场对低谷期营业利润给的倍数不算低,对资产负债表却只给约五折,这种组合只有在折价被预期长期存在时才讲得通。2022年3月期到2026年3月期,公司按市值计算的自有资本比率在38.1%到60.9%之间,市场从未把公司估到账面净资产的约六成以上。
折价的来源在股东名册:19.85%的控股股东来自创业家族的钢铁公司,两家商社合计近一成,销售渠道集中在住友集团一家,约450亿日元的金融资产只按存款和分红的收益率增值。市场定价的是这堆资产永远不会变成每股价值的概率。
反方证据同样存在:2026年的回购和首次证券出售说明工具没有被堵死,折价可能在没有宣布任何计划的情况下收窄。时间无法判断。
09.3|正常化后,业务层面的税前盈利能力在55亿至60亿日元
2022年3月期至2026年3月期的经常利润分别为37.79亿、76.10亿、115.55亿、77.16亿、56.83亿日元,五年均值72.69亿日元,三年均值83.18亿日元。由于内含每年13亿至17亿日元的金融收益(分红、补助金和汇兑),业务层面的周期中值税前盈利能力更接近55亿至60亿日元,市值约是其7倍。
过去十年没有出现经常利润层面的亏损年度,范围在35亿至171亿日元。但五年窗口里包含一次超级周期的下滑和一个低谷,均值要在2019年3月期式的高点和2021年3月期式的谷底同样可能再现时,才算公平的周期中值。2025年3月期之前的营业利润序列没有完整披露,所以营业层面的区间是由经常利润和2026年3月期营业外明细推出来的,不是精确序列。
09.4|下行保护有三层,风险是时间而不是本金
下行保护是财务性和结构性的:每股账面价值3,871日元对应2,042日元的股价,453亿日元的金融资产,无负债,一笔4.9%的分红,一个没有被迫卖出者的控股名册。三层各自独立:资产覆盖、收入下限、名册稳定。实际的下行是时间:折价持续的年份里只有约5%的持有收益,是机会成本损失,不是本金损失。
三件事会破坏这个保护:控股集团卖股、分红公式被取消、一次灾难性的投资失误。资产覆盖在公式不变的每一年靠留存收益增加。强制清算价值没有估计,证券里有关系持股,变现有成本。
土地方面,总部和京都(福知山)、冈山两处工厂的土地按历史成本12.62亿日元入账,没有披露评估,账面远低于重置成本;它既是隐含的储备,也提醒股权价值要靠盈利能力而不是资产登记簿来支撑。土地的市场价值未知,也没有估计,何况它们要继续用于生产,不能自由分配。
09.5|指引按低谷编制,真正的检验是第二季度阴极块销量
2027年3月期指引(2026年5月14日):销售额265亿日元(上升5.6%),营业利润34亿日元(下降15.2%,连续第三年下降),经常利润44亿日元,净利润30亿日元,每股收益149.64日元,按美元兑日元155编制,明确排除中东局势。中期计划为销售额106亿日元、营业利润11亿日元、净利润13亿日元,第一季度后原样保留。
扣除第一季度实绩,隐含的第二季度销售额约50.57亿日元,营业利润只有3.36亿日元(利润率6.6%);这是对不变计划的算术推算,不是公司指引。第一季度完成了计划销售额的52%、营业利润的69%、经常利润的74%和净利润的94%,但净利润靠5.27亿日元的证券出售收益才到这个水平。计划里要么是刻意保守,要么是真的预期第二季度偏弱,只有阴极块销量这一项无法被一次性因素伪装。
预期由公司自己设定:没有读到卖方一致预期,指引的可信度就是预期机制,而4月的计划废止已经让它受过一次损失。门槛低、一次性美化已被披露、销量无法粉饰,所以对只看标题的人,不对称性偏向怀疑者。当前约13.5至13.6倍的预测倍数,基本是按指引大体诚实来定价的;中期决算里“在预期范围内”的措辞能否延续,目前未知。
10|Kabugami 技术结构
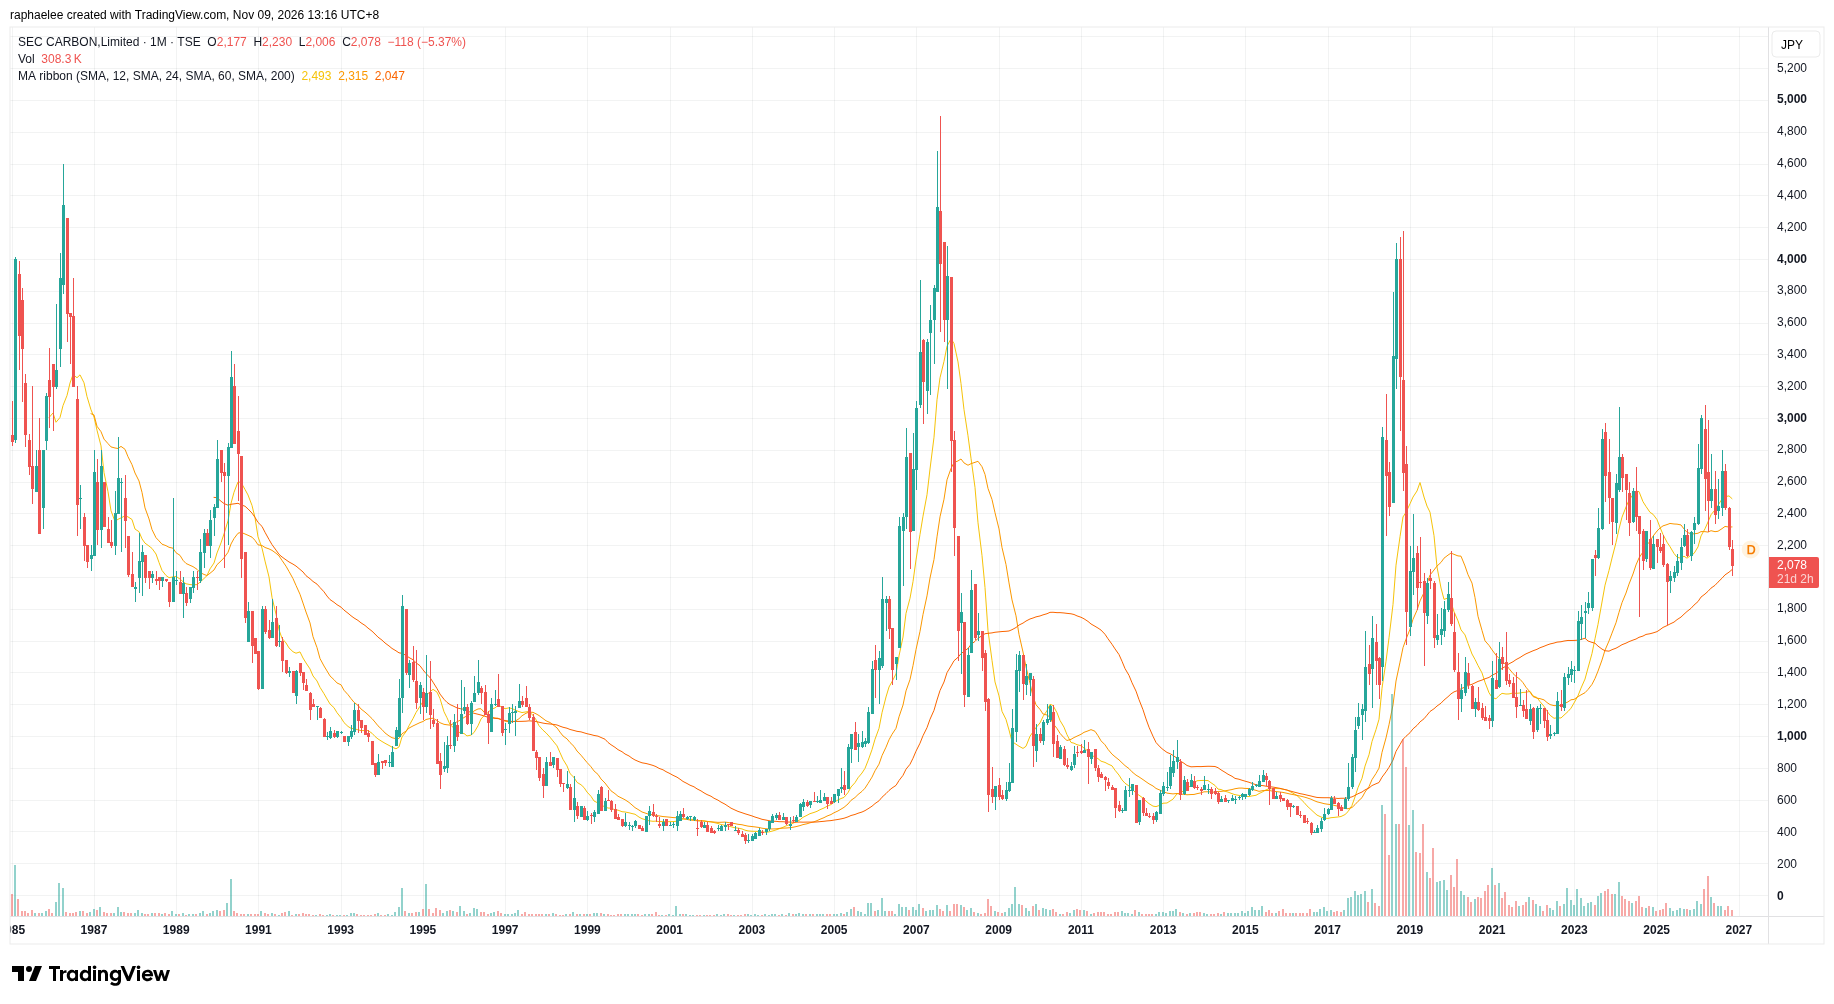
10.1|技术问题:回落停在五年均线,是底部区间在消化冲高,还是前两次冲高后整段回吐的开头
观察点是2026年11月6日的最近一个完整交易日。数据是2000年4月至2026年10月的月线(共319根,以雅虎财经口径的复权价格为基础),其中10月这根月线只走到27日;11月6日收盘价2,042日元取自IRBANK。
先定两个名词。“三年底部区间”指2023年至2025年价格主要运行的1,700至2,400日元一带;“冲高”指2026年1至3月涨到3,085日元的那一段。当前状态本章称为“底部消化”:冲高失败后,价格回落到底部区间上沿,还没有选择方向。
本章要回答的问题是:2026年1至3月的冲高,是这只股票一生中的第三次大冲高,已经失败并回落了七个月,价格现在落在60个月均线(约2,031日元)上,也就是三年底部区间的上沿。这是底部区间在消化冲高的筹码,从这里可以重新搭结构;还是前两次冲高之后整段退回的第一阶段?
10.2|一生三次冲高,前两次整段都还了回去
第一次在2000年到2008年间:2002年11月跌到最低322日元,经过长期整理后,2007年8月冲到历史高点4,900日元,随后完全回吐。第二次在2017年到2019年:价格从约500日元涨到2018年的4,178日元,之后涨幅全部还回去,2020年跌到1,044日元,2020年至2022年在1,000至1,650日元的平台里整理。
两次冲高都是从没有底部支撑的平台起飞,退回时也回到了平台。第三次不同:2023年价格恢复到2,966日元,当年最低1,336日元;2024年最高3,070日元、最低1,750日元;2025年在1,700至2,380日元之间运行,年末收在2,339日元,三年底部区间就是这样形成的,成交量平稳,没有冲高的特征。
2026年1至3月,价格从2,339日元涨到3,085日元(盘中),伴随现代记录里最大的成交量:3月180万股,4月267万股,3月到4月合计447万股。成交最重的4月是下跌月,没有财报消息。此后七个月逐月收低,收盘价从2,487日元降到2,042日元。
10.3|回落在放量见顶之后有序展开,已经走到五年均线
这次冲高的结尾落在原有的三重高点区域(2,966至3,085日元,由2023年、2024年和2026年三次高点构成),而不是开阔的上方空间,成交量在3月至4月达到高潮后逐月收缩,10月只有521,400股。回落是有序的:没有恐慌放量的月份,下跌在接近均线时减速,没有哪个月以扩大的幅度收在上月低点之下。
月线区间也在收窄:9月2,419至2,712日元,10月2,184至2,443日元,价格已压缩到60个月均线上。这种压缩只是波动性的事实,不是方向预测;这只股票历史上,冲高失败后在长期均线附近的压缩,曾向两个方向剧烈解决(2018年向上,2019年向下)。仓位大小应当按这一点来定。
这次与前两次的区别是,冲高从底部区间上起飞,回落至今被底部区间的上沿挡住。冲高被放弃时,成交量正处在高潮;当前这个失败的冲高,在下一根收在3,085日元之上的月线出现之前,都是非基本面买盘的极限。它的后续比前两次温和:价格收在五年均线附近,而不是砸穿底部区间。回撤形状的最终判断,还要看1,700至2,031日元这一带能否守住。
10.4|价格重心就在底部区间中间,上方有三重高点,下方有两层支撑
近年的主要运行区间是三年底部区间,大致1,700至2,400日元;60个月均线(2,031日元)从它中间穿过,价格此刻正在这里,所以当前位置是决策点而不是趋势:底部区间的重心要么接纳冲高留下的残余筹码,要么把它们推开。
下方的支撑依次是:60个月均线约2,031日元,底部区间的下沿1,700至1,750日元(2025年4月7日和2024年的低点),2023年低点1,336日元,再往下是1,000至1,650日元的旧平台。
上方的压力是24个月均线2,315日元,12个月均线2,512日元,然后是2,966至3,085日元的三重高点,三次独立的高点使它成为现代结构里最重的天花板;再往上只剩2018年的4,178日元和2007年的4,900日元,它们仍在图上,但与当前的博弈无关。过去十二个月的成交主要在2,184至3,085日元之间完成,价格若回到2,500至2,700日元,会遇到冲高时留下的成交密集区。
一个结构性矛盾:这只股票的持股支持是一生中最强的,有效流通股却是同类中最薄的,所以价格既最受保护,又最缺乏信息。风险不在高度(离冲高高点已跌34%,在底部区间中段),而在事件之间价格发现本身是停摆的。
10.5|恢复速度、涨跌反应和冲高质量
现在要恢复的不是崩盘,而是冲高:价格比2026年3月高点低34%,比2018年高点低51%。如果价格在11月和明年2月的决算中守住1,700至2,031日元一带,冲高的影响会减半,因为每守住一次,市场的参照点就从3,085日元向底部区间的运行范围靠近一点;2019年到2022年那次更大的冲高,花了几年才完成同样的回归。这是一个尚待验证的条件,不是已经发生的事。
涨跌反应不对称:从底部区间向上走出去,每次都在一个季度内被卖掉(2024年2月高点、2026年3月高点);跌进底部区间的下半部(2025年4月的1,700日元),则在一个季度内被买回。市场信任底部,不信任高度,按它的历史也理性,所以好消息要比坏消息更大才能让价格走同样的距离。
进入底部区间那一段(2023年至2025年)质量很好:价格上行、成交量平常、没有冲高特征。2026年的冲高质量最差:三个月、成交翻倍、直接冲进三重高点、成交量见顶就被放弃。真正的质量要看月线能在2,315日元之上逐步站稳,而且靠基本面消息,不是又一次放量冲高。
10.6|公开事件与价格的时序:价格先走,基本面后到
以上结论只由价格形成。事件在这之后才登场,而且只当作价格反应的证据:这只股票对事件,先反应在成交量上,再反应在方向上。2026年4月废止计划的窗口和5月决算与减值的窗口,都在回落中放出了大成交量;成交最重的4月是下跌月,没有财报消息,说明市场对计划、减值这类叙事事件的交易力度不亚于对数字。
4月10日废止计划,落在成交纪录月份之内。研究把这个对应关系作为假设:后来的回落,可能有一部分是价格在重新评估2031年3月期目标的可信度。这只是时间上的对应,不是技术成因;成交量记录属于价格证据本身,未被基本面改写。
5月电极减值背后的市场环境变化,在时间上也与价格相互对应:3月冲高结束,约两个月后减值公布,价格和资产负债表读到的,可能是同一件事,价格早了大约两个月。这也只是时间观察,不能证明因果;冲高的驱动因素没有被独立归因。
从更长的记录看,价格两次走在基本面前面:2023年的恢复早于2024年3月期的利润高点;2026年1至3月的冲高早于一个5月指引并未确认的复苏,此后的回落是价格向指引靠拢。图表现在不再领先于故事,而是定价在故事的低谷章节上,等待中期决算说明下一章是复苏还是复发。该决算预计在11月12日至13日发布,价格对它的真实反应在评审日无法观察。已经历七个月降风险的市场,在这家公司的历史上,往往是事件反应向上惊喜的时候,但这是历史倾向,不是预测。
10.7|后续什么价格行为确认,什么行为推翻
纯价格状态是:三年底部区间,上面焊着一次失败的三个月冲高,再加七个月有序回落,现在落在底部区间上沿的五年均线上,等待一份基本面财报来定方向。技术把握一般,信息主要来自月线;10月月线未走完,11月月线还在形成。
确认:一、11月或12月的月线收盘守在60个月均线(约2,031日元)之上,并经受住中期决算,说明是消化而不是下跌的延续;二、月线收盘重新站上24个月均线2,315日元,是修复的第一步;三、2026年的年内低点不低于2025年低点1,700日元,底部区间的下沿保持完好。
推翻:一、月线收盘跌破1,700日元,底部区间下沿破位,并重新打开前两次冲高都退回的1,000至1,650日元旧平台;二、月线收盘跌破2023年低点1,336日元,2023年到2026年被重新归类为在旧平台上方完成的派发;三、穿过底部区间下跌时放量(月成交超过100万股且收盘低于1,750日元),说明市场已从承接转为离场。
11|风险与催化剂
11.1|最大的风险是去库存复发,而且新固定成本让复发更贵
如果阴极块的客户去库存复发,或冶炼厂再次推迟换衬,周期这条腿就会失败。管理层自己也把这一点列为风险,同时列出的还有廉价电极进口。库存是最先发出信号的观察指标:在制品117.66亿日元,占年销售额的47%,总存货182.52亿日元,占73%,库存一旦再度被冲高,首先表现为存货增加和毛利率下降,早于利润表。2026年3月期“复苏比预期慢”就是已有的先例,管理层的展望也仍称各产品线处于严峻环境。
新设备完工和新工程开工把固定成本的底部抬高:销量兑现,营业杠杆很陡;落空,低谷更贵。库存账面价值不能当作可变现的下行保护,关于其可售性和折价没有证据。订单量和换衬计划没有披露,所以这个风险目前无法量化。
11.2|日元和中东:外部冲击到达利润表,比资产负债表的防御来得快
约73%的销售额(183.56亿日元)在海外,2027年3月期指引按美元兑日元155编制。2026年3月期有1.89亿日元汇兑收益,经常利润比预测高,原因是日元走弱和分红比预期多;2027年3月期第一季度,公司把部分恢复归因于日元走弱。日元回升是通向指引落空最快的路径,也会暴露销量低谷到底多深。没有描述对冲政策,敏感度没有量化。
管理层把中东局势排除在指引之外,理由是无法合理估计。最大的地区销售块亚洲和中东(76.31亿日元)里含有未量化的暴露,中东阴极块占多少没有披露,要靠2027年3月期财报里的地区明细,或一份量化被排除风险的修正公告来回答。政策传导是次要的:脱碳政策支撑客户的生产流程,也给公司自己高耗能的石墨化工序加税。
11.3|最近的验证是中期决算,之后是年度决算和资本政策的数字
2027年3月期中期决算预计在2026年11月12日至13日发布(按2024年和2025年都在11月13日发布推断,2025年当日还附带修正公告),评审日尚未公布。它要回答两个问题:指引能否经住一个计划本来就编得偏弱的季度;阴极块销量能否确认第一季度的拐点。结果在评审日不可知,价格对它的反应同样无法观察,技术状态的确认和推翻条件会在这次决算前后得到第一次检验。
之后依次是:2027年5月的全年决算和年末分红决定,2027年6月的证券报告和股东名册。资本政策只有带上数字才会成为催化剂:库存股注销、量化的证券出售、分红下限提高,或以亿日元计的回购。2026年的记录说明工具没有被堵死,所以任何一项披露都会直接重估折价,但没有时间表。
11.4|计划的可信度要靠每一期财报重建
指引把2027年3月期按低谷编制,隐含的第二季度营业利润只有3.36亿日元,近期预测的乐观偏差已经在计划废止中暴露过一次,所以每一期财报都会重新检验管理层的预测能力。中期决算是下一个检验点;2031年3月期的540亿日元销售额和12% ROE,只有在一期期财报里兑现,才从愿望变成路径。
指引本身的构成见估值章节,这里要强调的是一个后果:对只看标题“指引保持”的读者,它既可能掩盖销量的超预期,也可能掩盖销量的落空,真正能分辨的只有分产品销售额。
12|反常识发现
这是该公司的首份完整研究,所以以下七项都是本次研究得出的看法,没有从旧研究继承。
第一,亏损年度是更有现金的年度。2026年3月期净亏损0.74亿日元,营业现金流却达到77.66亿日元,因为减值和折旧不涉及现金,库存与应收随销量下降而释放;2027年3月期第一季度则开始反向吸收现金。只看标题的人会在两个方向上都读错。
第二,经常利润被金融层美化。约三分之一的经常利润来自分红、补助金和汇兑,碳素业务本身的经常性营业层面利润在40亿至44亿日元,任何从经常利润出发的正常化都会继承这份美化。
第三,指引的利润被前置到有一次性帮助的第一季度,隐含的第二季度营业利润只有约3.36亿日元,第一季度净利润的94%达成率依赖5.27亿日元的证券出售收益。
第四,金融资产456.68亿日元,已超过整家公司的市值。
第五,12%的ROE目标暗含股本缩小:靠利润一条腿,需要约93亿日元净利润,是预测的三倍,而只有利润那半有数字。
第六,减值后的电极折旧下降,会让这条线在没有市场复苏的情况下看起来变好,只有价格或销量才算数。
第七,同业的强劲业绩排除了行业疲弱的借口,把弱势归到公司自己的电极和阴极块换衬日历上。
13|下一次值得跟踪什么
13.1|最近的两道检验:中期决算和阴极块订单
中期决算会不会击败隐含的偏弱第二季度?这决定周期这条腿是否成立。中期决算预计在2026年11月12日至13日发布,评审时尚未公布;问题是第二季度营业利润(隐含约3.36亿日元)是否被阴极块销量击败,以及全年指引能否保持。相反的答案,分别对应销量带动的复苏和靠一次性因素撑起来的一个季度。解决问题的证据就是决算本身及其指引决定,下一次研究从这里开始。
阴极块的库存调整是不是真的结束了?这决定营业利润会不会恢复,也决定新增固定成本是杠杆还是负担。第一季度销售额上升51.8%,含发货顺延;订单量和冶炼厂下半年及2028年3月期的换衬计划是能回答它的证据。库存调整若复发,周期这条腿和低谷判断都失败;若已结束,更高固定成本上的营业杠杆会很陡。
13.2|资本政策能不能变成可测量的数字
资本政策支柱会不会可测量?这是投资判断的第二条腿:是否会出现更快的证券出售(投资证券281亿日元,第一季度已开始出售)、注销854,195股库存股、更大的回购或更高的分红下限,以及时间表。能回答的是任何带数字的资本政策公告、2027年5月的年度分红决定和2027年6月证券报告里的明细。
董事会对12% ROE目标的拆分是什么?利润恢复与股本缩小各占多少,会不会公布阶段性目标(分红净资产比、总回报率、证券出售金额),让持有人在2030年之前就能衡量。证据在2027年5月的决算资料或任何阶段性公告里,公司没有披露资本成本或拆分。
854,195股库存股(占已发行股份的4.1%)会不会注销?公司是否打算处理有效流通股薄和 Standard 市场流动性,还是把名册稳定本身当作政策?注销公告和2027年证券报告的股东名册变化可以回答;没有注销,回购就仍是可逆的。
控股集团想从这笔持股里得到什么?这决定折价会持续多久,也包括2026年6月更换代表董事是否改变了资本配置议程。可观察的证据只有大量持股报告的变化,以及2027年6月的股东名册和治理报告;没有披露制度要求说明意图,所以很可能一直没有答案。
13.3|产品、投资和地区上还没有答案的三件事
减值后的电极业务怎么收场?这决定是否还有进一步减值或退出成本。是缩减产能、退到价格可守的规格,还是按减值后的成本继续运转,管理层现在期待这批已减值资产有什么回报?下一步看电极销售额、产能或产品披露和贸易价格。公司对策略没有说明。
新在建工程26.74亿日元(2027年3月期第一季度末,完工后再度上升)在建什么、给哪个产品、预期回报多少?它是阴极块利基的延伸,还是第二块新利基,决定资本的方向和这笔新投资的资本回报风险。资本开支公告或决算资料点名项目就能回答。
中东暴露有多大?亚洲和中东合计76.31亿日元,管理层因无法估计而把中东影响排除在指引外;地区明细或一份量化被排除风险的修正公告可以解决,这是指引和阴极块发货时点的无界尾部风险。
特种碳素和微粉(半导体和电池相关需求,占销售额14.6%)能不能大到对2031年3月期540亿日元的销售目标有意义,还是目标算术其实默认阴极块的整轮超级周期?2027年3月期决算资料里的增长战略细节可以回答,分产品利润目前未披露。
14|Kabugami 评分卡
14.1|总分61.39/100,评级B:资产强、盈利平,技术无倾向
Kabugami 评分 V3.2:61.39/100,评级 B。八个维度的得分如下。财务韧性与下行防御11.7/13,竞争优势与结构耐久性9.52/14,盈利质量、现金转化与资本效率8.5/17,商业结构、产品、客户与关键依赖5.72/11。估值与安全边际10.8/15,资本配置与股东回报5.5/10,治理、所有权与管理层3.15/7,Kabugami 技术结构6.5/13。总体是一家防御极强、盈利处在低谷、资本转化尚未发生的公司。
操作结论是持有或小仓位分批,不追价;不确定性主要体现在阴极块订单和控股集团意图两项上,两者都没有披露,限制了对高分的信心;中期决算或后续资本政策披露之后,相关维度可能上调,也可能下调。
14.2|经营面四个维度:财务最强,盈利与商业结构偏弱
财务韧性与下行防御 11.7/13:无借款,自有资本比率89.2%,现金与证券相当于市值的108%,财务上基本没有失败路径;保留项是证券里的关系持股变现有税费和关系成本,持仓名单未核实。
竞争优势与结构耐久性 9.52/14:阴极块靠认证和失败成本留住客户,31%以上的毛利率经受住了销量大跌;这是推断,没有合同或独立份额数据,电极则没有同样的保护。
盈利质量、现金转化与资本效率 8.5/17:营业利润连降两年、全年净亏损,约三分之一经常利润不是本业,预测ROE只有3.87%;下行期现金转化很强,但复苏期会被存货和应收占用。
商业结构、产品、客户与关键依赖 5.72/11:一个产品加一个渠道,集中风险没有分散保护;中东销量和渠道条款未披露。
14.3|价格与股东面四个维度:估值偏正面,治理和技术没有倾向
估值与安全边际 10.8/15:资产覆盖和约5%的分红有扎实证据,但低谷利润上的倍数不低,折价能持续多久无法判断。
资本配置与股东回报 5.5/10:分红下限经受了亏损年度,回购方向打开但规模小、未注销,ROE目标的拆分未披露。
治理、所有权与管理层 3.15/7:持股稳定,却没有机制推动资本转化;2026年的动作偏积极但规模小,也可能只是一次性事件。
技术结构 6.5/13:价格处在三年底部区间上沿的决策带,没有确认也没有破位,在中期决算后的价格反应出现之前,不给出倾向。
14.4|V3.2 评分明细
| 模块 | 权重 | 得分 | 理由 |
|---|---|---|---|
| 财务韧性与下行防御 | 13 | 11.7 | 2026年3月期末总资产870.16亿日元、净资产776.28亿日元,自有资本比率89.2%,没有借款,连续五年有息负债为零。现金及存款175.33亿日元,加投资证券278.13亿日元,合计占总资产约52%;2027年3月期第一季度末现金与证券合计456.68亿日元,约为2026年11月6日市值422.6亿日元的108%。财务上基本没有失败路径,下行防御属于同类公司中的最强一档。 |
| 竞争优势与结构耐久性 | 14 | 9.52 | 铝电解用石墨化阴极块占销售额67.5%,是公司的核心产品。它的护城河来自认证和使用记录:阴极块失效会让冶炼厂损失一个电解槽,所以已通过认证的供应商能长期留在换衬周期里,竞争靠的是使用寿命和交货可靠性,而不是单价。证据主要是利润率表现:2026年3月期销量大幅下降,毛利率仍有31%以上,营业利润率16%。石墨电极则相反,价格由进口品决定,公司已对该设备计提60.63亿日元减值。 |
| 盈利质量、现金转化与资本效率 | 17 | 8.5 | 利润在连续两年下滑:经常利润从2024年3月期约115.55亿日元降到2026年3月期56.83亿日元,营业利润40.08亿日元(同比减少41.3%),因电极设备减值60.63亿日元,全年净亏损0.74亿日元。经常利润还包含17.16亿日元的营业外收益,其中分红8.45亿日元、补助金4.45亿日元,约三分之一不是卖碳素产品赚来的;碳素业务本身的经常性营业利润约在40至44亿日元。2027年3月期预测股本回报率只有3.9%,因为一半资产是低收益的金融资产。 |
| 商业结构、产品、客户与关键依赖 | 11 | 5.72 | 单一报告分部,阴极块占销售额67.5%,电极17.9%,特种碳素11.5%,微粉3.1%。约73%销售额在海外,经住友商事集团旗下的住友商事碳素原料公司销售的比例达57.8%(上年为66.6%,下降是因为阴极块销量下降)。关键原料是煅烧焦、无烟煤、沥青和电力,价格上涨已经抵消了销量恢复对毛利率的好处。 |
| 估值与安全边际 | 15 | 10.8 | 2026年11月6日收盘2,042日元,市值约422.6亿日元,实际市净率0.53倍;以公司预测每股收益149.64日元计,预测市盈率约13.6倍,预测股息率4.90%,EV/EBITDA约4.1倍。按五年平均经常利润约72.7亿日元,市值不到其6倍。现金与证券合计456.68亿日元,已超过市值。市场给低谷期营业利润的倍数不算低,却给资产负债表约五折定价,说明折价是对资本政策的折价,不是对破产或业务的折价。 |
| 资本配置与股东回报 | 10 | 5.5 | 分红政策为每股100日元与合并分红比例30%中取高者,2025年3月期和2026年3月期均支付20.04亿日元,亏损年度公式不变;2027年3月期预测每股100日元,对应预测分红比例66.8%。2026年5月14日决定的回购已在9月16日完成,第一季度买入20.75万股、5.29亿日元,库存股增至85.42万股(占已发行股份4.1%),并首次出售证券,获利5.27亿日元。方向已打开,规模偏小。 |
| 治理、所有权与管理层 | 7 | 3.15 | 大阪钢铁关联的大谷钢业持有19.85%并每年提交控股股东报告,三菱商事9.78%、住友商事5.02%、日本碳素4.06%、大和工业2.38%。股东结构稳定,但少数股东没有任何机制推动资本转化。2026年管理层行为偏积极:废止无法实现的三年计划,在决算中坦承电极减值并同日公布回购,6月更换代表董事,9月完成回购。 |
| Kabugami 技术结构 | 13 | 6.5 | 价格处于2023至2025年约1,700至2,400日元的三年底部区域内,2026年1至3月冲高至3,085日元后,连续七个月退回,11月6日收于2,042日元,正好落在60个月均线(约2,031日元)附近。冲高在成交量最大时结束,之后成交量逐月下降,回落有序,没有出现恐慌性放量。结构上既没有明确的新高位运行区间,也没有决定性的恶化,属于在决策带上等待事件的消化状态。 |
总分: 61.39 / 100 评级: B 操作建议: 以持有或小仓位分批为主,不追价。估值与资产覆盖提供了约5%的分红和较大的安全垫,但低谷利润上并不便宜,技术面也没有给出确认。预计11月12日至13日发布的中期决算是最近的检验:重点看阴极块销量是否超过指引隐含的偏弱第二季度,以及全年指引能否保持。若阴极块销量延续、同时出现有数字的库存股注销、证券出售或分红下限提高,可以逐步增加;若指引下调且阴极块销量下降、出现阴极块相关资产减值或分红公式被下调,应重新评估甚至退出。薄流通股意味着建仓和退出都要控制规模。
15|来源与合规
合规与风险声明
本报告为Kabugami.jp公开研究记录,不构成投资建议、投资招揽、证券买卖推荐、目标价、收益保证或适合性判断;投资者可能损失部分或全部本金。
本报告基于公开资料与研究判断制作。任何评分、估值、情景、技术结构或其他研究判断均可能因事实遗漏、资料时差、解释差异、模型错误、市场、流动性、信用、业务、技术、治理或资本政策变化而偏离实际结果。读者应阅读最新法定披露,并结合自身风险承受能力、资金期限及税务/法律状况独立决策。
15.1|数据截至2026年11月6日收盘,评审日为2026年11月9日
本研究的评审日是2026年11月9日。股价和估值数据截至2026年11月6日收盘,之后的价格变化没有计入。2027年3月期中期决算预计在11月12日至13日发布,评审日尚未公布,其结果、价格对它的反应都不在本报告的信息范围内。
主要来源如下。公司披露包括2026年3月期决算短信(2026年5月14日)、电极设备减值公告(同日)和2027年3月期第一季度决算短信(2026年8月7日)。
另有“2030 Make Real”中长期经营方针(2026年4月10日)、2025年11月13日的中期说明资料、公司网站的股东信息(截至2026年3月31日)和公司概况。市场与披露索引包括 IRBANK(TDnet 披露索引、股价、市盈率、市净率、股息率、融资融券数据),以及 Kabutan 报道的东海碳素2026年12月期第三季度累计业绩(2026年11月5日)。
背景资料为维基百科和日经公司概况(成立沿革、员工数、2008年前后的经历,只作背景使用)。公司英文名称来自日经公司概况和 EDINET 文件头。
技术部分使用2000年4月至2026年10月的月线价格(10月月线只到27日),11月6日收盘价取自 IRBANK。
15.2|哪些事实没有读到,会如何限制判断
以下事实没有核实,使相应判断留有余地:2026年6月19日财报数字更正的具体数字,以及税务和补助金注释没有逐行读,参考依据是2026年6月19日提交的证券报告附注;证券持仓的名单、取得成本和互相持股的比例没有读到;没有读到机构一致预期;公司没有披露分产品利润、订单量、在手订单、对冲政策,以及新增在建工程的用途;2008年前后的经历来自背景资料;2024年3月期的销售额和营业利润由2025年3月期财报的同比比例倒推。
估值数据口径不统一:EV 用2026年6月30日净现金,EBITDA 用2026年3月期,市值包含库存股,IRBANK 的市净率为0.52倍而本报告按实绩计算为0.53倍。这些限制主要影响对高分和估值结论的把握,不等于相反的结论。
本报告是研究参考,不构成买卖建议,使用的均为公开资料。投资有风险,持有这只流通股较薄的股票时,建仓和退出的规模要自行控制。
主要资料来源
- Impairment notice: JPY 6,063 million written down on graphite electrode plant
- FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets
- 2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31
- Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%
- Company profile: four carbon product lines, Kyoto works at the centre
- Corporate background: founded 1934, an independent carbon maker in the Otani orbit
- Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback
- FY3/2026 interim briefing: management's 'first quarter was the bottom' framing
- Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026)
- Major shareholders at 31 March 2026: the Otani bloc and the trading houses
- Earnings amplitude across two cycles, from the disclosure record's headlines
研究发现索引
展开本次 Review 的 99 项研究发现
F001|01|股价在押一个治理问题,周期只是第二个期权
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接证据;一手验证:32;反向验证:20
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Valuation arithmetic at the 6 November 2026 close怎么使用:直接证据;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:支持证据;一手验证:14、31
Management outlook: every product line still described as facing a harsh environment怎么使用:一手验证:14;反向验证:04、06、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close;支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;反证 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment
完整研究记录(核对用)
研究原文:Completed Research upgrades the opening question. SEC Carbon is not simply a value trap versus a trough purchase: the share price is best read as a forecast about whether a debt-free balance sheet holding about JPY 45.7 billion of cash and securities (108% of market capitalisation) will be converted into per-share value, with the cathode-block replacement cycle acting as a second, partly independent option. The operative question is which of two dated processes (cathode volume with operating leverage in FY3/27 H2, or measurable capital-policy conversion under the 2030 framework) delivers first, and whether the carry (4.9% forecast yield) is adequate while waiting.
内部研究类型:INVESTMENT_QUESTION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Defines what the ordinary shareholder is actually underwriting: governance-and-cycle optionality funded by a yield, not a franchise recovery alone.
不确定性(原始记录):The capital-conversion leg has no deadline and bloc intent is undisclosed; the cycle leg is tested only by prints after the review date.
F002|02|三分之二的收入押在一个产品的更换周期上
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论02|三分之二的收入押在一个产品的更换周期上
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/2026 tanshin header: issuer identity, listing and representative怎么使用:直接 / 支持;一手验证:01
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Company profile: four carbon product lines, Kyoto works at the centre怎么使用:直接 / 支持;一手验证:03、04、09、10
Corporate background: founded 1934, an independent carbon maker in the Otani orbit怎么使用:直接证据;一手验证:33;同业比较:01、09、12、23;其他用途:历史
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接证据;一手验证:02、05、07、15
Scale: roughly 270 employees produce JPY 25 billion of sales怎么使用:直接证据;专项深挖:09
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|FY3/2026 tanshin header: issuer identity, listing and representative;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域09) / 一手证据(研究域10)|Company profile: four carbon product lines, Kyoto works at the centre;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域23)|Corporate background: founded 1934, an independent carbon maker in the Otani orbit;直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 定向深挖(研究域09)|Scale: roughly 270 employees produce JPY 25 billion of sales
完整研究记录(核对用)
研究原文:SEC Carbon, Ltd. (TSE Standard 5304, founded 1934, Amagasaki; Kyoto/Fukuchiyama and Okayama works) is an independent carbon-products maker with one reported segment. FY3/26 sales by product: graphitized cathode blocks for aluminium smelting 67.5%, graphite electrodes 17.9%, carbon specialties 11.5%, fine powder 3.1%. It sells qualified consumables into other industries' maintenance and operating calendars, about 73% overseas, with 57.8% of sales through one Sumitomo-group trading channel. About 270 staff produce roughly JPY 93 million of sales each: a capital- and process-intensive materials maker.
内部研究类型:COMPANY_IDENTITY_AND_BUSINESS_MODEL
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Two thirds of the investment case is one product's installed-base mathematics; the shareholder owns a claim on a two-cycle business (aluminium maintenance, steel operation).
不确定性(原始记录):Product-level profit is not disclosed; model is described at revenue and group-margin level. Registered English name rests on Nikkei profile and EDINET header.
F003|02|合并范围基本等于母公司,没有隐藏的子公司利润
研究范围:开放研究+35项覆盖检查
写入正文:02|合并范围基本等于母公司,没有隐藏的子公司利润
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Parent-only accounts: the subsidiaries are a rounding item怎么使用:直接证据;反向验证:02
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接证据;外部现实校验:20
查看完整证据标签(核对用)
直接证据|Nippon Denkyoku: a small electrode affiliate brought into the equity method;直接证据 / 反证(研究域02)|Parent-only accounts: the subsidiaries are a rounding item;直接证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback
完整研究记录(核对用)
研究原文:The consolidated group is economically the parent plus small subsidiaries: parent-only sales are JPY 24,522 million (97.7% of consolidated) and minority interest is about JPY 14 million, so there is no hidden subsidiary profit pool. In FY3/26 the company acquired shares of Nippon Denkyoku, a small electrode-industry affiliate brought into the equity method; it lost JPY 16 million in FY3/26 and JPY 47 million in Q1 FY3/27, bought into the group in the same year the group's own electrode plant was written down.
内部研究类型:GROUP_PERIMETER_FACT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Valuation can treat the listed entity as the operating enterprise; no SOTP uplift from subsidiaries and no minority leakage.
不确定性(原始记录):Nippon Denkyoku's strategic purpose is not stated in the sources read; size is immaterial today.
F004|03|一个产品的更换周期,决定了这家公司的利润表
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接证据;一手验证:02、05、07、15
The cathode demand frame: relining cycles and smelter construction怎么使用:直接证据;一手验证:11;外部现实校验:02、03、10、11、15;专项深挖:03、05
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05)|The cathode demand frame: relining cycles and smelter construction
完整研究记录(核对用)
研究原文:The earnings engine is the cathode-block replacement cycle. Cathode blocks (67.5% of sales) are consumed when aluminium smelter pots are relined and when smelters are built; demand is lumpy and project-sized, concentrated in the Middle East, Canada, Brazil and Asia. FY3/26 cathode sales fell 23.0% on slower smelter renewal and a customer inventory adjustment that took longer than expected, and group operating profit fell 41.3%. Q1 FY3/27 cathode sales rose 51.8%, with management saying the adjustment has turned toward resolution and some Middle East shipments slipped in from the prior quarter, so part of the rebound is shipment timing.
内部研究类型:CORE_EARNINGS_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The cycle verdict, and therefore operating earnings power, depends on this one product's volume slope into the second half of FY3/27.
不确定性(原始记录):Order intake, backlog and smelter relining schedules are not disclosed; Q1 timing effects blur the true slope.
F005|06|亏损年度反而更有现金,复苏年度现金会被吸走
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接证据;一手验证:02、03、09、15;反向验证:08
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接证据;一手验证:02、05、07、15
The cathode demand frame: relining cycles and smelter construction怎么使用:直接证据;一手验证:11;外部现实校验:02、03、10、11、15;专项深挖:03、05
Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign怎么使用:直接证据;反向验证:07、15;专项深挖:02
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05)|The cathode demand frame: relining cycles and smelter construction;直接证据 / 反证(研究域07) / 反证(研究域15) / 定向深挖(研究域02)|Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign
完整研究记录(核对用)
研究原文:Cathode revenue is recurring in kind: relining cannot be deferred indefinitely, so FY3/26's decline is partly postponed rather than lost revenue, a timing debt the cycle owes back. The 2024-2026 downturn was an inventory event layered on the relining calendar, so manufacturer volume fell more than end demand and a recovery would overshoot the same way. Revenue is nevertheless concentrated by product (67.5%) and channel (57.8%, down from 66.6% only because cathode volume fell), and is translated at a weak yen.
内部研究类型:REVENUE_QUALITY_JUDGEMENT
内部来源标记:COVERAGE35
普通股东含义(原始记录):Postponed revenue returns with interest if the installed smelter base keeps running, which supports a higher-than-trough valuation of the franchise.
不确定性(原始记录):Smelter closures (as opposed to deferrals) would convert postponed revenue into lost revenue; no closure evidence in the record. Channel-level inventory is unobservable.
F006|05|护城河来自认证和失败成本,证据是利润率而非合同
研究范围:35项覆盖检查
写入正文:05|护城河来自认证和失败成本,证据是利润率而非合同14|经营面四个维度:财务最强,盈利与商业结构偏弱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Company profile: four carbon product lines, Kyoto works at the centre怎么使用:直接证据;一手验证:03、04、09、10
Margin structure: gross margin compressed 4.4 points; SG&A was cut in absolute terms怎么使用:直接证据;一手验证:10、16;同业比较:06;其他用途:历史
Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026)怎么使用:直接证据;一手验证:08;外部现实校验:05、07、08、09、12、28、35
The cathode demand frame: relining cycles and smelter construction怎么使用:直接证据;一手验证:11;外部现实校验:02、03、10、11、15;专项深挖:03、05
The electrode frame: structurally favoured process, cyclically hostile pricing怎么使用:直接证据;一手验证:08;反向验证:10;专项深挖:08
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域09) / 一手证据(研究域10)|Company profile: four carbon product lines, Kyoto works at the centre;直接证据 / 一手证据(研究域10) / 一手证据(研究域16) / 历史/同业比较(研究域06)|Margin structure: gross margin compressed 4.4 points; SG&A was cut in absolute terms;直接证据 / 一手证据(研究域08) / 外部现实(研究域05) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域28) / 外部现实(研究域35)|Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026);直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05)|The cathode demand frame: relining cycles and smelter construction;直接证据 / 一手证据(研究域08) / 反证(研究域10) / 定向深挖(研究域08)|The electrode frame: structurally favoured process, cyclically hostile pricing
完整研究记录(核对用)
研究原文:The cathode franchise is protected by qualification incumbency: a failed cathode block costs a smelter a pot, so incumbent qualified suppliers keep the relining calendar and competition runs on proven life and delivery reliability rather than yen per tonne. Evidence is margin behaviour: gross margins of 31-36% and a 16% operating margin through a severe volume downturn. Know-how is embodied in process, plant and people. Competition is fought on different fields by line: qualification in cathode blocks, outright price in electrodes, which is why one line earned a write-down and the other did not. Erosion would arrive slowly, through a rival's multi-year qualification success or a smelting-technology change.
内部研究类型:MOAT_AND_COMPETITIVE_POSITION
内部来源标记:COVERAGE35
普通股东含义(原始记录):The moat is what makes the trough survivable and the recovery option credible; it is capped because the same conservatism slows adoption of new products.
不确定性(原始记录):No contract-level or independent share evidence was read; the moat is inferred from margin behaviour and failure-cost asymmetry. Evidence of share loss at a major relining programme would be the falsifier.
F007|03|住友集团既是57.8%收入的出口,又是5.02%的股东
研究范围:开放研究+35项覆盖检查
写入正文:03|住友集团既是57.8%收入的出口,又是5.02%的股东14|经营面四个维度:财务最强,盈利与商业结构偏弱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign怎么使用:直接 / 支持;反向验证:07、15;专项深挖:02
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 支持证据 / 反证(研究域07) / 反证(研究域15) / 定向深挖(研究域02)|Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign
完整研究记录(核对用)
研究原文:Sumisho CRM, the Sumitomo Corporation group's carbon raw-materials company, carried JPY 14,514 million (57.8%) of FY3/26 sales (66.6% in FY3/25), and Sumitomo Corporation also holds 5.02% of the shares. The concentration is cyclical in degree but structural in kind: at a cathode peak, two thirds of revenue would again move through one counterparty's book. Share ownership aligns incentives but does not remove the exposure to a change in the Sumitomo group's carbon strategy, credit terms or channel economics.
内部研究类型:CONCENTRATION_RISK
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A single-counterparty shock reaches most revenue at once; the same relationship also supports register stability.
不确定性(原始记录):Commercial terms and the channel's margin share are undisclosed; resilience to a change in Sumitomo strategy is untestable from filings.
F008|06|账面亏损是承认,不是现金事件
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论06|账面亏损是承认,不是现金事件
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接 / 支持;一手验证:16、32;同业比较:14;其他用途:历史
Corporate background: founded 1934, an independent carbon maker in the Otani orbit怎么使用:直接 / 支持;一手验证:33;同业比较:01、09、12、23;其他用途:历史
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:直接证据;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 consolidated results: a second consecutive down year;直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域23)|Corporate background: founded 1934, an independent carbon maker in the Otani orbit;直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines
完整研究记录(核对用)
研究原文:Earnings have fallen two consecutive years from the FY3/24 peak. Ordinary profit went from about JPY 11.6 billion (FY3/24) to JPY 7,716 million (FY3/25) to JPY 5,683 million (FY3/26). FY3/26 sales were JPY 25,101 million (-19.5%), operating profit JPY 4,008 million (-41.3%) and the year closed with a net loss of JPY 74 million after a JPY 6,063 million impairment. Comprehensive income was JPY 5,831 million because securities valuation gains carried it.
内部研究类型:OBSERVED_PROFIT_TRAJECTORY
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Reported headline loss overstates operating weakness yet the underlying decline in operating profit is real and cycle-driven.
不确定性(原始记录):Peak-year figures are derived from year-on-year rates in the FY3/25 filing.
F009|04|周期处在复苏早期,但这家公司的低谷可以拖两年
研究范围:开放研究+35项覆盖检查
写入正文:04|周期处在复苏早期,但这家公司的低谷可以拖两年
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接证据;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
The FY3/24 peak: derived comparatives from the FY3/25 year-on-year rates怎么使用:直接 / 支持;一手验证:33;同业比较:02、03、28;其他用途:历史
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:直接证据;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
H1 FY3/2026 actuals: the base half against which the FY3/27 interim plan is set怎么使用:直接 / 支持;一手验证:12;同业比较:05、15、16、31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域28)|The FY3/24 peak: derived comparatives from the FY3/25 year-on-year rates;直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines;直接证据 / 支持证据 / 一手证据(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域31)|H1 FY3/2026 actuals: the base half against which the FY3/27 interim plan is set;支持证据|FY3/2026 consolidated results: a second consecutive down year
完整研究记录(核对用)
研究原文:FY3/24 was the peak of the current cycle (derived sales about JPY 37.3 billion, operating profit about JPY 10.2 billion): two years of decline removed about a third of sales and half of ordinary profit. Ordinary profit swung by a factor of five trough-to-peak twice in a decade (FY3/19 JPY 17,109 million, FY3/21 JPY 3,493 million, FY3/24 JPY 11,555 million, FY3/26 JPY 5,683 million). Inside the trough the shape was sequential recovery: Q1 FY3/26 operating profit JPY 609 million (13.9% margin), Q2 JPY 970 million (16.4%), which is the basis for management calling Q1 FY3/26 the bottom. The cycle is split: cathode orders have turned while electrodes keep falling. By pattern (three to five years trough to peak) the position is early-recovery, but the last two years of decline show troughs here can last two full years.
内部研究类型:CYCLE_POSITION_JUDGEMENT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Buying the trough is the historical trade; the historical risk is that the trough lasts longer than a holder expects.
不确定性(原始记录):Whether Q2 FY3/27 cathode volume confirms the turn or shows Q1 as shipment timing; no industry-wide volume series was read.
F010|06|利润率下降来自销量,不来自成本
研究范围:开放研究+35项覆盖检查
写入正文:06|利润率下降来自销量,不来自成本
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Margin structure: gross margin compressed 4.4 points; SG&A was cut in absolute terms怎么使用:直接 / 支持;一手验证:10、16;同业比较:06;其他用途:历史
Input costs: raw-material and fuel inflation is the stated offset to volume recovery怎么使用:直接证据;一手验证:06;外部现实校验:04、16;专项深挖:06
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 consolidated results: a second consecutive down year;直接证据|Q1 FY3/2027 results: volume recovery off a trough quarter;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域16) / 历史/同业比较(研究域06)|Margin structure: gross margin compressed 4.4 points; SG&A was cut in absolute terms;直接证据 / 一手证据(研究域06) / 外部现实(研究域04) / 外部现实(研究域16) / 定向深挖(研究域06)|Input costs: raw-material and fuel inflation is the stated offset to volume recovery
完整研究记录(核对用)
研究原文:The FY3/26 margin decline was a volume event, not a cost event: gross margin fell from 35.6% to 31.2% as fixed production costs were absorbed over 19.5% less revenue, while SG&A was cut JPY 456 million to JPY 3,813 million, so operating margin fell from 21.9% to 16.0%. In Q1 FY3/27 gross margin recovered only to 32.1% despite the volume rebound because raw-material and fuel inflation (calcined coke, anthracite, pitch, electricity) offset the gain. Pass-through of price recovery will be visible only in gross margin.
内部研究类型:MARGIN_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operating leverage into a volume recovery is real; part of it is absorbed by commodity and energy costs the holder cannot hedge.
不确定性(原始记录):Product-level margins and supplier contracts are undisclosed; commodity spread effect is not isolated.
F011|04|电极是被进口价格定价的业务,减值承认了这一点
研究范围:开放研究+35项覆盖检查
写入正文:04|电极是被进口价格定价的业务,减值承认了这一点06|账面亏损是承认,不是现金事件
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接证据;一手验证:02、03、09、15;反向验证:08
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接证据;一手验证:05;反向验证:03、19
Management outlook: every product line still described as facing a harsh environment怎么使用:直接证据;一手验证:14;反向验证:04、06、35
The electrode frame: structurally favoured process, cyclically hostile pricing怎么使用:直接证据;一手验证:08;反向验证:10;专项深挖:08
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment;直接证据 / 一手证据(研究域08) / 反证(研究域10) / 定向深挖(研究域08)|The electrode frame: structurally favoured process, cyclically hostile pricing
完整研究记录(核对用)
研究原文:On 14 May 2026 the company booked a JPY 6,063 million impairment on the artificial graphite electrode manufacturing equipment because market-environment changes pushed its recoverable amount below book value. The write-down is specific: management is signalling which of its two historic franchises it no longer believes can carry its book value, and it is not the cathode franchise. Electrodes are structurally favoured by scrap-based electric-arc-furnace steelmaking but cyclically crushed because low-cost Chinese and Indian imports set the marginal price against weak crude steel output. Electrode sales were nearly flat in FY3/26 (-0.9%) as a price/mix defence the write-down says cannot continue at book values; Q1 FY3/27 electrode sales fell 18.9%.
内部研究类型:ASSET_IMPAIRMENT_AND_FRANCHISE_ADMISSION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Management has conceded part of the asset base cannot earn its carrying value; the sub-franchise is exposed to import pricing the company cannot influence.
不确定性(原始记录):The electrode endgame (capacity cut, grade retreat or continued operation) is not stated; import price trends and overseas capacity exits are unobserved.
F012|06|账面亏损是承认,不是现金事件
研究范围:35项覆盖检查
写入正文:06|账面亏损是承认,不是现金事件
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接证据;一手验证:32;反向验证:20
The electrode frame: structurally favoured process, cyclically hostile pricing怎么使用:直接 / 支持;一手验证:08;反向验证:10;专项深挖:08
Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line怎么使用:直接 / 支持
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域08) / 反证(研究域10) / 定向深挖(研究域08)|The electrode frame: structurally favoured process, cyclically hostile pricing;直接证据 / 支持证据|Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line
完整研究记录(核对用)
研究原文:JPY 6,063 million of book value removed from the electrode equipment mechanically lowers future depreciation on that line, so smaller reported losses or small profits from electrodes are expected arithmetic. The write-down changes the cost denominator, not the market; only price or volume evidence should be read as recovery.
内部研究类型:ACCOUNTING_ARTEFACT_QUALIFIER
内部来源标记:COVERAGE35
普通股东含义(原始记录):Prevents mistaking accounting relief for operating recovery in the electrode line.
不确定性(原始记录):Depreciation saving amount is not disclosed by line.
F013|06|亏损年度反而更有现金,复苏年度现金会被吸走
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接证据;一手验证:32;反向验证:20
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接证据;一手验证:16、32;同业比较:14;其他用途:历史
FY3/2026 cash flow: operating cash flow rose through the loss year怎么使用:直接 / 支持;一手验证:17;同业比较:19;其他用途:历史
Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume怎么使用:直接证据;外部现实校验:19;专项深挖:18
Inventory structure: work in process is 47% of a year's sales怎么使用:直接证据;一手验证:06、19;反向验证:17、29;专项深挖:19
Working-capital structure: the group pays fast and collects slowly怎么使用:直接 / 支持;一手验证:17、19;专项深挖:10、15、17
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19)|FY3/2026 cash flow: operating cash flow rose through the loss year;直接证据 / 外部现实(研究域19) / 定向深挖(研究域18)|Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume;直接证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 定向深挖(研究域10) / 定向深挖(研究域15) / 定向深挖(研究域17)|Working-capital structure: the group pays fast and collects slowly
完整研究记录(核对用)
研究原文:The headline loss is an accounting admission, not a cash event. The JPY 6,063 million impairment turned a JPY 4,008 million operating profit into a JPY 74 million net loss, yet FY3/26 operating cash flow rose 71% to JPY 7,766 million because the impairment and JPY 2,048 million of depreciation are non-cash and cash taxes fell to JPY 1,073 million. Receivables of about JPY 9.4 billion and inventories of JPY 18.3 billion unwind when volume falls, so operating cash flow is countercyclical: it undershot ordinary profit in the FY3/25 upcycle (JPY 4,548 million versus JPY 7,716 million) and overshot it in the FY3/26 downcycle (JPY 7,766 million versus JPY 5,683 million). The company got cash-richer in its loss year; Q1 FY3/27 shows the reverse starting, with every inventory layer stocked while receivables fell JPY 2,388 million.
内部研究类型:CASH_VS_ACCOUNTING_DIVERGENCE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The shareholder's company is richer in cash after its worst earnings year than before it, and cash will deteriorate as earnings recover; a headline reader can misread both signals.
不确定性(原始记录):Whether FY3/27 recovery re-absorbs cash at the FY3/25 rate; no quarterly cash-flow statements for Q1.
F014|04|同业利润增长27.0%,行业疲弱不能当作借口
研究范围:35项覆盖检查
写入正文:04|同业利润增长27.0%,行业疲弱不能当作借口
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026)怎么使用:直接 / 支持;一手验证:08;外部现实校验:05、07、08、09、12、28、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 一手证据(研究域08) / 外部现实(研究域05) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域28) / 外部现实(研究域35)|Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026)
完整研究记录(核对用)
研究原文:Tokai Carbon (5301), the larger listed peer, printed Q3 FY12/26 cumulative ordinary profit up 27.0% on 5 November 2026, driven by carbon black and fine carbon. The comparison removes carbon industry weakness as an excuse: SEC Carbon's weakness is specific to electrodes and the cathode relining calendar, both company-level exposures, though product mixes differ.
内部研究类型:EXTERNAL_COUNTER_EVIDENCE
内部来源标记:COVERAGE35
普通股东含义(原始记录):Attributes the earnings drop to company-specific exposure rather than industry weather, which both raises the credit for a cathode turn and removes macro cover for misses.
不确定性(原始记录):Peer mix is broader (carbon black, industrial furnaces); comparability is partial and no independent share series was read.
F015|06|没有借款的资产负债表:金融资产比有形资产还大
研究范围:开放研究+35项覆盖检查
写入正文:06|没有借款的资产负债表:金融资产比有形资产还大09|下行保护有三层,风险是时间而不是本金14|经营面四个维度:财务最强,盈利与商业结构偏弱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:直接 / 支持;一手验证:18、29
Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored怎么使用:直接证据;同业比较:17、18、20、22、27;其他用途:历史
Valuation arithmetic at the 6 November 2026 close怎么使用:直接 / 支持;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27)|Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close
完整研究记录(核对用)
研究原文:At 31 March 2026 total assets were JPY 87,016 million, net assets JPY 77,628 million, equity ratio 89.2%, no borrowings, and interest-bearing debt to operating cash flow 0.0 years for five years. Cash and deposits of JPY 17,533 million plus investment securities of JPY 27,813 million (valuation reserve JPY 14,924 million) are 52% of total assets, against net tangible fixed assets of only JPY 13,316 million. At the Q1 FY3/27 balance sheet, cash plus securities of JPY 45,668 million were 108% of the 6 November market capitalisation of JPY 42.26 billion: on market pricing the operating business, plant, land and inventory are free. The same structure is why forecast ROE is 3.9% and PBR 0.52-0.53: downside protection and ROE dilution are one fact. The equity ratio dipped to 83.0% in FY3/24 during heavy investment and has since been restored by retained earnings and valuation gains, not new equity.
内部研究类型:BALANCE_SHEET_STRUCTURE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Guarantees survival through any customer-imposed cycle and caps returns with the same yen.
不确定性(原始记录):Securities are marked, land and plant are at historical cost; portfolio name-level composition and cost base (hence tax and relationship cost of unwinding) sit in securities-report schedules; Q1 securities valuation partly reflects relationship holdings that may not be freely saleable. Treasury shares are 4.1% of issued shares, so the market-capitalisation denominator includes treasury shares.
F016|09|下行保护有三层,风险是时间而不是本金
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
The capex cycle: a facility completed into the trough, depreciation stepping up怎么使用:直接 / 支持;一手验证:04、20;专项深挖:04、20;同业比较:04;其他用途:历史
Land and the old asset base: book values carry no revaluation怎么使用:直接 / 支持;一手验证:21;专项深挖:21;同业比较:29;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|The capex cycle: a facility completed into the trough, depreciation stepping up;直接证据 / 支持证据 / 一手证据(研究域21) / 历史/同业比较(研究域29) / 定向深挖(研究域21)|Land and the old asset base: book values carry no revaluation
完整研究记录(核对用)
研究原文:Land for the Amagasaki head office and the Kyoto (Fukuchiyama) and Okayama works is carried at JPY 1,262 million at historical cost, unchanged across balance sheets read, with no appraisal disclosed; the fixed-asset base is stated far below replacement cost. Machinery gross of JPY 48,159 million is 90% depreciated.
内部研究类型:UNMARKED_ASSET
内部来源标记:COVERAGE35
普通股东含义(原始记录):A hidden reserve of unknown size and a reminder that earnings power, not the asset register, must justify equity value; it is also not distributable without disrupting production.
不确定性(原始记录):Land market value is unknown and not estimated.
F017|07|股东名册和证券组合互为镜像
研究范围:35项覆盖检查
写入正文:07|股东名册和证券组合互为镜像08|资本政策要有数字,才算催化剂
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Cross-holding web: peers and partners on both sides of the register怎么使用:直接 / 支持;专项深挖:07、24;同业比较:21;其他用途:历史
Register size and liquidity: 4,922 shareholders, a Standard-market small cap怎么使用:直接 / 支持;反向验证:24
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register;直接证据 / 支持证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap
完整研究记录(核对用)
研究原文:The register and the portfolio mirror each other: Nippon Carbon (listed peer) holds 4.06%, Yamato Kogyo (steelmaker) 2.38%, banks and trading houses throughout, while the company's own JPY 27.8 billion securities portfolio is more than half unrealised gain on long-held relationship shares. The web is the register's shock absorber and its discount engine at once: it prevents hostile pressure for change and guarantees the float cannot price one in. The Q1 FY3/27 sale (JPY 527 million gain) is the first evidence in this research of the portfolio being actively trimmed.
内部研究类型:CROSS_HOLDING_WEB
内部来源标记:COVERAGE35
普通股东含义(原始记录):Stabilises operations and the register but supports the discount; unwinding would be the clearest sign capital policy is real.
不确定性(原始记录):Name-level composition and cost base are unread; which holdings are reciprocal commitments is unknown.
F018|07|股东名册就是折价:控股集团加两家商社
研究范围:开放研究+35项覆盖检查
写入正文:07|股东名册就是折价:控股集团加两家商社14|价格与股东面四个维度:估值偏正面,治理和技术没有倾向
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接证据;一手验证:01、07、24;外部现实校验:23
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Float behaviour: thin trading, one-sided margin balances, event-day volume怎么使用:直接证据;外部现实校验:24、25、27、30;专项深挖:34
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域27) / 外部现实(研究域30) / 定向深挖(研究域34)|Float behaviour: thin trading, one-sided margin balances, event-day volume;直接证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap
完整研究记录(核对用)
研究原文:The register is the discount. Otani Steel Corporation holds 19.85% and is the subject of annual controlling-shareholder filings, with Otani-family entities filing alongside; Mitsubishi Corporation holds 9.78% and Sumitomo Corporation 5.02% (the latter also intermediates 58% of sales); Master Trust 4.89%, Nippon Carbon 4.06%, MUFG Bank 2.66%, Yamato Kogyo 2.38%, Nippon Steel Engineering 2.09%; 4,922 shareholders. The effective float is thin: five-day average volume to 6 November was about 59,000 shares a day, margin buying was 20.96 times margin selling in the 17 July snapshot, and a 6 November session on 134,900 shares (+75% on trend) moved the price 4.18% without earnings news. Stability cuts both ways: no internal mechanism closes a discount and no forced seller exists.
内部研究类型:OWNERSHIP_AND_FLOAT_STRUCTURE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Minorities are junior partners in someone else's ecosystem: protected from disruption, excluded from forcing change; entry and exit both run through a thin float so position size is a binding constraint.
不确定性(原始记录):Bloc intentions are undisclosed; holdings are as of 31 March 2026 and intra-year changes are visible only through large-holding reports. Margin snapshot is dated 17 July.
F019|09|折价是对资本政策的折价,不是对破产或业务的折价
研究范围:开放研究+35项覆盖检查
写入正文:09|折价是对资本政策的折价,不是对破产或业务的折价14|价格与股东面四个维度:估值偏正面,治理和技术没有倾向
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:直接证据;一手验证:18、29
Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored怎么使用:直接证据;同业比较:17、18、20、22、27;其他用途:历史
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:一手验证:11、13、22、35;反向验证:23、33;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27)|Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored;反证 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31
完整研究记录(核对用)
研究原文:The valuation discount is a capital-governance discount, not a franchise or solvency discount. With a 19.85% controlling shareholder from the founding family's steel company, about a tenth of the register in two trading houses, a sales channel concentrated in one Sumitomo-group company, and about JPY 45 billion of financial assets compounding at deposit-and-dividend yields, the market prices the probability that the pile is never converted into per-share value. The market has never in FY3/22-FY3/26 valued the company above about three fifths of book equity (market-value equity ratio 38.1% to 60.9%). The market pays trough operating earnings at a full multiple while valuing the balance sheet at half, a combination that only makes sense if the discount is expected to be permanent.
内部研究类型:VALUATION_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The holder is paid in yield and discount to wait for governance or cycle change; re-rating is led by register events or prints, not abstract multiple expansion.
不确定性(原始记录):Opposing evidence: the 2026 buyback and first securities sale show the bloc is unblocked; the discount may narrow without a declared programme. Timing is undeterminable.
F020|09|低谷利润不算便宜,资产却被打了五折
研究范围:开放研究+35项覆盖检查
写入正文:09|低谷利润不算便宜,资产却被打了五折15|数据截至2026年11月6日收盘,评审日为2026年11月9日15|哪些事实没有读到,会如何限制判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
FY3/2026 cash flow: operating cash flow rose through the loss year怎么使用:直接 / 支持;一手验证:17;同业比较:19;其他用途:历史
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume怎么使用:直接 / 支持;外部现实校验:19;专项深挖:18
Valuation arithmetic at the 6 November 2026 close怎么使用:直接 / 支持;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:支持证据;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
Normalisation base: five-year ordinary-profit record and its financial-income content怎么使用:支持证据;一手验证:28;专项深挖:12、16、28
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 consolidated results: a second consecutive down year;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19)|FY3/2026 cash flow: operating cash flow rose through the loss year;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 支持证据 / 外部现实(研究域19) / 定向深挖(研究域18)|Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close;支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines;支持证据 / 一手证据(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|Normalisation base: five-year ordinary-profit record and its financial-income content
完整研究记录(核对用)
研究原文:Valuation at the 6 November 2026 close (review date 9 November 2026): share price JPY 2,042 (-4.18% on the day); market capitalisation JPY 42.26 billion on 20,694,340 issued shares; forecast PER 13.6x on FY3/27 company-forecast EPS of JPY 149.64 (unchanged at Q1); actual PBR 0.53x on FY3/26 net assets per share of JPY 3,871.46 (IRBANK shows 0.52x); FY3/26 ROE -0.1% as reported (net-loss year); forecast dividend yield 4.90% on JPY 100; EV/EBITDA 4.1x (EV JPY 24.65 billion after net cash of JPY 17.60 billion at 30 June 2026; EBITDA JPY 6.06 billion = FY3/26 operating profit JPY 4,008 million plus depreciation JPY 2,048 million). About 14 times FY3/27 forecast net income, but under 6 times the five-year average ordinary profit (about JPY 7,269 million, pre-tax): the gap is the price of cyclicality. Forecast ROE is 3.87%.
内部研究类型:VALUATION_SNAPSHOT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Provides the point-in-time pricing frame; trough earnings look full while assets look cheap.
不确定性(原始记录):Mixed bases: EV uses a 30 June 2026 net cash figure with FY3/26 EBITDA; PER uses company forecast; market capitalisation uses issued shares including treasury shares (4.1% of issued at Q1, possibly higher after the buyback completed in September); ex-treasury capitalisation would be modestly lower. Net cash includes relationship securities excluded from the EV cash figure. Price is the 6 November close; later November price action is not captured.
F021|09|正常化后,业务层面的税前盈利能力在55亿至60亿日元
研究范围:35项覆盖检查
写入正文:09|正常化后,业务层面的税前盈利能力在55亿至60亿日元
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:直接证据;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
Valuation arithmetic at the 6 November 2026 close怎么使用:直接证据;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
Normalisation base: five-year ordinary-profit record and its financial-income content怎么使用:直接证据;一手验证:28;专项深挖:12、16、28
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines;直接证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close;直接证据 / 一手证据(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|Normalisation base: five-year ordinary-profit record and its financial-income content
完整研究记录(核对用)
研究原文:Five-year ordinary profit (FY3/22-FY3/26: JPY 3,779 / 7,610 / 11,555 / 7,716 / 5,683 million) averages about JPY 7,269 million; the three-year mean is about JPY 8,318 million. Because the financial-income layer (JPY 1.3-1.7 billion a year of dividends, subsidies and FX) is embedded, operating-level mid-cycle pre-tax earning power sits nearer JPY 5.5-6.0 billion, against which the market capitalisation is about 7 times. Earning power has been durable in range (JPY 3.5-17 billion of ordinary profit across a decade with no loss year at the ordinary level), but the five-year window contains one supercycle descent and one trough, so its mean is a fair mid-cycle estimate only if FY3/19-style peaks and FY3/21-style troughs remain equally possible.
内部研究类型:NORMALIZED_EARNINGS_JUDGEMENT
内部来源标记:COVERAGE35
普通股东含义(原始记录):On normalised numbers the shares are cheap but not absurd; on trough numbers they are full: the decision is the cycle judgement plus the governance option.
不确定性(原始记录):Pre-FY3/25 operating profit history is not fully disclosed, so the operating-level range is derived from ordinary profit and FY3/26 non-operating detail, not a precise series.
F022|06|经常利润里有约三分之一不是卖碳素赚来的
研究范围:开放研究+35项覆盖检查
写入正文:06|经常利润里有约三分之一不是卖碳素赚来的14|经营面四个维度:财务最强,盈利与商业结构偏弱
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接 / 支持;一手验证:16、32;同业比较:14;其他用途:历史
Normalisation base: five-year ordinary-profit record and its financial-income content怎么使用:直接 / 支持;一手验证:28;专项深挖:12、16、28
Non-operating quality: subsidies and affiliate losses inside ordinary profit怎么使用:直接 / 支持;反向验证:16、28、32
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|Normalisation base: five-year ordinary-profit record and its financial-income content;直接证据 / 支持证据 / 反证(研究域16) / 反证(研究域28) / 反证(研究域32)|Non-operating quality: subsidies and affiliate losses inside ordinary profit
完整研究记录(核对用)
研究原文:Reported ordinary profit overstates the operating franchise in the trough. FY3/26 non-operating income of JPY 1,716 million (dividends JPY 845 million, subsidies JPY 445 million against JPY 26 million a year earlier, FX gains JPY 189 million, interest JPY 131 million) lifts ordinary profit 42% above operating profit. About a third of ordinary profit is not from selling carbon products, so the carbon businesses earned closer to JPY 4.0-4.4 billion of recurring operating-level profit. Three layers with three durabilities sit in one number: cathode operating margin (cyclical, real), electrode margin (impaired, contested) and financial income (stable, unrelated to operations). Any normalisation that starts from ordinary profit inherits the flattery.
内部研究类型:PROFIT_QUALITY_STRUCTURE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The same reported ordinary profit is worth less per yen than in FY3/24 because its mix shifted toward financial income; capitalise the layers separately.
不确定性(原始记录):Subsidy recurrence is unexplained in the sources read; the equity-method loss is small.
F023|06|经常利润里有约三分之一不是卖碳素赚来的
研究范围:35项覆盖检查
写入正文:06|经常利润里有约三分之一不是卖碳素赚来的15|哪些事实没有读到,会如何限制判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接证据;一手验证:32;反向验证:20
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接证据;一手验证:16、32;同业比较:14;其他用途:历史
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Non-operating quality: subsidies and affiliate losses inside ordinary profit怎么使用:直接证据;反向验证:16、28、32
Tax mechanics of the loss year: a deferred-tax credit cushioned the bottom line怎么使用:直接证据;外部现实校验:32;专项深挖:32
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 反证(研究域16) / 反证(研究域28) / 反证(研究域32)|Non-operating quality: subsidies and affiliate losses inside ordinary profit;直接证据 / 外部现实(研究域32) / 定向深挖(研究域32)|Tax mechanics of the loss year: a deferred-tax credit cushioned the bottom line
完整研究记录(核对用)
研究原文:Four disclosed items sit between operating reality and reported profit: the JPY 6,063 million electrode impairment (an economic admission, not cosmetic); a JPY 1,852 million deferred-tax adjustment gain generated by the impairment (net tax credit JPY 349 million on a JPY 423 million pre-tax loss, non-repeatable, flattering FY3/26's bottom line versus FY3/27's normal tax charge on JPY 3,000 million); subsidy income of JPY 445 million inside ordinary profit; and a partial numerical correction to the FY3/26 tanshin published 19 June 2026. None signals concealment; accounting reads as conservative-with-explanations.
内部研究类型:ACCOUNTING_ITEMS_REGISTER
内部来源标记:COVERAGE35
普通股东含义(原始记录):Adjusted for the four items the company is cleaner and less dramatic than headlines show in both directions; deferred tax assets are not cash.
不确定性(原始记录):The correction notice figures and the tax and subsidy notes were not read line by line; the securities report notes (filed 19 June 2026) are the reference.
F024|09|指引按低谷编制,真正的检验是第二季度阴极块销量
研究范围:开放研究+35项覆盖检查
写入正文:09|指引按低谷编制,真正的检验是第二季度阴极块销量11|计划的可信度要靠每一期财报重建
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接 / 支持;一手验证:31、35;反向验证:05、14、27
Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan怎么使用:直接 / 支持;反向验证:31
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 支持证据 / 反证(研究域31)|Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan
完整研究记录(核对用)
研究原文:FY3/27 guidance (14 May 2026) is built as a trough: sales JPY 26,500 million (+5.6%), operating profit JPY 3,400 million (-15.2%, a third straight annual decline), ordinary profit JPY 4,400 million, net income JPY 3,000 million, EPS JPY 149.64, at USD/JPY 155 with the Middle East explicitly excluded. The interim plan (sales JPY 10,600 million, operating profit JPY 1,100 million, net income JPY 1,300 million) was held at Q1. Subtracting Q1 actuals leaves an implied Q2 of sales about JPY 5,057 million and operating profit only about JPY 336 million (6.6% margin). Q1 delivered 52% of planned sales, 69% of operating profit, 74% of ordinary profit and 94% of net income, but the last only because of a JPY 527 million securities-sale gain. The interim verdict therefore turns on second-quarter cathode volume, the one number one-offs cannot fake; the plan embeds either deliberate conservatism or a genuinely weak expected Q2.
内部研究类型:GUIDANCE_CONSTRUCTION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A 'guidance held' headline can hide either a volume beat or a volume miss; one quarter and one product line decide whether guidance credibility is rebuilt.
不确定性(原始记录):H1 results had not been published at the review date; implied Q2 is arithmetic on an unchanged plan, not company guidance.
F025|09|指引按低谷编制,真正的检验是第二季度阴极块销量
研究范围:35项覆盖检查
写入正文:09|指引按低谷编制,真正的检验是第二季度阴极块销量
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接证据;一手验证:14、31
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接证据;一手验证:31、35;反向验证:05、14、27
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 反证(研究域31)|Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan
完整研究记录(核对用)
研究原文:Expectations are set by the company itself: no sell-side chorus was read, so guidance credibility is the expectations mechanism and the April plan break has already taxed it once. The bar is low, one-off flattery is disclosed and the volume line cannot be dressed up, so the asymmetry favours the sceptic about headlines. Traded multiples (about 13.5-13.6 times forecast) price guidance as roughly honest.
内部研究类型:EXPECTATIONS_JUDGEMENT
内部来源标记:COVERAGE35
普通股东含义(原始记录):A print-day move depends less on the headline than on cathode volume versus the implied weak Q2.
不确定性(原始记录):No analyst consensus series was read; whether 'within the expected range' language survives the H1 print is unknown.
F026|06|利润率下降来自销量,不来自成本
研究范围:开放研究+35项覆盖检查
写入正文:06|利润率下降来自销量,不来自成本08|资本在换方向:电极减值,同时新设备完工,新工程又开工
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
The capex cycle: a facility completed into the trough, depreciation stepping up怎么使用:直接 / 支持;一手验证:04、20;专项深挖:04、20;同业比较:04;其他用途:历史
Inventory structure: work in process is 47% of a year's sales怎么使用:直接 / 支持;一手验证:06、19;反向验证:17、29;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|The capex cycle: a facility completed into the trough, depreciation stepping up;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales
完整研究记录(核对用)
研究原文:Capacity is being rotated. Electrode assets were written down by JPY 6,063 million in the same year a large facility completed (construction in progress fell from JPY 8,505 million to JPY 1,552 million, machinery gross up JPY 2,956 million, buildings up JPY 1,090 million) and a new build cycle began (JPY 2,674 million by Q1 FY3/27, +JPY 1,121 million in the quarter). Depreciation stepped up from JPY 1,304 million to JPY 2,048 million and reached JPY 430 million in Q1 alone. Capital is being re-pointed away from commodity electrodes, but the filings do not say toward what, at what return. The higher fixed-cost floor arrives ahead of the recovery: operating leverage will be sharp if cathode volume delivers and the trough gets more expensive to sit in if it disappoints.
内部研究类型:CAPITAL_ALLOCATION_ROTATION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The shareholder has already paid for the next decade's capacity; what remains is utilisation risk and whether it earns above the cost of capital.
不确定性(原始记录):Product, purpose and budget of the completed facility and of the new construction are undisclosed; capex return and cost of capital are not stated.
F027|08|分红下限在亏损年度也没动,波动由分红比例吸收
研究范围:开放研究+35项覆盖检查
写入正文:08|分红下限在亏损年度也没动,波动由分红比例吸收
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Dividend policy: the higher of JPY 100 per share or a 30% payout ratio怎么使用:直接 / 支持;一手验证:26
Dividend record: JPY 100 held through the cycle turn, by formula怎么使用:直接 / 支持;一手验证:26
The dividend-on-equity anchor: the floor is a 2.6% DOE commitment怎么使用:直接 / 支持;专项深挖:26
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26)|Dividend policy: the higher of JPY 100 per share or a 30% payout ratio;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 100 held through the cycle turn, by formula;直接证据 / 支持证据 / 定向深挖(研究域26)|The dividend-on-equity anchor: the floor is a 2.6% DOE commitment
完整研究记录(核对用)
研究原文:Distribution policy is the higher of JPY 100 per share or a 30% consolidated payout. JPY 2,004 million was paid in both FY3/25 and FY3/26 (through a loss year, formula unchanged), with JPY 100 forecast for FY3/27 (interim 50, final 50), a 66.8% payout on forecast EPS of JPY 149.64: the floor clause, not the ratio clause, does the work. Against equity it is a dividend-on-equity floor of about 2.6% (FY3/26) to 2.8% (FY3/25); at the November price it is a 4.9% yield. The payout ratio absorbs earnings volatility while the dividend and therefore the yield floor stay stable.
内部研究类型:SHAREHOLDER_RETURN_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The waiting is compensated at about 5%, shifting the decision from if to how long; the formula survived a loss year unchanged.
不确定性(原始记录):A cut would require a formula change; whether the formula is ever raised is the signal not yet observed.
F028|08|回购方向已经打开,规模太小,推不动折价
研究范围:开放研究+35项覆盖检查
写入正文:08|回购方向已经打开,规模太小,推不动折价14|价格与股东面四个维度:估值偏正面,治理和技术没有倾向
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Dividend policy: the higher of JPY 100 per share or a 30% payout ratio怎么使用:直接 / 支持;一手验证:26
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
Share count: unchanged issuance, slow treasury accumulation怎么使用:直接证据;一手验证:25
Q1 FY3/2027 equity walk: the quarter's profit was fully distributed or bought back怎么使用:直接证据;反向验证:18、22、25、26
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:直接 / 支持;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover怎么使用:直接 / 支持;专项深挖:25;同业比较:25;其他用途:历史
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接证据;专项深挖:13、30
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:支持证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26)|Dividend policy: the higher of JPY 100 per share or a 30% payout ratio;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 一手证据(研究域25)|Share count: unchanged issuance, slow treasury accumulation;直接证据 / 反证(研究域18) / 反证(研究域22) / 反证(研究域25) / 反证(研究域26)|Q1 FY3/2027 equity walk: the quarter's profit was fully distributed or bought back;直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;直接证据 / 支持证据 / 历史/同业比较(研究域25) / 定向深挖(研究域25)|Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover;直接证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change
完整研究记录(核对用)
研究原文:Capital conversion has begun at walking pace. A buyback authorised on 14 May 2026, the day results were announced, bought 207,500 shares for JPY 529 million in Q1 (average about JPY 2,549) and was completed on 16 September 2026; off-auction buybacks also occurred in June and September 2024. Treasury shares rose from 646,695 to 854,195 (4.1% of issued); issuance has been frozen at 20,694,340 and the weighted-average count fell from 20,135,249 to 19,975,434. Retiring shares near JPY 2,549 against book value per share of JPY 3,871 transfers value to remaining holders, but the pace of about JPY 0.5-1.0 billion a year moves a JPY 77.6 billion equity base by about 1% a year. In Q1 FY3/27 net assets eased JPY 52 million despite JPY 1,224 million of net income: profits are returned about as fast as earned, and the pile does not shrink. The first securities sale (JPY 527 million gain) accompanied it. No treasury-share cancellation appears.
内部研究类型:CAPITAL_CONVERSION_PROGRESS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Direction is set and instruments are unblocked; scale is too small to change the discount, and the 2026 average price is roughly 25% above the 6 November close.
不确定性(原始记录):Full programme size is taken from the executed Q1 amount and the completion notice; later-quarter purchases are not read.
F029|08|12%的股本回报率目标,隐含着股本要缩小
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接证据;一手验证:11、13、22、35;反向验证:23、33
The ROE bridge the 2030 policy must cross怎么使用:直接 / 支持;一手验证:22;专项深挖:11、22
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域11) / 定向深挖(研究域22)|The ROE bridge the 2030 policy must cross;直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language
完整研究记录(核对用)
研究原文:ROE ran 10.8% at the FY3/24 peak, an estimated 4-5% in FY3/26 and is forecast at 3.9% for FY3/27. The 12% FY3/31 target cannot be reached by the profit leg alone on any guided trajectory: on unchanged equity of about JPY 77.6 billion it needs roughly JPY 9.3 billion of net income, three times the FY3/27 forecast. It is therefore silently a joint promise about earnings recovery and equity shrinkage, and only the first half has numbers attached. The abandoned plan had staged ROE at 8% for FY3/30, implying management expected the profit leg to do most of the work; the new policy adds capital-policy advancement as a pillar without quantifying the split.
内部研究类型:CAPITAL_EFFICIENCY_ARITHMETIC
内部来源标记:COVERAGE35
普通股东含义(原始记录):Without a denominator policy ROE mean-reverts to mid-single digits; with one the target is arithmetic, not hope. Current return is dividend yield plus slow book compounding.
不确定性(原始记录):No company cost-of-capital estimate or quantified capital-efficiency milestone was read.
F030|07|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回
研究范围:开放研究+35项覆盖检查
写入正文:07|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接证据;反向验证:12;同业比较:35;其他用途:历史
Plan arithmetic: even the plan document's near-term outlook overshot the year怎么使用:直接 / 支持;反向验证:11
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 支持证据 / 反证(研究域11)|Plan arithmetic: even the plan document's near-term outlook overshot the year
完整研究记录(核对用)
研究原文:On 10 April 2026 the company abolished its ninth three-year mid-term plan rather than miss it quietly and replaced it with the '2030 Make Real' policy: FY3/31 targets of sales JPY 54,000 million, operating profit JPY 10,000 million and ROE 12%, via strengthening the growth strategy and advancing capital policy. The abandoned plan targeted FY3/27 sales of JPY 44,000 million and operating profit of JPY 8,000 million, against FY3/27 guidance a month later of JPY 26,500 million and JPY 3,400 million (40% and 58% short). Even the plan document's FY3/26 outlook (sales JPY 29,200 million) overshot the actual result (JPY 25,101 million) by 14% five weeks before printing, exposing a near-term optimism bias. The FY3/31 sales target is more than double FY3/26 in a mature, slow-growth market, so it arithmetically requires share gain, a supercycle, or both; it should be treated as an aspiration to be re-earned through prints, not a path.
内部研究类型:PLAN_CREDIBILITY_JUDGEMENT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Credibility has to be rebuilt print by print starting with the H1 FY3/27 tanshin; candid abolition is mildly positive governance behaviour but removes any quantified roadmap.
不确定性(原始记录):Which growth sources management names and funds is unknown.
F031|07|2026年管理层的动作偏积极,但规模都不大
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接 / 支持;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:直接证据;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Leadership: a representative-director change was announced on 8 June 2026怎么使用:直接 / 支持;一手验证:23;反向验证:13、30;专项深挖:01、23
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;直接证据 / 支持证据 / 一手证据(研究域23) / 反证(研究域13) / 反证(研究域30) / 定向深挖(研究域01) / 定向深挖(研究域23)|Leadership: a representative-director change was announced on 8 June 2026
完整研究记录(核对用)
研究原文:The 2026 governance calendar was active: mid-term plan abolished 10 April, controlling-shareholder filing 24 April, FY3/26 results with impairment, buyback authorisation and dividend decision on 14 May, representative-director change announced 8 June ahead of the 26 June AGM, a partial numerical correction to the tanshin on 19 June, monthly buyback notices, and completion on 16 September. The board is managing toward credibility inside a perimeter the controlling bloc defines, conceding failures in print rather than promoting. No specific agenda for the leadership change is stated in any source read.
内部研究类型:GOVERNANCE_BEHAVIOUR
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Minorities cannot change the perimeter and can only judge whether behaviour inside it is improving; 2026 evidence is mildly positive.
不确定性(原始记录):Board composition and the governance report were not re-read; the new leadership's first full-year print is outstanding.
F032|01|两条腿各自会倒,只有阴极块资产减值会伤到根本
研究范围:35项覆盖检查
写入正文:01|两条腿各自会倒,只有阴极块资产减值会伤到根本07|2026年是方向转变,还是一组一次性事件
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接证据;一手验证:11、13、22、35;反向验证:23、33
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Corporate background: founded 1934, an independent carbon maker in the Otani orbit怎么使用:直接证据;一手验证:33;同业比较:01、09、12、23;其他用途:历史
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:直接证据;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接证据;专项深挖:13、30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域23)|Corporate background: founded 1934, an independent carbon maker in the Otani orbit;直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines;直接证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language
完整研究记录(核对用)
研究原文:Historically every turn in this name was delivered by the product cycle (FY3/19 supercycle and give-back; FY3/24 second peak). 2026 is the first year in which management and register actions (plan abolition, impairment, buyback, securities sale, leadership change) outnumber cycle events. Reading A: a regime change toward capital and governance, meaning today's price is a trough multiple on a re-rating asset. Reading B: a cluster of one-offs, meaning a fair price on a cyclical. The H1 and full-year prints and capital-policy follow-through discriminate between them.
内部研究类型:COMPETING_HYPOTHESIS
内部来源标记:COVERAGE35
普通股东含义(原始记录):Determines whether the discount is expected to close through governance or only through the cycle.
不确定性(原始记录):Unresolved by design; follow-through in FY3/27-FY3/28 disclosure, more instruments or silence, is required.
F033|11|最大的风险是去库存复发,而且新固定成本让复发更贵
研究范围:开放研究+35项覆盖检查
写入正文:11|最大的风险是去库存复发,而且新固定成本让复发更贵
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
Management outlook: every product line still described as facing a harsh environment怎么使用:直接 / 支持;一手验证:14;反向验证:04、06、35
Inventory structure: work in process is 47% of a year's sales怎么使用:直接 / 支持;一手验证:06、19;反向验证:17、29;专项深挖:19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 支持证据 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales
完整研究记录(核对用)
研究原文:The trough reading fails if the cathode inventory adjustment relapses or smelters defer relining again, a risk management itself flags alongside cheap electrode imports. Inventory is the relapse sensor: work in process is 47% of annual sales (JPY 11,766 million) and total inventories 73% (JPY 18,252 million), so renewed destocking would show up first as inventory build and margin compression, and the FY3/26 pattern, a recovery that took longer than expected, is the documented precedent. Management's outlook still describes every product line as facing a harsh environment.
内部研究类型:PRINCIPAL_RISK
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):A relapse would compound the cost of the new fixed-cost floor and delay both Thesis legs.
不确定性(原始记录):Order intake and relining schedules are not disclosed; inventory book value is not treated as liquid downside value (no evidence on saleability or haircut).
F034|11|日元和中东:外部冲击到达利润表,比资产负债表的防御来得快
研究范围:开放研究+35项覆盖检查
写入正文:11|日元和中东:外部冲击到达利润表,比资产负债表的防御来得快
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Management outlook: every product line still described as facing a harsh environment怎么使用:直接证据;一手验证:14;反向验证:04、06、35
FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155怎么使用:直接 / 支持;外部现实校验:06、14;专项深挖:14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment;直接证据 / 支持证据 / 外部现实(研究域06) / 外部现实(研究域14) / 定向深挖(研究域14)|FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155
完整研究记录(核对用)
研究原文:About 73% of sales (JPY 18,356 million) are exported and the forecast is struck at USD/JPY 155. FY3/26 booked JPY 189 million of FX gains, and ordinary profit beat forecast on a weaker yen and larger dividends; Q1 FY3/27 credits yen weakness for part of the recovery. A yen reversal is the fastest route to a guidance miss and would expose how deep the volume trough still is. No hedge policy is described. Management excluded the Middle East situation from guidance as unquantifiable, and the largest regional sales block (Asia and Middle East, JPY 7,631 million) contains the unmeasured exposure. Policy transmission is second order: decarbonisation supports customers' processes and taxes the company's own energy-intensive graphitisation.
内部研究类型:EXTERNAL_EXPOSURE_RISK
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The holder is long yen weakness and the aluminium cycle together; an external shock reaches the P&L faster than the balance sheet's defences matter.
不确定性(原始记录):Sensitivities are unquantified; hedging is undisclosed; Middle East cathode exposure is unknown.
F035|11|最近的验证是中期决算,之后是年度决算和资本政策的数字
研究范围:开放研究+35项覆盖检查
写入正文:11|最近的验证是中期决算,之后是年度决算和资本政策的数字
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接 / 支持;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接 / 支持;一手验证:31、35;反向验证:05、14、27
The interim print's timing: mid-November on a consistent calendar怎么使用:直接证据;一手验证:30;专项深挖:31、35
查看完整证据标签(核对用)
直接证据 / 支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 反证(研究域31)|Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan;直接证据 / 一手证据(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|The interim print's timing: mid-November on a consistent calendar
完整研究记录(核对用)
研究原文:The H1 FY3/27 interim tanshin, expected around 12-13 November 2026 on the prior-year pattern (13 November in 2024 and 2025, with a same-day revision notice in 2025) and not published at the review date, is the nearest verdict: whether guidance survives a quarter the plan built to be weak, and whether cathode volume confirms the Q1 turn. The FY3/27 full-year print and year-end dividend decision (May 2027) and the securities-report register (June 2027) follow.
内部研究类型:DATED_CATALYST
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Four prints a year and a standing set of capital-policy tripwires make the calendar legible; the thin float re-prices in days on disclosure.
不确定性(原始记录):Date inferred from pattern; outcome not knowable at the cut-off.
F036|08|资本政策要有数字,才算催化剂
研究范围:开放研究+35项覆盖检查
写入正文:08|资本政策要有数字,才算催化剂11|最近的验证是中期决算,之后是年度决算和资本政策的数字
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接证据;一手验证:11、13、22、35;反向验证:23、33
Cross-holding web: peers and partners on both sides of the register怎么使用:直接 / 支持;专项深挖:07、24;同业比较:21;其他用途:历史
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:直接 / 支持;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register;直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language
完整研究记录(核对用)
研究原文:The capital-policy pillar becomes a catalyst only when it acquires numbers: a treasury cancellation, a quantified securities-unwind programme, a raised dividend floor, or a buyback sized in billions rather than hundreds of millions. The 2026 record (completed buyback, first portfolio sale, ROE pledge) shows the instruments are unblocked, so the next disclosure on any of them reprices the discount directly. None of the three 2026 facts yet moves the equity base materially, which is the gap the valuation prices.
内部研究类型:CATALYST_CONDITION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The most direct path from the financial pile to per-share value.
不确定性(原始记录):No timetable, no bloc intent statement.
F037|01|股价在押一个治理问题,周期只是第二个期权
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|股价在押一个治理问题,周期只是第二个期权01|两条腿各自会倒,只有阴极块资产减值会伤到根本14|总分61.39/100,评级B:资产强、盈利平,技术无倾向
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Management outlook: every product line still described as facing a harsh environment怎么使用:一手验证:14;反向验证:04、06、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;反证 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment
完整研究记录(核对用)
研究原文:The shares price a permanent mid-cycle discount on a debt-free balance sheet whose financial assets alone exceed the market capitalisation. The position re-rates only if one of two dated processes delivers: the cathode-block replacement cycle printing rising volume and operating leverage through FY3/27's second half, or the capital-policy pillar of the 2030 framework converting the securities-and-cash pile into buybacks, cancellations or distributions at a pace minorities can measure. Absent both, the JPY 100 dividend floor and slow buybacks are carry, not catalyst. The thesis is a conjunction (trough and conversion option), so it degrades gracefully: each falsifier removes one leg and reprices the other, except a cathode-asset impairment, which attacks the franchise itself.
内部研究类型:INVESTMENT_THESIS
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Instruction set: hold while falsifiers stay unprinted and the carry pays; re-underwrite on the first falsifier; exit on the franchise-level one.
不确定性(原始记录):Counter-evidence: the 2026 sequence may be a cluster of one-offs rather than a regime change; capital conversion has no deadline so discipline must come from the dated falsifiers, not patience alone.
F038|01|什么会推翻这个判断
研究范围:35项覆盖检查
写入正文:01|什么会推翻这个判断
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接证据;一手验证:14、31
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接证据;一手验证:11、13、22、35;反向验证:23、33
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接证据;一手验证:31、35;反向验证:05、14、27
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接证据;专项深挖:13、30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language
完整研究记录(核对用)
研究原文:Dated, observable falsifiers: a guidance cut with cathode volume falling at H1; a second impairment, or any impairment of cathode assets (franchise-level); the dividend formula amended downward; the securities pile untouched and buybacks stopped through FY3/28; and evidence of share loss at a major relining programme. Falsification is defined on company disclosures and prints, not on price levels: price can falsify timing but not the thesis.
内部研究类型:FALSIFICATION_CONDITIONS
内部来源标记:COVERAGE35
普通股东含义(原始记录):Gives the holder concrete exit and re-underwriting triggers.
不确定性(原始记录):Residual unknown is controlling-bloc intent, which no disclosure regime compels.
F039|09|下行保护有三层,风险是时间而不是本金
研究范围:35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接证据;一手验证:18、20、21、29
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:直接证据;一手验证:18、29
Dividend record: JPY 100 held through the cycle turn, by formula怎么使用:直接证据;一手验证:26
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;直接证据 / 一手证据(研究域26)|Dividend record: JPY 100 held through the cycle turn, by formula
完整研究记录(核对用)
研究原文:Downside protection is financial and structural: book value JPY 3,871 per share against a JPY 2,042 price, JPY 45.3 billion of financial assets, no debt, a dividend floor paying 4.9%, and a controlling register with no forced sellers. Each layer (asset coverage, income floor, register stability) fails independently. The realistic downside is duration, years of about 5% carry while the discount persists, an opportunity-cost loss rather than a capital loss. Three events would break it: a bloc sale, a formula repeal, or a catastrophic capex error. Asset coverage grows by retained earnings each year the formula holds.
内部研究类型:DOWNSIDE_STRUCTURE
内部来源标记:COVERAGE35
普通股东含义(原始记录):Risk is time, not ruin.
不确定性(原始记录):Forced-liquidation value and land market value are not estimated; securities are partly relationship holdings that may be hard to monetise without cost.
F040|05|耐久对企业成立,对股票有条件
研究范围:开放研究
写入正文:05|耐久对企业成立,对股票有条件
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接证据;一手验证:02、03、09、15;反向验证:08
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接证据;一手验证:32;反向验证:20
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接证据;一手验证:18、20、21、29
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接证据;一手验证:01、07、24;外部现实校验:23
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接证据;一手验证:02、05、07、15
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales
完整研究记录(核对用)
研究原文:The durable core is a qualified consumable franchise wrapped in an over-capitalised shell. The franchise (SK-B cathode blocks qualified into the world's aluminium smelters, produced by a 92-year-old graphitisation process) survived the 2008 crisis, the electrode supercycle's rise and collapse and a two-year customer inventory strike, earning a 16% operating margin in its worst recent year. The shell (89% equity, no debt, JPY 45 billion of financial assets) lets the franchise wait out any customer cycle. Fragilities are equally structural: two thirds of revenue rides one product's maintenance calendar; the second franchise is formally impaired; three quarters of sales are exported through one channel; and the controlling register has not yet converted the shell into per-share value at a measurable pace. Durability is total for the enterprise and conditional for the share.
内部研究类型:STRUCTURAL_DURABILITY_JUDGEMENT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The company will be making cathode blocks in ten years; whether the share still trades below its securities portfolio depends on decisions in Toyama and the boardroom, not in the furnaces.
不确定性(原始记录):2008-crisis survival is background-sourced rather than read from primary filings in this research.
F041|11|最近的验证是中期决算,之后是年度决算和资本政策的数字
研究范围:开放研究
写入正文:11|最近的验证是中期决算,之后是年度决算和资本政策的数字13|最近的两道检验:中期决算和阴极块订单
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接证据;一手验证:31、35;反向验证:05、14、27
The interim print's timing: mid-November on a consistent calendar怎么使用:直接证据;一手验证:30;专项深挖:31、35
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 反证(研究域31)|Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan;直接证据 / 一手证据(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|The interim print's timing: mid-November on a consistent calendar
完整研究记录(核对用)
研究原文:What will the H1 FY3/27 interim tanshin show against the interim plan: is the implied weak second quarter (about JPY 336 million of operating profit) beaten on cathode-block volume, and does full-year guidance survive? Opposite answers separate a volume-led recovery from a one-off-flattered quarter; resolving evidence is the H1 tanshin and its guidance decision, expected about 12-13 November 2026 (after this review's information set).
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Nearest dated test of the cycle leg and guidance credibility.
不确定性(原始记录):Future disclosure; no reasonable current public path.
F042|03|订单数据缺位,是判断复苏斜率的最大缺口
研究范围:开放研究
写入正文:03|订单数据缺位,是判断复苏斜率的最大缺口13|最近的两道检验:中期决算和阴极块订单
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接证据;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接证据;反向验证:12;同业比较:35;其他用途:历史
The cathode demand frame: relining cycles and smelter construction怎么使用:直接证据;一手验证:11;外部现实校验:02、03、10、11、15;专项深挖:03、05
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05)|The cathode demand frame: relining cycles and smelter construction
完整研究记录(核对用)
研究原文:Is the cathode-block inventory adjustment at aluminium smelters genuinely over? Q1 FY3/27 cathode sales rose 51.8% with help from shipment timing; order intake and smelter relining schedules for the second half and FY3/28 are the resolving evidence. If the adjustment relapses, the trough reading and the cycle leg fail; if over, operating leverage on a higher fixed-cost base becomes sharp.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Decides whether operating earnings recover.
不确定性(原始记录):Order intake and backlog are not disclosed; H1 product sales are the next observable.
F043|06|账面亏损是承认,不是现金事件
研究范围:开放研究
写入正文:06|账面亏损是承认,不是现金事件13|产品、投资和地区上还没有答案的三件事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接证据;一手验证:32;反向验证:20
The electrode frame: structurally favoured process, cyclically hostile pricing怎么使用:直接证据;一手验证:08;反向验证:10;专项深挖:08
Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line怎么使用:直接证据
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 一手证据(研究域08) / 反证(研究域10) / 定向深挖(研究域08)|The electrode frame: structurally favoured process, cyclically hostile pricing;直接证据|Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line
完整研究记录(核对用)
研究原文:What is the electrode business's endgame after the JPY 6,063 million impairment: capacity reduction, a price/mix retreat to defensible grades, or continued operation at written-down cost, and what return does management now expect from the written-down asset base? Resolving evidence: electrode sales line in coming prints, capacity or product disclosures, trade pricing.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Determines whether a further write-down or exit cost remains.
不确定性(原始记录):No company statement on strategy was read.
F044|08|资本在换方向:电极减值,同时新设备完工,新工程又开工
研究范围:开放研究
写入正文:08|资本在换方向:电极减值,同时新设备完工,新工程又开工13|产品、投资和地区上还没有答案的三件事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接证据;外部现实校验:20
The capex cycle: a facility completed into the trough, depreciation stepping up怎么使用:直接证据;一手验证:04、20;专项深挖:04、20;同业比较:04;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 一手证据(研究域04) / 一手证据(研究域20) / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|The capex cycle: a facility completed into the trough, depreciation stepping up
完整研究记录(核对用)
研究原文:What is the new construction in progress (JPY 2,674 million at Q1 FY3/27, rising again after the FY3/26 completion) building, for which product, and at what expected return? A capex notice or results-materials disclosure naming the project would resolve it; the answer decides whether capital is being aimed at an extension of the cathode niche or a second niche.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Largest undisclosed capital fact; sets ROIC risk on the new build.
不确定性(原始记录):Not disclosed in the sources read.
F045|08|资本政策要有数字,才算催化剂
研究范围:开放研究
写入正文:08|资本政策要有数字,才算催化剂13|资本政策能不能变成可测量的数字
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接证据;一手验证:11、13、22、35;反向验证:23、33
Cross-holding web: peers and partners on both sides of the register怎么使用:直接证据;专项深挖:07、24;同业比较:21;其他用途:历史
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:直接证据;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接证据;专项深挖:13、30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register;直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;直接证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language
完整研究记录(核对用)
研究原文:Will the capital-policy pillar become measurable: a faster unwind of the JPY 28.1 billion investment-securities portfolio (sales began in Q1 FY3/27), cancellation of the 854,195 treasury shares, larger buybacks, or a higher dividend floor, and on what timetable? Resolving evidence: any numbered capital-policy notice, the FY3/27 dividend decision (May 2027) and the securities-report schedules (June 2027).
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Second leg of the Thesis.
不确定性(原始记录):No timetable disclosed.
F046|07|股东名册就是折价:控股集团加两家商社
研究范围:开放研究
写入正文:07|股东名册就是折价:控股集团加两家商社13|资本政策能不能变成可测量的数字
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接证据;一手验证:01、07、24;外部现实校验:23
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Leadership: a representative-director change was announced on 8 June 2026怎么使用:直接证据;一手验证:23;反向验证:13、30;专项深挖:01、23
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 一手证据(研究域23) / 反证(研究域13) / 反证(研究域30) / 定向深挖(研究域01) / 定向深挖(研究域23)|Leadership: a representative-director change was announced on 8 June 2026
完整研究记录(核对用)
研究原文:What does the Otani Steel controlling bloc want from this holding over the 2030 framework's horizon, and did the June 2026 representative-director change alter the capital-allocation agenda? Large-holding report changes, the FY3/27 register and governance report (June 2027) are the only observable evidence; no disclosure regime compels an intent statement.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):The single largest information event available in the register; sets the discount's duration.
不确定性(原始记录):Likely to remain unresolved by disclosure.
F047|11|日元和中东:外部冲击到达利润表,比资产负债表的防御来得快
研究范围:开放研究
写入正文:11|日元和中东:外部冲击到达利润表,比资产负债表的防御来得快13|产品、投资和地区上还没有答案的三件事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接证据;一手验证:02、03、09、15;反向验证:08
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接证据;一手验证:14、31
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接证据;一手验证:02、05、07、15
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接证据;一手验证:31、35;反向验证:05、14、27
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter
完整研究记录(核对用)
研究原文:How large is the Middle East exposure inside the Asia/Middle East sales region (JPY 7,631 million in FY3/26), given that management excluded the region's geopolitical impact from guidance as unquantifiable? Regional detail in the FY3/27 tanshin or a revision notice quantifying the excluded risk would resolve it.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Unbounded tail risk to guidance and cathode timing.
不确定性(原始记录):Undisclosed within a regional aggregate.
F048|07|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回
研究范围:开放研究
写入正文:07|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回13|产品、投资和地区上还没有答案的三件事
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接证据;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接证据;一手验证:05;反向验证:03、19
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接证据;一手验证:11、13、22、35;反向验证:23、33
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31
完整研究记录(核对用)
研究原文:Can the specialty and fine-powder lines (semiconductor- and battery-adjacent demand) grow fast enough to matter against a JPY 54,000 million FY3/31 sales target, or does the target arithmetic silently assume a full cathode supercycle? These lines are 14.6% of sales; growth-strategy detail in FY3/27 results materials would resolve it.
内部研究类型:RESEARCH_DEBT
内部来源标记:OPEN_DISCOVERY
普通股东含义(原始记录):Tests whether diversification is real optionality or only nominal.
不确定性(原始记录):Per-product margins undisclosed.
F049|08|12%的股本回报率目标,隐含着股本要缩小
研究范围:35项覆盖检查
写入正文:08|12%的股本回报率目标,隐含着股本要缩小13|资本政策能不能变成可测量的数字
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接证据;一手验证:11、13、22、35;反向验证:23、33
The ROE bridge the 2030 policy must cross怎么使用:直接证据;一手验证:22;专项深挖:11、22
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接证据;专项深挖:13、30
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 一手证据(研究域22) / 定向深挖(研究域11) / 定向深挖(研究域22)|The ROE bridge the 2030 policy must cross;直接证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language
完整研究记录(核对用)
研究原文:What split between profit recovery and equity reduction does the board assume in the FY3/31 ROE target of 12%, and will it publish interim milestones (a DOE floor, a total-return ratio, a portfolio-unwind amount) that let holders measure the capital-policy pillar before 2030? Resolving evidence: FY3/27 results materials (May 2027) or any interim capital-policy notice.
内部研究类型:RESEARCH_DEBT
内部来源标记:COVERAGE35
普通股东含义(原始记录):Turns an aspiration into a measurable commitment.
不确定性(原始记录):No company cost-of-capital or split disclosed.
F050|08|回购方向已经打开,规模太小,推不动折价
研究范围:35项覆盖检查
写入正文:08|回购方向已经打开,规模太小,推不动折价13|资本政策能不能变成可测量的数字
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:直接证据;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover怎么使用:直接证据;专项深挖:25;同业比较:25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;直接证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap;直接证据 / 历史/同业比较(研究域25) / 定向深挖(研究域25)|Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover
完整研究记录(核对用)
研究原文:Will the 854,195 treasury shares (4.1% of issued) be cancelled, and does the company intend to address its thin effective float and Standard-market liquidity as part of capital policy, or is register stability itself the policy? Resolving evidence: cancellation notices and register changes in the FY3/27 securities report.
内部研究类型:RESEARCH_DEBT
内部来源标记:COVERAGE35
普通股东含义(原始记录):Cancellation would make buybacks visibly permanent per-share transfers; float policy determines how readily a discount can close.
不确定性(原始记录):No cancellation appears in the disclosure index.
F051|03|一个产品的更换周期,决定了这家公司的利润表
研究范围:开放研究
归并到:F086
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
Margin structure: gross margin compressed 4.4 points; SG&A was cut in absolute terms怎么使用:直接 / 支持;一手验证:10、16;同业比较:06;其他用途:历史
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:支持证据;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:支持证据;反向验证:12;同业比较:35;其他用途:历史
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:支持证据;一手验证:16、32;同业比较:14;其他用途:历史
Corporate background: founded 1934, an independent carbon maker in the Otani orbit怎么使用:支持证据;一手验证:33;同业比较:01、09、12、23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域16) / 历史/同业比较(研究域06)|Margin structure: gross margin compressed 4.4 points; SG&A was cut in absolute terms;支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;支持证据|FY3/2026 consolidated results: a second consecutive down year;支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域23)|Corporate background: founded 1934, an independent carbon maker in the Otani orbit
完整研究记录(核对用)
研究原文:Cathode-block volume decline (-23.0%) on smelter renewal delay and inventory adjustment, carrying the group's fixed-cost absorption, is the first cause of the 41.3% operating-profit fall.
内部研究类型:CAUSES
内部来源标记:OPEN_DISCOVERY
F052|03|住友集团既是57.8%收入的出口,又是5.02%的股东
研究范围:开放研究+35项覆盖检查
写入正文:03|住友集团既是57.8%收入的出口,又是5.02%的股东14|经营面四个维度:财务最强,盈利与商业结构偏弱
归并到:F007
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(6项,重复标签已合并)
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign怎么使用:直接 / 支持;反向验证:07、15;专项深挖:02
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:支持证据;一手验证:01、07、24;外部现实校验:23
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:支持证据;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:支持证据;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:支持证据;反向验证:12;同业比较:35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 支持证据 / 反证(研究域07) / 反证(研究域15) / 定向深挖(研究域02)|Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign;支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing
完整研究记录(核对用)
研究原文:The Sumitomo-group channel intermediates the most channel-concentrated product line, so cathode volume and channel weight move together.
内部研究类型:INTERMEDIATES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F053|04|电极是被进口价格定价的业务,减值承认了这一点
研究范围:开放研究+35项覆盖检查
写入正文:04|电极是被进口价格定价的业务,减值承认了这一点06|账面亏损是承认,不是现金事件
归并到:F087
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接 / 支持;一手验证:16、32;同业比较:14;其他用途:历史
Tax mechanics of the loss year: a deferred-tax credit cushioned the bottom line怎么使用:直接证据;外部现实校验:32;专项深挖:32
Corporate background: founded 1934, an independent carbon maker in the Otani orbit怎么使用:支持证据;一手验证:33;同业比较:01、09、12、23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 外部现实(研究域32) / 定向深挖(研究域32)|Tax mechanics of the loss year: a deferred-tax credit cushioned the bottom line;支持证据|FY3/2026 consolidated results: a second consecutive down year;支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域23)|Corporate background: founded 1934, an independent carbon maker in the Otani orbit
完整研究记录(核对用)
研究原文:The electrode write-down converts a slow margin problem into a one-time balance-sheet admission that moves FY3/26 from JPY 4,008 million of operating profit to a JPY 74 million net loss, cushioned by a non-repeatable deferred-tax credit.
内部研究类型:CONVERTS_OPERATING_PROFIT_TO_NET_LOSS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F054|06|亏损年度反而更有现金,复苏年度现金会被吸走
研究范围:开放研究+35项覆盖检查
归并到:F013
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
FY3/2026 cash flow: operating cash flow rose through the loss year怎么使用:直接 / 支持;一手验证:17;同业比较:19;其他用途:历史
Working-capital structure: the group pays fast and collects slowly怎么使用:直接 / 支持;一手验证:17、19;专项深挖:10、15、17
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:支持证据;一手验证:18、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19)|FY3/2026 cash flow: operating cash flow rose through the loss year;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 定向深挖(研究域10) / 定向深挖(研究域15) / 定向深挖(研究域17)|Working-capital structure: the group pays fast and collects slowly;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;支持证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden
完整研究记录(核对用)
研究原文:Non-cash impairment and the countercyclical working-capital unwind added cash in the loss year, enlarging the financial pile that drives both downside protection and ROE dilution.
内部研究类型:ADDS_TO
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F055|06|没有借款的资产负债表:金融资产比有形资产还大
研究范围:开放研究+35项覆盖检查
写入正文:06|没有借款的资产负债表:金融资产比有形资产还大09|折价是对资本政策的折价,不是对破产或业务的折价
归并到:F091
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
The ROE bridge the 2030 policy must cross怎么使用:直接 / 支持;一手验证:22;专项深挖:11、22
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:支持证据;一手验证:18、29
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:支持证据;专项深挖:13、30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域11) / 定向深挖(研究域22)|The ROE bridge the 2030 policy must cross;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;支持证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language
完整研究记录(核对用)
研究原文:Half the balance sheet earns financial yields while the operating half earns cyclical materials returns, so the pile is the ROE ceiling and the target depends on a denominator policy.
内部研究类型:CAPS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F056|07|股东名册就是折价:控股集团加两家商社
研究范围:开放研究+35项覆盖检查
写入正文:07|股东名册就是折价:控股集团加两家商社08|资本政策要有数字,才算催化剂09|折价是对资本政策的折价,不是对破产或业务的折价
归并到:F088
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Float behaviour: thin trading, one-sided margin balances, event-day volume怎么使用:直接证据;外部现实校验:24、25、27、30;专项深挖:34
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:支持证据;一手验证:18、20、21、29
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:支持证据;一手验证:02、05、07、15
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:一手验证:11、13、22、35;反向验证:23、33;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域27) / 外部现实(研究域30) / 定向深挖(研究域34)|Float behaviour: thin trading, one-sided margin balances, event-day volume;直接证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap;支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;反证 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31
完整研究记录(核对用)
研究原文:A relationship-held register with no marginal mark-to-market seller and no external pressure mechanism sustains the 0.52-0.53x book discount until the bloc itself chooses conversion.
内部研究类型:CAUSES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F057|07|股东名册和证券组合互为镜像
研究范围:35项覆盖检查
写入正文:07|股东名册和证券组合互为镜像08|资本政策要有数字,才算催化剂
归并到:F017
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Cross-holding web: peers and partners on both sides of the register怎么使用:直接 / 支持;专项深挖:07、24;同业比较:21;其他用途:历史
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:支持证据;一手验证:18、20、21、29
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:支持证据;一手验证:02、05、07、15
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:一手验证:11、13、22、35;反向验证:23、33;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register;支持证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap;支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;反证 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31
完整研究记录(核对用)
研究原文:The cross-holding web stabilises the register while ensuring no hostile pressure that could force the pile into per-share value.
内部研究类型:REINFORCES
内部来源标记:COVERAGE35
F058|09|下行保护有三层,风险是时间而不是本金
研究范围:35项覆盖检查
归并到:F039
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:直接 / 支持;一手验证:18、29
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Valuation arithmetic at the 6 November 2026 close怎么使用:支持证据;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;支持证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close
完整研究记录(核对用)
研究原文:Asset coverage and zero debt form the first independent layer of downside protection.
内部研究类型:SUPPORTS
内部来源标记:COVERAGE35
F059|09|下行保护有三层,风险是时间而不是本金
研究范围:35项覆盖检查
归并到:F039
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Dividend policy: the higher of JPY 100 per share or a 30% payout ratio怎么使用:直接 / 支持;一手验证:26
Dividend record: JPY 100 held through the cycle turn, by formula怎么使用:直接 / 支持;一手验证:26
The dividend-on-equity anchor: the floor is a 2.6% DOE commitment怎么使用:直接 / 支持;专项深挖:26
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:支持证据;外部现实校验:20
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:支持证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26)|Dividend policy: the higher of JPY 100 per share or a 30% payout ratio;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 100 held through the cycle turn, by formula;直接证据 / 支持证据 / 定向深挖(研究域26)|The dividend-on-equity anchor: the floor is a 2.6% DOE commitment;支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change
完整研究记录(核对用)
研究原文:The JPY 100 floor provides a roughly 4.9% income layer that survived a loss year unchanged.
内部研究类型:SUPPORTS
内部来源标记:COVERAGE35
F060|09|低谷利润不算便宜,资产却被打了五折
研究范围:开放研究+35项覆盖检查
写入正文:09|低谷利润不算便宜,资产却被打了五折
归并到:F096
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接 / 支持;一手验证:16、32;同业比较:14;其他用途:历史
Normalisation base: five-year ordinary-profit record and its financial-income content怎么使用:直接 / 支持;一手验证:28;专项深挖:12、16、28
Non-operating quality: subsidies and affiliate losses inside ordinary profit怎么使用:直接 / 支持;反向验证:16、28、32
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:支持证据;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
Valuation arithmetic at the 6 November 2026 close怎么使用:支持证据;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|Normalisation base: five-year ordinary-profit record and its financial-income content;直接证据 / 支持证据 / 反证(研究域16) / 反证(研究域28) / 反证(研究域32)|Non-operating quality: subsidies and affiliate losses inside ordinary profit;支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines;支持证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close
完整研究记录(核对用)
研究原文:Separating the financial-income layer lowers operating-level normalised earnings below the ordinary-profit mean and prevents the flattery of ordinary profit from carrying into valuation.
内部研究类型:QUALIFIES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F061|09|指引按低谷编制,真正的检验是第二季度阴极块销量
研究范围:开放研究+35项覆盖检查
写入正文:09|指引按低谷编制,真正的检验是第二季度阴极块销量11|计划的可信度要靠每一期财报重建
归并到:F024
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接 / 支持;一手验证:31、35;反向验证:05、14、27
Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan怎么使用:直接 / 支持;反向验证:31
The interim print's timing: mid-November on a consistent calendar怎么使用:直接证据;一手验证:30;专项深挖:31、35
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:支持证据;一手验证:14、31
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:支持证据;外部现实校验:20
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:支持证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 支持证据 / 反证(研究域31)|Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan;直接证据 / 一手证据(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|The interim print's timing: mid-November on a consistent calendar;支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter;支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change
完整研究记录(核对用)
研究原文:The implied weak Q2 and one-off-assisted Q1 define what the H1 print must show; cathode volume is the discriminating variable.
内部研究类型:DEFINES_TEST_FOR
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F062|07|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回
研究范围:开放研究
写入正文:07|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回11|计划的可信度要靠每一期财报重建
归并到:F089
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33
Plan arithmetic: even the plan document's near-term outlook overshot the year怎么使用:直接 / 支持;反向验证:11
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:支持证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:支持证据;一手验证:31、35;反向验证:05、14、27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 反证(研究域11)|Plan arithmetic: even the plan document's near-term outlook overshot the year;支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter
完整研究记录(核对用)
研究原文:Management's near-term forecasting record, already taxed by the plan break, is tested again at the H1 print.
内部研究类型:CREDIBILITY_AT_STAKE_IN
内部来源标记:OPEN_DISCOVERY
F063|04|同业利润增长27.0%,行业疲弱不能当作借口
研究范围:35项覆盖检查
写入正文:04|同业利润增长27.0%,行业疲弱不能当作借口
归并到:F014
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026)怎么使用:直接 / 支持;一手验证:08;外部现实校验:05、07、08、09、12、28、35
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:支持证据;一手验证:32;反向验证:20
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:支持证据;一手验证:16、32;同业比较:14;其他用途:历史
Corporate background: founded 1934, an independent carbon maker in the Otani orbit怎么使用:支持证据;一手验证:33;同业比较:01、09、12、23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域08) / 外部现实(研究域05) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域28) / 外部现实(研究域35)|Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026);直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;支持证据|FY3/2026 consolidated results: a second consecutive down year;支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域23)|Corporate background: founded 1934, an independent carbon maker in the Otani orbit
完整研究记录(核对用)
研究原文:The peer's strong print shows the decline is company-specific (electrodes, cathode calendar) rather than carbon-industry weather.
内部研究类型:QUALIFIES_ATTRIBUTION_OF
内部来源标记:COVERAGE35
F064|08|资本在换方向:电极减值,同时新设备完工,新工程又开工
研究范围:开放研究+35项覆盖检查
写入正文:08|资本在换方向:电极减值,同时新设备完工,新工程又开工11|最大的风险是去库存复发,而且新固定成本让复发更贵
归并到:F090
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
The capex cycle: a facility completed into the trough, depreciation stepping up怎么使用:直接 / 支持;一手验证:04、20;专项深挖:04、20;同业比较:04;其他用途:历史
Inventory structure: work in process is 47% of a year's sales怎么使用:直接 / 支持;一手验证:06、19;反向验证:17、29;专项深挖:19
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:支持证据;一手验证:32;反向验证:20
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:支持证据;一手验证:14、31
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:支持证据;一手验证:02、05、07、15
Management outlook: every product line still described as facing a harsh environment怎么使用:支持证据;一手验证:14;反向验证:04、06、35
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|The capex cycle: a facility completed into the trough, depreciation stepping up;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;支持证据 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment
完整研究记录(核对用)
研究原文:A heavier fixed-cost floor raises the cost of a cathode relapse while sharpening the upside if volume delivers.
内部研究类型:AMPLIFIES
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F065|06|账面亏损是承认,不是现金事件
研究范围:35项覆盖检查
写入正文:06|账面亏损是承认,不是现金事件
归并到:F012
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line怎么使用:直接 / 支持
The electrode frame: structurally favoured process, cyclically hostile pricing怎么使用:直接 / 支持;一手验证:08;反向验证:10;专项深挖:08
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:支持证据;一手验证:32;反向验证:20
查看完整证据标签(核对用)
直接证据 / 支持证据|Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line;直接证据 / 支持证据 / 一手证据(研究域08) / 反证(研究域10) / 定向深挖(研究域08)|The electrode frame: structurally favoured process, cyclically hostile pricing;支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant
完整研究记录(核对用)
研究原文:Lower depreciation after the write-down can make the electrode line look better without market recovery; only price or volume counts.
内部研究类型:QUALIFIES_RECOVERY_READING_OF
内部来源标记:COVERAGE35
F066|08|资本政策要有数字,才算催化剂
研究范围:开放研究+35项覆盖检查
写入正文:08|资本政策要有数字,才算催化剂11|最近的验证是中期决算,之后是年度决算和资本政策的数字
归并到:F036
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:直接 / 支持;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:支持证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover怎么使用:支持证据;专项深挖:25;同业比较:25;其他用途:历史
Cross-holding web: peers and partners on both sides of the register怎么使用:支持证据;专项深挖:07、24;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;支持证据 / 一手证据(研究域26)|Dividend policy: the higher of JPY 100 per share or a 30% payout ratio;支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;支持证据 / 历史/同业比较(研究域25) / 定向深挖(研究域25)|Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover;支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register
完整研究记录(核对用)
研究原文:The completed buyback and first securities sale show the instruments are available; scale and numbered programmes are what remain.
内部研究类型:UNBLOCKS_INSTRUMENTS_FOR
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F067|01|股价在押一个治理问题,周期只是第二个期权
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|股价在押一个治理问题,周期只是第二个期权01|两条腿各自会倒,只有阴极块资产减值会伤到根本14|总分61.39/100,评级B:资产强、盈利平,技术无倾向
归并到:F037
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:支持证据;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Cross-holding web: peers and partners on both sides of the register怎么使用:支持证据;专项深挖:07、24;同业比较:21;其他用途:历史
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:支持证据;一手验证:18、20、21、29
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:支持证据;一手验证:14、31
Management outlook: every product line still described as facing a harsh environment怎么使用:一手验证:14;反向验证:04、06、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register;支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;反证 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment
完整研究记录(核对用)
研究原文:Measurable capital-policy conversion is the second re-rating leg of the Thesis.
内部研究类型:SUPPORTS_LEG_OF
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F068|01|股价在押一个治理问题,周期只是第二个期权
研究范围:开放研究
写入正文:00|报告身份、评分与核心结论01|股价在押一个治理问题,周期只是第二个期权01|两条腿各自会倒,只有阴极块资产减值会伤到根本14|总分61.39/100,评级B:资产强、盈利平,技术无倾向
归并到:F037
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(8项,重复标签已合并)
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:支持证据;一手验证:02、03、09、15;反向验证:08
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:支持证据;一手验证:18、20、21、29
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:支持证据;一手验证:11、13、22、35;反向验证:23、33
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:支持证据;一手验证:14、31
Management outlook: every product line still described as facing a harsh environment怎么使用:一手验证:14;反向验证:04、06、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;反证 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment
完整研究记录(核对用)
研究原文:Rising cathode volume with operating leverage through FY3/27 H2 is the first re-rating leg of the Thesis.
内部研究类型:SUPPORTS_LEG_OF
内部来源标记:OPEN_DISCOVERY
F069|01|两条腿各自会倒,只有阴极块资产减值会伤到根本
研究范围:开放研究+35项覆盖检查
写入正文:01|两条腿各自会倒,只有阴极块资产减值会伤到根本
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Management outlook: every product line still described as facing a harsh environment怎么使用:直接 / 支持;一手验证:14;反向验证:04、06、35;其他用途:反证
Inventory structure: work in process is 47% of a year's sales怎么使用:直接证据;一手验证:06、19;反向验证:17、29;专项深挖:19
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:支持证据;一手验证:02、05、07、15
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:支持证据;一手验证:18、20、21、29
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:支持证据;一手验证:11、13、22、35;反向验证:23、33
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 反证 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment;直接证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales;支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%
完整研究记录(核对用)
研究原文:A renewed inventory adjustment or relining deferral would remove the cycle leg and leave only carry.
内部研究类型:COUNTER_EVIDENCE_TO
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F070|01|股价在押一个治理问题,周期只是第二个期权
研究范围:35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|股价在押一个治理问题,周期只是第二个期权01|两条腿各自会倒,只有阴极块资产减值会伤到根本14|总分61.39/100,评级B:资产强、盈利平,技术无倾向
归并到:F037
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(7项,重复标签已合并)
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接证据;一手验证:31、35;反向验证:05、14、27
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接证据;专项深挖:13、30
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:支持证据;一手验证:18、20、21、29
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:支持证据;一手验证:11、13、22、35;反向验证:23、33
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Management outlook: every product line still described as facing a harsh environment怎么使用:一手验证:14;反向验证:04、06、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;反证 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment
完整研究记录(核对用)
研究原文:Each dated falsifier removes one Thesis leg; a cathode-asset impairment attacks the franchise itself.
内部研究类型:FALSIFIES_IF_PRINTED
内部来源标记:COVERAGE35
F071|11|日元和中东:外部冲击到达利润表,比资产负债表的防御来得快
研究范围:开放研究+35项覆盖检查
写入正文:11|日元和中东:外部冲击到达利润表,比资产负债表的防御来得快
归并到:F034
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155怎么使用:直接 / 支持;外部现实校验:06、14;专项深挖:14
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:支持证据;一手验证:31、35;反向验证:05、14、27
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域06) / 外部现实(研究域14) / 定向深挖(研究域14)|FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter;支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter
完整研究记录(核对用)
研究原文:A yen reversal against the USD/JPY 155 assumption would hit guidance fastest and expose the depth of the volume trough.
内部研究类型:THREATENS
内部来源标记:OPEN_DISCOVERY / COVERAGE35
F072|11|最近的验证是中期决算,之后是年度决算和资本政策的数字
研究范围:开放研究
写入正文:11|最近的验证是中期决算,之后是年度决算和资本政策的数字13|最近的两道检验:中期决算和阴极块订单
归并到:F041
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
The interim print's timing: mid-November on a consistent calendar怎么使用:直接证据;一手验证:30;专项深挖:31、35
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:支持证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:支持证据;一手验证:31、35;反向验证:05、14、27
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|The interim print's timing: mid-November on a consistent calendar;支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter
完整研究记录(核对用)
研究原文:The H1 print resolves this debt.
内部研究类型:WOULD_BE_RESOLVED_BY
内部来源标记:OPEN_DISCOVERY
F073|03|订单数据缺位,是判断复苏斜率的最大缺口
研究范围:开放研究
写入正文:03|订单数据缺位,是判断复苏斜率的最大缺口13|最近的两道检验:中期决算和阴极块订单
归并到:F042
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:支持证据;一手验证:02、03、09、15;反向验证:08
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:支持证据;反向验证:12;同业比较:35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing
完整研究记录(核对用)
研究原文:Unresolved order intake limits confidence in the cathode recovery slope.
内部研究类型:QUALIFIES_CONFIDENCE_IN
内部来源标记:OPEN_DISCOVERY
F074|06|账面亏损是承认,不是现金事件
研究范围:开放研究
写入正文:06|账面亏损是承认,不是现金事件13|产品、投资和地区上还没有答案的三件事
归并到:F043
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(1项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant
完整研究记录(核对用)
研究原文:Electrode strategy after the write-down is unstated.
内部研究类型:QUALIFIES_CONFIDENCE_IN
内部来源标记:OPEN_DISCOVERY
F075|08|资本在换方向:电极减值,同时新设备完工,新工程又开工
研究范围:开放研究
写入正文:08|资本在换方向:电极减值,同时新设备完工,新工程又开工13|产品、投资和地区上还没有答案的三件事
归并到:F044
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(4项,重复标签已合并)
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
The capex cycle: a facility completed into the trough, depreciation stepping up怎么使用:直接证据;一手验证:04、20;专项深挖:04、20;同业比较:04;其他用途:历史
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:支持证据;一手验证:32;反向验证:20
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:支持证据;一手验证:18、20、21、29
查看完整证据标签(核对用)
直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 一手证据(研究域04) / 一手证据(研究域20) / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|The capex cycle: a facility completed into the trough, depreciation stepping up;支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets
完整研究记录(核对用)
研究原文:The destination and return of the new build are unknown.
内部研究类型:QUALIFIES_CONFIDENCE_IN
内部来源标记:OPEN_DISCOVERY
F076|08|资本政策要有数字,才算催化剂
研究范围:开放研究
写入正文:08|资本政策要有数字,才算催化剂13|资本政策能不能变成可测量的数字
归并到:F045
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:支持证据;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Cross-holding web: peers and partners on both sides of the register怎么使用:支持证据;专项深挖:07、24;同业比较:21;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register
完整研究记录(核对用)
研究原文:Numbered capital-policy disclosures resolve the timetable question.
内部研究类型:WOULD_BE_RESOLVED_BY
内部来源标记:OPEN_DISCOVERY
F077|07|股东名册就是折价:控股集团加两家商社
研究范围:开放研究
写入正文:07|股东名册就是折价:控股集团加两家商社13|资本政策能不能变成可测量的数字
归并到:F046
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:支持证据;一手验证:18、20、21、29
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:支持证据;一手验证:02、05、07、15
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:一手验证:11、13、22、35;反向验证:23、33;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;反证 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31
完整研究记录(核对用)
研究原文:Bloc intent is the unresolved determinant of how long the register discount lasts.
内部研究类型:QUALIFIES_CONFIDENCE_IN
内部来源标记:OPEN_DISCOVERY
F078|11|日元和中东:外部冲击到达利润表,比资产负债表的防御来得快
研究范围:开放研究
写入正文:11|日元和中东:外部冲击到达利润表,比资产负债表的防御来得快13|产品、投资和地区上还没有答案的三件事
归并到:F047
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155怎么使用:支持证据;外部现实校验:06、14;专项深挖:14
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:支持证据;一手验证:32;反向验证:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;支持证据 / 外部现实(研究域06) / 外部现实(研究域14) / 定向深挖(研究域14)|FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155;支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant
完整研究记录(核对用)
研究原文:The excluded Middle East exposure is unquantified.
内部研究类型:QUALIFIES_CONFIDENCE_IN
内部来源标记:OPEN_DISCOVERY
F079|07|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回
研究范围:开放研究
写入正文:07|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回13|产品、投资和地区上还没有答案的三件事
归并到:F048
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;支持证据 / 反证(研究域11)|Plan arithmetic: even the plan document's near-term outlook overshot the year
完整研究记录(核对用)
研究原文:Whether non-cathode growth can matter against the FY3/31 target is unresolved.
内部研究类型:QUALIFIES_CONFIDENCE_IN
内部来源标记:OPEN_DISCOVERY
F080|08|12%的股本回报率目标,隐含着股本要缩小
研究范围:35项覆盖检查
写入正文:08|12%的股本回报率目标,隐含着股本要缩小13|资本政策能不能变成可测量的数字
归并到:F049
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
The ROE bridge the 2030 policy must cross怎么使用:直接 / 支持;一手验证:22;专项深挖:11、22
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:支持证据;专项深挖:13、30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域11) / 定向深挖(研究域22)|The ROE bridge the 2030 policy must cross;支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language
完整研究记录(核对用)
研究原文:The split between profit and equity shrinkage is unquantified.
内部研究类型:QUALIFIES_CONFIDENCE_IN
内部来源标记:COVERAGE35
F081|08|回购方向已经打开,规模太小,推不动折价
研究范围:35项覆盖检查
写入正文:08|回购方向已经打开,规模太小,推不动折价13|资本政策能不能变成可测量的数字
归并到:F050
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:直接 / 支持;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover怎么使用:直接 / 支持;专项深挖:25;同业比较:25;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;直接证据 / 支持证据 / 历史/同业比较(研究域25) / 定向深挖(研究域25)|Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover
完整研究记录(核对用)
研究原文:Without cancellation, treasury shares remain reversible and the per-share effect is partial.
内部研究类型:QUALIFIES_CONFIDENCE_IN
内部来源标记:COVERAGE35
F082|10|公开事件与价格的时序:价格先走,基本面后到
研究范围:开放研究
写入正文:10|公开事件与价格的时序:价格先走,基本面后到11|最近的验证是中期决算,之后是年度决算和资本政策的数字
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(5项,重复标签已合并)
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接 / 支持;一手验证:31、35;反向验证:05、14、27
The interim print's timing: mid-November on a consistent calendar怎么使用:直接证据;一手验证:30;专项深挖:31、35
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:支持证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 一手证据(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|The interim print's timing: mid-November on a consistent calendar;支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter
完整研究记录(核对用)
研究原文:The H1 FY3/27 print is the next dated public fundamental event against which the protected Technical Synthesis's own confirming and falsifying price evidence will be observed. This relation sets timing context only; it neither adds a technical cause nor changes the Technical State.
内部研究类型:CROSS_LANE_TIMING_CONTEXT
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F083|10|公开事件与价格的时序:价格先走,基本面后到
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(3项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;支持证据 / 反证(研究域11)|Plan arithmetic: even the plan document's near-term outlook overshot the year
完整研究记录(核对用)
研究原文:The April 2026 plan abolition is a dated public event that coincided with the period in which heavy trading volume appears in the price record; Research Cross-domain Integration records this association as a hypothesis (the price may have been discounting the FY3/31 targets) without making the event a technical cause.
内部研究类型:CROSS_LANE_TIMING_CONTEXT
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F084|10|公开事件与价格的时序:价格先走,基本面后到
研究范围:开放研究
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(2项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%
完整研究记录(核对用)
研究原文:The electrode market-environment change behind the May 2026 impairment is a fundamental event whose timing can be compared with price response in the protected Technical Synthesis; cross-domain integration frames the balance sheet and the register as reading the same electrode-market change about two months apart. This is a timing observation, not causal proof.
内部研究类型:CROSS_LANE_TIMING_CONTEXT
内部来源标记:OPEN_DISCOVERY / TECHNICAL
F085|02|企业耐久,股票有条件
研究范围:开放研究+35项覆盖检查
写入正文:02|企业耐久,股票有条件05|耐久对企业成立,对股票有条件
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(45项,重复标签已合并)
FY3/2026 tanshin header: issuer identity, listing and representative怎么使用:直接 / 支持;一手验证:01
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Company profile: four carbon product lines, Kyoto works at the centre怎么使用:直接 / 支持;一手验证:03、04、09、10
Corporate background: founded 1934, an independent carbon maker in the Otani orbit怎么使用:直接证据;一手验证:33;同业比较:01、09、12、23;其他用途:历史
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
Scale: roughly 270 employees produce JPY 25 billion of sales怎么使用:直接证据;专项深挖:09
Parent-only accounts: the subsidiaries are a rounding item怎么使用:直接证据;反向验证:02
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
The cathode demand frame: relining cycles and smelter construction怎么使用:直接证据;一手验证:11;外部现实校验:02、03、10、11、15;专项深挖:03、05
Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign怎么使用:直接 / 支持;反向验证:07、15;专项深挖:02
Margin structure: gross margin compressed 4.4 points; SG&A was cut in absolute terms怎么使用:直接 / 支持;一手验证:10、16;同业比较:06;其他用途:历史
Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026)怎么使用:直接证据;一手验证:08;外部现实校验:05、07、08、09、12、28、35
The electrode frame: structurally favoured process, cyclically hostile pricing怎么使用:直接证据;一手验证:08;反向验证:10;专项深挖:08
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Input costs: raw-material and fuel inflation is the stated offset to volume recovery怎么使用:直接证据;一手验证:06;外部现实校验:04、16;专项深挖:06
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接证据;一手验证:16、32;同业比较:14;其他用途:历史
FY3/2026 cash flow: operating cash flow rose through the loss year怎么使用:直接 / 支持;一手验证:17;同业比较:19;其他用途:历史
Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume怎么使用:直接证据;外部现实校验:19;专项深挖:18
Inventory structure: work in process is 47% of a year's sales怎么使用:直接 / 支持;一手验证:06、19;反向验证:17、29;专项深挖:19
Working-capital structure: the group pays fast and collects slowly怎么使用:直接 / 支持;一手验证:17、19;专项深挖:10、15、17
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:直接 / 支持;一手验证:18、29
Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored怎么使用:直接证据;同业比较:17、18、20、22、27;其他用途:历史
Valuation arithmetic at the 6 November 2026 close怎么使用:直接 / 支持;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
The capex cycle: a facility completed into the trough, depreciation stepping up怎么使用:直接 / 支持;一手验证:04、20;专项深挖:04、20;同业比较:04;其他用途:历史
Land and the old asset base: book values carry no revaluation怎么使用:直接 / 支持;一手验证:21;专项深挖:21;同业比较:29;其他用途:历史
Cross-holding web: peers and partners on both sides of the register怎么使用:直接 / 支持;专项深挖:07、24;同业比较:21;其他用途:历史
Register size and liquidity: 4,922 shareholders, a Standard-market small cap怎么使用:直接 / 支持;反向验证:24
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接 / 支持;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Float behaviour: thin trading, one-sided margin balances, event-day volume怎么使用:直接证据;外部现实校验:24、25、27、30;专项深挖:34
Dividend policy: the higher of JPY 100 per share or a 30% payout ratio怎么使用:直接 / 支持;一手验证:26
Dividend record: JPY 100 held through the cycle turn, by formula怎么使用:直接 / 支持;一手验证:26
The dividend-on-equity anchor: the floor is a 2.6% DOE commitment怎么使用:直接 / 支持;专项深挖:26
The FY3/24 peak: derived comparatives from the FY3/25 year-on-year rates怎么使用:直接 / 支持;一手验证:33;同业比较:02、03、28;其他用途:历史
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:直接证据;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
H1 FY3/2026 actuals: the base half against which the FY3/27 interim plan is set怎么使用:直接 / 支持;一手验证:12;同业比较:05、15、16、31;其他用途:历史
The ROE bridge the 2030 policy must cross怎么使用:直接 / 支持;一手验证:22;专项深挖:11、22
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:支持证据;专项深挖:13、30
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01)|FY3/2026 tanshin header: issuer identity, listing and representative;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域03) / 一手证据(研究域04) / 一手证据(研究域09) / 一手证据(研究域10)|Company profile: four carbon product lines, Kyoto works at the centre;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域23)|Corporate background: founded 1934, an independent carbon maker in the Otani orbit;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 定向深挖(研究域09)|Scale: roughly 270 employees produce JPY 25 billion of sales;直接证据|Nippon Denkyoku: a small electrode affiliate brought into the equity method;直接证据 / 反证(研究域02)|Parent-only accounts: the subsidiaries are a rounding item;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05)|The cathode demand frame: relining cycles and smelter construction;直接证据 / 支持证据 / 反证(研究域07) / 反证(研究域15) / 定向深挖(研究域02)|Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域16) / 历史/同业比较(研究域06)|Margin structure: gross margin compressed 4.4 points; SG&A was cut in absolute terms;直接证据 / 一手证据(研究域08) / 外部现实(研究域05) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域28) / 外部现实(研究域35)|Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026);直接证据 / 一手证据(研究域08) / 反证(研究域10) / 定向深挖(研究域08)|The electrode frame: structurally favoured process, cyclically hostile pricing;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据|FY3/2026 consolidated results: a second consecutive down year;直接证据|Q1 FY3/2027 results: volume recovery off a trough quarter;直接证据 / 一手证据(研究域06) / 外部现实(研究域04) / 外部现实(研究域16) / 定向深挖(研究域06)|Input costs: raw-material and fuel inflation is the stated offset to volume recovery;直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19)|FY3/2026 cash flow: operating cash flow rose through the loss year;直接证据 / 外部现实(研究域19) / 定向深挖(研究域18)|Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 定向深挖(研究域10) / 定向深挖(研究域15) / 定向深挖(研究域17)|Working-capital structure: the group pays fast and collects slowly;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27)|Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|The capex cycle: a facility completed into the trough, depreciation stepping up;直接证据 / 支持证据 / 一手证据(研究域21) / 历史/同业比较(研究域29) / 定向深挖(研究域21)|Land and the old asset base: book values carry no revaluation;直接证据 / 支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register;直接证据 / 支持证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域27) / 外部现实(研究域30) / 定向深挖(研究域34)|Float behaviour: thin trading, one-sided margin balances, event-day volume;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend policy: the higher of JPY 100 per share or a 30% payout ratio;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 100 held through the cycle turn, by formula;直接证据 / 支持证据 / 定向深挖(研究域26)|The dividend-on-equity anchor: the floor is a 2.6% DOE commitment;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域28)|The FY3/24 peak: derived comparatives from the FY3/25 year-on-year rates;直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines;直接证据 / 支持证据 / 一手证据(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域31)|H1 FY3/2026 actuals: the base half against which the FY3/27 interim plan is set;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域11) / 定向深挖(研究域22)|The ROE bridge the 2030 policy must cross;支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language
完整研究记录(核对用)
研究原文:Durable Business Portrait: a qualified cathode consumable franchise inside an over-capitalised, relationship-held shell|Foundation reconstructed before current change: the enterprise is durable (qualification moat, self-funded cycle endurance, high cash conversion in downturns) while the share is conditional (one-product concentration, one-channel concentration, an impaired second franchise, a controlling register that sets the pace of capital conversion). Self-repair capacity is high at the enterprise level; irreversible failure would require a cathode-franchise break, a bloc sale or a capex error.
内部研究类型:DURABLE_BUSINESS_PORTRAIT
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):The shareholder owns durable enterprise value whose per-share realisation is governed by register and capital-policy decisions.
不确定性(原始记录):Moat evidence is inferred from margins; product-level profit, contracts and independent share data are unavailable.
F086|03|一个产品的更换周期,决定了这家公司的利润表
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(23项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
The cathode demand frame: relining cycles and smelter construction怎么使用:直接证据;一手验证:11;外部现实校验:02、03、10、11、15;专项深挖:03、05
Margin structure: gross margin compressed 4.4 points; SG&A was cut in absolute terms怎么使用:直接 / 支持;一手验证:10、16;同业比较:06;其他用途:历史
Input costs: raw-material and fuel inflation is the stated offset to volume recovery怎么使用:直接证据;一手验证:06;外部现实校验:04、16;专项深挖:06
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接 / 支持;一手验证:16、32;同业比较:14;其他用途:历史
Corporate background: founded 1934, an independent carbon maker in the Otani orbit怎么使用:直接 / 支持;一手验证:33;同业比较:01、09、12、23;其他用途:历史
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:直接证据;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
The FY3/24 peak: derived comparatives from the FY3/25 year-on-year rates怎么使用:直接 / 支持;一手验证:33;同业比较:02、03、28;其他用途:历史
H1 FY3/2026 actuals: the base half against which the FY3/27 interim plan is set怎么使用:直接 / 支持;一手验证:12;同业比较:05、15、16、31;其他用途:历史
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Management outlook: every product line still described as facing a harsh environment怎么使用:直接 / 支持;一手验证:14;反向验证:04、06、35
FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155怎么使用:直接 / 支持;外部现实校验:06、14;专项深挖:14
Inventory structure: work in process is 47% of a year's sales怎么使用:直接 / 支持;一手验证:06、19;反向验证:17、29;专项深挖:19
Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign怎么使用:直接证据;反向验证:07、15;专项深挖:02
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:支持证据;一手验证:31、35;反向验证:05、14、27
The capex cycle: a facility completed into the trough, depreciation stepping up怎么使用:直接 / 支持;一手验证:04、20;专项深挖:04、20;同业比较:04;其他用途:历史
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05)|The cathode demand frame: relining cycles and smelter construction;直接证据 / 支持证据|FY3/2026 consolidated results: a second consecutive down year;直接证据 / 支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter;直接证据 / 支持证据 / 一手证据(研究域10) / 一手证据(研究域16) / 历史/同业比较(研究域06)|Margin structure: gross margin compressed 4.4 points; SG&A was cut in absolute terms;直接证据 / 一手证据(研究域06) / 外部现实(研究域04) / 外部现实(研究域16) / 定向深挖(研究域06)|Input costs: raw-material and fuel inflation is the stated offset to volume recovery;直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域23)|Corporate background: founded 1934, an independent carbon maker in the Otani orbit;直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域28)|The FY3/24 peak: derived comparatives from the FY3/25 year-on-year rates;直接证据 / 支持证据 / 一手证据(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域31)|H1 FY3/2026 actuals: the base half against which the FY3/27 interim plan is set;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment;直接证据 / 支持证据 / 外部现实(研究域06) / 外部现实(研究域14) / 定向深挖(研究域14)|FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales;直接证据 / 反证(研究域07) / 反证(研究域15) / 定向深挖(研究域02)|Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign;支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|The capex cycle: a facility completed into the trough, depreciation stepping up;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback
完整研究记录(核对用)
研究原文:Smelter relining deferral and inventory drawdown to cathode volume to group profit, with yen cushion|Relining deferral and customer inventory drawdown cut cathode volume; fixed-cost absorption turns a volume fall into a larger profit fall; yen weakness and financial income cushioned reported ordinary profit, so a yen reversal or a relapse would expose the true volume trough. Cycle, not competition or cost, is the first cause.
内部研究类型:CAUSAL_CHAIN
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Operating earnings power depends on one volume slope; yen and relapse are the fastest breakers.
不确定性(原始记录):Order intake invisible; Q1 rebound includes timing.
F087|04|电极是被进口价格定价的业务,减值承认了这一点
研究范围:开放研究+35项覆盖检查
写入正文:04|电极是被进口价格定价的业务,减值承认了这一点06|账面亏损是承认,不是现金事件
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(20项,重复标签已合并)
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
Management outlook: every product line still described as facing a harsh environment怎么使用:直接证据;一手验证:14;反向验证:04、06、35
The electrode frame: structurally favoured process, cyclically hostile pricing怎么使用:直接 / 支持;一手验证:08;反向验证:10;专项深挖:08
Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line怎么使用:直接 / 支持
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接 / 支持;一手验证:16、32;同业比较:14;其他用途:历史
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Non-operating quality: subsidies and affiliate losses inside ordinary profit怎么使用:直接证据;反向验证:16、28、32
Tax mechanics of the loss year: a deferred-tax credit cushioned the bottom line怎么使用:直接证据;外部现实校验:32;专项深挖:32
FY3/2026 cash flow: operating cash flow rose through the loss year怎么使用:直接 / 支持;一手验证:17;同业比较:19;其他用途:历史
Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume怎么使用:直接证据;外部现实校验:19;专项深挖:18
Inventory structure: work in process is 47% of a year's sales怎么使用:直接证据;一手验证:06、19;反向验证:17、29;专项深挖:19
Working-capital structure: the group pays fast and collects slowly怎么使用:直接 / 支持;一手验证:17、19;专项深挖:10、15、17
Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026)怎么使用:直接 / 支持;一手验证:08;外部现实校验:05、07、08、09、12、28、35
Parent-only accounts: the subsidiaries are a rounding item怎么使用:直接证据;反向验证:02
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接证据;外部现实校验:20
Corporate background: founded 1934, an independent carbon maker in the Otani orbit怎么使用:支持证据;一手验证:33;同业比较:01、09、12、23;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment;直接证据 / 支持证据 / 一手证据(研究域08) / 反证(研究域10) / 定向深挖(研究域08)|The electrode frame: structurally favoured process, cyclically hostile pricing;直接证据 / 支持证据|Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 反证(研究域16) / 反证(研究域28) / 反证(研究域32)|Non-operating quality: subsidies and affiliate losses inside ordinary profit;直接证据 / 外部现实(研究域32) / 定向深挖(研究域32)|Tax mechanics of the loss year: a deferred-tax credit cushioned the bottom line;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19)|FY3/2026 cash flow: operating cash flow rose through the loss year;直接证据 / 外部现实(研究域19) / 定向深挖(研究域18)|Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume;直接证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 定向深挖(研究域10) / 定向深挖(研究域15) / 定向深挖(研究域17)|Working-capital structure: the group pays fast and collects slowly;直接证据 / 支持证据 / 一手证据(研究域08) / 外部现实(研究域05) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域28) / 外部现实(研究域35)|Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026);直接证据|Nippon Denkyoku: a small electrode affiliate brought into the equity method;直接证据 / 反证(研究域02)|Parent-only accounts: the subsidiaries are a rounding item;直接证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;支持证据|FY3/2026 consolidated results: a second consecutive down year;支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域23)|Corporate background: founded 1934, an independent carbon maker in the Otani orbit
完整研究记录(核对用)
研究原文:Weak steel output and cheap imports to electrode price and volume to impairment to net loss|Import-set pricing pushed the electrode plant's recoverable amount below book; the write-down is a non-cash admission that converts operating profit to a net loss, creates a non-repeatable deferred-tax credit and lowers future depreciation, which will flatter electrode results without market recovery.
内部研究类型:CAUSAL_CHAIN
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):One sub-franchise is stranded at current prices; read recovery only from price or volume.
不确定性(原始记录):Endgame unstated.
F088|07|股东名册就是折价:控股集团加两家商社
研究范围:开放研究+35项覆盖检查
写入正文:07|股东名册就是折价:控股集团加两家商社08|资本政策要有数字,才算催化剂09|折价是对资本政策的折价,不是对破产或业务的折价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(27项,重复标签已合并)
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接 / 支持;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Float behaviour: thin trading, one-sided margin balances, event-day volume怎么使用:直接证据;外部现实校验:24、25、27、30;专项深挖:34
Register size and liquidity: 4,922 shareholders, a Standard-market small cap怎么使用:直接 / 支持;反向验证:24
Cross-holding web: peers and partners on both sides of the register怎么使用:直接 / 支持;专项深挖:07、24;同业比较:21;其他用途:历史
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:直接 / 支持;一手验证:18、29
Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored怎么使用:直接证据;同业比较:17、18、20、22、27;其他用途:历史
Valuation arithmetic at the 6 November 2026 close怎么使用:直接 / 支持;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
Dividend policy: the higher of JPY 100 per share or a 30% payout ratio怎么使用:直接 / 支持;一手验证:26
Dividend record: JPY 100 held through the cycle turn, by formula怎么使用:直接 / 支持;一手验证:26
The dividend-on-equity anchor: the floor is a 2.6% DOE commitment怎么使用:直接 / 支持;专项深挖:26
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
Share count: unchanged issuance, slow treasury accumulation怎么使用:直接证据;一手验证:25
Q1 FY3/2027 equity walk: the quarter's profit was fully distributed or bought back怎么使用:直接证据;反向验证:18、22、25、26
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:直接 / 支持;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover怎么使用:直接 / 支持;专项深挖:25;同业比较:25;其他用途:历史
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33;其他用途:反证
The ROE bridge the 2030 policy must cross怎么使用:直接 / 支持;一手验证:22;专项深挖:11、22
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
Leadership: a representative-director change was announced on 8 June 2026怎么使用:直接 / 支持;一手验证:23;反向验证:13、30;专项深挖:01、23
Corporate background: founded 1934, an independent carbon maker in the Otani orbit怎么使用:直接证据;一手验证:33;同业比较:01、09、12、23;其他用途:历史
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:直接证据;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:支持证据;一手验证:14、31
Management outlook: every product line still described as facing a harsh environment怎么使用:一手验证:14;反向验证:04、06、35;其他用途:反证
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域27) / 外部现实(研究域30) / 定向深挖(研究域34)|Float behaviour: thin trading, one-sided margin balances, event-day volume;直接证据 / 支持证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap;直接证据 / 支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27)|Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend policy: the higher of JPY 100 per share or a 30% payout ratio;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 100 held through the cycle turn, by formula;直接证据 / 支持证据 / 定向深挖(研究域26)|The dividend-on-equity anchor: the floor is a 2.6% DOE commitment;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 一手证据(研究域25)|Share count: unchanged issuance, slow treasury accumulation;直接证据 / 反证(研究域18) / 反证(研究域22) / 反证(研究域25) / 反证(研究域26)|Q1 FY3/2027 equity walk: the quarter's profit was fully distributed or bought back;直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;直接证据 / 支持证据 / 历史/同业比较(研究域25) / 定向深挖(研究域25)|Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover;直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;直接证据 / 支持证据 / 反证 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域11) / 定向深挖(研究域22)|The ROE bridge the 2030 policy must cross;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 支持证据 / 一手证据(研究域23) / 反证(研究域13) / 反证(研究域30) / 定向深挖(研究域01) / 定向深挖(研究域23)|Leadership: a representative-director change was announced on 8 June 2026;直接证据 / 一手证据(研究域33) / 历史/同业比较(研究域01) / 历史/同业比较(研究域09) / 历史/同业比较(研究域12) / 历史/同业比较(研究域23)|Corporate background: founded 1934, an independent carbon maker in the Otani orbit;直接证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines;支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;反证 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment
完整研究记录(核对用)
研究原文:Controlling register and thin float to unconverted financial pile to ROE ceiling to 0.52x book discount|The pile earns financial yields, caps ROE, and is the downside protection; the register supplies stability and no pressure to convert it; the dividend floor and slow buybacks return cash at about the pace it is earned, so the pile does not shrink. The discount closes only if the bloc chooses numbered conversion; whether 2026 is a regime change or a cluster of one-offs is open.
内部研究类型:CAUSAL_CHAIN
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Carry of about 5% plus option on conversion; the pace is set by holders the minority cannot influence.
不确定性(原始记录):Bloc intent undisclosed.
F089|07|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回
研究范围:开放研究+35项覆盖检查
写入正文:07|废止计划是坦率的,2031年3月期目标要靠财报一期期重新赢回11|计划的可信度要靠每一期财报重建
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(15项,重复标签已合并)
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接证据;反向验证:12;同业比较:35;其他用途:历史
Plan arithmetic: even the plan document's near-term outlook overshot the year怎么使用:直接 / 支持;反向验证:11
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接 / 支持;一手验证:31、35;反向验证:05、14、27
Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan怎么使用:直接 / 支持;反向验证:31
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接 / 支持;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
The interim print's timing: mid-November on a consistent calendar怎么使用:直接证据;一手验证:30;专项深挖:31、35
The ROE bridge the 2030 policy must cross怎么使用:直接 / 支持;一手验证:22;专项深挖:11、22
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接证据;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接证据;一手验证:05;反向验证:03、19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 支持证据 / 反证(研究域11)|Plan arithmetic: even the plan document's near-term outlook overshot the year;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 支持证据 / 反证(研究域31)|Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 一手证据(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|The interim print's timing: mid-November on a consistent calendar;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域11) / 定向深挖(研究域22)|The ROE bridge the 2030 policy must cross;直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;直接证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling
完整研究记录(核对用)
研究原文:Plan abolition to re-anchored FY3/31 targets to print-by-print credibility|A candid abolition of an unreachable plan replaced quantified FY3/27 targets with FY3/31 aspirations that require a cycle supercycle or step-change in capital returns; guidance is built as a trough with a weak implied Q2, so credibility is rebuilt only by volume prints.
内部研究类型:CAUSAL_CHAIN
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Treat targets as aspirations until re-earned.
不确定性(原始记录):Growth sources unnamed.
F090|08|资本在换方向:电极减值,同时新设备完工,新工程又开工
研究范围:开放研究+35项覆盖检查
写入正文:08|资本在换方向:电极减值,同时新设备完工,新工程又开工11|最大的风险是去库存复发,而且新固定成本让复发更贵
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(13项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
The capex cycle: a facility completed into the trough, depreciation stepping up怎么使用:直接 / 支持;一手验证:04、20;专项深挖:04、20;同业比较:04;其他用途:历史
Inventory structure: work in process is 47% of a year's sales怎么使用:直接 / 支持;一手验证:06、19;反向验证:17、29;专项深挖:19
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
Management outlook: every product line still described as facing a harsh environment怎么使用:直接 / 支持;一手验证:14;反向验证:04、06、35
The electrode frame: structurally favoured process, cyclically hostile pricing怎么使用:直接证据;一手验证:08;反向验证:10;专项深挖:08
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
The cathode demand frame: relining cycles and smelter construction怎么使用:直接证据;一手验证:11;外部现实校验:02、03、10、11、15;专项深挖:03、05
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|The capex cycle: a facility completed into the trough, depreciation stepping up;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment;直接证据 / 一手证据(研究域08) / 反证(研究域10) / 定向深挖(研究域08)|The electrode frame: structurally favoured process, cyclically hostile pricing;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05)|The cathode demand frame: relining cycles and smelter construction
完整研究记录(核对用)
研究原文:Capacity rotation: electrode write-down, completed facility, new build and a higher fixed-cost floor|Cost base is raised ahead of recovery; leverage is bought into a cathode upcycle with a heavier floor if the cycle disappoints.
内部研究类型:CAUSAL_CHAIN
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Capex risk converts to utilisation risk on an already-paid asset base.
不确定性(原始记录):Project identity and return undisclosed.
F091|06|没有借款的资产负债表:金融资产比有形资产还大
研究范围:开放研究+35项覆盖检查
写入正文:06|没有借款的资产负债表:金融资产比有形资产还大09|折价是对资本政策的折价,不是对破产或业务的折价
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(19项,重复标签已合并)
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:直接 / 支持;一手验证:18、29
Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored怎么使用:直接证据;同业比较:17、18、20、22、27;其他用途:历史
Valuation arithmetic at the 6 November 2026 close怎么使用:直接 / 支持;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
Dividend record: JPY 100 held through the cycle turn, by formula怎么使用:直接证据;一手验证:26
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接证据;一手验证:11、13、22、35;反向验证:23、33;其他用途:反证
The ROE bridge the 2030 policy must cross怎么使用:直接 / 支持;一手验证:22;专项深挖:11、22
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
FY3/2026 cash flow: operating cash flow rose through the loss year怎么使用:直接 / 支持;一手验证:17;同业比较:19;其他用途:历史
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume怎么使用:直接 / 支持;外部现实校验:19;专项深挖:18
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:支持证据;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
Normalisation base: five-year ordinary-profit record and its financial-income content怎么使用:支持证据;一手验证:28;专项深挖:12、16、28
Float behaviour: thin trading, one-sided margin balances, event-day volume怎么使用:直接证据;外部现实校验:24、25、27、30;专项深挖:34
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27)|Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close;直接证据 / 一手证据(研究域26)|Dividend record: JPY 100 held through the cycle turn, by formula;直接证据 / 反证 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域11) / 定向深挖(研究域22)|The ROE bridge the 2030 policy must cross;直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 支持证据|FY3/2026 consolidated results: a second consecutive down year;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19)|FY3/2026 cash flow: operating cash flow rose through the loss year;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 外部现实(研究域19) / 定向深挖(研究域18)|Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume;支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines;支持证据 / 一手证据(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|Normalisation base: five-year ordinary-profit record and its financial-income content;直接证据 / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域27) / 外部现实(研究域30) / 定向深挖(研究域34)|Float behaviour: thin trading, one-sided margin balances, event-day volume;直接证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap
完整研究记录(核对用)
研究原文:One balance-sheet fact wearing three prices|JPY 45.3 billion of cash and securities is simultaneously downside protection, the ROE ceiling and the cause of the discount, all three priced by the register's patience.
内部研究类型:CROSS_DOMAIN_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Protection and dilution of returns are one fact.
不确定性(原始记录):Realisability of relationship securities is untested.
F092|03|住友集团既是57.8%收入的出口,又是5.02%的股东
研究范围:开放研究+35项覆盖检查
写入正文:03|住友集团既是57.8%收入的出口,又是5.02%的股东07|股东名册和证券组合互为镜像
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(11项,重复标签已合并)
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign怎么使用:直接 / 支持;反向验证:07、15;专项深挖:02
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Float behaviour: thin trading, one-sided margin balances, event-day volume怎么使用:直接证据;外部现实校验:24、25、27、30;专项深挖:34
Register size and liquidity: 4,922 shareholders, a Standard-market small cap怎么使用:直接 / 支持;反向验证:24
Cross-holding web: peers and partners on both sides of the register怎么使用:直接 / 支持;专项深挖:07、24;同业比较:21;其他用途:历史
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:支持证据;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:支持证据;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:支持证据;反向验证:12;同业比较:35;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 支持证据 / 反证(研究域07) / 反证(研究域15) / 定向深挖(研究域02)|Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign;直接证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域27) / 外部现实(研究域30) / 定向深挖(研究域34)|Float behaviour: thin trading, one-sided margin balances, event-day volume;直接证据 / 支持证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap;直接证据 / 支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register;支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing
完整研究记录(核对用)
研究原文:The channel links customers to ownership|The Sumitomo group is at once the route to 58% of revenue and a 5% shareholder: commercial dependence and register stability are the same relationship measured in two statements.
内部研究类型:CROSS_DOMAIN_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Protection from disruption and exposure to one counterparty come together.
不确定性(原始记录):Channel terms undisclosed.
F093|06|亏损年度反而更有现金,复苏年度现金会被吸走
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(16项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接证据;一手验证:32;反向验证:20
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接证据;一手验证:16、32;同业比较:14;其他用途:历史
FY3/2026 cash flow: operating cash flow rose through the loss year怎么使用:直接 / 支持;一手验证:17;同业比较:19;其他用途:历史
Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume怎么使用:直接证据;外部现实校验:19;专项深挖:18
Inventory structure: work in process is 47% of a year's sales怎么使用:直接 / 支持;一手验证:06、19;反向验证:17、29;专项深挖:19
Working-capital structure: the group pays fast and collects slowly怎么使用:直接 / 支持;一手验证:17、19;专项深挖:10、15、17
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
The cathode demand frame: relining cycles and smelter construction怎么使用:直接证据;一手验证:11;外部现实校验:02、03、10、11、15;专项深挖:03、05
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Management outlook: every product line still described as facing a harsh environment怎么使用:直接 / 支持;一手验证:14;反向验证:04、06、35
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:支持证据;一手验证:18、29
查看完整证据标签(核对用)
直接证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19)|FY3/2026 cash flow: operating cash flow rose through the loss year;直接证据 / 外部现实(研究域19) / 定向深挖(研究域18)|Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 定向深挖(研究域10) / 定向深挖(研究域15) / 定向深挖(研究域17)|Working-capital structure: the group pays fast and collects slowly;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05)|The cathode demand frame: relining cycles and smelter construction;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;支持证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden
完整研究记录(核对用)
研究原文:Working capital links the cycle to the cash statement|The inventory-and-receivables machine made loss-year FY3/26 the better cash year (operating cash flow JPY 7,766 million) and is now restocking (Q1 FY3/27 built every inventory layer), so cash will deteriorate as earnings recover, a cross-current a headline reader will misread twice.
内部研究类型:CROSS_DOMAIN_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Recovery earnings will not convert to cash one-for-one; an inventory build is not itself demand evidence.
不确定性(原始记录):Rate of re-absorption in FY3/27 unknown.
F094|08|分红下限在亏损年度也没动,波动由分红比例吸收
研究范围:开放研究+35项覆盖检查
写入正文:08|分红下限在亏损年度也没动,波动由分红比例吸收
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(11项,重复标签已合并)
Dividend policy: the higher of JPY 100 per share or a 30% payout ratio怎么使用:直接 / 支持;一手验证:26
Dividend record: JPY 100 held through the cycle turn, by formula怎么使用:直接 / 支持;一手验证:26
The dividend-on-equity anchor: the floor is a 2.6% DOE commitment怎么使用:直接 / 支持;专项深挖:26
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接证据;一手验证:18、20、21、29
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:直接证据;一手验证:18、29
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接证据;一手验证:01、07、24;外部现实校验:23
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接 / 支持;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Float behaviour: thin trading, one-sided margin balances, event-day volume怎么使用:直接证据;外部现实校验:24、25、27、30;专项深挖:34
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:支持证据;外部现实校验:20
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域26)|Dividend policy: the higher of JPY 100 per share or a 30% payout ratio;直接证据 / 支持证据 / 一手证据(研究域26)|Dividend record: JPY 100 held through the cycle turn, by formula;直接证据 / 支持证据 / 定向深挖(研究域26)|The dividend-on-equity anchor: the floor is a 2.6% DOE commitment;直接证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;直接证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 外部现实(研究域24) / 外部现实(研究域25) / 外部现实(研究域27) / 外部现实(研究域30) / 定向深挖(研究域34)|Float behaviour: thin trading, one-sided margin balances, event-day volume;直接证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap;支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback
完整研究记录(核对用)
研究原文:The dividend formula links the register to the income statement|Because the floor pays JPY 100 regardless, the payout ratio (66.8% on forecast) is the shock absorber of the system: earnings volatility is exported into a ratio nobody trades on, leaving the yield and the price floor stable.
内部研究类型:CROSS_DOMAIN_MECHANISM
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Carry is stable; a rising payout ratio is the signal to watch.
不确定性(原始记录):Formula could be amended by the board.
F095|01|股价在押一个治理问题,周期只是第二个期权
研究范围:开放研究+35项覆盖检查
写入正文:00|报告身份、评分与核心结论01|股价在押一个治理问题,周期只是第二个期权01|什么会推翻这个判断14|总分61.39/100,评级B:资产强、盈利平,技术无倾向
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(23项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Valuation arithmetic at the 6 November 2026 close怎么使用:直接证据;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Management outlook: every product line still described as facing a harsh environment怎么使用:直接 / 支持;一手验证:14;反向验证:04、06、35;其他用途:反证
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接 / 支持;一手验证:31、35;反向验证:05、14、27
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接 / 支持;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
The interim print's timing: mid-November on a consistent calendar怎么使用:直接证据;一手验证:30;专项深挖:31、35
Cross-holding web: peers and partners on both sides of the register怎么使用:直接 / 支持;专项深挖:07、24;同业比较:21;其他用途:历史
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:直接 / 支持;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
Inventory structure: work in process is 47% of a year's sales怎么使用:直接 / 支持;一手验证:06、19;反向验证:17、29;专项深挖:19
FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155怎么使用:直接 / 支持;外部现实校验:06、14;专项深挖:14
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign怎么使用:直接 / 支持;反向验证:07、15;专项深挖:02
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 反证 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;直接证据 / 支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 反证(研究域31)|Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan;直接证据 / 一手证据(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|The interim print's timing: mid-November on a consistent calendar;直接证据 / 支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register;直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales;直接证据 / 支持证据 / 外部现实(研究域06) / 外部现实(研究域14) / 定向深挖(研究域14)|FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 反证(研究域07) / 反证(研究域15) / 定向深挖(研究域02)|Channel share shift: the Sumitomo channel's weight fell with cathode volume, not by redesign;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling
完整研究记录(核对用)
研究原文:Conjunctive thesis with dated falsifiers and catalysts|A trough-plus-conversion-option thesis whose legs fail independently; principal risk is cycle relapse, and the strongest counter-evidence is the possibility that the 2026 sequence is a cluster of one-offs.
内部研究类型:THESIS_AND_FALSIFICATION
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Hold while carry pays and falsifiers are unprinted; re-underwrite on first falsifier; exit on a franchise-level one.
不确定性(原始记录):Conversion leg has no deadline.
F096|09|低谷利润不算便宜,资产却被打了五折
研究范围:开放研究+35项覆盖检查
写入正文:09|低谷利润不算便宜,资产却被打了五折
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(28项,重复标签已合并)
FY3/2026 cash flow: operating cash flow rose through the loss year怎么使用:直接 / 支持;一手验证:17;同业比较:19;其他用途:历史
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume怎么使用:直接 / 支持;外部现实校验:19;专项深挖:18
Valuation arithmetic at the 6 November 2026 close怎么使用:直接 / 支持;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
Earnings amplitude across two cycles, from the disclosure record's headlines怎么使用:直接 / 支持;一手验证:12、28;外部现实校验:33;专项深挖:33;同业比较:08、10、11;其他用途:历史
Normalisation base: five-year ordinary-profit record and its financial-income content怎么使用:直接 / 支持;一手验证:28;专项深挖:12、16、28
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接 / 支持;一手验证:16、32;同业比较:14;其他用途:历史
Non-operating quality: subsidies and affiliate losses inside ordinary profit怎么使用:直接 / 支持;反向验证:16、28、32
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接证据;一手验证:32;反向验证:20
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接证据;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Tax mechanics of the loss year: a deferred-tax credit cushioned the bottom line怎么使用:直接证据;外部现实校验:32;专项深挖:32
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:直接 / 支持;一手验证:18、29
Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored怎么使用:直接证据;同业比较:17、18、20、22、27;其他用途:历史
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:一手验证:11、13、22、35;反向验证:23、33;其他用途:反证
The capex cycle: a facility completed into the trough, depreciation stepping up怎么使用:直接 / 支持;一手验证:04、20;专项深挖:04、20;同业比较:04;其他用途:历史
Land and the old asset base: book values carry no revaluation怎么使用:直接 / 支持;一手验证:21;专项深挖:21;同业比较:29;其他用途:历史
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接证据;一手验证:31、35;反向验证:05、14、27
Dividend record: JPY 100 held through the cycle turn, by formula怎么使用:直接证据;一手验证:26
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接证据;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
The FY3/24 peak: derived comparatives from the FY3/25 year-on-year rates怎么使用:直接 / 支持;一手验证:33;同业比较:02、03、28;其他用途:历史
H1 FY3/2026 actuals: the base half against which the FY3/27 interim plan is set怎么使用:直接 / 支持;一手验证:12;同业比较:05、15、16、31;其他用途:历史
查看完整证据标签(核对用)
直接证据 / 支持证据|FY3/2026 consolidated results: a second consecutive down year;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19)|FY3/2026 cash flow: operating cash flow rose through the loss year;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 支持证据 / 外部现实(研究域19) / 定向深挖(研究域18)|Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close;直接证据 / 支持证据 / 一手证据(研究域12) / 一手证据(研究域28) / 外部现实(研究域33) / 历史/同业比较(研究域08) / 历史/同业比较(研究域10) / 历史/同业比较(研究域11) / 定向深挖(研究域33)|Earnings amplitude across two cycles, from the disclosure record's headlines;直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|Normalisation base: five-year ordinary-profit record and its financial-income content;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 支持证据 / 反证(研究域16) / 反证(研究域28) / 反证(研究域32)|Non-operating quality: subsidies and affiliate losses inside ordinary profit;直接证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 外部现实(研究域32) / 定向深挖(研究域32)|Tax mechanics of the loss year: a deferred-tax credit cushioned the bottom line;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27)|Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored;反证 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 一手证据(研究域04) / 一手证据(研究域20) / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|The capex cycle: a facility completed into the trough, depreciation stepping up;直接证据 / 支持证据 / 一手证据(研究域21) / 历史/同业比较(研究域29) / 定向深挖(研究域21)|Land and the old asset base: book values carry no revaluation;直接证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 反证(研究域31)|Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan;直接证据 / 一手证据(研究域26)|Dividend record: JPY 100 held through the cycle turn, by formula;直接证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 支持证据 / 一手证据(研究域33) / 历史/同业比较(研究域02) / 历史/同业比较(研究域03) / 历史/同业比较(研究域28)|The FY3/24 peak: derived comparatives from the FY3/25 year-on-year rates;直接证据 / 支持证据 / 一手证据(研究域12) / 历史/同业比较(研究域05) / 历史/同业比较(研究域15) / 历史/同业比较(研究域16) / 历史/同业比较(研究域31)|H1 FY3/2026 actuals: the base half against which the FY3/27 interim plan is set
完整研究记录(核对用)
研究原文:From trough earnings and a financial pile to a governance-discounted price|At JPY 2,042 the market capitalises trough operating earnings at about 14 times forecast net income yet under 6 times five-year average ordinary profit, and values the securities-and-cash pile at more than the whole company. Normalised operating-level earning power is nearer JPY 5.5-6.0 billion pre-tax than the ordinary-profit mean; the discount is a governance forecast with the cycle as a second option.
内部研究类型:VALUATION_BRIDGE
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Cheap but not absurd on normalised numbers; full on trough numbers.
不确定性(原始记录):Mixed denominators and bases flagged on the snapshot node; no consensus series; land value unknown.
F097|12|七个只有拆开才看得见的读数
研究范围:开放研究+35项覆盖检查
写入正文:12|七个只有拆开才看得见的读数
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(30项,重复标签已合并)
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
FY3/2026 income statement detail: financial income bridges operating to ordinary profit怎么使用:直接 / 支持;一手验证:16、32;同业比较:14;其他用途:历史
FY3/2026 cash flow: operating cash flow rose through the loss year怎么使用:直接 / 支持;一手验证:17;同业比较:19;其他用途:历史
Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume怎么使用:直接证据;外部现实校验:19;专项深挖:18
Inventory structure: work in process is 47% of a year's sales怎么使用:直接 / 支持;一手验证:06、19;反向验证:17、29;专项深挖:19
Working-capital structure: the group pays fast and collects slowly怎么使用:直接 / 支持;一手验证:17、19;专项深挖:10、15、17
Normalisation base: five-year ordinary-profit record and its financial-income content怎么使用:直接 / 支持;一手验证:28;专项深挖:12、16、28
Non-operating quality: subsidies and affiliate losses inside ordinary profit怎么使用:直接 / 支持;反向验证:16、28、32
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接 / 支持;一手验证:31、35;反向验证:05、14、27
Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan怎么使用:直接 / 支持;反向验证:31
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:直接 / 支持;一手验证:18、20、21、29
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:直接 / 支持;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
Cash-flow indicators: five years of zero measured interest-bearing debt burden怎么使用:直接 / 支持;一手验证:18、29
Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored怎么使用:直接证据;同业比较:17、18、20、22、27;其他用途:历史
Valuation arithmetic at the 6 November 2026 close怎么使用:直接 / 支持;一手验证:27;外部现实校验:17、21、22;专项深挖:27、29
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
Management outlook: every product line still described as facing a harsh environment怎么使用:直接 / 支持;一手验证:14;反向验证:04、06、35
The electrode frame: structurally favoured process, cyclically hostile pricing怎么使用:直接 / 支持;一手验证:08;反向验证:10;专项深挖:08
Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line怎么使用:直接 / 支持
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接证据;一手验证:11、13、22、35;反向验证:23、33
The ROE bridge the 2030 policy must cross怎么使用:直接 / 支持;一手验证:22;专项深挖:11、22
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026)怎么使用:直接 / 支持;一手验证:08;外部现实校验:05、07、08、09、12、28、35
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
The cathode demand frame: relining cycles and smelter construction怎么使用:直接证据;一手验证:11;外部现实校验:02、03、10、11、15;专项深挖:03、05
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 支持证据 / 一手证据(研究域16) / 一手证据(研究域32) / 历史/同业比较(研究域14)|FY3/2026 income statement detail: financial income bridges operating to ordinary profit;直接证据 / 支持证据 / 一手证据(研究域17) / 历史/同业比较(研究域19)|FY3/2026 cash flow: operating cash flow rose through the loss year;直接证据 / 外部现实(研究域19) / 定向深挖(研究域18)|Q1 FY3/2027 balance-sheet movement: collections in, inventory building for volume;直接证据 / 支持证据 / 一手证据(研究域06) / 一手证据(研究域19) / 反证(研究域17) / 反证(研究域29) / 定向深挖(研究域19)|Inventory structure: work in process is 47% of a year's sales;直接证据 / 支持证据 / 一手证据(研究域17) / 一手证据(研究域19) / 定向深挖(研究域10) / 定向深挖(研究域15) / 定向深挖(研究域17)|Working-capital structure: the group pays fast and collects slowly;直接证据 / 支持证据 / 一手证据(研究域28) / 定向深挖(研究域12) / 定向深挖(研究域16) / 定向深挖(研究域28)|Normalisation base: five-year ordinary-profit record and its financial-income content;直接证据 / 支持证据 / 反证(研究域16) / 反证(研究域28) / 反证(研究域32)|Non-operating quality: subsidies and affiliate losses inside ordinary profit;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 支持证据 / 反证(研究域31)|Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;直接证据 / 支持证据 / 一手证据(研究域18) / 一手证据(研究域29)|Cash-flow indicators: five years of zero measured interest-bearing debt burden;直接证据 / 历史/同业比较(研究域17) / 历史/同业比较(研究域18) / 历史/同业比较(研究域20) / 历史/同业比较(研究域22) / 历史/同业比较(研究域27)|Five-year indicator path: the equity ratio dipped through the capex supercycle and was restored;直接证据 / 支持证据 / 一手证据(研究域27) / 外部现实(研究域17) / 外部现实(研究域21) / 外部现实(研究域22) / 定向深挖(研究域27) / 定向深挖(研究域29)|Valuation arithmetic at the 6 November 2026 close;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 一手证据(研究域14) / 反证(研究域04) / 反证(研究域06) / 反证(研究域35)|Management outlook: every product line still described as facing a harsh environment;直接证据 / 支持证据 / 一手证据(研究域08) / 反证(研究域10) / 定向深挖(研究域08)|The electrode frame: structurally favoured process, cyclically hostile pricing;直接证据 / 支持证据|Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line;直接证据 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域11) / 定向深挖(研究域22)|The ROE bridge the 2030 policy must cross;直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;直接证据 / 支持证据 / 一手证据(研究域08) / 外部现实(研究域05) / 外部现实(研究域07) / 外部现实(研究域08) / 外部现实(研究域09) / 外部现实(研究域12) / 外部现实(研究域28) / 外部现实(研究域35)|Peer reality check: Tokai Carbon's Q3 FY12/26 print (5 November 2026);直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05)|The cathode demand frame: relining cycles and smelter construction
完整研究记录(核对用)
研究原文:Research Dividend produced by the current FIRST_COMPLETE Review|Non-obvious gains from deeper research: loss year as a cash-richer year; ordinary profit flattered by a financial layer; guidance whose profit is front-loaded into a one-off-assisted Q1; financial assets exceeding the entire market value; an ROE target that silently needs equity shrinkage; post-impairment arithmetic that can mimic recovery; peer divergence that removes industry excuses. No prior Review exists, so all are current-Review discoveries.
内部研究类型:RESEARCH_DIVIDEND
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Changes how headline numbers should be read.
不确定性(原始记录):Novelty provenance is first-Review only.
F098|13|最近的两道检验:中期决算和阴极块订单
研究范围:开放研究+35项覆盖检查
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
证据来源(29项,重复标签已合并)
Guidance held at Q1: the interim plan implies a very soft second quarter怎么使用:直接 / 支持;一手验证:31、35;反向验证:05、14、27
The interim print's timing: mid-November on a consistent calendar怎么使用:直接证据;一手验证:30;专项深挖:31、35
Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling怎么使用:直接 / 支持;一手验证:05;反向验证:03、19
FY3/2026 interim briefing: management's 'first quarter was the bottom' framing怎么使用:直接 / 支持;反向验证:12;同业比较:35;其他用途:历史
The cathode demand frame: relining cycles and smelter construction怎么使用:直接证据;一手验证:11;外部现实校验:02、03、10、11、15;专项深挖:03、05
Impairment notice: JPY 6,063 million written down on graphite electrode plant怎么使用:直接 / 支持;一手验证:32;反向验证:20
The electrode frame: structurally favoured process, cyclically hostile pricing怎么使用:直接证据;一手验证:08;反向验证:10;专项深挖:08
Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line怎么使用:直接证据
Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback怎么使用:直接 / 支持;外部现实校验:20
The capex cycle: a facility completed into the trough, depreciation stepping up怎么使用:直接证据;一手验证:04、20;专项深挖:04、20;同业比较:04;其他用途:历史
2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31怎么使用:直接 / 支持;一手验证:11、13、22、35;反向验证:23、33;其他用途:反证
Cross-holding web: peers and partners on both sides of the register怎么使用:直接 / 支持;专项深挖:07、24;同业比较:21;其他用途:历史
Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026怎么使用:直接 / 支持;一手验证:25;同业比较:07、13、24、26、30;其他用途:历史
Capital instruments in motion during 2026: buyback, portfolio sales, plan language怎么使用:直接 / 支持;专项深挖:13、30
Major shareholders at 31 March 2026: the Otani bloc and the trading houses怎么使用:直接 / 支持;一手验证:01、07、24;外部现实校验:23
Disclosure index 2026: plan revision, impairment, buyback, leadership change怎么使用:直接 / 支持;一手验证:13、23、24、30;反向验证:01;同业比较:32;其他用途:历史
Leadership: a representative-director change was announced on 8 June 2026怎么使用:直接证据;一手验证:23;反向验证:13、30;专项深挖:01、23
FY3/2026 sales by product: the cathode-block cycle is the group's P&L怎么使用:直接 / 支持;一手验证:02、03、09、15;反向验证:08
FY3/2027 guidance: sales recovery, profit guided down a third consecutive year怎么使用:直接 / 支持;一手验证:14、31
Customer concentration: one Sumitomo-group trading channel carries 58% of sales怎么使用:直接 / 支持;一手验证:02、05、07、15
The ROE bridge the 2030 policy must cross怎么使用:直接 / 支持;一手验证:22;专项深挖:11、22
Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover怎么使用:直接 / 支持;专项深挖:25;同业比较:25;其他用途:历史
FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets怎么使用:支持证据;一手验证:18、20、21、29
Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%怎么使用:支持证据;一手验证:27;外部现实校验:01、13、18、26、29、31、34;反向验证:09、21
FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155怎么使用:支持证据;外部现实校验:06、14;专项深挖:14
查看完整证据标签(核对用)
直接证据 / 支持证据 / 一手证据(研究域31) / 一手证据(研究域35) / 反证(研究域05) / 反证(研究域14) / 反证(研究域27)|Guidance held at Q1: the interim plan implies a very soft second quarter;直接证据 / 反证(研究域31)|Interim plan mechanics: Q1 already delivered 94% of the interim net-income plan;直接证据 / 一手证据(研究域30) / 定向深挖(研究域31) / 定向深挖(研究域35)|The interim print's timing: mid-November on a consistent calendar;直接证据 / 支持证据 / 一手证据(研究域05) / 反证(研究域03) / 反证(研究域19)|Q1 FY3/2027 by product: cathode blocks +51.8%, electrodes still falling;直接证据 / 支持证据 / 历史/同业比较(研究域35) / 反证(研究域12)|FY3/2026 interim briefing: management's 'first quarter was the bottom' framing;直接证据 / 一手证据(研究域11) / 外部现实(研究域02) / 外部现实(研究域03) / 外部现实(研究域10) / 外部现实(研究域11) / 外部现实(研究域15) / 定向深挖(研究域03) / 定向深挖(研究域05)|The cathode demand frame: relining cycles and smelter construction;直接证据 / 支持证据 / 一手证据(研究域32) / 反证(研究域20)|Impairment notice: JPY 6,063 million written down on graphite electrode plant;直接证据 / 一手证据(研究域08) / 反证(研究域10) / 定向深挖(研究域08)|The electrode frame: structurally favoured process, cyclically hostile pricing;直接证据|Post-impairment cost base: the write-down lowers tomorrow's depreciation on the weakest line;直接证据 / 支持证据 / 外部现实(研究域20)|Q1 FY3/2027 quality: a securities gain and a completed slice of the buyback;直接证据 / 一手证据(研究域04) / 一手证据(研究域20) / 历史/同业比较(研究域04) / 定向深挖(研究域04) / 定向深挖(研究域20)|The capex cycle: a facility completed into the trough, depreciation stepping up;直接证据 / 支持证据 / 反证 / 一手证据(研究域11) / 一手证据(研究域13) / 一手证据(研究域22) / 一手证据(研究域35) / 反证(研究域23) / 反证(研究域33)|2030 Make Real: the three-year mid-term plan is abolished, targets pushed to FY3/31;直接证据 / 支持证据 / 历史/同业比较(研究域21) / 定向深挖(研究域07) / 定向深挖(研究域24)|Cross-holding web: peers and partners on both sides of the register;直接证据 / 支持证据 / 一手证据(研究域25) / 历史/同业比较(研究域07) / 历史/同业比较(研究域13) / 历史/同业比较(研究域24) / 历史/同业比较(研究域26) / 历史/同业比较(研究域30)|Buyback record: ToSTNeT-3 purchases in 2024, a market buyback completed in 2026;直接证据 / 支持证据 / 定向深挖(研究域13) / 定向深挖(研究域30)|Capital instruments in motion during 2026: buyback, portfolio sales, plan language;直接证据 / 支持证据 / 一手证据(研究域01) / 一手证据(研究域07) / 一手证据(研究域24) / 外部现实(研究域23)|Major shareholders at 31 March 2026: the Otani bloc and the trading houses;直接证据 / 支持证据 / 一手证据(研究域13) / 一手证据(研究域23) / 一手证据(研究域24) / 一手证据(研究域30) / 历史/同业比较(研究域32) / 反证(研究域01)|Disclosure index 2026: plan revision, impairment, buyback, leadership change;直接证据 / 一手证据(研究域23) / 反证(研究域13) / 反证(研究域30) / 定向深挖(研究域01) / 定向深挖(研究域23)|Leadership: a representative-director change was announced on 8 June 2026;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域03) / 一手证据(研究域09) / 一手证据(研究域15) / 反证(研究域08)|FY3/2026 sales by product: the cathode-block cycle is the group's P&L;直接证据 / 支持证据 / 一手证据(研究域14) / 一手证据(研究域31)|FY3/2027 guidance: sales recovery, profit guided down a third consecutive year;直接证据 / 支持证据 / 一手证据(研究域02) / 一手证据(研究域05) / 一手证据(研究域07) / 一手证据(研究域15)|Customer concentration: one Sumitomo-group trading channel carries 58% of sales;直接证据 / 支持证据 / 一手证据(研究域22) / 定向深挖(研究域11) / 定向深挖(研究域22)|The ROE bridge the 2030 policy must cross;直接证据 / 反证(研究域24)|Register size and liquidity: 4,922 shareholders, a Standard-market small cap;直接证据 / 支持证据 / 历史/同业比较(研究域25) / 定向深挖(研究域25)|Share-count dynamics: issuance frozen since before FY3/25, buybacks the only mover;支持证据|Q1 FY3/2027 results: volume recovery off a trough quarter;支持证据 / 一手证据(研究域18) / 一手证据(研究域20) / 一手证据(研究域21) / 一手证据(研究域29)|FY3/2026 balance sheet: 89.2% equity, financial assets exceed half of total assets;支持证据 / 一手证据(研究域27) / 外部现实(研究域01) / 外部现实(研究域13) / 外部现实(研究域18) / 外部现实(研究域26) / 外部现实(研究域29) / 外部现实(研究域31) / 外部现实(研究域34) / 反证(研究域09) / 反证(研究域21)|Market snapshot, 6 November 2026: PBR 0.52, yield 4.9%;支持证据 / 外部现实(研究域06) / 外部现实(研究域14) / 定向深挖(研究域14)|FX exposure: three quarters of sales overseas, guidance struck at USD/JPY 155;支持证据 / 反证(研究域11)|Plan arithmetic: even the plan document's near-term outlook overshot the year
完整研究记录(核对用)
研究原文:Carried Research Debt and next-evidence boundaries|Ten open questions remain; none has a reasonable current public path (H1 results are a future disclosure after the information set; others depend on company disclosure not yet issued). They condition confidence in cycle timing, capex return and capital-policy pace rather than reopening Research.
内部研究类型:RESEARCH_DEBT_REGISTER
内部来源标记:OPEN_DISCOVERY / COVERAGE35
普通股东含义(原始记录):Next Review starts from the H1 print, cathode order evidence, capital-policy numbers and the register.
不确定性(原始记录):Carried explicitly; not a Research reopen.
F099|10|技术问题:回落停在五年均线,是底部区间在消化冲高,还是前两次冲高后整段回吐的开头
写入正文:10|技术问题:回落停在五年均线,是底部区间在消化冲高,还是前两次冲高后整段回吐的开头10|一生三次冲高,前两次整段都还了回去10|回落在放量见顶之后有序展开,已经走到五年均线10|价格重心就在底部区间中间,上方有三重高点,下方有两层支撑10|恢复速度、涨跌反应和冲高质量10|公开事件与价格的时序:价格先走,基本面后到10|后续什么价格行为确认,什么行为推翻14|价格与股东面四个维度:估值偏正面,治理和技术没有倾向
还不能确定:受保护的 Technical Research 结构;公开边界以其正文路由为准。
原始研究记录为内部/英文表达;读者结论已经写入上方对应的中文正文。需要核对时再展开完整研究记录。
完整研究记录(核对用)
研究原文:Protected Technical Synthesis (RESEARCH_TRUTH.technical_state)
内部研究类型:PROTECTED_TECHNICAL_SYNTHESIS
内部来源标记:TECHNICAL
不确定性(原始记录):受保护的 Technical Research 结构;公开边界以其正文路由为准。
公开边界:受保护 Technical Research 仅保留可追踪身份,本索引不重写其内部语义。
本页为Kabugami.jp研究记录,不构成投资建议、投资勧诱、买卖推荐、目标价或收益保证。投资者可能损失全部本金。
Review Identity / Provenance
| Producer | Claude Research Lane |
|---|---|
| Review Date | 2026-11-09 |
| Score Version | V3.2 |
| Publication Source SHA | a422a9c6bd64deca373973f4ecff3ad8491a25ef |
| Delivery Commit SHA | a422a9c6bd64deca373973f4ecff3ad8491a25ef |
| Delivery Runtime Fingerprint | 2602446d7ce949535e8f178fbf279f5caa1a94e2d89d790554c72b6ab9946cf6 |
| Research Authority SHA | 8484dd6fa1bb2c23409435b8578f4302c0e86dc4 |
| Canonical Snapshot | dd5730da-9df1-5b15-8634-0924d4720196 |
| Canonical Revision | 1 |